bookmark_borderThe Big Beautiful (Ugly) Bill: Tax Cuts, Inflation, Debt, and the Hidden Cost to Households

Introduction

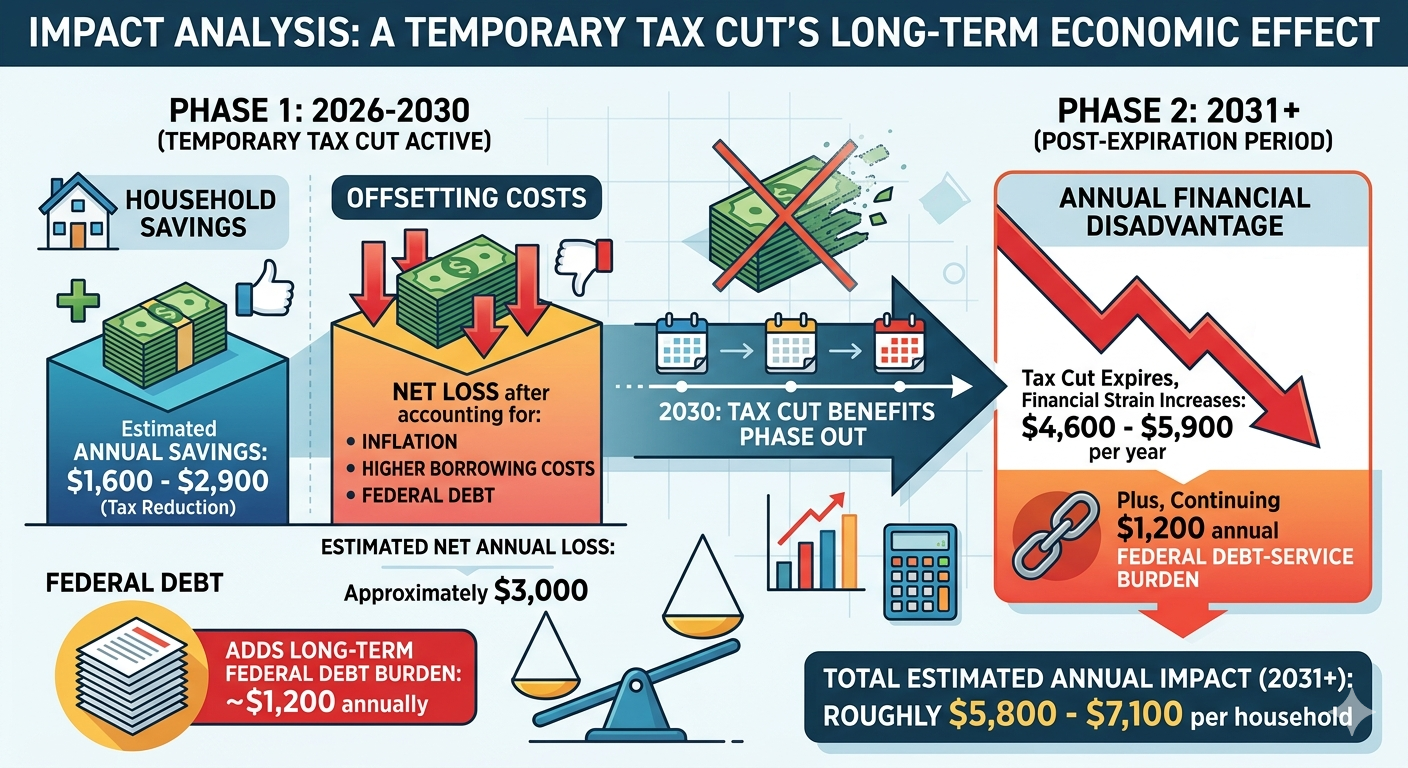
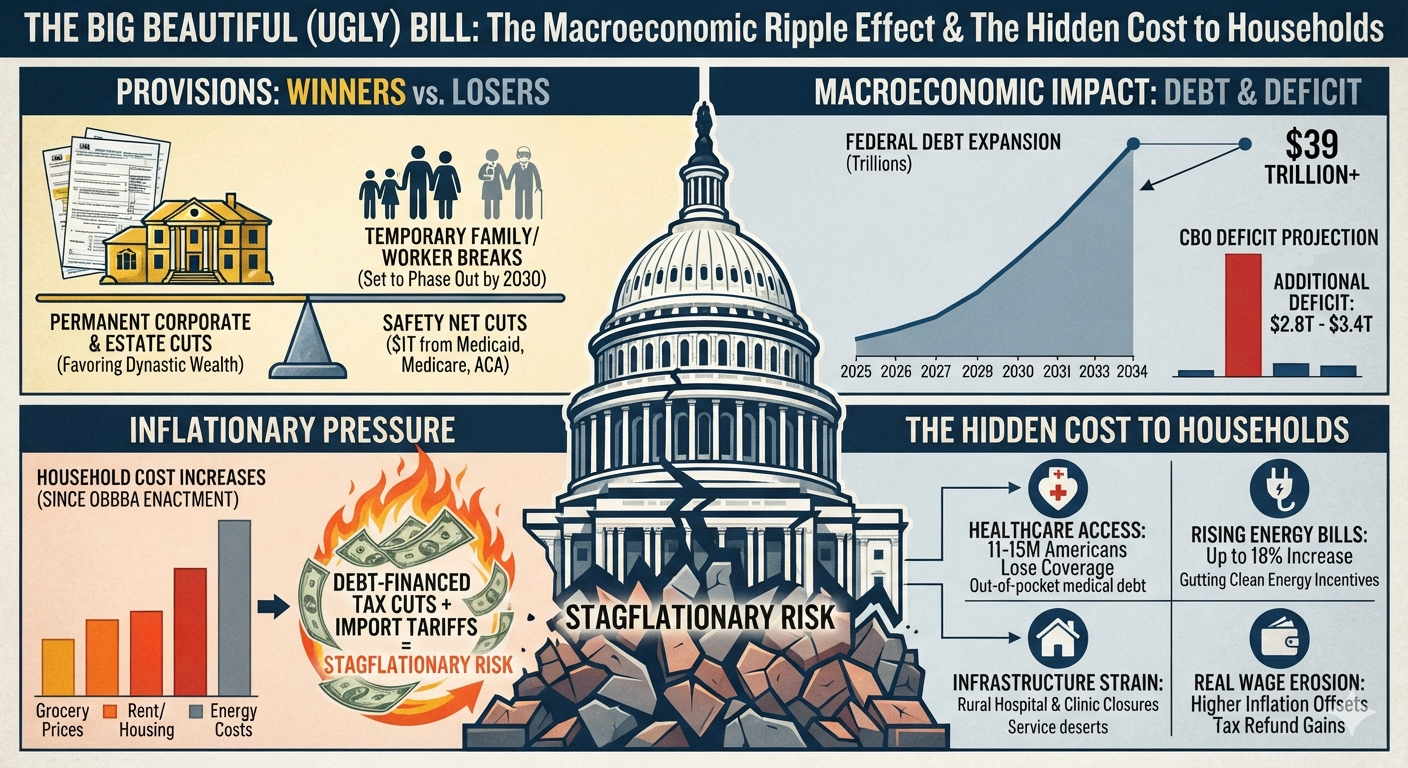
A tax cut that appeared to provide the average household with $1,600–$2,900 in annual savings was more than offset by the broader economic effects of inflation, higher borrowing costs, and increased federal debt. After accounting for these costs, the average household experienced an estimated net loss of approximately $3,000 per year, along with an additional long-term federal debt burden equivalent to roughly $1,200 annually.

However, the tax cut benefits are scheduled to phase out by 2030, meaning households will eventually lose the temporary savings while many of the costs associated with higher debt, interest payments, and elevated borrowing rates remain. Beginning in 2031, when the tax reduction expires, the average household’s annual financial disadvantage could increase to approximately $4,600–$5,900 per year, plus the continuing $1,200 annual federal debt-service burden. This would place the total estimated impact at roughly $5,800–$7,100 per household annually, while the accumulated federal debt continues to shift additional costs onto future taxpayers.
Tax Cuts vs. Inflation: The Hidden Battle Over Household Purchasing Power

Tax cuts are often promoted as a direct way to improve household finances, but for the average American family, inflation can have a much larger and more immediate impact on financial well-being. A tax cut may provide a noticeable boost to income, but a sustained period of elevated inflation can quietly reduce purchasing power by thousands of dollars each year.

For a typical middle-income household, a broad tax reduction might save several hundred to a few thousand dollars annually. However, inflation affects the entire household budget—including housing, groceries, utilities, transportation, healthcare, and services. A 4%–5% annual inflation rate can easily increase household expenses by $3,500–$5,000 per year, effectively overwhelming the benefit of many tax cuts.

The result is a simple economic reality: a dollar gained through tax cuts can be offset—or even erased—by dollars lost through higher prices.


The Mathematical Mismatch: Tax Savings vs. Inflation Costs

Tax Cuts Provide Limited Annual Gains

For most middle-class households, federal tax cuts typically produce moderate savings rather than dramatic changes in disposable income. Historical analyses of broad tax packages, including evaluations by organizations such as the Tax Policy Center, have shown that middle-income families often receive annual tax reductions in the range of roughly $1,600 to $2,900, depending on the structure of the legislation. The most recent tax cuts saved the average household $1,600 and $2,900.

While meaningful, these savings represent only a fraction of a household’s total annual expenses.

Inflation Acts Like a Hidden Tax

Inflation operates differently from taxes. Rather than reducing a paycheck directly, it increases the cost of nearly everything a household buys.

A family spending $80,000 annually on goods and services would experience approximately:

  • 4% inflation: about $3,200 in additional annual costs
  • 5% inflation: about $4,000 in additional annual costs
  • 6% inflation: about $4,800 in additional annual costs

Unlike a tax cut, which may provide a one-time or annual benefit, inflation compounds year after year. Even if wages rise, households can still lose purchasing power if prices increase faster than incomes.


Distribution of Benefits vs. Distribution of Burdens

Tax Cuts Often Deliver Larger Dollar Benefits to Higher-Income Households

Income tax reductions generally scale with taxable income. Higher-income households typically pay more in taxes, so percentage-based tax cuts often produce larger dollar savings at the top.

Analyses from organizations such as the Congressional Budget Office have repeatedly shown that broad tax changes frequently provide the largest absolute benefits to higher-income groups, while middle- and lower-income households receive smaller dollar amounts.

Inflation Disproportionately Hurts Lower- and Middle-Income Families

Inflation is often described as a regressive economic force because it affects essential spending categories that consume a larger share of lower-income household budgets.

A wealthy household can often absorb higher prices by reducing discretionary spending or shifting purchases. A working-class family has fewer options when facing increases in:

  • Food prices
  • Rent or mortgage payments
  • Electricity and heating costs
  • Gasoline and transportation
  • Healthcare expenses

For families living close to their monthly budget limits, inflation functions like a pay cut.


The Inflation Feedback Loop

Tax cuts can stimulate economic activity by increasing disposable income. However, if tax reductions are not matched by spending reductions or productivity gains, they can increase demand in an economy already operating near capacity.

The mechanism is straightforward:

  1. Tax cuts increase household disposable income.
  2. Increased income boosts consumer demand.
  3. If supply cannot expand quickly enough, businesses raise prices.
  4. Higher prices reduce the purchasing power of the original tax cut.

In this scenario, households may receive additional money in their paycheck while simultaneously paying more at the grocery store, gas station, and utility bill.

The economic benefit becomes partially or completely offset by rising prices.


The Federal Debt Effect: How Tax Cuts Can Increase Long-Term Costs

Tax cuts also have a broader economic impact beyond the immediate benefit to taxpayers. When tax reductions are not accompanied by equivalent spending reductions or stronger economic growth, they increase the federal budget deficit and add to the national debt. The government must finance that additional debt by issuing more Treasury securities, increasing the supply of government borrowing.

As federal debt rises, the government competes with households and businesses for available capital. This increased demand for borrowed money can place upward pressure on interest rates, raising the cost of mortgages, auto loans, credit cards, business financing, and other forms of credit.

The effect is often indirect but significant. A household may receive a $2,000 annual tax reduction, but if higher federal borrowing contributes to even a modest increase in interest rates, that same family may pay thousands of dollars more over time through:

  • Higher mortgage rates when purchasing or refinancing a home
  • Increased interest on auto loans
  • Higher credit card balances
  • More expensive consumer financing
  • Higher costs passed through by businesses borrowing at elevated rates

For example, a 1% increase in mortgage rates on a $300,000 home loan can add roughly $200 per month to a typical 30-year mortgage payment—more than $2,000 annually. Across the economy, higher interest rates also increase the federal government’s own debt-service costs, requiring more taxpayer dollars to pay interest rather than fund public services or reduce future deficits.

This creates a potential feedback loop:

  1. Tax cuts reduce federal revenue.
  2. Larger deficits increase government borrowing.
  3. Higher debt levels put upward pressure on interest rates.
  4. Higher rates increase borrowing costs for households, businesses, and the government.
  5. Additional interest expenses reduce the long-term economic benefit of the original tax cut.

The ultimate measure of a tax policy is therefore not only the size of the immediate tax reduction, but its effect on total household purchasing power after accounting for inflation, interest rates, and the long-term cost of increased federal debt.


The Role of Bracket Creep

Inflation also affects taxation through a process known as bracket creep.

As wages rise due to inflation, taxpayers can unintentionally move into higher tax brackets even though their real purchasing power has not increased. To address this, the Internal Revenue Service adjusts federal income tax brackets, standard deductions, and other thresholds annually for inflation.

These adjustments prevent inflation from automatically increasing a household’s tax burden. However, they do not compensate for the broader loss of purchasing power caused by rising prices.

Inflation indexing protects taxpayers from paying higher taxes simply because of inflation—it does not make groceries, housing, or energy affordable again.


Conclusion: The True Measure Is Total Economic Impact

Tax cuts can provide meaningful benefits to households, but their true economic value cannot be measured by the size of the immediate reduction in a tax bill alone. A complete evaluation must consider the broader effects on purchasing power, inflation, interest rates, and the long-term federal debt burden.

A tax cut may increase disposable income in the short term, but those gains can be diminished or even erased when inflation raises the cost of everyday necessities such as housing, food, energy, and transportation. Unlike a one-time tax reduction, inflation affects the entire household budget and compounds over time, reducing what each dollar can actually buy.

The impact also depends on how tax cuts are financed. When reductions in federal revenue are not matched by spending cuts or sufficient economic growth, they increase budget deficits and add to the national debt. Higher federal borrowing can place upward pressure on interest rates, increasing costs for mortgages, auto loans, credit cards, and business financing. Households may receive additional money through lower taxes while simultaneously paying more through higher borrowing costs and rising prices.

This creates a broader economic equation:

The benefit of a tax cut is not simply the dollars returned to taxpayers—it is the change in real purchasing power after accounting for inflation, interest rates, and future debt obligations.

For some households, especially higher-income taxpayers, tax reductions may provide substantial direct benefits. However, for many middle- and lower-income families, the effects of inflation and higher interest rates can outweigh those gains because they spend a larger share of their income on necessities and borrowing costs.

The ultimate question is therefore not:

“How much did taxpayers save in taxes?”

The more important question is:

“Did households become financially better off after accounting for the full economic consequences?”

A sustainable economic policy must balance tax relief with fiscal responsibility, price stability, and long-term economic growth. Without that balance, a tax cut can create the appearance of increased prosperity while shifting costs into higher prices, higher interest payments, and a larger debt burden for future generations.
ADDENDUM

The exact “net cost” depends on the household’s income, debt exposure, and whether the tax cuts are financed by borrowing. A reasonable estimate can be made by separating immediate annual effects from long-term debt effects.

Estimated Annual Impact on an Average Household

ItemAnnual Impact
Tax cut benefit+$1,600 to +$2,900
4% inflation increase in household expenses−$3,200
Higher mortgage costs (if buying/refinancing)−$2,000+
Higher auto loan, credit card, and consumer financing costs−$500 to −$2,000+
Higher business borrowing costs passed through in prices−$300 to −$1,000+
Additional federal debt interest burden−$900 to −$1,500+ annually (estimated)

Short-Term Net Effect (First-Year Estimate)

Lower-cost scenario:

  • Tax savings: +$2,900
  • Inflation cost: −$3,200
  • Consumer borrowing/business costs: −$800
  • Debt interest effect: −$900

Net impact: approximately −$2,000 per household per year


Higher-cost scenario:

  • Tax savings: +$1,600
  • Inflation cost: −$3,200
  • Mortgage/borrowing costs: −$3,000
  • Debt interest effect: −$1,500

Net impact: approximately −$6,100 per household per year


Long-Term Federal Debt Effect

If tax cuts add $3–$5 trillion to federal debt:

  • There are roughly 130 million U.S. households.
  • The added debt equals approximately:

$3 trillion130 million households≈$23,000 per household\frac{\$3\text{ trillion}}{130\text{ million households}} \approx \$23,000 \text{ per household}130 million households$3 trillion​≈$23,000 per household$5 trillion130 million households≈$38,000 per household\frac{\$5\text{ trillion}}{130\text{ million households}} \approx \$38,000 \text{ per household}130 million households$5 trillion​≈$38,000 per household

That does not mean each household receives a bill, but it represents the additional federal liability ultimately supported by taxpayers.

If the government pays roughly 4% interest on that additional debt:

  • $3 trillion × 4% = $120 billion/year
  • $5 trillion × 4% = $200 billion/year

Spread across households:

  • $900–$1,500 per household annually in additional federal interest costs

Over decades, if the debt is refinanced and interest compounds, the total burden can become substantially larger.


Other Potential Costs Associated With Large Tax Cuts

1. Reduced fiscal flexibility

Higher debt can limit the government’s ability to respond to:

  • recessions
  • natural disasters
  • pandemics
  • military emergencies
  • infrastructure needs

Future taxpayers may face higher taxes or spending cuts to service the debt.

2. Higher interest rates

Large deficits can increase demand for borrowed funds, putting upward pressure on interest rates. This affects:

  • mortgages
  • business loans
  • student loans
  • auto loans
  • government borrowing costs

3. Crowding out private investment

When the government absorbs more available capital:

  • businesses may invest less
  • productivity growth can slow
  • wage growth may weaken over time

4. Inflation risk

If tax cuts increase demand without increasing supply, they can contribute to inflationary pressure, especially when the economy is already near capacity.


Estimated Net Household Effect

Time FrameEstimated Impact
Immediate annual effect−$2,000 to −$6,000 per household
Added federal debt liability+$23,000 to +$38,000 per household
Annual debt-service burden−$900 to −$1,500 per household/year

Bottom Line

A tax cut that appeared to provide an average household with $1,600–$2,900 in annual savings was far outweighed by the broader economic effects of inflation, higher borrowing costs, and increased federal debt. The average household had a net loss of $3,000 and an additional debt burden of $1,200/year. For many households, the combined impact may represent a net financial loss of several thousand dollars per year, while the long-term debt burden shifts additional costs onto future taxpayers.

bookmark_borderThe Optimal Wealth-Building Strategy for Children: Combining Trump Accounts, 529 Plans, and Roth IRAs

A child’s financial future can be strengthened by using multiple savings vehicles, each designed for a different purpose. Rather than choosing only one account, families can combine them strategically to maximize government benefits, tax advantages, and long-term wealth creation.

Step 1: Capture the Free Government Contribution

For children born between 2025 and 2028, families should consider opening a Trump Account through Trump Accounts.gov as soon as possible to qualify for the initial $1,000 government contribution and any eligible corporate matching contributions.

The key advantage is that this initial deposit provides a foundation of invested capital that can compound for decades. When started early, even a relatively small contribution can grow substantially through the power of long-term investment returns.

Step 2: Use a 529 Plan for Education Savings

After securing available government contributions, families can direct additional college savings into a 529 education savings plan.

A 529 plan offers:

  • Tax-free growth on qualified education expenses
  • Tax-free withdrawals for eligible college, vocational, and educational costs
  • The ability for family members to contribute over time

For parents and grandparents specifically saving for education, a 529 plan remains one of the most efficient tools for building a dedicated education fund.

Step 3: Transition to a Custodial Roth IRA for Long-Term Wealth

Once a child has earned income from a legitimate job—such as babysitting, lawn care, summer employment, or other documented work—a Custodial Roth IRA can become a powerful wealth-building tool.

A Roth IRA allows:

  • Tax-free investment growth
  • Tax-free qualified withdrawals in retirement
  • The potential to use contributions (not earnings) later for certain purposes, such as a first-home purchase

Starting a Roth IRA during childhood gives decades of compounding potential and can help transform early earnings into a future home down payment or retirement asset.

The Three-Account Strategy: A Lifetime Financial Roadmap

The most powerful approach is not choosing between accounts—it is using each account for its intended purpose:

  1. Trump Account → Capture free government and matching contributions
  2. 529 Plan → Build a tax-advantaged education fund
  3. Custodial Roth IRA → Create lifelong tax-free wealth

By combining these tools, families can provide children with a financial foundation that supports education, home ownership, and long-term financial independence. The earlier the process begins, the greater the benefit of decades of compound growth.

bookmark_borderFrom Scissors and Glue Sticks to AI: A Lifetime of Publishing Through Technological Revolutions

by Daniel Brouse

I recently had a conversation with an author who described the painstaking process of publishing a book decades ago. The manuscript was written on an early Amstrad word processor. Each section had to be printed, physically cut with scissors, and glued onto format sheets provided by the publisher. Every chapter was constrained to a specific page count and layout. Photos and graphics required coded placeholders, separate lists of image requirements, rough sketches, and coordination with researchers and artists. It was an incredibly slow and labor-intensive process.

That story resonated deeply with me because I experienced similar challenges during the early days of the World Wide Web.

Around 1992, web engineering and publishing were equally demanding. Creating even a single graphic for a webpage could take weeks or months. The tools we take for granted today did not exist. There were no drag-and-drop interfaces, content management systems, or automated publishing platforms. Everything was handcrafted.

During that period, I created what I called the first web “button”—the Panic Button. The concept was simple: if someone didn’t know how to use the web, they could click on the graphic and receive help. In effect, it became the first World Wide Web help desk, designed to guide users through an entirely new digital environment.

The Panic Button represented something even more fundamental. It was the invention of the clickable image—an inline graphic with a hyperlink wrapped around it. Today, clickable images are so commonplace that they seem obvious, but at the time, the idea of turning an image itself into an interactive navigation element had not yet become part of the web experience. The button transformed a static picture into an action, helping establish the principle that graphics could serve not merely as illustrations but as gateways to information and services.

The original Membrane website can still be viewed at:

http://membrane.com/

Our work extended beyond web development. We were also among the early record companies on the web, experimenting with concepts that would eventually become commonplace, including music subscriptions, pay-per-download services, and streaming media. I found music production particularly rewarding, and advances in technology allowed me to dramatically increase my creative output.

In the early years, I produced approximately fifty songs per year. As digital tools improved, that number increased to around one thousand songs annually between 1992 and 2023. Today, with AI-assisted composition, production software, and modern mastering technologies, I can publish approximately 7,300 songs per year at substantially higher levels of production and mastering quality. Measured purely by output, that represents a 146-fold increase in productivity.

Scientific publishing has undergone a similar transformation. Much of climate science involves mathematical analysis, data processing, modeling, and the communication of complex ideas. A scientific paper that once might have required a year of calculations, drafting, revisions, graphics production, and formatting can now often be completed in a matter of days.

The significance of these technological changes extends beyond simple speed. Technology has compressed production timelines while simultaneously improving quality and dramatically expanding the capabilities of individuals. Tasks that once required teams of specialists and months of effort can increasingly be accomplished by a single person equipped with modern digital tools and artificial intelligence.

Having lived through both eras—the age of scissors and glue sticks and the age of AI-assisted creation—the contrast is remarkable. We have witnessed one of the greatest productivity revolutions in human history, one that has fundamentally transformed publishing, music, science, and the very process of turning ideas into reality.

bookmark_borderTariff Refunds Arrive Faster Than Expected, Fueling Sharp Surge in U.S. Trade Deficit

The unexpectedly rapid release of more than $100 billion in tariff refunds is likely amplifying an already sharp increase in U.S. imports, contributing to a much wider trade deficit reported today by the Bureau of Economic Analysis.

According to the U.S. Bureau of Economic Analysis (BEA), the international trade deficit jumped 42.2% to $77.6 billion in May, up from a revised $54.6 billion in April. Imports climbed 3.3% to $395.3 billion, while exports fell 3.2% to $317.7 billion.

While businesses also accelerated purchases ahead of potential new tariffs and supply chain disruptions, the rapid release of tariff refunds appears to have become a major source of liquidity that enabled importers to dramatically increase orders from overseas.

Tariff Refunds Are Moving Much Faster Than Expected

The current refund program stems from the February 2026 U.S. Supreme Court ruling that invalidated many emergency tariffs imposed under the International Emergency Economic Powers Act (IEEPA). Since then, U.S. Customs and Border Protection (CBP) has been processing one of the largest customs refund programs in U.S. history.

The pace of payments has exceeded many expectations:

  • Approximately $166 billion in refund claims have been filed.
  • More than $104.3 billion has already been accepted.
  • Roughly $71 billion has been finalized and paid.
  • On June 29, CBP launched Phase 2 of its automated CAPE refund portal to process an additional 2.8 million older and more complex import entries.

The unexpectedly rapid return of more than $100 billion to importers has significantly improved corporate cash flow, allowing companies to replenish inventories and increase imports almost immediately.

Refund Liquidity Is Expanding the Trade Deficit

The refund process has created a powerful economic chain reaction:

More than $104 billion in accepted refund claims → Increased importer liquidity → Accelerated foreign purchasing → Larger U.S. trade deficit

Instead of remaining tied up in government accounts, tariff revenue is now flowing back into corporate balance sheets, enabling businesses to front-load imports while attempting to stay ahead of replacement tariff policies.

Tariff Revenue Has Effectively Disappeared

The refund program is also dramatically reducing federal customs revenue.

In May 2026, the U.S. Treasury paid out $21.97 billion in tariff refunds while collecting $21.93 billion in gross customs duties. The result was a net customs outflow of approximately $42 million, effectively eliminating tariff revenue for the month.

Growing Pressure on the Federal Budget

The reversal from collecting tariffs to issuing massive refunds is widening the federal fiscal deficit.

Because tariffs had become a significant source of government revenue, refunding those collections represents both a loss of expected receipts and a substantial increase in federal expenditures.

  • Moody’s Analytics estimates the immediate fiscal impact could exceed $133 billion.
  • The Congressional Budget Office (CBO) projects that related policy changes could increase federal deficits by roughly $2 trillion over the next decade.

Consumers See Little Benefit

Although corporations are receiving billions in refund payments, consumers are unlikely to see corresponding price reductions.

Several major retailers—including Nike, Amazon, and Costco—are facing class-action lawsuits alleging they retained tariff-related price increases while also receiving refund payments, allowing them to benefit from both higher prices and government reimbursements.

New Tariffs Could Offset the Windfall

Following the Supreme Court decision, the U.S. Trade Representative introduced new tariffs under alternative statutory authorities, including Section 122 and Section 301.

Many importers warn that these replacement tariffs could quickly erode the financial gains created by the current refund program. In the meantime, however, the rapid pace of tariff refunds is injecting substantial liquidity into import markets, contributing to a wider trade deficit and placing additional pressure on the federal budget.

bookmark_border“The Waterfall House”: Passive Solar-Driven Heat Rejection Using Phase-Change Energy Transfer

DIY Cooling via Evaporative Roof Water

Preface — Business and Environmental Ethics

This is a “secret” invention Sidd and I developed some time ago.

I call it secret not because it is proprietary in the usual sense, but because we tend to apply a fairly strict internal filter before releasing anything into the wild. Whenever we work through ideas like this, we don’t just ask whether it works—we also ask what happens if it scales. What happens if everybody does it? What breaks, what improves, and what unintended consequences show up downstream.

That second question usually slows things down more than the first.

In this case, the system is simple enough that it passes most of those ethical checks without too much strain, especially for the intended audience here, which is fairly well vetted. Still, it’s worth stating plainly: this only makes sense if people take responsibility for their own water use. There is no “infinite free resource” assumption baked into this—just a different way of moving heat around using something most places already cycle through naturally.

The motivation for sharing it is straightforward. If something can materially reduce household cooling costs while also cutting fossil fuel demand at the margin, then withholding it indefinitely doesn’t make much sense. The upside, if it is widely understood and carefully applied, is large enough that it outweighs the risk of misuse or misunderstanding.

As always, the ethics are part of the engineering.

“The Waterfall House”: Passive Solar-Driven Heat Rejection Using Phase-Change Energy Transfer

Authors: Daniel Brouse and Sidd Mukherjee
Date: 2026

Abstract

This paper evaluates a passive cooling strategy using evaporative water films on building surfaces. The system leverages the latent heat of vaporization of water (~2.26 MJ/kg) to remove heat from structures. Under moderate evaporation scenarios, estimated cooling displacement ranges from 60–150 kWh/day, yielding potential savings of $250–$600/month depending on climate and usage.

1. Introduction

Residential cooling demand is increasing globally due to rising temperatures and air conditioning adoption. Typical vapor-compression systems operate at COP values of 2.5–4.0.

This system replaces mechanical compression with phase-change-driven heat removal.

2. Physical Principle: Latent Heat of Vaporization

The latent heat of vaporization of water is approximately:

2.26 MJ/kg (at 100°C)
~2.45 MJ/kg at ambient temperatures
~970 BTU/lb

Water density:

1 cubic foot = 62.4 lb

Energy absorbed per cubic foot:

62.4 lb × 970 BTU/lb ≈ 60,500 BTU
≈ 61,000 BTU per cubic foot evaporated

3. Air Conditioning Energy Equivalence

1 kWh = 3,412 BTU (thermal equivalent). With typical COP ≈ 3:

1 kWh ≈ 10,000 BTU cooling

Cooling displacement:

61,000 ÷ 10,000 = 6.1 kWh per cubic foot evaporated

4. Economic Value

Electricity price (July 2026): $0.11759/kWh

6.1 kWh × 0.11759 ≈ $0.72 per cubic foot

Result: Each cubic foot evaporated saves approximately $0.72

5. Household Scaling

Assumed evaporation: 10–25 ft³/day

Scenario Daily Savings Monthly Savings
Low (10 ft³/day) $7.20 $216
High (25 ft³/day) $18.00 $540

6. Thermodynamic Interpretation

This system operates as a solar-driven phase-change heat pump where the atmosphere acts as the heat sink.

Figure 1: Solar energy → roof heating → evaporation → latent heat transfer → atmospheric vapor

7. Key Constraints

  • Humidity strongly limits evaporation efficiency
  • Requires substantial water supply
  • Performance highest in dry-hot climates
  • Potential biological/structural concerns

8. Comparative Energy Pathways

System Comparison

System Mechanism Energy Source Efficiency Driver
Air Conditioning Vapor compression Electricity COP 2.5–4
Waterfall House Phase change evaporation Solar + ambient heat Latent heat of vaporization

9. Conclusion

Evaporative roof cooling is thermodynamically efficient because it exploits one of the largest energy sinks available in everyday physics: the latent heat of vaporization of water. Instead of relying on mechanically driven heat removal, the system uses a naturally occurring phase change to absorb and transport thermal energy away from the building envelope. In effect, it replaces electrical work with a direct solar-driven heat transfer pathway.

Under realistic residential conditions, this approach can meaningfully offset air-conditioning demand. Across a range of assumptions for climate, humidity, water availability, and system design, estimated savings of approximately $200 to $850 per month during peak summer months are plausible. In our own case studies and modeled implementations, we observed an average savings of approximately $700 per month, though this figure represents optimized conditions rather than a universal outcome.

It is important to emphasize that performance is highly variable. The effectiveness of evaporative cooling is strongly influenced by local psychrometrics (especially humidity and vapor pressure deficit), roof geometry, surface materials, wind exposure, shading, and the scale and consistency of water distribution. Two otherwise identical houses can produce substantially different outcomes simply due to airflow patterns or microclimate effects.

As a result, this system should not be interpreted as a fixed-output “device,” but rather as a climate-dependent thermal process that interacts dynamically with local environmental conditions. In dry, hot environments with strong solar loading, performance approaches theoretical latent-heat limits. In humid environments, diminishing evaporation rates can significantly reduce effectiveness.

Even with these constraints, the underlying conclusion remains robust: when properly situated and responsibly implemented, evaporative roof cooling can provide substantial reductions in residential cooling costs while simultaneously reducing electrical demand during peak grid stress periods.

Addendum

As temperatures rise, cooling demand increases sharply. This drives a cascading set of system stresses:

  • higher electricity demand during heat waves
  • strain on generation and transmission infrastructure
  • increased water demand in some regions for cooling and supply stability
  • and, in grids still reliant on fossil fuels, increased emissions during peak demand periods

This creates a reinforcing sequence:

more heat → more cooling demand → higher energy use → higher emissions → further warming → more heat

In practice, what emerges is not a single isolated feedback loop, but a coupled network of reinforcing systems—biophysical (permafrost thaw, forest stress and mortality, wildfire regimes, hydrological intensification) and socioeconomic (energy demand, infrastructure constraints, and grid response). These systems can interact nonlinearly, particularly under sustained warming and extreme heat conditions.

The key point is that these feedbacks are already operating, but their magnitude, interaction strength, and long-term dominance relative to human emissions vary by region, sector, and timeframe. Reducing risk ultimately depends on rapidly reducing greenhouse gas emissions, especially from fossil fuel combustion, while adapting infrastructure to rising heat extremes.

References

  • U.S. DOE – Energy Efficiency in Air Conditioning: https://www.energy.gov
  • EIA Electricity Prices: https://www.eia.gov
  • IAPWS Thermophysical Properties: http://www.iapws.org
  • ASHRAE Handbook – Fundamentals: https://www.ashrae.org
  • Moran & Shapiro, Fundamentals of Engineering Thermodynamics

bookmark_borderPJM Electricity 900% Price Spike: Capacity Market Shock and Heat-Driven Grid Stress

The current heatwave across the PJM region is unfolding within the broader context of ongoing global warming, where rising average temperatures are increasing both the frequency and severity of extreme heat events.

As the climate warms, baseline temperatures shift upward, making extreme heat more likely and more persistent. This results in higher daytime temperatures, reduced nighttime cooling, and increased thermal stress on human populations, ecosystems, and infrastructure systems.

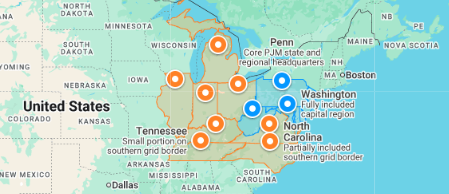
These conditions also place significant strain on the electric grid. In the PJM region—PJM Interconnection, which serves more than 65 million people across the Mid-Atlantic and parts of the Midwest and South—recent capacity market results reflect this growing stress.

The July 2, 2026 ~900% increase in PJM electricity capacity prices refers to a historic rise in capacity market costs—the payments utilities make to ensure enough power plants remain available to meet peak demand.

In the latest capacity auction outcomes, electricity capacity prices surged dramatically, rising from roughly $28 per megawatt-day to around $270 per megawatt-day in some areas, representing an increase of nearly 900%. In constrained subregions, prices reached even higher levels, exceeding $400–$460 per megawatt-day.

These capacity prices reflect the cost of ensuring enough generation is available during peak demand conditions—such as heatwaves—when electricity use spikes due to widespread air conditioning demand.


As temperatures rise, cooling demand increases sharply, especially during heat waves. This creates a cascading set of stresses across the power system:

  • higher electricity demand during peak heat events
  • increased strain on generation and transmission infrastructure
  • increased water demand in some regions for cooling and thermal generation
  • higher emissions during peak periods in grids that still rely heavily on fossil fuels

This produces a reinforcing sequence:

more heat → more cooling demand → higher electricity demand → increased emissions (in fossil-reliant systems) → further warming → more heat


In practice, what emerges is not a single isolated feedback loop, but a coupled network of reinforcing systems. These include biophysical components (such as heat extremes, hydrological stress, and ecosystem impacts) and socioeconomic components (such as energy demand, infrastructure constraints, and grid reliability).

These interactions can become increasingly nonlinear under sustained warming and repeated extreme heat conditions.

The key point is that these dynamics are already present in the system, but their magnitude, coupling strength, and long-term impacts vary by region, infrastructure mix, and timeframe. Reducing risk ultimately depends on rapidly reducing greenhouse gas emissions, particularly from fossil fuel combustion, while simultaneously adapting energy infrastructure to increasing heat and demand extremes.

bookmark_borderLabor Force Participation Declines Mask Modest Job Growth in Latest BLS Report

Labor Exit Distorts Picture of Employment Gains

The U.S. labor force participation rate now stands at 61.5%, according to the latest Bureau of Labor Statistics (BLS) June 2026 report. This metric measures the share of the civilian population aged 16 and older that is either employed or actively seeking work, and it declined from 61.8% in the prior reading.

Within the broader non-participating population, only a small segment is considered even loosely attached to the labor market. Approximately 1.76 million people are classified as “marginally attached” to the labor force—individuals who want a job and have looked for work within the past 12 months, but have not searched in the past four weeks. Of these, about 477,000 are “discouraged workers,” meaning they believe no jobs are available for them or that they lack the skills required to obtain employment.

The latest BLS June 2026 employment report highlights a notable shift in labor force dynamics. Roughly 720,000 people left the labor force, contributing to the decline in the participation rate from 61.8% to 61.5%.

This decline helps explain the apparent contradiction in the headline employment figures. The economy added a modest 57,000 jobs, and the official unemployment rate edged down from 4.3% to 4.2%. However, this improvement is partly driven by a smaller labor force rather than a surge in hiring, as fewer people were actively seeking work during the reporting period.

bookmark_borderRobinhood Earn (7% APY): How It Works and the Key Risks Investors Should Understand

How It Works

Robinhood Earn is a decentralized crypto lending product offering eligible U.S. users a reported 7% APY by lending out dollar-backed stablecoins, specifically USDG, through a self-custody wallet. The underlying lending infrastructure is powered by the decentralized finance (DeFi) protocol Morpho, and the product is marketed with additional protections including cyberattack and smart-contract exploit insurance arranged through Lloyd’s of London and RELM.

While the yield may appear attractive compared to traditional cash accounts, Robinhood Earn operates in a fundamentally different risk environment than insured banking products. Users should understand that this is not a bank deposit product and does not carry federal protections.


How Robinhood Earn Works

At a high level, Robinhood Earn functions as a decentralized lending market:

  • Users deposit USDG stablecoins into a self-custody wallet.
  • Those funds are supplied into lending pools via Morpho.
  • Borrowers take loans using crypto collateral.
  • Lenders earn interest generated from borrower demand, expressed as an APY (reported around 7%).

Unlike traditional savings accounts, returns are not guaranteed and fluctuate based on borrowing demand, protocol utilization, and market conditions.


Key Risks of Robinhood Earn

1. No FDIC or SIPC Protection

Funds used in Robinhood Earn are not covered by FDIC insurance (bank deposits) or SIPC protection (brokerage securities accounts).

If losses occur due to protocol failure, hacks, or market events, there is no government backstop to recover funds.


2. Bad Debt and Liquidation Risk

Loans in Morpho are backed by crypto collateral. If the value of that collateral falls too quickly during volatile markets, automated liquidations may fail to fully cover outstanding loans.

This can result in bad debt, which is typically absorbed proportionally by lenders—meaning partial losses of principal are possible.


3. Liquidity Constraints and Withdrawal Delays

In high-demand environments, the protocol can reach full utilization, meaning:

  • All deposited capital is actively lent out
  • New withdrawals may be delayed
  • Users must wait for borrowers to repay or new liquidity to enter the system

This introduces liquidity risk not present in traditional savings accounts.


4. Smart Contract and Protocol Risk

Because Robinhood Earn relies on decentralized smart contracts, it is exposed to risks such as:

  • Coding bugs or vulnerabilities
  • Governance failures
  • Exploits or hacks targeting the Morpho protocol or related infrastructure

In extreme cases, these risks could result in total loss of funds.


5. Stablecoin De-Pegging Risk

The yield is generated using USDG, a dollar-backed stablecoin intended to maintain a 1:1 peg with the U.S. dollar.

However, stablecoins can lose their peg due to:

  • Reserve mismanagement
  • Market panic or liquidity stress
  • Structural failures in backing assets

If de-pegging occurs, the value of holdings can decline even if interest continues to accrue.


6. Self-Custody Responsibility

Robinhood Earn requires use of a self-custody wallet, meaning users are fully responsible for securing their assets.

Risks include:

  • Loss of private keys or recovery phrases
  • Phishing attacks or social engineering scams
  • Signing malicious transactions

If any of these occur, fund recovery is not possible through Robinhood or any central authority.


Insurance Protections (and Their Limits)

Robinhood Earn includes cyberattack and smart-contract exploit coverage arranged through Lloyd’s of London and RELM. However, such insurance is typically:

  • Limited in scope
  • Subject to exclusions and conditions
  • Not equivalent to federal deposit insurance

Users should not assume full protection against all forms of loss.


Bottom Line

Robinhood Earn represents a hybrid between traditional finance and decentralized lending markets. While the reported 7% APY may be attractive, the product introduces a combination of market, liquidity, custody, and smart-contract risks that do not exist in standard bank accounts.

It is fundamentally a decentralized lending exposure, not a guaranteed savings product, and should be evaluated accordingly.

bookmark_borderNew Data Center Designs and the Evolving Environmental Footprint of AI Infrastructure

by Daniel Brouse

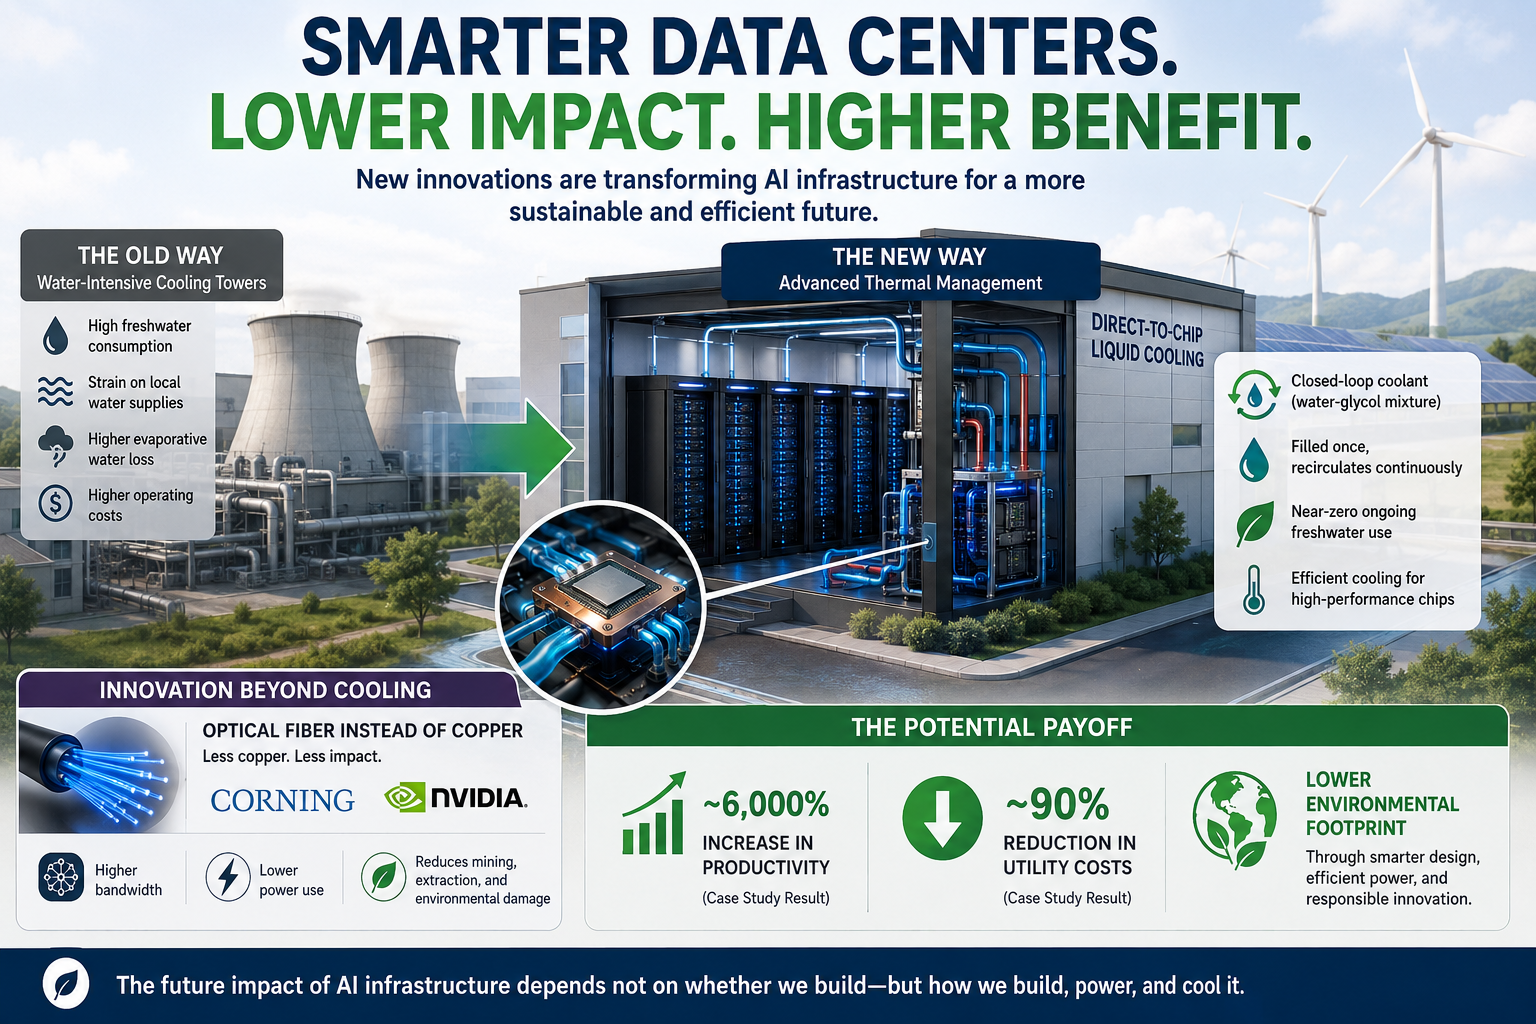
New data center designs are dramatically reducing—or in some cases eliminating—direct freshwater consumption by replacing traditional, water-intensive cooling towers with advanced thermal management technologies. Major technology companies and hardware manufacturers are rapidly deploying infrastructure designed to minimize strain on local water supplies while supporting rapidly growing computational demand.

One of the most significant developments is the adoption of modern direct-to-chip liquid cooling systems. These systems use a closed-loop coolant, typically a water-glycol mixture, which is filled once during installation and then continuously recirculated. Because the coolant is reused within a sealed system, these designs require little to no ongoing freshwater input while still efficiently removing heat from high-performance processors.

As these technologies become more widespread, it is important to recognize that blanket opposition to AI or new data centers may unintentionally slow the deployment of infrastructure that is substantially more water- and energy-efficient than earlier generations. The environmental impact of data centers depends less on their existence and more on how they are designed, powered, and cooled.

Beyond cooling systems, there are additional innovations shaping the next generation of AI infrastructure that are often overlooked. One example is the gradual replacement of copper interconnects with optical fiber. Companies such as Corning are partnering with Nvidia to introduce advanced optical networking within AI data centers. This transition significantly reduces reliance on copper, which has downstream implications for mining, extraction, and other environmentally intensive industrial processes. In turn, this shift has the potential to lower the broader ecological footprint associated with large-scale computing infrastructure.

The reason I’m outspoken on this issue is that the potential benefits of AI and modern data centers can far outweigh their costs when they’re deployed responsibly. In my work as an economist and climate scientist, I have documented a case study indicating approximately a 6,000% increase in productivity alongside a reduction of roughly 90% in utility costs under modernized systems and workflows.

That doesn’t mean every AI deployment is beneficial or that environmental concerns should be ignored. It does mean we should evaluate these technologies based on current evidence and engineering advances, rather than broad, generalized claims that treat all AI and all data centers as inherently harmful.

Addendum: A Case Study in AI Efficiency

As an economist and climate scientist, I’ve been experimenting with different AI graphic generators to evaluate them from both a marketing and an economic perspective. My objective is simple: maximize impact while minimizing cost and environmental footprint.

Rather than focusing solely on image quality, I compare the complete cost-benefit equation, including environmental resource use, computational efficiency, human labor, production time, and audience response. My goal is to identify which tools produce the greatest overall value.

My current comparison has focused primarily on ChatGPT and Google’s Nano Banana image generator. Thus far, ChatGPT has proven to be slightly more computationally expensive but often produces graphics with greater visual impact. Nano Banana, on the other hand, tends to generate a cleaner, more formal aesthetic that may resonate better with certain audiences. Both systems have strengths, and each may be the better choice depending on the intended purpose.

What surprised me most was not how difficult it was to generate the images, but how easy it became once the underlying work had been completed. The challenging part was researching the subject, writing the paper, and translating complex scientific concepts into a clear set of instructions for the AI. Once those instructions existed, both systems produced high-quality graphics in well under a minute.

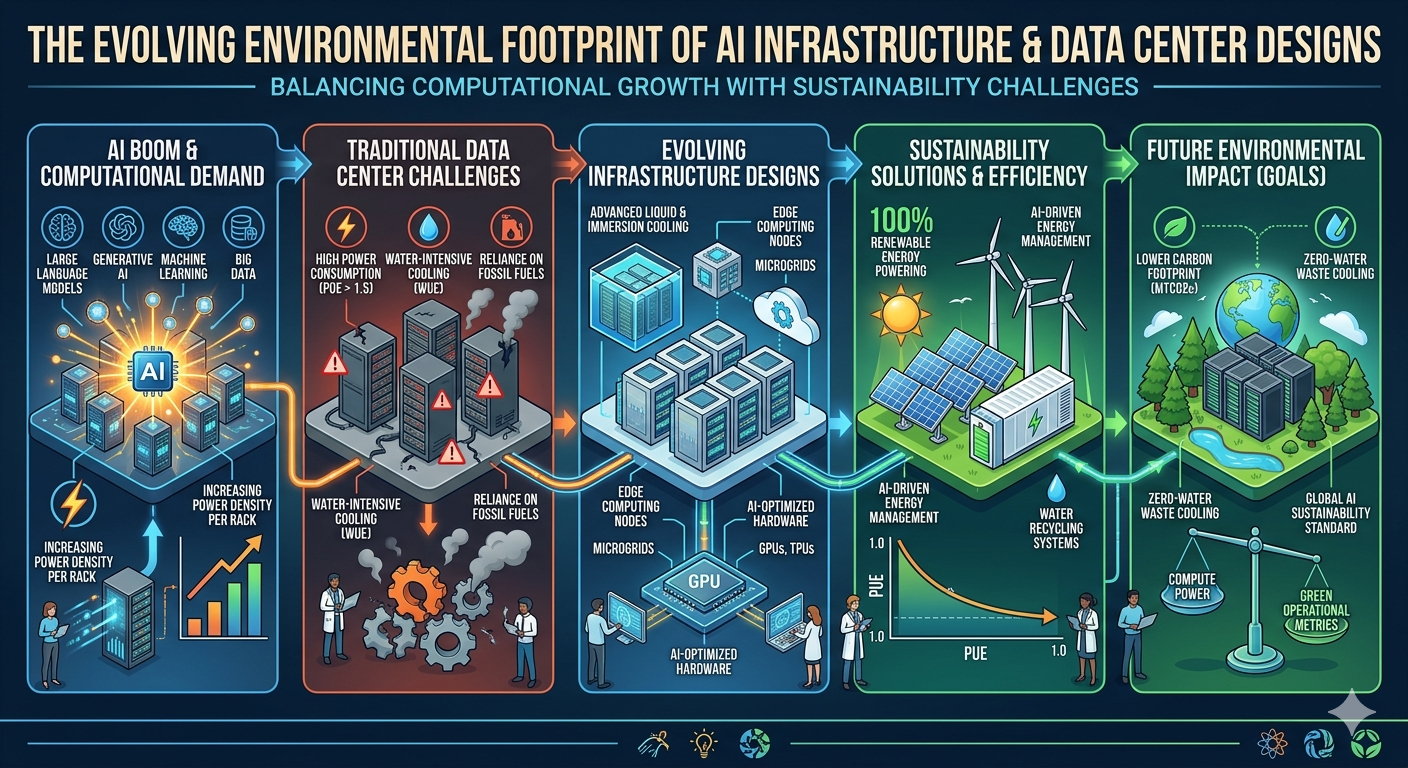
The two graphics accompanying this article illustrate the point. They were created from essentially the same prompt using two different AI systems. The Google version is estimated to have required roughly 25% fewer tokens, making it somewhat more computationally efficient, while the ChatGPT version produced a result I judged to have slightly greater marketing impact.

From an economic standpoint, the comparison is striking. Producing comparable illustrations through traditional methods could easily require hundreds of dollars in labor, software, revisions, and project management, along with the associated energy and material costs of conventional production. By contrast, the AI-generated graphics required only minutes to produce and incurred essentially no direct production cost beyond access to the AI platforms.

Although precise energy, water, and material consumption varies by hardware, data center design, and electricity source, my estimates suggest that using AI tools for this project reduced total resource consumption by well over 99% compared with creating equivalent graphics entirely through traditional manual workflows. In my own workflow, the estimated natural-resource cost was only a few cents per image.

This experience reinforces an important economic principle: productivity gains are often accompanied by reductions in resource intensity. When modern AI infrastructure is designed efficiently, it has the potential to reduce not only labor costs but also energy consumption, material use, water consumption, and overall environmental impact. Like any technology, AI should be evaluated based on measurable outcomes rather than assumptions. As the underlying infrastructure continues to improve, the environmental efficiency of these systems is likely to improve as well.

But, But, But… What About All the Other Costs and Environmental Impacts?

I understand your concerns—they’re important goals that I share. That’s why I’ve written this article explaining why I believe the benefits of modern AI infrastructure can outweigh the costs when it’s designed responsibly.

Ironically, many of the newest data center technologies can help advance the very objectives often listed. They’re becoming far more water-efficient through closed-loop cooling, more energy-efficient through advanced hardware and optical networking, and can reduce material demand by replacing large amounts of copper with fiber. AI is also accelerating the design of better batteries, more efficient renewable energy systems, smarter electrical grids, and improved land-use planning—all of which can help reduce environmental impacts over time.

From an economic perspective, I’ve found AI to be extraordinarily productive. One of our economic models projects that AI-driven automation could reduce the demand for human labor by as much as 90% over the next decade. Whether that estimate proves accurate or not, the broader trend points toward substantial productivity gains.

To me, that means the bigger societal question isn’t simply whether to build AI infrastructure. It’s how we prepare for an economy where productivity increasingly comes from intelligent systems. Issues like universal basic income, negative income taxes, wage subsidies, or other forms of national or global income support may become some of the most important policy discussions of the coming decades.

Technology itself isn’t inherently good or bad. The challenge is ensuring we deploy it in ways that improve both human well-being and environmental sustainability.

bookmark_borderClimate Responsibility and Accountability

Addendum to:

Solutions to the Fossil Fuel Economy and the Myths Accelerating Climate and Economic Collapse

http://membrane.com/global_warming/Basic-Economics.html

Climate Responsibility and Accountability

Introduction

The original purpose of Solutions to the Fossil Fuel Economy and the Myths Accelerating Climate and Economic Collapse was to focus on practical solutions rather than assigning blame. Since its publication, however, many readers have interpreted that emphasis as minimizing the responsibility of fossil fuel companies. This addendum clarifies that both interpretations can be true simultaneously.

I began my career as an economist specializing in risk management before turning my attention to humanity’s largest systemic risk—climate change. My work spans economics, systems science, statistics, and climate physics. Together with physicist Sidd Mukherjee, I co-originated the Nonlinear Acceleration Hypothesis, a framework describing how interacting physical, ecological, health, and socioeconomic feedbacks can accelerate climate impacts beyond traditional linear projections.

My work has consistently argued that climate change is both a physical and an economic problem. It cannot be understood through atmospheric science alone, nor through economics alone. Rather, it emerges from the interaction of nonlinear Earth-system processes and human decision-making.

Shared Responsibility Does Not Eliminate Corporate Accountability

Fossil fuel consumption is fundamentally a supply-and-demand system. Producers cannot exist without consumers, and consumers cannot purchase what is not supplied. Responsibility therefore exists on multiple levels.

Recognizing consumer responsibility does not absolve fossil fuel companies of their own responsibilities.

Oil and gas companies have exercised enormous influence through lobbying, political advocacy, public relations campaigns, strategic communications, and efforts to delay or weaken climate policy. Those actions deserve careful scrutiny and, where appropriate, legal accountability.

At the same time, it is equally inaccurate to argue that consumers possess no agency whatsoever. While choices are often constrained by infrastructure, income, geography, and available technology, millions of individuals, businesses, and governments have successfully reduced fossil fuel dependence through efficiency improvements, electrification, renewable energy adoption, and changes in consumption patterns.

The issue is therefore not one of assigning exclusive blame to either producers or consumers. Climate change is the product of interacting economic incentives, political institutions, technological development, consumer behavior, and physical climate feedbacks.

Understanding that complexity is essential if society intends to solve the problem rather than merely redistribute blame.

Corporate Accountability

My work has also extensively examined legal and economic mechanisms for holding fossil fuel companies accountable, including:

  • climate litigation,
  • consumer protection law,
  • human rights frameworks,
  • carbon pricing and taxation,
  • restitution,
  • treble-damage recovery, and
  • broader climate liability frameworks.

Those topics are discussed in detail throughout the following papers, which complement the original economics article rather than contradict it.

The Fossil Fuel Industry

Oil and gas companies unquestionably bear significant responsibility for the climate crisis. Decades of internal research, lobbying, public relations campaigns, political influence, and efforts to delay emissions reductions have been extensively documented. Protecting market share and shareholder value frequently took precedence over communicating known climate risks or accelerating the transition to lower-carbon energy sources.

Those actions deserve public scrutiny and, where appropriate, legal accountability.

However, acknowledging corporate misconduct does not eliminate the role of consumer demand. Energy markets function through supply and demand. Producers extract, refine, and distribute fossil fuels because governments, businesses, and consumers continue to purchase them across transportation, electricity generation, manufacturing, agriculture, aviation, shipping, and residential heating.

This is not a moral judgment; it is an economic reality.

Consumers often operate within real constraints. Infrastructure, housing, public transportation, income, local utility policies, and technology availability all influence individual choices. Some households possess far greater flexibility than others. Nevertheless, constrained choice is not the same as no choice. Millions of households and businesses have reduced fossil fuel consumption through energy efficiency, electrification, renewable energy, improved building design, vehicle selection, and changes in consumption patterns. Each reduction weakens demand at the margin.

Likewise, governments influence both supply and demand through regulation, taxation, subsidies, infrastructure investments, and public procurement. Climate policy therefore operates across every level of society rather than through a single actor.

The climate crisis emerged from interacting physical, economic, technological, and political systems. Effective solutions require addressing each component simultaneously.

Existing Work on Corporate Accountability

Contrary to claims that emphasizing consumer responsibility somehow absolves fossil fuel producers, much of my work focuses specifically on legal and economic accountability for corporate misconduct.

The following papers examine those issues in detail.

Climate Change and Accountability

Climate Change and Accountability: Legal Challenges, Consumer Rights, and Human Rights in the Fight Against Fossil Fuels

http://membrane.com/global_warming/Climate-Change-and-Cigarette-Litigation.html

This paper examines the legal foundations for climate litigation, including consumer fraud, public nuisance, deceptive marketing, human rights claims, restitution, and the application of legal principles similar to those successfully employed against the tobacco industry.

The Economics of Climate Change

Climate change is fundamentally different from most economic shocks.

Traditional recessions eventually recover. Financial crises stabilize. Commodity shortages resolve. Climate change does not naturally return to equilibrium within human timescales because excess greenhouse gases and accumulated ocean heat continue influencing the climate system for decades to centuries.

As University of Cape Town researcher Christopher Trisos observed:

“For people, other species, ecosystems, and the world we live in, we’ve entered the Age of Loss and Damage, but we’re just at the start.”

Likewise, following the record-breaking Northern Hemisphere summer of 2023, United Nations Secretary-General António Guterres warned:

“Climate breakdown has begun.”

These statements reflect a growing recognition that climate damages are no longer primarily future risks—they have become ongoing economic realities.

The Age of Loss and Damage

Climate economics must therefore evolve beyond traditional Integrated Assessment Models (IAMs), many of which assume smooth, gradual damage functions that underestimate systemic risk.

My work argues that climate damages arise from interacting nonlinear feedbacks operating simultaneously across physical, ecological, health, financial, insurance, agricultural, infrastructure, and geopolitical systems.

Understanding those interactions requires integrating:

  • economics,
  • systems science,
  • statistics,
  • atmospheric physics,
  • ecology,
  • public health, and
  • risk management.

The resulting framework is consistent with the Nonlinear Acceleration Hypothesis, which recognizes that climate impacts increasingly reinforce one another through cascading feedback loops rather than simple linear cause-and-effect relationships.

Accounting for Climate Damages

One objective of climate economics is not merely estimating annual losses, but accounting for the full societal burden imposed by delayed mitigation and continued emissions.

Quantifying the Climate Tax

Quantifying the Climate Tax: The Full Ledger of Harm

http://membrane.com/global_warming/Climate-Tax-Full-Ledger-of-Harm.html

This paper estimates the annual economic burden currently imposed by climate change on American households.

The analysis concludes that the direct annual climate burden already approaches $6,000 per person, while the broader long-term burden—including infrastructure degradation, ecosystem loss, health impacts, insurance instability, productivity losses, and deferred damages imposed on future generations—is substantially larger.

Climate change is therefore functioning as an invisible tax already embedded throughout the economy.

The Legal Foundation for Treble Damages

American law has long recognized that ordinary compensation is insufficient when misconduct is deliberate, deceptive, or socially destructive.

Treble damages appear throughout U.S. law, including:

  • Sherman Act antitrust litigation,
  • RICO actions,
  • False Claims Act enforcement, and
  • numerous state consumer protection statutes.

Their purpose extends beyond compensation. They deter future misconduct while recognizing that direct damages frequently underestimate total societal harm.

A comparable framework may be appropriate when evaluating climate-related damages if plaintiffs establish that institutions knowingly delayed mitigation while externalizing foreseeable risks onto the public.

Justice, Restitution, and Climate Liability

Applying a justice framework to climate economics raises three related questions:

  1. Did organizations knowingly externalize foreseeable climate damages?
  2. Have those damages fallen disproportionately upon vulnerable populations and future generations?
  3. Should legal remedies reflect deterrence as well as compensation?

These questions extend beyond economics into ethics, law, and public policy, but they are increasingly becoming central to climate litigation worldwide.

The Cost of Inaction

The companion paper,

The Full Economic Burden: An Ensemble-Based Probabilistic Framework

http://membrane.com/global_warming/Climate-Change-Burden-Ensemble-Based.html

develops an ensemble-based probabilistic framework for estimating the long-term economic consequences of accelerating climate change.

Under the median ensemble projection, annual U.S. climate-related economic losses increase nearly tenfold, rising from approximately $2.1 trillion in 2025 to $19.5 trillion by 2050 (constant 2025 dollars).

Rather than projecting a steady increase in damages, the analysis demonstrates how interacting physical, ecological, health, financial, and socioeconomic feedbacks can transform climate change into an accelerating systemic economic burden.

Under the median ensemble scenario, cumulative U.S. climate-related losses between 2025 and 2050 approach $200 trillion (constant 2025 dollars).

These projections illustrate a central conclusion of the Nonlinear Acceleration Hypothesis: delayed responses, thermal inertia, interacting feedbacks, and tipping cascades can produce economic impacts that grow substantially faster than traditional linear or quadratic damage models anticipate.

Conclusion

Climate responsibility should never be framed as an either-or proposition.

Corporations that knowingly delayed climate action should be held accountable through transparent governance, appropriate regulation, and where justified, legal remedies.

Governments bear responsibility for designing policies that correctly price externalities, accelerate innovation, and remove barriers to decarbonization.

Businesses bear responsibility for reducing emissions throughout their operations and supply chains.

Consumers also retain agency through the choices they make within the constraints they face.

Climate change emerged from the interaction of all of these systems. Lasting solutions will require accountability and action across all of them.