bookmark_borderThe United States and the 1.5°C Climate Tipping Point Crisis

by Daniel Brouse and Sidd Mukherjee

Overview

The United States bears an oversized responsibility for the climate crisis through its enormous historical contribution to greenhouse gas emissions. Yet U.S. climate policy is moving backward while Earth’s interconnected climate systems are destabilizing.

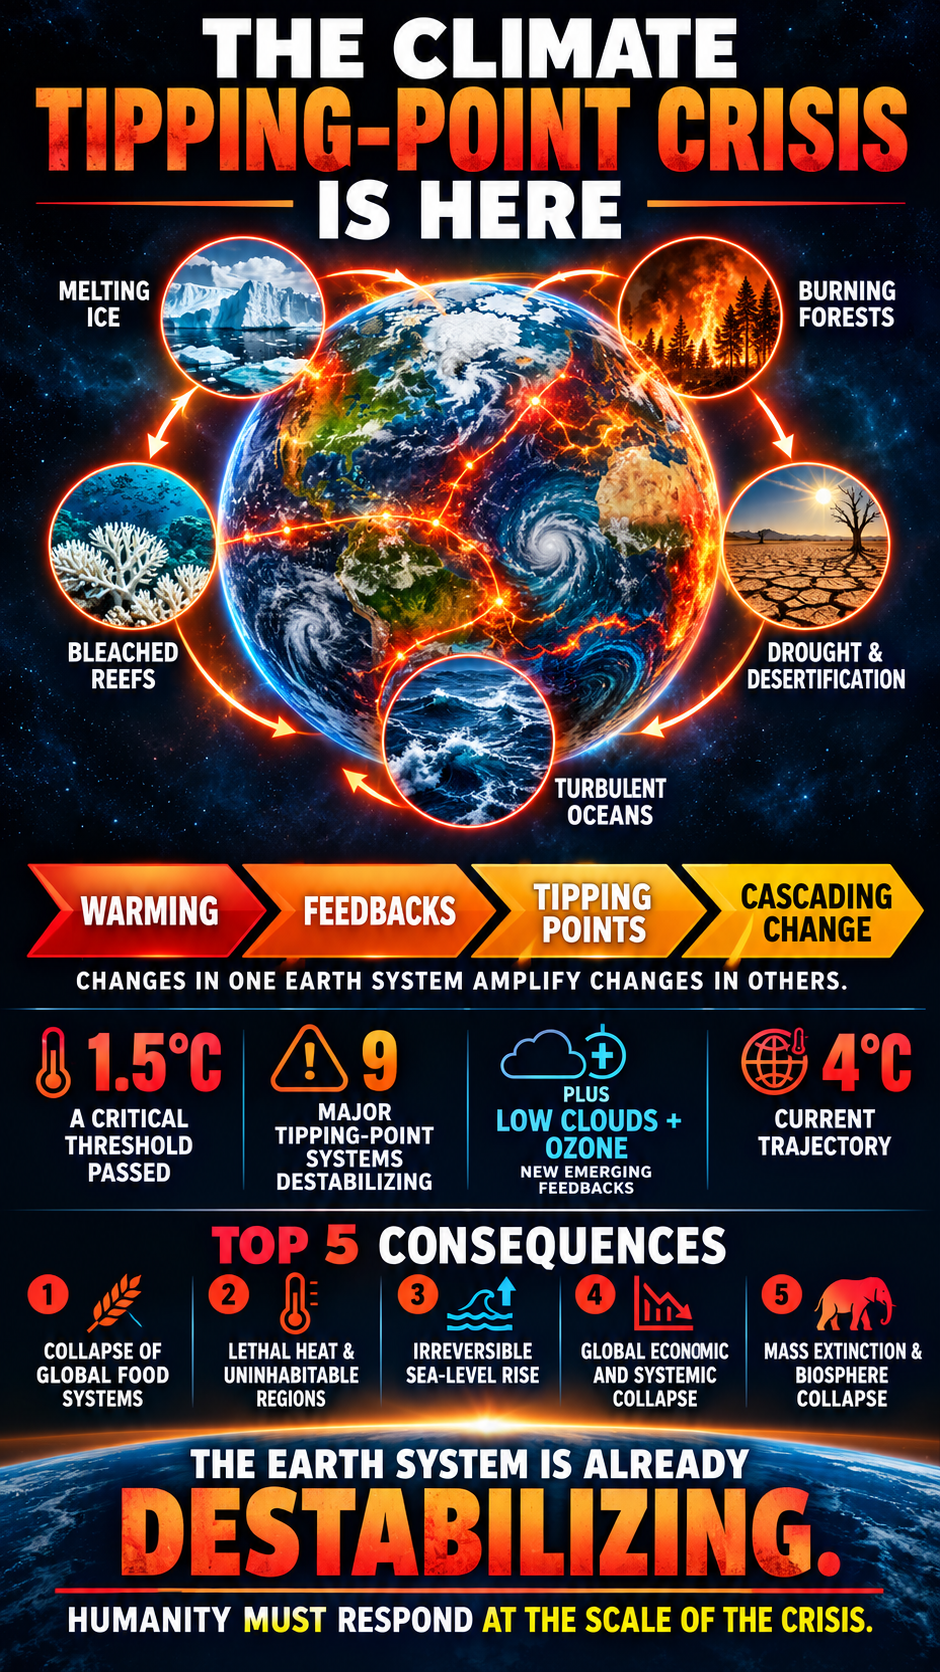
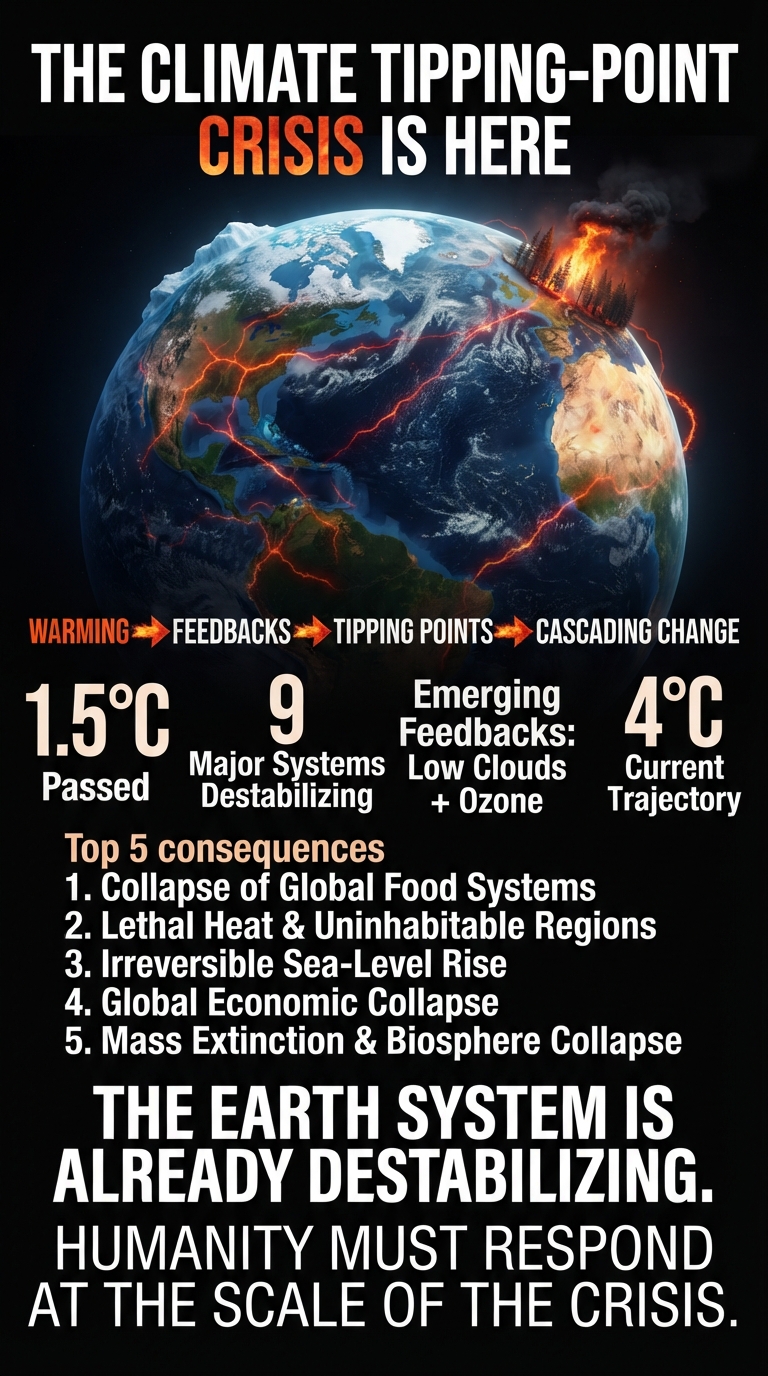
THE CLIMATE TIPPING-POINT CRISIS IS HERE.

Warming is no longer just a matter of rising temperatures. It is activating feedbacks that amplify changes across interconnected Earth systems, accelerating a climate domino effect.

WARMING → FEEDBACKS → TIPPING POINTS → CASCADING CHANGE

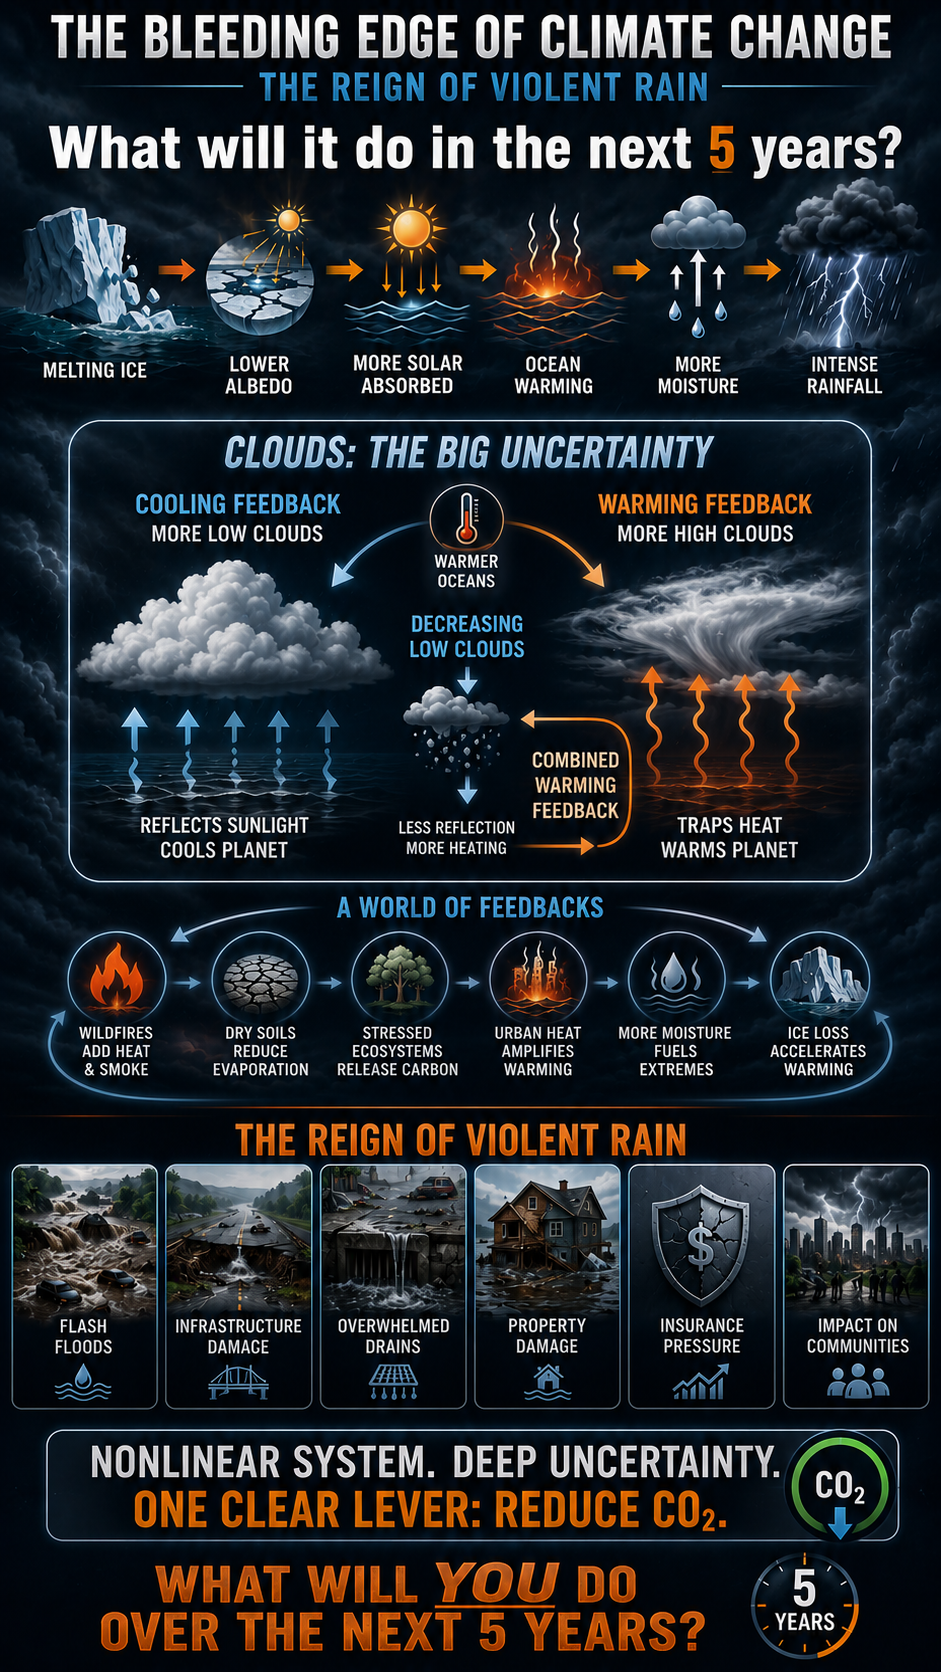
When one system destabilizes, it changes the conditions affecting others. Melting ice reduces Earth’s reflectivity. Thawing permafrost releases greenhouse gases. Forest degradation weakens natural carbon sinks. Declining low-level clouds and tropospheric ozone add further warming pressure.

THE KEY FACTS

  • 1.5°C — A critical climate threshold already crossed in individual years.
  • 9 major climate tipping-point systems — Already exhibiting destabilization.
  • LOW CLOUDS + OZONE — Emerging feedbacks intensifying the climate challenge.
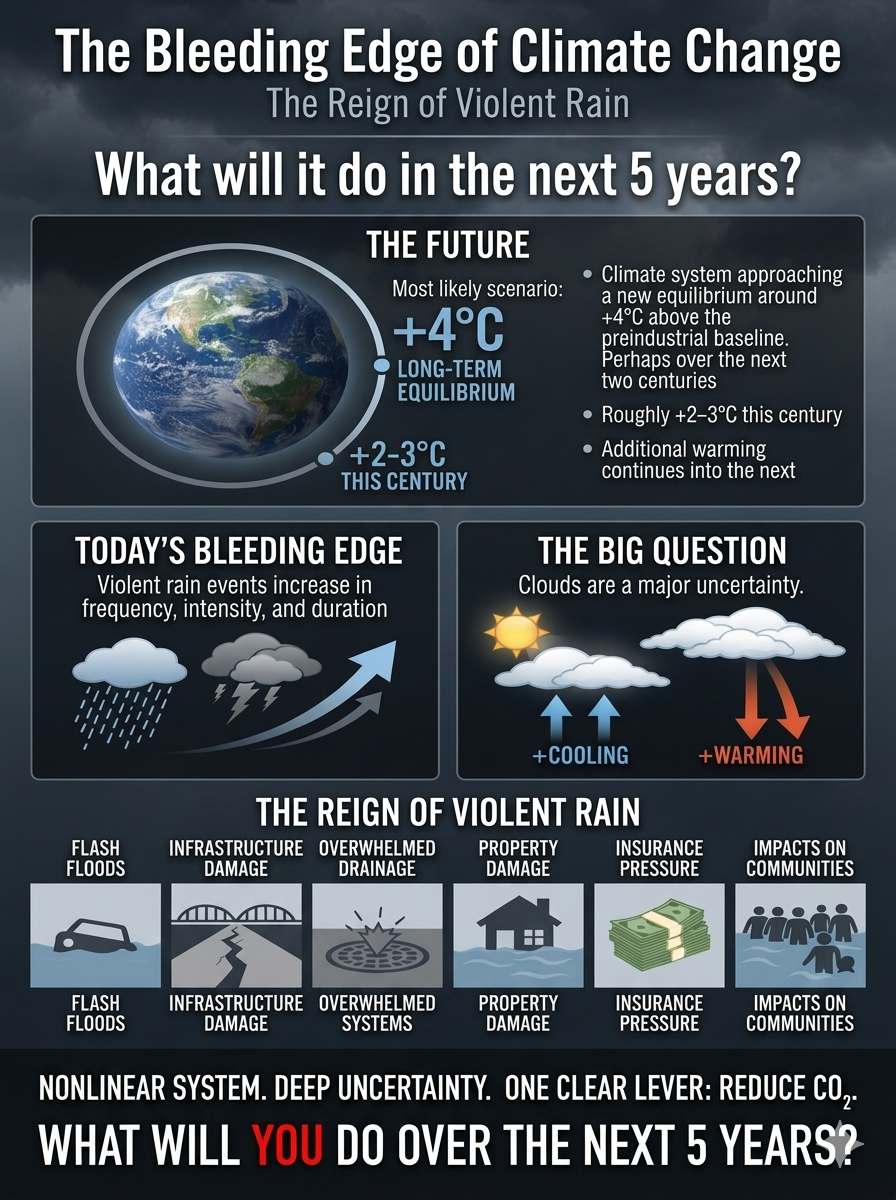
  • 4°C — The severe warming trajectory examined in this analysis for this century.

THE TOP FIVE CONSEQUENCES

  1. Collapse of Global Food Systems
  2. Lethal Heat and Uninhabitable Regions
  3. Irreversible Sea-Level Rise
  4. Global Economic and Systemic Collapse
  5. Mass Extinction and Biosphere Collapse

These are interconnected threats. Food insecurity, extreme heat, coastal inundation, economic disruption, and ecological collapse reinforce one another, placing human civilization and natural ecosystems under mounting pressure.

THE EARTH SYSTEM IS ALREADY DESTABILIZING.

The climate crisis is not simply a future problem. Observed changes are already underway, and interconnected feedbacks threaten to amplify their consequences. Political delay and continued emissions deepen the challenge.

HUMANITY MUST RESPOND AT THE SCALE OF THE CRISIS.

Read the full paper for the scientific framework, emerging feedbacks, climate tipping points, and consequences of a high-warming trajectory.

#ClimateChange #ClimateTippingPoints #GlobalWarming #ClimateScience #ClimateAction

Crossing 1.5°C: The Tipping Points Are Already Activating

The significance of crossing the 1.5°C global warming threshold extends far beyond a numerical temperature target. This threshold marks a critical boundary for the activation of major climate tipping points. At least nine major tipping-point systems are already exhibiting destabilization, with activation beginning below 1.5°C of global warming.

Other major tipping points associated with warming between 1.5°C and 2°C are also experiencing periods of activation. These observations demonstrate that the climate system is already undergoing fundamental changes as interconnected feedback processes intensify.

According to the UN Environment Programme (UNEP) and the Copernicus Climate Change Service, the long-term global average surface temperature has risen approximately 1.4°C above pre-industrial levels (1850–1900). Understanding this figure requires distinguishing sustained warming from individual annual temperature records.

1. Long-Term Warming: Approximately 1.4°C

To assess the Paris Agreement’s 1.5°C threshold, scientists examine long-term temperature averages rather than treating a single unusually warm year as proof of a sustained breach. A 20-year average smooths temporary fluctuations associated with natural climate variability, including El Niño.

By this long-term measure, global warming stands at approximately 1.4°C. The world is approaching the threshold associated with increasingly widespread and consequential climate tipping-point activation.

2. Annual Temperature Records: 1.55°C

Individual calendar years have already exceeded 1.5°C of warming.

In 2024, the global average surface temperature reached approximately 1.55°C above the pre-industrial baseline, making it the hottest year in the instrumental record. Human-caused greenhouse gas emissions, combined with natural climate variability, contributed to this record.

The 1.5°C threshold is therefore no longer merely a distant benchmark. Annual global temperatures have already crossed it, while long-term warming continues to approach the same boundary.

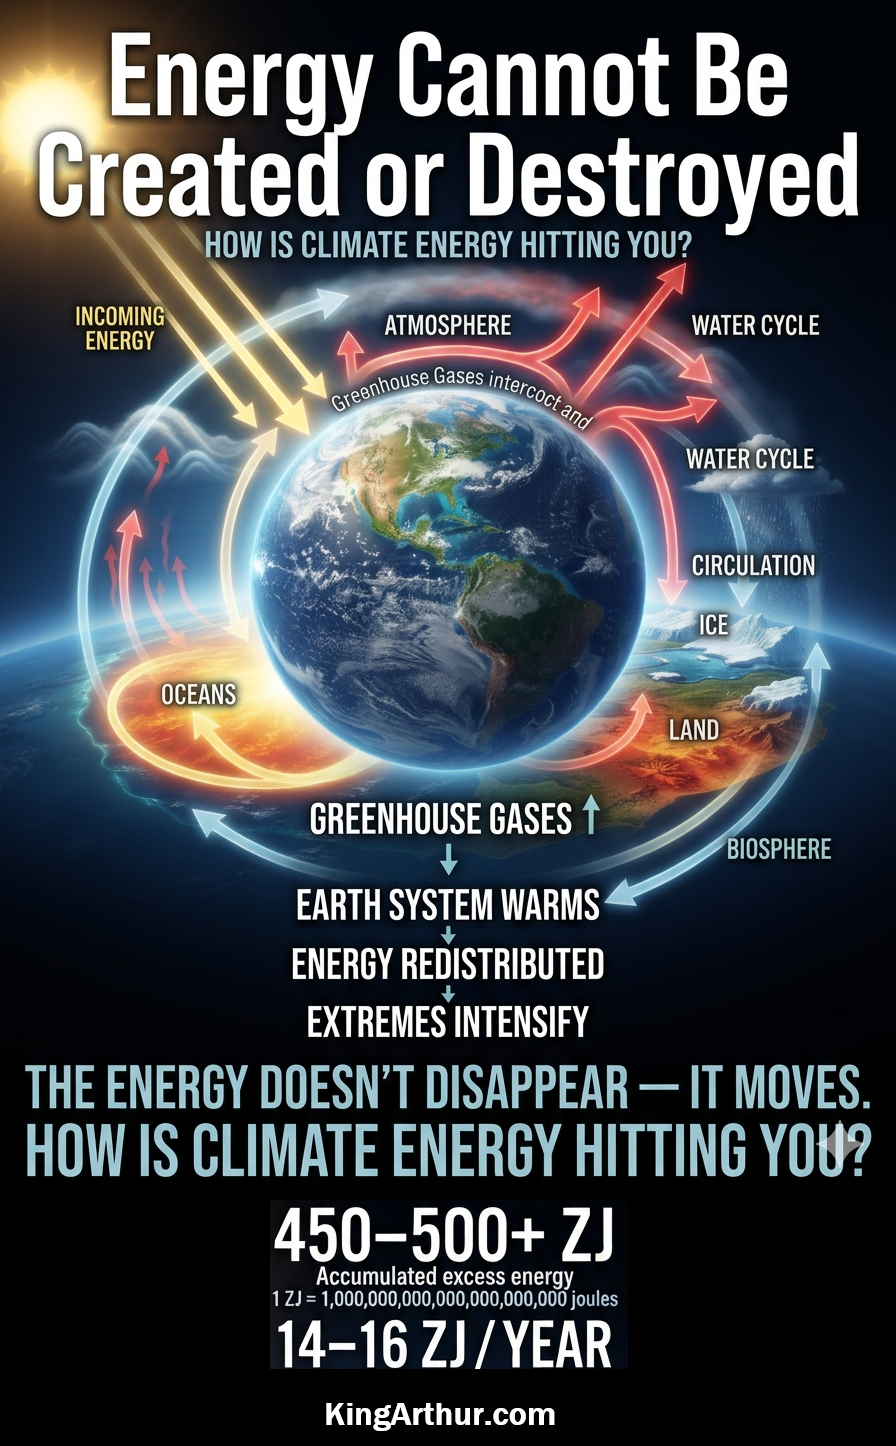
Once tipping points activate, self-reinforcing feedback processes intensify changes within the climate system. These processes connect warming to additional warming, accelerating the redistribution of energy throughout the atmosphere, oceans, cryosphere, and biosphere.

Nine Major Climate Tipping-Point Systems Undergoing Destabilization

A landmark synthesis published in Nature by leading international scientists identifies nine major climate tipping-point systems exhibiting destabilization. These systems have moved beyond abstract future concerns: measurable changes are occurring across interconnected components of the Earth system.

The Cryosphere: Ice Masses and Frozen Ground

Greenland Ice Sheet: Accelerating surface melting threatens the long-term stability of the ice sheet. Crossing its tipping threshold commits the planet to eventual, irreversible sea-level rise of approximately seven meters.

West Antarctic Ice Sheet: Marine ice-sheet instability is intensifying as warming ocean waters melt glaciers from below, undermining the structural stability of the ice sheet.

Parts of East Antarctica: Major subglacial basins are showing signs of accelerated ice loss, challenging earlier assumptions about the stability of these regions.

Arctic Sea Ice: Arctic sea ice is rapidly declining in extent and thickness. This loss reduces Earth’s albedo, or reflectivity, allowing the ocean to absorb more incoming solar energy and amplifying regional and global warming.

Permafrost: Abrupt thaw is occurring across northern latitudes. Decomposition of previously frozen organic material releases carbon dioxide and methane, adding greenhouse gases to the atmosphere and strengthening warming feedbacks.

Ocean and Atmospheric Circulation

Atlantic Meridional Overturning Circulation (AMOC): This major system of Atlantic Ocean currents, which includes the Gulf Stream, is experiencing substantial disruption. Freshwater entering the North Atlantic from melting Arctic and Greenland ice alters ocean density and threatens the circulation system’s stability.

Changes in ocean circulation affect heat transport, regional climate patterns, marine ecosystems, and the distribution of energy throughout the climate system.

The Biosphere: Forests and Marine Ecosystems

Amazon Rainforest: Deforestation and rising temperatures are intensifying drought stress across the Amazon. Increasingly dry conditions, forest degradation, and fire interact to push parts of the rainforest toward a degraded, fire-prone savannah state.

Boreal Forests: Extensive tree mortality and increasingly destructive wildfire cycles are disrupting forest regeneration across northern latitudes. These changes threaten the long-term stability of major forest ecosystems and their role in carbon storage.

Warm-Water Coral Reefs: Marine heatwaves have repeatedly exceeded critical thermal thresholds, producing widespread and severe coral bleaching. Repeated bleaching and ecological degradation threaten reef survival and accelerate transitions toward algae-dominated ecosystems.

These tipping-point systems do not operate independently. Destabilization in one part of the Earth system changes conditions in others, creating interconnected feedbacks and increasing the risk of cascading failures. The resulting domino effect makes the combined behavior of the climate system more consequential than any single tipping point considered in isolation.

The United States: A Major Setback in Global Climate Action

The United States’ climate policy direction represents a major setback in the international response to global warming.

According to the 2026 UN Environment Programme Emissions Gap Report: The Point of Return, the United States was identified as the only major economy experiencing a dramatic annual increase in greenhouse gas emissions. The reported increase of 133 million metric tons of carbon dioxide equivalent represents a substantial reversal in U.S. emissions performance.

The reported surge reflects the interaction of energy demand, fossil-fuel dependence, and federal policy changes. While other G20 economies reduced or stabilized their emissions, the United States moved in the opposite direction.

Policy Reversal: Withdrawal from the Paris Agreement

Following his second inauguration in January 2025, President Donald Trump signed an executive order initiating a second U.S. withdrawal from the 2015 Paris Climate Agreement. The withdrawal became official on January 27, 2026.

The administration defended the decision as a means of protecting American energy independence and resisting international regulations it characterized as unfair to domestic workers.

At the same time, federal policy reversed or weakened multiple climate measures. These changes targeted vehicle fuel-efficiency standards, halted tax credits supporting wind and solar development, and imposed requirements intended to keep aging fossil-fuel power plants operating.

Together, these policies weakened federal support for emissions reductions and reinforced the role of conventional fossil fuels in the U.S. energy system.

Coal, Electricity Demand, and Artificial Intelligence

The reported 133-million-metric-ton emissions increase coincided with rising electricity demand and renewed reliance on carbon-intensive power generation.

Coal resurgence: Increased coal-fired generation helped meet electricity demand while older power plants remained operational. Extending the operation of these plants reversed a longstanding downward trend in U.S. power-sector emissions.

Artificial intelligence and data centers: Rapid expansion of AI infrastructure created substantial new electricity demand. Data-center growth increased pressure on existing power grids, while the deployment of new energy infrastructure struggled to keep pace. Utilities consequently relied heavily on existing coal and natural-gas generation.

The interaction of rising electricity demand, fossil-fuel generation, and policy changes demonstrates how technological expansion without corresponding clean-energy deployment increases emissions.

Global Consequences

The UNEP report projects that current global climate policies and emissions trajectories will produce warming of approximately 2.6°C to 2.8°C by the end of the century. This trajectory represents a substantial overshoot of the Paris Agreement’s 1.5°C objective.

The United States’ retreat from climate commitments deepens the international leadership gap. The European Union, China, India, Brazil, and South Africa are among the major actors pursuing international climate cooperation outside the framework of U.S. participation.

The central problem is not simply that one country has changed its policies. It is that the world’s largest historical contributor to greenhouse gas emissions is weakening its climate response while the Earth system is already showing signs of destabilization.

The Deeper Problem: Climate Change Is Accelerating Beyond Historical Human Experience

The difficulty of predicting future climate conditions lies in the unprecedented speed and complexity of the changes now underway.

Humanity has never experienced human-driven climate change at the present rate of acceleration. As one scientific assessment explains, the current speed of human-induced carbon dioxide change and warming is nearly without precedent in the geological record, with the instantaneous meteorite impact associated with the extinction of non-avian dinosaurs 66 million years ago representing the principal known exception.

Past climate records provide essential evidence about Earth’s sensitivity and behavior. However, those records do not provide a direct historical precedent for a technologically advanced civilization deliberately transforming the atmosphere at the current rate while simultaneously confronting interconnected climate tipping points.

Humanity understands the mechanisms behind many individual climate feedbacks. The unprecedented challenge is determining how these mechanisms interact when multiple thresholds are crossed and destabilization spreads across interconnected systems.

A reasonable expectation is that a society confronting its greatest existential environmental threat would respond decisively. The U.S. policy reversal demonstrates that political and economic behavior does not necessarily follow that expectation, even as climate risks intensify.

From Individual Tipping Points to Cascading Feedbacks

The activation of nine major tipping-point systems raises a fundamental issue: the climate system is interconnected, and its response to multiple simultaneous disturbances is not equivalent to the sum of isolated changes.

As ice melts, albedo declines. As oceans absorb additional energy, marine heatwaves intensify. As forests deteriorate, carbon storage and ecosystem resilience decline. As permafrost thaws, greenhouse gases enter the atmosphere. These processes interact, reinforcing the original warming and altering the conditions under which other feedbacks operate.

This is the climate domino effect: warming activates feedbacks, feedbacks amplify warming, and interconnected systems move toward additional thresholds. The resulting cascade changes the trajectory of the entire Earth system.

The problem is compounded by emerging feedback mechanisms whose combined influence is not adequately represented in conventional climate projections.

Two Emerging Feedbacks: Low-Level Clouds and Tropospheric Ozone

Declining low-level clouds represent a major emerging climate feedback. Low clouds reflect incoming solar radiation back into space. A sustained decline in their coverage reduces this cooling influence and increases the energy retained by the Earth system.

Tropospheric ozone is another major climate-forcing agent. In addition to contributing to atmospheric warming, ozone damages vegetation, reduces photosynthetic performance, and impairs the ability of forests and other ecosystems to absorb carbon dioxide. These ecological effects weaken natural carbon sinks while adding to the climate system’s existing greenhouse forcing.

The significance of these feedbacks extends beyond their individual contributions. Their interaction with established feedbacks changes the overall balance of energy entering, leaving, and being redistributed throughout the climate system.

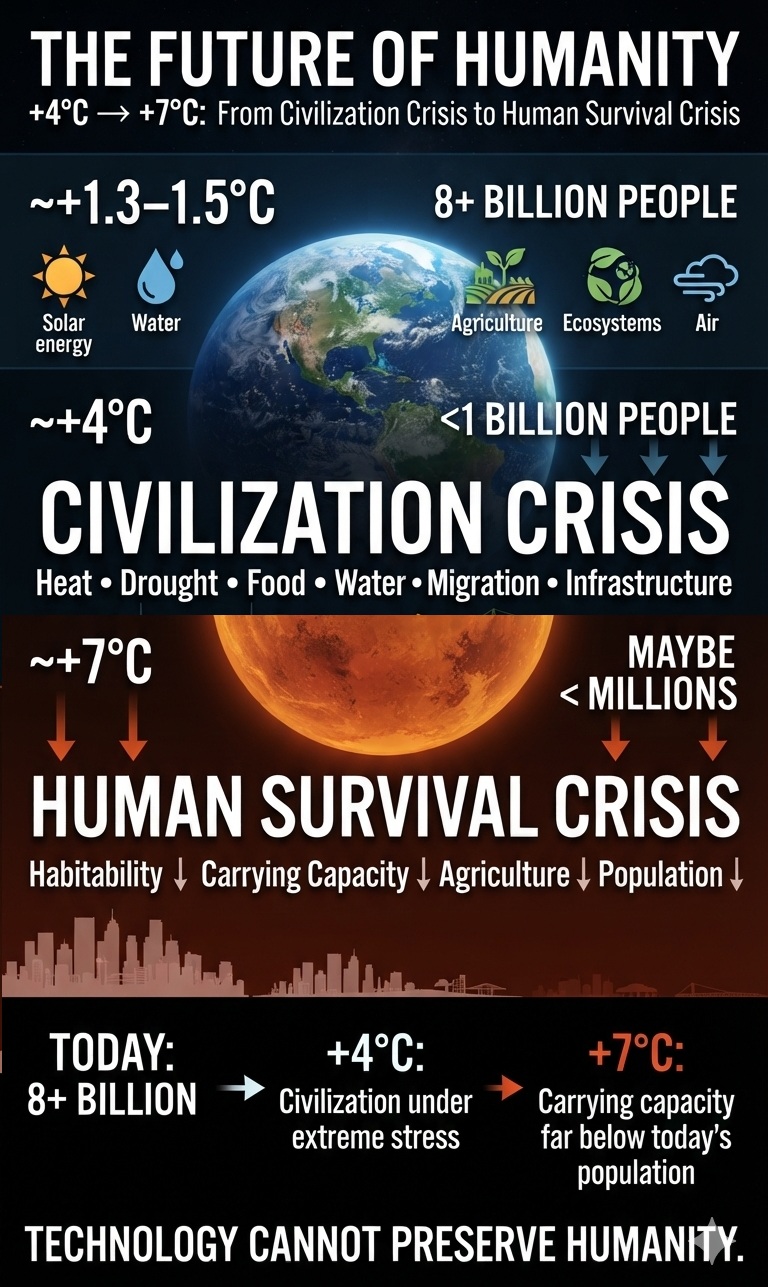
Previous probabilistic projections placed end-of-century warming on a trajectory approaching 2.8°C. Accounting for the combined influence of declining low-level clouds and tropospheric ozone supports a substantially more severe assessment, with warming of approximately 4°C this century representing the trajectory advanced in this analysis.

A 4°C outcome is not simply a more intense version of today’s climate. It represents a fundamental transformation of the conditions supporting human civilization and natural ecosystems.

The Consequences of a 4°C World

Warming of 4°C above pre-industrial levels would impose extraordinary stresses on food production, human habitability, coastlines, global economic systems, and biodiversity. The following risks describe the consequences associated with such a high-warming trajectory.

1. Collapse of Global Food Systems

Extreme heat, prolonged drought, and shifting precipitation patterns threaten agricultural productivity across the world’s major food-producing regions.

  • Simultaneous crop failures: Concurrent failures of wheat, maize, rice, and soybean harvests across multiple continents threaten global food supplies and destabilize international markets.
  • Tropical agricultural losses: Agricultural productivity in tropical and subtropical regions faces declines of up to 50%, undermining food security across major agricultural zones.
  • Marine food-system disruption: Marine heatwaves and ocean acidification damage fisheries and marine ecosystems, threatening a major source of protein for billions of people.

The convergence of agricultural losses and declining marine productivity places global food security under severe systemic pressure.

2. Lethal Heat and Uninhabitable Regions

Extreme heat and humidity threaten human survival across increasingly large areas of the planet.

  • Wet-bulb temperature extremes: Parts of the Middle East, South Asia, Central Africa, and the Amazon face dangerous combinations of heat and humidity. A sustained wet-bulb temperature of 35°C approaches the theoretical upper limit of human heat tolerance under the conditions used to define that threshold.
  • Mass displacement: A large share of the global population faces living conditions outside the historical human climate envelope, driving displacement on a scale involving hundreds of millions of people.

The consequences extend beyond direct heat mortality. Extreme temperatures undermine outdoor labor, public health, infrastructure, water availability, and the viability of entire communities.

3. Irreversible Sea-Level Rise and Coastal Inundation

A 4°C warming trajectory places the major ice sheets under extreme long-term stress and commits the planet to substantial, persistent sea-level rise.

  • Long-term inundation: Sea-level rise of approximately one to two meters by 2100 represents a severe coastal risk under high-warming scenarios. Continued ice-sheet loss commits the planet to much greater sea-level rise over subsequent centuries, with estimates of 10 to 20 meters associated with the most severe long-term outcomes.
  • Threats to major cities: Tokyo, New York, Shanghai, Mumbai, and Lagos, together with low-lying island nations, face escalating coastal inundation, infrastructure destruction, and displacement as sea levels rise.

The long response time of major ice sheets means that the consequences of sustained warming extend far beyond the end of this century.

4. Global Economic and Systemic Collapse

Climate disasters occurring simultaneously across regions place interconnected financial, economic, and political systems under extraordinary strain.

  • Severe economic contraction: High-warming assessments include scenarios involving global economic losses on the order of 30% to 50% by 2100. Losses of this magnitude would exceed the economic disruption associated with the Great Depression.
  • Resource conflicts: Competition over freshwater, fertile land, and other essential resources intensifies as drought expands and mountain glaciers diminish. These pressures increase the risks of geopolitical conflict, displacement, and state failure.

Insurance markets, public infrastructure, food distribution, financial systems, and government budgets face overlapping losses. The scale and interdependence of these impacts threaten the stability of the global economy.

5. Mass Extinction and Biosphere Collapse

Rapid climate disruption forces ecosystems to change faster than many species can adapt or migrate. Habitat loss, extreme heat, drought, wildfire, and ocean warming compound existing pressures on biodiversity.

  • Accelerating extinction risk: Under severe warming, a substantial share of plant and animal species faces extinction risk as habitats disappear or undergo fundamental transformation.
  • Amazon forest dieback: Continued warming, drought, deforestation, and fire intensify the risk of large-scale Amazon forest degradation and transition toward savannah-like ecosystems. The release of stored carbon would reinforce atmospheric warming and further destabilize the climate system.

Biosphere collapse is not an isolated ecological concern. Forests, soils, wetlands, and marine ecosystems regulate carbon storage, water cycles, regional climates, and food webs. Their deterioration weakens the natural systems on which human societies depend.

Conclusion: The Climate Tipping-Point Crisis Is Already Underway

The 1.5°C threshold represents a critical boundary in a climate system already undergoing measurable destabilization. Major ice sheets, Arctic sea ice, permafrost, ocean circulation, forests, and coral reefs are experiencing changes that interact through reinforcing feedbacks.

The danger lies in the coupling of these processes. Individual changes alter the conditions governing other components of the Earth system, creating a cascading response that conventional assessments of isolated climate risks fail to capture fully.

The United States’ retreat from climate commitments adds a major political and economic obstacle to the global response. Rising fossil-fuel emissions, expanding electricity demand, and the weakening of climate safeguards deepen the gap between the scale of the threat and the scale of the response.

Declining low-level clouds and tropospheric ozone further complicate the climate outlook by strengthening warming and undermining natural cooling and carbon-absorption processes. Their combined influence demands serious consideration when evaluating the trajectory toward 4°C of warming this century.

The central conclusion is clear: climate change is not merely a future problem defined by a temperature target. It is an accelerating Earth-system crisis involving interconnected feedbacks, tipping points, ecological disruption, and profound risks to human civilization.

The question is no longer whether climate change is destabilizing the Earth system. The observed evidence establishes that it is. The defining challenge is whether humanity will respond to the scale and speed of that destabilization before cascading consequences become substantially more severe.
bookmark_borderRestricted Insurance Coverage Is Transmitting Climate Risk Through the Financial System

by Daniel Brouse and Sidd Mukherjee

Do you have homeowners insurance? If you answered yes, do you know what is actually covered when climate change and extreme weather damage your property?

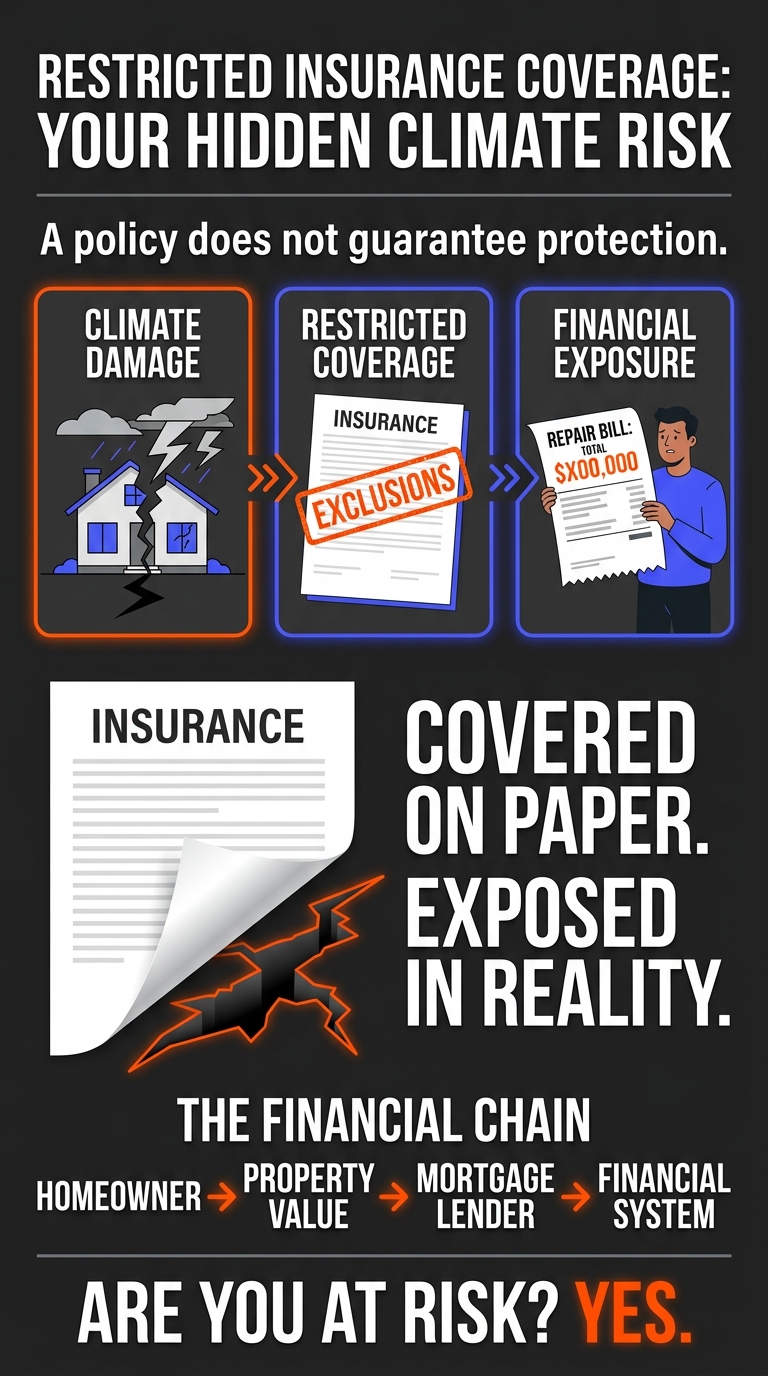
Most homeowners insurance policies exclude major categories of extreme weather damage, including flooding, while coverage for wind, hurricanes, and other hazards may be subject to significant limitations and exclusions. These restrictions are becoming more prevalent, creating one of the most significant emerging systemic risks to the global financial system.

In the United States, roof coverage is a particularly important concern. Many homeowners policies restrict roof-damage compensation through exclusions, depreciation provisions, actual-cash-value settlements, deductibles, or other limitations. Depending on the policy, a homeowner may have little chance of receiving enough compensation for a completely new roof, even when the damage is covered. As wind-related risks and losses intensify, these restrictions can leave homeowners responsible for an increasing share of repair and replacement costs.

The same principle applies to automobile insurance. If a tree is blown onto your car during a severe storm, are you covered? The answer depends on your policy, including whether you carry comprehensive coverage and whether any exclusions or limitations apply.

Climate change is already disrupting insurance markets, and the consequences extend far beyond rising premiums. Insurers are increasing prices, restricting coverage, declining renewals, and withdrawing from markets. These developments are creating growing financial vulnerabilities for homeowners, mortgage lenders, investors, businesses, and governments.

One of the most dangerous—and least understood—parts of this crisis is the expansion of restricted coverage. When an insurer refuses to cover a property, the problem is obvious. When a policy remains in force but excludes important risks, limits payouts, or imposes conditions that leave substantial losses uncovered, the danger is hidden. Homeowners may continue paying premiums believing they are protected, only to discover after a disaster that their policies do not cover the damage they suffered.

This is the delayed-disclosure trap: the financial vulnerability exists before the disaster, but its full consequences may not become apparent until a claim is denied or severely limited. By then, the homeowner may face repair costs, continuing mortgage obligations, and a damaged property without the insurance proceeds expected to cover the loss.

Restricted coverage can therefore undermine property values and mortgage security even when insurance remains available. A property may appear insured on paper while carrying substantial uninsured exposure. As these gaps widen, the distinction between having an insurance policy and having adequate financial protection has become increasingly important.

These developments are part of a larger system of interconnected feedbacks. Climate-related losses drive insurance costs higher and encourage insurers to limit their exposure. Higher costs and narrower protection weaken housing affordability and can depress property values. Declining property values and inadequate coverage increase financial risks for lenders and investors. When private insurance retreats, more costs shift to homeowners, businesses, and governments. These additional burdens can weaken the financial resources needed to prevent, withstand, and recover from future climate-related losses.

The central finding is that this feedback crisis is already underway. Rising premiums, insurance withdrawals, coverage restrictions, and growing exposure to uninsured losses are observable market developments. The interactions among these forces create additional risks that can reinforce one another, extending climate-related financial stress well beyond the locations directly affected by disasters.

The ultimate danger is not simply that insurance becomes more expensive. It is that insurance increasingly fails to provide the protection that households, lenders, and financial markets depend on. As this happens, climate risk has become a broader housing, credit, and economic crisis.

The Feedback Crisis Has Already Begun

The Whistleblower Warning: A Campaign to Expand Restricted Coverage

A memo by insurance-industry whistleblowers documents a disturbing development: the insurance industry is already well underway in what the whistleblowers characterize as a subversive campaign to expand restricted coverage, shifting financial risks onto homeowners without their full awareness.

The significance of this warning cannot be overstated. The expansion of restricted coverage changes the nature of the insurance crisis. The problem is no longer limited to rising premiums, canceled policies, or insurers refusing to cover high-risk properties. It also involves the erosion of protection within policies that homeowners continue to purchase and rely upon.

When insurers restrict coverage through exclusions, payout limitations, depreciation provisions, and other policy conditions, they can reduce their own exposure while transferring a greater share of potential losses to policyholders. When those restrictions are not adequately understood by homeowners, the transfer of risk can occur without a corresponding understanding of the financial consequences.

This creates a fundamental imbalance. Homeowners continue paying premiums and may reasonably believe they have protection against major property losses. Yet the actual terms of their policies may leave them responsible for substantial costs following a disaster. The gap between perceived protection and actual coverage can remain hidden until a claim is denied or the insurance payment falls far short of the amount needed to repair or replace damaged property.

The whistleblower warning therefore adds a critical dimension to the delayed-disclosure trap. Financial exposure is not simply increasing because climate-related disasters are becoming more costly. It is also increasing because the insurance protection intended to absorb those losses is being restricted, potentially without homeowners fully recognizing the changes.

The systemic consequences extend beyond individual households. Mortgage lenders may hold collateral whose owners cannot adequately insure or repair it. Investors may underestimate the uninsured exposure embedded in real estate portfolios. Communities may face declining property values and a growing burden of unrecoverable losses. When private insurance transfers more risk to homeowners, the resulting costs do not disappear. They are redistributed through household finances, mortgage markets, lending institutions, businesses, and ultimately, in some circumstances, governments and taxpayers.

This is the critical distinction: an insurance policy can remain active while the financial protection it provides deteriorates. Consequently, policy counts and insurance availability alone can understate the growth of climate-related financial risk.

The whistleblower allegations point to the need for scrutiny not only of insurance prices and market withdrawals, but also of how coverage restrictions are introduced, disclosed, and enforced. Regulators and policymakers must examine whether homeowners can readily understand the risks they are assuming, whether policy changes are adequately communicated, and whether the actual protection provided remains consistent with reasonable expectations.

If the documented practices are as extensive as the whistleblowers contend, the expansion of restricted coverage represents more than an insurance-market adjustment. It is a mechanism through which climate-related financial risk is being transferred to households while remaining largely concealed from homeowners, lenders, investors, and the broader financial system.

That makes restricted coverage a particularly dangerous link in the climate feedback crisis. The physical risk can increase, the financial protection can weaken, and the resulting vulnerability can remain hidden until a disaster exposes the full extent of the loss.

The Protection Gap Is a Critical Link in the Climate Feedback Crisis

The climate-insurance crisis is already unfolding. Rising premiums, restricted coverage, nonrenewals, and insurer withdrawals are changing the financial risks associated with property ownership. These are not merely forecasts of what might happen in a warmer future. They are observable developments whose economic consequences are already being felt.

Restricted coverage deserves particular attention because it can conceal financial exposure rather than eliminate it. When a policy excludes an increasingly important hazard, limits the amount payable, or imposes conditions that prevent a full recovery, the homeowner may remain exposed even while paying for insurance. The inadequacy of that protection may not become apparent until a disaster triggers a claim.

This delayed disclosure creates a dangerous mismatch between perceived security and actual financial resilience. Homeowners may believe their properties are protected. Mortgage lenders may assume that required insurance adequately safeguards their collateral. Investors may underestimate the exposure embedded in real estate portfolios. Yet a property with substantial uninsured risk can suffer serious financial damage even when an insurance policy remains active.

The consequences can reinforce one another. Climate-related damage increases insurance losses. Insurers respond through higher premiums, tighter policy terms, exclusions, and withdrawals. These changes increase ownership costs and expose homeowners to losses they cannot readily absorb. Property values and mortgage security can weaken, while financial distress, defaults, repair costs, and public financial obligations may rise. Governments and taxpayers can then inherit a larger share of the burden.

The feedback does not end there. When households, businesses, lenders, and governments must devote more resources to recovering from losses, fewer resources may remain available for risk reduction, resilience, and adaptation. If that shortfall leaves communities more vulnerable to subsequent disasters, future losses can grow, further intensifying insurance-market stress and financial instability.

This is the feedback mechanism at the heart of the crisis: climate risk increases financial vulnerability, and financial vulnerability is making society less capable of managing the next climate-related loss.

The appropriate response must therefore go beyond monitoring premiums and counting policy cancellations. Regulators, insurers, lenders, and policymakers need to examine what policies actually cover, how exclusions are changing, whether coverage limits remain adequate, and how much risk is being transferred to households and the public. Insurance availability alone is not a sufficient measure of financial protection.

The evidence establishes the need to take the observed disruption seriously and to investigate how its interacting effects are evolving. The precise scale and timing of future financial consequences remain uncertain, but the underlying feedback mechanisms are already visible. Waiting for the full consequences to emerge would mean waiting until hidden financial exposures become actual losses.

The critical question is no longer simply whether homeowners can obtain insurance. It is whether the insurance they can obtain will actually protect them when disaster strikes. As restricted coverage expands, the gap between insured property and adequately protected property has become one of the most consequential—and least visible—channels through which climate change destabilizes the economy.

Insurance can redistribute financial losses, but it cannot eliminate the physical risks that generate them. When those risks undermine the financial systems that support property ownership, lending, and investment, climate change becomes a systemic economic problem.

The insurance feedback crisis has already begun. Whether it remains manageable or develops into much broader financial instability depends on how quickly society recognizes these connections, exposes hidden coverage gaps, and acts to reduce the underlying risks.

bookmark_borderInsurance, Housing, Credit, and the Global Economy

by Daniel Brouse and Sidd Mukherjee

The Insurance Feedback Crisis: Climate Change Is Already Destabilizing Housing, Credit, and the Global Economy

How Rising Costs, Restricted Coverage, and Insurance Withdrawals Are Transmitting Climate Risk Through the Financial System

October 2026

Introduction

Climate change is already disrupting insurance markets, and the consequences extend far beyond rising premiums. Insurers are increasing prices, restricting coverage, declining renewals, and withdrawing from some markets. These developments are creating a growing financial vulnerability for homeowners, mortgage lenders, investors, businesses, and governments.

One of the most dangerous—and least understood—parts of this crisis is the expansion of restricted coverage. When an insurer refuses to cover a property, the problem is obvious. When a policy remains in force but excludes important risks, limits payouts, or imposes conditions that leave substantial losses uncovered, the danger is hidden. Homeowners may continue paying premiums believing they are protected, only to discover after a disaster that their policies do not cover the damage they suffered.

This is the delayed-disclosure trap: the financial vulnerability exists before the disaster, but its full consequences may not become apparent until a claim is denied or severely limited. By then, the homeowner may face repair costs, mortgage obligations, and a damaged property without the insurance proceeds expected to cover the loss.

Restricted coverage can therefore undermine property values and mortgage security even when insurance remains available. A property may appear insured on paper while carrying substantial uninsured exposure. As these gaps widen, the difference between having an insurance policy and having adequate financial protection becomes increasingly important.

These developments are part of a larger system of interconnected feedbacks. Climate-related losses drive insurance costs higher and encourage insurers to limit their exposure. Higher costs and narrower protection weaken housing affordability and property values. Reduced property values and inadequate coverage increase financial risks for lenders and investors. When private insurance retreats, more costs shift to homeowners, businesses, and governments. Those added burdens can weaken the financial resources needed to adapt to future climate risks.

The central finding is that this feedback crisis is already underway. Rising premiums, insurance withdrawals, coverage restrictions, and growing exposure to uninsured losses are observable market developments. The interactions among these forces are creating additional risks that can reinforce one another, extending climate-related financial stress well beyond the locations directly affected by disasters.

The ultimate danger is not simply that insurance becomes more expensive. It is that insurance increasingly fails to provide the protection that households, lenders, and financial markets depend on. When that happens, climate risk can become a broader housing, credit, and economic problem.

1. The Crisis Is Already Underway

For years, the economic consequences of climate change were discussed primarily in terms of future damage: projected disaster losses, future insurance costs, declining property values, and the possibility that some regions would eventually become uninsurable.

That framing is increasingly inadequate.

In vulnerable markets, insurance premiums have already risen sharply, coverage has become more restrictive, and some insurers have stopped writing new policies or withdrawn from particular areas. Property owners are confronting higher deductibles, policy nonrenewals, and fewer affordable alternatives. Public insurance programs have assumed greater importance in some jurisdictions where private coverage has become difficult to obtain.

These are present market developments, not merely projections.

Their significance extends beyond the insurance industry. Insurance is part of the financial infrastructure supporting property ownership, mortgage lending, commercial investment, and infrastructure development. When that infrastructure becomes more expensive or less accessible, the effects propagate into other sectors.

The emerging pattern is therefore not simply:

Climate change → More expensive disasters.

It is:

Climate change → Physical losses → Insurance disruption → Financial stress → Reduced economic resilience → Greater vulnerability to subsequent losses.

The final stages of this chain can feed back into the original problem. Households with fewer financial resources have less capacity to improve their properties. Municipalities under fiscal pressure have less flexibility to invest in protective infrastructure. Businesses facing higher insurance and borrowing costs may defer resilience investments.

The result is a system in which the costs of climate change can make society less capable of absorbing the next climate-related shock.

The insurance market is already exposing this vulnerability.

2. The Industry Is Warning About the Same Systemic Mechanism

The October 14, 2026, memorandum Sounding the Alarm, published by Inside Track x (Re)Insurance, describes concerns reported by senior professionals in the UK and European insurance, reinsurance, and brokerage sectors.

The memo identifies three principal responses to increasing physical risk:

  1. Higher premiums as insurers attempt to price expected losses and uncertainty.
  2. Restricted coverage as insurers narrow the risks they will accept.
  3. Market withdrawal when exposure cannot be made commercially viable.

All three responses are already familiar features of stressed insurance markets.

An insurer can reduce its own exposure by refusing to renew a policy. A reinsurer can protect its capital by increasing prices or reducing capacity. An underwriting department can improve its financial position by avoiding properties it considers too risky.

But none of these decisions removes the physical hazard.

Instead, the financial responsibility moves elsewhere. Homeowners retain more risk. Businesses absorb higher costs. Lenders face greater uncertainty about collateral. Governments confront greater pressure to support disaster recovery and provide insurance alternatives.

This creates a structural conflict between the financial stability of individual institutions and the financial stability of the broader economy.

The memo also warns that commercial incentives, limitations in catastrophe modeling, and fragmented assessments of exposure can prevent the industry from fully recognizing systemic risk.

The central warning reinforces an increasingly important conclusion: conventional risk management can protect individual institutions without adequately protecting the economic system in which they operate.

Restricted Coverage

Insurance is caught in a delayed-disclosure trap. When a homeowner cannot obtain coverage, the problem is immediately apparent. But an equally serious—and less visible—risk is the growing restriction of coverage. Policies may contain exclusions, limitations, and coverage gaps buried in the fine print, leaving homeowners exposed to losses they believe are insured. As insurers respond to rising risks and losses, these restrictions are expanding. The danger often becomes clear only after a disaster, when homeowners discover that their policies do not cover the damage. By then, it is too late to obtain the protection they thought they had.

3. The First Feedback Loop: Physical Losses Drive Insurance Disruption

The initial feedback begins with physical climate risk.

Flooding, wildfire, severe storms, extreme heat, and other hazards can damage buildings, interrupt businesses, destroy infrastructure, and increase claims. The consequences depend on the hazard, location, exposure, and vulnerability of the assets involved.

As insurers experience losses or revise their expectations of future losses, they adjust prices and coverage.

The initial sequence is direct:

Physical risk increases → Expected losses or uncertainty increase → Premiums rise and coverage tightens.

This relationship is already reflected in insurance-market decisions.

The feedback becomes more consequential when higher premiums and restricted coverage affect the financial viability of the properties being insured.

Insurance is not merely another household expense. It is part of the cost of maintaining property, satisfying mortgage requirements, operating a business, and attracting investment.

When insurance costs increase faster than household income or business revenue, the resulting financial pressure can become difficult to absorb. When suitable coverage disappears altogether, the problem changes from affordability to insurability.

The original physical risk has now produced a financial consequence that can persist even after a particular disaster ends.

A homeowner whose property survives a storm may still face a higher renewal premium. A business that escapes direct damage may still experience higher insurance costs. A community that avoids a catastrophic event may nevertheless face market repricing as insurers reassess its exposure.

This is the first critical transition: climate risk is no longer expressed exclusively through damage after a disaster. It is increasingly expressed through the cost and availability of financial protection before the next disaster occurs.

4. The Second Feedback Loop: Insurance Costs Pressure Property Values

Property values depend on more than a building’s physical condition and location. They also depend on the expected costs of ownership, the availability of financing, and the risks associated with future use.

Insurance disruption affects all three.

When premiums rise, the total cost of owning a property increases. When deductibles rise or coverage becomes less comprehensive, owners retain more potential financial loss. When insurers withdraw, buyers may have difficulty obtaining the coverage required by lenders or may have to accept more expensive alternatives.

These conditions can weaken demand for exposed properties.

The resulting feedback is:

Higher insurance costs → Higher ownership costs → Reduced affordability and buyer demand → Downward pressure on property values.

The process is already evident in the way insurance availability has become a growing consideration in real-estate transactions and property-risk assessments. Its magnitude varies by market, and a premium increase alone does not prove that property values have declined. But the economic mechanism is straightforward.

A property can lose economic value without suffering new physical damage. If buyers anticipate years of higher insurance costs, recurring flood losses, or difficulty obtaining a mortgage, they may be willing to pay less for it.

This creates a new form of climate-related financial exposure: the risk that the cost of protecting an asset undermines the value of owning it.

The implications are substantial because residential property represents a major share of household wealth. Commercial property supports business operations, employment, and investment. Property values also contribute to local tax revenues.

As insurance-related affordability problems spread, the consequences can extend beyond individual property owners into household balance sheets, commercial activity, and municipal finance.

5. The Third Feedback Loop: Property Risk Becomes Credit Risk

Mortgage lending depends on borrowers’ ability to repay their loans and on the value of the assets securing those loans.

Insurance supports both sides of that arrangement. It protects against specified losses that could impair collateral, while its premiums form part of the borrower’s ongoing cost of ownership. As insurance becomes more expensive or less available, both protections can weaken.

Higher premiums increase the monthly cost of homeownership. For financially constrained borrowers, that additional expense can reduce the ability to meet mortgage payments and other obligations. At the same time, inadequate coverage can leave a property owner and lender more exposed to the financial consequences of damage. If insurance difficulties reduce property demand or values, the collateral securing outstanding loans may also weaken.

The resulting feedback is:

Insurance disruption → Higher ownership costs and greater retained losses → Mortgage stress and weaker collateral → Increased credit risk.

The systemic concern is concentration. If insurance affordability deteriorates across a large number of properties in the same region, the financial consequences can occur together. Lenders may face correlated risks rather than isolated borrower problems. That possibility is particularly important where local economies, property tax revenues, employment, and household wealth are heavily dependent on real estate.

The risk is already being transmitted into financing decisions where insurance availability affects property transactions and underwriting. The connection between insurance and credit is established. The growing importance of climate-related insurability makes that connection increasingly consequential.

6. The Fourth Feedback Loop: Reinsurance Can Amplify Market Stress

Reinsurance provides financial protection to insurance companies against large or concentrated losses. It helps primary insurers manage their exposures and maintain the capacity to write policies. But reinsurance is itself exposed to catastrophe risk.

When reinsurers reassess expected losses or uncertainty, they may increase prices, change coverage terms, reduce available capacity, or require primary insurers to retain more risk. Primary insurers then face additional financial pressure. They may raise premiums, tighten underwriting, reduce policy limits, or withdraw from markets where acceptable returns cannot be achieved.

The feedback is:

Higher catastrophe losses or uncertainty → Reinsurance pressure → Higher primary-insurance costs or reduced capacity → Less affordable and less available coverage → Greater financial exposure outside the insurance system.

This process can spread the effects of physical risk beyond the location where a disaster occurs. An insurer’s response depends on its portfolio, reinsurance contracts, capital position, and exposure to multiple regions. The important point is that reinsurance does not eliminate catastrophe risk. It redistributes that risk through another layer of the financial system. If multiple insurers and reinsurers simultaneously reassess similar exposures, their decisions can reinforce market-wide tightening.

The October 2026 memo’s concern about interconnected risk is particularly relevant here. A firm may manage its own exposures prudently while the combined decisions of many firms reduce the capacity available to the wider economy.

The memo reinforces the need to monitor the relationship between physical losses, reinsurance costs, primary-market availability, and the financial resources available to absorb future losses.

7. The Fifth Feedback Loop: Public Intervention Transfers Costs to Taxpayers

As private insurance becomes unaffordable or unavailable, governments face growing pressure to intervene.

Public responses can include insurance programs of last resort, disaster assistance, infrastructure repairs, emergency housing, subsidized mitigation, and other forms of financial support.

Such measures can protect households and communities from immediate hardship. They can also preserve economic activity when private insurance capacity is insufficient. But they do not eliminate the physical losses. They redistribute part of the cost to public budgets.

The resulting feedback is:

Insurance withdrawal → Greater uninsured exposure → Increased demand for public support → Higher public expenditure and contingent liabilities → Greater fiscal pressure.

If the same communities repeatedly experience damaging events, governments may face recurring costs rather than a single temporary emergency. Meanwhile, the underlying economic base may weaken. Property values can come under pressure, businesses can suffer interruptions, and residents may relocate or reduce spending. These changes can reduce local revenues just as the need for public spending increases. The resulting fiscal squeeze is a direct consequence of the interaction between physical risk and financial vulnerability.

It is already visible in the expanding importance of public insurance and disaster-recovery arrangements in some exposed markets. The long-term fiscal consequences will depend on the scale of future losses, policy design, tax capacity, and the effectiveness of adaptation.

The danger is that public intervention can become a substitute for reducing underlying risk. If subsidies keep vulnerable properties insured without improving their resilience, governments may accumulate liabilities while leaving the physical exposure largely unchanged.

A sustainable response must therefore combine financial assistance with measures that reduce expected losses.

8. The Sixth Feedback Loop: Financial Stress Can Reduce Resilience

The preceding mechanisms reveal a more troubling feedback: the financial consequences of climate risk can reduce the capacity to manage future climate risk.

Consider a household facing higher premiums, a larger deductible, and rising repair costs. It may have less money available to install flood protection, replace a vulnerable roof, improve drainage, or strengthen the property against future damage.

Consider a municipality facing repeated disaster-recovery expenses and declining property revenues. It may have less capacity to upgrade stormwater infrastructure, maintain protective systems, or invest in long-term resilience.

Consider a business facing higher insurance and borrowing costs. It may delay investments that would otherwise reduce its exposure to future hazards.

The resulting feedback is:

Climate losses → Higher financial costs → Reduced capacity for adaptation → Greater vulnerability to subsequent losses.

This is a critical transition from a sequence of separate financial problems to a self-reinforcing system.

The original hazard creates damage or increases expected losses. Those losses generate financial pressure. Financial pressure constrains adaptation. Reduced adaptation leaves assets more exposed to future hazards. The next event then encounters a system that may be less prepared than before.

This mechanism is not merely theoretical. The financial constraints on households, municipalities, and businesses are real, and the need to pay for insurance and recovery competes with the need to invest in resilience.

9. The Combined Feedback System Is More Dangerous Than Any Individual Effect

The six feedbacks are interconnected.

Higher physical losses can raise insurance and reinsurance costs. Higher insurance costs can weaken property affordability. Reduced affordability can affect demand and financing. Weaker property values can increase credit risk and undermine local tax revenues. Public intervention can shift losses to taxpayers. Financial pressure can then reduce the resources available for adaptation.

These are not independent problems. They form a connected system in which stress in one sector can reinforce stress elsewhere.

The combined mechanism can be represented as follows:

Climate-related physical losses

↓

Higher insurance and reinsurance costs; restricted coverage and withdrawals

↓

Higher property ownership costs and greater uninsured exposure

↓

Weaker affordability, property demand, and financing conditions

↓

Increased mortgage vulnerability and public financial pressure

↓

Reduced resources for adaptation and recovery

↓

Greater vulnerability to future losses

The final step closes the feedback loop.

The significance is that the total economic effect can exceed the direct cost of any individual disaster. Financial interactions can prolong losses, transmit them to unaffected sectors, and weaken the capacity to recover. This is why insurance-market stress deserves attention as a systemic economic warning rather than simply an industry problem.

It also explains why waiting for an insurer or a major bank to fail would be the wrong approach. Financial instability can develop through declining affordability, reduced coverage, weaker investment, and growing public liabilities long before a dramatic institutional failure occurs.

The feedbacks do not need to culminate in a global financial collapse to cause substantial economic damage. They are already imposing persistent costs on households, businesses, and governments.

10. Why the 2008 Financial Crisis Is a Warning

The October 2026 industry memo compares the potential consequences of widespread uninsured property risk with vulnerabilities associated with the 2008 mortgage-market crisis. The comparison is useful because it highlights how problems involving property and credit can spread through interconnected financial relationships.

The 2008 crisis involved mortgage underwriting failures, excessive leverage, complex financial instruments, and weaknesses in financial oversight. Climate-related insurance disruption has a different underlying driver: changing physical risk and the difficulty of financing assets exposed to that risk.

The important similarity is the transmission mechanism. In both cases, problems involving the value, financing, or risk assessment of property can extend into lending and broader financial markets.

Climate-related insurance disruption can undermine property finance if coverage becomes unavailable, ownership costs rise sharply, or collateral values weaken. If these developments occur across many regions simultaneously, they could contribute to a broader financial shock.

The lesson is to recognize interconnected vulnerabilities before they become acute. Regulators and financial institutions should not wait for widespread defaults to begin evaluating how insurance-market disruption could affect lending, collateral, and public finance.

11. What the Evidence Already Shows

Observed developments

Insurance markets in several exposed regions are experiencing higher premiums, coverage restrictions, nonrenewals, and insurer withdrawals. Public insurance and disaster-assistance arrangements are increasingly important in some markets. Insurance availability is also an increasingly significant factor in property transactions and financial risk assessment.

These developments establish that insurance-market stress is already occurring.

Established economic mechanisms

Insurance costs affect property ownership expenses. Coverage requirements influence mortgage financing. Property values affect collateral. Reinsurance influences primary-market capacity. Public disaster spending affects government budgets.

These relationships provide a sound basis for evaluating how insurance disruption can transmit financial pressure across the economy.

Emerging systemic feedbacks

The interaction of insurance costs, property affordability, mortgage exposure, public liabilities, and reduced adaptation capacity creates a credible pathway toward self-reinforcing economic stress.

Uncertain outcomes

The crisis is already observable in its component parts. The systemic danger is that those parts can reinforce one another faster than institutions respond.

12. The Policy Response Must Address the Feedbacks, Not Just the Symptoms

The appropriate response is not simply to subsidize insurance premiums or require insurers to maintain coverage regardless of risk.

Those measures may provide temporary relief, but they cannot eliminate physical hazards. If they suppress risk signals without reducing exposure, they may encourage continued investment in vulnerable locations and transfer increasingly large liabilities to taxpayers.

A more effective response must address the causes and interactions of the feedback system.

Reduce the underlying physical risk

Greenhouse gas emissions influence long-term warming and many associated hazards. Reducing emissions limits additional future climate risk, although it cannot prevent all near-term losses.

Mitigation must be accompanied by adaptation because significant physical risks already exist.

Improve the resilience of exposed assets

Building standards, flood protection, drainage improvements, wildfire mitigation, resilient infrastructure, and risk-informed land use can reduce expected losses.

Investments should be evaluated against transparent estimates of their costs, benefits, maintenance requirements, and remaining exposure.

Where protection is not physically or economically sustainable, policymakers must consider fair and orderly relocation rather than assuming every property can be protected indefinitely.

Monitor the entire financial transmission chain

Regulators should examine insurance affordability and availability alongside mortgage performance, property values, reinsurance capacity, bank exposure, and public liabilities.

Stress tests should include scenarios in which insurance markets tighten across multiple regions at the same time.

The objective should be to identify correlated exposure before it generates substantial financial losses.

Improve catastrophe-model transparency

Insurers and reinsurers should clearly disclose material assumptions and uncertainties in their risk assessments. Independent review should investigate credible concerns about commercial pressure, inadequate data, and the underestimation of changing hazards.

The goal is to ensure that decisions reflect defensible estimates of risk rather than incentives to understate it.

Protect vulnerable households without concealing risk

Public support may be necessary to prevent immediate hardship and preserve access to essential coverage. But support should be linked, where appropriate, to mitigation, stronger building practices, and realistic assessments of long-term exposure.

A policy that preserves coverage without reducing the underlying risk defer costs rather than solve the problem.

13. Conclusion: The Feedback Crisis Has Already Begun

The Protection Gap Is a Critical Link in the Climate Feedback Crisis

The climate-insurance crisis is already unfolding. Rising premiums, restricted coverage, nonrenewals, and insurer withdrawals are changing the financial risks associated with owning property. These are not merely forecasts of what might happen in a warmer future. They are observable developments whose economic consequences are already being felt.

Restricted coverage deserves particular attention because it can conceal financial exposure rather than eliminate it. When a policy excludes an increasingly important hazard, limits the amount payable, or imposes conditions that prevent a full recovery, the homeowner may remain exposed even while paying for insurance. The inadequacy of that protection may not become apparent until a disaster triggers a claim.

This delayed disclosure creates a dangerous mismatch between perceived security and actual financial resilience. Homeowners may believe their properties are protected. Mortgage lenders may assume that required insurance adequately safeguards their collateral. Investors may underestimate the exposure embedded in real estate portfolios. Yet a property with substantial uninsured risk can suffer serious financial damage even when an insurance policy remains active.

The consequences can reinforce one another. Climate-related damage increases insurance losses. Insurers respond through higher premiums, tighter terms, exclusions, and withdrawals. Those changes increase ownership costs and expose homeowners to losses they cannot readily absorb. Property values and mortgage security can weaken, while defaults, repair costs, and public financial obligations may rise. Governments and taxpayers can then inherit a larger share of the burden. If these pressures reduce the resources available for prevention and adaptation, future losses can become even greater.

This is the feedback mechanism at the heart of the crisis: climate risk increases financial vulnerability, and financial vulnerability can make society less capable of managing the next climate-related loss.

The appropriate response must therefore go beyond monitoring premiums and counting policy cancellations. Regulators, insurers, lenders, and policymakers need to examine what policies actually cover, how exclusions are changing, whether coverage limits remain adequate, and how much risk is being transferred to households and the public. Insurance availability alone is not a sufficient measure of financial protection.

The evidence establishes the need to take the observed disruption seriously and to investigate how its interacting effects are evolving. The precise scale and timing of future financial consequences remain uncertain, but the underlying feedback mechanisms are already visible.

The critical question is no longer simply whether homeowners can obtain insurance. It is whether the insurance they can obtain will actually protect them when disaster strikes. As restricted coverage expands, the gap between insured property and adequately protected property may become one of the most consequential—and least visible—channels through which climate change destabilizes the economy.

Insurance can redistribute financial losses, but it cannot eliminate the physical risks that generate them. When those risks undermine the financial systems that support property ownership, lending, and investment, climate change becomes a systemic economic problem.

The feedback crisis has already begun. Whether it remains manageable or develops into much broader financial instability depends on how quickly society recognizes the connections and acts to reduce the underlying risks.


References and Further Reading

Primary industry source

Inside Track x (Re)Insurance. (October 14, 2026). Sounding the Alarm: Insurance and Reinsurance Memo.

https://static1.squarespace.com/static/697b3c8cf1bdde2c6ff1b5d5/t/6acebb5992f73c3954b746e5/1791933273139/Insurance+and+Reinsurance+Memo.pdf

This memo provides the principal industry perspective on physical risk, insurance repricing, coverage restrictions, market withdrawal, catastrophe modeling, and systemic financial vulnerability. Its findings should be interpreted in light of its aggregated and anonymized methodology.

Related research

Brouse, D., and Mukherjee, S. Climate Change and the Insurance Crisis: Rising Costs, Shrinking Availability, and the Limits of Insurability.

https://www.kingarthur.com/global_warming/Insurance-Cost-and-Availability.html

Brouse, D., and Mukherjee, S. Climate Change and Insurance: Costs, Availability, and Sustainability.

https://www.kingarthur.com/global_warming/Insurance-Cost-and-Availability-2025.html

Brouse, D., and Mukherjee, S. The Collapse Point: How Climate Change Is Breaking Insurance—and Capitalism With It.

https://www.kingarthur.com/global_warming/Insurance-Economic-Climate-Collapse.html

Brouse, D., and Mukherjee, S. Climate Risk, Insurance Market Instability, and Systemic Threats to Capital Formation.

https://www.kingarthur.com/global_warming/Insurance-Collapse-intro.html

Brouse, D. Financial Planning for Climate Change.

https://www.kingarthur.com/global_warming/Financial-Planning-for-Climate-Change.html

Brouse, D., and Mukherjee, S. Coupled Climate Feedbacks and Cascading Real Estate Risk.

https://www.kingarthur.com/global_warming/Feedbacks-Cascading-Real-Estate-Risk.html

Methodological note

This paper synthesizes an industry memorandum, related climate-insurance research, and established economic mechanisms. It does not present a new statistical model or independently estimate the probability of a global financial crisis. Claims about observed insurance-market disruption are distinct from claims about the magnitude of interconnected feedbacks or the timing of future systemic outcomes. Those latter questions require continued empirical investigation using insurance, reinsurance, property, credit, and public-finance data.

bookmark_borderThe Great Deceiver: Donald Trump, Christian Nationalism, the End Times, and the Moral Responsibility to Protect Humanity

By Daniel Brouse

Introduction: Faith, Science, and Political Accountability

I’m a fiscally conservative Republican economist who has been registered Republican since 1980. I also hold a degree in philosophy, with a concentration in morals and ethics, and have studied Christianity extensively, including reading the Bible in depth multiple times.

My family lineage can be traced to the Tribe of Judah and the family of Jesus. I’ve spent decades studying eschatology, particularly the biblical significance of my given name, Daniel, and the subject of the End Times. I’ve also conducted an extensive examination of the Book of Revelation.

Although I generally keep my religious beliefs separate from my scientific work, I’ve been analyzing Donald Trump’s conduct since the 1990s. My conclusions are informed by decades of economic analysis, moral philosophy, scientific research, and biblical study.

This paper brings those perspectives together to examine a question that extends beyond ordinary partisan politics: What happens when political power, religious certainty, deception, and disregard for human consequences converge?

My argument is that Trump’s conduct deserves serious scrutiny not because he is necessarily the literal Antichrist described in biblical prophecy, but because his political actions, public statements, and alliances raise profound moral questions about deception, authoritarianism, environmental destruction, Christian nationalism, and the treatment of vulnerable human beings.

1. My First Moral and Ethical Assessment of Trump

During the 1990s, I conducted a moral and ethical experiment involving Trump’s publicly traded business interests in the context of a widows-and-orphans fund.

Of all the businesses examined in that study, Trump’s was the only one in which I concluded that funds intended for widows and orphans had been stolen.

That experience left a lasting impression on my assessment of his character. It also established a personal foundation for my subsequent examination of Trump’s business practices, public conduct, and political career.

The conclusion was not based on whether I liked his personality, agreed with his politics, or approved of his business ambitions. It arose from an assessment of conduct against a moral standard: how people and institutions behave when entrusted with resources that affect others, particularly vulnerable people.

That distinction remains fundamental. Wealth, power, popularity, and claims of religious conviction do not exempt anyone from moral accountability.

2. The Great Deceiver: A Decade of Dangerous Consequences

Over the past decade, I’ve watched Trump develop into what I consider the Great Deceiver: a politician whose repeated falsehoods have undermined public trust, public health, and public safety.

His conduct during COVID-19, his rejection of climate science, and his decisions affecting foreign aid have contributed to consequences that, in my assessment, include millions of needless deaths. These actions belong in any serious examination of large-scale human suffering and crimes against humanity.

The term “Great Deceiver” is my moral and political characterization of Trump’s conduct. I use it deliberately because deception is not merely a personal failing when practiced by someone wielding enormous political power. It can shape public behavior, distort the understanding of reality, undermine institutions, and influence decisions affecting millions of lives.

During a public health emergency, misinformation can interfere with efforts to protect people. When a political leader repeatedly dismisses established scientific evidence, the consequences can extend beyond rhetoric into policy and public behavior. When decisions affect humanitarian assistance, the consequences can reach people who have little control over the political decisions that determine whether they receive help.

Climate change presents an equally serious moral problem. Rejecting established climate science and obstructing effective responses can increase risks to public health, food security, infrastructure, ecosystems, and future generations.

On September 23, 2025, Trump addressed the United Nations General Assembly and called climate change “the greatest con job ever perpetrated on the world.” This was a public and unmistakable expression of his rejection of mainstream climate science and international climate action. Source: Reuters, September 23, 2025.

These are not simply disagreements over the details of environmental policy. They concern the consequences of dismissing an extensive body of scientific evidence while exercising power over decisions that affect the lives of others.

The moral question is straightforward: When a political leader’s statements and decisions contribute to preventable suffering, what responsibility does that leader bear?

That question deserves examination regardless of party affiliation.

3. Is Trump the Antichrist?

Regarding the Antichrist, I agree with one part of the argument made by those who believe the figure described in biblical prophecy will be difficult to recognize: I don’t believe Trump is literally the Antichrist described in Scripture.

But that conclusion does not eliminate my concerns about his conduct or the movements he supports.

The concern is that Trump is helping advance political and religious movements that could bring about catastrophic consequences under the banner of Christianity. I see a dangerous convergence of Christian Zionism, white nationalism, and authoritarian politics, alongside an alarming relationship between elements of the Trump political network and the broader Epstein scandal.

The distinction matters. One can reject the claim that a political leader is literally the Antichrist while still examining whether that leader’s actions embody forms of deception, hypocrisy, cruelty, or destructive ambition that religious teachings warn against.

Biblical discernment should not be reduced to identifying a single individual who matches a prophetic description. It should also involve examining conduct, motives, consequences, and the treatment of other people.

A person can invoke God, Scripture, and Christian identity while pursuing policies that contradict the ethical principles those beliefs are supposed to uphold.

The question is not simply whether Trump fits a particular interpretation of Revelation. It is whether Christians are applying their moral teachings consistently when evaluating him.

4. Christian Zionism, Biblical Prophecy, and the War With Iran

The connection between Christian Zionism and Trump’s foreign policy deserves particular scrutiny.

Support for Israel among evangelical Christians is not exclusively theological; it also reflects strategic, cultural, historical, and political considerations. However, for some Christian Zionist constituencies, support for Israel is tied to specific interpretations of biblical prophecy and the End Times.

When prophetic expectations become intertwined with decisions about war, the consequences can extend far beyond theology.

The concern is that religious interpretations of history and prophecy can become entangled with political calculations in ways that make military escalation appear divinely justified or historically inevitable. When that happens, the ordinary requirements of foreign policy—evidence, strategic judgment, proportionality, diplomacy, and consideration of human consequences—risk being subordinated to a narrative of prophetic destiny.

The Trump administration’s confrontation with Iran in 2026 has intensified these concerns. The United States and Israel launched strikes against Iran in February 2026, and the conflict subsequently developed into a prolonged confrontation. The administration’s handling of the war has raised questions about its strategic objectives, its exit strategy, and the economic and human costs. Source: Reuters, October 8, 2026.

The relationship among the Trump administration, Christian Zionist organizations, and the war raises serious questions about the relative influence of American national interests, military strategy, religious prophecy, and domestic political pressures.

There is also a political contradiction within Trump’s coalition. An America First constituency has opposed prolonged foreign entanglements, while influential evangelical constituencies support policies toward Israel that some understand through a biblical, prophetic framework.

These positions are not necessarily irreconcilable, and Christian Zionists do not all share one interpretation of prophecy or one position on military action. Nevertheless, the tension deserves examination.

The concern is that the language of Christianity can be used to justify political decisions whose consequences include war, suffering, displacement, and death. A policy does not become morally defensible simply because its supporters attach religious meaning to it.

If religious conviction is influencing decisions about war, then those convictions must be examined alongside the evidence, strategic objectives, and human consequences of the decisions themselves.

5. The Epstein Scandal and the Ideology of Human Worth

The Epstein scandal raises additional questions about the ideological environment surrounding powerful political, financial, and social networks.

Publicly released statements attributed to Jeffrey Epstein include arguments that increased atmospheric carbon dioxide benefits plants and that climate change could serve as a mechanism for reducing overpopulation. Other statements attributed to him express disturbing views about executing elderly and infirm people and make racist claims about African music and learning.

These statements, if accurately represented in their original context, reveal a worldview in which human lives can be evaluated according to their perceived usefulness, with some people effectively treated as expendable.

That is the kind of thinking that raises concerns about eugenics, ecofascism, and a grotesque version of survival of the fittest.

The issue is not simply whether someone disputes climate policy or believes that population growth creates environmental pressures. It is the moral distinction between addressing environmental problems in ways that protect human dignity and treating human suffering or death as a desirable means of achieving an ideological objective.

Recognizing that distinction is essential.

The term “ecofascism” refers to the danger of combining authoritarian power, hierarchical judgments about human worth, and environmental or population arguments that rationalize unequal human survival. It is a warning about an ideological pattern, not a claim that every person skeptical of climate policy subscribes to that worldview.

Similarly, statements attributed to Epstein do not, by themselves, establish that Trump personally shares every belief expressed in them. My concern is the broader environment in which extreme wealth, political influence, racial hierarchy, authoritarianism, and disregard for environmental threats can intersect.

The questions are legitimate and serious: What values are being promoted? Whose lives are being treated as expendable? And what happens when people with immense resources and influence begin to regard some populations as less deserving of protection than others?

These questions belong in any serious examination of the moral consequences of concentrated power.

6. Deception, Political Loyalty, and the Surrender of Moral Judgment

This is why term “Great Deceiver” relevant.

Deception does not have to look like a mysterious biblical figure who charms everyone. It can also operate through political loyalty, religious certainty, propaganda, and the conviction that one’s own side is incapable of wrongdoing.

A leader need not persuade everyone. It may be enough to maintain the loyalty of a sufficiently committed group that interprets every criticism as persecution, every contradiction as a conspiracy, and every failure as someone else’s fault.

Under those conditions, evidence can lose its ability to change minds. Political identity becomes more important than independent judgment, and loyalty becomes a substitute for evaluating facts.

This creates a serious moral danger within religious communities. When a political leader claims to represent Christian values, supporters may be tempted to defend the leader rather than assess whether the leader’s conduct actually reflects those values.

But Scripture demands more than declarations of faith. It calls for discernment about character, conduct, hypocrisy, truthfulness, compassion, justice, and the treatment of the vulnerable.

Merely claiming Christian values does not demonstrate that a person practices them.

The fundamental problem with Trump’s most devoted followers is when they appear unwilling to apply the same moral standards to their political leader that they would apply to anyone else. When evidence conflicts with political loyalty, the evidence is dismissed and loyalty becomes a substitute for judgment.

That is not faith. It is the surrender of independent moral reasoning.

A meaningful moral standard must be applied consistently. If dishonesty is wrong when practiced by political opponents, it is also wrong when practiced by a political ally. If cruelty is unacceptable when directed at people we care about, it does not become acceptable when directed at people we dislike. If Scripture is a source of moral authority, it cannot be invoked selectively to excuse the behavior of a favored leader.

The test of conviction is not how fiercely we defend our own side. It is whether we remain willing to recognize wrongdoing when doing so is uncomfortable.

7. Beyond Trump: The Larger Crisis of Human Responsibility

The problem is much deeper than Trump or any political party.

Political corruption, institutional failure, disinformation, environmental destruction, and the exploitation of vulnerable people cannot be explained by one individual alone. They emerge from broader systems of incentives, beliefs, power, and social behavior.

But recognizing the larger problem does not absolve individuals of responsibility for their own conduct.

Trump’s influence matters precisely because political leaders can amplify existing problems, normalize behavior that was once considered unacceptable, and use institutional power to make harmful decisions consequential on a much larger scale.

The same principle applies to religious institutions, corporations, governments, and individuals. No institution should be exempt from scrutiny because it claims a noble purpose. No political movement should be immune from criticism because it presents itself as the defender of a particular faith or national identity.

The challenge is to develop standards of accountability that do not depend on political affiliation, religious identity, wealth, or social status.

That requires a willingness to examine evidence, challenge deception, protect the vulnerable, and recognize the consequences of our choices.

It also requires resisting the temptation to turn every disagreement into a battle between absolute good and absolute evil. Serious moral analysis demands both conviction and intellectual honesty. Strong conclusions should be accompanied by evidence, and evidence should not be dismissed merely because it threatens a cherished belief.

The objective is not to replace one form of blind allegiance with another. It is to restore the capacity for independent moral judgment.

8. The Covenant of Balance: An Interfaith Alternative

The following paper takes a constructive approach to these problems:

The Covenant of Balance: An Interfaith Synthesis of Ecological Ethics, Economics, Climate Science, Earth’s Energy Imbalance, and Integrated Climate Stewardship

https://www.kingarthur.com/global_warming/Covenant-of-Balance.html

The paper examines Christianity, Islam, Judaism, Buddhism, and Hinduism, identifying shared ethical principles of responsibility, compassion, moderation, stewardship, and avoiding needless harm. It connects those principles with climate science, economic accountability, and practical action.

The premise is simple: We do not need to share one religion, one political philosophy, or one interpretation of Scripture to recognize that our actions have consequences for other people and the living world.

Christianity offers teachings on creation care, stewardship, and love of neighbor. Islam emphasizes Mīzān, or balance, and responsible trusteeship. Judaism includes bal tashchit, the principle of avoiding needless destruction and waste. Buddhism highlights interdependence, compassion, and mindful consumption. Hinduism offers ethical resources through dharma, responsibility, and minimizing harm.

These traditions are distinct, and their adherents do not agree on every environmental or political question. Yet they offer meaningful grounds for cooperation around the protection of human life, the reduction of suffering, responsible resource use, and the preservation of the conditions that sustain future generations.

The paper also connects these ethical principles to Earth’s physical energy imbalance and the consequences of climate change.

Its practical framework is Integrated Climate Stewardship:

ZERO-OUT + BENEFIT-IN

ZERO-OUT means reducing actual sources of environmental harm. BENEFIT-IN means creating tangible improvements in affordability, efficiency, resilience, comfort, and quality of life while protecting the ecological systems on which we depend.

This approach seeks to unite moral responsibility with measurable results. It recognizes that environmental stewardship must extend beyond declarations of concern to practical decisions by households, businesses, institutions, and governments.

The same principle applies to political and religious life. Good intentions and declarations of faith are not sufficient. Our conduct must be evaluated according to its consequences for other people and the world we share.

The Covenant of Balance is an invitation to move beyond divisions that prevent cooperation. We can disagree about theology while working together to reduce suffering. We can hold different political beliefs while insisting on truthfulness and accountability. We can approach the natural world through different ethical traditions while recognizing our common dependence on its physical and ecological systems.

My objective is to find common ground among people of different faiths and beliefs so we can work together for the common good.

9. The Moral Test: Separating the Sheep From the Goats

If we’re going to talk about separating the sheep from the goats, perhaps we should begin by applying the same standards of truth, morality, compassion, and accountability to our own political leaders that we claim to find in Scripture.

Religious language should not function as a shield against scrutiny. Claims of divine purpose should not exempt political decisions from moral examination. And the authority of Scripture should not be used selectively to condemn opponents while excusing the conduct of political allies.

The deeper question is whether our beliefs make us more willing to confront wrongdoing or more determined to defend it when it comes from our own side.

A genuine commitment to truth requires the courage to examine uncomfortable evidence. A genuine commitment to morality requires consistency. A genuine commitment to compassion requires concern for people beyond our immediate community. And a genuine commitment to stewardship requires responsibility for the consequences of our actions.

These standards should apply to everyone, including presidents, religious leaders, corporations, political movements, and ordinary citizens.

Identifying the literal Antichrist is not the most urgent task facing humanity. The more immediate responsibility is to recognize deception, resist the misuse of religious authority, challenge destructive ideologies, protect vulnerable people, and hold those in power accountable for their conduct.

The danger is not confined to one political party, one religion, or one individual. It lies in the human capacity to rationalize wrongdoing when it serves our interests, confirms our beliefs, or strengthens our allegiance to a leader.

That is why the work of moral discernment matters.

Conclusion: Faith Should Sharpen Our Judgment

This perspective comes from decades of studying economics, moral philosophy, Christianity, eschatology, and the physical systems that sustain life. Although I generally keep my religious beliefs separate from my scientific work, I see no contradiction in examining the moral consequences of political decisions through both ethical and scientific frameworks.

I do not believe Trump is literally the Antichrist described in biblical prophecy. Nevertheless, I believe his conduct, his rejection of climate science, his approach to public health and foreign policy, and his relationship with political and religious movements raise profound questions about deception, responsibility, and the consequences of concentrated power.

My assessment of Trump as the Great Deceiver reflects my judgment of his conduct and its consequences. It is not a substitute for examining the evidence, and it should not be treated as a claim that every legal or historical question surrounding his actions has already been resolved.

But neither should the seriousness of those questions be diminished by political loyalty or religious identification.

If we are concerned about deception, we must examine the behavior of those who claim to defend the truth. If we are concerned about the End Times, we must not neglect the suffering and dangers unfolding in the present. If we claim to follow Christian values, we must evaluate our conduct and our leaders against the moral responsibilities those values entail.

And if we recognize that humanity faces threats extending beyond politics—including climate change, ecological disruption, and the consequences of destructive economic systems—we must be willing to cooperate across religious and ideological boundaries.

We do not have to agree on every theological question to agree that human life matters, deception should be challenged, vulnerable people deserve protection, and the Earth must be preserved for future generations.

My hope is that people of different faiths and beliefs can find common ground in these responsibilities and act together for the common good.

The ultimate test is not whether we can convincingly claim to stand on the side of God, country, or a particular political movement. It is whether our actions reflect truth, justice, compassion, and responsibility.

Faith should sharpen our moral judgment, not blind us to reality.

bookmark_borderHow Is Climate Energy Hitting You? Disruption in Penn’s Sylvania

by Daniel Brouse

Pennsylvania’s forests are being disrupted by accelerating seasonal expansion—the lengthening of warm-season conditions into spring and autumn. The change is doing more than making individual days warmer. It is altering the timing of tree life cycles, increasing ecological vulnerabilities, and shifting which species can successfully survive and reproduce.

As summer-like conditions expand into early spring and late autumn, biological events known as phenology are increasingly occurring outside the historical weather conditions to which Pennsylvania’s forests evolved.

The result is a cascade of ecological disruptions.

1. The “False Spring” Trap

Warmer late winters and early springs can trigger tree activity prematurely.

The process:
Early warmth stimulates sap flow and causes trees to break dormancy and open their buds earlier than their historical timing.

The impact:
When freezing temperatures return, newly developed leaves, flowers, and fruit are vulnerable to frost damage. The result can be severe losses to both natural vegetation and agriculture.

Pennsylvania experienced a striking example during the spring 2026 freeze, when unusually early-season warmth was followed by sharp freezes. Some Pennsylvania orchards reported losses of 70% to 90% for certain fruit crops.

The problem is not simply that spring is warmer. It is that spring is becoming less predictable relative to the biological clocks of trees.

2. Disrupted Fall Foliage Cycles

The expansion of summer-like heat into September and October can delay or disrupt the transition to autumn.

The process:
Trees respond to shortening day length and cooler temperatures by reducing chlorophyll production. The resulting chemical changes produce the familiar autumn colors.

The impact:
When unusually warm conditions persist, particularly when combined with late-summer drought, trees can remain under prolonged heat and water stress.

Instead of a gradual transition from green to brilliant autumn colors, stressed foliage may turn brown, shrivel, or drop prematurely.

Pennsylvania’s famous fall foliage season can therefore become shorter, less synchronized, and more variable from year to year.

3. Pests and Pathogens Thrive

Shorter, milder winters combined with longer, warmer summers can create more favorable conditions for many forest pests.

The eastern hemlock (Tsuga canadensis)—Pennsylvania’s official state tree—is particularly vulnerable. The invasive hemlock woolly adelgid has devastated hemlock populations throughout the eastern United States. Warmer conditions can increase winter survival and permit the insect to expand into areas where historically colder conditions provided greater limitations.

The emerald ash borer presents another example. This invasive beetle has killed millions of ash trees across North America, including Pennsylvania’s native ash species. Longer warm seasons can accelerate insect development and increase the number of generations that can occur during a year.

Climate energy therefore interacts with existing biological threats: warming does not have to create a pest or pathogen to make the damage worse—it can make an existing threat more effective.

4. Shifting Forest Demographics

As Pennsylvania’s growing season lengthens and temperatures rise, the climatic conditions suitable for different tree species are shifting.

The result is not an overnight replacement of Pennsylvania forests. Instead, the competitive balance among species can gradually change as seedlings establish, mature trees experience increasing stress, and disturbances create opportunities for different species to expand.

In some locations, Pennsylvania’s forests may increasingly favor species associated with warmer regions, while cool-adapted species face greater stress.

Cool-Loving Species Under Greater StressHeat-Tolerant or More Adaptable Species
Sugar mapleRed oak
American beechWhite oak
Yellow birchChestnut oak
Eastern hemlockHickories
Other northern hardwoodsSome southern Appalachian species

The transition will vary considerably by elevation, soil, moisture, latitude, and local microclimate. Forest composition is therefore likely to change unevenly across the Commonwealth rather than shifting uniformly from one species group to another.

The Larger Pattern

These changes are interconnected.

Earlier spring → premature growth → late-freeze vulnerability

Longer summer → heat and drought stress → weakened trees

Milder winter → greater pest survival → increased forest damage

Warmer autumn → delayed or disrupted dormancy → altered foliage cycles

Repeated stress → changing regeneration → shifting forest composition

Pennsylvania’s forests are adapted to seasonal variation. The emerging problem is that the seasons themselves are changing.

Climate energy is reaching Pennsylvania’s forests not simply as higher temperatures, but as changes in timing, duration, intensity, and ecological relationships.

The forest that future generations inherit may therefore look different from the forest Pennsylvania has known for centuries—not because one species suddenly disappears, but because the entire system is being gradually reorganized.

The seasons are moving. The forest is responding.

bookmark_borderThe Future of Humanity: +4°-7°C

by Daniel Brouse

Introdution

🌎 THE FUTURE OF HUMANITY

+4°C → +7°C: From Civilization Crisis to Human Survival Crisis

What happens to humanity if Earth doesn’t stop at +2°C or +3°C—but eventually reaches +4°C and then +7°C?

There is no scientifically established population number for a +7°C Earth.

But the physical constraints are becoming increasingly clear.

At approximately +4°C, humanity could face a civilization-scale crisis:

🔥 Extreme heat
💧 Water shortages
🌾 Agricultural disruption
🏙️ Infrastructure failures
🌍 Mass migration
⚡ Energy-system stress

Over the following centuries, continued warming toward +7°C could transform the question entirely.

The issue would no longer be simply:

How do we adapt civilization to a hotter planet?

It becomes:

How many humans can the planet physically support?

Technology could keep some people alive through underground facilities, controlled environments, hydroponic agriculture, protective equipment and advanced energy systems.

But there is an enormous difference between keeping thousands or millions of people alive in artificial environments and maintaining a civilization of 8+ billion people.

Today’s population depends upon the Earth providing enormous services essentially for free:

☀️ Solar energy
💧 Rainfall and freshwater
🌾 Productive soils
🌳 Ecosystems
🌬️ Breathable air
🌊 Functioning oceans
🌡️ Manageable temperatures
🌱 Outdoor agricultural space

At +7°C, humanity could increasingly have to manufacture artificially what the Earth currently provides naturally.

And that creates a fundamental problem:

Energy requires infrastructure.
Infrastructure requires materials.
Materials require mining and manufacturing.
Manufacturing requires energy and water.

Technology can extend human habitability.

But technology cannot be assumed to recreate the Earth for eight billion people.

The path from +4°C to +7°C could therefore represent a transition from:

Fighting to preserve civilization

to

Fighting to preserve humanity itself.

The Future of Humanity: +4°-7°C

The most likely scenario is for the planet to warm approximately 4°C by 2150, with the potential for +7°C over the longer term.

That raises an unavoidable question:

How many humans could survive on a planet that is +7°C warmer than the preindustrial Earth?

There are no official, peer-reviewed demographic consensus figures projecting an exact human population at +7°C of global warming. A +7°C scenario lies far beyond the temperature range of conventional climate projections for this century, so mainstream climate models do not provide a precise population forecast for such a world.

That does not mean the consequences are unknowable.

Scientists can examine the physical limits of human habitability, agricultural production, water availability, ecosystem function, infrastructure, energy requirements, and planetary carrying capacity. Taken together, these factors point toward a potentially catastrophic contraction of human population.

1. Planetary Carrying Capacity Could Fall Below One Billion

Climate scientists have previously addressed the question of Earth’s carrying capacity under extreme warming.

Hans Joachim Schellnhuber, former director of the Potsdam Institute for Climate Impact Research, has stated that at approximately +4°C, Earth’s sustainable carrying capacity could fall below one billion people.

At +7°C, the situation would be vastly more hostile.

The implied carrying capacity could therefore be a small fraction of today’s eight billion people. Under extreme-risk scenarios, humanity could potentially be reduced to a few million survivors concentrated in the remaining habitable regions, including high-latitude areas and highly protected technological environments.

There is no peer-reviewed demographic model establishing a precise population at +7°C. The absence of such a number should not be confused with evidence that the current population could be maintained.

The fundamental issue is carrying capacity.

A planet capable of supporting more than eight billion people under today’s climatic conditions does not necessarily retain that capacity after the climate system has been pushed several additional degrees beyond the historical range.

2. Physical Limits of Human Habitability

The most fundamental constraint is not economics.

It is thermodynamics.

Sherwood and Huber’s 2010 study examined the physiological limits imposed by extreme combinations of temperature and humidity. Their work established the importance of the 35°C wet-bulb temperature threshold as an approximate upper limit for human heat dissipation under extreme conditions.

At a wet-bulb temperature of 35°C, the human body can no longer effectively shed metabolic heat to the surrounding environment.

Even a healthy, hydrated, unclothed person resting in the shade with adequate air movement eventually becomes unable to maintain a safe core temperature.

A global warming level approaching +7°C would create regions in which these extreme combinations of heat and humidity become increasingly common.

The regions affected would include large portions of the tropics and subtropics, the Middle East, parts of Asia, and other heavily populated regions. This is not simply a matter of discomfort. At sufficiently high heat and humidity, the human body physically loses the ability to cool itself. Protective technology can delay the problem. It cannot eliminate the underlying thermodynamic limit.

3. Abrupt Carrying-Capacity Collapse

Population collapse does not require every human being to suddenly reach a temperature at which survival becomes impossible. It can occur when the systems supporting civilization cross critical thresholds. Mathematical population models have examined what happens when environmental carrying capacity suddenly declines because of severe environmental crises.

One such study published in Chaos, Solitons & Fractals modeled a hypothetical situation in which Earth’s sustainable carrying capacity abruptly fell to approximately two billion people. When carrying capacity suddenly becomes lower than the existing population, the model produces an extremely rapid population decline.

The population can fall by half within only a few decades. This is important because climate change does not operate as a single-variable problem. A collapse in agricultural production can cause food shortages. Food shortages can produce price shocks and famine. Famine can produce migration. Migration can produce political instability. Political instability can disrupt energy production and transportation. Energy shortages can further reduce agricultural production.

The resulting system is nonlinear.

Once multiple critical systems begin failing simultaneously, population decline can accelerate dramatically.


Earth Today vs. Earth at +7°C

MetricCurrent Era (~1.3–1.5°C)Potential Earth at +7°C
Global population~8.3 billionUnquantified, but potentially reduced to hundreds of millions or less
Human climate nicheMost humans live within a relatively narrow range of climatic conditionsLarge regions experience temperatures and humidity increasingly hostile to human survival
AgricultureGlobalized and heavily dependent on predictable climate, water, fertilizers and energySevere disruption of traditional outdoor agriculture, particularly in the tropics and mid-latitudes
Food productionPrimarily solar-powered outdoor agricultureIncreasing dependence on artificial environments and technologically controlled agriculture
WaterLarge-scale freshwater systems support cities and agricultureIncreasing drought, heat, evaporation and competition for water
Outdoor laborPossible across most populated regionsIncreasingly restricted by dangerous heat and humidity
InfrastructureDesigned around the historical climateIncreasingly stressed by extreme heat, storms, drought, flooding and water shortages
Primary mortality risksAging, disease, accidents and conventional disastersHeatstroke, famine, water shortages, disease, conflict and systemic infrastructure failure
CivilizationNatural ecosystems provide enormous life-support servicesIncreasing portions of the natural life-support system must be artificially replaced

Ultimately, a +7°C world is not simply a difficult demographic scenario.

It represents an extreme threat to the carrying capacity of Earth and to the technological civilization that currently supports billions of people.


Why Couldn’t Humans Simply Adapt?

A reasonable question is:

Why couldn’t humans simply adapt?

Why not wear protective clothing or cooling suits?

Why not live underground?

Why not grow hydroponic food?

Why not build artificial environments and maintain the current population?

Humans are extraordinarily adaptable.

Technology already allows small populations to survive in environments that would otherwise be extremely hostile.

Humans live in Antarctica.

Humans operate submarines.

Humans live in deserts.

Astronauts survive in space.

The problem is not whether technology can keep some humans alive.

The problem is whether technology can sustain eight billion humans in artificial environments after the natural environment has become hostile to large-scale civilization.

That creates fundamental bottlenecks involving energy, materials, infrastructure, maintenance, food production and thermodynamics.


1. The Hydroponic Energy Paradox

To feed eight billion people entirely indoors, humanity would have to replace much of the free energy currently supplied by the Sun. Traditional agriculture obtains solar energy directly. Millions of square kilometers of agricultural land receive sunlight without humanity having to manufacture the photons.

Indoor agriculture changes the equation. Artificial lighting must be produced. Water must be pumped. Nutrients must be circulated. Temperature and humidity must be controlled. Carbon dioxide must be managed. Air must be circulated. Crops must be harvested. The systems must be maintained continuously.

The Scale

Feeding eight billion people entirely indoors would require an enormous quantity of electricity for lighting, climate control, pumping, ventilation, automation and food processing.

The energy requirement would be many times greater than the amount of energy currently available to the human race for ordinary food production and could approach or exceed the scale of the entire existing global energy system depending on the crops and technologies used.

And food is not merely calories.

Humanity requires carbohydrates, proteins, fats, vitamins, minerals, animal feed, oils and a tremendous diversity of agricultural products.

The Catch-22

If that additional energy comes from fossil fuels, the energy system accelerates climate warming.

If it comes from renewable energy, enormous quantities of solar panels, wind turbines, transmission lines, batteries and other infrastructure must be manufactured and maintained.

If it comes from nuclear energy, enormous quantities of reactors, fuel-cycle infrastructure, cooling systems, transmission systems and industrial capacity must be maintained.

In every case, the artificial food system becomes dependent upon an enormous industrial infrastructure.

And that infrastructure itself must survive a +7°C world.


2. Environmental Degradation of Critical Machinery

Humanity cannot run a global civilization strictly from underground. Resources must still be extracted from the surface. Minerals must be mined. Construction materials must be manufactured. Energy systems must be maintained. Transportation systems must operate. Food-production systems require machinery. Factories require workers. The coolant problem becomes increasingly important. Mechanical and industrial systems must ultimately reject waste heat. Power plants, industrial equipment, refrigeration systems, data centers and other large-scale machinery rely on heat-transfer systems.

As surrounding air and water become hotter, the temperature difference available for rejecting heat becomes smaller. Cooling therefore becomes increasingly difficult and energy intensive. The problem is not that every machine instantly stops working at +7°C.

The problem is that the amount of energy and infrastructure required to keep machines operating rises while the surrounding civilization is simultaneously being subjected to increasing environmental stress.

Protective Suits

Humans can wear cooled protective suits or specialized thermal equipment. Such equipment can allow people to work temporarily in environments that would otherwise be dangerous.

But the suits require:

  • electricity
  • cooling
  • air filtration
  • communications
  • maintenance
  • replacement parts
  • charging
  • trained personnel

A protective suit can keep an individual alive.

It cannot make the surface environment normal.

It cannot eliminate the need to mine resources, maintain roads, operate ports, manufacture machinery, repair electrical grids, produce food and maintain global supply chains.

A civilization in which workers can safely operate outdoors only for limited periods becomes fundamentally different from today’s civilization.


3. The Enormous Resource Footprint of Underground Civilization

Housing eight billion people underground would require the largest engineering project in human history. Thousands of subterranean cities would have to be constructed.

The required quantities of:

  • concrete
  • steel
  • copper
  • electrical equipment
  • ventilation equipment
  • pumps
  • elevators
  • water systems
  • sewage systems
  • air filtration
  • cooling systems
  • power generation
  • energy storage
  • communications
  • transportation
  • food-production equipment

would be enormous.

Excavating underground cities would itself require enormous quantities of energy and heavy machinery. Concrete production would add another major industrial burden. The systems would also require continuous maintenance.

Ventilation and Air

An underground population of billions would require enormous systems for:

  • supplying breathable air
  • removing carbon dioxide
  • controlling humidity
  • filtering pollutants
  • managing waste
  • maintaining pressure
  • controlling temperature

A single systemic failure in an underground city’s ventilation or power system could produce immediate mass casualties.

The larger and more interconnected the system becomes, the greater the consequences of systemic failure.


4. Underground Civilization Still Depends on the Surface

Moving underground does not eliminate dependence on the natural world.

An underground civilization would still need:

Energy.

Energy requires power plants and transmission systems.

Minerals.

Minerals require mining.

Food.

Food requires agriculture or industrial food-production systems.

Water.

Water must be obtained, transported and treated.

Machinery.

Machines require factories, raw materials and replacement parts.

Human labor.

Workers must maintain the systems.

Waste disposal.

Waste must be processed and ultimately incorporated into material cycles.

Therefore, an underground civilization would not actually be independent of the surface.

It would be more dependent on a functioning industrial system.


5. The Psychological and Biological Reality

Human beings are not genetically adapted to live permanently inside completely artificial environments.

Humans evolved within complex natural ecosystems under natural cycles of sunlight, darkness, temperature, seasons, atmospheric conditions, microbial exposure and biological diversity.

A completely artificial environment would impose enormous psychological and biological stresses.

Long-term confinement, artificial lighting, restricted environments, isolation and separation from natural ecosystems create substantial physiological and psychological challenges.

The problem extends beyond human psychology.

Natural ecosystems provide services that artificial systems would have to replace:

  • water purification
  • decomposition
  • nutrient cycling
  • pollination
  • soil formation
  • carbon storage
  • atmospheric regulation
  • biological pest control

The more completely humans isolate themselves from the natural environment, the more of these services must be replaced technologically.

Every replacement system requires energy and maintenance.


6. The Fundamental Problem: Scale

This is the central issue.

Technology could undoubtedly allow a sliver of humanity to survive conditions that would otherwise be fatal.

A few million highly organized people living in underground facilities, protected environments or high-latitude regions could potentially survive conditions under which conventional civilization could not.

The problem is maintaining eight billion people.

There is an enormous difference between:

keeping a few thousand people alive in Antarctica

and

maintaining billions of people inside an artificial global biosphere.

The first has already been demonstrated.

The second has not.

The eight-billion-person civilization exists because the planet provides enormous quantities of environmental services essentially for free. The Sun provides energy. Rain provides water. Soils grow crops. Oceans regulate heat. Forests and wetlands process water and carbon. Natural ecosystems recycle nutrients. The atmosphere provides breathable air. Outdoor agriculture converts sunlight into food without humanity having to construct the entire system artificially.

A +7°C Earth would place increasing portions of those services under extreme stress.

Humanity could replace some of them.

Replacing all of them, for eight billion people, indefinitely is a completely different problem.


The Catch-22 of Technological Survival

The technological solution creates its own dependency chain:

Climate warming

↓

Natural systems become less reliable

↓

Artificial systems replace natural services

↓

Artificial systems require enormous amounts of energy

↓

Energy systems require enormous industrial infrastructure

↓

Industrial infrastructure requires mining, water, transportation and stable ecosystems

↓

Those systems are themselves damaged by climate change

↓

Maintenance becomes increasingly difficult

↓

Artificial life-support systems become increasingly vulnerable

This is the fundamental problem.

Technology does not eliminate environmental carrying capacity.

It extends it by using energy and resources.

But the energy and resources required to extend carrying capacity become increasingly difficult to obtain as the planetary environment deteriorates.


The Real Question

The real question is therefore not:

“Can a human being survive +7°C?”

A human can survive an extraordinary range of environments with sufficient technology.

The real question is:

“Can eight billion humans maintain a technologically advanced global civilization on a planet that is +7°C warmer?”

That is an entirely different question.

The answer depends on whether enough food, water, energy, materials, infrastructure and habitable space remain available to support the enormous interconnected system required to maintain billions of people.

At +7°C, every one of those requirements becomes more difficult.

And the problems interact. Food shortages affect political stability. Political instability affects energy production. Energy shortages affect water systems. Water shortages affect agriculture. Agricultural failures affect food supplies. Infrastructure failures affect everything.

The result is a coupled nonlinear system in which multiple simultaneous stresses can produce consequences far larger than any individual stress alone.


Summary of the Collapse

The path to a +7°C world does not require humanity to suddenly jump from today’s climate into an uninhabitable planet.

It can happen progressively.

The first major threshold is approximately +4°C of global warming over the next century.

At +4°C, humanity would still exist in enormous numbers. Civilization would still operate. Technology would still function. Many regions would remain habitable. But the environmental conditions supporting today’s eight-billion-person civilization would be profoundly degraded. Agriculture would face increasing heat and drought. Freshwater supplies would become increasingly stressed. Extreme heat would restrict outdoor labor across large regions. Coastal regions would face accelerating sea-level rise.

Ecosystems would be increasingly disrupted. Food production, water systems, energy infrastructure and transportation would become increasingly vulnerable to compound climate extremes.

The result would not necessarily be the immediate collapse of civilization.

It would be the beginning of a progressive contraction in Earth’s effective carrying capacity. And +4°C would not necessarily be the end of the warming process.

If greenhouse-gas emissions, climate feedbacks and Earth-system changes continue to push the planet beyond +4°C, warming could continue over the following centuries toward +7°C or more.

That changes the problem fundamentally.

At +7°C, the issue is no longer simply whether humanity can adapt its agriculture, infrastructure and cities to a warmer climate. The issue becomes whether the Earth can continue to provide the environmental foundation required to support billions of people at all.

Technology would undoubtedly allow some portion of humanity to survive a +7°C world. Highly protected underground facilities, high-latitude settlements, artificial environments, hydroponic agriculture, protective equipment and advanced energy systems could preserve human life under conditions that would otherwise be lethal. But that does not demonstrate that eight billion people could be sustained.

The current population of approximately eight billion is supported by a planetary system that provides enormous services essentially for free:

  • solar energy
  • rainfall
  • productive soils
  • natural ecosystems
  • breathable air
  • functioning oceans
  • manageable temperatures
  • outdoor agricultural space
  • natural water cycles
  • global biological productivity

At +4°C, humanity would increasingly struggle to maintain those services.

At +7°C, humanity could increasingly be forced to manufacture them.

Air would have to be conditioned.

Water would have to be increasingly purified and transported.

Food would increasingly require controlled environments.

Temperature would have to be artificially regulated.

Nutrients would have to be recycled.

Natural ecosystem services would increasingly have to be replaced by industrial systems.

The resource and energy requirements would become enormous. And every artificial replacement creates another dependency.

Energy requires infrastructure. Infrastructure requires materials. Materials require mining and manufacturing. Manufacturing requires energy and water. Energy and water systems depend upon functioning infrastructure and ecosystems.

The result is a civilization increasingly dependent upon an industrial system that is itself operating under increasingly hostile environmental conditions.

This creates a fundamental progression:

Today → +4°C → +7°C

Stable planetary support → severely degraded planetary support → radically reduced planetary carrying capacity

At approximately +4°C, the central problem becomes maintaining civilization under extreme environmental stress.

At approximately +7°C, the central problem becomes maintaining humanity itself at anything approaching today’s population.

The transition would not necessarily be smooth. Climate systems, ecosystems, food systems and human societies are nonlinear. Carrying capacity can decline gradually for a time and then fall rapidly when multiple thresholds are crossed.

A decline in agricultural productivity can trigger food shortages. Food shortages can trigger migration. Migration can destabilize political systems. Political instability can disrupt energy and transportation systems. Energy failures can disrupt water and food production. Those failures can further reduce carrying capacity.

The process can therefore become a positive feedback loop of environmental degradation and societal contraction.

A +7°C world could produce a catastrophic contraction in human carrying capacity, potentially reducing the population by billions.

The exact surviving population cannot be known in advance.

It could be hundreds of millions.

It could be far lower.

Under extreme technological survival scenarios, only a small fraction of today’s population could remain. The critical point is not the precise number.

The critical point is that the carrying capacity of a +7°C Earth could be radically below the population that exists today.

And that creates an important distinction between the next century and the centuries that follow.

The +4°C world is a civilization-scale crisis.

The +7°C world could become a human-survival crisis.

Humanity does not merely inhabit the planet.

Human civilization is a product of the planet’s environmental stability.

The civilization supporting eight billion people was built within a remarkably narrow range of climatic conditions. Push the planet several degrees beyond that range and humanity must increasingly substitute technology for the natural systems that made civilization possible in the first place.

Technology can preserve pockets of humanity. Technology can extend human habitability.

Technology cannot be assumed to reproduce the entire Earth system for eight billion people.

The path from +4°C to +7°C therefore represents more than another three degrees of warming.

It represents a potential transition from adapting civilization to a changing planet to attempting to manufacture an artificial planet capable of sustaining humanity.

That is the ultimate carrying-capacity problem.

At +4°C, humanity may be fighting to preserve civilization.

At +7°C, humanity may be fighting to preserve humanity itself.

bookmark_borderHOW IS CLIMATE ENERGY HITTING YOU? The First Law of Thermodynamics

by Daniel Brouse

The First Law of Thermodynamics and the Redistribution of Earth’s Excess Energy

Energy Cannot Be Created or Destroyed

The principle that energy cannot be created or destroyed is known as the Law of Conservation of Energy, or the First Law of Thermodynamics. In simple terms, the total energy within an isolated system remains constant. Energy can change form, move from one place to another, or be stored in different components of the system—but it does not simply disappear.

That principle provides a powerful way to understand today’s changing climate.

Since the beginning of the Industrial Revolution, human activities have fundamentally altered Earth’s energy balance by increasing concentrations of greenhouse gases in the atmosphere. These gases reduce the rate at which infrared energy escapes to space, leaving the climate system with a persistent energy imbalance.

The result is not simply a warmer atmosphere.

The additional energy is being redistributed throughout the Earth system—primarily into the oceans, but also into the atmosphere, land, ice, and biosphere. On the scale of the entire climate system, the accumulated excess energy is enormous: hundreds of zettajoules. One zettajoule (ZJ) is equal to one sextillion joules:

1 ZJ = 1,000,000,000,000,000,000,000 joules

And the rate of accumulation has accelerated dramatically in recent decades. The climate system is now absorbing roughly 14–16 zettajoules of additional energy per year.

That energy cannot simply vanish.

So Where Does It Go?

This is the critical question.

The First Law tells us that the energy must go somewhere. The climate system continuously transforms and redistributes it through processes involving ocean heating, atmospheric circulation, evaporation, water vapor, melting ice, changing pressure patterns, storms, droughts, and biological responses.

In other words, climate change is not merely a temperature problem.

It is an energy-distribution problem.

A warmer ocean can provide additional energy and moisture to the atmosphere. Increased evaporation transfers energy into the water cycle as latent heat. Water vapor itself is a powerful greenhouse gas, creating additional warming feedback. Atmospheric circulation then transports heat and moisture across continents and oceans, sometimes concentrating enormous amounts of energy in particular regions.

The result can be expressed in many different ways:

🌊 More heat stored in the oceans
💨 More water vapor and atmospheric energy
🔥 More intense heat extremes
🌧️ Heavier precipitation and flooding
🌵 More rapid drying and flash drought
🌀 More energetic storms
🧊 Accelerated ice loss
🌡️ Longer and more persistent heatwaves
🌊 Rising sea levels and coastal flooding
🌲 Stress on ecosystems and agriculture

These are not separate energy problems. They are different manifestations of the same underlying physical reality.

Climate Energy Does Not Stay Where It Enters

The atmosphere and oceans are coupled components of a planetary system. Energy entering one part of the system can be transported, transformed, stored, and released somewhere else.

A pulse of additional energy absorbed in the tropical Pacific, for example, does not necessarily remain confined to the Pacific. Atmospheric circulation can redistribute heat and moisture across vast distances. Ocean currents can transport heat toward higher latitudes. Changes in evaporation can alter rainfall thousands of miles away. Changes in atmospheric pressure can modify storm tracks and circulation patterns.

This is why the consequences of a warming climate can appear far from the original source of the energy.

The energy is not being destroyed.

It is being rerouted.

The Question We Should Be Asking

The important question is therefore not simply:

“How much has the planet warmed?”

A more revealing question is:

“Where is all of this additional energy going—and how is it being redistributed through the climate system?”

That question shifts our focus from temperature alone to the physics of an increasingly energized planetary system.

The First Law of Thermodynamics gives us the starting point:

Energy cannot be created or destroyed.

But it can be transformed.

It can be transported.

It can be stored.

And it can be released.

The climate system is doing all four.

The question is no longer whether the energy exists.

The question is: How is that energy hitting you?

Public Access Introduction

🌎⚡ ENERGY CANNOT BE CREATED OR DESTROYED

So where does all that extra energy in the climate system go?

It doesn’t disappear.

It moves. 🌊💨💧🌀🧊🌱

The oceans absorb enormous amounts of heat. The atmosphere transports energy and moisture. Evaporation moves latent heat. Storms redistribute energy through intense precipitation. Ocean currents carry heat across the planet. Ice melts. Land heats and dries. Ecosystems respond.

And the greenhouse effect changes the planet’s energy balance—leaving more energy within the Earth system before it can ultimately escape to space.

450–500+ ZJ
🌡️ Accumulated excess energy

14–16 ZJ / YEAR
⚡ Approximate additional energy absorbed annually

The important question isn’t simply “How much has the temperature risen?”

It is:

HOW IS CLIMATE ENERGY HITTING YOU?

Weather. Water. Heat. Flooding. Drought. Ecosystems. Agriculture. Infrastructure. Risk.

The energy doesn’t disappear.

THE ENERGY DOESN’T DISAPPEAR — IT MOVES.

🌎⚡ How is climate energy hitting you?

bookmark_borderSea-Level Rise: Rubbing Salt in the Wound

by Daniel Brouse and Sidd Mukherjee

How Is Climate Energy Hitting You?

The Jersey Shore Is Sure

Sea-Level Rise: Rubbing Salt in the Wound

Sea-level rise is not simply a matter of the ocean getting higher. Climate change is altering the physical forces that move water toward and onto the shoreline. Rising seas, changing atmospheric pressure, stronger winds, altered ocean circulation, storm surge, king tides, and saltwater intrusion can interact to turn gradual sea-level rise into a much more immediate coastal threat.

A Real-World Warning: The Wetlands Institute

The experience of The Wetlands Institute in Stone Harbor, New Jersey, provides a striking example of how quickly coastal conditions can change.

The institute’s Salt Marsh Trail reportedly flooded only a few times a year around 2000. Over the past five years, flooding has averaged nearly 70 times annually. The institute is closing its headquarters on September 7, 2026, to begin a major coastal-resilience transformation.

The response includes raising the Salt Marsh Trail by two to three feet using clean dredged material, temporarily relocating operations and educational programs, and pursuing a broader campaign to replace and elevate the existing campus buildings.

This is more than an inconvenience. Increasingly frequent inundation can fundamentally alter the coastal ecosystem itself.

The Climate Shift

  • Accelerated sea-level rise: Sea levels along parts of the New Jersey coast are rising faster than the global average.
  • Marsh degradation: Repeated inundation can overwhelm salt-marsh vegetation, converting productive marsh into mudflats and eventually open water.
  • Wildlife disruption: More frequent flooding threatens habitats used by marsh-dependent birds and can interfere with diamondback terrapin nesting.
  • Infrastructure exposure: Roads, buildings, trails, drainage systems, and utilities face increasingly frequent flooding even without a major storm.

The critical point is that the climate signal is not experienced as a smooth, uniform rise in water level. It is experienced as more frequent encounters with water.


1. The Inverse Barometer Effect: Atmospheric Pressure Pushes the Ocean

Atmospheric pressure exerts physical force on the ocean surface. When a deep low-pressure system moves over the coast, the reduced atmospheric weight allows the ocean surface to rise.

The approximate relationship is:

A 1-hectopascal (hPa) decrease in atmospheric pressure produces roughly a 1-centimeter rise in sea level.

A very deep storm can therefore raise the local ocean surface substantially before the effects of wind-driven storm surge are even considered.

This is known as the inverse barometer effect.

Climate change does not simply “raise the sea.” It can alter the atmospheric conditions that determine how that elevated ocean is distributed along the coastline at any particular moment.

Inverse Barometer Effect Examples

Storm typeApprox. pressure near coastPressure drop from 1013 hPaInverse-barometer rise
Ordinary coastal storm990–1000 hPa13–23 hPa5–9 in
Strong nor’easter970–985 hPa28–43 hPa11–17 in
Very strong coastal storm950–965 hPa48–63 hPa19–25 in
Sandy-type extreme~945 hPa~68 hPa~27 in / 2.2 ft
Exceptional low-pressure event930–940 hPa73–83 hPa29–33 in / 2.4–2.8 ft

The Combined Impact

The inverse barometer effect combines with wind stress, coastline shape, bathymetry, wave setup, tides, and storm track can produce much larger water-level changes. Hurricane Sandy’s actual coastal water levels were dramatically higher because the pressure effect was combined with enormous wind-driven surge, wave action, tide, and the storm’s exceptionally favorable track. At Sandy Hook, water reached about 8.9 feet above ground level, while the storm produced major surge throughout the central and northern Jersey Shore.

An additional 5 inches to 3 feet of sea-level rise represents a new baseline of climate energy impacting coastal communities. The inverse barometer effect then combines with wind stress, coastline shape, bathymetry, wave setup, tides, and storm track to produce much larger water-level changes. The result can be extreme coastal flooding, with observed water levels reaching roughly 9 feet above ground level along parts of the Jersey Shore and as much as 30 feet in parts of Florida during major storms.


2. Wind and Wave Energy: Turning Pressure Gradients Into Coastal Damage

Atmospheric pressure gradients—the differences between areas of high and low pressure—drive winds.

When those gradients become stronger, winds can become stronger and more persistent. Strong winds transfer energy to the ocean, generating larger waves and increasing wind setup, the piling of water against the coast.

The consequences can include:

  • Higher water levels along exposed shorelines
  • Larger and more destructive waves
  • Increased dune erosion
  • Offshore transport of beach sand
  • Overtopping of coastal defenses
  • Greater storm-surge penetration

The shoreline therefore experiences not only a higher baseline sea level but also increasingly energetic ways of moving that water around.


3. Altered Ocean Circulation: When Water Piles Up

Changes in large-scale atmospheric circulation can alter ocean currents and regional sea levels.

The relationship between the Gulf Stream, the North Atlantic circulation, winds, and coastal sea level is particularly important along the U.S. East Coast. Changes in ocean circulation can redistribute enormous volumes of water, producing dynamic sea-level changes that may differ substantially from the global average.

In simplified terms, when ocean circulation changes, water can accumulate against a coastline rather than being transported away from it.

That means a community can experience a rapid increase in local relative sea level even when the global mean is changing much more slowly.


4. Compound Coastal Flooding: When Everything Arrives Together

The most dangerous coastal flooding occurs when multiple processes reinforce one another.

Imagine a high tide occurring while:

  • Global sea level is already elevated.
  • A low-pressure storm raises the ocean through the inverse barometer effect.
  • Strong onshore winds push additional water toward land.
  • Large waves increase water levels and erode dunes.
  • Heavy rainfall overwhelms drainage systems.
  • Rivers are already elevated and cannot discharge efficiently.

These processes can combine into compound flooding.

The problem is not simply that the water is higher. The problem is that multiple pathways for moving water onto the land are operating simultaneously.

Salt marshes normally provide a natural buffer. But repeated inundation and erosion can eventually overwhelm the marsh itself. Once protective wetlands deteriorate, more wave energy reaches infrastructure, creating a feedback loop of increasing exposure and increasing damage.


Saltwater Intrusion: When the Ocean Moves Underground

Sea-level rise has another consequence that is much less visible than coastal flooding: saltwater intrusion.

Saltwater intrusion occurs when seawater moves into freshwater systems, including groundwater aquifers, rivers, wetlands, agricultural soils, and drinking-water supplies.

Two forces are especially important:

  1. Rising sea level increases the hydraulic pressure and inland reach of seawater.
  2. Drought and reduced groundwater recharge weaken the freshwater pressure pushing outward toward the sea.

Together, these forces can shift the boundary between freshwater and saltwater inland.

Research has projected that saltwater contamination could affect a very large proportion of coastal aquifers by 2100, although the extent varies substantially by geography, aquifer characteristics, groundwater use, and future climate conditions.


How the Saltwater Wedge Moves Inland

Under normal conditions, rainfall replenishes groundwater. Freshwater flows toward the coast and maintains a hydraulic gradient that helps resist seawater intrusion.

Because freshwater is less dense than seawater, a freshwater lens can exist above denser saltwater beneath coastal areas.

But the balance can shift.

1. Underground Aquifer Intrusion

As sea level rises, the hydraulic pressure exerted by seawater increases. At the same time, climate-driven drought and higher temperatures can reduce groundwater recharge in some regions.

Less freshwater flowing toward the ocean means less outward pressure resisting seawater.

The underground saltwater boundary can therefore migrate inland.

This process can occur largely out of sight until a well begins producing water with elevated salinity.

2. Surface and Vertical Infiltration

Storm surge, king tides, and coastal flooding can push seawater onto land.

If that water remains on the surface, it can infiltrate downward through soils and shallow geological formations, contaminating groundwater.

Repeated flooding is especially important because a single event may be temporary, while dozens of inundation events each year can progressively alter soil and groundwater chemistry.

3. The “Highway Effect”

Human modifications to coastal landscapes can provide pathways for seawater to travel inland.

Agricultural drainage ditches, shipping channels, tidal creeks, canals, and other engineered waterways can connect coastal waters with areas that were historically protected by natural terrain.

When sea level rises or storm surge moves inland, these channels can function as highways for saltwater.


The Ecological and Economic Consequences

Saltwater intrusion does not stop at the shoreline.

Ghost Forests

As saltwater enters coastal soils and groundwater, freshwater-dependent trees can die from prolonged salt stress. The result can be stands of dead trees known as ghost forests.

These landscapes provide visible evidence that the boundary between marine and terrestrial ecosystems is moving inland.

Agricultural Damage

Salt deposited on agricultural land can accumulate in the root zone.

Excessive soil salinity interferes with plants’ ability to absorb water and can reduce crop productivity. Persistent salinization can make valuable coastal farmland increasingly difficult—or eventually impossible—to farm without expensive remediation and freshwater management.

Infrastructure Corrosion

Saltwater and brackish groundwater are highly corrosive.

Repeated exposure can accelerate deterioration of underground pipes, electrical infrastructure, concrete, foundations, roads, and other infrastructure.

The damage can occur beneath the surface long before it becomes visually obvious.

Drinking-Water Threats

Coastal communities that depend on groundwater face a particularly serious vulnerability.

Pumping already lowers groundwater levels around wells. If the freshwater table is lowered too far, the hydraulic gradient resisting seawater intrusion weakens further.

This can create another feedback:

More pumping → lower freshwater pressure → greater saltwater intrusion → less usable freshwater.


The Larger Picture: Climate Energy Does Not Disappear

Sea-level rise is one expression of a much larger physical process.

The additional energy accumulating in the climate system does not simply produce a higher average temperature. Energy moves through the atmosphere, ocean, land, ice, and biosphere.

Along the coast, that energy can appear as:

Higher baseline sea level → more frequent tidal flooding → stronger storm impacts → erosion → wetland loss → saltwater intrusion → infrastructure damage → freshwater stress.

The critical distinction is between average conditions and actual events.

A few inches of average sea-level rise may sound modest. But those inches can determine whether a high tide remains below a road or flows across it. They can determine whether a storm surge is absorbed by a functioning marsh or reaches buildings and infrastructure.

The climate system does not deliver its additional energy evenly.

It delivers it through water, wind, waves, heat, storms, erosion, flooding, and ecological disruption.

And along the coast, the ocean is increasingly finding more ways to come ashore—and stay there.

bookmark_borderThe Bleeding Edge of Climate Change

by Daniel and Sidd

While Sidd was in town, I took some notes. Somehow, they turned into this:

Climate Change: The Big Picture

There are many ways to look at climate change. From a micro perspective, there are millions of individual feedbacks operating throughout the Earth system. From a macro perspective, there is the climate system as a whole.

Understanding how those feedbacks interact—and, more importantly, how they feed back into one another—is at the bleeding edge of climate science.

One of the simplest examples is the albedo effect. The physics of ice is straightforward: bright, reflective ice sends a portion of incoming solar energy back into space, while darker ocean absorbs it. Less ice means more absorbed energy and, therefore, more warming.

But the system quickly becomes much more complicated.

How does changing albedo affect cloud formation, particularly over the tropics? And what happens to the climate if those clouds increase—or decrease?

The low clouds are especially important. They can reflect substantial amounts of incoming sunlight back into space. If tropical low clouds diminish, the ocean could absorb significantly more solar energy, accelerating warming.

This is where the bleeding edge begins.

Clouds are arguably the largest remaining uncertainty in our understanding of climate sensitivity. They can both reflect incoming solar radiation and trap outgoing heat. Which effect dominates—and how that balance changes as the planet warms—is one of the great questions in climate science.

My expectation is that the climate system could eventually approach a new equilibrium around +4°C above the preindustrial baseline, perhaps over the course of a couple centuries. That would imply roughly +2–3°C this century, with additional warming continuing into the next.

But that remains uncertain.

The important point is that climate change is not a simple linear equation. It is a massively interconnected system in which changes in one component can alter another, which then feeds back into the first. Ice affects albedo. Albedo affects heating. Heating affects clouds. Clouds affect radiation. Radiation affects ocean temperatures. Ocean temperatures affect evaporation and atmospheric moisture. And the cycle continues.

Everything is nonlinear.

Yet uncertainty about the exact trajectory does not mean uncertainty about what we should do.

The clearest lever we have is still the same: reduce CO₂ emissions and slow the accumulation of greenhouse gases in the atmosphere.

And while the long-term equilibrium matters, there is a much more immediate question.

What happens to you over the next five years?

We are already seeing rainfall becoming more intense and, in many places, more destructive—violent. A warmer atmosphere can hold more water vapor, increasing the potential for extreme precipitation. The question isn’t simply how hot the planet might become over the next 50 years.

The more immediate question is:

What is the violent rain going to do to your home, your community, your infrastructure, your insurance—and you—over the next five years?

That is where climate change stops being a distant projection and starts becoming a personal reality.

bookmark_borderMoney Moves People: Why Demand Destruction May Be the Fastest Path Beyond Fossil Fuels

by Daniel Brouse

2026: The New Economic Reality

Money moves people.

The climate costs of fossil-fuel dependence are increasingly outweighing its benefits—not in some distant future, but here and now. We are moving beyond arguments about what climate change might cost decades from today. Across the Western world, climate impacts are already imposing costs of hundreds of billions of dollars in real time.

Insurance is only one part of the story.

Infrastructure, agriculture, transportation, labor productivity, public health, energy systems, and financial markets are all beginning to absorb the cost of a destabilizing climate. The economic question is therefore changing. It is no longer simply:

“What will climate change cost us?”

It is increasingly:

“How much are we willing to pay to preserve an energy system that is becoming progressively more expensive to maintain?”

Climate Stress Is Becoming an Economic Stress Test

The physical infrastructure of the global economy is already being affected.

Maersk CEO Vincent Clerc has warned that climate change is putting increasing pressure on European waterways and that substantial infrastructure investment will be needed to keep the Rhine operating as a critical transportation artery.

But the economic importance of waterways extends far beyond shipping.

Rivers, lakes, and reservoirs are also critical components of the energy, industrial, agricultural, municipal, and ecological systems that support modern economies.

When water levels fall or water temperatures rise, power plants can be affected directly. Thermoelectric and nuclear power plants rely heavily on water for cooling. If river flows become too low, or water temperatures become too high, operators may be forced to reduce generation or temporarily shut down units because sufficient cooling capacity is no longer available or because thermal discharge limits are exceeded.

That creates an economic chain reaction:

Lower river flows or higher water temperatures
↓
Reduced cooling capacity
↓
Reduced power generation
↓
Tighter electricity supplies
↓
Higher electricity prices and grid stress
↓
Higher operating costs for industry and consumers

The same waterways that transport fuel, raw materials, agricultural products, chemicals, and manufactured goods can therefore also be essential to producing the electricity needed to move and manufacture those goods.

Water is simultaneously a transportation system, cooling system, industrial input, agricultural resource, and ecological asset.

When that system becomes unstable, multiple economic sectors can be affected at the same time.

Low water levels can also restrict the movement of coal, oil, natural gas, grain, chemicals, construction materials, and other bulk commodities. Barges may have to reduce their loads or make more trips to transport the same volume of goods. In some cases, alternative transportation by rail or truck becomes necessary, increasing fuel consumption, congestion, labor costs, and emissions.

Flooding creates the opposite problem.

Excess water can damage ports, locks, bridges, rail connections, roads, warehouses, industrial facilities, and electrical infrastructure. A waterway can therefore become economically disruptive at both extremes—too little water and too much water.

Agriculture is similarly exposed. Rivers and reservoirs provide irrigation, livestock water, and municipal supplies. Persistent drought can reduce agricultural output while increasing competition among farmers, cities, industry, ecosystems, and energy producers for increasingly scarce water.

There is also a less visible economic cost: water temperature itself is becoming an economic variable.

Warmer rivers can reduce their ability to absorb additional heat from industrial processes and power-plant cooling systems. At the same time, warmer water can stress aquatic ecosystems, fisheries, and drinking-water systems, creating additional regulatory, treatment, and ecological costs.

This produces a broader economic concept that is often missed in conventional disaster accounting:

Waterway disruption is not a single-sector problem. It is a systems problem.

The Rhine and Danube are not simply waterways. They are components of Europe’s economic infrastructure. They connect ports, factories, power plants, farms, cities, mines, warehouses, rail networks, and consumers. When climate conditions interfere with their operation, the economic consequences propagate through the system. A river does not have to disappear to create an economic crisis. It only has to become less reliable. And reliability is one of the most valuable—and often least visible—assets in a modern economy.

The Economic Toll of Extreme Weather

Global extreme weather and natural disasters are generating enormous economic losses. Recent estimates from the International Chamber of Commerce, insurers including Swiss Re, and disaster-loss tracking organizations show that severe convective storms, wildfires, floods, and other extreme events are producing annual losses measured in the hundreds of billions of dollars.

The first half of 2026 alone has already produced approximately $100 billion in global economic losses, while the cumulative economic toll over the past decade has reached roughly $2 trillion, according to recent assessments.

And the year is not over.

The second half of the year normally includes the peak of the North Atlantic hurricane season, creating the potential for another substantial wave of losses.

The Major Economic Drivers

Escalating annual losses.
Global disaster losses continue to accumulate at extraordinary levels. The combined economic losses from 2022 and 2023 alone have been estimated at roughly $451 billion.

The concentration of U.S. losses.
The United States remains a major source of global insured catastrophe losses. By June 2026, the country had already experienced 12 billion-dollar weather and climate disasters, with estimated losses totaling approximately $31.9 billion.

Severe convective storms.
Hail, tornadoes, straight-line winds, and other severe thunderstorms have become an increasingly persistent source of financial losses. The United States recorded a record 21 billion-dollar severe-convective-storm events in 2025.

Extreme heat and productivity.
The economic damage from climate change is not limited to destroyed buildings and infrastructure. Heat reduces worker productivity, particularly in construction, agriculture, manufacturing, and outdoor occupations. Global heat-related productivity losses have been estimated at roughly 1% of world GDP annually—around $1 trillion.

The long-term U.S. bill.
U.S. billion-dollar weather and climate disasters have generated cumulative damages exceeding $3 trillion since systematic tracking began in 1980.

The Trajectory Is the Story

Recent U.S. disaster statistics illustrate the increasing economic burden:

YearBillion-Dollar EventsEstimated DamageMajor Loss Drivers
202523~$115 billionSevere storms, wildfires
202427~$182.7 billionSevere storms, tropical cyclones, extreme heat
202328$145+ billionSevere storms and other extreme events

The important point is not that every individual disaster can be attributed exclusively to climate change.

The economic signal emerges from the frequency, intensity, persistence, and cumulative cost of extreme conditions.

Climate change does not need to create every storm, flood, drought, or wildfire to transform the economics of risk. It only needs to increase the probability, severity, or duration of damaging events enough to alter the cost structure of society.

That is already happening.

“Demand Destruction” Is Our Friend

This brings us to one of the most powerful—and least appreciated—economic mechanisms in the energy transition:

Demand destruction.

The International Energy Agency has projected that global oil demand will decline more sharply than previously expected in 2026, forecasting a reduction of approximately 1.6 million barrels per day.

The significance extends beyond the number itself.

As an economist, I am less concerned with establishing a specific date by which the world must eliminate fossil fuels than I am with changing the economic forces that sustain fossil-fuel demand.

That distinction matters.

People do not necessarily change because someone wins an argument about climate science. They change because incentives change. Prices change. Risk changes. Availability changes. And eventually, behavior changes.

Money Moves People

I am unlikely to change the minds of the roughly 20% of Americans who are ideologically committed to policies that accelerate fossil-fuel dependence.

But that leaves the vast majority of the population. And economics can do much of the work. Integrated Climate Stewardship begins with reducing unnecessary consumption.

Consumerism drives energy demand, resource extraction, pollution, waste, and habitat destruction. Every unnecessary unit of consumption represents another demand for energy and materials somewhere in the global economy.

Consume less, and demand falls.

Demand falls, and the economic incentive to produce falls.

That is the mechanism.

The Economics of Personal Climate Stewardship

Today, only a small fraction of Americans appear to be pursuing a deliberately structured net-zero lifestyle through continuous behavioral reductions, efficiency improvements, and intentional balancing. But this does not mean the model cannot scale. The critical question is how climate stewardship is presented.

If reducing climate impact is framed exclusively as sacrifice, people resist. If it is framed as economic self-interest, the equation changes.

What happens when people discover that reducing unnecessary consumption can save them thousands of dollars a year?

What happens when energy efficiency lowers household expenses?

When smaller vehicles reduce fuel, maintenance, and insurance costs?

When reducing waste means buying fewer things that do not provide meaningful value?

When local production and durable goods become economically attractive?

When conservation becomes synonymous with financial resilience?

The behavior does not have to begin with ideology.

It can begin with a household budget.

Vote With Your Dollars

This is where the remaining majority of the population becomes economically important.

When millions of people begin making purchasing decisions based on cost, durability, efficiency, resilience, and environmental impact, they collectively alter demand.

When demand changes, markets respond. When fossil-fuel demand declines, the economic incentive to extract, refine, transport, and sell fossil fuels declines with it. This is fundamentally different from waiting for governments to impose every change from the top down. It is a bottom-up economic transition.

People do not have to agree about everything.

They do not have to become climate activists.

They do not even have to agree about climate policy.

They simply have to discover that some forms of consumption are no longer worth what they cost.

The Feedback Loop

The process can become self-reinforcing:

Lower unnecessary consumption
↓
Lower household costs
↓
Lower energy and resource demand
↓
Reduced fossil-fuel demand
↓
Lower economic incentive for fossil-fuel expansion
↓
Greater investment in alternatives and efficiency
↓
Further reductions in fossil-fuel demand

This is an economic feedback loop.

And unlike many climate-policy debates, it does not require everyone to agree on the destination before beginning the journey.

Demand Destruction Is the Transition

The transition away from fossil fuels is often described as a supply problem:

How quickly can we replace coal, oil, and natural gas?

But there is another side of the equation.

How quickly can we reduce the demand that makes fossil-fuel extraction profitable?

That may ultimately be the more powerful question.

We do not need to convince every person to become an environmentalist.

We need to make lower-carbon choices increasingly rational economic choices.

The climate crisis is already generating enormous costs. Insurance premiums are rising. Infrastructure is being stressed. Agricultural productivity is being disrupted. Heat is reducing labor capacity. Extreme weather is destroying capital. Supply chains are becoming more vulnerable.

These costs are not theoretical.

They are appearing on balance sheets, household budgets, insurance statements, government budgets, and corporate earnings reports.

The economic system is beginning to receive the bill.

And money moves people.

Demand destruction is not the enemy of the energy transition.

Demand destruction is the transition.