🌊 OCEAN MAELSTROM: THE CLIMATE-ECONOMIC SINGULARITY IS COMING INTO FOCUS
A landmark November 10, 2026 report from the Institute and Faculty of Actuaries, the University of Exeter, and The Ocean Race connects the dots between accelerating ocean degradation and global economic instability.
Its message is profound: The climate crisis is no longer just an environmental problem. It is becoming a systemic economic and financial crisis.
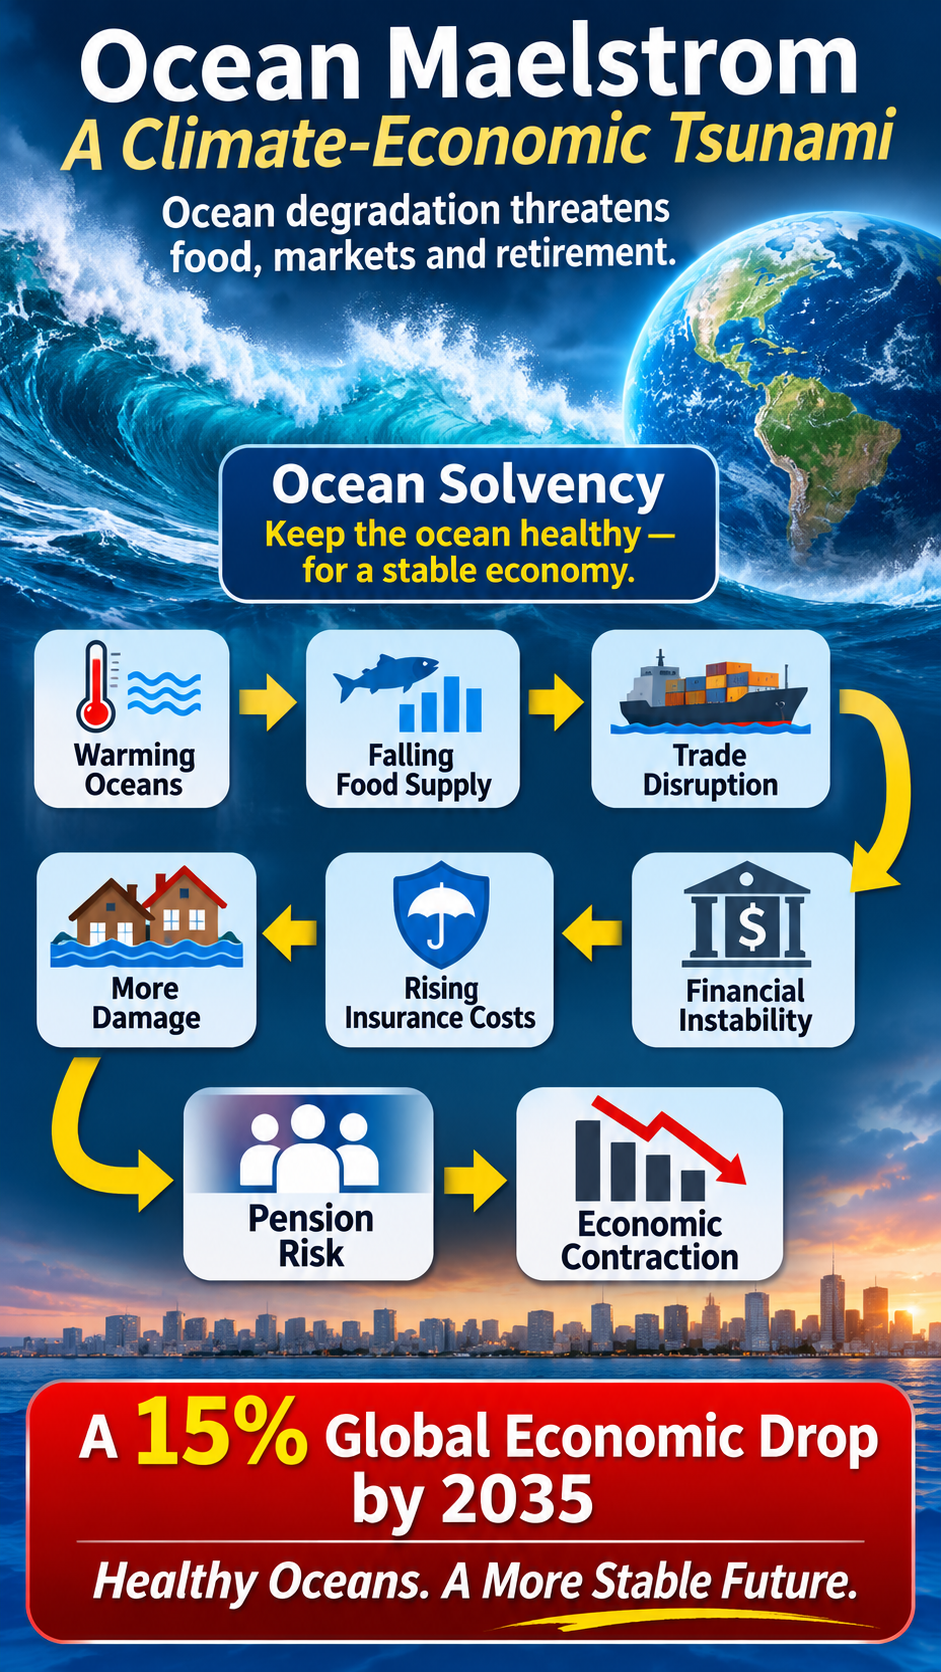
The report introduces Ocean Solvency—the ocean’s ability to continue providing the essential services upon which global civilization and economic activity depend.
But the implications go much further.
🌡️ Ocean degradation and climate disruption → Declining food production and rising prices → International trade and supply-chain disruptions → Increasing insurance losses → Financial market instability → Pension and retirement risks → Economic contraction.
Implications for Climate-Economic Coupling and Singularity
This is precisely the kind of interconnected, nonlinear risk that underlies the climate-economic coupling and singularity framework we’ve been developing.
Climate impacts do not occur in isolation. They propagate through interconnected physical, ecological, geopolitical, and financial systems. Each disruption creates additional pressures, while weakening the capacity of other systems to absorb the next shock.
The feedback becomes economic as well as environmental.
As climate disruption accelerates, economic losses increase. As economic stability deteriorates, the resources available for adaptation and resilience decline. That creates another reinforcing feedback loop.
The report explores a modeled scenario in which ocean-related shocks contribute to a 15% reduction in global economic output by 2035. This is a systemic-risk scenario.
The fundamental economic reality is difficult to escape:
The global economy cannot remain solvent while the natural systems supporting it become insolvent.
The climate-economic singularity is about more than rising temperatures. It is about the accelerating coupling of systems, the amplification of cascading failures, and the growing difficulty of containing consequences once multiple thresholds are crossed.
🌎 The ocean is not separate from the economy. It is part of the infrastructure that makes the global economy possible.
Update: Ocean Maelstrom — The Emerging Climate-Economic Feedback System
November 12, 2026
By Daniel Brouse and Sidd Mukherjee
5.5 Ocean Solvency and the Ocean Maelstrom: A New Dimension of Systemic Risk
Published November 10, 2026, Ocean Maelstrom: Navigating the Climate Storm is a landmark systemic-risk report developed by the Institute and Faculty of Actuaries (IFoA), the University of Exeter, and The Ocean Race.
The report provides an important independent assessment of the increasingly interconnected risks linking ocean degradation, climate instability, and global economic systems. Its central warning is that accelerating ocean degradation is not simply an environmental problem. It represents a growing threat to global food security, supply chains, insurance markets, pensions, financial markets, and overall economic stability.
Ocean Solvency: The Foundation of Economic Stability
The report introduces the concept of Ocean Solvency, defined by the ocean’s continuing ability to provide the essential ecosystem services upon which human societies and economies depend.
The ocean is fundamental to:
Global climate regulation and heat redistribution.
Food production and marine biodiversity.
Oxygen production and carbon absorption.
Global water cycles and weather patterns.
International commerce and maritime transportation.
Economic productivity and financial stability.
The report assesses current Ocean Solvency risk as severe, with the potential to become catastrophic to extreme by 2050 under a business-as-usual trajectory.
This introduces an important economic distinction: financial systems cannot remain solvent indefinitely if the natural systems supporting economic production become insolvent.
Ocean Maelstrom: A Systemic Risk Scenario
The report develops an Ocean Maelstrom scenario to demonstrate how multiple interacting pressures can produce cascading economic consequences.
Importantly, this is a plausible systemic-risk scenario, not a forecast. It examines how six individually plausible ocean, climate, and geopolitical pressures could interact between 2027 and 2035, producing consequences substantially greater than the sum of their individual impacts.
The scenario illustrates the transmission of physical climate and ecological disruptions through interconnected systems:
Ocean and climate disruption: Marine heatwaves, ocean circulation changes, declining biodiversity, and deteriorating marine ecosystems undermine ocean productivity and climate regulation.
Food and agricultural disruption: Changes in ocean conditions, fisheries, rainfall patterns, and agricultural production reduce food availability and increase food prices.
Supply-chain and trade disruption: Disruptions to marine resources, maritime infrastructure, ports, and international commerce amplify economic instability.
Insurance and infrastructure exposure: Increasing coastal damage, flooding, property losses, and infrastructure risks intensify insurance pressures and undermine asset valuations.
Sovereign and financial instability: Economic contraction, inflation, declining revenues, and increased government expenditures create additional pressure on national finances and financial markets.
Pension and retirement exposure: Investment losses, inflation, declining purchasing power, and weakened economic growth threaten long-term retirement security.
The Financial Consequences
One of the report’s most significant findings concerns the exposure of global retirement systems.
Global pension funds hold approximately $68.3 trillion in assets. Under the Ocean Maelstrom scenario, ocean-related shocks contribute to a modeled 15% reduction in global economic output by 2035.
This is not a prediction of a 15% economic contraction. It is a scenario-based assessment demonstrating the magnitude of potential systemic exposure.
The consequences extend beyond investment portfolios. Inflation reduces purchasing power, economic contraction weakens pension contributions, and deteriorating corporate and sovereign finances threaten the underlying assets supporting retirement systems.
The report identifies a particularly important problem with conventional financial risk models: ocean-related risks can simultaneously affect investment assets, liabilities, contribution capacity, and inflation. These risks are interconnected, persistent, and potentially difficult to diversify away.
Implications for Climate-Economic Coupling and Singularity
The Ocean Maelstrom report provides an important extension of the climate-economic coupling framework presented in this analysis.
It demonstrates how environmental degradation propagates through interconnected physical, ecological, geopolitical, and economic systems. More importantly, it illustrates how these interactions generate reinforcing feedback loops that reduce the capacity of societies and financial institutions to absorb subsequent disruptions.
The resulting feedback sequence can be expressed as:
This is not simply a linear chain of economic consequences. The individual components interact, reinforce one another, and create opportunities for cascading failures.
The relationship is particularly important when considered alongside the third-derivative framework developed in this paper:
dI/dt > 0
d²I/dt² > 0
d³I/dt³ > 0
The significance is that climate impacts increase, their rate of increase accelerates, and the acceleration itself increases. As physical and economic systems become more tightly coupled, disruptions can propagate faster and produce increasingly disproportionate consequences.
The Ocean Is Not Separate From the Economy
Traditional economic models frequently treat environmental degradation as an external cost. Ocean Maelstrom challenges that assumption by demonstrating that the ocean is foundational economic infrastructure.
The economic system is not independent of the Earth system. It is embedded within it.
When natural capital deteriorates, the resulting losses do not disappear simply because they are excluded from conventional accounting. They reappear as food-price inflation, insurance losses, infrastructure damage, declining productivity, financial instability, and increased public expenditures.
This creates an additional dimension of systemic risk: the deterioration of the natural systems that support economic activity simultaneously weakens the financial resources available to respond to that deterioration.
Conclusion: An Expanding Climate-Economic Singularity
Ocean Maelstrom reinforces the central argument of this analysis: climate instability and economic instability are increasingly interconnected components of a larger nonlinear system.
The report’s contribution is particularly significant because it translates ocean degradation into recognizable financial and actuarial risks. Food security, insurance, sovereign finances, investment portfolios, and retirement security are not separate issues. They are interconnected consequences of the same underlying Earth-system disruption.
The emergence of Ocean Solvency as a financial risk framework represents an important recognition that economic stability ultimately depends on environmental stability.
The climate-economic singularity is therefore not confined to rising temperatures, accelerating sea-level rise, or increasing disaster losses. It encompasses the progressive destabilization of the interconnected systems upon which global civilization depends.
The ocean is not merely another economic resource. It is part of the infrastructure that makes the global economy possible.
Primary Source
Trust, S., Ranchin, A., Hunt, L., Joslin, S., Chapman, G., & Abrams, J. F. (2026). Ocean Maelstrom: Navigating the Climate Storm. Institute and Faculty of Actuaries, University of Exeter, and The Ocean Race. November 2026.
Trump Was Warned About Nvidia CEO’s Relationship With Suspected Chinese Spy — Yet Invited Him Aboard Air Force One and to White House State Dinner
President Donald Trump says he believes Nvidia CEO Jensen Huang had no idea that the woman with whom he acknowledged having an intimate relationship was a suspected Chinese spy. Trump expressed confidence in Huang’s explanation, describing him as an “honorable guy.”
However, reporting by The New York Times raises significant questions about what Trump knew, when he knew it, and why he continued to give Huang access to some of the most sensitive diplomatic settings involving China.
1. The Air Force One Warning
According to The New York Times, Secretary of State Marco Rubio briefed Trump aboard Air Force One in May 2026, during the president’s trip to China.
Rubio reportedly informed Trump that U.S. intelligence had identified a relationship between Huang and Alice Huang, a Chinese businesswoman suspected of working with China’s Ministry of State Security.
The intelligence concerns were sufficiently serious that Rubio oversaw the preparation of a highly classified memorandum warning senior administration officials about the relationship.
Despite these warnings, Trump arranged for Jensen Huang to join his presidential delegation. During a stop in Alaska, Huang boarded Air Force One at Trump’s invitation and continued the journey to China.
The decision raises questions about how the administration evaluated the intelligence warning and whether national security concerns were adequately considered before granting Huang access to the presidential delegation.
2. The White House State Dinner
In September 2026, Trump hosted Chinese President Xi Jinping at a high-profile White House state dinner.
Despite the intelligence concerns surrounding Huang’s relationship with a suspected Chinese intelligence operative, Huang and his wife were invited to attend.
Huang was seated at the prominent head table alongside Trump and Xi.
The decision to include Huang in such a high-profile diplomatic setting raises additional questions about the administration’s handling of the intelligence concerns and its assessment of potential national security risks.
3. Trump’s Public Defense of Huang
Following the revelations, Trump defended Huang publicly.
Trump said Huang had told him he had no idea the woman was a spy and stated, “I really believe him.”
He also described Huang as an “honorable guy” and suggested that he should remain Nvidia’s CEO.
Meanwhile, Nvidia’s board has initiated an independent investigation into the relationship and associated national security concerns. The company has stated that it has no reason to believe its trade secrets or national security information were compromised, but that the investigation will examine the available evidence.
4. The Larger National Security Questions
This controversy extends beyond the personal relationship of a prominent technology executive.
Nvidia is a central supplier of advanced artificial intelligence chips, technologies that have major economic, military, and strategic implications in the competition between the United States and China.
The central questions are straightforward:
What intelligence did the administration possess about the suspected Chinese operation?
Why did Trump proceed with inviting Huang aboard Air Force One after receiving the reported warning?
Why was Huang subsequently seated alongside Trump and Xi at the White House state dinner?
Were appropriate national security safeguards maintained?
Did the administration adequately evaluate the potential risks to America’s technological and strategic interests?
These questions deserve serious congressional scrutiny and a transparent accounting of the administration’s decisions.
National security intelligence warnings are not simply political talking points. They exist to protect American interests. How those warnings are received, evaluated, and acted upon deserves accountability.
How Rising Energy Costs Move Through the Agricultural Supply Chain and Into Consumer Prices
By Daniel Brouse; Independent Economist, Financial Analyst, and Independent Climatologist
Simplified Overview
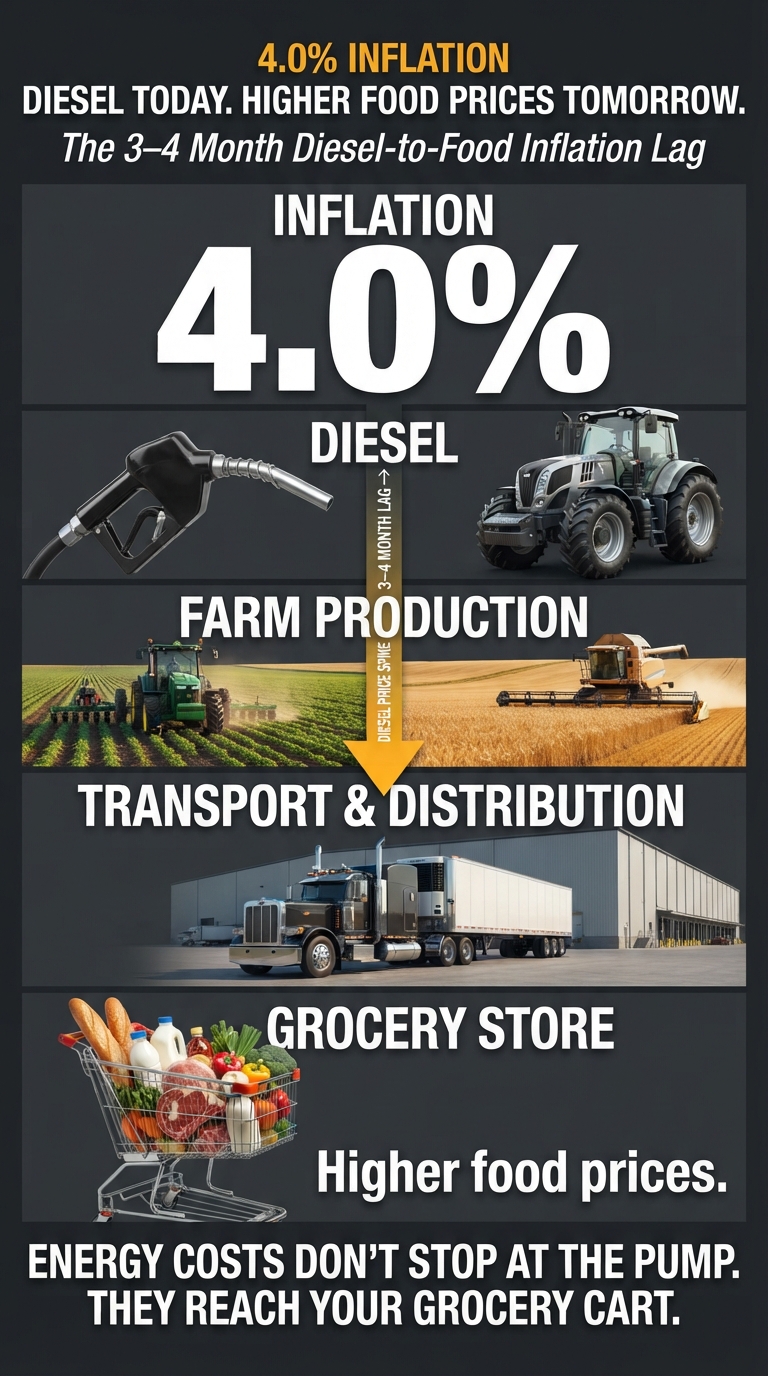
📈 4.0% INFLATION: DIESEL PRICES AND THE COMING FOOD INFLATION
With third-party calculations estimating annual consumer-price increases at 4.0%, up from 3.7% in September, monitoring diesel prices becomes particularly important when evaluating where food inflation is headed.
What you pay at the grocery store tomorrow may already be reflected in the diesel prices businesses are paying today.
Diesel is the lifeblood of the agricultural supply chain. It powers farm machinery, transports crops, moves food through processing facilities, and delivers products to grocery stores.
When diesel prices rise, the inflationary impact doesn’t stop at the fuel pump. It moves through the entire food supply chain, creating an estimated 3–4 month delay before higher operating costs work their way into consumer food prices.
🚜 Farm production 🚛 Freight and transportation 🏭 Food processing and distribution 🛒 Grocery-store prices
The economic lesson: Watch diesel prices today to understand food inflation tomorrow.
A closer look at the relationship between energy costs, agricultural production, and the inflationary pressures facing American households.
Energy prices are a major driver of food inflation. Among the most important indicators is diesel fuel, which powers the machinery, transportation networks, and logistics infrastructure supporting the entire agricultural supply chain.
Diesel price increases can provide an early warning of broader food-price inflation, with an estimated transmission lag of approximately three to four months. This delay reflects the time required for higher fuel and operating costs to move through agricultural production, freight transportation, food processing, distribution, and retail pricing.
The relationship is particularly important because food inflation does not respond to energy-price increases instantaneously. Instead, rising costs accumulate throughout the supply chain, creating a delayed inflationary effect that eventually reaches consumers.
This process resembles a supply-chain bullwhip effect: an initial increase in fuel costs propagates through multiple stages of production and distribution, amplifying operating expenses before they appear in retail food prices.
1. The October 2026 Inflation Report
The October 2026 Consumer Price Index (CPI) report released by the U.S. Bureau of Labor Statistics showed that overall consumer prices increased 0.4% month-over-month, while core inflation, which excludes volatile food and energy prices, increased 0.3%.
Third-party inflation calculations estimate that overall U.S. consumer prices are running approximately 4.0% higher than a year ago, up from an estimated 3.7% in September.
Although the October annual comparison is not an official BLS twelve-month CPI calculation, the third-party estimate provides an additional perspective on the continuing inflationary pressures affecting American households.
The distinction matters because inflation is not simply a measurement of what consumers paid last month. It reflects the cumulative increase in the cost of living, including the essential expenses of food, transportation, housing, and energy.
The relationship between energy costs and food prices deserves particular attention because changes in fuel prices can affect agricultural production and distribution well before their full impact appears in consumer inflation statistics.
2. Why Diesel Prices Lead Food Inflation
Diesel is one of the fundamental inputs supporting the modern food economy. Its influence extends across four interconnected stages of the agricultural supply chain.
A. Agricultural Production: The Farm-Level Lag
Diesel powers much of the heavy equipment required to produce food, including:
Tractors and planting equipment.
Combines and harvesting machinery.
Irrigation pumps and agricultural transport vehicles.
Equipment used for moving crops and materials around farms.
The transmission mechanism:
When diesel prices increase, farmers face higher operating costs for planting, cultivating, irrigating, and harvesting crops.
Those expenses become embedded in production costs. Depending on the crop, growing season, and timing of the fuel purchase, the increased costs may not be reflected in food prices until the resulting harvest moves through processing and distribution.
The inflationary effect: Higher agricultural production costs eventually place upward pressure on wholesale and retail food prices.
B. Freight and Logistics: The Transportation Lag
Food is particularly dependent on transportation because it must move from farms to processors, warehouses, distributors, and grocery stores.
Diesel powers much of the transportation infrastructure, including:
Commercial trucking fleets.
Agricultural freight transportation.
Diesel-powered rail locomotives.
Port equipment and certain shipping operations.
The transmission mechanism:
When diesel prices rise, trucking and logistics companies experience higher operating expenses. Fuel surcharges, freight-rate adjustments, and contract renegotiations transmit these increases to food distributors and manufacturers.
Existing transportation contracts and pricing arrangements can delay the full pass-through of higher fuel costs.
The inflationary effect: Higher freight expenses increase the delivered cost of food, creating additional upward pressure on wholesale and retail prices.
C. Food Processing, Warehousing, and Distribution
The agricultural supply chain does not end when crops leave the farm. Food must be processed, packaged, refrigerated, stored, and distributed before reaching consumers.
These operations depend on substantial energy inputs and transportation infrastructure.
The transmission mechanism:
Higher diesel prices increase the cost of moving agricultural commodities, transporting processed products, operating distribution fleets, and maintaining inventory throughout the supply chain.
Food manufacturers and retailers also operate under existing purchasing agreements and inventory cycles. They may temporarily absorb increased expenses rather than immediately passing every cost increase to consumers.
As inventories turn over and contracts are renewed, accumulated cost increases become more visible in wholesale and retail pricing.
The inflationary effect: Energy and transportation costs work their way through processing and distribution, extending the time between an initial diesel-price increase and its appearance at the grocery store.
D. Fertilizer and Agricultural Input Costs
Fuel prices also interact with the broader agricultural energy market.
Natural gas is a major feedstock for nitrogen fertilizer production, while petroleum-based inputs and diesel-powered transportation contribute to the cost of manufacturing and distributing agricultural chemicals and fertilizers.
The transmission mechanism:
Higher energy prices can increase fertilizer manufacturing, transportation, and distribution expenses. Farmers then face higher input costs when purchasing fertilizer for subsequent planting seasons.
Depending on the timing and magnitude of these increases, farmers may pay more for fertilizer, adjust application rates, or change planting decisions.
These decisions can affect production costs and, in some circumstances, crop yields during subsequent growing and harvesting cycles.
The inflationary effect: Higher agricultural input costs can contribute to additional food-price pressures months after the original energy-price increase.
3. The Three-to-Four-Month Inflation Transmission Window
The combined effects of agricultural production, transportation, processing, and distribution create a delay between changes in diesel prices and their eventual impact on consumer food prices.
The estimated three-to-four-month window represents a useful economic hypothesis for monitoring inflationary pressures. It is not a fixed delay applying equally to every food category or every fuel-price increase.
Different commodities respond at different speeds:
Fresh produce can experience relatively rapid transportation-cost pass-through.
Meat and poultry prices are influenced by feed costs, production cycles, processing, and refrigeration.
Packaged foods can experience longer delays because of inventory management, purchasing agreements, and manufacturing cycles.
The important economic principle is that energy-price increases propagate through the supply chain over time. Consequently, today’s diesel prices can provide information about potential food-price pressures in the months ahead.
4. Why This Relationship Matters for Inflation Forecasting
Traditional inflation analysis frequently concentrates on the latest CPI readings. However, CPI is a lagging indicator of many underlying production and distribution costs.
Diesel prices offer a different perspective because they reflect an important operating expense throughout the physical economy.
Monitoring diesel prices alongside food prices can help identify emerging inflationary pressures before they become fully visible in retail statistics.
A useful forecasting model would examine:
Monthly changes in national diesel prices.
Changes in agricultural production and input costs.
Changes in freight transportation costs.
Subsequent changes in wholesale food prices.
The eventual pass-through into grocery-store food prices.
Comparing these indicators over multiple years would help establish the actual transmission lag, quantify the relationship, and determine whether the three-to-four-month estimate holds consistently.
A particularly useful approach would be to compare diesel-price movements against the BLS Food at Home CPI, using time-lagged correlations and regression analysis. This would help distinguish the predictive relationship from the influence of other variables, including weather, crop yields, commodity markets, labor costs, and international supply disruptions.
5. Economic Implications
Food and energy are essential household expenses. When both experience sustained price increases, the resulting pressure on household budgets can be substantial.
Higher diesel prices affect more than what consumers pay at the pump. They increase the cost of producing, transporting, processing, and distributing the food Americans purchase every day.
This creates an important distinction between the initial inflationary shock and its downstream consequences.
Even when diesel prices stabilize, previously accumulated increases in production, freight, and distribution costs can continue working their way through the supply chain. Consequently, food inflation can remain elevated after the original fuel-price increase has subsided.
For policymakers, investors, businesses, and consumers, monitoring diesel prices provides an additional tool for evaluating future inflation risks.
Conclusion: Watch Diesel Today to Understand Food Inflation Tomorrow
Diesel is more than a transportation expense. It is a fundamental operating input throughout the agricultural economy.
Its influence extends from planting and harvesting to processing, refrigeration, transportation, warehousing, and retail distribution.
The estimated three-to-four-month transmission window illustrates why changes in diesel prices deserve attention when evaluating the future direction of food inflation.
With third-party calculations placing annual consumer-price increases at approximately 4.0%, up from 3.7% in September, the inflationary pressures affecting American households remain an important economic concern.
The broader economic lesson is straightforward:
By the time higher diesel costs appear in grocery-store prices, the inflationary pressures responsible for those increases have already been moving through the agricultural supply chain for months.
Monitoring diesel prices today provides an opportunity to anticipate tomorrow’s food inflation.
The climate system is crossing thresholds. Tipping points are activating, feedbacks are coupling, and the consequences are accelerating across interconnected planetary systems.
We are witnessing a fundamental change in Earth’s climate system.
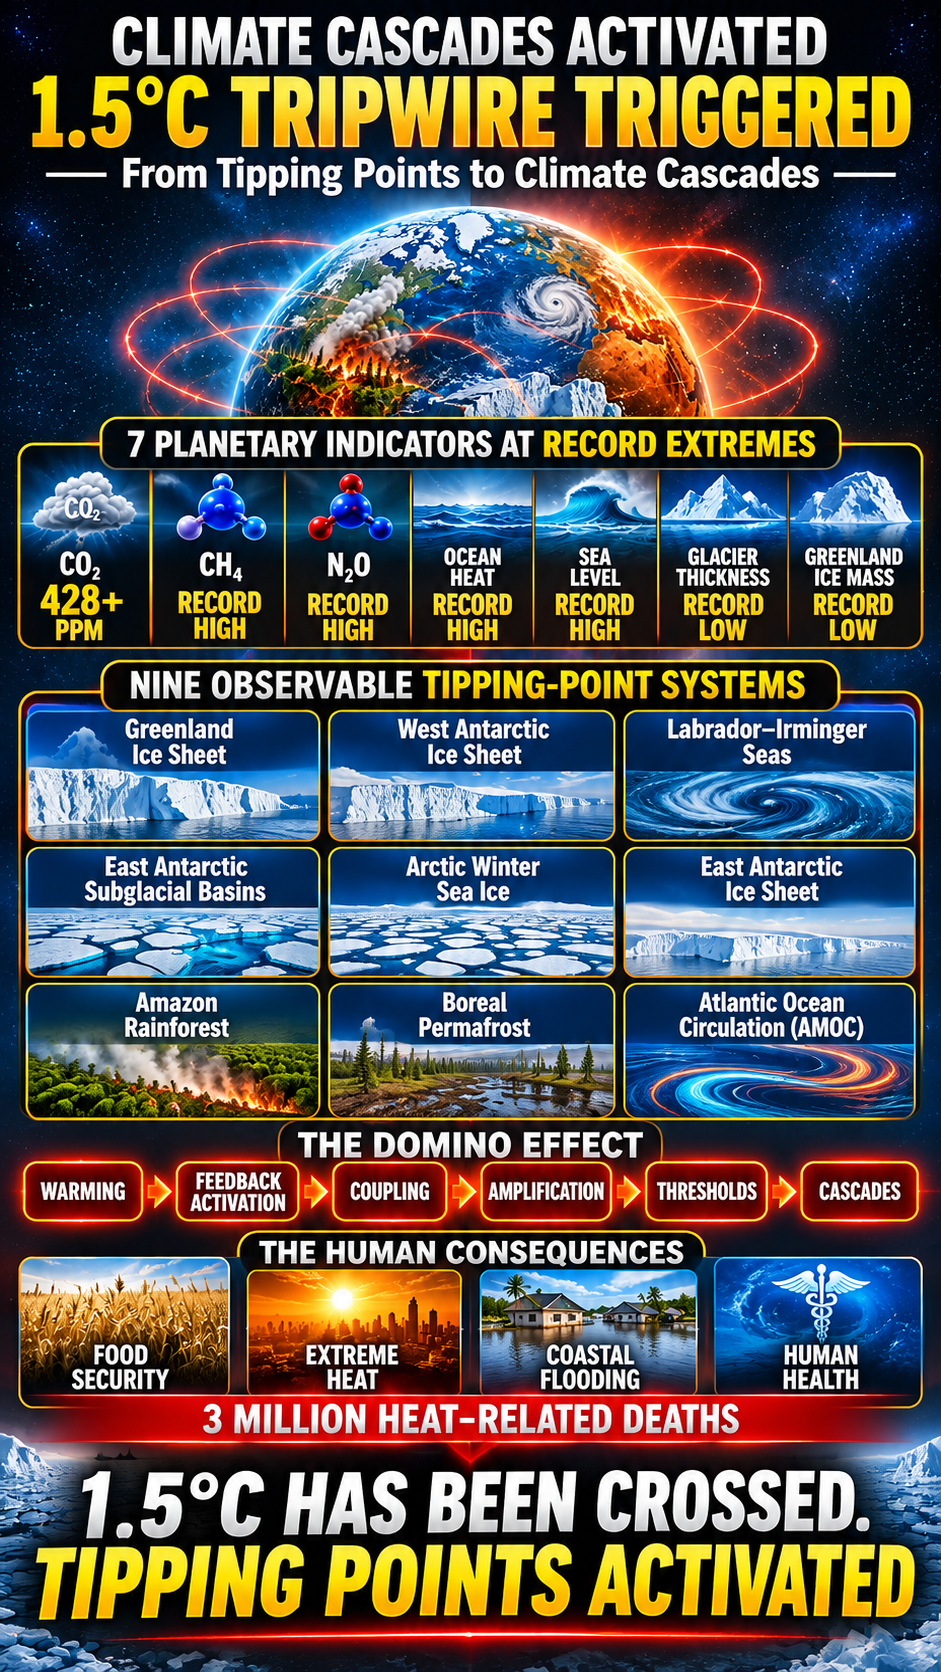
Seven planetary indicators have reached record extremes. Nine major climate tipping-point systems are showing observable signs of destabilization. Greenhouse gases continue accumulating, ocean heat is breaking records, sea levels are rising, and glaciers and ice sheets are losing mass.
But the greatest concern isn’t any single measurement.
It’s the connections.
🌡️ Warming activates feedbacks. 🔄 Feedbacks begin coupling. ⚡ Coupling amplifies the energy imbalance. 🌎 Amplification drives interconnected systems toward thresholds. 🌪️ Thresholds create the conditions for cascading change.
This is the climate Domino Effect.
The 1.5°C threshold was never a magical number. It represents an increasingly dangerous boundary for a nonlinear climate system in which feedbacks can reinforce one another and accelerate planetary destabilization.
The latest climate research documents the warning signs across the atmosphere, oceans, cryosphere, ecosystems, and human health.
Nearly 3 million heat-related deaths between 2016 and 2023 underscore the human consequences.
My latest infographic brings together the planetary indicators, nine tipping-point systems, feedback coupling, and the consequences for humanity.
This is what I call the First Tipping-Point Season: observing the interaction of climate feedbacks as they unfold.
The question is no longer simply how much the planet will warm.
It’s what happens when the systems that regulate our planet begin changing together.
1.5°C HAS BEEN CROSSED.
THE CLIMATE CASCADES ARE UNDERWAY.
🔬 Climate science is no longer just about measuring change. It’s about understanding the connections.
The 1.5°C Tripwire and the Era of Tipping-Point Cascades
Global warming has surpassed the critical 1.5°C threshold identified in the Paris Agreement, according to recent temperature tracking. The consequences include record-breaking climate extremes, escalating threats to human health, and growing instability across agriculture, coastal systems, and international climate diplomacy. Major scientific and health institutions are identifying climate change as a global health emergency.
The 1.5°C threshold—and the approximately 2°C level associated with greater climate-system disruption—does not represent a magical difference between 1.4°C and 1.5°C. These thresholds matter because every increase in global temperature raises the probability of triggering major climate tipping points.
Once tipping points activate, the question of whether global warming ultimately reaches 2°C, 3°C, or even 4–7°C becomes less relevant for two fundamental reasons.
First, tipping points can initiate self-reinforcing feedbacks that continue driving environmental change even after the original forcing changes.
Second, climate impacts do not increase proportionally with temperature. They accelerate, compound, and cascade as interconnected systems destabilize.
In other words, 1.5°C is not a destination. It is not merely a warning sign or an alarm.
It is a tripwire.
Nine Observable Climate Tipping Points
Nine major tipping-point systems have become observable, demonstrating the scale of destabilization underway across the planet.
Greenland Ice Sheet Collapse
West Antarctic Ice Sheet Collapse
Labrador–Irminger Seas / Subpolar Gyre Convection Collapse
These systems do not operate independently. Changes in one system affect the conditions governing others. Ice loss, ocean circulation, atmospheric circulation, freshwater input, surface reflectivity, and carbon-cycle feedbacks interact across planetary boundaries.
The central concern is no longer simply the activation of individual tipping points. It is the interaction, coupling, and amplification of multiple climate feedbacks.
November 2026: Planetary Indicators and Climate Acceleration
Oregon State University Annual Climate Report (November 2026)
The annual State of the Climate report, led by Oregon State University scientists, found that 7 of 16 vital planetary climate indicators had reached record extremes. The report documented accelerating warming, increasing climate instability, and dramatic glacial losses.
Seven planetary indicators stand out:
Atmospheric Carbon Dioxide (CO₂): Concentrations surpassed 428 parts per million (ppm) in May 2026—approximately 50% above pre-industrial levels.
Atmospheric Methane (CH₄): Reached an all-time high, increasing atmospheric heat trapping and planetary energy imbalance.
Atmospheric Nitrous Oxide (N₂O): Reached unprecedented concentrations alongside the other primary greenhouse gases, adding to atmospheric greenhouse forcing.
Global Ocean Heat Content: Reached the highest measured energy accumulation in recorded history. Oceans absorb more than 90% of the excess heat accumulating in Earth’s climate system.
Global Sea Level: Reached a record average high, driven by melting land ice and the thermal expansion of warming seawater.
Worldwide Glacier Thickness: Fell to an all-time historical low, demonstrating accelerating glacier loss, changing regional water systems, and increasing contributions to global sea-level rise.
Greenland Ice-Sheet Mass: Experienced extreme melting episodes and continued ice loss, reaching its lowest recorded mass.
The report also documented the decline of Oregon’s active glaciers from approximately 60 in the 1970s to just 27.
These seven indicators represent simultaneous record extremes across atmospheric greenhouse gases, ocean energy accumulation, global sea level, and the cryosphere.
The significance is their convergence. Greenhouse gas concentrations are increasing while ocean heat accumulation, sea-level rise, glacier loss, and Greenland ice-sheet depletion reach record extremes.
These are interconnected components of Earth’s climate system. Their simultaneous deterioration demonstrates the scale of planetary energy imbalance and the conditions driving climate feedback activation and coupling.
Global Health Emergency: The Human Cost
2026 Lancet Countdown Report
The newly released 2026 Lancet Countdown report designated climate change a global health crisis.
The report links global warming to nearly 3 million heat-related deaths between 2016 and 2023. It also warns that 60% of the human population, including 1.1 billion children, faces overlapping threats from drought, flooding, and wildfire smoke.
Climate change is no longer an environmental issue separate from public health, food security, economic stability, and human survival.
These impacts are interconnected. Heat stress affects agricultural productivity and human health. Drought and flooding threaten food supplies and infrastructure. Wildfire smoke damages respiratory health. Coastal instability threatens communities, property, and economic systems.
The consequences extend across generations.
The First Tipping-Point Season: Feedback Coupling and Amplification
The critical question is not simply how much the planet warms. It is what happens as warming changes the climate system itself.
Understanding how climate feedbacks interact—and, more importantly, how they amplify one another—is at the forefront of climate science.
Earth’s climate is not a simple thermostat in which each additional degree produces a proportionally larger but otherwise predictable effect. It is a complex, nonlinear system capable of crossing thresholds, activating self-reinforcing feedbacks, and shifting into fundamentally different states.
The first tipping-point season demonstrates that we are no longer examining tipping points solely as isolated possibilities. We are observing the interaction and coupling of climate feedbacks across interconnected planetary systems.
Once feedbacks become coupled, their combined influence changes the dynamics of the entire climate system. The resulting impacts extend beyond the original source of warming, creating additional pathways for energy redistribution, ice loss, ecological disruption, and further warming.
This is why the distinction between 2°C, 3°C, and 4–7°C cannot be understood through temperature projections alone. The behavior of the climate system, the activation of feedbacks, and the cascading consequences of destabilization matter just as much.
1.5°C: The Tripwire
The Paris Agreement’s 1.5°C threshold matters because it represents a boundary associated with increasing risks of irreversible climate-system changes.
The difference between 1.4°C and 1.5°C is not magical. The significance lies in the increasing probability of crossing thresholds that activate self-reinforcing processes.
The climate system is changing. Tipping points are becoming observable. Feedbacks are interacting. Their combined effects are accelerating climate disruption across planetary systems.
We are no longer simply approaching the tipping-point crisis. We are entering its cascading phase.
The following sources support the planetary indicators, greenhouse gas measurements, climate tipping-point research, cascading feedbacks, and human health impacts.
1. Planetary Indicators and Climate Acceleration
Copernicus Climate Change Service:Climate Indicators. Observational datasets tracking greenhouse gas concentrations, global temperatures, glacier loss, sea ice, ocean heat, and global sea-level changes.
UNEP / International Cryosphere Climate Initiative (ICCI) — November 2, 2026:Overshoot and the Cryosphere: Averting Global Meltdown. Joint scientific assessment examining the consequences of exceeding 1.5°C, including polar ice-sheet destabilization, glacier loss, declining sea ice, permafrost thaw, and changes in polar ocean systems.
Ripple et al. (2026), BioScience:The 2026 State of the Climate Report: Challenges and Opportunities. Peer-reviewed research documenting planetary vital signs, record-breaking climate indicators, accelerating warming, and changes across Earth’s interconnected climate systems.
NASA — Sea Level Change Portal:Global Sea-Level and Ice-Mass Measurements. Satellite observations and scientific data documenting global sea-level rise, Greenland and Antarctic ice loss, and ocean contributions to rising seas.
2. Climate Tipping Points and Cascading Feedbacks
Boers et al. (2025), Nature Geoscience:Destabilization of Earth System Tipping Elements. Observation-based evidence of declining stability in Greenland, Atlantic Meridional Overturning Circulation (AMOC), the Amazon, and South American monsoon systems.
Global Tipping Points Report (2023):Earth System Tipping Points. Comprehensive assessment of cryosphere, biosphere, and ocean-atmosphere tipping systems and their interactions.
Organisation for Economic Co-operation and Development (OECD):Climate Tipping Points: A Critical Moment for Action. Assessment of tipping thresholds, interactions, socioeconomic consequences, and cascading climate risks.
Nature Reviews Physics (October 2026):Tipping Points in Complex Ecological Systems. Research examining nonlinear dynamics, ecological destabilization, and cascading transitions in complex systems.
Daniel Brouse and Sidd Mukherjee (September 2026):Tipping Point Season: Climate Change Hunting Manual. Observational framework examining nine climate tipping-point systems and their interactions, coupling, and amplification.
3. Global Health Emergency
The Lancet Countdown (2026):2026 Global Report: A Decade of Escalating Health Harms. Global climate-health indicators documenting escalating threats to human health and the call to recognize climate change as a global health emergency.
World Health Organization (October 28, 2026):Climate Change Is a Growing Health Emergency. Summary of the 2026 Lancet Countdown findings and the growing public-health consequences of climate change.
Lancet Countdown — Data Explorer:Heat-Related Mortality. Underlying mortality estimates, research methodology, and attribution of heat-related deaths to human-caused climate change.
4. Additional Climate Science Resources
Indicators of Global Climate Change (2025 Update):Earth System Science Data (2026). Scientific assessment of global greenhouse gas concentrations, human influence on the climate system, and the Earth’s changing energy balance.
NASA — Global Climate Change:Vital Signs of the Planet. Climate measurements, satellite observations, and scientific explanations of global warming, greenhouse gases, sea-level rise, ice loss, and Earth’s changing climate.
European Commission — Polar and Ocean Research:Climate Tipping Points. Research resources examining polar and ocean systems, ice-sheet destabilization, and interconnected climate processes.
Let the investigations kick into high gear—and let clean, renewable energy lead the way! 🌎⚡🌱
At the top of my congressional investigation wish list: Donald Trump, Jeffrey Epstein, Energy Secretary Chris Wright, and potential crimes against humanity connected to climate policy.
The DOE Climate Working Group: Legal Violations, Ideological Networks, and Ecofascist Connections
Overview
Court rulings have established that the Department of Energy’s (DOE) Climate Working Group (CWG) violated the Federal Advisory Committee Act (FACA), a federal law requiring transparency, balanced representation, and public accountability in the operation of federal advisory committees.
The case exposes serious questions about the group’s formation, membership, ideological affiliations, and influence over federal climate policy.
Several individuals associated with the CWG have connections to the CO₂ Coalition, a nonprofit organization that challenges established climate science and promotes arguments emphasizing the benefits of atmospheric carbon dioxide.
The group’s analysis became a foundation for the Trump administration’s effort to overturn the EPA Endangerment Finding, a cornerstone of federal climate regulation. That reversal provided the administration with a basis for dismantling major climate and pollution protections.
The connections among the DOE, the CWG, fossil fuel interests, and individuals appearing in the Epstein files demand congressional investigation. Those connections include reported associations involving members of the administration and the broader climate-policy network.
Chris Wright: Fossil Fuel Industry to Secretary of Energy
Chris Wright (born January 15, 1965) is an American businessman and politician serving as the 17th U.S. Secretary of Energy.
His professional background is rooted in the fossil fuel industry.
Business Background
Liberty Energy
Wright founded and formerly served as CEO of Liberty Energy, a Denver-based energy company that became North America’s second-largest hydraulic fracturing (fracking) company.
Pinnacle Technologies
Founded in 1992, Pinnacle Technologies helped pioneer the hydraulic fracture mapping industry.
Wright’s transition from fossil fuel industry leadership to directing federal energy policy places his professional interests and policy decisions squarely within the scope of congressional oversight.
The Investigative Report: From Climate Denialism to Ecofascist Ideology
I began investigating climate denialism and the CO₂ Coalition in the spring of 2025, tracing its connections to the Department of Energy’s Climate Working Group.
My initial hypothesis centered on financial interests: fossil fuel companies and affiliated organizations fund campaigns that challenge established climate science, protect existing investments, and delay environmental regulation.
That financial motive explains part of the pattern. It does not explain the entire network.
The release of the Epstein files introduced another dimension to the investigation. Correspondence, affiliations, and publicly documented rhetoric raised questions about the intersection of elite networks, population ideology, eugenics, and environmental collapse.
The investigation therefore expanded beyond conventional climate denialism to examine the relationship between fossil fuel interests and ecofascist ideology.
Ecofascism: Environmental Collapse as a Tool of Human Elimination
Ecofascism combines environmental ideology with authoritarian hierarchy, racialized survival theories, eugenics, and the belief that certain populations are expendable.
Rather than treating environmental destruction as a threat to humanity, this ideology rationalizes unequal human survival and frames population reduction through catastrophe as beneficial.
The distinction is fundamental:
Climate denialism: Protects economic and political interests by undermining climate science and delaying environmental protections.
Eugenics: Assigns unequal value to human lives based on inherited characteristics and perceived human worth.
Ecofascism: Combines environmental collapse with authoritarian and eliminationist population ideology.
These ideas warrant examination wherever they intersect with political influence, environmental policy, and elite networks.
Epstein’s Publicly Released Statements
Publicly released statements attributed to Jeffrey Epstein include:
“I liked the argument that more CO₂ is good for plants.”
This statement echoes a central argument promoted by the CO₂ Coalition: that increased atmospheric carbon dioxide benefits vegetation through its role in plant growth.
However, the physiological benefits of additional CO₂ do not negate the destructive consequences of accelerating climate change, including extreme heat, drought, ecosystem disruption, and damage to agricultural systems.
Other statements attributed to Epstein reveal an explicit interest in population reduction, eugenics, and racial hierarchy:
“Maybe climate change is a good way of dealing with overpopulation—the earth’s forest fire. Potentially a good thing for the species.”
“Executions of the elderly and infirm make sense.”
“African music has lots of beats and little development—not an accident. It mirrors their learning process.”
These statements, if accurately attributed and understood in their documentary context, expose a worldview that extends far beyond conventional environmental policy disagreement.
They invoke population elimination, the devaluation of vulnerable people, and racialized judgments about human capability.
The Central Investigative Question
This investigation concerns more than climate science or fossil fuel industry influence.
It concerns the intersection of money, political power, ideological networks, environmental policy, and the unequal valuation of human life.
Financial interests can explain efforts to undermine climate science and obstruct regulation. Eugenic and eliminationist rhetoric raises a separate and deeply troubling question: whether environmental catastrophe is being rationalized within ideological networks that assign different values to different human populations.
The DOE Climate Working Group’s documented legal violations, its connections to climate-denial organizations, the administration’s reliance on its work, and the wider network of reported associations warrant a comprehensive congressional investigation.
Climate policy must serve humanity—not fossil fuel profits, authoritarian ideology, or theories that treat human lives as expendable.
The investigations need to follow the evidence, trace the money, expose the networks, establish accountability, and protect the public interest.
And the solution is clear: let clean, renewable energy lead the way.
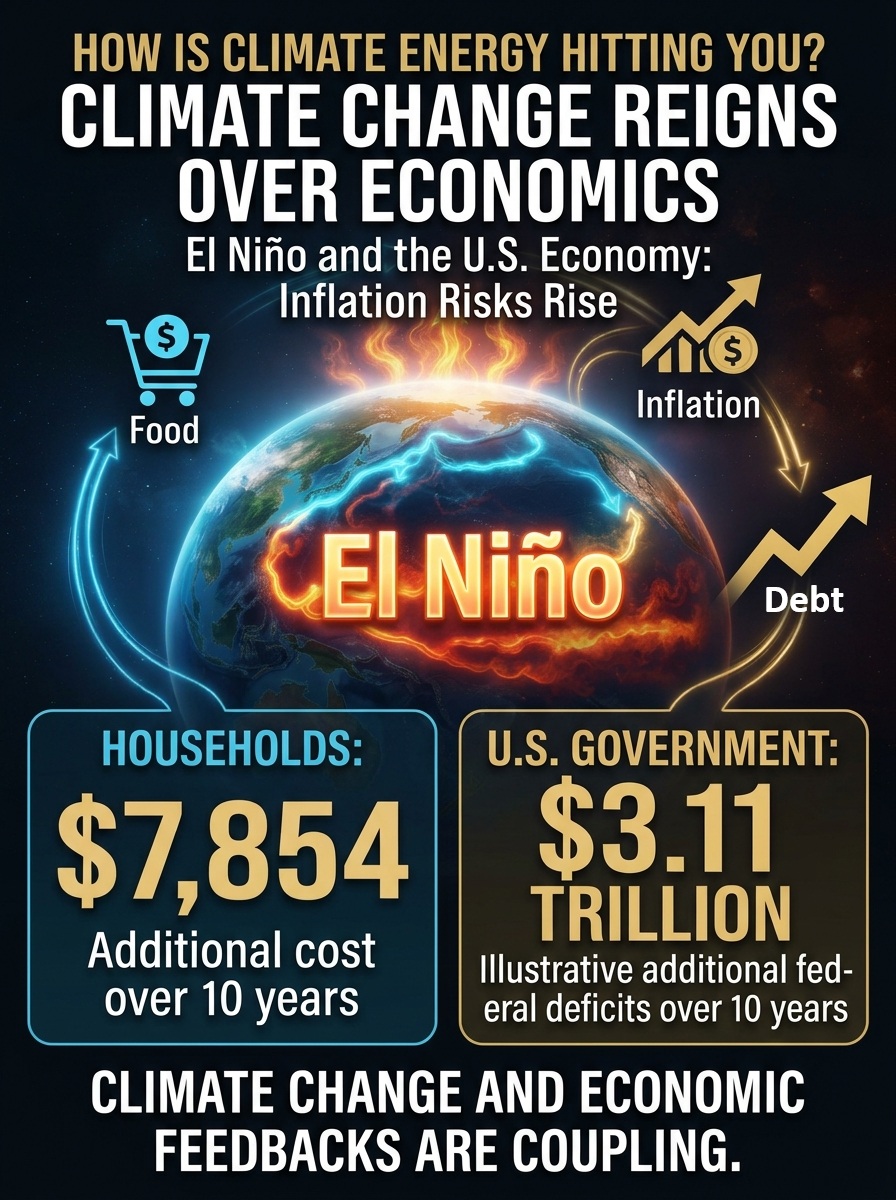
A 1-Percentage-Point Inflation Increase Could Cost Households, Increase Federal Spending, and Add Trillions to the National Debt
Federal Reserve research examines how El Niño can affect inflation, employment, household purchasing power, and the broader U.S. economy.
A new study from the Federal Reserve Bank of San Francisco identifies a significant economic risk associated with the current El Niño episode: U.S. inflation could increase by as much as 1 percentage point in 2027.
Although the initial price effects of the current episode are projected to fade by the end of 2026, historical estimates suggest that longer-term inflationary effects could emerge during 2027. These effects are linked primarily to core services and food prices, with the magnitude influenced partly by whether a La Niña episode follows El Niño.
The study also identifies potential employment gains, which may be widespread across industries and states during the year following El Niño.
An additional percentage point of inflation may sound relatively small, but its economic consequences extend far beyond higher grocery bills. It affects household purchasing power, government expenditures, interest rates, federal deficits, and the national debt.
1. What a 1-Percentage-Point Increase in Inflation Means for Household Budgets
The Federal Reserve study identifies an inflationary effect of as much as 1 percentage point in 2027.
Based on U.S. Bureau of Labor Statistics consumer expenditure data, the average American consumer unit spent approximately $78,535 annually in 2024.
An additional 1 percentage point of inflation, relative to the baseline, would translate into approximately $785 in additional annual household expenses, or about $65 per month.
Additional household expense
Amount
Monthly
$65.45
Annual
$785
Five years
$3,927
Ten years
$7,854
Illustrative calculations assume the additional 1% price-level difference persists, without further compounding.
The actual impact will vary depending on household spending patterns, particularly exposure to food, housing, transportation, and services.
The important distinction is that even when inflation subsequently slows, the higher price level generally remains. A reduction in the inflation rate does not reverse the previous price increases.
2. The National Economic Impact
The BLS reports approximately 135.76 million U.S. consumer units.
Applying the additional 1% expenditure to the national average produces an estimated:
$106.6 billion in additional annual household spending.
This is an illustrative national extrapolation, not a forecast of actual consumer spending. It demonstrates the potential economic scale of a relatively small change in the overall price level.
The consequences extend beyond consumer purchases:
Prices rise faster than otherwise expected.
Households pay more for food, services, and other necessities.
Higher price levels generally persist even after inflation subsequently slows.
Families whose incomes fail to keep pace with inflation experience declining purchasing power.
The effects also extend into employment, business operating costs, government expenditures, and financial markets.
3. Inflation and the Federal Budget
The combination of higher inflation and higher interest rates creates another economic challenge: the cost of financing the federal government.
The government faces pressure from two directions simultaneously.
Higher inflation increases government expenditures.
Social Security cost-of-living adjustments, federal contracts, military procurement, healthcare expenditures, and other government programs can become more expensive.
Higher interest rates increase the cost of financing the national debt.
As Treasury securities mature, the government must refinance portions of its outstanding debt at prevailing market rates. New borrowing also becomes more expensive.
The consequences extend beyond the immediate federal budget because additional interest payments contribute to future deficits and borrowing requirements.
The United States already carries an enormous national debt. Even relatively small changes in borrowing costs can translate into substantial additional federal expenditures.
4. What the Congressional Budget Office Estimates
The Congressional Budget Office (CBO) has examined how changes in inflation and interest rates affect federal revenues, expenditures, and deficits.
Its April 2026 analysis, How Changes in Economic Conditions Might Affect the Federal Budget: 2026 to 2036, provides useful estimates.
CBO examined a scenario in which inflation and nominal interest rates were each 0.1 percentage point higher every year than projected in its baseline forecast.
The resulting estimates include:
Federal budget impact
Additional cost
Cumulative deficits, 2027–2036
$311 billion
Higher direct interest costs
$339 billion
Additional interest from increased borrowing
$48 billion
The $311 billion figure represents the estimated net increase in cumulative deficits, not the sum of the interest-cost components.
CBO’s sensitivity methodology provides a way to examine the potential consequences of larger changes.
For perspective, scaling its combined inflation-and-interest-rate scenario to a sustained 1-percentage-point increase in both variables produces an illustrative estimate of approximately:
$3.11 trillion in additional federal deficits over ten years.
This is a sensitivity calculation based on CBO’s model, not a prediction of the fiscal consequences of the current El Niño episode. It assumes the changes persist relative to the baseline throughout the projection period.
CBO also separately estimates that a sustained 0.1-percentage-point increase in interest rates alone would add approximately $379 billion to cumulative deficits over the same decade.
These scenarios should not be added together because they represent different economic assumptions.
5. The National Debt Feedback Loop
Inflation and interest rates can reinforce existing fiscal pressures.
The inflation-debt spiral:
Higher inflation increases government expenditures.
Higher interest rates make Treasury refinancing more expensive.
Larger expenditures and interest payments increase federal deficits.
Larger deficits require additional government borrowing.
Additional borrowing increases the national debt.
More debt eventually requires additional interest payments.
The result is increasing interest obligations and greater fiscal pressure.
This does not mean every increase in inflation automatically produces an equivalent increase in interest rates. Monetary policy, economic growth, Treasury market conditions, and inflation expectations all influence the outcome.
However, the combination presents a significant risk to long-term fiscal stability.
6. What Does This Mean for Taxpayers?
The consequences extend well beyond the federal budget.
More tax revenue is directed toward servicing debt rather than public services and investment.
Government borrowing competes with private investment for available capital.
Higher borrowing costs can affect mortgages, business loans, and consumer credit.
The government’s ability to respond to future economic emergencies becomes more constrained.
A 1-percentage-point increase in inflation accompanied by a 1-percentage-point increase in interest rates has implications for federal spending, debt financing, and future taxation.
The approximately $3.11 trillion CBO sensitivity calculation illustrates the potential scale of the problem under sustained changes in both variables. It should not be interpreted as the actual projected cost of El Niño.
The outcome depends on how long inflation persists, how Treasury yields respond, and how quickly outstanding federal debt reprices.
7. Climate and Economics: The Bigger Picture
The economic implications of El Niño demonstrate how climate patterns can influence more than agriculture and weather-related disruptions.
They can affect:
Consumer prices and household purchasing power.
Employment and labor markets.
Government expenditures and federal deficits.
Interest rates and the cost of financing debt.
Long-term economic stability.
The economic implications of climate change extend well beyond the direct costs of storms, droughts, flooding, and extreme temperatures.
El Niño provides another example of how climate variability can transmit economic pressure through interconnected systems.
Climate risk is economic risk.
Understanding these connections is increasingly important for forecasting inflation, evaluating fiscal exposure, managing financial risks, and planning for the years ahead.
Insurance and Real Estate | Financial Analysis | Independent Climate Research | Physics and Climate Systems
Overview
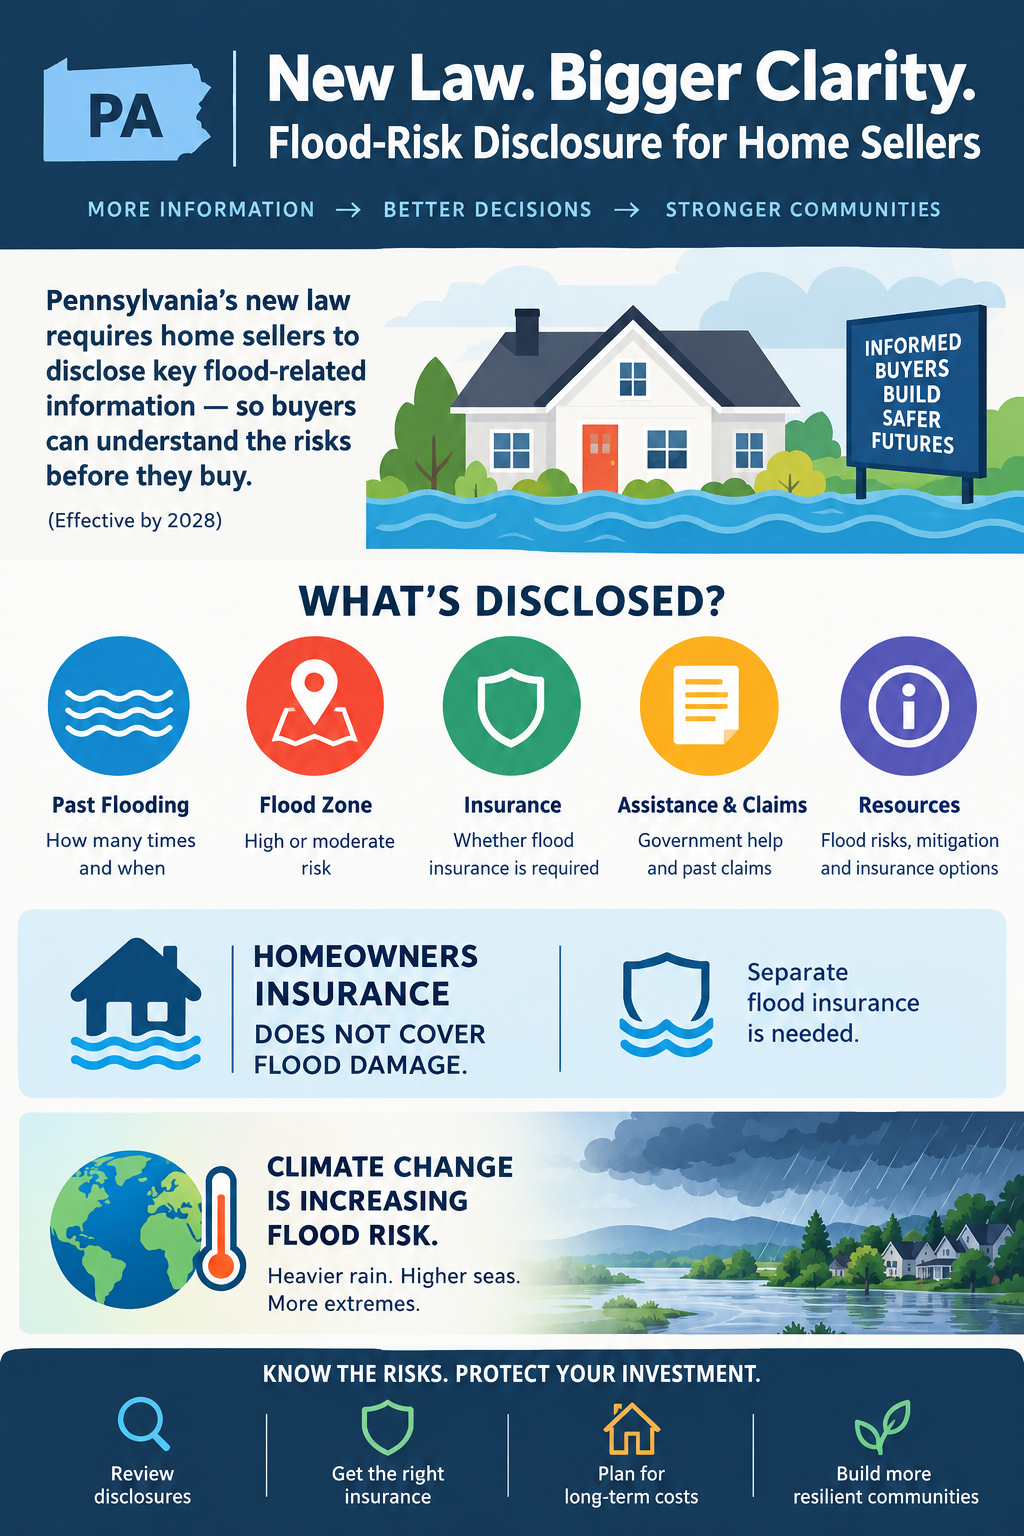
🏠 PENNSYLVANIA’S NEW FLOOD-RISK DISCLOSURE LAW: WHAT HOME BUYERS NEED TO KNOW
A home may be your biggest investment. Do you know its flood risk—and whether your insurance will cover the damage?
Pennsylvania’s new flood-risk disclosure law brings an important issue into focus: flood risk is not just an environmental problem. It is an insurance, real estate, financial planning, and consumer protection issue.
The paper, Flood-Risk Disclosure Is Financial Risk Management: Pennsylvania’s New Law and the Growing Climate Liability of Real Estate, Daniel Brouse and Sidd Mukherjee, examine the implications of this legislation and why informed property decisions matter.
Drawing on previous work in insurance, real estate, financial analysis, physics, and climate research, the paper explores:
• What Pennsylvania’s new law means for home buyers and sellers.
• Why standard homeowners insurance generally does not cover flood damage.
• How flood exposure can affect property values, insurance costs, and household finances.
• How climate change, better disclosure, insurance planning, and practical mitigation fit together.
• Why renters, existing homeowners, and taxpayers also have a stake in flood-risk awareness.
The bottom line: A property’s purchase price tells only part of the story. Buyers need to understand the risks, insurance limitations, and potential future expenses associated with owning it.
The conclusion is simple: Know the risks. Protect your investment. Build more resilient communities.
Pennsylvania’s new flood-risk disclosure law recognizes a fundamental principle of responsible financial decision-making: people cannot adequately evaluate a property’s financial risks when material information about those risks is unavailable or undisclosed. Signed into law on October 22, 2026, House Bill 1704 strengthens residential real estate disclosures concerning flood history, flood insurance, and related risk factors. The law also directs the Pennsylvania Insurance Department to provide public information about flood risks, mitigation, and insurance options.
This legislation has implications extending well beyond real estate transactions. Flood risk affects property valuation, mortgage lending, insurance adequacy, household financial security, municipal budgets, and taxpayer exposure. Climate change adds another dimension by altering the conditions under which property risks must be evaluated. Historical flood records and existing hazard maps are important, but they cannot, by themselves, establish the full range of future risks.
Drawing on decades of experience in insurance, real estate, financial analysis, and independent climate research, this paper argues that Pennsylvania’s legislation is an important step toward more informed property transactions. It also identifies the limitations of disclosure alone and the need for integrated climate-risk assessment, transparent insurance information, forward-looking property valuation, and financially responsible adaptation.
1. Introduction: The Financial Consequences of Undisclosed Risk
Pennsylvania has taken an important step toward protecting homebuyers from financial losses they may not anticipate when purchasing residential property.
On October 22, 2026, Governor Josh Shapiro signed House Bill 1704 into law. As reported by WHYY on October 27, the legislation expands the information residential property sellers must disclose about flooding and related risks. Compliance with the revised disclosure requirements is scheduled for the summer of 2028. WHYY’s report on the new law.
The underlying issue is straightforward: purchasing a home is one of the largest financial commitments most households make. Buyers need accurate information about the property’s condition, operating expenses, insurability, and exposure to foreseeable losses. When important risks are not adequately communicated, buyers can make decisions based on an incomplete assessment of the property’s true financial cost.
My professional experience spans real estate, mortgage banking, financial planning, accounting, and financial analysis. My independent climate research, which began in 1992, has focused on the physical processes driving climate change and the implications of a changing climate for human systems.
These fields converge on a common principle: risk that is omitted from a financial decision does not disappear. It remains a potential liability.
Flood-risk disclosure is therefore not simply a paperwork requirement. It is part of the larger responsibility to ensure that property buyers, lenders, insurers, and communities can make informed decisions about the assets and liabilities they assume.
2. What Pennsylvania’s New Law Requires
House Bill 1704 amends Pennsylvania’s residential real estate disclosure provisions under Title 68 of the Pennsylvania Consolidated Statutes.
The legislation strengthens the information buyers receive about flood-related risks. Among the provisions described in the enacted legislation and WHYY’s reporting are requirements concerning:
The number of times a property has experienced flooding and the estimated dates of those incidents.
Whether a property is located in a Federal Emergency Management Agency-designated high- or moderate-risk flood zone.
Whether flood insurance is required for the property.
Whether the seller has received government assistance for flood damage.
Whether the seller has filed a flood insurance claim.
The law also directs the Pennsylvania Insurance Department to publish information about flood-risk factors, mitigation measures, insurance coverage, and resources for identifying properties in flood-hazard areas.
The revised disclosure process will include a written notice advising prospective buyers that many Pennsylvania properties face flood risks and that standard homeowners insurance typically does not cover flood damage. Buyers are encouraged to consult insurance professionals and investigate separate flood coverage.
These requirements are significant because they connect property disclosures with practical financial decisions. Buyers need to know not only whether a property has flooded but also whether the insurance they expect to protect their investment will actually cover the loss.
The important distinction is between knowing that a risk exists and understanding the financial consequences of that risk. Effective disclosure should help buyers investigate both.
3. The Insurance Problem: Homeowners Coverage Is Not Flood Coverage
One of the most consequential misconceptions in residential property ownership is that a standard homeowners insurance policy covers every major source of property damage.
It does not.
Standard homeowners policies generally exclude flood damage. Flood insurance is typically purchased separately, either through the National Flood Insurance Program or an eligible private insurer. Coverage terms, exclusions, limits, deductibles, and eligibility vary by policy.
This distinction can have severe financial consequences.
A buyer may purchase a home, obtain a mortgage, and maintain homeowners insurance while remaining exposed to substantial flood losses. The existence of an insurance policy does not establish that the property is adequately insured against every material hazard.
From an insurance and financial-planning perspective, this is a problem of incomplete risk transfer. The homeowner retains a potentially substantial uninsured liability.
A flood can damage structural components, electrical systems, heating and cooling equipment, appliances, flooring, furnishings, and personal possessions. Recovery may involve temporary housing, repairs, reconstruction, and expenses that continue while a property is uninhabitable. Actual coverage depends on the applicable policies and circumstances.
The financial consequences extend beyond the initial repair bill. Flood damage may affect resale value, future insurance costs, mortgage affordability, and the amount of money a household can preserve for retirement or other needs.
This is why the insurance question must be addressed before a transaction closes.
Buyers should determine:
What hazards the homeowners policy covers and excludes.
Whether separate flood insurance is available and appropriate.
What the policy limits, deductibles, exclusions, and waiting periods are.
Whether the coverage is sufficient to address the property’s actual replacement and recovery costs.
How premiums and other carrying costs affect the household’s long-term budget.
Pennsylvania’s new law directs attention to these questions. Its broader value will depend on whether buyers use the information to evaluate their actual exposure rather than treating disclosure as another form to sign.
4. Real Estate Valuation Must Account for Risk
Real estate valuation is not simply a matter of comparing square footage, location, amenities, and recent sales.
A property’s economic value also depends on the costs and risks associated with owning it.
Flood exposure can affect insurance premiums, repair and maintenance expenses, financing conditions, marketability, and the potential for future losses. Two otherwise comparable properties may therefore have materially different economic profiles.
A waterfront home, for example, may offer exceptional recreational value, scenic views, and personal enjoyment. Those benefits may justify a higher purchase price for a particular buyer. However, the same property may carry additional insurance expenses, mitigation costs, and exposure to flooding.
There is no universal answer to whether a property with elevated flood risk is a good investment. That determination depends on the buyer’s objectives, financial resources, risk tolerance, insurance options, and the property’s specific characteristics.
The essential requirement is informed consent to the financial risk.
My experience in real estate and mortgage banking reinforces the importance of distinguishing a property’s purchase price from its total cost of ownership. A transaction can appear affordable at closing while creating substantial future expenses that were not incorporated into the buyer’s original budget.
A more complete financial assessment should consider:
Purchase price and financing costs.
Property taxes and ordinary maintenance.
Homeowners and flood insurance premiums.
Expected mitigation and resilience investments.
Potential deductibles and uninsured losses.
The implications of future hazard changes for resale and financing.
Not every risk can be expressed as a precise dollar amount. Nevertheless, acknowledging uncertainty is better financial practice than treating an incomplete estimate as a comprehensive valuation.
A property’s market price does not automatically reflect its full climate-related financial risk.
Improved disclosures can help correct that information gap, although disclosure alone cannot guarantee that prices, insurance premiums, or lending decisions will fully reflect future exposure.
5. Climate Change Changes the Risk-Assessment Problem
Flood risk is not determined by property history alone. It also depends on precipitation, drainage, topography, river conditions, coastal processes, land development, infrastructure, and the changing physical environment.
Climate change adds an important consideration: historical conditions are not necessarily a complete guide to future conditions.
Warmer air can hold more water vapor, increasing the potential for heavier precipitation under suitable atmospheric conditions. Changes in precipitation patterns can affect runoff, streamflow, drainage systems, and flood hazards. The resulting effects vary by location and depend on local geography, infrastructure, and other factors.
At the same time, flooding can occur outside formally designated high-risk zones. Localized rainfall, overwhelmed drainage systems, changing waterways, and other conditions can produce losses that a buyer might not anticipate from a single map or a property’s previous history.
This does not mean every property will experience increasing flood risk at the same rate. Nor does climate change eliminate the value of historical flood records or FEMA flood maps. Both remain important sources of information.
It means that risk assessment should consider multiple sources of evidence and distinguish present conditions from future possibilities.
My climate research has focused on the interaction of climate processes, feedbacks, and changes in the Earth’s energy system. That work informs a broader concern about financial risk: physical systems can change, and risk assessments that assume past conditions will continue indefinitely can become inadequate.
The appropriate response is not to disregard established flood maps. It is to use them alongside other relevant information, including local flood histories, drainage conditions, infrastructure assessments, updated hazard analyses, and credible forward-looking projections.
For real estate, the distinction is critical. A disclosure based on what a seller knows about past flooding serves a different purpose from a scientific assessment of what could happen to the property over the coming decades.
Historical disclosure documents the past. Climate-informed risk assessment helps evaluate the future. Both are necessary for sound decisions.
6. Disclosure Is Consumer Protection and Fiscal Responsibility
The economic benefits of better disclosure extend beyond individual buyers.
When a homeowner experiences a major uninsured loss, the consequences may include depleted savings, additional borrowing, delayed repairs, mortgage distress, or the loss of accumulated household wealth.
Public assistance may help some affected households, but disaster assistance is not a substitute for comprehensive insurance and does not guarantee full compensation for losses.
Flood damage can also affect local governments through emergency response expenses, infrastructure repairs, drainage improvements, and other recovery costs. Public insurance programs and disaster assistance may expose taxpayers to additional financial obligations.
These consequences connect private property decisions to public fiscal responsibility.
Better disclosure can help buyers make more informed choices about whether to purchase a property, obtain insurance, invest in mitigation, or reconsider the transaction. It can also encourage earlier investments in measures that reduce potential losses.
Depending on the property and hazard, mitigation may include improving drainage, protecting critical equipment, installing appropriate flood-resistant materials, elevating vulnerable components, or undertaking professionally designed structural improvements.
Not every mitigation measure is appropriate for every property, and its cost-effectiveness should be evaluated individually.
Nevertheless, identifying a risk before a loss occurs generally provides more opportunities to plan than discovering it after the damage is done.
Pennsylvania’s legislation addresses one part of this problem by strengthening the flow of information between sellers and buyers. The next challenge is to ensure that the information supports practical decisions rather than merely satisfying a disclosure requirement.
7. The Remaining Gap: Renters and Existing Property Owners
The new law primarily addresses residential property sales. It does not establish a comparable general flood-risk disclosure requirement for landlords and renters.
That distinction matters.
Renters can face serious financial consequences from flooding, including damage to personal belongings, displacement, temporary housing expenses, and interruptions to employment or daily life. A landlord’s building insurance does not necessarily cover a tenant’s personal possessions or additional living expenses.
Tenants may also have limited control over building-level mitigation measures and may not know whether a property has flooded previously.
The absence of equivalent disclosure requirements for renters leaves an important consumer-information gap. WHYY reports that a separate proposal concerning flood disclosures for rental properties had not advanced beyond committee referral as of its October 27, 2026, report.
A comprehensive approach to flood-risk communication should consider both owners and tenants, while distinguishing the respective responsibilities of property owners, insurers, and occupants.
Existing homeowners also need access to understandable information about their current exposure. They should not have to wait until they sell their homes to discover that their insurance coverage is inadequate or that local flood conditions warrant further investigation.
The public information resources required by House Bill 1704 can help address this broader need, provided they remain accessible, useful, and responsive to changing information.
8. Recommendations for a More Comprehensive Approach
Pennsylvania’s new law creates an opportunity to strengthen the relationship between real estate transactions, insurance decisions, climate adaptation, and financial planning.
Several additional measures would build on its foundation.
A. Make flood-risk information accessible before an offer is made
Buyers should be encouraged to investigate flood history, mapped hazards, insurance requirements, and available coverage early in the purchasing process. Discovering significant costs after making a binding commitment can leave buyers with fewer practical options.
B. Distinguish historical records from forward-looking risk
Disclosure forms should communicate what is known about past flooding without implying that a property with no documented history is free from risk. Public resources should help buyers understand the limitations of historical records and hazard maps.
C. Encourage insurance review before closing
Buyers should obtain quotes and review relevant policy terms before finalizing a purchase. This allows insurance costs, deductibles, exclusions, and coverage availability to inform the household budget and purchase decision.
D. Incorporate climate risk into property and infrastructure planning
Local governments, lenders, insurers, and property owners should evaluate relevant forward-looking hazard information when making long-term decisions. The appropriate analysis will differ between inland river flooding, localized stormwater flooding, and coastal exposure.
E. Expand consumer education
Disclosure is most effective when people understand what the information means. Public education should explain the difference between homeowners insurance and flood insurance, how to investigate risk, what mitigation can accomplish, and where to obtain qualified advice.
F. Evaluate affordability and financial feasibility
Some households have limited alternatives when searching for affordable housing. Better information cannot, by itself, resolve that constraint. Policy responses should recognize the need to balance risk awareness with practical access to housing and the cost of mitigation and insurance.
G. Improve transparency across the property lifecycle
Risk information should not be viewed solely as a requirement at the point of sale. Property owners, renters, insurers, lenders, and local officials all benefit from accessible information that supports ongoing risk management.
These recommendations are consistent with a basic principle of financial analysis: identify material risks, estimate their potential consequences, evaluate the available responses, and make decisions with a clear understanding of the remaining uncertainty.
9. Integrated Climate Stewardship and Property Risk
My broader approach to climate solutions is called Integrated Climate Stewardship. It emphasizes reducing avoidable resource consumption and climate impacts while directing resources toward practical benefits and resilience.
Applied to real estate, this framework supports a comprehensive approach to property risk rather than treating flood disclosure, insurance, energy use, infrastructure, and climate adaptation as unrelated issues.
A property is part of a larger system. Its financial performance depends not only on the building itself but also on the surrounding environment, public infrastructure, insurance market, utilities, and community resilience.
The same principle applies to climate risk. Effective management requires attention to both the physical hazard and the economic systems that determine who bears the losses.
For an individual homeowner, that may mean evaluating insurance coverage, reducing avoidable exposure, and making cost-effective improvements. For a community, it may mean improving drainage, maintaining infrastructure, updating hazard assessments, and evaluating development decisions against long-term risks.
For lenders and insurers, it means recognizing that reliable risk information is essential to assessing potential losses. For policymakers, it means considering the distribution of costs among property owners, private insurers, public programs, and taxpayers.
This is not an argument that every climate-related risk can be eliminated. It is an argument that avoidable financial exposure should not be ignored simply because the relevant costs may occur years after a transaction.
10. Conclusion: Disclosure Is the Beginning, Not the End
Pennsylvania’s new flood-risk disclosure law establishes an important principle for residential real estate: prospective buyers deserve more complete information about a property’s flood history and related insurance considerations.
That principle aligns with longstanding practices in responsible insurance, real estate, and financial analysis. A major financial commitment should be based on an informed assessment of material risks, not merely on the purchase price or the assumption that existing insurance covers every foreseeable loss.
The legislation is a meaningful step, but its limits must be understood. Disclosure does not prevent flooding, guarantee affordable insurance, eliminate uninsured losses, or ensure that property values accurately reflect future climate conditions. Its effectiveness will depend on implementation, public understanding, and the decisions that buyers and other stakeholders make with the information provided.
Climate change adds urgency to the broader question of how society evaluates long-lived assets. Homes, mortgages, infrastructure, and insurance arrangements often extend across decades. Risk assessments that rely exclusively on past conditions can leave households and institutions exposed when relevant conditions change.
My experience in insurance, real estate, mortgage banking, financial analysis, and climate research leads to one central conclusion:
Sound property ownership requires more than knowing what a home costs today. It requires understanding the risks, liabilities, and future expenses that come with owning it.
Pennsylvania’s new law moves the state toward that objective. The next step is to connect better disclosure with informed insurance decisions, climate-aware valuation, practical mitigation, and financially responsible planning.
The goal should be straightforward: fewer preventable losses, better-informed buyers, more resilient communities, and less avoidable financial risk for homeowners and taxpayers alike.
This paper presents professional and analytical commentary on flood-risk disclosure, insurance, real estate, and climate adaptation. It is not legal, insurance, investment, or property-specific advice.
Why the Age of Artificial Intelligence Requires a New Economic Model
By Daniel Brouse
The Economic Challenge of Artificial Intelligence
We need a new economic model that separates people’s ability to earn a living from the necessity of working for a living.
As artificial intelligence (AI) and automation transform the economy, traditional employment may no longer provide a reliable source of income for everyone. Machines can increasingly perform tasks that once required human labor, raising productivity while potentially eliminating jobs and weakening the link between employment and economic security.
One approach worth serious consideration is a $60,000 annual government stipend per person, funded in part by taxing pollution while eliminating income taxes. This would shift the tax burden away from human productivity and toward activities that impose environmental costs, while providing people with a more secure share of the economy’s productive output.
This is a proposed economic model, not an established policy. Its implementation would require careful consideration of funding, inflation, eligibility, existing public benefits, and the distribution of economic gains.
The Productivity and Disinflation Wildcard
Another important variable is the relationship between productivity gains and disinflation.
AI-driven improvements in productivity and efficiency could sharply reduce the cost of producing goods and services. As automation reduces labor requirements and technological advances improve resource utilization, prices could decline even as total economic output increases.
This creates an important possibility: We could produce more while requiring less human labor and fewer resources.
If these productivity gains translate into lower consumer prices, a given income could purchase more goods and services. The result could be a substantial improvement in living standards, provided the benefits reach consumers rather than being captured primarily as corporate profits.
However, lower production costs do not automatically translate into lower prices. Market competition, ownership, energy costs, access to resources, and corporate pricing decisions will influence how much of the savings consumers receive. Nor does greater productivity guarantee that every sector will experience falling prices.
The central economic challenge is to ensure that the benefits of technological progress are broadly shared rather than concentrated among a small number of business owners and investors.
We cannot stop technological progress, but we can redesign our economic system to distribute its benefits more equitably.
Global Responses: Policies Already Under Consideration
The economic transition driven by AI is not a distant possibility. It is already underway. Governments worldwide are considering different ways to address technological disruption, economic inequality, and the distribution of productivity gains.
These initiatives differ in their objectives and scope. Some involve direct cash payments, others explore basic income, and still others seek to capture more public revenue from digital economic activity. They provide examples of the policy options emerging as governments respond to a changing economy.
Taiwan: Proposed Cash Distribution
In August 2026, President Lai Ching-te announced plans for a NT$10,000 cash payment to eligible residents through the 2027 budget. The government cited strong economic growth driven by global demand for AI-related products and sought to share some of the benefits of that growth.
The proposal was referred for legislative review in October 2026. The planned distribution should therefore be understood as a proposed measure, not a completed payment program.
European Union: Debate Over AI Taxation
European policymakers and tax experts are examining how AI-driven automation could erode payroll-tax revenue used to fund pensions, healthcare, and other social programs.
Proposals include shifting more taxation toward corporate profits and exploring ways to capture economic value generated by AI. Direct taxation of AI systems or AI-generated work has also entered the policy debate, although no EU-wide AI-worker tax has been enacted.
The underlying concern is straightforward: If machines perform a growing share of economically valuable work, governments may need to reconsider how they fund public services traditionally financed through taxes on human employment.
South Korea: Basic-Income Proposals
South Korean political leaders, including Lee Jae-myung, have advocated basic-income policies amid concerns about economic inequality, automation, and employment disruption.
These proposals reflect a broader debate about whether traditional employment-based income distribution will remain adequate as AI changes the relationship between labor, productivity, and economic output.
The policy question is how to ensure that technological progress improves living standards across society, including for people whose jobs are displaced or whose bargaining power declines.
The Marshall Islands: Nationwide Universal Basic Income
In November 2025, the Marshall Islands launched its ENRA universal basic income program, providing regular distributions to eligible citizens.
The program uses multiple payment channels, including a dedicated digital wallet. It demonstrates how modern financial infrastructure can support nationwide cash transfers.
The program is funded through the country’s Compact Trust Fund rather than an AI-specific tax. Although it was not created as a response to AI-driven unemployment, it provides a real-world example of a government implementing regular, broadly distributed public payments.
Kenya: Taxation of the Digital Economy
Kenya has pursued taxation of digital economic activity as governments seek to capture revenue from an increasingly digital global economy.
In December 2024, Kenya replaced its 1.5% digital services tax with a 3% significant economic presence tax applying to qualifying nonresident digital businesses, subject to the relevant rules.
This approach illustrates one way to tax economic activity that may not fit traditional models of physical presence and employment. It is not specifically an AI tax or a universal basic-income funding mechanism, but it contributes to the broader discussion about how tax systems must evolve as technology changes how businesses generate revenue.
The United States: A Proposed AI Sovereign Wealth Fund
In June 2026, Senator Bernie Sanders introduced the American AI Sovereign Wealth Fund Act, proposing public ownership of a portion of qualifying AI companies through a federally managed sovereign wealth fund.
The proposal calls for a one-time transfer of 50% of the stock of qualifying AI companies with at least $200 million in annual AI sales. The fund would hold these shares and distribute public benefits, including annual dividends, while supporting priorities such as healthcare, education, and housing.
The legislation remains a proposal, not enacted law. Its approach differs from a universal stipend funded through environmental taxation, but it addresses the same fundamental question: Who should benefit from the wealth created by increasingly powerful technologies?
A sovereign wealth fund could give the public a direct financial stake in AI-generated economic value. A universal stipend funded through taxation would pursue a similar distributional objective through a different mechanism.
Both approaches raise important questions about implementation, governance, funding, and the long-term relationship between private ownership and public benefit.
The Broader Economic Implication
These examples represent different approaches to a common challenge: distributing the benefits of economic growth when technological progress reduces the need for human labor.
They are not all AI-specific initiatives, and none establishes that a permanent $60,000 annual stipend is already a widely adopted policy. Nevertheless, they demonstrate that governments are exploring alternatives to relying exclusively on employment-based income and conventional payroll taxation.
The essential question is becoming increasingly important:
As AI and automation increase productivity while reducing the need for human labor in some occupations, how should society distribute the resulting economic gains and finance essential public services?
Universal basic income, public dividends, sovereign wealth funds, digital-economy taxation, and environmental tax reform are among the approaches worth examining.
Productivity, Human Welfare, and Environmental Sustainability
AI presents both an economic challenge and an opportunity.
If technological progress allows society to produce more goods and services with fewer labor hours and less resource consumption, the potential benefits extend beyond corporate profitability. People could enjoy greater economic security, more free time, lower living costs, and improved access to essential goods and services.
Realizing those benefits requires more than technological innovation. It requires economic institutions that translate productivity gains into broadly shared prosperity.
Environmental taxation offers a complementary opportunity. Taxing pollution while reducing or eliminating taxes on income could encourage cleaner production while reducing the financial penalty on human work. The actual environmental and economic results would depend on tax design, implementation, and how revenues are distributed.
The goal should be an economic system that rewards innovation, supports human welfare, and accounts for environmental costs rather than treating them as someone else’s problem.
Conclusion: Adapt the Economy to the Technology
The transition to AI-driven productivity is already underway. Attempting to preserve every existing job or slow technological obsolescence indefinitely is not a sustainable strategy.
The more important task is to prepare society for an economy in which human labor may no longer be the primary constraint on production.
A guaranteed annual stipend, pollution-based taxation, reduced reliance on income taxes, and mechanisms for distributing AI-generated wealth are possible elements of a new economic model. Productivity-driven disinflation could further improve affordability if lower production costs translate into lower consumer prices.
None of these outcomes is automatic. They depend on policy choices, economic incentives, market structures, and how society chooses to distribute the benefits of innovation.
We cannot stop technological progress. We can decide whether its benefits are concentrated among a few or shared throughout society.
The objective should be clear: an economy that turns technological productivity into human prosperity while advancing environmental sustainability.
Note From the Author
We are likely facing the most profound economic revolution in human history, and we are dangerously unprepared for its consequences.
Ironically, the U.S. has ignored our most significant existential risk: climate change. The acceleration of Earth’s energy imbalance is already well underway, with consequences that extend far beyond rising temperatures. The economic damage is enormous and growing, with estimates reaching trillions of dollars annually and potentially tens of trillions by midcentury, depending on the scenario and methodology.
Here’s the irony: AI may be our best hope for solving the climate crisis. Its ability to accelerate scientific research, optimize energy systems, improve efficiency, and develop new technologies could help us respond at the scale and speed required.
But just as with climate change, technological capability alone isn’t enough. We need the political will and economic framework to put those capabilities to work for the public good.
Much of the public discussion of climate change still focuses on historical trends and older climate models. Since 2023–2024, however, our understanding of the climate system has advanced significantly as scientists increasingly examine real-time observations, accelerating changes, feedback loops, and complex Earth system behavior.
Understanding climate acceleration no longer requires multiple advanced degrees or an extensive background in nonlinear chaos theory. The evidence is increasingly visible in the world around us. In many ways, you can begin by simply looking out your window.
Florida Keys: Going Under
Dave Darlington Sr. shared this observation from Tavernier, Florida:
“Our last morning here in Tavernier, I wanted to speak to climate change. Some say it’s a hoax, but as the planet warms, glaciers and ice melt and salt water rises. Change is needed or future generations won’t enjoy what we have. Fran and I have come to this area since 1986 and seen profound change here. I wanted to share it with you. Until this administration cast off the ecologic safeguards there was hope. Will everyone do something? Now we are at a crucial point, vote carefully. Or throw it all away.”
Going Under
The photograph captures the ongoing threats of coastal flooding, tidal inundation, and saltwater intrusion driven by sea-level rise in this low-lying Florida Keys community.
Because these islands sit on highly porous limestone, rising seas threaten them from two directions: seawater can inundate the shoreline and push inland through the ground beneath it. These growing risks have prompted multimillion-dollar infrastructure projects in Tavernier and surrounding communities to protect homes, roads, and other critical infrastructure.
Unfortunately, much of this investment risks becoming a losing battle against accelerating sea-level rise. Over the next decade, protecting the most vulnerable areas will become increasingly difficult and expensive as rising seas intensify the threats facing coastal infrastructure. Managed retreat—planning for the relocation of people, homes, and infrastructure away from areas that can no longer be defended—is the only realistic long-term solution in the most vulnerable locations.
The underlying problem is physical: infrastructure can be elevated, drainage improved, and seawalls strengthened, but these measures cannot permanently overcome rising seas.
Insurance: When the Economics No Longer Work
Given the extent of climate damage already locked into the system, insurance prices serve a purpose beyond determining the cost of coverage. They increasingly reveal where the risks of homeownership are becoming economically unsustainable.
When homeowners insurance becomes unaffordable, it signals that the financial risks of owning property in that location may no longer justify the investment. Premiums, deductibles, coverage restrictions, and the growing difficulty of obtaining insurance all reveal the economic consequences of physical climate risks.
This is the interaction of physics and economics: as climate hazards intensify, the costs of protecting property rise. Eventually, the expense of maintaining and insuring a home can exceed what the property is worth owning.
Ironically, Florida became a prime example of how government intervention can subsidize homeowners insurance and delay the financial recognition of growing climate risks. Such subsidies may temporarily reduce costs for property owners, but they do not eliminate the underlying physical hazards. They shift the financial burden to taxpayers.
Dave responded: “Makes sense to me, that is one reason we left south Florida after Hurricane Andrew.”
His experience illustrates a difficult reality: people who recognize escalating risks and leave vulnerable areas may make their decisions long before the broader housing and insurance markets fully reflect those risks.
The bottom line: Climate change is not just a distant environmental problem. It is reshaping coastlines, threatening infrastructure, increasing insurance costs, and changing the economics of where people can safely and affordably live. The evidence is already visible. The challenge is recognizing what it means—and acting before the costs become overwhelming.
Trump promises to put America first. But his policies tell a different story.
From fossil-fuel subsidies and Russian diesel imports to government intervention, mounting economic burdens, and policies that deepen inequality, the contradictions are impossible to ignore.
Who pays the price? American families, the most vulnerable, and future generations.
Promises versus reality. Political rhetoric versus consequences.
The result: ideological extremism, economic inequality, and a governing agenda that contradicts its own claims.
When hypocrisy becomes policy, we all pay the price.
The Facts
Brent crude futures recently approached $117 per barrel. However, futures prices tell only half the story. Due to the geopolitical instability associated with Trump’s support for Vladimir Putin and Benjamin Netanyahu, both indicted war criminals, the cost of delivering physical oil has soared to approximately half the futures price, pushing the final cost of a barrel to $150–$175.
Ironically, this has triggered the fastest and most significant global shift away from fossil-fuel dependency, directly contradicting Trump’s “Drill, Baby, Drill” ideology and its rejection of climate science. His policies and geopolitical alliances are accelerating the very energy transition his administration seeks to obstruct.
Russia claims to have abducted more than 700,000 Ukrainian children. Meanwhile, Netanyahu’s military campaign in Gaza has killed tens of thousands of Palestinians, including tens of thousands of children..
Trump himself faces allegations of war crimes and crimes against humanity involving U.S. military operations in the Caribbean and the targeting and deaths of schoolchildren at Shajareh Tayyebeh Elementary School in Minab, Hormozgan Province, Iran. These events expose the devastating human consequences of the conflicts associated with these leaders.
The Economy: Tariffs, Deficits, and the Cost of Corruption
Trump’s tariffs, acts of war, anti-science claims, white nationalist policies, and corruption have contributed to unprecedented trade and budget deficits and an unsustainable national debt at record levels. The resulting fiscal pressures compound the economic burden of interest payments, while federal borrowing adds upward pressure to interest rates.
The Trump administration’s claims that racist, bigoted, and white nationalist policies “Make America Great Again” and put “America First” are contradicted by the economic consequences of its policies. Tariffs raise costs, trade conflicts disrupt markets, and government resources are directed toward favored industries while American households bear the burden.
This is not economic nationalism delivering broad-based prosperity. It is an economic agenda that places ideological priorities and political interests above the financial well-being of ordinary Americans. Its rhetoric bears the hallmarks of neo-fascist propaganda: ultranationalism, scapegoating, authoritarianism, and the presentation of exclusionary policies as patriotic necessities.
Fossil-Fuel Subsidies: Government Intervention Disguised as National Security
In his latest move, Trump has used his warmongering to subsidize the fossil-fuel industry. President Donald Trump invoked the Cold War-era Defense Production Act (DPA) to allocate up to $150 million in federal funding to subsidize and expand domestic oil-refining capacity.
This is direct government intervention in private markets, using public money and federal authority to protect and expand fossil-fuel infrastructure. The policy contradicts the administration’s free-market rhetoric while reinforcing dependence on the very fuels driving climate change.
Lifting Russian Diesel Sanctions: Fueling Putin’s War Machine
Trump’s intervention extends beyond domestic subsidies. On October 9, 2026, Trump announced a diesel-supply agreement with Russian President Vladimir Putin and temporarily eased U.S. sanctions on Russian diesel exports. The agreement reverses the direction of U.S. policy established after Russia’s invasion of Ukraine, when restrictions were imposed to deprive Moscow of revenue supporting its war. The U.S. Treasury subsequently issued a license allowing covered Russian diesel shipments to proceed without sanctions through April 2027.
On October 22, the Malta-flagged tanker Agioi Fanendes loaded approximately 40,000 metric tons of Russian diesel at Primorsk and headed for New York. Its cargo of 298,000–320,000 barrels represents just 7–8% of U.S. daily diesel consumption.
The irony is profound: after imposing sanctions to restrict Russian energy revenues and pressure Putin over his invasion of Ukraine, Trump has relaxed those restrictions to facilitate Russian diesel exports. This marginal contribution to U.S. fuel supplies undermines American credibility, weakens sanctions enforcement, and provides Moscow with renewed access to U.S. markets while its war against Ukraine continues.
The policy also exposes the weakness of the administration’s energy-security argument. A shipment representing a small fraction of one day’s U.S. diesel consumption does not resolve America’s structural dependence on volatile global fuel markets. Instead, the agreement ties American energy policy more closely to a Russian government waging war against a U.S. partner.
Trump’s Russian diesel agreement undermines U.S. credibility, weakens the rule-of-law framework behind sanctions, and rewards Putin with renewed access to American buyers. It also demonstrates how quickly the administration abandons its declared principles when political priorities demand it.
Government Ownership: Accusing China of What Washington Is Doing
The intervention extends far beyond oil refining and Russian diesel. As part of a major shift in U.S. industrial policy, ostensibly designed to strengthen national security and reduce reliance on China, the Trump administration has committed more than $26 billion to acquire equity stakes, warrants, or options in dozens of strategic private companies.
Financed through a combination of CHIPS Act funding, Department of Defense programs, and energy-related mandates, the federal portfolio encompasses at least 34 corporate deals.
This is a substantial expansion of government involvement in private enterprise. Rather than leaving investment decisions to private markets, the administration is using public resources to acquire financial interests in strategic businesses and influence the direction of American industry.
The hypocrisy is unmistakable: Trump condemns China for state-directed economic intervention while pursuing an increasingly interventionist industrial policy in the United States.
When China uses government resources to advance national industrial priorities, Trump presents it as a threat to free markets. When his own administration deploys federal funding, government ownership, strategic investment, and sanctions relief to advance its industrial and geopolitical priorities, he presents those actions as national security.
The distinction is political, not economic. Government intervention remains government intervention, regardless of whether it benefits Washington, Beijing, Moscow, or a favored private industry.
The Bottom Line: Hypocrisy as a Governing Strategy
The contradictions are undeniable.
An administration that rejects climate science and champions fossil fuels is presiding over geopolitical and economic developments that accelerate the global transition away from fossil-fuel dependence.
A president who claims to champion free markets is using federal power and taxpayer money to subsidize favored industries, acquire financial interests in private companies, and direct investment toward political and strategic priorities.
A political movement that promises to put America first is pursuing policies that impose substantial costs on American households, increase economic uncertainty, and compound the financial burdens inherited by future generations.
A president who condemns China’s government-directed economic policies is implementing comparable forms of intervention at home while claiming that his actions are fundamentally different.
The central issue is not whether government intervention is always wrong. It is the administration’s selective application of its own principles: free markets when criticizing political opponents, government intervention when advancing its own agenda, and national security as the justification for policies that benefit favored industries.
Trump’s record exposes the contradiction between his public rhetoric and his administration’s actions. White nationalism is presented as patriotism, science denial as economic policy, fossil-fuel subsidies as energy security, and government intervention as free-market leadership.
The result is a governing agenda defined by hypocrisy, ideological extremism, and policies that contradict the promises used to justify them—all at the expense of the most vulnerable, while further widening income inequality.