bookmark_borderWhen Climate Change Hits the Wallet: Insurance, Interest Rates, and Taxes

by Daniel Brouse

What will change consumer behavior when it comes to climate change?

Money. Insurance, interest rates, and taxes.

Most consumers do not substantially change their behavior until doing nothing becomes cost prohibitive.

For years, we assumed that climate change was unlikely to change consumer behavior in the near term. Climate change seemed too distant, too gradual, and too abstract to overcome the immediate economic incentives that drive everyday decisions.

That is now observably changing.

Climate change is increasingly entering the household economy through three powerful financial mechanisms:

Insurance. Interest rates. Taxes.

These mechanisms can transform climate change from an environmental issue that consumers can ignore into an economic reality they cannot.

Insurance

The United States, Australia, and parts of Asia and Latin America face some of the heaviest disruptions in insurance markets from climate change. The climate-driven insurance crisis is no longer just a problem for insurance companies. It has triggered a massive shift in housing and financial markets.

As climate risks increase, insurers are raising premiums, increasing deductibles, restricting coverage, and withdrawing from markets where losses have become too great.

That directly affects consumers.

Because most people rely on banks and mortgages to purchase homes, the withdrawal of insurers directly threatens both property values and mortgage stability. A home that cannot be affordably insured becomes more difficult to finance, sell, and maintain as an investment.

The chain is straightforward:

Climate change → insurance losses → higher premiums → reduced insurability → declining property values → mortgage disruption

This creates a powerful economic incentive for consumers to change where they live, what they buy, how they build, and how they protect their property.

Insurance therefore has become one of the first places where climate change forces consumer behavior to change—not through persuasion, but through price.

Interest Rates

Climate change is also becoming a financial problem through the cost of borrowing.

Developing and climate-vulnerable nations bear the heaviest burden. Climate change directly drives up sovereign bond yields, contributes to credit-rating downgrades, and locks vulnerable countries into a punishing vicious cycle of debt and disaster. A landmark 2026 report by ActionAid International revealed that across 65 of the world’s most climate-vulnerable countries, debt servicing is projected to consume a staggering 65% of all government revenue in 2026.

The mechanism is another accelerating feedback loop:

Climate disaster → economic losses → declining government revenue → increased borrowing → higher debt costs → reduced adaptive capacity → greater vulnerability

The consequences do not remain confined to developing nations.

The approximately $2 trillion annual climate-driven fiscal drain acts as a massive structural accelerator for interest rates in the United States. It does not directly determine daily Federal Reserve rate decisions. Instead, this enormous and growing economic burden alters the underlying macroeconomic conditions that the Federal Reserve and bond markets use to price capital.

Climate damage requires money. Rebuilding requires money. Infrastructure adaptation requires money. Insurance losses require money. Government deficits require money. And when the demand for capital rises while economic productivity and fiscal capacity are simultaneously pressured, the cost of capital rises.

Consumers ultimately experience that cost through mortgages, automobile loans, credit cards, business financing, and other forms of debt.

Taxes

Climate change affects taxation at both ends of the global economic spectrum.

Low-income developing nations face catastrophic losses in baseline tax revenue as climate disasters destroy crops, businesses, infrastructure, and productive capacity.

At the same time, wealthy economies are rapidly restructuring their tax systems around carbon emissions, energy production, subsidies, and the transition to lower-carbon energy.

The result is another financial feedback loop:

Climate damage → economic losses → reduced tax base → increased government spending → greater fiscal pressure → higher taxes and fees

In the United States, the financial impact of climate change is not represented by a single “climate tax.”

Instead, the costs are absorbed across federal, state, and local tax systems.

Local governments face increasing costs for damaged infrastructure, emergency response, stormwater management, roads, bridges, utilities, and other public services. Those costs ultimately have to be paid by taxpayers.

Property taxes can therefore become another mechanism through which climate change reaches the household balance sheet.

At the federal and state levels, climate-related disaster costs, infrastructure requirements, energy policies, and changes in taxation can add additional fiscal pressure.

Consumers may never see a line on their tax bill labeled “climate change.” They do not have to. They simply see the bill go up.

The Consumer Climate Feedback Loop

Insurance, interest rates, and taxes are not isolated financial effects.

They interact.

A homeowner faces higher insurance premiums because of increasing climate risk. Higher insurance costs increase the cost of homeownership. Reduced insurance availability threatens property values and mortgage financing. Climate-related disasters increase government expenditures. Government spending increases borrowing and tax pressure. Higher borrowing costs increase the cost of mortgages and other consumer debt.

The feedback loop becomes:

Climate disruption → financial losses → insurance increases → property and mortgage pressure → government spending → higher taxes and borrowing costs → higher household costs → changed consumer behavior

This is the critical transition.

Consumers do not necessarily have to become convinced by climate science before climate change changes their behavior. They only have to experience its economic consequences. A homeowner who can no longer afford insurance behaves differently. A buyer who cannot obtain a mortgage behaves differently. A family facing higher property taxes behaves differently. A business facing higher borrowing costs behaves differently. A community facing rapidly increasing infrastructure costs behaves differently.

The financial system can therefore become the transmission mechanism through which climate change reaches individual consumer decisions.

Ending Synthesis: When Climate Change Becomes Cost Prohibitive

The question is not whether climate change will eventually affect consumer behavior.

The question is when the financial consequences become large enough that consumers can no longer ignore them.

That threshold is already being crossed in parts of the world.

Insurance makes climate risk visible through premiums and availability.

Interest rates transmit climate-related economic and fiscal disruption into the cost of capital.

Taxes distribute the growing costs of climate damage, adaptation, infrastructure, and energy transition across households and businesses.

Together, they create a socioeconomic feedback loop:

Climate change → economic disruption → financial disruption → higher household costs → consumer behavior → market disruption → further economic pressure

This may prove far more powerful than climate messaging alone.

People can ignore a temperature graph.

They can dismiss a scientific projection.

They can debate climate policy.

But they cannot easily ignore an insurance cancellation, a mortgage that costs hundreds of dollars more each month, or a tax bill that keeps rising.

That is why money may ultimately become the mechanism that changes consumer behavior on climate change.

Climate change does not have to become universally accepted before it changes what people do.

It only has to become cost prohibitive to ignore.
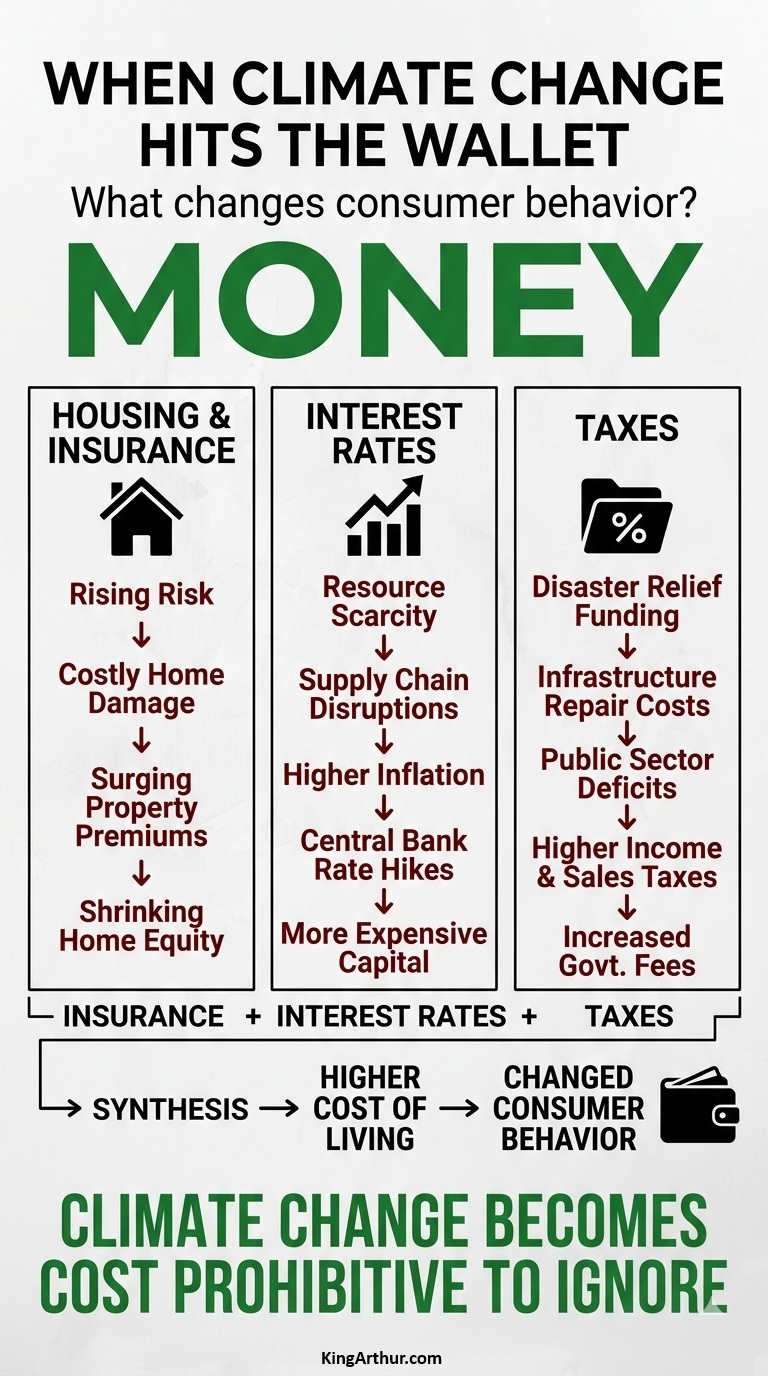
Simplified Social Media Version

💰 WHEN CLIMATE CHANGE HITS THE WALLET

What will actually change consumer behavior when it comes to climate change?

Money.

Insurance. Interest rates. Taxes.

For years, climate change was largely treated as an environmental issue. But that is changing as climate risk increasingly enters the household economy.

🏠 Insurance premiums and availability are being affected by rising climate risks.

💰 Climate-related economic and fiscal pressures are affecting the cost of capital.

🧾 The growing costs of climate damage, adaptation, infrastructure, and energy transition are increasingly flowing through tax systems.

These forces can reinforce one another:

Climate change → financial disruption → higher household costs → changed consumer behavior

Consumers may ignore a temperature graph. They are much less likely to ignore an insurance cancellation, a higher mortgage payment, or a rising tax bill.

Climate change does not have to be universally accepted before it changes behavior.

It only has to become cost prohibitive to ignore.

New paper:
“When Climate Change Hits the Wallet: Insurance, Interest Rates, and Taxes”
bookmark_borderPlug-And-Play Solar

Plug-and-play solar is becoming available around the world—and it could make solar power dramatically simpler and more accessible.

Plug-and-play solar is part of the emerging clean energy economy. Unlike conventional rooftop solar, these small systems can be installed with minimal equipment and, where permitted, connected directly to an existing electrical outlet. That makes solar potentially accessible to renters, apartment dwellers, condominium owners, and homeowners who cannot install a conventional rooftop system.

Cheaper and Healthier

Plug-and-play solar can reduce electricity costs because sunlight is free and the system produces electricity without ongoing fuel purchases. It also generates electricity without the combustion-related air pollutants produced by fossil-fuel power generation.

Instead of buying fuel from a utility to generate electricity somewhere else, a plug-in solar system can capture sunlight right from a balcony, patio, yard, or other suitable location and produce electricity at the point of use.

The basic idea is remarkably simple:

Sunlight → Solar panel → Inverter → Household outlet → Electricity

Great Britain Opens the Door

Great Britain has taken a major step toward making plug-in solar widely accessible. Beginning August 27, 2026, new rules established a legal framework for plug-in solar panels and other plug-in microgenerators.

Under the new framework, qualifying certified systems can connect to standard 13-amp domestic sockets, subject to safety requirements and output limits. Plug-in solar kits can produce up to 800 watts, and users must notify the local electricity network operator. The UK government says the systems could save households up to £110 per year and provide as much as 20% of average household electricity use.

Ofgem has also approved changes to the distribution code intended to facilitate plug-in solar while maintaining requirements for network safety, supply quality, and system operability.

The United States Is Moving State by State

The situation in the United States is less straightforward. There is currently no single nationwide legal framework for plug-in solar. Instead, states are beginning to establish their own rules.

As of September 2026, nine states have enacted legislation specifically addressing plug-in or balcony solar: Utah, Colorado, Maryland, Maine, Vermont, Connecticut, New Hampshire, Virginia, and New Jersey.

Meanwhile, additional states are considering plug-in-solar legislation. California and New York, among others, have active legislative efforts, illustrating how quickly the regulatory landscape is changing.

Plug-and-play solar is therefore more than another solar product. It represents a shift toward small, distributed, consumer-installed energy generation—putting a small power plant within reach of people who may never own a house with a conventional solar roof.

The sun is already there. Plug-and-play solar makes it easier to use.

☀️ THE CLEAN ENERGY ECONOMY

Harmony Hare says:

🔌 PLUG-AND-PLAY SOLAR IS CHEAPER AND HEALTHIER

Solar power doesn’t have to mean a massive rooftop installation.

Plug-and-play solar is changing the equation.

A small solar system can plug directly into an existing electrical outlet—turning a balcony, patio, yard, or other sunny space into a source of clean electricity.

☀️ FREE FUEL
The sun provides the energy. No gasoline. No coal. No natural gas. No ongoing fuel purchases.

💰 LOWER ENERGY COSTS
Generate some of your own electricity instead of buying all of it from the utility.

🌱 CLEANER AIR
Solar electricity generates power without the combustion emissions associated with fossil-fuel generation.

🏠 MORE ACCESSIBLE
Plug-and-play systems can potentially bring solar to renters, apartment dwellers, condo owners, and homeowners who cannot install conventional rooftop solar.

This is the Clean Energy Economy in action:

Small systems.
Simple installation.
Free sunlight.
Less fuel.
Less pollution.
More distributed energy.

The future of clean energy doesn’t have to be complicated.

Sometimes, you just plug it in. ☀️🔌

#CleanEnergyEconomy #PlugAndPlaySolar #SolarPower #CleanEnergy #DistributedEnergy #EnergySavings #RenewableEnergy

→ The Hitchhiker’s Guide to Climate Change

For the basics: Climate Change Simplified

bookmark_borderResidential Solar Power

Traditional Solar Installations

I’m generally against rooftop solar, particularly in the U.S. Much of the residential market is based on leased systems, which can be detrimental to the homeowner, especially when the home is eventually sold.

In general, I also recommend putting a new roof on before installing solar. Otherwise, replacing the roof later can mean additional costs and complications with the solar system. And the payback period can be longer than the length of time many homeowners actually own their homes.

There’s another fundamental problem: in both the U.S. and UK, it can be difficult to install enough rooftop solar to meet a home’s actual electricity demand, particularly during periods of peak heating or cooling. The times when energy demand is highest are not necessarily the times when a rooftop array produces the most electricity. That can make the system less useful—and potentially a liability when selling the property.

As a consultant, I almost always recommend ground-mounted solar when the property allows it. It avoids many of the structural, roofing, maintenance, and resale issues associated with rooftop systems while providing much greater flexibility in system placement and orientation.

In my view, there are very few disadvantages to properly designed ground-mounted solar, while many of the supposed advantages of rooftop solar are really advantages of having solar—not advantages of putting the panels on the roof.

Plug-And-Play Solar

What I’m totally in favor of, however, is plug-and-play solar. Plug-in solar, balcony solar, or other plug-and-play systems can connect directly to an existing electrical outlet, making solar dramatically simpler and less expensive to install. Great Britain has now established a legal framework for these systems: updated regulations taking effect August 27, 2026, created a legal category for plug-in microgenerators and allow certified systems to connect to standard 13-amp domestic sockets, subject to safety requirements, output limits generally up to 800 watts, and notification to the local electricity network operator. Unfortunately, the situation remains much less straightforward in the U.S., where regulation is largely state-by-state. At present, plug-in solar is legal in only nine states: Utah, Colorado, Maryland, Maine, Vermont, Connecticut, New Hampshire, Virginia, and New Jersey.

bookmark_borderClean Energy Economy

by Daniel Brouse

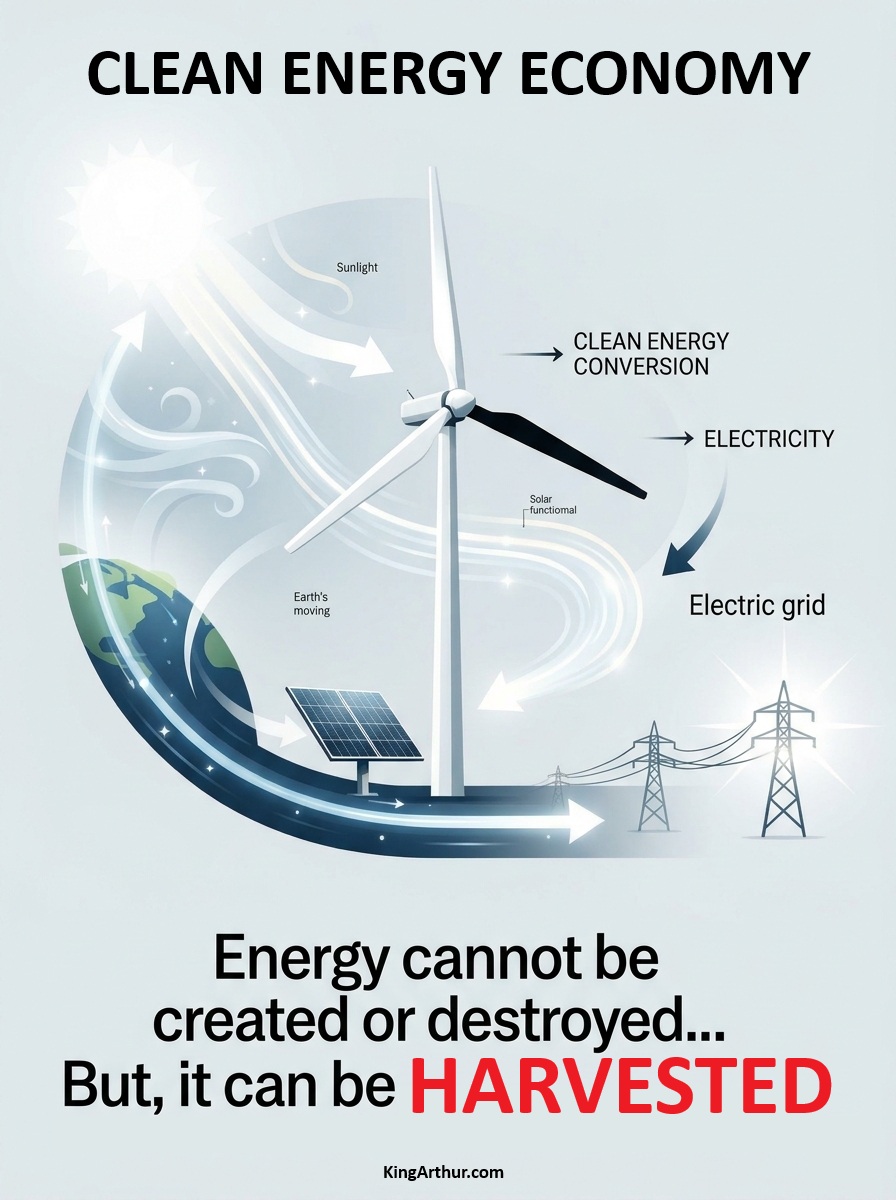
THE ENERGY IS ALREADY THERE.
THE CLEAN ENERGY ECONOMY HARVESTS IT.

Tonight’s homework assignment: Clean Energy Economy.

Energy cannot be created or destroyed. But it can be harnessed, converted, stored, transmitted, and used.

The sun is already delivering enormous amounts of energy to Earth.

The atmosphere is already moving.

Winds are already blowing.

Waves and currents are already moving.

The challenge isn’t creating energy from nothing. It is building systems that efficiently capture naturally available energy and convert it into useful electricity.

That is the basic idea behind a clean energy economy:

SUN + WIND + MOVING EARTH
↓
ENERGY HARVESTING
↓
ELECTRICITY
↓
STORAGE + TRANSMISSION
↓
USEFUL WORK

A wind turbine doesn’t create wind. A solar panel doesn’t create sunlight.

They harvest energy that is already moving through the Earth system and convert it into a form we can use.

The economic opportunity is therefore not simply replacing one fuel with another.

It is building an economy around capturing, converting, distributing, storing, and using energy that is already available.

THE ENERGY IS ALREADY THERE.

THE CLEAN ENERGY ECONOMY HARVESTS IT.

bookmark_borderThe Crack Spread: A Dramatic Shift in Refining Margins

The price difference between a refined petroleum product—such as gasoline or diesel—and the crude oil used to produce it is known as the crack spread. It is a widely used measure of refining margins and provides a useful way to examine how the relationship between crude oil costs and finished-fuel prices changes over time.

Key Market Data & Trends: The Past 12 Months

Looking at the past year reveals a dramatic period of volatility in refining margins.

Fall/Winter 2025 — The Baseline

Through late 2025, crude oil prices remained relatively low, dipping into the $55–$60-per-barrel range. Gasoline prices generally moved in tandem with crude, leaving the simple gasoline crack spread in a relatively compressed, historically typical range of approximately $15–$25 per barrel.

Spring 2026 — The Surge

That relationship changed sharply in spring 2026. Global crude prices climbed aggressively toward a 52-week peak near $117 per barrel. At the same time, wholesale gasoline futures rose substantially, exceeding $3.80 per gallon amid localized refinery bottlenecks and changing supply routes.

The result was a substantial expansion in the spread between the cost of crude and the market price of refined gasoline.

September 2026 — The Current Environment

As of September 16, 2026, WTI crude oil is approximately $104.03 per barrel, while front-month RBOB gasoline is trading around $3.35–$3.45 per gallon.

Converting the gasoline price to a barrel-equivalent basis produces approximately $140.70–$144.90 per barrel. Subtracting the $104.03 WTI price yields a simple gasoline crack spread of roughly $36.70–$40.90 per barrel.

That is substantially wider than the approximately $15–$25-per-barrel range observed during the late-2025 baseline period.

What the Crack Spread Shows

The crack spread does not represent the refinery’s actual profit. Refiners also incur costs for natural gas, electricity, transportation, labor, maintenance, environmental compliance, and other inputs. Refiners also process crude into multiple products rather than simply converting one barrel of crude into one barrel of gasoline.

Nevertheless, the spread provides an important market signal: the price relationship between crude oil and refined gasoline has widened considerably over the past year.

The change is particularly notable because the increase is occurring while crude itself remains above $100 per barrel. Consumers therefore face elevated gasoline prices from two directions: a high underlying crude-oil cost and a substantially wider refining margin.

In other words, the question is no longer simply “How expensive is crude oil?” It is also “How much more expensive has the refined product become relative to its crude-oil input?”

The crack spread provides a way to quantify that difference.

bookmark_borderClimate Debt Collection

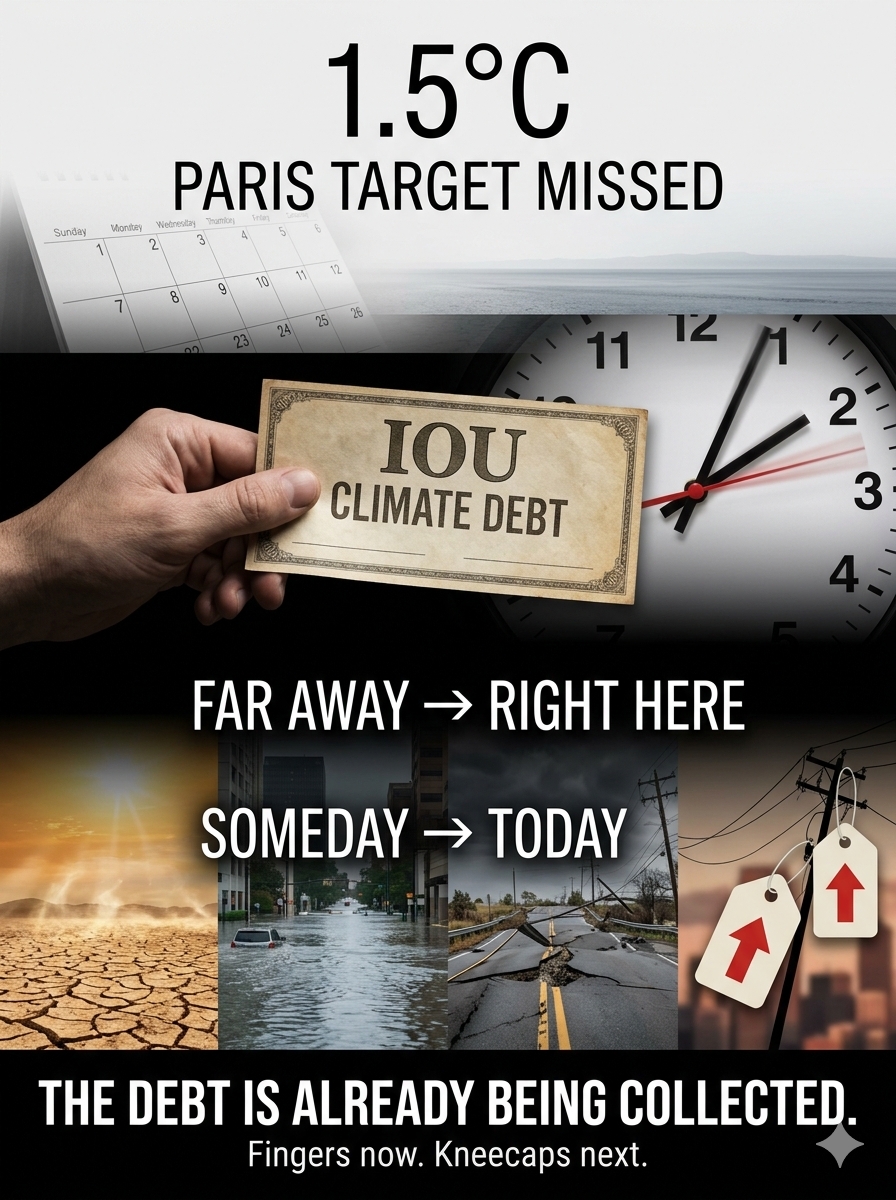
What happens when we miss the 1.5°C Paris target?

Think of it like owing money to a loan shark.

The debt doesn’t wait decades to be collected.

Our fingers are being broken now.
Our kneecaps are next.

One of the biggest challenges in communicating climate change is proximity—both in time and location.

If the consequences seem far away, people dismiss them.

If they’re happening somewhere else, people ignore them.

But climate change is moving from:
future → present
and
somewhere else → right here.

We missed the 1.5°C Paris target. The climate debt is already being collected.

How much pain do we need to feel before we pay attention?

bookmark_borderAbout the Price of Oil: The Price You Don’t See

What Does a Barrel of Oil Cost—and What Does It Mean to You?

When you hear the price of oil reported on the news, you are usually hearing the futures price.

But what does that number actually mean?

The futures price is essentially a “paper” price. Very little physical oil actually changes hands through the futures market. The price that matters to consumers and businesses buying and using petroleum products is the spot price—the price of physical oil being purchased today. And right now, there is a significant difference between the two.

Today, the futures price of oil is roughly $102–$107 per barrel. But the spot price—the actual price being paid for physical oil—is approximately $125–$150 per barrel.

That is the price that ultimately matters to everyone buying refined petroleum products, including gasoline, diesel, and heating oil.

The Pain at the Pump

This is why diesel has reached approximately $6 per gallon, making it the highest price in history. It is also why gasoline is currently averaging approximately $4.32 per gallon. Yes—this is the highest average gasoline price ever recorded for this time of year.

And what’s next?

Heating oil.

As we move toward the winter months, parts of the Northern Hemisphere are already seeing heating oil prices averaging between $5.15 and $5.75 per gallon. Yes. Just like gasoline, heating oil is trading at an absolute record high for the month of September.

Historically, heating oil prices have hovered around $3.50 to $4.00 per gallon during a typical winter season. The current offseason surge above $5.00 per gallon is unprecedented. And this is happening before winter has even arrived.

For millions of households that depend on heating oil, the implications are obvious. The price shock at the pump can become a much larger household energy shock when temperatures fall and heating demand rises.

Adding Fuel to the Fire

There is another problem developing in the background. Oil borrowed from the Strategic Petroleum Reserve (SPR) under the 2026 emergency exchanges is scheduled to be repaid in tranches between November 1, 2026, and September 30, 2028.

Under the 2026 SPR emergency exchange program managed by the U.S. Department of Energy (DOE), companies are contractually required to return approximately 1.18 to 1.24 barrels for every barrel they borrowed.

In other words, oil that was taken out of the reserve during an emergency must eventually be replaced—and companies are not simply returning the same amount of oil they received. They have to return more. That creates another future demand on the physical oil market.

So when you look at the oil price reported on television, don’t assume that the futures number tells the whole story.

The price of oil isn’t just a number on a screen.

It flows directly through the economy. It becomes diesel. It becomes gasoline. It becomes heating oil. It becomes transportation costs, food costs, manufacturing costs, electricity costs, and ultimately the cost of living.

And if physical oil is already trading substantially above the futures price, while heating demand is about to increase and SPR repayment obligations are beginning to come due, the question isn’t simply:

“What does oil cost today?”

The more important question is:

“What is the price of oil going to cost you tomorrow?”

bookmark_borderInflation Is Moving From Diesel to the Consumer

esterday brought the latest Producer Price Index (PPI) measure of inflation. Today, the focus shifts to consumer inflation.

The U.S. Bureau of Labor Statistics released the August 2026 Consumer Price Index (CPI) report, showing headline consumer inflation rising 0.4% in August on a seasonally adjusted basis and increasing 3.4% over the past 12 months.

Core inflation, which excludes volatile food and energy prices, rose 0.3% for the month. That was hotter than expected and is particularly important when viewed alongside yesterday’s PPI report.

The Diesel Problem

Historically, the Federal Reserve has placed considerable emphasis on core inflation because food and energy prices can be highly volatile. The logic is straightforward: temporary energy-price spikes can distort the underlying inflation trend.

But this energy shock is different.

The problem is diesel.

According to the latest BLS PPI data, the price of diesel fuel jumped an extraordinary 24.1% in August alone. BLS reported that more than one-third of the August increase in final-demand goods was attributable to diesel, while nearly two-thirds of the increase in processed goods for intermediate demand was also attributable to the 24.1% surge in diesel prices.

This is not simply a higher price at the pump for people who drive diesel vehicles. Diesel is embedded throughout the economy.

Trucks move food, consumer products, construction materials, manufactured goods, and virtually everything else through the nation’s supply chain. Diesel also powers agricultural machinery, construction equipment, mining equipment, generators, and other industrial machinery.

When diesel prices rise sharply and remain elevated, the increased cost of transportation and production eventually works its way into the prices consumers pay.

Why “Core” Inflation May Miss the Coming Shock

Energy is normally removed from core inflation because energy prices are volatile.

But removing energy from the calculation does not make its economic effects disappear.

A prolonged energy shock can become a supply-chain shock.

That distinction matters.

If gasoline or diesel prices briefly spike and then fall, businesses may absorb some of the increase. But if fuel costs remain elevated, businesses eventually have to recover those higher costs through higher prices for their products and services.

That means today’s diesel inflation can become tomorrow’s food inflation, transportation inflation, construction inflation, manufacturing inflation, and service inflation.

In other words, the energy shock can migrate into core inflation.

This is why the current situation deserves particular attention. The 24.1% monthly increase in diesel prices reported by BLS is large enough to create significant downstream pressure throughout the economy.

$6 Diesel Changes the Equation

Diesel prices have also reached extraordinary levels at the retail pump.

AAA data reported in early September showed the national diesel price approaching the $6-per-gallon threshold, with some markets already reaching or exceeding that level. In several markets, diesel prices were more than 60% above year-earlier levels.

That is a massive increase in one of the economy’s most important transportation and production inputs.

And there is another problem approaching.

Heating Oil Season Is Coming

Northern Hemisphere heating season is about to begin.

Heating oil and diesel are closely related middle-distillate petroleum products and compete for refinery capacity. BLS’s August PPI report also showed a substantial increase in home heating oil and distillates.

That means the diesel shock is arriving just as seasonal demand for heating fuel begins to increase.

For households in the Northeast and other regions that rely on heating oil, this could become a direct household expense. For everyone else, higher heating and transportation costs can still work their way through the prices of goods and services.

Yesterday’s PPI May Be Today’s Warning

The sequence of the data is important.

Yesterday’s PPI showed an enormous producer-level shock concentrated in energy, particularly diesel.

Today’s CPI shows consumer inflation remaining elevated.

The critical question is not simply whether headline CPI is 3.4% or whether core inflation is 0.3% for the month.

The bigger question is what happens when a massive energy-cost shock persists long enough to propagate through the entire economy.

Core inflation may initially appear relatively contained because energy is excluded from its calculation.

But the economy cannot exclude energy from its production and transportation costs.

Eventually, somebody pays the diesel bill.

And increasingly, that somebody is the consumer.

The current inflation story therefore may not be about an isolated spike in energy prices. It may be the beginning of an inflationary transmission process—from diesel, to producers, to transportation, to supply chains, and ultimately to consumer prices.

bookmark_borderInflation’s Fiscal Engine: How Government Spending Keeps Price Pressures Alive

How Fiscal Policy Is Becoming a Driving Force of Inflation

The U.S. Bureau of Labor Statistics (BLS) released its August 2026 Producer Price Index (PPI) report on September 10, revealing a renewed acceleration in wholesale prices. According to the report, headline PPI rose 0.4 percent month over month and climbed 5.4 percent over the year, with a significant increase in final-demand goods helping drive the advance. The PPI measures prices received by domestic producers and therefore provides an early look at price pressures moving through the production and distribution system.

The important question is not simply why did producer prices rise this month? It is a larger question:

Why does inflation continue to find fuel in an economy that has already experienced years of elevated prices?

One increasingly important answer is fiscal policy.

Inflation is not produced by a single variable. Energy prices, tariffs, supply disruptions, wages, housing costs, commodity prices, exchange rates, expectations, and monetary policy can all affect the price level. But fiscal policy determines another fundamental component of the inflation equation: how much purchasing power the government injects into the economy relative to the economy’s ability to supply goods and services.

When government spending persistently exceeds government revenues, the resulting deficit represents a substantial fiscal impulse. That impulse can support economic activity—and that is sometimes exactly what policymakers intend. But if demand is already strong, additional fiscal stimulus can also intensify competition for labor, materials, transportation, construction capacity, housing, and other scarce resources.

In other words:

Fiscal policy can become an inflation engine.

The Government Is Part of Aggregate Demand

It is easy to think of inflation as something caused primarily by consumers spending too much money.

But consumers are only one component of aggregate demand.

Businesses spend. Consumers spend. State and local governments spend. And the federal government spends.

The Federal Reserve defines aggregate demand as the combined demand for goods and services from households, businesses, and governments. Government purchases therefore enter the economy alongside private consumption and investment.

That matters because a government does not need to increase taxes to spend more money.

It can borrow.

When federal expenditures exceed federal revenues, the government finances the difference through borrowing. The resulting deficit does not automatically create inflation—particularly when the economy has substantial unused capacity. But persistent, large deficits can become inflationary when they add demand faster than the economy can expand its real supply of goods and services.

The distinction is crucial:

Deficit spending is not synonymous with inflation.

But under the right—or wrong—economic conditions, deficit spending can be an important source of inflationary pressure.

America’s Fiscal Imbalance Is Enormous

The scale of current federal deficits makes this more than an abstract theoretical issue.

The Congressional Budget Office estimated in August that the federal government had accumulated a $1.8 trillion deficit during the first ten months of fiscal year 2026. During that period, federal revenues increased by about 3 percent while outlays increased by about 5 percent. CBO subsequently estimated that the full-year 2026 deficit would reach approximately $2.1 trillion.

CBO’s longer-term projections similarly show deficits remaining historically large. Its February baseline projected a 2026 deficit of $1.9 trillion, equivalent to 5.8 percent of GDP, compared with a 50-year historical average deficit of 3.8 percent of GDP. Federal outlays were projected at 23.3 percent of GDP, substantially above their 50-year average of 21.2 percent.

That is a fiscal environment in which policymakers need to take seriously the possibility that government demand is contributing to persistent price pressure.

And there is another complication.

Fiscal Policy and Monetary Policy Can Pull in Opposite Directions

The Federal Reserve controls monetary policy. Congress and the Administration control fiscal policy.

These are different policy levers, but they interact.

The Federal Reserve explicitly notes that fiscal policy affects the economic outlook and that the Fed considers current and projected fiscal policy when determining the appropriate stance of monetary policy.

Consider the policy feedback:

Government spends more → aggregate demand increases → resource competition increases → prices rise → inflation persists → Federal Reserve faces greater pressure to maintain restrictive monetary policy.

This can create a peculiar policy conflict.

Fiscal policy may be pushing demand upward at the same time monetary policy is attempting to restrain demand.

The Fed can raise interest rates to cool borrowing, investment, housing, and consumption. But monetary policy cannot directly decide how much Congress spends or how much revenue the federal government collects.

Consequently, monetary policy can be forced to compensate for fiscal policy.

That is an important reason why blaming the Federal Reserve alone for inflation can miss half of the equation.

The Fiscal Multiplier Matters

Government spending does not necessarily have a one-for-one effect on economic activity.

Money spent by the government becomes income for someone else. That recipient spends some of it, creating income for another person or business, which can generate another round of spending.

This is the basic idea behind the fiscal multiplier.

When the economy has substantial unused capacity, that multiplier can increase real output without producing an equivalent increase in prices.

But when the economy is operating close to capacity, the same additional demand can produce a different result.

There may simply not be enough additional workers, factories, trucks, construction crews, housing, electricity, raw materials, or other productive resources available to satisfy the additional demand.

At that point, more nominal demand begins chasing a relatively constrained supply.

The result can be higher prices rather than proportionately higher real output.

That is the fiscal-inflation connection.

Deficits Can Also Keep Pressure on the Economy Longer

There is another reason persistent deficits matter.

A temporary fiscal expansion can be appropriate during a recession, emergency, war, financial crisis, or other period of severe economic weakness. The government can deliberately borrow and spend to prevent a collapse in demand.

The problem arises when emergency-style fiscal policy becomes structurally embedded after the emergency has passed.

If spending remains elevated while revenues remain insufficient to finance it, the government continues injecting fiscal demand into the economy.

The issue then becomes less about one year’s stimulus and more about the persistent fiscal stance.

That persistence matters for inflation expectations, interest rates, government borrowing costs, private investment, and the Federal Reserve’s policy response.

Government Spending Can Also Raise the Cost of Producing Things

Fiscal policy does not affect inflation only by stimulating demand.

Government policy can also affect the cost structure of the economy.

Government borrowing contributes to demand for credit. Large and persistent borrowing needs can put upward pressure on interest rates, particularly when private borrowers are competing for the same pool of financial resources.

Government spending can also increase demand for construction, engineering, defense production, transportation, technology, health care, energy, and other services.

When government becomes a very large buyer, private-sector buyers may have to compete for the same resources.

The result can be higher wages, higher input costs, higher financing costs, and higher prices.

In that sense, fiscal policy can influence both sides of the inflation equation:

More demand + constrained supply = greater price pressure.

The PPI Is an Important Warning Signal

This is why the August PPI deserves attention.

Producer prices are not consumer prices, and a single monthly PPI increase does not prove that fiscal policy caused the increase. Prices can move because of commodity markets, tariffs, energy shocks, supply disruptions, weather, transportation costs, exchange rates, or changes in margins.

But the PPI provides a useful window into the price pressures confronting businesses before those pressures are fully transmitted through the economy.

The July PPI data already showed that producer prices remained elevated: final-demand prices were up 4.7 percent over the year, while final-demand goods were up 6.5 percent and final-demand services were up 3.9 percent.

The August acceleration therefore raises a broader question about whether inflation is merely experiencing temporary disturbances—or whether the economy continues to contain structural forces capable of sustaining price increases.

Fiscal policy belongs prominently in that discussion.

Inflation Is a Policy Interaction, Not a Single-Agency Failure

It is tempting to divide economic policy into simple categories:

The Fed causes inflation.

Or:

Government spending causes inflation.

Or:

Tariffs cause inflation.

Or:

Corporations cause inflation.

Reality is considerably more complicated.

Inflation is an interaction among monetary policy, fiscal policy, supply, demand, expectations, financial conditions, international trade, energy markets, labor markets, and productivity.

But acknowledging complexity should not obscure responsibility.

If fiscal policy continually stimulates demand while monetary policy is attempting to suppress it, the two policies are working at cross-purposes.

And if the government repeatedly runs enormous deficits while the economy is operating near capacity, fiscal policy can become a persistent contributor to inflation rather than merely a temporary response to economic weakness.

The Fiscal Policy Question

The central economic question should therefore be expanded beyond:

“What is the Federal Reserve doing about inflation?”

It should also be:

“What is fiscal policy doing to inflation?”

That question is especially important when federal spending is growing faster than federal revenues and when deficits are measured in trillions of dollars.

The Federal Reserve can raise interest rates.

It can reduce them.

It can tighten.

It can ease.

But the Fed cannot balance the federal budget.

Congress and the Administration determine the government’s spending and taxation policies. As the Federal Reserve itself explains, fiscal policy is fundamentally the government’s tax-and-spending policy, while monetary policy is conducted independently by the central bank.

That division of responsibility matters.

If fiscal policy continually pushes aggregate demand upward, monetary policy may have to work harder to restrain it.

And that creates a potentially damaging cycle:

Large deficits → stronger aggregate demand → persistent inflation → tighter monetary policy → higher borrowing costs → greater federal interest expense → larger deficits.

The last step is particularly troubling because rising interest costs can themselves enlarge future deficits.

Inflation’s Fiscal Feedback Loop

This creates the possibility of a fiscal feedback loop:

Deficits increase → debt increases → interest expense increases → federal spending increases → deficits increase further.

CBO’s projections already show the importance of this mechanism. In its 2026 baseline, net federal interest costs were projected at roughly $1 trillion, or 3.3 percent of GDP. CBO projected that interest costs would continue rising as a share of the economy over the following decade.

That does not mean interest expense itself automatically creates consumer-price inflation.

It means that debt service becomes another claim on federal resources and another component of federal spending that must ultimately be financed through taxes, borrowing, or reductions elsewhere.

The larger the debt burden becomes, the less fiscal flexibility policymakers have when the next recession, financial crisis, war, pandemic, or climate disaster arrives.

The Bottom Line

The August 2026 PPI report is more than another monthly inflation statistic.

It is a reminder that inflationary pressure remains embedded in the U.S. economy.

Some of that pressure comes from supply-side forces. Some comes from international events. Some comes from tariffs, energy markets, labor costs, and other factors.

But fiscal policy should not be treated as an innocent bystander.

Government spending is demand.

Deficits finance spending that exceeds current revenues.

Persistent deficits can sustain aggregate demand even when inflation is already elevated.

And when that fiscal expansion collides with constrained productive capacity, the result can be continued upward pressure on prices.

The United States therefore faces a policy problem that cannot be solved by monetary policy alone.

If policymakers want durable price stability, they eventually have to address not only the price of money, but also the size and composition of government spending, taxation, borrowing, and deficits.

The inflation debate should consequently move beyond the familiar question of whether the Federal Reserve is tightening enough.

The harder question is:

Is fiscal policy itself helping to keep the inflation fire burning?

In 2026, the evidence says that question deserves considerably more attention.

bookmark_borderHow Is Climate Energy Hitting You? Nicolas Cage: Whole Sinkhole

by Daniel Brouse

Coastal Erosion, Property Loss & the Uninsurable Coast

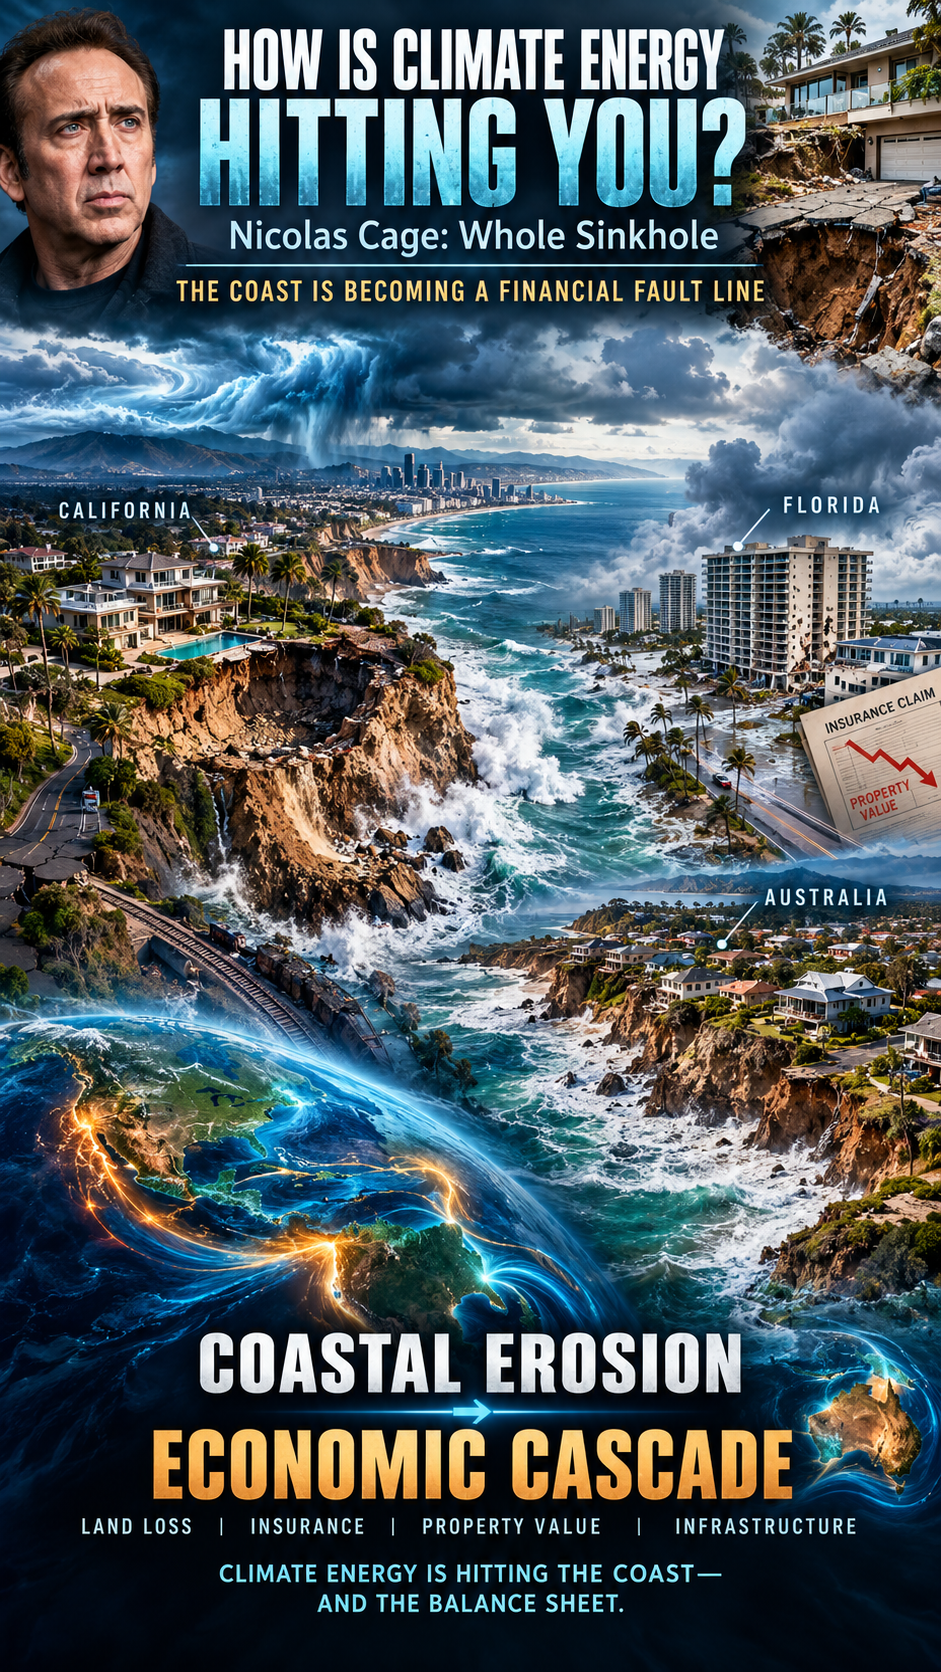
Nicolas Cage: Whole Sinkhole

On September 8, 2026, severe coastal erosion and high surf triggered by the aftermath of Hurricane Marie caused the driveway of Nicolas Cage’s $10.5 million beachfront mansion to completely collapse.

The resulting crater expanded to roughly 30 by 60 feet and plunged about 25 feet deep, swallowing the driveway, a construction-site portable restroom, and heavy concrete debris.

Powerful south swells, extreme high tides, and pounding waves from Tropical Storm/Hurricane Marie ate away at the coastline directly beneath the property.

The collapse ruptured a gas main, forcing utility crews to shut off natural gas along the street. Because the ground remained highly unstable, city officials declared a local state of emergency and red-tagged or ordered evacuations for roughly 30 surrounding homes. Fortunately, the home was unoccupied at the time, and no injuries were reported.

California’s Coastal Erosion

Climate change and coastal erosion are fundamentally reshaping California’s 1,100-mile coastline. What was once considered a slow-moving, long-term environmental shift has accelerated into a series of highly disruptive events, resulting in collapsing bluffs, shrinking beaches, and massive infrastructure vulnerabilities.

The severe impacts California is facing are driven by a combination of rising sea levels and intensifying ocean patterns.

1. Vanishing Beaches and the “Coastal Squeeze”

California’s famous sandy beaches are facing an existential crisis. The U.S. Geological Survey (USGS) estimates that 24% to 75% of California’s beaches could completely erode by the year 2100.

The Squeeze: Normally, a beach would naturally migrate inland as sea levels rise. However, much of California’s coast is experiencing a “coastal squeeze”: beaches are trapped between the rising ocean and human-made infrastructure such as seawalls, highways, and residential developments, leaving the sand nowhere to go.

Artificial Interventions: According to recent USGS satellite data, some Southern California beaches have artificially expanded, but this is entirely due to expensive human interventions, such as dredging and “beach nourishment” projects, rather than natural coastal resilience.

2. Sea Cliff Failures and Deadly Landslides

Roughly 70% of California’s coast is comprised of oceanfront bluffs and cliffs.

Increased Wave Attack: As baseline sea levels rise, waves strike the base of these cliffs more frequently and with greater force. This severely degrades their structural stability, triggering sudden and unpredictable cliff collapses and landslides.

Human and Property Risk: Bluff failures have turned deadly for beachgoers in areas such as Encinitas and San Francisco. They also pose an immediate threat to multi-million-dollar cliffside homes and vital transportation routes.

3. The “Triple Threat” of El Niño and Severe Storms

While climate change is steadily raising the global baseline sea level, seasonal weather anomalies can trigger immediate emergencies. Geomorphologists at the Scripps Institution of Oceanography warn that El Niño conditions create a devastating “triple threat”:

Elevated Ocean Height: El Niño patterns can temporarily push local sea levels up by an additional 6 to 13 inches. Combined with pre-industrial sea-level rise, this radically amplifies the baseline ocean height.

Powerful Swells: Stronger storms and intense wave energy eat away at protective sand berms at an accelerated rate.

Heavy Rain: Atmospheric rivers saturate coastal land, triggering landslides from the top down while waves batter the cliffs from the bottom up.

The compound effect of these forces was highly visible during recent extreme-weather events, which caused widespread flooding in Long Beach and massive coastal sinkholes in Malibu. Every 2 to 4 inches of sea-level rise effectively doubles coastal flood risks.

4. Compounding Economic and Ecological Damages

Infrastructure at Risk: The state’s Legislative Analyst’s Office estimates that $8 billion to $10 billion worth of existing property could be entirely underwater within the next few decades, with billions more at risk during high tides. Critical lifelines—including the Pacific Coast Highway and coastal rail links such as the Amtrak lines connecting San Diego to Los Angeles—frequently face service suspensions because of ground instability.

Ecological Degradation: California has already lost more than 60% of its historical coastal sand dune systems to development and erosion. This destroys critical habitats for native birds and mammals while removing the coastline’s natural buffer against storm surges.

Water Supply Risks: Rising tides put freshwater aquifers at risk of saltwater intrusion. Increased saltwater contamination in the Sacramento-San Joaquin Delta threatens the drinking-water supply for millions of Californians as well as adjacent agricultural land.

California’s Adaptive Strategy

In response, California passed legislation such as Senate Bill 272, requiring all local governments within the coastal zone to establish comprehensive sea-level-rise plans by January 1, 2034. Communities are forced to choose between “hard armoring”—building massive rock revetments and groins to hold back the sea—and “managed retreat,” the highly controversial process of moving structures and infrastructure entirely inland.

Florida Coastal Erosion

Florida is facing a systemic coastal real-estate crisis in which climate-driven physical erosion has collided with aggressive new legal and financial mandates.

The state is experiencing severe physical land loss, but the downstream financial impact—specifically skyrocketing condo fees, massive special assessments, and a plunging condo market—is reshaping the state’s housing economy.

Part 1: How Coastal Erosion Is Impacting Florida

Florida features a low-lying, highly vulnerable topography. Rising sea levels and climate-fueled hurricanes are causing severe coastline degradation.

Critical Erosion: The Florida Department of Environmental Protection has designated a majority of Florida’s coastline as facing “critical erosion risk.” Beaches and barrier islands are shrinking, eliminating natural buffers that protect buildings from storm surges.

Foundation Undermining: Storm surges and intense wave action systematically wash away sand beneath seawalls and structural slabs. Saltwater intrusion aggressively corrodes the steel rebar inside concrete foundations and parking garages, severely compromising structural integrity over time.

Boundary Shrinkage: Coastal erosion is shrinking the physical legal boundaries of private properties. By 2050, over 140,000 Florida properties are expected to be significantly altered by land loss.

Part 2: The Condo Crisis — Fees & Special Assessments

Historically, beachfront condo associations kept their Homeowners Association (HOA) fees artificially low by voting to “waive” reserve funding for long-term maintenance. The tragic 2021 collapse of Champlain Towers South in Surfside permanently ended this practice.

Following the disaster, Florida passed strict safety laws, including SB 4-D and subsequent updates such as HB 913, creating a financial perfect storm:

Mandatory Milestone Inspections: All buildings three stories or taller that reached 30 years of age—or 25 years if within three miles of the coast—were required to complete rigorous structural inspections. These inspections uncovered decades of hidden saltwater corrosion, concrete spalling, and foundation rot.

Structural Integrity Reserve Studies (SIRS): Associations must perform a SIRS to calculate the remaining lifespan of critical components such as roofs, foundations, and load-bearing walls.

The Ban on Waiving Reserves: Associations are strictly prohibited from waiving or underfunding reserves for structural items. They must collect the required cash.

The Financial Fallout

Six-Figure Special Assessments: Because buildings deferred maintenance for decades, unit owners are being hit with mandatory, one-time special assessments ranging from $50,000 to more than $400,000 per unit to pay for multi-million-dollar structural repairs.

Skyrocketing Monthly Fees: Regular monthly HOA fees have surged—sometimes by 20% to 50% in a single year—to cover ongoing reserve requirements and exploding commercial-property insurance premiums.

Surging Insurance Costs: Driven by storm damage and climate risk, many major private insurers have pulled out of Florida entirely. Condo buildings are forced onto high-cost, bare-minimum state-backed policies, adding thousands of dollars annually to an individual unit owner’s bottom line.

Part 3: Devastation of Real Estate Values

The financial strain of these assessments and fees has broken the economics of Florida condo ownership, resulting in a dramatic price correction along the coast.

The Mass Sell-Off: Fixed-income retirees and middle-class owners cannot afford a sudden $100,000 assessment or a doubling of their monthly dues. This has caused a massive influx of inventory as desperate owners try to unload their units before deadlines hit.

Evaporating Buyer Demand: Disclosures showing thousands of non-compliant buildings, paired with high risk, have terrified buyers. Buyers refuse to inherit pending six-figure structural repair bills, causing sales velocity to freeze.

Deep Price Disruption: According to market trackers, this massive supply glut and lack of demand has led to steep price drops for coastal condos. In stark contrast to single-family homes, aging coastal condos are seeing values plummet by 20% to 40%.

Coastal Gentrification: The ultimate trajectory is severe economic displacement. As middle-class owners are forced out, developers and wealthy buyers are buying up entire distressed buildings at steep discounts, either to demolish them or completely rebuild luxury projects out of pocket.

Australia Coastal Erosion

Over 250,000 Australian homes are at risk of coastal erosion, according to the “Rising Seas, Rising Bills” report published by the Climate Council on September 10, 2026.

Drawing on groundbreaking climate modeling from the University of Melbourne and the Australian National University, the report highlights the severe threat that rising sea levels and storm surges pose to Australia’s massive coastal population.

1. The Real Estate and Financial Risk

Properties Threatened: The report explicitly warns that more than 267,000 coastal properties—roughly a quarter of a million homes—are at risk of severe inundation and erosion damage by 2100.

The $855 Billion Economic Bill: Total economic losses are projected to hit at least $855 billion AUD by the end of the century. This includes $274.3 billion AUD in direct property damage, alongside $580.7 billion AUD in damage to farmland, nature reserves, and critical public infrastructure.

The Timeline: While 2100 is the benchmark for the worst damages, researchers stress that the economic shock waves will start crippling coastal real estate as early as 2040.

2. State-by-State Breakdown: Where Is Most Exposed?

The damage is not distributed evenly, with specific regions carrying extreme structural and financial burdens:

Queensland — 93,157 properties at risk: The worst-affected state by property count. The Gold Coast alone is officially named Australia’s most exposed urban area, facing a staggering $84.4 billion AUD in projected economic losses on its own.

New South Wales — 71,210 properties at risk: Communities in Northern NSW and the Central Coast are projected to experience far higher property losses than Greater Sydney.

Western Australia — 51,366 properties at risk: While it has fewer homes at risk than Queensland or New South Wales, Western Australia faces the highest overall financial loss, at $230.5 billion AUD, due to vast tracts of highly valuable coastal agricultural land that will be permanently lost to sea-level rise.

Victoria: Property losses are heavily concentrated in low-lying, densely populated urban areas around Melbourne’s Port Phillip Bay and the Yarra River.

3. The Uninsurable “Actions of the Sea”

Much like the condo crisis unfolding in Florida, Australia is facing a severe insurance reckoning.

The Exclusion Clause: Most standard private insurers in Australia explicitly exclude coverage for “actions of the sea.” This means regular ocean tidal flooding, steady coastal erosion, and sea-level rise are completely uncovered.

The Cost Burden: When a storm surge destroys a foundation or a cliff collapses, property owners will largely be forced to bear the multi-million-dollar stabilization or relocation costs entirely on their own. Experts warn that this will trigger massive drops in property values and result in “uninsurable” coastal ghost zones.

The Coast Is Becoming a Financial Fault Line

From California to Florida to Australia, coastal erosion is no longer simply a problem of disappearing sand or retreating shorelines. It is becoming a cascading climate-energy problem that reaches directly into property values, insurance markets, infrastructure, ecosystems, and household finances.

The Nicolas Cage sinkhole provides a dramatic example of how quickly coastal instability can turn an expensive piece of real estate into a dangerous hole in the ground. California demonstrates the growing physical vulnerability of beaches, cliffs, transportation corridors, and freshwater resources. Florida shows how physical climate risks can cascade into insurance crises, special assessments, and collapsing real-estate economics. Australia demonstrates how the same process can scale into a national financial exposure measured in hundreds of billions of dollars.

The underlying lesson is straightforward: coastal climate risk does not stop at the water’s edge.

As sea levels rise and extreme coastal events intensify, the physical loss of land can propagate through the economic system. Erosion undermines structures. Structural damage increases repair costs. Repair costs increase insurance premiums and assessments. Insurance becomes unavailable or unaffordable. Properties lose value. Buyers disappear. Communities face declining tax bases and increasingly expensive infrastructure protection.

What begins as coastal erosion can therefore become a cascading economic feedback.

Climate energy is hitting the coast—and increasingly, it is hitting the balance sheet.