bookmark_borderJuly 2026: The Record Heat Was Especially Dangerous After Sunset

by Daniel Brouse

July 2026 was officially the hottest month ever recorded for the contiguous United States since national records began in 1895. According to the National Oceanic and Atmospheric Administration (NOAA), the average temperature across the Lower 48 reached 76.9°F—about 3.3°F above the 20th-century average and roughly 0.1–0.2°F warmer than the previous July records set during the Dust Bowl era in 1936 and the exceptional heat of 2012.

But the most important part of this record may not have been the daytime heat.

It was the heat that refused to leave at night.

The nighttime record is the real warning signal

July’s average daytime maximum temperature was 89.5°F, which was 2.9°F above average and ranked as the sixth-warmest month on record for average high temperatures.

The average overnight minimum temperature, however, reached 64.2°F—an extraordinary 3.7°F above average. That was the warmest average minimum temperature ever recorded for the contiguous United States, surpassing the previous record, set in July 2022, by 0.7°F.

That distinction matters.

A hot afternoon is dangerous, but a hot afternoon followed by a substantial nighttime cooldown gives the human body, vegetation, soils, buildings, infrastructure, and electrical systems an opportunity to recover.

When nighttime temperatures remain elevated, that recovery period disappears.

July 2026 therefore represents more than another record for daytime heat. It demonstrates an increasingly important characteristic of a warming climate: the thermal baseline is rising around the clock.

Why nighttime temperatures matter so much

Nighttime cooling is a fundamental part of Earth’s daily heat cycle.

After sunset, the land surface normally loses energy through infrared radiation. As the surface cools, the air near the ground cools as well. This produces the familiar drop from afternoon highs to early-morning lows.

Greenhouse-gas-driven warming interferes with that process. A warmer atmosphere contains more heat and can emit more infrared radiation back toward the surface. Increased atmospheric moisture can further enhance this effect because water vapor is itself a powerful greenhouse gas.

Cloud cover, humidity, soil moisture, wind, urbanization, and atmospheric circulation also influence how much the temperature falls overnight.

The result is not simply that afternoons become hotter. The floor beneath the temperature curve rises. That is critically important because the minimum temperature determines how much accumulated heat is actually released before the next day begins. If an afternoon reaches 100°F but the temperature falls to 65°F overnight, the body and environment experience a meaningful period of relief. If that same afternoon is followed by an 82°F night, the next day begins with the system already carrying a substantial heat load.

This is why nighttime warming can transform an episodic heatwave into a cumulative heat event.

The human body needs nighttime recovery

The human body is particularly vulnerable to persistent nighttime heat because sleep is one of the primary periods available for physiological recovery.

During sleep, the body normally reduces its core temperature. A hot bedroom makes that process more difficult. Higher nighttime temperatures can increase sweating, heart rate, dehydration, and thermal stress while disrupting normal sleep.

Research examining hundreds of thousands of U.S. respondents found that increases in nighttime temperatures were associated with more reports of insufficient sleep, with particularly strong effects during summer.

The consequences extend beyond simply feeling tired the next morning.

Repeated nights of inadequate sleep can impair cognitive performance, mood, immune function, metabolic regulation, and the ability to cope with additional heat stress.

Nighttime heat therefore creates a potentially dangerous cycle:

Hot day → inadequate nighttime cooling → poor sleep and incomplete recovery → greater vulnerability the next day → another hot day.

Research specifically examining nighttime warming has also found significant associations between hot nights and mortality. One modeling study concluded that nighttime warming could become an increasingly important component of future heat-related mortality, with the mortality risk on hot nights substantially higher than on days without hot nighttime conditions.

More recent multicountry research likewise finds that hot nights themselves contribute independently to heat-related mortality risk.

In other words, nighttime heat is not merely an inconvenience between two hot days. It is itself a health hazard.

The agricultural implications are equally important

Plants do not stop metabolizing when the sun goes down.

At night, plants continue to respire. They consume stored energy and undergo physiological processes that are essential for growth, reproduction, and recovery from daytime stress. When nighttime temperatures remain unusually high, respiration increases and plants can consume more of the carbohydrates they produced during the day.

Research involving wheat has demonstrated this effect experimentally. A field study found that artificially increasing nighttime temperatures by 2°C reduced grain yield, with yield declining by approximately 1.9% for every 1°C increase in nighttime temperature in the experiment.This is especially significant because nighttime warming can affect crops even when daytime temperatures do not become dramatically more extreme.

A crop can therefore experience a double burden:

More daytime heat stress + less nighttime physiological recovery.

Higher nighttime temperatures can also increase water loss and alter plant stomatal behavior, while warmer soils can accelerate moisture loss and biological activity. For agriculture, the problem is not simply the temperature at noon. It is the accumulated thermal stress across the entire 24-hour cycle.

Nighttime heat also keeps the landscape from resetting

The same principle applies beyond human beings and crops.

Soils need to cool.

Water bodies need to release heat.

Buildings need to dissipate stored heat.

Urban infrastructure needs to shed the energy accumulated during the day.

Even ecosystems depend upon daily temperature cycles.

When nights remain warm, all of these systems begin the following day from a higher thermal starting point.

This can become particularly important during prolonged heatwaves. Consider two hypothetical heatwaves with identical daytime highs:

Heatwave A:
100°F day → 65°F night → 100°F day → 65°F night

Heatwave B:
100°F day → 82°F night → 100°F day → 82°F night

The daytime maximum is identical.

But Heatwave B is vastly more difficult for people, plants, buildings, soils, and ecosystems because the system never receives the same opportunity to cool.

That is the hidden dimension of persistent heat.

Nighttime warming can amplify the consequences of daytime warming

It is important to be precise here: rising nighttime temperatures should not be described as a standalone climate “feedback” in the strict physical sense. Rather, nighttime warming is both a consequence of increased heat retention in the climate system and an amplifier of the impacts produced by daytime warming.

The distinction matters.

The physical climate system contains genuine feedbacks—such as increased atmospheric water vapor, declining snow and ice, and changes in soil moisture—that can amplify warming.

Nighttime warming is an important expression of those processes at the surface.

And once it occurs, it can amplify consequences across other systems.

For example:

Higher greenhouse-gas concentrations → greater atmospheric heat retention → warmer nights → less nighttime recovery → greater human heat stress → greater vulnerability to the next day’s heat.

A parallel agricultural pathway is:

Warmer nights → increased plant respiration and physiological stress → reduced recovery → lower productivity → greater vulnerability to subsequent heat and drought.

This is why minimum temperatures deserve far more attention than they traditionally receive.

The energy system feels it too

There is another important consequence: electricity demand.

Hot afternoons increase air-conditioning demand. But when temperatures remain high overnight, air conditioners continue operating long after sunset.

That extends the period of peak or elevated electricity demand and reduces the opportunity for buildings to naturally cool.

Instead of a system experiencing:

high demand → nighttime relief → recovery

the grid can experience:

high demand → continued overnight demand → high demand again.

This becomes especially problematic when multiple consecutive days and nights are exceptionally warm.

The result is a compound infrastructure stress rather than a single afternoon peak.

Nighttime temperatures reveal accumulated heat

There is also a deeper climate signal embedded in minimum temperatures.

Daytime temperatures can be strongly influenced by short-term weather conditions, including sunshine, wind, soil moisture, and atmospheric circulation. Minimum temperatures are also affected by these factors, but persistently elevated nighttime temperatures can reveal something particularly important: the atmosphere and surface are retaining more heat between sunset and sunrise.

That makes nighttime minimums an important indicator of how the climate system is changing.

July 2026 provides an extraordinary example.

The United States did not merely experience exceptionally hot afternoons.

It experienced exceptionally warm mornings.

The average minimum temperature was 3.7°F above normal—an even larger anomaly than the daytime maximum—and established a national record by a substantial margin.

That is why the July 2026 record deserves to be examined differently from a conventional heat record.

The most important number may be 64.2°F, not 89.5°F.

A warmer baseline changes what “extreme” means

There is another consequence that is easy to overlook.

As nighttime temperatures rise, the definition of a dangerous heat event changes.

Historically, a very hot day followed by a relatively cool night allowed the human body and natural systems to partially recover. But as the nighttime baseline rises, temperatures that once represented nighttime relief can themselves become hazardous.

The result is a compression of the daily thermal cycle.

The difference between daytime and nighttime temperatures becomes smaller, while the entire 24-hour temperature profile shifts upward. This means climate change is not simply producing more extreme peaks. It is elevating the entire thermal floor.

And once that floor rises sufficiently, heat becomes persistent rather than episodic.

July 2026 fits into a larger global pattern

The U.S. record occurred within an exceptionally warm global month. According to the Copernicus Climate Change Service, July 2026 was the joint-second-warmest July globally, tied with July 2024. Global ocean surface temperatures outside the polar regions were the highest recorded for any July, with developing El Niño conditions contributing to the unusually warm ocean state.

NOAA also reports that El Niño is continuing to strengthen and is expected to persist into early 2027, adding another natural source of variability to an already substantially warmer climate background.

El Niño can help explain why a particular period becomes exceptionally warm, but it does not explain away the long-term warming trend. Natural variability operates on top of a climate system whose baseline has been shifted upward by human-caused greenhouse-gas emissions.

That distinction is essential.

The warning hidden in the overnight record

July 2026 should therefore not be remembered simply as the month when the United States broke another temperature record. It should be remembered as a month when the nighttime thermal floor rose dramatically. The record daytime heat was dangerous. The record nighttime heat made it harder to recover from that danger.

For people, that means poorer sleep and greater cumulative heat stress. For agriculture, it means less nighttime recovery and additional physiological stress. For buildings and power systems, it means less overnight cooling and prolonged energy demand. For soils and ecosystems, it means less opportunity to shed accumulated heat.

And for the climate system itself, it is another indication that the traditional rhythm of hot day → cool night → recovery is being disrupted.

That is the significance of rising nighttime temperatures.

A hotter afternoon creates heat stress. A hotter night prevents the system from recovering from it.

When both happen repeatedly, heat stops behaving like a series of isolated events and begins behaving like a persistent environmental load.

That may ultimately be one of the most consequential—and least appreciated—features of a warming climate.
bookmark_borderIntegrated Climate Stewardship: The Fossil Fuel Question and Answer

Question:

I use phasing out in a way that means completely ending the use and production of fossil fuels down to zero. Phasing down means a gradual reduction or scaling back in FF use over time without specifying a complete stop. Would add or alter that in any way?

How would you define differntiate ‘transition away’?

Reply:

I would slightly modify your definition of “phasing down” to: “a gradual reduction or scaling back in fossil-fuel use over time without specifying a date for complete cessation.”

There are really two separate issues for me:

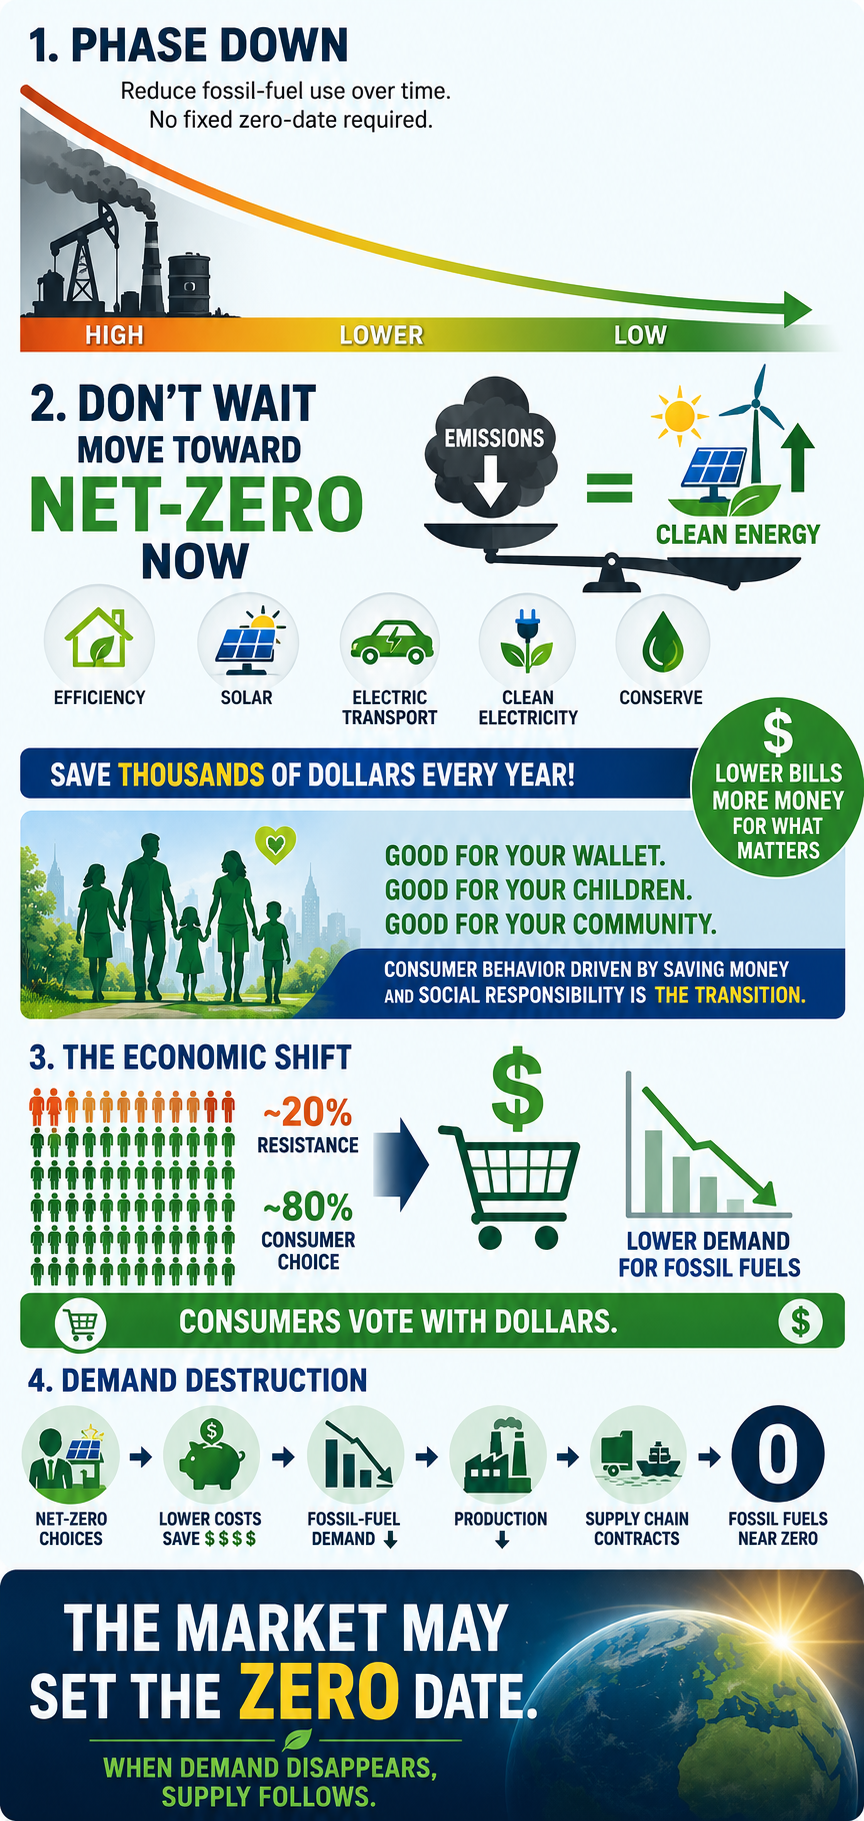
1. For this generation, I prefer net-zero carbon emissions as the immediate goal. If someone isn’t already moving toward net-zero, I think they should start now. We don’t need to wait for a theoretical future phase-out date to begin reducing emissions.

2. As both a climatologist and an economist, I’m not convinced that setting a specific date for the complete elimination of fossil fuels is ultimately what matters. In the U.S., roughly 20% of the population appears ideologically committed to policies that would accelerate climate change. Nothing I say or do is likely to change that.

But that still leaves roughly 80% of the population—and I think economics is going to do much of the work.

Right now, perhaps only ~0.5% of Americans are seriously attempting a structured net-zero lifestyle through continuous behavioral reductions and intentional balancing. As more people discover that net-zero can actually save them thousands of dollars a year while also leaving a better environment for their children and grandchildren, I expect consumer behavior to change.

When the remaining ~79.5% begin voting with their dollars, fossil-fuel demand will fall. That creates demand destruction, which ultimately means suppliers will have less and less reason to produce fossil fuels.

So, ironically, I don’t think we necessarily need to establish the exact date when fossil fuels reach zero. The market may establish that date for us. The “complete stop” happens when there is no longer sufficient demand to sustain the fossil-fuel supply chain.

Question:

When you use the term net zero is it with the understanding that the “net” component allows continuous greenhouse gas emissions under the assumption that unproven removal technologies or flawed offsets will balance them out later, delaying necessary fossil fuel phaseouts?

Net zero is a contentious term within my community and I want to be clear that I understand how you see and apply it.

Reply:

That’s an important distinction. When I use the term net-zero, I’m talking about it at the personal/lifestyle level, and I am not using “net” to justify continuing to emit greenhouse gases while assuming that unproven technologies or questionable offsets will clean up the problem later.

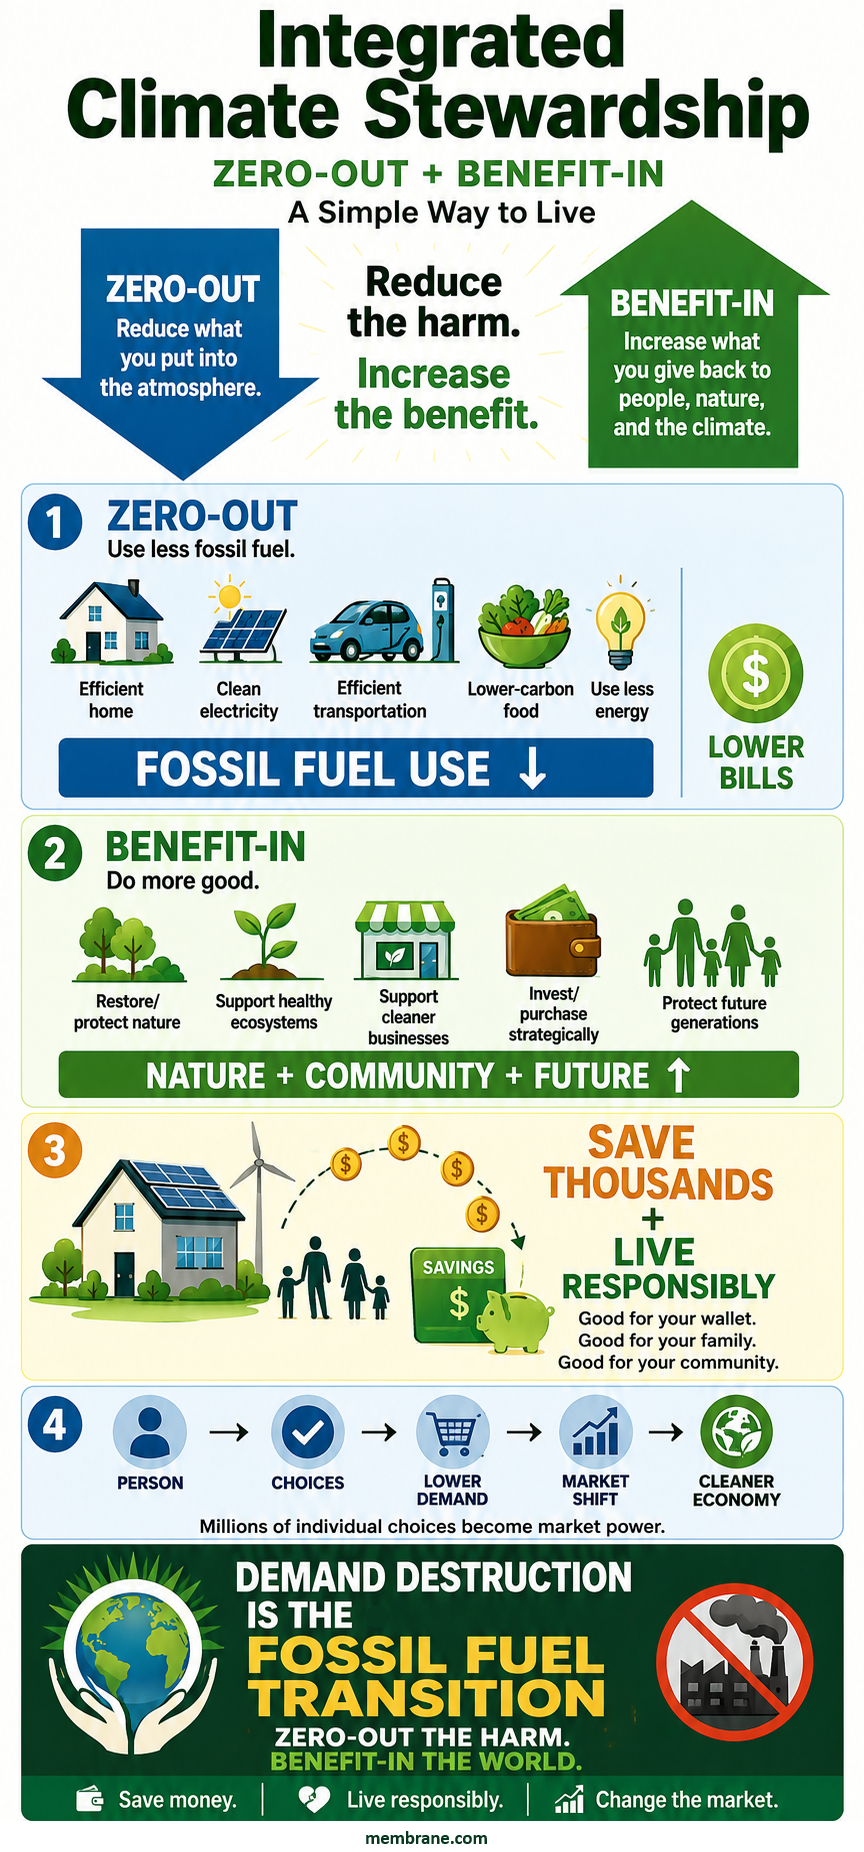
What I mean is closer to “Holistic Net-Zero Living” or “Integrated Climate Stewardship”: reducing and, wherever realistically possible, zeroing out the emissions associated with my own lifestyle first, while also taking responsibility for the impacts I can’t immediately eliminate.

For me, that means a 360-degree carbon strategy:

ZEROING OUT / STRUCTURAL DECARBONIZATION

  • Electrifying transportation and home energy
  • Increasing energy efficiency
  • Using clean electricity
  • Reducing fossil-fuel consumption as close to zero as practical
  • Reducing high-carbon consumption, including dietary choices

BEYOND MY DIRECT FOOTPRINT

  • Supporting ecosystem restoration and conservation
  • Protecting forests and biodiversity
  • Supporting businesses and technologies that accelerate decarbonization
  • Using my purchasing and investment decisions to create economic demand for cleaner alternatives

So I’m not saying, “Keep emitting and someone will remove it later.” Quite the opposite. The first priority is eliminating the emissions themselves.

I think of the “net” component as recognizing that an individual cannot instantly eliminate every indirect emission associated with modern life. Rather than pretending those emissions don’t exist, I try to compensate through additional positive actions while continuously working to reduce the underlying footprint.

Ultimately, my goal isn’t simply to achieve a favorable carbon-accounting number. It’s to change the way I live so that my actual fossil-fuel demand approaches zero—and to use my economic choices to help make that transition happen systemically.

That’s why I sometimes think “holistic net-zero living” or “integrated climate stewardship” communicates what I mean better than simply saying “net-zero.”

Question:

Why continue using the language of ‘net zero’? What economic model do you see best aligns w/ what you have outlined?

Reply:

Haaha… good questions.

A: I’m actually in the process of writing the paper that officially changes my language from “net-zero” to “Integrated Climate Stewardship.” So thank you for pushing me on that. I think the new terminology better captures what I’ve been trying to describe.

B: I’m also working on the economic model, and that one is considerably trickier—not because of the terminology, but because AI is changing the underlying economics so rapidly.

I see AI as a double-edged sword. On one edge, as AI replaces more human labor and productivity, the human contribution to economic production could eventually become a much smaller share of GDP. AI may also be capable of producing enormous amounts of economic value with far less energy per unit of output than traditional human labor and many existing production systems.

But the other edge of that sword is wealth distribution.

If the ownership of AI, capital, and productive capacity becomes increasingly concentrated, we could see extraordinary productivity growth occurring alongside increasingly unjust wealth inequality. We could potentially solve one problem—resource and energy efficiency—while creating another: who actually owns and benefits from the productivity?

That’s the economic model I’m wrestling with now: how do we build an economy where AI-driven productivity, decarbonization, consumer savings, and environmental stewardship reinforce each other while the resulting wealth is broadly distributed?

That may ultimately be a much bigger economic question than the climate transition itself.

Question:

Have you been sitting with the economic of degrowth in all of this then? Sounds like there is that tension in what is being considered.

Reply:

Yes. I’ve been sitting with the economics of degrowth quite a bit. And I think there’s an interesting tension here.

Traditional capitalism is fundamentally tied to population growth, human labor, productivity, and consumption. But AI potentially breaks that relationship. If technology increasingly replaces human labor, then economic growth can continue—even accelerate—while the economic value of human labor declines, perhaps dramatically.

So I’m not sure the future necessarily looks like “degrowth.” It may be something stranger: exponential technological growth occurring alongside declining human labor demand, an aging population in the developed regions of the world, and potentially declining population worldwide.

That raises a much bigger question: if human labor is no longer the primary engine of economic value, what exactly are we trying to maximize—and how should the economy distribute the benefits of that productivity?

That’s the economic model I’m wrestling with right now.

Question:

What about lands and waters in these considerations?

Can we agree that what we need must be either mined or grown?

Raw materials come from somewhere with significant externalities — often left out of economic theory.

My other issue is the assumptive ghost of interest-bearing-debt as a driver of unnecessary growth.

Reply:

Yes—and I think land, water, and raw materials have to be part of the model. My initial modeling, however, is pointing toward a very different problem than the one we traditionally assume.

If AI continues improving itself, productivity could eventually become extraordinarily resource-efficient. Very little additional human labor—and potentially much less land, water, or energy per unit of economic output—may be required for productivity and growth. At the same time, consumers could be forced to consume much less because their income from labor is declining. And as solar and other clean-energy technologies continue becoming cheaper, the pressure for some forms of mining and extraction could decline as well.

That brings me back to your point about interest-bearing debt. I think sovereign debt may become the critical part of the equation.

Productivity gains and abundant cheap clean energy are profoundly deflationary. Deflation sounds wonderful for consumers in theory—but not if it is accompanied by collapsing labor income. You could have falling costs and prices while households simultaneously lose the purchasing power needed to buy anything.

Now add governments facing enormous debt obligations while their traditional tax base is shrinking because human labor is becoming less economically valuable. Governments could increasingly rely on interest-bearing debt to finance poverty reduction, redistribution, and some form of basic income.

And that creates a potentially nasty feedback loop: AI-driven productivity → declining labor income → shrinking tax base → rising sovereign debt → greater reliance on monetary expansion → inflationary pressure.

Historically, severe sovereign debt problems have sometimes been resolved through substantial currency devaluation and inflation. I’m not saying hyperinflation is inevitable—but it is one of the risks I’m now modeling.

The really strange possibility is that we could simultaneously have exponential productivity, increasingly abundant cheap energy, falling costs of production—and increasing economic hardship for ordinary people.

In other words, the problem may not ultimately be whether the planet can produce enough. It may be whether humans can maintain enough income, purchasing power, and economic agency to participate in the abundance that AI creates.

That, to me, is where the economic model gets really interesting.

bookmark_borderThe Future of Energy Is Not Static

By Daniel Brouse
Economist & Climatologist
Membrane Domain USA
August 10, 2026

I’m not certain what the future holds. I don’t think anyone can be.

But I’m also not convinced that the future of fossil fuels can be projected simply by looking at today’s production levels and assuming they will continue indefinitely.

There is a very real possibility that economics, energy security, technological substitution, and even economic disruption could phase out fossil fuels much faster than most people expect.

In fact, some of the data already point in that direction.

The Energy Transition Is Already Moving

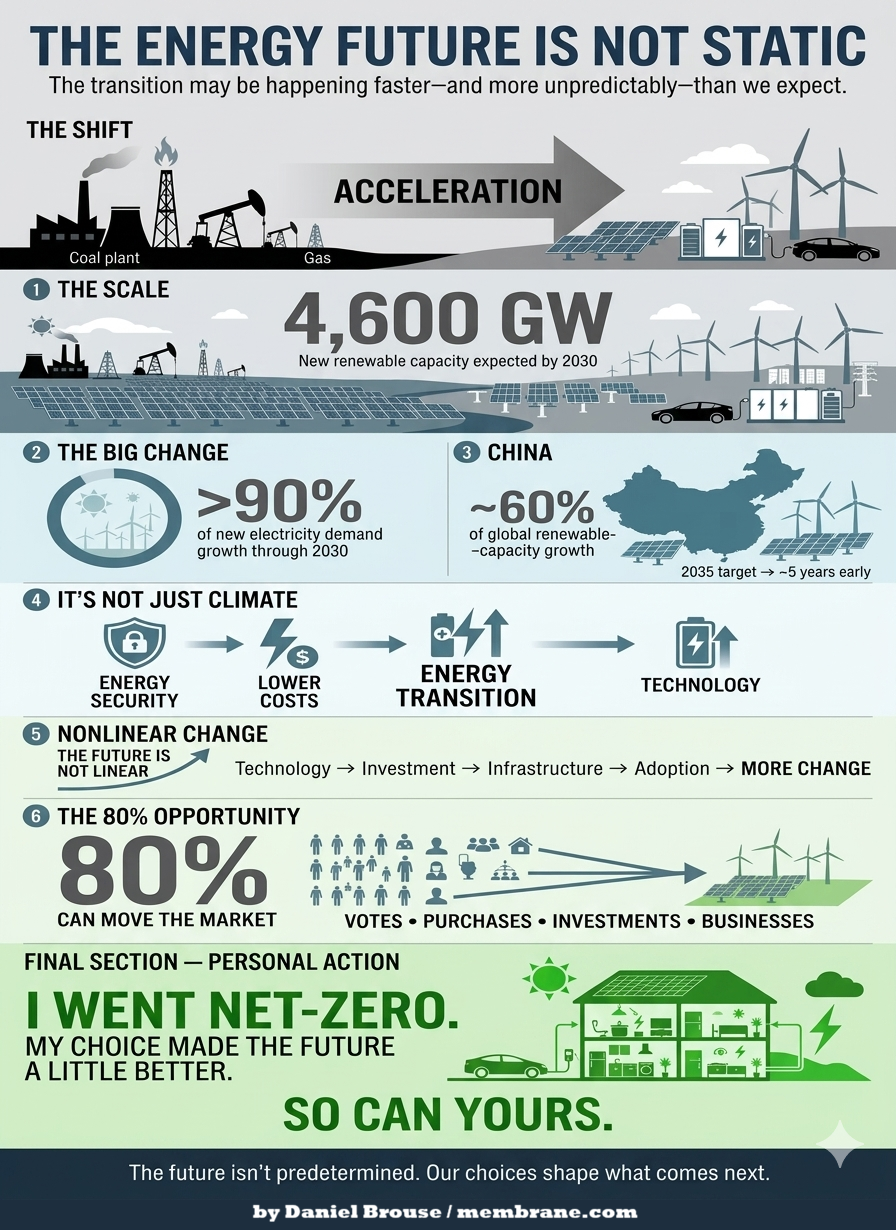
The International Energy Agency estimates that global renewable capacity will increase by roughly 4,600 GW between 2025 and 2030—an extraordinary expansion roughly equivalent to the combined current power capacity of China, the European Union, and Japan.

Solar PV is expected to account for almost 80% of that expansion.

Even more significant is what this means for the growth of electricity demand. Renewables are expected to provide more than 90% of the increase in global electricity generation through 2030.

This is not simply a distant prediction about some hypothetical future energy system. It represents an enormous investment already underway.

And the transition is happening particularly rapidly in China.

China is now responsible for nearly 60% of global renewable-capacity growth. In 2025 alone, it added roughly 314 GW of solar capacity and is on track to reach its 2035 wind-and-solar target approximately five years early.

Whatever one’s views on climate policy, these numbers are difficult to dismiss.

The global energy system is changing.

And it is changing rapidly.

This Isn’t Just About Climate Policy

There is another factor that deserves considerably more attention: energy security.

The transition away from fossil fuels is not being driven exclusively by environmental concerns. Increasingly, it is also becoming an economic and strategic imperative.

The disruption of oil and gas flows through critical transportation routes such as the Strait of Hormuz demonstrates the vulnerability inherent in an energy system dependent upon globally traded fossil fuels.

For Europe and Asia in particular, domestic renewable generation, energy storage, electrification, and efficiency increasingly represent something more than climate policy.

They are energy-security assets.

A solar panel or wind turbine doesn’t need to be transported through a geopolitical chokepoint every time it generates electricity. Once installed, domestic renewable resources can reduce exposure to international fuel-price shocks, supply disruptions, and geopolitical conflicts.

That changes the economic calculation.

And it is one reason I believe the energy transition may prove considerably more nonlinear than many conventional forecasts assume.

The Future May Be Nonlinear

I agree that we shouldn’t pretend we know exactly what the future holds.

My point is almost the opposite.

The future may be much more nonlinear than either of us can confidently predict.

Technologies don’t necessarily replace one another gradually. Once a technology becomes sufficiently cheap, reliable, scalable, and convenient, adoption can accelerate rapidly.

The same thing can happen with infrastructure.

Battery storage becomes cheaper. Electric vehicles become more capable. Solar becomes less expensive. Transmission improves. Heat pumps become more efficient. Businesses discover that electrification can reduce operating costs. Consumers begin choosing technologies that save them money.

Each development can reinforce the others.

And once enough pieces of the system change, the economics of the entire energy system can change with them.

This is why simply extrapolating today’s fossil-fuel production into the future can be misleading.

Could “Drill, Baby, Drill” Backfire?

There is an irony here.

Policies intended to expand U.S. fossil-fuel production could potentially accelerate the transition they are intended to slow if they contribute to greater volatility, geopolitical exposure, or investment in alternatives.

Consider what could happen during a serious economic downturn.

A major recession could cause substantial demand destruction. Businesses would consume less energy. Consumers would drive less and purchase fewer goods. Industrial production would decline.

Fossil-fuel consumption could fall sharply.

That would potentially undermine the very industry that policies designed around expanding fossil-fuel production are intended to strengthen.

There is no guarantee this will happen. But that’s precisely the point.

The future contains feedback loops.

Economic conditions affect energy demand. Energy prices affect technology adoption. Technology affects investment. Investment affects infrastructure. Infrastructure affects energy prices and security. Geopolitical events affect all of them.

The result is a system capable of changing much faster than a simple linear projection would suggest.

This Isn’t an All-or-Nothing Choice

I’m not trying to create another online debate.

I’m simply pointing out that the data show a transition already underway—and its speed is anything but static.

And perhaps the most important point is that this isn’t an all-or-nothing proposition.

Every increment of transition matters.

Every electric vehicle displaces some gasoline consumption. Every solar panel replaces some electricity that otherwise might have come from fossil fuels. Every efficiency improvement reduces energy demand. Every battery installation makes intermittent renewable energy more useful. Every business that electrifies reduces some exposure to fossil-fuel prices.

The more we transition, the more reasonable—and manageable—the future becomes.

We don’t need to transform the entire energy system overnight.

We need to keep moving.

Technology Is Changing More Than Energy

There is another reason I remain optimistic.

Ironically, AI and rapidly advancing technology are accelerating climate science at a pace that may eventually rival the acceleration of climate change itself.

Research that once took years can increasingly be explored in hours.

Large datasets can be analyzed in ways that weren’t previously practical. Relationships between variables can be identified more quickly. Models can be tested, refined, and compared at extraordinary speed.

I’ve been able to identify hundreds of interacting feedbacks and relationships that weren’t even being seriously considered just a few years ago.

That doesn’t mean every hypothesis will be correct.

It means our ability to investigate complex systems is expanding extraordinarily quickly.

And that gives me reason for optimism.

Humans have an extraordinary capacity to adapt, innovate, and solve difficult problems—especially when we are sufficiently motivated to do so.

The future is not predetermined.

What we do now can still make an enormous difference in what comes next.

The 80% Question

A final thought concerns something that initially struck me as particularly concerning.

Roughly 20% of Americans appear to be actively fighting the energy transition.

At first, I found that almost dumbfounding. I expected the number to be closer to less than 2%.

But there is another way to look at it.

That still leaves roughly 80% of the population.

And if that 80% chooses to act—through voting, investment, purchasing decisions, business decisions, and simply choosing where to spend their dollars—the market can move remarkably quickly.

We don’t necessarily have to fight the remaining 20%.

We can vote with our dollars.

Markets respond to demand.

If enough consumers and businesses choose alternatives, capital will follow. Manufacturers will respond. Infrastructure will change. Companies will adapt.

And eventually, the fossil-fuel industry will have to adapt as well—or gradually lose market share.

That is the power of an energy transition driven not only by government policy, but by millions of individual economic decisions.

My Choice. Your Choice. Our Future.

I went net-zero years ago.

If I can do it, anybody can.

I don’t claim that my individual decision changed the world.

But my choice made the future a little better than it otherwise would have been.

And so can yours.

The future of energy isn’t predetermined by today’s production numbers, today’s political battles, or today’s assumptions.

It will be shaped by billions of decisions made by consumers, businesses, investors, engineers, scientists, and governments.

Some of those decisions will be political.

Many will be economic.

Some will be technological.

And countless others will be personal.

That’s why I don’t think the question is whether we can predict exactly what the energy system will look like in 10, 20, or 30 years.

We can’t.

The more important question is:

What direction are we moving—and how much can our choices influence where we ultimately arrive?

The transition is already underway.

Its speed is accelerating.

And the future is still ours to shape.

bookmark_borderScience Is Science: Confronting Denialism and Ecofascism

About Denialism and Ecofascism: Science Is Science

The Observation
Glad to know you’re watching out! At the same time, this divisiveness—when we desperately need everyone to pull together because it’s a CRISIS, right?—makes me somehow deeply sad.

That’s a big job right there… How do we reach those who seem furthest away from any kind of understanding? We need both a Winston Churchill and a Mahatma Gandhi in this endeavor…

The Response
Agreed. Both denialism and ecofascism are ideologies that ultimately defy logic. In very different ways, they can become a kind of combination of self-destruction and destruction of others.

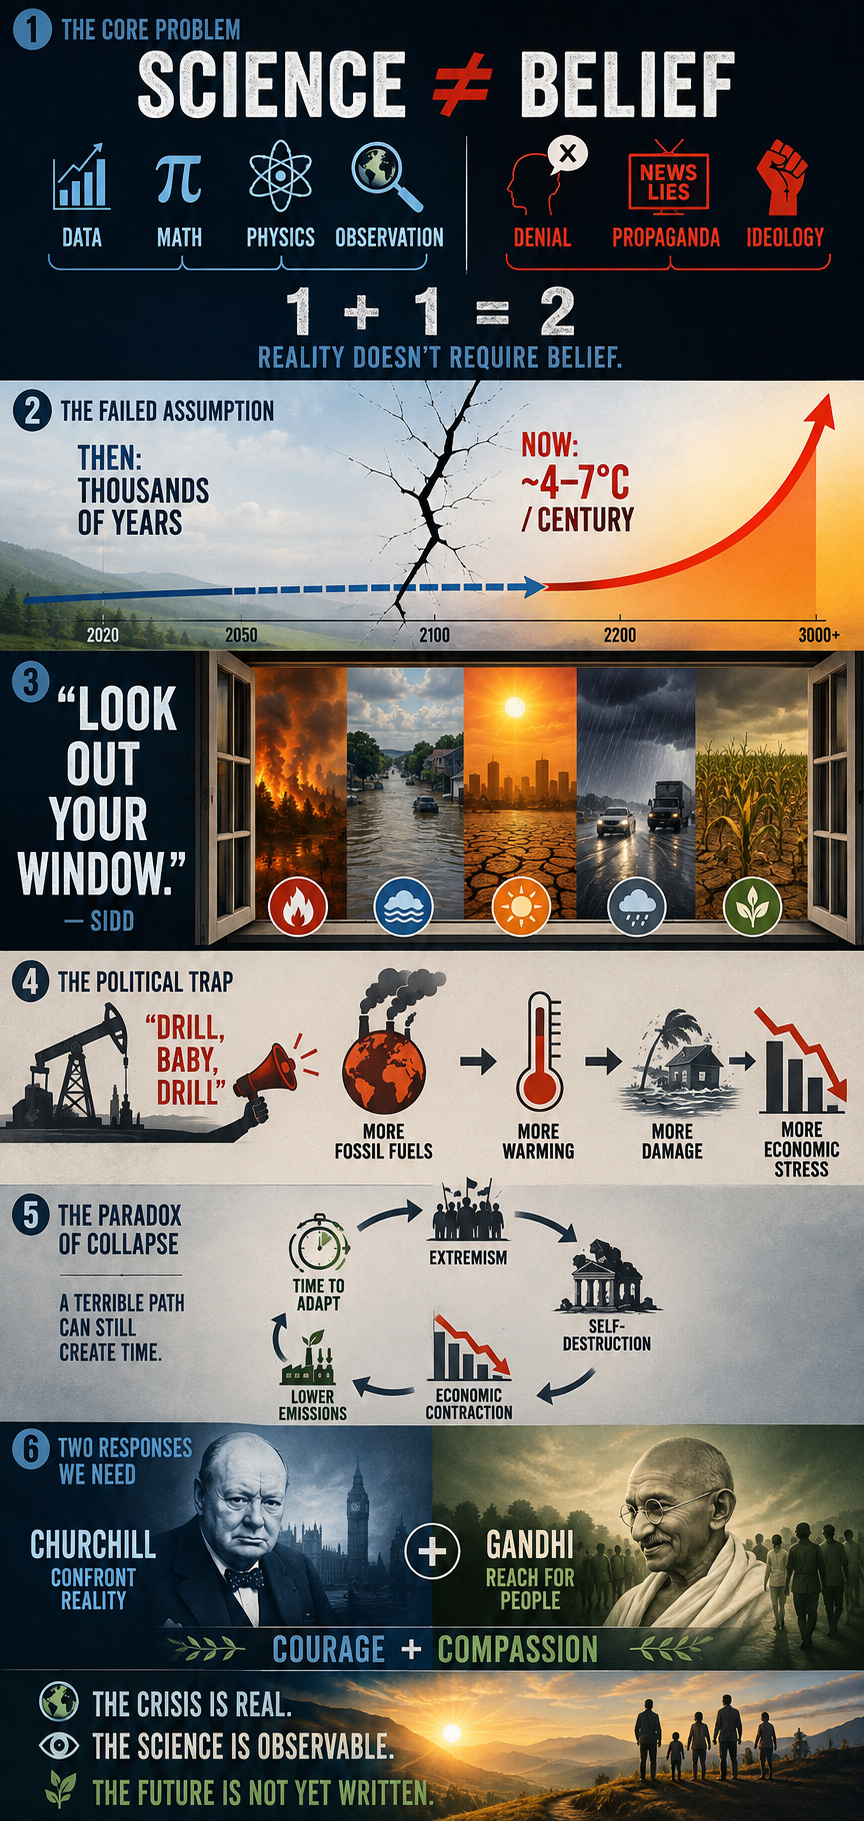
I’ve spent years battling misinformation, propaganda, and rhetoric. To the best of my knowledge, neither Sidd nor I have successfully converted—or even educated—a single committed denier. Climate science has somehow been transformed into a “belief” system. But science has nothing to do with belief. 1 + 1 = 2. If someone refuses to “believe” that, what exactly can you do?

From the beginning, our work has been based on observations, data, mathematics, and the laws of physics. So yes, I think this is at the heart of the crisis. When we started this work, we genuinely believed humanity would eventually take action. We thought we had thousands, if not tens of thousands, of years to adapt. That was the one thing we got wrong.

A couple of years ago, after explaining my continuing attempts to reach climate deniers, I asked Sidd what we could possibly do. His response was essentially, “Dude, just tell them to look out their window.” It sounds simplistic, but there is profound truth in it. The consequences are becoming increasingly difficult to deny.

Since then, we’ve had to rebuild much of our modeling. A +4°C world within thousands of years is no longer the worst-case scenario we worry about. The possibility of 4–7°C of warming within a century has become a much more serious concern in our work.

And then there is the political dimension. The rise of white-nationalist and authoritarian governments in the U.S. and elsewhere has made an already difficult problem considerably harder. Paradoxically, though, history offers one small reason for hope: fascism ultimately fails. It is inherently self-destructive.

The “drill, baby, drill” mentality is economically and environmentally self-defeating. A severe economic contraction could, ironically, buy humanity some time for adaptation while drastically reducing emissions. That is hardly the future anyone should want, but history has repeatedly demonstrated that systems built on extremism and authoritarianism eventually consume themselves.

So yes—we desperately need both the Churchill and Gandhi dimensions: the willingness to confront reality without flinching, and the willingness to keep reaching for people rather than giving up on them. I’m just not sure humanity has ever faced a crisis where we needed both quite this badly.

bookmark_borderThe Humidity Paradox: Why a Warmer Atmosphere Is Getting Wetter—and Drier at the Same Time

by Daniel Brouse

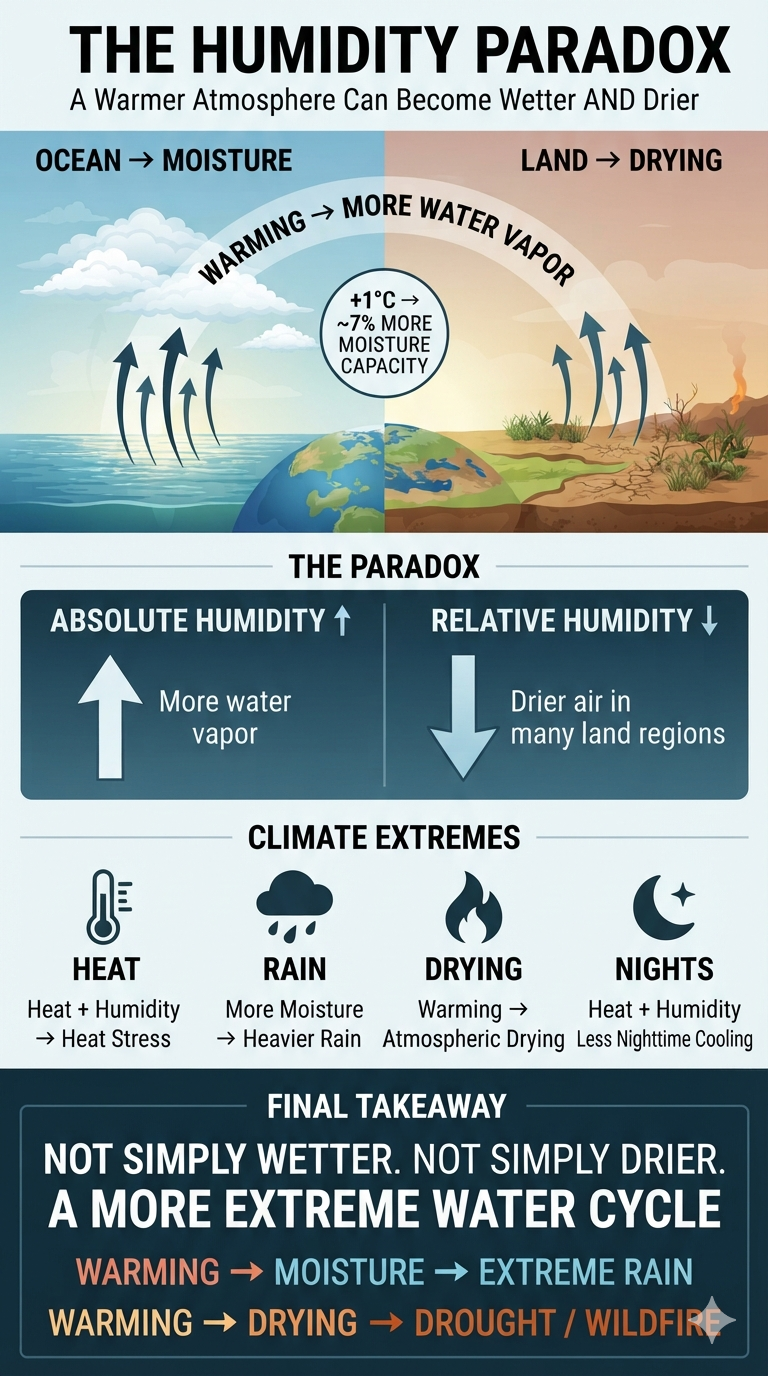
Absolute humidity—the total amount of water vapor in the air—is increasing globally as the climate warms. The fundamental physics is straightforward: according to the Clausius–Clapeyron relationship, warmer air can hold substantially more water vapor. For every 1°C (1.8°F) of warming, the atmosphere’s water-holding capacity increases by roughly 7%.

As human-caused greenhouse gas emissions raise global temperatures, evaporation from the oceans and land surface increases, adding more water vapor to the atmosphere. This creates an important distinction, however: the atmosphere can contain more water vapor even while relative humidity declines in many regions.

The Humidity Paradox

Absolute humidity measures how much water vapor is actually present in the air.

Relative humidity measures how close the air is to saturation relative to the maximum amount of moisture it could hold at that temperature.

Because warmer air has a rapidly increasing moisture capacity, these two measurements can move in different directions.

Over Much of the World’s Land

Relative humidity has declined across many continental regions. Land surfaces are warming faster than the oceans, particularly in already-dry and semi-arid regions. As temperatures rise, the atmosphere’s capacity to hold water vapor can increase faster than the actual moisture supplied by evaporation.

The result is a paradoxical combination:

More water vapor in the atmosphere + lower relative humidity = a warmer, thirstier atmosphere.

This can increase atmospheric drying demand, soil-moisture loss, vegetation stress, drought intensity, and wildfire risk.

Several regions show particularly pronounced drying trends:

  • American West and Southwest: Rapid warming is increasing atmospheric moisture demand faster than water availability in many areas, intensifying drought and wildfire conditions.
  • Interior South America: Parts of the Amazon Basin and surrounding interior regions are experiencing declining relative humidity as warming and land-use change affect moisture recycling.
  • Mediterranean Basin and Southern Europe: Declining relative humidity contributes to stronger atmospheric drying, soil desiccation, and more severe heat and drought conditions.
  • Southern Africa and Central Asia: Large continental interiors are increasingly exposed to atmospheric drying because warming is increasing moisture demand faster than local moisture supplies can compensate.

Over Oceans and Moisture-Rich Regions

Over much of the ocean, relative humidity is more stable because evaporation provides a continuing source of atmospheric moisture. In some regions, relative humidity can increase because of ocean warming, atmospheric circulation changes, and enhanced moisture transport.

The tropical oceans are especially important. Their vast warm-water surfaces provide enormous quantities of moisture to the atmosphere, helping maintain high humidity and supplying the water vapor that can fuel intense precipitation and tropical cyclones.

In the Arctic and other high-latitude regions, declining sea ice exposes more open ocean to the atmosphere. Increased evaporation from newly exposed water can raise local atmospheric moisture and influence clouds, precipitation, and regional energy balance.

Monsoonal regions can also experience large seasonal increases in humidity when atmospheric circulation transports moisture-rich maritime air over land, producing dangerous combinations of heat and humidity.

The Dangerous Consequences of Rising Atmospheric Moisture

1. Severe Heat Stress

Humidity directly affects the body’s ability to cool itself.

When air is already moisture-rich, sweat evaporates less efficiently. This reduces the body’s primary mechanism for dissipating heat and can sharply increase heat stress, particularly during prolonged periods of extreme heat.

The combination of high temperature + high humidity is therefore much more dangerous than temperature alone suggests.

2. More Extreme Rainfall

A warmer atmosphere can contain more water vapor. When moisture-rich air rises, cools, and condenses, that additional atmospheric moisture can contribute to substantially heavier precipitation.

This creates an important climate feedback:

Warming → More atmospheric moisture → Greater precipitation potential → More extreme rainfall → Greater flood risk

The same atmosphere that can become dangerously dry over land between storms can also produce much more intense rainfall when moisture is concentrated and lifted.

3. Hotter and More Humid Nights

High humidity can reduce nighttime evaporative cooling, particularly when temperatures remain elevated.

This matters because the human body needs nighttime cooling to recover from daytime heat exposure. When nights remain unusually warm and humid, physiological heat stress can accumulate over consecutive days.

The result is another dangerous combination:

Hotter days + warmer nights + higher humidity = greater cumulative heat stress.

One Atmosphere, Two Humidity Signals

The apparent contradiction between increasing absolute humidity and declining relative humidity disappears when the two measurements are understood as different properties of the atmosphere.

Absolute humidity asks: How much water vapor is actually there?

Relative humidity asks: How much water vapor is there compared with how much the warmer air could potentially hold?

Climate warming can therefore produce both simultaneously:

More atmospheric water vapor globally

while

relative humidity declines across many warming continental interiors.

This is one of the most important—and frequently misunderstood—features of climate-driven hydroclimatic change.

The atmosphere is becoming wetter in absolute terms while becoming more moisture-hungry in many land regions.

That combination can intensify the hydrologic extremes of a warming world:

More atmospheric moisture → More extreme precipitation

Warmer land → Lower relative humidity → Greater atmospheric drying demand

Higher humidity + higher temperatures → Greater heat stress

Hotter oceans → More evaporation → More atmospheric moisture

The result is not simply a “wetter” or “drier” planet.

It is a planet with a more energetic and increasingly polarized water cycle, where extreme moisture and extreme atmospheric drying can occur closer together in both space and time.

bookmark_borderReal Estate Climate Risk Models

by Daniel Brouse and Sidd Mukherjee

Background

Sidd said: “frightening article by Jeff Masters. We saw some of this coming, the flood risk aint just
along the coast, it extends 100 miles inland…
the water cant get out …”

https://yaleclimateconnections.org/2026/08/the-floods-of-the-future-wont-come-one-at-a-time/

In the 1990s, Sidd and I began developing real-estate-based climate risk models. From the beginning, one of the underlying high-risk factors was flooding—and, closely linked to it, the availability and affordability of flood insurance. In the early 2000s, we met with FEMA, Fannie Mae (FNMA), and Freddie Mac (FHLMC) to better understand their flood-risk modeling and emerging plans for managed retreat.

In October 2023, Sidd observed: “Now I am thinking the violent rain will be a bigger problem before we die.”

That concern has become increasingly relevant. As the Earth warms, warmer air can physically hold more water vapor than cooler air. For every 1°C (1.8°F) increase in temperature, the atmosphere can hold approximately 7% more moisture, increasing the potential for extreme precipitation. Over a 10°C increase, atmospheric moisture-holding capacity would nearly double, creating the potential for substantially more intense rainfall.

The problem, however, is not simply the amount of water falling from the sky. It is also what happens when that water moves across the landscape—and whether infrastructure and government response systems are capable of managing, containing, and recovering from the resulting flows.

Flow forces scale with the square of velocity (v²). As flow speeds increase—whether from heavier rainfall, steeper runoff, or more intense hydrological events—the destructive force of moving water rises rapidly. Density further magnifies this effect. Water is roughly 800 times denser than air, meaning that a comparable flow velocity can produce dramatically greater force.

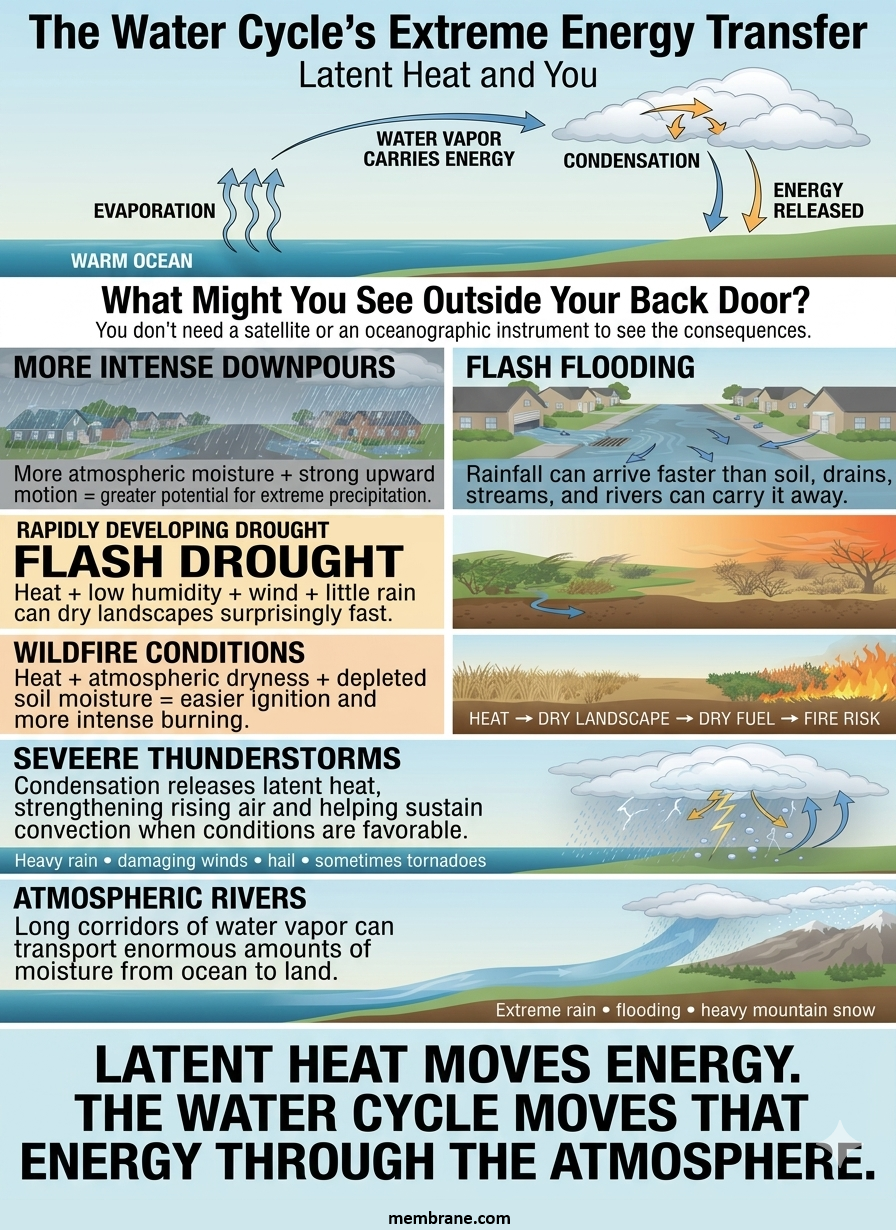
Together, we developed a series of models incorporating the Clausius–Clapeyron relationship, the extreme energy transfer within the water cycle through latent heat, and fluid-flow dynamics. These models increasingly pointed toward a risk structure in which flooding could no longer be treated as an isolated coastal problem. Instead, precipitation intensity, runoff, topography, infrastructure vulnerability, insurance stress, and limited recovery capacity can interact and compound one another across much larger regions.

By 2026, the framework had evolved from a theoretical real-estate climate-risk model into a broader multiplicative risk framework that could be evaluated against observed real-world conditions.

The latest evolution of this work is presented in the following three papers:

bookmark_borderHigh-Risk U.S. Real Estate Regions Under the Multiplicative Climate Risk Framework

by Daniel Brouse and Sidd Mukherjee

The Multiplicative Climate Risk Formula

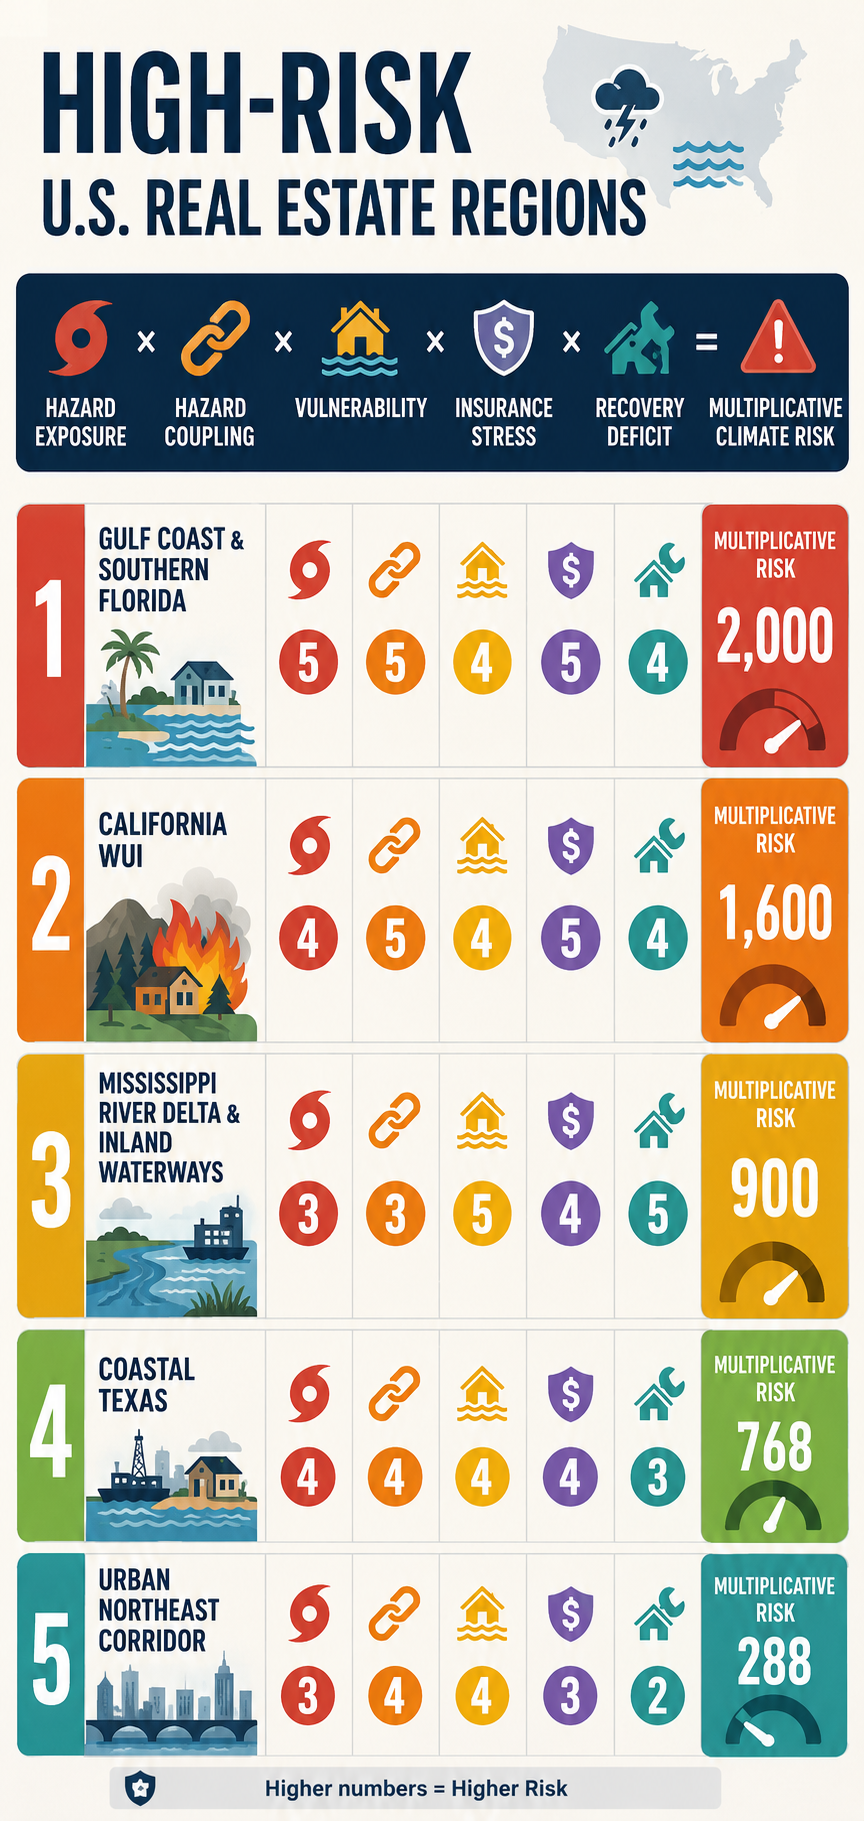
The Multiplicative Climate Risk Formula is a real-estate climate-risk model designed to capture how multiple hazards and vulnerabilities can interact and compound rather than occur independently. The framework incorporates interconnected risks including sea-level rise, storm surge, extreme precipitation, flooding, hydroclimatic whiplash, wildfires, drought, extreme heat, hurricanes, landslides, avalanches, and other cascading hazards.

Rather than treating each hazard as an isolated threat, the model evaluates how hazard exposure, hazard coupling, structural vulnerability, insurance stress, and recovery deficits can multiply overall real-estate risk.

The central premise is simple:

Climate risk is not merely additive. When multiple vulnerabilities interact, their combined impact can be substantially greater than the sum of their individual effects.

Applying the Multiplicative Climate Risk Formula reveals an important characteristic of climate-driven real-estate risk: the highest-risk regions are not necessarily those experiencing the most dramatic individual weather events. The greatest systemic risk emerges where multiple risk dimensions interact and amplify one another.

A region can experience severe hurricanes, wildfires, flooding, or extreme heat without necessarily experiencing the highest level of cascading real-estate risk. The critical question is what happens when physical hazards interact with high exposure, hazard coupling, structural vulnerability, insurance-market stress, and limited recovery capacity.

The framework therefore evaluates five interacting dimensions:

Hazard Exposure × Hazard Coupling × Vulnerability × Insurance Stress × Recovery Deficit = Multiplicative Climate Risk

Each component is scored from 1 to 5, where:

1 = Low Risk

2 = Moderate-Low Risk

3 = Moderate Risk

4 = High Risk

5 = Extreme Risk

The resulting score is not a probability of loss or a conventional actuarial measure. It is a comparative systems-risk index designed to identify locations where multiple weaknesses can reinforce one another.

This distinction is critical.

A region with a score of 5 in one category but relatively low scores elsewhere may be less systemically exposed than a region scoring 4 or 5 across nearly every category.

The multiplicative framework captures that interaction:

Physical Hazard ↑ + Coupling ↑ + Vulnerability ↑ + Insurance Stress ↑ + Recovery Capacity ↓ → Cascading Real-Estate Risk ↑↑

The following ranking represents a comparative assessment of major U.S. real-estate risk regions, incorporating physical hazards and the increasingly important financial and institutional dimensions of climate exposure.


1. Gulf Coast & Southern Florida

The Compound-Compounding Zone

Hazard Exposure — 5/5

The Gulf Coast and southern Florida face some of the country’s most concentrated combinations of acute and chronic climate hazards.

These include:

Major Hurricanes + Storm Surge + Extreme Rainfall + Sea-Level Rise + Coastal Flooding + Extreme Heat

The region’s vulnerability is not based on any single hazard. It is the convergence of multiple hazards affecting a densely developed coastal real-estate market.

Hazard Coupling — 5/5

The defining characteristic is the interaction among hazards.

A tropical cyclone can simultaneously produce:

Storm Surge + Extreme Rainfall + River Flooding + High Winds

Sea-level rise increases the baseline upon which storm surge occurs, while extreme rainfall can overwhelm drainage systems at the same time that elevated coastal water levels restrict drainage.

The resulting process is:

Hurricane → Storm Surge + Extreme Rainfall → Drainage Impairment → Compound Flooding → Widespread Property Exposure

This is precisely the type of coupled hazard that can produce disproportionate economic consequences.

Vulnerability — 4/5

The region contains enormous quantities of residential, condominium, commercial, and infrastructure assets exposed to coastal and flood hazards.

Building age and construction standards vary substantially. Newer construction and mitigation measures can reduce vulnerability, while older structures and properties with inadequate flood, wind, or drainage protection remain substantially more exposed.

The critical issue is therefore not simply the age of the housing stock, but the mismatch between:

Long-Lived Real Estate Assets → Rapidly Changing Climate Risk

Insurance Stress — 5/5

Insurance is one of the most consequential real-estate constraints in the region.

The combination of hurricanes, storm surge, flooding, wind damage, sea-level rise, and repeated catastrophe losses places substantial pressure on insurance availability and affordability.

The resulting feedback is:

Climate Risk ↑ → Expected Losses ↑ → Insurance Premiums ↑ → Deductibles and Coverage Restrictions ↑ → Insurance Availability ↓

For homeowners, insurance costs directly increase the cost of ownership.

For commercial real estate, rising insurance expenses can reduce net operating income and asset values by increasing operating costs. The effect is particularly significant for multifamily, hospitality, retail, and other income-producing properties.

The insurance problem therefore extends beyond individual policies.

It becomes a real-estate valuation problem:

Insurance Cost ↑ → Cost of Ownership ↑ → Buyer Demand ↓ → Property Values ↓

Recovery Deficit — 4/5

The region’s substantial public and private capital resources provide recovery capacity, but the scale of the infrastructure challenge is enormous.

Long-term pressures include:

Flood-Control Systems + Pump Stations + Drainage Networks + Seawalls + Roads + Bridges + Utilities + Wastewater Systems

The concern is not whether these systems can recover from one disaster.

The concern is whether:

Repeated Damage > Available Recovery and Adaptation Capacity

If the frequency of major events increases faster than infrastructure can be repaired, upgraded, or relocated, a recovery deficit can develop.

Multiplicative Risk

5 × 5 × 4 × 5 × 4 = 2,000

Total Risk Factor: 2,000

The Gulf Coast and southern Florida therefore represent the most pronounced example of compound climate-real-estate risk in the framework.


2. Central & Southern California Wildland-Urban Interface

The Fire–Flood–Insurance Cascade Zone

Hazard Exposure — 4/5

The Central and Southern California WUI faces a combination of:

Wildfire + Extreme Heat + Drought + Water Stress + Extreme Rainfall

The exposure is particularly consequential because enormous quantities of residential real estate have been constructed adjacent to or within wildfire-prone landscapes.

Hazard Coupling — 5/5

The defining feedback is:

Drought → Vegetation Stress → Wildfire → Vegetation Loss → Soil Destabilization → Extreme Rainfall → Mudslides and Debris Flows

This is a classic sequential compound-risk mechanism.

Wildfire does not simply produce immediate property losses.

It can alter the landscape in ways that increase the consequences of subsequent precipitation events.

The result is:

Wildfire → Landscape Transformation → Increased Post-Fire Flood/Mudslide Risk

This creates a risk cascade extending beyond the original fire.

Vulnerability — 4/5

Residential development in steep terrain, narrow canyons, and areas with constrained evacuation routes can create substantial exposure.

Vulnerability also depends on construction standards, defensible space, vegetation management, access routes, and the ability of communities to recover rapidly after catastrophic fires.

Insurance Stress — 5/5

California represents one of the clearest examples of insurance-market stress becoming a real-estate problem.

The combination of catastrophic wildfire exposure, rapidly changing risk conditions, and repeated losses creates pressure on insurers to increase premiums, restrict coverage, reduce exposure, or withdraw from high-risk markets.

When private insurance becomes unavailable or unaffordable, property owners may be forced into residual or state-backed insurance mechanisms.

The resulting feedback is:

Wildfire Risk ↑ → Insurance Losses ↑ → Premiums ↑ → Coverage Restrictions ↑ → Private Insurance Availability ↓ → Residual-Market Dependence ↑

This creates a second real-estate feedback:

Insurance Availability ↓ → Financing Constraints ↑ → Buyer Pool ↓ → Property Liquidity ↓ → Property Values ↓

The insurance problem can therefore become a leading indicator of broader real-estate repricing.

Recovery Deficit — 4/5

Large wildfire events can produce extensive reconstruction requirements simultaneously.

The recovery system must contend with:

Destroyed Housing + Infrastructure Damage + Debris Removal + Labor Requirements + Construction Demand + Supply Constraints

The resulting competition for labor and materials can extend rebuilding timelines and increase reconstruction costs.

The longer recovery takes, the greater the potential for:

Recovery Delay → Business Interruption → Household Displacement → Reduced Local Economic Activity → Reduced Community Resilience

Multiplicative Risk

4 × 5 × 4 × 5 × 4 = 1,600

Total Risk Factor: 1,600

The California WUI therefore represents a particularly important example of insurance availability becoming a leading indicator of real-estate climate risk.


3. Coastal Texas

The Industrial and Commercial Risk Hub

Hazard Exposure — 4/5

Coastal Texas faces:

Hurricanes + Storm Surge + Extreme Rainfall + Flash Flooding + Extreme Heat + Grid Stress

The region’s importance is amplified by its enormous concentration of industrial, commercial, petrochemical, port, logistics, and residential assets.

Hazard Coupling — 4/5

The physical hazards can interact through several pathways.

For example:

Extreme Heat → Electricity Demand ↑ → Grid Stress ↑ → Power Disruption → Cooling/Industrial/Commercial Disruption

At the same time:

Hurricane → Wind + Surge + Rainfall → Flooding + Power Loss → Business Interruption

And:

Flooding + Heat + Power Loss → Mold + Water Damage + Equipment Failure + Building-System Damage

This produces a multi-system cascade rather than a single flood loss.

Vulnerability — 4/5

Coastal Texas contains enormous concentrations of development and infrastructure in flood-prone and low-lying areas.

Impervious surfaces can increase runoff, while dense development can make drainage problems more consequential.

The concentration of industrial and commercial assets also creates correlated economic risk.

A single major event can affect multiple businesses, transportation systems, suppliers, utilities, and customers simultaneously.

Insurance Stress — 4/5

Insurance costs and coverage limitations are becoming an increasingly important component of real-estate risk.

Wind, hail, hurricane, flood, and business-interruption exposures can produce substantial premiums and deductibles.

As insurers reassess catastrophe exposure, property owners can increasingly absorb a greater portion of the risk through:

Higher Deductibles + Coverage Restrictions + Increased Premiums + Greater Self-Insurance

For commercial real estate, increasing insurance expenses directly affect:

Operating Expenses ↑ → NOI ↓ → Capitalization Value ↓

This provides a direct financial transmission mechanism between climate risk and commercial property valuation.

Recovery Deficit — 3/5

Coastal Texas possesses substantial private capital and strong economic capacity, which can accelerate reconstruction.

However, public infrastructure and regional systems can take much longer to repair.

The result is a two-speed recovery:

Private Capital → Rapid Property Recovery

while:

Public Infrastructure → Slower System Recovery

This creates a temporary resilience gap.

Multiplicative Risk

4 × 4 × 4 × 4 × 3 = 768

Total Risk Factor: 768

Coastal Texas represents an important example of how high-value commercial real estate can convert physical climate exposure into large-scale correlated financial losses.


4. Mississippi River Delta & Inland Waterways

The Structural-Aging and Recovery-Deficit Zone

Hazard Exposure — 3/5

The Mississippi Delta and associated inland waterways face:

River Flooding + Extreme Rainfall + Severe Convective Storms + Subsidence + Coastal Flooding

The region’s raw hazard exposure is lower than some Gulf Coast locations, but the interaction of hazards with infrastructure and socioeconomic vulnerability dramatically increases systemic risk.

Hazard Coupling — 3/5

One important pathway is:

Upstream Extreme Rainfall → River Discharge ↑ → Downstream Flooding → Prolonged Inundation → Structural and Infrastructure Damage

In coastal portions of the Delta, this can interact with:

River Flooding + Storm Surge + Sea-Level Rise → Compound Inland/Coastal Flooding

The duration of inundation can be as important as peak water depth because prolonged water exposure can increase mold, structural deterioration, electrical damage, and infrastructure failure.

Vulnerability — 5/5

This region’s primary vulnerability is structural.

Risk is amplified by:

Aging Infrastructure + Levee Dependence + Aging Buildings + Economic Constraints + Limited Local Fiscal Capacity

The critical issue is not simply whether flood-control infrastructure exists.

It is whether that infrastructure can be maintained, upgraded, and replaced at the rate required under changing climate conditions.

Insurance Stress — 4/5

Flood insurance is an essential component of property financing in designated high-risk areas where federal requirements apply.

However, the availability and affordability of private flood coverage can vary substantially by location and risk profile.

Where private coverage is limited, property owners can become increasingly dependent on federal flood insurance and other residual mechanisms.

This creates another form of concentration risk:

Private Insurance Capacity ↓ → Public Backstop Dependence ↑

The problem becomes more acute when repeated losses increase premiums, deductibles, or coverage restrictions faster than property values and household incomes can absorb them.

Recovery Deficit — 5/5

This is the region’s defining weakness.

A major flood can produce:

Property Damage → Income Loss → Reduced Local Tax Revenue → Infrastructure Damage → Limited Local Recovery Capacity

Federal disaster assistance can be essential, but administrative processes, funding requirements, and reconstruction complexity can extend recovery timelines.

The resulting feedback can become:

Low Local Fiscal Capacity → Slow Recovery → Persistent Damage → Lower Property Values → Lower Tax Base → Even Lower Recovery Capacity

Multiplicative Risk

3 × 3 × 5 × 4 × 5 = 900

Total Risk Factor: 900

This produces an important result:

The Mississippi Delta scores lower than Coastal Texas in raw hazard exposure but higher in total multiplicative risk.

That is precisely why a multiplicative framework is useful.

A moderate physical hazard can produce extreme systemic risk when combined with high vulnerability and a severe recovery deficit.


5. Urban Northeast Corridor

The Legacy-Infrastructure and Urban-Flooding Zone

Hazard Exposure — 3/5

The urban Northeast faces:

Nor’easters + Extreme Rainfall + Tidal Flooding + Sea-Level Rise + Urban Flash Flooding

The region does not necessarily experience the most extreme individual climate hazards in the country.

Its risk derives from density, infrastructure age, and enormous concentrations of economic value.

Hazard Coupling — 4/5

A central pathway is:

Sea-Level Rise → Higher Coastal Baseline → Reduced Stormwater Drainage Capacity → Heavy Rainfall → Urban Flooding

The resulting flooding can affect:

Basements + Subways + Tunnels + Electrical Systems + Transportation Networks + Commercial Districts

This creates a particularly important urban cascade:

Extreme Rainfall → Stormwater Overload → Transit Disruption → Workforce Disruption → Business Interruption → Economic Loss

Vulnerability — 4/5

The region contains extraordinary quantities of legacy infrastructure and older real estate.

Many structures were designed under climate conditions substantially different from those now emerging.

Below-grade spaces can be especially vulnerable:

Basement Housing + Electrical Rooms + Subway Infrastructure + Underground Transportation

This makes the region highly sensitive to intense precipitation even when properties are not located directly adjacent to rivers or coastlines.

Insurance Stress — 3/5

Insurance remains more available than in the most stressed coastal and wildfire markets, but the trajectory remains important.

Increasing flood claims, basement losses, storm damage, and infrastructure disruption can gradually increase premiums and deductibles.

The principal concern is therefore not an immediate insurance-market collapse but gradual repricing of urban climate exposure.

The feedback is:

Urban Flood Risk ↑ → Claims ↑ → Insurance Costs ↑ → Cost of Ownership ↑ → Property-Value Pressure ↑

Recovery Deficit — 2/5

The Northeast possesses comparatively strong municipal tax bases, financial resources, infrastructure institutions, and access to federal resources.

This provides substantial recovery capacity.

However, the scale and age of infrastructure create long-term adaptation challenges.

The region’s primary weakness is therefore not immediate recovery capacity but the enormous cost of modernizing legacy systems before they become repeatedly overwhelmed.

Multiplicative Risk

3 × 4 × 4 × 3 × 2 = 288

Total Risk Factor: 288

The Urban Northeast demonstrates that high population density and high property values do not automatically produce the highest multiplicative risk.

Strong fiscal and institutional recovery capacity can substantially reduce systemic risk.


Real-Estate Climate Risk Comparison Matrix

The following matrix applies the five-factor multiplicative framework:

RegionHazard ExposureHazard CouplingVulnerabilityInsurance StressRecovery DeficitMultiplicative Risk
1. Gulf Coast & Southern Florida554542,000
2. California WUI454541,600
3. Mississippi River Delta & Inland Waterways33545900
4. Coastal Texas44443768
5. Urban Northeast Corridor34432288

Why the Ranking Matters

The ranking demonstrates why climate-driven real-estate risk cannot be measured solely by the severity of weather.

The Mississippi Delta provides the clearest example.

Its 3/5 hazard-exposure score is lower than Coastal Texas’s 4/5, yet its overall multiplicative score is higher:

Mississippi Delta → 900

Coastal Texas → 768

The difference arises from the interaction of:

High Vulnerability + High Insurance Stress + Severe Recovery Deficit

This is the essence of cascading risk.

A region does not need to have the most extreme weather to have the greatest systemic vulnerability.

It needs to have the most dangerous combination of interacting weaknesses.


The Central Insurance Feedback

Across the five regions, insurance functions as one of the primary transmission mechanisms connecting physical climate risk to real-estate values.

The feedback can be represented as:

Climate Risk ↑ → Expected Losses ↑ → Insurance Claims ↑ → Premiums ↑ → Deductibles ↑ → Coverage Restrictions ↑ → Insurance Availability ↓ → Cost of Ownership ↑ → Property Demand ↓ → Property Values ↓

Once property values begin declining, another feedback can emerge:

Property Values ↓ → Mortgage Collateral ↓ → Lending Risk ↑ → Financing Constraints ↑ → Buyer Pool ↓ → Property Liquidity ↓ → Property Values ↓

Insurance therefore does not merely compensate property owners after losses.

It can influence whether a property can be:

Owned → Financed → Sold → Developed → Maintained → Insured

This makes insurance availability and affordability a critical component of real-estate climate risk.


The Major Coupled Feedback Loops

1. Insurance–Property Value Feedback

Climate Risk ↑ → Insurance Losses ↑ → Premiums ↑ / Availability ↓ → Cost of Ownership ↑ → Buyer Demand ↓ → Property Values ↓


2. Property Value–Tax Base Feedback

Property Values ↓ → Tax Base ↓ → Municipal Revenue ↓ → Infrastructure Investment ↓ → Resilience ↓ → Flood Risk ↑ → Property Values ↓


3. Recovery-Deficit Feedback

Disaster Frequency ↑ → Recovery Window ↓ → Unresolved Damage ↑ → Vulnerability ↑ → Next-Event Losses ↑ → Recovery Window ↓


4. Insurance–Mortgage Feedback

Physical Risk ↑ → Insurance Stress ↑ → Coverage Constraints ↑ → Mortgage Risk ↑ → Lending Constraints ↑ → Buyer Pool ↓ → Property Values ↓


5. Commercial Real-Estate Feedback

For income-producing properties:

Climate Risk ↑ → Insurance + Maintenance + Adaptation Costs ↑ → Operating Expenses ↑ → NOI ↓ → Property Value ↓

This relationship is particularly important for multifamily, hospitality, retail, industrial, and other income-producing properties.


The Cascading Real-Estate Framework

The five regional examples reveal several recurring stages in the emerging climate-real-estate cascade:

Physical Hazard

Warming → Sea-Level Rise + Heavier Rainfall + Stronger/Slower Storms + Extreme Heat + Drought

Hazard Coupling

Multiple Hazards → Compound Events → Greater Physical Exposure

Property Damage

Compound Hazard → Structural Damage + Infrastructure Damage + Business Interruption

Insurance Stress

Losses ↑ → Premiums ↑ + Deductibles ↑ + Coverage Restrictions ↑ + Availability ↓

Property Repricing

Insurance Cost ↑ → Cost of Ownership ↑ → Buyer Demand ↓ → Property Values ↓

Financial Amplification

Property Values ↓ → Mortgage Risk ↑ + Investment ↓ + Liquidity ↓

Municipal Amplification

Property Values ↓ → Tax Base ↓ → Infrastructure Investment ↓

Resilience Erosion

Infrastructure Investment ↓ + Recovery Capacity ↓ → Vulnerability ↑

Cascading Risk

Vulnerability ↑ → Future Losses ↑ → Insurance Stress ↑ → Property Values ↓

The resulting closed-loop system is:

Climate Hazard → Physical Loss → Insurance Stress → Property-Value Decline → Investment Decline → Tax-Base Erosion → Infrastructure Deterioration → Recovery Deficit → Greater Vulnerability → Greater Future Loss


The Central Finding

The Multiplicative Climate Risk framework produces a fundamentally different understanding of climate-exposed real estate.

The highest-risk region is not necessarily the region with:

The Most Hurricanes

The Most Wildfires

The Most Rainfall

or

The Highest Sea-Level Rise

Instead, it is the region where multiple risk factors interact:

Hazard Exposure × Hazard Coupling × Vulnerability × Insurance Stress × Recovery Deficit

The resulting system can become self-reinforcing:

Climate Hazard → Insurance Stress → Property-Value Decline → Investment Decline → Tax-Base Erosion → Infrastructure Resilience Decline → Recovery Deficit → Greater Vulnerability → Greater Future Loss

This is the central transition from climate hazard to cascading real-estate risk.

The most consequential property-market question is therefore no longer simply:

Will this property flood, burn, or be damaged by extreme weather?

It is:

Can this property remain insurable, financeable, valuable, maintainable, and economically viable as climate hazards become more frequent and increasingly coupled?

That question shifts climate-risk analysis from the physical event itself to the long-term resilience of the economic system surrounding the property.

And that is where the greatest risks may emerge.

The weather creates the shock.
Coupled hazards amplify the shock.
Insurance translates the shock into financial cost.
Real estate capitalizes the cost into property values.
Weak recovery capacity allows the damage to accumulate.
And cascading feedbacks can turn a climate hazard into a real-estate crisis.

bookmark_borderAmericans Are Feeling the Heat—But Fewer Believe Climate Change Is Happening

by Daniel Brouse

An AP-NORC poll reveals a deeply troubling contradiction in the American public’s understanding of climate change: Americans are increasingly experiencing the effects of extreme heat, yet fewer now believe climate change is actually happening.

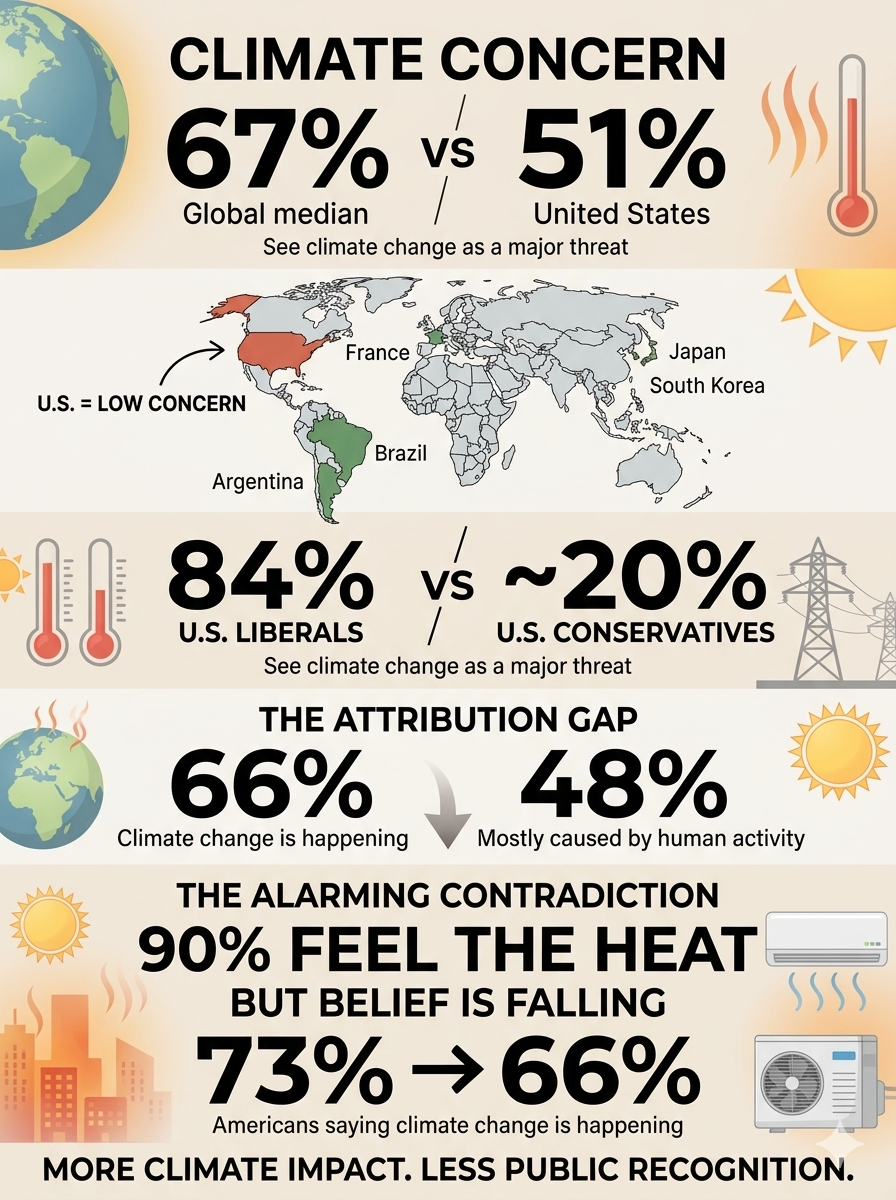
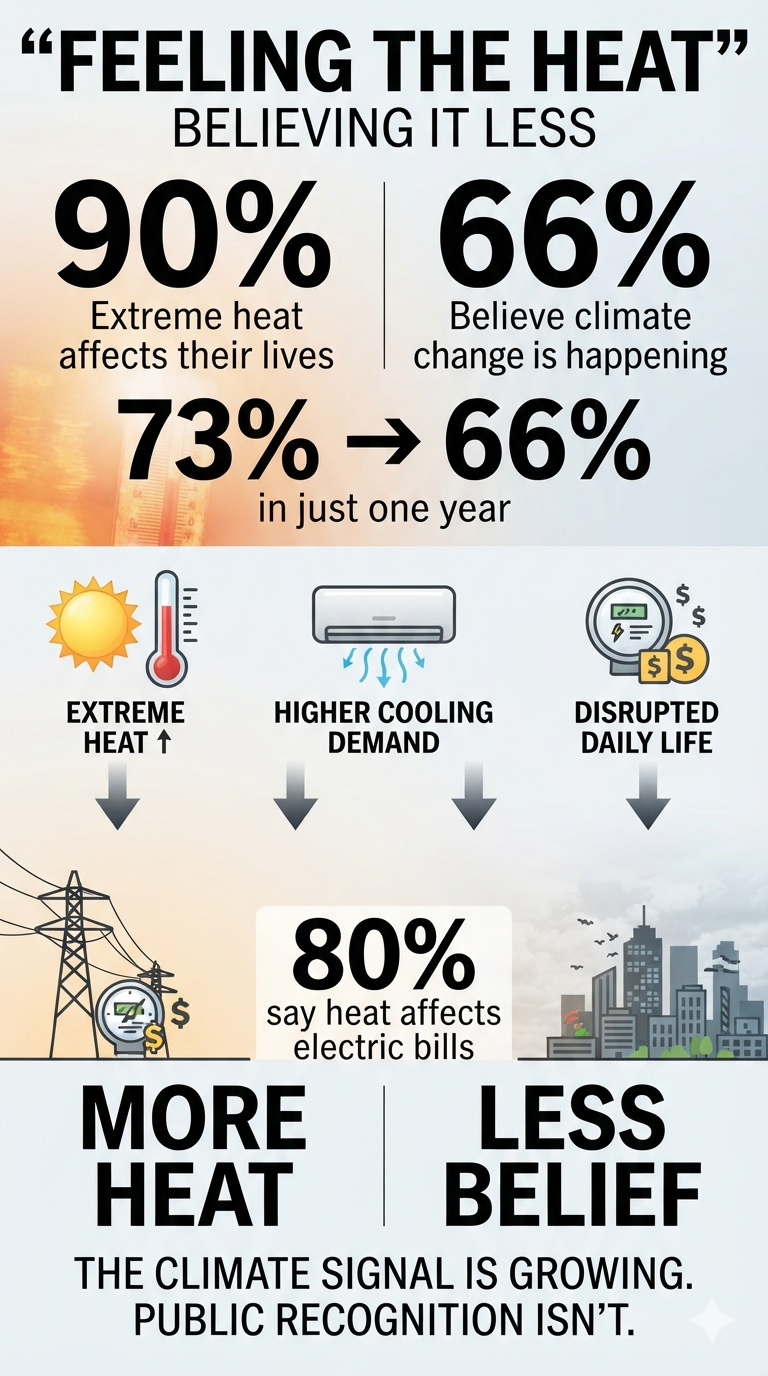
According to the poll, just 66% of Americans say climate change is happening, down sharply from 73% a year ago. That seven-percentage-point decline is particularly alarming because it comes at a time when Americans are reporting increasingly direct and disruptive experiences with extreme heat.

The disconnect raises an important question: How can people increasingly experience the consequences of a changing climate while becoming less likely to recognize climate change as the cause?

Extreme Heat Is Becoming Personal

The same poll found that 90% of Americans say extreme heat has affected their lives in some way, up from 83% in July 2024.

The impacts aren’t confined to abstract concerns about the environment. Americans report that extreme heat is affecting everyday life, including:

  • Electricity bills
  • Outdoor activities
  • Sleep
  • Travel and vacations
  • Daily routines

Perhaps most significantly, about 80% say extreme heat has affected their electricity bills, up from 69% in 2024.

In the Midwest, the increase is even more striking: 44% now say extreme heat has had a major impact on their electricity bills, compared with 29% two years ago.

That is climate change translated into something tangible: a higher household expense.

The Perception–Attribution Gap

The most important finding may not be the increase in heat-related disruption. It may be the growing gap between what Americans experience and what they believe is causing it.

The survey presents two seemingly contradictory trends:

90% say extreme heat has affected their lives.

Yet only 66% say climate change is happening.

And that 66% figure is down from 73% just one year ago.

This is a remarkable perception–attribution gap.

Americans can recognize that summers are becoming more difficult, electricity costs are rising, outdoor activities are being disrupted and extreme heat is affecting sleep—without necessarily connecting those experiences to a changing climate.

The result is a potentially dangerous disconnect between physical reality and public understanding.

Political Division Is Part of the Explanation

Political ideology continues to play an enormous role in how Americans interpret climate-related experiences.

Democrats are substantially more likely than Republicans to describe extreme heat as having a major impact on their lives. But that doesn’t mean Republicans aren’t experiencing the same heat.

The distinction is increasingly about interpretation and attribution.

People across the political spectrum can experience the same 100-degree day. They can experience the same oppressive humidity, pay the same higher electricity bill and face the same restrictions on outdoor activity.

But they may reach very different conclusions about why it is happening.

That distinction matters because climate change doesn’t require public agreement in order to produce physical consequences.

Climate Change Is Becoming an Economic Issue

The AP-NORC findings also demonstrate why climate change should not be viewed exclusively as an environmental issue.

Extreme heat creates a chain of consequences:

Higher temperatures → greater air-conditioning demand → higher electricity consumption → increased household costs

But that is only one pathway.

Extreme heat can also affect worker productivity, agriculture, infrastructure, public health, insurance losses and energy-grid reliability.

The household electricity bill may therefore be only the first visible economic manifestation of a much larger systemic problem.

The public doesn’t need to understand atmospheric physics to experience these consequences.

They simply need to notice that something is different.

The Most Alarming Finding Isn’t the Heat

The increase in extreme-heat impacts is concerning, but the seven-point decline in belief that climate change is happening may be even more alarming.

The country is experiencing a growing number of climate-related disruptions while simultaneously becoming less certain—or less willing—to identify climate change as the underlying cause.

That creates a dangerous situation for public policy.

Democratic societies depend upon the public recognizing problems before governments can effectively address them. If the physical impacts become increasingly severe while public recognition of their underlying causes declines, political pressure for adaptation and mitigation can weaken precisely when the need for action is growing.

This creates a potential feedback loop:

More climate disruption → greater personal impacts → greater economic costs → political polarization → weaker recognition of climate change → less public support for climate action → greater future vulnerability

That is not merely a communications problem.

It is a systemic risk.

Experience Is Increasing Faster Than Understanding

The AP-NORC poll doesn’t measure the physical climate system. It measures what Americans are experiencing and what they believe.

Those are different things.

The survey cannot establish how much of an individual’s electricity bill, sleep disruption or outdoor inconvenience is attributable specifically to climate change. Establishing those causal relationships requires observational climate data and scientific attribution studies.

But the poll does reveal something extremely important about the human response to climate change.

The consequences are becoming increasingly personal while public recognition of climate change is moving in the opposite direction.

That should concern everyone, regardless of political affiliation.

The challenge is no longer simply convincing people that the climate is changing.

It is explaining why their increasingly familiar experiences—extreme heat, higher cooling demand, disrupted outdoor activities, poor sleep and growing economic costs—are connected to a much larger physical system.

Americans may not agree about climate change.

But increasingly, they are living with its consequences.

And the most alarming finding from this poll is that as those consequences become harder to escape, fewer Americans say climate change is actually happening: 66% today, compared with 73% a year ago.

America Is an International Outlier on Climate Change

The decline in American belief becomes even more concerning when viewed against the rest of the world.

A 2025 Pew Research Center international survey of 25 countries found that a global median of 67% of respondents considered climate change a major threat to their country. In the United States, however, only 51% said the same—a gap of 16 percentage points.

The U.S. was among the least concerned countries surveyed. Americans were less likely than respondents in 13 of the 16 high-income countries included in the survey to view climate change as a major threat. In countries such as Argentina, Brazil, France, Japan and South Korea, roughly 80% of respondents regarded climate change as a major threat.

The difference is particularly striking because the United States is not insulated from climate impacts. Americans are experiencing extreme heat, rising cooling demand, disrupted outdoor activities and other consequences of a warming climate, yet concern about climate change remains comparatively low.

The American Divide Is Also Unusually Political

The international comparison becomes even more revealing when political ideology is considered.

Pew found that approximately 84% of U.S. liberals regarded climate change as a major threat, compared with only about 20% of U.S. conservatives. That enormous gap makes the United States an international outlier in the degree to which climate change has become politically polarized.

The result is a remarkable paradox.

Americans across the political spectrum can experience the same heat wave, pay the same electricity bill and endure the same disruption to their daily lives. Yet they may reach dramatically different conclusions about what those experiences mean.

The disagreement therefore isn’t simply about the physical environment. It is increasingly about how Americans interpret the physical environment.

Believing the Climate Is Changing Is Not the Same as Accepting Why

Another Pew measure illustrates the problem even more clearly.

In 2026, only 48% of Americans said the Earth is warming mostly because of human activity. That is substantially lower than the 66% who currently say climate change is happening in the AP-NORC poll.

The difference is crucial.

A person can acknowledge that the climate is changing without accepting that human activity is primarily responsible for that change. Others may accept human-caused warming but disagree about its severity, consequences or appropriate policy response.

This creates several layers of public perception:

Is the climate changing?

↓

Is human activity causing it?

↓

Is it becoming dangerous?

↓

Should government and society act?

Americans can answer those questions very differently.

An Alarming Combination

Taken together, the international and domestic polling reveals a troubling pattern:

90% — say extreme heat has affected their lives

80% — say heat has affected their electricity bills

73% → 66% — Americans saying climate change is happening

51% — Americans calling climate change a major national threat

48% — Americans saying warming is mostly caused by human activity

The numbers measure different things and should not be treated as interchangeable. But together they reveal a striking disconnect between experience, attribution and concern.

The United States is already an international outlier in climate skepticism and political polarization. Now, at a time when Americans report increasingly personal impacts from extreme heat, the share saying climate change is happening has fallen seven percentage points in only one year.

That may be the most troubling finding of all.

The physical climate signal is becoming harder to escape, while public recognition of that signal is moving in the opposite direction.

bookmark_borderClimate Change Impacts and You: The Rising Cost of a Changing Climate

by Daniel Brouse

Introduction

Climate change is no longer simply a future environmental threat. It is increasingly affecting American households through higher costs, declining air quality, extreme heat, infrastructure disruptions, property damage, and changing patterns of disease.

Although catastrophic floods, hurricanes, wildfires, and other disasters dominate the headlines, the most widespread climate impact may be less dramatic: the steady financial pressure climate change places on everyday household budgets. Food prices, insurance premiums, utility bills, and the costs of maintaining homes and communities are all increasingly influenced by a changing climate.

The impacts are not distributed equally. Some are nearly universal, while others are concentrated in particular regions or communities. The ranking below therefore considers two factors: how widely households are exposed and how severely the impact can disrupt everyday life.

Ranking of Climate Impacts on the Average U.S. Household

RankImpact CategoryPrimary Household ThreatsUbiquitySeverity
1Economic ImpactsFood inflation, insurance premiums, taxes, utility costsNearly universalHigh financial strain
2Air Quality & Chronic HealthWildfire smoke, longer allergy seasons, heat stressVery highHigh health risk
3Grid & Utility DisruptionsBlackouts, heat-related demand, water shortagesHigh, but regionalHigh daily disruption
4Acute Physical DamageFloods, hail, hurricanes, wildfiresRegional/localCatastrophic when exposed
5Vector-Borne DiseasesLyme disease, mosquitoes, expanding pathogen rangesRegional and expandingModerate to high health risk

Global Ranking of Climate Impacts on the Average Household

The ranking below shifts the order of impacts based on global reach and the immediate threat to human life and livelihoods across developing and developed nations alike.

RankImpact CategoryPrimary Global Household ThreatsUbiquitySeverity
1Economic & Food SecurityGlobal food price spikes, crop failures, loss of agricultural livelihoodsUniversal (100% of homes)Extreme financial/survival strain
2Acute Physical DamageCatastrophic monsoon flooding, sea-level rise, mega-wildfires, historic droughtsVery High (Millions displaced)Catastrophic loss of shelter
3Air Quality & Extreme HeatLethal wet-bulb temperatures, severe dust/smoke pollution, urban heat islandsHigh (Equatorial & Urban zones)Critical health emergency
4Grid & Utility DisruptionsTotal lack of power access, severe municipal water shortages, drying river basinsHigh (Varies by infrastructure)High daily survival disruption
5Vector-Borne DiseasesMalaria, Dengue fever expansion, waterborne cholera outbreaksExpanding (Sub-tropical regions)High health and mortality risk

1. Economic Impacts: The Most Universal Climate Burden

Economic impacts rank first because households do not have to live in a flood zone, wildfire corridor, or hurricane-prone region to pay the economic costs of climate change. Climate-related costs increasingly reach Americans through food prices, insurance premiums, utility bills, taxes, public fees, and the rising cost of maintaining homes and infrastructure.

Climate change can therefore function as a cost multiplier, increasing expenses both directly and indirectly.

Climate-Driven Food Inflation

Drought, extreme heat, excessive rainfall, and other weather disruptions can reduce agricultural yields and interfere with food production and supply chains. Because food markets are interconnected, production losses in one region can influence prices far beyond the location of the original climate event.

The effects can reach everyday staples and commodities such as coffee, wheat, corn, beef, fruits, and vegetables.

The result is a climate-related cost that can reach virtually every household through the grocery bill—even when the household is hundreds or thousands of miles from the drought, flood, or heatwave affecting agricultural production.

The Insurance Crisis

Insurance is one of the clearest mechanisms through which climate risk is transferred directly to households.

As floods, hurricanes, wildfires, severe storms, and other disasters generate increasingly costly losses, insurers may respond by raising premiums, increasing deductibles, restricting coverage, or withdrawing from particularly high-risk markets.

For homeowners, climate risk can therefore produce a double financial burden:

higher insurance costs + higher uninsured exposure.

In some locations, the problem extends beyond affordability. Homeowners may find that certain types of coverage are difficult or impossible to obtain through conventional private insurance markets.

Rising Utility Costs

Hotter summers increase demand for air conditioning. As temperatures remain elevated for longer periods, households may need to run cooling systems more frequently and for longer durations.

That increases electricity consumption while simultaneously placing additional stress on the power grid.

Climate change can therefore affect household budgets through both higher energy consumption and the cost of maintaining a more resilient electrical system.

Water systems can face similar pressures. Drought, declining water supplies, flooding, and changing precipitation patterns may require communities to invest in new reservoirs, treatment capacity, pipelines, drainage systems, and other infrastructure.

Those investments ultimately have to be paid for.

Taxes, Assessments, and Public Costs

One of the least visible climate costs is the portion that reaches households through government budgets rather than private markets.

When climate-related disasters become more costly, governments must spend more on emergency response, disaster recovery, infrastructure repair, flood protection, stormwater management, wildfire preparedness, water systems, coastal protection, and long-term climate adaptation.

Those expenses can eventually reach households through:

  • Property taxes used to finance infrastructure repairs and resilience projects.
  • Special assessments and municipal fees for stormwater, drainage, flood control, and other local projects.
  • Higher utility rates needed to upgrade vulnerable water and electrical systems.
  • State and federal taxes that help finance disaster recovery, emergency response, agricultural assistance, infrastructure rebuilding, and resilience programs.
  • Public insurance and disaster programs when private insurance markets cannot absorb the full cost of catastrophic losses.

This creates an important economic chain:

Climate hazard → physical damage → insurance losses → government response → infrastructure spending → taxes, fees, and utility costs.

The household may never experience the original flood, wildfire, hurricane, or drought, yet it can still participate in paying the bill.

Rising Property and Maintenance Costs

Climate stress can also increase the cost of owning and maintaining a home.

More intense rainfall can require improved drainage. Stronger storms can increase demand for roofing and exterior repairs. Heat can accelerate deterioration of infrastructure and building materials. Flooding and wildfire risk can require additional mitigation measures.

At the same time, widespread disasters can create temporary shortages of construction materials, contractors, equipment, and skilled labor, increasing repair costs.

The Hidden Climate Cost

Taken together, these effects mean that climate change does not have to destroy your home to affect your household finances.

A household can experience climate-related costs through:

  • Higher grocery prices
  • Higher insurance premiums
  • Higher electricity and water bills
  • Higher taxes and public fees
  • Higher repair and maintenance costs

Together, these expenses create a growing household climate burden—even when a family never experiences a major climate disaster firsthand.

The important point is that climate change is not simply a collection of isolated disasters. It is increasingly an economic force that propagates through markets, insurance systems, government budgets, and household expenses.

For the average American household, this may ultimately be the most widespread way climate change is experienced: not as one catastrophic event, but as a persistent accumulation of additional costs.

2. Air Quality & Chronic Health: A Widespread Physical Exposure

Climate change also affects the quality of the air people breathe.

Wildfire Smoke

Wildfire smoke can travel hundreds or even thousands of miles, carrying fine particulate matter such as PM₂.₅ into communities far from the original fire.

These particles can penetrate deep into the respiratory system and aggravate existing respiratory and cardiovascular problems. As wildfire activity and smoke exposure increase in some regions, air-quality impacts are no longer limited to communities immediately adjacent to fires.

Longer Allergy Seasons

Warmer temperatures can alter plant growing seasons and extend periods of pollen production.

For people with asthma or seasonal allergies, longer or more intense pollen seasons can mean more days of symptoms, greater medication use, and reduced quality of life.

Heat Stress

Rising baseline temperatures also increase the frequency and duration of dangerous heat.

Homes without adequate cooling, outdoor workplaces, and communities with limited access to cooling resources can be particularly vulnerable. Extreme heat is not merely uncomfortable—it can place substantial physiological stress on the human body.


3. Grid & Utility Disruptions: Climate Stress on Essential Infrastructure

Modern households depend on electricity, water, transportation, telecommunications, and other infrastructure every day.

Climate extremes can place additional stress on these systems.

Power Grid Failures

Extreme heat can push electricity demand toward peak levels as households and businesses increase air-conditioning use.

At the same time, extreme weather can damage transmission lines, substations, transformers, and other infrastructure.

The consequences can range from higher electricity costs to localized outages and, under severe conditions, prolonged disruptions to essential services.

Water Scarcity

Drought can reduce reservoir levels, groundwater availability, and other sources of municipal water.

Communities may respond with conservation requirements, watering restrictions, infrastructure investments, or higher water costs.

Water stress can therefore become both an environmental problem and a household financial problem.


4. Acute Physical Damage: Catastrophic Where It Strikes

Floods, hurricanes, wildfires, severe thunderstorms, hail, and high winds can cause enormous damage to homes, vehicles, businesses, and infrastructure.

This category ranks fourth not because the damage is minor, but because exposure is geographically concentrated.

A household directly hit by a major disaster can experience losses vastly greater than those associated with ordinary climate-related inflation.

Floods and Flash Floods

Intense rainfall can overwhelm drainage systems and produce rapid flooding in locations that may not have traditionally been considered high-risk.

Coastal communities also face storm surge and rising sea levels that can increase the consequences of major storms.

Severe Hail and Wind

Severe convective storms can produce damaging hail and straight-line or tornadic winds.

Roofing, siding, windows, vehicles, and other property can be damaged within minutes, creating repair costs that are often compounded by rising construction and insurance expenses.

Wildfires

Wildfires can destroy homes and communities directly while also creating secondary effects through smoke, evacuation, infrastructure disruption, and insurance losses.


5. Vector-Borne Diseases: A Smaller but Expanding Risk

Climate change can also alter the geographic range and seasonal activity of disease-carrying organisms.

Tick-Borne Illnesses

Changes in temperature and seasonal conditions can affect the distribution and activity of ticks and their hosts.

In some regions, this may increase opportunities for exposure to Lyme disease and other tick-borne illnesses.

Mosquito-Borne Diseases

Changing temperature and precipitation patterns can also influence mosquito populations and the geographic conditions suitable for certain mosquito-borne diseases.

The importance of this category varies considerably by region, but changing environmental conditions can alter the boundaries of disease risk over time.

Other Pathogens

Environmental changes can also affect exposure to less common infectious diseases, including tularemia (rabbit fever), which can be transmitted through several pathways involving ticks, biting flies, infected animals, or contaminated environments.


The Basics: How Climate Change Reaches Your Household

Climate change may seem like a global-scale phenomenon, but its consequences increasingly arrive through very ordinary parts of daily life.

Your Wallet: A Rising Cost of Living

Climate change can function like a hidden cost multiplier, increasing expenses directly and indirectly.

  • Higher grocery bills: Weather extremes can disrupt agricultural production and food supply chains.
  • Higher insurance premiums: Increasing disaster losses can raise premiums, deductibles, and coverage costs.
  • Higher utility bills: Hotter temperatures increase cooling demand and electricity consumption.
  • Higher repair costs: Disasters can increase demand for construction materials, contractors, and replacement vehicles.
  • Higher infrastructure costs and taxes: Communities may need to spend more on flood protection, stormwater systems, water supplies, roads, and electrical infrastructure.

The result is that climate change does not need to destroy your house to affect your household finances.


Your Health: New Physical Strains

A warmer climate can change the environmental conditions in which people live.

Extended Allergy Seasons

Longer growing seasons and changing pollen patterns can increase exposure for people with seasonal allergies and asthma.

Heat Stress

More frequent and intense heat events increase risks of heat exhaustion, heatstroke, dehydration, and other heat-related illnesses.

Air Pollution

Wildfire smoke and other climate-related air-quality problems can expose people to unhealthy concentrations of fine particulate matter.

Vector-Borne Disease

Changing environmental conditions can alter the geographic and seasonal ranges of ticks, mosquitoes, and other disease vectors.


Your Environment: Infrastructure and Safety

Climate change also affects the physical systems surrounding your home.

Property Damage

Flooding, severe storms, wildfires, hail, and high winds can damage homes, vehicles, and personal property.

Travel Disruptions

Flooded roads, damaged bridges, severe storms, wildfire smoke, and extreme heat can disrupt transportation and cause delays.

Power and Water Reliability

Extreme heat, drought, storms, and other hazards can put additional pressure on electricity and water systems.

These disruptions can affect people even when their own property escapes direct physical damage.


What You Can Do

Climate change is a global problem, but households can take practical steps to reduce both personal vulnerability and unnecessary expense.

Audit Home Energy

Improve insulation, use efficient lighting and appliances, and manage heating and cooling more efficiently.

Prepare for Emergencies

Maintain a basic emergency kit, understand local flood and wildfire risks, and have a plan for prolonged power outages.

Protect Your Property

Keep gutters and drainage systems clear, maintain trees and vegetation around structures, and understand your property’s exposure to flooding, wind, wildfire, and other hazards.

Reduce Waste

Reducing food waste, conserving water, and using energy efficiently can lower household costs while reducing resource demand.

Know Your Insurance

Review deductibles, exclusions, flood coverage, and other policies before disaster strikes. Standard homeowners insurance does not necessarily cover every major climate-related hazard.


The Bottom Line

Climate change is often discussed in terms of distant environmental consequences, but for American households, the most immediate effects are increasingly personal and financial.

You may encounter climate change as:

a higher grocery bill,
a larger insurance premium,
a higher electric bill,
a smoky summer afternoon,
a longer allergy season,
a power outage,
a flooded road,
a damaged roof,
or a greater risk of heat stress.

The most dramatic climate disasters will continue to make the headlines. But the deeper transformation may be quieter: climate change is becoming embedded in the ordinary economics and infrastructure of everyday life.

The question is no longer simply what will climate change do to the planet?

It is increasingly:

What will climate change cost you?

bookmark_borderThe Water Cycle’s Extreme Energy Transfer

Latent Heat and You

By Daniel Brouse

You probably think of the water cycle as a simple process:

Evaporation → clouds → rain

But there is something hidden inside that cycle: energy.

Every time water evaporates, enormous amounts of energy move from one place to another. As climate change warms the oceans and atmosphere, this energy-transfer system is becoming more powerful—and you may see the consequences right outside your back door.


The Invisible Energy Transfer

When sunlight warms the ocean, some of that energy becomes heat stored in the water.

But the ocean also has a powerful way to get rid of heat: evaporation.

When a water molecule changes from liquid to vapor, it takes energy with it. That energy is called latent heat.

Approximately:

1 kilogram of evaporated water = about 2.45 megajoules of energy transported into the atmosphere.

That is energy you cannot see.

The water vapor can then travel hundreds or thousands of miles before it condenses into clouds and rain.

When condensation occurs, the stored energy is released back into the atmosphere as heat.

So the basic process is:

Ocean heat → evaporation → water vapor → atmospheric transport → condensation → heat released into the atmosphere

The water cycle is therefore also an energy-transfer system.


Why Does Climate Change Matter?

A warmer planet changes both sides of this process.

Warmer ocean water provides more energy for evaporation.

At the same time, warmer air can contain more water vapor. The Clausius-Clapeyron relationship tells us that the atmosphere’s capacity to hold water vapor increases by roughly 7% for every 1°C (1.8°F) of warming.

That does not mean rainfall increases everywhere by 7%. Weather patterns, circulation, geography, and seasonal conditions still determine where and when rain occurs.

But it does mean that when the atmosphere has access to additional moisture, there is more water—and therefore more latent energy—available to move through the weather system.

Think of the atmosphere as carrying an invisible reservoir of water and stored energy.

As that reservoir grows, some weather events can become more intense.


The Same Energy Can Help Produce Drought AND Flooding

This is where things become especially important.

During a hot, dry period, increased evaporation can pull moisture out of:

Soil → vegetation → lakes → streams

That can accelerate drying.

The sequence can look like:

Heat → increased evaporation → soil moisture loss → stressed vegetation → flash drought → wildfire risk

Then the weather pattern changes.

Moisture that has accumulated over warm oceans can be transported into the region. When that moisture rises and condenses, its stored latent heat is released into the atmosphere.

The sequence can become:

Warm ocean → evaporation → water vapor → moisture transport → rising air → condensation → latent heat release → stronger convection → heavier rainfall

The result can be a rapid transition from extreme dryness to extreme rainfall.

This is one component of what scientists call hydroclimatic whiplash.


What Might You See Outside Your Back Door?

You don’t need a satellite or an oceanographic instrument to see the consequences.

You may notice:

More intense downpours

Instead of a steady, moderate rain, you may experience rainfall that dumps a large amount of water in a short period.

More atmospheric moisture + strong upward motion = greater potential for extreme precipitation.

Flash flooding

When rainfall arrives faster than soil, storm drains, streams, and rivers can absorb or carry it away, water rapidly accumulates.

A few hours of extreme rainfall can overwhelm systems designed for older precipitation patterns.

Rapidly developing drought

A landscape can dry surprisingly quickly when high temperatures combine with low humidity, wind, and a lack of rainfall.

This can produce flash droughts that develop much faster than traditional droughts.

Wildfire conditions

Dry vegetation becomes fuel.

Heat + atmospheric dryness + depleted soil moisture can create landscapes that ignite more easily and burn more intensely.

Severe thunderstorms

Condensation releases latent heat into storm clouds. That energy can strengthen rising air and help sustain convection when other atmospheric conditions are favorable.

The result can include stronger thunderstorms, torrential rain, damaging winds, hail, and sometimes tornadoes.

Atmospheric rivers

Long corridors of moisture can transport enormous quantities of water vapor from the ocean toward land.

When those moisture streams encounter favorable atmospheric conditions, they can produce extreme rainfall, flooding, and—in mountainous regions—heavy snowfall.


The Climate Change Connection

The important point is not that climate change “causes every storm.”

It doesn’t.

Weather is still controlled by many interacting factors, including atmospheric pressure, temperature gradients, moisture gradients, winds, fronts, topography, and natural climate variability.

Climate change changes the background conditions in which those weather systems operate.

A warmer atmosphere can hold more moisture.

A warmer ocean can provide more moisture through evaporation.

A warmer climate can increase evaporative demand over land.

And when abundant moisture eventually condenses, the release of latent heat can add energy to developing storms.

The result is a climate system with the potential for more extreme swings:

Heat → drying → drought → wildfire

followed by:

Moisture transport → intense rainfall → flooding → erosion

And sometimes the cycle can repeat.


The Hidden Energy in a Raindrop

The next time you watch a heavy rainstorm from your back door, consider what you are actually seeing.

That rain began as water somewhere else—often over an ocean.

Energy from the Earth’s climate system helped evaporate it.

Atmospheric circulation transported it.

The water vapor eventually rose, cooled, and condensed.

And when it condensed, the energy stored during evaporation was released into the atmosphere.

What looks like “just rain” is actually the final visible stage of a massive planetary energy-transfer process.

The water cycle moves water.

The latent heat cycle moves energy.

And climate change is altering both.


The Bottom Line

The most important idea is simple:

Warm oceans → more evaporation → more atmospheric moisture → more latent energy available to weather systems.

At the same time:

Hotter land → greater evaporative demand → faster drying → greater drought and wildfire risk.

Those two pathways can collide when atmospheric circulation transports moisture into a region that has just experienced prolonged heat and dryness.

That is the essence of hydroclimatic whiplash:

Drought can be followed by flooding.

Wildfire conditions can be followed by extreme rainfall.

A warming climate can produce both more intense drying and more intense precipitation.

The water cycle is not just about where the water goes.

It is about where the energy goes.

And as the planet warms, understanding that hidden energy transfer is increasingly important to understanding the extreme weather we can see right outside our own back doors.