During the 1980s, I worked primarily as an economist specializing in risk management. By the early 1990s, however, it had become clear that the greatest systemic risk facing civilization was not financial—it was climate change.
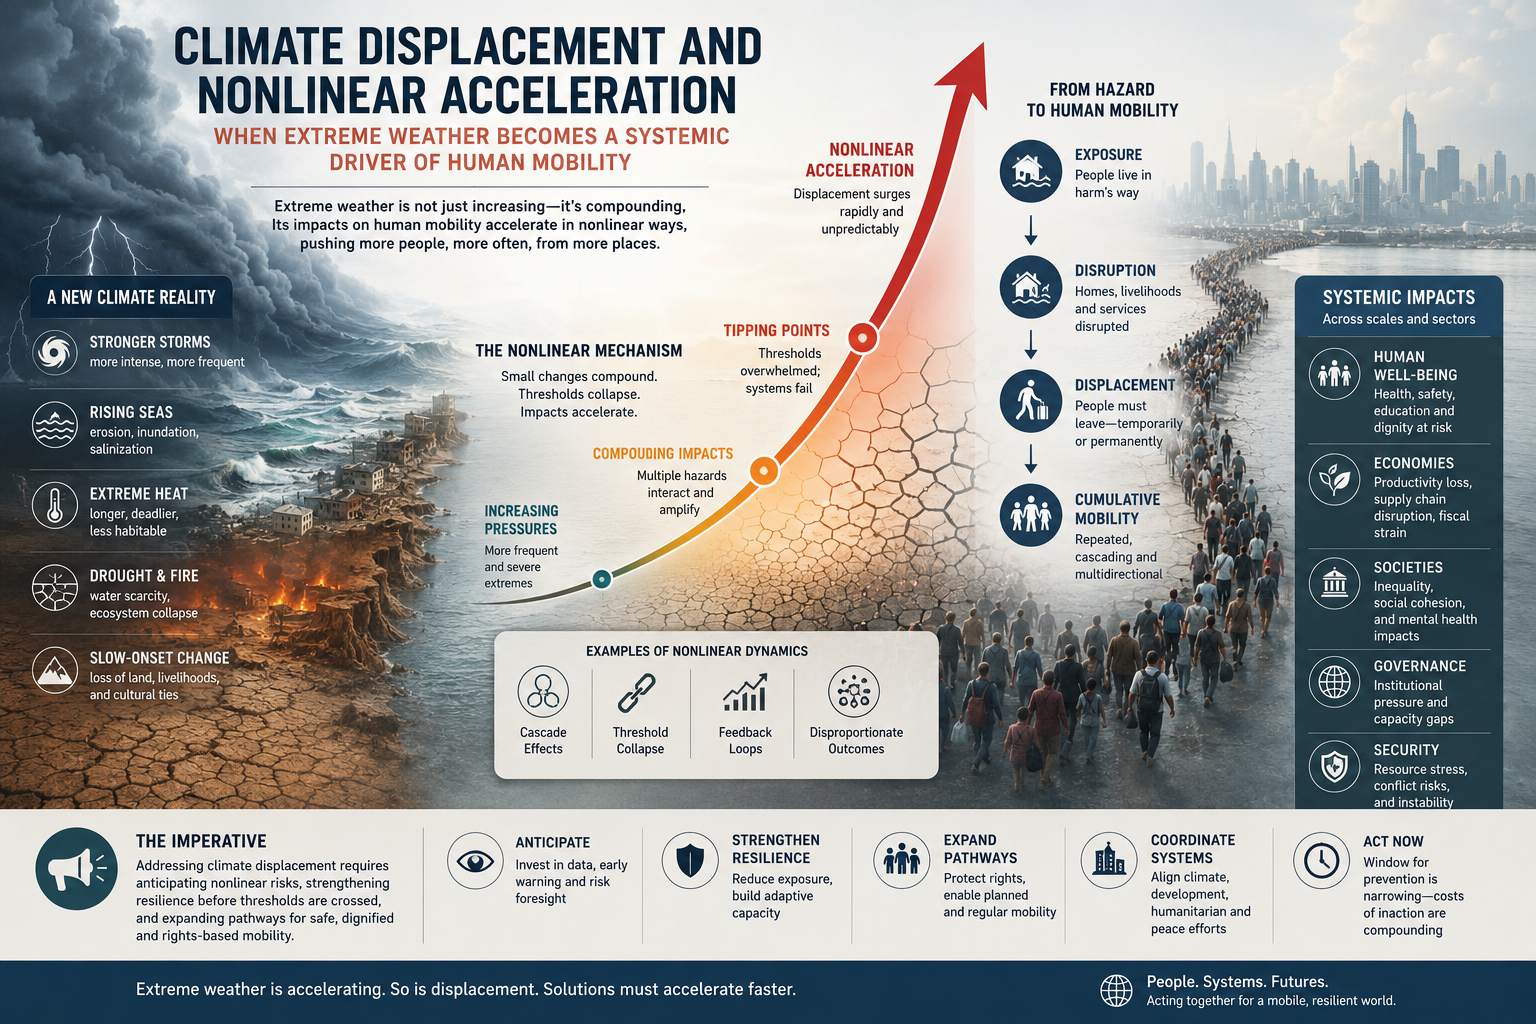
Working with physicist Sidd Mukherjee, we began developing what we called the Nonlinear Acceleration Hypothesis: the idea that climate change would not progress as a slow, linear process, but instead would accelerate as reinforcing Earth-system feedbacks became increasingly dominant.
Over the past three decades, an expanding body of observational evidence has increasingly supported this perspective. Today, nonlinear climate dynamics, positive feedbacks, tipping points, and cascading Earth-system interactions have become central concepts within modern climate science and climate-risk research.
From Linear Assumptions to Nonlinear Reality
By 1995, I had become convinced that many climate indicators were evolving exponentially rather than linearly. Sidd agreed the hypothesis was plausible but argued that a much longer observational record would be necessary before drawing firm conclusions.
At the time, most climate projections implicitly assumed relatively gradual warming. While serious, climate change was generally viewed as unfolding over centuries, leaving substantial time for adaptation and mitigation.
Yet observational evidence already suggested something different. Looking beyond annual variability, many climate indicators appeared to be accelerating.
By 2004, sufficient observations had accumulated to demonstrate nonlinear behavior across multiple components of the Earth system. Greenland Ice Sheet dynamics, in particular, were no longer consistent with simple equilibrium assumptions. Ocean heat uptake, ice-sheet mass loss, atmospheric moisture, and extreme precipitation all exhibited increasing rates of change.
A striking pattern emerged.
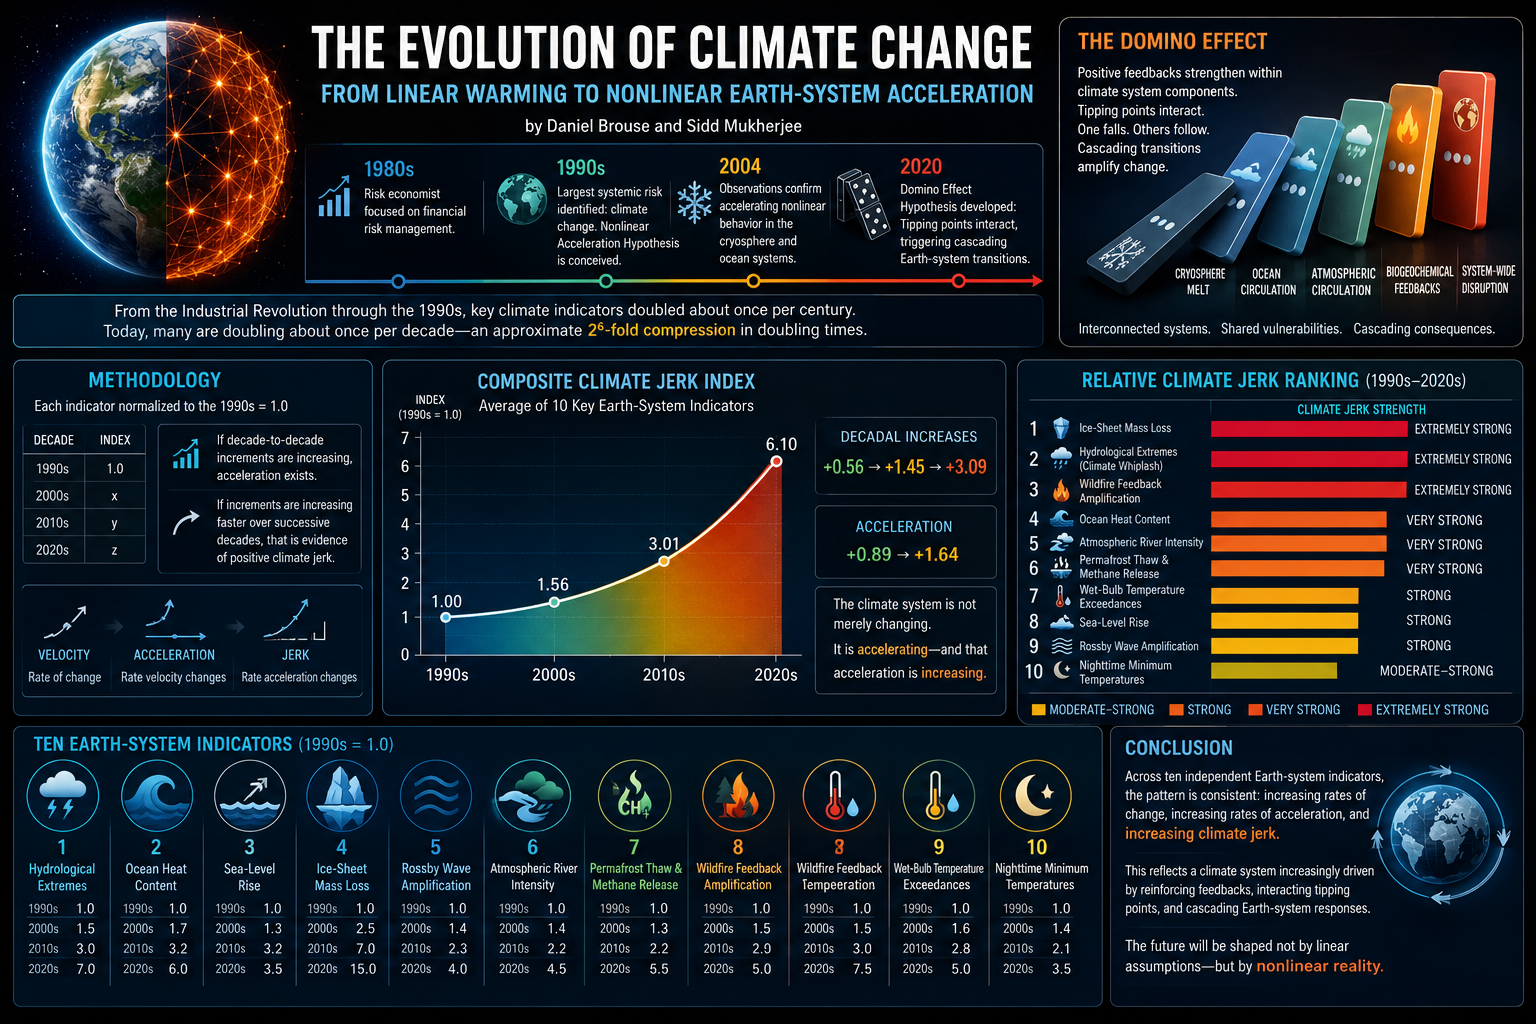
From the Industrial Revolution through approximately the 1990s, many leading indicators of climate change appeared to double on timescales approaching one century.
Today, many of those same indicators are doubling on timescales measured in roughly one decade.
This represents an approximate 2⁶-fold compression of doubling times over successive decades—a remarkable acceleration in the pace of climate change.
Rather than simply warming faster, the Earth system appears to be evolving into an increasingly nonlinear state in which the rate of change itself continues to accelerate.
If sustained, this may represent one of the most abrupt large-scale climate transitions in Earth’s geological history.
The Domino Effect
By 2020, our work expanded into what we termed the Domino Effect Hypothesis.
Many components of the climate system contain internal positive feedback mechanisms. As these feedbacks strengthen, the climate system becomes progressively less dependent upon external forcing because it increasingly reinforces its own evolution.
These critical threshold transitions are commonly known as climate tipping points.
Unlike gradual warming, tipping points exhibit nonlinear behavior in which relatively small additional forcing can produce disproportionately large—and potentially irreversible—changes.
Even more importantly, tipping points rarely occur in isolation.
The atmosphere, oceans, cryosphere, biosphere, and carbon cycle are tightly interconnected. Destabilization within one subsystem can reduce the stability of others, producing a sequence of interacting transitions throughout the Earth system.
This cascading behavior—often referred to as tipping cascades—forms the basis of the Domino Effect.
Since its proposal, extensive observational evidence has demonstrated that interacting climate feedbacks are a defining feature of modern climate dynamics and now occupy a central position within contemporary climate-risk literature.
Methodology
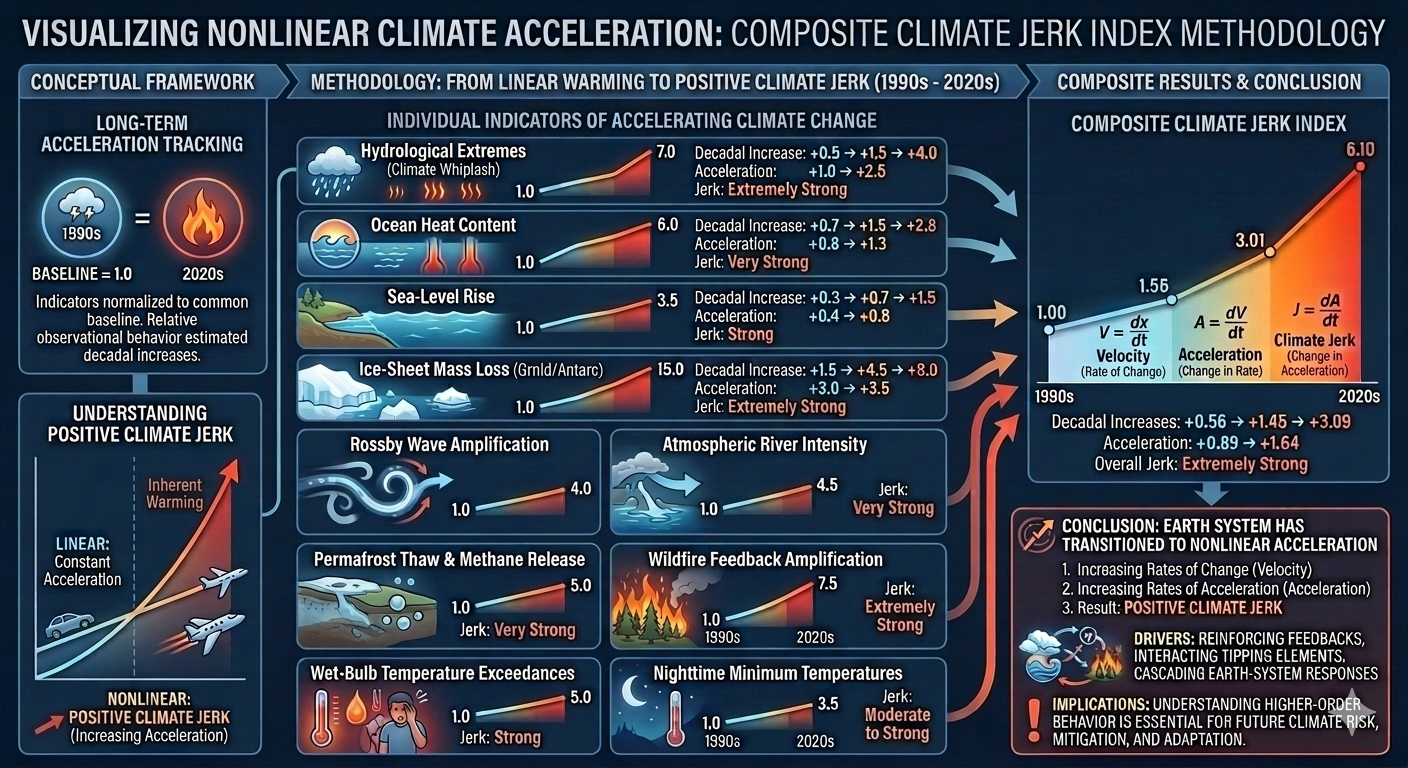
To illustrate long-term changes in climate acceleration, each indicator was normalized to a common baseline:
1990s = 1.0
Relative observational behavior was then estimated for each subsequent decade.
If the decade-to-decade increases become progressively larger, the indicator exhibits positive acceleration.
If the acceleration itself continues increasing over time, this represents positive climate jerk—the rate at which acceleration is increasing.
In physics:
Velocity describes the rate of change.
Acceleration describes the rate at which velocity changes.
Jerk describes the rate at which acceleration changes.
Applied to climate science, positive climate jerk indicates that Earth’s climate is not simply changing faster—it is accelerating faster over time.
1. Hydrological Extremes and Climate Whiplash
Decade
Index
1990s
1.0
2000s
1.5
2010s
3.0
2020s
7.0
Decadal increase: +0.5 → +1.5 → +4.0
Acceleration: +1.0 → +2.5
Climate Jerk:Extremely Strong
2. Ocean Heat Content
Decade
Index
1990s
1.0
2000s
1.7
2010s
3.2
2020s
6.0
Decadal increase: +0.7 → +1.5 → +2.8
Acceleration: +0.8 → +1.3
Climate Jerk:Very Strong
3. Sea-Level Rise
Decade
Index
1990s
1.0
2000s
1.3
2010s
2.0
2020s
3.5
Decadal increase: +0.3 → +0.7 → +1.5
Acceleration: +0.4 → +0.8
Climate Jerk:Strong
4. Ice-Sheet Mass Loss
(Greenland and Antarctica Combined)
Decade
Index
1990s
1.0
2000s
2.5
2010s
7.0
2020s
15.0
Decadal increase: +1.5 → +4.5 → +8.0
Acceleration: +3.0 → +3.5
Climate Jerk:Extremely Strong
5. Rossby Wave Amplification
Decade
Index
1990s
1.0
2000s
1.4
2010s
2.3
2020s
4.0
Climate Jerk:Strong
6. Atmospheric River Intensity
Decade
Index
1990s
1.0
2000s
1.3
2010s
2.2
2020s
4.5
Climate Jerk:Very Strong
7. Permafrost Thaw and Methane Release
Decade
Index
1990s
1.0
2000s
1.4
2010s
2.5
2020s
5.0
Climate Jerk:Very Strong
8. Wildfire Feedback Amplification
Decade
Index
1990s
1.0
2000s
1.5
2010s
3.0
2020s
7.5
Climate Jerk:Extremely Strong
9. Wet-Bulb Temperature Exceedances
Decade
Index
1990s
1.0
2000s
1.6
2010s
2.8
2020s
5.0
Climate Jerk:Strong
10. Nighttime Minimum Temperatures
Decade
Index
1990s
1.0
2000s
1.4
2010s
2.1
2020s
3.5
Climate Jerk:Moderate to Strong
Composite Climate Jerk Index
A simple average of the ten normalized indicators produces the following composite behavior:
Decade
Composite Index
1990s
1.00
2000s
1.56
2010s
3.01
2020s
6.10
Decadal increases
+0.56 → +1.45 → +3.09
Acceleration
+0.89 → +1.64
Conclusion
Viewed collectively, these observational indicators suggest that the Earth’s climate system has undergone a profound transition since the late twentieth century. The evidence indicates not only increasing rates of change, but increasing rates of acceleration—a phenomenon that may be described as positive climate jerk.
This behavior is consistent with a climate system increasingly influenced by reinforcing feedbacks, interacting tipping elements, and cascading Earth-system responses.
Whether evaluated through ice-sheet dynamics, ocean heat uptake, hydrological extremes, atmospheric circulation, wildfire amplification, or permafrost thaw, the emerging pattern is remarkably consistent: the climate system is not merely changing—it is accelerating, and that acceleration itself continues to increase.
Understanding this higher-order behavior may prove essential for accurately assessing future climate risk and for developing mitigation and adaptation strategies that account for the nonlinear dynamics of the Earth system.
An Ensemble-Based Probabilistic Framework for Estimating the Full Economic Burden of Climate Change in the United States
Daniel Brouse and Sidd Mukherjee
Abstract
Traditional estimates of climate damages generally report single-value estimates or narrow ranges that fail to capture the cascading uncertainty inherent in coupled human-natural systems. Climate change is not a single hazard but a network of interacting physical, ecological, epidemiological, economic, and social feedbacks.
This paper proposes an ensemble-based probabilistic accounting framework that estimates the true annual economic burden of climate change in the United States as a distribution rather than a point estimate.
Using 2025 as the baseline year, we define a conservative lower bound of $2.06 trillion annually (approximately $6,050 per American) consisting only of directly attributable and well-quantified damages.
Additional categories—including infectious disease emergence, ecosystem collapse, climate migration, geopolitical instability, financial contagion, biodiversity loss, fossil-fuel subsidies, and other partially attributable systemic risks—are represented probabilistically through an ensemble framework.
Rather than producing one “correct” number, the framework generates prediction intervals describing the likely range of the true climate burden.
1. Introduction
Climate damages are fundamentally nonlinear.
Traditional integrated assessment models generally estimate expected damages using equilibrium assumptions and relatively independent variables.
Real-world climate systems behave differently.
Climate interacts simultaneously with
ecosystems
economics
epidemiology
infrastructure
migration
finance
agriculture
conflict
public health
Each contains reinforcing feedback loops.
The objective is therefore not prediction of a single value but estimation of a probability distribution.
2. The Climate Damage Ensemble
Define total damages as: Dₜₒₜₐₗ = Dₒᵦₛₑᵣᵥₑd + ∑ Dᵢ
Wildfire → Smoke → Respiratory disease → Lost labor → Lower GDP → Reduced adaptation capacity → Greater vulnerability
The ensemble models these interactions through conditional dependence rather than assuming independence.
6. Prediction Intervals
Instead of a single estimate, the framework produces confidence bands.
Illustrative example
Percentile
Annual Cost
5th
$2.06T
25th
$2.7T
Median
~$4T
75th
~$6T
90th
~$8T
95th
~$10T+
These values would ultimately emerge from the Monte Carlo simulation rather than being fixed assumptions.
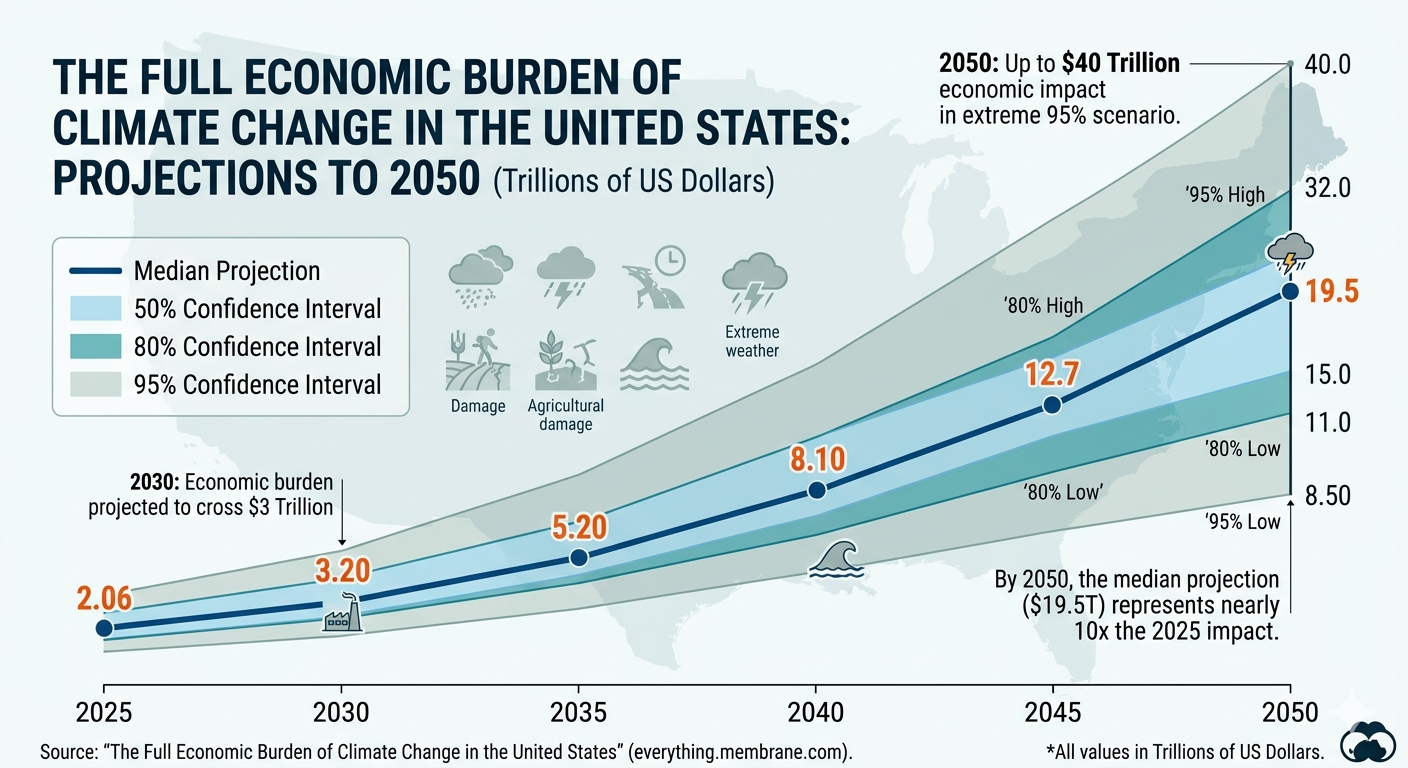
7. Fan Charts
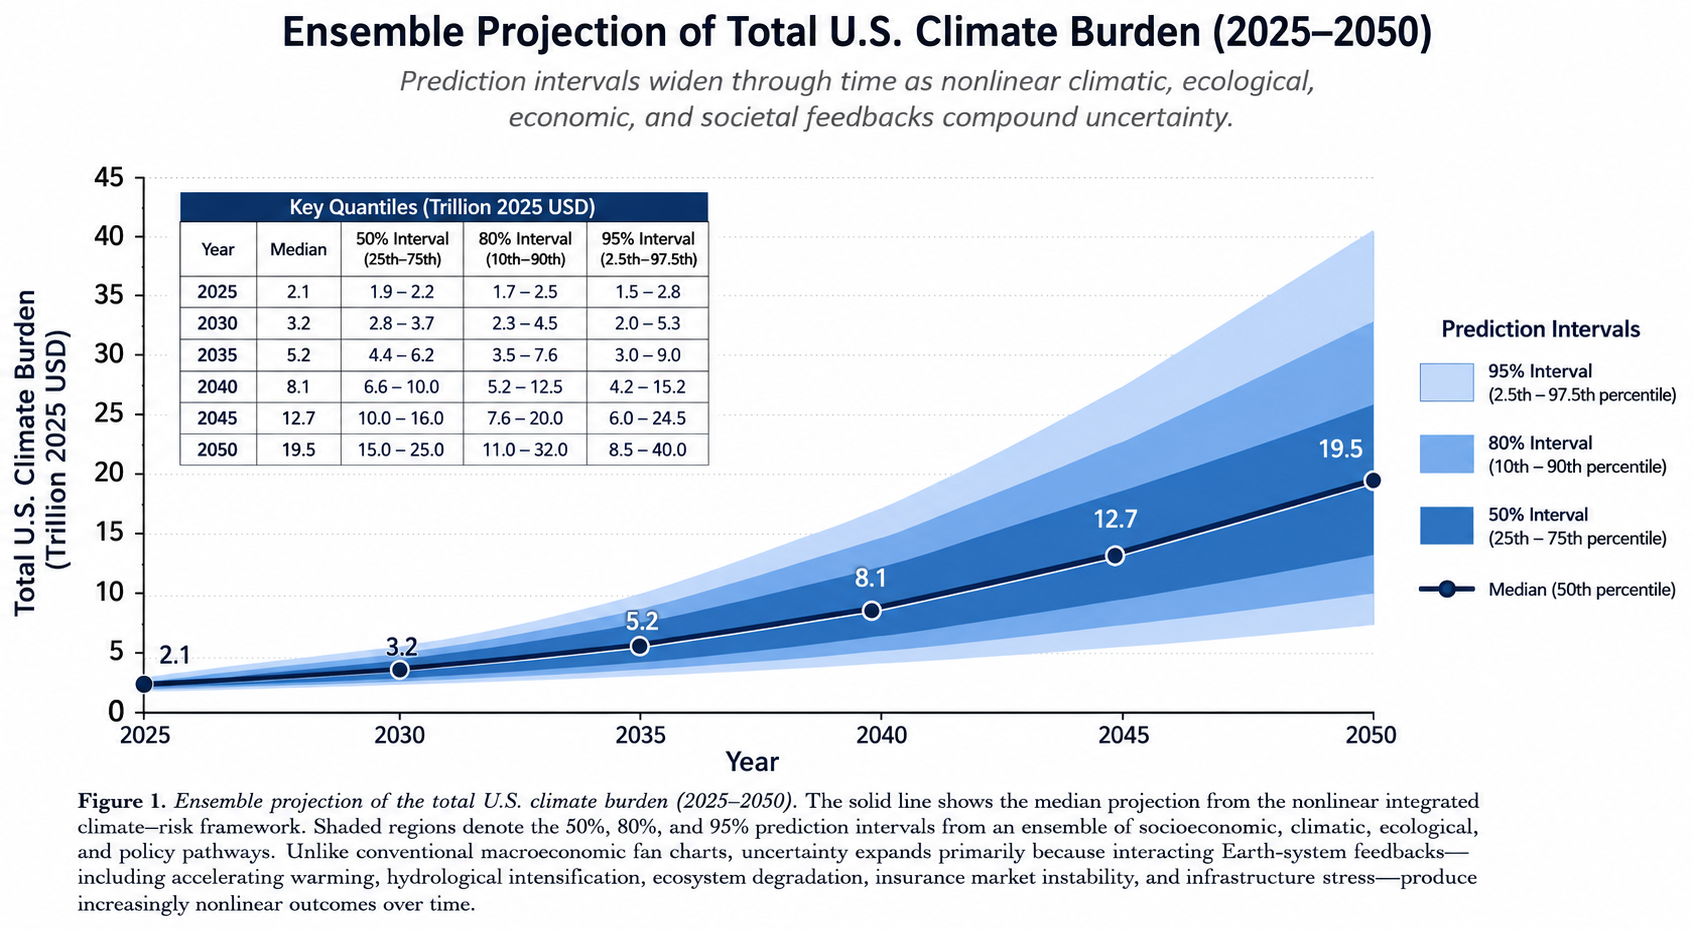
The preferred visualization is not a line graph. Instead, it is to plot 2025 through 2050 with widening prediction bands.
The widening fan reflects increasing uncertainty produced by nonlinear climate feedbacks.
Unlike economic forecasting, these intervals widen primarily because interacting Earth-system feedbacks amplify uncertainty over time.
Year
Median
50% Low
50% High
80% Low
80% High
95% Low
95% High
2025
2.06
1.90
2.20
1.70
2.50
1.50
2.80
2030
3.20
2.80
3.70
2.30
4.50
2.00
5.30
2035
5.20
4.40
6.20
3.50
7.60
3.00
9.00
2040
8.10
6.60
10.00
5.20
12.50
4.20
15.20
2045
12.7
10.0
16.0
7.60
20.0
6.00
24.5
2050
19.5
15.0
25.0
11.0
32.0
8.50
40.0
* In trillions of US dollars.
Figure X. Ensemble projection of the total U.S. climate burden (2025–2050). The solid center line represents the median projection from the nonlinear integrated climate-risk framework. Shaded regions denote the 50%, 80%, and 95% prediction intervals derived from an ensemble of socioeconomic, climatic, ecological, and policy pathways. Unlike conventional macroeconomic fan charts, uncertainty expands primarily because interacting Earth-system feedbacks—including accelerating warming, hydrological intensification, ecosystem degradation, insurance market instability, and infrastructure stress—produce increasingly nonlinear outcomes over time. Consequently, the widening fan reflects structural uncertainty arising from feedback amplification rather than simple forecast error accumulation.
This style closely matches the fan charts used by central banks, but adapts them to nonlinear climate-risk modeling, making it appropriate for a publication on ensemble climate-economic projections.
8. Interpretation
The conservative estimate of $2.06 trillion should not be interpreted as the expected value.
Rather, it is the lower bound supported by presently attributable damages.
The ensemble median is expected to exceed this value substantially as additional climate-sensitive costs become attributable.
Conversely, the upper tail represents systemic risks whose probabilities remain uncertain but whose consequences could dominate future economic losses.
9. Conclusion
Climate damages are not deterministic.
Neither are they adequately represented by point estimates.
A probabilistic ensemble framework better reflects the state of climate science, economics, epidemiology, ecology, and complex systems theory.
Instead of asking
“What does climate change cost?”
the scientifically appropriate question becomes
“What is the probability distribution of the total societal cost once all interacting climate feedbacks are considered?”
This framework shifts climate economics from deterministic bookkeeping toward full systemic risk analysis, consistent with modern catastrophe modeling, insurance science, and Earth-system dynamics.
We develop a probabilistic ensemble framework to estimate the annual economic burden of climate change in the United States.
The approach decomposes total damages into observed, directly attributable components and a set of latent, partially observable,
or structurally uncertain damage channels. These are combined within a stochastic simulation framework to generate a full probability distribution of annual climate damages.
Total damages are defined as:
DTotal = DObs + Σ Di
where DObs represents empirically observed and directly attributable damages, and Di represents uncertain damage channels modeled as stochastic processes.
2. Baseline Observed Damages (2025)
The baseline estimate DObs is constructed from sectorally disaggregated empirical loss data for the United States in 2025.
All included components meet a conservative attribution threshold requiring strong empirical linkage to climate-related hazards.
Table 1. Baseline Observed Damages (2025)
Sector
Damage Category
Estimated Annual Loss (USD)
Data Basis
Extreme events
Hurricanes, floods, droughts, wildfire direct losses
0.78T
NOAA, FEMA loss estimates
Insurance & infrastructure
Uninsured losses, premium escalation, rebuilding
0.32T
Industry loss reports
Health impacts
Heat mortality, air quality, morbidity, productivity loss
0.41T
CDC, EPA burden estimates
Agriculture
Yield losses, supply disruption, input volatility
0.27T
USDA crop loss models
Energy system impacts
Cooling demand, grid stress, peak pricing effects
0.18T
EIA demand elasticity
Macro-financial impacts
GDP losses, capital disruption, adaptation expenditure
0.10T
IMF-style macro damage estimates
Total observed baseline:
DObs = 2.06 trillion USD (2025)
Per capita estimate:
2.06T / 340M ≈ 6,050 USD/person
3. Latent and Partially Attributable Damage Channels
We define a second class of damages Di, representing climate-linked risks that are supported by physical or epidemiological mechanisms but remain incompletely attributable in aggregate economic terms.
Each Di is modeled as a stochastic variable:
Di ~ 𝒟(θi, σi)
4. Infectious Disease and Pandemic Risk Module
Climate change may influence infectious disease dynamics via:
Shifts in vector ecology
Habitat fragmentation
Zoonotic spillover risk
Altered pathogen persistence environments
COVID-19-related impacts are excluded from DObs due to attribution uncertainty but included in ensemble tail-risk modeling.
5. Climate-Sensitive Disease Expansion Model
Following Mora et al. (Nature Climate Change), evidence indicates:
58% of known human pathogenic diseases are climate-sensitive
Disease risk is modeled as:
Dhealth,i = f(Ei, Vi, Ci)
Ei: exposure expansion
Vi: vector suitability change
Ci: climate hazard intensity
6. Fossil Fuel Subsidy Module
Subsidies are excluded from baseline accounting due to definitional heterogeneity.
We define a bounded distribution:
S ~ Triangular(10¹⁰, 10¹¹, 7×10¹¹)
7. Stochastic Ensemble Construction
Total damages are computed using Monte Carlo simulation:
D(k)Total = DObs + Σ Xi(k)
Where k = 1…100,000 simulations.
Distribution types include:
Lognormal (health, infrastructure)
Gamma (agriculture, extreme events)
Pareto (tail risk)
Mixture distributions (financial system risk)
8. Dependence Structure
We impose a dependency structure using a copula-based framework:
DObs represents a lower-bound empirical estimate.
DTotal represents the full probabilistic damage distribution including latent and tail-risk components.
DObs ≤ E[DTotal]
11. Data Sources
NOAA climate disaster loss datasets
FEMA disaster expenditure reports
CDC morbidity and mortality statistics
USDA agricultural loss data
EIA energy demand data
IMF macroeconomic climate damage frameworks
IPCC AR6 assessment reports
12. Limitations
Partial observability of latent damage channels
Structural uncertainty in tail-risk distributions
Simplified correlation structure
Attribution uncertainty in health and ecological modules
Non-stationarity of climate–economy relationships
Results should be interpreted as probabilistic risk estimates rather than point forecasts.
A common criticism of climate damage accounting is that it focuses on the costs of fossil fuels without acknowledging the benefits they have provided to modern civilization. This criticism conflates two distinct concepts: the benefits of energy and the benefits of burning fossil fuels.
This paper does not argue that reliable energy, transportation, heating, cooling, hospitals, agriculture, or modern industry are undesirable. On the contrary, these systems have dramatically improved human welfare, life expectancy, productivity, and economic development. The relevant policy question, however, is not whether society benefits from energy, but whether combusting fossil fuels remains the lowest-cost means of providing that energy once all associated costs are properly accounted for.
The objective of this paper is therefore not to evaluate the value of modern civilization itself, but to quantify the economic damages associated with fossil fuel combustion that are routinely excluded from market prices. These damages include premature mortality, morbidity, infrastructure destruction, agricultural losses, insurance destabilization, ecosystem degradation, climate-driven displacement, productivity losses, and the transfer of costs to future generations.
From an economic perspective, these are externalized costs—costs imposed on society that are not fully reflected in the price of fossil fuels. When these damages are omitted, fossil fuels appear artificially inexpensive. The perception of “cheap energy” therefore depends, in part, on shifting substantial costs onto taxpayers, public health systems, ecosystems, and future generations rather than incorporating them into present-day market transactions.
Accordingly, the appropriate comparison is not between modern civilization and a world without energy. Rather, it is between alternative methods of supplying the energy services upon which modern civilization depends. As cleaner energy technologies become increasingly capable of providing electricity, heating, cooling, transportation, and industrial power, the relevant economic question becomes whether continued reliance on fossil fuel combustion remains socially optimal once its full costs are recognized.
Conservative Scope of the Analysis
The estimates presented in this paper are intentionally conservative. Throughout the analysis, costs were included only when there was sufficient evidence to support reasonably direct attribution to climate change. Where attribution remained uncertain, the associated damages were excluded from the calculations.
For example, climate change may influence the emergence, geographic distribution, and severity of zoonotic diseases and may have interacted with demographic, ecological, and environmental factors during the COVID-19 pandemic. However, because the degree of attribution remains uncertain, none of the health or economic costs associated with COVID-19 were included in the calculations presented in this paper.
This exclusion is substantial. More than 1.23 million deaths in the United States have been officially attributed to COVID-19. In addition, economists estimate that Long COVID imposes an annual economic burden ranging from several billion dollars to well over $200 billion, depending on assumptions regarding healthcare expenditures, workforce participation, disability, and lost productivity. Should future research establish a stronger causal connection between climate change and pandemic emergence, these costs would represent a significant addition to the climate burden estimated in this paper.
COVID-19 is only one example of a broader category of climate-sensitive health risks. A growing body of evidence demonstrates that climate change is altering the ecology of infectious disease transmission. Deforestation, habitat fragmentation, warming temperatures, and changing precipitation patterns increase contact between humans and wildlife while simultaneously expanding the geographic range of disease vectors and pathogens.
As temperatures rise, climate-sensitive vectors such as mosquitoes and ticks are expanding into regions where they previously could not survive year-round, increasing the risk of diseases including dengue fever, malaria, West Nile virus, Lyme disease, chikungunya, and Zika virus. Likewise, environmental disruption increases opportunities for zoonotic spillover events involving pathogens such as Ebola viruses, avian influenza viruses, coronaviruses, and numerous other emerging infectious diseases.
The scale of this problem was comprehensively documented in the landmark study “Over half of known human pathogenic diseases can be aggravated by climate change,” published in Nature Climate Change. Led by Camilo Mora and colleagues at the University of Hawaii at Mānoa, the study systematically reviewed the scientific literature and concluded that 58% of all known human pathogenic diseases have been aggravated by one or more climatic hazards, including warming, flooding, drought, heat waves, storms, sea-level rise, and changes in land cover.
The authors identified more than one thousand distinct pathways through which climatic hazards increase disease transmission, severity, or human exposure. These mechanisms include shifts in wildlife migration, expansion of vector populations into higher latitudes and elevations, increased survival of pathogens during warmer winters, flooding of contaminated water systems, displacement of human populations, and increased interaction between humans, livestock, and wildlife.
The researchers concluded that the diversity and complexity of these transmission pathways make comprehensive adaptation increasingly difficult. As Mora and colleagues observed, the number of diseases affected and the multitude of transmission mechanisms make it unrealistic to expect adaptation alone to eliminate the growing health risks associated with climate change. Consequently, reducing greenhouse gas emissions remains the most effective long-term strategy for limiting climate-driven disease emergence.
For these reasons, the exclusion of pandemic-related costs from the present analysis should not be interpreted as evidence that climate change has no influence on infectious disease. Rather, it reflects a deliberately conservative methodological choice. Until attribution science can quantify these relationships with greater confidence, the associated mortality and economic losses remain outside the scope of this paper. Consequently, the climate burden estimates presented here are more likely to understate than overstate the true long-term societal costs of climate change.
Similarly, this paper excludes government support for fossil fuels in the form of explicit and implicit subsidies. Estimates of annual U.S. fossil fuel subsidies vary widely depending on methodology—from approximately $10 billion in direct fiscal support to several hundred billion dollars annually when unpriced environmental and public health externalities are included. Because no universally accepted accounting framework exists for these subsidies, they were omitted entirely from the reported estimates.
These exclusions are deliberate methodological choices intended to avoid overstating climate damages. Consequently, the estimates presented here should be interpreted as conservative lower-bound estimates of the economic burden imposed by climate change. Incorporating additional categories of attributable damages or broader measures of fossil fuel subsidies would almost certainly increase the estimated societal costs beyond those reported in this paper.
Macro-Welfare Frameworks vs. Economic Justice Valuation in the United States
Daniel Brouse and Sidd Mukherjee
I. Introduction
A. Research Problem
Climate change imposes large and growing costs on the United States, yet there is still no centralized national ledger that captures the full burden in a unified way. Conventional economic indicators—especially GDP, insured losses, and direct disaster tallies—systematically undercount the real cost of climate disruption because they omit or minimize non-market harms such as premature mortality, reduced life expectancy, chronic illness, degraded quality of life, ecological destabilization, and the unequal distribution of climate damages across vulnerable populations.
A narrow GDP-centered framework also fails to capture a second dimension of climate cost: accountability. A large share of today’s climate burden is not simply the product of random weather volatility. It is the cumulative result of delayed mitigation, externalized damages, underpriced emissions, regulatory failure, and in some cases decades of deception regarding the risks of fossil-fuel dependence. That means climate accounting must confront not only what climate change is costing the economy, but also what it should cost under a framework of social justice and deterrence.
B. Thesis Statement
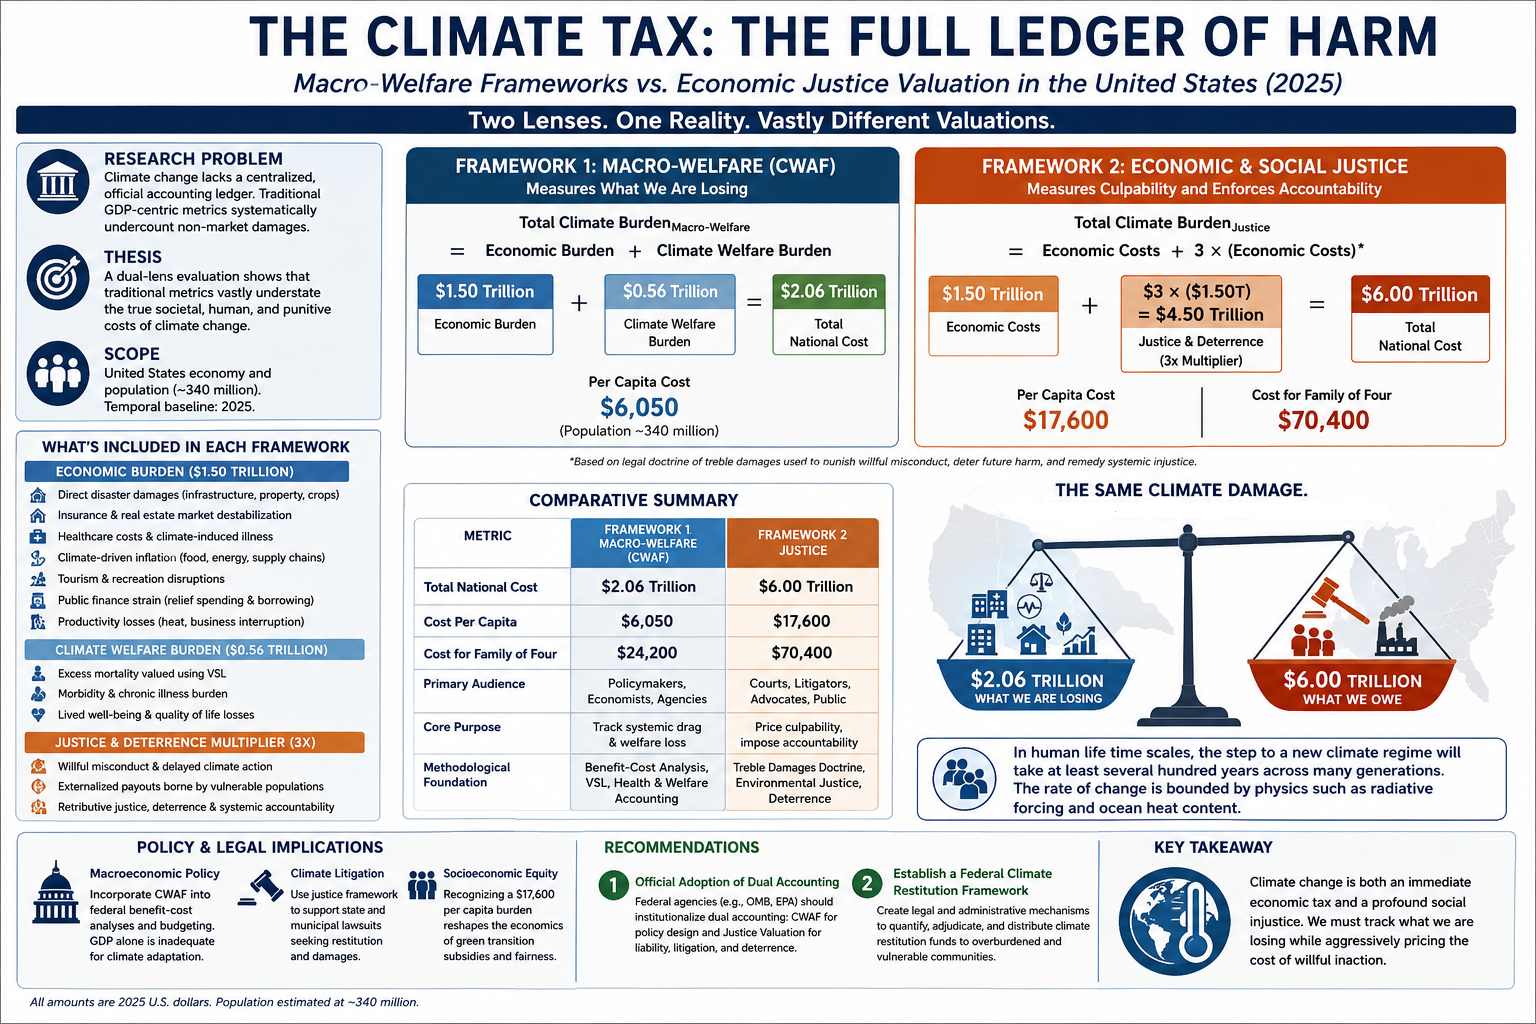
Evaluating the 2025 U.S. cost of climate change requires moving beyond direct disaster losses and beyond GDP-centered accounting. Using a dual-lens approach, it compares:
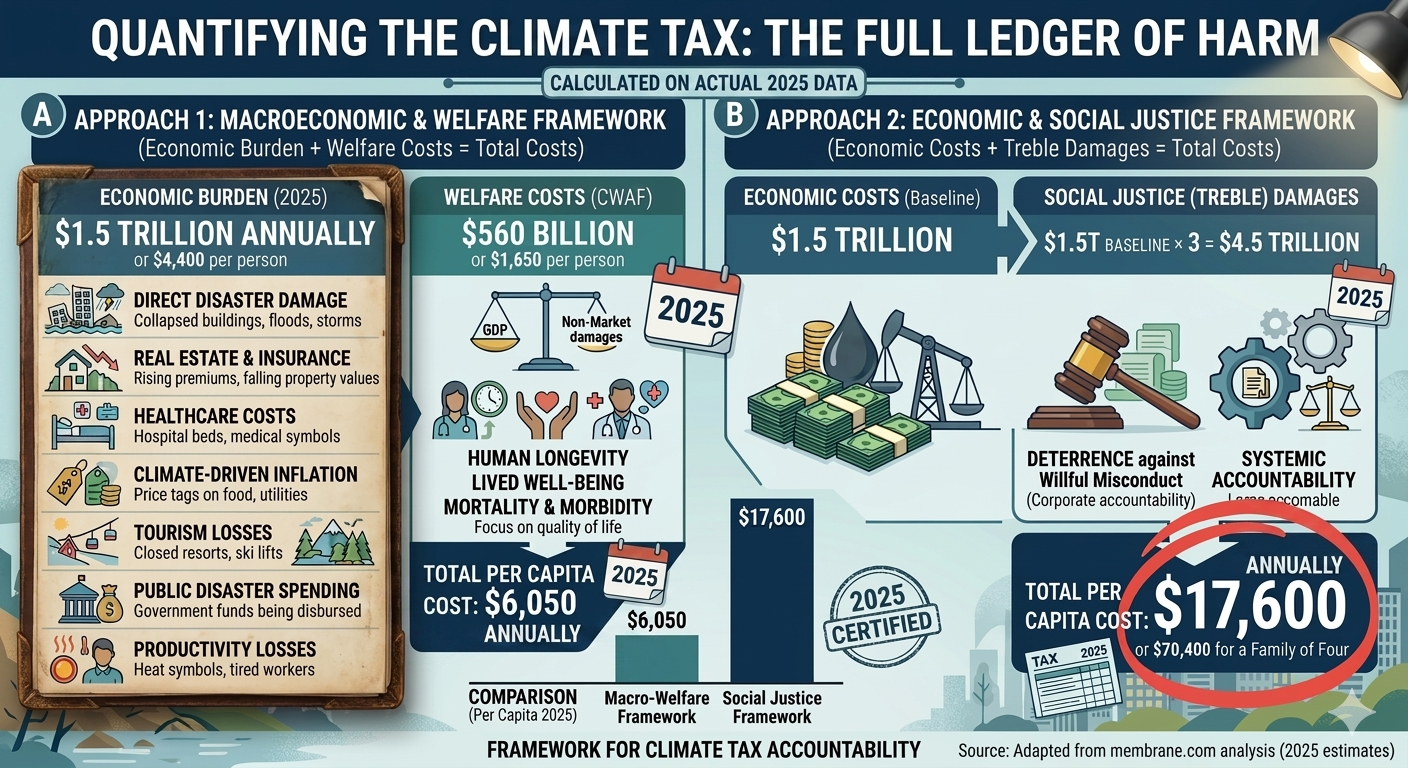
a Macroeconomic and Welfare Framework, which estimates the 2025 U.S. climate burden at approximately $2.06 trillion, or about $6,050 per person, and
an Economic and Social Justice Framework, which applies a treble-damages logic to climate-linked economic harms and yields a 2025 burden of approximately $6.0 trillion, or about $17,600 per person.
The core claim is that traditional economic metrics substantially understate the true societal burden of climate change. Climate damages should be understood not only as macroeconomic drag and welfare erosion, but also as a form of externalized injury with distributive, ethical, and potentially punitive dimensions.
C. Scope of the Study
This study focuses on the United States in calendar year 2025. Per-capita values are based on a U.S. population baseline of approximately 340 million residents. The analysis is national rather than state-specific and is intended as a high-level accounting framework rather than a final litigation damages model.
II. Methodology 1: The Macroeconomic and Welfare Framework
A. Conceptual Architecture
The first framework combines two components:
Economic burden: the direct and indirect market-facing costs imposed by climate change in 2025; and
Climate welfare burden: the non-market human costs associated with mortality, life-expectancy loss, morbidity, and degraded quality of life.
For 2025, the study uses the following central values:
$1.50T + $0.56T = $2.06T
On a per-capita basis:
$2.06T / 340M = $6,059 ≈ $6,050 per person
This can also be expressed as:
$4,400 + $1,650 = $6,050
where:
$4,400 per person is the estimated economic burden, and
$1,650 per person is the estimated climate welfare burden.
B. The Economic Burden Baseline: $1.5 Trillion ($4,400 per Capita)
The economic burden baseline is designed to capture the direct and indirect market-facing cost of climate change in the United States in 2025. It includes seven broad categories of loss.
1. Direct disaster damages
This category includes physical destruction from hurricanes, inland flooding, wildfires, convective storms, drought-related losses, heat-related infrastructure damage, and other extreme-weather events. It covers residential, commercial, public-sector, insured, and uninsured losses.
2. Real estate and insurance destabilization
Climate change is increasingly priced into property markets and insurance markets through higher premiums, policy nonrenewals, shrinking insurability, reserve stress, and geographic repricing of risk. These effects act as a quasi-tax on households, businesses, and municipalities even in years without a single catastrophic event.
3. Healthcare and health-insurance costs
Heat stress, wildfire smoke, respiratory disease, cardiovascular strain, injuries, mental-health burdens, and other climate-related medical effects increase both direct healthcare spending and insurance costs. These costs are counted here only insofar as they represent market expenditures rather than welfare losses already captured separately in the climate welfare framework.
4. Climate-driven inflation and household cost pressure
Climate shocks increase the price of food, electricity, water, transportation, and household essentials through crop disruption, supply-chain interruption, infrastructure stress, and energy-demand spikes. These effects function as a hidden climate tax on households and are treated as part of the economic burden.
5. Tourism and recreation losses
Climate volatility disrupts beach economies, ski industries, lake and river recreation, outdoor events, park visitation, and seasonal tourism revenue. The direct revenue loss belongs in the economic burden, while the lost enjoyment and diminished lived experience belong more naturally in the welfare framework.
6. Public finance and fiscal burden
Federal, state, and local governments increasingly absorb climate costs through disaster relief, infrastructure repair, emergency response, insurance backstops, and climate-related borrowing. These expenditures represent real public resource costs even when financed through debt.
7. Productivity losses
Heat stress, smoke exposure, flooding, power outages, transportation interruption, and business downtime reduce labor productivity and economic output. These losses are among the most undercounted but economically significant climate costs.
Taken together, these categories produce a 2025 U.S. economic burden estimate of approximately $1.5 trillion.
On a per-capita basis:
$1.50T / 340M = $4,412 ≈ $4,400 per person
This figure is intended as an integrated estimate of the market-facing annual climate burden imposed on the United States in 2025.
C. The Climate Welfare Accounting Framework (CWAF): $560 Billion ($1,650 per Capita)
The second component of Framework 1 is the Climate Welfare Accounting Framework (CWAF), which measures the direct erosion of human well-being from climate change. CWAF is designed to capture losses that do not appear clearly in GDP or conventional market accounts, including premature mortality, reduced life expectancy, chronic morbidity, and diminished quality of life.
1. CWAF structure
CWAF is organized around three pillars:
Pillar A: Mortality valuation
Pillar B: Life-expectancy loss
Pillar C: Morbidity and quality-of-life loss
The raw component identity is:
CWAF(raw) = A + B + C
Using the central estimates in this framework:
A = $375B
B = $80B
C = $180B
So the raw component sum is:
$375B + $80B + $180B = $635B
However, because mortality, life-year loss, and morbidity estimates can overlap at the margins even after careful structuring, the framework applies a conservative overlap adjustment and presents a central CWAF estimate of approximately $560 billion rather than the full raw sum of $635 billion.
Thus:
CWAF raw central estimate = $635B
CWAF adjusted central estimate ≈ $560B
On a per-capita basis:
$560B / 340M = $1,647 ≈ $1,650 per person
2. Pillar A: Mortality valuation
Pillar A estimates the welfare cost of climate-attributable premature mortality using the Value of a Statistical Life (VSL) framework used in federal regulatory analysis.
The stylized formula is:
A = D × VSL
where:
D = estimated climate-attributable premature deaths in 2025
VSL = value of a statistical life
Pillar A is treated as a contemporaneous willingness-to-pay valuation of mortality risk, not as a decomposition of life-years. Because Pillar A values mortality using a contemporaneous VSL, discounting is primarily relevant to Pillar B and to any portion of Pillar C that reflects future streams of lost healthy life rather than same-year welfare loss.
3. Pillar B: Life-expectancy loss
Pillar B captures the welfare loss associated with reductions in healthy life expectancy caused by heat exposure, smoke exposure, chronic disease burdens, and other climate-linked pathways that may not appear as immediate mortality events in a single-year accounting frame.
The stylized formula is:
B = Σ(LYᵢ × VSLY)
where:
LYᵢ = climate-attributable life-years lost for group i
VSLY = value of a statistical life-year
Pillar B is constructed as a non-overlapping residual welfare component and is not derived by mechanically decomposing Pillar A’s VSL estimate into life-years. Instead, it captures life-expectancy and health losses not already subsumed within the mortality valuation framework used in Pillar A. Put differently, Pillar A (VSL-based mortality valuation) captures the welfare equivalent of premature mortality as a contemporaneous risk realization, while Pillar B is calibrated to exclude mortality already captured in Pillar A and instead reflects residual life-expectancy and morbidity effects not subsumed by VSL valuation.
4. Pillar C: Morbidity and quality-of-life loss
Pillar C estimates the welfare cost of climate-driven morbidity, including heat-related illness, smoke-related respiratory burdens, mental-health stress, chronic disease aggravation, and other forms of degraded physical and psychological well-being.
The stylized formula is:
C = Σ(Qᵢ × Vᵢ)
where:
Qᵢ = quantity of climate-attributable morbidity burden for condition i
Vᵢ = monetized welfare value associated with that burden
This pillar can be operationalized using QALY, DALY, or related health-welfare valuation methods.
D. Summary of Framework 1
The Macroeconomic and Welfare Framework yields the following 2025 estimate:
$1.50T + $0.56T = $2.06T
Per capita:
$2.06T / 340M = $6,059 ≈ $6,050 per person
For a family of four:
4 × $6,050 = $24,200
Framework 1 therefore estimates that climate change imposed a 2025 macro-welfare burden of roughly $2.06 trillion on the United States, equivalent to about $6,050 per person or $24,200 for a family of four.
III. Methodology 2: The Economic and Social Justice Framework
A. Conceptual Architecture
Framework 2 asks a different question. Instead of measuring only the annual economic and welfare burden of climate change, it asks what the ledger would look like if climate damages were valued through a justice and deterrence lens, analogous to legal doctrines that multiply proven damages in response to willful misconduct, fraud, or socially destructive externalization of harm.
This framework begins with the same $1.5 trillion economic damage baseline used in Framework 1, but applies a treble-damages logic to those economic damages only.
Let:
E = Economic Climate Damages = $1.5T
Then the justice framework is:
Justice Cost = E + 3E = 4E
Substituting the 2025 baseline:
$1.5T + 3($1.5T) = $6.0T
Equivalently:
4 × $1.5T = $6.0T
On a per-capita basis:
$6.0T / 340M = $17,647 ≈ $17,600 per person
For a family of four:
4 × $17,600 = $70,400
Why the treble multiplier is applied only to the $1.5T economic burden
The treble-damages multiplier is applied only to the market-facing economic damage ledger ($1.5T), not to the CWAF welfare component ($560B). This choice is intentional. The justice framework is designed as a liability-style multiplier on economic damages—that is, on direct and indirect market harms such as property destruction, insurance destabilization, healthcare spending, public fiscal outlays, productivity loss, and climate-driven price pressures. By contrast, the CWAF already monetizes non-market welfare harms such as mortality risk, life-expectancy degradation, and morbidity-related quality-of-life loss. Trebling those welfare values would risk both conceptual double counting and an analytically awkward punitive replication of already-imputed welfare losses. Accordingly, Framework 2 should be understood as a justice-weighted escalation of the economic climate ledger, not as a trebling of the entire macro-welfare burden.
This framework is therefore not presented as a conventional welfare-economics estimate. It is a normative legal-economic framework designed to reflect accountability, deterrence, and the uneven distribution of climate harm.
B. The Legal Foundation of Treble Damages
Treble damages are a long-established feature of U.S. law in contexts where ordinary compensation is considered inadequate to deter or punish egregious misconduct. They appear most prominently in:
Antitrust law, including the Sherman Act
Civil racketeering actions, including RICO-based claims
False Claims Act enforcement, where fraud against the public fisc can trigger multiplied damages
The logic of treble damages is not merely compensatory. It is also punitive and deterrent. Trebling recognizes that some harms are imposed through conduct sufficiently reckless, deceptive, or socially damaging that ordinary compensation fails to capture either the full social cost or the need for institutional deterrence.
C. Application to Climate Justice
The justice framework applies this legal logic to climate damages on the theory that a substantial share of modern climate costs reflects not only physical climate change, but also delayed mitigation, historic externalization of damages, and sustained campaigns of misinformation or obstruction that prolonged fossil-fuel dependence and delayed adaptation.
Three considerations motivate the treble-damages approach:
1. Willful misconduct and delayed action
If major emitters or institutions knowingly delayed action while externalizing foreseeable climate harms onto the public, then a purely compensatory accounting of damages may understate the true social cost of that conduct.
2. Unequal distribution of harm
Climate damages are not evenly distributed. Lower-income households, communities of color, medically vulnerable populations, outdoor workers, and disaster-prone regions often bear disproportionate burdens. A justice framework therefore recognizes that climate losses are not merely aggregate economic losses but also distributional injuries.
3. Deterrence and accountability
A damages framework that merely reimburses a fraction of direct losses may fail to deter future misconduct. A justice-oriented framework treats climate damages as the basis for a larger accountability regime aimed at shifting incentives, strengthening disclosure, and pricing the cost of willful inaction.
IV. Comparative Analysis
A. Aggregate Results
The two frameworks produce sharply different valuations of the 2025 U.S. climate burden.
Metric
Framework 1: Macro-Welfare
Framework 2: Justice
Economic burden baseline
$1.50 trillion
$1.50 trillion
Welfare burden (CWAF)
$0.56 trillion
—
Treble-damages penalty on economic burden
—
$4.50 trillion
Total national cost
$2.06 trillion
$6.00 trillion
Cost per capita
$6,050
$17,600
Cost for family of four
$24,200
$70,400
Framework 1 estimates the full annual burden of climate change on the economy and on human welfare. Framework 2 estimates the justice-weighted accountability cost of climate harm if society chose to treat delayed mitigation and externalized damages as punishable economic injury.
B. Analytical Differences Between the Frameworks
1. Audience and institutional use
Framework 1 is primarily relevant to:
fiscal policy analysts
macroeconomists
central banks
public-health planners
federal agencies conducting benefit-cost analysis
Framework 2 is more relevant to:
litigators
state attorneys general
municipal plaintiffs
tort scholars
climate-justice advocates
2. Philosophical foundation
Framework 1 measures systemic drag, welfare erosion, and hidden social cost. It asks: What is climate change costing the country in real economic and human terms right now?
Framework 2 measures culpability, deterrence, and social restitution. It asks: What would climate damages look like if society priced not only the injury itself, but also the institutional misconduct that helped produce and intensify it?
3. Risk allocation
Framework 1 reveals the extent to which climate change already functions as a hidden national tax on households, businesses, and governments. Framework 2 goes further by reallocating that burden conceptually back toward those who knowingly profited while imposing climate costs on others.
V. Policy, Legal, and Economic Implications
A. Macroeconomic Policy
The first implication is that GDP alone is no longer an adequate climate accounting tool. A country can rebuild after a flood, spend more on medical care, or borrow more for disaster relief, and those expenditures may still appear as positive economic activity in national accounts even as the underlying social condition worsens.
Incorporating macro-welfare climate accounting into federal analysis would improve:
Office of Management and Budget benefit-cost analysis
federal adaptation planning
public-health prioritization
insurance and housing policy
long-run fiscal projections
A climate burden of roughly $2.06 trillion in 2025, or about $6,050 per person, implies that climate change already functions as a material macroeconomic drag on the United States.
B. Climate Litigation and Tort Reform
The second implication is legal. The justice framework provides a conceptual bridge between aggregate climate economics and climate liability. If climate damages are increasingly litigated through state, municipal, and public-nuisance actions, a framework that translates economic harm into a deterrence-oriented damages structure may become increasingly relevant.
This does not mean courts should automatically adopt a 3x multiplier in climate litigation. Rather, it suggests that climate damages can be conceptualized not merely as diffuse acts of nature, but as partly socialized harms linked to historic patterns of concealment, delay, and cost externalization.
C. Socioeconomic Equity
A third implication concerns equity. If the annual climate burden is framed as $17,600 per person under a justice-based model, the economics of adaptation, resilience spending, green infrastructure, household subsidies, and climate restitution look very different. The scale of the burden implies that aggressive decarbonization and resilience investment may be economically justified not merely as environmental policy, but as partial relief from a large and regressive climate tax.
VI. Limitations
Several limitations should be acknowledged.
A. Framework 1 limitations
The macro-welfare framework is a synthetic accounting model rather than a single-source official estimate. Its economic burden baseline aggregates multiple categories of loss that are themselves subject to uncertainty, overlap, and incomplete attribution. The CWAF component similarly relies on bounded welfare estimates rather than a single fully observed national health ledger.
B. Framework 2 limitations
The justice framework is explicitly normative. It is not a standard welfare-economic estimate and should not be confused with a measured national-income loss. Its treble-damages logic is best understood as a legal-economic thought experiment grounded in deterrence and accountability rather than as a conventional national-accounts statistic.
C. Attribution limitations
Not every harmful event in 2025 can be cleanly attributed to climate change, and climate-health pathways remain unevenly measured across disease categories, geographies, and populations. As with all climate-damages accounting, results depend partly on attribution choices, valuation assumptions, and the treatment of overlap among categories.
VII. Conclusion
A. Restatement of Main Findings
This study develops a dual accounting of the 2025 U.S. climate burden.
Under the Macroeconomic and Welfare Framework, climate change imposed an estimated burden of:
$1.50T + $0.56T = $2.06T
equivalent to roughly:
$2.06T / 340M = $6,059 ≈ $6,050 per person
or:
4 × $6,050 = $24,200 for a family of four
Under the Economic and Social Justice Framework, applying a treble-damages logic to the $1.5 trillion economic burden yields:
$1.5T + 3($1.5T) = $6.0T
equivalent to roughly:
$6.0T / 340M = $17,647 ≈ $17,600 per person
or:
4 × $17,600 = $70,400 for a family of four
B. Final Synthesis
Climate change now functions in the United States as both an immediate economic tax and a profound social injustice. The first framework measures what the country is losing in output, health, welfare, and resilience. The second asks what those losses would look like if climate harm were treated not merely as misfortune, but as a large-scale social injury intensified by delayed action, externalized damages, and institutional failure.
The gap between $2.06 trillion and $6.0 trillion is therefore not a contradiction. It reflects two different but complementary questions:
What is climate change costing the United States right now?
What should climate damages cost if accountability and deterrence are taken seriously?
C. Future Research Directions
Future work should extend this framework in at least four directions:
State-level and metropolitan climate-tax estimates, especially for high-risk regions facing acute insurance, flood, heat, or wildfire stress
Sector-specific justice multipliers, particularly for fossil-fuel litigation and public-finance exposure
Improved climate-health attribution models, especially for smoke exposure, heat mortality, chronic disease aggravation, and infectious disease pathways
Dynamic multi-year climate ledgers that track the compounding interaction of direct disaster losses, welfare erosion, and legal liability over time
Appendix A. Summary Tables
A1. Framework 1: Macro-Welfare Burden
Component
Aggregate Cost
Per Capita
Economic burden baseline
$1.50 trillion
$4,400
Climate Welfare Accounting Framework (CWAF)
$0.56 trillion
$1,650
Total Framework 1 burden
$2.06 trillion
$6,050
A2. CWAF Raw Component Structure
CWAF Pillar
Low
Central
High
Mortality cost
$225B
$375B
$562.5B
Life expectancy loss cost
$40B
$80B
$140B
Morbidity / quality-of-life cost
$100B
$180B
$280B
Total welfare cost (raw component sum)
$365B
$635B
$982.5B
Note: The raw central sum of $635B is conservatively adjusted downward in the CWAF headline estimate to approximately $560B to account for overlap risk across mortality, life-year loss, and morbidity channels.
U.S. Environmental Protection Agency. (2010). Guidelines for Preparing Economic Analyses. National Center for Environmental Economics, U.S. EPA, Washington, DC. Available at: EPA Guidelines for Preparing Economic Analyses
Social cost of carbon, climate damages, and climate-economy valuation
Interagency Working Group on the Social Cost of Greenhouse Gases, United States Government. (2021). Technical Support Document: Social Cost of Carbon, Methane, and Nitrous Oxide Interim Estimates under Executive Order 13990. Washington, DC. Available at: Interagency Working Group Technical Support Document
Rennert, K., Errickson, F., Prest, B. C., Rennels, L., Newell, R. G., Pizer, W., Kingdon, C., Wingenroth, J., Cooke, R., Parthum, B., Smith, D., Cromar, K., Diaz, D., Moore, F. C., Müller, U. K., Mendelsohn, R., Anthoff, D., Rose, S., & Waldhoff, S. (2022). “Comprehensive evidence implies a higher social cost of CO₂.” Nature, 610, 687–692.
Carleton, T. A., Jina, A., Delgado, M. T., Greenstone, M., Houser, T., Hsiang, S., Hultgren, A., Jisu, K., McCusker, K., Nath, I., Rising, J., Rode, A., Seo, H. K., Viaene, A., Yuan, J., & Zhang, A. T. (2022). “Valuing the global mortality consequences of climate change accounting for adaptation costs and benefits.” The Quarterly Journal of Economics, 137(4), 2037–2105.
U.S. climate impacts, health burden, and national assessment context
U.S. Global Change Research Program. (2023). Fifth National Climate Assessment. Washington, DC: U.S. Global Change Research Program. Available at: https://nca2023.globalchange.gov/
Romanello, M., Di Napoli, C., Green, C., Kennard, H., Lampard, P., Scamman, D., Walawender, M., Ali, Z., et al. (2024). “The 2024 report of the Lancet Countdown on health and climate change: facing record-breaking threats from delayed action.” The Lancet. (Use the final journal citation details/DOI exactly as published in the version you relied on.)
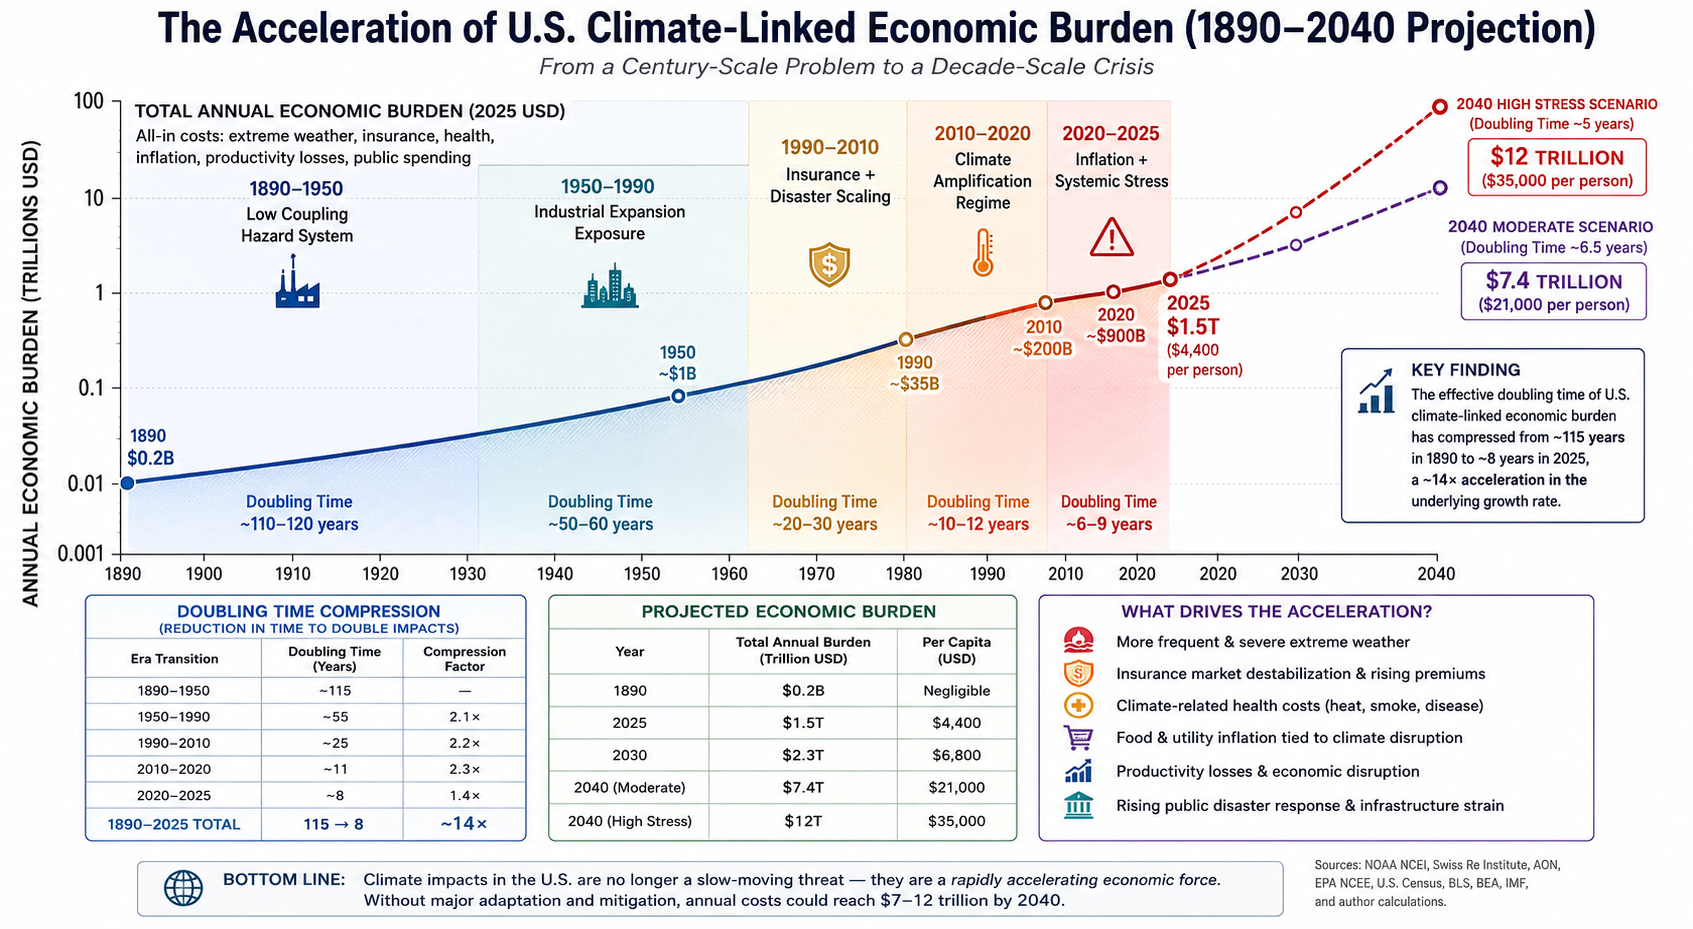
This paper estimates the long-run evolution of U.S. climate-related economic burdens and finds strong evidence of nonlinear acceleration. Using a reconstructed baseline in the late 19th century and an integrated 2025 estimate of approximately $1.5 trillion annually in climate-attributable economic losses, we estimate that the effective doubling time of climate-related economic burden has compressed from ~115 years (circa 1890) to ~8 years in the present regime. We project forward under continued compression dynamics to 2030 and 2040, showing that costs may enter multi-trillion-dollar annual regimes within the next two decades if current nonlinear amplification persists.
1. Economic Burden Definition
The total climate-linked economic burden is defined as:
Climate-linked economic burden in the United States exhibits a nonlinear acceleration regime characterized by a ~14× compression in doubling times since 1890, shifting from century-scale dynamics to decade-scale systemic amplification.
10. Conclusion
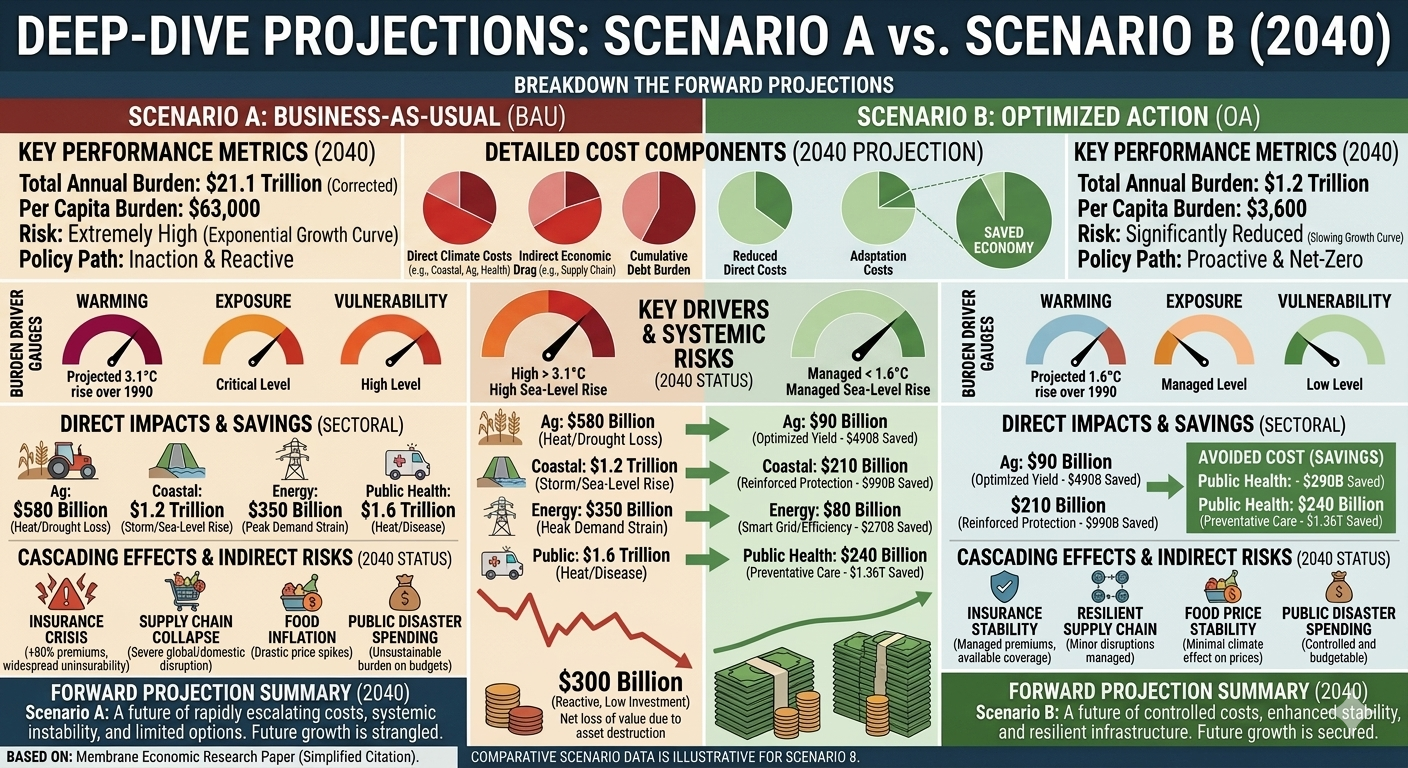
The United States climate-linked economic burden has transitioned from a low-coupling hazard system in the late 19th century to a highly nonlinear, inflation-amplified economic stress system in the 21st century. Using a 2025 estimate of $1.5 trillion annually, we find that doubling times have compressed from ~115 years to ~8 years, implying a ~14× acceleration in the growth rate of climate-attributable damages. Under continued compression, annual burdens may reach $7–12 trillion by 2040.
Estimating the Per-Person Economic Burden of Extreme Weather, Insurance Destabilization, Climate Inflation, and Health Impacts
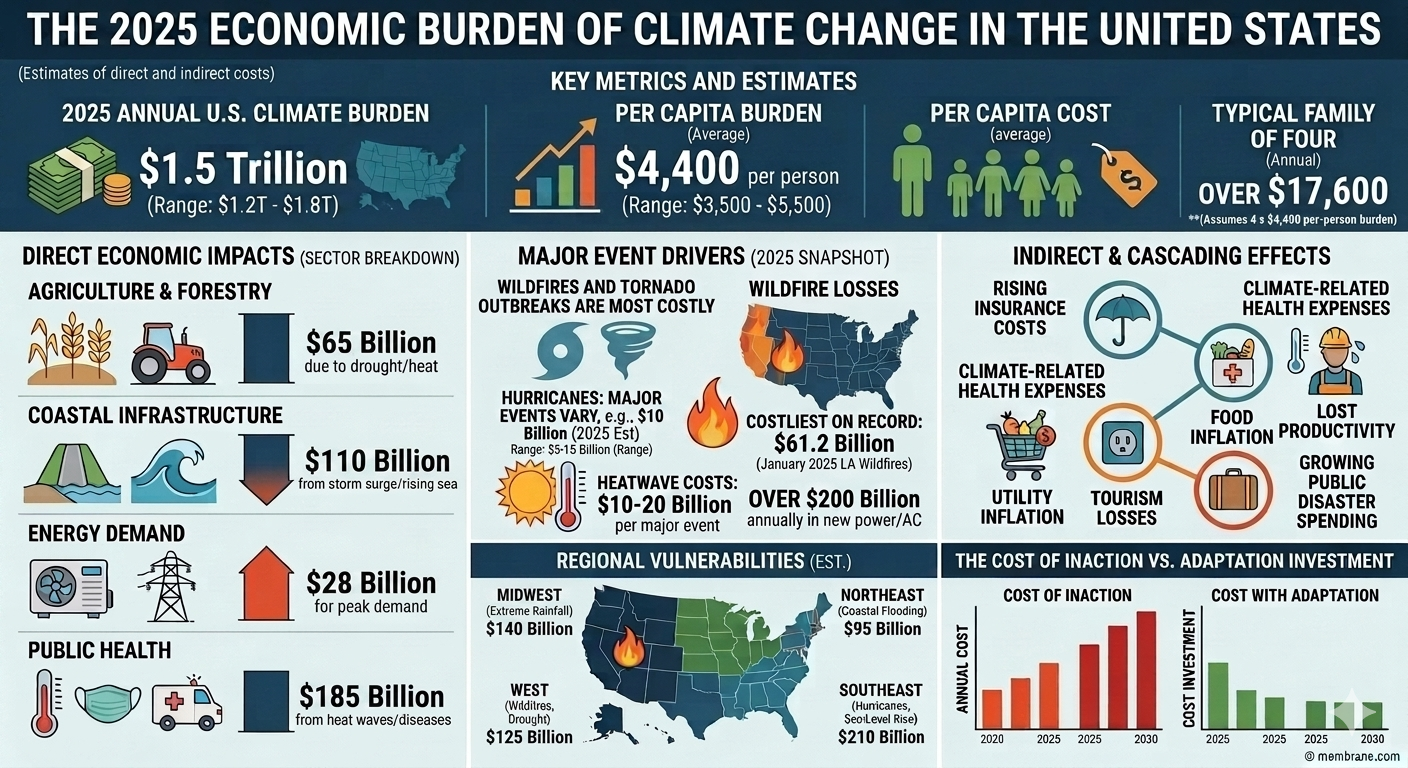
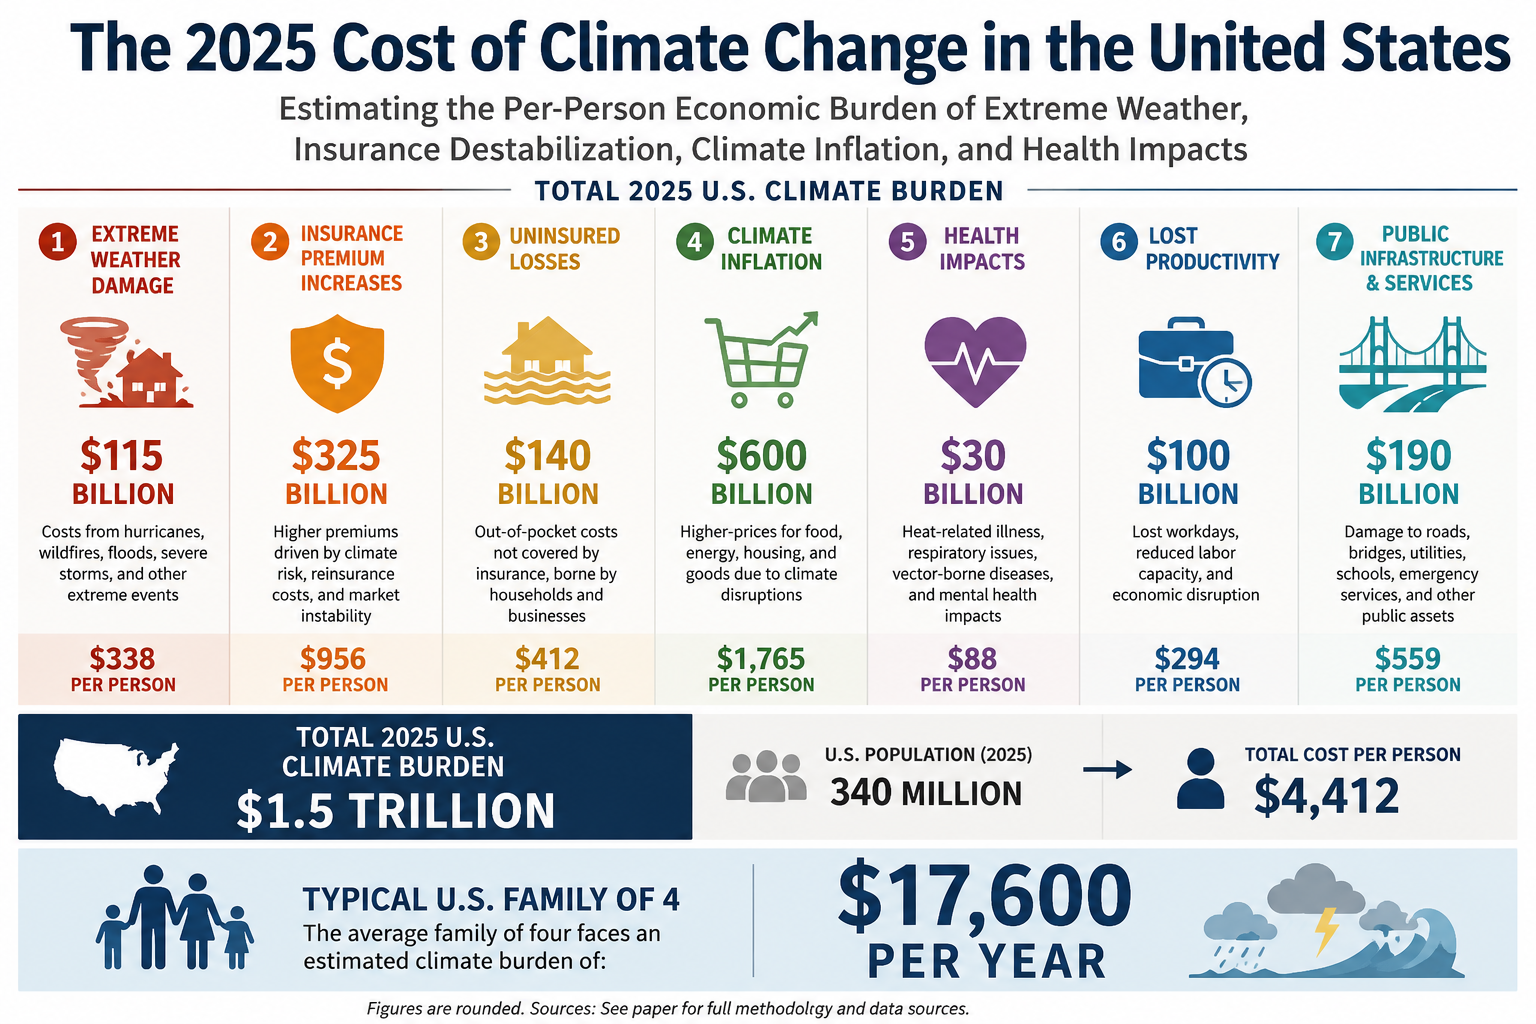
A reasonable all-in estimate for the 2025 economic burden of climate change on the United States is about $1.5 trillion, or roughly $4,400 per person. For a family of four, the implied annual burden is roughly $17,600.That burden extends far beyond direct disaster losses and includes rising insurance costs, climate-related health expenses, food and utility inflation, lost productivity, tourism losses, and growing public disaster spending.
By Daniel Brouse and Sidd Mukherjee
Abstract
Climate change in the United States is no longer best understood solely as an environmental problem or a tally of disaster losses. It has become a broad economic burden imposed on households, businesses, insurers, healthcare systems, and governments through multiple overlapping channels. In 2025, this burden extended far beyond direct storm, wildfire, flood, and heat damage. It also appeared in rising property-insurance costs, housing-market instability, climate-driven health expenses, higher utility bills, food inflation, tourism losses, public disaster spending, and reduced labor productivity.
This paper presents a bottom-up estimate of the all-in 2025 economic cost of climate change in the United States, with the goal of approximating the average cost per person when both direct and indirect burdens are considered. Because no official ledger exists for “total climate costs,” the analysis aggregates seven major categories of climate-related economic burden: (1) direct disaster damages, (2) property insurance and real-estate destabilization, (3) healthcare and health-insurance costs, (4) climate-driven inflation in food, utilities, and supply chains, (5) tourism and recreation losses, (6) government expenditures and public borrowing strain, and (7) productivity losses and business interruption.
Using a U.S. population of approximately 340 million, the paper estimates a 2025 climate burden of roughly $1.5 trillion, with a plausible range of $1.2 trillion to $1.8 trillion. On a per-person basis, this implies an average cost of approximately $4,400 per American in 2025, with a conservative range of $3,500 to $5,500 per person. For a family of four, the implied annual burden is roughly $17,600.
The core conclusion is that climate change now functions as a diffuse but powerful economic tax on American life. It raises insurance premiums, erodes home values, inflates electricity and food costs, worsens public-health burdens, strains local and federal budgets, and lowers productivity. Even when households are not directly hit by a flood, wildfire, or hurricane, they increasingly pay for climate change through the price system, the insurance system, the healthcare system, and the tax system. Climate change in the United States is therefore not just a future risk; it is already a major annual cost center embedded in the daily economy.
1. Introduction
Public discussion of climate change in the United States often focuses on dramatic physical events: hurricanes, floods, wildfires, heatwaves, droughts, and billion-dollar disasters. While those events are important, they capture only part of the actual economic burden climate change now imposes. The larger story is that climate disruption has begun to function as a system-wide cost escalator. It increases insurance premiums, weakens housing markets, strains public infrastructure, raises electricity demand, amplifies health expenses, disrupts supply chains, and inflates food prices. In short, climate change is no longer merely a source of episodic disaster losses. It is increasingly a permanent drag on household finances and national economic stability.
This distinction matters because the official accounting of climate damages remains incomplete. Annual disaster-loss tallies typically capture only direct physical damage: insured losses, destroyed structures, infrastructure repair, and some immediate business interruption. They generally do not capture the full downstream cost of heat-related illness, wildfire smoke exposure, insurance market retreat, declining property values in flood-prone communities, higher grocery bills caused by weather-related crop disruption, or the fiscal burden of repeated emergency appropriations. The result is that climate change is often underestimated as an economic force because the damage is fragmented across categories that are normally tracked separately.
The goal of this paper is to estimate the average cost per person in the United States due to climate change in 2025, including both direct and indirect costs. Rather than looking only at disaster damages, the paper uses a broader economic framework that includes the channels through which climate risk is already transmitted into everyday life. These channels include property insurance and housing destabilization, healthcare costs, health-insurance pressure, climate-driven inflation, lost tourism revenue, public fiscal strain, and lost productivity.
The premise is simple: if climate change is now affecting the economy through multiple systems at once, then measuring its burden requires more than adding up burned homes and flooded roads. It requires asking how much climate disruption is already embedded in the bills Americans pay, the risks they insure, the taxes they fund, the wages they lose, and the wealth they fail to preserve.
This paper estimates that the total 2025 climate burden on the United States was approximately $1.5 trillion, or roughly $4,400 per person. That estimate is necessarily approximate, because some categories—especially climate-related inflation and property-value impairment—cannot be measured with perfect precision. But even under conservative assumptions, the results point in the same direction: climate change is already costing the average American several thousand dollars per year, whether or not they realize it.
2. Methodology: A Bottom-Up Estimate of the 2025 Climate Burden
There is no single official database that reports the “total cost of climate change” for a given year in the United States. Any attempt to estimate that figure must therefore combine multiple categories of loss and cost transmission. The central methodological challenge is to build a broad estimate without double-counting the same damage in multiple places.
To address that, this paper separates climate costs into seven major categories and treats each as an incremental climate-attributable burden rather than as a total category expenditure. The categories are:
Direct disaster damages
Property insurance and real-estate destabilization
Healthcare and health-insurance costs
Climate-driven inflation in food, utilities, and supply chains
Tourism and recreation losses
Government expenditures and fiscal strain
Productivity losses and business interruption
The logic is not that all food inflation, all insurance inflation, or all healthcare spending is caused by climate change. Rather, the question is: what share of these burdens in 2025 can plausibly be attributed to climate disruption? The estimate therefore focuses on the incremental climate component of each category.
Using a U.S. population of 340 million, the paper translates each category’s national cost into a per-person burden. The final total is presented as a range, with a central estimate used for the headline figure.
3. Direct Disaster Damages: The Visible but Incomplete Baseline
The most visible component of climate cost is direct disaster damage: destroyed homes, burned neighborhoods, damaged roads, downed power lines, emergency response costs, and insured losses from floods, storms, wildfires, and other extreme events. These costs are widely reported because they are dramatic, immediate, and often insurable.
For 2025, a reasonable national baseline for direct disaster damages is approximately $115 billion. This reflects the year’s major climate-related disasters, including catastrophic wildfires, severe storms, flooding, and other billion-dollar events. That total is useful because it anchors the analysis in a concrete measure of visible physical damage.
But direct disaster losses are only the beginning of the story. They do not include most health impacts from wildfire smoke and extreme heat, much of the uninsured or underinsured damage absorbed by households, long-term property-value erosion in high-risk areas, or the broad inflationary effects of weather disruption on food and energy. Disaster losses therefore function here as a baseline floor, not a complete accounting of climate cost.
Using a population of 340 million, $115 billion in direct losses translates to roughly:
($115 billion) / (340 million) ≈ $338 per person
That figure is significant, but it is also misleadingly small if treated as the total climate burden. The rest of the paper shows why.
4. Property Insurance and Real-Estate Destabilization
4.1 Insurance premiums as climate transmission mechanisms
One of the clearest ways climate change now enters household budgets is through the property insurance market. As wildfire risk, hurricane losses, inland flooding, and severe convective storms intensify, insurers have raised premiums sharply, tightened underwriting standards, reduced coverage, or exited some markets entirely. These changes are not merely administrative adjustments. They are a direct financial transmission of climate risk into household cash flow.
By 2025, homeowners across the United States were already facing significantly higher insurance costs than they paid only a few years earlier. National average homeowners insurance premiums had risen sharply since 2021, outpacing wage growth and standard inflation. In high-risk states, the increases were much more severe. This means climate change is no longer just a future threat to homeownership. It is already a monthly budget issue.
To estimate the climate-driven premium burden, this paper assumes that a substantial portion of recent premium growth reflects climate-related risk repricing. With approximately 86 million owner-occupied households in the United States, even a few hundred dollars of annual climate-attributable premium increase per household produces tens of billions of dollars in national burden.
A rough estimate of the incremental 2025 climate-driven homeowners insurance burden is approximately $47 billion.
4.2 The “protection gap” and uninsured losses
Premium increases are only part of the cost. The larger and more dangerous issue is the protection gap: the widening difference between total physical losses and the portion actually covered by insurance. As climate disasters intensify, insurers increasingly protect themselves by raising deductibles, limiting coverage, or leaving risky markets altogether. The losses do not disappear. They are simply transferred to homeowners, renters, local governments, state residual insurance pools, and federal taxpayers.
This means a major disaster can impose large economic costs even when insurance coverage appears to exist on paper. Deductibles, exclusions, underinsurance, and uninsured property losses all create direct household financial stress. Local governments may also absorb part of the burden through emergency repairs, temporary housing, and infrastructure response.
For 2025, this paper estimates the protection gap and related uninsured burden at roughly $100 billion to $180 billion.
4.3 Property value impairment and housing-market destabilization
Climate change also erodes housing wealth through a slower mechanism: property repricing. Homes exposed to repeated flooding, wildfire smoke, chronic coastal inundation, or rapidly rising insurance costs become harder to insure, harder to finance, and harder to sell. Even if a home is not destroyed, the expected future cost of owning it can rise enough to depress its market value.
This effect matters because American household wealth is deeply tied to home equity. When climate risk begins to reduce resale value or increase carrying costs, the result is not merely a “real-estate issue.” It becomes a balance-sheet problem for households and a tax-base problem for municipalities.
Because these losses are diffuse and difficult to observe in real time, they are often excluded from climate accounting. Yet they are economically real. This paper conservatively assigns $100 billion to $170 billion in 2025 property-value impairment and housing-market friction costs attributable to climate exposure.
4.4 Total property and housing burden
Combining premium increases, protection-gap losses, and property-market destabilization, the total 2025 property insurance and real-estate climate burden is estimated at:
$250 billion to $400 billion
On a per-person basis, that implies:
($250 billion) / (340 million) ≈ $735 per person
to
($400 billion) / (340 million) ≈ $1,176 per person
This is one of the largest and most direct climate burdens already visible in the household economy.
5. Healthcare and Health Insurance Costs
Extreme weather does not stop at property damage. It also leaves a major financial footprint in the healthcare system. Climate-related health burdens include emergency-room visits during heatwaves, hospitalizations from smoke exposure, respiratory and cardiovascular stress during wildfire events, injuries during storms and floods, mental-health impacts from displacement and repeated disaster exposure, and rising claims associated with climate-sensitive disease patterns.
Extreme heat is especially important because it is already one of the deadliest weather-related hazards in the United States. It contributes to dehydration, kidney stress, cardiovascular strain, respiratory distress, pregnancy complications, and dangerous workplace conditions. Wildfire smoke adds another layer of harm by exposing millions of people to fine particulates and toxic compounds that can worsen asthma, heart disease, and lung injury.
These health burdens create costs through several channels:
direct medical treatment,
increased emergency-room utilization,
public-health response,
higher health-insurance claims,
employer healthcare costs,
lost workdays and reduced labor capacity.
The financial burden of these impacts is not fully visible in standard disaster-loss reporting because many of the costs are absorbed later through hospitals, insurers, employers, Medicare, Medicaid, and household medical bills. In effect, climate change raises healthcare costs not only by causing acute disasters, but by amplifying the baseline disease and treatment burden associated with heat and air pollution.
This paper estimates the incremental 2025 climate-related health and health-insurance burden at approximately:
$100 billion to $180 billion
Per person, that implies roughly:
$294 to $529 per person
A central estimate of $140 billion is reasonable for 2025, particularly given the scale of smoke exposure, heat stress, and extreme-weather-related healthcare disruptions.
6. Climateflation: Food, Utilities, and Supply-Chain Costs
6.1 Climate change as a hidden tax on household consumption
One of the most important and least appreciated channels of climate cost is inflation. Climate change increasingly acts as a hidden tax on everyday life by raising the cost of food, electricity, logistics, and consumer goods. This is not because climate change explains all inflation. It does not. But it does increase price pressure through several pathways:
drought and flood damage to crops,
livestock heat stress,
water shortages,
higher cooling demand,
power-grid strain,
storm-related transport disruption,
warehouse and refrigeration costs,
spoilage and inventory loss,
interruptions to rail, trucking, and river transport.
These pressures feed into the price system even for households that never experience a direct disaster. Climate change therefore affects family budgets not just through insurance or emergency repairs, but through recurring monthly bills for groceries, utilities, and goods whose supply chains are increasingly exposed to weather disruption.
6.2 Utility cost increases from heat
Persistent summer heatwaves raise electricity demand as homes, offices, warehouses, and hospitals rely more heavily on air conditioning. Utilities must manage higher peak demand, more stressed transmission systems, and sometimes reduced efficiency of generation and delivery infrastructure during extreme heat. These costs are passed on through higher rates, fuel adjustments, and capacity charges.
A reasonable estimate for the 2025 climate-attributable utility burden is $60 billion to $100 billion.
6.3 Food inflation and agricultural volatility
Food prices are especially vulnerable to climate disruption. Droughts, floods, heatwaves, and shifting seasonal conditions affect crop yields, planting schedules, water availability, livestock productivity, storage costs, and transport reliability. When these disruptions occur across multiple regions or commodity groups, the effect compounds. The result is not just one bad harvest, but persistent volatility across the food system.
This paper conservatively estimates that $250 billion to $350 billion of the 2025 consumer food-price burden can be attributed to climate-related agricultural and supply-chain disruption.
6.4 Supply-chain and logistics pass-through
Climate disruption also raises costs through business interruption, transportation delays, warehouse cooling expenses, spoilage, shipping rerouting, and inventory risk. These are eventually passed on to consumers and businesses across the economy.
For 2025, this paper assigns $180 billion to $250 billion to the broader supply-chain and logistics burden associated with climate disruption.
6.5 Total climateflation burden
Combining utilities, food inflation, and logistics pass-through, the total 2025 climateflation burden is estimated at:
$500 billion to $700 billion
Per person, that equals roughly:
$1,470 to $2,059 per person
This makes climateflation the single largest category in the 2025 climate burden estimate.
7. Tourism and Recreation Losses
Climate change also imposes substantial costs on local and regional economies that depend on tourism and outdoor recreation. Extreme heat, wildfire smoke, coastal flooding, beach erosion, poor snow conditions, storm damage, and unpredictable seasonal patterns all reduce tourism demand and disrupt recreation-dependent businesses.
Examples include:
park closures due to wildfire or heat,
canceled outdoor festivals and events,
lower visitation to smoke-affected regions,
shortened or erratic ski seasons,
damage to coastal tourism infrastructure,
lost restaurant, hotel, and service-sector revenue in climate-affected destinations.
These losses may seem secondary compared with insurance or health costs, but in many regions they are economically important. A canceled tourism season can mean lost wages, reduced sales-tax revenue, weakened hotel occupancy, and stress on small businesses already operating with narrow margins.
For 2025, this paper estimates the climate-related tourism and recreation burden at:
$20 billion to $40 billion
Per person, that is approximately:
$59 to $118 per person
8. Government Expenditures and Fiscal Strain
Taxpayers also bear a major share of the climate burden through public spending and public finance. Disaster relief, emergency housing, infrastructure repair, wildfire suppression, flood control, insurance backstops, and local recovery grants all require funding. These costs may be spread across federal, state, and local budgets, but they are ultimately part of the economic burden climate change imposes on the public.
In addition to direct spending, climate risk can increase the cost of borrowing for local governments. Municipal bond investors and credit-rating agencies increasingly evaluate physical climate vulnerability when assessing long-term fiscal risk. Communities facing repeated flooding, wildfire exposure, or insurance-market stress may face higher borrowing costs for roads, water systems, schools, and other routine infrastructure.
The public climate burden therefore has two components:
direct fiscal spending on response, repair, and recovery, and
higher structural financing costs for climate-exposed jurisdictions.
This paper estimates the 2025 public-sector climate burden at:
$80 billion to $120 billion
Per person, that equals roughly:
$235 to $353 per person
9. Productivity Losses and Business Interruption
A final major category is the cost of lost work, reduced productivity, and interrupted business activity. Extreme heat reduces labor output, especially in construction, agriculture, warehousing, delivery, transportation, and other outdoor or non-climate-controlled sectors. Wildfires and smoke events can shut down worksites and keep customers home. Floods and storms interrupt logistics, force evacuations, close schools, and disrupt childcare arrangements that allow people to work.
These losses matter because they spread climate costs through the labor market even when no major asset is destroyed. A family may lose income because a parent misses work during a flood recovery or because a heatwave reduces available hours. A small business may lose revenue because smoke or road closures keep customers away. A local economy may lose millions in output because transport links or utility systems fail during extreme weather.
This paper estimates the 2025 productivity and business-interruption burden at:
$120 billion to $220 billion
Per person, that equals approximately:
$353 to $647 per person
10. Summary Table: The 2025 Climate Burden in the United States
Category
Estimated 2025 U.S. climate cost
Per person
Direct disaster damages
$115 billion
$338
Property insurance + real-estate destabilization
$250–$400 billion
$735–$1,176
Healthcare + health insurance
$100–$180 billion
$294–$529
Climateflation (food, utilities, supply chains)
$500–$700 billion
$1,470–$2,059
Tourism + recreation losses
$20–$40 billion
$59–$118
Government expenditures + fiscal strain
$80–$120 billion
$235–$353
Productivity losses + business interruption
$120–$220 billion
$353–$647
11. Central Estimate
Using the midpoint of each category yields the following 2025 estimate:
This implies a total 2025 U.S. climate burden of approximately $1.5 trillion.
Dividing by a U.S. population of 340 million:
$1.5 trillion ÷ 340 million ≈ $4,412 per person
Rounded to the nearest hundred dollars:
Average 2025 climate cost per person in the United States: approximately $4,400
A reasonable conservative range is $3,500 to $5,500 per person.
For a family of four, that implies a total annual burden of approximately:
4 × $4,400 = $17,600
12. Discussion: Climate Change as an Economic Tax on American Life
The most important implication of this analysis is that climate change is already functioning as a diffuse economic tax on American life. It is not merely a matter of future risk or isolated disaster recovery. It now affects the economy through the insurance system, the housing system, the healthcare system, the utility system, the food system, and the tax system.
Most Americans will not experience the climate burden as a single line item. They will experience it as a set of pressures that appear unrelated at first glance:
a higher homeowners insurance premium,
a larger health-insurance renewal,
an unusually high summer electric bill,
more expensive groceries,
rising local taxes for infrastructure repair,
difficulty selling a flood-prone property,
missed work after a smoke event or flood,
a vacation canceled by heat, fire, or storm damage.
Taken separately, these costs may seem manageable or even invisible. Taken together, they form a substantial and growing transfer of wealth away from households and toward damage control, adaptation, emergency response, and loss absorption.
The burden also falls unevenly. Households in coastal areas, wildfire corridors, heat-prone cities, drought-exposed agricultural regions, and flood-prone inland communities often bear a much larger share than the national average. Lower-income households are especially vulnerable because they have less capacity to absorb rising insurance costs, medical bills, evacuation expenses, or repeated utility shocks. In that sense, climate change is not only an environmental stressor and an economic stressor. It is also a force that can widen inequality by imposing the heaviest burden on those with the thinnest financial buffers.
13. Conclusion
This paper estimates that the 2025 cost of climate change in the United States was approximately $1.5 trillion, equal to roughly $4,400 per person or $17,600 for a family of four. A conservative range of $3,500 to $5,500 per person captures the uncertainty in the estimate while still underscoring the scale of the burden.
The key point is not the false precision of any single number. It is the recognition that climate change now imposes a broad, recurring, and deeply embedded economic burden on the United States. Direct disaster damages remain important, but they are only one part of the story. The larger burden increasingly arrives through rising insurance costs, real-estate destabilization, health expenses, climate-driven inflation, tourism losses, public fiscal strain, and lost productivity.
In other words, climate change is no longer simply something Americans pay for after a disaster. It is something they are already paying for every month—through their premiums, utility bills, grocery receipts, taxes, healthcare costs, and weakened property values. The economic question is no longer whether climate change is expensive. It is how much of the American cost of living is now being quietly shaped by it.
Sources List
1. U.S. Billion-Dollar Disaster Data (Core Economic Loss Foundation)
5. Macroeconomic & Integrated Climate Damage Literature
Kopits, E. et al. (2025). Economic Impacts of Climate Change in the United States: Integrating and Harmonizing Evidence from Recent Studies. https://arxiv.org/abs/2509.00212
Extreme Heat, Coastal Flooding, and the Cascading Threat to Economic Stability and Human Health
By Daniel Brouse and Sidd Mukherjee
Abstract
The greatest overall climate risk to the United States is not a single hazard in isolation, but the cascading interaction of extreme heat, coastal flooding, infrastructure fragility, rising property losses, and financial destabilization. In a warming climate, these threats do not remain neatly compartmentalized. Extreme heat raises mortality, strains electric grids, and reduces labor productivity. Coastal flooding and sea-level rise erode housing markets, damage infrastructure, and increase displacement. Together, they place growing pressure on insurers, lenders, public budgets, and household finances. The result is a systemic threat in which physical climate hazards increasingly translate into economic instability and human health crises.
This paper argues that intensifying heatwaves and coastal flooding now represent the most consequential climate threats to the United States because they operate simultaneously as public-health emergencies, infrastructure stressors, and financial shock multipliers. Extreme heat is already the deadliest weather hazard in the United States, and climate projections indicate a sharp increase in heat-related illness and mortality in coming decades. At the same time, rising sea levels and stronger coastal storms threaten trillions of dollars in real estate, infrastructure, and municipal tax bases. These physical impacts are already spilling into financial systems through rising insurance costs, insurer withdrawals, mortgage risk, and increasing federal disaster expenditures.
The paper also addresses the practical financial implications of these risks for households. Because climate risk is increasingly transmitted through housing, insurance, utility disruptions, and emergency expenses, household resilience now requires a more explicit form of climate-aware financial planning. We outline a basic defense strategy centered on auditing property exposure, strengthening insurance coverage, and scaling emergency cash reserves. The central conclusion is that climate change in the United States should no longer be viewed only as an environmental issue. It is now a converging health, infrastructure, housing, and financial stability problem.
1. Introduction
For much of the public, climate change is still imagined as a distant environmental problem: warmer summers, stronger hurricanes, rising seas, and occasional natural disasters whose costs are counted after the fact. That framing is now obsolete. The most serious climate threat to the United States is no longer simply the direct damage from individual weather events. It is the cascading destabilization that occurs when extreme weather repeatedly disrupts health systems, energy systems, housing markets, insurance markets, and household finances all at once.
Two hazards sit at the center of this risk landscape: extreme heat and coastal flooding. Extreme heat is already the leading weather-related killer in the United States, and its burden is projected to rise sharply as warming intensifies. Heat does not merely kill directly through heat stroke. It worsens cardiovascular disease, kidney stress, respiratory illness, pregnancy risks, and worker safety. It also undermines the infrastructure needed to survive it by straining the electric grid during periods of peak air-conditioning demand. Coastal flooding, meanwhile, threatens one of the most valuable concentrations of wealth in the United States: coastal housing, infrastructure, ports, roads, tourism assets, and tax bases. Rising seas and stronger storm surges mean that what was once episodic flood risk increasingly becomes chronic flood exposure.
These hazards matter not only because of their physical effects, but because of the systems they strike. A prolonged heatwave in a heavily urbanized region can simultaneously increase mortality, overload hospitals, raise power demand, buckle transportation infrastructure, and cause localized blackouts. A coastal flood can destroy homes, shut down roads and water systems, disrupt local businesses, reduce municipal revenue, and trigger insurance disputes and mortgage distress. When these events occur repeatedly—or overlap with each other and with other climate extremes—the result is no longer a simple disaster-recovery cycle. It becomes a broader form of economic and social destabilization.
The United States is especially vulnerable to this dynamic because so much of its wealth is embedded in climate-exposed property and infrastructure. Coastal counties contain a large share of the nation’s population, real estate value, and critical infrastructure. Urban areas increasingly face dangerous heat amplified by concrete, asphalt, weak tree cover, and aging electrical systems. Insurance markets in some states are already showing signs of strain, with rising premiums, shrinking availability, and growing dependence on state-backed residual markets. Federal disaster budgets, meanwhile, are being asked to absorb ever-larger losses.
This paper argues that the greatest overall U.S. climate risk is the combined threat to human health and economic stability from extreme heat and coastal flooding. These hazards are not isolated sectors of concern. They are multipliers that can destabilize the systems people rely on most: power, housing, insurance, transportation, healthcare, and household liquidity. In that sense, climate change is no longer just a matter of environmental risk. It is increasingly a question of whether the country’s infrastructure, financial architecture, and public-health systems can withstand repeated high-cost disruption.
2. The Core Threat: Extreme Heat as a National Health and Infrastructure Emergency
2.1 Extreme heat is already the deadliest weather hazard in the United States
Extreme heat receives less dramatic media coverage than hurricanes or wildfires, yet it is already the most lethal weather-related hazard in the country. Unlike tornadoes or floods, heat deaths are often dispersed, medically complex, and undercounted. People die not only from acute heat stroke, but from heart attacks, kidney failure, respiratory stress, dehydration, and complications in already vulnerable populations. Older adults, outdoor workers, children, low-income households without reliable cooling, and people with chronic illness face disproportionate risk.
This is what makes heat uniquely dangerous: it is both invisible and systemic. It penetrates homes, workplaces, schools, nursing facilities, and city streets. It accumulates over multiple days and nights, especially in urban areas where nighttime cooling is weak. It is also one of the few climate hazards that can simultaneously affect large portions of the country at once, rather than striking a single state or coast.
Climate projections suggest that heat-related mortality will rise sharply in the United States by mid-century, with tens of thousands of additional deaths annually under higher warming scenarios. Even where direct mortality is avoided, heat drives hospitalizations, lost labor productivity, school disruption, agricultural stress, and higher household energy bills. It is a public-health burden and an economic burden at the same time.
2.2 Heat undermines the infrastructure needed to survive it
Extreme heat is especially dangerous because it attacks the very systems needed for protection. The most obvious example is the electric grid. During heatwaves, electricity demand surges as millions of homes and businesses depend on air conditioning. At the same time, high temperatures reduce the efficiency of power generation and transmission equipment. Transformers, substations, rail lines, roads, and even airport operations can be degraded by sustained heat.
This creates a cruel feedback loop. The hotter it gets, the more society depends on electricity to stay alive; but the hotter it gets, the more stressed the electric system becomes. A major blackout during a prolonged heat event is not simply an inconvenience. It is a mass public-health emergency. Air conditioning fails, refrigeration for medicine and food is lost, water pumping and wastewater systems may be disrupted, hospitals face backup power strain, and vulnerable residents can deteriorate quickly.
Heat also affects labor systems and productivity. Construction workers, delivery drivers, agricultural workers, warehouse employees, and utility crews face rising risk of heat exhaustion and heat stroke. Productivity falls as temperatures climb, while workplace injuries and medical complications increase. In that sense, heat is not just a health hazard. It is a slow-moving productivity shock that ripples through local economies.
3. Coastal Flooding and Sea-Level Rise: The Slow-Motion Destruction of Property and Place
3.1 Coastal real estate is one of the largest climate-exposed asset classes in the United States
The United States has concentrated enormous wealth along its coasts. Homes, condominiums, commercial districts, highways, airports, ports, sewage systems, tourist economies, and municipal tax bases are heavily clustered in areas vulnerable to sea-level rise, storm surge, tidal flooding, and rainfall-driven compound flood events. That means coastal flooding is not merely a localized nuisance or a problem for beachfront mansions. It is a threat to some of the most economically valuable land in the country.
The risk is no longer confined to dramatic hurricane landfalls. Sea-level rise is turning what used to be rare coastal flooding into a chronic and escalating exposure problem. High-tide flooding, saltwater intrusion, groundwater rise, repeated stormwater backups, and more destructive storm surge baselines all undermine property values and raise long-term maintenance costs. The problem is especially severe because most households and local governments are not structured to handle property that remains habitable in the short term but becomes steadily more expensive, harder to insure, and harder to resell over time.
This is why the climate threat to coastal property is not just a disaster story; it is a balance-sheet story. The value of a home, a municipal tax base, or a commercial corridor depends on confidence that it can remain insurable, financeable, and functional. Once that confidence weakens, climate risk begins to migrate from the shoreline into the banking system, insurance system, and local public finances.
3.2 Trillion-dollar property losses are no longer a theoretical concern
Rising sea levels and intensifying coastal storms put trillions of dollars of U.S. real estate and infrastructure at risk over the coming decades. In some locations, the risk is catastrophic destruction during major storms. In others, the danger is more gradual but no less severe: chronic flooding, repeated repair costs, mold and structural damage, sewage intrusion, declining buyer demand, and insurance withdrawal.
The distinction matters because financial markets often respond to chronic risk differently than they respond to sudden catastrophe. A house destroyed by a storm produces an immediate insurance claim and a visible loss. A house that floods twice in ten years, faces rising premiums, and becomes harder to sell may never produce a headline, but it can still erode household wealth and neighborhood stability. At scale, that is how climate risk migrates into the broader economy—through falling asset quality, rising borrowing costs, and the slow repricing of exposed property.
Coastal communities also face a fiscal trap. If flood risk depresses property values or drives insurer retreat, municipal revenues can weaken at the same moment infrastructure costs are rising. Roads need to be elevated, drainage improved, seawalls maintained, pumps installed, and emergency services expanded. This combination—shrinking revenue and rising adaptation cost—is one of the most dangerous long-term climate dynamics for local governments.
4. From Weather Disaster to Systemic Financial Stress
4.1 Insurance markets are becoming climate stress sensors
One of the clearest signs that climate risk is moving from the environmental domain into the financial domain is the behavior of insurance markets. In several high-risk states, insurers have raised premiums sharply, restricted coverage, or exited markets entirely. This is not because insurers have suddenly become ideological actors; it is because repeated losses are forcing a repricing of risk that many households and political systems are unprepared to accept.
When insurers withdraw, the effects extend far beyond annual premium bills. Mortgage lenders typically require adequate insurance coverage. Homebuyers may find that a property is technically available for sale but financially inaccessible because the cost of insuring it has exploded. Existing homeowners can see their monthly carrying costs jump sharply, not because their mortgage changed, but because insurance and deductibles did. State-backed insurers of last resort become overloaded. Public pressure rises for subsidies, bailouts, or post-disaster aid.
In other words, the insurance market becomes a climate risk transmission channel. It translates future climate expectations into present-day household costs and housing-market constraints. It also serves as a rough early-warning system: when insurers retreat, they are effectively signaling that the probability distribution of loss is becoming too unstable for normal private pricing.
4.2 Housing markets and public budgets are increasingly exposed
The housing market is especially vulnerable because American household wealth is heavily tied to home equity. If climate risk begins to materially affect insurability, resale value, or mortgage availability, the result is not simply a property problem. It becomes a household balance-sheet problem. A family may own what looks like a valuable home on paper, yet face rising insurance costs, growing flood exposure, and a shrinking pool of future buyers.
Federal and state budgets are also under strain. Disaster relief, rebuilding grants, subsidized insurance backstops, emergency response, and infrastructure repair all impose rising fiscal burdens. As climate losses mount, governments face a difficult political choice: either allow households and localities to absorb increasingly unaffordable risk, or socialize more of the losses through public spending. Neither path is fiscally comfortable.
The United States therefore faces a climate-finance paradox. The places most exposed to flooding, heat, and storm losses often remain economically attractive in the near term, which encourages continued development. But that development increases the amount of value sitting in harm’s way, which makes the eventual repricing of risk even more destabilizing.
5. Infrastructure Collapse as the Bridge Between Physical Hazard and Economic Damage
Climate risk becomes economically explosive when it disables infrastructure. Heat and flooding are especially dangerous because they strike systems that every other system depends on.
The electric grid is a prime example. Extreme heat drives up electricity demand precisely when power systems are under the greatest strain. Flooding can damage substations, fuel supply chains, underground cables, and backup systems. Water and wastewater networks are vulnerable to both drought and flood: pipes can buckle in extreme heat, treatment systems can be overwhelmed by stormwater, and power failures can disable pumping systems. Transportation networks are similarly exposed. Roads, bridges, rail corridors, tunnels, airports, and ports all face climate-related stress from heat, flooding, storm surge, or sea-level rise.
When infrastructure fails, the losses multiply. A flood is no longer just a flooded street; it becomes a supply-chain disruption, a hospital access problem, a workplace disruption, a food refrigeration problem, a school closure, and a business interruption event. A heatwave is no longer just hot weather; it becomes a power emergency, a health emergency, and a labor productivity shock. This is why the real climate risk is not adequately measured by insured losses alone. The deeper risk lies in system interdependence—the fact that one climate shock can trigger failures across multiple sectors at once.
6. The Human Health Consequences of Economic Disruption
Climate damages are often separated into “economic” and “human” categories, but in practice those categories are deeply entangled. Economic disruption is itself a health threat.
A household that loses power during a heatwave faces immediate medical risk if an elderly resident depends on cooling, refrigerated medicine, or electrically powered medical equipment. A family displaced by flooding may face respiratory illness from mold, mental-health stress, medication disruption, and job instability. Communities with repeated disasters often see rising anxiety, depression, substance abuse, and long-term health deterioration. Hospitals themselves are vulnerable to flooding, heat stress, and power outages, meaning the healthcare system can be compromised precisely when demand is surging.
The financial side of disruption also matters. Medical vulnerability is magnified when households cannot afford deductibles, temporary lodging, car repairs, evacuation costs, or missed work. A climate shock that drains savings or forces high-interest borrowing can create months or years of downstream health stress. In this sense, climate change does not simply injure people directly. It erodes the economic buffers that protect health.
That is why extreme heat and coastal flooding are such powerful national threats. They do not merely cause damage; they degrade the systems that households rely on to survive damage.
7. Household Financial Defense in a Climate-Disrupted Economy
If climate change increasingly manifests through housing risk, insurance strain, utility disruption, and emergency expenses, then climate resilience must include household financial planning. This is not a substitute for public policy or emissions reduction. It is a practical recognition that families are already being forced to absorb part of the climate risk transfer.
7.1 Audit property exposure before you buy—or before you assume you are safe
One of the most important financial decisions a household can make is where it lives. In a climate-disrupted economy, that means evaluating not just school districts, commute times, and tax rates, but environmental risk. Traditional flood-zone maps are no longer enough, especially in areas facing heavier rainfall, shifting flood patterns, sea-level rise, or wildfire expansion.
Households should assess the specific risk profile of any property they own or intend to buy, including flood, heat, fire, and storm vulnerability over the likely ownership period. A home that appears “safe” under outdated flood mapping may still face a meaningful probability of repeated damage over a 30-year mortgage horizon. Climate risk is increasingly a property-level due diligence issue.
A simple example illustrates the stakes. A $400,000 home outside a traditional FEMA flood zone may still face a substantial chance of flooding over a 30-year mortgage because rainfall intensity and drainage conditions have changed. Discovering that before purchase is not academic—it may be the difference between building wealth and buying into a recurring liability.
7.2 Bulletproof insurance coverage rather than assuming your homeowners policy will save you
Many households discover only after a flood that standard homeowners insurance does not cover rising water from the ground up. Wind, sewer backup, wildfire deductibles, and replacement-cost gaps can also create ugly surprises. Climate resilience therefore requires active insurance management, not passive renewal.
Households in flood-prone or increasingly flood-prone areas should evaluate separate flood coverage through the National Flood Insurance Program or private carriers. Policies should be reviewed annually, especially after renovations, changes in local risk, or major storms. Deductibles matter as much as premiums. A policy that technically covers an event but leaves the homeowner exposed to a large deductible can still produce severe financial stress.
A modest annual premium may look expensive until compared with the cost of even a few inches of floodwater in a finished home. In that sense, insurance is not merely a regulatory requirement or a bureaucratic nuisance. It is a key layer of household climate defense.
7.3 Scale emergency reserves to climate reality
Traditional financial advice often recommends three months of living expenses in emergency savings. That may be inadequate in a climate-disrupted environment, particularly for households exposed to storm risk, wildfire risk, repeated power outages, or income disruptions tied to extreme weather.
Climate shocks generate costs that are immediate and awkwardly timed: hotel stays, evacuation fuel, food spoilage, tree removal, temporary generators, insurance deductibles, vehicle damage, childcare disruptions, and unpaid time off work. These are precisely the kinds of expenses that push households onto high-interest credit card debt if cash reserves are thin.
For families in climate-vulnerable regions—or with jobs tied to exposed industries—a stronger target may be six to nine months of liquid reserves. The point is not to hoard cash irrationally. It is to maintain enough liquidity to absorb a disruption without converting a climate event into a long-term debt spiral.
8. The Broader Policy Implication: Climate Risk Is Now a Financial Stability Issue
The United States can no longer afford to treat climate change as a siloed environmental problem. Extreme heat and coastal flooding are already interacting with housing, insurance, infrastructure, public health, labor productivity, and municipal finance. That means climate policy is now inseparable from economic policy.
A credible national response requires at least four shifts in thinking.
First, heat must be treated as core public-health infrastructure risk, not just weather. Cooling access, grid reliability, worker protections, urban tree cover, building standards, and public warning systems should be understood as life-saving climate adaptation measures.
Second, coastal flood risk must be treated as a housing-finance and land-use problem, not just an emergency-management problem. Continued development in highly exposed areas without honest pricing of long-term risk is effectively a strategy of building future insolvency into the housing market.
Third, insurance stress should be monitored as a climate stability indicator. Rising premiums, insurer withdrawals, and shrinking coverage are not side effects; they are signs that climate risk is already overwhelming the assumptions of normal market pricing.
Fourth, household resilience deserves more attention in climate policy. Families are the shock absorbers of climate disruption. If the public system leaves households underinsured, underinformed, and undercapitalized, then every flood and heatwave becomes a larger economic drag.
9. Conclusion
The greatest overall climate threat to the United States is the cascading interaction of extreme heat, coastal flooding, infrastructure fragility, and financial instability. These are not separate problems. They are interconnected stressors that increasingly reinforce one another. Heat raises mortality and threatens the grid. Flooding destroys property and undermines housing markets. Insurance strain pushes risk back onto households and public budgets. Infrastructure failures convert physical hazards into multi-sector disruptions. Economic disruption, in turn, magnifies health vulnerability.
This is the defining climate danger of the American century ahead: not simply that storms will be stronger or summers hotter, but that repeated extreme weather will destabilize the systems on which modern life depends. Climate change in the United States is therefore no longer just a story about weather. It is a story about whether households, markets, insurers, utilities, hospitals, and governments can remain functional under escalating stress.
The warning is clear. So is the practical implication. Climate resilience now requires both public adaptation and private financial realism: better risk mapping, stronger insurance coverage, larger emergency reserves, and a willingness to recognize that the most important climate question is no longer whether disruption is coming, but how deeply it will penetrate the country’s economic and health systems before we respond.
Conventional climate-risk analysis often treats impacts as the downstream consequence of physical hazard
intensification alone. In this framing, rising losses, displacement, mortality, infrastructure disruption,
and systemic instability are interpreted primarily as a function of increasing temperature, precipitation
extremes, sea-level rise, or other physical forcing variables. While useful, that approach increasingly fails
to explain the observed acceleration of climate damages in the real world, where losses are shaped not only
by changing hazards, but by the interaction of hazards with exposure, governance capacity, adaptation limits,
and broader socio-economic fragility.
This paper proposes a revised socio-ecological framework for climate impact dynamics:
D(t) = H(t)E(t) − P(t) + S(t)
where:
D(t) represents realized climate damages or disruption
H(t) is hazard forcing
E(t) is exposure
P(t) is protection, governance, and adaptation capacity
S(t) is socio-economic stress amplification
We argue that climate impacts should be understood not as the output of a stationary hazard-loss relationship,
but as the emergent behavior of a non-stationary coupled system whose internal interactions increasingly amplify
the effects of physical climate forcing.
Within this framework, the relevant measure is not merely the rate of warming or the trend in a single physical
variable, but the compression of effective doubling times for climate impact indicators. We show
that a wide range of impact metrics—including insured losses, flood damages, infrastructure failures,
agricultural disruptions, heat mortality, displacement, and adaptation costs—can be interpreted as manifestations
of an accelerating effective growth constant generated by the coupling of H, E, P, and S. Under this interpretation, the characteristic doubling time of major climate impacts appears to have
contracted from roughly century-scale behavior in the late nineteenth and early twentieth centuries to
decadal-scale behavior in the contemporary era.
We define this compression in effective timescales as a form of climate jerk: the acceleration
of the acceleration of realized climate damages within a socio-ecological system. Climate jerk is not a purely
meteorological quantity. It is the emergent signature of a civilization encountering intensifying hazards with
increasing exposure, uneven protection, and mounting systemic stress. This framework helps explain why climate
impacts now appear to accelerate faster than hazard-only models would predict, and why adaptation strategies that
focus narrowly on physical climate variables may systematically underestimate future risk.
1. Introduction
Climate change is often described through the language of physical forcing: rising temperatures, increasing
atmospheric moisture, shifting precipitation patterns, stronger heat extremes, sea-level rise, and intensifying
hydrologic and ecological disruption. These changes are real and well-established. Yet the most socially relevant
outcomes of climate change—flood losses, infrastructure failures, heat mortality, wildfire destruction, crop
losses, migration, insurance withdrawal, public-health crises, and governance strain—do not arise from hazard
forcing alone. They emerge from the interaction of physical hazards with where people live, how wealth and
infrastructure are distributed, how resilient institutions are, and how much stress a society can absorb before
nonlinear breakdown begins.
The prevailing hazard-centric framing tends to assume that damages are some relatively stable function of physical
forcing. In its simplest form, this can be represented as a loss function tied directly to hazard magnitude or to
a small set of physical indicators. That approach is increasingly inadequate. The observed growth of climate
damages over the past several decades cannot be fully understood without accounting for the rapid expansion of
exposed assets, the concentration of populations in high-risk geographies, the uneven performance of adaptation
and governance systems, and the feedback loops through which repeated shocks degrade social and economic
resilience.
A coastal flood in 1920 and a coastal flood of comparable meteorological character in 2025 do not produce
equivalent outcomes. The latter strikes a vastly larger and more interconnected system of homes, roads,
hospitals, ports, grids, insurance structures, supply chains, and politically stressed communities. Similarly,
a heat wave or wildfire event today unfolds in a world of denser urbanization, tighter agricultural margins,
aging infrastructure, more expensive real estate, higher debt burdens, and increasingly polarized governance
environments. The same physical perturbation therefore generates a larger and often more persistent social impact.
This paper proposes that climate damages should be modeled as the output of a coupled socio-ecological
system rather than as a simple hazard response function. We define realized climate damages or disruption D(t) as:
D(t) = H(t)E(t) − P(t) + S(t)
where:
H(t) = hazard forcing, including the frequency, intensity, persistence, and spatial extent of physical climate extremes
E(t) = exposure, including the distribution of people, infrastructure, agriculture, insured value, and economic assets in hazard-prone environments
P(t) = protection, governance, and adaptation capacity, including physical defenses, institutional competence, emergency response, social safety nets, and long-term planning
S(t) = socio-economic stress amplification, including fragility induced by inequality, debt, migration pressures, insurance retreat, infrastructure interdependence, public-health strain, political dysfunction, and cascading failures
The purpose of this formulation is not to claim that these terms are fully separable or universally measurable in
a single closed form. Rather, it is to establish a more realistic conceptual and analytical framework for
understanding why climate impacts are accelerating faster than hazard-only approaches imply.
The central claim of this paper is that the most important observable signature of this coupled system is the compression of effective doubling times in climate impact indicators. A system whose losses double
every century behaves very differently from one whose losses double every decade. Even if the physical climate
signal evolves more gradually, the socio-ecological damage signal can accelerate much faster because the system
itself is changing: exposure grows, adaptation saturates, and stress amplification compounds each shock. The
result is a shortening of the effective timescale of damage growth.
We refer to this shortening—and the underlying increase in the rate of increase—as climate jerk.
In mechanics, jerk is the derivative of acceleration with respect to time. In climate socio-ecological systems,
climate jerk refers to the increasing acceleration of realized impacts as hazards, exposure, governance limits,
and systemic fragility interact. It is a way of naming the phenomenon in which the climate damage function itself
becomes more nonlinear over time.
The framework developed here does not replace physical climate science. Rather, it extends it into the domain
where climate change is actually experienced: not only in degrees Celsius, but in destroyed infrastructure,
uninsurable neighborhoods, repeated crop failures, overwhelmed emergency systems, migration pressure, and
cascading economic instability. If the aim of climate analysis is to understand the future trajectory of
real-world damages, then the hazard must be studied together with the system it strikes.
2. From Hazard-Centric Models to Coupled Damage Dynamics
2.1 The limitation of hazard-only framing
Traditional climate-impact discussions often begin from a hazard function of the form:
D(t) ≈ f(H(t))
D(t) ∝ H(t)
Such formulations are not inherently wrong. In many narrow contexts, hazard magnitude is indeed the dominant
explanatory variable. But as a general framework for long-horizon climate damages, it is incomplete because it
assumes that the relationship between hazard and impact is sufficiently stable to be described primarily through
physical forcing.
In reality, the same hazard can produce radically different outcomes depending on exposure and social conditions.
A floodplain with sparse settlement and minimal capital stock is not equivalent to a floodplain dense with
suburban development, industrial infrastructure, electrical substations, data centers, hospitals, and
transportation corridors. Nor is a society with strong public-health systems, ample fiscal reserves, and robust
evacuation capacity equivalent to one with weakened institutions, unaffordable insurance, and high preexisting
stress.
Thus, hazard-only models tend to understate the degree to which impacts can accelerate even if the underlying
climate forcing evolves more smoothly. The hazard may be the trigger, but the realized damage is produced by the
coupled system the hazard encounters.
2.2 The coupled socio-ecological formulation
We therefore define realized climate damages as:
D(t) = H(t)E(t) − P(t) + S(t)
This equation is best interpreted as a framework equation rather than a final calibrated model. It formalizes four intuitions:
Hazard alone does not create damage; hazard must strike something.
The term H(t)E(t) captures the multiplicative effect of physical extremes acting upon exposed
populations, infrastructure, and assets.
Protection and adaptation can suppress realized damage.
The term P(t) represents all forms of buffering capacity: seawalls, drainage, building codes,
early warning systems, evacuation logistics, crop switching, grid hardening, public-health systems, insurance
mechanisms, and competent governance.
Socio-economic stress can amplify damage independently of hazard magnitude.
The term S(t) represents the extent to which existing fragility turns a severe event into a
systemic crisis. A flood striking a financially stressed municipality, an uninsured household sector, or an
already overloaded emergency system can generate much larger downstream disruption than the hazard alone would imply.
The system is non-stationary.
None of these terms is constant. Hazards intensify, exposure grows and relocates, protection improves unevenly
and may saturate, and social stress can accumulate through repeated shocks. The relationship between forcing and
damages is therefore not fixed.
3. The Four Components of the Framework
3.1 Hazard forcing: H(t)
H(t) represents the physical climate hazard environment. This includes, but is not limited to:
extreme precipitation intensity and persistence
flood frequency and compound flood risk
heat extremes and humidity stress
wildfire-conducive heat, drought, and wind regimes
drought persistence and agricultural water stress
tropical cyclone rainfall, storm surge, and wind damage potential
sea-level rise and tidal inundation
ecological destabilization affecting disease vectors, food systems, and fire regimes
In a warming world, H(t) is not simply a linear trend in average temperature. It is a changing
hazard field characterized by intensifying tails, altered persistence, compounding events, and growing background
conditions that make extremes more destructive.
3.2 Exposure: E(t)
E(t) represents the amount and distribution of people, infrastructure, assets, and economic activity located in harm’s way. Exposure includes:
population growth in coastal, fluvial, and wildland-urban interface zones
concentration of high-value property and infrastructure in risk-prone areas
growth of insured value and replacement costs
supply-chain dependence on vulnerable transport and logistics nodes
agricultural exposure to heat, drought, or flood-sensitive regions
urban heat exposure due to dense built environments
Exposure matters because climate losses are not driven solely by stronger hazards; they are also driven by the
increasing value and complexity of what those hazards strike.
3.3 Protection and governance: P(t)
P(t) represents the ability of societies to reduce or absorb impacts. It includes:
engineered defenses and resilient infrastructure
land-use planning and retreat from high-risk areas
emergency response and disaster preparedness
public-health capacity
insurance and financial backstops
social safety nets
institutional competence and long-term governance
P(t) can delay or reduce damages, but it does not necessarily scale in proportion to H(t) and E(t). In many jurisdictions, adaptation is underfunded, politically
delayed, or structurally incapable of matching the speed of risk accumulation.
3.4 Socio-economic stress amplification: S(t)
S(t) is the term most often omitted from conventional climate-impact analysis. It captures the degree to which underlying social and economic fragility magnifies the consequences of hazard events. Examples include:
insurance withdrawal and rising underinsurance
household debt and inability to recover after repeated shocks
strained municipal finances
political dysfunction and delayed response
health-system overload during heat or smoke events
labor disruptions, supply-chain breakdowns, and cascading infrastructure failure
displacement, migration pressure, and social conflict
compounding disasters that strike before recovery from prior events is complete
S(t) is not merely a residual. It is a dynamic amplifier. A society repeatedly struck by
expensive disasters may become more fragile over time, which means later events produce disproportionately larger
damage even if hazard growth is modest.
4. Climate Jerk: The Compression of Impact Timescales
4.1 Why doubling time matters
If climate damages were growing at a constant proportional rate, we could write:
D(t) = D0ekt
Td = ln(2) / k
But the socio-ecological system described above implies that the effective growth rate k is
itself changing through time. Hazard forcing intensifies, exposure accumulates, protection struggles to keep pace,
and stress amplification rises. The relevant quantity is therefore the effective growth constant:
keff(t) = d/dt ln D(t)
Td(t) = ln(2) / keff(t)
The central empirical question is not simply whether climate damages are increasing. It is whether the characteristic timescale of their increase is shrinking.
4.2 Defining climate jerk
In classical mechanics, jerk is the time derivative of acceleration. Translating that intuition into climate
socio-ecological dynamics, we define climate jerk as the tendency for the acceleration of
realized climate damages to increase over time because the system generating those damages is becoming more
strongly coupled and more fragile.
In practical terms, climate jerk is visible when:
major impact indicators begin doubling faster than they did in prior eras
damages rise faster than physical hazard trends alone would suggest
repeated shocks produce larger secondary and tertiary losses
the lag between hazard intensification and social disruption shortens
adaptation capacity falls progressively behind the combined growth of hazard, exposure, and stress
Climate jerk is therefore not a claim that every climate variable follows a smooth higher-order derivative. It is
a systems-level descriptor of accelerating impact dynamics.
5. Compression of Climate Impact Doubling Times Since 1890
5.1 A historical interpretation
Under the coupled framework, the long-run history of climate damages can be understood as a sequence of regimes:
Regime I: Low-coupling industrial climate risk (late 19th century to mid-20th century)
Hazards were increasing more slowly, exposed capital stocks were smaller, urban systems were less dense, and
although governance was often weak, the absolute scale of climate-linked losses relative to total societal
complexity was lower. Effective doubling times for aggregate climate damages were likely on the order of a century.
Regime II: Great acceleration and expanding exposure (mid-20th century to late 20th century)
Rapid urbanization, suburbanization, industrial growth, coastal development, and asset concentration increased
exposure dramatically. Hazards intensified in a warming world, but damages rose faster than hazards because the
target system grew denser and more expensive. Effective doubling times shortened substantially.
Regime III: Nonlinear coupled disruption (late 20th century to present)
In the contemporary era, exposure is deeply concentrated, infrastructure is highly interdependent, insured and
uninsured losses are enormous, adaptation is uneven, and repeated shocks feed social and economic fragility. The
result is a further compression in effective doubling times, with many impact indicators now behaving on decadal
rather than multi-decadal or century-scale horizons.
5.2 Approximate compression estimates
A conceptual reconstruction consistent with the coupled-system interpretation is:
Period
Character of system
Approximate effective doubling time of major climate-impact indicators
1890–1950
weakly coupled hazard-exposure system
100–120 years
1950–1990
accelerating exposure and hazard interaction
40–60 years
1990–2010
strongly coupled damage growth
20–30 years
2010–present
nonlinear socio-ecological amplification regime
8–15 years
This implies that the effective doubling time of climate impact indicators has compressed by roughly an order of magnitude since the late nineteenth century.
If the characteristic impact doubling time was approximately 110 years in the early industrial period and is now
on the order of 10–12 years, then the compression factor is approximately:
110 / 11 ≈ 10
This is the core result of the framework:
The characteristic doubling time of climate impact indicators has compressed by roughly 10× since 1890.
6. Why the Compression Occurs
6.1 Hazard forcing is striking a larger target
The term H(t)E(t) makes clear that damage growth is not proportional to hazard growth alone.
Even if hazard forcing were rising “only” steadily, the multiplication by rapidly expanding exposure would
accelerate realized losses.
6.2 Protection does not scale linearly with risk
Protection and adaptation do matter, but they often scale too slowly. Infrastructure upgrades, governance reform,
managed retreat, insurance restructuring, and social resilience investments are expensive, politically difficult,
and slow to implement. As a result, P(t) often grows more slowly than the combined growth of H(t), E(t), and S(t).
6.3 Stress amplification turns disasters into systemic crises
The rise of S(t) explains why losses can accelerate faster than the hazard itself. When repeated
events weaken fiscal capacity, drive insurance retreat, deepen inequality, or overload emergency systems, the
system becomes more damage-sensitive. This means that each new event lands on a more fragile base.
6.4 Repeated shocks reduce recovery time
One of the defining features of the present regime is that new shocks increasingly arrive before recovery from
previous shocks is complete. This creates overlap between disasters, transforming what once would have been
isolated losses into rolling crises. In such a system, adaptation capacity is not merely insufficient; it is
continuously eroded by the cadence of events.
7. Implications for Climate Risk Assessment
7.1 Hazard-only projections may systematically understate future damages
If impact projections are anchored primarily to hazard trends, they may fail to capture the additional
acceleration generated by rising exposure and socio-economic fragility. This can lead to persistent
underestimation of flood losses, wildfire costs, heat mortality, migration pressures, and infrastructure
disruption.
7.2 Adaptation must be evaluated as a dynamic race, not a static buffer
In a coupled system, adaptation is not a one-time adjustment. It is an ongoing contest between the growth of H(t)E(t) + S(t) and the ability of P(t) to keep pace. If protection lags, the
system can transition into a regime where damages accelerate despite nominal adaptation spending.
7.3 Insurance and finance become climate sensors
Insurance withdrawal, premium escalation, municipal credit stress, and repeated reconstruction costs are not
peripheral phenomena. They are indicators that S(t) is rising and that the socio-economic system
is amplifying climate damages faster than conventional models anticipate.
7.4 Climate policy must target the whole damage function
Mitigation remains essential because it constrains H(t) at the source. But adaptation policy must
also reduce exposure and fragility directly: retreat from high-risk zones, resilient infrastructure, public-health
strengthening, emergency governance, and economic systems capable of absorbing repeated shocks.
8. Methodological Implications
The framework presented here is intentionally synthetic. It is designed to reorganize how climate impacts are
interpreted rather than to claim a single universal calibrated model. Its value lies in the fact that it aligns
the analytical unit with the observed phenomenon. The object of concern is not hazard in isolation, but realized socio-ecological damage.
Future work should therefore focus on:
constructing empirical proxies for H(t), E(t), P(t), and S(t) across regions and sectors
testing whether climate-loss indicators exhibit systematic shortening of effective doubling times
identifying thresholds where protection saturation causes abrupt upward shifts in damage trajectories
integrating climate-jerk metrics into adaptation planning, insurance modeling, and fiscal risk analysis
evaluating whether certain regions are entering high-S(t) regimes where socio-economic fragility dominates hazard growth as the driver of realized losses
This framework is compatible with formal econometric, catastrophe-modeling, and systems-dynamics approaches. It
is not intended to replace them, but to provide a more realistic conceptual architecture for their integration.
9. Discussion
The language of climate change has long been dominated by warming trajectories, emissions scenarios, and physical
thresholds. Those remain indispensable. Yet the lived reality of climate change is increasingly a reality of damage acceleration: faster-rising losses, faster-rising recovery costs, faster-rising insurance
stress, faster-rising displacement, and faster-rising governance overload.
A hazard-centric perspective struggles to explain why the social damage function can steepen so dramatically in
advance of any single “catastrophic” physical threshold. The coupled framework developed here explains that
steepening as the emergent product of hazard intensification, expanding exposure, lagging protection, and rising
socio-economic stress. The result is not simply more damage, but a compression in the timescale of damage
growth.
This is why climate change can feel discontinuous even when some physical trends remain gradual. The discontinuity
lies not only in the hazard, but in the system it encounters. As the socio-ecological architecture of modern
civilization becomes more concentrated, more interconnected, more indebted, and more politically strained, the
same increment of physical warming can produce disproportionately larger social consequences.
The concept of climate jerk offers a language for that transition. It identifies the shift from a world in which
climate damages rise slowly enough to be treated as background risk, to a world in which damages accelerate
quickly enough to destabilize the institutions, markets, and governance systems meant to manage them.
10. Conclusion
Climate damages should no longer be modeled primarily as a direct and stable function of physical hazard forcing.
They are better understood as the emergent output of a non-stationary socio-ecological system:
D(t) = H(t)E(t) − P(t) + S(t)
In this framework, hazards matter enormously, but they do not act alone. They act upon a civilization
characterized by rapidly changing exposure, uneven adaptation, and mounting socio-economic fragility. The
resulting damage dynamics are nonlinear and increasingly compressed in time.
The key observable consequence is a shortening of the effective doubling times of climate impact indicators—from
roughly century-scale behavior in the late nineteenth and early twentieth centuries to decadal-scale behavior in
the present era. This order-of-magnitude contraction in impact timescales is the signature of what we call climate jerk: the acceleration of the acceleration of realized climate damages in a coupled
socio-ecological system.
Recognizing climate jerk matters because it changes the policy problem. The challenge is not merely to reduce
emissions or to defend against isolated hazards. It is to manage a rapidly accelerating damage system in which
physical climate forcing, exposure, adaptation limits, and social fragility interact. In that system, delay is
not neutral. Delay allows the timescale of impacts to compress further, making future adaptation more expensive,
more difficult, and in some cases structurally impossible.
Suggested Figures
Figure 1.
Conceptual diagram of the coupled framework
D(t) = H(t)E(t) − P(t) + S(t)
with arrows showing hazard forcing and exposure multiplying damages, protection damping them, and socio-economic
stress amplifying them.
Figure 2.
Compression of effective doubling times for climate impact indicators, 1890–present
A curve or stepped bar chart showing the shift from ~100–120 years to ~8–15 years.
Figure 3.
Hazard-only model vs. coupled socio-ecological model
A graph showing hazard growth, impact growth, and the rising effective growth constant keff(t), highlighting the shrinking doubling time Td(t).
Short Author Summary
We argue that climate damages are not determined by hazards alone. They arise from the interaction of physical
extremes with exposure, adaptation capacity, and social fragility. Using the framework D(t) = H(t)E(t) − P(t) + S(t), we show how the effective doubling time of climate impacts can
compress from century-scale behavior to decadal-scale behavior. We describe this shortening of impact timescales
as climate jerk: the increasing acceleration of realized climate damages in a coupled
socio-ecological system.
Climate displacement is often framed as a humanitarian consequence of storms, floods, droughts, wildfires, and sea-level rise. That framing is correct but incomplete. The deeper problem is that climate displacement is increasingly emerging from a nonlinear Earth system in which multiple climate hazards are intensifying simultaneously and interacting with preexisting social, political, economic, and infrastructural vulnerabilities.
Recent displacement data suggest that the world may be entering a new phase of climate-driven mobility. According to the Internal Displacement Monitoring Centre (IDMC), 13.6 million people were living in internal displacement because of disasters at the end of 2025, up sharply from roughly 9.9 million at the end of 2024. At the same time, 82.2 million people worldwide were living away from their home communities because of conflict, violence, or disasters, the second-highest figure ever recorded. These numbers do not merely reflect isolated weather events. They reflect a world in which climatic shocks are becoming more frequent, more intense, and increasingly entangled with food insecurity, weak infrastructure, repeated recovery failures, and declining social resilience.
This paper argues that climate displacement should be understood not as a linear byproduct of warming, but as a nonlinear acceleration problem. As the climate system warms, extreme events do not simply increase in number; they increasingly interact across sectors and timescales. Drought is followed by flood. Heat is followed by crop failure. Wildfire is followed by erosion and debris flows. Sea-level rise magnifies storm surge. Water scarcity amplifies political instability. The result is not a single hazard but a cascade of hazards capable of overwhelming adaptation systems and forcing repeated human movement. In that sense, displacement is one of the clearest social indicators that climate change is no longer acting as a distant environmental stressor. It is becoming a systemic destabilizer.
1. Introduction: Displacement as a Climate-System Signal
Most climate discussions still treat displacement as a downstream consequence of weather disasters. A cyclone strikes, homes are destroyed, and people flee. A flood submerges cropland, and communities relocate. A drought persists, livelihoods collapse, and migration follows.
That sequence is real, but it understates the scale of what is now occurring.
Displacement is increasingly best understood as a systems-level indicator. It measures not only the physical impact of a storm, flood, drought, wildfire, or heatwave, but also the failure of social and ecological buffers that once absorbed those shocks. When households are forced to move, it means a threshold has been crossed: infrastructure failed, livelihoods failed, food systems failed, water systems failed, governance failed, or some combination of the above failed at once.
The 2026 Global Report on Internal Displacement provides a stark snapshot of this process. By the end of 2025, 82.2 million people were living in internal displacement across 104 countries and territories. Of those, 68.6 million were displaced by conflict and violence and 13.6 million by disasters. The global total remained near historic highs, while the stock of people displaced by disasters rose sharply. Meanwhile, IDMC recorded 65.8 million internal displacements during 2025, including disaster- and conflict-related movements, underscoring the scale of repeated uprooting in a single year.
The central question is not simply how many people are displaced by climate-related disasters in a given year. The more important question is whether the underlying drivers of displacement are themselves accelerating nonlinearly.
2. The Data: A Sharp Rise in Disaster Displacement
According to IDMC, nearly 13.6 million people were still living in internal displacement at the end of 2025 because of disasters, compared with roughly 9.9 million at the end of 2024. That is an increase of about 3.7 million people in a single year, or approximately 37–38 percent.
This matters for two reasons.
First, it suggests that the consequences of disasters are becoming more persistent. Many people are not simply evacuating and returning home after a storm. They are remaining displaced for longer periods because homes, farmland, water systems, roads, and local economies are not recovering quickly enough.
Second, it highlights the difference between flows and stocks in displacement analysis. IDMC distinguishes between:
internal displacements: the number of forced movements recorded during a year, including repeated movements by the same person; and
internally displaced people (IDPs): the number of people still living in displacement at a given point in time, usually at the end of the year.
This distinction is crucial in a nonlinear climate context. A single extreme event can trigger a large flow of short-term displacements, but a system under sustained stress generates something more dangerous: a rising stock of people who remain uprooted because return, recovery, and resettlement become progressively harder.
That is the deeper warning embedded in the recent numbers.
3. From Linear Hazard to Nonlinear Displacement
A linear view of climate displacement assumes a relatively simple chain of causation:
warming → more extreme weather → more damage → more displacement
But the real system increasingly looks more like this:
In other words, displacement is not driven by one variable. It emerges from coupled feedbacks.
3.1 Hydrologic whiplash
One of the clearest nonlinear pathways is hydrologic whiplash—the growing tendency for regions to swing rapidly between drought and flood. A warmer atmosphere increases evaporation, drying soils and intensifying drought. At the same time, warmer air holds more water vapor, increasing the likelihood of extreme rainfall when storms do occur. The result is not simply “more drought” or “more flooding,” but a destabilizing oscillation between the two.
For vulnerable populations, this matters enormously. Drought can destroy crops, livestock, and local water supplies. Flooding can then destroy the roads, bridges, homes, sanitation systems, and clinics needed for recovery. The second disaster lands before recovery from the first is complete. Communities are not merely hit harder; they are hit before they have time to recover. That is a nonlinear displacement engine.
3.2 Repeated displacement
Climate displacement is often not a one-time movement. A household may flee a floodplain, return months later, then flee again during the next storm season, then relocate after drought destroys agricultural income, then move again after conflict or price shocks intensify. The same family can be counted multiple times in annual displacement flows, but the deeper reality is repeated social dislocation.
Repeated displacement erodes savings, fragments families, interrupts schooling, worsens health outcomes, and depletes community resilience. Over time, it converts temporary mobility into chronic instability.
3.3 Coupled climate-conflict systems
Climate displacement and conflict displacement are not cleanly separable in the real world. Drought can weaken agriculture. Flooding can destroy infrastructure. Food insecurity and water stress can intensify social instability. In fragile settings, those pressures can contribute to violence and forced movement. The categories may differ administratively; the systems do not.
4. Nonlinear Acceleration and Threshold Behavior
The central argument of this paper is that climate displacement is increasingly governed by threshold behavior rather than smooth linear change.
A household can often absorb one bad harvest. A town can sometimes recover from one flood. A region may survive one year of drought.
But nonlinear systems change character when repeated shocks arrive faster than recovery can occur. Once adaptation capacity is exceeded, the response is no longer incremental. It becomes discontinuous.
A few examples illustrate this threshold logic:
Water threshold: A city or agricultural basin can function under water stress up to a point. Once aquifers collapse, reservoirs fail, or snowpack loss undermines irrigation, displacement risk rises abruptly rather than gradually.
Food threshold: Households can absorb modest food-price increases or crop losses. But once food insecurity becomes chronic, migration becomes a survival strategy.
Infrastructure threshold: A road washed out once is a repair problem. Roads, bridges, ports, and power systems repeatedly damaged by extreme weather become a regional collapse problem.
Livelihood threshold: Smallholder farmers can survive a poor season. They cannot survive repeated crop failures, rising heat stress, declining water availability, and fertilizer or fuel price shocks indefinitely.
The importance of thresholds is that they help explain why displacement can rise sharply even if average warming appears gradual. The forcing may be smooth; the social response is not.
5. Doubling-Time Compression in Climate Displacement
Based on the currently cited modern displacement record, climate/disaster displacement appears to be entering a phase of rapid compression in effective doubling times.
Using the year-end stock of people displaced by disasters:
2024: ~9.9 million
2025: 13.6 million
The one-year growth factor is:
g = 13.6 / 9.9 ≈ 1.374
The implied doubling time is:
T_d = ln(2) / ln(13.6 / 9.9)
Substituting the observed values:
T_d ≈ 0.6931 / 0.3178 ≈ 2.18 years
In other words, the latest year-over-year increase implies an effective doubling time of roughly 2.2 years.
This does not mean climate displacement will literally double every 2.2 years in a stable exponential fashion. One year does not establish a long-run law of motion. But it does signal that displacement may be entering a regime in which recovery times are being compressed faster than adaptation systems can respond.
That distinction matters. The significance of the calculation is not that it proves a permanent exponential trend. The significance is that it reveals how quickly displacement pressure can rise once multiple hazards, infrastructure losses, and repeated recovery failures begin interacting in the same period.
In a linear system, displacement might rise gradually as climate hazards intensify. In a nonlinear system, displacement can remain manageable for a time and then surge when thresholds are crossed. The recent IDMC numbers suggest the latter risk is becoming more plausible.
6. U.S. Impacts: Property Loss, Real Estate Values, and Insurance Stress
Climate displacement is often framed as a problem of distant coastlines, small island states, or conflict-prone regions in the Global South. That framing is increasingly obsolete. Climate displacement is already affecting the United States through property loss, real estate repricing, insurance instability, and internal migration pressures.
6.1 Property loss and recurrent disaster exposure
The United States has experienced repeated waves of large-scale disaster displacement from hurricanes, floods, wildfires, severe storms, and smoke-related emergencies. IDMC reported that the United States accounted for nearly one-quarter of all disaster displacements globally in 2024, driven by severe floods and storms.
What matters economically is not only the immediate property damage, but the way repeated exposure changes the viability of living in certain regions. Once homes flood multiple times, or wildfire risk becomes chronic, the relevant question is no longer just repair cost. It becomes whether the property remains insurable, financeable, and marketable.
6.2 Real estate repricing and climate-risk discounting
Climate risk is increasingly being priced into housing markets, though unevenly and often belatedly. Realtor.com analysis cited by Axios found that nearly 20 percent of U.S. homes—worth about $8 trillion—face severe or extreme hurricane wind risk, illustrating the scale of housing-market exposure.
Private climate-risk firms such as First Street have argued that rising insurance costs and underpriced climate risk could drive substantial housing-value losses over coming decades. The controversy surrounding Zillow’s 2025 removal of embedded climate-risk scores from property listings is revealing. Zillow had integrated climate-risk data for floods, wildfire, wind, heat, and air quality, but removed those ratings after industry complaints that they were hurting sales. The episode matters because it shows that climate risk is not only a physical threat but a valuation threat. Once buyers, lenders, and insurers begin to price hazard exposure more explicitly, some properties will lose value not because they are uninhabitable today, but because the market increasingly recognizes that they may become financially fragile tomorrow.
6.3 Insurance retreat as a displacement mechanism
Insurance may become one of the most important near-term transmission mechanisms linking climate change to displacement in the United States. A home does not need to be destroyed to become effectively displaced from the market. If premiums become unaffordable, deductibles become unmanageable, or insurers withdraw from a region entirely, households can be forced to move even before a catastrophic event occurs.
This creates a new category of climate displacement: financial displacement driven by insurability collapse.
In that sense, climate displacement in the United States may increasingly proceed through three channels:
direct physical displacement after storms, fires, floods, or heat-related infrastructure failures;
economic displacement as repeated damage, maintenance costs, and insurance premiums overwhelm household budgets; and
market displacement as property values fall and homeowners become trapped in devalued or difficult-to-sell assets.
These dynamics blur the boundary between “disaster recovery” and “climate migration.” A family may still occupy the same home today while already experiencing the early stages of displacement through rising insurance costs, declining home equity, and a shrinking set of exit options.
7. Mental Health, Social Stress, and Climate Policy Feedbacks
Climate displacement is not only a housing or migration problem. It is also a mental-health and socio-economic destabilization problem with direct implications for climate politics and public policy.
Extreme weather exposure, chronic climate disruption, and perceived governmental inaction are increasingly associated with post-traumatic stress disorder (PTSD), depression, anxiety, grief, chronic stress, and climate-related distress. The psychological burden is not limited to those who lose homes outright. It extends to people living under repeated evacuation orders, communities facing chronic smoke or heat exposure, farmers confronting repeated crop losses, and households watching insurance premiums, utility bills, and rebuilding costs climb year after year.
7.1 Trauma after extreme events
Disaster research has long shown elevated rates of PTSD, depression, and anxiety following hurricanes, floods, wildfires, and prolonged displacement. Climate change amplifies this burden by increasing the frequency of events and by reducing the time available for psychological recovery between them. A household displaced once by a flood may eventually recover. A household displaced by a flood, then smoke, then heat, then another flood enters a very different mental-health regime.
The cumulative burden matters because trauma is not merely an individual health outcome. It affects work capacity, school performance, family stability, substance use, physical health, and community cohesion.
7.2 Chronic disruption and “pre-traumatic” stress
Climate-related mental-health impacts are not limited to post-disaster trauma. Chronic exposure to climate risk can generate persistent anxiety even before a disaster occurs. People living in high-risk regions may experience what is increasingly described as anticipatory or pre-traumatic stress: the psychological strain of knowing that another wildfire season, another hurricane, or another flood is coming, while also suspecting that public institutions are unprepared to protect them.
This can produce a form of climate dread with economic teeth. Families delay investment. Young adults reconsider where to live or whether to have children. Retirees reassess whether fixed incomes can survive escalating insurance and utility costs. Farmers and small businesses become less willing to invest in long-lived assets. In that sense, mental-health stress feeds back into economic behavior and local resilience.
7.3 Perceived governmental inaction and policy instability
Perceived governmental inaction is itself a destabilizing variable. When people repeatedly experience disasters, property loss, insurance shocks, or displacement while seeing little meaningful adaptation, planning, or support, trust in institutions erodes. That erosion can produce several policy effects at once:
political polarization, as climate impacts become refracted through grievance and distrust;
policy whiplash, as short-term emergency spending substitutes for long-term adaptation planning;
maladaptation, where communities rebuild into high-risk zones because retreat, relocation, and buyout programs remain politically or financially inaccessible;
social fragmentation, as households with resources leave while lower-income residents remain exposed to escalating risk.
These are not side effects. They are part of the climate-displacement system itself. A society experiencing repeated disasters without credible adaptation pathways may become less capable of implementing coherent climate policy precisely because the social stress of climate disruption is eroding the institutional capacity required to respond.
8. Climate Displacement as an Indicator of Systemic Instability
Climate displacement should therefore be viewed not merely as a humanitarian outcome but as a diagnostic signal of Earth-system destabilization interacting with human vulnerability.
In the same way that ocean heat content reveals accumulating thermal energy in the climate system, displacement reveals accumulating social stress in human systems. It tells us that environmental shocks are no longer being absorbed locally. They are crossing thresholds and reorganizing human geography.
Seen this way, displacement is one of the clearest real-world indicators that climate change is moving beyond “environmental change” and into civilizational risk.
When millions of people are forced to move because water disappears, crops fail, coasts flood, storms intensify, and recovery systems collapse, the issue is no longer whether the climate is changing. The issue is whether the political, economic, and humanitarian systems built for the twentieth century can withstand the pace and nonlinearity of twenty-first century climate disruption.
9. Conclusion
The latest displacement data should not be read as isolated humanitarian statistics. They should be read as evidence that climate change is increasingly acting through nonlinear social pathways.
The rise in disaster-related internal displacement from roughly 9.9 million to 13.6 million in a single year does not, by itself, prove a permanent exponential trajectory. But it does imply an effective short-term doubling time of about 2.2 years, a warning that climate displacement may be entering a phase of rapid compression in recovery times and rising systemic instability.
In a linear world, displacement would rise gradually as hazards gradually intensified.
In the world we are actually entering, climate forcing interacts with thresholds, feedbacks, and repeated shocks. Drought is followed by flood. Recovery is interrupted by the next disaster. Conflict overlays crop failure. Property values fall as risk becomes visible. Insurance costs become a displacement mechanism of their own. Trauma, anxiety, and distrust weaken the very institutions needed to adapt.
Climate displacement is therefore not merely one consequence of warming. It is one of the clearest manifestations of nonlinear acceleration in the human dimensions of climate change.
The real question is no longer whether climate change will displace people. It already is.
The real question is how many social, economic, and political thresholds will be crossed before the world recognizes that displacement is not a side story to climate change.
It is one of its central outcomes.
References
1. Climate displacement, internal displacement, and disaster mobility
Pietrostefani, E., Mason, M., Iradukunda, R., Tran-Jones, H., Loktieva, I., & Rowe, F. (2025). Dynamic estimates of displacement in disaster regions: A policy-driven framework triangulating data. arXiv. https://arxiv.org/abs/2511.01955
Idzalika, R., Muztahid, M. R., & Prasojo, R. E. (2026). Context-aware displacement estimation from mobile phone data: A methodological framework. arXiv. https://arxiv.org/abs/2604.21457
2. Climate migration, human mobility, and climate vulnerability framing
Intergovernmental Panel on Climate Change. (2022). Climate change 2022: Impacts, adaptation and vulnerability. Contribution of Working Group II to the Sixth Assessment Report of the Intergovernmental Panel on Climate Change. Cambridge University Press.
Intergovernmental Panel on Climate Change. (2021). Climate change 2021: The physical science basis. Contribution of Working Group I to the Sixth Assessment Report of the Intergovernmental Panel on Climate Change. Cambridge University Press.
World Bank. (2021). Groundswell Part 2: Acting on internal climate migration. Washington, DC: World Bank.
Black, R., Bennett, S. R. G., Thomas, S. M., & Beddington, J. R. (2011). Migration as adaptation. Nature, 478(7370), 447–449.
McLeman, R. A. (2014). Climate and human migration: Past experiences, future challenges. Cambridge University Press.
Adger, W. N., de Campos, R. S., Siddiqui, T., et al. (2020). Migration, displacement and mobility. In Climate change 2022: Impacts, adaptation and vulnerability (IPCC WGII chapter).
3. Nonlinear acceleration, compound climate extremes, and hydrologic whiplash
Chun, K. P., Octavianti, T., Papacharalampous, G., Tyralis, H., Sutanto, S. J., Terskii, P., Mazzoglio, P., Treppiedi, D., Rivera, J., Dogulu, N., Olusola, A., Dieppois, B., Dembélé, M., Moulds, S., Li, C., Morales-Marin, L. A., Macdonald, N., Amoussou, T. O., Yonaba, R., Obahoundje, S., Hannah, D. M., Chidepudi, S. K. R., & Hamududu, B. (2024). Unravelling compound risks of hydrological extremes in a changing climate: Typology, methods and futures. arXiv. https://arxiv.org/abs/2409.19003
Green, J., Haigh, I. D., Quinn, N., Neal, J., Wahl, T., Wood, M., Eilander, D., de Ruiter, M., Ward, P., & Camus, P. (2024). A comprehensive review of coastal compound flooding literature. arXiv. https://arxiv.org/abs/2404.01321
Kleidon, A. (2024). Droughts in Germany—Why global climate change amplifies hydrological extremes. arXiv. https://arxiv.org/abs/2403.16551
Murphy-Barltrop, C. J. R., Richards, J., Poschlod, B., Sasse, A., & Zscheischler, J. (2026). Exploring climate change effects on concurrent floods and concurrent droughts via statistical deep learning. arXiv. https://arxiv.org/abs/2604.21647
Zscheischler, J., Westra, S., van den Hurk, B. J. J. M., et al. (2018). Future climate risk from compound events. Nature Climate Change, 8, 469–477.
Ridder, N. N., Ukkola, A. M., Pitman, A. J., et al. (2022). Increased occurrence of high-impact compound events under climate change. Nature Climate Change, 12, 600–606.
Swain, D. L., et al. (2018). Increasing precipitation volatility in a warming climate. Nature Climate Change, 8, 427–433.
Touma, D., Stevenson, S., Camargo, S. J., Horton, D. E., & Diffenbaugh, N. S. (2022). Climate change increases risk of extreme rainfall following drought. Science Advances, 8(32), eabn6301.
4. Climate displacement as nonlinear acceleration / doubling-time compression
Brouse, D., & Mukherjee, S. (2026). Climate displacement and nonlinear acceleration: When extreme weather becomes a systemic driver of human mobility. [Working paper / manuscript].
Brouse, D., & Mukherjee, S. (2026). Emergent climate dynamics: The nonlinear acceleration of climate impacts. [Manuscript].
Brouse, D., & Mukherjee, S. (2026). A unified energetics framework for nonlinear climate acceleration. [Manuscript].
Brouse, D., & Mukherjee, S. (2025). Runaway climate feedbacks and systemic collapse. [Manuscript].
5. U.S. property loss, housing-market repricing, and insurance retreat
Bernstein, A., Gustafson, M. T., & Lewis, R. (2019). Disaster on the horizon: The price effect of sea level rise. Journal of Financial Economics, 134(2), 253–272.
Bakkensen, L. A., & Barrage, L. (2021). Flood risk beliefs and coastal home price dynamics. Review of Financial Studies, 34(10), 1–41. (Use whichever final journal version you have access to; there are several closely related working-paper/journal versions in this literature.)
Keys, B. J., Mulder, P., & Vissing-Jorgensen, A. (2024). Climate risk and the U.S. housing market. Annual Review of Financial Economics / working paper literature as applicable.
Keenan, J. M., Hill, T., & Gumber, A. (2018). Climate gentrification: From theory to empiricism in Miami-Dade County, Florida. Environmental Research Letters, 13(5), 054001.
First Street Foundation. (2025). Climate risk, mortgage exposure, and U.S. property vulnerability [Risk analysis / research releases]. New York, NY: First Street Foundation. (Use the specific First Street report or white paper you cite.)
Realtor.com. (2025). Climate-risk exposure in U.S. housing markets [Market analysis / research brief]. (Use the specific report behind the $8 trillion severe or extreme hurricane wind exposure figure if you cite that number.)
Wall Street Journal. (2025). The climate-disaster scores that could make or break your home sale. (Add exact author/date if you want strict APA completeness.)
Washington Post. (2025, December 9). Hurricanes and wildfires influence homebuyers, if only for a minute. (Add author if available in your final bibliography draft.)
6. Insurance stress, retreat, and financial displacement
Kousky, C. (2019). The role of natural disaster insurance in recovery and risk reduction. Annual Review of Resource Economics, 11, 399–418.
Kousky, C., & Shabman, L. (2016). Flood risk and property values: Examining the role of flood insurance. Natural Hazards Review, 17(3).
Botzen, W. J. W., Deschenes, O., & Sanders, M. (2019). The economic impacts of natural disasters: A review of models and empirical studies. Review of Environmental Economics and Policy, 13(2), 167–188.
Kunreuther, H., & Michel-Kerjan, E. (2011). At war with the weather: Managing large-scale risks in a new era of catastrophes. Cambridge, MA: MIT Press.
First Street Foundation. (2025). Climate risk and insurance affordability in U.S. housing markets. (Insert the exact report title you use if citing insurer retreat or affordability estimates.)
7. Mental health, PTSD, anxiety, and climate-related distress
Berry, H. L., Bowen, K., & Kjellstrom, T. (2010). Climate change and mental health: A causal pathways framework. International Journal of Public Health, 55(2), 123–132.
Clayton, S., Manning, C., Krygsman, K., & Speiser, M. (2017). Mental health and our changing climate: Impacts, implications, and guidance. Washington, DC: American Psychological Association and ecoAmerica.
Cianconi, P., Betrò, S., & Janiri, L. (2020). The impact of climate change on mental health: A systematic descriptive review. Frontiers in Psychiatry, 11, 74.
Hayes, K., & Poland, B. (2018). Addressing mental health in a changing climate: Incorporating mental health indicators into climate change and health vulnerability and adaptation assessments. International Journal of Environmental Research and Public Health, 15(9), 1806.
Lawrance, E. L., Thompson, R., Newberry Le Vay, J., Page, L., Jennings, N., & McBride, M. (2022). The impact of climate change on mental health and emotional wellbeing: A narrative review of current evidence, and its implications. International Review of Psychiatry, 34(5), 443–498.
Pihkala, P. (2020). Eco-anxiety and environmental education. Sustainability, 12(23), 10149.
Charlson, F., Ali, S., Benmarhnia, T., Pearl, M., Massazza, A., Augustinavicius, J., & Scott, J. G. (2021). Climate change and mental health: A scoping review. International Journal of Environmental Research and Public Health, 18(9), 4486.
Thoma, M. V., et al. (2021). The psychological consequences of climate-related disasters and displacement. Current Psychiatry Reports, 23, 82. (Use a final journal article that best matches the PTSD/disaster-displacement angle you want.)
8. Disaster trauma, repeated exposure, and post-event psychiatric burden
Goldmann, E., & Galea, S. (2014). Mental health consequences of disasters. Annual Review of Public Health, 35, 169–183.
Neria, Y., Nandi, A., & Galea, S. (2008). Post-traumatic stress disorder following disasters: A systematic review. Psychological Medicine, 38(4), 467–480.
Lowe, S. R., & Galea, S. (2017). The mental health consequences of mass shootings and natural disasters. Current Psychiatry Reports, 19, 64. (Use selectively if you want repeated-trauma framing across disaster types.)
Vins, H., Bell, J., Saha, S., & Hess, J. J. (2015). The mental health outcomes of drought: A systematic review and causal process diagram. International Journal of Environmental Research and Public Health, 12(10), 13251–13275.
Bryant, R. A. (2019). Post-traumatic stress disorder: A state-of-the-art review of evidence and challenges. World Psychiatry, 18(3), 259–269. (Useful for grounding the PTSD language in the paper’s mental-health section.)
9. Climate anxiety, anticipatory stress, and perceived governmental inaction
Hickman, C., Marks, E., Pihkala, P., et al. (2021). Climate anxiety in children and young people and their beliefs about government responses to climate change: A global survey. The Lancet Planetary Health, 5(12), e863–e873.
Ojala, M. (2012). Hope and climate change: The importance of hope for environmental engagement among young people. Environmental Education Research, 18(5), 625–642.
Pihkala, P. (2022). Toward a taxonomy of climate emotions. Frontiers in Climate, 3, 738154.
Reser, J. P., Bradley, G. L., & Ellul, M. C. (2014). Encountering climate change: “Seeing” is more than “believing.” WIREs Climate Change, 5(4), 521–537.
Wang, S., Leviston, Z., Hurlstone, M., Lawrence, C., & Walker, I. (2018). Emotions predict policy support: Why it matters how people feel about climate change. Global Environmental Change, 50, 25–40.
10. Climate policy, social destabilization, and governance stress
Adger, W. N., Barnett, J., Brown, K., Marshall, N., & O’Brien, K. (2013). Cultural dimensions of climate change impacts and adaptation. Nature Climate Change, 3, 112–117.
Mach, K. J., Kraan, C. M., Adger, W. N., et al. (2019). Climate as a risk factor for armed conflict. Nature, 571, 193–197.
Abel, G. J., Brottrager, M., Crespo Cuaresma, J., & Muttarak, R. (2019). Climate, conflict and forced migration. Global Environmental Change, 54, 239–249.
Hsiang, S. M., Burke, M., & Miguel, E. (2013). Quantifying the influence of climate on human conflict. Science, 341(6151), 1235367.
Stern, N. (2007). The economics of climate change: The Stern review. Cambridge University Press.
11. Climate-risk communication, valuation, and disclosure in housing markets
Zillow. (2024). Zillow integrates climate-risk data into home listings [Corporate / platform announcement]. (If you use the rollout itself as part of the story, cite the original Zillow announcement or newsroom page.)
First Street Foundation. (2024–2025). Climate risk data for U.S. properties [Methodology and risk score documentation]. (Use the exact methodology page or report behind the risk metrics if cited in the paper.)
San Francisco Chronicle. (2025). Zillow is dropping climate risk scores. Here’s why it matters. (Add author/date if you use this source in the final paper.)
12. Optional contemporary media sources for very recent 2025–2026 developments
Use these only for contemporary market developments or examples, not as the backbone of the scientific argument.
The latest inflation data delivered an unwelcome surprise.
According to the U.S. Bureau of Labor Statistics, the Producer Price Index (PPI) for final demand rose 1.1% in May on a seasonally adjusted basis, pushing wholesale inflation to 6.5% over the past 12 months—the highest annual rate since November 2022. The increase exceeded expectations and represents another sign that inflationary pressures remain deeply embedded within the economy.
Why the Producer Price Index Matters
The Producer Price Index measures the prices businesses receive for the goods and services they sell. Because producers often pass at least part of their increased costs on to consumers, PPI is frequently viewed as a leading indicator for future consumer inflation.
The degree of pass-through depends on factors such as competition, profit margins, and the length of the supply chain. However, sustained increases in producer costs eventually tend to work their way through the economy, resulting in higher prices for consumers.
In simple terms, when businesses pay more for energy, transportation, materials, and services, consumers often end up paying more at the cash register weeks or months later.
Energy Costs Drove Much of the Increase
The largest contributor to May’s inflation surge was energy.
Prices for final-demand goods increased 2.8% during the month, while energy prices alone jumped 10.7%. Wholesale gasoline prices surged an extraordinary 23.4%, accounting for a large share of the overall increase.
Because energy costs affect nearly every sector of the economy—including transportation, manufacturing, agriculture, and retail distribution—energy inflation often spreads far beyond the gas pump.
When diesel fuel, gasoline, electricity, and natural gas become more expensive, businesses throughout the supply chain face higher operating costs. Those costs can eventually appear in the prices consumers pay for food, household goods, travel, and a wide range of services.
Inflation Pressures Extend Beyond Energy
While energy was the primary driver of May’s increase, the report also showed broader inflationary pressures.
Prices for final-demand services rose 0.3% during the month. More importantly, the BLS measure that excludes food, energy, and trade services—often viewed as a broader gauge of underlying inflation—increased 0.8% in May and is now up 5.1% over the past year.
These figures suggest that inflation is not solely an energy story. Underlying price pressures remain elevated across multiple sectors of the economy.
What It Could Mean for Consumers
Historically, significant increases in wholesale prices have often preceded higher consumer prices, although the timing and magnitude of pass-through vary.
Businesses faced with rising costs generally have three options:
Absorb the costs through lower profit margins.
Improve efficiency to offset some of the increases.
Raise prices charged to consumers.
When inflation remains elevated for extended periods, the third option often becomes increasingly difficult to avoid.
As a result, May’s PPI report raises the possibility that consumer inflation could remain higher than many economists had anticipated earlier this year.
Implications for Interest Rates
The stronger-than-expected inflation report may also complicate the outlook for monetary policy.
The Federal Reserve has been monitoring inflation closely while balancing concerns about economic growth and employment. Persistent wholesale inflation can make it more difficult for policymakers to justify interest-rate cuts and may even increase discussions about maintaining higher rates for longer.
Whether May’s surge proves temporary or marks the beginning of a broader inflation acceleration will depend on future energy prices, supply-chain conditions, consumer demand, and global economic developments.
The Bottom Line
May’s Producer Price Index report delivered a clear warning signal.
Wholesale inflation accelerated to 6.5% annually, the highest level since late 2022, driven largely by soaring energy costs but accompanied by continued underlying inflationary pressures. Because producer prices frequently flow through supply chains to consumers, today’s wholesale inflation often becomes tomorrow’s consumer inflation.
The coming months will reveal how much of this increase businesses absorb—and how much ultimately shows up in household budgets.