When I began this journey more than three decades ago, I wasn’t a climate researcher. I was a financial planner specializing in business, economics, estate planning, and risk management. My academic background included economics, philosophy, and extensive study in physics, calculus, statistics, and systems analysis. My career focused on a simple question:
How do you create the best possible future for the people who come after you?
In the early 1990s, I met a brilliant scientist named Sidd. We shared a curiosity about complex systems and a desire to test ideas rather than simply debate them. Together, we began an experiment that has now spanned more than thirty years.
Our goal was unusual. We wanted to build what we jokingly called a one-size-fits-all, bulletproof shareware estate plan—not for one family, but for every family on Earth.
At the same time, I was helping pioneer some of the earliest privately owned web servers. Before commercial hosting became commonplace, we were operating online while many organizations were still connected through universities. It was the same era when Yahoo! itself was running from Stanford University.
By 1995, our website, KingArthur.com, was attracting millions of visitors each month. The internet gave us something few researchers had ever possessed: the ability to interact directly with millions of people across cultures, countries, religions, and generations.
One question became central to our experiment:
“When it comes to your life and what you leave behind, what is the single most important thing?”
We expected many people to answer with wealth, success, fame, or legacy.
Instead, they overwhelmingly answered something much simpler.
Among people under fifty, the most common answer was their children.
Among those over fifty, the answer shifted to their grandchildren.
The experiment revealed something profound. The greatest wealth most people hope to preserve is not money. It is the opportunity for future generations to experience the same joys they have experienced themselves.
In other words, the ultimate estate plan is remarkably simple:
To my children’s children’s children.
The greatest inheritance most of us hope to leave is not a larger bank account. It is the chance for our descendants to raise children of their own, watch them grow, and someday become grandparents themselves.
When we began this experiment, I did not have grandchildren.
Today I do.
That changes everything.
Coincidentally, I was recently asked a question that perfectly captured the purpose of this work:
“Can you play with me on this? I’m wearing my nutritional ecologist hat here, and I’m in a municipal-level discussion that is trying to zoom out seven generations while also identifying the baby steps needed over the next four-year election cycle.”
My immediate thought was:
Exactly.
That is what this experiment has always been about.
An estate plan should not end with our children—or even our grandchildren. It should extend seven generations into the future.
My grandchildren deserve the opportunity to become grandparents themselves. Their grandchildren deserve the same opportunity.
That is entirely achievable—but only if we make wise decisions today.
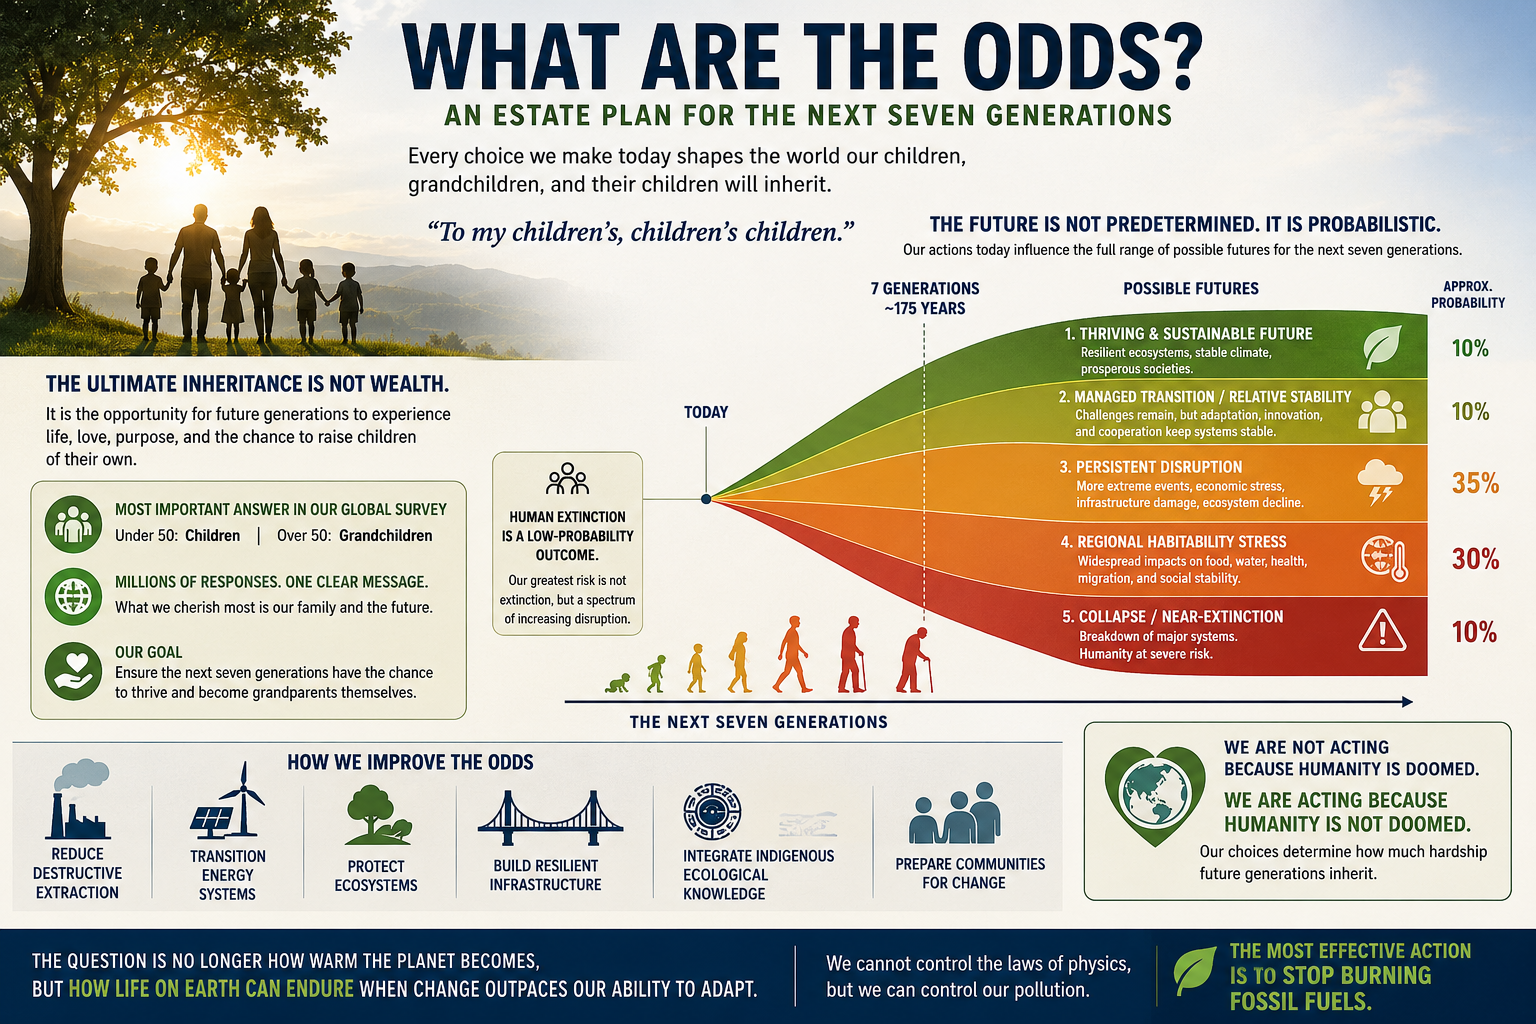
The graph that follows illustrates that idea.
Every choice we make now influences the range of possible futures available to the next seven generations.
Some outcomes are relatively optimistic. Some involve increasing climate disruption.
Some are far more severe.
Importantly, human extinction remains a low-probability outcome.
The far more likely future is not one of sudden extinction, but one that spans a spectrum of increasing disruption—affecting ecosystems, agriculture, infrastructure, economies, public health, migration, and regional habitability.
The probabilities are not fixed. They are shaped by the decisions humanity makes over the coming decades.. including today.
That changes the conversation entirely.
The question is no longer:
“Are humans going extinct?”
The more important question is:
“How difficult do we want life to be for the next seven generations?”
That question naturally leads to practical priorities:
Reduce destructive extraction of fossil fuels and natural resources.
Transition to cleaner and more resilient energy systems.
Protect and restore forests, wetlands, and other ecosystems.
Build infrastructure capable of withstanding future climate conditions.
Integrate Indigenous ecological knowledge alongside modern science.
Prepare communities to adapt to unavoidable change.
The most important message is this:
We are not acting because humanity is doomed.
We are acting because humanity is not doomed.
Our choices today determine how much hardship future generations inherit.
Ultimately, this is not simply a discussion about climate change.
It is an estate planning exercise on a planetary scale.
The question is no longer how warm the planet becomes.
The question is how well civilization—and the generations that follow us—can endure as environmental change accelerates faster than our ability to adapt.
We cannot rewrite the laws of physics. But we can decide how much pollution we continue to add to the atmosphere.
The most effective step we can take is also the simplest:
Stop burning fossil fuels as quickly and responsibly as possible, while building a more resilient world for the generations that follow.
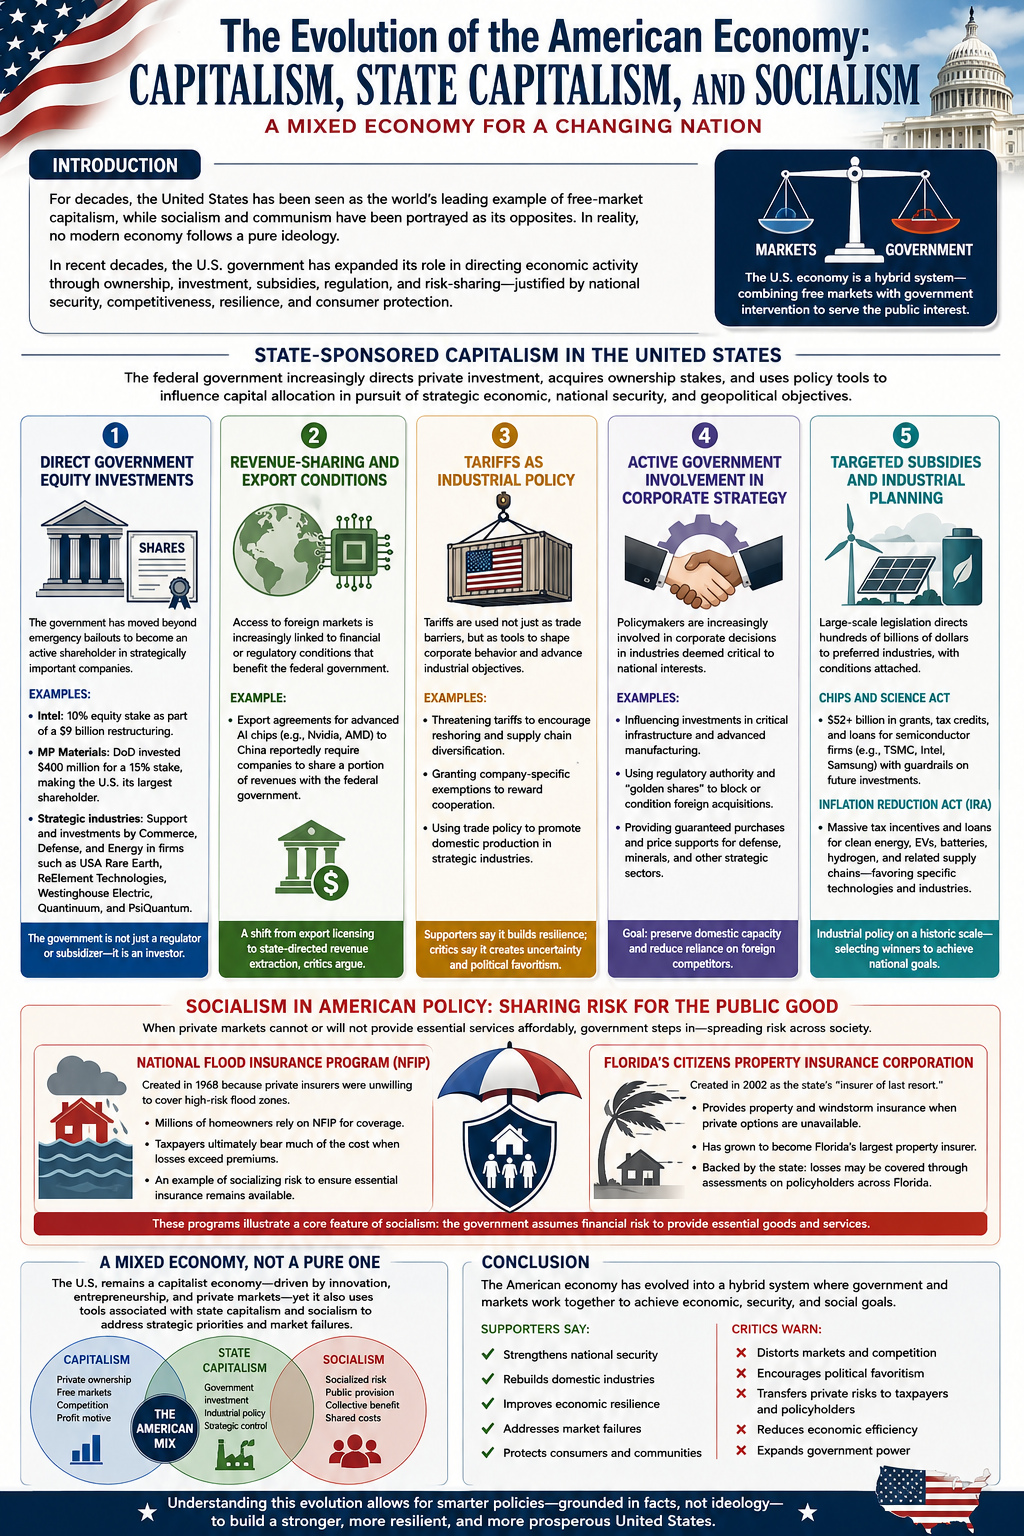
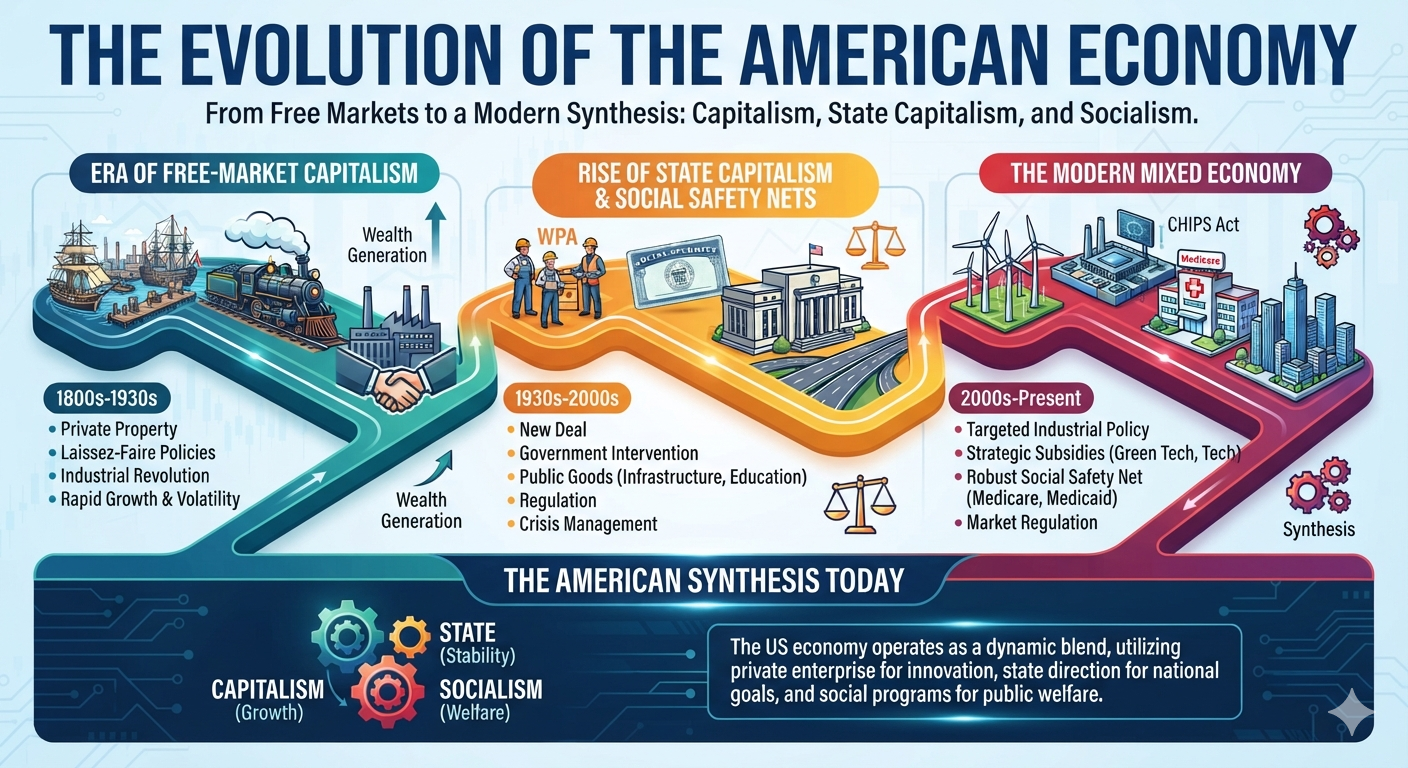
For much of its history, the United States has been portrayed as the world’s leading example of free-market capitalism, while socialism and communism have often been presented as fundamentally incompatible with American economic principles. In reality, no modern economy operates as a pure ideological model. Instead, governments continually adapt their economic policies in response to war, financial crises, technological competition, natural disasters, and changing national priorities.
Over the past several decades—and especially in recent years—the United States has significantly expanded the role of government in directing economic activity. Federal and state governments now provide targeted subsidies, acquire ownership stakes in private companies, shape investment decisions, guarantee markets for strategic industries, and assume financial risks that private markets are unwilling to bear. These policies are generally justified on the grounds of national security, economic competitiveness, supply-chain resilience, disaster recovery, or consumer protection.
This paper examines how these policies reflect characteristics traditionally associated with state-sponsored capitalism and socialism. Rather than arguing that the United States has abandoned capitalism, it demonstrates how the American economy has evolved into a hybrid system that combines free markets with substantial government intervention. Understanding this evolution provides important context for evaluating current economic policy and the changing relationship between government and private enterprise.
State-Sponsored Capitalism in the United States
State-sponsored capitalism (also called state capitalism) refers to an economic system in which the government plays an increasingly active role in directing private investment, acquiring ownership stakes in companies, or using public policy to influence capital allocation in pursuit of strategic economic, national security, or geopolitical objectives.
In recent years, the United States has moved further toward this model. While market mechanisms remain the foundation of the U.S. economy, successive administrations have expanded the federal government’s role through direct investments, industrial policy, subsidies, export controls, tariffs, and other forms of intervention designed to strengthen domestic manufacturing, secure critical supply chains, and enhance national competitiveness.
The principal mechanisms through which the federal government has pursued state-sponsored capitalism include the following:
1. Direct Government Equity Investments
Historically, federal ownership of private corporations was generally limited to temporary emergency bailouts. More recently, however, the government has begun acquiring direct equity positions in strategically important companies.
Examples include:
Intel: The federal government obtained a 10% equity stake in Intel as part of a restructuring package that included approximately $9 billion in federal support.
MP Materials: The Department of Defense invested approximately $400 million to acquire a 15% ownership stake in MP Materials, making the federal government its largest shareholder while supporting domestic rare-earth mineral production.
Strategic Industries: Federal agencies, including the Departments of Commerce, Defense, and Energy, have supported or invested in companies involved in critical technologies and infrastructure, including USA Rare Earth, ReElement Technologies, Westinghouse Electric Corporation, Quantinuum, and PsiQuantum.
These investments represent a notable departure from traditional industrial policy by making the government not only a regulator and subsidizer, but also an investor.
2. Revenue-Sharing and Export Conditions
The federal government has increasingly linked access to export markets with financial or regulatory conditions.
One example is the export framework governing advanced artificial intelligence chips. Agreements allowing companies such as Nvidia and AMD to export certain AI processors to China have reportedly included provisions requiring companies to share a portion of the resulting revenues with the federal government. Critics, including analysts at the Cato Institute, argue that this approach resembles state-directed revenue extraction rather than conventional export licensing.
3. Tariffs as Industrial Policy
Tariffs have become an increasingly important instrument of industrial strategy.
Rather than functioning solely as broad trade barriers, tariffs have also been used to influence corporate behavior.
Examples include:
Threatening tariffs to encourage companies to relocate manufacturing or diversify supply chains.
Granting company-specific exemptions or adjustments that reward firms aligning with national industrial objectives.
Using trade policy to encourage domestic production in strategically important industries.
Supporters argue these measures strengthen national resilience, while critics contend they increase uncertainty and allow greater political influence over private investment decisions.
4. Active Government Involvement in Corporate Strategy
Federal policymakers have become increasingly involved in major corporate decisions affecting industries considered strategically important.
Examples include:
Influencing investment decisions involving critical infrastructure and advanced manufacturing.
Exercising regulatory authority to discourage foreign acquisitions of strategically important companies.
Employing “golden share” mechanisms or comparable government veto powers in selected transactions involving national security interests.
Providing guaranteed purchase agreements or price supports for defense-related technologies, critical minerals, and other strategic industries.
These policies seek to preserve domestic industrial capacity while reducing dependence on foreign suppliers.
5. Targeted Subsidies and Industrial Planning
The expansion of state involvement did not begin with direct government ownership. Earlier legislation established a broad framework for government-directed industrial policy through grants, tax incentives, loans, and regulatory requirements.
The CHIPS and Science Act
The CHIPS and Science Act committed more than $52 billion in grants, tax credits, and loan guarantees to expand domestic semiconductor manufacturing. Major beneficiaries include Intel, TSMC, Samsung, and other semiconductor producers.
Recipients were also subject to “guardrail” provisions limiting certain future investments in countries considered strategic competitors.
The Inflation Reduction Act (IRA)
The Inflation Reduction Act created extensive tax credits, grants, and financing mechanisms supporting renewable energy, electric vehicles, battery manufacturing, hydrogen production, and related supply chains.
The legislation represents one of the largest industrial policy initiatives in U.S. history, directing hundreds of billions of dollars toward technologies identified by policymakers as priorities for the energy transition.
A New Economic Model?
Taken together, these policies illustrate a significant evolution in the relationship between the federal government and private enterprise. Rather than relying primarily on market incentives and regulatory oversight, the government has increasingly acted as investor, financier, customer, shareholder, trade negotiator, and strategic planner.
Supporters argue that these interventions are necessary to compete with state-directed economies such as China, strengthen national security, rebuild domestic manufacturing, and secure critical supply chains.
Critics counter that expanding government ownership, selective subsidies, preferential treatment, and direct intervention in private markets blur the traditional distinction between free-market capitalism and state-sponsored capitalism. They warn that such policies may distort competition, encourage political favoritism, and reduce market efficiency.
Whether viewed as a pragmatic response to global competition or a fundamental shift in American economic philosophy, the growing role of the federal government in directing private capital represents one of the most consequential developments in U.S. economic policy in decades.
Socialism
One characteristic commonly associated with socialism is the government assuming responsibility for providing goods or services that private markets are unable or unwilling to provide. In these cases, financial risks and costs are shared across society through taxes, mandatory assessments, or publicly backed insurance programs.
The U.S. insurance industry provides several examples of this approach.
The National Flood Insurance Program (NFIP)
The National Flood Insurance Program (NFIP), administered by the Federal Emergency Management Agency (FEMA), was established in 1968 because private insurers were largely unwilling to provide affordable flood insurance in many high-risk areas.
Rather than leaving homeowners without coverage, the federal government assumed much of the financial risk. Today, millions of property owners purchase flood insurance through the NFIP, with taxpayers ultimately bearing a substantial portion of catastrophic losses when claims exceed collected premiums. The program illustrates how the government has socialized a specific category of insurance risk that the private market has historically struggled to insure profitably.
Florida’s Citizens Property Insurance Corporation
Florida provides one of the clearest state-level examples of government intervention in insurance markets.
The Citizens Property Insurance Corporation was created by the Florida Legislature in 2002 as a government-established, not-for-profit insurer intended to serve as the state’s “insurer of last resort.” Its purpose is to provide property and windstorm insurance for homeowners, condominium owners, renters, and businesses that cannot obtain comparable coverage from private insurers.
As hurricanes have become more destructive, litigation costs have risen, and many private insurers have reduced their exposure or exited the Florida market altogether, Citizens has expanded dramatically. What began as a safety net has evolved into Florida’s largest property insurer, covering well over one million policies.
Unlike a private insurance company operating solely for profit, Citizens is backed by the state. If claims substantially exceed its financial reserves, Florida law allows Citizens to levy assessments on many insurance policies throughout the state to help cover losses. In effect, the financial risk is spread broadly among policyholders rather than borne exclusively by the individual customers who file claims.
A Mixed Economic Model
Programs such as the National Flood Insurance Program and Citizens Property Insurance Corporation illustrate how the United States operates as a mixed economy rather than a purely laissez-faire capitalist system. When private markets fail to provide essential services at affordable prices, governments have often stepped in to provide financing, insurance, or direct support.
Supporters argue that these programs protect homeowners, stabilize housing markets, and ensure that essential insurance remains available despite increasing climate and catastrophe risks.
Critics contend that publicly backed insurance can distort market signals, encourage development in high-risk areas, and shift financial burdens from individual property owners to taxpayers or other policyholders.
Regardless of one’s perspective, these programs demonstrate that government assumption of economic risk—one characteristic often associated with socialist policies—has become an established component of the American insurance system while coexisting with a predominantly private-market economy.
Conclusion
The American economy has never been completely free of government intervention, but the scope and nature of that intervention have changed substantially over time. Today, federal and state governments influence private markets through direct ownership, industrial policy, targeted subsidies, publicly backed insurance programs, trade policy, regulatory oversight, and strategic investments. These policies increasingly resemble characteristics associated with state-sponsored capitalism, while programs such as federally backed flood insurance and state-run insurers illustrate elements commonly associated with socialized risk.
Supporters argue that these interventions strengthen national security, rebuild domestic manufacturing, improve economic resilience, and address market failures that private enterprise alone cannot solve. Critics contend that expanding government involvement can reduce market efficiency, distort competition, encourage political favoritism, and transfer private risks to taxpayers.
The United States remains a capitalist economy, but it is no longer accurately described as a purely laissez-faire one. Instead, it has evolved into a mixed economic system in which free markets coexist with significant government participation. Recognizing this reality allows for a more informed discussion of public policy—one based not on political labels, but on the practical ways governments and markets increasingly work together to shape economic outcomes.
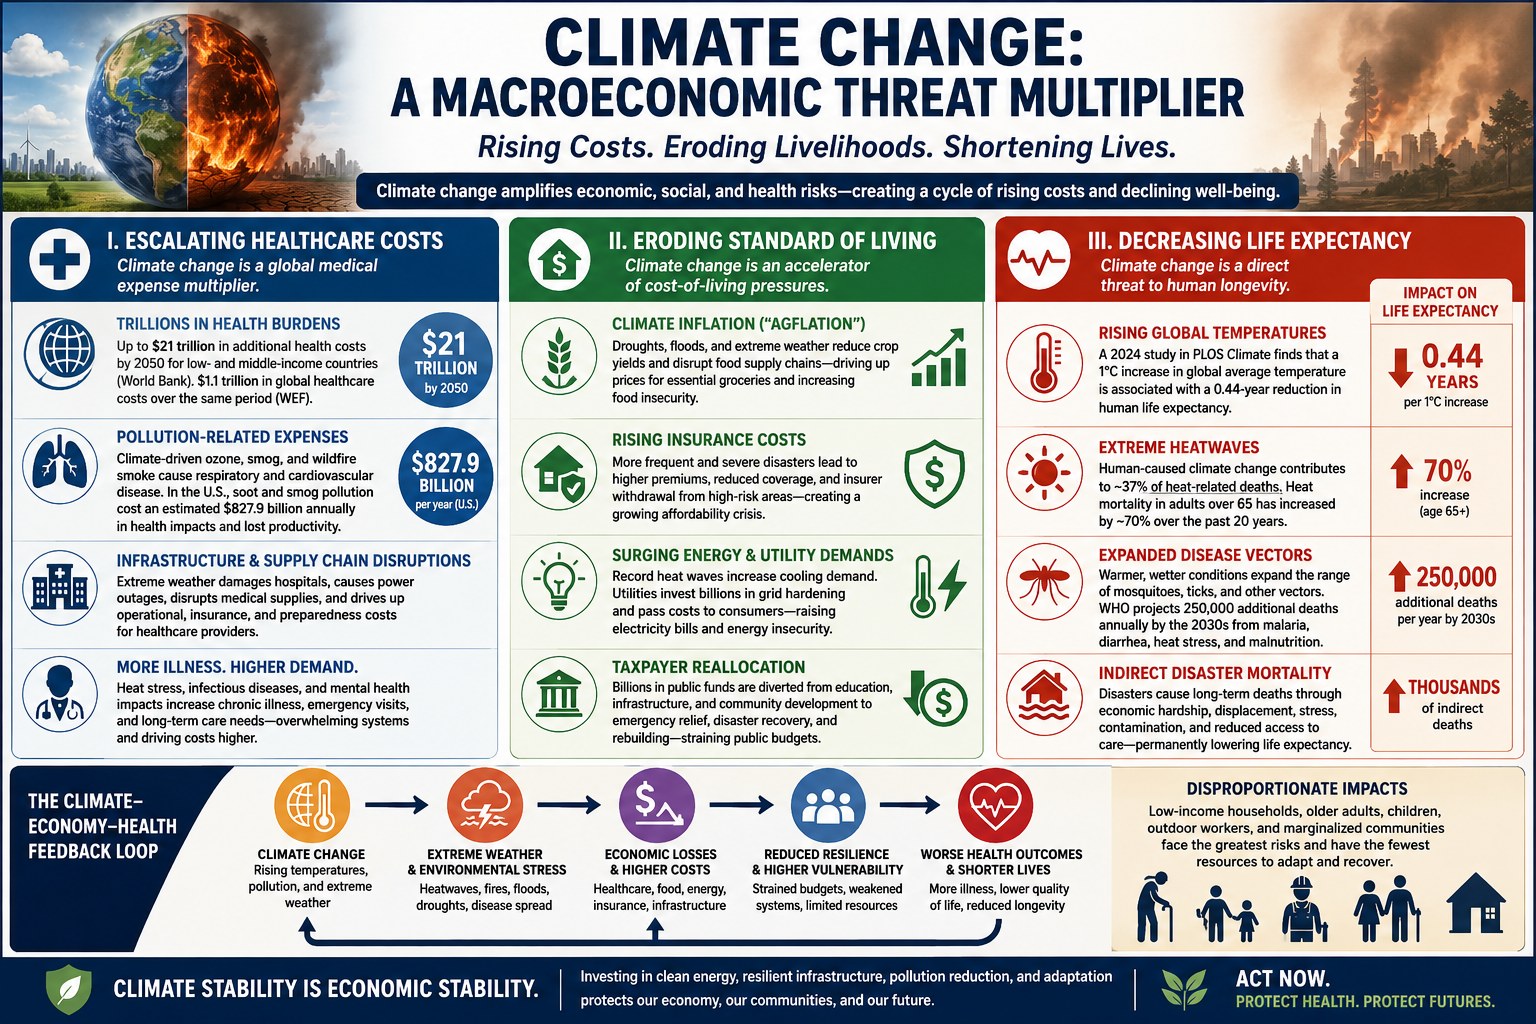
Introduction: Climate Change as an Economic and Human Security Crisis
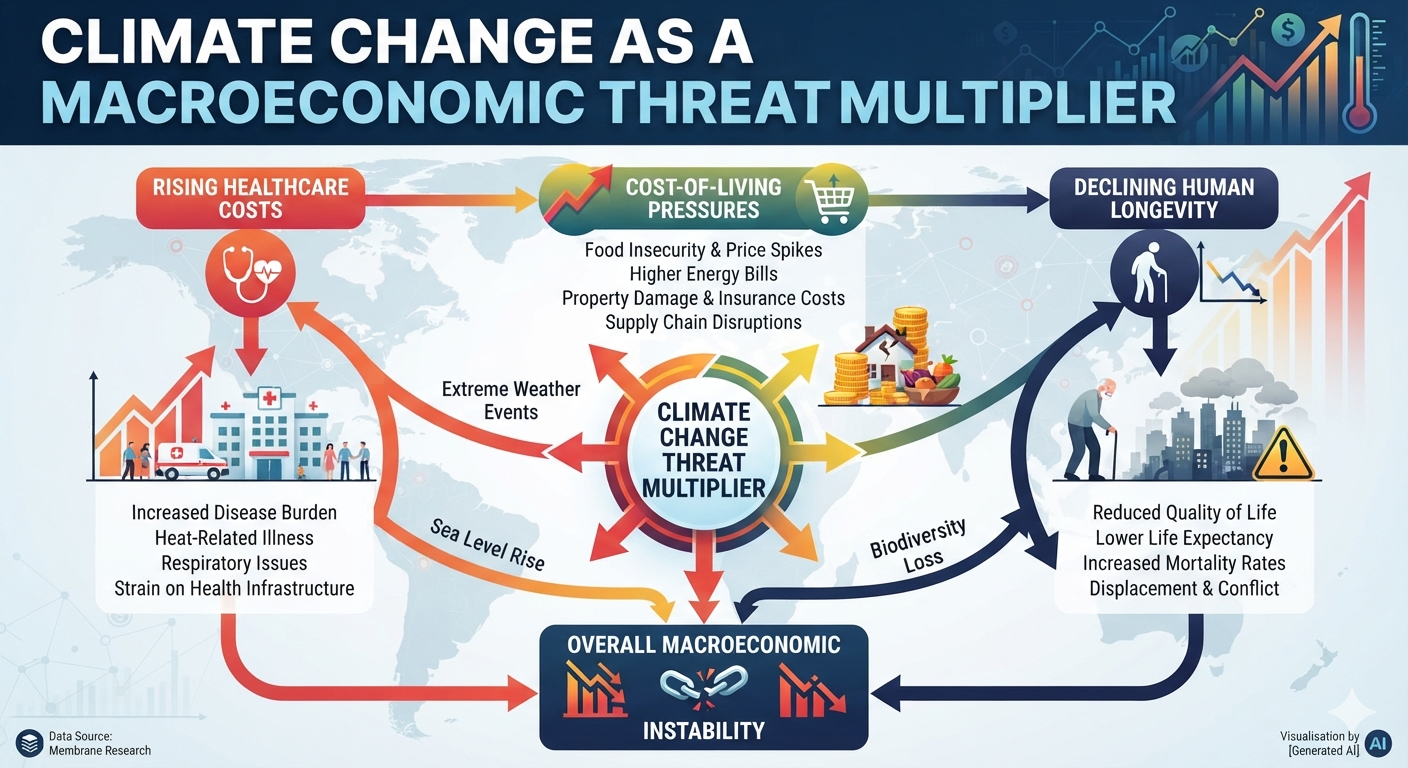
Climate change is no longer only an environmental challenge; it has become a powerful macroeconomic threat multiplier that amplifies existing social, economic, and public health vulnerabilities. Rising temperatures, increasingly extreme weather events, deteriorating air quality, and destabilized ecosystems are creating cascading financial pressures that extend from governments and businesses to individual households.
The economic consequences of climate change are increasingly visible through three interconnected pathways:
Escalating healthcare costs caused by heat exposure, air pollution, infectious diseases, and climate-related disasters.
Erosion of living standards through inflationary pressures on food, energy, insurance, housing, and public infrastructure.
Declining human longevity as environmental stressors undermine physical health, increase mortality, and reverse decades of progress in life expectancy.
These impacts are not distributed equally. Low-income households, elderly populations, outdoor workers, and marginalized communities often face the greatest exposure while having the fewest resources to adapt. Climate change therefore transforms environmental instability into a localized economic and human health crisis.
I. Escalating Healthcare Costs: Climate Change as a Global Medical Expense Multiplier
Climate change is placing unprecedented strain on healthcare systems by increasing both the frequency and severity of climate-related illnesses while simultaneously disrupting healthcare infrastructure.
1. Trillions of Dollars in Climate-Driven Health Burdens
The financial consequences of climate-related health impacts are expected to reach historic levels.
The World Bank estimates that climate-related health crises could impose approximately $21 trillion in additional costs by 2050 across low- and middle-income countries, reflecting increased disease burdens, reduced productivity, and expanding healthcare needs.
The World Economic Forum estimates that climate change could create approximately $1.1 trillion in additional global healthcare costs over the same period.
These costs represent more than direct medical expenses. They include lost productivity, reduced workforce participation, premature mortality, emergency response requirements, and infrastructure adaptation.
2. Pollution-Related Healthcare Expenses
Climate change and fossil fuel combustion are closely linked. Rising temperatures accelerate atmospheric chemical reactions that increase ground-level ozone formation, intensifying smog episodes and worsening respiratory and cardiovascular disease.
Fine particulate matter (PM2.5), ozone, wildfire smoke, and other pollutants contribute to:
Asthma and chronic respiratory illness
Heart attacks and strokes
Lung disease
Premature deaths
Increased emergency room visits
In the United States alone, soot and smog pollution are estimated to generate hundreds of billions of dollars annually in health-related costs, including medical expenses and lost economic productivity.
The growing frequency of wildfire smoke events demonstrates how climate impacts can transform regional air pollution into a national health emergency. Smoke from distant wildfires can travel thousands of miles, exposing millions of people far from the original source.
3. Healthcare Infrastructure and Supply Chain Disruptions
Extreme weather events increasingly threaten the operational stability of healthcare systems.
Climate-related disruptions include:
Hospitals losing electrical power during heat waves, hurricanes, and wildfires
Flooding damaging medical facilities
Disruptions in pharmaceutical and medical equipment supply chains
Increased emergency response costs
Higher insurance and operational expenses for healthcare providers
Hospitals are being forced to spend billions on climate resilience measures, including backup power systems, flood protection, cooling infrastructure, and emergency preparedness.
II. Eroding Standard of Living: Climate Change as a Cost-of-Living Accelerator
Climate change is increasingly becoming an economic reality experienced directly through household budgets. The same forces increasing healthcare costs are also driving inflationary pressures throughout the economy.
1. Climate Inflation and Agricultural Instability (“Agflation”)
Food systems are among the most climate-sensitive sectors of the global economy.
Rising temperatures, droughts, flooding, changing precipitation patterns, and extreme storms reduce agricultural productivity by damaging:
Crop yields
Livestock health
Fisheries
Agricultural infrastructure
Transportation networks
These disruptions create supply-side inflation, increasing prices for essential goods including:
Grains
Fruits and vegetables
Meat and dairy products
Transportation-dependent food products
Climate-driven food inflation disproportionately harms lower-income households because food represents a larger percentage of their monthly expenses.
2. Rising Insurance Costs and the Retreat From High-Risk Regions
The insurance industry has become one of the clearest economic indicators of accelerating climate risk.
As hurricanes, wildfires, floods, and severe storms become more frequent and destructive:
Insurance premiums increase dramatically.
Coverage becomes more restricted.
Insurers withdraw from vulnerable markets.
Property values decline in high-risk regions.
Homeowners increasingly face a difficult choice: pay rapidly increasing premiums or assume greater financial risk without adequate coverage.
This creates a growing climate affordability crisis, particularly for homeowners living in areas exposed to wildfire, coastal flooding, extreme storms, and severe weather.
3. Rising Energy Demand and Utility Costs
Climate change increases energy demand while simultaneously placing stress on energy infrastructure.
During extreme heat events:
Electricity consumption rises sharply due to increased air conditioning demand.
Utilities must invest billions in grid upgrades.
Transmission systems require additional protection against storms and wildfires.
Energy insecurity becomes a growing concern as vulnerable households struggle to afford cooling during dangerous heat events.
4. Taxpayer Costs and Public Financial Burdens
Climate disasters increasingly redirect public resources away from long-term investments toward emergency response and recovery.
Government spending is increasingly allocated toward:
Disaster relief
Infrastructure repairs
Emergency housing assistance
Flood recovery
Wildfire response
Agricultural assistance
These expenditures compete directly with funding for:
Education
Transportation improvements
Community development
Public health programs
Climate change therefore functions as a long-term fiscal drain, increasing government expenditures while reducing resources available for economic development.
III. Declining Human Longevity: Climate Change as a Biological Stressor
Beyond economic impacts, climate change increasingly affects the fundamental measure of human well-being: life expectancy.
The cumulative effects of extreme heat, pollution exposure, disease expansion, food insecurity, and climate disasters are slowing—and in some regions reversing—historical gains in longevity.
Climate Driver
Impact on Human Health and Longevity
Rising Global Temperatures
A 2024 study published in PLOS Climate found that a 1°C increase in global average temperature is associated with approximately a 0.44-year reduction in life expectancy.
Extreme Heatwaves
Human-caused climate change is estimated to contribute to approximately 37% of heat-related deaths. Heat-related mortality among adults over age 65 has increased substantially over recent decades.
Expanded Disease Vector Ranges
Warmer and wetter conditions allow mosquitoes, ticks, and other disease vectors to expand into new regions, increasing risks from malaria, dengue fever, Lyme disease, and other infections.
Food and Water Stress
Climate disruption increases risks of malnutrition, dehydration, agricultural failure, and water insecurity, particularly in vulnerable populations.
Indirect Disaster Mortality
Floods, hurricanes, wildfires, and other disasters create long-term health impacts through displacement, economic hardship, psychological stress, and environmental contamination.
This feedback loop means climate impacts are not isolated events. A wildfire, flood, or heat wave can simultaneously damage infrastructure, increase healthcare expenses, reduce productivity, raise insurance costs, and shorten human lives.
The poorest communities often experience the strongest effects because they have fewer resources to prepare, recover, and relocate.
Conclusion: Climate Stability Is Economic Stability
Climate change represents one of the largest economic and public health challenges of the modern era. Its consequences extend far beyond environmental degradation, affecting national budgets, household finances, healthcare systems, and human survival.
Addressing climate change is therefore not simply an environmental investment—it is an economic resilience strategy and a public health imperative. Investments in clean energy, resilient infrastructure, pollution reduction, efficient buildings, and climate adaptation can reduce future costs while protecting both human health and economic stability.
The cost of inaction is no longer measured only in degrees of warming. It is measured in rising medical bills, shrinking household budgets, damaged communities, and lost years of human life.
🌎 Climate Change and Personal Finances: The Rising Cost of a Changing Climate
Climate change is no longer only an environmental challenge—it is becoming a growing financial challenge for households everywhere.
While headline inflation may appear moderate, the costs most affected by climate change are rising faster than many household incomes.
🔥 Extreme heat is increasing electricity demand and stressing energy infrastructure. ⛈️ Severe storms and hail events are driving higher comprehensive auto insurance costs. 🏠 Floods, hurricanes, wildfires, and extreme weather are pushing homeowners insurance premiums higher. 🌾 Droughts, floods, and shifting growing conditions are increasing food-price volatility. 🔨 Climate-related damage and rebuilding costs are raising housing expenses.
A new economic reality is emerging:
Climate-sensitive expenses are becoming a larger share of household budgets.
The financial impacts of climate change are not limited to major disasters. They appear in recurring expenses—monthly utility bills, insurance premiums, repair costs, and the price of everyday goods.
Building financial resilience means preparing for this changing economic landscape:
✅ Reduce high-interest debt ✅ Build emergency savings ✅ Improve home energy efficiency ✅ Review insurance coverage ✅ Invest in weather protection and resilience ✅ Plan for increasing climate-related costs
Climate change is reshaping not only our environment, but also the economics of everyday life.
📊 Read the full report:
“Climate Change and Personal Finances: Managing Household Costs in an Era of Rising Climate Risk”
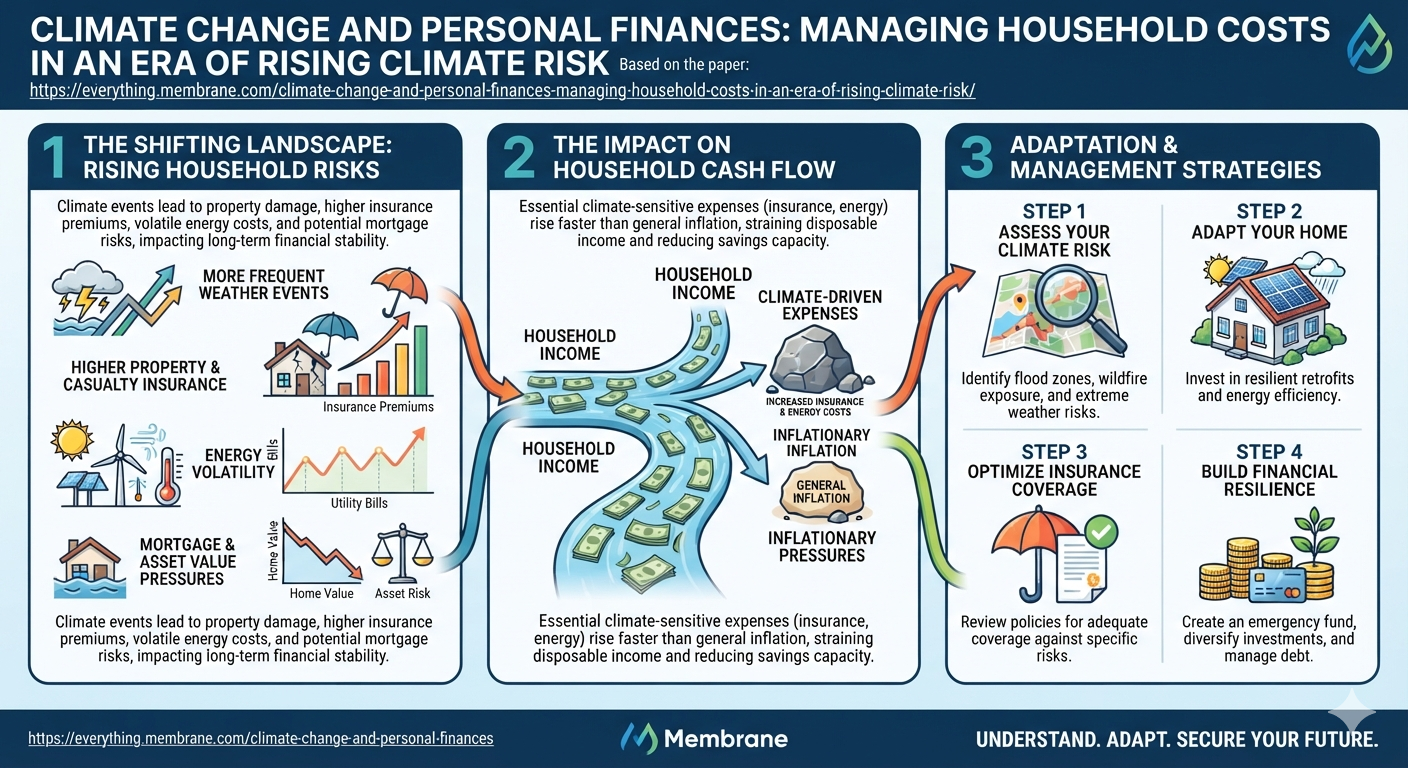
Climate change is no longer simply an environmental issue. It has become an economic force that influences nearly every aspect of household finances. Extreme weather, rising insurance losses, damaged infrastructure, disruptions to agriculture, and increasing energy demand are reshaping the cost of living.
While the overall inflation rate captures broad price changes across the economy, climate change increasingly creates uneven inflation. Some goods remain relatively stable, while climate-sensitive sectors experience much faster price growth.
Understanding these trends allows households to better prepare for an increasingly volatile financial future.
Overall Inflation
The Consumer Price Index for All Urban Consumers (CPI-U) currently reflects annual inflation of approximately 3.5%.
Although this represents moderate overall inflation, it masks significant differences among individual household expenses. Energy, insurance, housing, and weather-sensitive goods continue to experience above-average price increases, while wages have largely kept pace only with headline inflation.
As climate change intensifies, these differences are expected to become even more pronounced.
Household Price Trends
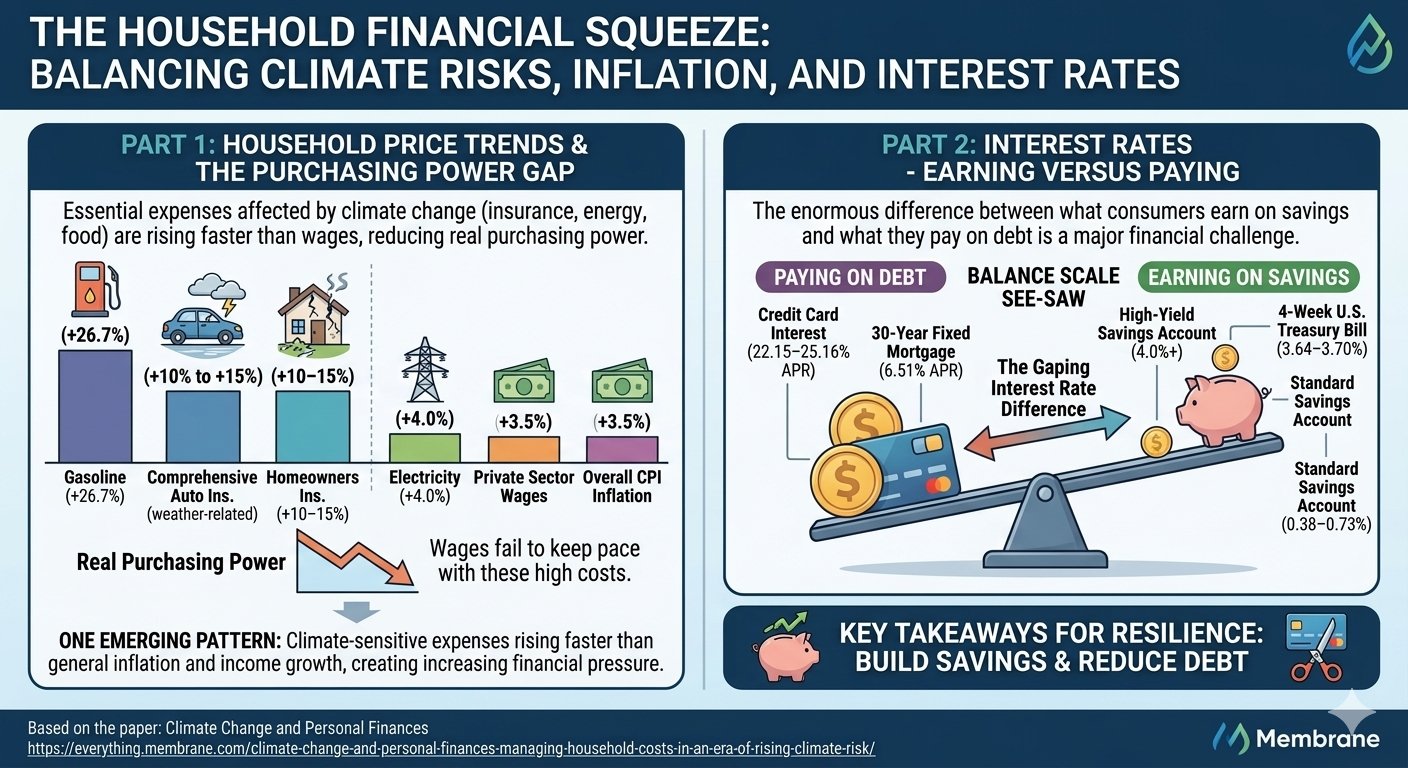
Major components of household budgets are experiencing dramatically different rates of inflation. Essential expenses increasingly affected by climate change—such as insurance, energy, housing repairs, and food—are rising faster than average wage gains. As a result, many households are experiencing a decline in real purchasing power despite wages keeping pace with headline inflation.
Household Expense
Annual Change
Overall CPI Inflation
+3.5%
Gasoline
+26.7%
Electricity
+4.0%
Comprehensive Auto Insurance (weather-related losses)
+10% to +15%
Homeowners Insurance
+10–15%
Private Sector Wages
+3.5%
One consistent pattern is emerging:
One consistent pattern is emerging: climate-sensitive expenses are rising faster than overall inflation and household income growth, creating increasing financial pressure for families adapting to a changing climate.
Energy Costs
Energy remains one of the largest sources of household inflation.
Gasoline prices have risen sharply due to geopolitical tensions, supply disruptions, refinery constraints, and transportation bottlenecks. While climate change is not the sole cause of gasoline inflation, extreme weather increasingly disrupts oil production, refining capacity, pipelines, and shipping routes.
Electricity prices have also continued to climb.
Several factors contribute:
Increased demand during prolonged heat waves
Expansion of electric transmission infrastructure
Grid modernization
Storm damage and repairs
Higher fuel and maintenance costs
As summers become hotter and heat waves last longer, residential electricity demand for air conditioning continues to increase.
The Insurance Crisis
Perhaps no household expense illustrates climate change more clearly than insurance.
Insurers base premiums on expected future losses—not past averages.
As hurricanes, wildfires, hailstorms, tornadoes, flooding, and severe convective storms become more destructive, insurance companies are paying record claims.
These losses eventually appear as:
Higher premiums
Larger deductibles
Reduced coverage
More exclusions
Non-renewals
Complete withdrawal from high-risk markets
Homeowners insurance has become one of the fastest-growing household expenses in many regions.
In some states, premiums have doubled within only a few years.
For households, insurance is increasingly becoming a direct monthly cost of climate change.
Comprehensive Auto Insurance and Climate Risk
Unlike collision insurance, which covers accidents between vehicles, comprehensive automobile insurance protects against damage caused by natural hazards and other non-collision events. As climate change increases the frequency and severity of extreme weather, comprehensive claims have risen substantially.
Common climate-related comprehensive claims include:
Hail damage
Falling trees and branches during windstorms
Flash flood damage
Hurricane storm surge
Wildfire damage
Tornado debris
Lightning strikes
Wind-blown objects
Ice and snow damage
Large hailstorms alone now produce billions of dollars in insured vehicle losses each year. Modern vehicles are particularly vulnerable because aluminum body panels, panoramic glass roofs, advanced sensors, cameras, and radar systems are expensive to repair or replace.
Flash flooding has also become one of the fastest-growing sources of comprehensive auto losses. Vehicles caught in flooded roadways often suffer catastrophic engine, electrical, and electronic damage, resulting in total-loss claims.
As insurers pay increasing numbers of weather-related claims, many companies have adjusted comprehensive premiums, increased deductibles, or refined risk models based on regional exposure to hail, flooding, hurricanes, wildfires, and severe convective storms.
While collision coverage is primarily influenced by driving behavior, repair costs, and accident frequency, comprehensive insurance increasingly reflects the financial consequences of a changing climate. For many households, the rising cost of comprehensive coverage has become another indirect expense associated with more frequent and more destructive extreme weather events.
Food Prices
Although food inflation fluctuates from year to year, climate change is placing increasing pressure on agricultural production.
Extreme heat, drought, flooding, hurricanes, and shifting growing seasons reduce crop yields while increasing production costs.
Examples include:
Heat-stressed livestock
Drought-reduced grain harvests
Flood-damaged vegetables
Disease outbreaks
Pollinator decline
Water shortages
The result is greater price volatility at grocery stores.
Consumers may increasingly experience periods where staple foods rise rapidly following major climate disasters.
Housing Costs
Housing costs are increasingly influenced by climate risk.
Construction materials become more expensive following disasters.
Labor shortages emerge after major storms.
Building codes become stricter.
Flood-resistant construction, stronger roofing systems, improved insulation, and wildfire-resistant materials all increase upfront construction costs while reducing long-term risk.
Mortgage lenders are also beginning to incorporate climate risk into property valuations.
Properties facing repeated flooding, wildfire exposure, or coastal erosion may experience declining values while insurance costs continue rising.
Wages and Purchasing Power
Private-sector wages have increased approximately 3.5% over the past year.
While this roughly matches headline inflation, it does not fully offset the faster growth of essential household expenses such as insurance, electricity, housing, and healthcare.
As a result, many households experience “cost-of-living compression,” where income keeps pace with average inflation but fails to keep pace with the expenses that matter most.
Interest Rates: Earning Versus Paying
One of the largest financial challenges facing households is the enormous difference between what consumers earn on savings and what they pay on debt.
Financial Instrument
Typical Rate
Credit Card Interest
22.15–25.16% APR
30-Year Fixed Mortgage
6.51% APR
High-Yield Savings Account
4.0%+
4-Week U.S. Treasury Bill
3.64–3.70%
Standard Savings Account
0.38–0.73%
The modern banking system rewards households that maintain liquidity while imposing extremely high costs on revolving debt.
Credit card interest rates frequently exceed 20%, making high-interest debt one of the largest obstacles to long-term financial security.
Conversely, households that maintain emergency savings can now earn meaningful returns through high-yield savings accounts and short-term Treasury securities.
Climate Change and Financial Risk
Climate change introduces several new forms of financial risk that traditional household budgeting rarely considered:
Increasing insurance premiums
Larger deductibles
Rising utility bills
Disaster repair costs
Temporary job interruptions after extreme weather
Declining property values in high-risk areas
Higher food prices
Greater investment volatility
These risks compound over time, making financial resilience increasingly important.
Strategies for Financial Resilience
Households can take practical steps to reduce their financial vulnerability to climate-related economic shocks.
Build an Emergency Fund
Maintaining three to six months of living expenses provides flexibility following disasters, temporary unemployment, or unexpected repairs.
Eliminate High-Interest Debt
Paying down credit cards earning 22–25% interest often provides a greater guaranteed return than most investments.
Improve Energy Efficiency
Investments such as insulation, efficient appliances, heat pumps, smart thermostats, and LED lighting can reduce utility costs while improving comfort during heat waves.
Review Insurance Coverage
Homeowners should regularly review policy limits, deductibles, exclusions, flood coverage, and replacement-cost estimates to ensure protection reflects today’s risks.
Diversify Investments
Diversification across asset classes, industries, and geographic regions can help reduce exposure to climate-related disruptions affecting any single sector.
Prepare for Extreme Weather
Emergency supplies, backup power, important documents, evacuation plans, and home maintenance can reduce both financial losses and recovery time after disasters.
The Economics of Adaptation
One of the defining economic realities of the coming decades will be the growing cost of adaptation.
Communities will invest billions in:
Stronger electrical grids
Flood-control systems
Coastal defenses
Wildfire mitigation
Stormwater infrastructure
More resilient buildings
Expanded emergency response capabilities
Although these investments require substantial upfront spending, they often cost far less than rebuilding after repeated disasters. For individual households, similar investments—such as reinforcing roofs, improving drainage, elevating utilities in flood-prone areas, or increasing home energy efficiency—can reduce future repair costs, lower insurance claims, and improve long-term resilience.
Conclusion
Climate change is increasingly shaping household finances through higher insurance premiums, rising energy costs, greater food-price volatility, and growing expenditures on disaster preparedness and infrastructure. At the same time, high borrowing costs amplify the financial strain on families carrying significant debt.
The central challenge is no longer simply inflation, but the uneven way inflation affects climate-sensitive expenses. Insurance, utilities, housing, and food are consuming a larger share of household budgets, even when overall inflation appears moderate.
Building emergency savings, reducing high-interest debt, investing in energy efficiency, maintaining appropriate insurance coverage, and preparing for extreme weather can strengthen financial resilience. As climate risks continue to evolve, households that proactively adapt their financial strategies will be better positioned to absorb future economic shocks and maintain long-term financial stability.
A Capital Preservation Strategy for an Uncertain Future
By Daniel Brouse
Introduction: Avoid the Minsky Moment
A “Minsky Moment” refers to a sudden, major collapse of asset prices following a long period of market growth and speculative risk-taking. Named after American economist Hyman Minsky and coined by Paul McCulley of PIMCO in 1998, the concept explains why long periods of economic stability inherently build the foundation for severe financial crises.
Climate change is no longer just an environmental issue—it is becoming a financial planning issue. Rising insurance costs, increasing weather-related losses, higher inflation risks, and growing economic uncertainty make protecting capital more important than ever.
The first objective of any sound financial plan is not maximizing returns. It is ensuring that your savings remain available, secure, and able to preserve purchasing power. Liquidity gives you flexibility when unexpected expenses arise, while capital preservation prevents temporary market disruptions from becoming permanent financial losses.
One of the simplest and most effective strategies is to combine a high-yield savings account with a TreasuryDirect account that invests in short-term U.S. Treasury Bills.
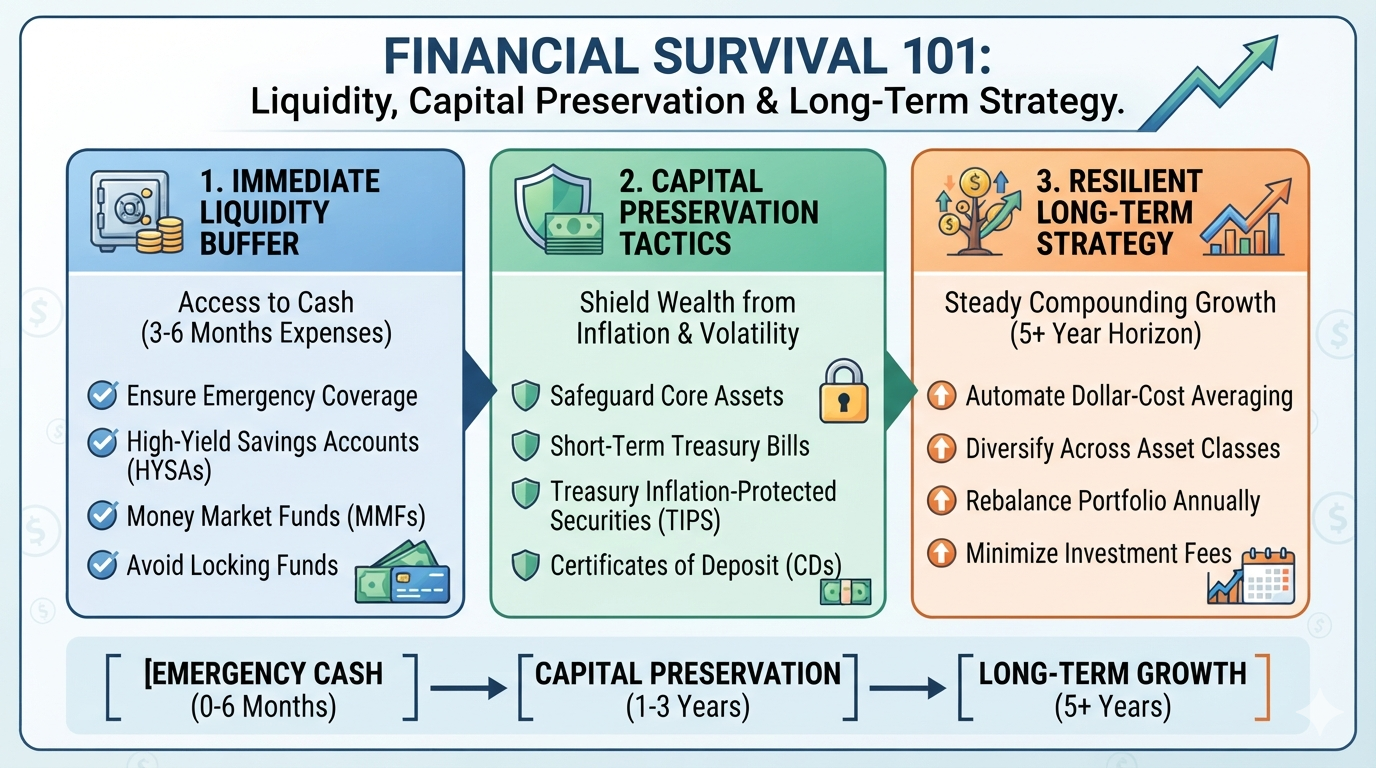
Step 1: Build an Immediate Liquidity Buffer
Every financial plan should begin with readily accessible cash.
Financial advisors generally recommend maintaining three to six months of living expenses in highly liquid accounts that can be accessed immediately during emergencies.
Good options include:
High-Yield Savings Accounts (HYSA)
Money Market Accounts
Money Market Mutual Funds
Unlike long-term investments, these accounts allow you to pay for unexpected expenses without selling stocks or bonds during a market decline.
A high-yield savings account serves as the foundation of your liquidity strategy.
Step 2: Open a TreasuryDirect Account
Once you’ve accumulated several hundred dollars beyond your emergency cash reserve, consider opening a TreasuryDirect account with the U.S. Treasury.
TreasuryDirect allows individuals to purchase Treasury securities directly from the federal government without brokerage fees.
Among the available securities, 4-week Treasury Bills (T-Bills) are particularly attractive for capital preservation.
Why 4-Week Treasury Bills?
Treasury Bills are considered one of the safest investments in the world because they are backed by the full faith and credit of the United States government.
Additional advantages include:
Extremely low default risk
Monthly maturity
High liquidity
Competitive interest rates
Exempt from state and local income taxes
Because they mature every four weeks, they provide exceptional flexibility if economic conditions change.
Understanding How Treasury Bills Work
Treasury Bills are sold through regularly scheduled government auctions.
Unlike traditional savings accounts, T-Bills are purchased at a discount to their face value.
For example:
Purchase Price: $99.60
Face Value at Maturity: $100.00
The $0.40 difference represents your interest earnings.
When the bill matures four weeks later, the Treasury pays the full face value directly into your account.
Funds used to purchase the bill are automatically withdrawn from your linked bank account after the auction.
Why Short-Term Bills Are Safer Than Long-Term Bonds
Many investors assume all Treasury securities carry identical risk.
They do not.
There is a critical distinction between:
Treasury Bills (4-week to 52-week)
Treasury Notes (2-10 years)
Treasury Bonds (20-30 years)
Longer-term bonds are highly sensitive to interest rate changes.
If inflation increases or interest rates rise, existing bonds decline in market value. Investors who need to sell before maturity can lose a substantial portion of their principal.
Short-term Treasury Bills largely avoid this problem.
Because they mature every month, your principal is quickly returned, allowing you to reinvest at current interest rates.
In today’s uncertain economic environment, short-term T-Bills generally provide much greater flexibility and significantly lower interest-rate risk than longer-term government bonds.
Automate the Process
TreasuryDirect allows investors to automatically reinvest maturing Treasury Bills.
For example:
Purchase a 4-week Treasury Bill.
Set it to automatically roll over for up to 12 cycles.
Each month, your principal purchases a new Treasury Bill.
Your interest is deposited back into your bank account.
This creates a largely automated income stream while maintaining monthly access to your capital.
As interest accumulates in your savings account, it can eventually be invested into additional Treasury Bills, creating a gradual compounding effect.
I Bonds: Protection Against Inflation
Another useful Treasury investment is the Series I Savings Bond (I Bond).
Unlike Treasury Bills, I Bonds are specifically designed to protect purchasing power during periods of inflation.
Their interest rate consists of:
A fixed rate
An inflation-adjusted rate that changes every six months
When inflation rises, I Bond yields increase accordingly.
During the inflation surge of 2022, newly issued I Bonds briefly paid annualized rates above 9%, illustrating how they can provide meaningful protection during periods of rapidly rising prices.
Additional advantages include:
Exempt from state and local income taxes
Federal taxes deferred until redemption
Potential education tax benefits if used for qualified higher education expenses and eligibility requirements are met
Because I Bonds cannot be redeemed during their first year and incur a modest interest penalty if redeemed before five years, they are best viewed as a medium-term inflation hedge rather than an emergency fund.
Retirement Accounts
Capital preservation becomes even more important inside retirement accounts.
Money that cannot easily be replaced should generally avoid unnecessary risk.
If you are nearing retirement—or simply wish to reduce volatility—consider investments that prioritize preservation of principal while earning yields comparable to short-term Treasury Bills or other low-risk cash equivalents.
The objective is not to chase maximum returns but to ensure retirement savings remain available when needed.
Building a Layered Financial Strategy
A resilient financial plan consists of three distinct layers.
Time Horizon
Objective
Typical Investments
0–6 Months
Immediate liquidity
High-yield savings accounts, money market funds
1–3 Years
Capital preservation
4-week Treasury Bills, I Bonds, short-term Treasury funds, short-term CDs
10+ Years
Long-term growth
Diversified stock index funds, international equities, retirement accounts
This layered approach allows each dollar to serve a specific purpose rather than forcing every investment to accomplish every objective. While there is no one-size-fits-all allocation, your age, financial obligations, income stability, and future plans should guide how much you keep in each layer.
For individuals following a prudent capital preservation strategy, a sample allocation might look like this:
Age 50 and older: Approximately 80% in immediate liquidity, 15% in capital preservation investments such as short-term Treasury Bills and I Bonds, and 5% in long-term growth investments.
Age 30–50: Approximately 50% in immediate liquidity, 40% in capital preservation, and 10% in long-term growth investments.
Under age 30: Approximately 20% in immediate liquidity, 60% in capital preservation, and 20% in long-term growth investments.
These allocations prioritize financial flexibility and preservation of principal in an era of increasing economic uncertainty. Younger investors generally have more time to recover from financial setbacks and can afford somewhat greater exposure to long-term growth assets, while those approaching or entering retirement often benefit from emphasizing liquidity and protecting accumulated wealth. Individual circumstances vary, however, so these percentages should be viewed as a prudent framework rather than a universal rule.
Long-Term Investing PrinciplesAfter establishing sufficient liquidity and protecting core capital, long-term wealth creation still depends on disciplined planning, risk management, and consistent investing.
Traditional investment principles remain important, but today’s financial environment requires a broader understanding of risk. Investors should consider not only market performance but also their ability to access capital, protect assets, and adapt to changing economic conditions.
Key principles include:
Maintain adequate liquidity and access to cash. A strong financial plan requires readily available funds to handle emergencies, unexpected expenses, and investment opportunities without being forced to sell assets at unfavorable times.
Evaluate insurance exposure. Rising insurance costs, coverage limitations, and changing underwriting standards can significantly affect personal finances and asset values. This applies not only to homeowners insurance but also to auto and rental insurance, which are increasingly influenced by climate-related risks. For example, hail damage is one of the leading causes of auto insurance claims, and the increasing frequency and severity of severe storms can contribute to higher premiums and reduced coverage availability. Renters can also be affected as rising property insurance costs are often passed through in the form of higher rents and fees.
Assess climate-related financial risks. Property location, extreme weather exposure, infrastructure resilience, and changing insurance availability are increasingly important factors in long-term financial planning. Climate risks can influence property values, mortgage decisions, municipal finances, and the overall cost of living in vulnerable areas.
Rebalance periodically. Adjust your portfolio over time to maintain your intended allocation among liquidity, capital preservation, and growth investments.
Minimize investment expenses. Lower fees allow more of your returns to compound over time. Favor cost-efficient investment vehicles such as low-cost index funds and ETFs when appropriate.
Markets will inevitably fluctuate, but disciplined long-term investing, combined with sound risk management and financial flexibility, has historically rewarded patient investors. The goal is not simply to maximize returns—it is to build a resilient financial foundation capable of adapting to changing economic, environmental, and personal circumstances.
Climate Change and Financial Resilience
Climate change introduces new financial risks that previous generations rarely considered.
Increasingly, homeowners and investors must account for:
Rising insurance premiums
More frequent weather-related disasters
Inflationary pressures from supply disruptions
Higher infrastructure costs
Regional declines in real estate values
Greater economic uncertainty
These risks do not necessarily mean financial collapse is imminent. However, they do reinforce the importance of maintaining adequate liquidity and protecting principal. Investors with readily available cash are better positioned to handle emergencies, adapt to changing market conditions, and take advantage of opportunities that arise during periods of economic stress.
Conclusion
Successful investing begins with preserving financial flexibility.
A high-yield savings account provides immediate liquidity. Short-term Treasury Bills offer one of the safest ways to earn competitive returns while protecting principal. I Bonds provide an additional layer of inflation protection for longer-term savings.
Together, these tools create a strong foundation for financial resilience in an increasingly uncertain world.
No investment strategy can eliminate risk entirely, but maintaining liquidity, preserving capital, and investing for long-term growth can help individuals and families navigate economic volatility—including the growing financial challenges associated with climate change—with greater confidence and stability.
Capital preservation has always been a cornerstone of sound financial planning. In periods of heightened economic uncertainty, however, it becomes the overriding priority.
The goal is not to maximize returns at all costs. It is to ensure that you retain enough purchasing power and financial flexibility to navigate whatever comes next.
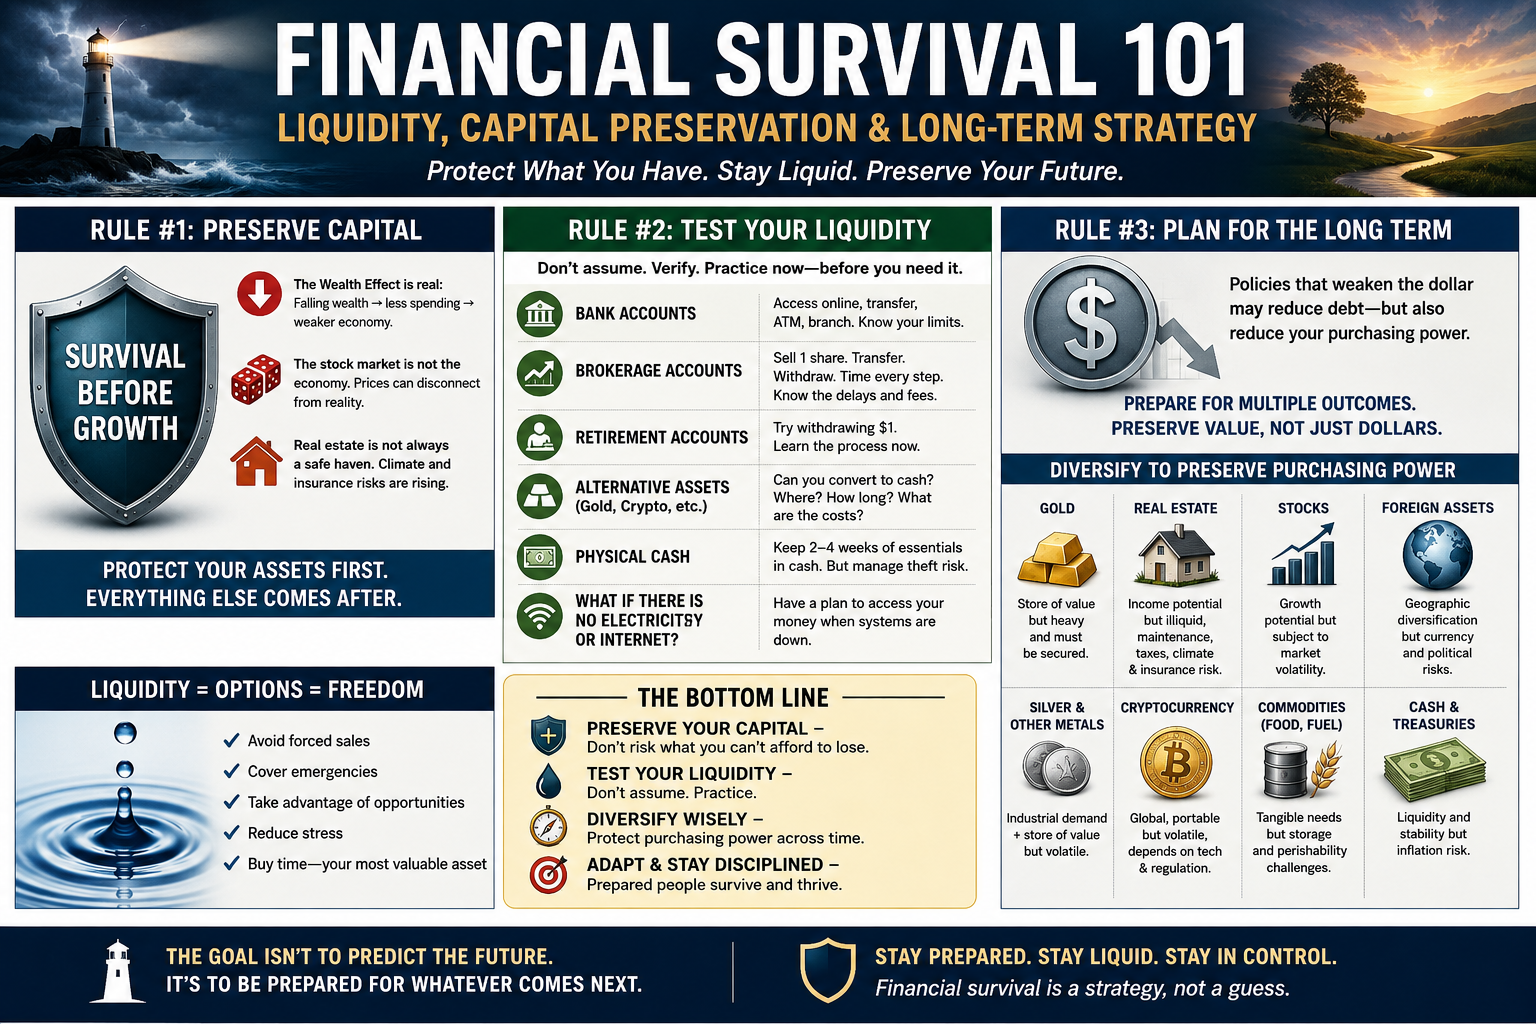
One concept increasingly influencing both Wall Street and Main Street is the Wealth Effect.
When household wealth rises—through higher stock prices, appreciating home values, or growing retirement accounts—people generally feel more confident. They spend more, borrow more, and invest more.
The opposite is equally true.
When people perceive themselves to be poorer, they begin cutting expenses. Vacations are postponed. New cars aren’t purchased. Home renovations are delayed. Restaurants see fewer customers. Businesses experience lower sales, which often leads to reduced hiring and layoffs.
The decline becomes self-reinforcing.
What begins as falling asset prices can eventually slow the broader economy.
The Stock Market Is Not the Economy
One of the biggest mistakes investors make is assuming that the stock market and the economy move together.
Over long periods they are related.
Over shorter periods they often are not.
Modern financial markets are increasingly driven by institutional trading, derivatives, leverage, algorithmic trading, and investor sentiment. Prices can become disconnected from underlying economic fundamentals for extended periods.
That means:
Rising stock prices do not necessarily mean the economy is healthy.
Falling stock prices do not automatically signal economic collapse.
Markets frequently overshoot in both directions.
Investors should avoid making emotional decisions based solely on market movements.
Real Estate Is Not Always a Safe Haven
For generations, real estate has been viewed as one of the safest long-term investments.
That assumption deserves closer examination.
Unlike stocks or bank deposits, real estate is highly illiquid. Selling a property can take weeks or months, and transactions involve significant costs, including commissions, taxes, legal fees, inspections, and financing contingencies.
Climate-related risks are adding another layer of uncertainty.
In many regions, insurance premiums have risen dramatically or insurers have withdrawn from markets altogether. Mortgage lenders are increasingly evaluating climate exposure, flood risk, wildfire danger, and long-term property resilience.
Some coastal communities, wildfire-prone regions, and flood zones are already experiencing declining property values, slower sales, or reduced insurance availability.
Examples include portions of:
California wildfire zones
Coastal Florida
Louisiana
Low-lying Atlantic and Gulf Coast communities
These trends do not mean that all real estate is at immediate risk. Many properties may remain attractive for decades. However, location-specific climate and insurance risks are becoming increasingly important considerations in short- and medium-term financial planning. Over the longer term, climate change is expected to affect virtually all real estate to varying degrees. The nature and severity of those risks will differ by location, but no property is likely to remain entirely insulated from changing climate conditions, rising insurance costs, evolving regulations, or shifting market preferences.
Real estate should no longer be evaluated solely by neighborhood, schools, and appreciation potential. Future insurability, financing availability, infrastructure resilience, and climate exposure are becoming equally important.
Step Two: Liquidity
What Good Are Assets If You Can’t Use Them?
After protecting capital comes a second priority:
Liquidity.
Liquidity measures how quickly an asset can be converted into usable cash without suffering significant losses.
During normal times, liquidity is often taken for granted.
During financial stress, it becomes priceless.
Many investors discover too late that assets they believed were readily available actually require days, weeks, or months to access.
That is why liquidity should be tested—not assumed.
Perform Your Own Liquidity Stress Test
Think of this as a financial fire drill.
You hope you’ll never need it.
But you’ll be grateful you’ve practiced.
Bank Accounts
Can you:
Access funds through online banking?
Use a debit card?
Transfer money electronically?
Withdraw cash from an ATM?
Obtain larger amounts from a local branch?
What is your backup plan if electricity, internet access, or electronic payments become unavailable?
Know your daily withdrawal limits.
Understand your bank’s policies before an emergency occurs.
Brokerage Accounts
Try the complete process:
Sell one share of a stock or ETF.
Transfer the proceeds to your checking account.
Withdraw cash.
Time every step.
Record:
Settlement delays
Transfer times
Bank holds
Fees
Unexpected obstacles
A brokerage balance isn’t liquid until the money reaches your wallet.
Retirement Accounts
Many retirement accounts allow withdrawals under certain circumstances.
Even if taxes or penalties apply, learn the mechanics now.
Understanding the paperwork, timing, and restrictions before an emergency reduces stress later.
Precious Metals
If you own gold or silver, ask yourself:
Where would I sell it?
How quickly could I receive payment?
Would I receive fair market value?
Would payment be immediate?
Owning precious metals is different from converting them into cash.
Practice the process.
Cryptocurrency
Crypto markets operate around the clock, but converting digital assets into spendable cash involves several steps.
Can you:
Sell cryptocurrency?
Transfer proceeds to your bank?
Withdraw physical cash?
What is your backup plan if electricity, internet access become temporarily unavailable?
Test a small transaction.
Don’t wait until markets become volatile.
Cash on Hand
Most financial planners recommend maintaining an emergency reserve.
Consider keeping enough physical cash to cover several weeks of essential expenses while avoiding excessive amounts that create theft or security risks.
Cash remains useful during temporary disruptions to banking networks, power outages, or payment systems.
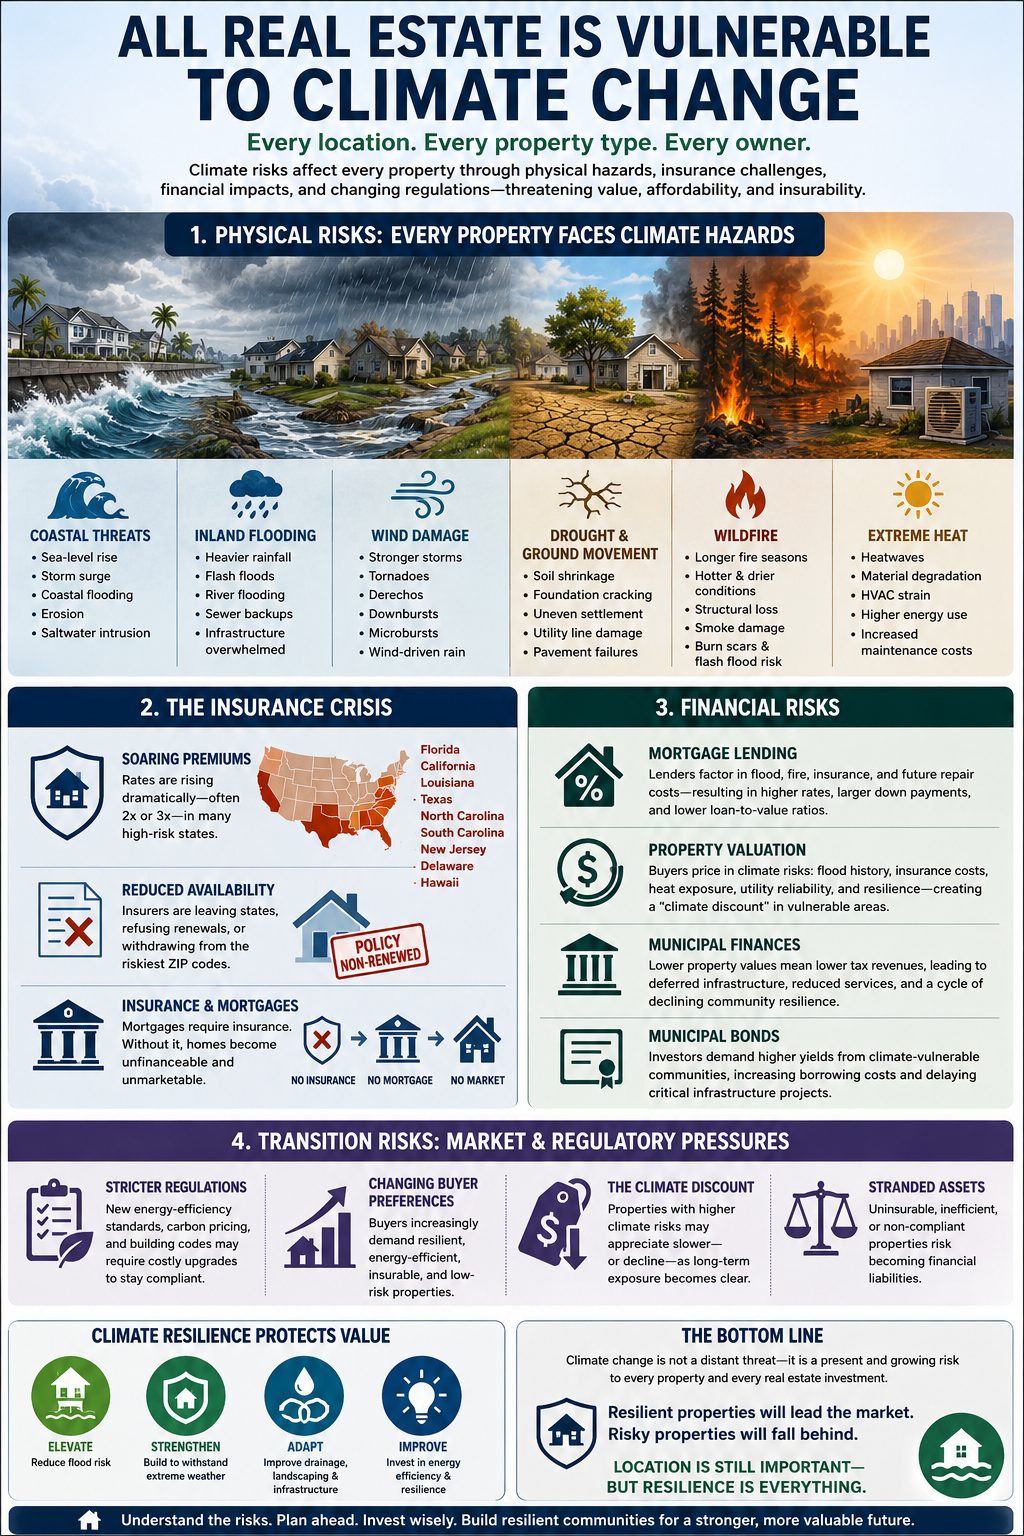
Understanding the Physical, Financial, and Market Risks Facing Property Owners
For generations, real estate has been viewed as one of the safest long-term investments. Land cannot be manufactured, buildings can be improved, and population growth has historically supported rising property values. Climate change is altering many of the assumptions that have underpinned real estate markets for decades.
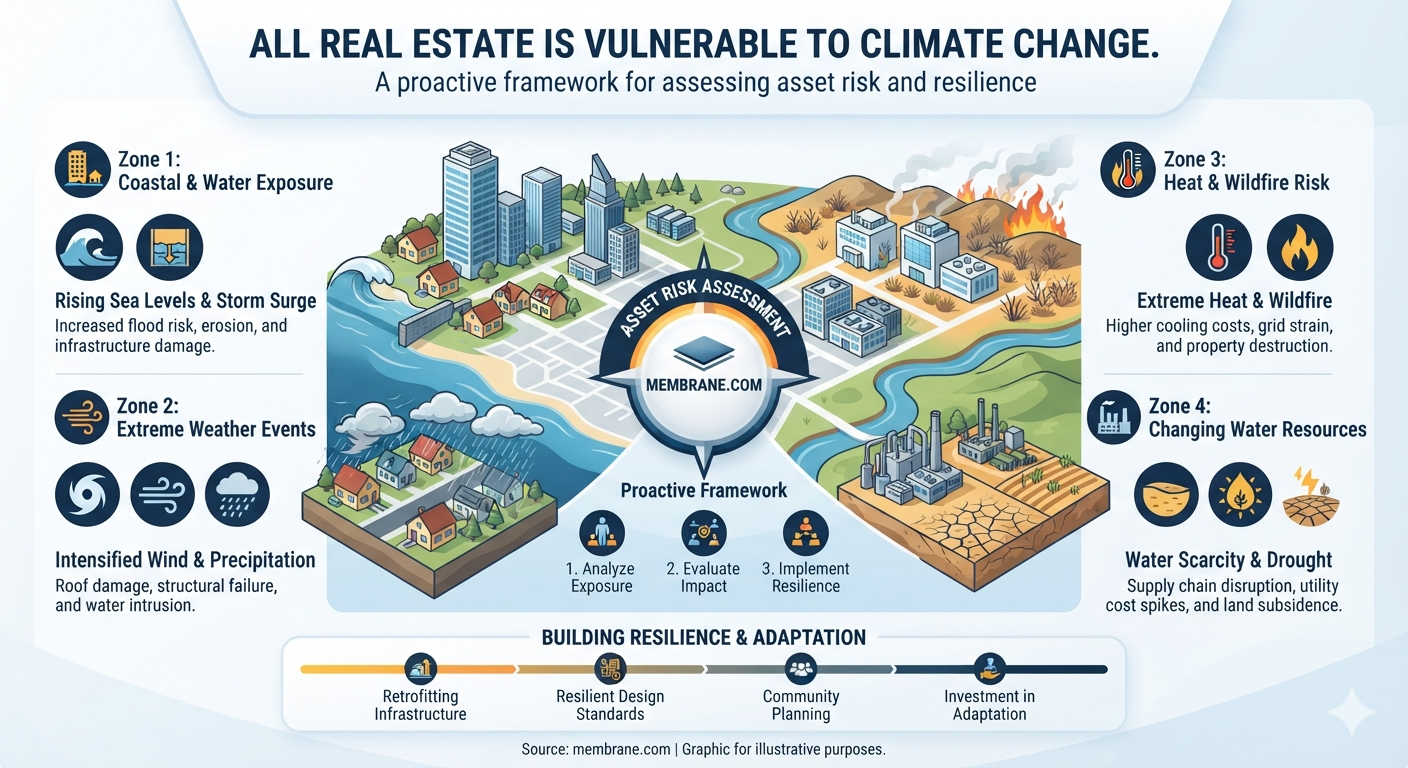
Contrary to popular belief, climate risk is not confined to beachfront homes or wildfire-prone forests. Every property is exposed to climate-related risks, although the specific hazards vary by location. These risks extend far beyond physical damage. They increasingly affect insurance availability, mortgage lending, municipal finances, infrastructure reliability, property values, and long-term market liquidity.
The vulnerability of real estate can be understood through four interconnected categories: physical risks, insurance risks, financial and lending risks, and transition risks.
1. Physical Risks: Every Property Faces Climate Hazards
Climate change is increasing both the frequency and intensity of many weather-related hazards. Every region experiences different threats, but no location is completely immune.
Coastal Regions
Coastal properties face some of the most visible climate risks, including:
Rising sea levels
More frequent nuisance flooding
Stronger storm surges
Accelerated shoreline erosion
Saltwater intrusion into groundwater
Even modest sea-level rise significantly increases flood frequency because storm surges begin from a higher baseline.
Inland Flooding
Many inland communities once considered “safe” are experiencing increasing flood losses.
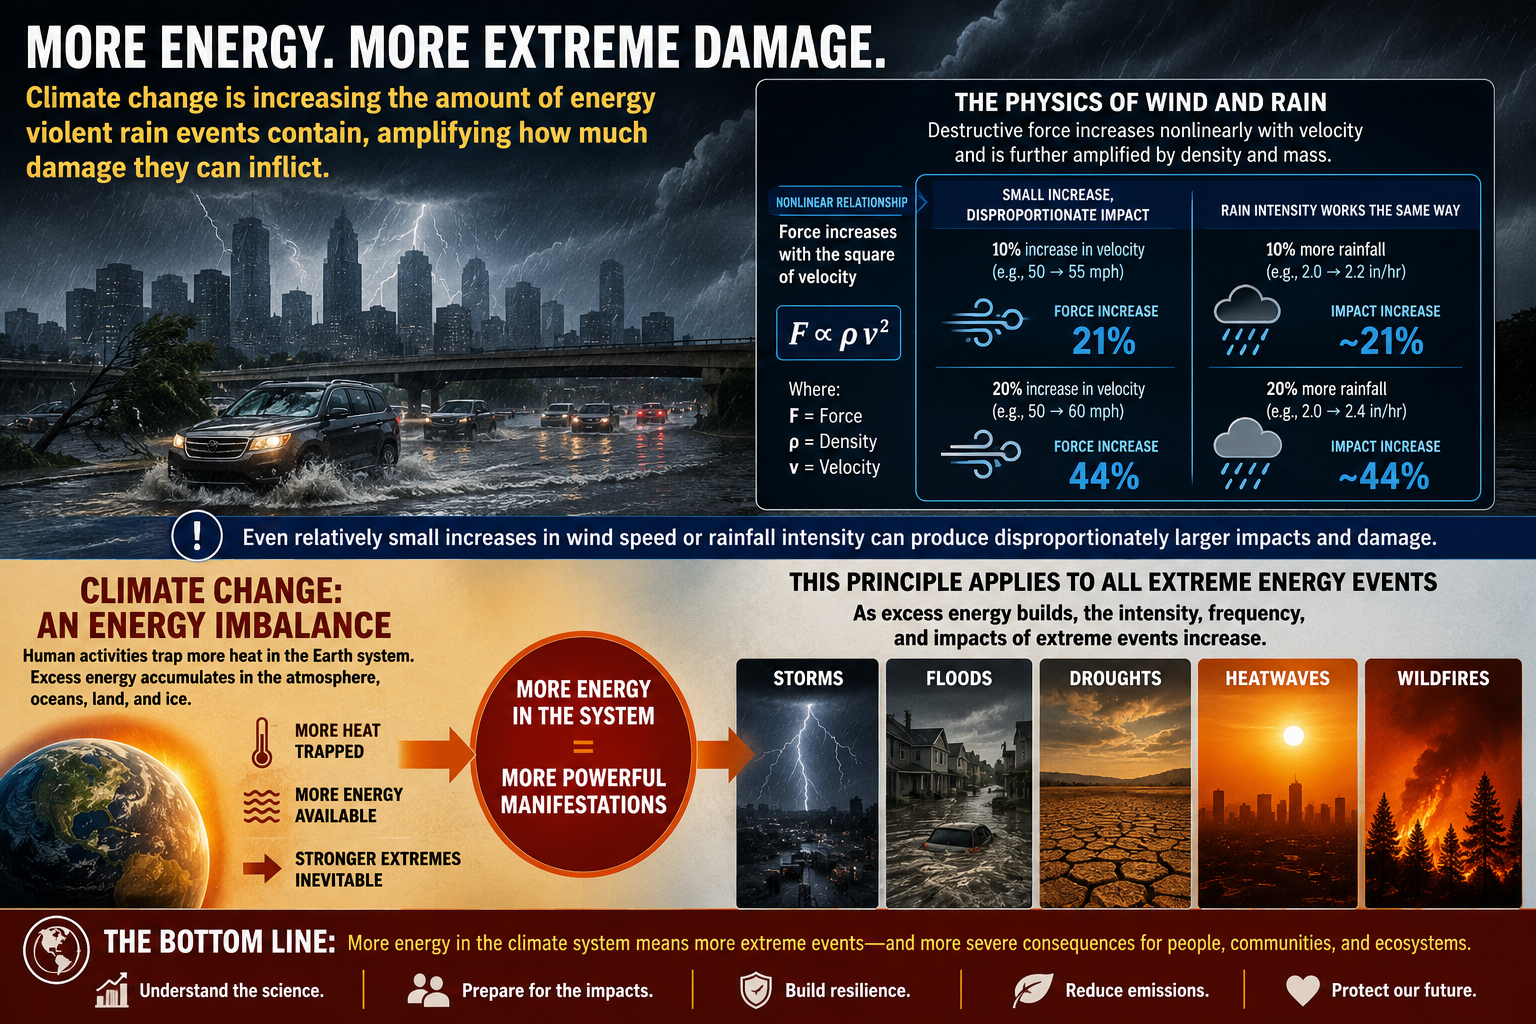
Warmer air holds approximately 7% more water vapor for every 1°C of warming, increasing the potential for intense rainfall events. As storms become more moisture-laden, drainage systems designed for twentieth-century rainfall often become overwhelmed.
Consequences include:
Flash flooding
River flooding
Basement flooding
Sewer backups
Road washouts
Bridge failures
Properties located well outside traditional floodplains are increasingly experiencing damaging floods.
Wind Damage
For much of the United States, wind represents the largest source of insured property losses.
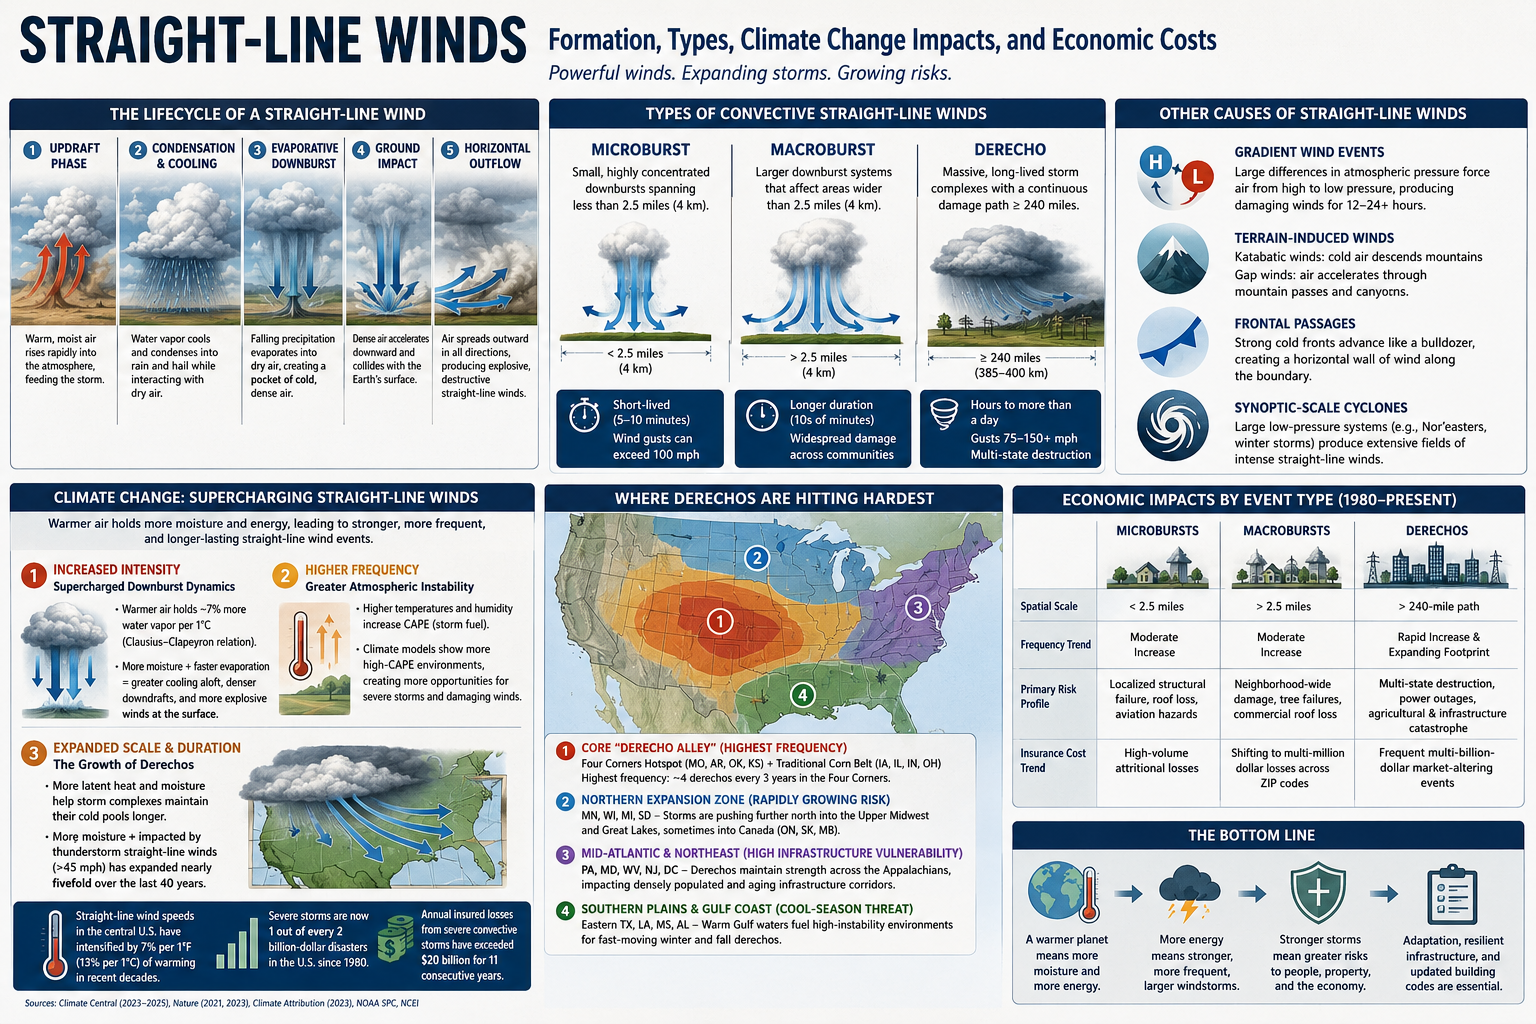
Climate change is increasing atmospheric energy available for:
Severe thunderstorms
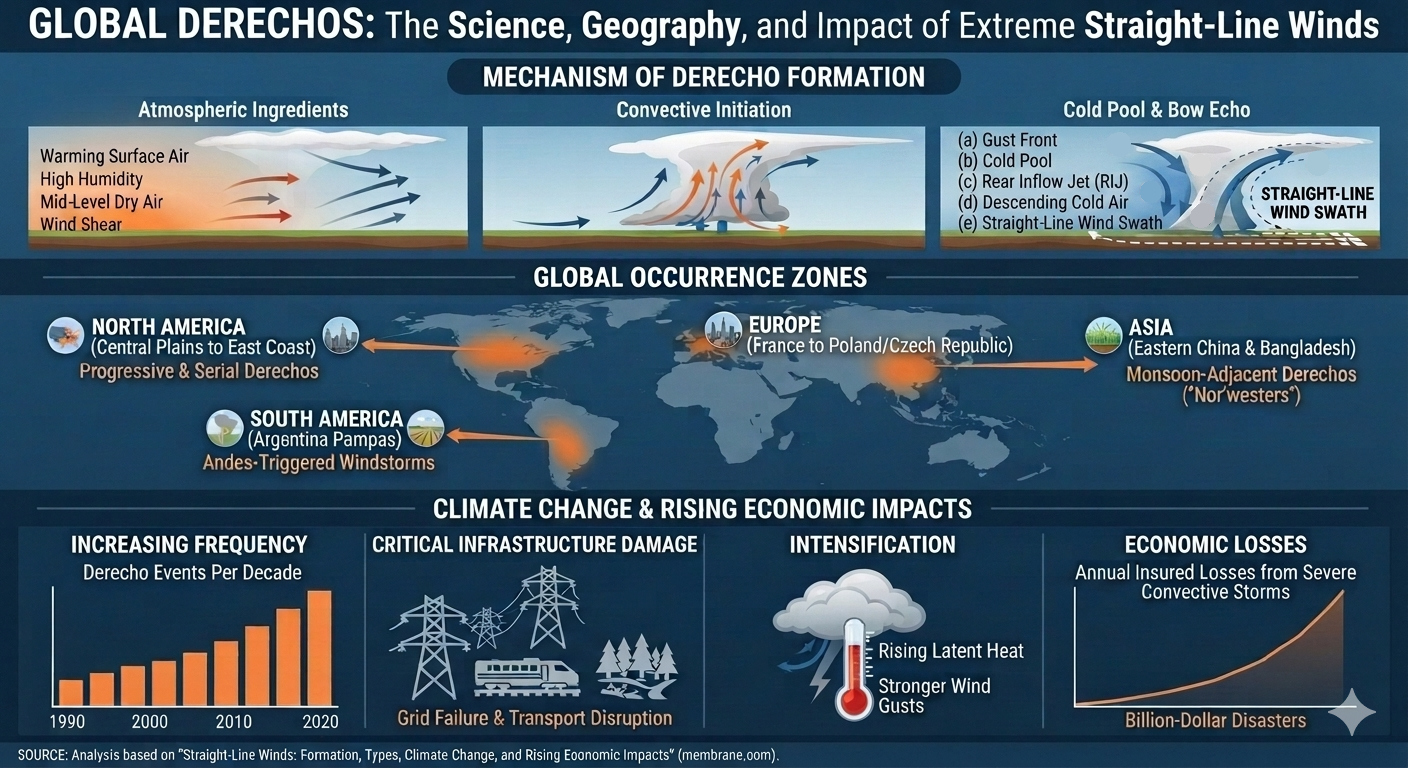
Derechos
Tornado outbreaks
Downbursts
Microbursts
Hurricane wind fields
Roofs, siding, windows, and mature trees are particularly vulnerable. Wind-driven rain often causes damage even when structures remain standing.
Wildfire
Longer fire seasons, hotter temperatures, and more frequent droughts have dramatically expanded wildfire risk.
Wildfires threaten real estate through:
Direct structural destruction
Smoke damage
Utility failures
Water contamination
Long-term reductions in property desirability
Burn scars also increase the likelihood of flash flooding and debris flows during subsequent rainstorms.
Drought and Ground Movement
Extended drought affects soils in complex ways.
Clay-rich soils shrink as they dry, causing:
Foundation cracking
Uneven settlement
Utility line damage
Pavement failures
Conversely, periods of heavy rainfall following drought can produce rapid soil expansion that further stresses structures.
Extreme Heat
Heat affects virtually every building.
Higher temperatures accelerate deterioration of:
Roofing materials
Asphalt pavement
Exterior paints
Sealants
HVAC systems
Buildings require more cooling energy while mechanical systems experience greater wear, increasing maintenance and operating costs.
2. The Insurance Crisis
Insurance is becoming one of the most important climate risks facing property owners.
Historically, insurance spread risk across large geographic regions. As climate-related losses increase, that model is becoming increasingly difficult to sustain.
Rising Premiums
Many homeowners and commercial property owners have experienced substantial premium increases.
States experiencing particularly rapid increases include:
Florida
California
Louisiana
Texas
North Carolina
South Carolina
New Jersey
Delaware
Hawaii
In many communities, insurance costs are rising faster than home values.
Reduced Availability
Some insurers are:
Leaving entire states
Declining to insure specific ZIP codes
Refusing policy renewals
Restricting coverage amounts
Increasing deductibles
As private insurers withdraw, many homeowners are forced into state-sponsored insurers of last resort, which often provide less comprehensive coverage at higher cost.
Most mortgage lenders require continuous hazard insurance throughout the life of the loan.
If insurance becomes unavailable or unaffordable:
Mortgage approvals become more difficult.
Existing homeowners may violate loan requirements.
Buyers qualify for smaller loans.
Market demand declines.
Property values weaken.
Without insurance, many homes effectively become difficult or impossible to finance.
3. Financial Risks Beyond Property Damage
Climate change affects real estate markets even before disasters occur.
Financial institutions increasingly incorporate climate risk into lending and investment decisions.
Mortgage Lending
Banks and mortgage investors evaluate:
Flood exposure
Wildfire risk
Insurance availability
Future repair costs
Local infrastructure resilience
Higher perceived risk may result in:
Larger down payment requirements
Higher interest rates
Reduced loan-to-value ratios
Shorter lending horizons
Properties once viewed as routine collateral may gradually become more difficult to finance.
Property Valuation
Real estate markets depend heavily on expectations of future value.
Buyers increasingly consider:
Flood history
Fire history
Heat exposure
Insurance costs
Utility reliability
Local resilience investments
Two otherwise identical homes may command significantly different prices simply because one carries greater long-term climate risk.
Municipal Finances
Local governments rely heavily on property taxes.
If climate risks reduce property values, municipalities may experience:
Lower tax revenues
Deferred infrastructure maintenance
Reduced public services
Higher municipal borrowing costs
This creates a feedback loop in which deteriorating infrastructure further reduces property values.
Municipal Bonds
Cities and counties finance roads, schools, water systems, and flood-control projects through municipal bonds.
Increasing climate risks may lead investors to demand higher yields from municipalities perceived as vulnerable. Higher borrowing costs can delay infrastructure improvements, making communities even more susceptible to future climate impacts.
Credit rating agencies are paying increasing attention to long-term climate resilience when evaluating municipal creditworthiness.
4. Transition Risks
Not all climate risks arise from weather.
Many result from changes in markets, technology, regulations, and consumer preferences.
Energy Efficiency Requirements
Governments are gradually adopting stricter standards for:
Building efficiency
Carbon emissions
Appliance performance
Building electrification
Energy benchmarking
Older buildings may require expensive upgrades to remain competitive.
Changing Buyer Preferences
Homebuyers increasingly ask questions such as:
Is the property insurable?
How often does it flood?
What are annual insurance costs?
Does the home have backup power?
Is the roof hurricane-rated?
Are energy costs manageable?
These considerations increasingly influence purchasing decisions.
The Emerging Climate Discount
Economists have begun describing the possibility of a “climate discount” or “climate bubble.”
Properties with elevated climate risks may experience slower appreciation—or outright depreciation—as markets increasingly recognize long-term exposure.
Unlike traditional real estate cycles, climate-related devaluation may persist because the underlying physical risks continue to evolve.
5. Climate Risk Is Becoming a Core Investment Risk
Climate change is transforming real estate from an asset class valued primarily by location into one increasingly valued by resilience.
Future property performance will depend not only on neighborhood desirability but also on:
Infrastructure quality
Flood protection
Insurance availability
Building efficiency
Utility reliability
Community adaptation efforts
Investors, lenders, insurers, and homebuyers are already incorporating these factors into financial decisions.
Conclusion
Climate change does not mean that all real estate will suddenly lose value or become uninhabitable. Real estate will remain one of the world’s largest and most important asset classes. However, the factors that determine value are changing.
The greatest risk is not a sudden collapse of the housing market but a gradual repricing of climate risk. Some properties may remain highly desirable for decades, while others may face increasing costs from insurance, maintenance, financing, and regulatory compliance.
Understanding these risks allows homeowners, investors, developers, lenders, and policymakers to make informed decisions. Investments in resilient construction, improved infrastructure, energy efficiency, and thoughtful land-use planning can reduce long-term vulnerability and help preserve property values.
The future of real estate will increasingly be determined not simply by location, location, location, but by location, resilience, and adaptability.
“The greater risk is a gradual degradation of living standards if adaptation is delayed.“
by Daniel Brouse
Introduction
Climate change is often discussed as if it will either produce an imminent societal collapse or, conversely, have little economic consequence. Neither view is supported by the physical science.
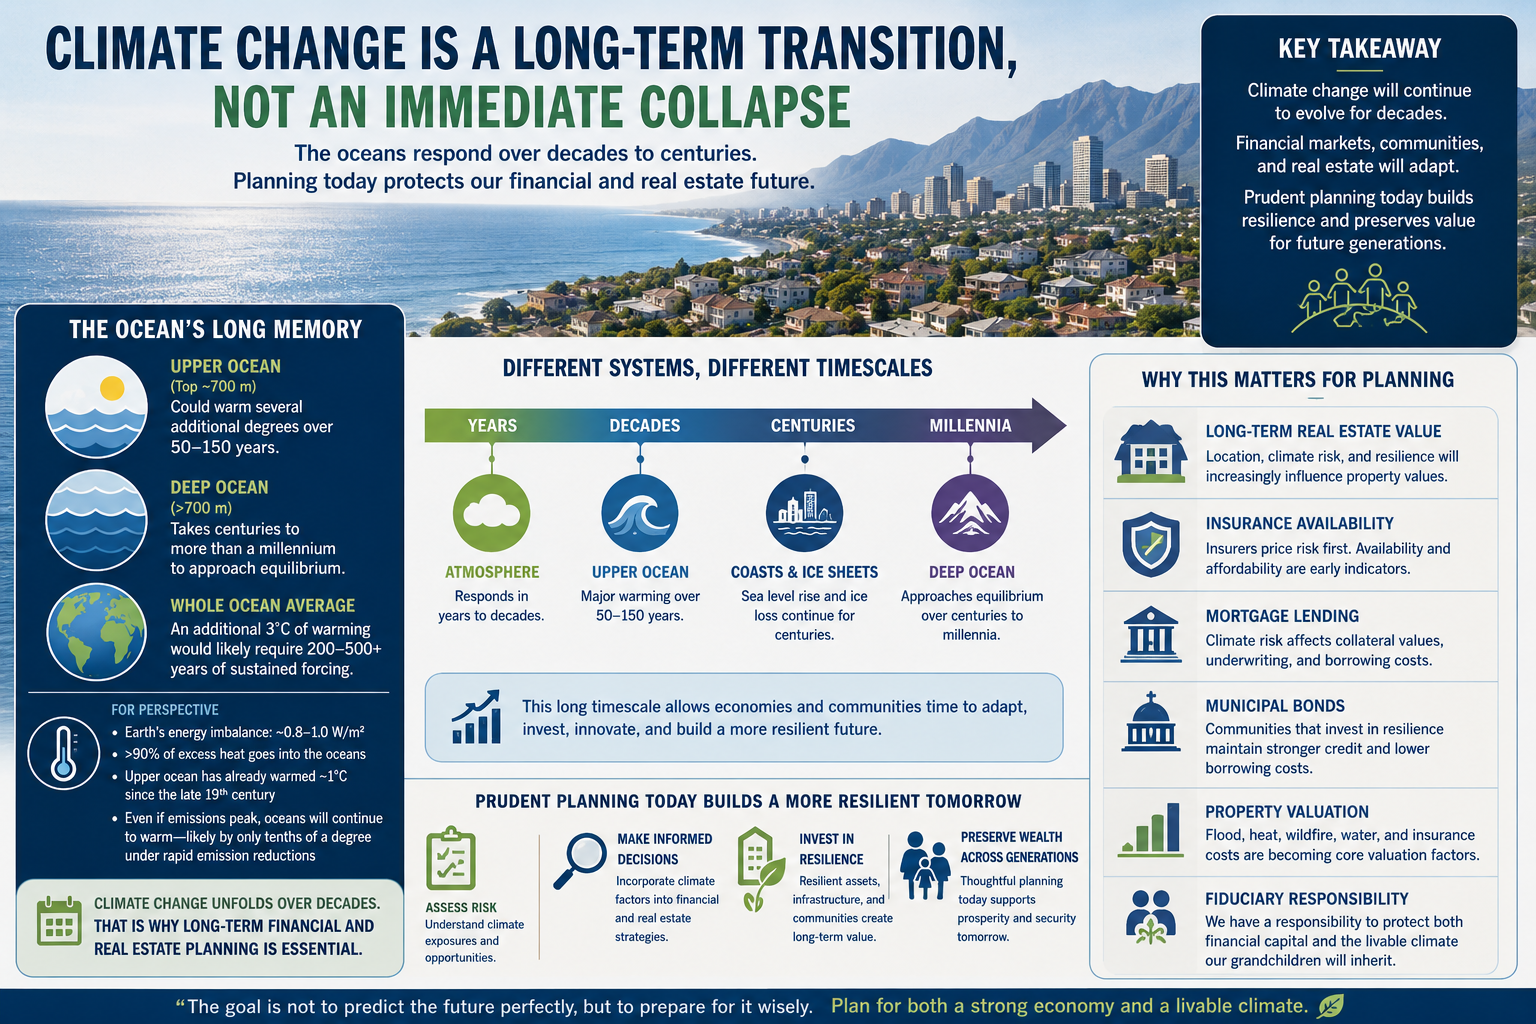
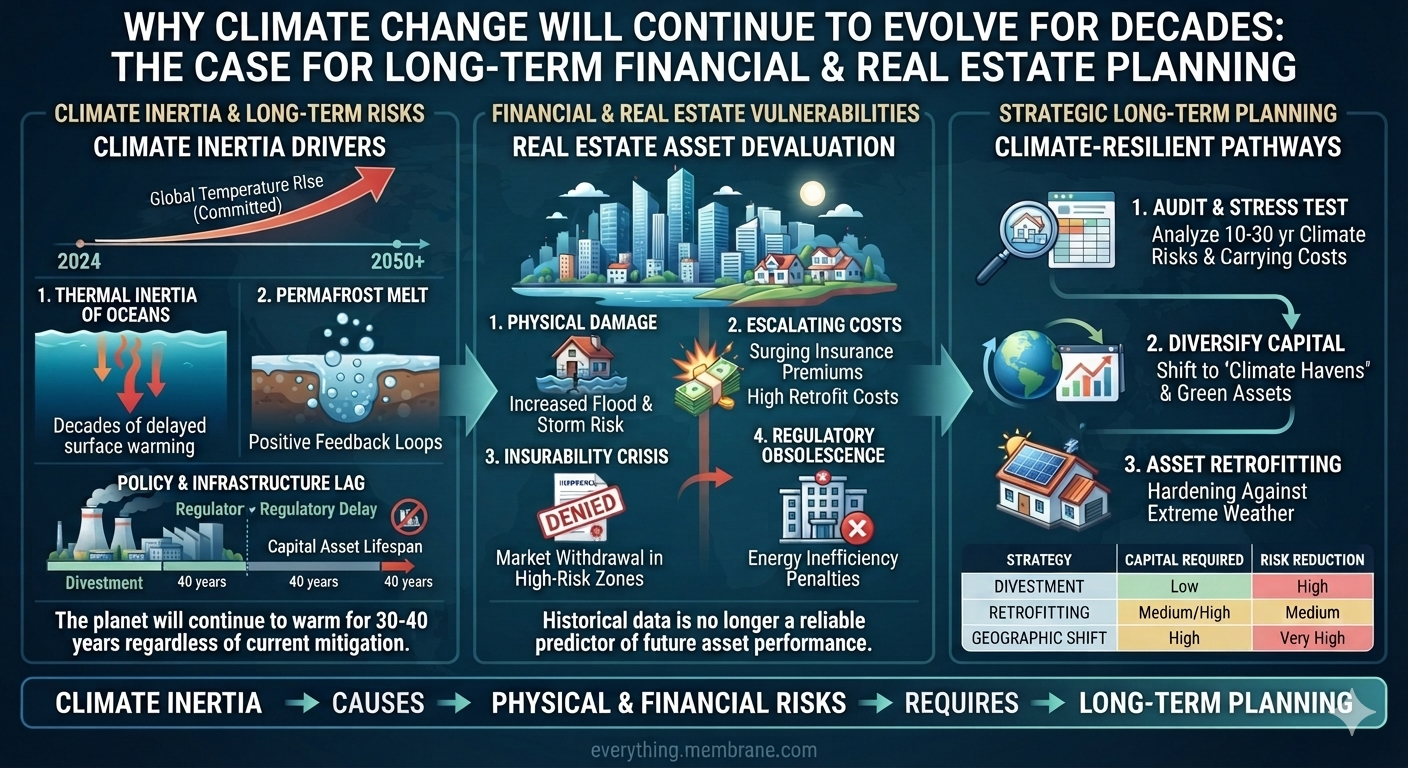
The Earth’s climate system responds over multiple timescales. While the atmosphere reacts relatively quickly to changes in greenhouse gas concentrations, the oceans—the planet’s largest heat reservoir—respond much more slowly. This difference, known as thermal inertia, means that many of the economic consequences of climate change will continue to unfold over decades, regardless of whether emissions peak today or several years from now.
For investors, homeowners, businesses, insurers, lenders, and governments, this distinction is critical. The evidence points not toward an immediate collapse of the global economy, but toward a long period of increasing environmental risks that will progressively reshape financial markets and real estate values.
The Ocean’s Long Memory
If greenhouse gas concentrations remained near current levels long enough to maintain today’s radiative forcing, it would likely take many decades to centuries for the global ocean to warm by an additional 3°C.
Current scientific understanding suggests:
The upper ocean (roughly the top 700 meters) could warm several additional degrees over approximately 50–150 years.
The deep ocean requires centuries to more than a millennium to approach equilibrium.
The global ocean average would likely require several centuries of sustained forcing to warm another 3°C.
More than 90% of Earth’s excess heat enters the oceans, giving the climate system enormous momentum.
Even if atmospheric temperatures stabilize, sea level rise, marine heat waves, glacier retreat, and many coastal impacts continue because the oceans continue redistributing heat.
Climate change therefore behaves less like flipping a switch and more like steering an aircraft carrier. Once underway, changes continue for decades.
Why This Does Not Mean Immediate Economic Collapse
The nonlinear acceleration of climate change does not imply that modern economies disappear within a few years.
Economic systems continually adapt.
History demonstrates remarkable resilience through world wars, financial crises, pandemics, technological revolutions, and natural disasters. Markets evolve. Capital reallocates. Infrastructure is rebuilt. New technologies emerge.
Climate change represents another major structural transformation—not an instantaneous end to economic activity.
The greater risk is a gradual degradation of living standards if adaptation is delayed.
Financial Markets Price Risk—They Do Not Ignore It
Climate risk is becoming another measurable input.
Rather than causing markets to cease functioning, climate change increasingly changes how capital is allocated.
Investment flows are likely to favor:
Resilient infrastructure
Water management
Energy efficiency
Distributed power systems
Climate-resilient agriculture
Advanced building technologies
Adaptation engineering
Markets rarely stop functioning.
They reprice risk.
Mortgage Lending in a Changing Climate
Mortgage lending has always depended upon one fundamental assumption:
The collateral will retain value over the life of the loan.
Most residential mortgages extend 15 to 30 years.
Commercial financing often spans decades.
Those time horizons now overlap directly with accelerating climate risks.
Lenders are increasingly evaluating:
Flood exposure
Wildfire probability
Coastal erosion
Extreme heat
Water availability
Infrastructure resilience
Local adaptation policies
Climate risk is becoming credit risk.
Properties with increasing exposure may experience:
Higher insurance costs
Larger reserve requirements
Lower loan-to-value ratios
Increased underwriting scrutiny
Higher borrowing costs
Conversely, resilient communities with strong infrastructure may receive more favorable financing because they present lower long-term risk.
Climate-informed lending is simply modern risk management.
Insurance Availability May Become the First Market Signal
Insurance companies often detect climate risk before property markets do.
Unlike homeowners, insurers continuously update catastrophe models using the latest observations and loss data.
When risks increase, insurers respond by:
Raising premiums
Increasing deductibles
Restricting coverage
Reducing policy limits
Withdrawing from selected markets
Recent developments in wildfire-prone states, hurricane-exposed coastlines, and hail-prone regions illustrate this trend.
In many communities, insurance affordability—not property damage itself—may become the first significant economic consequence of climate change.
Without affordable insurance:
Mortgage financing becomes more difficult.
Homeownership becomes more expensive.
Property values may weaken.
Municipal tax bases can come under pressure.
Insurance increasingly serves as an early warning system for long-term climate risk.
Municipal Bonds and Local Government Finance
Climate resilience is increasingly becoming a municipal finance issue.
Cities and counties finance much of their infrastructure through municipal bonds.
Those bonds ultimately depend upon:
Stable tax revenues
Economic growth
Reliable infrastructure
Sustainable operating costs
As climate risks increase, municipalities may require additional investments in:
Flood control
Stormwater systems
Water supply
Cooling infrastructure
Grid modernization
Emergency services
Road and bridge resilience
Communities that invest proactively may maintain stronger credit quality over time.
Communities that defer adaptation could face rising maintenance costs, increasing insurance expenses, and pressure on their fiscal health.
For municipal investors, climate resilience increasingly becomes part of long-term credit analysis.
Property Valuation Is Becoming Dynamic
Historically, property valuation focused on:
Location
Schools
Transportation
Employment
Neighborhood quality
Climate is becoming another location characteristic.
Future valuation models will likely incorporate increasing amounts of climate-related information, including:
FEMA flood maps
Local flood history
Heat exposure
Wind risk
Wildfire potential
Water reliability
Insurance costs
Building resilience
Community adaptation investments
Properties will not simply gain or lose value because of climate change.
Rather, markets will increasingly differentiate between properties based on their long-term resilience.
The result is likely to be greater divergence between communities that prepare and those that do not.
Investment Implications
Because climate impacts unfold over decades, financial planning becomes more—not less—important.
Assuming there will be “no economy” several years from now is neither supported by economic history nor by climate science.
Instead, investors should recognize that long-term wealth preservation increasingly depends upon understanding long-term environmental risk.
That includes:
Diversified investment portfolios.
Climate-informed real estate decisions.
Appropriate insurance coverage.
Infrastructure resilience.
Geographic diversification.
Long-term retirement planning.
Planning remains one of the strongest tools available for reducing future financial risk.
Fiduciary Responsibility Across Generations
Every generation inherits assets built by those before it.
Likewise, every generation passes assets forward.
That fiduciary responsibility extends beyond investment portfolios.
It includes:
Homes.
Communities.
Infrastructure.
Businesses.
Natural resources.
Financial systems.
Protecting both environmental and financial capital is not a contradiction.
It is prudent stewardship.
Planning for climate risk is no different than planning for inflation, demographic change, technological disruption, or changing interest rates.
Responsible investors prepare for foreseeable risks rather than assuming those risks either do not exist or will immediately end the economic system.
Conclusion
Climate science indicates that many impacts will continue evolving over decades because Earth’s oceans absorb and release heat slowly.
That long timescale does not support predictions of imminent economic collapse.
Instead, it points toward an extended period during which markets continuously adapt by repricing risk, directing capital toward resilience, and rewarding long-term planning.
For homeowners, investors, lenders, insurers, businesses, and governments, the challenge is not deciding whether there will be an economy.
The challenge is helping shape an economy that is both financially resilient and environmentally sustainable.
The goal is not simply to leave future generations a larger investment portfolio.
It is to leave them both a livable climate and an economy capable of supporting opportunity for decades to come.
Straight-line winds are among the most destructive weather hazards on Earth, yet they often receive far less public attention than tornadoes and hurricanes. These powerful, non-rotational winds can flatten forests, rip roofs from buildings, topple power lines, and cause widespread infrastructure failures. In many cases, the damage resembles the aftermath of a tornado or even a hurricane.
Unlike tornadoes, which concentrate damage within a rotating vortex, straight-line winds can devastate broad regions simultaneously. Wind speeds frequently exceed 70–100 mph and, in extreme cases, may surpass 140 mph. Because they can strike with little warning and affect large geographic areas, straight-line wind events represent a growing hazard to communities, transportation systems, utilities, and the insurance industry.
Emerging research indicates that climate change is altering the atmospheric ingredients that produce severe convective storms. As the atmosphere warms and stores more energy, straight-line wind events are becoming more frequent, more destructive, and increasingly widespread. These changes are transforming severe convective storms into one of the fastest-growing sources of weather-related economic losses in the United States.
What Are Straight-Line Winds?
Straight-line winds are powerful horizontal winds that move outward from their source without rotating. They are most commonly produced by the downward plunge and subsequent outward surge of rain-cooled air from severe thunderstorms.
Unlike tornadoes, which draw air inward and rotate violently around a central vortex, straight-line winds push air exclusively outward along the ground. Despite this difference, their destructive potential can rival or even exceed that of weak-to-moderate tornadoes.
The Lifecycle of a Straight-Line Wind Event
1. Updraft Phase
Warm, moist air rises rapidly into the atmosphere, feeding the development of a growing thunderstorm.
2. Condensation and Cooling
As water vapor ascends, it cools and condenses into rain and hail while interacting with surrounding layers of drier air.
3. Evaporative Downburst Formation
Falling precipitation evaporates into dry air aloft. Because evaporation absorbs heat, it creates a large pocket of extremely cold, dense air.
4. Ground Impact
This dense air mass accelerates downward as a powerful downdraft and collides with Earth’s surface.
5. Horizontal Outflow
Upon impact, the descending air can no longer move downward. Instead, it compresses and surges outward in all directions, producing an explosive burst of destructive straight-line winds.
Classification of Convective Straight-Line Wind Events
Meteorologists classify thunderstorm-generated straight-line winds according to their size and duration.
Microbursts
Microbursts are highly concentrated downbursts spanning less than 2.5 miles (4 km). Although typically lasting only five to ten minutes, they can produce sudden wind gusts exceeding 100 mph and are particularly dangerous because of their intensity and lack of warning.
Macrobursts
Macrobursts are larger downburst systems that spread destruction across areas wider than 2.5 miles (4 km) and often persist significantly longer than microbursts.
Derechos
Derechos are massive, long-lived convective storm systems that produce continuous swaths of wind damage extending at least 240–250 miles (385–400 km). By definition, derechos generate sustained winds of at least 58 mph, with gusts commonly ranging between 75 and 150 mph.
Other Causes of Straight-Line Winds
Although convective downbursts are the most common source of straight-line winds, meteorologists classify any non-rotational horizontal wind as a straight-line wind, regardless of its origin.
Gradient Wind Events
These winds arise from large differences in atmospheric pressure. Air naturally flows from areas of high pressure toward low pressure. When powerful pressure systems are positioned close together, the resulting pressure gradient can accelerate air to damaging speeds. Unlike thunderstorm downbursts that last only minutes, gradient wind events can persist for 12 to 24 hours or longer.
Terrain-Induced Winds
Mountain landscapes frequently create severe straight-line winds.
Katabatic Winds: Cold, dense air descends from elevated plateaus or ice sheets under the influence of gravity, accelerating dramatically before spreading across valleys below.
Examples include:
Santa Ana winds in California
Bora winds in southeastern Europe
Gap Winds: Air masses forced through narrow mountain passes and canyons become compressed and accelerated, producing intense horizontal wind speeds.
Frontal Passages
The leading edge of a strong cold front can generate destructive straight-line winds. As dense cold air advances, it acts like an atmospheric bulldozer, forcing warmer air upward and creating a powerful wall of horizontal wind along the frontal boundary.
Synoptic-Scale Extratropical Cyclones
Large non-tropical low-pressure systems, such as Nor’easters and major winter storms, produce extensive fields of intense straight-line winds through tightly packed pressure gradients extending across hundreds of miles.
Climate Change and the Intensification of Straight-Line Winds
Climate change directly influences the atmospheric variables that fuel severe convective storms, causing thunderstorm-generated straight-line winds to become more frequent, intensely destructive, and geographically expanded.
Research synthesized by Climate Central and peer-reviewed studies published in Nature indicates that straight-line wind speeds across portions of the central United States have already intensified by approximately 7% per 1°F (13% per 1°C) of atmospheric warming during recent decades.
Several physical mechanisms are driving these changes.
The fundamental engine behind a straight-line wind event is the evaporative downburst. Climate change amplifies this process in multiple ways.
Higher Atmospheric Moisture Capacity
According to the Clausius-Clapeyron relationship, a warmer atmosphere can hold approximately 7% more water vapor for every 1°C increase in temperature. This additional moisture allows thunderstorms to contain substantially greater amounts of precipitation.
Enhanced Evaporative Cooling
When this larger volume of precipitation falls through relatively dry layers of air, evaporation occurs more rapidly. The evaporation dramatically cools the descending air, making it denser and heavier than its surroundings.
The greater the temperature contrast between the chilled downdraft and the surrounding environment, the faster the air accelerates downward. The result is a more violent impact at the surface and stronger, more destructive straight-line wind speeds.
Severe convective storms require highly unstable atmospheric conditions.
Elevated Convective Available Potential Energy (CAPE)
Warmer temperatures and increased humidity elevate Convective Available Potential Energy (CAPE), a measure of the energy available for thunderstorm development.
More Severe Storm Environments
Advanced climate models consistently project increases in high-CAPE environments under continued greenhouse gas forcing. These environments provide more opportunities for ordinary thunderstorms to intensify into severe systems capable of producing damaging straight-line winds.
3. Expanded Scale and Duration: The Growth of Derechos
Climate change also appears to be altering the longevity and geographic footprint of large convective systems.
Longer-Lived Storm Complexes
A warmer atmosphere contains greater amounts of latent heat and moisture, enabling storm systems to maintain their rain-cooled cold pools for longer periods. Because these cold pools drive storm propagation, straight-line wind events can persist over hundreds of miles.
Fivefold Geographic Expansion
Research summarized by Climate Attribution indicates that the total area affected by thunderstorm-generated straight-line winds exceeding 45 mph has expanded nearly fivefold during the past forty years. Regions farther north and east that historically experienced fewer severe wind events are increasingly experiencing high-intensity derecho systems.
The Severe Convective Storm Crisis
The financial consequences of straight-line winds have fundamentally changed since 1980. Driven by climate change, expanding development patterns, and inflation, severe convective storms have become the most frequent billion-dollar disaster category in the United States.
According to Climate Central, severe storms now account for approximately one out of every two billion-dollar weather disasters recorded since 1980. Annual insured losses from severe convective storms that generally remained below $5 billion during the 1980s have evolved into an eleven-year streak of annual losses exceeding $20 billion.
Comparing Straight-Line Wind Types and Their Economic Impacts
Neighborhood-wide damage and extensive tree failures
Multi-state infrastructure destruction and widespread power outages
Insurance Cost Trend
High-volume attritional losses
Increasing multi-million-dollar localized losses
Frequent multi-billion-dollar catastrophe events
Economic Impacts by Event Type
Microbursts and Macrobursts: The Aggregate Loss Problem
Microbursts and macrobursts generally function as localized “attritional losses” for the insurance industry. Individually, most events do not exceed catastrophe thresholds. However, their increasing frequency means they collectively generate billions of dollars in annual claims.
As residential development has expanded into previously rural areas, localized downbursts increasingly strike populated communities. The financial impact often manifests through:
Roof replacements
Siding damage
Broken windows
Vehicle losses
Fallen tree claims
Localized business interruptions
Although these events rarely dominate national headlines, their cumulative economic impact has become enormous.
Derechos: The Multi-Billion-Dollar Market Shifters
Derechos represent the fastest-growing financial threat among straight-line wind events.
Geographic Expansion
Greater atmospheric moisture allows derecho complexes to maintain their structure over much longer distances. Storms increasingly extend into regions where infrastructure and housing stock were not designed to withstand sustained horizontal winds of 80–110 mph.
Hurricane-Scale Damage
Events such as the 2020 Midwest Derecho, which caused more than $11 billion in damages, demonstrated that a single modern derecho can inflict destruction comparable to that of a major landfalling hurricane.
Consequences frequently include:
Regional power grid failures
Agricultural devastation
Widespread commercial losses
Transportation disruptions
Long-duration business interruptions
Extensive residential destruction
Geographic Shifts in Derecho Risk: Expanding Beyond Traditional Boundaries
The United States Midwest and the Corn Belt are experiencing the most severe impacts and greatest geographic expansion associated with intensifying derechos. Although a climatological “hot zone” for these storms has long existed in the central United States, climate change appears to be altering the environmental conditions that govern their formation and propagation.
Warmer atmospheric temperatures, increased moisture availability, and persistent summer heat domes are creating environments capable of sustaining larger and longer-lived convective systems. As a result, regions that historically experienced relatively infrequent derecho activity are increasingly facing severe straight-line wind events with multi-billion-dollar consequences.
1. The Core “Derecho Alley”: Highest Frequency and Agricultural Exposure
Similar to the nation’s Tornado Alley, a region often referred to as Derecho Alley experiences the highest baseline concentration of derechos in North America, averaging approximately one major event each year.
The Four Corners Hotspot
The area encompassing:
Southwest Missouri
Northwest Arkansas
Northeast Oklahoma
Southeast Kansas
records the highest historical frequency of derechos, averaging roughly four major events every three years.
The Traditional Corn Belt
Immediately east lies the traditional Corn Belt, including:
Iowa
Illinois
Indiana
Ohio
These states possess extensive flat terrain and some of the world’s most productive agricultural land. The lack of significant topographic barriers allows derecho complexes to accelerate and maintain their structure over hundreds of miles with minimal disruption.
The consequences can be enormous. A single derecho may flatten millions of acres of corn and soybeans within hours, producing severe agricultural losses, disrupting supply chains, damaging grain storage and transportation infrastructure, and generating billions of dollars in economic damages.
2. The Northern Expansion Zone: A Rapidly Growing Risk
As atmospheric warming and persistent summer heat increasingly extend farther north, states that once viewed derechos as rare anomalies are experiencing a growing number of severe events.
Impacted States
Minnesota
Wisconsin
Michigan
South Dakota
Emerging Trends
Strengthening high-pressure systems and expanding zones of atmospheric instability are supporting derecho development farther into the Upper Midwest and Great Lakes regions. Some events are now maintaining sufficient intensity to continue into Canada, affecting:
Ontario
Saskatchewan
Manitoba
This northward expansion represents one of the clearest examples of shifting severe weather boundaries in a warming climate.
3. The Mid-Atlantic and Northeast: High Infrastructure Vulnerability
Although derechos occur less frequently in the eastern United States than in the Plains and Midwest, their societal and economic impacts are often disproportionately large.
Impacted States
Pennsylvania
Maryland
West Virginia
New Jersey
Washington, D.C.
Emerging Trends
Historically, the Appalachian Mountains often weakened convective systems moving eastward. However, recent events suggest that increasingly energetic storm complexes are better able to maintain their structural integrity while crossing the mountains.
As a result, damaging straight-line winds are increasingly reaching densely populated metropolitan corridors of the Mid-Atlantic and Northeast.
The consequences include:
Large-scale electrical grid failures
Widespread tree damage
Transportation disruptions
Telecommunications outages
Extensive residential and commercial property losses
Because much of the region’s electrical and transportation infrastructure is decades old and designed for historical wind conditions, vulnerability to major derecho events remains exceptionally high.
4. The Southern Plains and Gulf Coast: The Cool-Season Threat
Approximately 70 percent of all derechos occur during the warm season between May and August. However, a secondary corridor remains active during autumn and winter.
Impacted States
Eastern Texas
Louisiana
Mississippi
Alabama
Emerging Trends
The Gulf of Mexico is supplying increasingly warm and moisture-rich air masses later into the year. These conditions can create highly unstable environments even during winter months, supporting the development of fast-moving cool-season derechos.
Because communities generally associate severe convective storms with spring and summer, winter derechos often arrive with lower public awareness and preparedness, increasing the potential for widespread impacts.
A Global Phenomenon
Although North America experiences some of the world’s most powerful and well-documented derechos, these storms are not unique to the United States. Derecho-like convective systems occur on nearly every continent and are increasingly being recognized in:
Central Europe
Eastern Asia
The subtropical plains of South America
As the global atmosphere continues to warm and store more moisture and energy, researchers are increasingly investigating whether the environmental conditions that support long-lived convective windstorms are becoming more common in regions that historically experienced them only rarely.
The expanding geographic footprint of derechos underscores a central lesson of climate science: severe weather hazards are not remaining stationary. As atmospheric energy increases, the boundaries of extreme events are shifting, exposing new populations, infrastructure, and economic systems to risks that were once considered geographically improbable.
Insurance Industry Responses
Global insured losses from severe convective storms are increasing at an estimated average annual rate of approximately 9%, substantially exceeding the growth rate of losses from other natural catastrophes.
In response, insurers are rapidly restructuring coverage across many regions of the United States.
Traditional policies that once contained flat-dollar wind deductibles are increasingly being replaced by percentage-based wind and hail deductibles ranging from 1% to 5% of a home’s insured value. These changes shift thousands of dollars of immediate disaster costs directly onto homeowners and businesses.
The insurance industry increasingly recognizes straight-line wind events not as isolated weather anomalies but as an emerging systemic risk requiring substantial adjustments in underwriting practices, pricing models, and catastrophe exposure management.
Conclusion: More Energy in the Atmosphere Means More Extreme Winds
Straight-line winds demonstrate a fundamental principle of climate physics: a warmer world is a more energetic world.
As greenhouse gases trap additional heat, the atmosphere stores more moisture and potential energy, creating increasingly favorable conditions for severe convective storms. The result is an environment capable of producing stronger downbursts, more frequent severe thunderstorms, and larger, longer-lived derecho systems.
Climate change does not cause any individual straight-line wind event in isolation. However, it is increasingly altering the environmental ingredients that govern these storms by increasing atmospheric moisture, elevating instability, and supporting more persistent convective systems.
The consequences extend well beyond meteorology. Straight-line winds are becoming a growing challenge for public safety, infrastructure resilience, electrical grid reliability, insurance markets, and building design standards. As the climate system continues to warm, understanding and preparing for these increasingly energetic wind events will become essential for protecting communities and reducing future economic losses.
What are the climate risks where you live?
Many people are surprised to learn that their greatest weather-related risk is often wind damage. Wind and hail damage are among the most common homeowners insurance claims in the United States, accounting for roughly 40% of all property damage claims.
Standard homeowners policies from major insurers generally cover wind damage under dwelling and personal property coverage. These claims can include repairs for roof and shingle damage, siding damage, structural failures, and damage caused by wind-driven debris such as fallen trees.
However, homeowners in high-risk areas—such as coastal regions and “Tornado Alley”—may face separate windstorm deductibles. Unlike a standard fixed deductible (for example, $1,000), these deductibles are often calculated as a percentage of the home’s insured value, typically ranging from 1% to 5%.
“Climate change is increasing the amount of energy violent rain events contain, amplifying how much damage they can inflict.”
The physics of wind and rain are important to understand: their destructive force increases nonlinearly with velocity and is further amplified by density and mass. Even relatively small increases in wind speed or rainfall intensity can produce disproportionately larger impacts and damage.
This principle applies to all extreme energy events. At its core, climate change is an energy imbalance. As excess heat accumulates within the Earth system, more energy becomes available to drive storms, floods, droughts, heatwaves, and wildfires. As the energy intensifies, so do its manifestations.