Climate change is making water security impossible to ignore. You don’t need a scientific report to see it—just look out your window. Floods, droughts, shrinking reservoirs, and increasing competition for freshwater are becoming part of everyday life.
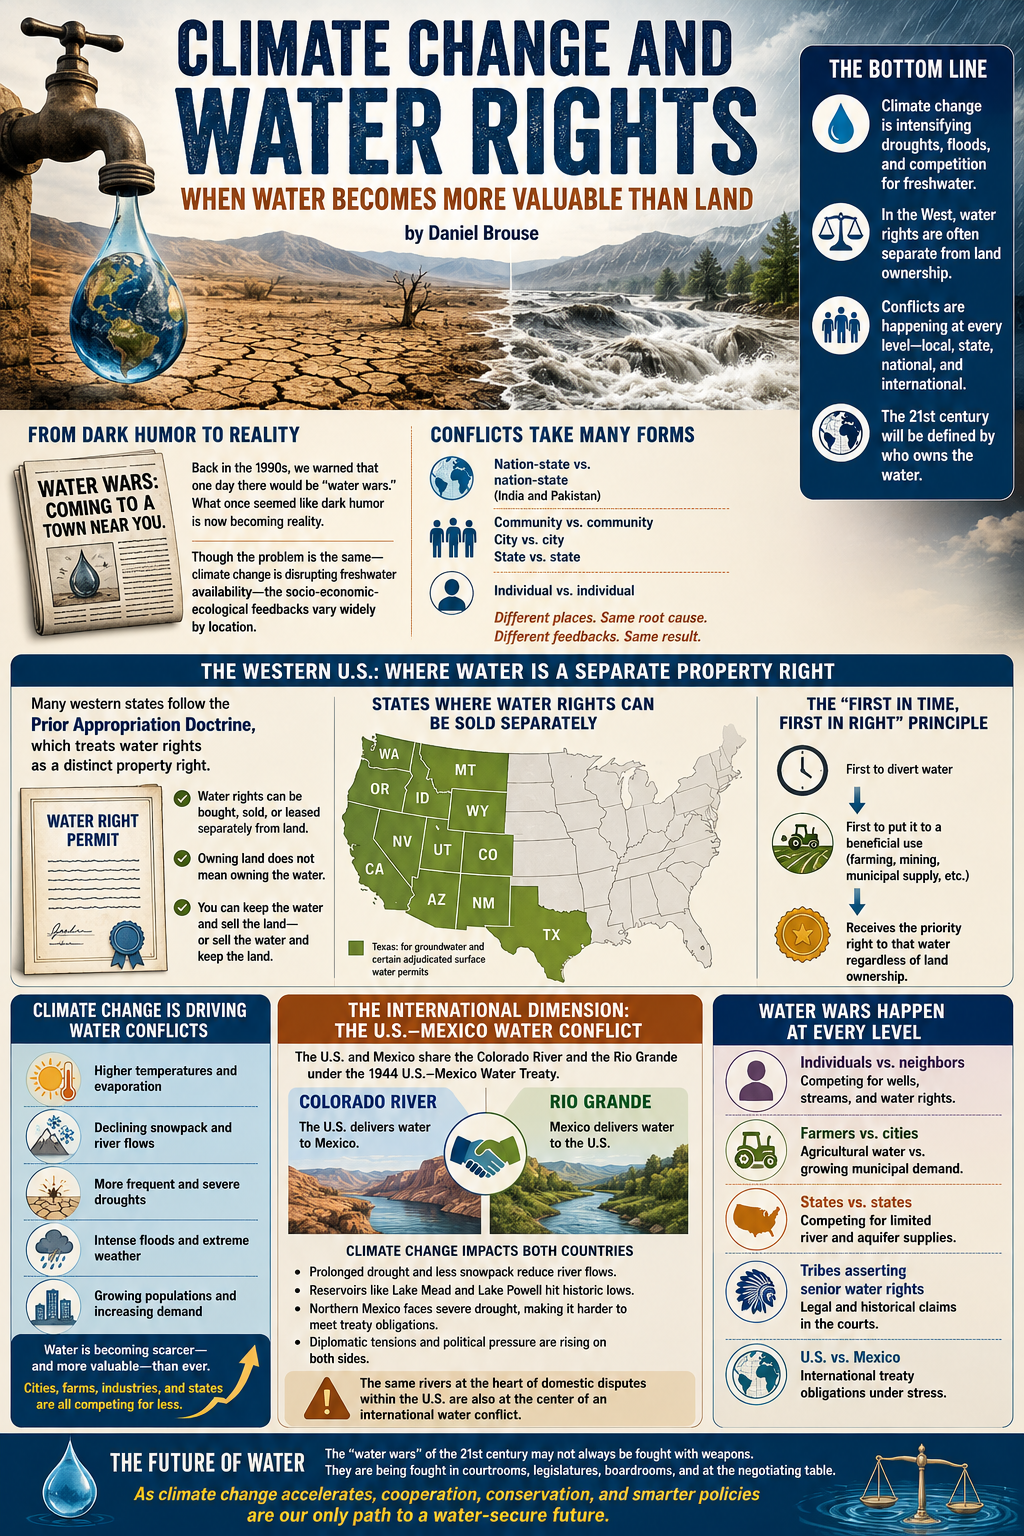
Back in the 1990s, we warned that one day there would be “water wars.” We jokingly wrote headlines like, “Water Wars: Coming to a Town Near You.” Unfortunately, what once seemed like dark humor is steadily becoming reality.
The underlying problem is the same everywhere: climate change is disrupting the availability of freshwater. However, the resulting socio-economic and ecological feedbacks vary dramatically depending on geography, politics, and legal systems. In some regions, conflicts arise between nations, such as India and Pakistan over shared river systems. In others, disputes occur between neighboring communities, businesses, or even individual property owners.
The western United States provides one of the clearest examples of these emerging water conflicts. Unlike most of the eastern United States, many western states treat water rights as separate from land ownership.
Water Rights Are Not Always Property Rights
In much of the western United States, water rights can be bought, sold, or leased independently of the land itself. These states generally follow the Prior Appropriation Doctrine, a legal framework that treats water rights as a distinct form of property.
Under this system, owning land does not necessarily mean owning the water that flows across or beneath it. Likewise, someone can retain ownership of valuable water rights even after selling the associated land.
States Where Water Rights Can Be Sold Separately
States that commonly allow water rights to be severed from real estate include:
Colorado
Arizona
California
Nevada
New Mexico
Utah
Wyoming
Montana
Idaho
Washington
Oregon
Texas (for groundwater and certain adjudicated surface water permits)
The “First in Time, First in Right” Principle
These states generally operate under the principle of “first in time, first in right.”
The first individual or entity to divert water and put it to a legally recognized beneficial use—such as agriculture, mining, industry, or municipal supply—receives a priority right to continue using that water.
Because the right is tied to beneficial use rather than land ownership, water rights become a separate economic asset. A farmer, for example, may sell a ranch while retaining the associated water rights, or sell those rights to a nearby city while continuing to own the land.
Climate Change Is Increasing the Value of Water
As climate change intensifies droughts, reduces snowpack, alters river flows, and increases evaporation, freshwater is becoming an increasingly scarce resource. In many regions, water rights are appreciating faster than the land they once served.
Cities are purchasing agricultural water rights to supply growing populations. Farmers compete with municipalities, industries, and neighboring states for limited supplies. Rivers that once flowed year-round now run seasonally, while reservoirs experience historic lows followed by damaging floods.
The result is an expanding marketplace where water is increasingly treated as a financial asset rather than simply a natural resource.
The Future of Water Conflicts
The “water wars” we predicted decades ago have already begun. They may not always resemble armed conflicts between nations. More often, they take the form of lawsuits, interstate compacts, regulatory battles, infrastructure disputes, and competition between agriculture, industry, municipalities, and environmental interests.
As climate change accelerates, freshwater will become one of the defining economic and political issues of the 21st century. In many regions, the question will no longer be who owns the land—it will be who owns the water.
The International Dimension: The U.S.–Mexico Water Conflict
The western United States is not only experiencing domestic “water wars” between states, cities, farmers, and industries—it is also involved in an increasingly contentious international dispute with Mexico over many of the same river systems.
The conflict centers primarily on the Colorado River and the Rio Grande, which are governed by the 1944 U.S.–Mexico Water Treaty. Under the treaty, the United States delivers water from the Colorado River to Mexico, while Mexico provides water from tributaries feeding the Rio Grande to the United States.
For decades, the agreement functioned reasonably well because both countries generally had sufficient water supplies. Climate change has dramatically altered that equation.
Prolonged drought, declining snowpack in the Rocky Mountains, higher temperatures, and increased evaporation have reduced river flows throughout the American Southwest. Reservoirs such as Lake Mead and Lake Powell have reached historically low levels, forcing difficult decisions about how increasingly scarce water should be allocated.
At the same time, northern Mexico has experienced severe drought, making it difficult to meet its treaty obligations to deliver water to the United States. The resulting shortages have led to diplomatic disputes, political pressure, and growing tensions between agricultural users, municipalities, and federal governments on both sides of the border.
What makes this conflict particularly significant is that it is driven by the very same rivers already at the center of domestic disputes within the United States. States such as California, Arizona, Nevada, Colorado, New Mexico, and Texas are competing with one another for diminishing supplies while simultaneously relying on international agreements that are becoming more difficult to satisfy under a changing climate.
In effect, the Colorado River and Rio Grande now support multiple layers of competition:
Individuals versus neighboring landowners.
Farmers versus rapidly growing cities.
States versus other states.
Native American tribes asserting senior water rights.
The United States versus Mexico under international treaty obligations.
As climate change continues to reduce the reliability of freshwater supplies, these overlapping legal, economic, and political conflicts are likely to intensify. The future of water management will require not only engineering and conservation but also new approaches to interstate and international cooperation. The “water wars” of the 21st century are no longer a prediction—they are unfolding simultaneously at the local, state, national, and international levels.
Understanding the Physical, Financial, and Market Risks Facing Property Owners
For generations, real estate has been viewed as one of the safest long-term investments. Land cannot be manufactured, buildings can be improved, and population growth has historically supported rising property values. Climate change is altering many of the assumptions that have underpinned real estate markets for decades.
Contrary to popular belief, climate risk is not confined to beachfront homes or wildfire-prone forests. Every property is exposed to climate-related risks, although the specific hazards vary by location. These risks extend far beyond physical damage. They increasingly affect insurance availability, mortgage lending, municipal finances, infrastructure reliability, property values, and long-term market liquidity.
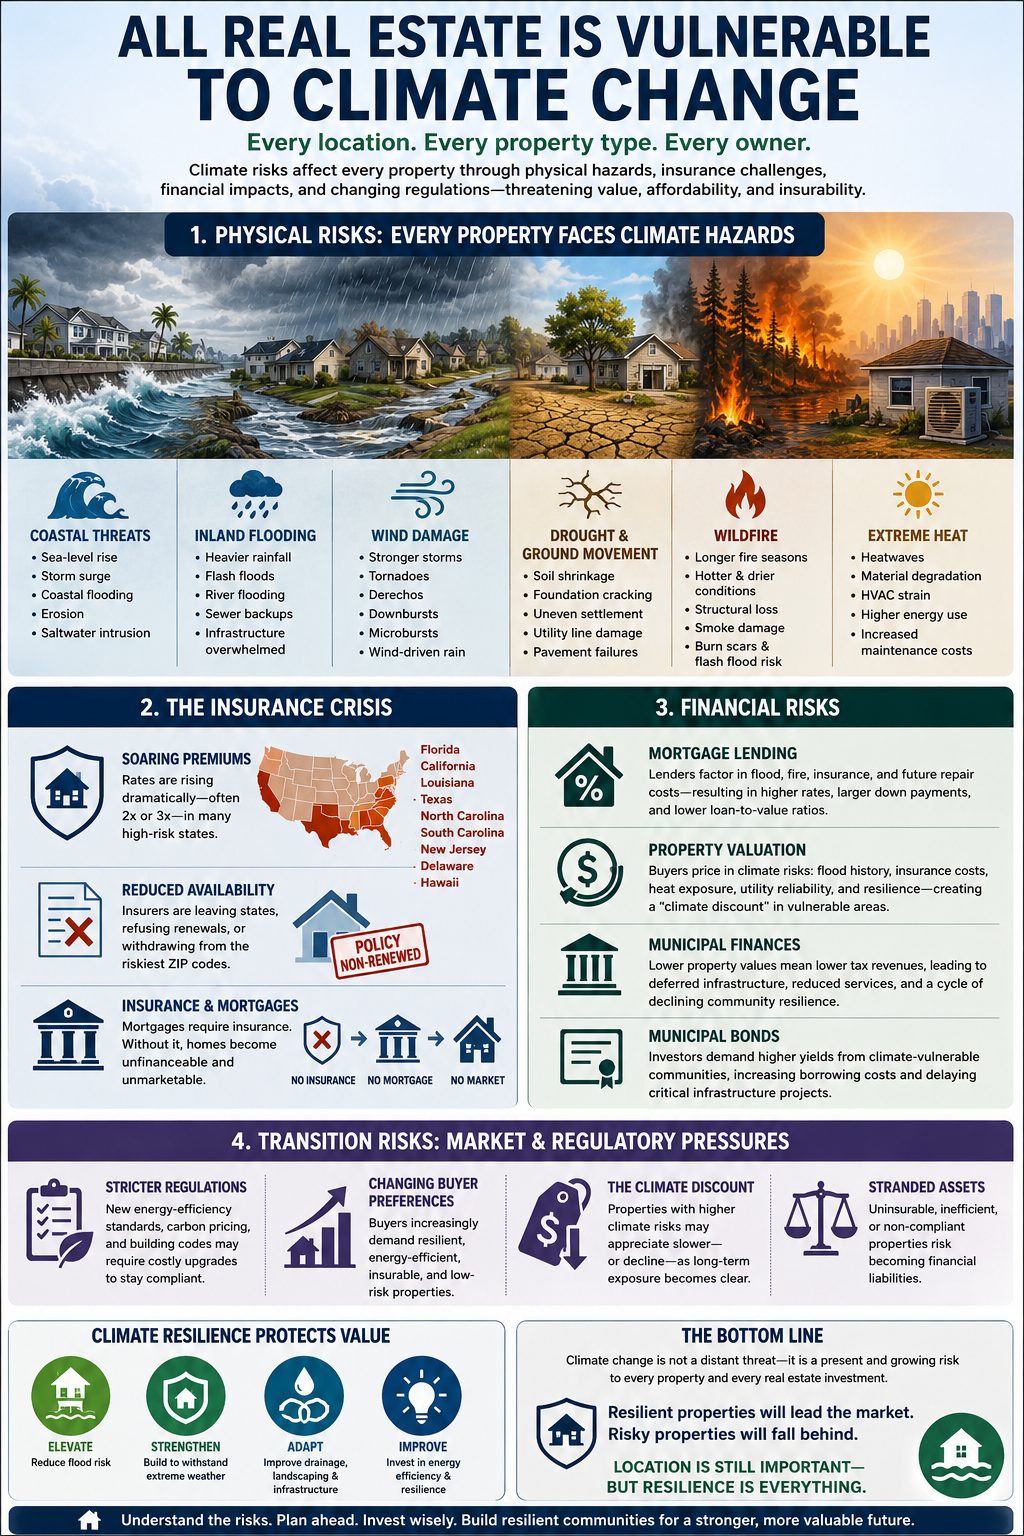
The vulnerability of real estate can be understood through four interconnected categories: physical risks, insurance risks, financial and lending risks, and transition risks.
1. Physical Risks: Every Property Faces Climate Hazards
Climate change is increasing both the frequency and intensity of many weather-related hazards. Every region experiences different threats, but no location is completely immune.
Coastal Regions
Coastal properties face some of the most visible climate risks, including:
Rising sea levels
More frequent nuisance flooding
Stronger storm surges
Accelerated shoreline erosion
Saltwater intrusion into groundwater
Even modest sea-level rise significantly increases flood frequency because storm surges begin from a higher baseline.
Inland Flooding
Many inland communities once considered “safe” are experiencing increasing flood losses.
Warmer air holds approximately 7% more water vapor for every 1°C of warming, increasing the potential for intense rainfall events. As storms become more moisture-laden, drainage systems designed for twentieth-century rainfall often become overwhelmed.
Consequences include:
Flash flooding
River flooding
Basement flooding
Sewer backups
Road washouts
Bridge failures
Properties located well outside traditional floodplains are increasingly experiencing damaging floods.
Wind Damage
For much of the United States, wind represents the largest source of insured property losses.
Climate change is increasing atmospheric energy available for:
Severe thunderstorms
Derechos
Tornado outbreaks
Downbursts
Microbursts
Hurricane wind fields
Roofs, siding, windows, and mature trees are particularly vulnerable. Wind-driven rain often causes damage even when structures remain standing.
Wildfire
Longer fire seasons, hotter temperatures, and more frequent droughts have dramatically expanded wildfire risk.
Wildfires threaten real estate through:
Direct structural destruction
Smoke damage
Utility failures
Water contamination
Long-term reductions in property desirability
Burn scars also increase the likelihood of flash flooding and debris flows during subsequent rainstorms.
Drought and Ground Movement
Extended drought affects soils in complex ways.
Clay-rich soils shrink as they dry, causing:
Foundation cracking
Uneven settlement
Utility line damage
Pavement failures
Conversely, periods of heavy rainfall following drought can produce rapid soil expansion that further stresses structures.
Extreme Heat
Heat affects virtually every building.
Higher temperatures accelerate deterioration of:
Roofing materials
Asphalt pavement
Exterior paints
Sealants
HVAC systems
Buildings require more cooling energy while mechanical systems experience greater wear, increasing maintenance and operating costs.
2. The Insurance Crisis
Insurance is becoming one of the most important climate risks facing property owners.
Historically, insurance spread risk across large geographic regions. As climate-related losses increase, that model is becoming increasingly difficult to sustain.
Rising Premiums
Many homeowners and commercial property owners have experienced substantial premium increases.
States experiencing particularly rapid increases include:
Florida
California
Louisiana
Texas
North Carolina
South Carolina
New Jersey
Delaware
Hawaii
In many communities, insurance costs are rising faster than home values.
Reduced Availability
Some insurers are:
Leaving entire states
Declining to insure specific ZIP codes
Refusing policy renewals
Restricting coverage amounts
Increasing deductibles
As private insurers withdraw, many homeowners are forced into state-sponsored insurers of last resort, which often provide less comprehensive coverage at higher cost.
Most mortgage lenders require continuous hazard insurance throughout the life of the loan.
If insurance becomes unavailable or unaffordable:
Mortgage approvals become more difficult.
Existing homeowners may violate loan requirements.
Buyers qualify for smaller loans.
Market demand declines.
Property values weaken.
Without insurance, many homes effectively become difficult or impossible to finance.
3. Financial Risks Beyond Property Damage
Climate change affects real estate markets even before disasters occur.
Financial institutions increasingly incorporate climate risk into lending and investment decisions.
Mortgage Lending
Banks and mortgage investors evaluate:
Flood exposure
Wildfire risk
Insurance availability
Future repair costs
Local infrastructure resilience
Higher perceived risk may result in:
Larger down payment requirements
Higher interest rates
Reduced loan-to-value ratios
Shorter lending horizons
Properties once viewed as routine collateral may gradually become more difficult to finance.
Property Valuation
Real estate markets depend heavily on expectations of future value.
Buyers increasingly consider:
Flood history
Fire history
Heat exposure
Insurance costs
Utility reliability
Local resilience investments
Two otherwise identical homes may command significantly different prices simply because one carries greater long-term climate risk.
Municipal Finances
Local governments rely heavily on property taxes.
If climate risks reduce property values, municipalities may experience:
Lower tax revenues
Deferred infrastructure maintenance
Reduced public services
Higher municipal borrowing costs
This creates a feedback loop in which deteriorating infrastructure further reduces property values.
Municipal Bonds
Cities and counties finance roads, schools, water systems, and flood-control projects through municipal bonds.
Increasing climate risks may lead investors to demand higher yields from municipalities perceived as vulnerable. Higher borrowing costs can delay infrastructure improvements, making communities even more susceptible to future climate impacts.
Credit rating agencies are paying increasing attention to long-term climate resilience when evaluating municipal creditworthiness.
4. Transition Risks
Not all climate risks arise from weather.
Many result from changes in markets, technology, regulations, and consumer preferences.
Energy Efficiency Requirements
Governments are gradually adopting stricter standards for:
Building efficiency
Carbon emissions
Appliance performance
Building electrification
Energy benchmarking
Older buildings may require expensive upgrades to remain competitive.
Changing Buyer Preferences
Homebuyers increasingly ask questions such as:
Is the property insurable?
How often does it flood?
What are annual insurance costs?
Does the home have backup power?
Is the roof hurricane-rated?
Are energy costs manageable?
These considerations increasingly influence purchasing decisions.
The Emerging Climate Discount
Economists have begun describing the possibility of a “climate discount” or “climate bubble.”
Properties with elevated climate risks may experience slower appreciation—or outright depreciation—as markets increasingly recognize long-term exposure.
Unlike traditional real estate cycles, climate-related devaluation may persist because the underlying physical risks continue to evolve.
5. Climate Risk Is Becoming a Core Investment Risk
Climate change is transforming real estate from an asset class valued primarily by location into one increasingly valued by resilience.
Future property performance will depend not only on neighborhood desirability but also on:
Infrastructure quality
Flood protection
Insurance availability
Building efficiency
Utility reliability
Community adaptation efforts
Investors, lenders, insurers, and homebuyers are already incorporating these factors into financial decisions.
Conclusion
Climate change does not mean that all real estate will suddenly lose value or become uninhabitable. Real estate will remain one of the world’s largest and most important asset classes. However, the factors that determine value are changing.
The greatest risk is not a sudden collapse of the housing market but a gradual repricing of climate risk. Some properties may remain highly desirable for decades, while others may face increasing costs from insurance, maintenance, financing, and regulatory compliance.
Understanding these risks allows homeowners, investors, developers, lenders, and policymakers to make informed decisions. Investments in resilient construction, improved infrastructure, energy efficiency, and thoughtful land-use planning can reduce long-term vulnerability and help preserve property values.
The future of real estate will increasingly be determined not simply by location, location, location, but by location, resilience, and adaptability.
“The greater risk is a gradual degradation of living standards if adaptation is delayed.“
by Daniel Brouse
Introduction
Climate change is often discussed as if it will either produce an imminent societal collapse or, conversely, have little economic consequence. Neither view is supported by the physical science.
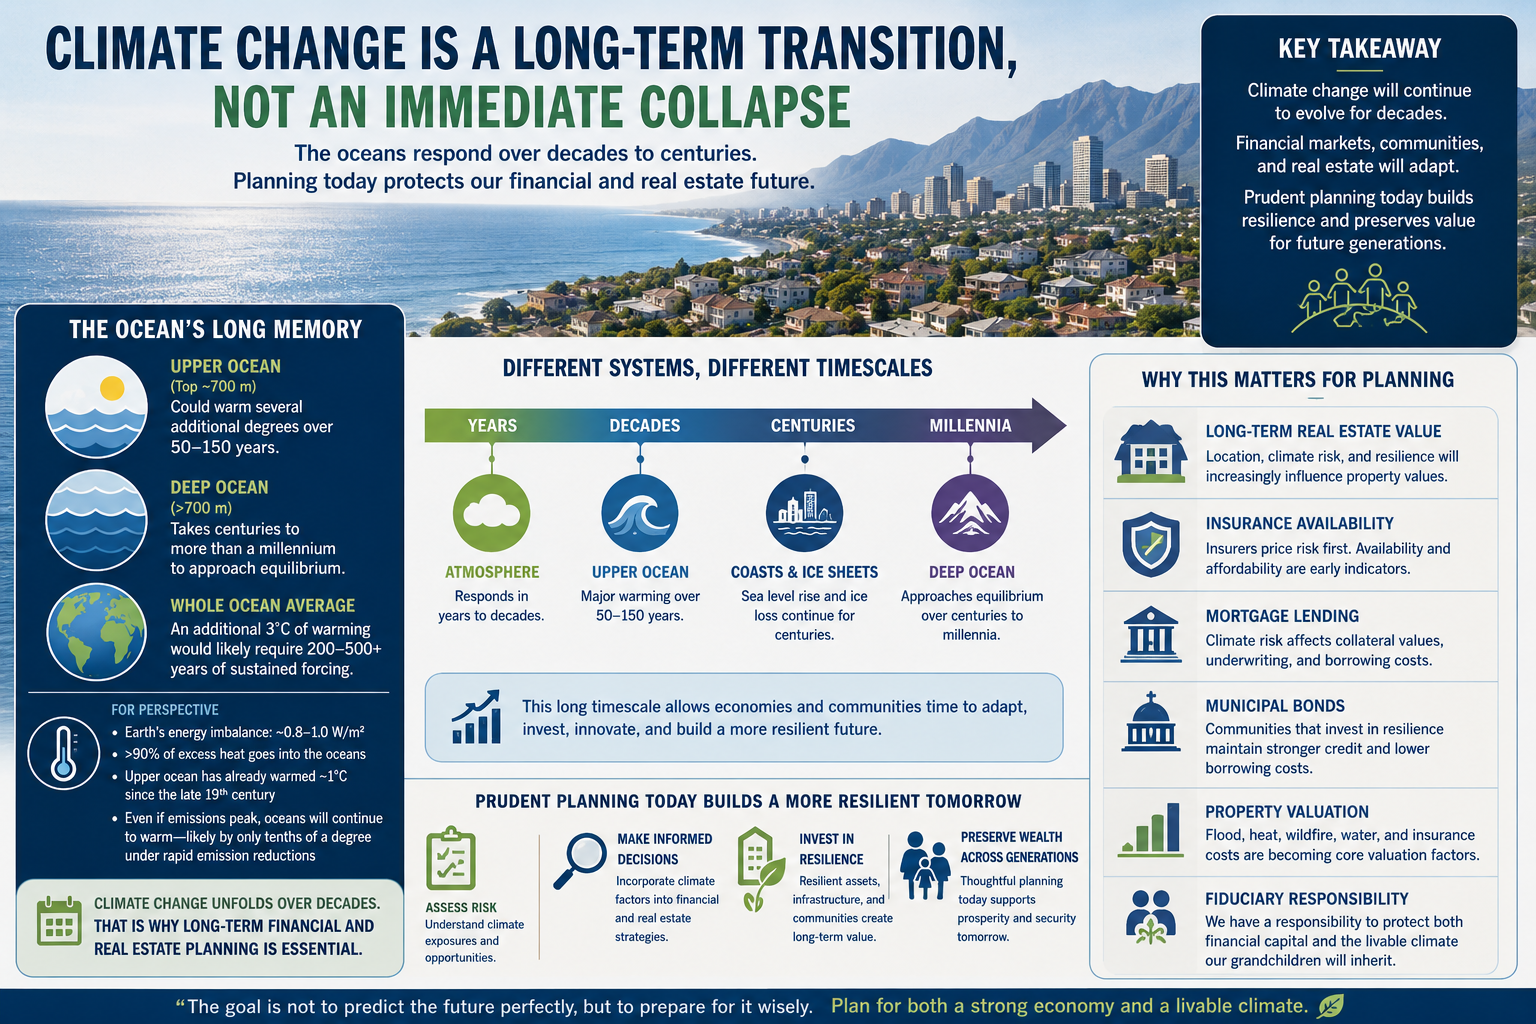
The Earth’s climate system responds over multiple timescales. While the atmosphere reacts relatively quickly to changes in greenhouse gas concentrations, the oceans—the planet’s largest heat reservoir—respond much more slowly. This difference, known as thermal inertia, means that many of the economic consequences of climate change will continue to unfold over decades, regardless of whether emissions peak today or several years from now.
For investors, homeowners, businesses, insurers, lenders, and governments, this distinction is critical. The evidence points not toward an immediate collapse of the global economy, but toward a long period of increasing environmental risks that will progressively reshape financial markets and real estate values.
The Ocean’s Long Memory
If greenhouse gas concentrations remained near current levels long enough to maintain today’s radiative forcing, it would likely take many decades to centuries for the global ocean to warm by an additional 3°C.
Current scientific understanding suggests:
The upper ocean (roughly the top 700 meters) could warm several additional degrees over approximately 50–150 years.
The deep ocean requires centuries to more than a millennium to approach equilibrium.
The global ocean average would likely require several centuries of sustained forcing to warm another 3°C.
More than 90% of Earth’s excess heat enters the oceans, giving the climate system enormous momentum.
Even if atmospheric temperatures stabilize, sea level rise, marine heat waves, glacier retreat, and many coastal impacts continue because the oceans continue redistributing heat.
Climate change therefore behaves less like flipping a switch and more like steering an aircraft carrier. Once underway, changes continue for decades.
Why This Does Not Mean Immediate Economic Collapse
The nonlinear acceleration of climate change does not imply that modern economies disappear within a few years.
Economic systems continually adapt.
History demonstrates remarkable resilience through world wars, financial crises, pandemics, technological revolutions, and natural disasters. Markets evolve. Capital reallocates. Infrastructure is rebuilt. New technologies emerge.
Climate change represents another major structural transformation—not an instantaneous end to economic activity.
The greater risk is a gradual degradation of living standards if adaptation is delayed.
Financial Markets Price Risk—They Do Not Ignore It
Climate risk is becoming another measurable input.
Rather than causing markets to cease functioning, climate change increasingly changes how capital is allocated.
Investment flows are likely to favor:
Resilient infrastructure
Water management
Energy efficiency
Distributed power systems
Climate-resilient agriculture
Advanced building technologies
Adaptation engineering
Markets rarely stop functioning.
They reprice risk.
Mortgage Lending in a Changing Climate
Mortgage lending has always depended upon one fundamental assumption:
The collateral will retain value over the life of the loan.
Most residential mortgages extend 15 to 30 years.
Commercial financing often spans decades.
Those time horizons now overlap directly with accelerating climate risks.
Lenders are increasingly evaluating:
Flood exposure
Wildfire probability
Coastal erosion
Extreme heat
Water availability
Infrastructure resilience
Local adaptation policies
Climate risk is becoming credit risk.
Properties with increasing exposure may experience:
Higher insurance costs
Larger reserve requirements
Lower loan-to-value ratios
Increased underwriting scrutiny
Higher borrowing costs
Conversely, resilient communities with strong infrastructure may receive more favorable financing because they present lower long-term risk.
Climate-informed lending is simply modern risk management.
Insurance Availability May Become the First Market Signal
Insurance companies often detect climate risk before property markets do.
Unlike homeowners, insurers continuously update catastrophe models using the latest observations and loss data.
When risks increase, insurers respond by:
Raising premiums
Increasing deductibles
Restricting coverage
Reducing policy limits
Withdrawing from selected markets
Recent developments in wildfire-prone states, hurricane-exposed coastlines, and hail-prone regions illustrate this trend.
In many communities, insurance affordability—not property damage itself—may become the first significant economic consequence of climate change.
Without affordable insurance:
Mortgage financing becomes more difficult.
Homeownership becomes more expensive.
Property values may weaken.
Municipal tax bases can come under pressure.
Insurance increasingly serves as an early warning system for long-term climate risk.
Municipal Bonds and Local Government Finance
Climate resilience is increasingly becoming a municipal finance issue.
Cities and counties finance much of their infrastructure through municipal bonds.
Those bonds ultimately depend upon:
Stable tax revenues
Economic growth
Reliable infrastructure
Sustainable operating costs
As climate risks increase, municipalities may require additional investments in:
Flood control
Stormwater systems
Water supply
Cooling infrastructure
Grid modernization
Emergency services
Road and bridge resilience
Communities that invest proactively may maintain stronger credit quality over time.
Communities that defer adaptation could face rising maintenance costs, increasing insurance expenses, and pressure on their fiscal health.
For municipal investors, climate resilience increasingly becomes part of long-term credit analysis.
Property Valuation Is Becoming Dynamic
Historically, property valuation focused on:
Location
Schools
Transportation
Employment
Neighborhood quality
Climate is becoming another location characteristic.
Future valuation models will likely incorporate increasing amounts of climate-related information, including:
FEMA flood maps
Local flood history
Heat exposure
Wind risk
Wildfire potential
Water reliability
Insurance costs
Building resilience
Community adaptation investments
Properties will not simply gain or lose value because of climate change.
Rather, markets will increasingly differentiate between properties based on their long-term resilience.
The result is likely to be greater divergence between communities that prepare and those that do not.
Investment Implications
Because climate impacts unfold over decades, financial planning becomes more—not less—important.
Assuming there will be “no economy” several years from now is neither supported by economic history nor by climate science.
Instead, investors should recognize that long-term wealth preservation increasingly depends upon understanding long-term environmental risk.
That includes:
Diversified investment portfolios.
Climate-informed real estate decisions.
Appropriate insurance coverage.
Infrastructure resilience.
Geographic diversification.
Long-term retirement planning.
Planning remains one of the strongest tools available for reducing future financial risk.
Fiduciary Responsibility Across Generations
Every generation inherits assets built by those before it.
Likewise, every generation passes assets forward.
That fiduciary responsibility extends beyond investment portfolios.
It includes:
Homes.
Communities.
Infrastructure.
Businesses.
Natural resources.
Financial systems.
Protecting both environmental and financial capital is not a contradiction.
It is prudent stewardship.
Planning for climate risk is no different than planning for inflation, demographic change, technological disruption, or changing interest rates.
Responsible investors prepare for foreseeable risks rather than assuming those risks either do not exist or will immediately end the economic system.
Conclusion
Climate science indicates that many impacts will continue evolving over decades because Earth’s oceans absorb and release heat slowly.
That long timescale does not support predictions of imminent economic collapse.
Instead, it points toward an extended period during which markets continuously adapt by repricing risk, directing capital toward resilience, and rewarding long-term planning.
For homeowners, investors, lenders, insurers, businesses, and governments, the challenge is not deciding whether there will be an economy.
The challenge is helping shape an economy that is both financially resilient and environmentally sustainable.
The goal is not simply to leave future generations a larger investment portfolio.
It is to leave them both a livable climate and an economy capable of supporting opportunity for decades to come.
Complex social-ecological feedback loops arise when human systems and natural systems react to climate change in ways that amplify one another. Because Earth’s climate operates as a nonlinear system, these interactions do not unfold gradually — they can accelerate suddenly, compound unpredictably, and push the system toward irreversible shifts.
This nonlinear, cross-regional feedback behavior is something we have been modeling for decades — where climate physics couples directly with economic networks.
In the 1990s we underestimated one variable: human delay. We assumed mitigation would begin in earnest. It did not.
Now we observe potential doubling in the intensity or frequency of certain climate impacts on timescales of 2–10 years rather than centuries. The apparent acceleration has compressed from millennial-scale shifts to multi-decade nonlinear surges.
Denialism and Ecofascism
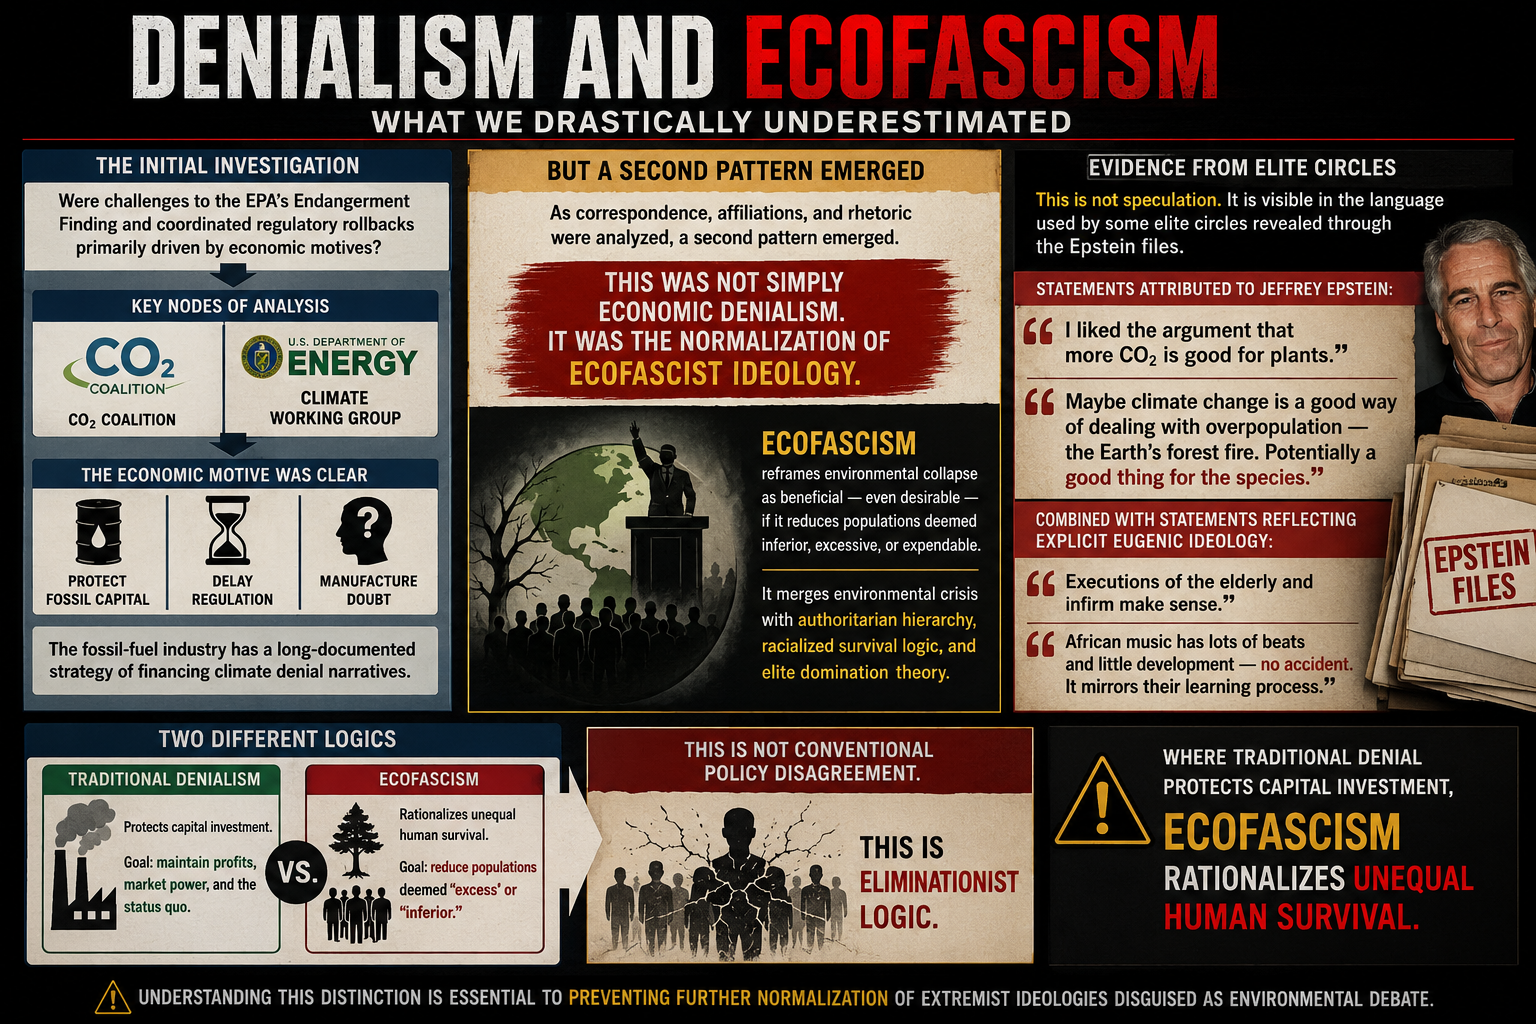
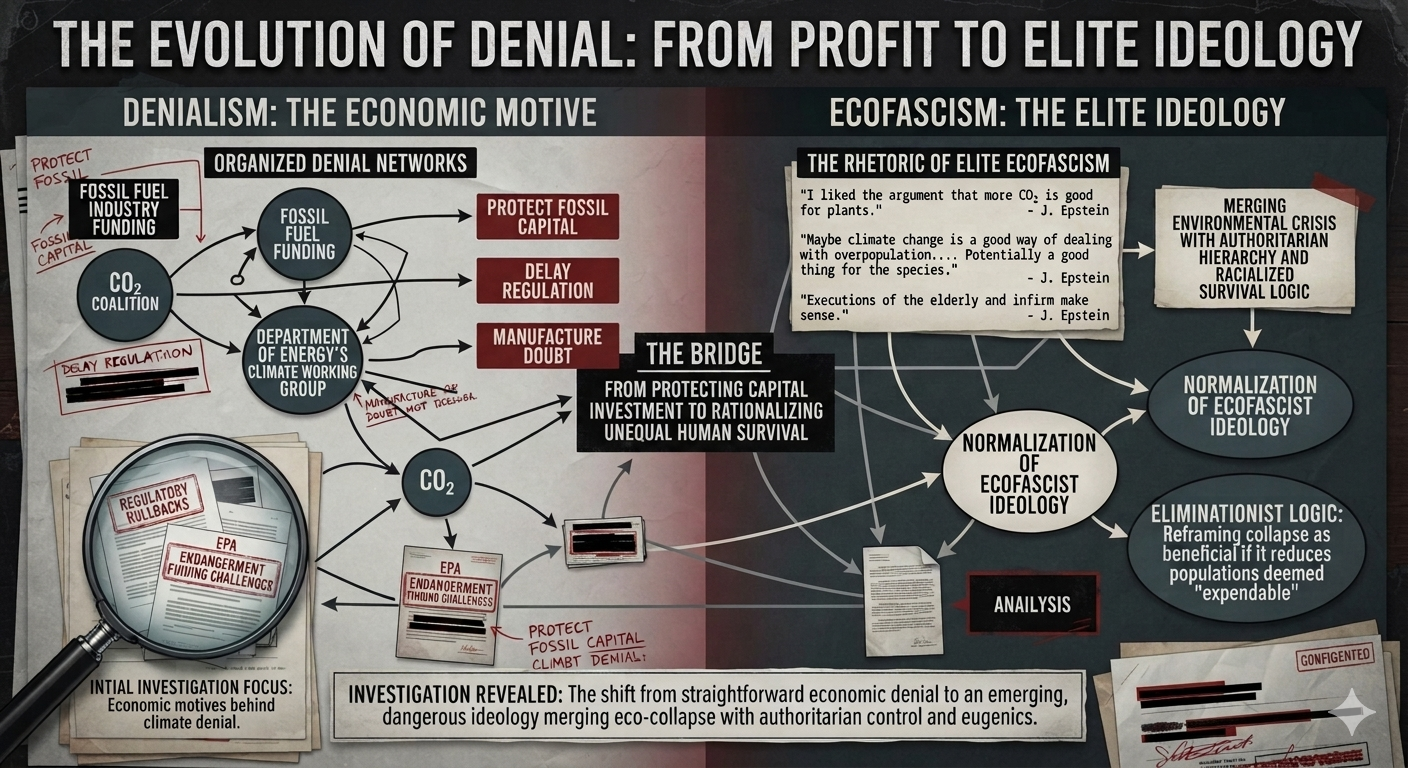
One factor we drastically underestimated was the influence of organized denialism and emerging ecofascist ideology.
Initially the investigation focused on a straightforward institutional question:
Were challenges to the EPA’s Endangerment Finding and coordinated regulatory rollbacks primarily driven by economic motives — specifically the fossil-fuel industry’s long-documented strategy of financing climate denial narratives?
Organizations such as the CO₂ Coalition and the Department of Energy’s Climate Working Group were key nodes of analysis. The economic motive was clear and well documented: protect fossil capital, delay regulation, and manufacture doubt.
But as correspondence, affiliations, and rhetoric were analyzed, a second pattern emerged.
This was not simply economic denialism. It was the normalization of ecofascist ideology.
Ecofascism reframes environmental collapse as beneficial — even desirable — if it reduces populations deemed inferior, excessive, or expendable. It merges environmental crisis with authoritarian hierarchy, racialized survival logic, and elite domination theory.
This is not speculation. It is visible in the language used by some elite circles revealed through the Epstein files.
Examples include statements attributed to Jeffrey Epstein such as:
“I liked the argument that more CO₂ is good for plants.”
“Maybe climate change is a good way of dealing with overpopulation — the Earth’s forest fire. Potentially a good thing for the species.”
Combined with statements reflecting explicit eugenic ideology:
“Executions of the elderly and infirm make sense.”
“African music has lots of beats and little development — no accident. It mirrors their learning process.”
This is not conventional policy disagreement. This is eliminationist logic.
Where traditional denial protects capital investment, ecofascism rationalizes unequal human survival.
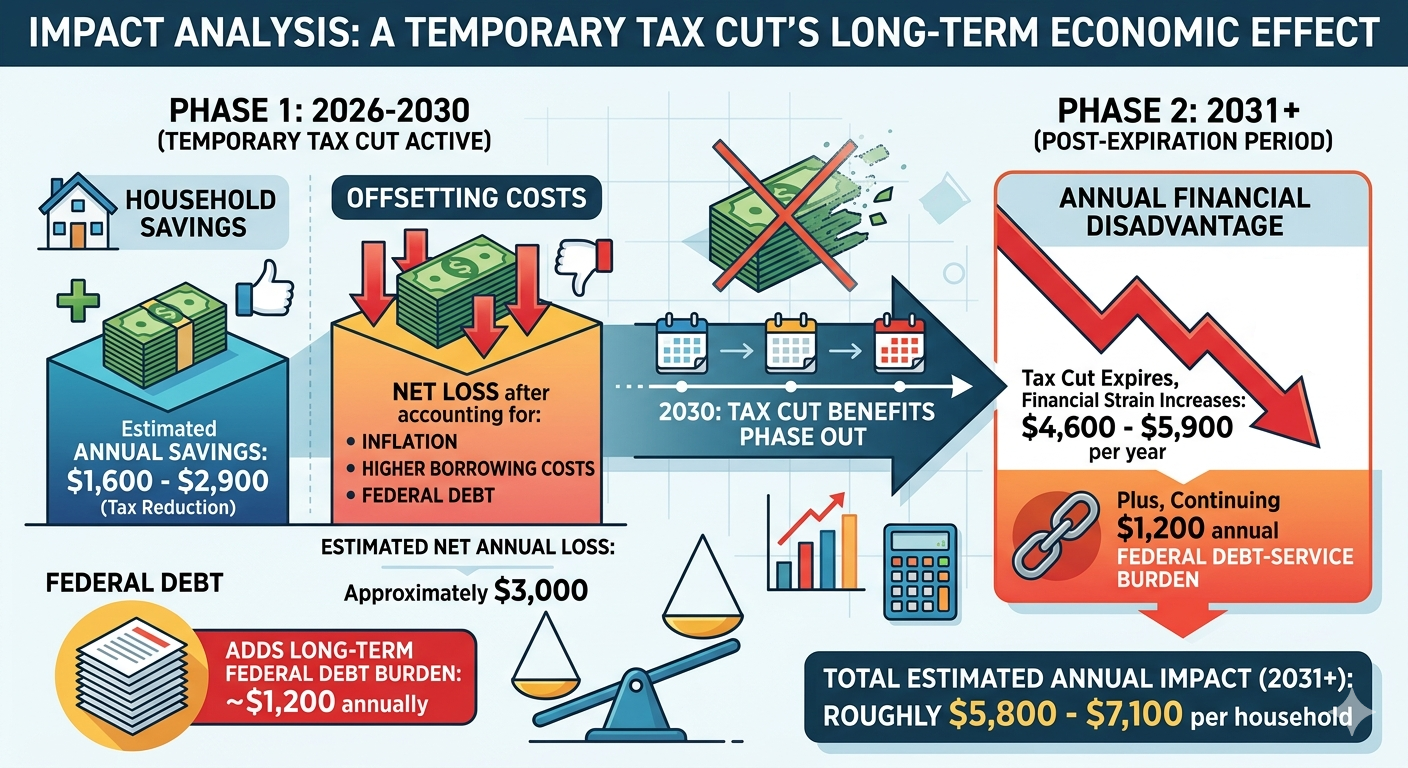
A tax cut that appeared to provide the average household with $1,600–$2,900 in annual savings was more than offset by the broader economic effects of inflation, higher borrowing costs, and increased federal debt. After accounting for these costs, the average household experienced an estimated net loss of approximately $3,000 per year, along with an additional long-term federal debt burden equivalent to roughly $1,200 annually.
However, the tax cut benefits are scheduled to phase out by 2030, meaning households will eventually lose the temporary savings while many of the costs associated with higher debt, interest payments, and elevated borrowing rates remain. Beginning in 2031, when the tax reduction expires, the average household’s annual financial disadvantage could increase to approximately $4,600–$5,900 per year, plus the continuing $1,200 annual federal debt-service burden. This would place the total estimated impact at roughly $5,800–$7,100 per household annually, while the accumulated federal debt continues to shift additional costs onto future taxpayers.
Tax Cuts vs. Inflation: The Hidden Battle Over Household Purchasing Power
Tax cuts are often promoted as a direct way to improve household finances, but for the average American family, inflation can have a much larger and more immediate impact on financial well-being. A tax cut may provide a noticeable boost to income, but a sustained period of elevated inflation can quietly reduce purchasing power by thousands of dollars each year.
For a typical middle-income household, a broad tax reduction might save several hundred to a few thousand dollars annually. However, inflation affects the entire household budget—including housing, groceries, utilities, transportation, healthcare, and services. A 4%–5% annual inflation rate can easily increase household expenses by $3,500–$5,000 per year, effectively overwhelming the benefit of many tax cuts.
The result is a simple economic reality: a dollar gained through tax cuts can be offset—or even erased—by dollars lost through higher prices.
The Mathematical Mismatch: Tax Savings vs. Inflation Costs
Tax Cuts Provide Limited Annual Gains
For most middle-class households, federal tax cuts typically produce moderate savings rather than dramatic changes in disposable income. Historical analyses of broad tax packages, including evaluations by organizations such as the Tax Policy Center, have shown that middle-income families often receive annual tax reductions in the range of roughly $1,600 to $2,900, depending on the structure of the legislation. The most recent tax cuts saved the average household $1,600 and $2,900.
While meaningful, these savings represent only a fraction of a household’s total annual expenses.
Inflation Acts Like a Hidden Tax
Inflation operates differently from taxes. Rather than reducing a paycheck directly, it increases the cost of nearly everything a household buys.
A family spending $80,000 annually on goods and services would experience approximately:
4% inflation: about $3,200 in additional annual costs
5% inflation: about $4,000 in additional annual costs
6% inflation: about $4,800 in additional annual costs
Unlike a tax cut, which may provide a one-time or annual benefit, inflation compounds year after year. Even if wages rise, households can still lose purchasing power if prices increase faster than incomes.
Distribution of Benefits vs. Distribution of Burdens
Tax Cuts Often Deliver Larger Dollar Benefits to Higher-Income Households
Income tax reductions generally scale with taxable income. Higher-income households typically pay more in taxes, so percentage-based tax cuts often produce larger dollar savings at the top.
Analyses from organizations such as the Congressional Budget Office have repeatedly shown that broad tax changes frequently provide the largest absolute benefits to higher-income groups, while middle- and lower-income households receive smaller dollar amounts.
Inflation Disproportionately Hurts Lower- and Middle-Income Families
Inflation is often described as a regressive economic force because it affects essential spending categories that consume a larger share of lower-income household budgets.
A wealthy household can often absorb higher prices by reducing discretionary spending or shifting purchases. A working-class family has fewer options when facing increases in:
Food prices
Rent or mortgage payments
Electricity and heating costs
Gasoline and transportation
Healthcare expenses
For families living close to their monthly budget limits, inflation functions like a pay cut.
The Inflation Feedback Loop
Tax cuts can stimulate economic activity by increasing disposable income. However, if tax reductions are not matched by spending reductions or productivity gains, they can increase demand in an economy already operating near capacity.
The mechanism is straightforward:
Tax cuts increase household disposable income.
Increased income boosts consumer demand.
If supply cannot expand quickly enough, businesses raise prices.
Higher prices reduce the purchasing power of the original tax cut.
In this scenario, households may receive additional money in their paycheck while simultaneously paying more at the grocery store, gas station, and utility bill.
The economic benefit becomes partially or completely offset by rising prices.
The Federal Debt Effect: How Tax Cuts Can Increase Long-Term Costs
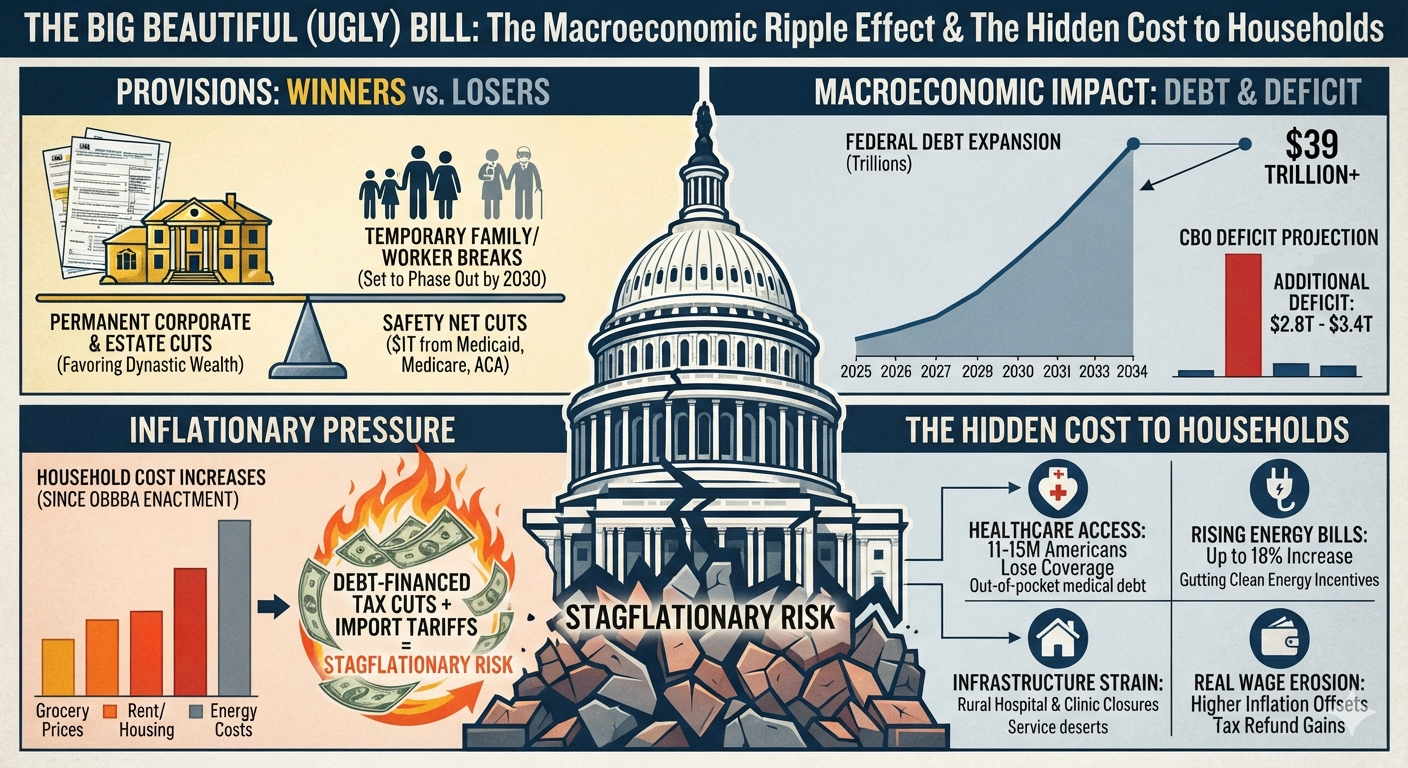
Tax cuts also have a broader economic impact beyond the immediate benefit to taxpayers. When tax reductions are not accompanied by equivalent spending reductions or stronger economic growth, they increase the federal budget deficit and add to the national debt. The government must finance that additional debt by issuing more Treasury securities, increasing the supply of government borrowing.
As federal debt rises, the government competes with households and businesses for available capital. This increased demand for borrowed money can place upward pressure on interest rates, raising the cost of mortgages, auto loans, credit cards, business financing, and other forms of credit.
The effect is often indirect but significant. A household may receive a $2,000 annual tax reduction, but if higher federal borrowing contributes to even a modest increase in interest rates, that same family may pay thousands of dollars more over time through:
Higher mortgage rates when purchasing or refinancing a home
Increased interest on auto loans
Higher credit card balances
More expensive consumer financing
Higher costs passed through by businesses borrowing at elevated rates
For example, a 1% increase in mortgage rates on a $300,000 home loan can add roughly $200 per month to a typical 30-year mortgage payment—more than $2,000 annually. Across the economy, higher interest rates also increase the federal government’s own debt-service costs, requiring more taxpayer dollars to pay interest rather than fund public services or reduce future deficits.
This creates a potential feedback loop:
Tax cuts reduce federal revenue.
Larger deficits increase government borrowing.
Higher debt levels put upward pressure on interest rates.
Higher rates increase borrowing costs for households, businesses, and the government.
Additional interest expenses reduce the long-term economic benefit of the original tax cut.
The ultimate measure of a tax policy is therefore not only the size of the immediate tax reduction, but its effect on total household purchasing power after accounting for inflation, interest rates, and the long-term cost of increased federal debt.
The Role of Bracket Creep
Inflation also affects taxation through a process known as bracket creep.
As wages rise due to inflation, taxpayers can unintentionally move into higher tax brackets even though their real purchasing power has not increased. To address this, the Internal Revenue Service adjusts federal income tax brackets, standard deductions, and other thresholds annually for inflation.
These adjustments prevent inflation from automatically increasing a household’s tax burden. However, they do not compensate for the broader loss of purchasing power caused by rising prices.
Inflation indexing protects taxpayers from paying higher taxes simply because of inflation—it does not make groceries, housing, or energy affordable again.
Conclusion: The True Measure Is Total Economic Impact
Tax cuts can provide meaningful benefits to households, but their true economic value cannot be measured by the size of the immediate reduction in a tax bill alone. A complete evaluation must consider the broader effects on purchasing power, inflation, interest rates, and the long-term federal debt burden.
A tax cut may increase disposable income in the short term, but those gains can be diminished or even erased when inflation raises the cost of everyday necessities such as housing, food, energy, and transportation. Unlike a one-time tax reduction, inflation affects the entire household budget and compounds over time, reducing what each dollar can actually buy.
The impact also depends on how tax cuts are financed. When reductions in federal revenue are not matched by spending cuts or sufficient economic growth, they increase budget deficits and add to the national debt. Higher federal borrowing can place upward pressure on interest rates, increasing costs for mortgages, auto loans, credit cards, and business financing. Households may receive additional money through lower taxes while simultaneously paying more through higher borrowing costs and rising prices.
This creates a broader economic equation:
The benefit of a tax cut is not simply the dollars returned to taxpayers—it is the change in real purchasing power after accounting for inflation, interest rates, and future debt obligations.
For some households, especially higher-income taxpayers, tax reductions may provide substantial direct benefits. However, for many middle- and lower-income families, the effects of inflation and higher interest rates can outweigh those gains because they spend a larger share of their income on necessities and borrowing costs.
The ultimate question is therefore not:
“How much did taxpayers save in taxes?”
The more important question is:
“Did households become financially better off after accounting for the full economic consequences?”
A sustainable economic policy must balance tax relief with fiscal responsibility, price stability, and long-term economic growth. Without that balance, a tax cut can create the appearance of increased prosperity while shifting costs into higher prices, higher interest payments, and a larger debt burden for future generations.
ADDENDUM
The exact “net cost” depends on the household’s income, debt exposure, and whether the tax cuts are financed by borrowing. A reasonable estimate can be made by separating immediate annual effects from long-term debt effects.
Estimated Annual Impact on an Average Household
Item
Annual Impact
Tax cut benefit
+$1,600 to +$2,900
4% inflation increase in household expenses
−$3,200
Higher mortgage costs (if buying/refinancing)
−$2,000+
Higher auto loan, credit card, and consumer financing costs
−$500 to −$2,000+
Higher business borrowing costs passed through in prices
−$300 to −$1,000+
Additional federal debt interest burden
−$900 to −$1,500+ annually (estimated)
Short-Term Net Effect (First-Year Estimate)
Lower-cost scenario:
Tax savings: +$2,900
Inflation cost: −$3,200
Consumer borrowing/business costs: −$800
Debt interest effect: −$900
Net impact: approximately −$2,000 per household per year
Higher-cost scenario:
Tax savings: +$1,600
Inflation cost: −$3,200
Mortgage/borrowing costs: −$3,000
Debt interest effect: −$1,500
Net impact: approximately −$6,100 per household per year
Long-Term Federal Debt Effect
If tax cuts add $3–$5 trillion to federal debt:
There are roughly 130 million U.S. households.
The added debt equals approximately:
130 million households$3 trillion≈$23,000 per household130 million households$5 trillion≈$38,000 per household
That does not mean each household receives a bill, but it represents the additional federal liability ultimately supported by taxpayers.
If the government pays roughly 4% interest on that additional debt:
$3 trillion × 4% = $120 billion/year
$5 trillion × 4% = $200 billion/year
Spread across households:
$900–$1,500 per household annually in additional federal interest costs
Over decades, if the debt is refinanced and interest compounds, the total burden can become substantially larger.
Other Potential Costs Associated With Large Tax Cuts
1. Reduced fiscal flexibility
Higher debt can limit the government’s ability to respond to:
recessions
natural disasters
pandemics
military emergencies
infrastructure needs
Future taxpayers may face higher taxes or spending cuts to service the debt.
2. Higher interest rates
Large deficits can increase demand for borrowed funds, putting upward pressure on interest rates. This affects:
mortgages
business loans
student loans
auto loans
government borrowing costs
3. Crowding out private investment
When the government absorbs more available capital:
businesses may invest less
productivity growth can slow
wage growth may weaken over time
4. Inflation risk
If tax cuts increase demand without increasing supply, they can contribute to inflationary pressure, especially when the economy is already near capacity.
Estimated Net Household Effect
Time Frame
Estimated Impact
Immediate annual effect
−$2,000 to −$6,000 per household
Added federal debt liability
+$23,000 to +$38,000 per household
Annual debt-service burden
−$900 to −$1,500 per household/year
Bottom Line
A tax cut that appeared to provide an average household with $1,600–$2,900 in annual savings was far outweighed by the broader economic effects of inflation, higher borrowing costs, and increased federal debt. The average household had a net loss of $3,000 and an additional debt burden of $1,200/year. For many households, the combined impact may represent a net financial loss of several thousand dollars per year, while the long-term debt burden shifts additional costs onto future taxpayers.
The unexpectedly rapid release of more than $100 billion in tariff refunds is likely amplifying an already sharp increase in U.S. imports, contributing to a much wider trade deficit reported today by the Bureau of Economic Analysis.
According to the U.S. Bureau of Economic Analysis (BEA), the international trade deficit jumped 42.2% to $77.6 billion in May, up from a revised $54.6 billion in April. Imports climbed 3.3% to $395.3 billion, while exports fell 3.2% to $317.7 billion.
While businesses also accelerated purchases ahead of potential new tariffs and supply chain disruptions, the rapid release of tariff refunds appears to have become a major source of liquidity that enabled importers to dramatically increase orders from overseas.
Tariff Refunds Are Moving Much Faster Than Expected
The current refund program stems from the February 2026 U.S. Supreme Court ruling that invalidated many emergency tariffs imposed under the International Emergency Economic Powers Act (IEEPA). Since then, U.S. Customs and Border Protection (CBP) has been processing one of the largest customs refund programs in U.S. history.
The pace of payments has exceeded many expectations:
Approximately $166 billion in refund claims have been filed.
More than $104.3 billion has already been accepted.
Roughly $71 billion has been finalized and paid.
On June 29, CBP launched Phase 2 of its automated CAPE refund portal to process an additional 2.8 million older and more complex import entries.
The unexpectedly rapid return of more than $100 billion to importers has significantly improved corporate cash flow, allowing companies to replenish inventories and increase imports almost immediately.
Refund Liquidity Is Expanding the Trade Deficit
The refund process has created a powerful economic chain reaction:
More than $104 billion in accepted refund claims → Increased importer liquidity → Accelerated foreign purchasing → Larger U.S. trade deficit
Instead of remaining tied up in government accounts, tariff revenue is now flowing back into corporate balance sheets, enabling businesses to front-load imports while attempting to stay ahead of replacement tariff policies.
Tariff Revenue Has Effectively Disappeared
The refund program is also dramatically reducing federal customs revenue.
In May 2026, the U.S. Treasury paid out $21.97 billion in tariff refunds while collecting $21.93 billion in gross customs duties. The result was a net customs outflow of approximately $42 million, effectively eliminating tariff revenue for the month.
Growing Pressure on the Federal Budget
The reversal from collecting tariffs to issuing massive refunds is widening the federal fiscal deficit.
Because tariffs had become a significant source of government revenue, refunding those collections represents both a loss of expected receipts and a substantial increase in federal expenditures.
Moody’s Analytics estimates the immediate fiscal impact could exceed $133 billion.
The Congressional Budget Office (CBO) projects that related policy changes could increase federal deficits by roughly $2 trillion over the next decade.
Consumers See Little Benefit
Although corporations are receiving billions in refund payments, consumers are unlikely to see corresponding price reductions.
Several major retailers—including Nike, Amazon, and Costco—are facing class-action lawsuits alleging they retained tariff-related price increases while also receiving refund payments, allowing them to benefit from both higher prices and government reimbursements.
New Tariffs Could Offset the Windfall
Following the Supreme Court decision, the U.S. Trade Representative introduced new tariffs under alternative statutory authorities, including Section 122 and Section 301.
Many importers warn that these replacement tariffs could quickly erode the financial gains created by the current refund program. In the meantime, however, the rapid pace of tariff refunds is injecting substantial liquidity into import markets, contributing to a wider trade deficit and placing additional pressure on the federal budget.
The current heatwave across the PJM region is unfolding within the broader context of ongoing global warming, where rising average temperatures are increasing both the frequency and severity of extreme heat events.
As the climate warms, baseline temperatures shift upward, making extreme heat more likely and more persistent. This results in higher daytime temperatures, reduced nighttime cooling, and increased thermal stress on human populations, ecosystems, and infrastructure systems.
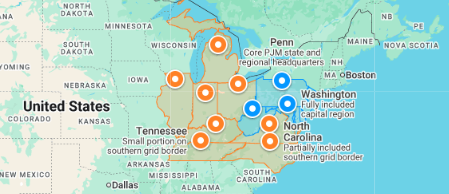
These conditions also place significant strain on the electric grid. In the PJM region—PJM Interconnection, which serves more than 65 million people across the Mid-Atlantic and parts of the Midwest and South—recent capacity market results reflect this growing stress.
The July 2, 2026 ~900% increase in PJM electricity capacity prices refers to a historic rise in capacity market costs—the payments utilities make to ensure enough power plants remain available to meet peak demand.
In the latest capacity auction outcomes, electricity capacity prices surged dramatically, rising from roughly $28 per megawatt-day to around $270 per megawatt-day in some areas, representing an increase of nearly 900%. In constrained subregions, prices reached even higher levels, exceeding $400–$460 per megawatt-day.
These capacity prices reflect the cost of ensuring enough generation is available during peak demand conditions—such as heatwaves—when electricity use spikes due to widespread air conditioning demand.
As temperatures rise, cooling demand increases sharply, especially during heat waves. This creates a cascading set of stresses across the power system:
higher electricity demand during peak heat events
increased strain on generation and transmission infrastructure
increased water demand in some regions for cooling and thermal generation
higher emissions during peak periods in grids that still rely heavily on fossil fuels
This produces a reinforcing sequence:
more heat → more cooling demand → higher electricity demand → increased emissions (in fossil-reliant systems) → further warming → more heat
In practice, what emerges is not a single isolated feedback loop, but a coupled network of reinforcing systems. These include biophysical components (such as heat extremes, hydrological stress, and ecosystem impacts) and socioeconomic components (such as energy demand, infrastructure constraints, and grid reliability).
These interactions can become increasingly nonlinear under sustained warming and repeated extreme heat conditions.
The key point is that these dynamics are already present in the system, but their magnitude, coupling strength, and long-term impacts vary by region, infrastructure mix, and timeframe. Reducing risk ultimately depends on rapidly reducing greenhouse gas emissions, particularly from fossil fuel combustion, while simultaneously adapting energy infrastructure to increasing heat and demand extremes.
The U.S. labor force participation rate now stands at 61.5%, according to the latest Bureau of Labor Statistics (BLS) June 2026 report. This metric measures the share of the civilian population aged 16 and older that is either employed or actively seeking work, and it declined from 61.8% in the prior reading.
Within the broader non-participating population, only a small segment is considered even loosely attached to the labor market. Approximately 1.76 million people are classified as “marginally attached” to the labor force—individuals who want a job and have looked for work within the past 12 months, but have not searched in the past four weeks. Of these, about 477,000 are “discouraged workers,” meaning they believe no jobs are available for them or that they lack the skills required to obtain employment.
The latest BLS June 2026 employment report highlights a notable shift in labor force dynamics. Roughly 720,000 people left the labor force, contributing to the decline in the participation rate from 61.8% to 61.5%.
This decline helps explain the apparent contradiction in the headline employment figures. The economy added a modest 57,000 jobs, and the official unemployment rate edged down from 4.3% to 4.2%. However, this improvement is partly driven by a smaller labor force rather than a surge in hiring, as fewer people were actively seeking work during the reporting period.
Robinhood Earn is a decentralized crypto lending product offering eligible U.S. users a reported 7% APY by lending out dollar-backed stablecoins, specifically USDG, through a self-custody wallet. The underlying lending infrastructure is powered by the decentralized finance (DeFi) protocol Morpho, and the product is marketed with additional protections including cyberattack and smart-contract exploit insurance arranged through Lloyd’s of London and RELM.
While the yield may appear attractive compared to traditional cash accounts, Robinhood Earn operates in a fundamentally different risk environment than insured banking products. Users should understand that this is not a bank deposit product and does not carry federal protections.
How Robinhood Earn Works
At a high level, Robinhood Earn functions as a decentralized lending market:
Users deposit USDG stablecoins into a self-custody wallet.
Those funds are supplied into lending pools via Morpho.
Borrowers take loans using crypto collateral.
Lenders earn interest generated from borrower demand, expressed as an APY (reported around 7%).
Unlike traditional savings accounts, returns are not guaranteed and fluctuate based on borrowing demand, protocol utilization, and market conditions.
Key Risks of Robinhood Earn
1. No FDIC or SIPC Protection
Funds used in Robinhood Earn are not covered by FDIC insurance (bank deposits) or SIPC protection (brokerage securities accounts).
If losses occur due to protocol failure, hacks, or market events, there is no government backstop to recover funds.
2. Bad Debt and Liquidation Risk
Loans in Morpho are backed by crypto collateral. If the value of that collateral falls too quickly during volatile markets, automated liquidations may fail to fully cover outstanding loans.
This can result in bad debt, which is typically absorbed proportionally by lenders—meaning partial losses of principal are possible.
3. Liquidity Constraints and Withdrawal Delays
In high-demand environments, the protocol can reach full utilization, meaning:
All deposited capital is actively lent out
New withdrawals may be delayed
Users must wait for borrowers to repay or new liquidity to enter the system
This introduces liquidity risk not present in traditional savings accounts.
4. Smart Contract and Protocol Risk
Because Robinhood Earn relies on decentralized smart contracts, it is exposed to risks such as:
Coding bugs or vulnerabilities
Governance failures
Exploits or hacks targeting the Morpho protocol or related infrastructure
In extreme cases, these risks could result in total loss of funds.
5. Stablecoin De-Pegging Risk
The yield is generated using USDG, a dollar-backed stablecoin intended to maintain a 1:1 peg with the U.S. dollar.
However, stablecoins can lose their peg due to:
Reserve mismanagement
Market panic or liquidity stress
Structural failures in backing assets
If de-pegging occurs, the value of holdings can decline even if interest continues to accrue.
6. Self-Custody Responsibility
Robinhood Earn requires use of a self-custody wallet, meaning users are fully responsible for securing their assets.
Risks include:
Loss of private keys or recovery phrases
Phishing attacks or social engineering scams
Signing malicious transactions
If any of these occur, fund recovery is not possible through Robinhood or any central authority.
Insurance Protections (and Their Limits)
Robinhood Earn includes cyberattack and smart-contract exploit coverage arranged through Lloyd’s of London and RELM. However, such insurance is typically:
Limited in scope
Subject to exclusions and conditions
Not equivalent to federal deposit insurance
Users should not assume full protection against all forms of loss.
Bottom Line
Robinhood Earn represents a hybrid between traditional finance and decentralized lending markets. While the reported 7% APY may be attractive, the product introduces a combination of market, liquidity, custody, and smart-contract risks that do not exist in standard bank accounts.
It is fundamentally a decentralized lending exposure, not a guaranteed savings product, and should be evaluated accordingly.
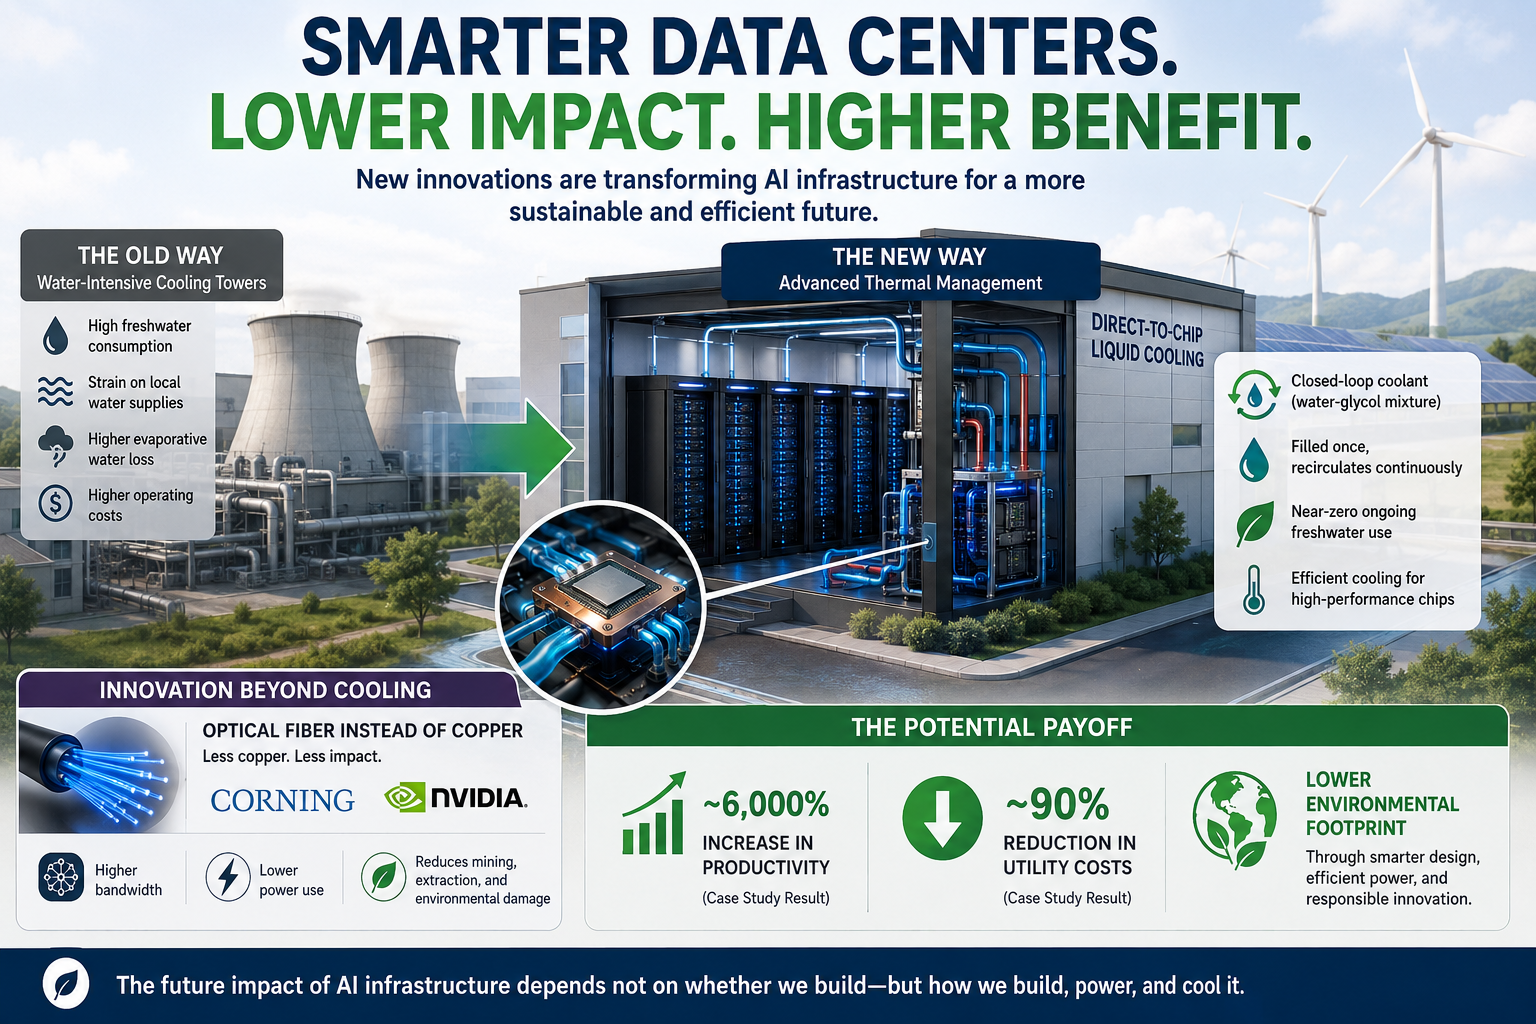
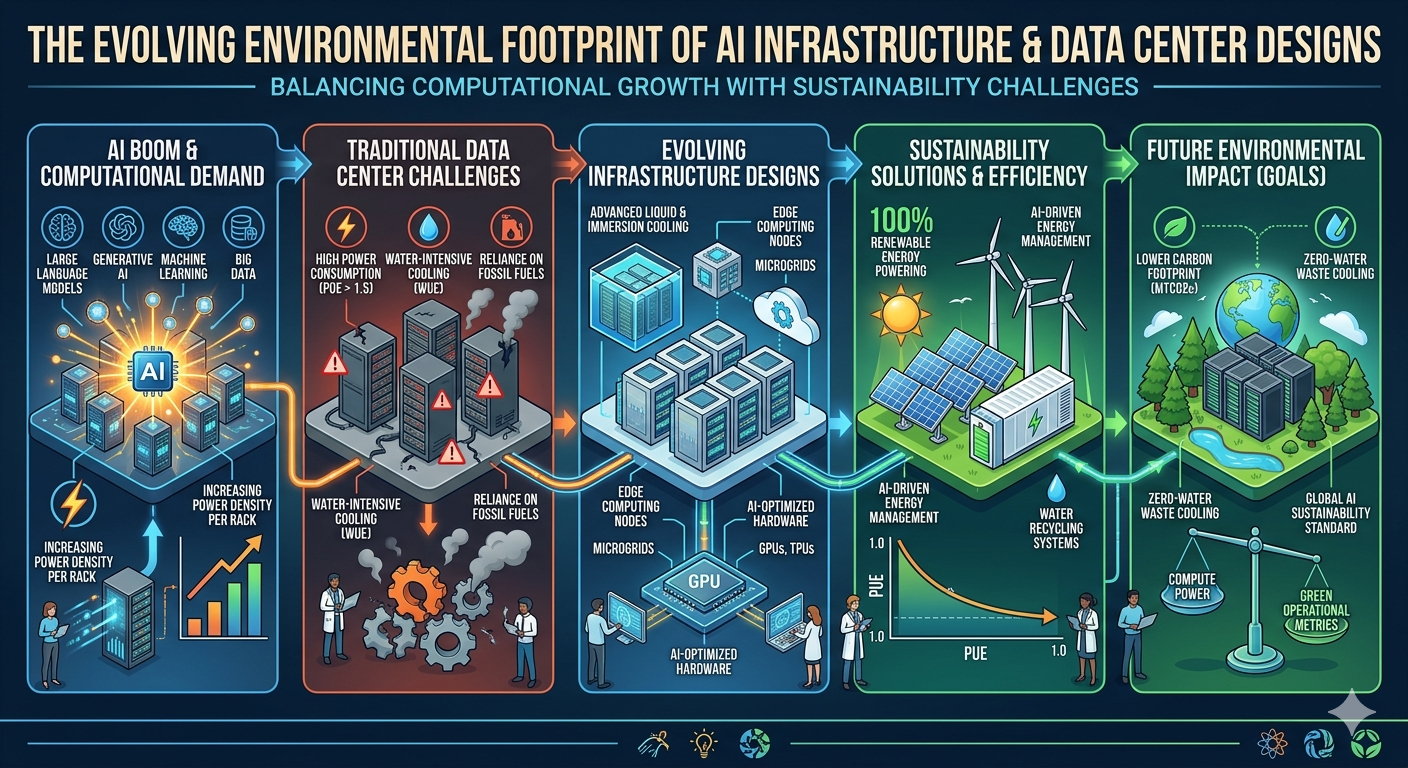
New data center designs are dramatically reducing—or in some cases eliminating—direct freshwater consumption by replacing traditional, water-intensive cooling towers with advanced thermal management technologies. Major technology companies and hardware manufacturers are rapidly deploying infrastructure designed to minimize strain on local water supplies while supporting rapidly growing computational demand.
One of the most significant developments is the adoption of modern direct-to-chip liquid cooling systems. These systems use a closed-loop coolant, typically a water-glycol mixture, which is filled once during installation and then continuously recirculated. Because the coolant is reused within a sealed system, these designs require little to no ongoing freshwater input while still efficiently removing heat from high-performance processors.
As these technologies become more widespread, it is important to recognize that blanket opposition to AI or new data centers may unintentionally slow the deployment of infrastructure that is substantially more water- and energy-efficient than earlier generations. The environmental impact of data centers depends less on their existence and more on how they are designed, powered, and cooled.
Beyond cooling systems, there are additional innovations shaping the next generation of AI infrastructure that are often overlooked. One example is the gradual replacement of copper interconnects with optical fiber. Companies such as Corning are partnering with Nvidia to introduce advanced optical networking within AI data centers. This transition significantly reduces reliance on copper, which has downstream implications for mining, extraction, and other environmentally intensive industrial processes. In turn, this shift has the potential to lower the broader ecological footprint associated with large-scale computing infrastructure.
The reason I’m outspoken on this issue is that the potential benefits of AI and modern data centers can far outweigh their costs when they’re deployed responsibly. In my work as an economist and climate scientist, I have documented a case study indicating approximately a 6,000% increase in productivity alongside a reduction of roughly 90% in utility costs under modernized systems and workflows.
That doesn’t mean every AI deployment is beneficial or that environmental concerns should be ignored. It does mean we should evaluate these technologies based on current evidence and engineering advances, rather than broad, generalized claims that treat all AI and all data centers as inherently harmful.
Addendum: A Case Study in AI Efficiency
As an economist and climate scientist, I’ve been experimenting with different AI graphic generators to evaluate them from both a marketing and an economic perspective. My objective is simple: maximize impact while minimizing cost and environmental footprint.
Rather than focusing solely on image quality, I compare the complete cost-benefit equation, including environmental resource use, computational efficiency, human labor, production time, and audience response. My goal is to identify which tools produce the greatest overall value.
My current comparison has focused primarily on ChatGPT and Google’s Nano Banana image generator. Thus far, ChatGPT has proven to be slightly more computationally expensive but often produces graphics with greater visual impact. Nano Banana, on the other hand, tends to generate a cleaner, more formal aesthetic that may resonate better with certain audiences. Both systems have strengths, and each may be the better choice depending on the intended purpose.
What surprised me most was not how difficult it was to generate the images, but how easy it became once the underlying work had been completed. The challenging part was researching the subject, writing the paper, and translating complex scientific concepts into a clear set of instructions for the AI. Once those instructions existed, both systems produced high-quality graphics in well under a minute.
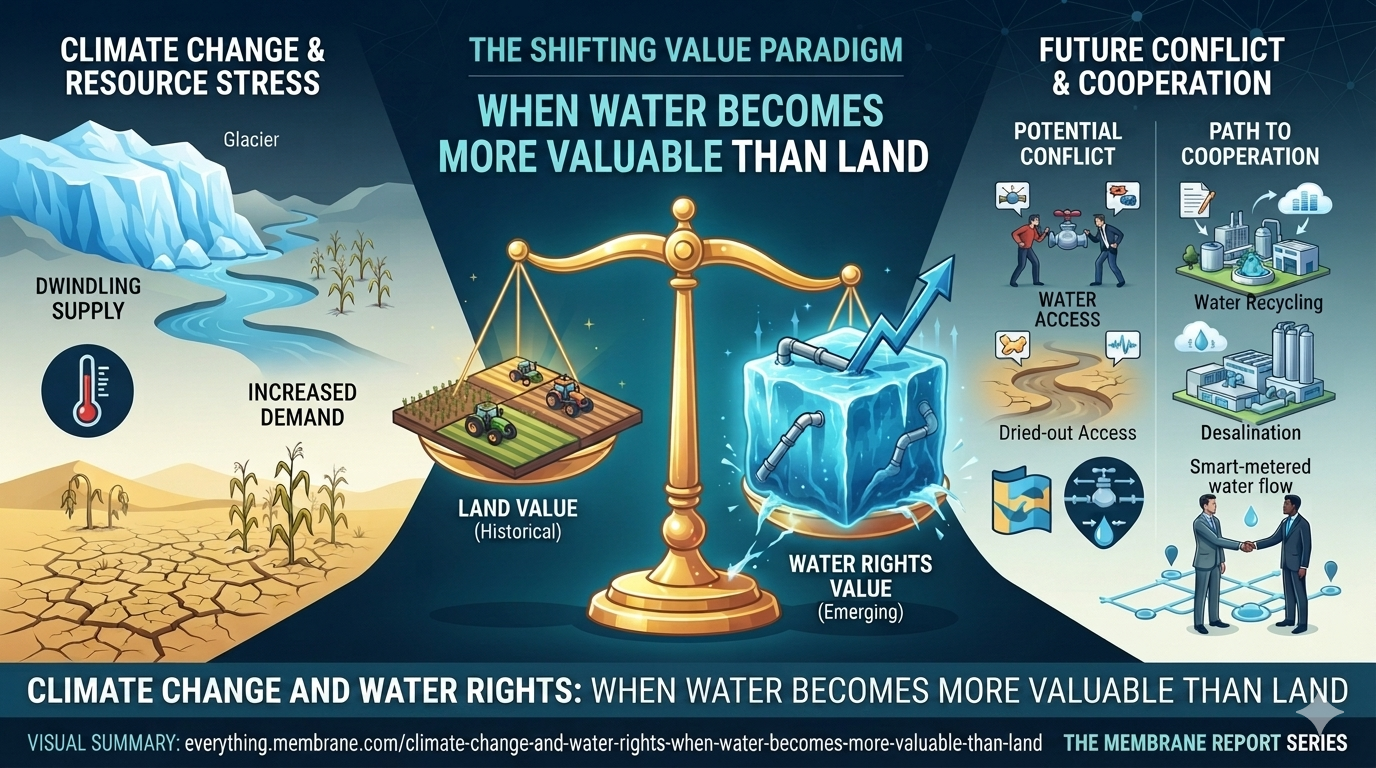
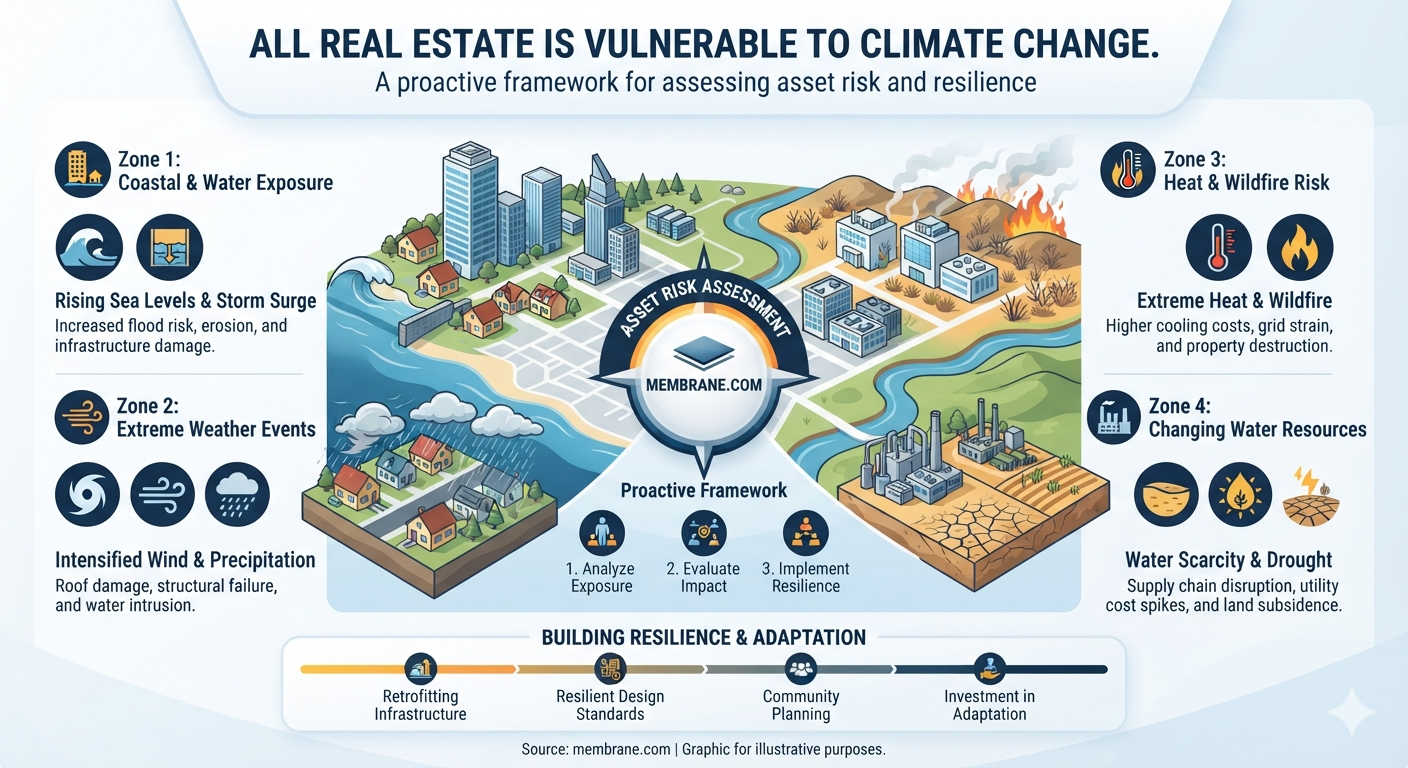
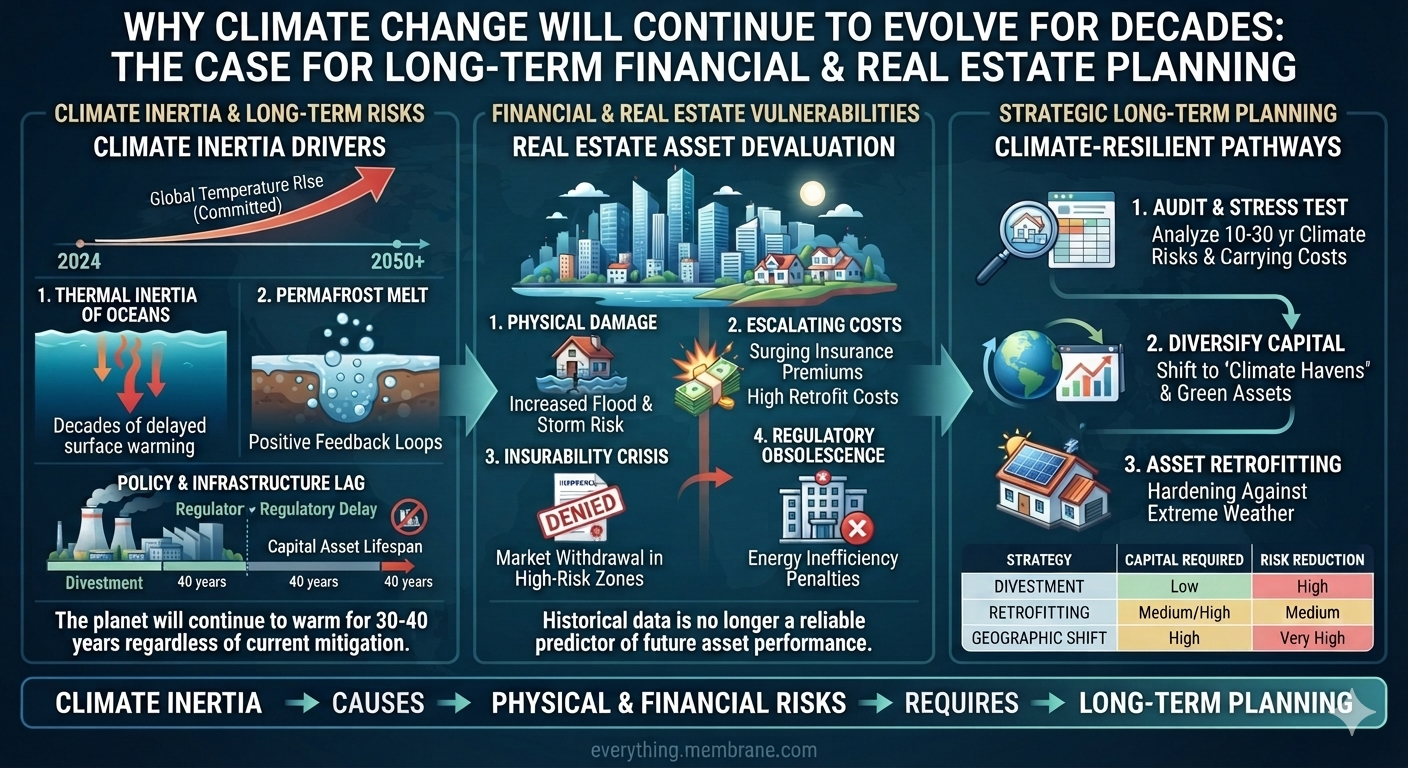
The two graphics accompanying this article illustrate the point. They were created from essentially the same prompt using two different AI systems. The Google version is estimated to have required roughly 25% fewer tokens, making it somewhat more computationally efficient, while the ChatGPT version produced a result I judged to have slightly greater marketing impact.
From an economic standpoint, the comparison is striking. Producing comparable illustrations through traditional methods could easily require hundreds of dollars in labor, software, revisions, and project management, along with the associated energy and material costs of conventional production. By contrast, the AI-generated graphics required only minutes to produce and incurred essentially no direct production cost beyond access to the AI platforms.
Although precise energy, water, and material consumption varies by hardware, data center design, and electricity source, my estimates suggest that using AI tools for this project reduced total resource consumption by well over 99% compared with creating equivalent graphics entirely through traditional manual workflows. In my own workflow, the estimated natural-resource cost was only a few cents per image.
This experience reinforces an important economic principle: productivity gains are often accompanied by reductions in resource intensity. When modern AI infrastructure is designed efficiently, it has the potential to reduce not only labor costs but also energy consumption, material use, water consumption, and overall environmental impact. Like any technology, AI should be evaluated based on measurable outcomes rather than assumptions. As the underlying infrastructure continues to improve, the environmental efficiency of these systems is likely to improve as well.
But, But, But… What About All the Other Costs and Environmental Impacts?
I understand your concerns—they’re important goals that I share. That’s why I’ve written this article explaining why I believe the benefits of modern AI infrastructure can outweigh the costs when it’s designed responsibly.
Ironically, many of the newest data center technologies can help advance the very objectives often listed. They’re becoming far more water-efficient through closed-loop cooling, more energy-efficient through advanced hardware and optical networking, and can reduce material demand by replacing large amounts of copper with fiber. AI is also accelerating the design of better batteries, more efficient renewable energy systems, smarter electrical grids, and improved land-use planning—all of which can help reduce environmental impacts over time.
From an economic perspective, I’ve found AI to be extraordinarily productive. One of our economic models projects that AI-driven automation could reduce the demand for human labor by as much as 90% over the next decade. Whether that estimate proves accurate or not, the broader trend points toward substantial productivity gains.
To me, that means the bigger societal question isn’t simply whether to build AI infrastructure. It’s how we prepare for an economy where productivity increasingly comes from intelligent systems. Issues like universal basic income, negative income taxes, wage subsidies, or other forms of national or global income support may become some of the most important policy discussions of the coming decades.
Technology itself isn’t inherently good or bad. The challenge is ensuring we deploy it in ways that improve both human well-being and environmental sustainability.