The latest U.S. tariff framework is now in place, and while tariffs are collected at the border, it’s American families who ultimately pay most of the bill.
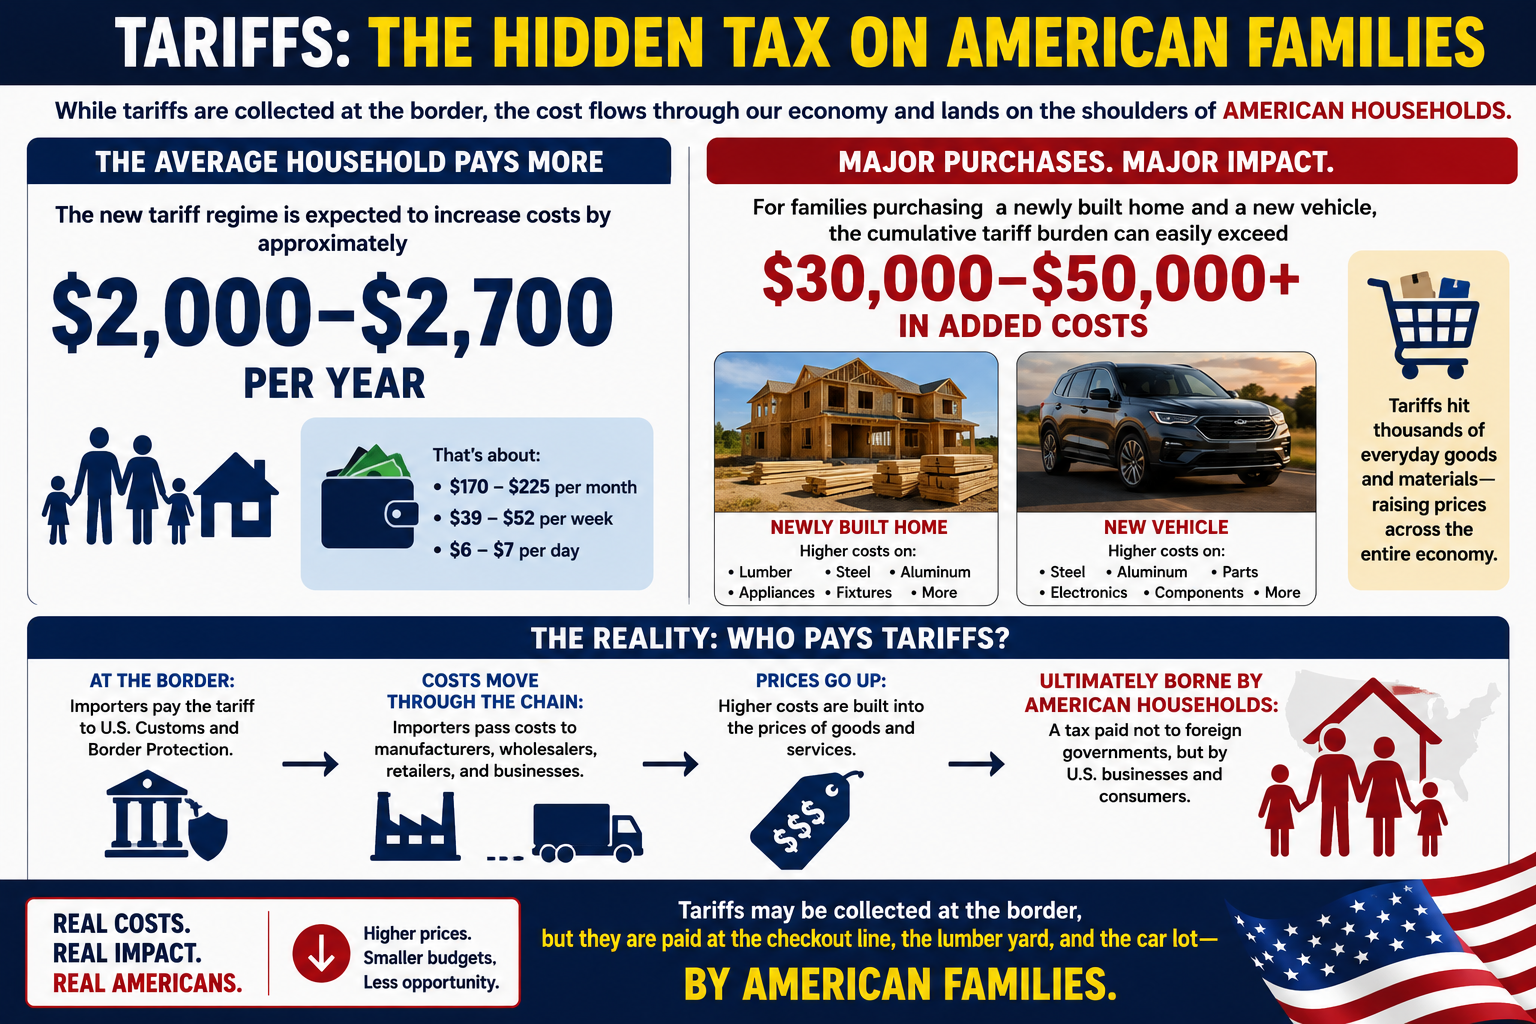
📊 Highlights: • Average household: +$2,000–$2,700 per year • Buying a new home and a new car? The added cost from tariffs on steel, aluminum, lumber, vehicles, appliances, and other goods could exceed $30,000–$50,000. • New tariffs now cover nearly 99.4% of U.S. imports from 60 trading partners, while additional 50% tariffs on many Canadian products are scheduled to begin in August.
The article explains what changed, which goods are affected, who legally pays the tariff, and who ultimately bears the economic burden.
Read the full analysis and decide for yourself: Are tariffs protecting American industry, or are they becoming one of the largest hidden taxes on American consumers?
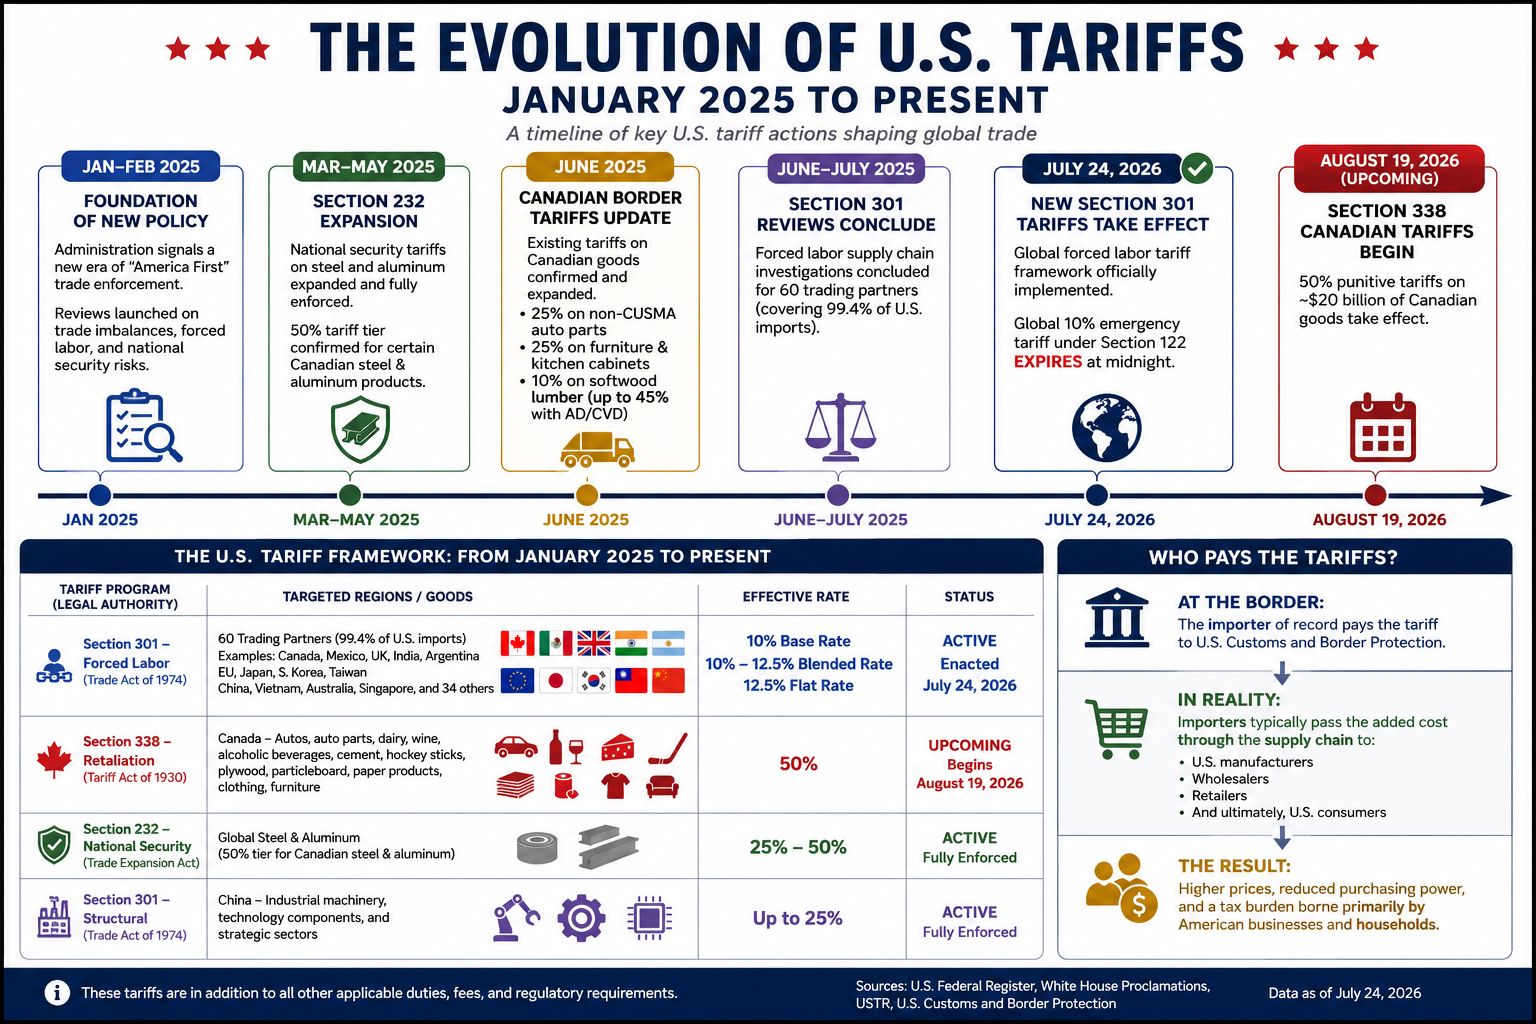
Effective July 24, 2026, the United States implemented a new tariff regime targeting imports from approximately 60 trading partners, representing 99.4% of all U.S. imports. The tariffs are based on supply-chain forced labor investigations.
Tariff Rates
10% Base Rate
Canada
Mexico
United Kingdom
India
Argentina
10%–12.5% Blended Rate
European Union
Japan
South Korea
Taiwan
12.5% Flat Rate
China
Vietnam
Australia
Singapore
34 additional economies under investigation
Exemptions
Several strategically important commodities remain exempt, including:
Crude oil
Natural gas
Fertilizer
Selected primary food products
These tariffs also do not stack with existing Section 232 national security duties.
2. Upcoming Canadian Tariffs: Section 338
Beginning August 19, 2026, the United States is scheduled to impose 50% retaliatory tariffs on approximately $20 billion of Canadian imports under Section 338 of the Tariff Act of 1930.
Products Subject to the 50% Tariff
Dairy products
Wine and other alcoholic beverages
Automobiles
Auto parts
Cement
Hockey equipment
Plywood
Particleboard
Paper products
Clothing
Furniture
These tariffs bypass normal CUSMA (USMCA) preferential treatment.
Exemptions
The following Canadian exports are excluded:
Energy products
Potash
Fish
Critical minerals
3. Existing Tariffs That Remain in Effect
Several major tariff programs adopted during 2025 and 2026 continue unchanged.
Section 232 National Security Tariffs
These duties continue to apply to steel and aluminum imports, including tariffs reaching 50% on certain Canadian steel and aluminum products.
Existing Canadian Import Tariffs
Additional tariffs remain in place on:
25% on non-CUSMA-compliant auto parts
25% on upholstered furniture and kitchen cabinets
10% tariff on Canadian softwood lumber, with combined anti-dumping and countervailing duties pushing the effective rate to approximately 45%
Section 301 China Tariffs
Long-standing tariffs on Chinese imports also remain active, with rates reaching 25% on numerous products, including:
Industrial machinery
Technology equipment
Electronic components
Strategic manufacturing inputs
Current U.S. Tariff Framework
Tariff Program
Primary Target
Rate
Status
Section 301 – Forced Labor
60 trading partners
10%–12.5%
Active (July 24, 2026)
Section 338 – Canada
Autos, dairy, wine, cement, consumer goods
50%
Begins August 19, 2026
Section 232 – National Security
Steel & aluminum
25%–50%
Active
Section 301 – China
Industrial & technology products
Up to 25%
Active
Who Really Pays Tariffs?
Legally, tariffs are paid by the U.S. importer when goods enter the country through Customs and Border Protection.
Economically, however, that is only the beginning of the story.
Importers generally recover those additional costs by increasing the prices they charge wholesalers, retailers, manufacturers, and ultimately consumers. Numerous economic studies of recent U.S. tariffs have found that most of the cost is passed through to American businesses and households rather than absorbed by foreign exporters.
In some industries, foreign suppliers may reduce prices to remain competitive, meaning they share part of the burden. But the overall trade data and pricing evidence show that the majority of tariff costs are ultimately borne within the United States through higher prices, reduced business margins, or both.
In other words, while tariffs are collected at the border from importers, they function much like a domestic consumption tax. The final bill is usually paid by American businesses and consumers—not by foreign governments.
Conclusion
For the average American household, the new tariff regime is expected to increase costs by approximately $2,000–$2,700 per year. For families purchasing a newly built home and a new vehicle, the cumulative tariff burden can easily exceed $30,000–$50,000 through higher prices on construction materials, automobiles, appliances, and other imported goods. While tariffs are collected at the border from importers, they are ultimately borne by American businesses and consumers in the form of higher prices—a tax paid not to foreign governments, but by U.S. households.
Oil is one of those subjects that’s surprisingly slippery—both physically and economically. Most people know prices go up and down, but few realize that even storing oil comes with limits.
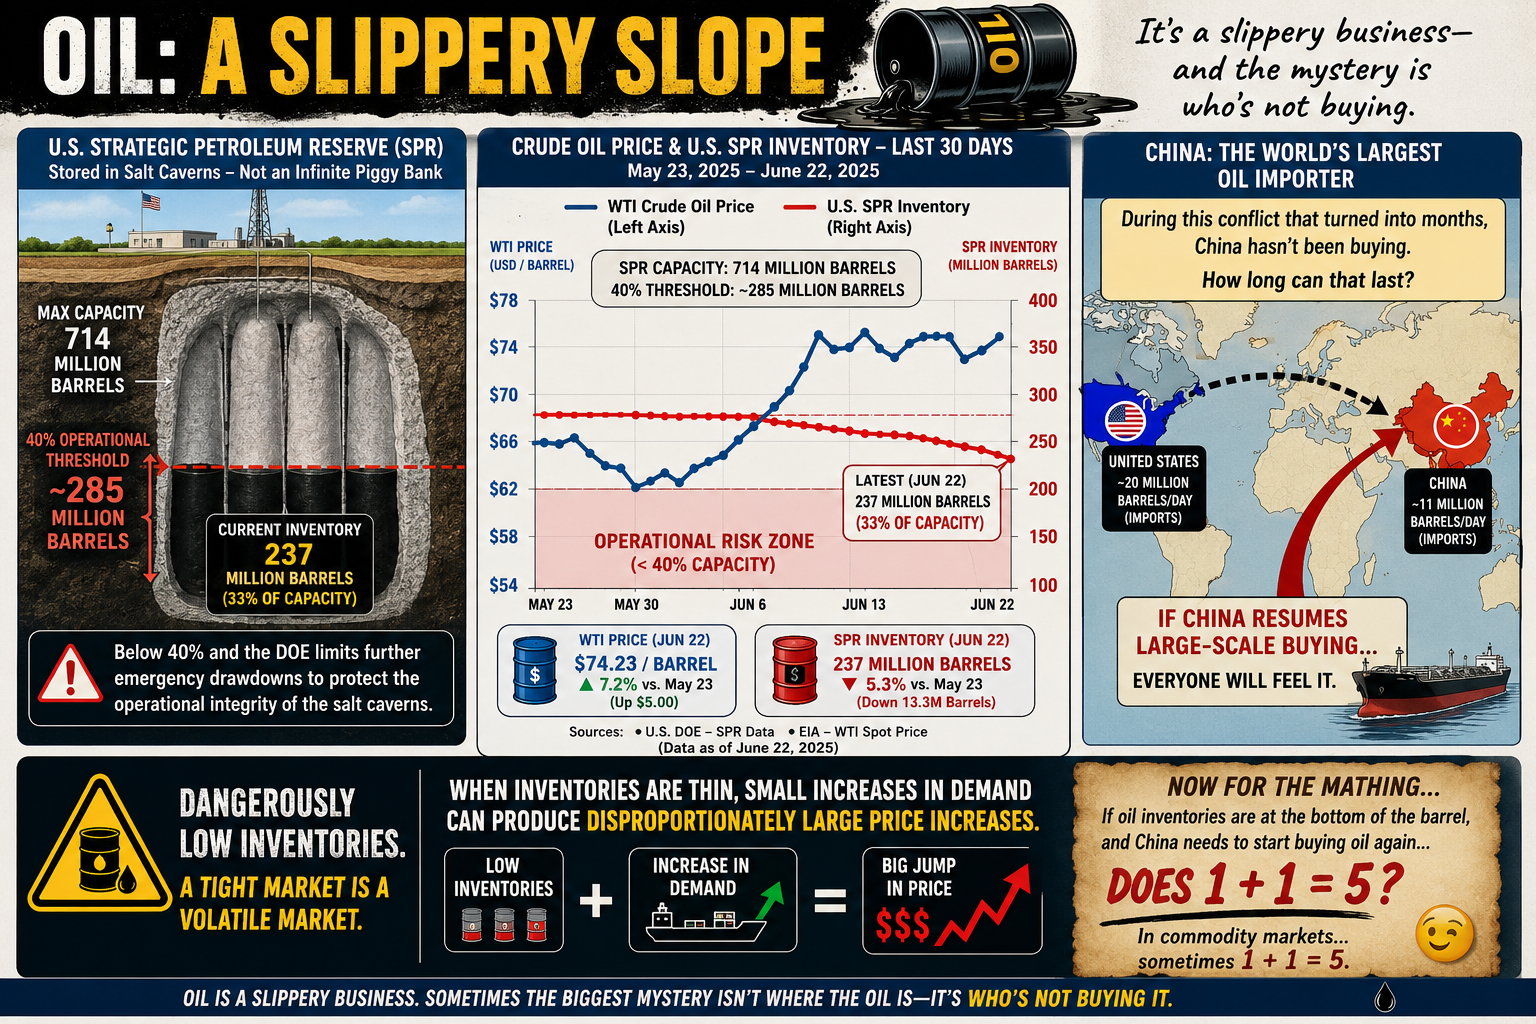
Take the U.S. Strategic Petroleum Reserve (SPR). It’s often treated like a giant underground gas tank that can be drained and refilled at will. Not quite. The reserve is stored in massive salt caverns, and if inventories fall below roughly 40% of its 714 million-barrel capacity (about 285 million barrels), the Department of Energy limits additional emergency withdrawals. The reason isn’t politics—it’s geology. Keeping enough oil in the caverns helps maintain their long-term operational integrity.
The same basic challenge applies everywhere. Oil storage isn’t as simple as stacking barrels in a warehouse. Tanks, pipelines, and underground caverns all have practical operating limits, and those limits can shape energy policy as much as supply and demand.
Then there’s China.
Despite a conflict that many expected would trigger a buying spree, China has reportedly remained on the sidelines for months rather than aggressively increasing crude purchases. Whether that’s because of existing inventories, weak domestic demand, economic strategy, or expectations of lower future prices is open to debate.
The interesting question isn’t whether China can avoid buying oil today. It’s how long it can continue doing so.
Eventually, inventories run down, demand changes, or market conditions shift. And when one of the world’s largest oil consumers steps back into the market, everyone notices.
Oil has always been a slippery business. Sometimes the biggest mystery isn’t where the oil is—it’s who’s not buying it.
Now for the Math…
If global oil inventories are scraping the bottom of the barrel, and the world’s largest importer suddenly has to start buying again…
…does 1 + 1 = 5?
Not in arithmetic. But in commodity markets, sometimes it feels that way.
When supply is already tight, prices don’t rise in a neat, linear fashion. A relatively small increase in demand can trigger a disproportionately large jump in price as buyers compete for the same limited barrels. Traders see it coming, futures markets react, inventories shrink even faster, and a little bit of demand can snowball into a much bigger price move.
In other words, 1 + 1 doesn’t equal 5 because the math changed—it equals 5 because human behavior did.
Oil markets have always had a nonlinear streak. When inventories are comfortable, an extra million barrels a day barely makes a ripple. But when stocks are running low and spare capacity is scarce, that same million barrels can feel like throwing a match into a room full of gasoline.
That’s why economists watch inventories just as closely as production. Sometimes the most important number isn’t how much oil is being pumped—it’s how much is left in the tank.
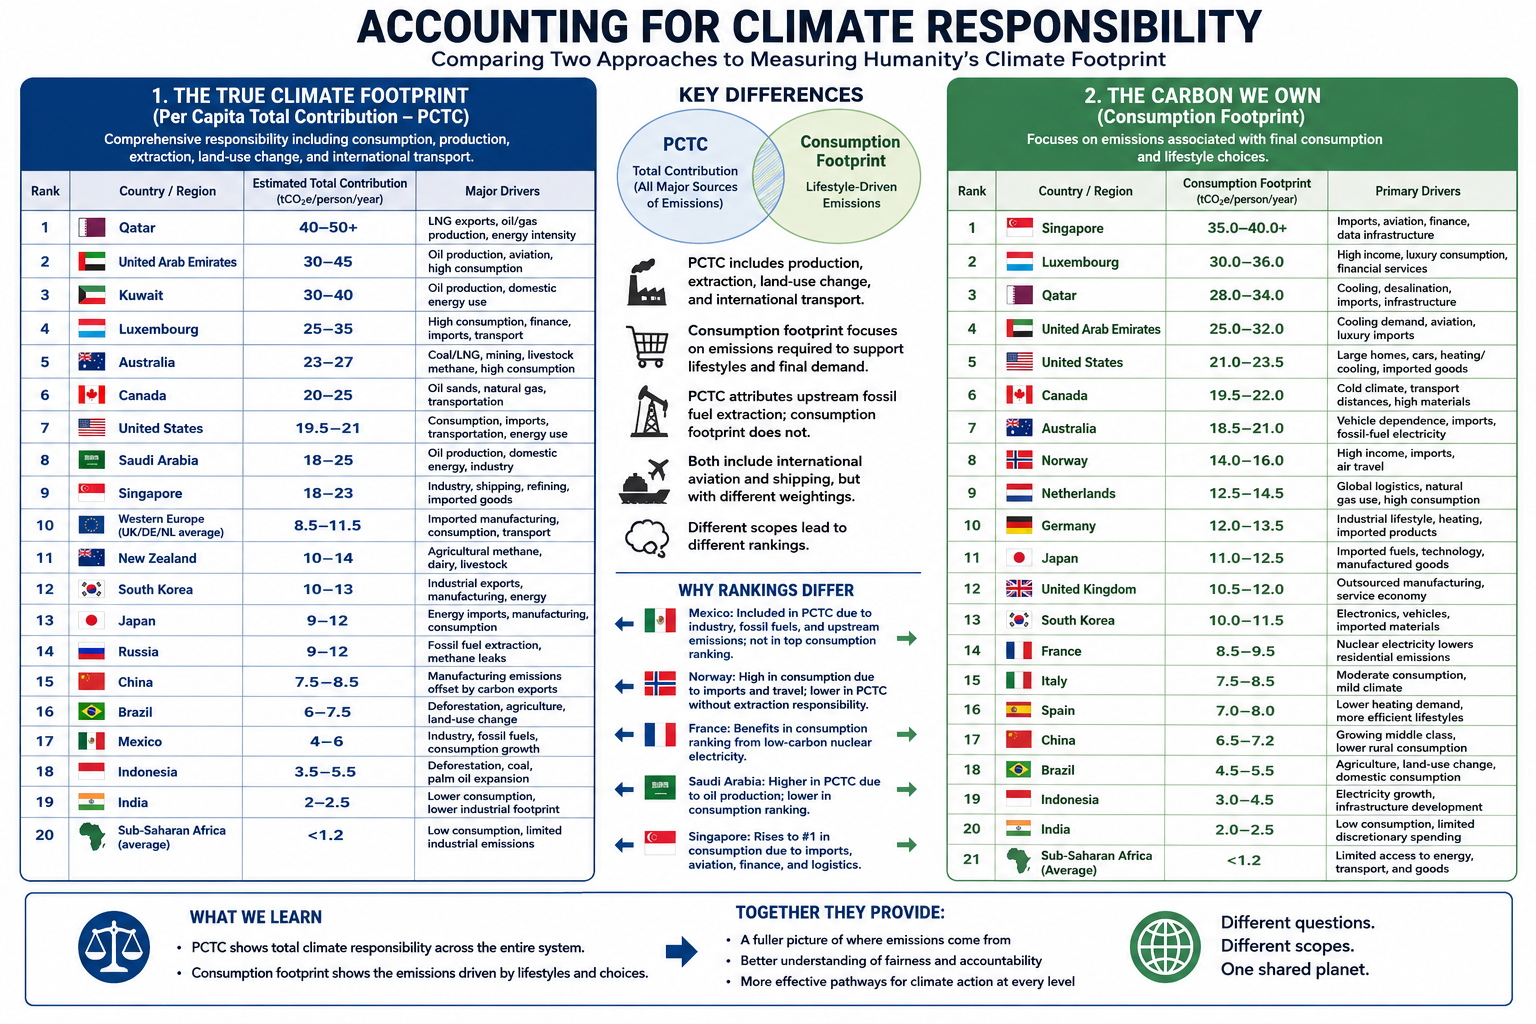
Comparing Two Approaches to Measuring Humanity’s Climate Footprint
Climate responsibility depends on how emissions are assigned. Traditional territorial accounting attributes emissions to the country where they occur, but globalization has made that approach increasingly incomplete. Modern supply chains, international trade, and service-based economies often separate where emissions are produced from who ultimately benefits from them.
To explore this problem from two different perspectives, I developed two complementary accounting frameworks.
The first paper, The True Climate Footprint: Measuring Per Capita Total Contribution Beyond Territorial Emissions, introduces the Per Capita Total Contribution (PCTC) framework. PCTC seeks to estimate an individual’s or nation’s complete climate responsibility by incorporating not only consumption, but also several major sources of emissions that are frequently omitted from conventional carbon accounting.
All major greenhouse gases (CO₂, CH₄, N₂O, and others expressed as CO₂-equivalent)
Responsibility associated with fossil fuel production where appropriate
The second paper, The Carbon We Own: Why Consumption Matters More, examines climate responsibility from a different perspective. Rather than estimating total climate contribution, it focuses specifically on the carbon footprint required to support modern lifestyles using a consumption-based accounting approach.
Unlike PCTC, this framework intentionally places less emphasis on fossil fuel extraction and producer responsibility in order to better isolate the climate impacts associated with everyday consumption.
After completing the first paper, I wanted to examine the climate footprint from the perspective of the consumer rather than the entire climate system. The PCTC framework provides a comprehensive measure of total responsibility, but it does not distinguish as clearly between emissions driven by individual lifestyle choices and those associated with resource extraction or national production.
A consumption-based framework highlights decisions that individuals and societies can influence more directly. Choices such as lowering a home’s thermostat, improving insulation, selecting public transportation or electric vehicles instead of internal combustion vehicles, reducing air travel, or purchasing fewer carbon-intensive goods become more visible within the accounting. It also better captures the increasingly important role of service-based economies. While services may appear less energy-intensive than manufacturing, sectors such as healthcare, finance, telecommunications, cloud computing, and artificial intelligence rely on extensive digital infrastructure—including energy-hungry data centers—that can be substantially underrepresented in traditional emissions inventories.
Finally, I wanted a more detailed comparison among developed economies, particularly within Europe. Countries such as Norway and France illustrate why accounting methodology matters. Norway has one of the world’s cleanest domestic electricity systems, powered primarily by hydropower, yet it is also a major exporter of oil and natural gas. France, by contrast, derives much of its electricity from nuclear power, resulting in comparatively low-carbon domestic energy while maintaining a high standard of living. Comparing these countries under both frameworks reveals how different accounting methods assign responsibility and helps illustrate the strengths and limitations of each approach.
Taken together, these two papers do not compete—they answer different questions. Per Capita Total Contribution (PCTC) asks, What is humanity’s full climate responsibility?Consumption-based accounting asks, What emissions are required to sustain the lifestyle of the average resident? Used together, they provide a more complete understanding of climate responsibility than either framework alone.
Conclusion
Although The True Climate Footprint and The Carbon We Own both seek to improve upon traditional territorial emissions accounting, they answer different questions because they are built on different accounting frameworks.
The True Climate Footprint uses the Per Capita Total Contribution (PCTC) framework to estimate an individual’s or nation’s complete contribution to climate change. It extends beyond consumption to include land-use change, upstream fossil fuel extraction, international shipping and aviation, and the full spectrum of greenhouse gases. In some cases, it also attributes responsibility associated with fossil-fuel production, providing a broad measure of humanity’s total climate impact.
By contrast, The Carbon We Own focuses specifically on consumption-based climate responsibility. Using Multi-Regional Input-Output (MRIO) accounting, it assigns emissions to the final consumer by emphasizing direct household energy use, embedded emissions in imported goods, services, and lifestyle choices. It intentionally deemphasizes extraction and producer responsibility in order to better represent the carbon footprint required to sustain modern patterns of consumption.
Because these frameworks measure different aspects of climate responsibility, their rankings are not expected to be identical.
Mexico provides a useful illustration. Under the PCTC framework, Mexico’s estimated footprint includes domestic industry, fossil fuel production, growing consumption, and upstream emissions, resulting in an estimated contribution of approximately 4–6 tonnes of CO₂-equivalent per person per year. In the consumption-based analysis, however, Mexico does not appear among the highest-ranking countries because the focus is limited to end-user consumption, and the published rankings emphasize the world’s largest per-capita consumption footprints.
Similar differences appear elsewhere. Norway’s position changes substantially because one framework incorporates the climate responsibility associated with fossil fuel production, while the other emphasizes domestic consumption. France benefits in the consumption-based analysis because its low-carbon nuclear electricity reduces household emissions despite maintaining a high standard of living. Saudi Arabia ranks differently depending on whether responsibility is assigned to oil production or to energy consumption. Singapore rises dramatically under consumption accounting because imported goods, international aviation, finance, logistics, and digital infrastructure contribute heavily to its consumption footprint despite relatively limited domestic manufacturing.
These examples demonstrate that accounting methodology influences how climate responsibility is distributed. Production-based, consumption-based, and total-contribution frameworks each illuminate different dimensions of the global climate system.
Rather than viewing these approaches as competing methodologies, they should be regarded as complementary analytical tools. The Per Capita Total Contribution (PCTC) framework asks, What is a nation’s or individual’s total contribution to climate change? The consumption-based framework asks, What emissions are required to sustain the average resident’s lifestyle? Together, they provide a more complete understanding of climate responsibility than either approach can achieve alone, revealing both the systemic impacts of resource production and the powerful role of consumer demand in shaping the global climate.
For decades, climate responsibility has often been measured by where fossil fuels are extracted or where products are manufactured. While useful for tracking national emissions, this production-based approach can misrepresent who ultimately drives demand.
A consumption-based accounting approach shifts the focus to the end user. Instead of assigning emissions to the country where a product is made, it attributes emissions to the people and businesses that ultimately consume the energy, goods, and services.
Under this framework, every kilowatt-hour of electricity, every heating bill, every medical service, and every consumer product is assigned to its final destination.
For example, if a smartphone is manufactured in Asia using electricity generated from coal and then shipped across the Pacific to a consumer in Los Angeles, the emissions associated with mining, manufacturing, transportation, and delivery are attributed to the American consumer—not the manufacturing country.
This approach provides a more accurate picture of the carbon footprint associated with modern lifestyles.
How Consumption-Based Carbon Accounting Works
Most consumption analyses rely on Multi-Regional Input-Output (MRIO) economic models, which trace emissions through global supply chains before assigning them to final consumers.
Individual carbon footprints are generally divided into three major categories:
1. Direct Household Energy
Emissions from energy used directly by households, including:
Home heating and cooling
Residential electricity
Personal vehicle fuel
Digital activities such as internet usage and streaming services
2. Embedded Goods
Emissions generated while producing and transporting purchased products, including:
Electronics
Vehicles
Furniture
Clothing
Building materials
Household appliances
These emissions often occur in countries far from the final consumer.
3. Services
Many of the largest emissions in developed economies come not from physical products but from services, including:
Healthcare
Commercial aviation
Banking and finance
Cloud computing
Water and wastewater treatment
Telecommunications
In the United States alone, healthcare contributes roughly 1.6 tonnes of CO₂-equivalent emissions per person each year, illustrating how service-based economies can generate substantial carbon footprints even as heavy industry declines.
Major Findings from Global Consumption Accounting
The Rise of Service Economies
In wealthy economies such as Singapore, Luxembourg, and several Western European countries, manufacturing represents only a small portion of domestic emissions.
Instead, much of their climate impact comes from:
Commercial aviation
Financial systems
Cloud computing
Global logistics
Luxury consumption
High levels of imported goods
As economies become increasingly service-oriented, carbon emissions become embedded in complex international supply chains rather than local smokestacks.
Geography Still Matters
Climate strongly influences direct household energy use.
Countries with long, cold winters or extremely hot summers require substantially more energy for climate control.
For example:
Canada and the United States consume large amounts of energy for winter heating and summer air conditioning, particularly because of larger average home sizes.
Australia records comparatively higher emissions from agriculture, mining, and infrastructure development than from residential heating.
Local climate remains an important contributor even after imported goods are included.
China’s Manufacturing Versus Consumption
China illustrates one of the largest differences between production-based and consumption-based accounting.
Because China manufactures enormous quantities of products for export, its territorial emissions are among the highest in the world.
However, when emissions are allocated to the people who ultimately purchase those products, China’s domestic per-capita consumption footprint is estimated at roughly 6.8 tonnes of CO₂-equivalent per year.
This highlights the distinction between:
Production emissions (where goods are made)
Consumption emissions (who ultimately benefits from those goods)
Many products manufactured in China are consumed in North America and Europe, meaning a significant share of manufacturing emissions is driven by foreign demand.
Consumption Footprints Across Europe
Norway: Clean Electricity, High Consumption
Estimated consumption footprint: 14.8 tonnes CO₂e per person
Norway’s electricity is more than 85% hydropower, giving it one of the cleanest electrical grids in the world.
Yet Norwegians have high purchasing power and consume large quantities of imported goods, including:
Electric vehicles
Consumer electronics
Luxury goods
Imported foods
Norway also has one of the world’s highest rates of air travel per capita, increasing its service-sector emissions.
The result is a consumption footprint considerably larger than its territorial emissions suggest.
United Kingdom: Outsourcing Manufacturing
Estimated consumption footprint: 11.2 tonnes CO₂e per person
The United Kingdom has significantly reduced domestic production emissions by retiring coal-fired power plants and expanding renewable electricity.
However, much of the country’s manufacturing has shifted overseas.
The UK imports large quantities of:
Electronics
Machinery
Clothing
Construction materials
Consequently, much of its carbon footprint exists outside its borders, while domestic emissions increasingly come from finance, digital infrastructure, commercial services, and transportation.
France: The Nuclear Advantage
Estimated consumption footprint: 9.2 tonnes CO₂e per person
France demonstrates how a low-carbon electricity system can substantially reduce consumption emissions.
French households enjoy living standards comparable to neighboring Western European countries, yet much of their residential electricity, rail transportation, and heating is supplied by nuclear energy.
As a result, France’s direct household energy emissions are estimated to be roughly 30% lower than those of many neighboring countries with similar consumption patterns.
China Compared with Western Europe
When emissions are assigned to consumers rather than producers, an average citizen in countries such as Germany or the United Kingdom is responsible for nearly twice the carbon footprint of the average Chinese citizen.
Although China’s middle class continues to grow and domestic consumption is increasing, much of the country’s industrial output still serves international markets.
This comparison illustrates a key insight of consumption-based accounting:
A nation’s production does not necessarily reflect the climate impact of its residents’ lifestyles.
A Different Way to Think About Climate Responsibility
Consumption-based accounting reframes climate responsibility by asking a simple question:
Who ultimately benefits from the energy and resources consumed?
Rather than focusing solely on where emissions occur, this approach follows products and services through global supply chains to their final users.
For affluent economies that import large volumes of manufactured goods while exporting much of their industrial production, consumption-based accounting often reveals substantially higher per-capita climate footprints than traditional territorial inventories.
Viewed through this lens, lifestyle choices, purchasing power, housing, transportation, travel, healthcare, digital services, and overall consumption patterns become the primary drivers of individual climate responsibility.
Ultimately, the atmosphere responds to total emissions, regardless of where they occur. Consumption-based accounting provides a complementary perspective to traditional production-based inventories by connecting those emissions to the people and economies whose demand created them.
Global Consumption Footprint Rankings
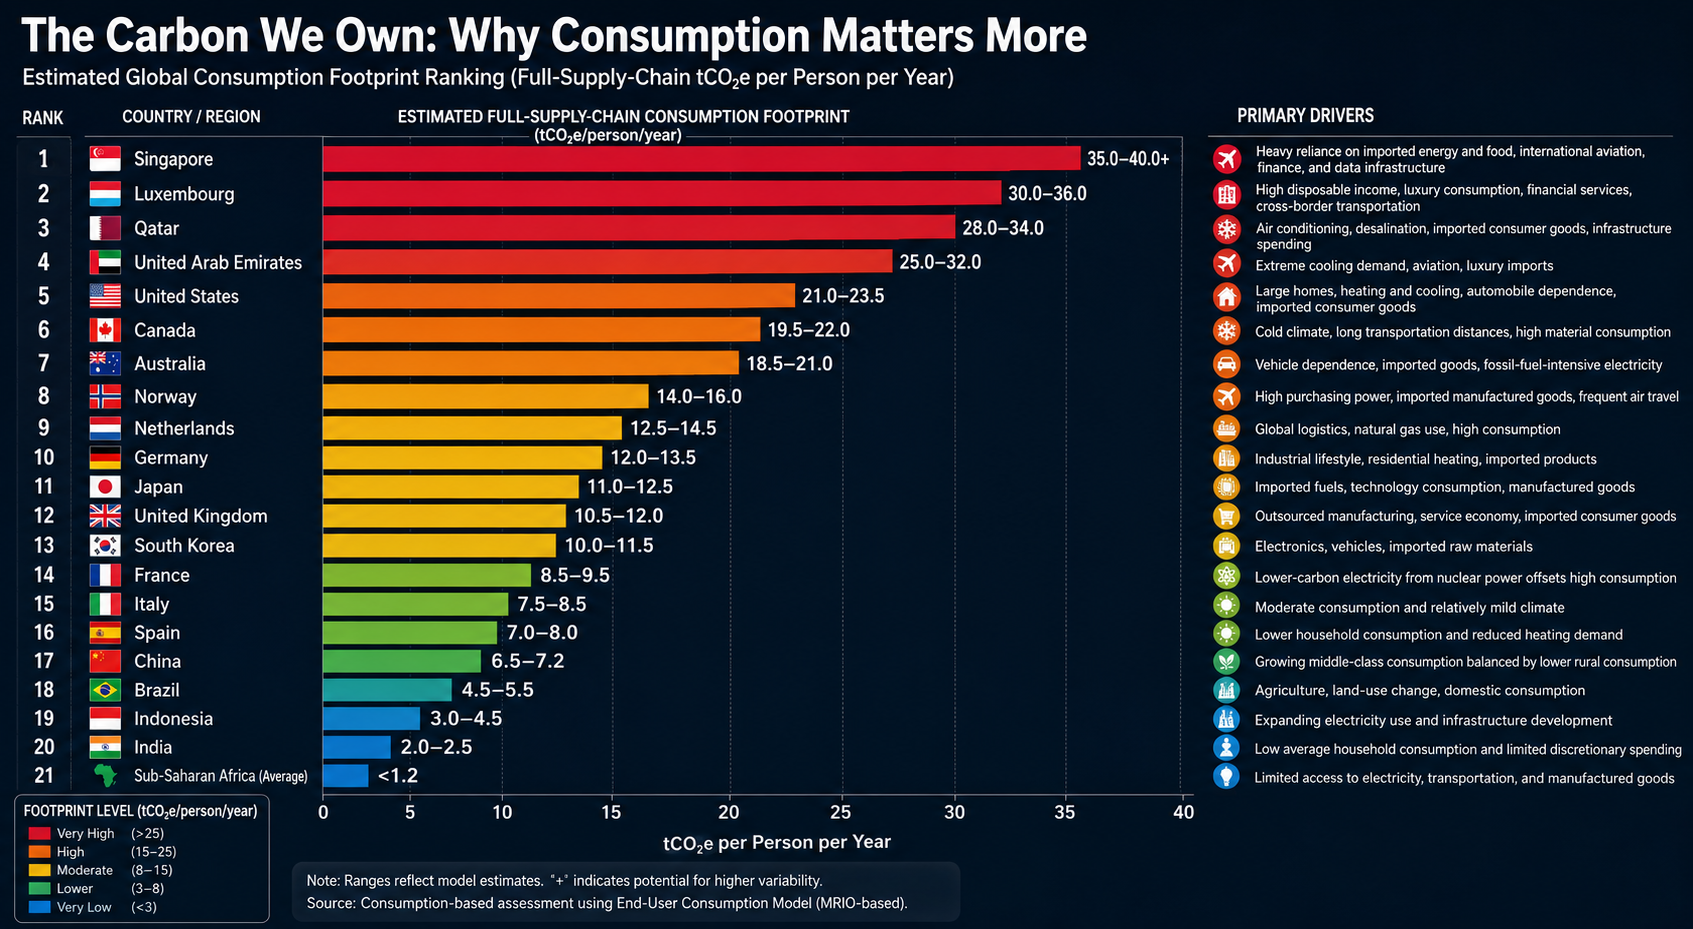
Traditional emissions inventories assign carbon pollution to the country where fossil fuels are extracted or products are manufactured. A consumption-based accounting approach instead assigns those emissions to the people and economies that ultimately consume the goods and services.
The rankings below are based on an End-User Consumption Model, which allocates the full upstream supply-chain emissions—including raw material extraction, manufacturing, international transportation, agricultural land-use change, and other embedded emissions—to the final purchaser.
Rather than measuring where emissions occur, this framework estimates the carbon footprint required to sustain the average lifestyle of a country’s residents. It reflects direct household energy use, consumption of imported goods, transportation, public infrastructure, and carbon-intensive services.
Expanding electricity use and infrastructure development
20
🇮🇳 India
2.0–2.5
Low average household consumption and limited discretionary spending
21
Sub-Saharan Africa (Average)
<1.2
Limited access to electricity, transportation, and manufactured goods
Key Patterns
Small, Wealthy Nations Have the Largest Per-Capita Footprints
Singapore and Luxembourg rank highest despite having relatively little domestic heavy industry. Their residents consume large quantities of imported goods and services, while extensive international transportation, finance, aviation, and digital infrastructure contribute substantial embedded emissions.
High-Income, Car-Oriented Economies Form the Next Tier
The United States, Canada, and Australia consistently rank among the world’s largest per-capita consumers. Large homes, automobile-dependent communities, extensive heating or cooling needs, and high levels of discretionary consumption combine to produce substantial lifestyle-related emissions.
Countries such as France and Norway demonstrate that cleaner electricity significantly lowers household energy emissions. However, imported goods, international travel, and service-sector activities remain important contributors to their overall consumption footprints.
Manufacturing Countries Are Not Necessarily the Largest Consumers
China’s production-based emissions are among the highest globally because it manufactures goods for international markets. Under a consumption-based framework, however, the average Chinese citizen’s lifestyle footprint remains considerably lower than that of residents in many affluent Western countries.
Consumption Capacity Is the Strongest Predictor
Perhaps the clearest finding is the enormous gap between affluent economies and developing regions. Average per-capita consumption in Sub-Saharan Africa remains a small fraction of that in the world’s wealthiest nations, reflecting differences in income, energy access, transportation, housing, and consumer purchasing power.
This comparison underscores a central conclusion of consumption-based accounting: the carbon footprint of an individual is driven primarily by the scale and complexity of the lifestyle they support, rather than the geographic location where the associated emissions physically occur.
When I began this journey more than three decades ago, I wasn’t a climate researcher. I was a financial planner specializing in business, economics, estate planning, and risk management. My academic background included economics, philosophy, and extensive study in physics, calculus, statistics, and systems analysis. My career focused on a simple question:
How do you create the best possible future for the people who come after you?
In the early 1990s, I met a brilliant scientist named Sidd. We shared a curiosity about complex systems and a desire to test ideas rather than simply debate them. Together, we began an experiment that has now spanned more than thirty years.
Our goal was unusual. We wanted to build what we jokingly called a one-size-fits-all, bulletproof shareware estate plan—not for one family, but for every family on Earth.
At the same time, I was helping pioneer some of the earliest privately owned web servers. Before commercial hosting became commonplace, we were operating online while many organizations were still connected through universities. It was the same era when Yahoo! itself was running from Stanford University.
By 1995, our website, KingArthur.com, was attracting millions of visitors each month. The internet gave us something few researchers had ever possessed: the ability to interact directly with millions of people across cultures, countries, religions, and generations.
One question became central to our experiment:
“When it comes to your life and what you leave behind, what is the single most important thing?”
We expected many people to answer with wealth, success, fame, or legacy.
Instead, they overwhelmingly answered something much simpler.
Among people under fifty, the most common answer was their children.
Among those over fifty, the answer shifted to their grandchildren.
The experiment revealed something profound. The greatest wealth most people hope to preserve is not money. It is the opportunity for future generations to experience the same joys they have experienced themselves.
In other words, the ultimate estate plan is remarkably simple:
To my children’s children’s children.
The greatest inheritance most of us hope to leave is not a larger bank account. It is the chance for our descendants to raise children of their own, watch them grow, and someday become grandparents themselves.
When we began this experiment, I did not have grandchildren.
Today I do.
That changes everything.
Coincidentally, I was recently asked a question that perfectly captured the purpose of this work:
“Can you play with me on this? I’m wearing my nutritional ecologist hat here, and I’m in a municipal-level discussion that is trying to zoom out seven generations while also identifying the baby steps needed over the next four-year election cycle.”
My immediate thought was:
Exactly.
That is what this experiment has always been about.
An estate plan should not end with our children—or even our grandchildren. It should extend seven generations into the future.
My grandchildren deserve the opportunity to become grandparents themselves. Their grandchildren deserve the same opportunity.
That is entirely achievable—but only if we make wise decisions today.
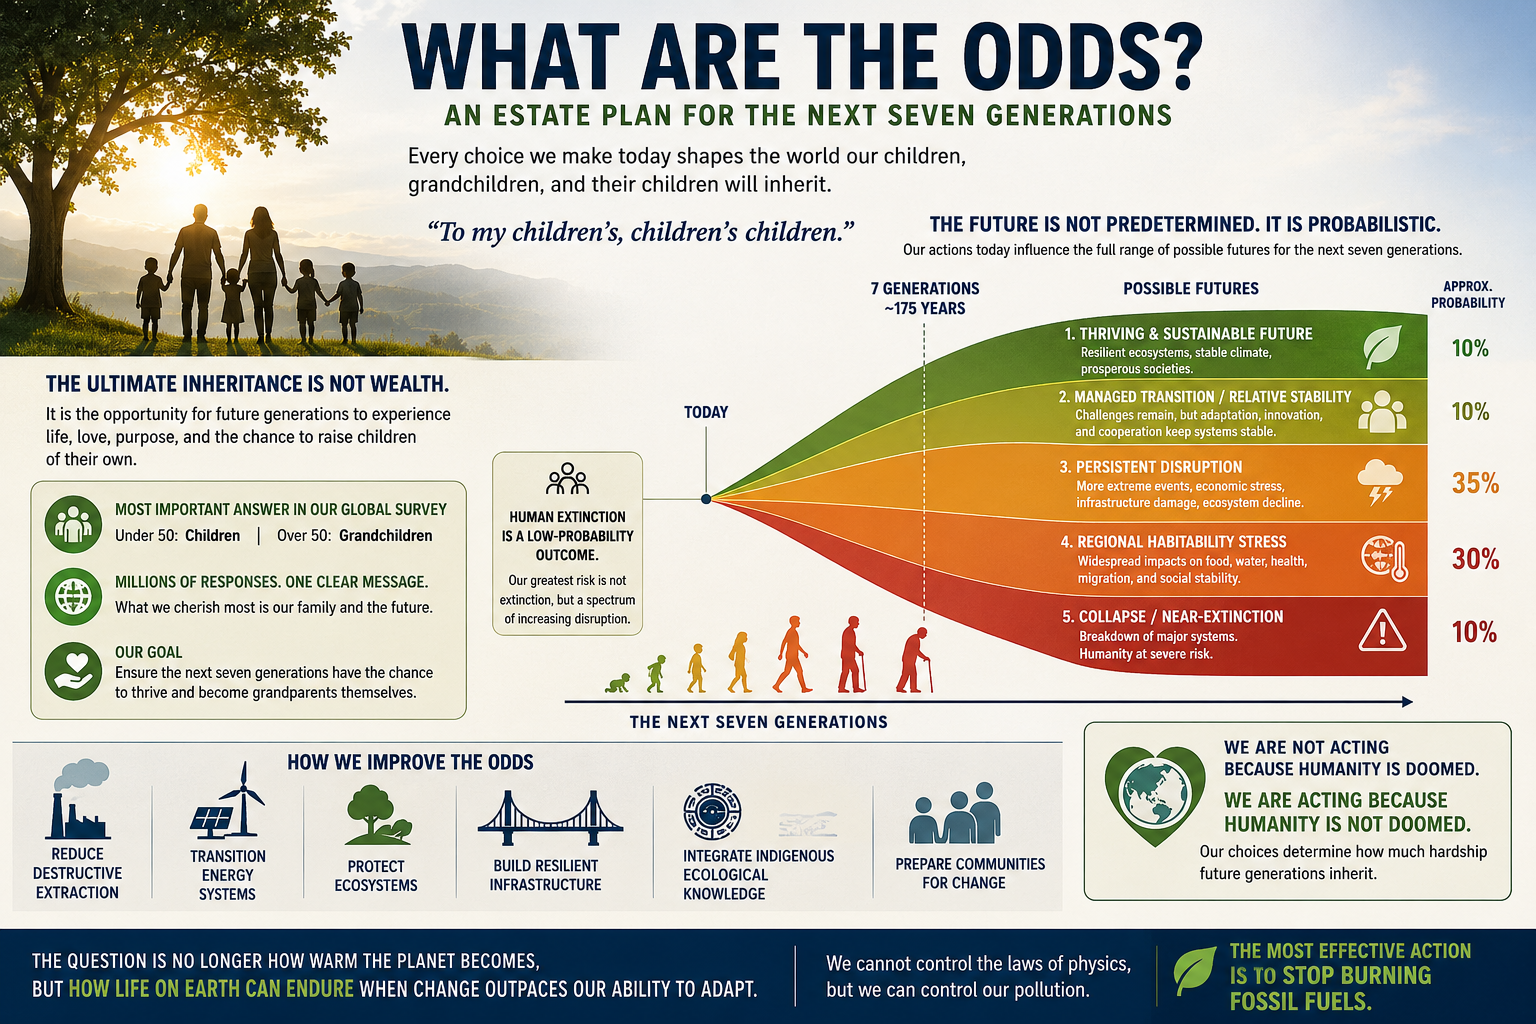
The graph that follows illustrates that idea.
Every choice we make now influences the range of possible futures available to the next seven generations.
Some outcomes are relatively optimistic. Some involve increasing climate disruption.
Some are far more severe.
Importantly, human extinction remains a low-probability outcome.
The far more likely future is not one of sudden extinction, but one that spans a spectrum of increasing disruption—affecting ecosystems, agriculture, infrastructure, economies, public health, migration, and regional habitability.
The probabilities are not fixed. They are shaped by the decisions humanity makes over the coming decades.. including today.
That changes the conversation entirely.
The question is no longer:
“Are humans going extinct?”
The more important question is:
“How difficult do we want life to be for the next seven generations?”
That question naturally leads to practical priorities:
Reduce destructive extraction of fossil fuels and natural resources.
Transition to cleaner and more resilient energy systems.
Protect and restore forests, wetlands, and other ecosystems.
Build infrastructure capable of withstanding future climate conditions.
Integrate Indigenous ecological knowledge alongside modern science.
Prepare communities to adapt to unavoidable change.
The most important message is this:
We are not acting because humanity is doomed.
We are acting because humanity is not doomed.
Our choices today determine how much hardship future generations inherit.
Ultimately, this is not simply a discussion about climate change.
It is an estate planning exercise on a planetary scale.
The question is no longer how warm the planet becomes.
The question is how well civilization—and the generations that follow us—can endure as environmental change accelerates faster than our ability to adapt.
We cannot rewrite the laws of physics. But we can decide how much pollution we continue to add to the atmosphere.
The most effective step we can take is also the simplest:
Stop burning fossil fuels as quickly and responsibly as possible, while building a more resilient world for the generations that follow.
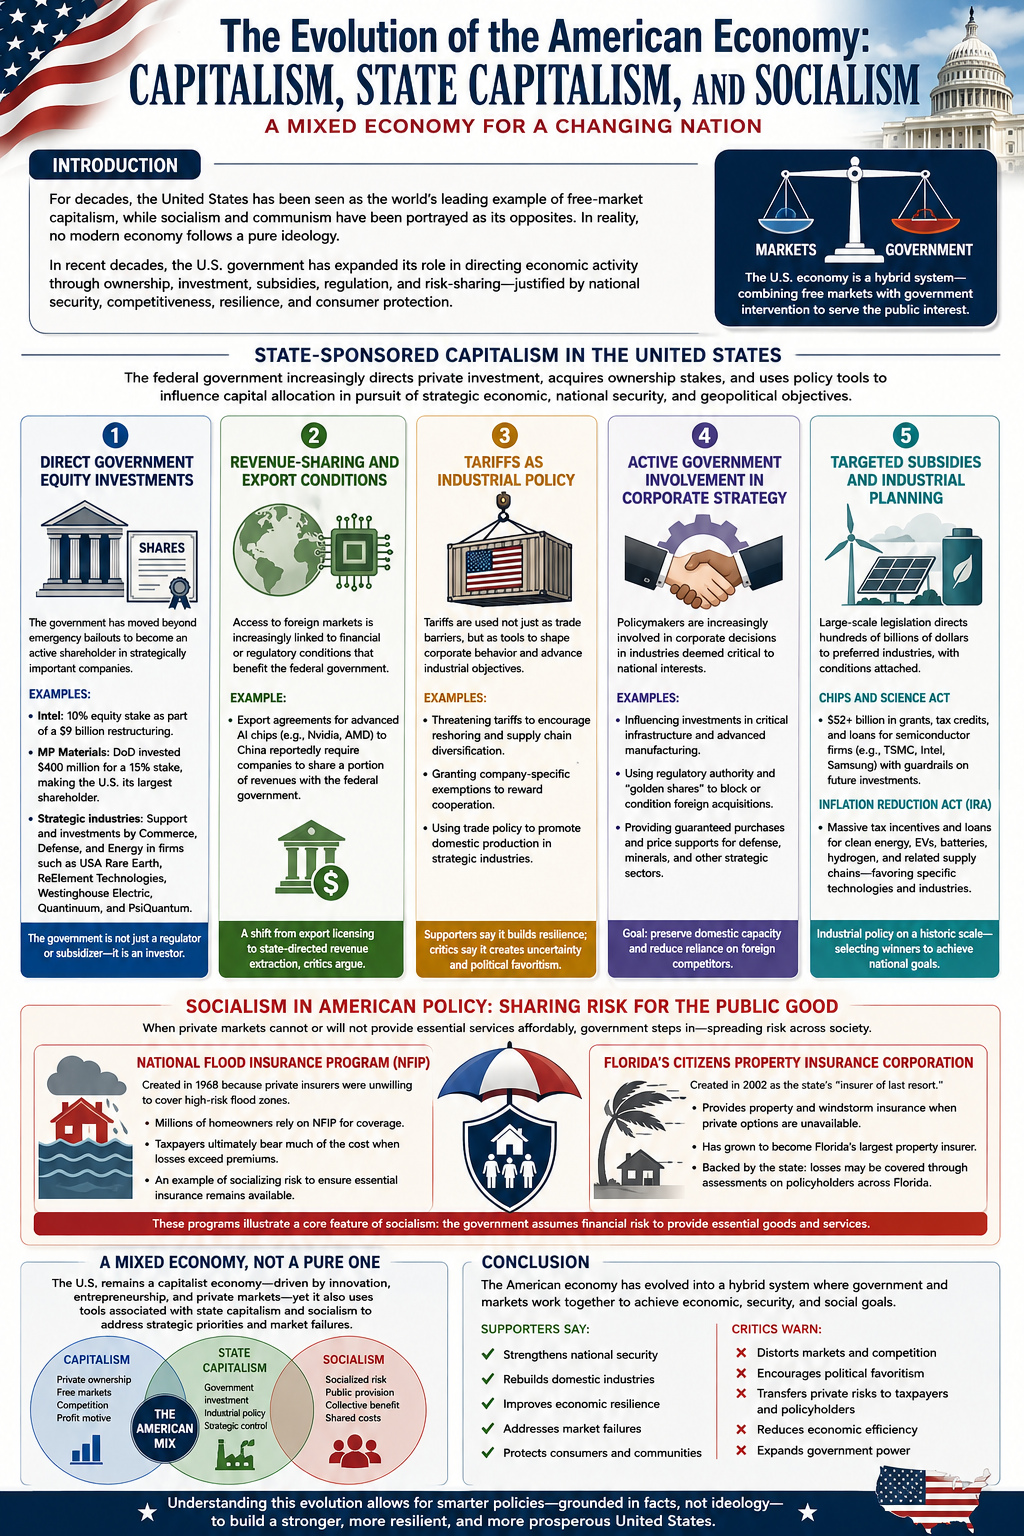
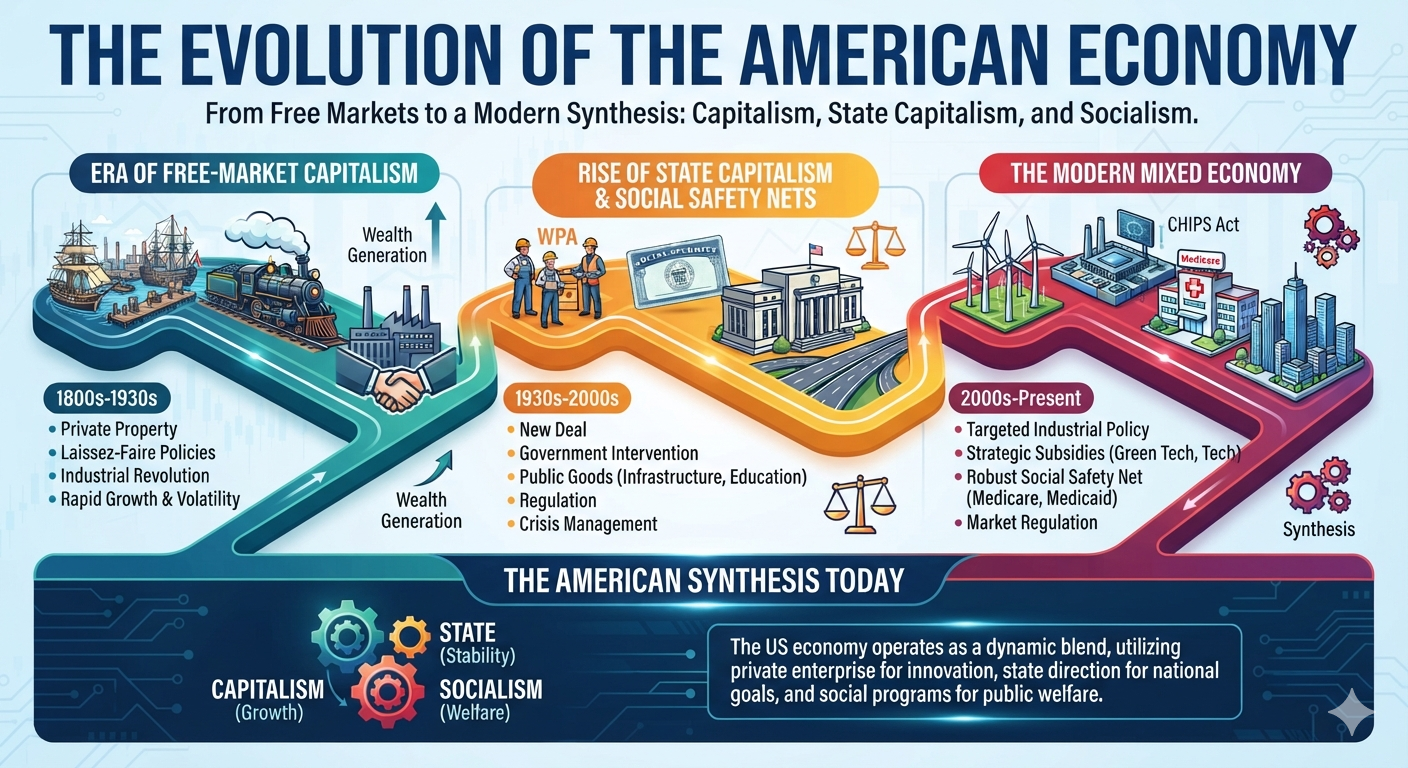
For much of its history, the United States has been portrayed as the world’s leading example of free-market capitalism, while socialism and communism have often been presented as fundamentally incompatible with American economic principles. In reality, no modern economy operates as a pure ideological model. Instead, governments continually adapt their economic policies in response to war, financial crises, technological competition, natural disasters, and changing national priorities.
Over the past several decades—and especially in recent years—the United States has significantly expanded the role of government in directing economic activity. Federal and state governments now provide targeted subsidies, acquire ownership stakes in private companies, shape investment decisions, guarantee markets for strategic industries, and assume financial risks that private markets are unwilling to bear. These policies are generally justified on the grounds of national security, economic competitiveness, supply-chain resilience, disaster recovery, or consumer protection.
This paper examines how these policies reflect characteristics traditionally associated with state-sponsored capitalism and socialism. Rather than arguing that the United States has abandoned capitalism, it demonstrates how the American economy has evolved into a hybrid system that combines free markets with substantial government intervention. Understanding this evolution provides important context for evaluating current economic policy and the changing relationship between government and private enterprise.
State-Sponsored Capitalism in the United States
State-sponsored capitalism (also called state capitalism) refers to an economic system in which the government plays an increasingly active role in directing private investment, acquiring ownership stakes in companies, or using public policy to influence capital allocation in pursuit of strategic economic, national security, or geopolitical objectives.
In recent years, the United States has moved further toward this model. While market mechanisms remain the foundation of the U.S. economy, successive administrations have expanded the federal government’s role through direct investments, industrial policy, subsidies, export controls, tariffs, and other forms of intervention designed to strengthen domestic manufacturing, secure critical supply chains, and enhance national competitiveness.
The principal mechanisms through which the federal government has pursued state-sponsored capitalism include the following:
1. Direct Government Equity Investments
Historically, federal ownership of private corporations was generally limited to temporary emergency bailouts. More recently, however, the government has begun acquiring direct equity positions in strategically important companies.
Examples include:
Intel: The federal government obtained a 10% equity stake in Intel as part of a restructuring package that included approximately $9 billion in federal support.
MP Materials: The Department of Defense invested approximately $400 million to acquire a 15% ownership stake in MP Materials, making the federal government its largest shareholder while supporting domestic rare-earth mineral production.
Strategic Industries: Federal agencies, including the Departments of Commerce, Defense, and Energy, have supported or invested in companies involved in critical technologies and infrastructure, including USA Rare Earth, ReElement Technologies, Westinghouse Electric Corporation, Quantinuum, and PsiQuantum.
These investments represent a notable departure from traditional industrial policy by making the government not only a regulator and subsidizer, but also an investor.
2. Revenue-Sharing and Export Conditions
The federal government has increasingly linked access to export markets with financial or regulatory conditions.
One example is the export framework governing advanced artificial intelligence chips. Agreements allowing companies such as Nvidia and AMD to export certain AI processors to China have reportedly included provisions requiring companies to share a portion of the resulting revenues with the federal government. Critics, including analysts at the Cato Institute, argue that this approach resembles state-directed revenue extraction rather than conventional export licensing.
3. Tariffs as Industrial Policy
Tariffs have become an increasingly important instrument of industrial strategy.
Rather than functioning solely as broad trade barriers, tariffs have also been used to influence corporate behavior.
Examples include:
Threatening tariffs to encourage companies to relocate manufacturing or diversify supply chains.
Granting company-specific exemptions or adjustments that reward firms aligning with national industrial objectives.
Using trade policy to encourage domestic production in strategically important industries.
Supporters argue these measures strengthen national resilience, while critics contend they increase uncertainty and allow greater political influence over private investment decisions.
4. Active Government Involvement in Corporate Strategy
Federal policymakers have become increasingly involved in major corporate decisions affecting industries considered strategically important.
Examples include:
Influencing investment decisions involving critical infrastructure and advanced manufacturing.
Exercising regulatory authority to discourage foreign acquisitions of strategically important companies.
Employing “golden share” mechanisms or comparable government veto powers in selected transactions involving national security interests.
Providing guaranteed purchase agreements or price supports for defense-related technologies, critical minerals, and other strategic industries.
These policies seek to preserve domestic industrial capacity while reducing dependence on foreign suppliers.
5. Targeted Subsidies and Industrial Planning
The expansion of state involvement did not begin with direct government ownership. Earlier legislation established a broad framework for government-directed industrial policy through grants, tax incentives, loans, and regulatory requirements.
The CHIPS and Science Act
The CHIPS and Science Act committed more than $52 billion in grants, tax credits, and loan guarantees to expand domestic semiconductor manufacturing. Major beneficiaries include Intel, TSMC, Samsung, and other semiconductor producers.
Recipients were also subject to “guardrail” provisions limiting certain future investments in countries considered strategic competitors.
The Inflation Reduction Act (IRA)
The Inflation Reduction Act created extensive tax credits, grants, and financing mechanisms supporting renewable energy, electric vehicles, battery manufacturing, hydrogen production, and related supply chains.
The legislation represents one of the largest industrial policy initiatives in U.S. history, directing hundreds of billions of dollars toward technologies identified by policymakers as priorities for the energy transition.
A New Economic Model?
Taken together, these policies illustrate a significant evolution in the relationship between the federal government and private enterprise. Rather than relying primarily on market incentives and regulatory oversight, the government has increasingly acted as investor, financier, customer, shareholder, trade negotiator, and strategic planner.
Supporters argue that these interventions are necessary to compete with state-directed economies such as China, strengthen national security, rebuild domestic manufacturing, and secure critical supply chains.
Critics counter that expanding government ownership, selective subsidies, preferential treatment, and direct intervention in private markets blur the traditional distinction between free-market capitalism and state-sponsored capitalism. They warn that such policies may distort competition, encourage political favoritism, and reduce market efficiency.
Whether viewed as a pragmatic response to global competition or a fundamental shift in American economic philosophy, the growing role of the federal government in directing private capital represents one of the most consequential developments in U.S. economic policy in decades.
Socialism
One characteristic commonly associated with socialism is the government assuming responsibility for providing goods or services that private markets are unable or unwilling to provide. In these cases, financial risks and costs are shared across society through taxes, mandatory assessments, or publicly backed insurance programs.
The U.S. insurance industry provides several examples of this approach.
The National Flood Insurance Program (NFIP)
The National Flood Insurance Program (NFIP), administered by the Federal Emergency Management Agency (FEMA), was established in 1968 because private insurers were largely unwilling to provide affordable flood insurance in many high-risk areas.
Rather than leaving homeowners without coverage, the federal government assumed much of the financial risk. Today, millions of property owners purchase flood insurance through the NFIP, with taxpayers ultimately bearing a substantial portion of catastrophic losses when claims exceed collected premiums. The program illustrates how the government has socialized a specific category of insurance risk that the private market has historically struggled to insure profitably.
Florida’s Citizens Property Insurance Corporation
Florida provides one of the clearest state-level examples of government intervention in insurance markets.
The Citizens Property Insurance Corporation was created by the Florida Legislature in 2002 as a government-established, not-for-profit insurer intended to serve as the state’s “insurer of last resort.” Its purpose is to provide property and windstorm insurance for homeowners, condominium owners, renters, and businesses that cannot obtain comparable coverage from private insurers.
As hurricanes have become more destructive, litigation costs have risen, and many private insurers have reduced their exposure or exited the Florida market altogether, Citizens has expanded dramatically. What began as a safety net has evolved into Florida’s largest property insurer, covering well over one million policies.
Unlike a private insurance company operating solely for profit, Citizens is backed by the state. If claims substantially exceed its financial reserves, Florida law allows Citizens to levy assessments on many insurance policies throughout the state to help cover losses. In effect, the financial risk is spread broadly among policyholders rather than borne exclusively by the individual customers who file claims.
A Mixed Economic Model
Programs such as the National Flood Insurance Program and Citizens Property Insurance Corporation illustrate how the United States operates as a mixed economy rather than a purely laissez-faire capitalist system. When private markets fail to provide essential services at affordable prices, governments have often stepped in to provide financing, insurance, or direct support.
Supporters argue that these programs protect homeowners, stabilize housing markets, and ensure that essential insurance remains available despite increasing climate and catastrophe risks.
Critics contend that publicly backed insurance can distort market signals, encourage development in high-risk areas, and shift financial burdens from individual property owners to taxpayers or other policyholders.
Regardless of one’s perspective, these programs demonstrate that government assumption of economic risk—one characteristic often associated with socialist policies—has become an established component of the American insurance system while coexisting with a predominantly private-market economy.
Conclusion
The American economy has never been completely free of government intervention, but the scope and nature of that intervention have changed substantially over time. Today, federal and state governments influence private markets through direct ownership, industrial policy, targeted subsidies, publicly backed insurance programs, trade policy, regulatory oversight, and strategic investments. These policies increasingly resemble characteristics associated with state-sponsored capitalism, while programs such as federally backed flood insurance and state-run insurers illustrate elements commonly associated with socialized risk.
Supporters argue that these interventions strengthen national security, rebuild domestic manufacturing, improve economic resilience, and address market failures that private enterprise alone cannot solve. Critics contend that expanding government involvement can reduce market efficiency, distort competition, encourage political favoritism, and transfer private risks to taxpayers.
The United States remains a capitalist economy, but it is no longer accurately described as a purely laissez-faire one. Instead, it has evolved into a mixed economic system in which free markets coexist with significant government participation. Recognizing this reality allows for a more informed discussion of public policy—one based not on political labels, but on the practical ways governments and markets increasingly work together to shape economic outcomes.
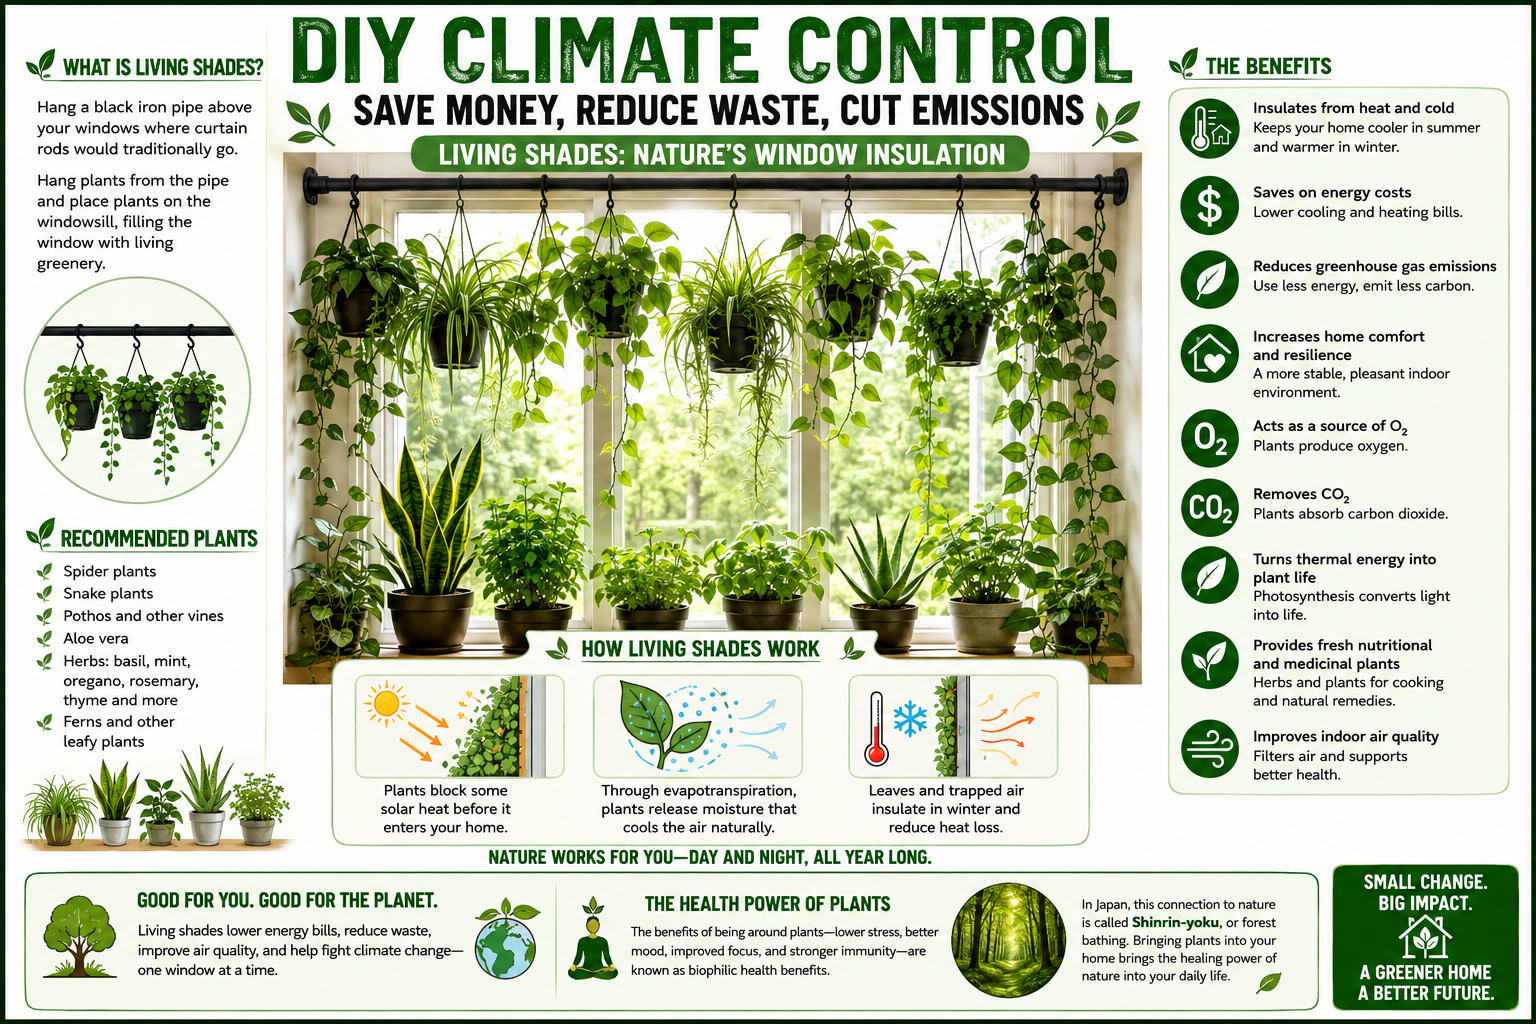
DIY Climate Control: Save Money, Reduce Waste, and Cut Greenhouse Gas Emissions
by Daniel Brouse
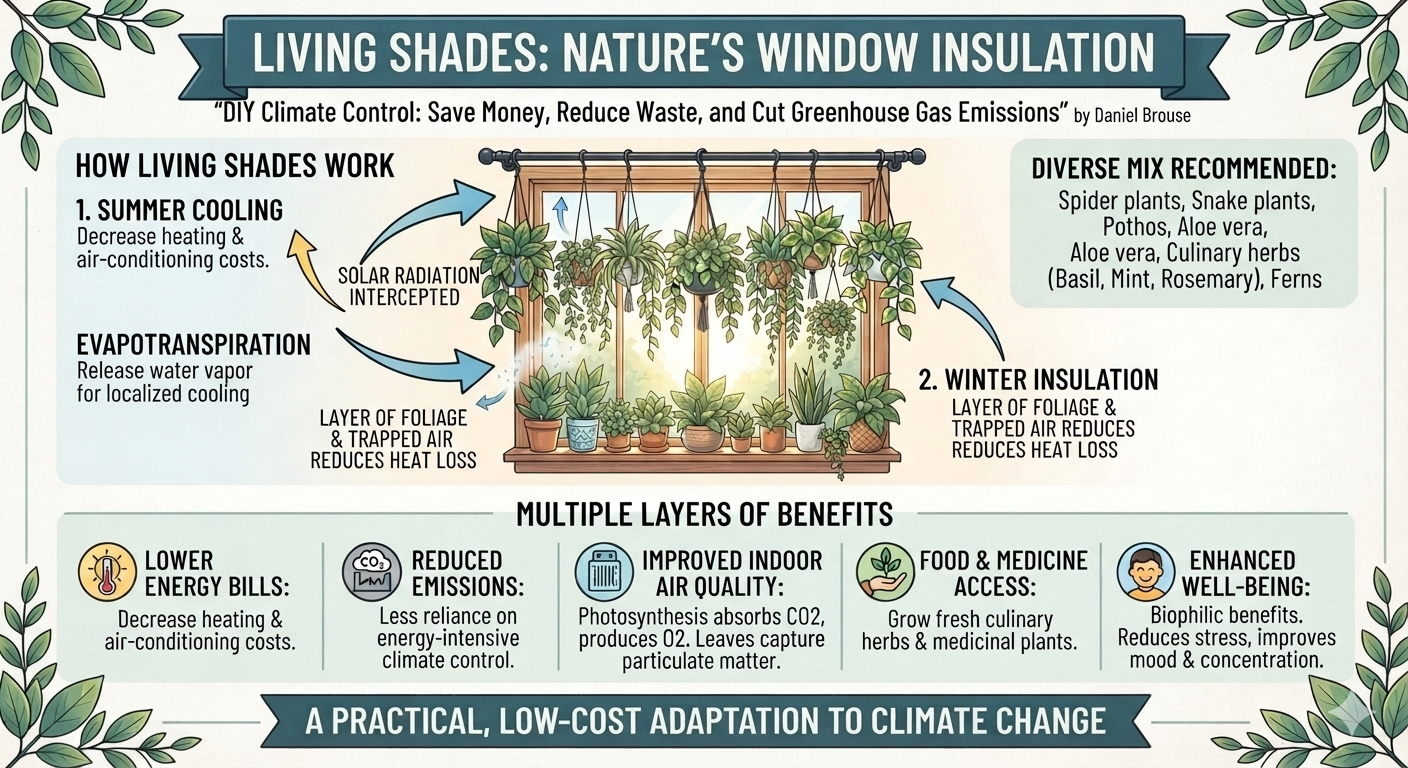
One of the simplest and most affordable ways to improve your home’s energy efficiency is to create living shades. Instead of installing traditional curtains or blinds, mount a sturdy black iron pipe above each window and suspend a collection of houseplants from it. Complement the hanging plants with additional plants on the windowsill, creating a dense layer of living vegetation between the window and the room.
A diverse mix of plants works best. Excellent choices include:
Spider plants
Snake plants
Pothos and other trailing vines
Aloe vera
Culinary herbs such as basil, mint, oregano, rosemary, and thyme
Ferns and other leafy houseplants
As the plants mature, they naturally form a living curtain that performs several useful functions simultaneously.
How Living Shades Work
Plants intercept a portion of incoming solar radiation before it enters the room. Through evapotranspiration, they also release water vapor that provides localized evaporative cooling around windows. During winter, the layer of foliage and trapped air provides modest insulation that helps reduce heat loss.
Unlike synthetic window coverings, living shades continuously improve indoor environmental quality while producing no waste and requiring very little energy to operate.
Benefits
Living shades can help:
Lower indoor temperatures during sunny weather.
Reduce winter heat loss through windows.
Decrease heating and air-conditioning costs.
Improve household energy efficiency.
Reduce greenhouse gas emissions associated with home energy use.
Increase indoor humidity during dry winter months.
Capture small amounts of airborne particulate matter on leaf surfaces.
Absorb carbon dioxide while producing oxygen through photosynthesis.
Improve indoor air quality and occupant comfort.
Provide fresh culinary herbs and medicinal plants.
Increase household resilience by producing small quantities of food year-round.
Create a calming, attractive indoor environment.
While individual houseplants should not be viewed as major carbon sinks, a home filled with vegetation contributes to a healthier indoor ecosystem while reducing reliance on energy-intensive climate control.
Beyond Energy Savings: The Health Benefits of Indoor Nature
The benefits of living plants extend beyond lower utility bills.
A growing body of research shows that exposure to vegetation can reduce stress, improve mood, enhance concentration, and promote psychological well-being. Collectively, these effects are known as biophilic health benefits, reflecting humanity’s innate connection to the natural world.
In Japan, the practice of intentionally immersing oneself in nature is known as Shinrin-yoku, or forest bathing. Research has shown that spending time around plants and trees can lower stress hormones, reduce blood pressure, improve immune function, and promote relaxation. While a living room cannot replace a forest, incorporating abundant indoor vegetation brings many of these restorative qualities into everyday life.
Living shades therefore provide multiple layers of value:
Lower energy bills.
Reduced greenhouse gas emissions.
Improved indoor air quality.
Increased food and medicinal plant production.
Enhanced physical comfort.
Better mental health and overall well-being.
As climate change drives higher temperatures and rising energy costs, living shades represent a practical, low-cost adaptation strategy that transforms ordinary windows into productive, energy-saving ecosystems.
Introduction: Climate Change as an Economic and Human Security Crisis
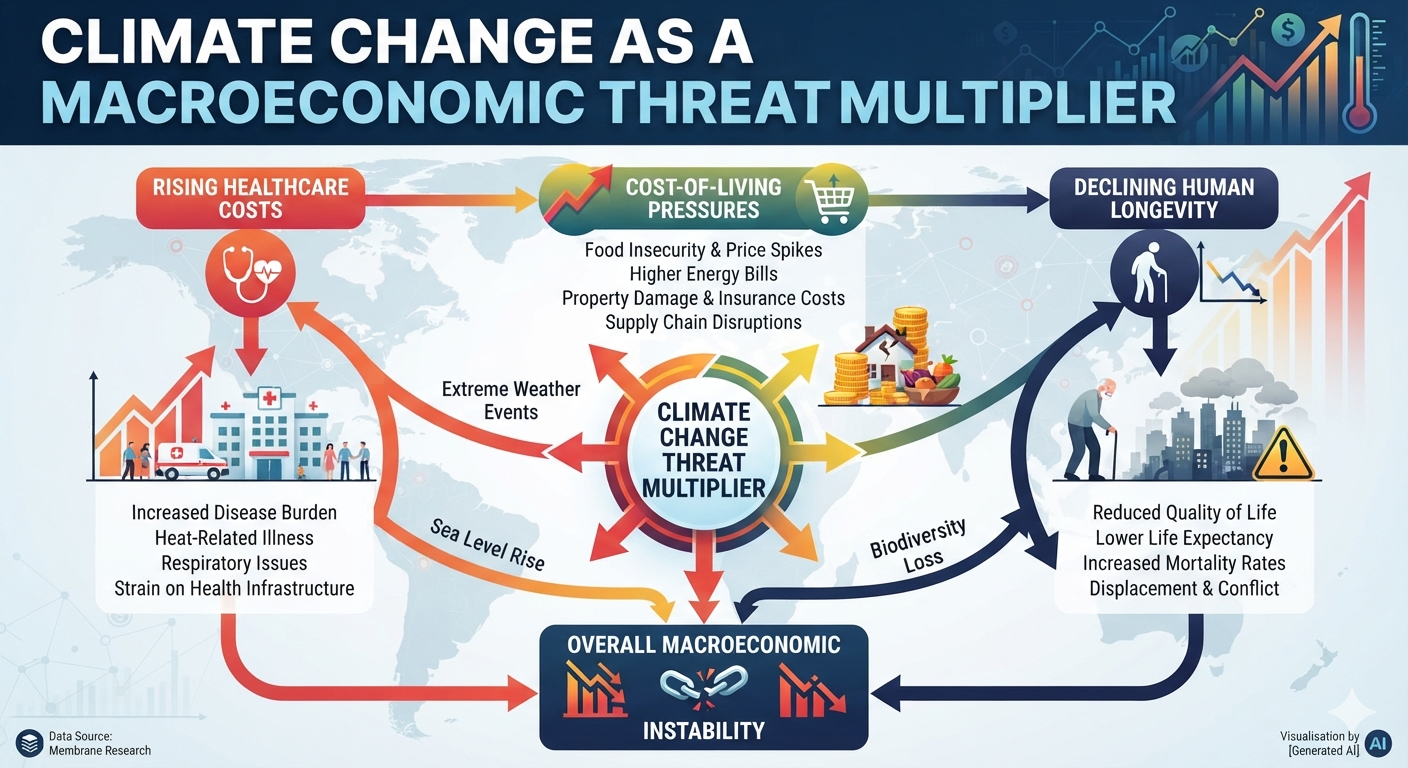
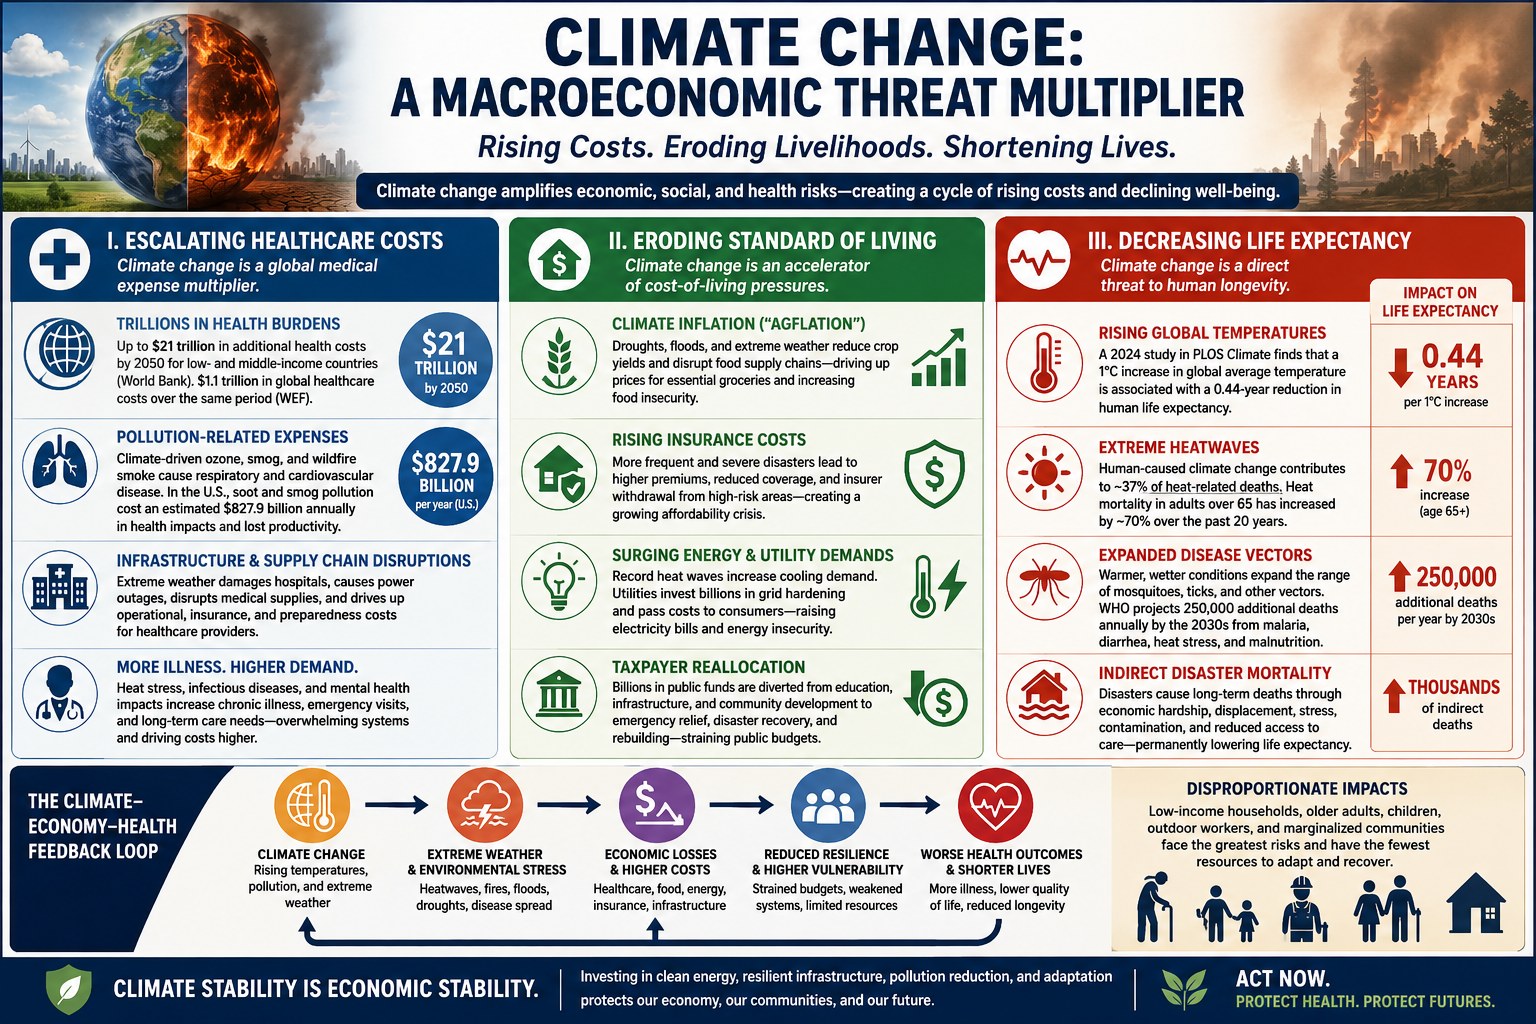
Climate change is no longer only an environmental challenge; it has become a powerful macroeconomic threat multiplier that amplifies existing social, economic, and public health vulnerabilities. Rising temperatures, increasingly extreme weather events, deteriorating air quality, and destabilized ecosystems are creating cascading financial pressures that extend from governments and businesses to individual households.
The economic consequences of climate change are increasingly visible through three interconnected pathways:
Escalating healthcare costs caused by heat exposure, air pollution, infectious diseases, and climate-related disasters.
Erosion of living standards through inflationary pressures on food, energy, insurance, housing, and public infrastructure.
Declining human longevity as environmental stressors undermine physical health, increase mortality, and reverse decades of progress in life expectancy.
These impacts are not distributed equally. Low-income households, elderly populations, outdoor workers, and marginalized communities often face the greatest exposure while having the fewest resources to adapt. Climate change therefore transforms environmental instability into a localized economic and human health crisis.
I. Escalating Healthcare Costs: Climate Change as a Global Medical Expense Multiplier
Climate change is placing unprecedented strain on healthcare systems by increasing both the frequency and severity of climate-related illnesses while simultaneously disrupting healthcare infrastructure.
1. Trillions of Dollars in Climate-Driven Health Burdens
The financial consequences of climate-related health impacts are expected to reach historic levels.
The World Bank estimates that climate-related health crises could impose approximately $21 trillion in additional costs by 2050 across low- and middle-income countries, reflecting increased disease burdens, reduced productivity, and expanding healthcare needs.
The World Economic Forum estimates that climate change could create approximately $1.1 trillion in additional global healthcare costs over the same period.
These costs represent more than direct medical expenses. They include lost productivity, reduced workforce participation, premature mortality, emergency response requirements, and infrastructure adaptation.
2. Pollution-Related Healthcare Expenses
Climate change and fossil fuel combustion are closely linked. Rising temperatures accelerate atmospheric chemical reactions that increase ground-level ozone formation, intensifying smog episodes and worsening respiratory and cardiovascular disease.
Fine particulate matter (PM2.5), ozone, wildfire smoke, and other pollutants contribute to:
Asthma and chronic respiratory illness
Heart attacks and strokes
Lung disease
Premature deaths
Increased emergency room visits
In the United States alone, soot and smog pollution are estimated to generate hundreds of billions of dollars annually in health-related costs, including medical expenses and lost economic productivity.
The growing frequency of wildfire smoke events demonstrates how climate impacts can transform regional air pollution into a national health emergency. Smoke from distant wildfires can travel thousands of miles, exposing millions of people far from the original source.
3. Healthcare Infrastructure and Supply Chain Disruptions
Extreme weather events increasingly threaten the operational stability of healthcare systems.
Climate-related disruptions include:
Hospitals losing electrical power during heat waves, hurricanes, and wildfires
Flooding damaging medical facilities
Disruptions in pharmaceutical and medical equipment supply chains
Increased emergency response costs
Higher insurance and operational expenses for healthcare providers
Hospitals are being forced to spend billions on climate resilience measures, including backup power systems, flood protection, cooling infrastructure, and emergency preparedness.
II. Eroding Standard of Living: Climate Change as a Cost-of-Living Accelerator
Climate change is increasingly becoming an economic reality experienced directly through household budgets. The same forces increasing healthcare costs are also driving inflationary pressures throughout the economy.
1. Climate Inflation and Agricultural Instability (“Agflation”)
Food systems are among the most climate-sensitive sectors of the global economy.
Rising temperatures, droughts, flooding, changing precipitation patterns, and extreme storms reduce agricultural productivity by damaging:
Crop yields
Livestock health
Fisheries
Agricultural infrastructure
Transportation networks
These disruptions create supply-side inflation, increasing prices for essential goods including:
Grains
Fruits and vegetables
Meat and dairy products
Transportation-dependent food products
Climate-driven food inflation disproportionately harms lower-income households because food represents a larger percentage of their monthly expenses.
2. Rising Insurance Costs and the Retreat From High-Risk Regions
The insurance industry has become one of the clearest economic indicators of accelerating climate risk.
As hurricanes, wildfires, floods, and severe storms become more frequent and destructive:
Insurance premiums increase dramatically.
Coverage becomes more restricted.
Insurers withdraw from vulnerable markets.
Property values decline in high-risk regions.
Homeowners increasingly face a difficult choice: pay rapidly increasing premiums or assume greater financial risk without adequate coverage.
This creates a growing climate affordability crisis, particularly for homeowners living in areas exposed to wildfire, coastal flooding, extreme storms, and severe weather.
3. Rising Energy Demand and Utility Costs
Climate change increases energy demand while simultaneously placing stress on energy infrastructure.
During extreme heat events:
Electricity consumption rises sharply due to increased air conditioning demand.
Utilities must invest billions in grid upgrades.
Transmission systems require additional protection against storms and wildfires.
Energy insecurity becomes a growing concern as vulnerable households struggle to afford cooling during dangerous heat events.
4. Taxpayer Costs and Public Financial Burdens
Climate disasters increasingly redirect public resources away from long-term investments toward emergency response and recovery.
Government spending is increasingly allocated toward:
Disaster relief
Infrastructure repairs
Emergency housing assistance
Flood recovery
Wildfire response
Agricultural assistance
These expenditures compete directly with funding for:
Education
Transportation improvements
Community development
Public health programs
Climate change therefore functions as a long-term fiscal drain, increasing government expenditures while reducing resources available for economic development.
III. Declining Human Longevity: Climate Change as a Biological Stressor
Beyond economic impacts, climate change increasingly affects the fundamental measure of human well-being: life expectancy.
The cumulative effects of extreme heat, pollution exposure, disease expansion, food insecurity, and climate disasters are slowing—and in some regions reversing—historical gains in longevity.
Climate Driver
Impact on Human Health and Longevity
Rising Global Temperatures
A 2024 study published in PLOS Climate found that a 1°C increase in global average temperature is associated with approximately a 0.44-year reduction in life expectancy.
Extreme Heatwaves
Human-caused climate change is estimated to contribute to approximately 37% of heat-related deaths. Heat-related mortality among adults over age 65 has increased substantially over recent decades.
Expanded Disease Vector Ranges
Warmer and wetter conditions allow mosquitoes, ticks, and other disease vectors to expand into new regions, increasing risks from malaria, dengue fever, Lyme disease, and other infections.
Food and Water Stress
Climate disruption increases risks of malnutrition, dehydration, agricultural failure, and water insecurity, particularly in vulnerable populations.
Indirect Disaster Mortality
Floods, hurricanes, wildfires, and other disasters create long-term health impacts through displacement, economic hardship, psychological stress, and environmental contamination.
This feedback loop means climate impacts are not isolated events. A wildfire, flood, or heat wave can simultaneously damage infrastructure, increase healthcare expenses, reduce productivity, raise insurance costs, and shorten human lives.
The poorest communities often experience the strongest effects because they have fewer resources to prepare, recover, and relocate.
Conclusion: Climate Stability Is Economic Stability
Climate change represents one of the largest economic and public health challenges of the modern era. Its consequences extend far beyond environmental degradation, affecting national budgets, household finances, healthcare systems, and human survival.
Addressing climate change is therefore not simply an environmental investment—it is an economic resilience strategy and a public health imperative. Investments in clean energy, resilient infrastructure, pollution reduction, efficient buildings, and climate adaptation can reduce future costs while protecting both human health and economic stability.
The cost of inaction is no longer measured only in degrees of warming. It is measured in rising medical bills, shrinking household budgets, damaged communities, and lost years of human life.
🌎 Climate Change and Personal Finances: The Rising Cost of a Changing Climate
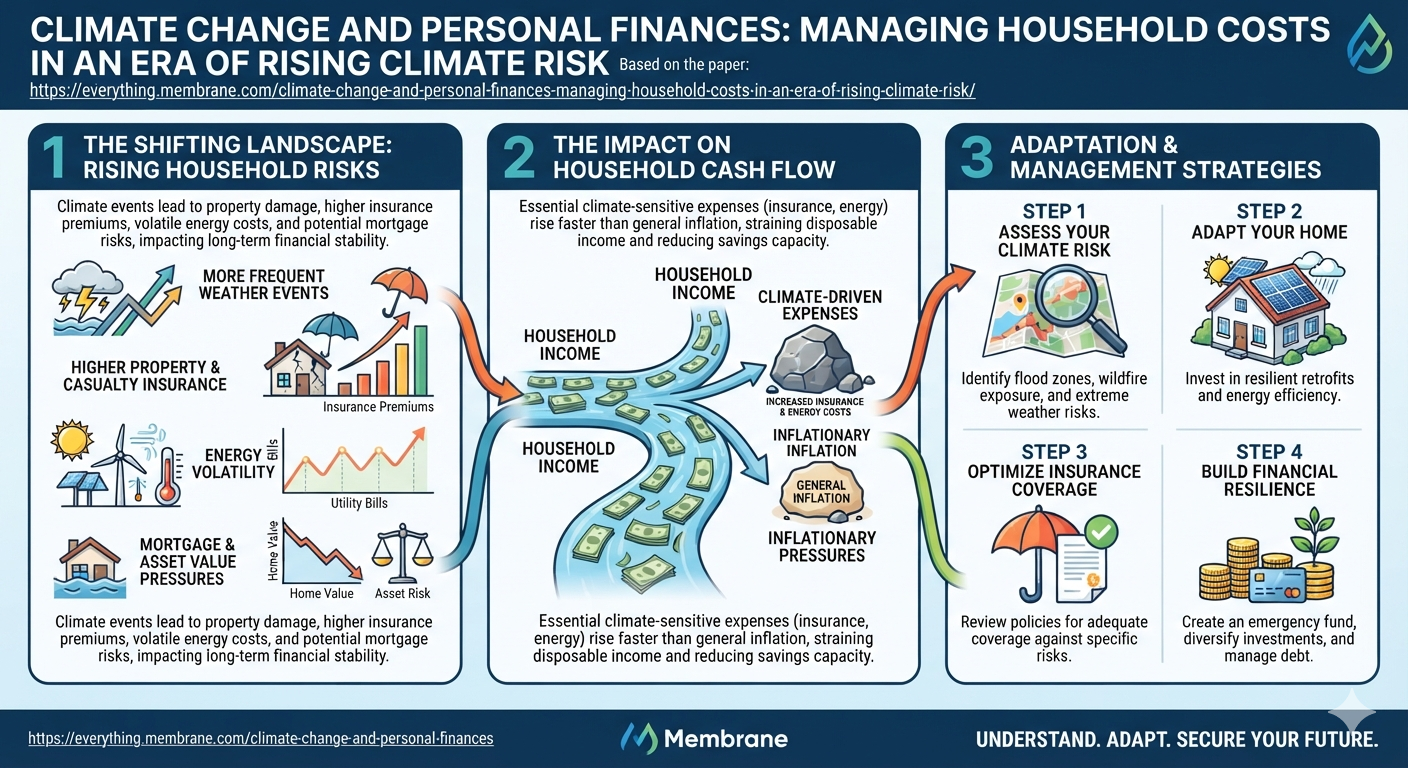
Climate change is no longer only an environmental challenge—it is becoming a growing financial challenge for households everywhere.
While headline inflation may appear moderate, the costs most affected by climate change are rising faster than many household incomes.
🔥 Extreme heat is increasing electricity demand and stressing energy infrastructure. ⛈️ Severe storms and hail events are driving higher comprehensive auto insurance costs. 🏠 Floods, hurricanes, wildfires, and extreme weather are pushing homeowners insurance premiums higher. 🌾 Droughts, floods, and shifting growing conditions are increasing food-price volatility. 🔨 Climate-related damage and rebuilding costs are raising housing expenses.
A new economic reality is emerging:
Climate-sensitive expenses are becoming a larger share of household budgets.
The financial impacts of climate change are not limited to major disasters. They appear in recurring expenses—monthly utility bills, insurance premiums, repair costs, and the price of everyday goods.
Building financial resilience means preparing for this changing economic landscape:
✅ Reduce high-interest debt ✅ Build emergency savings ✅ Improve home energy efficiency ✅ Review insurance coverage ✅ Invest in weather protection and resilience ✅ Plan for increasing climate-related costs
Climate change is reshaping not only our environment, but also the economics of everyday life.
📊 Read the full report:
“Climate Change and Personal Finances: Managing Household Costs in an Era of Rising Climate Risk”
Climate change is no longer simply an environmental issue. It has become an economic force that influences nearly every aspect of household finances. Extreme weather, rising insurance losses, damaged infrastructure, disruptions to agriculture, and increasing energy demand are reshaping the cost of living.
While the overall inflation rate captures broad price changes across the economy, climate change increasingly creates uneven inflation. Some goods remain relatively stable, while climate-sensitive sectors experience much faster price growth.
Understanding these trends allows households to better prepare for an increasingly volatile financial future.
Overall Inflation
The Consumer Price Index for All Urban Consumers (CPI-U) currently reflects annual inflation of approximately 3.5%.
Although this represents moderate overall inflation, it masks significant differences among individual household expenses. Energy, insurance, housing, and weather-sensitive goods continue to experience above-average price increases, while wages have largely kept pace only with headline inflation.
As climate change intensifies, these differences are expected to become even more pronounced.
Household Price Trends
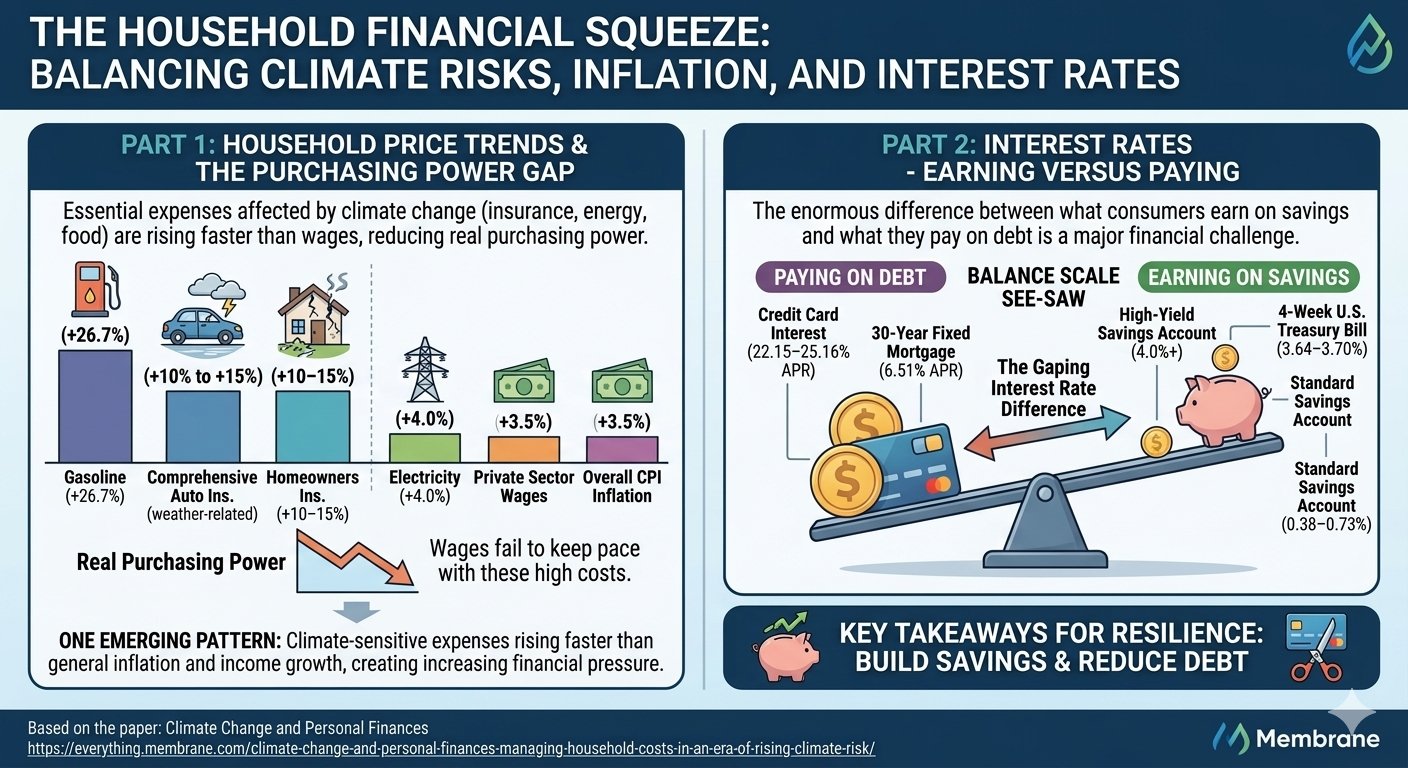
Major components of household budgets are experiencing dramatically different rates of inflation. Essential expenses increasingly affected by climate change—such as insurance, energy, housing repairs, and food—are rising faster than average wage gains. As a result, many households are experiencing a decline in real purchasing power despite wages keeping pace with headline inflation.
Household Expense
Annual Change
Overall CPI Inflation
+3.5%
Gasoline
+26.7%
Electricity
+4.0%
Comprehensive Auto Insurance (weather-related losses)
+10% to +15%
Homeowners Insurance
+10–15%
Private Sector Wages
+3.5%
One consistent pattern is emerging:
One consistent pattern is emerging: climate-sensitive expenses are rising faster than overall inflation and household income growth, creating increasing financial pressure for families adapting to a changing climate.
Energy Costs
Energy remains one of the largest sources of household inflation.
Gasoline prices have risen sharply due to geopolitical tensions, supply disruptions, refinery constraints, and transportation bottlenecks. While climate change is not the sole cause of gasoline inflation, extreme weather increasingly disrupts oil production, refining capacity, pipelines, and shipping routes.
Electricity prices have also continued to climb.
Several factors contribute:
Increased demand during prolonged heat waves
Expansion of electric transmission infrastructure
Grid modernization
Storm damage and repairs
Higher fuel and maintenance costs
As summers become hotter and heat waves last longer, residential electricity demand for air conditioning continues to increase.
The Insurance Crisis
Perhaps no household expense illustrates climate change more clearly than insurance.
Insurers base premiums on expected future losses—not past averages.
As hurricanes, wildfires, hailstorms, tornadoes, flooding, and severe convective storms become more destructive, insurance companies are paying record claims.
These losses eventually appear as:
Higher premiums
Larger deductibles
Reduced coverage
More exclusions
Non-renewals
Complete withdrawal from high-risk markets
Homeowners insurance has become one of the fastest-growing household expenses in many regions.
In some states, premiums have doubled within only a few years.
For households, insurance is increasingly becoming a direct monthly cost of climate change.
Comprehensive Auto Insurance and Climate Risk
Unlike collision insurance, which covers accidents between vehicles, comprehensive automobile insurance protects against damage caused by natural hazards and other non-collision events. As climate change increases the frequency and severity of extreme weather, comprehensive claims have risen substantially.
Common climate-related comprehensive claims include:
Hail damage
Falling trees and branches during windstorms
Flash flood damage
Hurricane storm surge
Wildfire damage
Tornado debris
Lightning strikes
Wind-blown objects
Ice and snow damage
Large hailstorms alone now produce billions of dollars in insured vehicle losses each year. Modern vehicles are particularly vulnerable because aluminum body panels, panoramic glass roofs, advanced sensors, cameras, and radar systems are expensive to repair or replace.
Flash flooding has also become one of the fastest-growing sources of comprehensive auto losses. Vehicles caught in flooded roadways often suffer catastrophic engine, electrical, and electronic damage, resulting in total-loss claims.
As insurers pay increasing numbers of weather-related claims, many companies have adjusted comprehensive premiums, increased deductibles, or refined risk models based on regional exposure to hail, flooding, hurricanes, wildfires, and severe convective storms.
While collision coverage is primarily influenced by driving behavior, repair costs, and accident frequency, comprehensive insurance increasingly reflects the financial consequences of a changing climate. For many households, the rising cost of comprehensive coverage has become another indirect expense associated with more frequent and more destructive extreme weather events.
Food Prices
Although food inflation fluctuates from year to year, climate change is placing increasing pressure on agricultural production.
Extreme heat, drought, flooding, hurricanes, and shifting growing seasons reduce crop yields while increasing production costs.
Examples include:
Heat-stressed livestock
Drought-reduced grain harvests
Flood-damaged vegetables
Disease outbreaks
Pollinator decline
Water shortages
The result is greater price volatility at grocery stores.
Consumers may increasingly experience periods where staple foods rise rapidly following major climate disasters.
Housing Costs
Housing costs are increasingly influenced by climate risk.
Construction materials become more expensive following disasters.
Labor shortages emerge after major storms.
Building codes become stricter.
Flood-resistant construction, stronger roofing systems, improved insulation, and wildfire-resistant materials all increase upfront construction costs while reducing long-term risk.
Mortgage lenders are also beginning to incorporate climate risk into property valuations.
Properties facing repeated flooding, wildfire exposure, or coastal erosion may experience declining values while insurance costs continue rising.
Wages and Purchasing Power
Private-sector wages have increased approximately 3.5% over the past year.
While this roughly matches headline inflation, it does not fully offset the faster growth of essential household expenses such as insurance, electricity, housing, and healthcare.
As a result, many households experience “cost-of-living compression,” where income keeps pace with average inflation but fails to keep pace with the expenses that matter most.
Interest Rates: Earning Versus Paying
One of the largest financial challenges facing households is the enormous difference between what consumers earn on savings and what they pay on debt.
Financial Instrument
Typical Rate
Credit Card Interest
22.15–25.16% APR
30-Year Fixed Mortgage
6.51% APR
High-Yield Savings Account
4.0%+
4-Week U.S. Treasury Bill
3.64–3.70%
Standard Savings Account
0.38–0.73%
The modern banking system rewards households that maintain liquidity while imposing extremely high costs on revolving debt.
Credit card interest rates frequently exceed 20%, making high-interest debt one of the largest obstacles to long-term financial security.
Conversely, households that maintain emergency savings can now earn meaningful returns through high-yield savings accounts and short-term Treasury securities.
Climate Change and Financial Risk
Climate change introduces several new forms of financial risk that traditional household budgeting rarely considered:
Increasing insurance premiums
Larger deductibles
Rising utility bills
Disaster repair costs
Temporary job interruptions after extreme weather
Declining property values in high-risk areas
Higher food prices
Greater investment volatility
These risks compound over time, making financial resilience increasingly important.
Strategies for Financial Resilience
Households can take practical steps to reduce their financial vulnerability to climate-related economic shocks.
Build an Emergency Fund
Maintaining three to six months of living expenses provides flexibility following disasters, temporary unemployment, or unexpected repairs.
Eliminate High-Interest Debt
Paying down credit cards earning 22–25% interest often provides a greater guaranteed return than most investments.
Improve Energy Efficiency
Investments such as insulation, efficient appliances, heat pumps, smart thermostats, and LED lighting can reduce utility costs while improving comfort during heat waves.
Review Insurance Coverage
Homeowners should regularly review policy limits, deductibles, exclusions, flood coverage, and replacement-cost estimates to ensure protection reflects today’s risks.
Diversify Investments
Diversification across asset classes, industries, and geographic regions can help reduce exposure to climate-related disruptions affecting any single sector.
Prepare for Extreme Weather
Emergency supplies, backup power, important documents, evacuation plans, and home maintenance can reduce both financial losses and recovery time after disasters.
The Economics of Adaptation
One of the defining economic realities of the coming decades will be the growing cost of adaptation.
Communities will invest billions in:
Stronger electrical grids
Flood-control systems
Coastal defenses
Wildfire mitigation
Stormwater infrastructure
More resilient buildings
Expanded emergency response capabilities
Although these investments require substantial upfront spending, they often cost far less than rebuilding after repeated disasters. For individual households, similar investments—such as reinforcing roofs, improving drainage, elevating utilities in flood-prone areas, or increasing home energy efficiency—can reduce future repair costs, lower insurance claims, and improve long-term resilience.
Conclusion
Climate change is increasingly shaping household finances through higher insurance premiums, rising energy costs, greater food-price volatility, and growing expenditures on disaster preparedness and infrastructure. At the same time, high borrowing costs amplify the financial strain on families carrying significant debt.
The central challenge is no longer simply inflation, but the uneven way inflation affects climate-sensitive expenses. Insurance, utilities, housing, and food are consuming a larger share of household budgets, even when overall inflation appears moderate.
Building emergency savings, reducing high-interest debt, investing in energy efficiency, maintaining appropriate insurance coverage, and preparing for extreme weather can strengthen financial resilience. As climate risks continue to evolve, households that proactively adapt their financial strategies will be better positioned to absorb future economic shocks and maintain long-term financial stability.
Climate Control Feedback Loops: When Cooling Becomes Part of the Climate System
How the growing need for air conditioning is creating new reinforcing climate feedbacks
Introduction
For most of the twentieth century, air conditioning was considered a luxury in many parts of the world. Today, in an increasing number of regions, it is becoming essential for human health and survival. As climate change drives longer, hotter, and more humid heat waves, indoor climate control is rapidly shifting from a convenience to a critical component of public safety.
This transition carries an important consequence that is often overlooked: climate control itself is becoming part of the climate system. Cooling technologies are increasingly intertwined with energy production, infrastructure resilience, water availability, urban design, and greenhouse gas emissions. As societies become more dependent on mechanical cooling, air conditioning becomes linked to a growing number of reinforcing climate feedback loops.
Many of these feedbacks are indirect, but together they form an interconnected system capable of amplifying both climate risks and societal vulnerability. Understanding these emerging “climate control feedback loops” is becoming increasingly important as the world enters an era of persistent extreme heat.
Heat Is Becoming a Public Health Emergency
Heat waves are starting earlier, becoming more intense, and lasting longer as climate change reshapes weather patterns around the world. In the United States, extreme heat events have become dramatically more likely because of human-caused global warming. Similar trends are occurring across Europe, the United Kingdom, Asia, Australia, and many developing nations where populations and infrastructure were never designed for prolonged extreme heat.
Extreme heat is far more than an inconvenience—it is a major public health hazard.
High temperatures place increasing stress on the cardiovascular system, kidneys, lungs, and immune system while reducing the body’s ability to regulate its core temperature. Heat exhaustion, heat stroke, dehydration, and cardiovascular failure become more common during prolonged heat events. Emerging research also suggests that some heat-related cellular and metabolic impacts may occur at lower temperatures than previously believed, particularly when high humidity limits the body’s ability to cool itself through perspiration.
As these conditions become more common, reliable indoor cooling increasingly becomes a life-saving necessity rather than simply a comfort.
Climate Control Is Becoming Critical Infrastructure
Modern societies are becoming increasingly dependent upon:
air conditioning
electrical grids
water infrastructure
cooling centers
healthcare systems
refrigeration
telecommunications
indoor climate stabilization technologies
Each of these systems depends upon the others.
Hospitals require electricity to operate cooling systems.
Power plants often require large amounts of water for cooling.
Water systems require electricity to pump and distribute water.
Telecommunications rely upon climate-controlled data centers.
The result is an increasingly interconnected infrastructure network that becomes progressively more vulnerable during extreme heat.
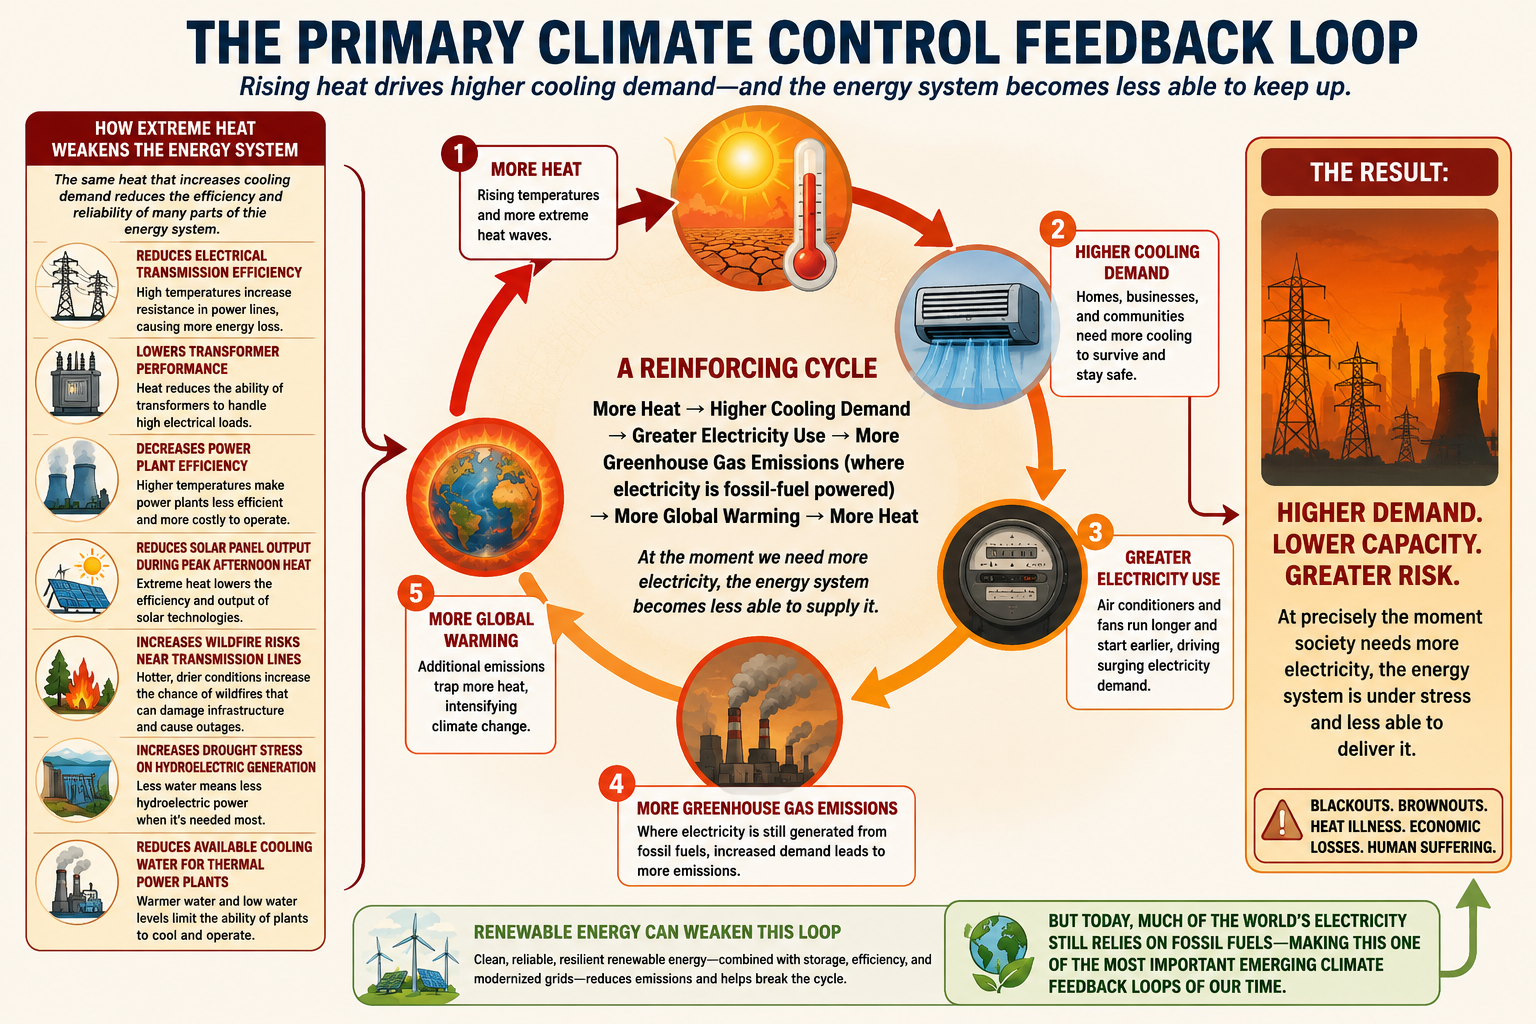
The Primary Climate Control Feedback Loop
As temperatures rise, cooling demand rises simultaneously.
Unfortunately, the same heat that increases cooling demand also reduces the efficiency of many parts of the energy system.
Extreme heat can:
reduce electrical transmission efficiency
lower transformer performance
decrease power plant efficiency
reduce solar panel output during peak afternoon heat
increase wildfire risks near transmission lines
increase drought stress on hydroelectric generation
reduce available cooling water for thermal power plants
At precisely the moment society needs more electricity, the energy system often becomes less capable of supplying it.
The reinforcing cycle becomes:
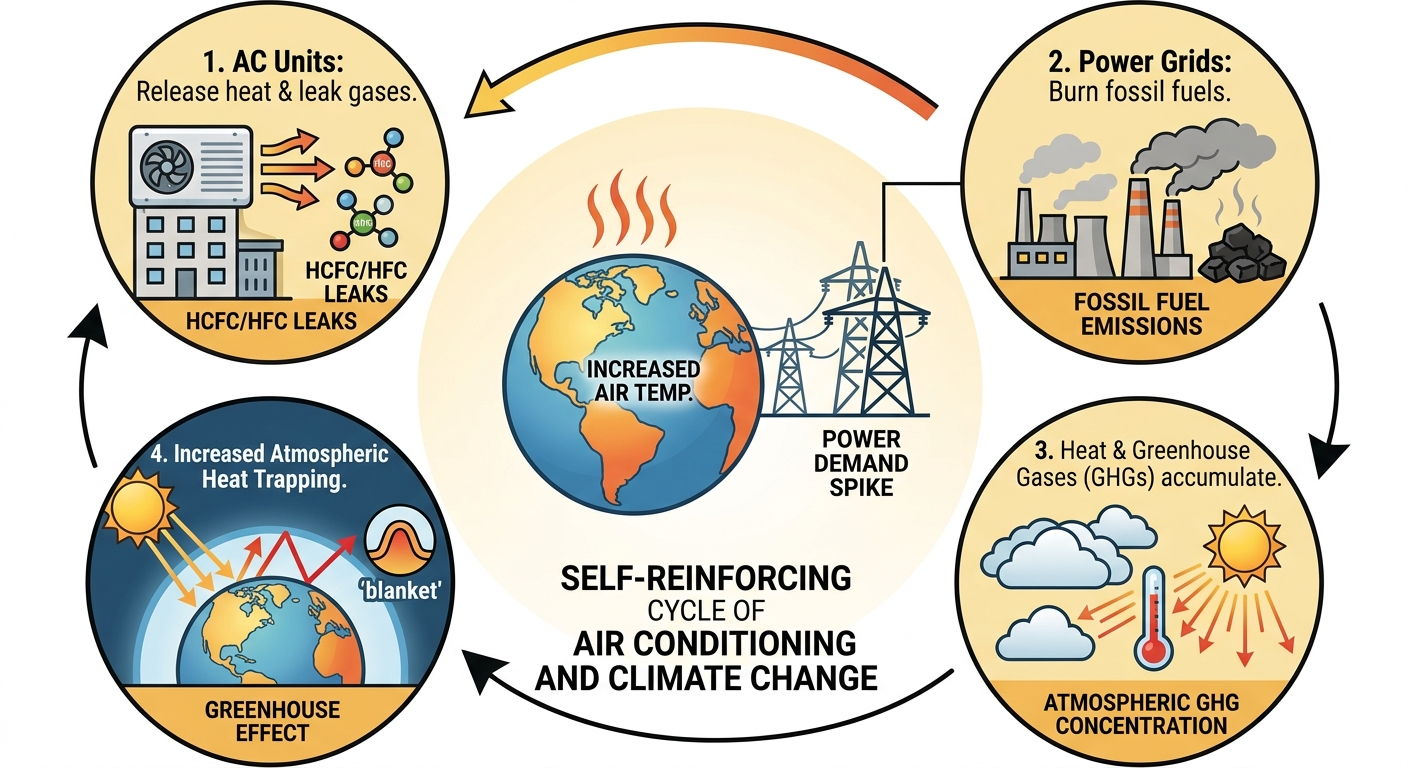
More Heat → Higher Cooling Demand → Greater Electricity Use → More Greenhouse Gas Emissions (where electricity is fossil-fuel powered) → More Global Warming → More Heat
Although renewable energy can weaken this loop, much of the world’s electricity still relies upon fossil fuels, making this one of the most important emerging climate feedbacks.
Additional Climate Control Feedback Loops
Urban Heat Island Feedback
Cities absorb enormous amounts of solar energy through asphalt, concrete, brick, and roofing materials.
Air conditioners remove heat from inside buildings but release that heat outdoors through their condensers.
As more buildings use air conditioning:
Indoor Heat → Outdoor Heat Release → Higher Urban Temperatures → Greater Air Conditioning Demand → More Waste Heat
Large cities can become several degrees warmer simply from accumulated waste heat released by millions of cooling systems operating simultaneously.
Electrical Grid Feedback
As cooling demand grows:
Heat Wave → Air Conditioning Demand Surges → Grid Stress → Brownouts or Blackouts → Loss of Cooling → Higher Heat Illness and Mortality
During major heat waves, the electrical grid itself becomes one of the most vulnerable components of society.
Power failures during extreme heat can quickly become humanitarian disasters.
Water Infrastructure Feedback
Many cooling systems depend upon water.
Meanwhile, hotter temperatures increase evaporation while drought reduces water supplies.
Climate Warming → Drought → Reduced Water Supply → Less Cooling Capacity → Greater Heat Stress → Increased Cooling Demand
Thermoelectric power plants, cooling towers, and some industrial cooling systems all become less reliable during water shortages.
Refrigerant Feedback
Although newer refrigerants are improving, many cooling systems still contain gases with very high global warming potential.
More Cooling Equipment → More Refrigerant Leakage → Increased Greenhouse Warming → More Heat → More Cooling Equipment
Even relatively small refrigerant leaks can have significant climate impacts if high-global-warming-potential gases are involved.
Healthcare Feedback
Extreme heat increases hospital admissions.
Hospitals require continuous climate control.
More Heat → More Heat Illness → Greater Hospital Demand → Higher Energy Consumption → Additional Emissions → More Heat
Healthcare systems become both victims of climate change and contributors to increased energy demand.
Economic Productivity Feedback
Extreme heat lowers worker productivity.
Businesses compensate by increasing indoor cooling.
Higher Temperatures → Lower Worker Productivity → Increased Air Conditioning Use → Greater Energy Demand → Additional Warming
This loop becomes especially important in manufacturing, warehouses, offices, and logistics.
Housing Inequality Feedback
Not everyone can afford adequate cooling.
Communities with limited access to air conditioning experience greater illness, higher mortality, and reduced economic resilience.
Lower Income → Less Cooling → Greater Heat Exposure → Reduced Economic Opportunity → Continued Inability to Invest in Cooling
How Wildfire Smoke Increases Air Conditioning Demand
Wildfire smoke illustrates how climate feedbacks can extend well beyond temperature alone.
Smoke contains aerosols, soot, and black carbon that alter the atmosphere in multiple ways. During the day, dense smoke may partially block incoming sunlight in some locations. At night, however, smoke acts like an insulating blanket by absorbing and re-radiating longwave infrared radiation emitted from Earth’s surface. Instead of allowing accumulated daytime heat to escape efficiently into space, smoke traps a portion of that heat near the ground.
Buildings normally cool overnight by releasing stored heat through roofs, walls, windows, and ventilation. When smoke reduces nighttime cooling:
buildings retain more heat overnight
indoor temperatures begin each morning at a higher level
air conditioners start earlier
cooling systems operate longer
afternoon peak electricity demand increases
electrical grids experience additional stress
Where electricity generation still depends on fossil fuels, increased cooling demand can produce additional greenhouse gas emissions.
Wildfire smoke also deposits black carbon onto snow and ice. Darkened snow absorbs more solar radiation, reducing surface reflectivity (albedo) and accelerating melting. Faster snow and ice loss exposes darker land and ocean surfaces, which absorb even more solar energy and further amplify regional warming.
This creates multiple reinforcing feedbacks operating simultaneously.
Climate Change → More Frequent and Intense Wildfires → More Smoke, Black Carbon, and Aerosols → Nighttime Heat Trapping + Black Carbon Deposition on Snow and Ice → Warmer Nights + Reduced Surface Albedo → Accelerated Regional Warming → Higher Air Conditioning Demand + Faster Arctic Ice Melt → Greater Greenhouse Gas Emissions (where grids remain fossil-fuel powered) + Increased Solar Heat Absorption → Additional Global Warming → More Frequent and Intense Wildfires
Rather than a single feedback loop, wildfire smoke demonstrates how one climate impact can trigger several interconnected reinforcing loops that amplify one another.
Building Resilience
Preparing for extreme heat does not always require expensive renovations. Many low-cost measures can significantly improve resilience while reducing energy demand.
Examples include:
improving attic insulation
installing reflective roofing materials
adding exterior shading
planting shade trees
improving ventilation
using ceiling fans
sealing air leaks
installing high-efficiency heat pumps
increasing battery backup capability
incorporating passive cooling design
expanding urban tree canopies
Each improvement reduces dependence upon mechanical cooling while lowering stress on electrical infrastructure.
Conclusion
Climate control is rapidly becoming one of the defining infrastructure challenges of the twenty-first century. As temperatures continue to rise, air conditioning is evolving from a consumer appliance into a critical component of public health, economic stability, and societal resilience.
Yet the expansion of climate control also creates new reinforcing feedback loops involving energy systems, cities, water resources, healthcare, digital infrastructure, refrigerants, and wildfire dynamics. These feedbacks demonstrate that climate change is no longer simply an environmental issue—it is an interconnected systems problem in which human responses can either amplify or reduce future warming.
Breaking these feedback loops will require more than expanding air conditioning. It will depend upon cleaner electricity, higher-efficiency cooling technologies, passive building design, urban greening, resilient electrical grids, improved water management, and thoughtful climate adaptation. Every improvement that reduces the energy required to keep people safe weakens these reinforcing cycles.
The future of climate resilience will not be determined solely by how much we cool our buildings, but by how intelligently we redesign the systems that make cooling possible.