In response to the U.S. administration’s recent implementation of reciprocal tariffs affecting numerous trading partners, the European Union (EU) has enacted counter-tariffs targeting a broad range of American goods.These measures aim to pressure the U.S. by focusing on exports from states that traditionally support the Republican Party, often referred to as “red states.”
Scope and Implementation of EU Tariffs:
Targeted Products:The EU’s tariffs encompass a variety of U.S. exports, including motorcycles, bourbon, peanut butter, and jeans.Additionally, agricultural commodities such as soybeans, beef, and poultry, as well as industrial goods like tobacco, iron, steel, and aluminum, are affected.Notably, Louisiana’s soybean exports, Kansas’s beef, and Southern states’ poultry are among the products targeted.
Economic Impact:These countermeasures impact U.S. exports valued at approximately €26 billion ($28 billion), aligning with the economic scale of the U.S. tariffs.The EU’s strategy appears to be a calculated effort to influence U.S. trade policy by affecting regions that are politically significant to the current administration.
Implementation Timeline:The EU’s tariffs are being rolled out in phases, with the initial measures starting in mid-April 2025.This staggered approach allows for potential negotiations between the EU and the U.S. to resolve trade disputes before further escalation occurs.
By strategically targeting exports from Republican-leaning states, the EU seeks to apply economic pressure on the U.S. administration, potentially influencing future trade negotiations and policies. Additionally, EU citizens are increasingly boycotting U.S. products and travel as part of their response to the ongoing trade tensions.
Trade War!
On April 2, President Trump unilaterally declared a trade war against the rest of the world, imposing protectionist tariffs on 180 countries — calling it “Liberation Day.” This action was taken without congressional approval and in direct violation of the Constitution.
The tariffs, particularly those imposed during the trade war with China and Japan, are indirectly contributing to a liquidity issue for U.S. Treasury bonds in several key ways:
1. Higher Borrowing Costs and Inflationary Pressure
Tariffs raise the cost of imports, driving up prices for American consumers and businesses. This, in turn, creates inflationary pressure. To combat this, the Federal Reserve may increase interest rates. Higher rates mean higher borrowing costs for the U.S. government when issuing new Treasury bonds. As a result, demand for these bonds could decrease as investors seek higher returns elsewhere.
2. Declining Foreign Demand
China and Japan, two of the largest holders of U.S. Treasury bonds, have shown increasing reluctance to purchase these bonds due to tariffs and trade tensions. If these countries — or others — reduce their purchases as part of a broader effort to decouple from the U.S. economy or as retaliation, foreign demand for Treasuries could significantly drop. This decrease in demand reduces bond liquidity, making it harder for the U.S. to sell them at favorable rates.
3. Reduced Global Confidence in U.S. Debt
Ongoing tariffs and trade tensions, combined with uncertainty about the U.S. economic outlook, may prompt global investors to question the stability of U.S. fiscal policies. This reduced confidence could further decrease demand for U.S. Treasuries, especially in an environment where global debt and fiscal imbalances are on the rise.
4. Increased Government Borrowing
The economic fallout from tariffs may require the U.S. government to increase its borrowing to cover rising costs, such as subsidies for affected industries like agriculture or manufacturing. This increased borrowing adds more Treasury bonds to the market. However, if demand does not increase proportionally, this oversupply reduces bond liquidity and could push down bond prices.
5. Risk of Credit Rating Downgrade
If tariffs are perceived to exacerbate the U.S. fiscal deficit or lead to long-term economic harm, credit rating agencies may downgrade the U.S. credit rating. A downgrade would increase the perceived risk of holding U.S. debt, making investors less willing to buy Treasury bonds at current prices. This would further harm the liquidity of U.S. Treasuries.
6. Shifting Investor Preferences
Amid rising tariffs and geopolitical uncertainty, global investors may seek safer, more stable assets. Although U.S. Treasuries have traditionally been seen as a “safe haven,” prolonged economic stress from tariffs may lead investors to look for less risky alternatives. This shift in preference further reduces liquidity in the Treasury market.
In summary, tariffs indirectly affect Treasury bond liquidity by raising borrowing costs, reducing foreign demand, fostering fiscal uncertainty, and potentially increasing government borrowing. These factors combine to create an environment where Treasury bonds become less liquid, making it harder for the U.S. government to issue debt at favorable terms.
How Tariffs Drive Up Mortgage Rates and Impact Homebuyers
The negative impact of tariffs on mortgage interest rates is largely indirect but can still have significant consequences for homeowners and potential buyers. Here’s a breakdown of how tariffs can lead to higher mortgage rates:
1. Rising Inflationary Pressures
Tariffs increase the cost of imported goods, which drives up the prices of everyday products for consumers. This inflationary pressure can lead the Federal Reserve to raise interest rates in an attempt to cool the economy and control inflation. When the Fed hikes its benchmark interest rates, it becomes more expensive for banks to borrow money, which in turn raises the cost of loans, including mortgages. As a result, mortgage interest rates rise, making homeownership less affordable.
2. Increased Borrowing Costs for the U.S. Government
When tariffs are imposed, they often lead to higher government spending or borrowing (e.g., subsidies for affected industries like agriculture). The U.S. government may increase its debt issuance to cover these expenses, which can put upward pressure on long-term interest rates, including mortgage rates. When there are more U.S. Treasury bonds in circulation, yields may rise, influencing mortgage rates, since mortgages are closely tied to the yield on 10-year Treasury bonds.
3. Weakening of the U.S. Dollar
Trade wars and tariffs can cause the U.S. dollar to weaken. A weaker dollar can increase the cost of imports, fueling inflation. To counteract this, the Federal Reserve might raise interest rates, as discussed earlier. Additionally, a weaker dollar can lead to higher yields on U.S. bonds to make them more attractive to foreign investors. This rise in yields on U.S. Treasury bonds can push mortgage rates higher as well.
4. Increased Uncertainty and Risk
Tariffs introduce economic uncertainty, as businesses face higher input costs and reduced trade access. This uncertainty can make investors more risk-averse. As a result, investors may demand higher returns on U.S. government debt to compensate for the perceived risk, pushing up Treasury yields. Since mortgage rates are closely linked to these yields, an increase in bond yields due to tariff-induced uncertainty can directly lead to higher mortgage interest rates.
5. Global Investment Shifts
As tariffs raise the cost of doing business in the U.S. and disrupt trade relations, global investors might seek safer or more stable investment opportunities. If they pull back from U.S. assets, including Treasury bonds, this can raise the cost of borrowing for the U.S. government and businesses, again putting upward pressure on mortgage rates. The global capital flow can impact the availability of capital for U.S. homeowners, driving rates higher.
6. Slower Economic Growth
The combination of higher costs for businesses, less international trade, and reduced consumer spending due to inflationary pressures from tariffs can lead to slower overall economic growth. Slower growth increases the risk of economic instability, prompting the Fed to adjust rates in response. Even if the Fed lowers interest rates to stimulate the economy, the global effects of tariffs on inflation and uncertainty may prevent any significant relief for mortgage rates in the short term.
Tariffs create a chain reaction that drives up inflation, raises borrowing costs for the U.S. government, weakens the dollar, and creates economic uncertainty. All of these factors push up mortgage interest rates, making it harder for prospective homebuyers and homeowners refinancing to afford their homes.
Would you like to expand on how this could affect housing markets in different regions or for specific income brackets?
In response to President Trump’s recent tariff increases on Chinese imports, China has retaliated by imposing an 84% tariff on U.S. goods.This escalation significantly impacts American farmers, as agricultural products are primary targets in China’s countermeasures.
Impact on U.S. Farmers:
Loss of Competitive Edge:The steep tariffs make U.S. agricultural products substantially more expensive in the Chinese market.Consequently, Chinese buyers are likely to turn to alternative suppliers from other countries, diminishing the market share for American farmers.
Financial Strain:The increased tariffs exacerbate existing financial pressures on U.S. farmers, who are already contending with high input costs and low commodity prices.The added burden threatens their profitability and overall financial stability.
Ripple Effect on Rural Economies:Agriculture plays a crucial role in the economic health of rural communities.Reduced exports due to tariffs can lead to decreased income for farmers, which in turn affects local businesses and services that rely on the agricultural sector.
This development underscores the escalating trade tensions between the U.S. and China, with American farmers bearing significant repercussions.
Trade War!
On April 2, President Trump unilaterally declared a trade war against the rest of the world, imposing protectionist tariffs on 180 countries — calling it “Liberation Day.” This action was taken without congressional approval and in direct violation of the Constitution.
The Peterson Institute for International Economics (PIIE) calculated that the cumulative average tariff rate on Chinese imports would reach nearly 125% following the implementation of an additional 84% tariff by the Trump administration.This calculation accounts for the compounding effect of successive tariff increases over time.
Here’s a breakdown of how this figure is derived:
Initial Average Tariff Rate: Before the recent tariff announcement, the average tariff rate on Chinese imports was approximately 20.8%. This figure includes tariffs imposed during President Trump’s first term and subsequent adjustments under President Biden.
Additional Tariff Imposed: An additional 84% tariff is set to be applied to Chinese imports.
Compounded Tariff Calculation: The new tariff is applied on top of the existing tariffs, leading to a compounded effect. The formula to calculate the cumulative tariff rate is
Total Tariff Rate = (1 + 0.208) * (1 + 0.84) – 1
Total Tariff Rate = 1.208 * 1.84 – 1
Total Tariff Rate = 2.22472 – 1
Total Tariff Rate = 1.22472 or 122.472%
Rounding this figure gives approximately 122.5%, which aligns with PIIE’s calculation of nearly 125%.
This compounding effect illustrates how successive tariff increases can significantly elevate the overall tariff rate, leading to substantial impacts on trade dynamics and economic relations between the involved countries.
The new wave of tariffs on Chinese imports isn’t just economically misguided — it’s economically self-destructive. Far from punishing China, these tariffs act as a massive tax on American consumers and businesses. Tariffs are paid by U.S. importers, not by China. The costs inevitably flow downstream, driving up prices on everything from electronics and cars to construction materials, clothing, and medical equipment. In other words, tariffs are inflation accelerators — hitting American families directly at a time when inflation is already a concern.
Worse, these policies cripple the very U.S. manufacturers they claim to protect. American factories depend heavily on Chinese parts and materials to remain globally competitive. By driving up input costs, tariffs make U.S. manufacturing less competitive, not more. The likely result is fewer U.S. factory jobs, higher consumer prices, and a growing incentive for companies to offshore even more production.
China will not sit idly by, either. Retaliatory tariffs targeting U.S. exports — especially agricultural products like soybeans, pork, and corn — are almost guaranteed. U.S. farmers, already vulnerable in a highly competitive global market, will feel the squeeze first. Exporters of aircraft, cars, and technology are next in line.
Over time, this kind of trade policy encourages global supply chains to bypass the United States altogether. Multinational companies hate uncertainty and will naturally redirect investment to more stable environments like Mexico, Vietnam, or Indonesia. This risks isolating the U.S. economy from global trade flows and eroding its long-standing central role in the global economy.
Economically, the U.S. faces a toxic mix: rising prices alongside slowing growth — the classic recipe for stagflation. Inflation accelerates because of higher import costs, while growth slows as manufacturing, exports, and consumer demand contract under the weight of higher prices. Rising unemployment in key sectors becomes a real risk.
Perhaps most ironically, this tariff policy undermines America’s own technological leadership. Many U.S. innovations, from iPhones to solar panels, rely on Chinese components. Disrupting these supply chains increases costs for R&D, slows the adoption of green technologies, and handicaps U.S. efforts to lead the world in the next generation of tech.
Strategically, it’s even worse. The more the U.S. behaves like an unreliable or hostile trading partner, the more it pushes other countries — including allies — toward China’s orbit. China gains a propaganda victory, portraying itself as the stable alternative to an erratic and isolationist America.
Ultimately, these tariffs function less like economic policy and more like economic self-sabotage. They tax Americans, hurt U.S. businesses, fuel inflation, slow growth, threaten jobs, and weaken America’s position in the world. It’s like burning down your own house because you don’t like the neighbor’s paint color.
White House Tariff Clarification — The Executive Order outlines that the total tariffs on China under Trump 2.0 amount to 145%, on top of approximately 20% imposed during Trump 1.0, resulting in an effective tariff rate of around 165%. However, most economists agree that tariffs exceeding 50% function effectively as a trade embargo, severely limiting or eliminating imports altogether.
It’s honestly hard to watch this and understand how any of his followers are falling for what has to be the worst attempt at “Don the Con” yet. I can’t find a single credible economist who agrees with Trump on this. Eliminating immigration and launching a trade war at the same time isn’t strategy — it’s economic suicide. It’s like going nuclear on your own economy. I’d say someone needs to take the “codes” out of his hands — but it’s too late. He’s already launched them.
Trade War!
On April 2, President Trump unilaterally declared a trade war against the rest of the world, imposing protectionist tariffs on 180 countries — calling it “Liberation Day.” This action was taken without congressional approval and in direct violation of the Constitution.
Why doesn’t the stock market just crash in a straight line?
Short Sellers in Short:
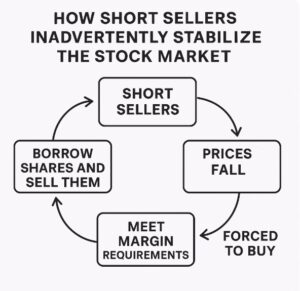
Short sellers inadvertently stabilize the market because when prices fall too far, too fast → their margin requirements force them to buy stock to cover losses → creating upward buying pressure → which puts a floor under falling prices.
This happens automatically even if short sellers are betting against a stock — because their broker doesn’t care about their opinion, only about risk.
Step-by-step: How it works
1. Short sellers borrow shares and sell them
→ They hope to buy back later at a lower price.
Example:
Short seller borrows and sells 100 shares at $50 = $5,000 proceeds.
2. If the stock price rises, losses are unlimited
→ If price goes from $50 → $75 → $100 → $200 → Losses grow exponentially.
3. Brokers set margin requirements
→ Short sellers must have enough collateral (cash or assets) to cover potential losses.
→ If stock price rises or becomes volatile, margin calls happen.
4. Forced buying happens on margin calls
→ If a short seller can’t meet the margin requirement, the broker will buy back the stock on their behalf to close the position.
→ This buying happens regardless of fundamentals — it’s a risk-control mechanism.
5. The stabilizing effect
→ When markets are falling and lots of people are short → at some point, shorts must take profit or cover losses.
→ That buying pressure offsets panic selling.
→ Result: Short sellers, ironically, help prevent free-fall crashes from going on indefinitely.
Why is this stabilizing?
Short sellers add liquidity on the way down (by selling into overvalued prices).
They add demand on the way up (when forced to cover or take profits).
It’s like a shock absorber: → They accelerate down-moves initially → but put a floor under them eventually.
Caveat:
If too many people are short → this can create short squeezes — where forced buying causes prices to overshoot upward. (See: GameStop 2021)
Bottom line:
Short sellers stabilize the market — not because they want to — but because risk management rules force them to act in ways that counter extreme price moves.
→ Sell high → Buy low → But margin rules ensure that “buy low” can’t wait forever.
Short Sellers Help Stabilize the Stock Market
Flow:
→ Short Sellers borrow shares & sell
→ Prices fall — their bet is working
→ But if Prices rise or get volatile
→ They hit Margin Requirements
→ Forced to Buy Back shares
→ That buying pressure helps Stabilize Prices
Structural, Non-Emotional Buyers
Another big stabilizing force: Structural, non-emotional buyers — like mutual funds, index funds, pensions, and insurance companies — that must stay invested due to their mandates.
Even when panic selling hits, there are built-in sources of demand that automatically slow or reverse sell-offs — not because they “like the market” — but because of rules, math, and fiduciary responsibility.
Key Stabilizing Forces in a Sell-Off
1. Index Funds (Passive Funds)
Mandate: Match an index (S&P 500, Nasdaq, etc.)
Sell-off impact: When markets drop, they often receive inflows from 401(k)s, IRAs, target-date funds.
Result: They are forced to buy proportional amounts of every stock in the index — including the falling ones.
2. Mutual Funds (Active Funds)
Mandate: Typically must stay 90%-100% invested.
Sell-off impact: If they get cash inflows from investors seeing a dip as a buying opportunity → they have to deploy that cash → buying falling stocks.
3. Target-Date Retirement Funds
Mandate: Automatically reallocate to equities after big drops (to maintain stock/bond ratios).
Sell-off impact: If stocks crash and bonds stay flat → they rebalance → forced stock buyers.
4. Insurance Companies & Pensions
Mandate: Long-term liabilities require long-term assets → stocks are part of that.
Sell-off impact: They may be value buyers in panic sell-offs to lock in future returns.
5. Corporate Buybacks
Mandate: Pre-approved buyback plans often accelerate when shares fall below certain levels (seen as “cheap”).
Sell-off impact: Automatic buy demand from companies themselves.
The more forced buyers appear due to structural mandates.
The more cash gets deployed automatically.
The more short-sellers are forced to buy back.
This is why stock market crashes — unless driven by systemic financial collapse — often slow down or reverse before valuations hit absurd lows.
Here’s how a crash works:
1. Stabilizers Create “Speed Bumps,” Not Floors
Short-seller covering, passive fund buying, and corporate buybacks don’t prevent a crash.
They just create temporary demand pockets → slowing or reversing declines briefly.
These speed bumps make the crash feel chaotic, not orderly.
→ Sharp Drop
→ Violent Bounce (forced buying, covering, rebalancing)
→ New Selling Pressure (fund redemptions, fear returns)
→ Another Drop
→ Another Bounce
→ Capitulation (selling exhaustion)
→ Bottom (nobody left to sell)
→ Stabilizers don’t prevent crashes. → They just interrupt them. → They inject buying at unpredictable moments → creating volatility spikes, not smooth declines. → If fear or liquidity risk is greater than the stabilizing force → new lows come. → But the deeper the drop, the stronger those stabilizing forces eventually become.
Why This Crash is Different
What makes this crash different? It’s self-inflicted. Unlike past downturns driven by credit bubbles or external shocks, this slowdown is the result of deliberate policy choices. The combination of restrictive immigration, escalating tariffs, and poorly coordinated climate responses has created a global drag on growth unlike anything since the Great Depression. This isn’t just a business cycle — it’s structural. If nationalist, isolationist, and protectionist policies persist, it’s possible that markets won’t fully recover for a generation — or at all.
It’s honestly hard to watch this and understand how any of his followers are falling for what has to be the worst attempt at “Don the Con” yet. I can’t find a single credible economist who agrees with Trump on this. Eliminating immigration and launching a trade war at the same time isn’t strategy — it’s economic suicide. It’s like going nuclear on your own economy. I’d say someone needs to take the “codes” out of his hands — but it’s too late. He’s already launched them.
Trade War!
On April 2, President Trump unilaterally declared a trade war against the rest of the world, imposing protectionist tariffs on 180 countries — calling it “Liberation Day.” This action was taken without congressional approval and in direct violation of the Constitution.
FORECASTS COME TO FRUITION Drill, Baby, Drill (How Hate and Ignorance Distort Economic Perspectives)
July 2024 – Pre-Election Warning: Concerns were raised about candidate Trump’s proposed economic policies, highlighting potential unintended consequences such as heightened inflation and increased national debt—both of which could undermine economic stability. Additionally, experts cautioned that his administration’s environmental stance, including withdrawing from the Paris Agreement and rolling back over 100 environmental regulations, could have devastating effects on both the economy and the environment. Now, much of this forecast is unfolding before our very eyes.
Economic Outlook 2025 – 2035
November 2024 – Post-Election Analysis: Concerns are mounting over the potential consequences of President Elect Trump’s proposed economic policies, particularly their impact on inflation, national debt, and climate change. The Committee for a Responsible Federal Budget estimates these policies could add $7.75–$10 trillion to the national debt over the next decade. Additionally, projections suggest inflation could rise to at least 6% by 2026, with consumer prices potentially increasing by 20% by 2028. These forecasts have since been revised, reflecting higher inflation and slower economic growth, compounded by the significant fallout of an ill-conceived trade war.
Financial Disclosure: Trump’s Crimes and Conflicts of Interest
This article examines financial disclosure and conflict-of-interest regulations for U.S. presidents and officials, highlighting the ethical expectations and legal requirements for transparency. It discusses President Donald Trump’s failure to meet traditional financial disclosure norms, including his refusal to divest from business interests, his lack of transparency in financial reporting, and documented conflicts of interest.
It really comes down to how one defines a recession. Traditional recessions are often characterized by rising unemployment, but with Trump’s immigration policies severely restricting the labor force, the job market may appear tighter than usual — even as the underlying economy deteriorates.
When you factor in these artificial constraints on labor supply, there’s easily a 90%+ probability of a U.S. recession this year. And given the ripple effects of tariffs, trade wars, and global uncertainty, I’d estimate a 95% chance of a global recession as well. This won’t look like past recessions on the surface — but in terms of slowing growth, rising costs, reduced output, and widespread economic strain, it absolutely qualifies.
For the past several years, immigration has contributed roughly 80% of U.S. GDP growth. Even before factoring in the tariffs, the U.S. economy was already facing the prospect of slow — if not flat — growth this year. Now, with the addition of what amounts to the largest regressive tax increase in U.S. history, the outlook has gone from concerning to potentially catastrophic. While the full impact of these tariffs remains uncertain, the risks are clear: higher consumer prices, reduced purchasing power, supply chain disruptions, and broad-based economic strain — especially for lower- and middle-income households. The combination of anti-immigration policies choking labor supply and tariffs imposing massive new costs on consumers and businesses creates a perfect storm of stagnation and inflation. Together, these policies could produce the most damaging U.S. economy in over a century.
How can the climate breakdown and collapse of the climate system be explained through chaos theory?
Great question — this is one of those rare cases where chaos theory isn’t just useful — it’s necessary to understand what’s happening with the climate system.
In a nutshell:
The climate system is a non-linear, complex, feedback-driven system — exactly the kind of system chaos theory was developed to describe.
Chaos Theory Basics (quick refresher)
Chaos theory studies how small changes in initial conditions can lead to wildly different outcomes in complex systems. This is often called sensitive dependence on initial conditions — or famously, the butterfly effect.
In chaotic systems:
Behavior looks random, but is deterministic underneath.
Predictability breaks down over time.
Feedback loops accelerate instability.
Thresholds or tipping points matter more than averages.
System nears a critical threshold (edge of chaos).
Seemingly small trigger (like a bad El Niño year) causes cascading failures:
ocean currents stall
food systems fail
regional collapses emerge
global feedbacks accelerate
The Frightening Part (but also the scientific truth)
Climate breakdown isn’t a slow, smooth, linear decline. It’s a chaotic, non-linear system heading for phase shifts, tipping points, and potential collapse.
That’s why decades of “x degrees = y impacts” models are failing. Real-world climate disruption is jumping ahead faster than expected — because the system is moving into a chaotic regime.
A Final Visual Metaphor (from chaos theory)
Imagine Earth’s climate as a ball rolling in a valley:
Stable = ball stays in the valley bottom.
We’ve pushed the ball up the slope (burning fossil fuels).
The higher it goes, the more unstable.
At some point the ball tips over into another valley — a new stable state (but maybe hostile to life as we know it).
This is what collapse looks like in chaos theory.
Bottom Line
Climate change isn’t just “getting hotter.” It’s a chaotic transition, where:
Local events become global.
Predictability evaporates.
System stability breaks.
Collapse happens not slowly — but in lurches, jumps, and phase changes.
Our updated climate model, which integrates complex social-ecological dynamics with the non-linear, feedback-driven behavior of physical systems, indicates global temperatures could rise by as much as 9°C this century.
It is terrifying to watch American journalism go silent — not because reporters don’t care, but because many of us know exactly what happens when we speak the truth now.
I know. I’ve been an investigative journalist for over 45 years, filming police corruption, government lies, and abuse of power across this country. I have faced threats before. But this — this is something darker.
On election day, I realized I could no longer safely use my real name. The night before, I dreamed I was arrested at a protest. That is not paranoia. That is preparation in Trump’s America.
Since returning to power, Trump has wasted no time weaponizing the legal system against his perceived enemies — especially the press. Major networks like ABC and independent journalists face a relentless barrage of lawsuits, not because Trump expects to win, but because he wants to bleed them dry and silence them. Under a Justice Department now resembling a political death squad, who will stop him?
And it’s not just lawsuits. State and federal crackdowns on peaceful protests are increasing, targeting Americans exercising their constitutional rights. Their crime? Daring to oppose genocide, war, or environmental destruction. At the Hands Off! protests, the loudest chants weren’t just against war — they demanded the release of political prisoners held in America today.
This is no longer creeping fascism. It is marching down Main Street with impunity.
Anyone who knows history sees the signs. This is how it starts: with fear. With silence. With people convincing themselves, “It can’t happen here.”
But it is happening here.
A Coordinated Assault on Truth
Trump is not alone. In Israel, Netanyahu’s far-right government has banned journalists from reporting in Gaza and outlawed Al Jazeera, the region’s most reliable independent outlet. Reporters who attempt to document atrocities face arrest or worse.
Both leaders understand that silencing truth is essential to maintaining authoritarian power. Their tactics are deliberate: demonize the press, weaponize courts, spread disinformation, and make public dissent a punishable offense.
Meanwhile, as these leaders dismantle democratic institutions, they fuel crises that demand accountability: genocide in Gaza, escalating wars, environmental collapse, and economic ruin. Silencing journalists silences the evidence.
Why This Moment Matters
We have entered a dangerous feedback loop: authoritarian regimes suppress dissent, allowing them to escalate violence and repression, which in turn demands more suppression to avoid accountability.
Independent journalism is the last line of defense. Without it, people will not know the full extent of the atrocities being committed in their name, the corruption draining their futures, or the environmental collapse accelerating under deregulation.
We, as journalists, continue to report — even if anonymously — because silence is complicity.
And we, as citizens, must decide if we will let fear dictate our future.
Citizen, beware.
Journalist, beware.
Truth is now treason in Trump’s America, and in Netanyahu’s Israel.
If we allow the silencing of journalism, the silencing of democracy will follow.
Donald J. Trump (DJT) Hotels & Casinos was an entertainment company that owned and operated the Trump Plaza Hotel and Casino, Trump Taj Mahal Casino Resort, Trump’s Castle Casino Resort and Trump Indiana.
Besides revenues from gambling, the properties offered other forms of entertainment. The Taj Mahal was an experience unto itself. Just the entrance had $1 million in 24-karat gold leaf… and, millions of dollars worth of German crystal chandeliers sparkled over the lobby’s Carrera marble-floor.
I’m an economist. In the 1990s, I conducted a moral and ethics experiment involving the stock DJT for a widows and orphans fund, during which Trump misappropriated the funds. A business bankruptcy impacts more people than a personal bankruptcy and is seen as a more significant violation of business ethics and morals.
The original stock with the ticker symbol DJT belonged to Trump Hotels & Casino Resorts (THCR), a company founded by Donald Trump in the 1990s. It operated various casinos and resorts, including Trump Plaza, Trump Taj Mahal, and Trump Marina in Atlantic City. THCR faced ongoing financial difficulties, which eventually led to four major bankruptcies. In 1995, the company went public under the ticker DJT, aiming to raise funds to refinance debts and expand its casino ventures. However, the company quickly became over-leveraged with high-interest debt, which plagued its operations.
The first bankruptcy in the timeline occurred in 1991, before DJT went public, when Trump’s Taj Mahal casino filed for Chapter 11 bankruptcy after failing to generate enough revenue to service its over $1 billion debt from junk bonds. Trump had to give up half of his ownership in the Taj Mahal but retained control of the casino. In 2004, Trump Hotels & Casino Resorts (by then public under DJT) filed for bankruptcy a second time due to its massive debt load and struggling casino operations. During this bankruptcy, Trump gave up more control of the company to creditors, though he stayed on as chairman.
In 2009, the company, rebranded as Trump Entertainment Resorts, filed for Chapter 11 again, marking the third bankruptcy. Trump resigned as chairman and left the board of directors, maintaining only a small ownership stake. Despite these efforts, the financial situation worsened, and in 2014, the company filed for bankruptcy a fourth time, leading to the closure of the Trump Plaza and Trump Taj Mahal casinos. This final bankruptcy signaled the end of Trump’s casino ventures, though his name remained on some properties through branding agreements.
The successive bankruptcies decimated the value of DJT stock, and Trump’s stake in the company dwindled over time. By the time of the 2014 bankruptcy, Trump had little control over the company. Eventually, DJT stock ceased to exist as the company’s assets were sold off. The bankruptcies are often cited as part of Trump’s controversial financial history, where he used bankruptcy laws to restructure debts, often at the cost of shareholders and creditors.
Conclusion
It’s difficult to determine the exact number of corporate bankruptcies associated with Donald Trump’s business ventures, in part because of how some analysts count them. In this particular case, there were four separate bankruptcy filings, though many analysts count them collectively as a single event. Broadly, most sources agree that Trump’s companies have filed for bankruptcy at least six times, with some estimates — depending on how repeat filings by the same entity are treated — placing the total closer to 12 to 14.
In each instance, critics have argued that Trump personally profited despite the financial losses borne by shareholders, lenders, and employees. These allegations typically focus on patterns of aggressive debt use, questionable fiscal management, and the transfer of risk from Trump to investors and creditors.
Now, he is doing it worldwide.
As one economist put it:
“Trump didn’t just pick a trade war — he picked one with the entire planet.”
A Crisis of This Magnitude Has Not Been Seen in Nearly 100 Years
While past recessions were driven by financial collapses (such as 2008’s mortgage crisis or the dot-com bubble in 2000), this economic crisis is entirely policy-driven. The sheer scale of the tariffs, combined with global retaliation and the isolation of the U.S., has created a trade collapse not seen since the 1930s. If history is any guide, the consequences could be severe, with prolonged economic hardship, market instability, and lasting damage to U.S. credibility in global trade.
Trade War!
On April 2, President Trump unilaterally declared a trade war against the rest of the world, imposing protectionist tariffs on 180 countries — calling it “Liberation Day.” This action was taken without congressional approval and in direct violation of the Constitution.