bookmark_borderWhen Hypothesis Becomes Theory: Trump’s Trade War Has Triggered a Global Credit War

by Daniel Brouse
April 11, 2025

For decades, economists have quietly asked a disturbing hypothetical: What happens if the U.S. launches a trade war and a credit war at the same time? It was an academic curiosity — a thought experiment for textbooks, not real life. Until now.

Donald Trump has turned that hypothesis into reality.

During Trump’s first term (Trump 1.0), he laid the groundwork — tearing up trade agreements, undermining global institutions, and threatening America’s economic alliances. But now, in Trump 2.0, he’s gone from testing the waters to executing a full-scale economic experiment on a global stage.

What was once theory is now practice. And the world is starting to buckle under the strain.

Trade War Meets Credit War: A Dangerous Combination

Most people think of tariffs as isolated tools — a tax on imported goods here, a protectionist policy there. But in a global economy powered by complex capital flows, the consequences are far more sweeping. Tariffs don’t just hit goods — they hit trust, stability, and most importantly: liquidity.

By weaponizing trade, Trump has triggered a second, even more dangerous war: a global credit war.

Here’s why that matters.

The U.S. dollar has long been the world’s reserve currency because global trade flows through it. Countries that export goods to the U.S. accumulate dollars — and those dollars flow right back into U.S. assets like Treasury bonds. That system keeps interest rates low, funds U.S. debt, and stabilizes the global economy.

But what happens when that trade flow is deliberately choked off?

The Early Signs of System Failure

If foreign countries export less to the U.S., they earn fewer dollars. If they have fewer dollars, they buy fewer U.S. Treasuries. And if they buy fewer Treasuries, U.S. borrowing costs go up — triggering higher interest rates, tighter credit, and financial instability.

This is not just a theoretical concern anymore. We are seeing early evidence that this credit war is underway:

  • Bond market liquidity is evaporating.

  • Foreign demand for U.S. Treasuries is declining.

  • Global central banks are diversifying away from the dollar.

  • Gold, commodities, and non-dollar assets are surging.

  • Interest rates are rising — not because of growth, but because of risk.

Chaos Theory in Action

This is a classic example of a complex, non-linear dynamic system at work — the domain of chaos theory. The parts are all connected, but not in simple, linear ways. A shock in one area — tariffs — is now producing unpredictable disruptions in areas that may seem unrelated but are fundamentally tied together.

The variables in this system include:

  • The value of the U.S. dollar

  • U.S. debt and Treasury markets

  • Interest rates (both domestic and global)

  • Inflation and deflation pressures

  • Recession — or worse, depression

  • Foreign cash flows and investment patterns

  • Trade wars and their escalation

  • Climate disasters exacerbating supply shocks

  • Immigration pressures triggered by economic collapse

The Big Question: What If the Dollar Loses Its Reserve Status?

Ultimately, the darkest scenario is no longer unthinkable: What happens if the U.S. dollar loses its status as the world’s reserve currency?

This would unleash a profound economic reset, marked by:

  • Exploding U.S. borrowing costs

  • A collapse in consumer purchasing power

  • Global capital flight from U.S. assets

  • Severe contraction in both trade and credit

  • Domestic political and economic instability unlike anything in modern history

Conclusion: We Are In the Experiment Now

This is no longer just economic theory.

This is real.

Trump’s trade war has metastasized into a global credit war. The feedback loops are forming. The shocks are compounding. And the system is starting to behave exactly as economists long feared: chaotically, violently, and unpredictably.

Welcome to the experiment. We’re all in it now. The only question left is whether the damage is reversible — or if we’ve already crossed the tipping point.

Capital Preservation During Trumpenomics

The Inevitable Collapse: How Trump’s Policies and Climate Neglect Will Reshape the Economy
Trumpenomics: The Decline of the US

bookmark_borderClimate Collapse Will Break Capitalism

by Daniel Brouse
April 11, 2025

As extreme weather accelerates, the world is nearing a tipping point where insurance — and capitalism itself — can no longer function.

The climate crisis is on track to destabilize and ultimately destroy global capitalism, according to a stark warning from one of the world’s largest insurers. Allianz SE board member Günther Thallinger has sounded the alarm: the growing cost of climate-driven disasters threatens to break the financial sector’s ability to operate — starting with insurance.

Speaking as both a top executive of Allianz and chair of its investment board, Thallinger said the world is fast approaching temperature thresholds beyond which many climate risks will simply become uninsurable. And without insurance, critical sectors of modern finance — from mortgages and real estate to infrastructure and industry — will cease to function.

“Heat and water destroy capital,” Thallinger wrote in a widely discussed LinkedIn post. “Flooded homes lose value. Overheated cities become uninhabitable. Entire asset classes are degrading in real time.”

A Financial System on the Brink

Current government policies still allow global carbon emissions to rise, putting the world on track for a temperature increase between 2.2°C and 3.4°C above pre-industrial levels. The damage expected at 3°C is so severe, Thallinger warned, that it will overwhelm governments’ ability to provide financial relief or adaptation measures.

Already, the scale of climate-related damage is staggering. Insurance company Aviva estimated that extreme weather caused $2 trillion in damages globally between 2013 and 2023. In 2024 alone, GallagherRE reported climate losses of $400 billion. Insurers like Zurich have declared it “essential” to reach net-zero emissions by 2050 to avoid systemic collapse.

But Thallinger warns that time is running out — and that the breakdown is already underway. In parts of California, for example, insurers have stopped covering homes due to escalating wildfire risks. Entire regions, he said, are becoming “uninsurable.”

The Math No Longer Works

“As temperatures rise to 1.5°C, 2°C, 3°C, insurers will no longer be able to offer coverage for many of these risks,” Thallinger said. “The math breaks down: the premiums required exceed what people or companies can pay. This is already happening.”

Our updated climate model, now integrating complex social-ecological factors as part of a dynamic and non-linear system, shows that global temperatures could rise by up to 9°C within this century—far beyond previous predictions of a 4°C rise over the next thousand years. This level of warming will render much of the world uninhabitable within this century.

Without insurance, the ripple effects spread rapidly through the financial system. Mortgages, infrastructure investment, agriculture, and transportation all rely on insurance to manage risk. Remove that foundation, and the global credit system starts to seize up — a “climate-induced credit crunch.”

“This is a systemic risk threatening the very foundation of the financial sector,” Thallinger warned.

Nick Robins, chair of the Just Transition Finance Lab at the London School of Economics, called the analysis “devastating,” adding that it highlights not only a financial crisis but a civilizational one.

The End of Adaptation Myths

Thallinger also pushed back on the comforting narrative that humanity can simply adapt its way through climate breakdown.

“There is no way to ‘adapt’ to temperatures beyond human tolerance,” he wrote. “Whole cities built on flood plains cannot simply pick up and move uphill.”

Australia’s disaster recovery spending has already increased sevenfold between 2017 and 2023. No government, Thallinger argued, will be able to cover the cost when multiple extreme events strike in rapid succession — something climate models increasingly predict.

At 3°C, Capitalism Fails

At 3°C of warming, the damage becomes uninsurable, governments become financially crippled, and adaptation becomes largely impossible.

“That means no more mortgages, no new real estate development, no long-term investment, no financial stability,” Thallinger concluded. “The financial sector as we know it ceases to function. And with it, capitalism as we know it ceases to be viable.”

The Solution? Urgent, Global Decarbonization

The only solution, Thallinger said, is to end fossil fuel burning at unprecedented speed and scale. Everything else — delay, half-measures, false comforts — will only hasten systemic collapse.

“The good news is we already have the technologies to switch from fossil combustion to zero-emission energy,” he said. “The only thing missing is speed and scale. This is about saving the conditions under which markets, finance, and civilization itself can continue to operate.”

Or, as Janos Pasztor, former UN assistant secretary-general for climate change, put it: “The insurance sector is a canary in the coal mine when it comes to climate impacts.”

This canary is no longer just singing — it’s screaming.

The Human Induced Climate Change Experiment

bookmark_borderThe Economic Reality Behind the Tariff ‘Pause’: A 35% Tariff Rate

by Daniel Brouse
April 10, 2025

On April 9, economists were left scratching their heads, wondering why anyone believed that the announcement of a “PAUSE” on tariffs would have any meaningful impact on the economy. It was a classic case of wishful thinking, with little grounding in the hard numbers that define economic reality. By April 10, as the smoke cleared, it became increasingly clear that the “pause” was more of a symbolic gesture than a substantive shift in trade policy.

A closer look at the numbers reveals the magnitude of the tariff situation. When we break it down, the initial tariff rate on imports stood at around 3%. However, the story changes dramatically on what is known as “Liberation Day,” when the effective tariff rate spiked to a staggering 40%. This isn’t a typo — it was a significant jump, and it marked a crucial point in the broader context of global trade.

On April 9, the effective tariff rate without factoring in China, the United States’ largest trading partner, shifted to 18%. This rate was still the highest we’ve seen since the 1940s. While this sounds like a notable shift, it doesn’t fully capture the broader impact. When we include China in the equation, the story takes an even more dramatic turn. The total effective tariff rate, including both the general tariffs and consumption taxes on Chinese imports, skyrocketed to a range of 30-35%. This figure is nothing short of unprecedented, making it the highest effective tariff rate in U.S. history.

The implications of these numbers are far-reaching. For one, a tariff rate that high can have serious consequences for both consumers and businesses, leading to higher costs for imported goods and potentially stifling economic growth. A “pause” on tariffs might sound like a step toward easing trade tensions, but in reality, it does little to reverse the long-term economic pressures already set in motion.

So, while the announcement of a tariff “pause” may have been met with some optimism, the underlying reality is that U.S. tariffs are at historically high levels, and the true impact of these policies is just beginning to unfold. For economists and policymakers alike, it’s crucial to move beyond superficial gestures and focus on the hard economic data that tells the real story of America’s trade situation.

Trumpenomics: The Decline of the US

bookmark_borderWall Street: When First is Last

by Daniel Brouse
April 10, 2025

How Some of the Biggest Market Gains Are Actually Signs of the Worst Losses

Those who appeared to be first, ended up last. Those who appeared to be last, ended up first.

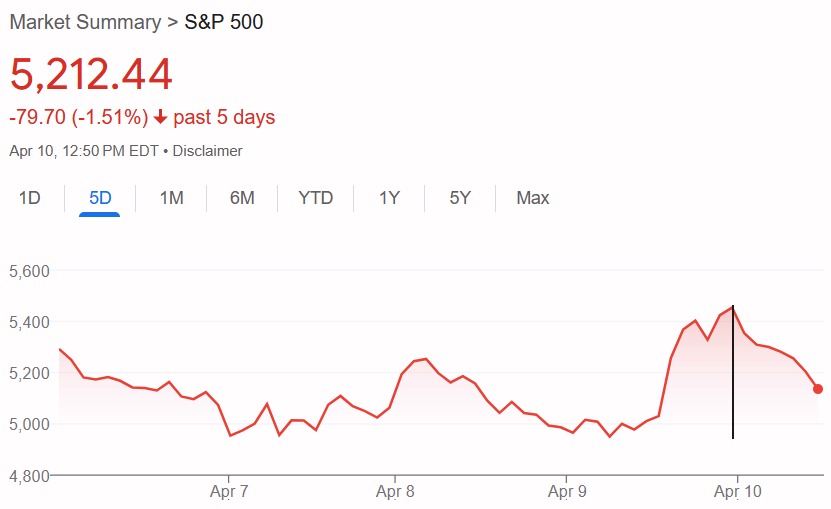
April 9 wasn’t just another volatile day on Wall Street — it was a near-perfect example of how markets behave during a crash, and why some of the biggest one-day rallies in history often happen inside brutal bear markets.

It’s one of the great paradoxes of investing:

The biggest up-days don’t mean recovery — they often signal panic, forced liquidation, and deeper instability ahead.

What Actually Happened?

In essence, the trillions of dollars that appeared to be gains in the market were really losses for short sellers. That’s the hidden truth of sharp rallies during a crash — the money didn’t come from real investment demand; it came from forced buying.

The key difference is this: when markets rise under normal conditions, long-term investors have unrealized gains — profits on paper, but not yet cashed out. But in a short squeeze, those unrealized gains for stockholders are directly matched by realized losses for short sellers who are forced to buy at any price to cover their positions.

It’s not wealth creation — it’s wealth transfer under pressure. In the chaos of a market crash, those who looked like winners became losers — and those who looked like losers became winners.

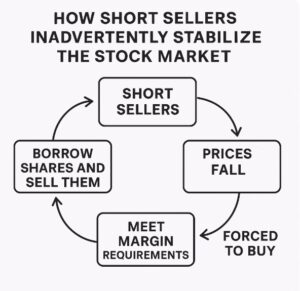
Short Sellers Help Stabilize the Stock Market

The Mechanics

Markets spiked sharply after a sudden and dramatic policy reversal was announced — a move investors hoped might slow down the economic freefall.

But here’s the key:
This initial surge wasn’t organic buying. It was mechanical.

→ Short sellers — traders betting against the market — suddenly got squeezed.
→ When prices jump too fast, short sellers face margin calls — demands from brokers to put up more money or buy back the stock they bet against.
→ Since short-selling carries unlimited loss potential, these traders are forced to buy shares no matter the price to avoid catastrophic losses.

That panic buying drives prices even higher, triggering more margin calls in a dangerous feedback loop.

Why Does This Matter?

Because once those short positions are closed (covered), the artificial buying pressure evaporates.

And here’s the brutal part:
→ Many of those same shares bought in a panic are quickly sold again by longer-term bearish investors or funds desperate to raise cash.

That’s what you saw today — the so-called “pullback” was not just natural volatility; it was the aftershock of forced buying unwinding itself.

Markets gave back much of yesterday’s gains. And worse, they are now at risk of retesting — or breaking — the recent lows.

The Illusion of Safety

In chaotic markets like this, price action becomes non-linear and unpredictable.

Massive rallies during a downturn are not necessarily signs of strength — they are often signs of extreme stress within the system.

This is why some of the biggest single-day gains in market history occurred during the Great Depression, the 2008 Financial Crisis, and the early phases of COVID’s market panic.

It’s not recovery.
It’s chaos.

Why Crashes Look Like This: Forced Buyers Meet Forced Sellers

Several key forces converge during these phases:

  • Short-sellers covering in panic.

  • Margin calls across hedge funds and leveraged traders.

  • Index funds and mutual funds, required to stay fully invested, reluctantly buying dips.

  • Passive investing structures amplifying volatility both directions.

  • Algorithmic trading chasing momentum.

These dynamics create a dangerous loop:
→ Sharp rallies from forced buying.
→ Followed by brutal reversals from forced selling.

The result?
A jagged, chaotic pattern — not a smooth decline.

And the Most Important Lesson:

In a true crash, there is no guaranteed floor.

Support levels only exist until panic overwhelms them. Fundamentals don’t matter when liquidity disappears.

Markets become driven by positioning, margin calls, and liquidity — not valuation.

This is why the old phrase still applies:
“Bear market rallies are designed to fool the maximum number of people in the minimum amount of time.”

Closing Thought:

The real danger today isn’t just volatility — it’s the fact that this is largely self-inflicted economic destruction.

Policy mistakes — from trade wars to immigration freezes to climate inaction to protectionist tariffs — have combined into a global slowdown unlike anything since the Great Depression.

And unlike past crashes, there is a real risk this time that the damage is structural — not cyclical.

Recovery is not guaranteed.

One-Week Chart Highlighting Record One-Day Spike

Trumpenomics: The Decline of the US

bookmark_borderState of the Economic Union: Still Horrible

by Daniel Brouse
April 10, 2025

April 9th’s unprecedented bounce in the stock market was nothing more than a temporary sugar high — a dead cat bounce in market jargon. It was fleeting, emotional, and utterly disconnected from the underlying economic reality. Fundamentally, nothing positive has changed. In fact, the situation is worse. Far worse.

Why Did Trump Blink on Tariffs?

The reason for Trump’s abrupt about-face on his tariffs wasn’t because of some grand negotiation tactic or economic strategy. It was panic. The night before, the U.S. Treasury bond market suffered one of its worst liquidity crises in modern history. The collapse in bond demand triggered fears that the Federal Reserve might have to step in with emergency intervention. At that exact moment, Trump announced a 90-day “pause” on certain tariffs — a clear attempt to calm the waters.

This pause was not a sign of strength. It was a sign of weakness and desperation.

Traders took the opportunity to buy oversold stocks, but longer-term investors smartly used the bounce to sell into strength. And this morning? Futures were already down again, signaling that smart money knows this isn’t over.

Tariffs Are Still in Place — And More Are Coming

Many of these countries already have long-standing trade agreements with the U.S. — agreements that Trump has repeatedly violated or unilaterally torn up. So why would anyone believe he’s negotiating in good faith now? The pattern is clear: deals don’t mean much if one side keeps changing the rules.

Nothing about the structural trade conflict has improved. The tariff pause doesn’t change the fact that the U.S. and China, the world’s two largest economies, are escalating toward a full-blown economic war. The new tariff structure is estimated to create an effective 145% tariff on Chinese imports into the U.S., and an 84% tariff on U.S. exports to China.

Global trade between the two countries could fall by 80% or more — a staggering figure that would destroy supply chains, eliminate jobs, increase consumer prices, and plunge the global economy into recession.

This is already happening.

Canceled CapEx and Collapsing Investment

We are seeing the damage show up in real-time across corporate America. Capital expenditures (CapEx) — the lifeblood of future economic growth — are being slashed or outright canceled:

  • Microsoft abandoned its $1 billion data center project in Ohio citing “market uncertainty.”

  • Ford shelved expansion plans in Michigan and cut thousands of jobs due to tariffs increasing steel and aluminum costs.

  • Harley-Davidson moved part of its production overseas to avoid retaliatory tariffs — killing U.S. factory jobs.

  • Boeing warned of major losses and delayed production schedules as global aircraft orders stall.

  • Caterpillar and Deere both cut forward guidance citing collapsing demand in agriculture and construction tied directly to the trade war.

  • Tesla scaled back its China expansion plans, warning of higher costs and lower demand.

  • Semiconductor manufacturers like Intel and Nvidia cut CapEx due to weakening global tech demand.

  • Even Apple hinted at slowing investment in U.S. facilities as its supply chain costs spiral higher.

This is just the tip of the iceberg. Thousands of small and medium businesses — the true backbone of the economy — are quietly canceling investments, freezing hiring, and shelving growth plans. Why build or expand if tomorrow’s rules are unknown and changing by tweet?

The Elephant in the Room: The Bond Market

The most misunderstood part of this entire crisis is the bond market — and Trump’s obsession with the 10-year Treasury yield.

Foreign countries like China and Japan hold the largest reserves of U.S. Treasuries. These reserves come from trade surpluses — dollars earned from selling goods to the U.S. But as Trump deliberately shrinks trade with the world, those dollar flows disappear. Less trade means fewer dollars. Fewer dollars means less buying of U.S. debt. Less demand for Treasuries means higher interest rates — even in the face of a slowing economy.

Ironically, this amounts to a self-inflicted credit war. Trump is attacking the very trade flows that fund the U.S. deficit. Worse, foreign countries are starting to invest their existing reserves elsewhere — in gold, in Euros, in commodities — anything but the U.S. dollar.

This isn’t just about trade anymore. This is about credit strength, reserve status, and financial stability.

Conclusion: The Real State of the Economic Union

The market bounce was a head fake.

  • The trade war is still escalating.

  • Global CapEx is collapsing.

  • Treasury demand is weakening.

  • Interest rates are likely to stay elevated despite recession risks.

  • Foreign capital is leaving.

  • Inflation remains persistent due to tariffs and a weaker dollar.

  • Corporate earnings are declining.

  • Uncertainty is growing.

Tariffs didn’t just disrupt goods and supply chains — they shattered America’s credibility. The so-called “reciprocal tariff” numbers were pure fiction, rooted in a fundamental misunderstanding of how global trade and capital flows actually work. Worse, they injected chaos into global markets and made U.S. trade policy look reckless, arbitrary, and unmoored from reality. Longtime allies and trading partners, faced with unpredictability from Washington, began hedging their bets and reducing their exposure to the U.S. economy. Suddenly, what was once considered the world’s most reliable safe haven didn’t feel so safe anymore.

This is not a healthy economy. This is an economy headed for stagflation — slow growth, high inflation, and rising interest rates — the worst possible scenario.

The State of the Economic Union?

Still horrible. And likely to get worse.


Trumpenomics: The Decline of the US

bookmark_borderCredit War!

by Daniel Brouse
April 9, 2025

Trump’s fixation on the 10-year Treasury bond comes down to a perfect storm of contradictions — and desperation. Here’s why it matters:

  1. He promised lower interest rates but has no real ability to deliver them.

  2. He can’t control interest rates — the market does.

  3. His budgets don’t work with elevated rates — every tick higher adds billions (or even trillions) to the national debt through higher borrowing costs.

  4. Higher interest rates, combined with a weakening dollar, fuel persistent inflation — creating a vicious feedback loop of rising prices and rising rates.

  5. Foreign countries — especially Japan and China — hold massive amounts of U.S. Treasuries. The overnight spike in bond yields started in Asian markets, signaling not just a financial crisis, but the possibility of a global credit war layered on top of the existing trade war.

Bottom line: The 10-year bond rate isn’t just a financial number — it’s a pressure gauge on Trump’s entire economic strategy. And right now, that gauge is flashing red — Credit War!

Ironically, this would be a completely self-inflicted credit war. By wrongly insisting that trade deficits are somehow tied to national budget deficits and debt, Trump is essentially forcing foreign countries to accept fewer U.S. dollars through reduced trade. And when those countries accumulate fewer dollars, they naturally invest less in U.S. assets — especially safe-haven investments like Treasuries. Less demand for Treasuries means higher interest rates, weaker credit strength, and greater financial instability — all triggered by a fundamental misunderstanding of how global trade and capital flows actually work.

April 10 State of the Economic Union: Still Horrible


Trumpenomics: The Decline of the US

bookmark_borderStock Market Update: A Worsening Economic Landscape

by Daniel Brouse
April 9, 2025

At this point, I wouldn’t pay much attention to the stock market. The bond market has effectively become what some are calling the “Trump Put” — a term that suggests Trump will only alter his damaging policies when the pain from a market collapse becomes too severe. That’s essentially what happened today, as a sharp reaction in the bond market forced a pause in his reckless policy-making. However, this is merely an indicator of the kind of knee-jerk reactions we can expect from Trump in the future. Unfortunately, the stock market is no longer a reliable indicator of overall economic health.

The truth is, much of the economic damage has already been done, and the fallout continues to worsen despite any attempts at intervention. The ripple effects of the Trump administration’s policies are visible across various sectors, and they are causing long-term harm to the economy. A clear example of this can be seen in Microsoft’s recent decision to cancel its $1 billion data center project in Ohio. The tech giant had initially committed to the development as part of its efforts to expand its cloud infrastructure, but the escalating uncertainty around tariffs and trade policies made the investment untenable.

This cancellation is far from an isolated incident. Companies across industries are pulling back on capital expenditures (CapEx) as they deal with the volatility created by these policies. For example, automakers are delaying or scrapping plans to expand production in the U.S. due to rising material costs from tariffs on steel and aluminum. Many manufacturers are cutting back on factory upgrades and hiring freezes, as uncertainty about future trade relations with key partners like China and Europe looms large.

Retailers, too, are feeling the squeeze. Large retail chains, which were already grappling with declining foot traffic and shifting consumer behavior, are now having to rethink expansion plans due to supply chain disruptions and the growing cost of imports. In addition to scaling back on new store openings, some are halting infrastructure investments, such as distribution centers and technology upgrades, as their financial outlook worsens.

The real estate sector is also suffering. Construction projects across the country have been delayed or canceled as developers face rising costs for materials like lumber and steel — costs driven up by tariffs. The uncertainty surrounding trade agreements and the broader economic landscape has led to a slowdown in both commercial and residential real estate development. High-profile projects, including those planned for large metropolitan areas, are now on hold indefinitely, as developers and investors await clearer signals from Washington.

This widespread reduction in CapEx is a clear indicator of the long-term economic damage caused by policies that prioritize short-term political gain over long-term stability. Companies aren’t just scaling back; they are actively preparing for an unpredictable future where market conditions could remain volatile. As this domino effect continues, it’s likely we will see even more industries scaling back their investments, further exacerbating the economic decline.

In short, while the stock market may see short-term corrections and rallies, the underlying damage to the economy continues to unfold. Corporate America is reacting with caution, and the full scope of the consequences is likely to play out over the coming months and years. The Trump administration’s approach to economic management has left a trail of uncertainty that companies are not willing to ignore. The impact of these decisions will likely be felt for much longer than the stock market’s momentary shifts suggest.

bookmark_borderTariff Turmoil: The Chaos and Confusion Surrounding U.S. Trade Policies in 2025

by Daniel Brouse
April 9, 2025

From Sector-Specific Levies to Unpredictable Pauses, Determining What Tariffs Remain in Effect Has Never Been More Complex

In a stunning reversal, the Trump administration just announced a 90-day pause on its controversial reciprocal tariffs policy — a clear sign that recent market chaos is starting to bite. With a record spike in interest rates overnight and global investors fleeing U.S. debt, the pause appears to be a desperate attempt to calm financial markets rattled by the escalating trade war.
For months, Trump’s tariff strategy has been framed as strength — but today’s move signals growing recognition that aggressive trade policies are now directly threatening U.S. economic stability. The world is no longer automatically turning to U.S. Treasuries in a crisis, and investors are demanding higher rates to hold American debt — a dangerous shift for the global economy.
While the pause buys time, it underscores a bigger problem: trust, once lost in global markets, is hard to recover.

Current Situation
As of April 9, 2025, the United States has implemented a series of tariffs under President Trump’s “reciprocal tariff” policy. Initially, a universal 10% tariff on all imports was set to take effect on April 5, 2025. However, on April 9, 2025, President Trump announced a 90-day pause on tariffs for over 75 countries that opted to negotiate rather than impose retaliatory measures.

Despite this pause, tariffs remain in effect for certain countries, most notably China. The tariffs on Chinese imports have been increased to a total of 145%, escalating the U.S.-China trade conflict.

The situation is dynamic, with ongoing negotiations and potential policy adjustments. For the most accurate and current information, it is advisable to consult official communications from the U.S. Trade Representative or the White House.

There are still significant tariff measures affecting imports from various countries and specific sectors; however, it is not at all transparent as to the actual law. Following is our best guess:

1. Canada and Mexico Tariffs:

  • 25% Tariff on Non-USMCA-Compliant Goods: On March 4, 2025, the U.S. imposed a 25% tariff on imports from Canada and Mexico that do not meet United States-Mexico-Canada Agreement (USMCA) standards.

  • Energy Imports: Canadian energy resources are subject to a reduced tariff of 10%, as per the adjustments made on March 4, 2025.

  • Reciprocal Tariffs: In response, Canada has imposed a 25% tariff on U.S. vehicle imports that do not meet USMCA standards.

2. Sector-Specific Tariffs:

  • Steel and Aluminum: Effective March 12, 2025, a 25% tariff was applied to imports of steel and aluminum articles, as well as certain derivative products, from all countries.

  • Energy Sector: While specific details on energy-related tariffs are limited, the White House has indicated that energy imports may be subject to new tariffs to promote domestic production.

  • Lumber: Lumber imports are among the sectors that could face new tariffs, as the administration has warned of potential measures to support domestic industries. ​

3. Tariff Status and Exemptions:

  • USMCA-Compliant Goods: Products that comply with USMCA standards are exempt from certain tariffs, including those on vehicles and specific goods from Canada and Mexico.

  • De Minimis Threshold: The U.S. has removed the de minimis exemption for low-value shipments from China, Hong Kong, and Macau, effective May 2, 2025, eliminating the $800 duty-free threshold for these regions.

4. Ongoing Developments:

  • Retaliatory Measures: Affected countries, including China, the EU and Canada, have announced retaliatory tariffs in response to U.S. measures, further complicating the trade landscape. ​

  • Future Tariff Considerations: The administration has indicated that additional tariffs may be imposed on sectors such as copper, pharmaceuticals, semiconductors, and lumber to encourage domestic production.

China: Although challenging to calculate precisely, this appears to bring the total tax on imports from China to 165% (updated). It also remains unclear whether the tax on EVs will now rise to 265%.

A 30-35% Tariff Rate

The Economic Reality Behind the Tariff ‘Pause’: A 35% Tariff Rate

On April 9, the effective tariff rate without factoring in China, the United States’ largest trading partner, shifted to 18%. This rate was still the highest we’ve seen since the 1940s. While this sounds like a notable shift, it doesn’t fully capture the broader impact. When we include China in the equation, the story takes an even more dramatic turn. The total effective tariff rate, including both the general tariffs and consumption taxes on Chinese imports, skyrocketed to a range of 30-35%

Resources:

Trumpenomics: The Decline of the US

bookmark_borderAmerica’s Trade War Is Costing More Than We Realize — It’s Costing Global Trust

by Daniel Brouse
April 9, 2025

Today’s record spike in U.S. interest rates is grabbing headlines — but it’s a symptom, not the disease. The real crisis is deeper and far more dangerous: America’s trade war has shattered the trust that once made U.S. financial markets the safest in the world.

For decades, the U.S. enjoyed an extraordinary advantage. No matter what turmoil rocked the world — wars, recessions, pandemics — foreign investors would rush to buy U.S. Treasuries. It wasn’t just about returns. It was about trust. The U.S. was stable, predictable, and reliable. That trust kept our borrowing costs low, our dollar strong, and our economy resilient.

But Trump’s trade war changed everything.

Tariffs didn’t just hit goods and supply chains — they hit America’s credibility. They introduced chaos into global markets, made U.S. policy look arbitrary, and forced long-time allies and trading partners to start hedging their bets. Suddenly, the “safe haven” didn’t feel so safe anymore.

And now we’re seeing the fallout.

Today’s bond market shock — one of the sharpest interest rate spikes in history — is part of a larger shift. Foreign investors aren’t rushing to U.S. Treasuries like they used to. Some are moving to gold. Others to European bonds. Some are simply staying home.

That shift comes at a staggering cost. Without foreign demand for our debt, the U.S. has to offer higher and higher interest rates to attract buyers. That means rising borrowing costs across the entire economy — for the government, for businesses, for homeowners.

This isn’t just about tariffs on steel or soybeans. This is about America losing its greatest economic weapon: trust.

And once trust is gone, it doesn’t come back easily — or quickly. No matter what happens next with Trump’s tariff policies, the damage is done. The U.S. has moved from “most trusted” to “no longer reliable” in the eyes of global investors.

That’s a legacy of the trade war we’ll be paying for long after the headlines move on.

Tariffs and the Liquidity Crisis in Long U.S. Treasuries

Trumpenomics: The Decline of the US

bookmark_borderThe Destructive Legacy of Trump’s Climate and Economic Policies: A Call for Urgent Action

by Daniel Brouse
April 9, 2025

Donald Trump’s dismissal of climate science and his aggressive promotion of fossil fuel extraction have resulted in a harmful and increasingly unsustainable energy policy. By labeling climate change as a “hoax” and referring to policies designed to combat it as “The Green New Scam,” Trump has ignored the overwhelming scientific consensus that climate change is real and accelerating. His catchphrase, “Drill, Baby, Drill,” is emblematic of an energy policy that favors short-term profits from fossil fuel extraction over the long-term health of the planet. This approach has not only worsened the climate crisis but has also contributed to growing economic instability. If left unchecked, the policies enacted during Trump’s administration will likely render the planet uninhabitable for future generations, causing irreversible damage to both the environment and the economy.

Trump’s Climate-Defying Actions: A Clear Threat to the U.S.

One of the most glaring examples of Trump’s failure to address climate change is his active support for policies that encourage fossil fuel extraction, even in the face of overwhelming evidence of its destructive impacts. While news broke about a major leak in the Keystone pipeline, causing widespread environmental damage, Trump was busy pandering to coal executives at a Republican fundraiser, celebrating the reopening of coal mining on public lands. At the same time, his Energy Secretary went on financial news outlets and falsely claimed that coal-fired power plants emit nothing but water vapor. This blatant ignorance and the spread of misinformation not only mislead the public but also accelerate the environmental degradation that is already threatening our future.

“Drill, Baby, Drill”: The Policy That Puts Us All at Risk

Perhaps no phrase better encapsulates Trump’s approach to energy policy than “Drill, Baby, Drill.” This mantra, which prioritizes fossil fuel extraction, is a cornerstone of an energy strategy that ignores the overwhelming evidence of climate change and its economic consequences. The immediate result of this policy is an increase in carbon emissions, which exacerbates the very climate crisis that threatens to destabilize both our environment and economy.

Climate change, driven by such policies, presents the most severe threat to not only our ecosystems but also to the global economy. The fallout from unchecked environmental destruction will have far-reaching effects, from agricultural disruptions to significant increases in healthcare costs and the destruction of vital infrastructure.

The Economic Consequences of Climate Change: A Perfect Storm of Inflation and Instability

Trump’s climate-denying energy policies are not just harmful to the planet—they have also created a volatile economic environment. The first inflationary shock tied to climate change occurred in 2019, when a devastating drought in Taiwan crippled the semiconductor industry. Taiwan, a global leader in microchip production, saw critical manufacturing facilities forced to shut down due to water shortages. This disruption, which impacted the global supply chain, marked the beginning of a series of economic challenges tied to climate-induced disasters.

In the years since, climate-related disasters have continued to escalate. From severe hurricanes and wildfires to prolonged droughts, each event has intensified the economic instability caused by climate change. These disasters have driven up insurance premiums, adding to the financial burden on homeowners and businesses alike. President Trump’s “Drill, Baby, Drill” approach has only fueled this instability by perpetuating fossil fuel dependency, accelerating climate change, and deepening the economic crisis.

The Price of Inaction: U.S. Faces Trillions in Economic Losses

In 2023, the United States experienced a record-breaking number of climate-related events, each causing damage exceeding one billion dollars. The cumulative impact of these events is staggering, with some individual disasters costing hundreds of billions of dollars. The frequency and severity of these events highlight the accelerating pace of climate change and the urgent need for intervention.

Projections suggest that the long-term economic costs of climate change could reach trillions of dollars for the U.S. alone. These costs stem from a range of factors, including the destruction of infrastructure, increased healthcare expenditures due to climate-related illnesses, and disruptions to agriculture and the food supply chain. Perhaps most concerning of all is the projected rise in homeowners’ insurance premiums, driven by the growing frequency of climate disasters. Short sellers predict that, within the next decade, up to 25% of U.S. properties could become uninsurable. Without significant policy changes, these costs will continue to rise, exacerbating the inflationary pressures already plaguing the U.S. economy.

A Future at Risk: The Need for Urgent Action

The economic effects of climate change go beyond financial losses—they have the potential to undermine future growth, reduce productivity, and deepen social inequalities. Proactive investments in renewable energy, climate resilience, and sustainable practices are not just necessary to protect the environment—they are also critical to safeguarding economic stability and future prosperity. Without a dramatic shift in policy direction, the U.S. risks a future where economic growth is stunted, natural disasters become the new normal, and entire communities are left to cope with the aftermath.

As a climate scientist with decades of experience developing climate models, I have seen firsthand the alarming projections of global warming. Our updated climate model, now integrating complex social-ecological factors as part of a dynamic and non-linear system, suggests that global temperatures could rise by as much as 9°C within this century. This is far beyond previous estimates of a 4°C increase over the next thousand years, and such an extreme rise in temperature would render much of the world uninhabitable within our lifetimes.

Without urgent intervention, the accelerating pace of climate change will surpass our ability to adapt, leading to widespread ecological collapse, economic destabilization, and loss of human life on a scale never before seen. The time to act is now. Climate change is not a distant threat—it is happening right now, and the choices we make today will determine whether or not future generations will inherit a livable planet.

Conclusion: A Call for Immediate Change

Donald Trump’s policies, which have ignored the science of climate change and prioritized fossil fuel extraction, have exacerbated the environmental and economic challenges facing the world. These policies, driven by ignorance and short-term profit motives, have intensified the climate crisis and undermined global efforts to transition to a more sustainable future. It is critical that we shift away from such destructive policies and invest in solutions that will not only protect our environment but also safeguard the future of the global economy. The window for action is closing, and the time for change is now.

The Persistence of Climate Change Denial: Impact and Consequences
Politicians Hinder Fight Against Climate Change
Insurance Cost and Availability

The Human Induced Climate Change Experiment

Trumpenomics: The Decline of the US