bookmark_borderThe Link Between GDP and Immigration

by Daniel Brouse
January 31, 2025

In the most recent quarter, the U.S. GDP experienced a decline, coinciding with historically low levels of immigration over the past few quarters. This is not a coincidence—there is a well-documented and direct relationship between economic growth and immigration. In modern times, immigration has accounted for approximately 80% of GDP growth, as new workers, consumers, and entrepreneurs contribute to economic expansion, productivity, and innovation.

With the current restrictive immigration policies, the U.S. economy faces a significant risk of contraction. A shrinking labor force leads to slower business growth, increased labor shortages, and reduced consumer demand—all of which hinder GDP expansion. Additionally, declining immigration reduces the number of younger workers paying into Social Security and Medicare, exacerbating long-term fiscal challenges.

If current trends continue, the economy is expected to suffer severe negative consequences, including slower growth, rising inflationary pressures due to labor shortages, and weakened global competitiveness. Addressing immigration policy is not just a social or political issue—it is an economic imperative.

ADDITIONAL RESOURCES

Economic Outlook

Trump’s Proposed Tariffs on Mexico and Canada: A Policy Analysis

Economic Facts on Immigration, Budget Deficits and Inflation

Immigration and the Wage Inflation Spiral

The True Costs (and Benefitlessness) of a Trump Economy

bookmark_borderPlanetary Solvency: Risks and Recommendations

Increasingly severe climate and nature driven impacts are highly likely, including fires, floods, heat and droughts. This is a national security issue as food, water and heat stresses will impact populations. If unchecked then mass mortality, involuntary mass migration events and severe GDP contraction are likely.

Planetary Solvency defines Catastrophic impacts as:
• Economic contraction, GDP loss of over 25%
• Mass human mortality events resulting in over 2 billion deaths
• Warming of 2°C or more, triggering high number of climate tipping points
• Breakdown of some critical ecosystem services and Earth Systems.
• Major Extinction Events in multiple geographies.
• Ocean circulation severely impacted.
• Severe socio-political fragmentation in many regions, low lying regions lost.
• Heat and water stress driving mass migration of billions.
• Catastrophic mortality events from disease, nutrition, thirst and conflict

Planetary Solvency: Risks and Recommendations

The Human Induced Climate Change Experiment

bookmark_borderHomeowners Insurance Coverage $1 Trillion Climate Change Hole

by Daniel Brouse
January 12, 2025

The “$1 trillion hole” in homeowners insurance coverage refers to the growing gap between the actual costs of damage caused by natural disasters and the insurance coverage available to homeowners. This coverage gap has emerged due to a combination of factors, many of which are exacerbated by climate change and its associated risks. Here’s a detailed explanation:

What Contributes to the $1 Trillion Hole?

  1. Increasing Frequency and Intensity of Natural Disasters:
    • Climate change has led to more frequent and severe weather events, such as hurricanes, wildfires, floods, and tornadoes. These events cause greater financial losses, outpacing the capacity of insurance systems to absorb the costs.
  2. Underinsurance by Homeowners:
    • Many homeowners are either uninsured or underinsured, meaning their policies do not provide enough coverage to rebuild or repair homes after disasters. Some may not carry specific disaster coverage (e.g., flood or earthquake insurance), leaving them vulnerable.
  3. Rising Construction Costs:
    • The costs of rebuilding homes have surged due to inflation, supply chain disruptions, labor shortages, and updated building codes. Even those with insurance may find that their policies do not fully cover these increased costs.
  4. Insurance Industry Retreat:
    • In high-risk areas, particularly those prone to wildfires (e.g., California) or hurricanes (e.g., Florida), private insurers are pulling out of the market or dramatically increasing premiums. This leaves many homeowners reliant on state-backed plans, which are often more limited in coverage and face financial strain themselves.
  5. Lack of Government Support:
    • Government disaster relief programs and state-backed insurance plans, such as California’s FAIR Plan or Florida’s Citizens Property Insurance Corporation, are not sufficient to cover the full scope of damages. These programs are financially stretched and may not be able to address future catastrophic losses.
  6. Growing Risk Awareness:
    • Advanced risk modeling and climate science have shown that many areas are significantly more vulnerable to disasters than previously thought. This has caused insurers to reassess their exposure, further limiting coverage availability and affordability.

Implications of the Gap

  • Economic Strain on Homeowners: Many homeowners face bankruptcy or foreclosure after disasters because they cannot afford repairs or rebuilds without adequate insurance.
  • Real Estate Market Instability: The lack of affordable insurance is making it harder to buy, sell, or maintain properties in high-risk areas, potentially leading to a devaluation of real estate in these regions.
  • Taxpayer Burden: When insurance coverage falls short, governments often step in to provide disaster relief, placing additional financial strain on taxpayers.
  • Widening Inequality: Wealthier homeowners may be able to self-insure or rebuild after disasters, but low- and middle-income families often bear the brunt of the gap, deepening socioeconomic disparities.

Solutions Being Proposed

  • Climate Adaptation and Resilience:
    Investments in infrastructure, updated building codes, and measures such as fireproofing or floodproofing homes are often suggested to reduce future losses. However, as climate change continues to intensify, the escalating costs of such adaptations risk becoming unsustainable. Long-term solutions must account for the reality that some areas may no longer be viable for habitation.
  • Expanded Federal Support:
    Proposals for a national disaster insurance program aim to address coverage gaps and distribute financial risk across the country. While appealing in theory, this approach also faces sustainability challenges. As climate-related disasters grow in frequency and intensity, the financial burden on federal programs and taxpayers could spiral out of control, making this solution increasingly impractical without addressing the root causes of climate change.
  • Incentives for Private Insurers:
    Offering tax breaks or subsidies to encourage private insurers to remain in high-risk markets has been proposed. However, as the cost of insuring properties in vulnerable areas continues to rise, even these measures may prove insufficient or unsustainable. Without meaningful efforts to mitigate climate risks, the financial viability of these incentives is likely to erode.
  • Increased Awareness and Education:
    Educating homeowners about their risks and the importance of comprehensive insurance is critical. However, beyond awareness, action is needed. Homeowners in high-risk areas must consider relocating to regions with lower susceptibility to climate-related disasters. Managed migration or “climate retreat” should be prioritized to ensure long-term safety and financial stability for individuals and communities alike.

The “$1 trillion hole” is a stark reminder of the systemic challenges posed by climate change and highlights the need for innovative solutions to ensure financial security for homeowners and the stability of the broader economy.


bookmark_borderA System Under Strain: The Insurance Crisis

by Daniel Brouse
January 11, 2025

California Faces Unprecedented Challenges as Los Angeles Wildfires Rage

Just days into the devastating wildfires sweeping through Los Angeles, with flames still raging uncontrollably, early damage estimates have already reached a staggering $57 billion. As these fires continue to spread, that figure is expected to climb, highlighting the intensifying toll of climate change-driven catastrophes. These fires are not just an environmental disaster but also an economic and social crisis, testing the resilience of systems designed to mitigate the impact of such events.

A System Under Strain: The Insurance Crisis

California is among several states grappling with the growing frequency and intensity of climate-related disasters. Over recent years, the financial burden on the insurance industry has escalated, driven by catastrophic wildfires, prolonged droughts, and extreme weather events. Many private insurers, unable to sustain losses or raise premiums due to state-imposed price controls, have either stopped issuing new policies or left the state entirely.

In response, California implemented government-subsidized homeowners’ insurance programs to provide coverage for those left without options. However, these systems, including the state-backed FAIR Plan, quickly became overburdened. The FAIR Plan, originally conceived as a safety net for homeowners in high-risk areas, has seen a surge in demand as private insurers retreat.

Amendments to Insurance Laws

Recognizing the unsustainability of the current system, California recently amended its insurance regulations to allow companies to charge customers for catastrophic risks. While this measure aims to stem the exodus of private insurers from the state, it has sparked concerns about affordability. Homeowners in high-risk areas may find themselves priced out of coverage altogether, leaving many vulnerable to financial ruin in the wake of disasters like the Los Angeles wildfires.

Testing the Limits of Preparedness

The Los Angeles wildfires are poised to test the sustainability of the FAIR Plan and the broader insurance framework. With record losses anticipated, the state faces a critical challenge: balancing the financial viability of insurance programs with the need to provide affordable coverage to residents. This balancing act is made even more complex by the sheer scale and frequency of disasters driven by climate change, which shows no signs of abating.

The losses that the FAIR Plan is expected to incur from the Los Angeles wildfires are likely to be substantial, potentially unprecedented. While exact figures will depend on the extent of the fires, initial damage estimates for the ongoing wildfires have already reached $57 billion. Given that the FAIR Plan serves as a safety net for high-risk areas, including many wildfire-prone regions, a significant portion of the claims resulting from these fires is expected to fall under its coverage.

Key Factors Impacting FAIR Plan Losses

  1. High-Value Properties: Los Angeles and its surrounding areas are home to many high-value properties, which significantly increases the financial burden on the FAIR Plan when destruction or damage occurs. Uniquely, the current wildfires have spread not only through brush and vegetation, as is typical, but also from house to house. This unprecedented pattern of fire spread has led to compounded damages, affecting entire neighborhoods and making the financial impact even more severe.
  2. Increased Participation: The withdrawal of private insurers from the market has left many homeowners with no option but to turn to the FAIR Plan for coverage. This surge in participation has dramatically amplified the plan’s exposure to catastrophic losses, as a growing number of high-risk properties fall under its umbrella.
  3. Severity of Wildfires: Decades of drought, coupled with strong winds and persistently dry conditions, have fueled the intensity of the ongoing wildfires, making them extremely difficult to contain. The widespread destruction has led to an unprecedented number of claims, placing significant pressure on the FAIR Plan’s financial resources.
  4. Cost of Rebuilding: The costs of rebuilding are expected to escalate due to rising construction material prices, labor shortages, and stringent building codes. Unlike traditional wildfires that primarily burn through vegetation, these fires have spread from house to house, causing extensive structural damage. Rebuilding in affected areas will likely involve significant upgrades to meet new building codes aimed at preventing similar disasters in the future, further inflating claim payouts and financial liabilities for the FAIR Plan.

Projected Financial Impact

While it is too early to provide a definitive figure, some experts anticipate that the FAIR Plan could face billions of dollars in claims from the Los Angeles wildfires. The financial strain may lead to increased premiums for policyholders, additional government subsidies, or even calls for federal assistance to stabilize the program.

Challenges Ahead

The FAIR Plan was never designed to handle catastrophic losses on this scale. As the frequency and severity of climate-driven disasters continue to escalate, the plan’s financial sustainability is at risk. This situation highlights the urgent need for systemic reform in how high-risk areas are insured and managed in the face of a changing climate.

A Broader Wake-Up Call

The Los Angeles wildfires are a stark reminder of the far-reaching consequences of climate change. Beyond the immediate devastation, they underscore the urgent need for comprehensive strategies to mitigate risk, including aggressive emissions reductions, infrastructure improvements, and disaster preparedness. Without decisive action, the costs—both financial and human—will only continue to rise.

As California battles this latest crisis, it serves as a warning to the rest of the world: climate change is not a distant threat but a present and escalating reality, demanding immediate and sustained action.

Insurance Cost and Availability Brouse (2024)

Climate Change and Insurance: The Los Angeles Wildfires Brouse (2025)

The Cost of Climate Change: Rising Homeowners Insurance Rates Brouse (2024)


bookmark_borderThe Los Angeles Wildfires: A Record-Breaking Climate Disaster

by Daniel Brouse
January 9, 2025

The Los Angeles wildfires are shaping up to be the most expensive climate disaster in history. Just days into the crisis, with most fires still raging out of control, early damage estimates have already reached a staggering $57 billion. As these fires continue to spread, that figure is expected to climb, marking a sobering milestone in the era of climate change-driven catastrophes.

Vast Areas of California: A Growing Case for Uninhabitability

Large swaths of California, particularly in fire-prone regions like Los Angeles, are increasingly becoming uninhabitable due to the rapid escalation of extreme climate events. The frequency and intensity of these events are growing at an exponential rate and could become 64 times more severe within the next decade, according to projections. This dire trend poses significant risks not only to lives and property but also to the long-term sustainability of human habitation in these areas.

Natural Disasters and Exacerbated Risks

The Los Angeles region is expected to face an escalating barrage of natural disasters, including wildfires, droughts, and flooding. As climate change accelerates, the impact of these events is compounded by human actions. For instance, during recent wildfires, millions of gallons of saltwater were dropped to extinguish flames. While effective in firefighting, this practice leaves behind a devastating legacy: salt contamination of the soil. Salt can render the land infertile for decades, severely impacting agriculture, vegetation, and ecosystems, and making it difficult for communities to rebuild sustainably.

Environmental Compromises in Rebuilding

Compounding the challenges, California has begun relaxing its environmental regulations to expedite post-fire cleanup and rebuilding efforts. While this may speed up recovery, it introduces significant risks. The clean-up processes often leave behind toxic and carcinogenic residues, creating a hazardous foundation for future development. Rebuilding homes and infrastructure on contaminated ground poses severe health risks for residents, including exposure to harmful chemicals that can persist for generations.

Economic and Human Implications

Even if financial institutions and insurers are willing to continue underwriting the costs of rebuilding in these high-risk areas, the question arises: Who would want to live there?

  • Health Risks: Prolonged exposure to toxic soil and air contaminants from fire debris can lead to long-term health issues, including respiratory problems and cancer.
  • Safety Concerns: The relentless cycle of destruction and rebuilding undermines the sense of security for residents.
  • Financial Burden: The cost of insurance and rebuilding will continue to rise, making it increasingly unaffordable for many homeowners.

The Growing Case for Managed Retreat

As the risks of inhabiting these regions continue to climb, the concept of managed retreat—relocating communities from high-risk areas to safer ones—becomes an increasingly viable option. Policymakers, urban planners, and residents must weigh the economic, environmental, and human costs of staying versus the benefits of relocating.

In the face of exponential climate risks, California must rethink its approach to land use, rebuilding policies, and disaster preparedness. Without drastic intervention and forward-thinking strategies, vast areas of the state may soon become permanently uninhabitable, leaving behind ghost towns of abandoned homes and unlivable landscapes.


Growing Risks from Combined Extreme Weather Events

The Los Angeles wildfires are an exceptionally severe example of multiple climate extremes converging to create a catastrophic event. Over the past several decades, the region has experienced a record-breaking drought that has significantly lowered the water table, leaving vegetation dry and highly flammable. This prolonged period of aridity set the stage for the rapid ignition and spread of the fires. Adding to this perilous situation, hurricane-strength winds fanned the flames, transforming a single fire into multiple rapidly spreading infernos. These winds, fueled by high-pressure systems and seasonal weather patterns, carried embers over vast distances, igniting new hotspots and making containment efforts almost impossible. The extreme winds posed an additional challenge: they were so intense that aerial firefighting efforts — a critical component of fire suppression — were rendered ineffective. Planes and helicopters, which typically drop water and fire retardants, could not operate safely, leaving firefighters on the ground to battle the blazes under incredibly dangerous conditions.

This convergence of drought, high winds, and unrelenting fire illustrates the growing intensity and complexity of climate-related disasters. It also highlights the urgent need for stronger disaster preparedness, investment in climate resilience, and policies aimed at mitigating the root causes of climate change.

California, already grappling with the escalating costs of climate-related disasters, is one of three states that have had to implement government-backed hazard insurance programs. The move was necessitated by the increasing frequency and intensity of wildfires, hurricanes, and other natural disasters. However, state-imposed regulations that limit price increases have pushed many private insurers to stop issuing new policies in the state or withdraw from the market entirely.

A Changing Insurance Landscape

To address the growing insurance crisis, California recently amended its laws, allowing insurers to charge customers for catastrophic risks. This marks a significant departure from previous regulations, which sought to shield homeowners from exorbitant premiums. While the new laws aim to retain insurance providers in the state, they come with a cost: the affordability of coverage.

For many Californians, especially those in high-risk areas, the changes mean that insurance premiums will likely skyrocket, making it difficult — if not impossible — for average homeowners to secure coverage. This leaves vulnerable populations at greater risk, particularly in areas repeatedly struck by disasters, where rebuilding without insurance becomes a monumental financial burden.

The Broader Impact of the Wildfires

The economic toll of the Los Angeles wildfires extends far beyond the immediate destruction of homes, infrastructure, and businesses:

  1. Rising Insurance Premiums: Even for those who manage to retain coverage, premiums are expected to increase sharply, adding to the already high cost of living in the state.
  2. Housing Market Instability: Expensive or unavailable insurance could drive potential buyers out of the market, leading to decreased property values and reduced housing demand.
  3. Disproportionate Burden on Low-Income Residents: The inability to afford insurance could force low- and middle-income families to abandon homes in high-risk areas, exacerbating socioeconomic disparities.
  4. Pressure on Federal and State Funds: As private insurers retreat, government-backed programs will face mounting pressure, further straining public resources.

A Call for Long-Term Solutions

As of January 2025, the acceleration of climate change impacts appears to be doubling every two years. This trend suggests that the damage caused by climate change today is twice as severe as it was just two years ago. If this trajectory continues, the damage could be four times worse in two years and eight times worse in four years. These projections are conservative, assuming the doubling interval remains stable and does not shrink further — a possibility that cannot be ruled out given the current trajectory.

Alarmingly, this rapid acceleration does not seem to be an anomaly. If it persists, the consequences could far exceed prior expectations, potentially pushing the Earth’s climate system into uncharted and catastrophic territory. Recent updates to climate models, which now integrate complex social-ecological interactions, indicate that global temperatures could rise by up to 9°C within this century — a stark departure from earlier predictions of a 4°C rise over the next thousand years.

Such an increase would have devastating impacts, including widespread ecosystem collapse, extreme weather events becoming the norm, uninhabitable regions due to heat and drought, and severe disruptions to food and water supplies. The urgency to act has never been greater, as the window to mitigate these risks continues to close rapidly.

The Los Angeles wildfires serve as yet another warning about the urgent need to address climate change and its far-reaching consequences. While policy changes may help stabilize the insurance market in the short term, they do not address the root causes of the escalating disasters. California, along with other vulnerable states, must invest in:

  • Climate Mitigation Strategies: Expanding efforts to reduce greenhouse gas emissions, adopt renewable energy, and implement sustainable land-use practices.
  • Disaster Preparedness and Resilience: Strengthening infrastructure, improving fire prevention measures, and ensuring equitable access to recovery resources.
  • Federal Support and Collaboration: Coordinating with federal agencies to develop nationwide policies that address the challenges posed by an increasingly volatile climate.

As the costs of inaction continue to rise, California’s wildfire crisis underscores the critical importance of systemic changes to reduce risk and protect communities from the growing threat of climate disasters.
Insurance Cost and Availability

The Cost of Climate Change: Rising Homeowners Insurance Rates

How is All Real Estate at Risk From Climate Change?

The Human Induced Climate Change Experiment

bookmark_borderClimate Change Superfund Act

by Daniel Brouse

New York State has enacted the Climate Change Superfund Act, a pioneering law that mandates large fossil fuel companies to contribute financially toward mitigating climate change impacts. Signed by Governor Kathy Hochul, this legislation requires major oil, gas, and coal companies to pay a total of $75 billion over 25 years, equating to $3 billion annually.

Key Provisions of the Law:

  • Financial Contributions: The law targets companies responsible for significant greenhouse gas emissions between 2000 and 2018, compelling them to fund climate adaptation and infrastructure projects across New York State.
  • Allocation of Funds: The collected funds will be utilized for projects aimed at enhancing the state’s resilience to climate-related challenges, such as flooding and extreme heat. This includes investments in transportation, water and sewage systems, and building infrastructure.
  • Implementation Timeline: Payments are scheduled to commence in 2028, with the state developing regulations to identify liable parties and assess fines in the interim.

Context and Implications:

This legislation positions New York as the second state, following Vermont, to hold fossil fuel companies financially accountable for their contributions to climate change. The law is inspired by existing superfund laws that require polluters to finance the cleanup of environmental hazards.

Proponents, including State Senator Liz Krueger, emphasize that this approach shifts the financial burden of climate adaptation from taxpayers to the corporations most responsible for environmental damage. However, industry representatives, such as the American Petroleum Institute, have criticized the legislation as punitive, and legal challenges are anticipated, with claims that the law may conflict with federal regulations.

As the state moves forward with implementing this law, it will establish specific regulations to identify responsible parties and determine the exact financial obligations of each company. The effectiveness of this legislation in addressing climate change impacts and its influence on similar initiatives in other jurisdictions will be closely monitored.

Climate Change Laws and Litigation

The Human Induced Climate Change Experiment

bookmark_borderAvian Influenza: Lessons from History and the Looming Public Health Threat

by Daniel Brouse

Bird flu, or avian influenza, has been known and circulating for over a century. The first documented outbreak in poultry was in Italy in 1878, described as a “fowl plague.” It wasn’t until the mid-20th century that the disease was recognized as being caused by influenza A viruses. Over time, the virus has evolved, becoming a significant threat to both avian and human populations.

Timeline of Significant Developments

  • 1878: The first recorded description of bird flu as a fowl plague in Italy.
  • 1955: Scientists identified the causative agent as a type A influenza virus.
  • 1997: The H5N1 strain of avian influenza caused the first known human infections in Hong Kong, marking a significant point of concern due to its potential to jump species.
  • 2000s: H5N1 outbreaks spread across Asia, Europe, and Africa, with sporadic human cases reported. Other strains like H7N9 also emerged as threats.
  • 2020s: Bird flu outbreaks, particularly of the H5N1 strain, became more widespread, impacting multiple continents and leading to significant economic and public health challenges.

Thus, avian influenza has been circulating in wild birds and domestic poultry for over 140 years, with heightened awareness and research since the late 20th century due to its zoonotic potential.

Recent Developments: Economic and Public Health Impact

By 2020, H5N1 outbreaks had spread to every continent, leading to the culling of countless chickens. In Lancaster County, Pennsylvania, alone, millions of chickens were culled in just one month. This had a profound economic impact, leading to a significant spike in the price of chicken meat and eggs. The phrase, “What about the price of eggs?” became a colloquial reference to the crisis, highlighting bird flu’s far-reaching consequences.

Zoonotic Diseases: The Same Mistake Twice

Bird flu’s potential to jump species and infect humans has long been a concern. However, recent developments show that this concern is no longer hypothetical. The virus is now spreading in a wide variety of species, including cats, mice, and other mammals. Alarmingly, there has been a noticeable increase in human hospitalizations and deaths attributed to the disease.

The world has faced a similar scenario with COVID-19, another zoonotic disease that made the jump from animals to humans. For COVID-19, governments and health organizations rapidly developed and implemented free testing, which was crucial in determining the extent of human infections and curbing its spread. Vaccinations further helped mitigate the pandemic’s impact. Yet, inexplicably, there is no systematic testing for bird flu, despite its growing threat.

The Case for Immediate Action

An effective bird flu vaccine already exists, but it has not yet been approved for widespread use. This inaction mirrors early missteps in the COVID-19 pandemic and underscores a failure to learn from past experiences. Testing and vaccination are proven strategies for controlling zoonotic diseases, yet bird flu has not received the urgent attention it demands.

The stakes are high. Without systematic testing and the deployment of vaccines, bird flu will continue to spread unchecked, increasing the risk of a global pandemic. Immediate and coordinated action is necessary to:

  1. Implement widespread testing for bird flu in both animals and humans.
  2. Expedite the approval and distribution of the bird flu vaccine.
  3. Enhance surveillance of zoonotic diseases to prevent future pandemics.

In conclusion, the lessons from COVID-19 must not be ignored. The world cannot afford to repeat the same mistakes, especially when the tools to address the threat of bird flu are already within reach. The time to act is now.

Health and Wellness

bookmark_borderHow Risk Management Turns to Crisis Management

by Daniel Brouse
December 23, 2024

I have spent my life in the study and implementation of risk management. I obtained degrees with honors and academic accolades in economics, philosophy, and logic, including becoming the youngest subscriber to the Federal Reserve’s “Beige Book,” the country’s youngest university-level statistics tutor, and an inductee into both the Pi Gamma Mu and Phi Sigma Tau honor societies. This foundation was followed by 40 years of research, development, and real-world experience in risk management.

By the 1990s, it had become clear that the greatest risk to humans is, indeed, humans. First, climate change climbed from a substantial risk to an impending crisis. By the 2000s, the aging population emerged as the leading risk to short-term economic sustainability. Today, these two risks—human-induced climate change and an aging population—have combined and evolved into an existential crisis.

This is not to say that we should give up hope or abandon ship. Quite the contrary. Acknowledging the gravity of our circumstances makes it essential to invoke a robust and effective crisis management plan. What follows is an exploration of these intertwined crises and the paths forward to mitigate them.


The Rise of Human-Induced Climate Change

Climate change represents is the most profound example of a long-ignored risk evolving into a crisis. For decades, scientists and policymakers issued warnings about rising global temperatures, extreme weather events, and the cascading effects of environmental degradation. Despite this, global emissions and deforestation rates surged, driven by short-term economic priorities and political inertia.

The impacts are now undeniable. Wildfires, hurricanes, droughts, and floods have intensified, costing lives and overwhelming economies. Infrastructure built for past climates struggles to withstand today’s conditions, let alone those of the future. Furthermore, climate change disproportionately affects vulnerable populations, exacerbating global inequities and threatening social stability.

Complex feedback loops in climate science refer to interactions between different components of the Earth’s climate system that can amplify or dampen the effects of initial changes, leading to non-linear and often unpredictable outcomes. These feedback loops play a crucial role in shaping the behavior of the climate system and can influence various climate phenomena, including temperature changes, ice melt, and precipitation patterns. Tipping points are Critical Milestones that directly impact the rate of acceleration in climate change by multiplying the number and intensity of feedback loops. Identifying and understanding these tipping points is crucial for climate science and policymaking. Crossing multiple tipping points has led to the domino effect, resulting in much more rapid and severe climate change than previously projected.

Addressing this crisis requires immediate and coordinated action:

  • Transitioning to renewable energy: Fossil fuels must be phased out in favor of sustainable alternatives.
  • Implementing adaptive infrastructure: Cities and communities need to be redesigned to withstand the challenges of a changing climate.
  • Global cooperation: International agreements like the Paris Accord must be strengthened and enforced to meet ambitious targets.
  • Reducing pollution and greenhouse gases: Fossil fuel pollution is the leading cause of death worldwide and the greatest contributor to the climate crisis. Mitigating this requires aggressive policies to limit emissions and promote cleaner technologies.


The Economic Risks of an Aging Population

Parallel to the climate crisis is the demographic challenge of aging populations, particularly in developed nations. By the 2000s, it became clear that declining birth rates and increasing life expectancy were reshaping economic landscapes. Pension systems, healthcare infrastructure, and labor markets are all under strain.

Economic growth slows as the working-age population shrinks relative to retirees. Healthcare costs soar, and governments face mounting fiscal pressures. Wealth disparities exacerbate these challenges, as those without adequate savings face severe hardship in retirement.

Key strategies to address this demographic shift include:

  • Reforming healthcare and pensions: Systems must be made more efficient and sustainable.
  • Encouraging workforce participation: Policies that enable older adults to remain in the workforce longer can help ease economic pressures.
  • Investing in education and technology: Automation and productivity-enhancing technologies can offset labor shortages.
  • Demographic Solutions: Encouraging higher birth rates or increasing immigration can help stabilize the worker-to-retiree ratio. Mass immigration is likely the only viable solution for addressing both short-term and long-term challenges.

Bridging the Crises: An Integrated Approach

The climate and demographic crises are interconnected. Climate change disproportionately affects the elderly, who are more vulnerable to heatwaves, natural disasters, and health impacts. Simultaneously, the economic strain of aging populations limits resources available for climate mitigation and adaptation.

Addressing these crises requires an integrated approach that considers both environmental and economic sustainability. Policymakers, businesses, and individuals must work together to:

  • Redesign tax systems: Taxes should incentivize sustainable practices and ensure equitable contributions from all sectors.  Ideally, taxation should focus primarily on fossil fuel combustion. Pollution from fossil fuels is the leading cause of death globally. While the cost of human life is immeasurable, the associated increase in healthcare expenses places a significant burden on the economy. Additionally, the societal costs of climate change — driven largely by fossil fuel combustion — likely represent an even greater economic and environmental challenge. Redirecting taxation in this way could incentivize cleaner energy alternatives while addressing these critical issues. A 100% tax on a barrel of oil and a 1,000% tax on a ton of coal could significantly reduce wealth inequality while simultaneously fostering a sustainable economy.
  • Reduce wealth disparities: Closing the wealth gap can enhance resilience and provide resources for climate action. Taxing fossil fuel combustion could be the single largest factor in creating a more equitable future.
  • Embrace innovation: Technologies that address both climate and economic challenges must be prioritized.

Conclusion: From Crisis to Opportunity

Acknowledging the dual crises of climate change and an aging population is not a sign of defeat but a call to action. Humanity has faced existential threats before and emerged stronger through innovation, cooperation, and resilience. By transitioning from risk management to effective crisis management, we can not only mitigate these challenges but also build a more sustainable and equitable future.

What follows are detailed papers on the sustainability of our environment and economy, including energy, taxation, debt, healthcare, and wealth disparity. These explorations aim to provide actionable insights and solutions to navigate this critical juncture in human history.

The Human Induced Climate Change Experiment

Climate Change and Insurance: Costs, Availability, and Sustainability

Balancing the Books: How Public-Private Healthcare Models Can Sustain Economic Growth

Taxation in a Changing World: Challenges, Inefficiencies, and Paths to Sustainability

Wealth Taxes Are Illogical

Economic Outlook 2025 – 2035

bookmark_borderWhy Are Rates Rising While the Federal Reserve is Cutting?

by Daniel Brouse
December 21, 2024

At first glance, it seems counterintuitive: the Federal Reserve is cutting interest rates, yet most other interest rates, particularly long-term ones, are rising. To understand this phenomenon, we need to examine the interplay of economic forces shaping the financial landscape.

A Strong Economy Fuels Rising Rates

The current U.S. economy remains robust, marked by strong employment numbers and resilient consumer spending. Wage inflation is another contributing factor, as tight labor markets push wages higher. These dynamics create upward pressure on long-term interest rates because lenders demand higher returns to compensate for the inflationary environment. Investors anticipate continued economic growth, which increases the demand for credit and drives up yields on longer-term bonds.

Long-Term Rates Reflect Uncertainty and Risk

The Federal Reserve’s interest rate cuts primarily influence short-term borrowing costs. However, long-term rates are determined by broader market forces, including expectations about inflation, fiscal policy, and economic stability. With a bleak outlook for fiscal responsibility under the next administration, markets are pricing in higher risks, leading to a rise in long-term interest rates. Concerns about rising deficits and government spending exacerbate this trend, as they fuel fears of inflation and creditworthiness.

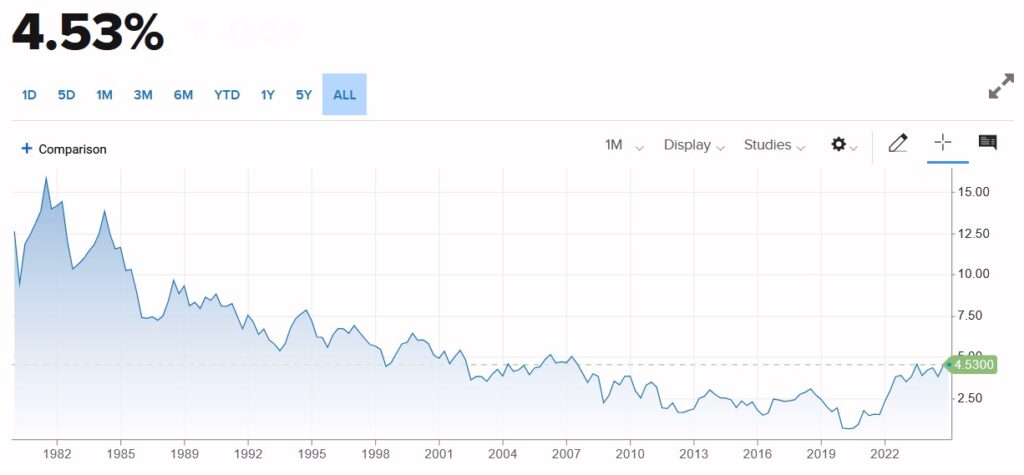
The Highest Rates Since 2007

This dynamic has pushed long-term interest rates, such as those on 10-year Treasury bonds, back to levels not seen since 2007. This rise signals a return to pre-financial-crisis conditions where borrowing costs were higher, reflecting a stronger economy but also heightened financial risks. Higher long-term rates affect mortgages, corporate loans, and consumer credit, making borrowing more expensive across the board.

A Complex Outlook

While the Federal Reserve is attempting to manage short-term economic stability through rate cuts, its actions are counterbalanced by market forces driving long-term rates upward. The disconnect highlights the complexity of today’s financial environment, where strong economic fundamentals coexist with uncertainty about the future.

The key takeaway? Rising long-term rates amidst Fed rate cuts reflect a confluence of economic strength, wage-driven inflation, and fiscal uncertainty. For businesses and consumers, this underscores the importance of cautious financial planning in a period of mixed signals and evolving risks.

10-Year Treasury Yield (2024)

Debunking Economic Myths: Misleading Narratives and the Path to Real Progress

Business and the Economy

bookmark_borderAnthony Fauci: A Case Study in Public-Private Healthcare

by Daniel Brouse
December 19, 2024

The United States arguably has one of the most advanced healthcare systems in the world, a feat achieved despite having one of the least healthy populations globally. The true challenge in improving health, economic stability, and overall well-being in the U.S. lies in individual lifestyle choices and personal responsibility. Many Americans remain undereducated about critical topics such as health, wellness, and financial management. Compounding these challenges are unhealthy habits, such as reliance on fossil fuels, consumption of processed foods, and insufficient physical activity.

Despite these obstacles, the U.S. healthcare system—a unique public-private partnership—continues to stand out. While some advocate for universal healthcare modeled after other nations, many of those systems are struggling under economic pressures. For instance, France has faced years of civil unrest driven partly by the unsustainable costs of its national healthcare system, leading to government instability. Similarly, Canada’s healthcare model is under strain, illustrated by the resignation of its finance minister and calls for the Prime Minister to step down. The UK’s National Health Service (NHS) is also plagued by long treatment delays, nationwide nursing strikes, and reports of patient deaths while awaiting care. Germany, Italy, and Greece, among others, are facing similar demise.  Even China, often viewed as an example of universal healthcare success, is grappling with economic strain from an aging population and has faced public protests over healthcare policies.

An example of the U.S. system’s strength is its response to the COVID-19 pandemic. Pfizer-BioNTech and Moderna, two companies with strong U.S. ties, developed groundbreaking mRNA vaccines with significant financial and logistical support from the U.S. government. Initiatives like Operation Warp Speed accelerated the development and distribution of COVID-19 vaccines, showcasing the efficacy of the public-private partnership. While China’s Sinopharm and Sinovac vaccines were developed earlier, they relied on traditional inactivated virus technology, whereas the U.S.-supported vaccines utilized the innovative mRNA approach, which proved more effective in preventing severe disease and death. Everybody in the U.S. was offered multiple doses of the vaccine free of charge.

Much of this success can be attributed to Dr. Anthony Fauci, who served as the director of the National Institute of Allergy and Infectious Diseases (NIAID) from 1984 to 2022. Throughout his career, Dr. Fauci spearheaded research efforts on infectious diseases like HIV/AIDS, tuberculosis, and malaria, as well as emerging threats like Zika, Ebola, and COVID-19. His leadership and expertise during the COVID-19 pandemic were instrumental in coordinating the largest public-private healthcare initiative in history, leading to the rapid development of revolutionary vaccines that saved millions of lives worldwide.

However, Dr. Fauci’s career has not been without controversy. Critics argued that his early approach to the HIV/AIDS epidemic focused too heavily on vaccine development at the expense of expanding treatment strategies. Antiretroviral therapy (ART), which suppresses the HIV virus to undetectable levels in the blood, has proven highly effective in preventing transmission—a principle summarized by the phrase “Undetectable = Untransmittable” (U=U). ART has transformed HIV from a deadly disease into a manageable condition, but the U.S. lagged behind in championing its widespread adoption during the early years of the epidemic.

Fauci’s reputation shifted dramatically during the COVID-19 pandemic. Amid widespread misinformation and political interference, particularly from then-President Trump, Dr. Fauci became a steadfast advocate for science and public health. His insistence on factual communication and his role in developing the first effective mRNA vaccines solidified his legacy. Under his leadership, Pfizer-BioNTech and Moderna developed the world’s first mRNA vaccines, which not only curbed the pandemic but also laid the groundwork for future medical innovations.

The U.S. healthcare system’s ability to respond to such crises highlights the strength of its public-private model. While individual lifestyle changes remain a critical component of improving health outcomes, the innovative and collaborative nature of the U.S. healthcare system continues to position it as a global leader in medical advancement.

Balancing the Books: How Public-Private Healthcare Models Can Sustain Economic Growth

Health and Wellness