bookmark_borderHomeowners Insurance Coverage $1 Trillion Climate Change Hole

by Daniel Brouse
January 12, 2025

The “$1 trillion hole” in homeowners insurance coverage refers to the growing gap between the actual costs of damage caused by natural disasters and the insurance coverage available to homeowners. This coverage gap has emerged due to a combination of factors, many of which are exacerbated by climate change and its associated risks. Here’s a detailed explanation:

What Contributes to the $1 Trillion Hole?

  1. Increasing Frequency and Intensity of Natural Disasters:
    • Climate change has led to more frequent and severe weather events, such as hurricanes, wildfires, floods, and tornadoes. These events cause greater financial losses, outpacing the capacity of insurance systems to absorb the costs.
  2. Underinsurance by Homeowners:
    • Many homeowners are either uninsured or underinsured, meaning their policies do not provide enough coverage to rebuild or repair homes after disasters. Some may not carry specific disaster coverage (e.g., flood or earthquake insurance), leaving them vulnerable.
  3. Rising Construction Costs:
    • The costs of rebuilding homes have surged due to inflation, supply chain disruptions, labor shortages, and updated building codes. Even those with insurance may find that their policies do not fully cover these increased costs.
  4. Insurance Industry Retreat:
    • In high-risk areas, particularly those prone to wildfires (e.g., California) or hurricanes (e.g., Florida), private insurers are pulling out of the market or dramatically increasing premiums. This leaves many homeowners reliant on state-backed plans, which are often more limited in coverage and face financial strain themselves.
  5. Lack of Government Support:
    • Government disaster relief programs and state-backed insurance plans, such as California’s FAIR Plan or Florida’s Citizens Property Insurance Corporation, are not sufficient to cover the full scope of damages. These programs are financially stretched and may not be able to address future catastrophic losses.
  6. Growing Risk Awareness:
    • Advanced risk modeling and climate science have shown that many areas are significantly more vulnerable to disasters than previously thought. This has caused insurers to reassess their exposure, further limiting coverage availability and affordability.

Implications of the Gap

  • Economic Strain on Homeowners: Many homeowners face bankruptcy or foreclosure after disasters because they cannot afford repairs or rebuilds without adequate insurance.
  • Real Estate Market Instability: The lack of affordable insurance is making it harder to buy, sell, or maintain properties in high-risk areas, potentially leading to a devaluation of real estate in these regions.
  • Taxpayer Burden: When insurance coverage falls short, governments often step in to provide disaster relief, placing additional financial strain on taxpayers.
  • Widening Inequality: Wealthier homeowners may be able to self-insure or rebuild after disasters, but low- and middle-income families often bear the brunt of the gap, deepening socioeconomic disparities.

Solutions Being Proposed

  • Climate Adaptation and Resilience:
    Investments in infrastructure, updated building codes, and measures such as fireproofing or floodproofing homes are often suggested to reduce future losses. However, as climate change continues to intensify, the escalating costs of such adaptations risk becoming unsustainable. Long-term solutions must account for the reality that some areas may no longer be viable for habitation.
  • Expanded Federal Support:
    Proposals for a national disaster insurance program aim to address coverage gaps and distribute financial risk across the country. While appealing in theory, this approach also faces sustainability challenges. As climate-related disasters grow in frequency and intensity, the financial burden on federal programs and taxpayers could spiral out of control, making this solution increasingly impractical without addressing the root causes of climate change.
  • Incentives for Private Insurers:
    Offering tax breaks or subsidies to encourage private insurers to remain in high-risk markets has been proposed. However, as the cost of insuring properties in vulnerable areas continues to rise, even these measures may prove insufficient or unsustainable. Without meaningful efforts to mitigate climate risks, the financial viability of these incentives is likely to erode.
  • Increased Awareness and Education:
    Educating homeowners about their risks and the importance of comprehensive insurance is critical. However, beyond awareness, action is needed. Homeowners in high-risk areas must consider relocating to regions with lower susceptibility to climate-related disasters. Managed migration or “climate retreat” should be prioritized to ensure long-term safety and financial stability for individuals and communities alike.

The “$1 trillion hole” is a stark reminder of the systemic challenges posed by climate change and highlights the need for innovative solutions to ensure financial security for homeowners and the stability of the broader economy.


bookmark_borderA System Under Strain: The Insurance Crisis

by Daniel Brouse
January 11, 2025

California Faces Unprecedented Challenges as Los Angeles Wildfires Rage

Just days into the devastating wildfires sweeping through Los Angeles, with flames still raging uncontrollably, early damage estimates have already reached a staggering $57 billion. As these fires continue to spread, that figure is expected to climb, highlighting the intensifying toll of climate change-driven catastrophes. These fires are not just an environmental disaster but also an economic and social crisis, testing the resilience of systems designed to mitigate the impact of such events.

A System Under Strain: The Insurance Crisis

California is among several states grappling with the growing frequency and intensity of climate-related disasters. Over recent years, the financial burden on the insurance industry has escalated, driven by catastrophic wildfires, prolonged droughts, and extreme weather events. Many private insurers, unable to sustain losses or raise premiums due to state-imposed price controls, have either stopped issuing new policies or left the state entirely.

In response, California implemented government-subsidized homeowners’ insurance programs to provide coverage for those left without options. However, these systems, including the state-backed FAIR Plan, quickly became overburdened. The FAIR Plan, originally conceived as a safety net for homeowners in high-risk areas, has seen a surge in demand as private insurers retreat.

Amendments to Insurance Laws

Recognizing the unsustainability of the current system, California recently amended its insurance regulations to allow companies to charge customers for catastrophic risks. While this measure aims to stem the exodus of private insurers from the state, it has sparked concerns about affordability. Homeowners in high-risk areas may find themselves priced out of coverage altogether, leaving many vulnerable to financial ruin in the wake of disasters like the Los Angeles wildfires.

Testing the Limits of Preparedness

The Los Angeles wildfires are poised to test the sustainability of the FAIR Plan and the broader insurance framework. With record losses anticipated, the state faces a critical challenge: balancing the financial viability of insurance programs with the need to provide affordable coverage to residents. This balancing act is made even more complex by the sheer scale and frequency of disasters driven by climate change, which shows no signs of abating.

The losses that the FAIR Plan is expected to incur from the Los Angeles wildfires are likely to be substantial, potentially unprecedented. While exact figures will depend on the extent of the fires, initial damage estimates for the ongoing wildfires have already reached $57 billion. Given that the FAIR Plan serves as a safety net for high-risk areas, including many wildfire-prone regions, a significant portion of the claims resulting from these fires is expected to fall under its coverage.

Key Factors Impacting FAIR Plan Losses

  1. High-Value Properties: Los Angeles and its surrounding areas are home to many high-value properties, which significantly increases the financial burden on the FAIR Plan when destruction or damage occurs. Uniquely, the current wildfires have spread not only through brush and vegetation, as is typical, but also from house to house. This unprecedented pattern of fire spread has led to compounded damages, affecting entire neighborhoods and making the financial impact even more severe.
  2. Increased Participation: The withdrawal of private insurers from the market has left many homeowners with no option but to turn to the FAIR Plan for coverage. This surge in participation has dramatically amplified the plan’s exposure to catastrophic losses, as a growing number of high-risk properties fall under its umbrella.
  3. Severity of Wildfires: Decades of drought, coupled with strong winds and persistently dry conditions, have fueled the intensity of the ongoing wildfires, making them extremely difficult to contain. The widespread destruction has led to an unprecedented number of claims, placing significant pressure on the FAIR Plan’s financial resources.
  4. Cost of Rebuilding: The costs of rebuilding are expected to escalate due to rising construction material prices, labor shortages, and stringent building codes. Unlike traditional wildfires that primarily burn through vegetation, these fires have spread from house to house, causing extensive structural damage. Rebuilding in affected areas will likely involve significant upgrades to meet new building codes aimed at preventing similar disasters in the future, further inflating claim payouts and financial liabilities for the FAIR Plan.

Projected Financial Impact

While it is too early to provide a definitive figure, some experts anticipate that the FAIR Plan could face billions of dollars in claims from the Los Angeles wildfires. The financial strain may lead to increased premiums for policyholders, additional government subsidies, or even calls for federal assistance to stabilize the program.

Challenges Ahead

The FAIR Plan was never designed to handle catastrophic losses on this scale. As the frequency and severity of climate-driven disasters continue to escalate, the plan’s financial sustainability is at risk. This situation highlights the urgent need for systemic reform in how high-risk areas are insured and managed in the face of a changing climate.

A Broader Wake-Up Call

The Los Angeles wildfires are a stark reminder of the far-reaching consequences of climate change. Beyond the immediate devastation, they underscore the urgent need for comprehensive strategies to mitigate risk, including aggressive emissions reductions, infrastructure improvements, and disaster preparedness. Without decisive action, the costs—both financial and human—will only continue to rise.

As California battles this latest crisis, it serves as a warning to the rest of the world: climate change is not a distant threat but a present and escalating reality, demanding immediate and sustained action.

Insurance Cost and Availability Brouse (2024)

Climate Change and Insurance: The Los Angeles Wildfires Brouse (2025)

The Cost of Climate Change: Rising Homeowners Insurance Rates Brouse (2024)


bookmark_borderThe Los Angeles Wildfires: A Record-Breaking Climate Disaster

by Daniel Brouse
January 9, 2025

The Los Angeles wildfires are shaping up to be the most expensive climate disaster in history. Just days into the crisis, with most fires still raging out of control, early damage estimates have already reached a staggering $57 billion. As these fires continue to spread, that figure is expected to climb, marking a sobering milestone in the era of climate change-driven catastrophes.

Vast Areas of California: A Growing Case for Uninhabitability

Large swaths of California, particularly in fire-prone regions like Los Angeles, are increasingly becoming uninhabitable due to the rapid escalation of extreme climate events. The frequency and intensity of these events are growing at an exponential rate and could become 64 times more severe within the next decade, according to projections. This dire trend poses significant risks not only to lives and property but also to the long-term sustainability of human habitation in these areas.

Natural Disasters and Exacerbated Risks

The Los Angeles region is expected to face an escalating barrage of natural disasters, including wildfires, droughts, and flooding. As climate change accelerates, the impact of these events is compounded by human actions. For instance, during recent wildfires, millions of gallons of saltwater were dropped to extinguish flames. While effective in firefighting, this practice leaves behind a devastating legacy: salt contamination of the soil. Salt can render the land infertile for decades, severely impacting agriculture, vegetation, and ecosystems, and making it difficult for communities to rebuild sustainably.

Environmental Compromises in Rebuilding

Compounding the challenges, California has begun relaxing its environmental regulations to expedite post-fire cleanup and rebuilding efforts. While this may speed up recovery, it introduces significant risks. The clean-up processes often leave behind toxic and carcinogenic residues, creating a hazardous foundation for future development. Rebuilding homes and infrastructure on contaminated ground poses severe health risks for residents, including exposure to harmful chemicals that can persist for generations.

Economic and Human Implications

Even if financial institutions and insurers are willing to continue underwriting the costs of rebuilding in these high-risk areas, the question arises: Who would want to live there?

  • Health Risks: Prolonged exposure to toxic soil and air contaminants from fire debris can lead to long-term health issues, including respiratory problems and cancer.
  • Safety Concerns: The relentless cycle of destruction and rebuilding undermines the sense of security for residents.
  • Financial Burden: The cost of insurance and rebuilding will continue to rise, making it increasingly unaffordable for many homeowners.

The Growing Case for Managed Retreat

As the risks of inhabiting these regions continue to climb, the concept of managed retreat—relocating communities from high-risk areas to safer ones—becomes an increasingly viable option. Policymakers, urban planners, and residents must weigh the economic, environmental, and human costs of staying versus the benefits of relocating.

In the face of exponential climate risks, California must rethink its approach to land use, rebuilding policies, and disaster preparedness. Without drastic intervention and forward-thinking strategies, vast areas of the state may soon become permanently uninhabitable, leaving behind ghost towns of abandoned homes and unlivable landscapes.


Growing Risks from Combined Extreme Weather Events

The Los Angeles wildfires are an exceptionally severe example of multiple climate extremes converging to create a catastrophic event. Over the past several decades, the region has experienced a record-breaking drought that has significantly lowered the water table, leaving vegetation dry and highly flammable. This prolonged period of aridity set the stage for the rapid ignition and spread of the fires. Adding to this perilous situation, hurricane-strength winds fanned the flames, transforming a single fire into multiple rapidly spreading infernos. These winds, fueled by high-pressure systems and seasonal weather patterns, carried embers over vast distances, igniting new hotspots and making containment efforts almost impossible. The extreme winds posed an additional challenge: they were so intense that aerial firefighting efforts — a critical component of fire suppression — were rendered ineffective. Planes and helicopters, which typically drop water and fire retardants, could not operate safely, leaving firefighters on the ground to battle the blazes under incredibly dangerous conditions.

This convergence of drought, high winds, and unrelenting fire illustrates the growing intensity and complexity of climate-related disasters. It also highlights the urgent need for stronger disaster preparedness, investment in climate resilience, and policies aimed at mitigating the root causes of climate change.

California, already grappling with the escalating costs of climate-related disasters, is one of three states that have had to implement government-backed hazard insurance programs. The move was necessitated by the increasing frequency and intensity of wildfires, hurricanes, and other natural disasters. However, state-imposed regulations that limit price increases have pushed many private insurers to stop issuing new policies in the state or withdraw from the market entirely.

A Changing Insurance Landscape

To address the growing insurance crisis, California recently amended its laws, allowing insurers to charge customers for catastrophic risks. This marks a significant departure from previous regulations, which sought to shield homeowners from exorbitant premiums. While the new laws aim to retain insurance providers in the state, they come with a cost: the affordability of coverage.

For many Californians, especially those in high-risk areas, the changes mean that insurance premiums will likely skyrocket, making it difficult — if not impossible — for average homeowners to secure coverage. This leaves vulnerable populations at greater risk, particularly in areas repeatedly struck by disasters, where rebuilding without insurance becomes a monumental financial burden.

The Broader Impact of the Wildfires

The economic toll of the Los Angeles wildfires extends far beyond the immediate destruction of homes, infrastructure, and businesses:

  1. Rising Insurance Premiums: Even for those who manage to retain coverage, premiums are expected to increase sharply, adding to the already high cost of living in the state.
  2. Housing Market Instability: Expensive or unavailable insurance could drive potential buyers out of the market, leading to decreased property values and reduced housing demand.
  3. Disproportionate Burden on Low-Income Residents: The inability to afford insurance could force low- and middle-income families to abandon homes in high-risk areas, exacerbating socioeconomic disparities.
  4. Pressure on Federal and State Funds: As private insurers retreat, government-backed programs will face mounting pressure, further straining public resources.

A Call for Long-Term Solutions

As of January 2025, the acceleration of climate change impacts appears to be doubling every two years. This trend suggests that the damage caused by climate change today is twice as severe as it was just two years ago. If this trajectory continues, the damage could be four times worse in two years and eight times worse in four years. These projections are conservative, assuming the doubling interval remains stable and does not shrink further — a possibility that cannot be ruled out given the current trajectory.

Alarmingly, this rapid acceleration does not seem to be an anomaly. If it persists, the consequences could far exceed prior expectations, potentially pushing the Earth’s climate system into uncharted and catastrophic territory. Recent updates to climate models, which now integrate complex social-ecological interactions, indicate that global temperatures could rise by up to 9°C within this century — a stark departure from earlier predictions of a 4°C rise over the next thousand years.

Such an increase would have devastating impacts, including widespread ecosystem collapse, extreme weather events becoming the norm, uninhabitable regions due to heat and drought, and severe disruptions to food and water supplies. The urgency to act has never been greater, as the window to mitigate these risks continues to close rapidly.

The Los Angeles wildfires serve as yet another warning about the urgent need to address climate change and its far-reaching consequences. While policy changes may help stabilize the insurance market in the short term, they do not address the root causes of the escalating disasters. California, along with other vulnerable states, must invest in:

  • Climate Mitigation Strategies: Expanding efforts to reduce greenhouse gas emissions, adopt renewable energy, and implement sustainable land-use practices.
  • Disaster Preparedness and Resilience: Strengthening infrastructure, improving fire prevention measures, and ensuring equitable access to recovery resources.
  • Federal Support and Collaboration: Coordinating with federal agencies to develop nationwide policies that address the challenges posed by an increasingly volatile climate.

As the costs of inaction continue to rise, California’s wildfire crisis underscores the critical importance of systemic changes to reduce risk and protect communities from the growing threat of climate disasters.

Insurance Cost and Availability

The Cost of Climate Change: Rising Homeowners Insurance Rates

How is All Real Estate at Risk From Climate Change?
The Human Induced Climate Change Experiment

bookmark_borderThe Cost of Climate Change: Rising Homeowners Insurance Rates

The average annual homeowners insurance premium for a $300,000 house varies widely by state, driven by factors like natural disaster risks, repair costs, and location-specific risks. For example, in states with frequent hurricanes, like Florida, the average premium is exceptionally high, around $10,996. In contrast, Idaho has a more affordable rate, at around $1,636, while Pennsylvania averages closer to $1,306. Other states with high premiums include Louisiana at $6,354 and Mississippi at $4,312.

These rates also reflect a significant trend of rising costs, largely due to inflation, increased construction expenses, and more frequent severe weather events. The national average is currently around $2,377, but premiums vary depending on additional factors such as home age, proximity to a fire station, and local building costs.


Here’s a list of average annual homeowners insurance premiums for a $300,000 house across each U.S. state:

State Average Premium ($)
Alabama $3,939
Alaska $1,116
Arizona $1,961
Arkansas $3,368
California $1,782
Colorado $4,072
Connecticut $1,764
Delaware $1,207
Florida $10,996
Georgia $2,426
Hawaii $1,150
Idaho $1,636
Illinois $2,050
Indiana $1,866
Iowa $2,120
Kansas $3,437
Kentucky $2,476
Louisiana $6,354
Maine $1,322
Maryland $1,670
Massachusetts $1,863
Michigan $1,840
Minnesota $2,332
Mississippi $4,312
Missouri $2,706
Montana $1,778
Nebraska $3,962
Nevada $1,224
New Hampshire $1,225
New Jersey $1,267
New Mexico $3,362
New York $2,257
North Carolina $2,110
North Dakota $2,519
Ohio $1,342
Oklahoma $5,444
Oregon $1,232
Pennsylvania $1,306
Rhode Island $2,036
South Carolina $3,082
South Dakota $2,562
Tennessee $2,470
Texas $2,621
Utah $1,034
Vermont $1,001
Virginia $1,091
Washington $1,055
West Virginia $1,150
Wisconsin $1,244
Wyoming $1,449

These values reflect the high variability in rates, with states like Florida and Louisiana seeing particularly high premiums due to frequent hurricanes, while states like Vermont and Utah have relatively lower rates due to fewer natural disaster risks.


Why are California’s rates relatively low given the high number of climate disasters?  California, Louisiana, and Florida have state subsidized property insurance which impacts the price.  California’s relatively lower average homeowners insurance rate, despite frequent wildfires and some insurers leaving the market, is due to a mix of state regulations, subsidies, and specific factors affecting the insurance market.

  1. Regulatory Controls on Rates: California’s Department of Insurance tightly regulates rate increases and approval processes. Insurers need state approval to raise premiums, which limits how much they can adjust rates based on risk factors like wildfires. This results in rates that don’t fully reflect the increasing risk of wildfires​.
  2. California FAIR Plan: For homeowners who can’t get standard insurance coverage due to wildfire risk, California offers the FAIR (Fair Access to Insurance Requirements) Plan. This high-risk insurance pool helps maintain some level of coverage in fire-prone areas, though it often comes at a higher cost and covers only basic needs. However, it provides a safety net, reducing pressure on average premiums by ensuring high-risk properties are not covered by standard policies​.
  3. Market Exit and Coverage Caps: Major insurers like State Farm and Allstate have indeed stopped issuing new policies in some high-risk areas, and other insurers are limiting coverage. However, this shift is recent, so current averages may not yet fully reflect the changes. Over time, as these limitations impact more homeowners, average premiums could increase or force more people into the FAIR Plan, which may be more expensive​.
  4. Risk Assessment and Geographic Variation: Not all areas in California are equally affected by wildfires. Coastal and urban areas have a lower risk compared to rural and mountainous regions. Since insurance premiums are partially based on location, areas with lower risk dilute the statewide average rate, making it appear relatively lower than what might be expected given the high-profile wildfire damage in certain parts​.

While California’s wildfire risk is high, average insurance rates appear relatively low due to strict regulations on private insurers and the exclusion of high-risk, state-subsidized policies from these averages.This approach may be unsustainable, and rapid changes are likely—either through significantly rising premiums or reduced access to private insurance as more companies withdraw from the state.

CONCLUSION

All of these rates are expected to rise by 25% annually for the foreseeable future, driven by factors such as increased natural disasters, inflation, and higher repair and construction costs. In addition, up to 50% of U.S. properties could face challenges in securing private homeowners insurance, particularly in high-risk areas. States most vulnerable to an insurance market collapse due to escalating premiums and insurer withdrawals include Florida, Louisiana, Mississippi, Georgia, Oklahoma, Texas, Arizona, Arkansas, Alabama, New Mexico, Nevada, Colorado, California, and Washington. As natural disasters like wildfires, hurricanes, and flooding become more frequent and severe, these states are increasingly at risk of a market breakdown, which could leave homeowners with limited or unaffordable coverage options​.

THE FUTURE
Florida’s homeowners insurance market has effectively become socialized, with taxpayers increasingly bearing the financial burden. Due to severe weather risks and skyrocketing claim costs, many private insurers have pulled out of the state or raised premiums to unaffordable levels. In response, Florida has had to expand state-run insurance programs, such as Citizens Property Insurance Corporation, which was originally meant as a last-resort insurer but is now one of the largest insurers in the state. As a result, when large-scale disasters occur, taxpayers often end up covering the costs, either through increased assessments or state funding support. Without major reform or federal intervention, Florida’s insurance market could face even greater instability, pushing more costs onto taxpayers.

Regarding climate change education, while a majority of U.S. parents and teachers support it, Florida’s restrictive standards limit teachers’ ability to address human-related climate impacts without risking conflicts with official guidelines or community pushback. Yet, the evidence of climate change is undeniable in Florida, which faces a heightened risk of severe environmental impacts. Rising sea levels threaten Florida’s extensive coastline, leading to more frequent “sunny day” flooding in areas like Miami and the Keys. Additionally, warming ocean temperatures are fueling stronger, more frequent hurricanes that intensify faster and bring heavier rainfall, as seen in recent hurricanes like Ian and Michael.

In Arkansas, the stance is mixed: the state shows minimal official support for policies addressing human-caused climate change and does not prioritize it as an urgent issue. Discussions around emissions reduction or clean energy transition are limited compared to other states. However, Arkansas is increasingly affected by climate change, evident in more frequent intense rainfall, flooding, and rising temperatures, which are altering agricultural cycles and stressing water resources essential to the state’s economy.

The Human Induced Climate Change Experiment

bookmark_borderClimate Change Wildfires

by Daniel Brouse and Sidd Mukherjee

About the 2023 wildfires in Hawaii, Governor Josh Green said, “For perspective, we’ve had six fire emergencies this August, we had six fire emergencies between 1953 and 2003. That’s how- how fast things are changing. I know that there is debate out there whether we should be talking about climate change or not. Well, let’s be real world, climate change is here we are in the midst of it with a hotter planet, and fiercer storms.”

Climate change is contributing to the increased intensity and frequency of wildfires through a combination of factors that create favorable conditions for wildfires to ignite, spread, and become more destructive. Here are some key ways in which climate change influences wildfires:

  1. Higher Temperatures:
    • Impact: Rising global temperatures increase the likelihood of extreme heat events.
    • Effect on Wildfires: Higher temperatures contribute to drier conditions, leading to increased evaporation and moisture loss from vegetation. Dry and hot conditions provide a more conducive environment for wildfires to ignite and spread.
  2. Drought Conditions:
    • Impact: Changes in precipitation patterns and prolonged droughts are linked to climate change.
    • Effect on Wildfires: Drought conditions result in dry vegetation, making it more susceptible to ignition. Reduced soil moisture levels also contribute to the flammability of ecosystems.
  3. Changing Rainfall Patterns:
    • Impact: Climate change alters regional rainfall patterns, leading to more intense rainfall in some areas and prolonged dry spells in others.
    • Effect on Wildfires: Areas experiencing reduced rainfall may face prolonged dry seasons, creating conditions favorable for wildfires. Intense rainfall in certain regions can lead to the growth of vegetation, which later dries out and becomes potential fuel for fires.
  4. Warming Winters:
    • Impact: Warmer winter temperatures can affect snowpack and contribute to earlier snowmelt.
    • Effect on Wildfires: Reduced snowpack and earlier snowmelt can result in drier soil and vegetation earlier in the year, extending the wildfire season and increasing the period of vulnerability to fire ignition.
  5. Extended Fire Season:
    • Impact: Changes in climate contribute to longer and more intense fire seasons.
    • Effect on Wildfires: A longer fire season means that conditions conducive to wildfires persist for a more extended period, increasing the likelihood of ignition and the potential for wildfires to become larger and more destructive.
  6. Insect Infestations:
    • Impact: Warmer temperatures allow for the proliferation of certain insects, such as bark beetles.
    • Effect on Wildfires: Insect-infested trees become more susceptible to disease and wildfire. Dead and dry trees contribute to the fuel load, increasing the intensity and spread of wildfires.
  7. Wind Patterns:
    • Impact: Changes in climate can influence wind patterns.
    • Effect on Wildfires: Changes in wind patterns can contribute to the rapid spread of wildfires. Strong winds can carry embers over long distances, leading to the ignition of new areas.
  8. Thawing Permafrost:
    • Impact: Warming temperatures contribute to the thawing of permafrost.
    • Effect on Wildfires: Thawing permafrost releases stored carbon, creating flammable conditions. It can also lead to changes in vegetation types, altering fuel availability for wildfires.

The combination of these factors creates a feedback loops, where more intense and frequent wildfires release large amounts of carbon dioxide into the atmosphere, contributing to further climate change. This cycle reinforces the importance of addressing both the causes and consequences of climate change to mitigate the impact on wildfire risk. While the beautiful sunsets during forest fires create captivating visuals, it’s essential to recognize the environmental and health impacts associated with wildfires. Wildfires can cause significant damage to ecosystems, contribute to air pollution, and pose risks to human health. The mesmerizing sunsets are a visible reminder of the interconnectedness of atmospheric processes and the far-reaching effects of natural events like wildfires.

In addition to the carbon feedback loop (the carbon emissions of Canada’s fires outweighed the combined emissions from its oil and gas, transport and agriculture sectors), the fires also cause the melting of the permafrost and zombie fires to burn in the permafrost. The permafrost collapse is a self-sustaining feedback loop/tipping point. As the permafrost melts, the peatlands emit CO2 and methane. The increase in CO2 and methane results in more warming that results in more peatland emissions. A third feedback loop is created with lightning strikes. The study Forests at Risk Due to Lightning Fires found a sensitivity of extratropical intact forests to potential increases in lightning fires, which would have far-reaching consequences for terrestrial carbon storage and biodiversity. The results show that, on a global scale, lightning is the primary ignition source of fires in temperate and boreal forests. Global warming causes more extreme weather events and conditions for lightning creating more forest fires that create more warming and more lightning strikes.

The study Wildfire as a major driver of recent permafrost thaw in boreal peatlands published in the Journal Nature Communications found wildfires have caused a quarter of permafrost thaw (2,000 square kilometres) in Western Canada’s boreal peatlands over the past 30 years. “Historically, permafrost in this area underwent a natural cycle of thawing and reforming, but given current climate conditions and projections for the future, this fire-induced thaw appears to be irreversible,” said Carolyn Gibson, who conducted the research.

On January 1, 2024, the article, Why Are Alaska’s Rivers Turning Orange?, was published in Scientific America. “Streams in Alaska are turning orange with iron and sulfuric acid. Scientists who have studied these rusting rivers agree that the ultimate cause is climate change. Kobuk Valley National Park has warmed by 2.4 degrees Celsius (4.32 degrees Fahrenheit) since 2006 and could get another 10.2 degrees C hotter by 2100, a greater increase than projected for any other national park. The heat may already have begun to thaw 40 percent of the park’s permafrost, the layer of earth just under the topsoil that normally remains frozen year-round. McPhee wanted to protect the Salmon River because humans had ‘not yet begun to change it.’ Now, less than 50 years later, we have done just that. The last great wilderness in America, which by law is supposed to be ‘untrammeled by man,’ is being trammeled from afar by our global emissions.”

NASA reported: Wildland fire experts have described Canada’s 2023 fire season as record-breaking and shocking. Over the course of a fire season that started early and ended late, blazes have burned an estimated 18.4 million hectares. Hundreds of fires exceeded 10,000 hectares (39 square miles), large enough to be considered “megafires.” These megafires were also unusually widespread this season, charring forests from British Columbia and Alberta in the west to Quebec and the Atlantic provinces in the east to the Northwest Territories and the Yukon in the north.

Though the rate of change in climate disasters’ intensity, duration, and likelihood vary according to the type of extreme weather, a “rule-of-thumb” can be derived from the Canada wildfires of 2023. The World Weather Attribution Organization found, “Climate change made the cumulative severity of Quebec’s 2023 fire season to the end of July around 50% more intense, and seasons of this severity at least seven times more likely to occur.”

50% more intense
7 x more likely

Sidd said, “Do you remember back in the early 2000’s when we thought we wouldn’t live to see the extreme changes due to global warming?”

Daniel replied, “I think 2023 is the most significant year so far. We saw confirmation of tipping points being crossed for Mountain Glacier Loss, Greenland Ice Sheet Collapse, Antarctic Ice Sheet Collapse, and potentially the Collapse of AMOC.”

Sidd continued, “We already knew that. It was Canada catching on fire that I could not believe. I never thought I’d live to see the day.”

Daniel asked, “Do you think the permafrost and peatlands will have zombie fires and cause the permafrost tipping point?”

Sidd responded, “Yes. They are gone, too. We already know from the permafrost peatland fires in Siberia.”

Daniel ponders, “Hmmmm… I guess that means my plan went up in smoke? My worst case scenario / last resort emergency plan was to escape to Canada.”

ALSO SEE:
How is All Real Estate at Risk From Climate Change? Brouse and Mukherjee (2024)
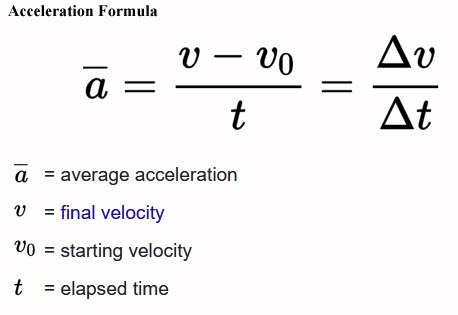
The Long-term Breathing Experiment / Brouse (2023)
Health Impacts of Air Pollution / Brouse (2023)
Climate Change: Rate of Acceleration / Brouse and Mukherjee (2023)
Toppled Tipping Points: The Domino Effect / Brouse and Mukherjee (2023)
Tree Extinction Due to Human Induced Environmental Stress / Mukherjee and Brouse (2005)
Soil Degradation and Desertification / Brouse (2024)
Create a Climate-Resilient Environment in and Around Your Home / Brouse (2024)


bookmark_borderHow is All Real Estate at Risk From Climate Change?

By Daniel Brouse and Sidd Mukherjee

Climate change poses risks to real estate in the United States in various ways, and these risks can affect property values, insurance costs, and overall property resilience. Here are some ways in which all US real estate is at risk from climate change:

  1. Sea Level Rise and Coastal Properties:
    • Coastal properties are particularly vulnerable to sea level rise, storm surges, and coastal erosion. As sea levels continue to rise due to global warming, properties near coastlines may experience increased flooding and damage from more frequent and severe storms. Storm surges in Florida are an example.
  2. Extreme Weather Events:
    • Climate change is contributing to an increase in the frequency and intensity of extreme weather events, such as hurricanes, wildfires, floods, and droughts. Properties in regions prone to these events are at risk of damage, destruction, and increased insurance costs.
  3. Temperature Extremes:
    • Rising temperatures can lead to more frequent and prolonged heatwaves, affecting property infrastructure, energy demand, and potentially decreasing property values in areas with extreme heat.
  4. Changes in Precipitation Patterns:
    • Changes in precipitation patterns, including increased violent rainfall or prolonged droughts, can impact properties by causing flooding, landslides, or water scarcity. These changes may affect property values and increase maintenance costs.
  5. Wildfires:
    • Increased temperatures and changing precipitation patterns contribute to the risk of wildfires. Properties in wildfire-prone areas face threats to both their physical structures and the surrounding environment.
  6. Homeowners and Flood Insurance Costs:
    • Flood insurance will become expensive and difficult to obtain. Climate-related risks can lead to higher insurance premiums and deductibles, particularly in high-risk areas. As the frequency and severity of climate-related events increase, insurance companies may reassess risk models and adjust pricing accordingly.
  7. Infrastructure Vulnerability:
    • Climate change can impact infrastructure such as roads, bridges, and utilities. Properties relying on vulnerable infrastructure may face challenges related to accessibility, reliability, and potential increases in repair and maintenance costs.
  8. Health Risks:
    • Humans will experience greater loss and damage to life and quality of life from air pollution, decreasing supply of potable water, extreme weather events, and disease. The greatest short term climate change risk to human health is deadly humid heat (wet-bulb temperature). Climate change can affect human health, and properties in areas prone to heatwaves, air pollution, or vector-borne diseases may face increased health risks. This could influence property values and community desirability.Almost all survivors of climate-related disasters suffer from mental distress. Of those who have not experienced climate disasters, more than two-thirds of U.S. adults (68%) have reported climate change anxiety.
  9. Regulatory Changes:
    • Governments may implement stricter building codes, zoning regulations, and disclosure requirements related to climate-related risks. Non-compliance could affect property values and lead to increased costs for property owners. Loss and damage litigation against oil companies and governments will change world economics.
  10. Shifts in Property Demand:

It’s important to note that the degree of risk varies by region and property type. Some areas may experience more immediate and severe impacts, while others may be more resilient. Assessing and mitigating these risks require a comprehensive understanding of local climate vulnerabilities and the implementation of strategies to enhance property resilience. Policymakers, real estate professionals, and property owners are increasingly recognizing the importance of addressing climate risks to ensure the long-term sustainability and value of real estate assets. Thus, our recommendation to evacuate Florida now (i.e. Managed Retreat).

Create a Climate-Resilient Environment in and Around Your Home Brouse (2024)

Managed Retreat: Relocating Due to Climate Change Extreme Weather Events Brouse (2023)

Stormwater Runoff Management for Your House Brouse (2024)

Tree Extinction Due to Human Induced Environmental Stress Mukherjee and Brouse (2005-present)

Soil Degradation and Desertification Brouse (2024)

Atmospheric Rivers Mukherjee and Brouse (2022-2023)

Violent Rain and the Substrate Brouse and Laden (2024)

The Long-term Breathing Experiment Brouse (2023)

Health Impacts of Air Pollution Brouse (2023)

Plymouth Meeting, Pennsylvania and the Substrate Daniel Brouse (2023)

Real Estate Underwater: A Florida Climate Change Case Study Daniel Brouse (2023)

Climate Change Impacts on Flood Risks and Real Estate Values Sidd Mukherjee and Daniel Brouse (2023)

Real Estate and Climate Change: Stranded on an Island Daniel Brouse (2023)

Tipping Cascades, Social-Ecological Systems, and the Hottest Year in History Brouse (2024)

All About Flood Insurance Brouse and Mukherjee (1995-present)

The Age of Loss and Damage Brouse (2023)

bookmark_borderCalifornia Homeowners Insurance Consider Climate Change Prices

California use to only allow a max of 7% increase a year on homeowners insurance… and only base premiums on past payouts on a property. Not anymore.

“California will let insurance companies consider climate change when setting their prices, the state’s chief regulator announced Thursday, a move aimed at preventing insurers from fleeing the state over fears of massive losses from wildfires and other natural disasters. The rule change could mean higher rates for homeowners who are already seeing dramatic increases. Eight insurance companies doing business in California have requested rate increases of at least 20% or higher this year, according to the California Department of Insurance,” AP news reported.

“Modernizing our insurance market is not going to be easy or happen overnight. We are in really unchartered territory and we must make difficult choices when the world is changing rapidly.” California Insurance Commissioner Ricardo Lara said.

“Insurers have advanced a very powerful argument that the past is not as good a predictor of the future as it used to be,” said Amy Bach, executive director of United Policyholders. “I think the (Insurance) department did what it needed to do to try to restore a viable market. We don’t have a viable market right now in this state in a lot of areas.”

Florida and Louisiana already have a homeowners insurance crisis with companies fleeing the states. The 9th National Risk Assessment for Homeowners Insurance found 1/4 of all homes in the nation are underpriced for climate risk insurance.

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderClimate Change: Insurance Risk

The 9th National Risk Assessment for Homeowners Insurance found climate risks place 39 million U.S. homes at risk of losing their insurance. “Sound pricing is going to make it unaffordable to live in certain places as climate impacts emerge.”

“There’s this climate insurance bubble out there,” said Jeremy Porter, the head of climate implications at First Street and a contributor to the report. “And you can quantify it.”

“There’s no education to the public of what’s going on and where the risk is,” said Porter, explaining that most insurance models are proprietary. Even the Federal Emergency Management Agency (FEMA) doesn’t make flood insurance pricing available to the public. Homeowners must obtain coverage through a private insurance broker for a quote.

Wildfires are the fastest growing natural disaster risk. According to the report, “It’s not just wildfires – pressure on flood and wind insurance is increasing, too.”

Porter went on to say, “You don’t want someone to live in a place that always burns. They don”t belong there. We’re subsidizing people to live in harm’s way. Large numbers of people will need to be relocated away from areas that will be uninsurable. There is a reckoning on the horizon and it’s not pretty.”

Flow Speeds

The burning of fossil fuels and other human released emissions have impacted momentum’s impact. A warmer atmosphere can hold more moisture. Warmer air allows for the creation of more massive raindrops. Warmer ocean temperatures create stronger hurricanes. Hail and tornadoes form in strong thunderstorm clouds with intense updrafts, high liquid-water content, and large water droplets.

Sidd added: It’s worse than that. Wind and water flow forces scale as the square of velocity, so as flow speeds increase (say due to more intense heating or heavier rain) the damage scales as the square of the velocity.

So a twenty mile an hour wind exerts four times as much force as a ten mile an hour wind. And a forty mile an hour wind exerts sixteen times as much force as a ten mile an hour wind. A wind of fifty miles an hour exerts twenty five times and a wind of sixty miles an hour exerts thirty six times as much force as one of ten miles an hour. Then you have the density term. Water is about eight hundred times denser than air, So the force exerted by a ten mile an hour flow of water is eight hundred times that of a ten mile an hour wind. So as flow velocities go up due to climate change, force and damage scale as square of the velocities. What is not clear is how much these velocities increase with climate change. But in a sense we are seeing this already as, for example, flood and sewage systems succumb and hillsides fall down, and so on.

Climate change’s influence on wind and water flow forces caused more severe damage and deaths. The Maui wildfire of August 2023 is an example. What would have been a fairly routine wildfire was fanned out-of-control by hurricane force winds. One headline read, “Maui fires: Hawaii blazes fanned by Hurricane Dora”. Another headline read, “Hawaii wildfires kill as ‘apocalypse’ hits Maui island”. The New York Times reported, “Gov. Josh Green of Hawaii said on Thursday that the devastating wildfires that swept through western Maui and killed at least 55 people, and possibly many more, were ‘likely the largest natural disaster in Hawaii state history.'”

Both wind and water flow forces contributed to the devastation. Hurricane Dora was at least 500 miles from Hawaii yet the wind forces impacted the fire in Maui. The winds were so strong that before the fire reached Lahaina extremely hot air blew over the town. The streets were so hot they burnt people’s feet trying to flee. The surface of everything became hot. Even after people jumped into the ocean, they said the debris in the water was too hot to float on. Almost all the boats in the harbor burned.

The blast of hot air over Lahaina created the conditions for a flashpoint. A flashpoint is the temperature at which a particular organic compound gives off sufficient vapor to ignite in air. The entire town ignited so quickly that warning sirens could not be activated and people did not have time to escape.

In an unexpected twist, water flow forces also contributed to the chaos. How could water flow add to the fire emergency conditions? When people fled the heat and fire, they jumped into the sea. ABC news reported: Shawn Dougherty, of Lahaina, was among the hundreds of residents forced to flee the resort city when the wildfire began engulfing their homes.

Like others, Dougherty said his only means of survival was to jump into the ocean with his girlfriend, but while some found safety in nearby jetties, the rocks and coral tore up Dougherty’s body.

“At one point, it seemed like I might drown,” he told ABC News. “{I’m a good swimmer, but the water was just really rough because of the wind and the turbulence.”

Norway Floods 2023

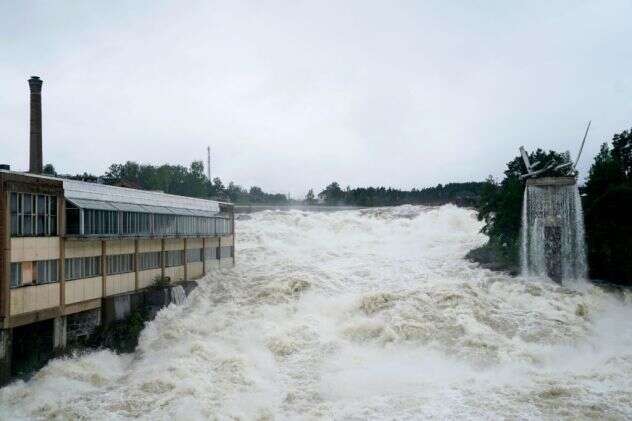
Also in August of 2023, climate change’s influence on water flow forces caused more severe damage and deaths. AccuWeather reported, “Dam bursts open as deadly flooding washes away homes in Norway. Torrents of water gushed through multiple towns across Norway and landslides cascaded down mountainsides after a deluge drenched Norway.”

Summary

By increasing the energy in the system, humans have increased flow volumes, masses and velocities leading to increased damage (and deaths.)

Newton’s second law: F = m * a
F = force
m = mass of an object
a = acceleration

Acceleration Formula

ALSO SEE
Climate Change: Rate of Acceleration
By 2020, there was enough data to see the “doubling period” of some anthropogenic climate affects had gone from 100 years to 10 years. For instance the rate of sea level rise has gone from about 1.5 millimeters per year to over 3 millimeters. We expect to see the doubling period to continue to shrink raising the possibility of sea levels rising a foot/year by 2050.

Tipping points and feedback loops are parts of an equation that determine the rate of acceleration in climate change.

Climate Change: The End of Times

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderInsurance, and the Lack Thereof

The Washington Post reported, “Home insurers cut natural disasters from policies as climate risks grow“.

“Allstate, American Family, Nationwide, Erie Insurance Group and Berkshire Hathaway — have told regulators that extreme weather patterns caused by climate change have led them to stop writing coverages in some regions, exclude protections from various weather events and raise monthly premiums and deductibles.”

“they will cut out damage caused by hurricanes, wind and hail from policies underwriting property along coastlines and in wildfire country”

“places once considered safe from natural catastrophes could lose crucial insurance protections while their natural disaster exposure expands or intensifies ”

“Allstate said its climate risk mitigation strategy would include “limiting new [auto and property] business … in areas most exposed to hurricanes” and “implementing tropical cyclone and/or wind/hail deductibles or exclusions where appropriate.””

“Nationwide said it no longer underwrites coverage for “properties within a certain distance to the coastline” because of hurricane potential.”

“There’s no place to hide from these severe natural disasters”

“a policy in a region afflicted by hurricanes may exclude coverage for wind or hail damage, or in wildfire country, a policy without fire and smoke protection.”

“Activity has been observed in recent years that has differed from historical norms or modeled expectations.”

More articles on Flood Insurance, Rising Sea Levels and Global Warming.