On August 21, 2026, President Donald Trump announced a temporary 90-day waiver of out-of-quota tariffs on imported ground beef, allowing up to 300,000 metric tons to enter the U.S. market tariff-free in an effort to reduce grocery prices. The president said he had secured a commitment that the imported meat would be sold at 25% below current market prices, providing relief from persistent food inflation.
The move is intended to address a dramatic increase in the cost of ground beef, which has risen roughly 57% over the past five years. But the policy immediately drew backlash from domestic cattle ranchers and rural-state Republicans, including Senator Tim Sheehy, who warned that flooding the market with cheaper foreign beef could undermine American cattle producers.
There is another problem that may be even more important to consumers: much of the imported beef affected by the policy is frozen beef destined for commercial and restaurant use, rather than the fresh ground beef consumers typically purchase at the grocery store. That means the immediate impact on household grocery bills may be considerably smaller than the headline numbers suggest.
More importantly, the tariff waiver does little to address the underlying forces driving higher beef prices.
Climate Change Is Becoming an Inflation Problem
The cattle industry is increasingly exposed to the economic consequences of climate extremes. Drought, extreme heat, wildfires, water scarcity, degraded pasture, and volatile feed supplies all increase the cost of raising cattle. When these pressures become severe enough, ranchers may be forced to reduce their herds, further constraining beef supplies and pushing prices higher.
This creates a feedback loop. Climate extremes increase production costs and reduce the supply of cattle. Reduced supply raises beef prices. Higher prices then encourage producers to rebuild their herds, but rebuilding takes years. Another drought or extreme-weather event during that process can once again force herd reductions.
This is why simply importing cheaper beef may treat the symptom without addressing the disease.
The larger economic issue is what I call climate inflation: the gradual—and increasingly rapid—incorporation of climate-related costs into the prices of food, energy, insurance, housing, transportation, and other necessities.
For the past several years, inflation discussions have focused primarily on monetary policy, supply chains, labor costs, tariffs, and government spending. Those factors certainly matter. But climate-driven disruptions are becoming an increasingly important component of the cost structure of the economy.
And unlike a temporary tariff or a change in interest rates, climate pressures can compound over time.
The Beef Problem Is Bigger Than Beef
A 90-day tariff waiver may provide some temporary relief. It may even benefit restaurants and commercial food purchasers if imported frozen beef reaches the market at substantially lower prices.
But it does not create more water, restore drought-stricken grazing land, prevent wildfires, reduce extreme heat, or rebuild cattle herds that have been lost to climate-driven conditions.
Nor does it address the increasingly expensive insurance, infrastructure, agricultural, and supply-chain consequences of a changing climate.
If climate extremes continue to intensify, we should expect more of these conflicts. Policymakers will repeatedly face the same choice: temporarily suppress prices by opening markets to cheaper imports, or address the underlying conditions that are making domestic production increasingly expensive.
Where’s the beef?
It may increasingly be somewhere else.
And that is the larger warning. Climate change is no longer simply an environmental issue. It is becoming an economic variable—and climate inflation may prove to be one of the most consequential economic developments of the next decade.
The U.S. Department of the Treasury intervened on August 19, 2026, announcing that it will at least double the size of its liquidity-support bond buyback operations in an effort to calm a highly volatile Treasury market.
Under the direction of Treasury Secretary Scott Bessent, the maximum repurchase limits for longer-dated nominal coupon securities will increase from $2 billion to at least $4 billion per operation. The larger limits, covering the 10- to 20-year and 20- to 30-year sectors, are scheduled to take effect September 9 and remain in place through November 4, 2026.
The intervention followed a prolonged “buyers’ strike” in the Treasury market that pushed the 30-year Treasury yield to approximately 5.34%—its highest level since 2007. Concerns surrounding persistent inflation, the prospect of war with Iran, heavy borrowing by the artificial-intelligence sector, and the U.S. national debt surpassing the $40 trillion threshold have contributed to growing pressure on longer-term government bonds.
The Treasury announcement produced an immediate market response. Bond prices rallied, while the 30-year Treasury yield fell by nearly 10 basis points to approximately 5.19%. Major Wall Street stock indexes also rebounded as investors responded to the prospect of increased liquidity and stability in the Treasury market.
A Troubling Signal
While Treasury describes the expanded buybacks as a liquidity-support measure, the intervention raises a broader question: How much government intervention should occur in what is supposed to be a private, market-driven financial system?
The Treasury market is the foundation of the U.S. financial system. When the government becomes an increasingly active participant in supporting the market for its own debt, it can create the perception that market forces are no longer being allowed to fully determine the price of that debt.
That is concerning not only for investors, but also for citizen-taxpayers. Ultimately, the federal government is supporting a debt market built upon obligations that taxpayers are responsible for financing.
The market’s reaction is therefore significant. The immediate rally may provide short-term relief, but the underlying pressures— inflation, enormous federal borrowing, rising interest costs, geopolitical risk, and declining demand for long-term Treasury securities—remain.
Government intervention may calm the market temporarily. It does not eliminate the underlying risks.
When the government has to step into its own debt market to provide liquidity, the intervention itself becomes a market signal—and the bond market has reacted accordingly.
UPDATE
After I wrote the bond article, Scott Bessent appeared live on CNBC for an interview. He doubled down on the Treasury’s intervention in the bond market, apparently because the market did not react strongly enough to his initial announcement. He emphasized that $4 billion per operation is now the minimum baseline for Treasury buybacks.
The good news? The Treasury doesn’t have that much money available to keep buying back bonds.
While Sidd was in town, I took some notes. Somehow, they turned into this:
Climate Change: The Big Picture
There are many ways to look at climate change. From a micro perspective, there are millions of individual feedbacks operating throughout the Earth system. From a macro perspective, there is the climate system as a whole.
Understanding how those feedbacks interact—and, more importantly, how they feed back into one another—is at the bleeding edge of climate science.
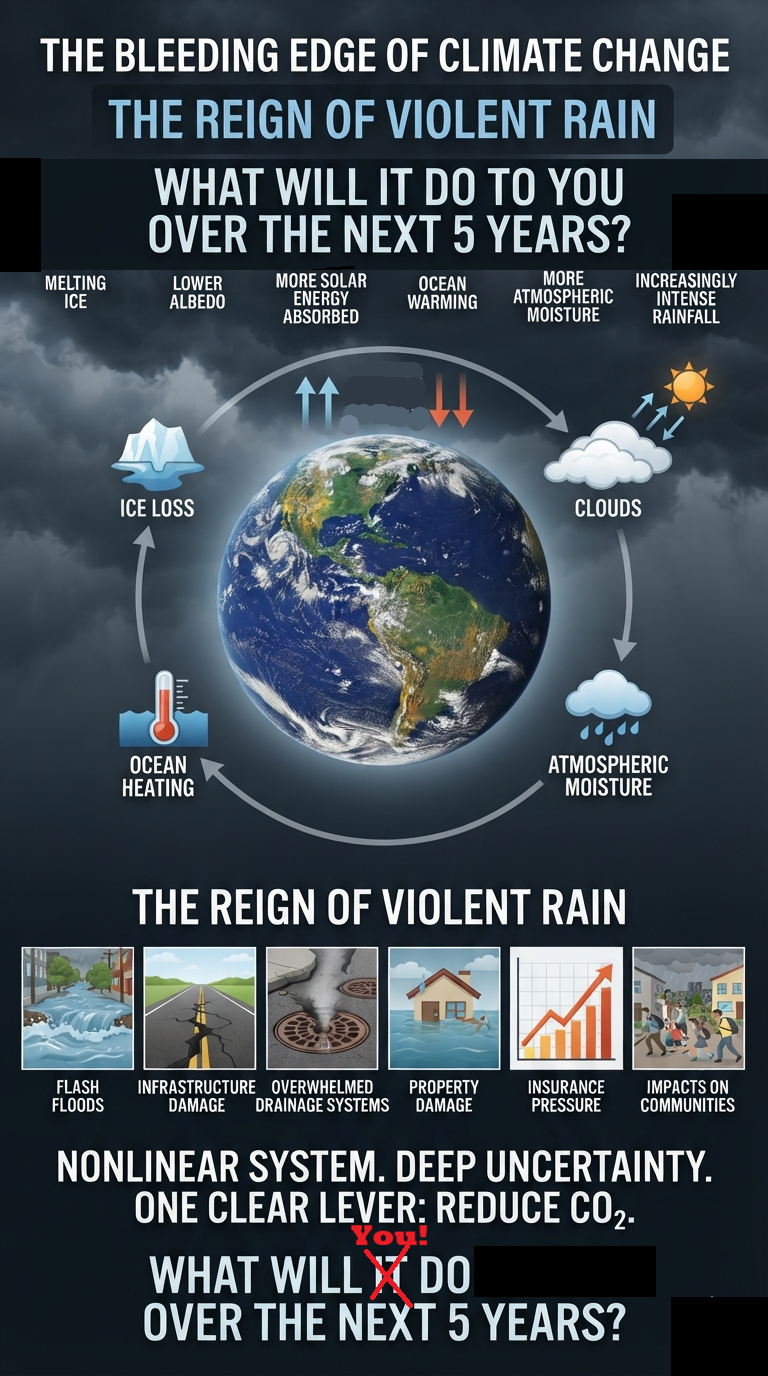
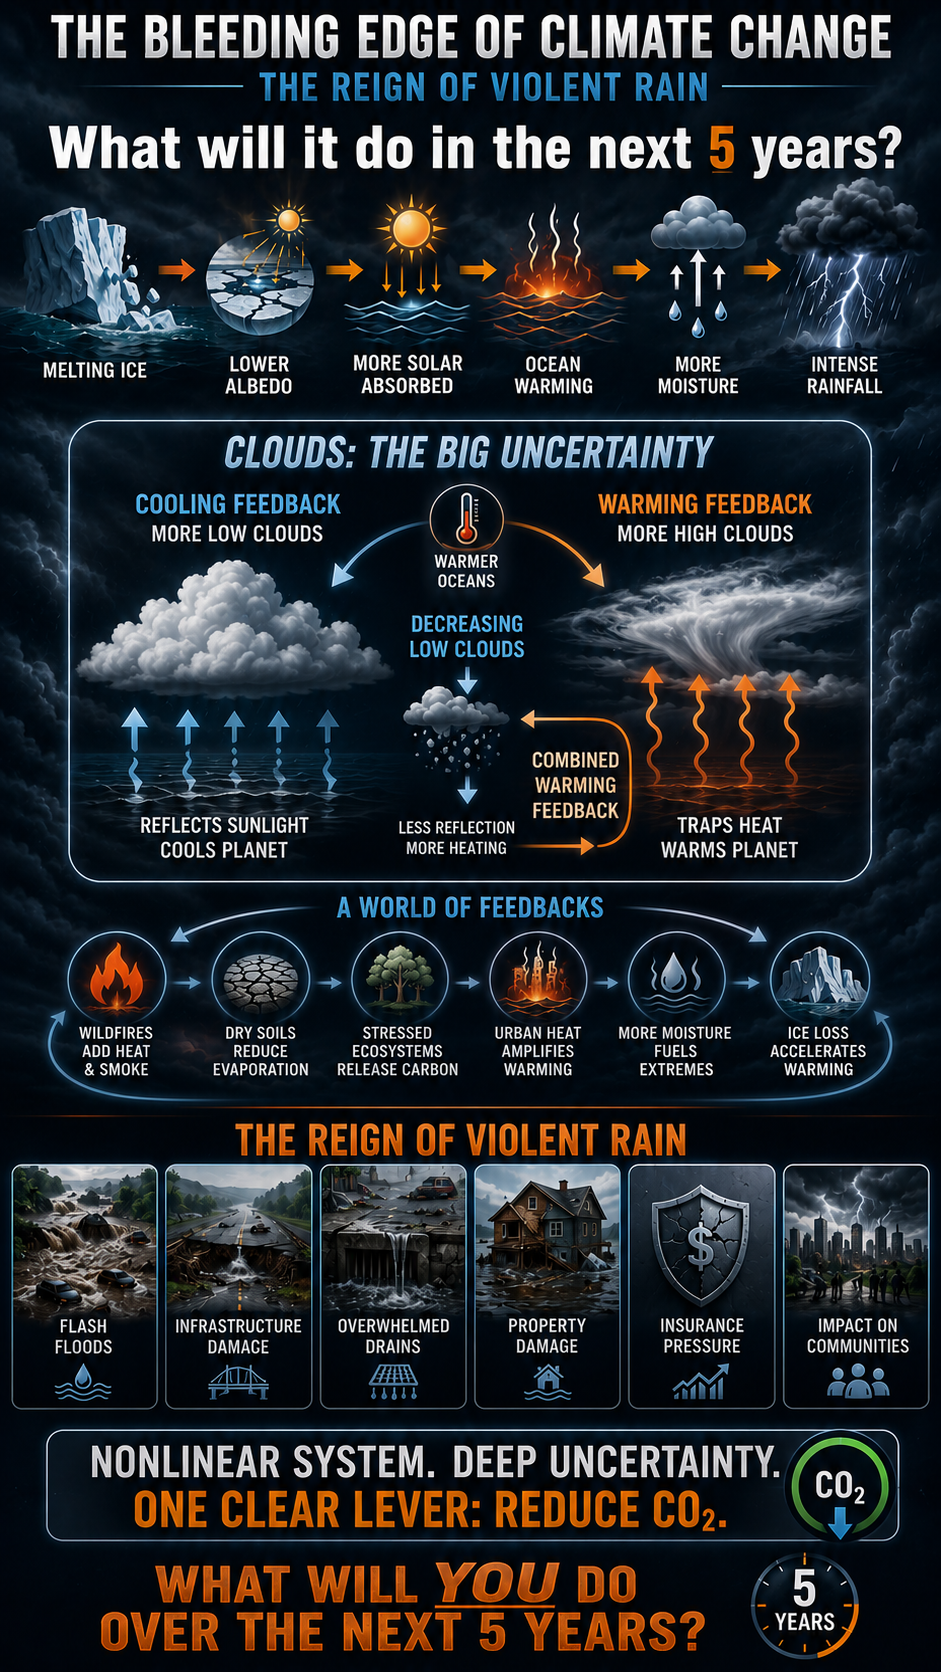
One of the simplest examples is the albedo effect. The physics of ice is straightforward: bright, reflective ice sends a portion of incoming solar energy back into space, while darker ocean absorbs it. Less ice means more absorbed energy and, therefore, more warming.
But the system quickly becomes much more complicated.
How does changing albedo affect cloud formation, particularly over the tropics? And what happens to the climate if those clouds increase—or decrease?
The low clouds are especially important. They can reflect substantial amounts of incoming sunlight back into space. If tropical low clouds diminish, the ocean could absorb significantly more solar energy, accelerating warming.
This is where the bleeding edge begins.
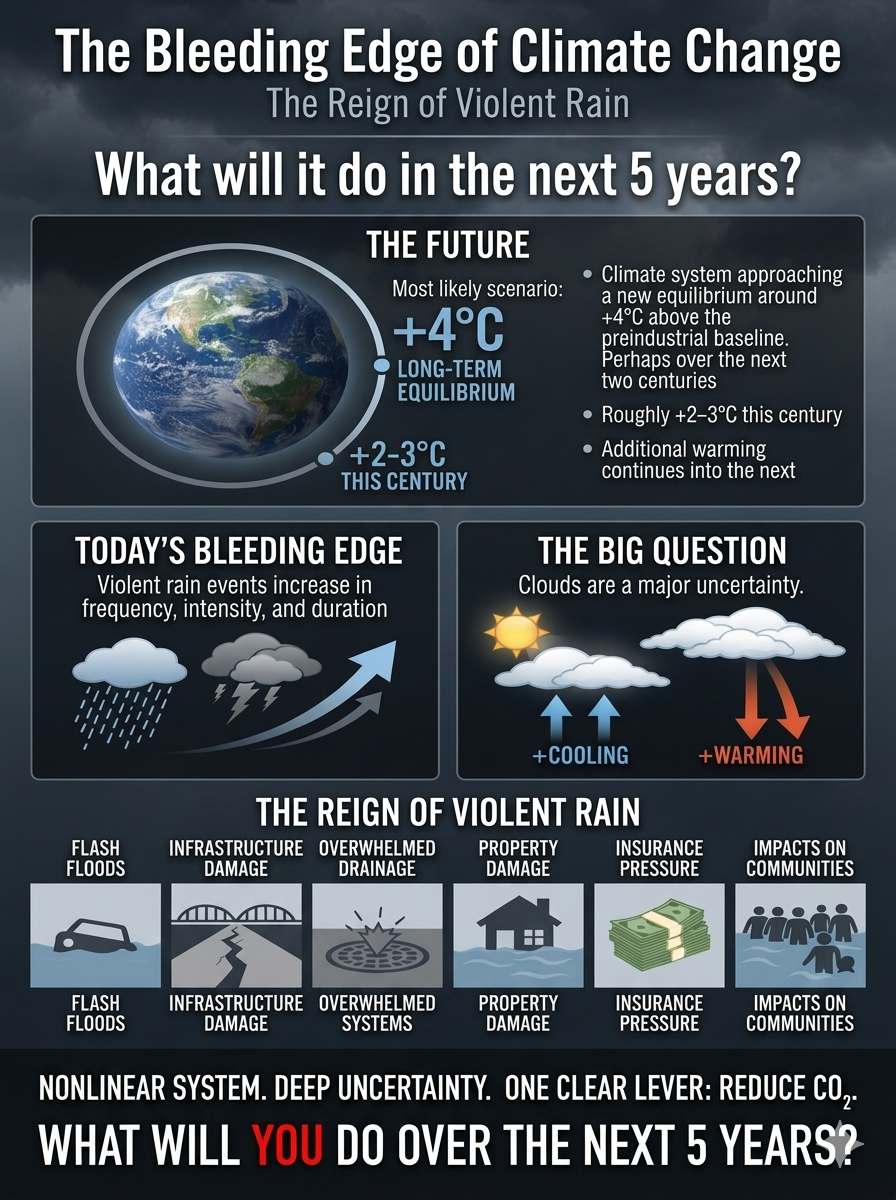
Clouds are arguably the largest remaining uncertainty in our understanding of climate sensitivity. They can both reflect incoming solar radiation and trap outgoing heat. Which effect dominates—and how that balance changes as the planet warms—is one of the great questions in climate science.
My expectation is that the climate system could eventually approach a new equilibrium around +4°C above the preindustrial baseline, perhaps over the course of a couple centuries. That would imply roughly +2–3°C this century, with additional warming continuing into the next.
But that remains uncertain.
The important point is that climate change is not a simple linear equation. It is a massively interconnected system in which changes in one component can alter another, which then feeds back into the first. Ice affects albedo. Albedo affects heating. Heating affects clouds. Clouds affect radiation. Radiation affects ocean temperatures. Ocean temperatures affect evaporation and atmospheric moisture. And the cycle continues.
Everything is nonlinear.
Yet uncertainty about the exact trajectory does not mean uncertainty about what we should do.
The clearest lever we have is still the same: reduce CO₂ emissions and slow the accumulation of greenhouse gases in the atmosphere.
And while the long-term equilibrium matters, there is a much more immediate question.
What happens to you over the next five years?
We are already seeing rainfall becoming more intense and, in many places, more destructive—violent. A warmer atmosphere can hold more water vapor, increasing the potential for extreme precipitation. The question isn’t simply how hot the planet might become over the next 50 years.
The more immediate question is:
What is the violent rain going to do to your home, your community, your infrastructure, your insurance—and you—over the next five years?
That is where climate change stops being a distant projection and starts becoming a personal reality.
The U.S. federal budget deficit reached a record $432 billion in July 2026, the largest deficit ever recorded for the month of July and the widest monthly shortfall since March 2021.
The July surge pushed the cumulative deficit for the first 10 months of fiscal year 2026 to approximately $1.8 trillion—already exceeding the $1.775 trillion deficit recorded for the entire 2025 fiscal year, with two months still remaining. The nonpartisan Congressional Budget Office (CBO) now projects the full-year FY2026 deficit could reach approximately $2.1 trillion.
At the same time, the cost of financing that debt is rising sharply.
Today’s $25 billion, 30-year Treasury bond auction is on track to clear at a yield of approximately 5.23%–5.24%, which would represent the highest yield on newly issued 30-year U.S. government debt since 2001.
The combination is significant: federal borrowing is accelerating while the market is demanding substantially higher compensation for holding long-term U.S. debt.
The elevated 30-year yield reflects a growing term premium—the additional return investors demand to compensate for the risks associated with holding long-duration government debt. Those risks include persistent fiscal deficits, rapidly expanding federal debt, inflation uncertainty, and the possibility that the supply of Treasury securities will continue to overwhelm demand at historically low yields.
This creates a potentially important feedback loop.
The United States is therefore confronting two pressures simultaneously: the government is borrowing more, and borrowing is becoming more expensive.
A single month’s deficit does not establish a fiscal crisis. But the combination of a $432 billion July shortfall, an already $1.8 trillion fiscal-year deficit, a projected $2.1 trillion full-year gap, and long-term Treasury yields above 5% is an increasingly difficult fiscal equation.
The critical issue is no longer simply how large the federal deficit is.
It is how much more expensive it will become to finance it.
The climate costs of fossil-fuel dependence are increasingly outweighing its benefits—not in some distant future, but here and now. We are moving beyond arguments about what climate change might cost decades from today. Across the Western world, climate impacts are already imposing costs of hundreds of billions of dollars in real time.
Insurance is only one part of the story.
Infrastructure, agriculture, transportation, labor productivity, public health, energy systems, and financial markets are all beginning to absorb the cost of a destabilizing climate. The economic question is therefore changing. It is no longer simply:
“What will climate change cost us?”
It is increasingly:
“How much are we willing to pay to preserve an energy system that is becoming progressively more expensive to maintain?”
Climate Stress Is Becoming an Economic Stress Test
The physical infrastructure of the global economy is already being affected.
Maersk CEO Vincent Clerc has warned that climate change is putting increasing pressure on European waterways and that substantial infrastructure investment will be needed to keep the Rhine operating as a critical transportation artery.
But the economic importance of waterways extends far beyond shipping.
Rivers, lakes, and reservoirs are also critical components of the energy, industrial, agricultural, municipal, and ecological systems that support modern economies.
When water levels fall or water temperatures rise, power plants can be affected directly. Thermoelectric and nuclear power plants rely heavily on water for cooling. If river flows become too low, or water temperatures become too high, operators may be forced to reduce generation or temporarily shut down units because sufficient cooling capacity is no longer available or because thermal discharge limits are exceeded.
That creates an economic chain reaction:
Lower river flows or higher water temperatures ↓ Reduced cooling capacity ↓ Reduced power generation ↓ Tighter electricity supplies ↓ Higher electricity prices and grid stress ↓ Higher operating costs for industry and consumers
The same waterways that transport fuel, raw materials, agricultural products, chemicals, and manufactured goods can therefore also be essential to producing the electricity needed to move and manufacture those goods.
Water is simultaneously a transportation system, cooling system, industrial input, agricultural resource, and ecological asset.
When that system becomes unstable, multiple economic sectors can be affected at the same time.
Low water levels can also restrict the movement of coal, oil, natural gas, grain, chemicals, construction materials, and other bulk commodities. Barges may have to reduce their loads or make more trips to transport the same volume of goods. In some cases, alternative transportation by rail or truck becomes necessary, increasing fuel consumption, congestion, labor costs, and emissions.
Flooding creates the opposite problem.
Excess water can damage ports, locks, bridges, rail connections, roads, warehouses, industrial facilities, and electrical infrastructure. A waterway can therefore become economically disruptive at both extremes—too little water and too much water.
Agriculture is similarly exposed. Rivers and reservoirs provide irrigation, livestock water, and municipal supplies. Persistent drought can reduce agricultural output while increasing competition among farmers, cities, industry, ecosystems, and energy producers for increasingly scarce water.
There is also a less visible economic cost: water temperature itself is becoming an economic variable.
Warmer rivers can reduce their ability to absorb additional heat from industrial processes and power-plant cooling systems. At the same time, warmer water can stress aquatic ecosystems, fisheries, and drinking-water systems, creating additional regulatory, treatment, and ecological costs.
This produces a broader economic concept that is often missed in conventional disaster accounting:
Waterway disruption is not a single-sector problem. It is a systems problem.
The Rhine and Danube are not simply waterways. They are components of Europe’s economic infrastructure. They connect ports, factories, power plants, farms, cities, mines, warehouses, rail networks, and consumers. When climate conditions interfere with their operation, the economic consequences propagate through the system. A river does not have to disappear to create an economic crisis. It only has to become less reliable. And reliability is one of the most valuable—and often least visible—assets in a modern economy.
The Economic Toll of Extreme Weather
Global extreme weather and natural disasters are generating enormous economic losses. Recent estimates from the International Chamber of Commerce, insurers including Swiss Re, and disaster-loss tracking organizations show that severe convective storms, wildfires, floods, and other extreme events are producing annual losses measured in the hundreds of billions of dollars.
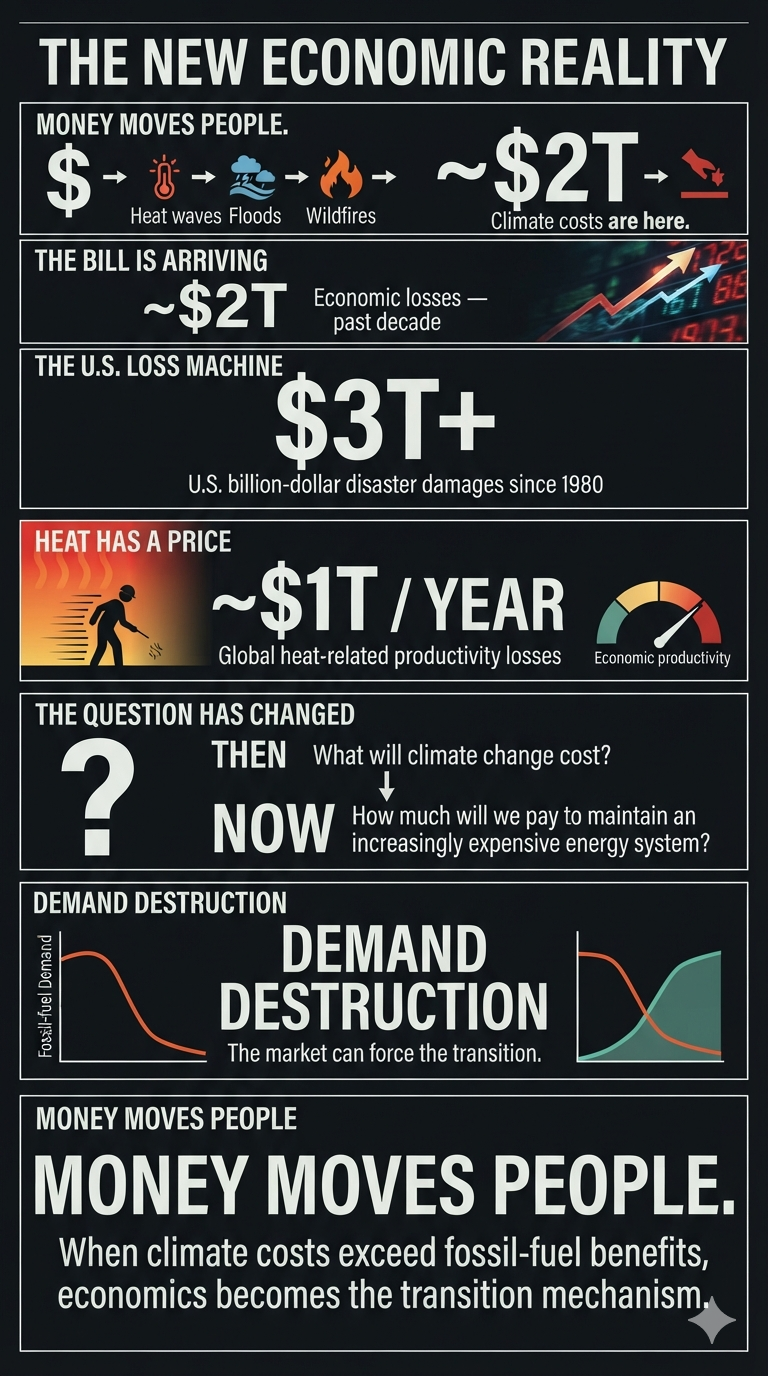
The first half of 2026 alone has already produced approximately $100 billion in global economic losses, while the cumulative economic toll over the past decade has reached roughly $2 trillion, according to recent assessments.
And the year is not over.
The second half of the year normally includes the peak of the North Atlantic hurricane season, creating the potential for another substantial wave of losses.
The Major Economic Drivers
Escalating annual losses. Global disaster losses continue to accumulate at extraordinary levels. The combined economic losses from 2022 and 2023 alone have been estimated at roughly $451 billion.
The concentration of U.S. losses. The United States remains a major source of global insured catastrophe losses. By June 2026, the country had already experienced 12 billion-dollar weather and climate disasters, with estimated losses totaling approximately $31.9 billion.
Severe convective storms. Hail, tornadoes, straight-line winds, and other severe thunderstorms have become an increasingly persistent source of financial losses. The United States recorded a record 21 billion-dollar severe-convective-storm events in 2025.
Extreme heat and productivity. The economic damage from climate change is not limited to destroyed buildings and infrastructure. Heat reduces worker productivity, particularly in construction, agriculture, manufacturing, and outdoor occupations. Global heat-related productivity losses have been estimated at roughly 1% of world GDP annually—around $1 trillion.
The long-term U.S. bill. U.S. billion-dollar weather and climate disasters have generated cumulative damages exceeding $3 trillion since systematic tracking began in 1980.
The Trajectory Is the Story
Recent U.S. disaster statistics illustrate the increasing economic burden:
Year
Billion-Dollar Events
Estimated Damage
Major Loss Drivers
2025
23
~$115 billion
Severe storms, wildfires
2024
27
~$182.7 billion
Severe storms, tropical cyclones, extreme heat
2023
28
$145+ billion
Severe storms and other extreme events
The important point is not that every individual disaster can be attributed exclusively to climate change.
The economic signal emerges from the frequency, intensity, persistence, and cumulative cost of extreme conditions.
Climate change does not need to create every storm, flood, drought, or wildfire to transform the economics of risk. It only needs to increase the probability, severity, or duration of damaging events enough to alter the cost structure of society.
That is already happening.
“Demand Destruction” Is Our Friend
This brings us to one of the most powerful—and least appreciated—economic mechanisms in the energy transition:
Demand destruction.
The International Energy Agency has projected that global oil demand will decline more sharply than previously expected in 2026, forecasting a reduction of approximately 1.6 million barrels per day.
The significance extends beyond the number itself.
As an economist, I am less concerned with establishing a specific date by which the world must eliminate fossil fuels than I am with changing the economic forces that sustain fossil-fuel demand.
That distinction matters.
People do not necessarily change because someone wins an argument about climate science. They change because incentives change. Prices change. Risk changes. Availability changes. And eventually, behavior changes.
Money Moves People
I am unlikely to change the minds of the roughly 20% of Americans who are ideologically committed to policies that accelerate fossil-fuel dependence.
But that leaves the vast majority of the population. And economics can do much of the work. Integrated Climate Stewardship begins with reducing unnecessary consumption.
Consumerism drives energy demand, resource extraction, pollution, waste, and habitat destruction. Every unnecessary unit of consumption represents another demand for energy and materials somewhere in the global economy.
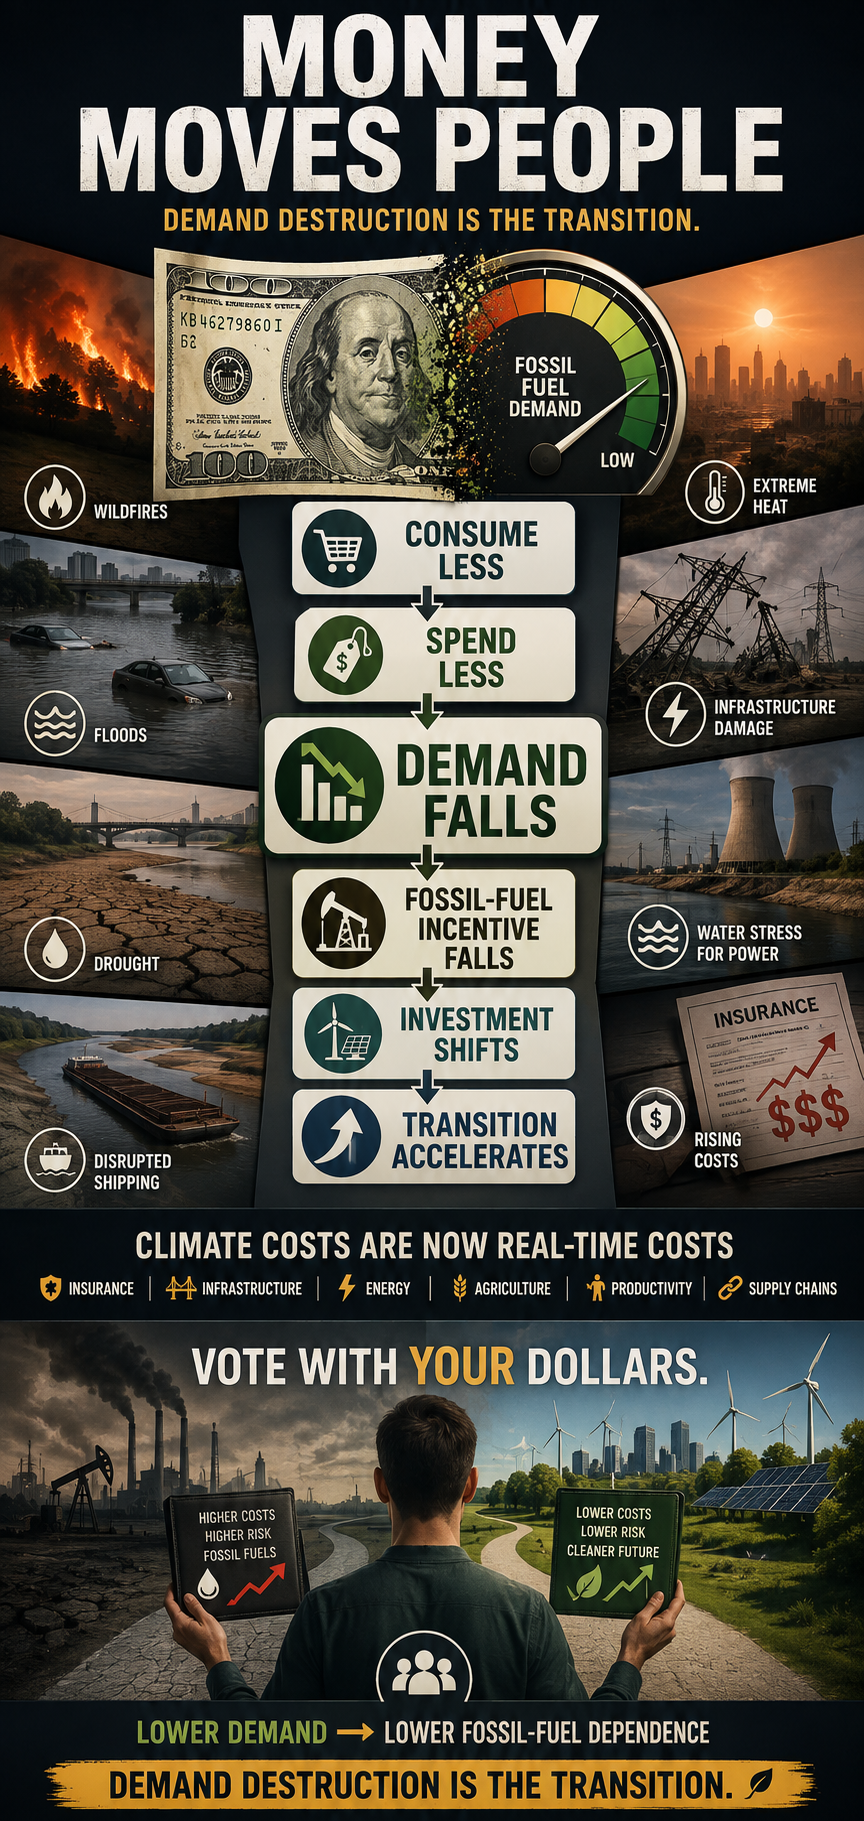
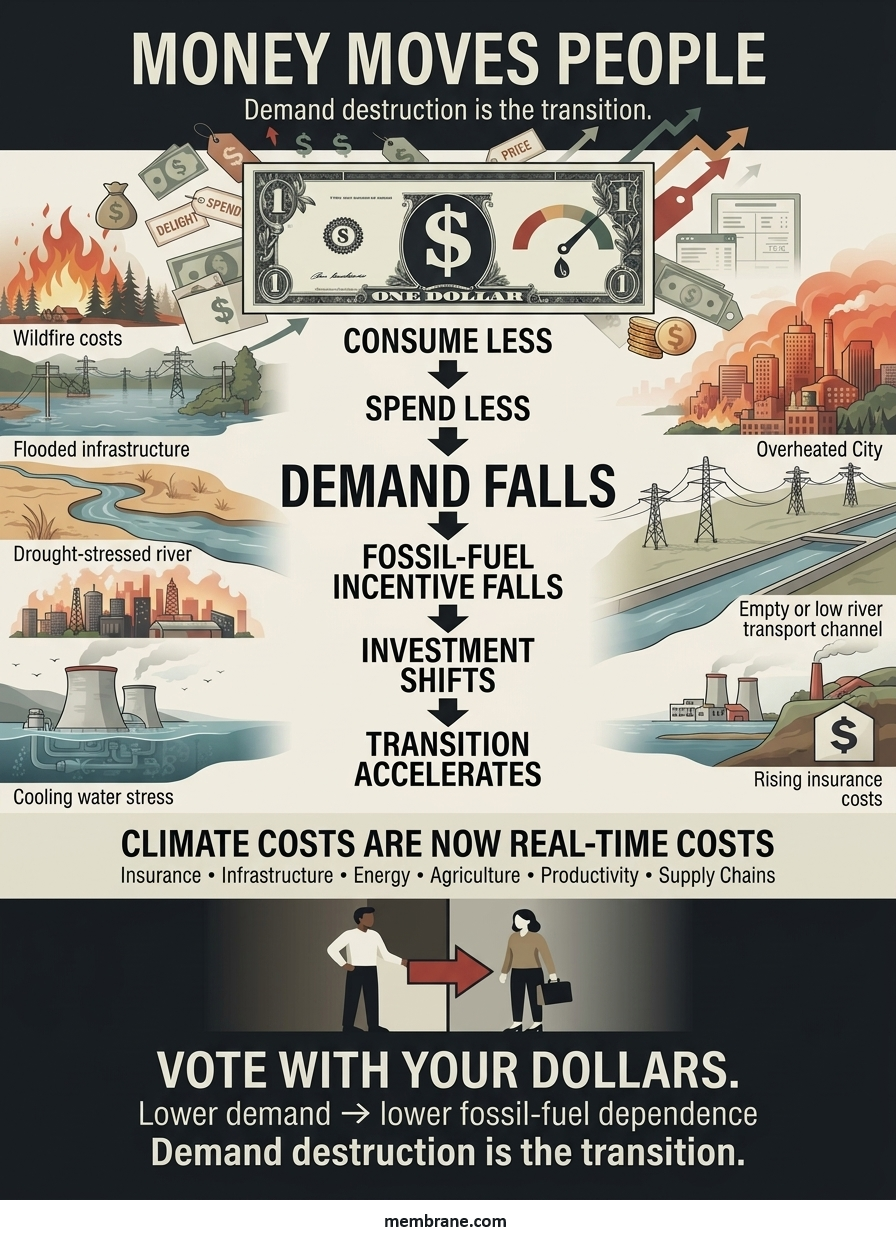
Consume less, and demand falls.
Demand falls, and the economic incentive to produce falls.
That is the mechanism.
The Economics of Personal Climate Stewardship
Today, only a small fraction of Americans appear to be pursuing a deliberately structured net-zero lifestyle through continuous behavioral reductions, efficiency improvements, and intentional balancing. But this does not mean the model cannot scale. The critical question is how climate stewardship is presented.
If reducing climate impact is framed exclusively as sacrifice, people resist. If it is framed as economic self-interest, the equation changes.
What happens when people discover that reducing unnecessary consumption can save them thousands of dollars a year?
What happens when energy efficiency lowers household expenses?
When smaller vehicles reduce fuel, maintenance, and insurance costs?
When reducing waste means buying fewer things that do not provide meaningful value?
When local production and durable goods become economically attractive?
When conservation becomes synonymous with financial resilience?
The behavior does not have to begin with ideology.
It can begin with a household budget.
Vote With Your Dollars
This is where the remaining majority of the population becomes economically important.
When millions of people begin making purchasing decisions based on cost, durability, efficiency, resilience, and environmental impact, they collectively alter demand.
When demand changes, markets respond. When fossil-fuel demand declines, the economic incentive to extract, refine, transport, and sell fossil fuels declines with it. This is fundamentally different from waiting for governments to impose every change from the top down. It is a bottom-up economic transition.
People do not have to agree about everything.
They do not have to become climate activists.
They do not even have to agree about climate policy.
They simply have to discover that some forms of consumption are no longer worth what they cost.
The Feedback Loop
The process can become self-reinforcing:
Lower unnecessary consumption ↓ Lower household costs ↓ Lower energy and resource demand ↓ Reduced fossil-fuel demand ↓ Lower economic incentive for fossil-fuel expansion ↓ Greater investment in alternatives and efficiency ↓ Further reductions in fossil-fuel demand
This is an economic feedback loop.
And unlike many climate-policy debates, it does not require everyone to agree on the destination before beginning the journey.
Demand Destruction Is the Transition
The transition away from fossil fuels is often described as a supply problem:
How quickly can we replace coal, oil, and natural gas?
But there is another side of the equation.
How quickly can we reduce the demand that makes fossil-fuel extraction profitable?
That may ultimately be the more powerful question.
We do not need to convince every person to become an environmentalist.
We need to make lower-carbon choices increasingly rational economic choices.
The climate crisis is already generating enormous costs. Insurance premiums are rising. Infrastructure is being stressed. Agricultural productivity is being disrupted. Heat is reducing labor capacity. Extreme weather is destroying capital. Supply chains are becoming more vulnerable.
These costs are not theoretical.
They are appearing on balance sheets, household budgets, insurance statements, government budgets, and corporate earnings reports.
The economic system is beginning to receive the bill.
And money moves people.
Demand destruction is not the enemy of the energy transition.
A 4.9% year-over-year Producer Price Index (PPI) increase means the average price level producers face is nearly 5% higher than it was one year ago.
The math is straightforward:
5.0% − 4.9% = 0.1 percentage point
That puts the headline PPI rate just one-tenth of a percentage point below 5%.
For example, if an identical basket of wholesale goods cost a business $100,000 in July 2025, a 4.9% increase means that same basket would cost approximately $104,900 in July 2026.
And 4.9% doesn’t happen in isolation. Businesses are operating on a cost structure already elevated by previous years of inflation. The new increase compounds on top of those higher prices.
There is another important point: 4.9% is an average. Different industries can experience dramatically different increases. Businesses heavily dependent on energy, transportation, food, or raw materials can face considerably higher cost pressures.
Those higher producer costs can eventually move through the supply chain and put additional pressure on consumer prices.
So no, 4.9% isn’t technically 5.0%. But it is mathematically very close—and economically, a nearly 5% annual increase in producer prices is significant.
Do the math. Then look at what those numbers mean for the real economy.
The Oil Import Surge & Inventory Anomaly
While July wholesale energy costs fell and helped moderate the PPI data, the energy market itself is experiencing significant near-term turbulence amid the ongoing closure of the Strait of Hormuz and stalled U.S.-Iran negotiations.
This creates a bifurcated picture in the U.S. oil market: headline inventories are surging, but the increase appears to be driven primarily by an extraordinary jump in imports rather than a sudden expansion of domestic production.
• The Massive Build: The Energy Information Administration (EIA) reported a 17.4 million-barrel increase in U.S. commercial crude inventories for the week ending August 7. That was the largest single-week build since January 2023.
• The Import Catalyst: Net crude imports nearly doubled their recent four-week average, reaching approximately 4.28 million barrels per day. That surge points to an unusual compression in the commercial shipping and inventory cycle, with refiners sourcing substantially more crude from international markets.
• Refinery Strain: U.S. refinery utilization slipped only 0.3 percentage points to 96.2%. That remains an extremely high utilization rate and suggests refiners are operating near capacity while the market adjusts to disrupted international supply routes.
The important distinction is this: A massive inventory build does not automatically mean the underlying oil market is oversupplied.
In this case, the inventory increase appears closely tied to an extraordinary surge in imports and the disruption of normal shipping patterns. The numbers therefore need to be interpreted within the broader geopolitical and logistical environment.
The headline inventory number tells only part of the story. The flow of crude into the country—and why that flow changed so dramatically—is the more important signal.
“According to newly released data from GasBuddy and the American Automobile Association (AAA), the national average price of gasoline has never been above $4.00 a gallon this late in the calendar year.“
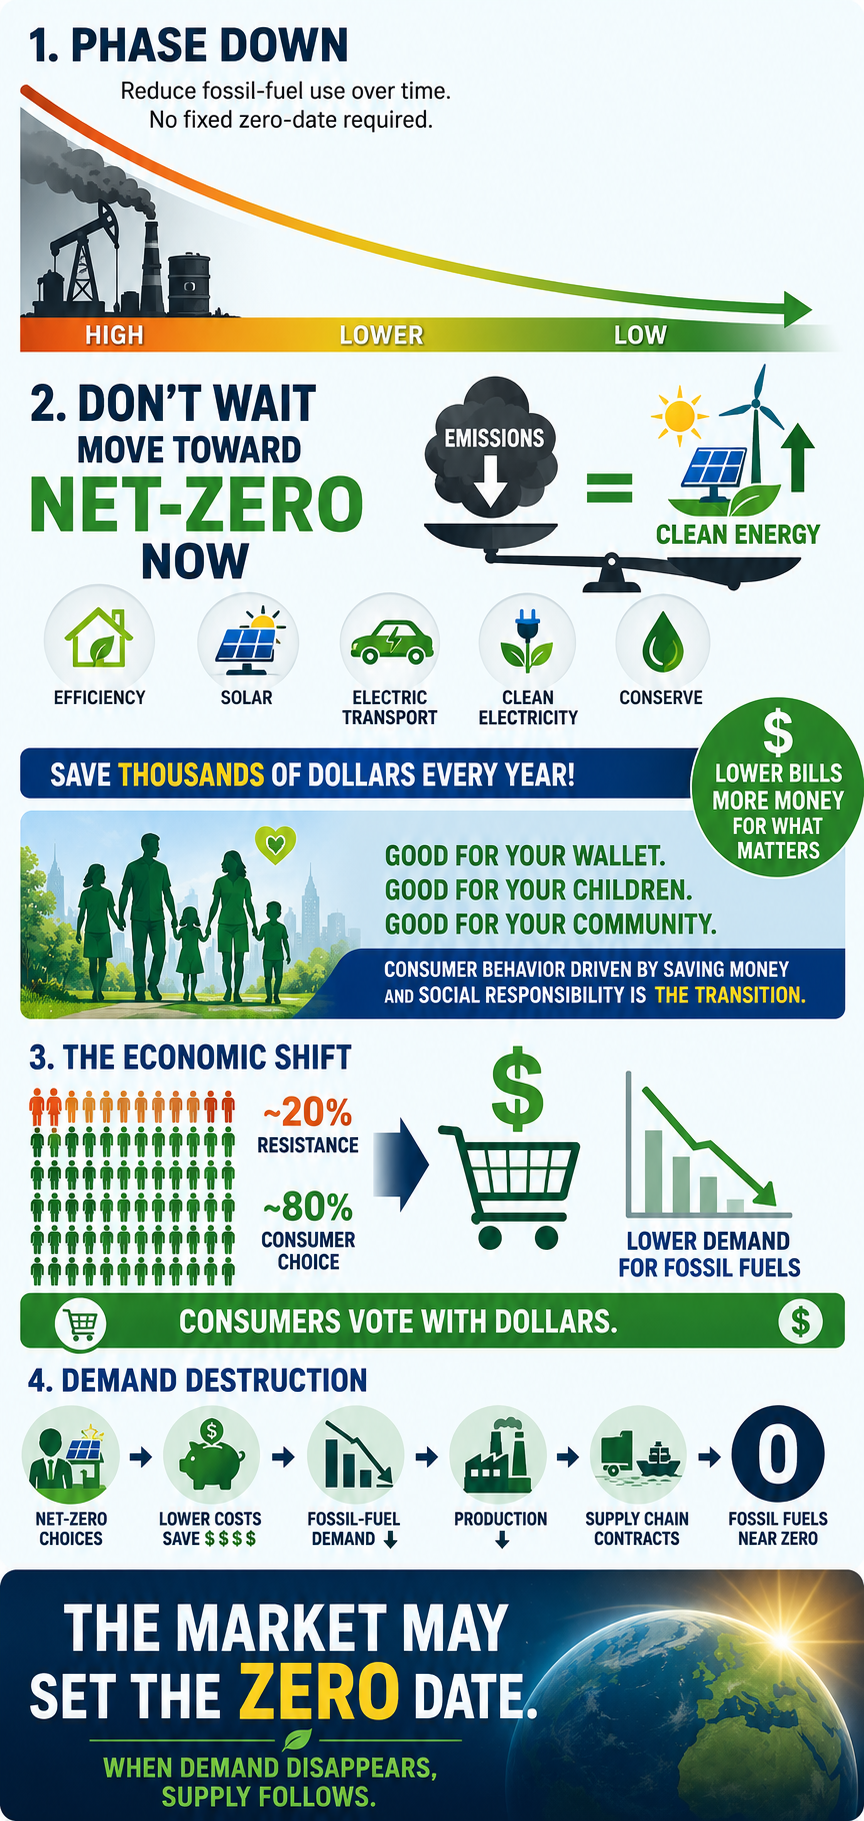
I use phasing out in a way that means completely ending the use and production of fossil fuels down to zero. Phasing down means a gradual reduction or scaling back in FF use over time without specifying a complete stop. Would add or alter that in any way?
How would you define differntiate ‘transition away’?
Reply:
I would slightly modify your definition of “phasing down” to: “a gradual reduction or scaling back in fossil-fuel use over time without specifying a date for complete cessation.”
There are really two separate issues for me:
1. For this generation, I prefer net-zero carbon emissions as the immediate goal. If someone isn’t already moving toward net-zero, I think they should start now. We don’t need to wait for a theoretical future phase-out date to begin reducing emissions.
2. As both a climatologist and an economist, I’m not convinced that setting a specific date for the complete elimination of fossil fuels is ultimately what matters. In the U.S., roughly 20% of the population appears ideologically committed to policies that would accelerate climate change. Nothing I say or do is likely to change that.
But that still leaves roughly 80% of the population—and I think economics is going to do much of the work.
Right now, perhaps only ~0.5% of Americans are seriously attempting a structured net-zero lifestyle through continuous behavioral reductions and intentional balancing. As more people discover that net-zero can actually save them thousands of dollars a year while also leaving a better environment for their children and grandchildren, I expect consumer behavior to change.
When the remaining ~79.5% begin voting with their dollars, fossil-fuel demand will fall. That creates demand destruction, which ultimately means suppliers will have less and less reason to produce fossil fuels.
So, ironically, I don’t think we necessarily need to establish the exact date when fossil fuels reach zero. The market may establish that date for us. The “complete stop” happens when there is no longer sufficient demand to sustain the fossil-fuel supply chain.
Question:
When you use the term net zero is it with the understanding that the “net” component allows continuous greenhouse gas emissions under the assumption that unproven removal technologies or flawed offsets will balance them out later, delaying necessary fossil fuel phaseouts?
Net zero is a contentious term within my community and I want to be clear that I understand how you see and apply it.
Reply:
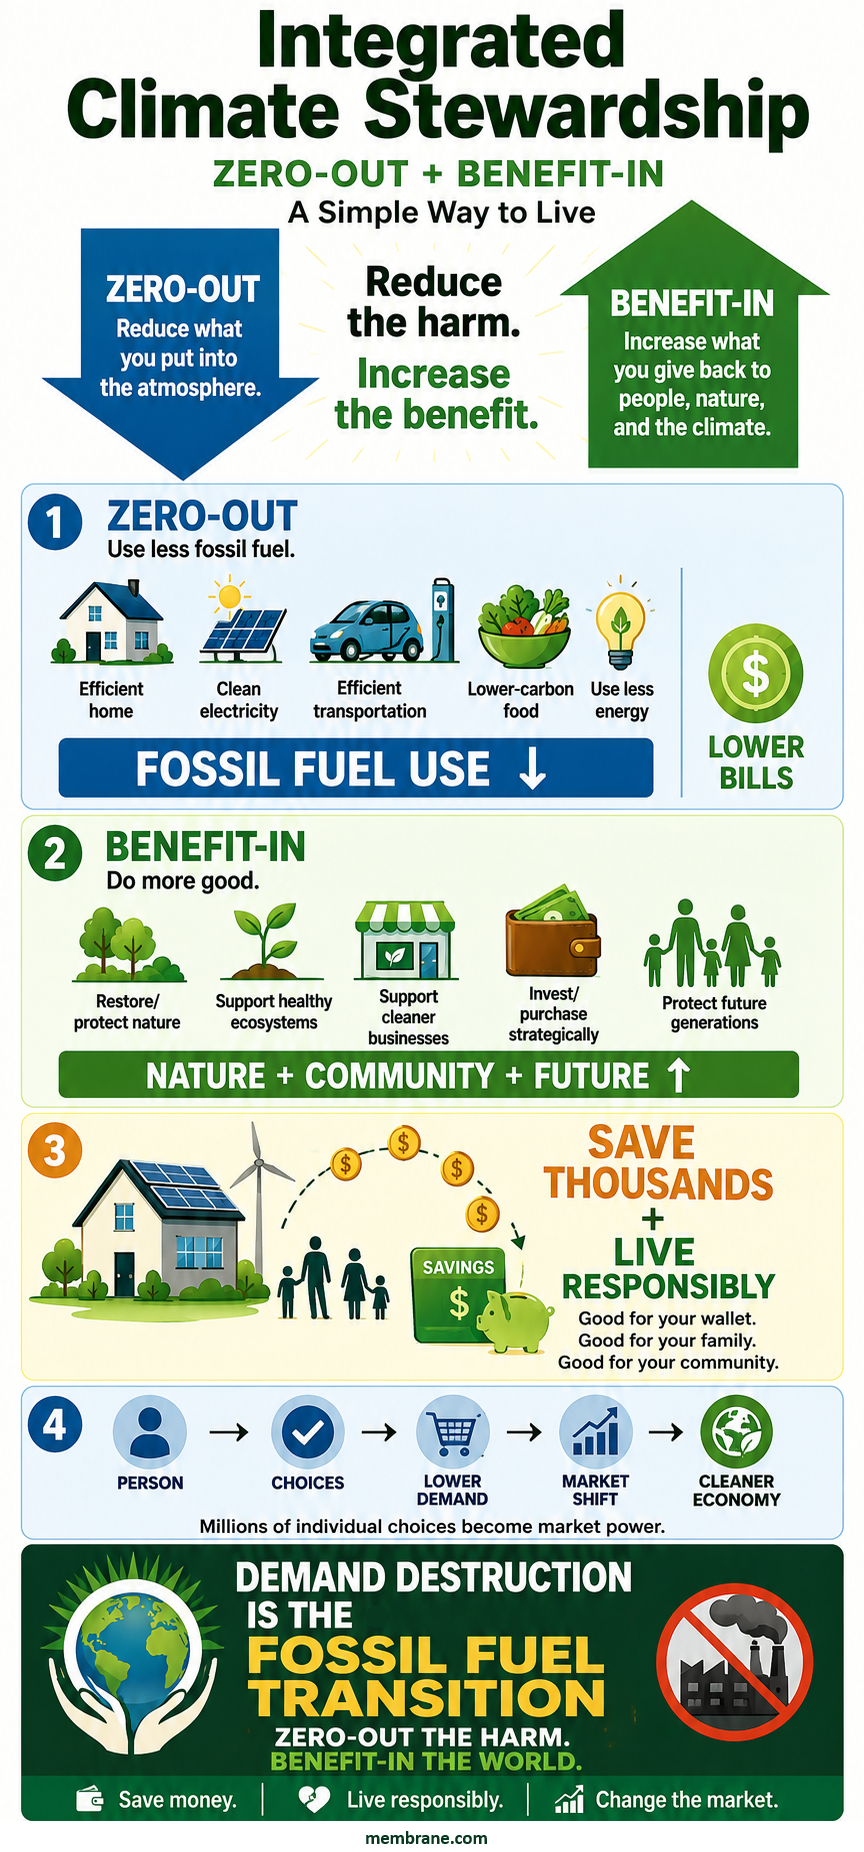
That’s an important distinction. When I use the term net-zero, I’m talking about it at the personal/lifestyle level, and I am not using “net” to justify continuing to emit greenhouse gases while assuming that unproven technologies or questionable offsets will clean up the problem later.
What I mean is closer to “Holistic Net-Zero Living” or “Integrated Climate Stewardship”: reducing and, wherever realistically possible, zeroing out the emissions associated with my own lifestyle first, while also taking responsibility for the impacts I can’t immediately eliminate.
For me, that means a 360-degree carbon strategy:
ZEROING OUT / STRUCTURAL DECARBONIZATION
Electrifying transportation and home energy
Increasing energy efficiency
Using clean electricity
Reducing fossil-fuel consumption as close to zero as practical
Reducing high-carbon consumption, including dietary choices
BEYOND MY DIRECT FOOTPRINT
Supporting ecosystem restoration and conservation
Protecting forests and biodiversity
Supporting businesses and technologies that accelerate decarbonization
Using my purchasing and investment decisions to create economic demand for cleaner alternatives
So I’m not saying, “Keep emitting and someone will remove it later.” Quite the opposite. The first priority is eliminating the emissions themselves.
I think of the “net” component as recognizing that an individual cannot instantly eliminate every indirect emission associated with modern life. Rather than pretending those emissions don’t exist, I try to compensate through additional positive actions while continuously working to reduce the underlying footprint.
Ultimately, my goal isn’t simply to achieve a favorable carbon-accounting number. It’s to change the way I live so that my actual fossil-fuel demand approaches zero—and to use my economic choices to help make that transition happen systemically.
That’s why I sometimes think “holistic net-zero living” or “integrated climate stewardship” communicates what I mean better than simply saying “net-zero.”
Question:
Why continue using the language of ‘net zero’? What economic model do you see best aligns w/ what you have outlined?
Reply:
Haaha… good questions.
A: I’m actually in the process of writing the paper that officially changes my language from “net-zero” to “Integrated Climate Stewardship.” So thank you for pushing me on that. I think the new terminology better captures what I’ve been trying to describe.
B: I’m also working on the economic model, and that one is considerably trickier—not because of the terminology, but because AI is changing the underlying economics so rapidly.
I see AI as a double-edged sword. On one edge, as AI replaces more human labor and productivity, the human contribution to economic production could eventually become a much smaller share of GDP. AI may also be capable of producing enormous amounts of economic value with far less energy per unit of output than traditional human labor and many existing production systems.
But the other edge of that sword is wealth distribution.
If the ownership of AI, capital, and productive capacity becomes increasingly concentrated, we could see extraordinary productivity growth occurring alongside increasingly unjust wealth inequality. We could potentially solve one problem—resource and energy efficiency—while creating another: who actually owns and benefits from the productivity?
That’s the economic model I’m wrestling with now: how do we build an economy where AI-driven productivity, decarbonization, consumer savings, and environmental stewardship reinforce each other while the resulting wealth is broadly distributed?
That may ultimately be a much bigger economic question than the climate transition itself.
Question:
Have you been sitting with the economic of degrowth in all of this then? Sounds like there is that tension in what is being considered.
Reply:
Yes. I’ve been sitting with the economics of degrowth quite a bit. And I think there’s an interesting tension here.
Traditional capitalism is fundamentally tied to population growth, human labor, productivity, and consumption. But AI potentially breaks that relationship. If technology increasingly replaces human labor, then economic growth can continue—even accelerate—while the economic value of human labor declines, perhaps dramatically.
So I’m not sure the future necessarily looks like “degrowth.” It may be something stranger: exponential technological growth occurring alongside declining human labor demand, an aging population in the developed regions of the world, and potentially declining population worldwide.
That raises a much bigger question: if human labor is no longer the primary engine of economic value, what exactly are we trying to maximize—and how should the economy distribute the benefits of that productivity?
That’s the economic model I’m wrestling with right now.
Question:
What about lands and waters in these considerations?
Can we agree that what we need must be either mined or grown?
Raw materials come from somewhere with significant externalities — often left out of economic theory.
My other issue is the assumptive ghost of interest-bearing-debt as a driver of unnecessary growth.
Reply:
Yes—and I think land, water, and raw materials have to be part of the model. My initial modeling, however, is pointing toward a very different problem than the one we traditionally assume.
If AI continues improving itself, productivity could eventually become extraordinarily resource-efficient. Very little additional human labor—and potentially much less land, water, or energy per unit of economic output—may be required for productivity and growth. At the same time, consumers could be forced to consume much less because their income from labor is declining. And as solar and other clean-energy technologies continue becoming cheaper, the pressure for some forms of mining and extraction could decline as well.
That brings me back to your point about interest-bearing debt. I think sovereign debt may become the critical part of the equation.
Productivity gains and abundant cheap clean energy are profoundly deflationary. Deflation sounds wonderful for consumers in theory—but not if it is accompanied by collapsing labor income. You could have falling costs and prices while households simultaneously lose the purchasing power needed to buy anything.
Now add governments facing enormous debt obligations while their traditional tax base is shrinking because human labor is becoming less economically valuable. Governments could increasingly rely on interest-bearing debt to finance poverty reduction, redistribution, and some form of basic income.
And that creates a potentially nasty feedback loop: AI-driven productivity → declining labor income → shrinking tax base → rising sovereign debt → greater reliance on monetary expansion → inflationary pressure.
Historically, severe sovereign debt problems have sometimes been resolved through substantial currency devaluation and inflation. I’m not saying hyperinflation is inevitable—but it is one of the risks I’m now modeling.
The really strange possibility is that we could simultaneously have exponential productivity, increasingly abundant cheap energy, falling costs of production—and increasing economic hardship for ordinary people.
In other words, the problem may not ultimately be whether the planet can produce enough. It may be whether humans can maintain enough income, purchasing power, and economic agency to participate in the abundance that AI creates.
That, to me, is where the economic model gets really interesting.
By Daniel Brouse Economist & Climatologist Membrane Domain USA August 10, 2026
I’m not certain what the future holds. I don’t think anyone can be.
But I’m also not convinced that the future of fossil fuels can be projected simply by looking at today’s production levels and assuming they will continue indefinitely.
There is a very real possibility that economics, energy security, technological substitution, and even economic disruption could phase out fossil fuels much faster than most people expect.
In fact, some of the data already point in that direction.
The Energy Transition Is Already Moving
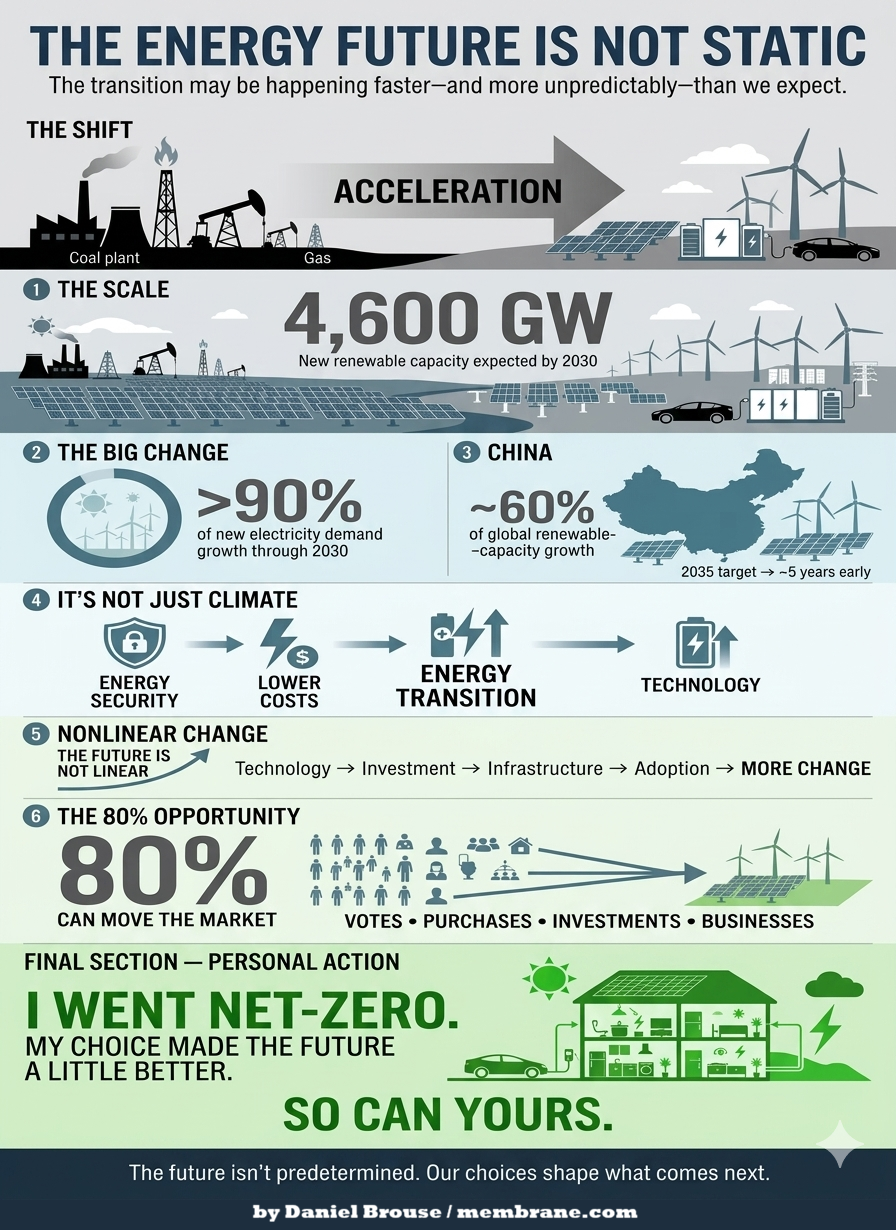
The International Energy Agency estimates that global renewable capacity will increase by roughly 4,600 GW between 2025 and 2030—an extraordinary expansion roughly equivalent to the combined current power capacity of China, the European Union, and Japan.
Solar PV is expected to account for almost 80% of that expansion.
Even more significant is what this means for the growth of electricity demand. Renewables are expected to provide more than 90% of the increase in global electricity generation through 2030.
This is not simply a distant prediction about some hypothetical future energy system. It represents an enormous investment already underway.
And the transition is happening particularly rapidly in China.
China is now responsible for nearly 60% of global renewable-capacity growth. In 2025 alone, it added roughly 314 GW of solar capacity and is on track to reach its 2035 wind-and-solar target approximately five years early.
Whatever one’s views on climate policy, these numbers are difficult to dismiss.
The global energy system is changing.
And it is changing rapidly.
This Isn’t Just About Climate Policy
There is another factor that deserves considerably more attention: energy security.
The transition away from fossil fuels is not being driven exclusively by environmental concerns. Increasingly, it is also becoming an economic and strategic imperative.
The disruption of oil and gas flows through critical transportation routes such as the Strait of Hormuz demonstrates the vulnerability inherent in an energy system dependent upon globally traded fossil fuels.
For Europe and Asia in particular, domestic renewable generation, energy storage, electrification, and efficiency increasingly represent something more than climate policy.
They are energy-security assets.
A solar panel or wind turbine doesn’t need to be transported through a geopolitical chokepoint every time it generates electricity. Once installed, domestic renewable resources can reduce exposure to international fuel-price shocks, supply disruptions, and geopolitical conflicts.
That changes the economic calculation.
And it is one reason I believe the energy transition may prove considerably more nonlinear than many conventional forecasts assume.
The Future May Be Nonlinear
I agree that we shouldn’t pretend we know exactly what the future holds.
My point is almost the opposite.
The future may be much more nonlinear than either of us can confidently predict.
Technologies don’t necessarily replace one another gradually. Once a technology becomes sufficiently cheap, reliable, scalable, and convenient, adoption can accelerate rapidly.
The same thing can happen with infrastructure.
Battery storage becomes cheaper. Electric vehicles become more capable. Solar becomes less expensive. Transmission improves. Heat pumps become more efficient. Businesses discover that electrification can reduce operating costs. Consumers begin choosing technologies that save them money.
Each development can reinforce the others.
And once enough pieces of the system change, the economics of the entire energy system can change with them.
This is why simply extrapolating today’s fossil-fuel production into the future can be misleading.
Could “Drill, Baby, Drill” Backfire?
There is an irony here.
Policies intended to expand U.S. fossil-fuel production could potentially accelerate the transition they are intended to slow if they contribute to greater volatility, geopolitical exposure, or investment in alternatives.
Consider what could happen during a serious economic downturn.
A major recession could cause substantial demand destruction. Businesses would consume less energy. Consumers would drive less and purchase fewer goods. Industrial production would decline.
Fossil-fuel consumption could fall sharply.
That would potentially undermine the very industry that policies designed around expanding fossil-fuel production are intended to strengthen.
There is no guarantee this will happen. But that’s precisely the point.
The future contains feedback loops.
Economic conditions affect energy demand. Energy prices affect technology adoption. Technology affects investment. Investment affects infrastructure. Infrastructure affects energy prices and security. Geopolitical events affect all of them.
The result is a system capable of changing much faster than a simple linear projection would suggest.
This Isn’t an All-or-Nothing Choice
I’m not trying to create another online debate.
I’m simply pointing out that the data show a transition already underway—and its speed is anything but static.
And perhaps the most important point is that this isn’t an all-or-nothing proposition.
Every increment of transition matters.
Every electric vehicle displaces some gasoline consumption. Every solar panel replaces some electricity that otherwise might have come from fossil fuels. Every efficiency improvement reduces energy demand. Every battery installation makes intermittent renewable energy more useful. Every business that electrifies reduces some exposure to fossil-fuel prices.
The more we transition, the more reasonable—and manageable—the future becomes.
We don’t need to transform the entire energy system overnight.
We need to keep moving.
Technology Is Changing More Than Energy
There is another reason I remain optimistic.
Ironically, AI and rapidly advancing technology are accelerating climate science at a pace that may eventually rival the acceleration of climate change itself.
Research that once took years can increasingly be explored in hours.
Large datasets can be analyzed in ways that weren’t previously practical. Relationships between variables can be identified more quickly. Models can be tested, refined, and compared at extraordinary speed.
I’ve been able to identify hundreds of interacting feedbacks and relationships that weren’t even being seriously considered just a few years ago.
That doesn’t mean every hypothesis will be correct.
It means our ability to investigate complex systems is expanding extraordinarily quickly.
And that gives me reason for optimism.
Humans have an extraordinary capacity to adapt, innovate, and solve difficult problems—especially when we are sufficiently motivated to do so.
The future is not predetermined.
What we do now can still make an enormous difference in what comes next.
The 80% Question
A final thought concerns something that initially struck me as particularly concerning.
Roughly 20% of Americans appear to be actively fighting the energy transition.
At first, I found that almost dumbfounding. I expected the number to be closer to less than 2%.
But there is another way to look at it.
That still leaves roughly 80% of the population.
And if that 80% chooses to act—through voting, investment, purchasing decisions, business decisions, and simply choosing where to spend their dollars—the market can move remarkably quickly.
We don’t necessarily have to fight the remaining 20%.
We can vote with our dollars.
Markets respond to demand.
If enough consumers and businesses choose alternatives, capital will follow. Manufacturers will respond. Infrastructure will change. Companies will adapt.
And eventually, the fossil-fuel industry will have to adapt as well—or gradually lose market share.
That is the power of an energy transition driven not only by government policy, but by millions of individual economic decisions.
My Choice. Your Choice. Our Future.
I went net-zero years ago.
If I can do it, anybody can.
I don’t claim that my individual decision changed the world.
But my choice made the future a little better than it otherwise would have been.
And so can yours.
The future of energy isn’t predetermined by today’s production numbers, today’s political battles, or today’s assumptions.
It will be shaped by billions of decisions made by consumers, businesses, investors, engineers, scientists, and governments.
Some of those decisions will be political.
Many will be economic.
Some will be technological.
And countless others will be personal.
That’s why I don’t think the question is whether we can predict exactly what the energy system will look like in 10, 20, or 30 years.
We can’t.
The more important question is:
What direction are we moving—and how much can our choices influence where we ultimately arrive?
About Denialism and Ecofascism: Science Is Science
The Observation Glad to know you’re watching out! At the same time, this divisiveness—when we desperately need everyone to pull together because it’s a CRISIS, right?—makes me somehow deeply sad.
That’s a big job right there… How do we reach those who seem furthest away from any kind of understanding? We need both a Winston Churchill and a Mahatma Gandhi in this endeavor…
The Response Agreed. Both denialism and ecofascism are ideologies that ultimately defy logic. In very different ways, they can become a kind of combination of self-destruction and destruction of others.
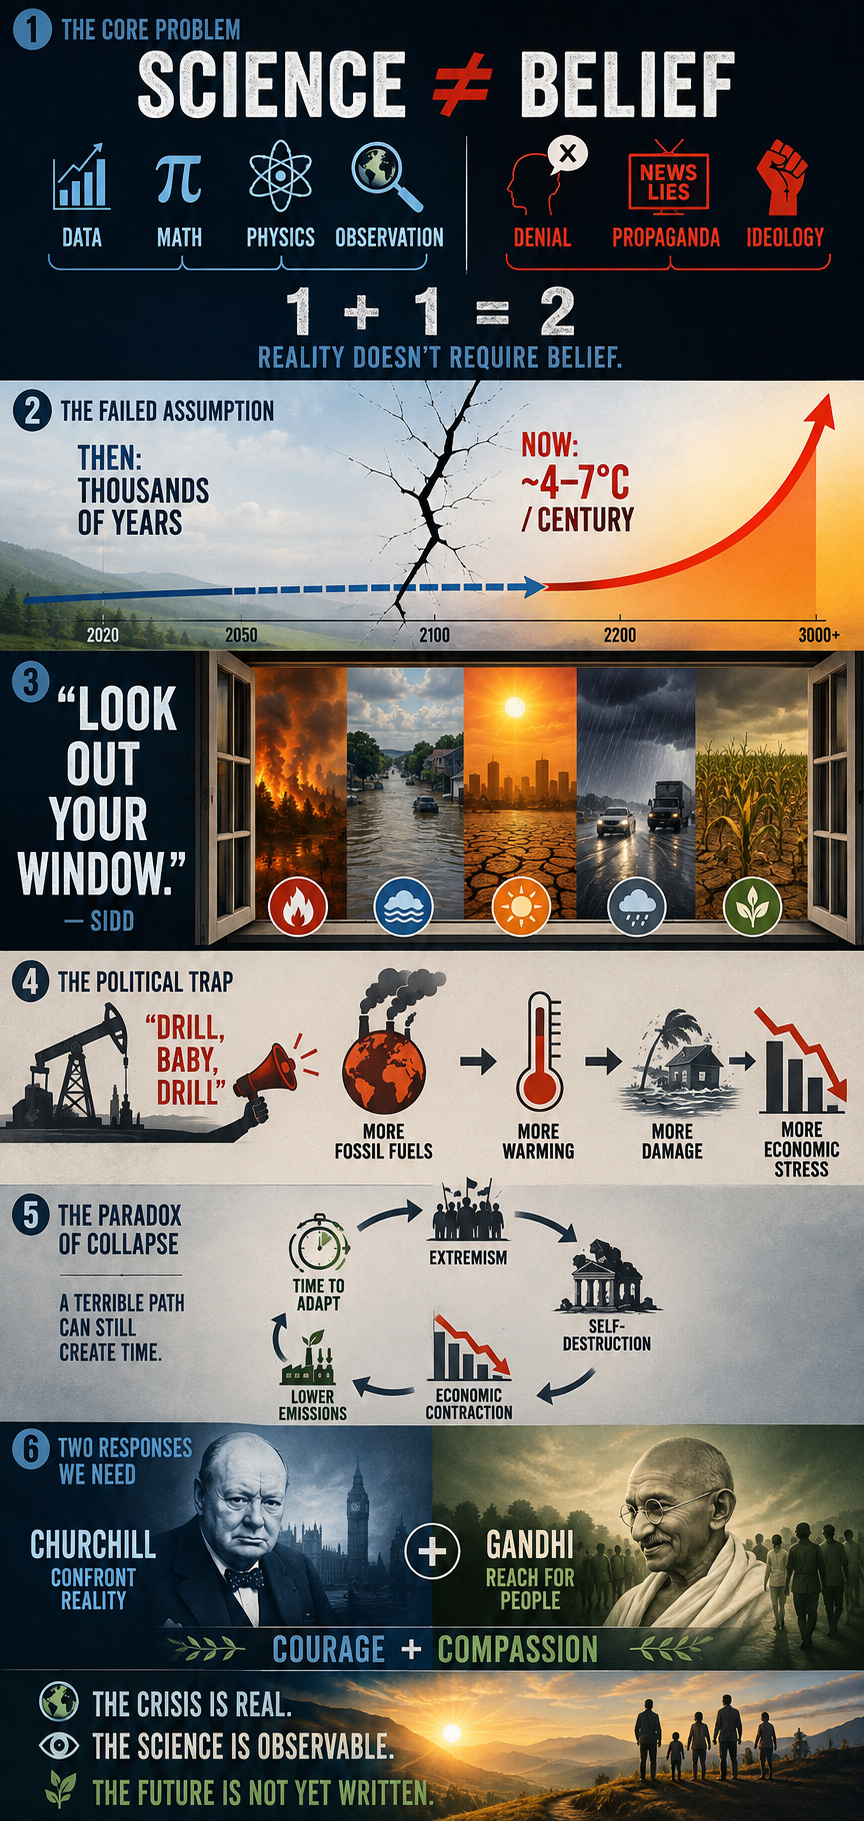
I’ve spent years battling misinformation, propaganda, and rhetoric. To the best of my knowledge, neither Sidd nor I have successfully converted—or even educated—a single committed denier. Climate science has somehow been transformed into a “belief” system. But science has nothing to do with belief. 1 + 1 = 2. If someone refuses to “believe” that, what exactly can you do?
From the beginning, our work has been based on observations, data, mathematics, and the laws of physics. So yes, I think this is at the heart of the crisis. When we started this work, we genuinely believed humanity would eventually take action. We thought we had thousands, if not tens of thousands, of years to adapt. That was the one thing we got wrong.
A couple of years ago, after explaining my continuing attempts to reach climate deniers, I asked Sidd what we could possibly do. His response was essentially, “Dude, just tell them to look out their window.” It sounds simplistic, but there is profound truth in it. The consequences are becoming increasingly difficult to deny.
Since then, we’ve had to rebuild much of our modeling. A +4°C world within thousands of years is no longer the worst-case scenario we worry about. The possibility of 4–7°C of warming within a century has become a much more serious concern in our work.
And then there is the political dimension. The rise of white-nationalist and authoritarian governments in the U.S. and elsewhere has made an already difficult problem considerably harder. Paradoxically, though, history offers one small reason for hope: fascism ultimately fails. It is inherently self-destructive.
The “drill, baby, drill” mentality is economically and environmentally self-defeating. A severe economic contraction could, ironically, buy humanity some time for adaptation while drastically reducing emissions. That is hardly the future anyone should want, but history has repeatedly demonstrated that systems built on extremism and authoritarianism eventually consume themselves.
So yes—we desperately need both the Churchill and Gandhi dimensions: the willingness to confront reality without flinching, and the willingness to keep reaching for people rather than giving up on them. I’m just not sure humanity has ever faced a crisis where we needed both quite this badly.
Sidd said: “frightening article by Jeff Masters. We saw some of this coming, the flood risk aint just along the coast, it extends 100 miles inland… the water cant get out …”
In the 1990s, Sidd and I began developing real-estate-based climate risk models. From the beginning, one of the underlying high-risk factors was flooding—and, closely linked to it, the availability and affordability of flood insurance. In the early 2000s, we met with FEMA, Fannie Mae (FNMA), and Freddie Mac (FHLMC) to better understand their flood-risk modeling and emerging plans for managed retreat.
In October 2023, Sidd observed: “Now I am thinking the violent rain will be a bigger problem before we die.”
That concern has become increasingly relevant. As the Earth warms, warmer air can physically hold more water vapor than cooler air. For every 1°C (1.8°F) increase in temperature, the atmosphere can hold approximately 7% more moisture, increasing the potential for extreme precipitation. Over a 10°C increase, atmospheric moisture-holding capacity would nearly double, creating the potential for substantially more intense rainfall.
The problem, however, is not simply the amount of water falling from the sky. It is also what happens when that water moves across the landscape—and whether infrastructure and government response systems are capable of managing, containing, and recovering from the resulting flows.
Flow forces scale with the square of velocity (v²). As flow speeds increase—whether from heavier rainfall, steeper runoff, or more intense hydrological events—the destructive force of moving water rises rapidly. Density further magnifies this effect. Water is roughly 800 times denser than air, meaning that a comparable flow velocity can produce dramatically greater force.
Together, we developed a series of models incorporating the Clausius–Clapeyron relationship, the extreme energy transfer within the water cycle through latent heat, and fluid-flow dynamics. These models increasingly pointed toward a risk structure in which flooding could no longer be treated as an isolated coastal problem. Instead, precipitation intensity, runoff, topography, infrastructure vulnerability, insurance stress, and limited recovery capacity can interact and compound one another across much larger regions.
By 2026, the framework had evolved from a theoretical real-estate climate-risk model into a broader multiplicative risk framework that could be evaluated against observed real-world conditions.
The latest evolution of this work is presented in the following three papers: