bookmark_borderThe Demise of the Dollar and U.S. Exceptionalism

by Daniel Brouse
April 13, 2025

Economic Collapse Ends the Era of Mass Consumption, Capitalism, and Fossil Fuel Dependence

In 2017 and 2018, many economists warned of rising inflation and interest rates due to Donald Trump’s economic, environmental, and social policies — warnings that were largely dismissed at the time. Few believed the U.S. dollar, the linchpin of global finance, could lose its status as the world’s reserve currency. That confidence, once deeply rooted in the strength of U.S. institutions and global leadership, is now unraveling.

Trump’s Debt-Driven Economics: A Personal Philosophy Gone National

In office, Donald Trump mirrored his personal business model on a national scale: borrow excessively and sidestep repayment. Having declared bankruptcy over six times, Trump’s track record raised serious concerns about his approach to fiscal responsibility. That approach translated into:

  • Massive tax cuts without corresponding spending reductions.

  • Explosive deficit growth, pushing the national debt beyond the size of the U.S. economy.

  • Crowding out private investment as government borrowing soared, pushing up interest rates.

The result was an era of artificially inflated growth fueled by unsustainable debt and reckless financial policies.

Weakening the Dollar: Trade Wars and Protectionist Failures

Trump’s “Make America Great Again” agenda, anchored in economic nationalism, inflicted direct damage on the U.S. dollar’s global standing. His administration’s use of tariffs, trade barriers, and unilateral withdrawal from international agreements led to:

  • Erosion of trust in the U.S. as a stable trading partner.

  • Increased costs for imported goods, contributing to persistent inflation.

  • Undermining the predictability and liquidity of global trade, which the U.S. dollar heavily relies upon.

A reserve currency depends not only on economic strength but on political stability, institutional reliability, and global trust. Trump’s policies weakened all three pillars.

When Trade War Meets Credit War

What was once a hypothetical scenario — simultaneous trade and credit wars — has become reality in Trump’s second term.

In Trump 1.0, the groundwork was laid: shredding trade agreements, attacking global institutions, and retreating from multilateral leadership. In Trump 2.0, that playbook has scaled up into a full-blown economic experiment.

This time, the effects are no longer speculative. They are materializing in real time.

Tariffs are not just taxes on goods. They are also blows to global liquidity and trust. Countries that earn fewer dollars from exports to the U.S. have fewer dollars to invest back into U.S. Treasuries and assets. That’s how a trade war becomes a credit war.

Early Warning Signs of Systemic Breakdown

The early tremors of this dual war are already visible:

  • Bond market liquidity is vanishing as fewer international buyers participate.

  • Foreign demand for U.S. Treasuries is declining, despite rising yields.

  • Global central banks are diversifying reserves away from the dollar.

  • Gold, commodities, and non-dollar assets are surging as safe havens.

  • Interest rates are climbing, not because of growth, but because of risk.

This creates a dangerous feedback loop: less trade, fewer dollars abroad, reduced Treasury demand, higher U.S. borrowing costs, and ultimately tighter credit across the economy.

Collateral Damage: The U.S. Housing Market and Mortgage-Backed Securities

Trump’s policies are also destabilizing a once-resilient cornerstone of the U.S. financial system: the mortgage-backed securities (MBS) market.

As foreign central banks accumulate fewer dollars, their purchases of U.S. MBS and Treasuries decline. This reduces liquidity and drives up borrowing costs for American households.

Simultaneously, domestic strain is rising. FHA mortgage delinquencies have reached 11%, and investors in the secondary mortgage market are offloading debt at 5–10% discounts to raise cash—signaling a broader crisis of confidence.

The Unsustainable Status Quo: Debt, Decline, and Desperation

The U.S. government’s rising debt, coupled with shrinking foreign capital inflows, will make refinancing more difficult. As a result, the U.S. may be forced to do something it hasn’t done in nearly a century: balance its budget.

That prospect threatens to upend decades of U.S. economic expansion. It could lead to:

  • A collapse in the standard of living.

  • Reduced life expectancy as healthcare, infrastructure, and social services are gutted.

  • Exploding property taxes and insurance costs, with annual increases potentially exceeding 100% in a high-inflation environment.

With few tools left, the U.S. could resort to the nuclear option: hyperinflation. Turning trillions of dollars in debt into billions via inflation would devastate consumers, retirees, and anyone on a fixed income. It would also destroy the credibility of the dollar.

A Pyrrhic Victory? The Painful Path to Environmental Sustainability

Ironically, there may be a sliver of hope in this economic unraveling. If Trump’s economic collapse ends the era of mass consumption, over-leveraged capitalism, and fossil fuel dependence, it could reduce global emissions and slow the pace of climate change.

A forced degrowth scenario—where economic contraction leads to lower carbon output—might offer the time humanity needs to adapt, innovate, and survive. But it would come at enormous cost: to livelihoods, stability, and America’s global role.

Conclusion: Exceptionalism Undone

The U.S. dollar’s fall from dominance, combined with unprecedented political and fiscal recklessness, is dismantling the illusion of American exceptionalism. Once the anchor of global finance, the U.S. is now showing signs of becoming a net liability to the world economy.

The question is no longer whether the dollar can fall—but whether it can be saved. And if it cannot, what comes next for a nation built on the myth of infinite credit, endless growth, and unquestioned supremacy?

* WARNING * — Our updated climate model, now integrating complex social-ecological factors as part of a dynamic and non-linear system, shows that global temperatures could rise by up to 9°C within this century — far beyond previous predictions of a 4°C rise over the next thousand years. This level of warming will render much of the world uninhabitable within this century.

Climate Collapse Will Break Capitalism

The Destructive Legacy of Trump’s Climate and Economic Policies

Trumpenomics: The Decline of the US

State of the Climate Crisis 2025
 

bookmark_borderDollar Outflows, Fed Policy, and Foreign Mortgage Holdings Amid Economic Strain

by Daniel Brouse
April 13, 2025

Over the past three months, global capital flows, Federal Reserve policy, and the health of U.S. mortgage-backed securities have each come under renewed pressure as economic uncertainty deepens. The confluence of a weakening dollar, rising international disinvestment, and domestic credit strains is redefining the outlook for U.S. financial stability. This article examines three interrelated developments shaping the current landscape: the movement of cash out of dollar-denominated assets, the Federal Reserve’s role in currency and credit stabilization, and the evolving status of U.S. mortgage debt in foreign portfolios.

I. Capital Flight from the Dollar: A Three-Month Trend

In recent months, capital has been steadily flowing out of U.S. dollar-denominated assets into foreign currencies and non-dollar investment vehicles. This shift has accelerated due to waning investor confidence in U.S. fiscal discipline and monetary policy, compounded by a volatile geopolitical environment.

As of early April 2025:

  • The U.S. Dollar Index dropped below 100 for the first time since July 2023, down 2.7% in just one week and 7.6% year-to-date.

  • In January 2025, net capital outflows from the U.S. reached $48.8 billion, reversing inflows seen in late 2024.

  • The euro and Canadian dollar gained notable strength, with repatriation flows and currency hedging strategies pushing the loonie to a four-month high.

Simultaneously, central banks have continued diversifying their reserves:

  • The U.S. dollar’s share of global foreign exchange reserves has fallen to 57.4%, its lowest level since 1994, with increased holdings in euros, yuan, and gold.

These movements reflect broader skepticism toward U.S. fiscal direction and a growing appetite for global alternatives that offer more stable returns or diversified geopolitical exposure.

II. The Federal Reserve’s Response: Balance Sheet Maneuvers and Liquidity Safeguards

In an effort to manage the dollar’s decline and stabilize financial conditions, the Federal Reserve has taken several notable steps. Although it has not directly intervened in foreign exchange markets, its recent balance sheet and interest rate decisions indicate a shift toward cautious support for dollar stability.

In March 2025, the Fed announced it would:

  • Reduce the pace of its balance sheet runoff, decreasing the monthly cap on Treasury redemptions from $25 billion to just $5 billion starting in April.

  • Maintain the cap on agency debt and mortgage-backed securities at $35 billion, with excess payments being reinvested in Treasurys.

  • Hold interest rates steady at 4.25% to 4.5%, while continuing to offer overnight repurchase operations to preserve liquidity with a $500 billion ceiling.

These measures aim to preserve Treasury market liquidity while ensuring the financial system remains well-functioning amid deteriorating external confidence. However, the Fed’s efforts are complicated by inflationary pressures tied to trade policies and ongoing credit tightening.

III. Foreign Holdings of U.S. Mortgage Debt and the Strain on the Secondary Market

Another fault line is emerging in the mortgage finance sector, where both international and domestic stressors are reshaping the market.

As of mid-2024:

  • Foreign investors held roughly $1.635 trillion in U.S. asset-backed securities (ABS), including mortgage-backed securities (MBS).

  • This represents 12.6% of the $12.982 trillion in long-term U.S. debt securities held abroad.

  • Major foreign holders of U.S. MBS include Japan ($253 billion), Canada ($190 billion), and the Cayman Islands ($107 billion).

Recent months have seen rising unease in the secondary mortgage market. The credit tightening cycle, paired with new tariffs and trade-related uncertainty, has made private credit assets—including MBS—less liquid and more volatile:

  • Investors are increasingly selling private credit and MBS in the secondary market at 5–10% discounts below par to raise cash.

  • Mortgage delinquencies among FHA borrowers have surged to 11%, underscoring the financial vulnerability of lower-income households.

These developments suggest that foreign investors are not only rebalancing away from U.S. government debt but also reassessing their exposure to U.S. housing-linked assets, which are increasingly seen as high-risk due to domestic economic fragility and policy unpredictability.

Conclusion: A System Under Strain

Taken together, the weakening of the dollar, strategic shifts in Federal Reserve policy, and erosion of investor confidence in U.S. mortgage debt paint a picture of an economic system under significant strain. As trade and credit tensions continue to weigh on global sentiment, the U.S. financial system faces growing pressure from both external capital flight and internal market stress. In this environment, maintaining liquidity, credibility, and policy coherence will be essential for preventing further destabilization of core financial markets.

Capital Preservation During Trumpenomics

The Inevitable Collapse: How Trump’s Policies and Climate Neglect Will Reshape the Economy

Trumpenomics: The Decline of the US

bookmark_borderThe Race Against Time: Climate Crisis vs. the United States

by Daniel Brouse
April 12, 2025

Abstract
Humanity stands at a historic crossroads where the accelerating pace of climate change threatens to overtake both our capacity for response and the viability of the global economic system itself. Recent models indicate that without immediate intervention, climate change could cause the collapse of capitalism as we know it—potentially as soon as 2050. At the same time, U.S. political developments—particularly Trump-era trade, fiscal, and environmental policies—may unintentionally hasten this collapse. The central question becomes: Will the U.S. economic system implode before climate change forces its hand, or has irreversible damage already been done?

I. Climate Change: From Hypothesis to Imminent Catastrophe

In the 1990s, we proposed a hypothesis: that climate change would not follow a linear trajectory but would instead accelerate non-linearly—driven by feedback loops such as polar ice melt, permafrost thaw, ocean acidification, and carbon release from soil and forests. Over the following decades, this hypothesis evolved into an established scientific theory, now widely accepted by the international scientific community.

Through collaboration with a physicist from Ohio State University, we observed a startling trend in the “doubling time” of climate impacts. Originally pegged at around 100 years, this timeframe has since shrunk to 10 years, and now—alarmingly—approaches just 2. That means climate-related damages could be 64 times worse a decade from now than they are today. These aren’t worst-case scenarios; they are conservative models assuming no further acceleration.

Our latest models integrate not only geophysical systems but also social, political, and economic feedback loops. The results are grim: we now forecast a potential 9°C rise in global temperatures within this century—a rate that would make much of the planet uninhabitable and render large-scale human migration and system failure unavoidable.

II. A New Threat Emerges: Trumpenomics and the War on Global Stability

Ironically, the Trump administration—through its aggressive trade, credit, and isolationist policies—has accelerated the very breakdown of capitalism that climate change is expected to cause.

The imposition of widespread tariffs, especially those based on falsified “reciprocal” trade deficits, has triggered not just a trade war, but a credit war. This combination has never before been tested in modern economic history. During Trump’s first term, the stage was set. Now, in his second term, the global economy is being subjected to a real-time, uncontrolled experiment.

The administration’s “drill, baby, drill” energy policy, paired with unprecedented regulatory rollbacks, has only deepened the climate crisis. Yet, from an economic systems perspective, it is the trade and credit dislocations that may deliver the first major blow.

III. Global Trade, Capital Flows, and the Liquidity Death Spiral

Most people think of tariffs as mere taxes on goods. But in today’s complex financial system, their impact extends far beyond the shipping yard.

When the U.S. imports less, foreign exporters earn fewer dollars. This reduces their ability to invest in U.S. Treasuries—the bedrock of the global financial system. As demand for Treasuries falls, yields rise, borrowing costs spike, and credit conditions tighten. This sets off a self-reinforcing liquidity crisis, undermining everything from consumer lending to corporate investment.

The risk is real and growing: a scenario where the U.S. dollar loses its global reserve status is no longer the stuff of academic theory. Should this occur, the fallout would include:

  • Exploding U.S. borrowing costs

  • A collapse in consumer purchasing power

  • Capital flight from U.S. markets

  • Severe contraction in both trade and credit

  • Domestic political and social unrest on a scale not seen in modern history

IV. The Tipping Point: Will Climate Collapse or Economic Collapse Win the Race?

The economic trajectory of the U.S. under Trump’s policies suggests that a post-capitalist transition may be triggered by domestic fiscal instability rather than climate catastrophe alone. In other words, the United States may be the first nation to economically implode under the dual weight of environmental and self-inflicted economic collapse.

Complicating matters, the U.S. is simultaneously dealing with aging infrastructure, mounting national debt, deteriorating public health, climate-related disasters, and rising political extremism—all of which erode resilience and reduce the chances of a coordinated national response.

This raises a chilling question: Will the collapse of the U.S. economy accelerate faster than climate change itself—or are we already too late to avoid either fate?

The U.S. dollar’s decline from global dominance — driven by unprecedented political dysfunction and fiscal recklessness — is unraveling the myth of American exceptionalism. Once the cornerstone of international finance, the United States now risks becoming a net liability to the world economy. Paradoxically, this economic unraveling may carry a sliver of hope. If Trump’s economic collapse marks the end of mass consumption, over-leveraged capitalism, and fossil fuel dependency, it could trigger a sharp drop in global emissions and slow the pace of climate change. Such a forced degrowth scenario–where contraction curbs carbon output–might buy humanity precious time to adapt, innovate, and survive. But this path would come at a steep cost: to livelihoods, political stability, and America’s standing in the world.

Conclusion: What Comes After?

Regardless of which crisis arrives first, one outcome is increasingly likely: the U.S. standard of living will fall sharply, and life expectancy may follow. Whether that post-collapse society can still be sustainable—or even enjoyable—will depend on the decisions we make in the next few years.

Our only hope is to treat this as a true “race against time” and respond with urgency, humility, and collective will. The future depends not just on science and economics, but on whether we can choose survival over ideology, cooperation over conflict, and truth over convenience.

The Human Induced Climate Change Experiment

bookmark_borderWhen Hypothesis Becomes Theory: Trump’s Trade War Has Triggered a Global Credit War

by Daniel Brouse
April 11, 2025

For decades, economists have quietly asked a disturbing hypothetical: What happens if the U.S. launches a trade war and a credit war at the same time? It was an academic curiosity — a thought experiment for textbooks, not real life. Until now.

Donald Trump has turned that hypothesis into reality.

During Trump’s first term (Trump 1.0), he laid the groundwork — tearing up trade agreements, undermining global institutions, and threatening America’s economic alliances. But now, in Trump 2.0, he’s gone from testing the waters to executing a full-scale economic experiment on a global stage.

What was once theory is now practice. And the world is starting to buckle under the strain.

Trade War Meets Credit War: A Dangerous Combination

Most people think of tariffs as isolated tools — a tax on imported goods here, a protectionist policy there. But in a global economy powered by complex capital flows, the consequences are far more sweeping. Tariffs don’t just hit goods — they hit trust, stability, and most importantly: liquidity.

By weaponizing trade, Trump has triggered a second, even more dangerous war: a global credit war.

Here’s why that matters.

The U.S. dollar has long been the world’s reserve currency because global trade flows through it. Countries that export goods to the U.S. accumulate dollars — and those dollars flow right back into U.S. assets like Treasury bonds. That system keeps interest rates low, funds U.S. debt, and stabilizes the global economy.

But what happens when that trade flow is deliberately choked off?

The Early Signs of System Failure

If foreign countries export less to the U.S., they earn fewer dollars. If they have fewer dollars, they buy fewer U.S. Treasuries. And if they buy fewer Treasuries, U.S. borrowing costs go up — triggering higher interest rates, tighter credit, and financial instability.

This is not just a theoretical concern anymore. We are seeing early evidence that this credit war is underway:

  • Bond market liquidity is evaporating.

  • Foreign demand for U.S. Treasuries is declining.

  • Global central banks are diversifying away from the dollar.

  • Gold, commodities, and non-dollar assets are surging.

  • Interest rates are rising — not because of growth, but because of risk.

Chaos Theory in Action

This is a classic example of a complex, non-linear dynamic system at work — the domain of chaos theory. The parts are all connected, but not in simple, linear ways. A shock in one area — tariffs — is now producing unpredictable disruptions in areas that may seem unrelated but are fundamentally tied together.

The variables in this system include:

  • The value of the U.S. dollar

  • U.S. debt and Treasury markets

  • Interest rates (both domestic and global)

  • Inflation and deflation pressures

  • Recession — or worse, depression

  • Foreign cash flows and investment patterns

  • Trade wars and their escalation

  • Climate disasters exacerbating supply shocks

  • Immigration pressures triggered by economic collapse

The Big Question: What If the Dollar Loses Its Reserve Status?

Ultimately, the darkest scenario is no longer unthinkable: What happens if the U.S. dollar loses its status as the world’s reserve currency?

This would unleash a profound economic reset, marked by:

  • Exploding U.S. borrowing costs

  • A collapse in consumer purchasing power

  • Global capital flight from U.S. assets

  • Severe contraction in both trade and credit

  • Domestic political and economic instability unlike anything in modern history

Conclusion: We Are In the Experiment Now

This is no longer just economic theory.

This is real.

Trump’s trade war has metastasized into a global credit war. The feedback loops are forming. The shocks are compounding. And the system is starting to behave exactly as economists long feared: chaotically, violently, and unpredictably.

Welcome to the experiment. We’re all in it now. The only question left is whether the damage is reversible — or if we’ve already crossed the tipping point.

Capital Preservation During Trumpenomics

The Inevitable Collapse: How Trump’s Policies and Climate Neglect Will Reshape the Economy

Trumpenomics: The Decline of the US

bookmark_borderClimate Collapse Will Break Capitalism

by Daniel Brouse
April 11, 2025

As extreme weather accelerates, the world is nearing a tipping point where insurance — and capitalism itself — can no longer function.

The climate crisis is on track to destabilize and ultimately destroy global capitalism, according to a stark warning from one of the world’s largest insurers. Allianz SE board member Günther Thallinger has sounded the alarm: the growing cost of climate-driven disasters threatens to break the financial sector’s ability to operate — starting with insurance.

Speaking as both a top executive of Allianz and chair of its investment board, Thallinger said the world is fast approaching temperature thresholds beyond which many climate risks will simply become uninsurable. And without insurance, critical sectors of modern finance — from mortgages and real estate to infrastructure and industry — will cease to function.

“Heat and water destroy capital,” Thallinger wrote in a widely discussed LinkedIn post. “Flooded homes lose value. Overheated cities become uninhabitable. Entire asset classes are degrading in real time.”

A Financial System on the Brink

Current government policies still allow global carbon emissions to rise, putting the world on track for a temperature increase between 2.2°C and 3.4°C above pre-industrial levels. The damage expected at 3°C is so severe, Thallinger warned, that it will overwhelm governments’ ability to provide financial relief or adaptation measures.

Already, the scale of climate-related damage is staggering. Insurance company Aviva estimated that extreme weather caused $2 trillion in damages globally between 2013 and 2023. In 2024 alone, GallagherRE reported climate losses of $400 billion. Insurers like Zurich have declared it “essential” to reach net-zero emissions by 2050 to avoid systemic collapse.

But Thallinger warns that time is running out — and that the breakdown is already underway. In parts of California, for example, insurers have stopped covering homes due to escalating wildfire risks. Entire regions, he said, are becoming “uninsurable.”

The Math No Longer Works

“As temperatures rise to 1.5°C, 2°C, 3°C, insurers will no longer be able to offer coverage for many of these risks,” Thallinger said. “The math breaks down: the premiums required exceed what people or companies can pay. This is already happening.”

Our updated climate model, now integrating complex social-ecological factors as part of a dynamic and non-linear system, shows that global temperatures could rise by up to 9°C within this century—far beyond previous predictions of a 4°C rise over the next thousand years. This level of warming will render much of the world uninhabitable within this century.

Without insurance, the ripple effects spread rapidly through the financial system. Mortgages, infrastructure investment, agriculture, and transportation all rely on insurance to manage risk. Remove that foundation, and the global credit system starts to seize up — a “climate-induced credit crunch.”

“This is a systemic risk threatening the very foundation of the financial sector,” Thallinger warned.

Nick Robins, chair of the Just Transition Finance Lab at the London School of Economics, called the analysis “devastating,” adding that it highlights not only a financial crisis but a civilizational one.

The End of Adaptation Myths

Thallinger also pushed back on the comforting narrative that humanity can simply adapt its way through climate breakdown.

“There is no way to ‘adapt’ to temperatures beyond human tolerance,” he wrote. “Whole cities built on flood plains cannot simply pick up and move uphill.”

Australia’s disaster recovery spending has already increased sevenfold between 2017 and 2023. No government, Thallinger argued, will be able to cover the cost when multiple extreme events strike in rapid succession — something climate models increasingly predict.

At 3°C, Capitalism Fails

At 3°C of warming, the damage becomes uninsurable, governments become financially crippled, and adaptation becomes largely impossible.

“That means no more mortgages, no new real estate development, no long-term investment, no financial stability,” Thallinger concluded. “The financial sector as we know it ceases to function. And with it, capitalism as we know it ceases to be viable.”

The Solution? Urgent, Global Decarbonization

The only solution, Thallinger said, is to end fossil fuel burning at unprecedented speed and scale. Everything else — delay, half-measures, false comforts — will only hasten systemic collapse.

“The good news is we already have the technologies to switch from fossil combustion to zero-emission energy,” he said. “The only thing missing is speed and scale. This is about saving the conditions under which markets, finance, and civilization itself can continue to operate.”

Or, as Janos Pasztor, former UN assistant secretary-general for climate change, put it: “The insurance sector is a canary in the coal mine when it comes to climate impacts.”

This canary is no longer just singing — it’s screaming.

The Human Induced Climate Change Experiment

bookmark_borderThe Economic Reality Behind the Tariff ‘Pause’: A 35% Tariff Rate

by Daniel Brouse
April 10, 2025

On April 9, economists were left scratching their heads, wondering why anyone believed that the announcement of a “PAUSE” on tariffs would have any meaningful impact on the economy. It was a classic case of wishful thinking, with little grounding in the hard numbers that define economic reality. By April 10, as the smoke cleared, it became increasingly clear that the “pause” was more of a symbolic gesture than a substantive shift in trade policy.

A closer look at the numbers reveals the magnitude of the tariff situation. When we break it down, the initial tariff rate on imports stood at around 3%. However, the story changes dramatically on what is known as “Liberation Day,” when the effective tariff rate spiked to a staggering 40%. This isn’t a typo — it was a significant jump, and it marked a crucial point in the broader context of global trade.

On April 9, the effective tariff rate without factoring in China, the United States’ largest trading partner, shifted to 18%. This rate was still the highest we’ve seen since the 1940s. While this sounds like a notable shift, it doesn’t fully capture the broader impact. When we include China in the equation, the story takes an even more dramatic turn. The total effective tariff rate, including both the general tariffs and consumption taxes on Chinese imports, skyrocketed to a range of 30-35%. This figure is nothing short of unprecedented, making it the highest effective tariff rate in U.S. history.

The implications of these numbers are far-reaching. For one, a tariff rate that high can have serious consequences for both consumers and businesses, leading to higher costs for imported goods and potentially stifling economic growth. A “pause” on tariffs might sound like a step toward easing trade tensions, but in reality, it does little to reverse the long-term economic pressures already set in motion.

So, while the announcement of a tariff “pause” may have been met with some optimism, the underlying reality is that U.S. tariffs are at historically high levels, and the true impact of these policies is just beginning to unfold. For economists and policymakers alike, it’s crucial to move beyond superficial gestures and focus on the hard economic data that tells the real story of America’s trade situation.

Trumpenomics: The Decline of the US

bookmark_borderWall Street: When First is Last

by Daniel Brouse
April 10, 2025

How Some of the Biggest Market Gains Are Actually Signs of the Worst Losses

Those who appeared to be first, ended up last. Those who appeared to be last, ended up first.

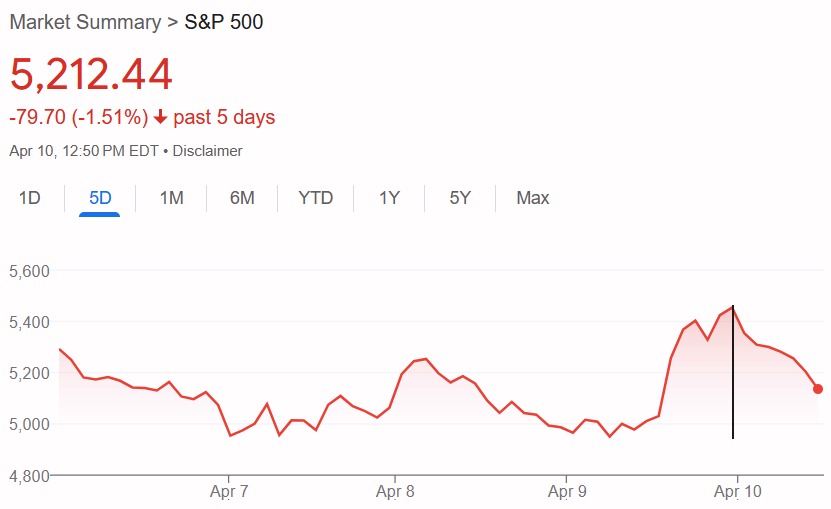
April 9 wasn’t just another volatile day on Wall Street — it was a near-perfect example of how markets behave during a crash, and why some of the biggest one-day rallies in history often happen inside brutal bear markets.

It’s one of the great paradoxes of investing:

The biggest up-days don’t mean recovery — they often signal panic, forced liquidation, and deeper instability ahead.

What Actually Happened?

In essence, the trillions of dollars that appeared to be gains in the market were really losses for short sellers. That’s the hidden truth of sharp rallies during a crash — the money didn’t come from real investment demand; it came from forced buying.

The key difference is this: when markets rise under normal conditions, long-term investors have unrealized gains — profits on paper, but not yet cashed out. But in a short squeeze, those unrealized gains for stockholders are directly matched by realized losses for short sellers who are forced to buy at any price to cover their positions.

It’s not wealth creation — it’s wealth transfer under pressure. In the chaos of a market crash, those who looked like winners became losers — and those who looked like losers became winners.

Short Sellers Help Stabilize the Stock Market

The Mechanics

Markets spiked sharply after a sudden and dramatic policy reversal was announced — a move investors hoped might slow down the economic freefall.

But here’s the key:
This initial surge wasn’t organic buying. It was mechanical.

→ Short sellers — traders betting against the market — suddenly got squeezed.
→ When prices jump too fast, short sellers face margin calls — demands from brokers to put up more money or buy back the stock they bet against.
→ Since short-selling carries unlimited loss potential, these traders are forced to buy shares no matter the price to avoid catastrophic losses.

That panic buying drives prices even higher, triggering more margin calls in a dangerous feedback loop.

Why Does This Matter?

Because once those short positions are closed (covered), the artificial buying pressure evaporates.

And here’s the brutal part:
→ Many of those same shares bought in a panic are quickly sold again by longer-term bearish investors or funds desperate to raise cash.

That’s what you saw today — the so-called “pullback” was not just natural volatility; it was the aftershock of forced buying unwinding itself.

Markets gave back much of yesterday’s gains. And worse, they are now at risk of retesting — or breaking — the recent lows.

The Illusion of Safety

In chaotic markets like this, price action becomes non-linear and unpredictable.

Massive rallies during a downturn are not necessarily signs of strength — they are often signs of extreme stress within the system.

This is why some of the biggest single-day gains in market history occurred during the Great Depression, the 2008 Financial Crisis, and the early phases of COVID’s market panic.

It’s not recovery.
It’s chaos.

Why Crashes Look Like This: Forced Buyers Meet Forced Sellers

Several key forces converge during these phases:

  • Short-sellers covering in panic.

  • Margin calls across hedge funds and leveraged traders.

  • Index funds and mutual funds, required to stay fully invested, reluctantly buying dips.

  • Passive investing structures amplifying volatility both directions.

  • Algorithmic trading chasing momentum.

These dynamics create a dangerous loop:
→ Sharp rallies from forced buying.
→ Followed by brutal reversals from forced selling.

The result?
A jagged, chaotic pattern — not a smooth decline.

And the Most Important Lesson:

In a true crash, there is no guaranteed floor.

Support levels only exist until panic overwhelms them. Fundamentals don’t matter when liquidity disappears.

Markets become driven by positioning, margin calls, and liquidity — not valuation.

This is why the old phrase still applies:
“Bear market rallies are designed to fool the maximum number of people in the minimum amount of time.”

Closing Thought:

The real danger today isn’t just volatility — it’s the fact that this is largely self-inflicted economic destruction.

Policy mistakes — from trade wars to immigration freezes to climate inaction to protectionist tariffs — have combined into a global slowdown unlike anything since the Great Depression.

And unlike past crashes, there is a real risk this time that the damage is structural — not cyclical.

Recovery is not guaranteed.

One-Week Chart Highlighting Record One-Day Spike

Trumpenomics: The Decline of the US

bookmark_borderCredit War!

by Daniel Brouse
April 9, 2025

Trump’s fixation on the 10-year Treasury bond comes down to a perfect storm of contradictions — and desperation. Here’s why it matters:

  1. He promised lower interest rates but has no real ability to deliver them.

  2. He can’t control interest rates — the market does.

  3. His budgets don’t work with elevated rates — every tick higher adds billions (or even trillions) to the national debt through higher borrowing costs.

  4. Higher interest rates, combined with a weakening dollar, fuel persistent inflation — creating a vicious feedback loop of rising prices and rising rates.

  5. Foreign countries — especially Japan and China — hold massive amounts of U.S. Treasuries. The overnight spike in bond yields started in Asian markets, signaling not just a financial crisis, but the possibility of a global credit war layered on top of the existing trade war.

Bottom line: The 10-year bond rate isn’t just a financial number — it’s a pressure gauge on Trump’s entire economic strategy. And right now, that gauge is flashing red — Credit War!

Ironically, this would be a completely self-inflicted credit war. By wrongly insisting that trade deficits are somehow tied to national budget deficits and debt, Trump is essentially forcing foreign countries to accept fewer U.S. dollars through reduced trade. And when those countries accumulate fewer dollars, they naturally invest less in U.S. assets — especially safe-haven investments like Treasuries. Less demand for Treasuries means higher interest rates, weaker credit strength, and greater financial instability — all triggered by a fundamental misunderstanding of how global trade and capital flows actually work.

April 10 State of the Economic Union: Still Horrible


Trumpenomics: The Decline of the US

bookmark_borderTariff Turmoil: The Chaos and Confusion Surrounding U.S. Trade Policies in 2025

by Daniel Brouse
April 9, 2025

From Sector-Specific Levies to Unpredictable Pauses, Determining What Tariffs Remain in Effect Has Never Been More Complex

In a stunning reversal, the Trump administration just announced a 90-day pause on its controversial reciprocal tariffs policy — a clear sign that recent market chaos is starting to bite. With a record spike in interest rates overnight and global investors fleeing U.S. debt, the pause appears to be a desperate attempt to calm financial markets rattled by the escalating trade war.
For months, Trump’s tariff strategy has been framed as strength — but today’s move signals growing recognition that aggressive trade policies are now directly threatening U.S. economic stability. The world is no longer automatically turning to U.S. Treasuries in a crisis, and investors are demanding higher rates to hold American debt — a dangerous shift for the global economy.
While the pause buys time, it underscores a bigger problem: trust, once lost in global markets, is hard to recover.

Current Situation
As of April 9, 2025, the United States has implemented a series of tariffs under President Trump’s “reciprocal tariff” policy. Initially, a universal 10% tariff on all imports was set to take effect on April 5, 2025. However, on April 9, 2025, President Trump announced a 90-day pause on tariffs for over 75 countries that opted to negotiate rather than impose retaliatory measures.

Despite this pause, tariffs remain in effect for certain countries, most notably China. The tariffs on Chinese imports have been increased to a total of 145%, escalating the U.S.-China trade conflict.

The situation is dynamic, with ongoing negotiations and potential policy adjustments. For the most accurate and current information, it is advisable to consult official communications from the U.S. Trade Representative or the White House.

There are still significant tariff measures affecting imports from various countries and specific sectors; however, it is not at all transparent as to the actual law. Following is our best guess:

1. Canada and Mexico Tariffs:

  • 25% Tariff on Non-USMCA-Compliant Goods: On March 4, 2025, the U.S. imposed a 25% tariff on imports from Canada and Mexico that do not meet United States-Mexico-Canada Agreement (USMCA) standards.

  • Energy Imports: Canadian energy resources are subject to a reduced tariff of 10%, as per the adjustments made on March 4, 2025.

  • Reciprocal Tariffs: In response, Canada has imposed a 25% tariff on U.S. vehicle imports that do not meet USMCA standards.

2. Sector-Specific Tariffs:

  • Steel and Aluminum: Effective March 12, 2025, a 25% tariff was applied to imports of steel and aluminum articles, as well as certain derivative products, from all countries.

  • Energy Sector: While specific details on energy-related tariffs are limited, the White House has indicated that energy imports may be subject to new tariffs to promote domestic production.

  • Lumber: Lumber imports are among the sectors that could face new tariffs, as the administration has warned of potential measures to support domestic industries. ​

3. Tariff Status and Exemptions:

  • USMCA-Compliant Goods: Products that comply with USMCA standards are exempt from certain tariffs, including those on vehicles and specific goods from Canada and Mexico.

  • De Minimis Threshold: The U.S. has removed the de minimis exemption for low-value shipments from China, Hong Kong, and Macau, effective May 2, 2025, eliminating the $800 duty-free threshold for these regions.

4. Ongoing Developments:

  • Retaliatory Measures: Affected countries, including China, the EU and Canada, have announced retaliatory tariffs in response to U.S. measures, further complicating the trade landscape. ​

  • Future Tariff Considerations: The administration has indicated that additional tariffs may be imposed on sectors such as copper, pharmaceuticals, semiconductors, and lumber to encourage domestic production.

China: Although challenging to calculate precisely, this appears to bring the total tax on imports from China to 165% (updated). It also remains unclear whether the tax on EVs will now rise to 265%.

A 30-35% Tariff Rate

The Economic Reality Behind the Tariff ‘Pause’: A 35% Tariff Rate

On April 9, the effective tariff rate without factoring in China, the United States’ largest trading partner, shifted to 18%. This rate was still the highest we’ve seen since the 1940s. While this sounds like a notable shift, it doesn’t fully capture the broader impact. When we include China in the equation, the story takes an even more dramatic turn. The total effective tariff rate, including both the general tariffs and consumption taxes on Chinese imports, skyrocketed to a range of 30-35%

Resources:

Trumpenomics: The Decline of the US

bookmark_borderAmerica’s Trade War Is Costing More Than We Realize — It’s Costing Global Trust

by Daniel Brouse
April 9, 2025

Today’s record spike in U.S. interest rates is grabbing headlines — but it’s a symptom, not the disease. The real crisis is deeper and far more dangerous: America’s trade war has shattered the trust that once made U.S. financial markets the safest in the world.

For decades, the U.S. enjoyed an extraordinary advantage. No matter what turmoil rocked the world — wars, recessions, pandemics — foreign investors would rush to buy U.S. Treasuries. It wasn’t just about returns. It was about trust. The U.S. was stable, predictable, and reliable. That trust kept our borrowing costs low, our dollar strong, and our economy resilient.

But Trump’s trade war changed everything.

Tariffs didn’t just hit goods and supply chains — they hit America’s credibility. They introduced chaos into global markets, made U.S. policy look arbitrary, and forced long-time allies and trading partners to start hedging their bets. Suddenly, the “safe haven” didn’t feel so safe anymore.

And now we’re seeing the fallout.

Today’s bond market shock — one of the sharpest interest rate spikes in history — is part of a larger shift. Foreign investors aren’t rushing to U.S. Treasuries like they used to. Some are moving to gold. Others to European bonds. Some are simply staying home.

That shift comes at a staggering cost. Without foreign demand for our debt, the U.S. has to offer higher and higher interest rates to attract buyers. That means rising borrowing costs across the entire economy — for the government, for businesses, for homeowners.

This isn’t just about tariffs on steel or soybeans. This is about America losing its greatest economic weapon: trust.

And once trust is gone, it doesn’t come back easily — or quickly. No matter what happens next with Trump’s tariff policies, the damage is done. The U.S. has moved from “most trusted” to “no longer reliable” in the eyes of global investors.

That’s a legacy of the trade war we’ll be paying for long after the headlines move on.

Tariffs and the Liquidity Crisis in Long U.S. Treasuries

Trumpenomics: The Decline of the US