The cost of transporting crude oil by the world’s largest oil tankers has reached extraordinary levels.
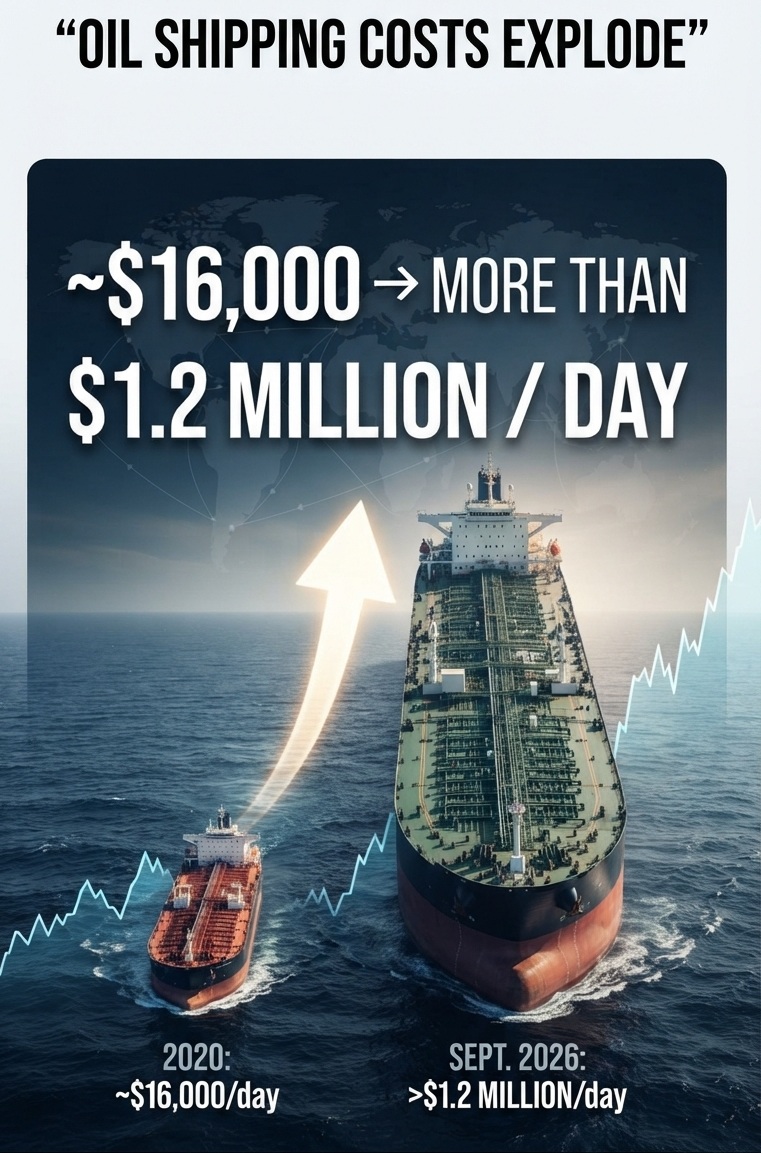
On the benchmark TD3C route — a 270,000-metric-ton Very Large Crude Carrier (VLCC) traveling from the Middle East Gulf to China — daily time-charter-equivalent (TCE) earnings have surged from roughly $16,000/day in 2020 to more than $1.2 million/day in September 2026.
That is not simply a large increase. It represents an extraordinary transformation in the economics of moving oil by sea.
From $16,000 to $1.2 Million a Day
Period
Approx. TD3C Daily Rate/TCE
What Was Driving the Market
2020
~$16,000/day
Pandemic-era demand collapse and abundant tanker capacity
2025
~$35,000/day average*
Tightening tanker fundamentals, geopolitical rerouting and limited fleet growth
September 2026
$1,212,503/day
Middle East conflict, disruption around the Strait of Hormuz, rerouting and severe tanker scarcity
*McQuilling reported a TD3C average earning of approximately $35,136/day for the first eight months of 2025, rather than $160,000/day.
The 2020 figure is also consistent with contemporary tanker-market estimates. McQuilling projected the TD3C round-trip voyage at approximately $16,200/day for 2020.
Then came 2026.
The $1.2 Million-a-Day Shock
In September 2026, the TD3C benchmark moved into territory rarely seen in modern tanker shipping.
The Baltic Exchange reported that the TD3C rate rose to Worldscale 1,140, corresponding to a round-trip TCE of approximately $1,212,503 per day for a standard Baltic VLCC.
Earlier in September, the same benchmark had already exceeded $1 million/day, with the Baltic assessment reaching approximately $1.099 million/day on September 15.
The surge reflects an extraordinary combination of factors:
disruption to Middle Eastern oil-export routes;
sharply reduced traffic through the Strait of Hormuz;
attacks and security risks affecting regional shipping;
longer and more complicated voyages;
ships being tied up in shuttle and ship-to-ship operations;
and a limited number of immediately available VLCCs.
Reuters reported on September 21 that only 17 commodity vessels transited the Strait of Hormuz over the weekend, compared with 37 the previous week and a pre-conflict average of about 125 vessels per day.
Why Shipping Costs Matter
Oil does not simply move from the wellhead to the refinery.
It has to be transported.
When the cost of transporting a cargo of crude suddenly multiplies, the consequences extend through the entire energy system.
At today’s extreme tanker rates, transportation itself can represent a substantial portion of the delivered cost of crude. The Wall Street Journal reported that VLCC charter costs had exceeded $1 million/day, equivalent to roughly $26 per barrel on the affected voyages.
That means the disruption is not merely a problem for shipowners and oil traders.
Higher transportation costs can therefore add pressure to gasoline, diesel, jet fuel and other petroleum products even when the underlying price of crude oil is moving differently.
An Extraordinary Comparison
The scale of the change is easier to see this way:
2020: ~$16,000/day ↓ 2025: ~$35,000/day average ↓ September 2026:$1,212,503/day
From the approximate 2020 level to the September 2026 TD3C assessment, the daily TCE increased by roughly 75×.
That is an extraordinary change in the economics of moving a single cargo of oil.
And it demonstrates something important about modern energy systems:
When a critical transportation chokepoint is disrupted, the cost of moving energy can become a crisis of its own.
A market under extreme stress
The current rate should not be interpreted as a normal annual shipping cost. It is a spot-market benchmark during an exceptional geopolitical disruption. Rates can move dramatically in either direction as vessel availability, security conditions, oil flows and trade routes change.
But the magnitude of the September 2026 spike is unmistakable.
The cost of moving oil by VLCC has gone from tens of thousands of dollars per day to more than $1.2 million per day.
That is a remarkable indicator of just how much stress has entered the global oil-transportation system.
Plug-and-play solar is becoming available around the world—and it could make solar power dramatically simpler and more accessible.
Plug-and-play solar is part of the emerging clean energy economy. Unlike conventional rooftop solar, these small systems can be installed with minimal equipment and, where permitted, connected directly to an existing electrical outlet. That makes solar potentially accessible to renters, apartment dwellers, condominium owners, and homeowners who cannot install a conventional rooftop system.
Cheaper and Healthier
Plug-and-play solar can reduce electricity costs because sunlight is free and the system produces electricity without ongoing fuel purchases. It also generates electricity without the combustion-related air pollutants produced by fossil-fuel power generation.
Instead of buying fuel from a utility to generate electricity somewhere else, a plug-in solar system can capture sunlight right from a balcony, patio, yard, or other suitable location and produce electricity at the point of use.
Great Britain has taken a major step toward making plug-in solar widely accessible. Beginning August 27, 2026, new rules established a legal framework for plug-in solar panels and other plug-in microgenerators.
Under the new framework, qualifying certified systems can connect to standard 13-amp domestic sockets, subject to safety requirements and output limits. Plug-in solar kits can produce up to 800 watts, and users must notify the local electricity network operator. The UK government says the systems could save households up to £110 per year and provide as much as 20% of average household electricity use.
Ofgem has also approved changes to the distribution code intended to facilitate plug-in solar while maintaining requirements for network safety, supply quality, and system operability.
The United States Is Moving State by State
The situation in the United States is less straightforward. There is currently no single nationwide legal framework for plug-in solar. Instead, states are beginning to establish their own rules.
As of September 2026, nine states have enacted legislation specifically addressing plug-in or balcony solar: Utah, Colorado, Maryland, Maine, Vermont, Connecticut, New Hampshire, Virginia, and New Jersey.
Meanwhile, additional states are considering plug-in-solar legislation. California and New York, among others, have active legislative efforts, illustrating how quickly the regulatory landscape is changing.
Plug-and-play solar is therefore more than another solar product. It represents a shift toward small, distributed, consumer-installed energy generation—putting a small power plant within reach of people who may never own a house with a conventional solar roof.
The sun is already there. Plug-and-play solar makes it easier to use.
☀️ THE CLEAN ENERGY ECONOMY
Harmony Hare says:
🔌 PLUG-AND-PLAY SOLAR IS CHEAPER AND HEALTHIER
Solar power doesn’t have to mean a massive rooftop installation.
Plug-and-play solar is changing the equation.
A small solar system can plug directly into an existing electrical outlet—turning a balcony, patio, yard, or other sunny space into a source of clean electricity.
☀️ FREE FUEL The sun provides the energy. No gasoline. No coal. No natural gas. No ongoing fuel purchases.
💰 LOWER ENERGY COSTS Generate some of your own electricity instead of buying all of it from the utility.
🌱 CLEANER AIR Solar electricity generates power without the combustion emissions associated with fossil-fuel generation.
🏠 MORE ACCESSIBLE Plug-and-play systems can potentially bring solar to renters, apartment dwellers, condo owners, and homeowners who cannot install conventional rooftop solar.
This is the Clean Energy Economy in action:
Small systems. Simple installation. Free sunlight. Less fuel. Less pollution. More distributed energy.
The future of clean energy doesn’t have to be complicated.
I’m generally against rooftop solar, particularly in the U.S. Much of the residential market is based on leased systems, which can be detrimental to the homeowner, especially when the home is eventually sold.
In general, I also recommend putting a new roof on before installing solar. Otherwise, replacing the roof later can mean additional costs and complications with the solar system. And the payback period can be longer than the length of time many homeowners actually own their homes.
There’s another fundamental problem: in both the U.S. and UK, it can be difficult to install enough rooftop solar to meet a home’s actual electricity demand, particularly during periods of peak heating or cooling. The times when energy demand is highest are not necessarily the times when a rooftop array produces the most electricity. That can make the system less useful—and potentially a liability when selling the property.
As a consultant, I almost always recommend ground-mounted solar when the property allows it. It avoids many of the structural, roofing, maintenance, and resale issues associated with rooftop systems while providing much greater flexibility in system placement and orientation.
In my view, there are very few disadvantages to properly designed ground-mounted solar, while many of the supposed advantages of rooftop solar are really advantages of having solar—not advantages of putting the panels on the roof.
Plug-And-Play Solar
What I’m totally in favor of, however, is plug-and-play solar. Plug-in solar, balcony solar, or other plug-and-play systems can connect directly to an existing electrical outlet, making solar dramatically simpler and less expensive to install. Great Britain has now established a legal framework for these systems: updated regulations taking effect August 27, 2026, created a legal category for plug-in microgenerators and allow certified systems to connect to standard 13-amp domestic sockets, subject to safety requirements, output limits generally up to 800 watts, and notification to the local electricity network operator. Unfortunately, the situation remains much less straightforward in the U.S., where regulation is largely state-by-state. At present, plug-in solar is legal in only nine states: Utah, Colorado, Maryland, Maine, Vermont, Connecticut, New Hampshire, Virginia, and New Jersey.
THE ENERGY IS ALREADY THERE. THE CLEAN ENERGY ECONOMY HARVESTS IT.
Tonight’s homework assignment: Clean Energy Economy.
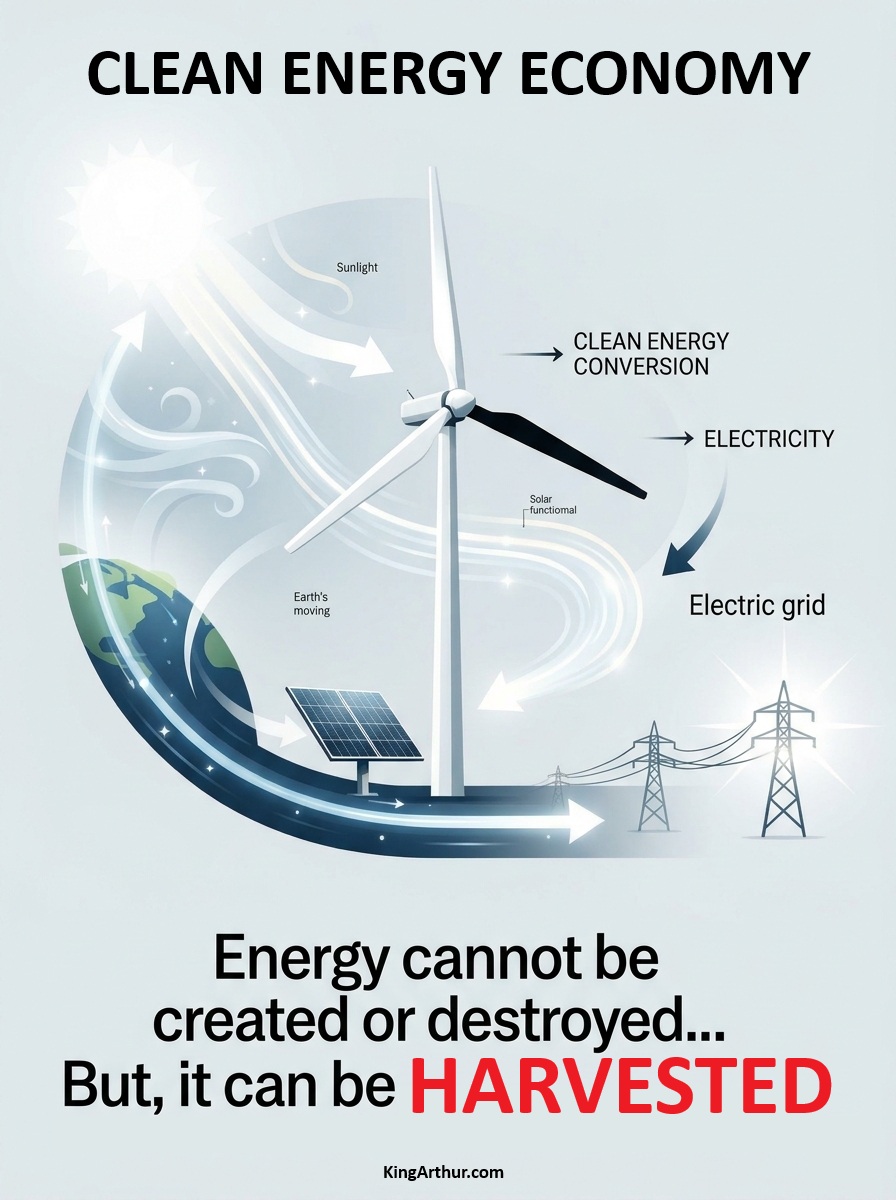
Energy cannot be created or destroyed. But it can be harnessed, converted, stored, transmitted, and used.
The sun is already delivering enormous amounts of energy to Earth.
The atmosphere is already moving.
Winds are already blowing.
Waves and currents are already moving.
The challenge isn’t creating energy from nothing. It is building systems that efficiently capture naturally available energy and convert it into useful electricity.
That is the basic idea behind a clean energy economy:
SUN + WIND + MOVING EARTH ↓ ENERGY HARVESTING ↓ ELECTRICITY ↓ STORAGE + TRANSMISSION ↓ USEFUL WORK
A wind turbine doesn’t create wind. A solar panel doesn’t create sunlight.
They harvest energy that is already moving through the Earth system and convert it into a form we can use.
The economic opportunity is therefore not simply replacing one fuel with another.
It is building an economy around capturing, converting, distributing, storing, and using energy that is already available.
The price difference between a refined petroleum product—such as gasoline or diesel—and the crude oil used to produce it is known as the crack spread. It is a widely used measure of refining margins and provides a useful way to examine how the relationship between crude oil costs and finished-fuel prices changes over time.
Key Market Data & Trends: The Past 12 Months
Looking at the past year reveals a dramatic period of volatility in refining margins.
Fall/Winter 2025 — The Baseline
Through late 2025, crude oil prices remained relatively low, dipping into the $55–$60-per-barrel range. Gasoline prices generally moved in tandem with crude, leaving the simple gasoline crack spread in a relatively compressed, historically typical range of approximately $15–$25 per barrel.
Spring 2026 — The Surge
That relationship changed sharply in spring 2026. Global crude prices climbed aggressively toward a 52-week peak near $117 per barrel. At the same time, wholesale gasoline futures rose substantially, exceeding $3.80 per gallon amid localized refinery bottlenecks and changing supply routes.
The result was a substantial expansion in the spread between the cost of crude and the market price of refined gasoline.
September 2026 — The Current Environment
As of September 16, 2026, WTI crude oil is approximately $104.03 per barrel, while front-month RBOB gasoline is trading around $3.35–$3.45 per gallon.
Converting the gasoline price to a barrel-equivalent basis produces approximately $140.70–$144.90 per barrel. Subtracting the $104.03 WTI price yields a simple gasoline crack spread of roughly $36.70–$40.90 per barrel.
That is substantially wider than the approximately $15–$25-per-barrel range observed during the late-2025 baseline period.
What the Crack Spread Shows
The crack spread does not represent the refinery’s actual profit. Refiners also incur costs for natural gas, electricity, transportation, labor, maintenance, environmental compliance, and other inputs. Refiners also process crude into multiple products rather than simply converting one barrel of crude into one barrel of gasoline.
Nevertheless, the spread provides an important market signal: the price relationship between crude oil and refined gasoline has widened considerably over the past year.
The change is particularly notable because the increase is occurring while crude itself remains above $100 per barrel. Consumers therefore face elevated gasoline prices from two directions: a high underlying crude-oil cost and a substantially wider refining margin.
In other words, the question is no longer simply “How expensive is crude oil?” It is also “How much more expensive has the refined product become relative to its crude-oil input?”
The crack spread provides a way to quantify that difference.
What Does a Barrel of Oil Cost—and What Does It Mean to You?
When you hear the price of oil reported on the news, you are usually hearing the futures price.
But what does that number actually mean?
The futures price is essentially a “paper” price. Very little physical oil actually changes hands through the futures market. The price that matters to consumers and businesses buying and using petroleum products is the spot price—the price of physical oil being purchased today. And right now, there is a significant difference between the two.
Today, the futures price of oil is roughly $102–$107 per barrel. But the spot price—the actual price being paid for physical oil—is approximately $125–$150 per barrel.
That is the price that ultimately matters to everyone buying refined petroleum products, including gasoline, diesel, and heating oil.
The Pain at the Pump
This is why diesel has reached approximately $6 per gallon, making it the highest price in history. It is also why gasoline is currently averaging approximately $4.32 per gallon. Yes—this is the highest average gasoline price ever recorded for this time of year.
And what’s next?
Heating oil.
As we move toward the winter months, parts of the Northern Hemisphere are already seeing heating oil prices averaging between $5.15 and $5.75 per gallon. Yes. Just like gasoline, heating oil is trading at an absolute record high for the month of September.
Historically, heating oil prices have hovered around $3.50 to $4.00 per gallon during a typical winter season. The current offseason surge above $5.00 per gallon is unprecedented. And this is happening before winter has even arrived.
For millions of households that depend on heating oil, the implications are obvious. The price shock at the pump can become a much larger household energy shock when temperatures fall and heating demand rises.
Adding Fuel to the Fire
There is another problem developing in the background. Oil borrowed from the Strategic Petroleum Reserve (SPR) under the 2026 emergency exchanges is scheduled to be repaid in tranches between November 1, 2026, and September 30, 2028.
Under the 2026 SPR emergency exchange program managed by the U.S. Department of Energy (DOE), companies are contractually required to return approximately 1.18 to 1.24 barrels for every barrel they borrowed.
In other words, oil that was taken out of the reserve during an emergency must eventually be replaced—and companies are not simply returning the same amount of oil they received. They have to return more. That creates another future demand on the physical oil market.
So when you look at the oil price reported on television, don’t assume that the futures number tells the whole story.
The price of oil isn’t just a number on a screen.
It flows directly through the economy. It becomes diesel. It becomes gasoline. It becomes heating oil. It becomes transportation costs, food costs, manufacturing costs, electricity costs, and ultimately the cost of living.
And if physical oil is already trading substantially above the futures price, while heating demand is about to increase and SPR repayment obligations are beginning to come due, the question isn’t simply:
“What does oil cost today?”
The more important question is:
“What is the price of oil going to cost you tomorrow?”
esterday brought the latest Producer Price Index (PPI) measure of inflation. Today, the focus shifts to consumer inflation.
The U.S. Bureau of Labor Statistics released the August 2026 Consumer Price Index (CPI) report, showing headline consumer inflation rising 0.4% in August on a seasonally adjusted basis and increasing 3.4% over the past 12 months.
Core inflation, which excludes volatile food and energy prices, rose 0.3% for the month. That was hotter than expected and is particularly important when viewed alongside yesterday’s PPI report.
The Diesel Problem
Historically, the Federal Reserve has placed considerable emphasis on core inflation because food and energy prices can be highly volatile. The logic is straightforward: temporary energy-price spikes can distort the underlying inflation trend.
But this energy shock is different.
The problem is diesel.
According to the latest BLS PPI data, the price of diesel fuel jumped an extraordinary 24.1% in August alone. BLS reported that more than one-third of the August increase in final-demand goods was attributable to diesel, while nearly two-thirds of the increase in processed goods for intermediate demand was also attributable to the 24.1% surge in diesel prices.
This is not simply a higher price at the pump for people who drive diesel vehicles. Diesel is embedded throughout the economy.
Trucks move food, consumer products, construction materials, manufactured goods, and virtually everything else through the nation’s supply chain. Diesel also powers agricultural machinery, construction equipment, mining equipment, generators, and other industrial machinery.
When diesel prices rise sharply and remain elevated, the increased cost of transportation and production eventually works its way into the prices consumers pay.
Why “Core” Inflation May Miss the Coming Shock
Energy is normally removed from core inflation because energy prices are volatile.
But removing energy from the calculation does not make its economic effects disappear.
A prolonged energy shock can become a supply-chain shock.
That distinction matters.
If gasoline or diesel prices briefly spike and then fall, businesses may absorb some of the increase. But if fuel costs remain elevated, businesses eventually have to recover those higher costs through higher prices for their products and services.
That means today’s diesel inflation can become tomorrow’s food inflation, transportation inflation, construction inflation, manufacturing inflation, and service inflation.
In other words, the energy shock can migrate into core inflation.
This is why the current situation deserves particular attention. The 24.1% monthly increase in diesel prices reported by BLS is large enough to create significant downstream pressure throughout the economy.
$6 Diesel Changes the Equation
Diesel prices have also reached extraordinary levels at the retail pump.
AAA data reported in early September showed the national diesel price approaching the $6-per-gallon threshold, with some markets already reaching or exceeding that level. In several markets, diesel prices were more than 60% above year-earlier levels.
That is a massive increase in one of the economy’s most important transportation and production inputs.
And there is another problem approaching.
Heating Oil Season Is Coming
Northern Hemisphere heating season is about to begin.
Heating oil and diesel are closely related middle-distillate petroleum products and compete for refinery capacity. BLS’s August PPI report also showed a substantial increase in home heating oil and distillates.
That means the diesel shock is arriving just as seasonal demand for heating fuel begins to increase.
For households in the Northeast and other regions that rely on heating oil, this could become a direct household expense. For everyone else, higher heating and transportation costs can still work their way through the prices of goods and services.
Yesterday’s PPI May Be Today’s Warning
The sequence of the data is important.
Yesterday’s PPI showed an enormous producer-level shock concentrated in energy, particularly diesel.
The critical question is not simply whether headline CPI is 3.4% or whether core inflation is 0.3% for the month.
The bigger question is what happens when a massive energy-cost shock persists long enough to propagate through the entire economy.
Core inflation may initially appear relatively contained because energy is excluded from its calculation.
But the economy cannot exclude energy from its production and transportation costs.
Eventually, somebody pays the diesel bill.
And increasingly, that somebody is the consumer.
The current inflation story therefore may not be about an isolated spike in energy prices. It may be the beginning of an inflationary transmission process—from diesel, to producers, to transportation, to supply chains, and ultimately to consumer prices.
How Fiscal Policy Is Becoming a Driving Force of Inflation
The U.S. Bureau of Labor Statistics (BLS) released its August 2026 Producer Price Index (PPI) report on September 10, revealing a renewed acceleration in wholesale prices. According to the report, headline PPI rose 0.4 percent month over month and climbed 5.4 percent over the year, with a significant increase in final-demand goods helping drive the advance. The PPI measures prices received by domestic producers and therefore provides an early look at price pressures moving through the production and distribution system.
The important question is not simply why did producer prices rise this month? It is a larger question:
Why does inflation continue to find fuel in an economy that has already experienced years of elevated prices?
One increasingly important answer is fiscal policy.
Inflation is not produced by a single variable. Energy prices, tariffs, supply disruptions, wages, housing costs, commodity prices, exchange rates, expectations, and monetary policy can all affect the price level. But fiscal policy determines another fundamental component of the inflation equation: how much purchasing power the government injects into the economy relative to the economy’s ability to supply goods and services.
When government spending persistently exceeds government revenues, the resulting deficit represents a substantial fiscal impulse. That impulse can support economic activity—and that is sometimes exactly what policymakers intend. But if demand is already strong, additional fiscal stimulus can also intensify competition for labor, materials, transportation, construction capacity, housing, and other scarce resources.
In other words:
Fiscal policy can become an inflation engine.
The Government Is Part of Aggregate Demand
It is easy to think of inflation as something caused primarily by consumers spending too much money.
But consumers are only one component of aggregate demand.
Businesses spend. Consumers spend. State and local governments spend. And the federal government spends.
The Federal Reserve defines aggregate demand as the combined demand for goods and services from households, businesses, and governments. Government purchases therefore enter the economy alongside private consumption and investment.
That matters because a government does not need to increase taxes to spend more money.
It can borrow.
When federal expenditures exceed federal revenues, the government finances the difference through borrowing. The resulting deficit does not automatically create inflation—particularly when the economy has substantial unused capacity. But persistent, large deficits can become inflationary when they add demand faster than the economy can expand its real supply of goods and services.
The distinction is crucial:
Deficit spending is not synonymous with inflation.
But under the right—or wrong—economic conditions, deficit spending can be an important source of inflationary pressure.
America’s Fiscal Imbalance Is Enormous
The scale of current federal deficits makes this more than an abstract theoretical issue.
The Congressional Budget Office estimated in August that the federal government had accumulated a $1.8 trillion deficit during the first ten months of fiscal year 2026. During that period, federal revenues increased by about 3 percent while outlays increased by about 5 percent. CBO subsequently estimated that the full-year 2026 deficit would reach approximately $2.1 trillion.
CBO’s longer-term projections similarly show deficits remaining historically large. Its February baseline projected a 2026 deficit of $1.9 trillion, equivalent to 5.8 percent of GDP, compared with a 50-year historical average deficit of 3.8 percent of GDP. Federal outlays were projected at 23.3 percent of GDP, substantially above their 50-year average of 21.2 percent.
That is a fiscal environment in which policymakers need to take seriously the possibility that government demand is contributing to persistent price pressure.
And there is another complication.
Fiscal Policy and Monetary Policy Can Pull in Opposite Directions
The Federal Reserve controls monetary policy. Congress and the Administration control fiscal policy.
These are different policy levers, but they interact.
The Federal Reserve explicitly notes that fiscal policy affects the economic outlook and that the Fed considers current and projected fiscal policy when determining the appropriate stance of monetary policy.
Consider the policy feedback:
Government spends more → aggregate demand increases → resource competition increases → prices rise → inflation persists → Federal Reserve faces greater pressure to maintain restrictive monetary policy.
This can create a peculiar policy conflict.
Fiscal policy may be pushing demand upward at the same time monetary policy is attempting to restrain demand.
The Fed can raise interest rates to cool borrowing, investment, housing, and consumption. But monetary policy cannot directly decide how much Congress spends or how much revenue the federal government collects.
Consequently, monetary policy can be forced to compensate for fiscal policy.
That is an important reason why blaming the Federal Reserve alone for inflation can miss half of the equation.
The Fiscal Multiplier Matters
Government spending does not necessarily have a one-for-one effect on economic activity.
Money spent by the government becomes income for someone else. That recipient spends some of it, creating income for another person or business, which can generate another round of spending.
This is the basic idea behind the fiscal multiplier.
When the economy has substantial unused capacity, that multiplier can increase real output without producing an equivalent increase in prices.
But when the economy is operating close to capacity, the same additional demand can produce a different result.
There may simply not be enough additional workers, factories, trucks, construction crews, housing, electricity, raw materials, or other productive resources available to satisfy the additional demand.
At that point, more nominal demand begins chasing a relatively constrained supply.
The result can be higher prices rather than proportionately higher real output.
That is the fiscal-inflation connection.
Deficits Can Also Keep Pressure on the Economy Longer
There is another reason persistent deficits matter.
A temporary fiscal expansion can be appropriate during a recession, emergency, war, financial crisis, or other period of severe economic weakness. The government can deliberately borrow and spend to prevent a collapse in demand.
The problem arises when emergency-style fiscal policy becomes structurally embedded after the emergency has passed.
If spending remains elevated while revenues remain insufficient to finance it, the government continues injecting fiscal demand into the economy.
The issue then becomes less about one year’s stimulus and more about the persistent fiscal stance.
That persistence matters for inflation expectations, interest rates, government borrowing costs, private investment, and the Federal Reserve’s policy response.
Government Spending Can Also Raise the Cost of Producing Things
Fiscal policy does not affect inflation only by stimulating demand.
Government policy can also affect the cost structure of the economy.
Government borrowing contributes to demand for credit. Large and persistent borrowing needs can put upward pressure on interest rates, particularly when private borrowers are competing for the same pool of financial resources.
Government spending can also increase demand for construction, engineering, defense production, transportation, technology, health care, energy, and other services.
When government becomes a very large buyer, private-sector buyers may have to compete for the same resources.
The result can be higher wages, higher input costs, higher financing costs, and higher prices.
In that sense, fiscal policy can influence both sides of the inflation equation:
More demand + constrained supply = greater price pressure.
The PPI Is an Important Warning Signal
This is why the August PPI deserves attention.
Producer prices are not consumer prices, and a single monthly PPI increase does not prove that fiscal policy caused the increase. Prices can move because of commodity markets, tariffs, energy shocks, supply disruptions, weather, transportation costs, exchange rates, or changes in margins.
But the PPI provides a useful window into the price pressures confronting businesses before those pressures are fully transmitted through the economy.
The July PPI data already showed that producer prices remained elevated: final-demand prices were up 4.7 percent over the year, while final-demand goods were up 6.5 percent and final-demand services were up 3.9 percent.
The August acceleration therefore raises a broader question about whether inflation is merely experiencing temporary disturbances—or whether the economy continues to contain structural forces capable of sustaining price increases.
Fiscal policy belongs prominently in that discussion.
Inflation Is a Policy Interaction, Not a Single-Agency Failure
It is tempting to divide economic policy into simple categories:
The Fed causes inflation.
Or:
Government spending causes inflation.
Or:
Tariffs cause inflation.
Or:
Corporations cause inflation.
Reality is considerably more complicated.
Inflation is an interaction among monetary policy, fiscal policy, supply, demand, expectations, financial conditions, international trade, energy markets, labor markets, and productivity.
But acknowledging complexity should not obscure responsibility.
If fiscal policy continually stimulates demand while monetary policy is attempting to suppress it, the two policies are working at cross-purposes.
And if the government repeatedly runs enormous deficits while the economy is operating near capacity, fiscal policy can become a persistent contributor to inflation rather than merely a temporary response to economic weakness.
The Fiscal Policy Question
The central economic question should therefore be expanded beyond:
“What is the Federal Reserve doing about inflation?”
It should also be:
“What is fiscal policy doing to inflation?”
That question is especially important when federal spending is growing faster than federal revenues and when deficits are measured in trillions of dollars.
The Federal Reserve can raise interest rates.
It can reduce them.
It can tighten.
It can ease.
But the Fed cannot balance the federal budget.
Congress and the Administration determine the government’s spending and taxation policies. As the Federal Reserve itself explains, fiscal policy is fundamentally the government’s tax-and-spending policy, while monetary policy is conducted independently by the central bank.
That division of responsibility matters.
If fiscal policy continually pushes aggregate demand upward, monetary policy may have to work harder to restrain it.
CBO’s projections already show the importance of this mechanism. In its 2026 baseline, net federal interest costs were projected at roughly $1 trillion, or 3.3 percent of GDP. CBO projected that interest costs would continue rising as a share of the economy over the following decade.
That does not mean interest expense itself automatically creates consumer-price inflation.
It means that debt service becomes another claim on federal resources and another component of federal spending that must ultimately be financed through taxes, borrowing, or reductions elsewhere.
The larger the debt burden becomes, the less fiscal flexibility policymakers have when the next recession, financial crisis, war, pandemic, or climate disaster arrives.
The Bottom Line
The August 2026 PPI report is more than another monthly inflation statistic.
It is a reminder that inflationary pressure remains embedded in the U.S. economy.
Some of that pressure comes from supply-side forces. Some comes from international events. Some comes from tariffs, energy markets, labor costs, and other factors.
But fiscal policy should not be treated as an innocent bystander.
Government spending is demand.
Deficits finance spending that exceeds current revenues.
Persistent deficits can sustain aggregate demand even when inflation is already elevated.
And when that fiscal expansion collides with constrained productive capacity, the result can be continued upward pressure on prices.
The United States therefore faces a policy problem that cannot be solved by monetary policy alone.
If policymakers want durable price stability, they eventually have to address not only the price of money, but also the size and composition of government spending, taxation, borrowing, and deficits.
The inflation debate should consequently move beyond the familiar question of whether the Federal Reserve is tightening enough.
The harder question is:
Is fiscal policy itself helping to keep the inflation fire burning?
In 2026, the evidence says that question deserves considerably more attention.
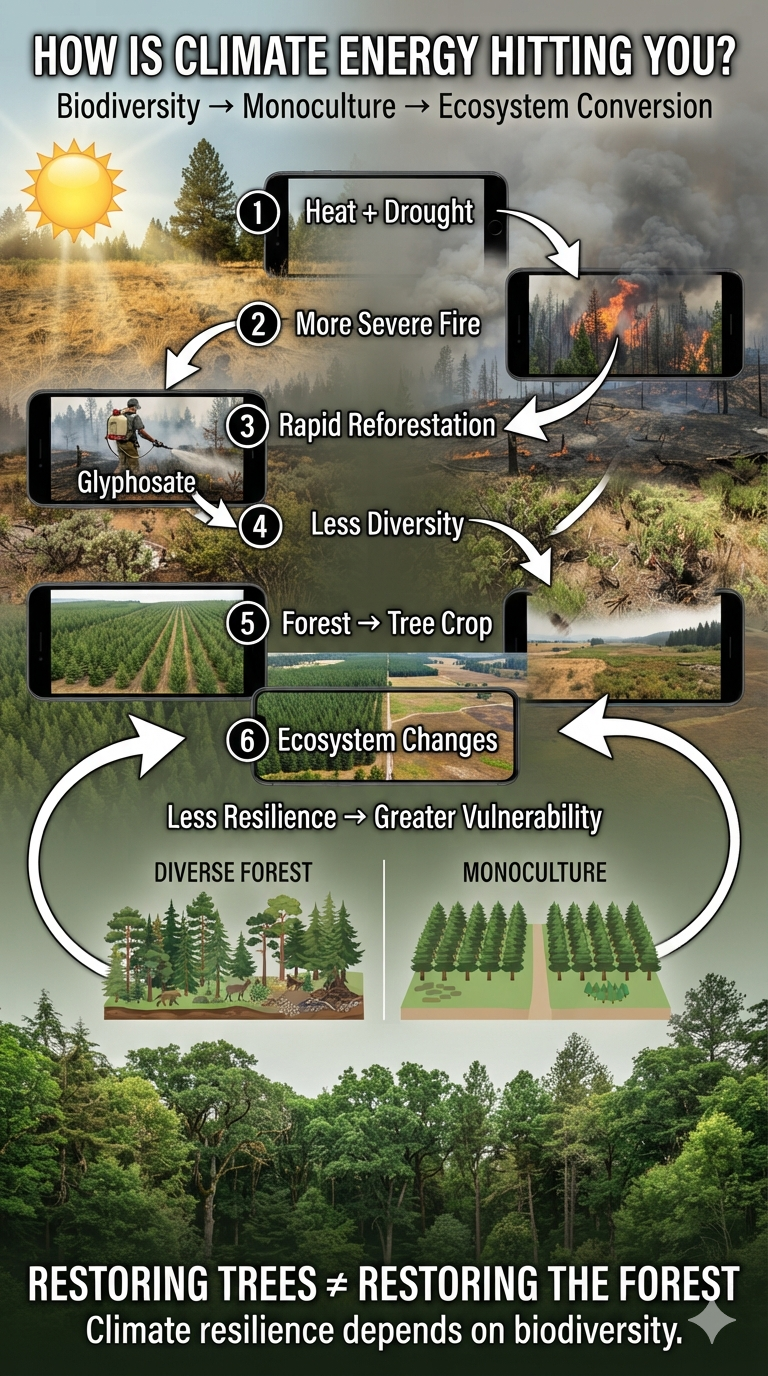
From Biodiversity to Monoculture: The Socio-Economic-Ecological Feedback Loop
Climate change is often described as a problem of rising temperatures, but temperature is only one expression of the additional energy entering the Earth system.
That energy moves through the atmosphere, hydrologic cycle, soils, vegetation, ecosystems, agriculture, forests, and human economies. As each system responds, it can alter the conditions experienced by the others.
This creates feedback loops.
A recent investigation by the Center for Investigative Reporting found that glyphosate is being sprayed in California forests at record levels. The U.S. Forest Service, timber companies, and other land managers use glyphosate after wildfire or timber harvest to suppress competing vegetation and improve the establishment of commercially valuable conifers.
At first glance, this may appear to be a straightforward forestry practice: kill competing plants, plant trees, and accelerate forest recovery.
But viewed through the lens of climate-system dynamics, it raises a much larger question:
What happens when our response to climate disruption further simplifies the ecosystems we depend upon for resilience?
Climate Energy Is Changing the Recovery Environment
Western forests are already experiencing a combination of higher temperatures, increasing atmospheric moisture demand, changing precipitation and snowpack, declining soil moisture, drought stress, and increasingly severe wildfire.
A forest can experience increasing stress for years without an obvious transformation. Then a threshold can be crossed.
Trees die.
Seed sources disappear.
Regeneration fails.
Shrubs and grasses occupy the landscape.
The ecosystem begins transitioning from one state to another.
As the paper explains, under moderate emissions scenarios, up to 40% of western conifer forests could convert to shrubland or grassland by 2100.
That is not simply forest damage.
It is ecosystem conversion.
And once we recognize that distinction, the economics of post-fire forest management look different.
The Economics of Reforestation
After a major wildfire, rapidly growing shrubs, grasses, ferns, and deciduous vegetation can compete with planted conifer seedlings for water, nutrients, and sunlight.
From a timber-production perspective, that competition is a problem.
Glyphosate provides an efficient way to remove it.
The Forest Service has used herbicide treatments as part of regeneration efforts because suppressing competing vegetation can improve the early survival and growth of desired seedlings. Forest research acknowledges that this is one reason herbicides have been used in reforestation.
The economic objective is therefore understandable:
But that is not necessarily the same objective as:
restore biodiversity → restore ecological function → increase climate resilience.
Those two objectives can overlap.
They can also conflict.
A Forest Is Not a Tree Farm
The distinction matters because a forest is not simply a collection of trees.
A functioning forest contains an enormous biological network:
multiple tree species
shrubs
grasses
flowering plants
fungi and mycorrhizal networks
insects and pollinators
birds
mammals
reptiles and amphibians
soil organisms
decomposers
streams and wetlands
genetic diversity
Each component participates in the functioning of the ecosystem.
When glyphosate is applied to eliminate “competing” vegetation, those plants are competitors only from the perspective of the desired crop.
From the perspective of the ecosystem, they may be food, shelter, habitat, soil cover, pollinator resources, firebreaks, nutrient sources, or participants in water and carbon cycling.
This creates a fundamental difference between restoration and production.
Production asks:
How efficiently can we produce the desired commodity?
Ecological restoration asks:
How effectively can we restore the biological relationships that make the ecosystem resilient?
Biodiversity Is Infrastructure
Biodiversity is often treated as an aesthetic or conservation issue.
It is much more than that.
Biodiversity is a form of ecological infrastructure.
Different species respond differently to drought, heat, insects, disease, fire, and changing precipitation. A diverse ecosystem therefore contains multiple biological responses to disturbance.
If one species performs poorly, another may survive.
If one food source disappears, another may remain.
If one plant cannot regenerate under new climatic conditions, another may occupy the available ecological niche.
This is one reason biological diversity can provide resilience.
A simplified ecosystem has fewer alternatives.
A diverse ecosystem has more.
That distinction becomes increasingly important as climate variability increases.
From Biodiversity to Monoculture
The problem becomes more obvious when forestry is compared with modern industrial agriculture.
Large-scale agriculture often relies on monocultures: enormous areas devoted to a single crop or a very small number of genetically similar crops. Monoculture creates economic efficiencies. Machines can plant, fertilize, spray, harvest, and transport a standardized product at enormous scale. But biological simplification creates vulnerabilities.
A pest that specializes in the crop has an enormous continuous food supply. A disease can spread rapidly through genetically similar plants. Soil nutrients can become depleted. Pollinator and insect diversity can decline. Herbicide and pesticide dependence can increase.
The economic system becomes increasingly dependent upon external inputs to maintain productivity.
The result can be a feedback loop:
biodiversity declines → ecological resistance declines → pests and disease become more consequential → chemical inputs increase → biodiversity declines further.
This is not an argument that all monoculture agriculture inevitably fails.
It is an argument that efficiency and resilience are not the same thing.
The same distinction applies to forestry.
The Forest Monoculture
When post-fire management suppresses naturally regenerating vegetation in order to establish commercially desirable conifers, the landscape can move toward a forest plantation rather than a naturally regenerating forest.
A plantation can contain thousands of trees and still possess considerably less biodiversity than the ecosystem it replaced.
This creates a dangerous semantic trap. We see trees. We call it a forest. But ecological function depends upon far more than tree cover.
A plantation of one or a few commercially valuable species can look green from above while functioning very differently from a diverse forest.
And in a warming climate, that distinction can become critical.
Ecosystem Conversion Versus Reforestation
This is where the concept of ecosystem conversion becomes important.
Suppose a severe wildfire destroys a mature conifer forest.
The original ecosystem does not necessarily return.
Under the warmer and drier conditions described in my Western U.S. Woodlands paper, grasses and shrubs may become better adapted to the post-fire environment than the trees that previously occupied it.
The second pathway is not simply allowing the ecosystem to respond to its new climate. It is imposing an economic land-use objective upon that response. That distinction should be explicit in public policy.
The Carbon Question
There is another important distinction. A green landscape is not necessarily equivalent to the forest that existed before. Grasslands and shrublands photosynthesize and absorb carbon.
So do plantations.
But carbon uptake is not the same thing as carbon storage.
A mature forest contains carbon in:
trunks
branches
roots
dead wood
forest soils
long-lived biomass
The Ecosystem Conversion paper makes this distinction explicitly:
carbon uptake ≠ carbon storage capacity
and
positive carbon flux ≠ preservation of the previous carbon stock.
A plantation may therefore satisfy a narrow definition of reforestation while failing to reproduce the carbon reservoir, biodiversity, hydrology, and ecological complexity of the original forest.
The Glyphosate Feedback
This brings us back to glyphosate. The current controversy is not simply about a herbicide. It is about the interaction between climate disruption, economic incentives, land management, biodiversity, and ecosystem resilience.
The emerging feedback looks something like this:
Climate warming
↓
Heat + drought + atmospheric moisture demand
↓
More severe wildfire
↓
Loss of mature forest
↓
Economic pressure to recover timber production
↓
Herbicide use to suppress competing vegetation
↓
Reduced vegetation diversity
↓
Simplified forest structure
↓
Greater dependence on managed inputs
↓
Potentially reduced ecological resilience
↓
Greater vulnerability to future climate disturbances
This does not mean glyphosate necessarily causes every subsequent step.
The feedback is systemic.
The larger point is that a management strategy designed to optimize one component of a complex system can unintentionally weaken other components.
The Scientific Evidence Must Be Independent
There is also a legitimate question about the evidence used to evaluate glyphosate. The recent investigation found that a study heavily relied upon by the Forest Service in assessing glyphosate safety was subsequently retracted after concerns about Monsanto’s involvement in the research process.That does not establish that every use of glyphosate is unsafe. It does establish why the underlying evidence should be independently reviewed.
When government policy determines what chemicals can be sprayed across public landscapes, the scientific foundation for those decisions should be exceptionally transparent.
Public land requires public confidence. And public confidence requires independent science.
From Wildfire Recovery to a National Policy
The issue also has a national economic dimension.
On February 18, 2026, President Donald Trump signed an executive order titled “Promoting the National Defense by Ensuring an Adequate Supply of Elemental Phosphorus and Glyphosate-Based Herbicides.”
The order invokes the Defense Production Act and directs federal action to ensure an adequate domestic supply of glyphosate-based herbicides. That places glyphosate within a much larger economic framework involving agriculture, forestry, chemical manufacturing, supply chains, and national security.
The feedback becomes:
climate disruption → increased agricultural and forestry stress → greater dependence on chemical intervention → greater economic importance of chemical production → stronger incentives to maintain chemical availability.
The system becomes self-reinforcing.
The Bigger Problem: Optimizing the Wrong Variable
Climate change forces us to rethink what we mean by efficiency. A system can be economically efficient while being ecologically fragile. A monoculture can produce enormous quantities of a commodity while containing very little biological diversity. A plantation can produce timber while failing to reproduce the ecological functions of a natural forest. A landscape can be covered in green vegetation while holding substantially less carbon than the forest it replaced. And a post-fire intervention can accelerate tree planting while simultaneously simplifying the ecosystem that must survive the next climate shock.
The central question is therefore not:
How quickly can we replace the trees we lost?
It is:
What kind of ecosystem will survive the climate that is coming?
The Resilience Test
Climate change is increasing the importance of resilience.
A resilient ecosystem does not necessarily maximize production under ideal conditions.
It maintains function when conditions become abnormal.
That means diversity matters.
Species diversity.
Genetic diversity.
Structural diversity.
Age diversity.
Habitat diversity.
Landscape diversity.
Biological diversity is effectively a portfolio of responses to uncertainty.
Industrial systems tend to reduce that diversity because standardization creates efficiency.
Climate instability does the opposite.
It increases the value of diversity.
That creates one of the central contradictions of the climate era:
The more unstable the climate becomes, the more we need ecological diversity—and the more economic pressure we may face to simplify ecosystems for efficiency.
Climate Energy Is Hitting the Whole System
This is ultimately what I mean by How Is Climate Energy Hitting You?
Climate energy does not stop with a thermometer reading or a measurement of atmospheric carbon dioxide. It moves through the entire coupled human-Earth system.
Heat changes water demand.
Water stress changes forests.
Forest stress changes wildfire.
Wildfire changes ecosystems.
Ecosystem disruption changes economic decisions.
Economic decisions change land management.
Land management changes biodiversity.
Biodiversity changes resilience.
And declining resilience feeds back into the next disturbance.
The resulting system is not a collection of unrelated environmental problems. It is a coupled socio-economic-ecological feedback system in which changes in one component propagate through the others.
Wildfire becomes an economic loss.
Economic loss creates pressure for rapid recovery.
Rapid recovery creates demand for herbicides, machinery, labor, and planted timber.
Those interventions alter ecosystems.
Altered ecosystems influence water, biodiversity, soil, carbon storage, and future fire behavior.
Government policy can then reinforce the economic system that produced the intervention in the first place.
The feedback can therefore become self-reinforcing.
The challenge is to recognize when a short-term economic solution becomes a long-term ecological feedback.
That distinction becomes especially important when an ecosystem crosses a threshold. Restoring the trees may not be the same thing as restoring the forest.
And once biodiversity has been converted into monoculture, replanting the landscape does not necessarily recreate the ecosystem that was lost.
Climate change is not simply changing the weather.
It is changing the decisions we make about the world around us—and those decisions can become feedbacks that determine how resilient that world remains.
On August 21, 2026, President Donald Trump announced a temporary 90-day waiver of out-of-quota tariffs on imported ground beef, allowing up to 300,000 metric tons to enter the U.S. market tariff-free in an effort to reduce grocery prices. The president said he had secured a commitment that the imported meat would be sold at 25% below current market prices, providing relief from persistent food inflation.
The move is intended to address a dramatic increase in the cost of ground beef, which has risen roughly 57% over the past five years. But the policy immediately drew backlash from domestic cattle ranchers and rural-state Republicans, including Senator Tim Sheehy, who warned that flooding the market with cheaper foreign beef could undermine American cattle producers.
There is another problem that may be even more important to consumers: much of the imported beef affected by the policy is frozen beef destined for commercial and restaurant use, rather than the fresh ground beef consumers typically purchase at the grocery store. That means the immediate impact on household grocery bills may be considerably smaller than the headline numbers suggest.
More importantly, the tariff waiver does little to address the underlying forces driving higher beef prices.
Climate Change Is Becoming an Inflation Problem
The cattle industry is increasingly exposed to the economic consequences of climate extremes. Drought, extreme heat, wildfires, water scarcity, degraded pasture, and volatile feed supplies all increase the cost of raising cattle. When these pressures become severe enough, ranchers may be forced to reduce their herds, further constraining beef supplies and pushing prices higher.
This creates a feedback loop. Climate extremes increase production costs and reduce the supply of cattle. Reduced supply raises beef prices. Higher prices then encourage producers to rebuild their herds, but rebuilding takes years. Another drought or extreme-weather event during that process can once again force herd reductions.
This is why simply importing cheaper beef may treat the symptom without addressing the disease.
The larger economic issue is what I call climate inflation: the gradual—and increasingly rapid—incorporation of climate-related costs into the prices of food, energy, insurance, housing, transportation, and other necessities.
For the past several years, inflation discussions have focused primarily on monetary policy, supply chains, labor costs, tariffs, and government spending. Those factors certainly matter. But climate-driven disruptions are becoming an increasingly important component of the cost structure of the economy.
And unlike a temporary tariff or a change in interest rates, climate pressures can compound over time.
The Beef Problem Is Bigger Than Beef
A 90-day tariff waiver may provide some temporary relief. It may even benefit restaurants and commercial food purchasers if imported frozen beef reaches the market at substantially lower prices.
But it does not create more water, restore drought-stricken grazing land, prevent wildfires, reduce extreme heat, or rebuild cattle herds that have been lost to climate-driven conditions.
Nor does it address the increasingly expensive insurance, infrastructure, agricultural, and supply-chain consequences of a changing climate.
If climate extremes continue to intensify, we should expect more of these conflicts. Policymakers will repeatedly face the same choice: temporarily suppress prices by opening markets to cheaper imports, or address the underlying conditions that are making domestic production increasingly expensive.
Where’s the beef?
It may increasingly be somewhere else.
And that is the larger warning. Climate change is no longer simply an environmental issue. It is becoming an economic variable—and climate inflation may prove to be one of the most consequential economic developments of the next decade.