bookmark_borderCoastal Real Estate Financial Crisis

The rising sea level is putting a trillion dollars of real estate at high risk.

“The question is no longer if rising seas will erode coastal home values, but who will get stuck with the devalued assets when the markets turn,” reported Dee Gill.

“Alarmingly, more than half of that (at-risk property) exposure is estimated to lie outside FEMA flood zones. That means those properties are at higher risk of being underinsured, and, therefore, the loans attached to them are at higher risk of impairment, with increased risk for the value of the related CMBS (securities).” —CFTC
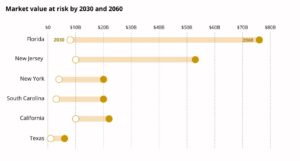
Market Value at Risk of Flooding

“Fannie and Freddie carry about $5.6 trillion in assets, mainly home mortgages and related securities. Ultimately, taxpayers backstop the payments on loans under the agencies’ control, UCLA’s Yu explains. Their regulator, the Federal Housing Finance Agency, issued a request for information in January, in part to assess flood risks. The entities require flood insurance that might mitigate their losses only on properties inside FEMA’s poorly drawn flood zones. Coverage limits imposed by NFIP — $250,000 for the structure and $100,000 for personal property — mean many coastal homes that have coverage are grossly underinsured.” — UCLA / Is the $1 Trillion Coastal Housing Market a Future Financial Crisis?

BlackRock, the G20-backed Financial Stability Board and the U.S. Commodity Futures Trading Commission are voicing concerns about unflagged flood risks squirreled away in mortgage-backed securities, bond markets and other real estate-backed investments. Common themes: The exact size of exposure is elusive but big; markets don’t currently price for it; these assets pose a threat to the stability of the global financial system.
More on Flood Insurance and Real Estate Risk

bookmark_borderNational Flood Insurance Program Increasing Rates

FEMA is updating the National Flood Insurance Program’s (NFIP) risk rating methodology through the implementation of a new pricing methodology called Risk Rating 2.0. The methodology leverages industry best practices and cutting-edge technology to enable FEMA to deliver rates that are actuarily sound, equitable, easier to understand and better reflect a property’s flood risk.

The Bradenton Herald reports, “More than a million Floridians will see their flood insurance premium rise next year, FEMA said Thursday.

The good news is, most will see increases of less than $120 a year. The bad news is that homeowners will likely see annual rate hikes like that for the foreseeable future.

The new strategy is meant to help pull the program out of its $20 billion debt and encourage people to live in safer, less flood-prone homes.

The new program will stop charging flood insurance premiums based solely on whether a home is within or outside of a flood zone and instead consider a range of factors like distance from the ocean, rainfall flooding and the cost to rebuild a home.

Starting April 2022, this pricing revamp will lead to higher prices for a majority of Florida’s 1.7 million policyholders — the most of any state — as well as a decrease for about 20% of policies, more than 340,000 policyholders.

“It allows us to set accurately sound rates and communicate flood risk better than we ever have before,” David Maurstad, senior executive of FEMA’s National Flood Insurance Program.

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderIncreasing Cost and Risk of Flood Insurance

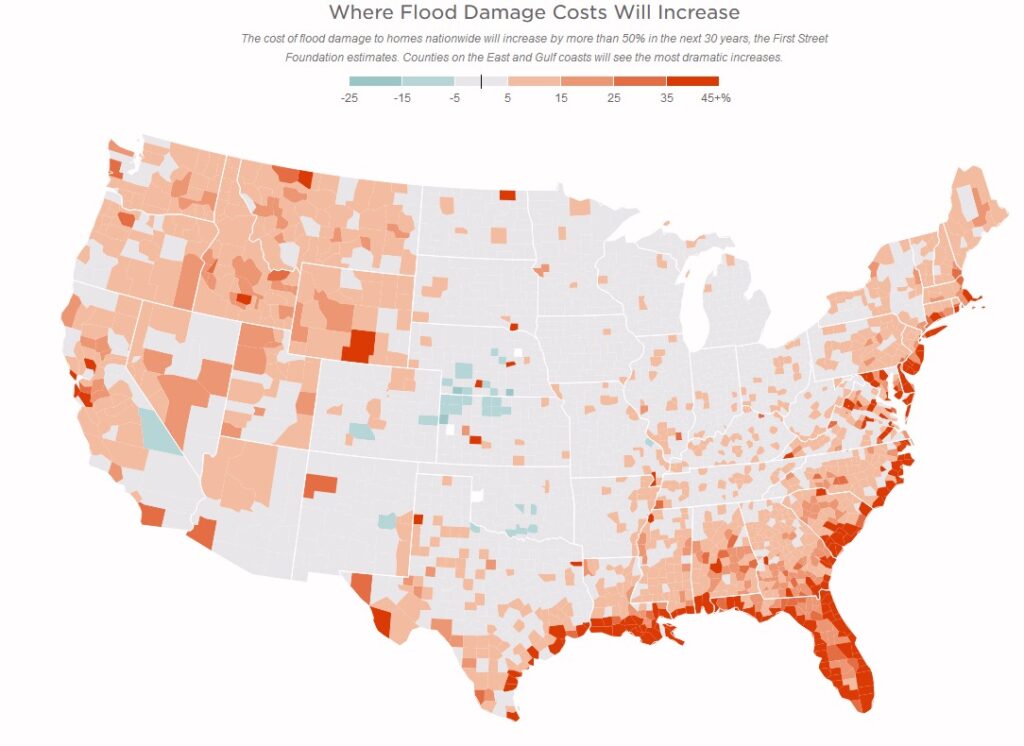
The cost of flood damage to homes nationwide will increase by more than 50% in the next 30 years, the First Street Foundation estimates.

Flood Insurance Forecast

A report by NPR radio, A Looming Disaster: New Data Reveal Where Flood Damage Is An Existential Threat, found:
The federal government provides the vast majority of residential flood insurance in the U.S. Most policies are underpriced relative to the actual cost of flood damage.

The new data show that flood insurance rates would need to more than quadruple to keep up with the costs of climate-driven flooding. The Federal Emergency Management Agency is already preparing to raise insurance premiums in many places later this year in an effort to save the National Flood Insurance Program, which has accrued more than $36 billion in debt.

FEMA warns that the First Street Foundation’s analysis is only an estimate and that FEMA didn’t provide the research group with details about the new flood insurance pricing plan, known as Risk Rating 2.0.

“Any entity claiming that they can provide insight or comparison to the Risk Rating 2.0 initiative, including premium amounts, is misinformed and setting public expectations that are not based in fact,” writes David Maurstad, the senior executive of the National Flood Insurance Program, in an email to NPR. “While entities are free to suggest or estimate their opinion of what flood insurance premiums should be, they are offering exactly that — an opinion — and they do not have insight into the Risk Rating 2.0 initiative.”

For homeowners who are currently underpaying for flood insurance, FEMA says it plans to raise rates by up to 18% each year until the price is accurate, according to a January report by the Congressional Research Service. The agency will begin rolling out the new pricing in October.

As the cost of insurance goes up, many people who need flood insurance will likely be unable to afford it, leaving them to face lasting damage. Research has found that disasters can erode family stability and exacerbate mental and physical ailments when people don’t have the money they need to repair their homes.

“If you don’t have the finances you need to recover, then families have to make really difficult trade-offs, like maybe forgo spending on medical expenses because otherwise you don’t have a safe home,” says Carolyn Kousky, the executive director of the Wharton Risk Management and Decision Processes Center at the University of Pennsylvania.

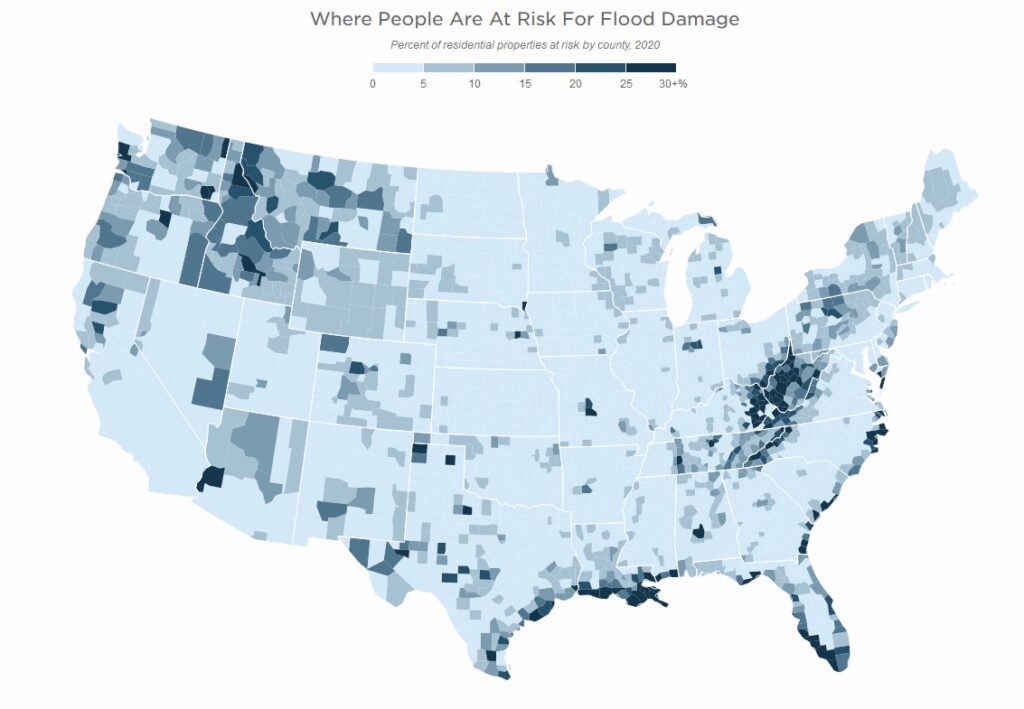
Flood Damage Risk
Flood Damage Risk
Flood Damage Cost
Flood Damage Cost

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderIncreasing Cost of Flood Insurance

“Increased awareness of flood risk and rising future insurance costs impact perceptions of value, which will impact real estate markets,” said Matthew Eby, founder and executive director of First Street Foundation.

First Street Foundation published a report that concludes: “Rising sea levels and extreme weather could cause $20 billion of flood damage to at-risk U.S. homes this year, rising to $32 billion (per year) by 2051.”

First Street Foundation Flood Insurance Forecast

“Roughly 4.3 million homes – concentrated in Florida, California, South Carolina and Texas – have a substantial risk of sustaining economic damage from flooding this year, the report shows. The majority are not required by the U.S. government to have flood insurance. Were all of them to buy federal insurance, National Flood Insurance Program (NFIP) rates would need to increase 4.5 times to cover the risk, according to the report. The current average NFIP premium for these 4.3 million homes is $981,” reports Kate Duguid of Reuters.

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderThe Cumulative Costs of Climate Change

“The crisis carries a profound warning. As climate change brings more frequent and intense storms, floods, heat waves, wildfires and other extreme events, it is placing growing stress on the foundations of the country’s economy: Its network of roads and railways, drinking-water systems, power plants, electrical grids, industrial waste sites and even homes. Failures in just one sector can set off a domino effect of breakdowns in hard-to-predict ways,” as reported by The New York Times in the article Texas Blackouts Point to Coast-to-Coast Crises Waiting to Happen.

“We are colliding with a future of extremes,” said Alice Hill, who oversaw planning for climate risks on the National Security Council during the Obama administration. “We base all our choices about risk management on what’s occurred in the past, and that is no longer a safe guide.”

“Sewer systems are overflowing more often as powerful rainstorms exceed their design capacity. Coastal homes and highways are collapsing as intensified runoff erodes cliffs. Coal ash, the toxic residue produced by coal-burning plants, is spilling into rivers as floods overwhelm barriers meant to hold it back. Homes once beyond the reach of wildfires are burning in blazes they were never designed to withstand.”

“I am extremely concerned by the lack of emergency-management expertise reflected in Biden’s climate team,” said Samantha Montano, an assistant professor at the Massachusetts Maritime Academy who focuses on disaster policy. “There’s an urgency here that still is not being reflected.”

A White House spokesman, Vedant Patel, said in a statement, “Building resilient and sustainable infrastructure that can withstand extreme weather and a changing climate will play an integral role in creating millions of good paying, union jobs” while cutting greenhouse gas emissions.

“All these issues are converging,” said Robert D. Bullard, a professor at Texas Southern University who studies wealth and racial disparities related to the environment. “And there’s simply no place in this country that’s not going to have to deal with climate change.”

bookmark_borderFlood Factor: Estimate Flood Insurance Risk by Address

Flood Factor allows you to enter a property address to determine the future risk of severe flooding.

Access data calculated by a team of more than 80 world-renowned experts using decades of peer-reviewed research.

Over 142 million properties, neighborhoods, and cities analyzed
View any home’s Flood Factor and understand what can be done to protect it from flooding.

>FEMA Current Flood Maps by Address
Whether you are in a high risk zone or not, you may need flood insurance because most homeowners insurance doesn’t cover flood damage. If you live in an area with low or moderate flood risk, you are 5 times more likely to experience flood than a fire in your home over the next 30 years. For many, a National Flood Insurance Program’s flood insurance policy could cost less than $400 per year. Call your insurance agent today and protect what you’ve built.

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderYou Can Not Fight the Rising Tide

aA “Built atop spongy marsh and old tidal creeks filled with sawdust”
A report by Yale School of the Environment found cities are going to lose the costly battle to hold back the sea.

“It’s a nightmare,” says Ana Zimmerman, who moved her family to higher ground after her James Island home flooded twice.

“wall-off the historic downtown with an 8-mile-long seawall that would cost nearly $2 billion. ”

“In Miami, the Army Corps is studying a 13-foot-high flood wall … Most of the estimated $8 billion price tag would be covered by federal taxpayers … ”

“In Galveston, Texas, the Corps has proposed placing a massive Dutch-style surge gate … estimated cost has ballooned from $2 billion to $37 billion ”

“In New Jersey, the Corps last year published a preliminary plan … Cost estimates range from several billion dollars up to $15 billion.”

“In New York, the Corps proposed building a huge seawall across Lower Manhattan … somewhere between $62 billion and $119 billion”

“In America, we have yet to come to terms with the fact that climate change tells us there are some places where growth is no longer possible.”

“a big wall of distraction”

“Miamians seem to have this horrible concept of permanence of place, even though Miami has only been around a hundred years ”

” the National Flood Insurance Program, which is $20 billion in debt”

“Americans keep flocking to the coast, and builders keep accommodating them. ”

“We’re continuing with more building on a peninsula that’s sinking”

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderSea Level Rise and Real Estate

In the research paper, Sea level rise and coastal flooding threaten affordable housing, the authors explain how vast sections of real estate will become uninhabitable in the near future.

Sea Level Rise Impact on Housing

About Flood Insurance

Do I Need Flood Insurance?
Flood Risks Across the USA Seriously Underestimated
Climate Change: Suspension Of Belief
Climate Denial and Climate Change Change
Underwater: Sea Level Rise
Disaster on the Horizon: The Price Effect of Sea Level Rise
Climate Change And Credit
Real Estate and the Rising Sea Level


bookmark_borderResidential Real Estate Flood Risk Information

Do you know if you need flood insurance? Do you know if you have flood insurance? What happens when your house gets flooded?

Flood risk information has not been readily available to the average consumer. Climate change is making your flood risk drastically increase.

Now, one of the major real estate databases (Realtor.com) is making flood information available to the public.

In the NPR story, Major Real Estate Website Now Shows Flood Risk. Should They All?, experts explain the trend.

“People are buying property with little knowledge of whether it’s going to flood or not,” says Harriet Festing, co-founder of the advocacy group Higher Ground, which connects people across the country who have survived floods. “It ruins lives.”

Millions of buyers risk overpaying for homes likely to be hit with a natural disaster over the course of a 30-year mortgage. But representatives for other realty sites say home sellers are reluctant to publish flood risk information, since it could decrease their home’s value.

What you need to know about flood insurance and your home.

bookmark_borderGreenland Ice Sheet: largest single contributor to rising sea levels.

Dynamic ice loss from the Greenland Ice Sheetdriven by sustained glacier retreat

by Michalea D. King, Ian M. Howat, Salvatore G. Candela, Myoung J. Noh, Seonsgu Jeong, Brice P. Y. Noël, Michiel R. van den Broeke3, Bert Wouters, Adelaide Negrete

Greenland-Ice-Sheet.pdf

The Greenland Ice Sheet is losing mass at accelerated rates in the 21st century, making it thelargest single contributor to rising sea levels. Fasterflow of outlet glaciers has substantiallycontributed to this loss, with the cause of speedup, and potential for future change, uncertain.

“The ice sheet is now in this new dynamic state, where even if we went back to a climate that was more like what we had 20 or 30 years ago, we would still be pretty quickly losing mass,” Ian Howat, co-author of the study and a professor at Ohio State University, said.

CNN reports, “Sea levels are projected to rise by more than 3 feet by the end of the century, wiping away beaches and coastal properties. Coastal states like Florida, and low-lying island nations are particularly vulnerable. Just 3 feet of sea level rise could put large areas of coastline underwater. Forty percent of the US population resides in coastal areas that are vulnerable to sea level rise.”

“There’s a lot of places, like in Florida especially, where one meter alone would cover a lot of existing land areas,” King said. “And that’s exacerbated when you get storms and hurricanes and things like that, that then cause extra surge on top of a higher baseline.”

“We’ve passed the point of no return but there’s obviously more to come,” Howat said. “Rather than being a single tipping point in which we’ve gone from a happy ice sheet to a rapidly collapsing ice sheet, it’s more of a staircase where we’ve fallen off the first step but there’s many more steps to go down into the pit.”

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

Greenland: Slip Sliding Away