bookmark_borderCarbon Offsets: Planting Trees is Greenwashing

By Daniel Brouse
June 28, 2023

This article is in response to “Animal Agriculture is the Leading Cause of Climate Change“.

I said, “About the paper, it is not a good paper… flawed in several ways. The main problem with the paper is it depends on “the potential to sequester over 2000 Giga tons.” No amount of sequestering will solve our problem. Sequestration is only a temporary solution. The most important thing for people to do is stop the use of hydrocarbon based products today… followed by everything else. Minimize consumption of everything.

Plant vegetation sequestration only lasts for several years (with old growth hardwood some sequestration may last up to 100 years.) We wrote a paper on it a few years ago. Though the paper focuses on hemp, it covers all vegetation (The Hemp Myth, Carbon Sinks and the Environment).

Some people argue that we can not abruptly stop the use of fossil fuels or it will cause social unrest. The total collapse of society is inevitable. Even if we stopped using fossil fuels today, we have already baked in a rise of 2 degrees Celsius. “The Earth will exceed 1.5℃ (average global surface temperature over the surface of the earth for ten years) by the 2040’s and a societal collapse will ensue. For the most part, the Earth will be uninhabitable for humans by 2070 UNLESS immediate action is taken.” — Brouse and Mukherjee

The average life of a tree planted for carbon credit sequestration is 7 years. (In addition, “Tree Extinction Due to Human Induced Environmental Stress” is already lowering the life expectancy of all trees.) Climate scientists, such as myself, are against the use of sequestering for carbon credits. Giving carbon offsets for planting trees and allowing for the continued use of fossil fuels is greenwashing and accelerates the pace of climate change.

The Human Induced Climate Change Experiment

bookmark_borderCorsi-Rosenthal Box: The Best Air Purifier

What is a Corsi-Rosenthal Box and how do you build one? The Corsi-Rosenthal Box is a simple DIY air filter and purifier that outperforms and can be more effective than expensive HEPA purifiers.

Corsi-Rosenthal Boxes are made from cardboard, tape, furnace air filters, and a box fan.

Corsi-Rosenthal Box
Corsi-Rosenthal Box

The Corsi-Rosenthal Box was invented by Richard Corsi, PhD, of the University of California-Davis and Jim Rosenthal, CEO of Tex-Air Filters.

“One night, I just scribbled out this idea on a piece of paper,” said Corsi. “It wasn’t an original idea – people had put a single filter on a box fan before. But not with MERV 13 filters.” (MERV — minimum efficiency reporting values — is the measure of how well a filter captures particles. The higher the MERV, the more effective the filter.)

“The Corsi-Rosenthal box outperformed the HEPA filter on every sized particle,” Rosenthal said. “You have such high flow from these fans, way more flow than you get out of a commercial HEPA filter. The air goes through the filter more than once in the same period of time. It may only get 50% of the particles at first. But the second time through, it’s getting much more.”

Corsi-Rosenthal Box Test

Smoke from wildfires in Canada brought record-breaking air pollution to the United States this spring, creating dangerous air quality from Bismarck, N.D., to Denver and Detroit to New York City and Washington. According to a Washington Post analysis of smoke data through June 7 (2023) from Stanford University, 197 air quality monitoring stations have reported all-time high pollution from wildfires.

During the Air Quality Crisis of 2023 the plant-based long-term breathing experiment failed the test. After 4 days in a row of Unhealthy (151 to 200 AQI) to Hazardous (301 and higher AQI) outdoor air quality, the the plant-filtered indoor air quality was unhealthy.

Even with spider plant filled windows and dozens of other plants, humans still suffered from itchy eyes, scratchy throats, and headaches.

Christopher suggested, “You should look into Corsi-Rosenthal… they consistently outperform high-end air filtration systems and it’s a simple DIY project.”

Sidd independently advised, “We are way beyond that (plant filtration). Put in something about Corsi-Rosenthal filters and CO2 monitors to judge ventilation.

Sooo… luckily I had a couple furnace filters, a box fan, and a case of beer. After constructing a crude Corsi-Rosenthal Box, the entire first floor was cleared of noticeable pollutants within 15 minutes. The itchy eyes, scratchy throat, and headache dissipated.

Makeshift / Emergency Corsi-Rosenthal Box

To confirm our results, we brought in the hound dog. Dogs are even more sensitive to air quality. After days of suffering in unhealthy air quality, the hound immediately laid down with his nose in the flow of the circulating Corsi-Rosenthal filtered air.

Conclusion
Air quality is already considered the number one contributing factor to death worldwide. Climate change is making poor air quality even more extreme. A combination of plant and Corsi-Rosenthal filtered air is recommended on a daily basis.

Our experiment was conducted in Southeastern Pennsylvania during an extreme air quality event; however, to our east is Philadelphia. The immediate Philadelphia area rarely has a day of Good air quality. Most summer days are Moderate to Very Unhealthy. To our west is Morgantown and Lancaster County. Even though Lancaster is a much more rural area, it continuously has some of the worst air quality in the world. So it doesn’t really matter where you live, implementing plant and Corsi-Rosenthal filtered air to the daily routine will likely improve your quality and quantity of life.

More on Clean Water, Air, and Healthy Plants
More Things You Can Do to Help the Environment and Your Health


bookmark_borderYour National Debt

by Daniel Brouse
June 8, 2023

The Economic Monsters: Inflation and Interest Rates
I Economic Forecast = Inflation (2018)
II Inflation Bites (2022)
III U.S. Mass Consumption Results in Global Economic Disparity, Inequity, and Poverty (2023)
IV Investment Recommendation: Savings Bonds / I Bonds (2023)

Part V: Your National Debt

The federal government currently has $31.83 trillion in federal debt. So, what does that mean to you?

Some economists say it doesn’t mean anything. As long as the U.S. dollar remains the world’s reserve currency, the federal government can spend without limit. Other economists disagree.

Here is what to watch for:
1. a declining influence of the dollar as the world reserve currency
The dollar has been falling out of favor with many world economies. The dollar has also been sanctioned to be used by many countries and companies. Though efforts by groups like BRICS (Brazil, Russia, India, China, and South Africa) to form their own reserve currency will likely fail, the overall dependency on the dollar is weakening. The dollar will not be able to go on with “business as usual”.

2. the amount of debt (bills, notes, bonds) being sold by the Treasury
In 2023, Congress suspended the debt ceiling. During the April – June 2023 quarter and the Treasury said, “Treasury expects to borrow $726 billion in privately-held net marketable debt, assuming an end-of-June cash balance of $550 billion. The borrowing estimate is $449 billion higher than announced in January 2023.” Now that the debt ceiling has been suspended the Treasury is staring a $1tn borrowing drive. The trillion-dollar borrowing spree will have many impacts. For instance The Financial Times reports, “analysts fear scale of new issuance following debt ceiling fight will push up yields and suck cash out of deposits.” As investors pull their savings out of bank accounts and put it into high yielding Treasuries, this will put an added burden on the already struggling banking sector and further put into play the role of the Federal Reserve.

3. the amount of national debt being bought by the Federal Reserve
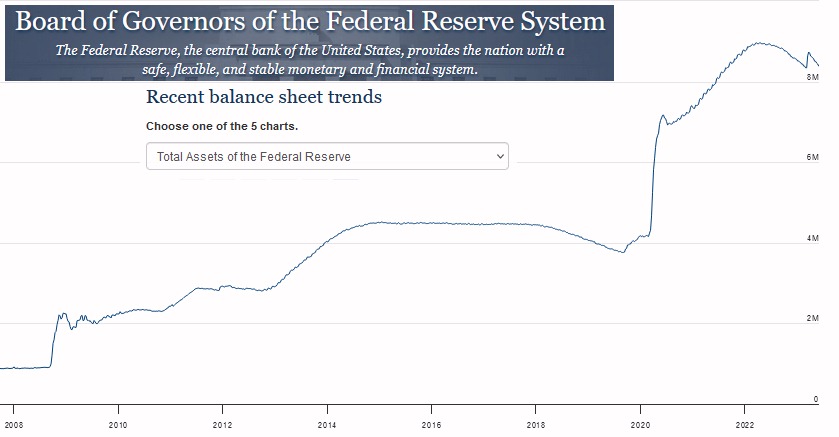
What will the Federal Reserve do? In the Spring of 2022, the Fed said they would not only stop buying Treasuries, but they would also start selling their Treasury assets. Initially, the Fed said the inflation was transitory. They were wrong. In order to fight inflation, the Fed needed to raise interest rates and reduce their assets (Treasuries). The Federal Reserve really shouldn’t be holding assets in the first place. During the financial crisis of 2007-2014, the Federal Reserve started buying trillions of dollars of assets including Treasury securities. Then during the COVID financial crisis, the Fed bought trillions more. In 2022, the Fed did stop buying Treasuries and as the securities matured, the Fed did not participate in as many Treasury rollovers. (Treasury rollover describes the process by which principal payments from maturing Treasury securities held by the SOMA are reinvested in newly auctioned securities.) However, in the graph below you see a sudden uptick in 2023.

Federal Reserve Balance Sheet Assets

The spike in assets in the Spring of 2023 was due to bank failures. The failing banks had billions of dollars in Treasuries that had lost value due to the rising interest rates. When interest rates go up, the value of existing lower yielding securities goes down. So, the Fed bought the devalued assets at full face value. The Fed may also have intervened in the markets to prop up the price of marketable securities in the open market.

What’s Next?
All of these interventions by the Fed have failed to bring inflation down to an acceptable level. Now the Treasury is going to borrow an addition 1 trillion dollars further increasing the demands on borrowing, interest rates, and the banking system. In fact, anything further the Fed does may stoke inflation. If the Fed buys more Treasuries, interest rates will be subsidized lower stimulating inflation. It will in effect be the same as printing money. Rising interest rates will increase the National Debt. Increasing the National Debt will raise interest rates. It is a vicious circle.

While our fiscal and monetary mess is unraveling, the costs of climate change are growing exponentially. Included in the debt ceiling suspension is a provision for unlimited emergency federal spending. Unfortunately this means that the government can continue to ignore the causes of climate change and instead give trillion dollar subsidies to the fossil fuel industry through emergency disaster relief. Yes, another vicious circle — more fossil fuels subsidies result in more climate catastrophes… resulting in more fossil fuel subsidies, etc. The end result will be additional trillions in government borrowing while the standard of living declines.

Recommendations
Given the above, our outlook and recommendations remain the same — persistent inflation and higher interest rates. Individual investors should max-out their annual I Bonds of up to $10k. Leftover saving should be invested in 4-week and 26-week Treasury bills. At maturity securities should be rolled over for the same length of time UNTIL interest rates peak. At that time, longer maturities should be considered.

BONUS
You can make all your transactions commission free at Treasury Direct. Marketable Treasuries are issued at a discounted rate. That means you get paid your interest in advance (giving you an even higher rate of return.)

The Economic Monsters: Inflation and Interest Rates

  1. Economic Forecast = Inflation (2018)
  2. Inflation Bites (2022)
  3. U.S. Mass Consumption Results in Global Economic Disparity, Inequity, and Poverty (2023)
  4. Investment Recommendation: Savings Bonds / I Bonds
  5. Your National Debt

Business & Economics

bookmark_borderClimate Change: Stranded on an Island

by Daniel Brouse

Climate change brings with it the inevitability of rising sea levels. Even if green house gas emissions were stopped completely, the sea will continue to rise for hundreds or thousands of years.

Not only will the submerged properties be affected by the rising tides, so will all the new island properties. Initially, some properties will just be temporarily cut-off from civilization. Eventually, those temporary islands will become permanent.

An initial reaction may be “Oh, I’ve always wanted to live on island;” however, being stranded on a deserted island is not fun. It is important to look forward and evaluate the risk in value to real estate. Much of the newly isolated land will become worthless.

ARS Technica reports, “having a property above water won’t be much good if flooding nearby means you can’t get to a hospital or grocery store when you need to or lose access to electricity or other services. It’s entirely possible for rising seas to leave a property high, dry, but uninhabitable as rising seas cut connections to essential services. A group of researchers has analyzed the risk of isolation driven by sea level rise, and shows it’s a major contributor to the future risks the US faces.”

If you’re interested in comparing the risk of isolation to that of inundation, the researchers built a website that lets you explore the risks under different sea level rise scenarios.

The Journal Nature published “Risk of isolation increases the expected burden from sea-level rise”:

The typical displacement metric for sea-level rise adaptation planning is property inundation. However, this metric may underestimate risk as it does not fully capture the wider cascading or indirect effects of sea-level rise. To address this, we propose complementing it by considering the risk of population isolation: those who may be cut off from essential services. We investigate the importance of this metric by comparing the number of people at risk from inundation to the number of people at risk from isolation. Considering inundated roadways during mean higher high water tides in the coastal United States shows, although highly spatially variable, that the increase across the United States varies between 30% and 90% and is several times higher in some states. We find that risk of isolation may occur decades sooner than risk of inundation. Both risk metrics provide critical information for evaluating adaptation options and giving priority to support for at-risk communities.

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderCOVID: Insulin Reduction, Diabetes, High Cholesterol, Heart Disease and Stroke

by Daniel Brouse
March 11, 2023

COVID=19

Post-COVID patients are at an increased risk of developing or exacerbating diabetes.

In addition, the American Heart Association (AHA) states that diabetes often lowers HDL (good) cholesterol levels and raises triglycerides and LDL (bad) cholesterol levels.

Both blood sugar and cholesterol increase the risk for heart disease and stroke.

Coronavirus Transforms Pancreas Cell Function
When COVID infects cells, it impairs cell activity and can also change their function. When insulin-producing beta cells in the pancreas become infected with the virus, they produce much less insulin than usual, and also start to produce glucose and digestive enzymes. “We call this a change of cell fate,” said study leader Dr. Shuibing Chen, who described the work in a presentation at the annual meeting of the European Association for the Study of Diabetes.

It is not clear whether the changes are long-lasting, or if they might be reversible (though individuals have been impacted more than 3-years after infection), the researchers reported in Cell Metabolism in August 2021, SARS-CoV-2 infection induces beta cell transdifferentiation. “Single-cell RNA sequencing and immunostaining from ex vivo infections confirmed that multiple types of pancreatic islet cells were susceptible to SARS-CoV-2, eliciting a cellular stress response and the induction of chemokines. Upon SARS-CoV-2 infection, beta cells showed a lower expression of insulin and a higher expression of alpha and acinar cell markers, including glucagon and trypsin1, respectively, suggesting cellular transdifferentiation. Trajectory analysis indicated that SARS-CoV-2 induced eIF2-pathway-mediated beta cell transdifferentiation, a phenotype that could be reversed with trans-integrated stress response inhibitor (trans-ISRIB). Altogether, this study demonstrates an example of SARS-CoV-2 infection causing cell fate change, which provides further insight into the pathomechanisms of COVID-19.”

Diabetes Risk Rises After COVID
A March 2022 study published in the Journal Nature found, “Even mild SARS-CoV-2 infections can amplify a person’s chance of developing diabetes, especially for those already susceptible to the disease. People who get COVID-19 have a greater risk of developing diabetes up to a year later, even after a mild SARS-CoV-2 infection, compared with those who never had the disease.”

A study published in February of 2022 in JAMA, Diabetes After COVID-19 Infection, found COVID-19 Omicron infection is linked to new-onset diabetes. COVID-19 Omicron survivors may be at a greater than 60% risk of new-onset type 1 or 2 diabetes (a potential precursor of heart attack and stroke.)

A Cedars-Sinai news release said that data trends and patterns suggest that COVID-19 may act as a disease accelerator, amplifying the risk of an illness that may have come later in life. “So, it could be that instead of being diagnosed with diabetes by age 65, a person with preexisting risk for diabetes might—after a COVID-19 infection—be more likely to develop diabetes by age 45 or 55.”

The Pennsylvania State University meta-analysis Association of COVID‑19 with Diabetes included eight studies on new-onset type 1 or 2 diabetes in COVID-19 survivors published from December 2019 to October 2022. COVID-19 was tied to a 66% higher risk of new-onset diabetes regardless of age or sex. “Given the extraordinary number of COVID-19 survivors globally, the modest increase in diabetes risk could correspond to a drastic rise in the number of people diagnosed with the disease worldwide,” the authors wrote.

Cholesterol Levels
The study Risks and burdens of incident dyslipidaemia in long COVID found people with a prior COVID infection had a 24% increased risk for high cholesterol levels.

“These are people who never had cholesterol problems before,” said Dr. Ziyad Al-Aly, an author of the study and a clinical epidemiologist at Washington University in St. Louis. “Now, all of a sudden, they started having problems weeks and months after Covid-19.”

In June of 2023, the study Incidence of Diabetes in Children and Adolescents During the COVID-19 Pandemic was published in the Journal Nature and found COVID is linked to surge in child and teen diabetes.

Increased Risk of Heart Disease and Stroke
The Centers for Disease Control says, “High blood cholesterol is a major modifiable risk factor for heart disease, the leading cause of death in the United States. A 10% decrease in total blood cholesterol levels can reduce the incidence of heart disease by as much as 30%,” and “Over time, high blood sugar can damage blood vessels and the nerves that control your heart. People with diabetes are also more likely to have other conditions that raise the risk for heart disease.”

COVID: Hypertension, Heart-disease Risk Soars

Long COVID Update: Living With It

COVID in Your Genes

MORE ON COVID: COVID-19 / SARS-CoV-2 / Novel Coronavirus

bookmark_borderAntarctic Ice Sheet Is Melting at Accelerated Rate

The Word Economic Forum published the report The Antarctic ice sheet is melting. And this is bad news for humanity.

* The Antarctic ice sheet has been strongly decreasing since 2016.
* If left unchecked, the complete melting of the West Antarctic ice sheet would cause a global sea level increase of 3.3 metres in the future, says an expert.
* At present, the world is heading towards a warming of 2.8C by the end of this century.
* The Antarctic ice sheet will therefore continue to melt and contribute to sea level rise, which will test the adaptive capacity of humanity.

The consequences of the collapsing ice sheet
The sustained melting of the West Antarctic ice sheet could indicate that an unstable retreat (which reinforces itself) is underway or imminent. However, there is high uncertainty about this phenomenon.

The mechanism that would explain this unstable retreat is known as Marine Ice Sheet Instability.

If the bed, where the ice sheet lies, slopes down towards the interior, it destabilizes the position of the grounding line — zone where this ice sheet starts to float. The thinning of the ice shelf causes this grounding line to retreat, which leads to an influx of ice from the ice sheet to the sea. This, subsequently, causes the thinning of the ice shelf and so on and so forth.

The bottom line is that the melting of the Antarctic ice sheet contributes to and will continue to contribute to sea level rise for a long time, which will test the adaptive capacity of humanity.

The sea level increase by 2100 will particularly affect the tropical countries. And so, what happens in the Antarctic will definitely not stay in the Antarctic.

In February of 2023. the Copernicus Programme issued the repot Copernicus: Antarctic sea ice extent reaches all-time minimum in February – Second warmest winter on record in Europe.

February 2023 – temperature highlights:
* February 2023 was the fifth warmest globally
* Most of Europe had above-average air temperatures, particularly northern Norway and Sweden, and the Svalbard region
* Above-average temperatures occurred in the eastern United States, northern Russia, and in Pakistan and India
* Below-average temperatures were experienced across the Iberian Peninsula, Türkiye, the western United States, * Canada, northeast Russia, and northern Australia

February 2023 – Sea ice highlights:
* Antarctic sea ice reached its lowest monthly extent in the satellite data record, at 34% below the average for February, breaking the previous record of February 2017.
* Antarctic daily sea ice extent also reached an all-time minimum, surpassing the previous record set in February 2022.
* Sea ice concentrations were much below-average in all sectors of the Southern Ocean.
* Arctic sea ice extent was 4% below average, ranking 2nd lowest for February in the satellite data record, jointly with February 2016 and 2017.
* Arctic sea ice concentrations were most below-average in the Barents Sea and Svalbard region.

Sea-level Rise: Greenland and the Collapse of the Antarctic Ice Sheet

More articles on Flood Insurance, Extreme Weather Events, Rising Sea Levels and Global Warming

bookmark_borderLong COVID Update: 3 Years of Living With It

by Daniel Brouse
March 7, 2023

COVID=19

In February of 2020, I contracted SARS-CoV-2. By May of 2020, I recognized a pattern of recurring symptoms including: difficulty breathing, congestion, cough, stomach aches, diarrhea, loss of taste and smell, temperature deregulation, night sweats, nightmares, vivid dreams, dizziness, brain fog, headaches, muscle aches, earaches, and peripheral neuropathy.

Over the next year, I was able to treat most of these symptoms with nicotinic acid; however, reducing the niacin dosage yielded increased symptoms. It was only after becoming fully vaccinated in 2021 (post-infection vaccination) that I appear to have been cured of most of the above symptoms. Approximately ninety days after my second dose of the COVID vaccine I was able to reduce my niacin dosage with no ill side effects.

The problem with long COVID is many aspects of the condition(s) do not readily present themselves. In my case, COVID appears to have permanently:
1) increased hypertension
2) increased blood sugar
3) increased cholesterol

If you have had COVID, I highly recommend a medical physical and complete blood work. Though only 10% of people “present with symptoms”, it appears COVID will impact 99% of survivors in the long-term.

With vaccination, medication, and diet, I have been able to control all of my known conditions.

I’m coming to the conclusion that there are 2 main things going on: 1) persistent virus 2) epigenetic changes

1) SARS-CoV-2 can live in organs for an indefinite period of time. Even after testing negative for weeks, the virus can be active in the brain, heart, blood, etc.

2) There appear to be dozens of epigenetic modifications.  The changes are not uniform across the population due mainly to preexisting conditions and/or predispositions (eg family history).

In my case, it is likely I had both conditions.  The persistent COVID-19 was causing most of my readily apparent symptoms.  The niacin helped treat the NAD+ deficiency but did not help clear the virus. It was only after I was fully vaccinated that I was able to clear the virus.

On the other hand, the epigenetic changes appear to be of a permanent nature.  My genes are now programmed for increased hypertension, blood sugars, and cholesterol. Unfortunately, it is quite likely I have other undetected epigenetic modifications. I am looking to my family history and being extra diligent on cancer and other health screenings.

The BBC has produced a documentary entitled The long haul of long Covid that talks about COVID induced: cognitive impairment, fatigue, lactic acid, metabolic dysfunction, micro clots, hypertension, blood sugar, diabetes, asthma, allergies, overactive immune system, muscle and joint pain, arthritis, migraines, shortness of breath, and other chronic problems.

Three years after the official declaration of a pandemic, 65 million people – one in 10 who had Covid-19 – still have symptoms. Some are so ill they are yet to return to work.

The Economist’s health editor, Natasha Loder, examines the science behind long Covid and hears about the challenges as researchers try to unravel the cause behind a condition associated with around 200 symptoms.

Natasha gains insights about the disease from Dr Walter Koroshetz, co-director of the long Covid Recover study in the United States, pulmonologist Dr Lancelot Pinto in Mumbai, India, and long Covid expert Dr Waasila Jassat in Johannesburg, South Africa.

She also meets Dr Emma Wall at London’s Francis Crick Institute to hear about the UK’s long Covid drug trial and Dr Maria Teresa Ferretti, from the Women’s Brain Project, discusses why women are twice as likely to get long Covid than men.

Some Known COVID Chronic Conditions

* Persistent SARS-CoV-2 RNA in multiple organs and throughout the brain
* Destruction of Good Gut Bacteria Resulting in a Compromised Immune System
* Epigenetic Modifications (Changes to DNA)
* Change in Cell Fate
* Tryptophan Deficiency
* Dysfunctional Kynurenine Pathway
* Neurological Damage
* New-Onset Alzheimer’s Disease
* Exertional Intolerance, Oxygen Extraction, Reduced Exercise Capacity
* Down Regulating NAD+
* Up Regulating IDO
* Rogue Antibodies
* Insulin Reduction, Diabetes, High Cholesterol, Heart Disease and Stroke
* Increased Risk of Cancer
* Blood Clots
* Hypertension, Vascular Disorders, Myocarditis and Heart Disease
* Multisystem Inflammatory Syndrome in Children (MIS-C)
* Dysregulation of the innate immune system, i.e. “cytokine storm”

MORE ON COVID: COVID-19 / SARS-CoV-2 / Novel Coronavirus

The Long COVID NAD+ Plus Immune System Diet

COVID: Heart-disease Risk Soars

COVID-19: Increased Risk of Autoimmune Diseases

COVID-19 Compromises Your Immune System (Immunocompromised)

COVID-19: reinfection increases risks of death, hospitalization and damage to multiple organs

COVID-19: Aging Accelerant

Long-COVID: 4 Out of 5 Experiencing Limitations in Daily Activities

Long-COVID: What We Know About Long Haulers Syndrome

bookmark_borderClimate Change Impacts on Flood Risks and Real Estate Values

by Daniel Brouse and Sidd Mukherjee
February 26, 2023

Climate change poses many risks to real estate values. In general, as energy is added to a system, the fluctuations in the system increase. So, we expect more storms, more droughts, more wildfires, more floods, more fluctuations of all kinds. What we are saying is that weather conditions will become more volatile due to the impact of humans. For the most part, weather events will become more extreme. Even the momentum of rain will cause a harder rain to fall damaging roofs, sidewalks, and driveways.

Some of the most vulnerable real estate is along coastlines and near floodplains. The study published in the Journal Nature Unpriced climate risk and the potential consequences of overvaluation in US housing markets found:

Climate change impacts threaten the stability of the US housing market. In response to growing concerns that increasing costs of flooding are not fully captured in property values, we quantify the magnitude of unpriced flood risk in the housing market by comparing the empirical and economically efficient prices for properties at risk. We find that residential properties exposed to flood risk are overvalued by US$121–US$237 billion, depending on the discount rate. In general, highly overvalued properties are concentrated in counties along the coast with no flood risk disclosure laws and where there is less concern about climate change. Low-income households are at greater risk of losing home equity from price deflation, and municipalities that are heavily reliant on property taxes for revenue are vulnerable to budgetary shortfalls.

Sidd Mukherjee said, “Pay close attention to Figure 4 in the main paper (top left map, zoom in to max.) The red boundaries are where properties are seriously overvalued and where tax revenues will collapse after flooding.

High Flood Risk Real Estate (The darker the color the higher the risk)

Sidd goes on to say, “Don’t miss the supplementaries.”
Flood Risk to Real Estate Supplementaries

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderEarliest Spring on Record: Climate Change in Real Time

by Daniel Brouse
February 24, 2023

Parts of Texas, Arkansas, Ohio, Maryland, and New York are all experiencing the earliest spring conditions on record. The National Phenology Network has published a study on February 21, 2023 that found:
Spring leaf out continues to spread north, arriving several days to weeks earlier than average (the period of 1991-2020) in much of the Southeast, lower Midwest, and mid-Atlantic. New York City is 32 days early, Baltimore, MD is 20 days early, and Louisville, KY is 16 days early. Much of southern California and Arizona are days to over a week late, while the coastal Northwest is days to weeks early. Phoenix, AZ is a week late. Seattle, WA is a week early.

“It’s a little unsettling, it’s certainly something that is out of the bounds of when we’d normally expect spring,” said Teresa Crimmins, director of the National Phenology Network and an environmental scientist at the University of Arizona. “It perhaps isn’t surprising, given the trajectory our planet is on, but it is surprising when you live through it.”

Parts of the Southeast, lower Midwest, and mid-Atlantic are seeing either the earliest spring on record or a spring that only occurs once every 40 years

The Human Induced Climate Change Experiment

bookmark_borderReal Estate Underwater: Displacement and Climate Refugees

by Daniel Brouse
February 22, 2023

For years climate scientists have been trying to develop models for the real estate market impacted by rising sea levels. Florida is proving to be a microcosm of coastal real estate.

“Everybody thinks this is a God-given sea level,” Harold Wanless, who heads the University of Miami’s geology department told the Miami Herald. “There’s nothing special about where the sea level is right now.”

In fact, almost all scientists agree there is going to be significant sea level rise within the next century. Miami-Dade County has developed extremely detailed elevation maps because the county is only about 6 feet above sea level with the highest elevations under 25 feet. So far, sea levels have risen about 6 inches in Miami-Dade. The rate of rise is increasing at an exponential rate.  The Southeast Florida Regional Climate Compact expects sea levels to rise 3 to 8 feet over the next century. NOAA’s extreme worst-case climate projections show sea levels rising by 14 feet in Southern Florida. Leading climate scientists expect sea levels to rise even higher and faster. “Once we have destabilized these ice sheets, there will be no stable coastline for centuries. I repeat: There will be no stable coastline for centuries. I apologize to the children,” said Sidd Mukherjee in his paper Longthaw.

It is certain that much of the coastline will not have to wait decades to see extreme sea level rise. In 2022, the West Coast of Florida saw a sudden sea level rise of up to 20 feet that destroyed 5,000 houses and damaged 35,000 additional homes. Insured damages were between $50 billion and 65 billion after Hurricane Ian made landfall with extreme winds, torrential rain, and storm surge. Uninsured damages were estimated at an additional $50 billion.

As sea levels rise, it is unclear if real estate built on higher ground will be able to retain any value. Florida real estate located at the higher elevations is still dependent on low-lying infrastructure. “You’re not going to have roads to get around on. You’re not going to have sewage treatment facilities. You won’t have garbage pickup. You won’t have a source of fresh water,” said Wanless. “All those things are the unfortunate reality of the future, and it won’t wait until sea levels have risen 20 feet.”

The inability to obtain flood insurance will likely be a leading driver in climate displacement out of Florida. If residents wait too long, they will likely become indigent climate refugees fleeing after letting their property values plunge to zero. Standard flood insurance only covers up to $250,000 of property damage, nothing below the first floor, and cumulative to the life of the property. (That is to say, if a previous homeowner made a claim of $100,000, the new homeowner is only covered for $150,000.) In the event a homeowner is able to obtain a flood insurance policy, the cost of the insurance has been increasing yearly. In 2022, FEMA announced its new pricing policy: “FEMA is updating the National Flood Insurance Program’s (NFIP) risk rating methodology through the implementation of a new pricing methodology called Risk Rating 2.0. The methodology leverages industry best practices and cutting-edge technology to enable FEMA to deliver rates that are actuarily sound, equitable, easier to understand and better reflect a property’s flood risk.” Flood insurance rates have quadrupled in Miami-Dade County.

FEMA also has the 50% rule — the 50% Rule is a regulation of the National Flood Insurance Program (NFIP) that prohibits improvements to a structure exceeding 50% of its market value unless the entire structure is brought into full compliance with current flood regulations. Many existing structures cannot be rebuilt to their previous size, or for structures like trailers they cannot be rebuilt at all.

Quite a few private insurance companies have pulled out of Florida altogether. Five Florida insurance companies have already pulled out of the state. In addition, these private insurers are in liquidation:
AMERICAN CAPITAL ASSURANCE CORPORATION
AVATAR PROPERTY AND CASUALTY INSURANCE COMPANY
FEDNAT INSURANCE COMPANY
FLORIDA SPECIALTY INSURANCE COMPANY
GUARANTEE INSURANCE COMPANY
GULFSTREAM PROPERTY AND CASUALTY INSURANCE COMPANY
PHYSICIANS UNITED PLAN, INC.
SOUTHERN FIDELITY INSURANCE COMPANY
ST. JOHNS INSURANCE COMPANY, INC.
SUNSHINE STATE INSURANCE COMPANY
UNIVERSAL HEALTH CARE INSURANCE COMPANY, INC.
UNIVERSAL HEALTH CARE, INC.
WESTON PROPERTY & CASUALTY INSURANCE COMPANY
WINDHAVEN INSURANCE COMPANY

The Florida Office of Insurance Regulation has had to step in and provide state assistance for reinsurance coverage through state-run Citizens Property Insurance. The St. Lucie News Tribune reports, “The dramatic decision to assume financial responsibility for a raft of struggling insurers underscores the dire circumstances Florida is facing as a large portion of its homeowners insurance market teeters on the brink of collapse.”

Most mortgages require homeowner’s insurance in addition to flood insurance for properties located in a flood zone. Washington, D.C. is finally addressing the concept of some areas being too vulnerable to insure and addressing a
“Managed Retreat”.

Some Florida residents have already glimpsed the future and are moving out now. The Insider reports:

The Faasts had lived the kind of life you can only live in the Keys: Connie worked on commercial fishing boats and in a local aquarium, while Glenn owned a boat maintenance company and raced Jet Skis in his spare time. They had stuck it out in the Keys through several major storms, including 2005’s Hurricane Wilma, which brought five feet of water to their little island and totaled three of their cars; Connie still shudders when she remembers the image of her husband wading through the water around their house with snakes climbing all over him, clinging to him for shelter from the flood. The Faasts had second thoughts after that storm, but the Keys were paradise, and besides, they didn’t know where else they would go.

When Irma came 12 years later, though, the choice was much easier. During the evacuation, it took the Faasts a week to find a decaying hotel in Orlando where they could wait out the storm. As the hurricane passed over the center of the state, it knocked out their power, leaving them and their pets to spend the night in 100-degree heat without air conditioning. “That was it for us,” she said. They had to get out — not just out of the Keys, but out of Florida altogether.

In conclusion:
Do not buy real estate on or near floodplain. You can avoid being a climate refuge due to economic climate displacement. Make sure your property has land ingress and egress from the closest 1,000-year-floodplain. Do not invest in any property located near a coast. Do not invest in a property that is below sea level. Do not invest in real estate located in Florida.

“Mostly stay away from the coasts because of both wind and rain issues from weather systems spinning inland. Even if you are not in a floodplain, a couple feet of rain in a day will cut off roads and overwhelm your sump pumps. Not to speak of wind taking power and telecom down.” — Sidd Mukerhjee (February 5, 2018)

More articles on Flood Insurance, Rising Sea Levels and Global Warming.