bookmark_borderLow-Level Ozone: The Invisible Climate Pollutant Threatening Human Health and Accelerating Global Warming

by Daniel Brouse

Introduction

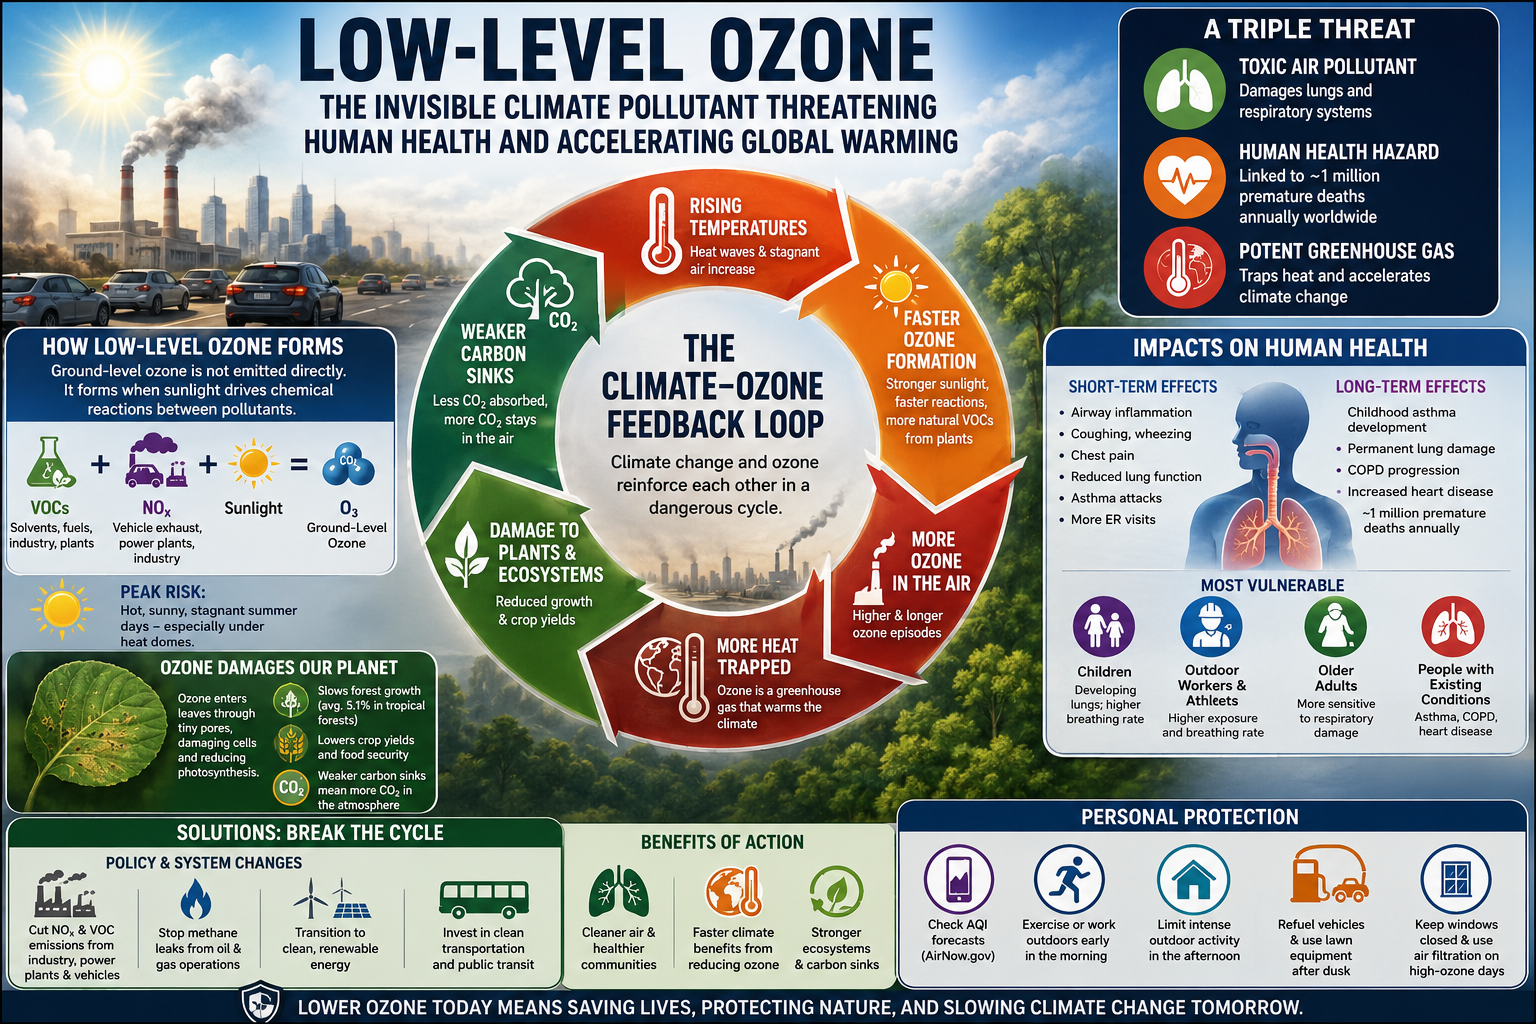
Low-level ozone (tropospheric ozone) has emerged as one of the most dangerous yet underappreciated pollutants affecting both human health and Earth’s climate system. Unlike the protective ozone layer high in the stratosphere, ground-level ozone is a toxic gas that damages the lungs, weakens ecosystems, reduces agricultural productivity, and traps heat in the atmosphere.

Ozone is also a key component of a powerful climate feedback loop. As temperatures rise, ozone formation accelerates. In turn, ozone damages forests and other vegetation that normally remove carbon dioxide from the atmosphere, weakening these natural carbon sinks while simultaneously acting as a greenhouse gas itself.

Because ozone is highly reactive and short-lived, measuring its full health impacts is challenging. Current research estimates that long-term exposure to ozone contributes to approximately one million premature deaths worldwide each year, although the true burden may be substantially higher due to the difficulty of isolating ozone exposure from other air pollutants.

Low-level ozone therefore represents a dangerous triple threat:

  • A highly reactive air pollutant
  • A major human health hazard
  • A potent short-lived greenhouse gas

The Formation of Low-Level Ozone

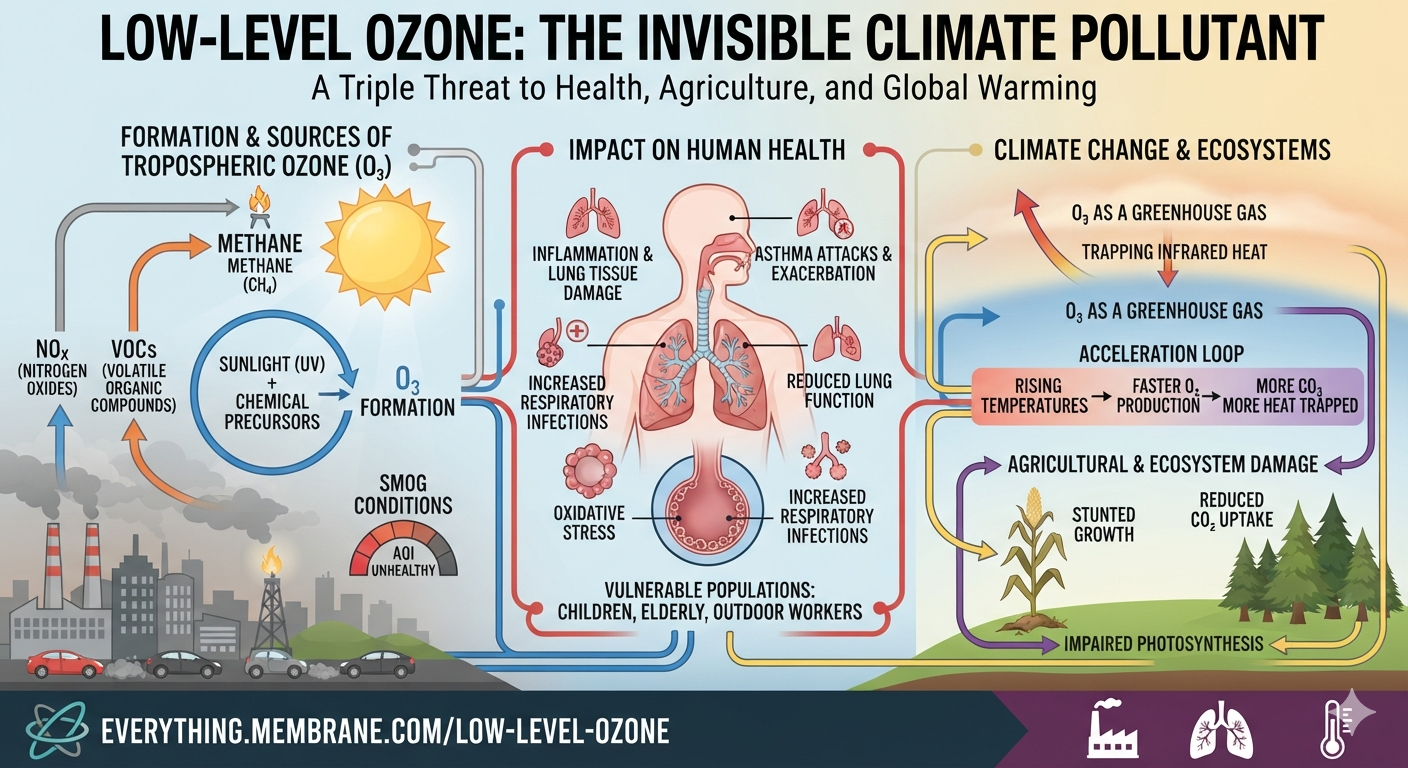
Ground-level ozone is the primary ingredient of urban smog. Unlike many pollutants, it is not emitted directly from vehicles or industrial facilities. Instead, it forms through sunlight-driven chemical reactions involving precursor pollutants.

Ozone Formation

Volatile Organic Compounds (VOCs) + Nitrogen Oxides (NOₓ) + Sunlight → Ozone (O₃)

Major Sources of Ozone Precursors

Nitrogen oxides (NOₓ) originate from:

  • Motor vehicles
  • Power plants
  • Industrial boilers
  • Ships and aircraft

Volatile Organic Compounds (VOCs) originate from:

  • Gasoline vapors
  • Chemical manufacturing
  • Paints and solvents
  • Oil and gas production
  • Vegetation (especially during hot weather)

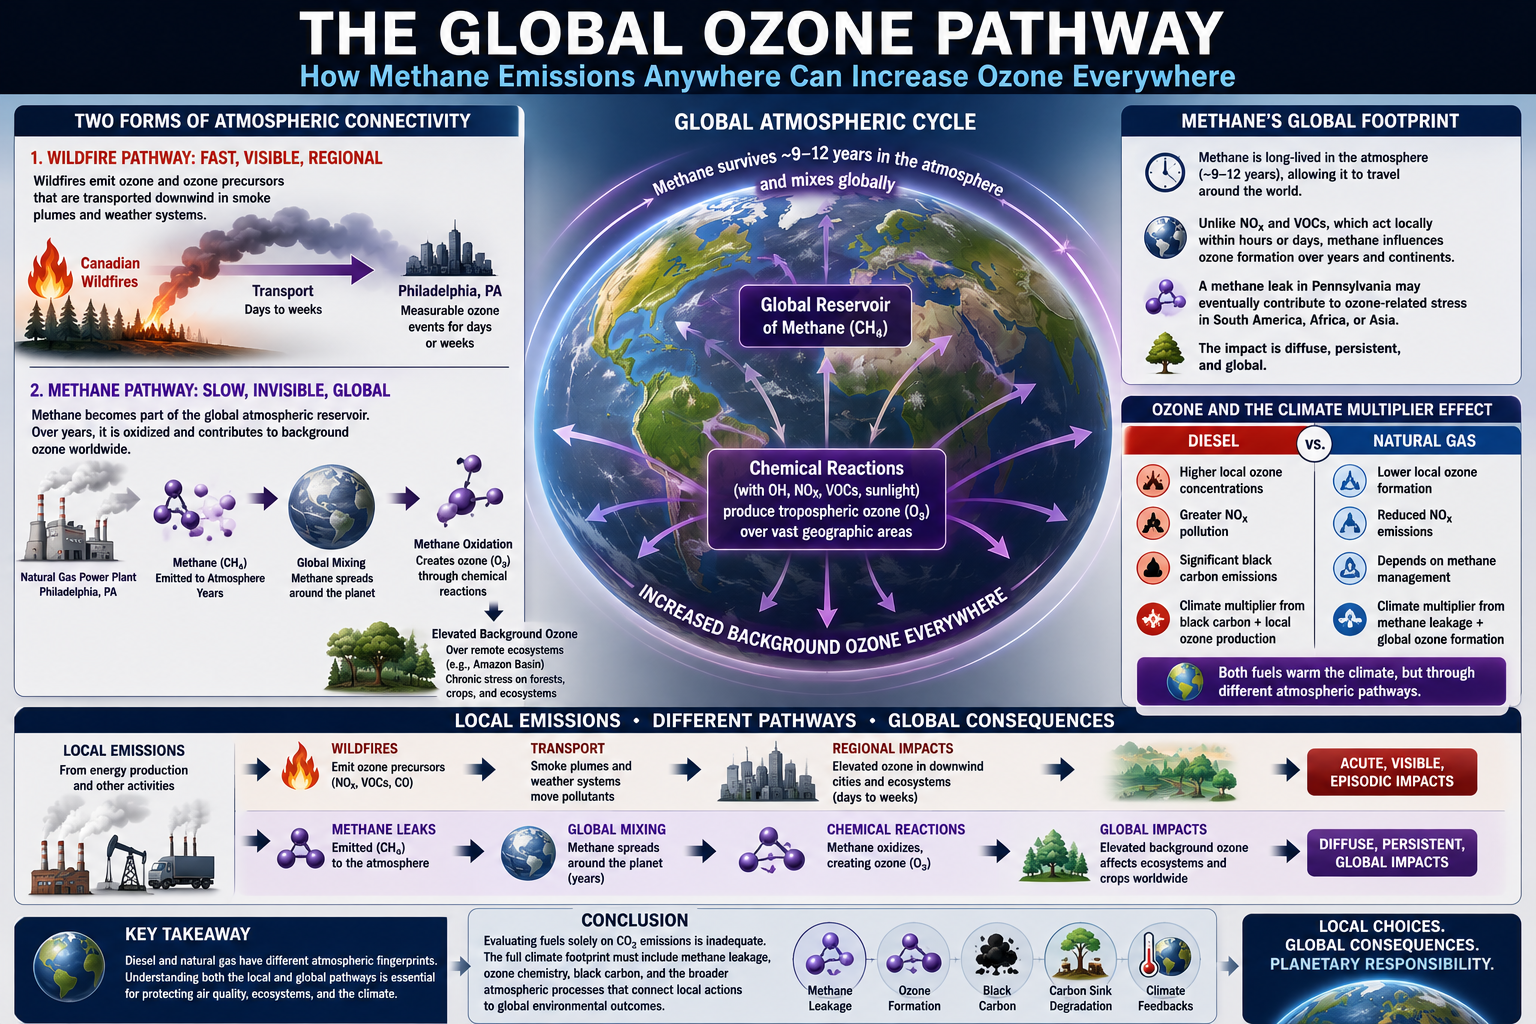
Methane also contributes to background ozone formation on a global scale.

Because sunlight powers these reactions, ozone concentrations typically peak during hot, sunny, stagnant summer afternoons, particularly beneath persistent high-pressure systems and heat domes.


Human Health Impacts

When inhaled, ozone behaves like a powerful oxidizing chemical that attacks delicate lung tissue. It inflames the respiratory system, damages airway cells, and reduces lung function within minutes of exposure.

Many physicians describe ozone as acting like “sandpaper on the lungs.”

Short-Term Health Effects

Acute exposure may cause:

  • Airway inflammation
  • Chest pain during deep breathing
  • Persistent coughing
  • Wheezing
  • Shortness of breath
  • Reduced lung capacity
  • Increased asthma attacks
  • More emergency room visits

Long-Term Health Effects

Repeated exposure has been associated with:

  • Childhood asthma development
  • Permanent lung tissue damage
  • Reduced lung growth
  • Chronic Obstructive Pulmonary Disease (COPD) progression
  • Increased cardiovascular disease
  • Elevated risk of premature death

Current global estimates attribute roughly one million premature deaths annually to ozone exposure.

NOTE: to effectively filter ozone, you need a respirator equipped with an activated carbon (charcoal) layer or organic vapor chemical cartridges. Standard particulate masks (like basic N95s) will only filter dust, not harmful ozone gas.


Who Is Most Vulnerable?

Although ozone affects everyone, several populations experience substantially greater risk.

Children

Children breathe more air per pound of body weight than adults while their lungs are still developing, making them particularly susceptible to permanent respiratory damage.

Older Adults

Age-related declines in lung function and higher rates of cardiovascular disease increase sensitivity to ozone exposure.

Outdoor Workers and Athletes

Construction workers, landscapers, agricultural workers, first responders, and athletes inhale much larger volumes of air during physical activity, resulting in higher ozone doses.

People with Existing Health Conditions

Individuals with:

  • Asthma
  • COPD
  • Emphysema
  • Chronic bronchitis
  • Heart disease

often experience significantly worsened symptoms during high-ozone events.


The Climate-Ozone Feedback Loop

Climate change and ozone pollution reinforce one another through a powerful positive feedback loop.

Rising Temperatures
         │
         ▼
 Faster Ozone Formation
         │
         ▼
 More Greenhouse Warming
         │
         ▼
 Increased Heat Waves
         │
         ▼
 More Ozone Formation

At the same time:

Higher Ozone
      │
      ▼
Plant Damage
      │
      ▼
Reduced Photosynthesis
      │
      ▼
Weaker Carbon Sinks
      │
      ▼
Higher Atmospheric CO₂
      │
      ▼
More Global Warming

These interconnected feedbacks accelerate both climate change and declining air quality.


The Ozone Climate Penalty

One of the most concerning consequences of climate change is the ozone climate penalty.

Even if emissions of NOₓ and VOCs remain unchanged, warmer temperatures alone increase ozone production by:

  • Accelerating atmospheric chemical reactions
  • Increasing the frequency of stagnant air masses
  • Producing longer-lasting heat domes
  • Extending the ozone season
  • Increasing wildfire smoke, which adds additional ozone precursors

As global temperatures continue to rise, ozone episodes become both more frequent and more intense.


Stressed Ecosystems Produce More Ozone

Plants themselves contribute to ozone formation.

During hot weather, many tree species release larger amounts of natural volatile organic compounds (especially isoprene).

Normally these emissions are harmless.

However, when mixed with human-produced NOₓ pollution, they significantly increase ozone production.

This creates another reinforcing feedback:

Higher temperatures → More natural VOC emissions → More ozone → More warming


Ozone as a Greenhouse Gas

Tropospheric ozone is also a significant short-lived climate pollutant.

It absorbs infrared radiation escaping from Earth’s surface, trapping heat within the lower atmosphere.

Although ozone remains in the atmosphere for only weeks, it is continuously regenerated through pollution, making it an important contributor to ongoing global warming.

Reducing ozone precursors can therefore improve both air quality and climate within relatively short timeframes.


Destruction of Carbon Sinks

One of ozone’s most overlooked impacts is its damage to global vegetation.

Ozone enters plants through microscopic leaf openings called stomata.

Once inside, it damages cells responsible for photosynthesis.

Consequences include:

  • Slower forest growth
  • Reduced crop yields
  • Lower photosynthetic efficiency
  • Increased tree mortality
  • Reduced carbon sequestration

Research indicates that ozone exposure has reduced tropical forest growth by approximately 5%, significantly weakening one of Earth’s largest natural carbon sinks.

As forests lose their ability to absorb carbon dioxide, more CO₂ remains in the atmosphere, accelerating climate change.


Breaking the Feedback Loop

Reducing ozone pollution requires both public policy and individual action.

Policy Solutions

Reduce Ozone Precursors

  • Strengthen NOₓ emission standards
  • Reduce methane leaks from oil and gas production
  • Limit industrial VOC emissions
  • Improve vehicle emission controls

Transition to Clean Energy

Replacing fossil fuels with renewable energy simultaneously reduces:

  • NOₓ emissions
  • VOC emissions
  • Methane leakage
  • Carbon dioxide emissions

This provides immediate health benefits while slowing climate change.


Personal Protection

Individuals can reduce their exposure during ozone episodes by:

  • Monitoring the Air Quality Index (AQI)
  • Limiting strenuous outdoor activity during the afternoon
  • Exercising early in the morning
  • Keeping windows closed on high-ozone days
  • Using indoor air filtration when available
  • Delaying vehicle refueling and gasoline-powered lawn equipment use until evening
  • Following local air quality alerts

Conclusion

Low-level ozone is far more than an urban air pollutant. It is a toxic oxidant that harms nearly every organ system, weakens forests and crops, reduces Earth’s capacity to absorb carbon dioxide, and contributes directly to global warming.

As climate change intensifies, rising temperatures create conditions that generate even more ozone, establishing a dangerous positive feedback loop in which warming degrades air quality, and degraded air quality accelerates further warming.

Breaking this cycle requires reducing fossil fuel emissions, limiting methane and ozone precursors, protecting vulnerable populations during high-ozone events, and accelerating the transition to cleaner energy systems. Because ozone is a short-lived climate pollutant, reducing its formation offers one of the fastest opportunities to improve public health while slowing the pace of climate change.
bookmark_borderAir Quality and Climate Change: The Hidden Health Crisis of Global Warming

by Daniel Brouse

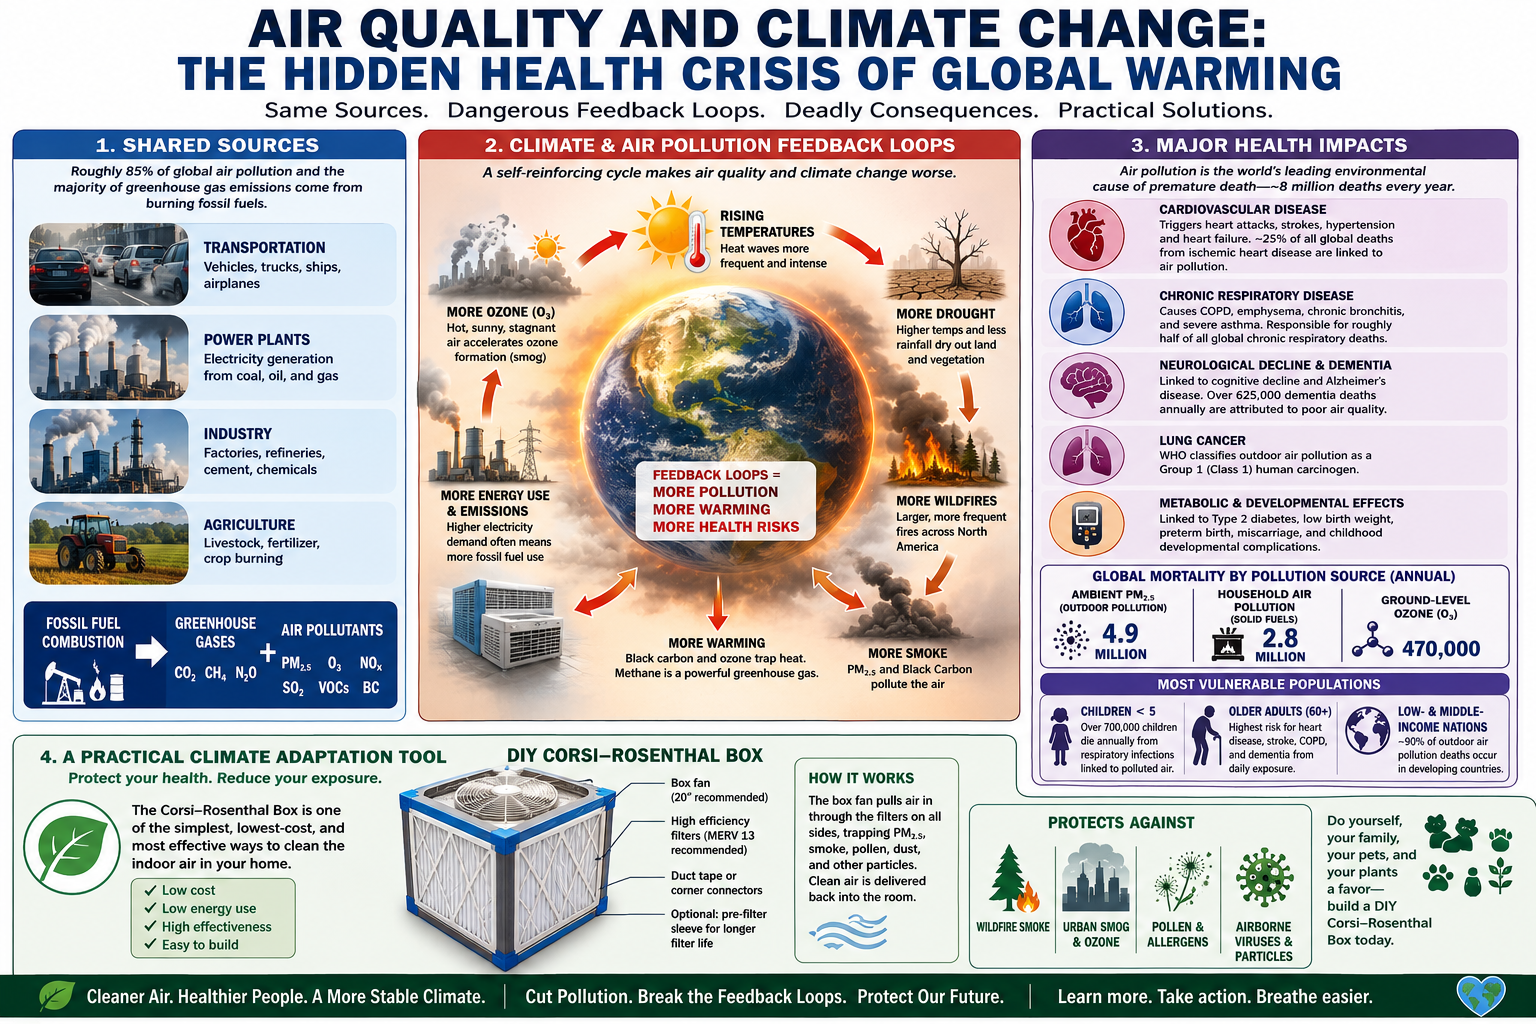
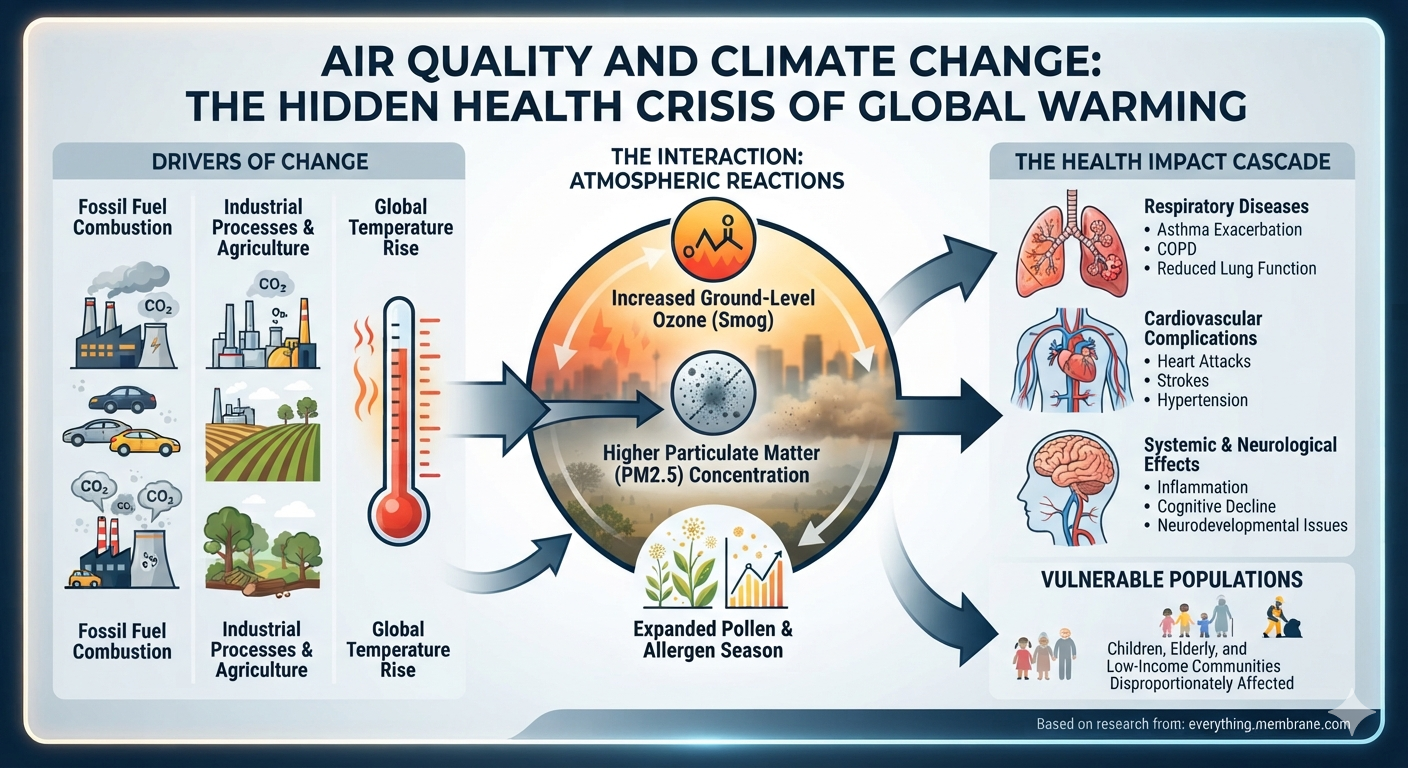
Air pollution and climate change are deeply interconnected because both are driven primarily by the combustion of fossil fuels. Many of the same pollutants that degrade local air quality—including ground-level ozone (O₃), methane (CH₄), and black carbon (soot)—also act as powerful climate forcers that accelerate global warming.

The relationship is bidirectional: climate change worsens air pollution, while air pollution further accelerates climate change through multiple reinforcing feedback loops.

Shared Sources

Approximately 85% of global air pollution and the majority of greenhouse gas emissions originate from burning fossil fuels for transportation, electricity generation, industry, and agriculture. Reducing fossil fuel consumption therefore provides one of the greatest opportunities to improve both climate stability and public health simultaneously.

Climate Change Worsens Air Pollution

As temperatures rise, air quality deteriorates through several mechanisms:

  • Ground-Level Ozone: Hot, sunny, stagnant weather accelerates the chemical reactions that produce ground-level ozone—the primary ingredient of urban smog. Climate warming increases both the frequency and severity of dangerous ozone episodes.
  • Wildfire Smoke: Rising temperatures, prolonged droughts, and changing precipitation patterns increase the frequency and intensity of wildfires. Smoke from these fires releases enormous quantities of fine particulate matter (PM₂.₅), causing hazardous air quality over vast regions.
  • Longer Pollution Episodes: Heat domes and stagnant high-pressure systems trap pollutants near the ground for extended periods, allowing contaminants to accumulate to unhealthy concentrations.

Air Pollution: The World’s Leading Environmental Killer

Air pollution is the leading environmental risk factor for premature death. Each year, exposure to polluted air contributes to an estimated 7.9–8.1 million premature deaths worldwide—approximately one out of every eight deaths globally. This exceeds the annual mortality attributed to tobacco use.

Nearly 90% of this health burden results from chronic noncommunicable diseases that are either caused or worsened by long-term exposure to polluted air.

Major Health Effects

Microscopic pollutants, particularly fine particulate matter (PM₂.₅), penetrate deep into the lungs and enter the bloodstream, triggering widespread inflammation throughout the body.

Cardiovascular Disease

Air pollution significantly increases the risk of heart attacks, strokes, hypertension, and heart failure. Approximately one-quarter of all global deaths from ischemic heart disease are linked to polluted air.

Chronic Respiratory Disease

Long-term exposure contributes directly to:

  • Chronic Obstructive Pulmonary Disease (COPD)
  • Emphysema
  • Chronic bronchitis
  • Severe asthma

Air pollution accounts for roughly half of all deaths from chronic respiratory diseases worldwide.

Neurological Disease

Growing evidence links chronic air pollution exposure to cognitive decline, Alzheimer’s disease, and other forms of dementia. Recent global estimates attribute more than 625,000 dementia-related deaths annually to poor air quality.

Cancer

The World Health Organization classifies outdoor air pollution as a Group 1 (Class 1) human carcinogen, the same highest-risk category used for tobacco smoke and asbestos. Long-term exposure substantially increases the risk of lung cancer.

Metabolic and Developmental Disorders

Research also links air pollution to:

  • Type 2 diabetes
  • Low birth weight
  • Premature birth
  • Miscarriage
  • Childhood developmental disorders
  • Reduced cognitive development

Global Mortality by Pollution Source

Most pollution-related deaths result from three primary exposure pathways:

SourceEstimated Annual Deaths
Ambient PM₂.₅ (outdoor pollution)4.9 million
Household air pollution (solid fuels)2.8 million
Ground-level ozone (O₃)470,000

Together, these exposure pathways account for approximately 8 million premature deaths every year.

Most Vulnerable Populations

The health burden of air pollution is not evenly distributed.

Young Children

More than 700,000 children under age five die annually from respiratory infections associated with polluted air, making air pollution the second-leading environmental risk factor for early childhood mortality.

Older Adults

Adults over age 60 experience the highest rates of pollution-related cardiovascular disease, respiratory illness, stroke, and dementia.

Low- and Middle-Income Countries

Approximately 90% of outdoor air pollution deaths occur in developing nations, where rapid industrialization, heavy reliance on fossil fuels, and limited access to healthcare combine to create disproportionate health risks.


Air Pollution and Climate Feedback Loops

Air pollution is not merely a consequence of climate change—it also reinforces it.

Several important feedback loops illustrate this interaction:

Fossil Fuel Combustion → Greenhouse Gas Emissions → Global Warming → More Wildfires → More Smoke (PM₂.₅ and Black Carbon) → Additional Atmospheric Heating

Global Warming → Higher Temperatures → Increased Ground-Level Ozone → Poorer Air Quality → Greater Public Health Impacts

Extreme Heat → Increased Air Conditioning Demand → Higher Electricity Consumption → Greater Fossil Fuel Use (where grids remain carbon-intensive) → More Greenhouse Gas Emissions → Additional Warming

These reinforcing cycles demonstrate why improving air quality is also an effective climate mitigation strategy.


A Practical Climate Adaptation Tool

While reducing greenhouse gas emissions remains essential, individuals can take practical steps to reduce their exposure to worsening air pollution.

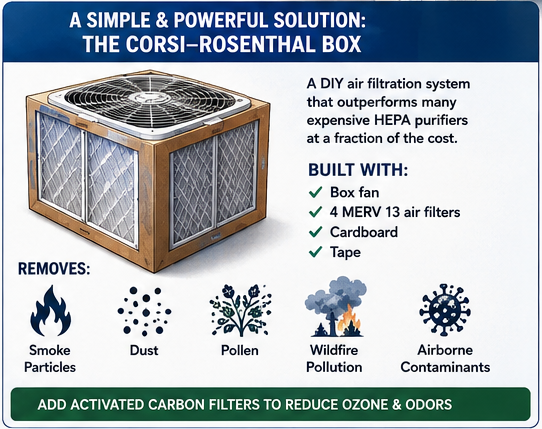
One of the simplest, least expensive, and most effective indoor air filtration systems is the Corsi–Rosenthal Box.

Constructed from four or five high-efficiency furnace filters and a standard box fan, a Corsi–Rosenthal Box can remove large amounts of smoke, dust, pollen, and airborne particulate matter at a fraction of the cost of commercial air purifiers.

Its energy efficiency is particularly important because it helps improve indoor air quality without significantly increasing electricity demand. This is especially valuable as climate change drives greater air-conditioning use, creating another reinforcing feedback loop:

More Heat → More Air Conditioning → Greater Energy Demand → More Greenhouse Gas Emissions (where electricity is fossil-fuel based) → Additional Warming

A Corsi–Rosenthal Box helps break part of this cycle by providing highly effective air filtration using very little electricity.

Whether you’re protecting yourself from wildfire smoke, urban smog, allergens, or airborne viruses, it is one of the most cost-effective climate adaptation tools available.

Do yourself, your family, your pets, and even your houseplants a favor—build a DIY Corsi–Rosenthal Box.

Corsi–Rosenthal Box Instructions

Corsi–Rosenthal Box Instructions

bookmark_borderClimate Control Feedback Loops

Climate Control Feedback Loops: When Cooling Becomes Part of the Climate System

How the growing need for air conditioning is creating new reinforcing climate feedbacks

Introduction

For most of the twentieth century, air conditioning was considered a luxury in many parts of the world. Today, in an increasing number of regions, it is becoming essential for human health and survival. As climate change drives longer, hotter, and more humid heat waves, indoor climate control is rapidly shifting from a convenience to a critical component of public safety.

This transition carries an important consequence that is often overlooked: climate control itself is becoming part of the climate system. Cooling technologies are increasingly intertwined with energy production, infrastructure resilience, water availability, urban design, and greenhouse gas emissions. As societies become more dependent on mechanical cooling, air conditioning becomes linked to a growing number of reinforcing climate feedback loops.

Many of these feedbacks are indirect, but together they form an interconnected system capable of amplifying both climate risks and societal vulnerability. Understanding these emerging “climate control feedback loops” is becoming increasingly important as the world enters an era of persistent extreme heat.


Heat Is Becoming a Public Health Emergency

Heat waves are starting earlier, becoming more intense, and lasting longer as climate change reshapes weather patterns around the world. In the United States, extreme heat events have become dramatically more likely because of human-caused global warming. Similar trends are occurring across Europe, the United Kingdom, Asia, Australia, and many developing nations where populations and infrastructure were never designed for prolonged extreme heat.

Extreme heat is far more than an inconvenience—it is a major public health hazard.

High temperatures place increasing stress on the cardiovascular system, kidneys, lungs, and immune system while reducing the body’s ability to regulate its core temperature. Heat exhaustion, heat stroke, dehydration, and cardiovascular failure become more common during prolonged heat events. Emerging research also suggests that some heat-related cellular and metabolic impacts may occur at lower temperatures than previously believed, particularly when high humidity limits the body’s ability to cool itself through perspiration.

As these conditions become more common, reliable indoor cooling increasingly becomes a life-saving necessity rather than simply a comfort.


Climate Control Is Becoming Critical Infrastructure

Modern societies are becoming increasingly dependent upon:

  • air conditioning
  • electrical grids
  • water infrastructure
  • cooling centers
  • healthcare systems
  • refrigeration
  • telecommunications
  • indoor climate stabilization technologies

Each of these systems depends upon the others.

Hospitals require electricity to operate cooling systems.

Power plants often require large amounts of water for cooling.

Water systems require electricity to pump and distribute water.

Telecommunications rely upon climate-controlled data centers.

The result is an increasingly interconnected infrastructure network that becomes progressively more vulnerable during extreme heat.


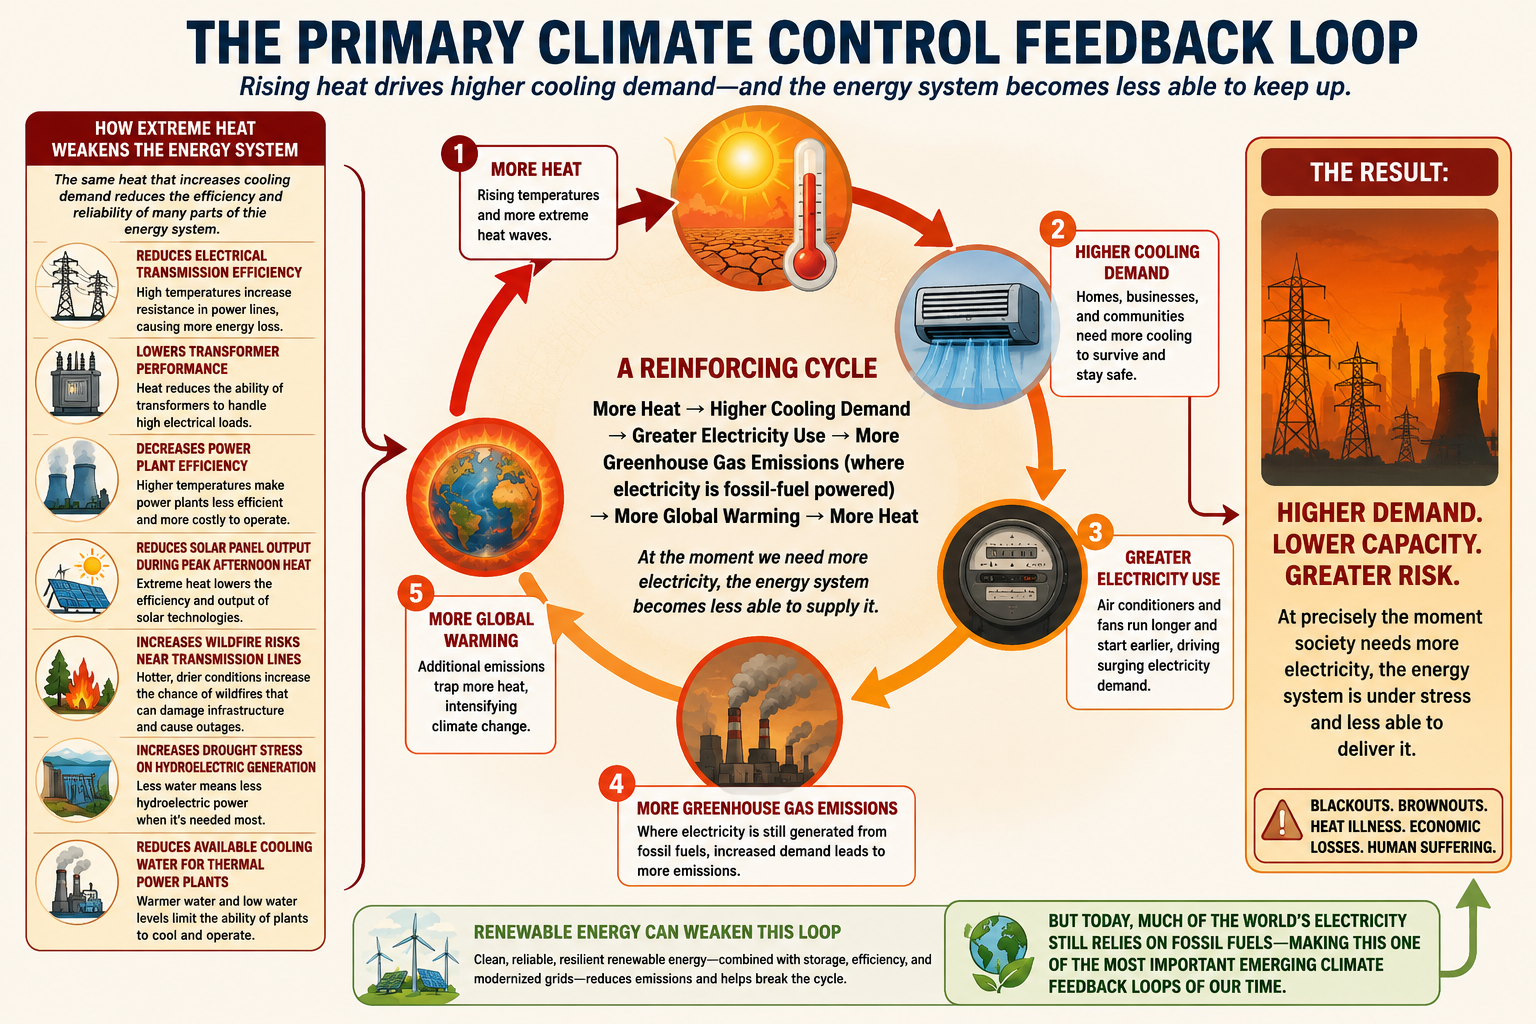
The Primary Climate Control Feedback Loop

As temperatures rise, cooling demand rises simultaneously.

Unfortunately, the same heat that increases cooling demand also reduces the efficiency of many parts of the energy system.

Extreme heat can:

  • reduce electrical transmission efficiency
  • lower transformer performance
  • decrease power plant efficiency
  • reduce solar panel output during peak afternoon heat
  • increase wildfire risks near transmission lines
  • increase drought stress on hydroelectric generation
  • reduce available cooling water for thermal power plants

At precisely the moment society needs more electricity, the energy system often becomes less capable of supplying it.

The reinforcing cycle becomes:

More Heat → Higher Cooling Demand → Greater Electricity Use → More Greenhouse Gas Emissions (where electricity is fossil-fuel powered) → More Global Warming → More Heat

Although renewable energy can weaken this loop, much of the world’s electricity still relies upon fossil fuels, making this one of the most important emerging climate feedbacks.


Additional Climate Control Feedback Loops

Urban Heat Island Feedback

Cities absorb enormous amounts of solar energy through asphalt, concrete, brick, and roofing materials.

Air conditioners remove heat from inside buildings but release that heat outdoors through their condensers.

As more buildings use air conditioning:

Indoor Heat → Outdoor Heat Release → Higher Urban Temperatures → Greater Air Conditioning Demand → More Waste Heat

Large cities can become several degrees warmer simply from accumulated waste heat released by millions of cooling systems operating simultaneously.


Electrical Grid Feedback

As cooling demand grows:

Heat Wave → Air Conditioning Demand Surges → Grid Stress → Brownouts or Blackouts → Loss of Cooling → Higher Heat Illness and Mortality

During major heat waves, the electrical grid itself becomes one of the most vulnerable components of society.

Power failures during extreme heat can quickly become humanitarian disasters.


Water Infrastructure Feedback

Many cooling systems depend upon water.

Meanwhile, hotter temperatures increase evaporation while drought reduces water supplies.

Climate Warming → Drought → Reduced Water Supply → Less Cooling Capacity → Greater Heat Stress → Increased Cooling Demand

Thermoelectric power plants, cooling towers, and some industrial cooling systems all become less reliable during water shortages.


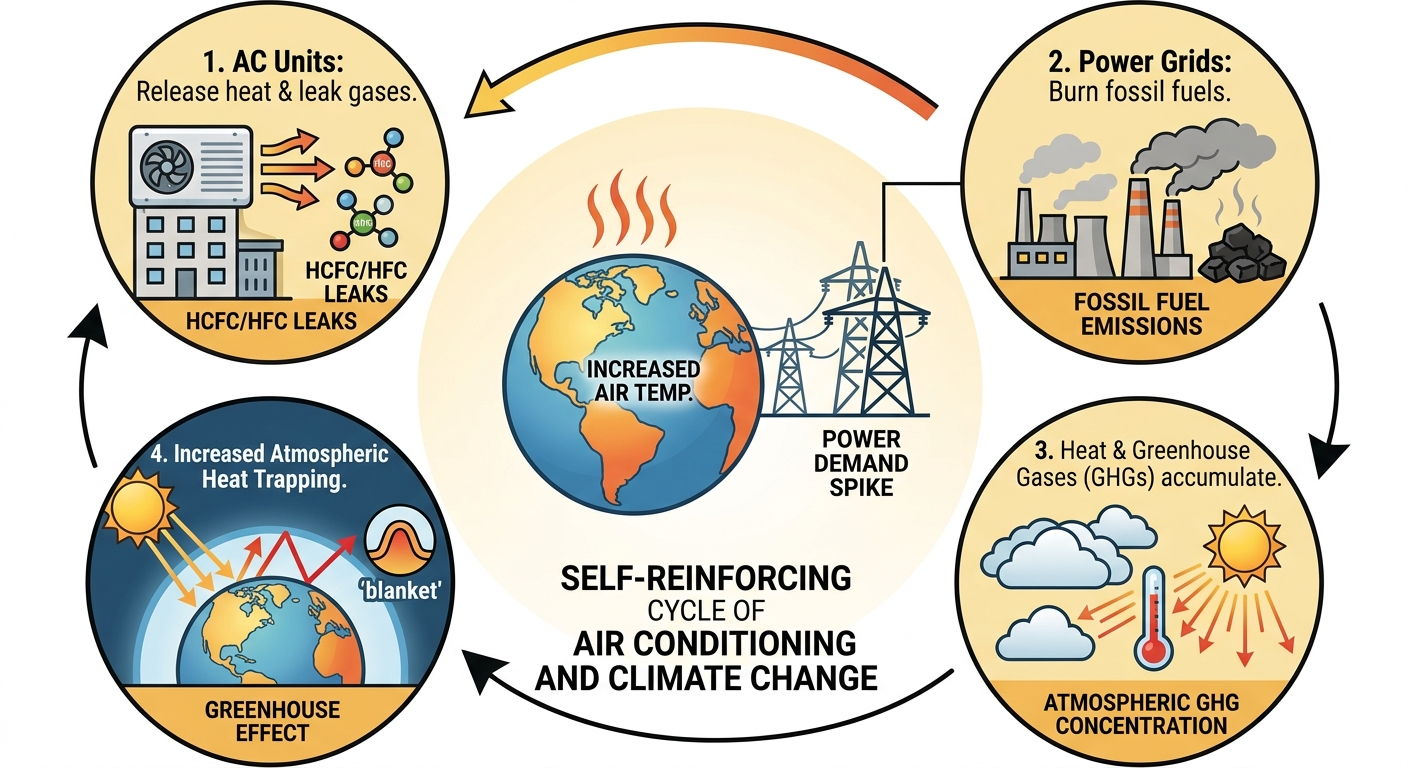
Refrigerant Feedback

Although newer refrigerants are improving, many cooling systems still contain gases with very high global warming potential.

More Cooling Equipment → More Refrigerant Leakage → Increased Greenhouse Warming → More Heat → More Cooling Equipment

Even relatively small refrigerant leaks can have significant climate impacts if high-global-warming-potential gases are involved.


Healthcare Feedback

Extreme heat increases hospital admissions.

Hospitals require continuous climate control.

More Heat → More Heat Illness → Greater Hospital Demand → Higher Energy Consumption → Additional Emissions → More Heat

Healthcare systems become both victims of climate change and contributors to increased energy demand.


Economic Productivity Feedback

Extreme heat lowers worker productivity.

Businesses compensate by increasing indoor cooling.

Higher Temperatures → Lower Worker Productivity → Increased Air Conditioning Use → Greater Energy Demand → Additional Warming

This loop becomes especially important in manufacturing, warehouses, offices, and logistics.


Housing Inequality Feedback

Not everyone can afford adequate cooling.

Communities with limited access to air conditioning experience greater illness, higher mortality, and reduced economic resilience.

Lower Income → Less Cooling → Greater Heat Exposure → Reduced Economic Opportunity → Continued Inability to Invest in Cooling

Climate change increasingly amplifies existing socioeconomic inequalities.


How Wildfire Smoke Increases Air Conditioning Demand

Wildfire smoke illustrates how climate feedbacks can extend well beyond temperature alone.

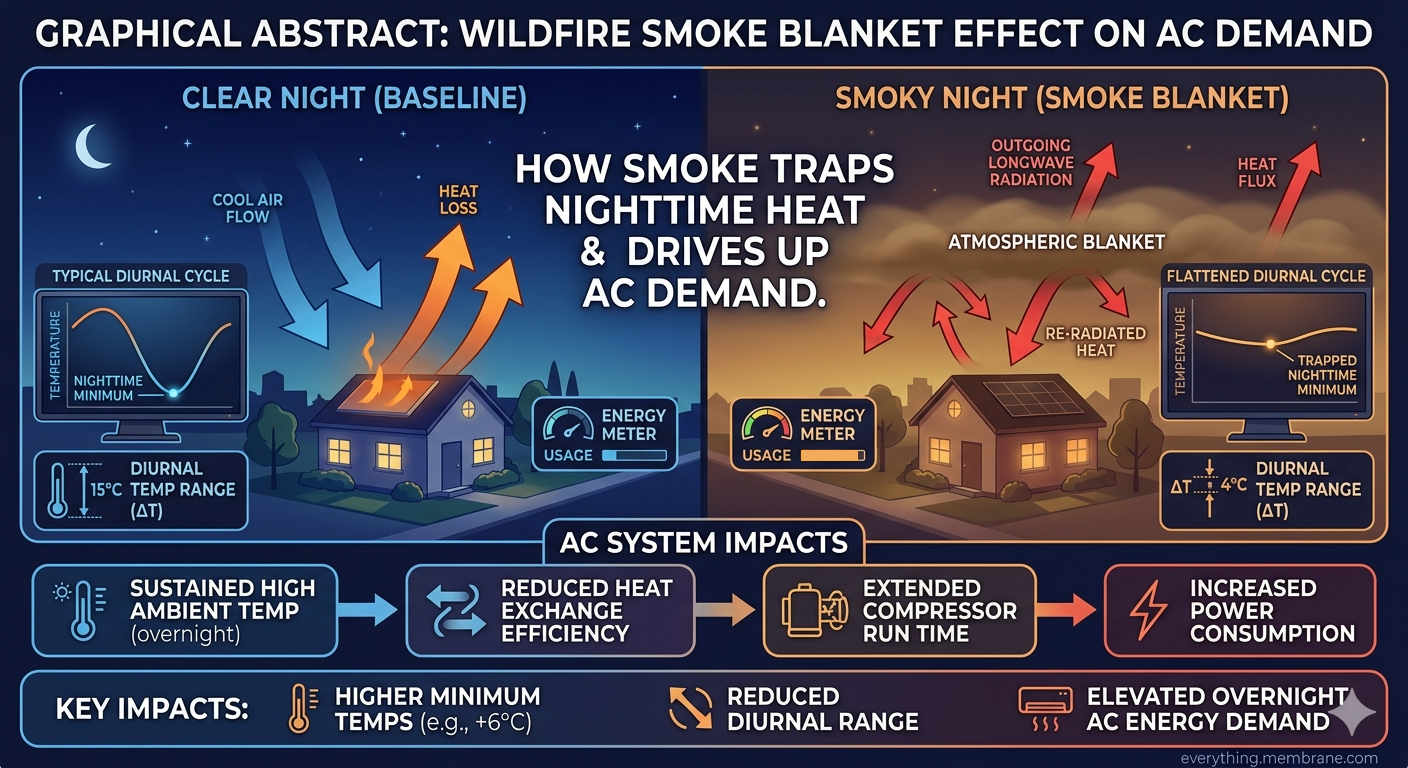
Smoke contains aerosols, soot, and black carbon that alter the atmosphere in multiple ways. During the day, dense smoke may partially block incoming sunlight in some locations. At night, however, smoke acts like an insulating blanket by absorbing and re-radiating longwave infrared radiation emitted from Earth’s surface. Instead of allowing accumulated daytime heat to escape efficiently into space, smoke traps a portion of that heat near the ground.

Buildings normally cool overnight by releasing stored heat through roofs, walls, windows, and ventilation. When smoke reduces nighttime cooling:

  • buildings retain more heat overnight
  • indoor temperatures begin each morning at a higher level
  • air conditioners start earlier
  • cooling systems operate longer
  • afternoon peak electricity demand increases
  • electrical grids experience additional stress

Where electricity generation still depends on fossil fuels, increased cooling demand can produce additional greenhouse gas emissions.

Wildfire smoke also deposits black carbon onto snow and ice. Darkened snow absorbs more solar radiation, reducing surface reflectivity (albedo) and accelerating melting. Faster snow and ice loss exposes darker land and ocean surfaces, which absorb even more solar energy and further amplify regional warming.

This creates multiple reinforcing feedbacks operating simultaneously.

Climate Change → More Frequent and Intense Wildfires → More Smoke, Black Carbon, and Aerosols → Nighttime Heat Trapping + Black Carbon Deposition on Snow and Ice → Warmer Nights + Reduced Surface Albedo → Accelerated Regional Warming → Higher Air Conditioning Demand + Faster Arctic Ice Melt → Greater Greenhouse Gas Emissions (where grids remain fossil-fuel powered) + Increased Solar Heat Absorption → Additional Global Warming → More Frequent and Intense Wildfires

Rather than a single feedback loop, wildfire smoke demonstrates how one climate impact can trigger several interconnected reinforcing loops that amplify one another.


Building Resilience

Preparing for extreme heat does not always require expensive renovations. Many low-cost measures can significantly improve resilience while reducing energy demand.

Examples include:

  • improving attic insulation
  • installing reflective roofing materials
  • adding exterior shading
  • planting shade trees
  • improving ventilation
  • using ceiling fans
  • sealing air leaks
  • installing high-efficiency heat pumps
  • increasing battery backup capability
  • incorporating passive cooling design
  • expanding urban tree canopies

Each improvement reduces dependence upon mechanical cooling while lowering stress on electrical infrastructure.


Conclusion

Climate control is rapidly becoming one of the defining infrastructure challenges of the twenty-first century. As temperatures continue to rise, air conditioning is evolving from a consumer appliance into a critical component of public health, economic stability, and societal resilience.

Yet the expansion of climate control also creates new reinforcing feedback loops involving energy systems, cities, water resources, healthcare, digital infrastructure, refrigerants, and wildfire dynamics. These feedbacks demonstrate that climate change is no longer simply an environmental issue—it is an interconnected systems problem in which human responses can either amplify or reduce future warming.

Breaking these feedback loops will require more than expanding air conditioning. It will depend upon cleaner electricity, higher-efficiency cooling technologies, passive building design, urban greening, resilient electrical grids, improved water management, and thoughtful climate adaptation. Every improvement that reduces the energy required to keep people safe weakens these reinforcing cycles.

The future of climate resilience will not be determined solely by how much we cool our buildings, but by how intelligently we redesign the systems that make cooling possible.

bookmark_borderWorldwide Water Wars

Climate Change, Water Scarcity, and the Geopolitics of a Thirsty Planet

by Daniel Brouse

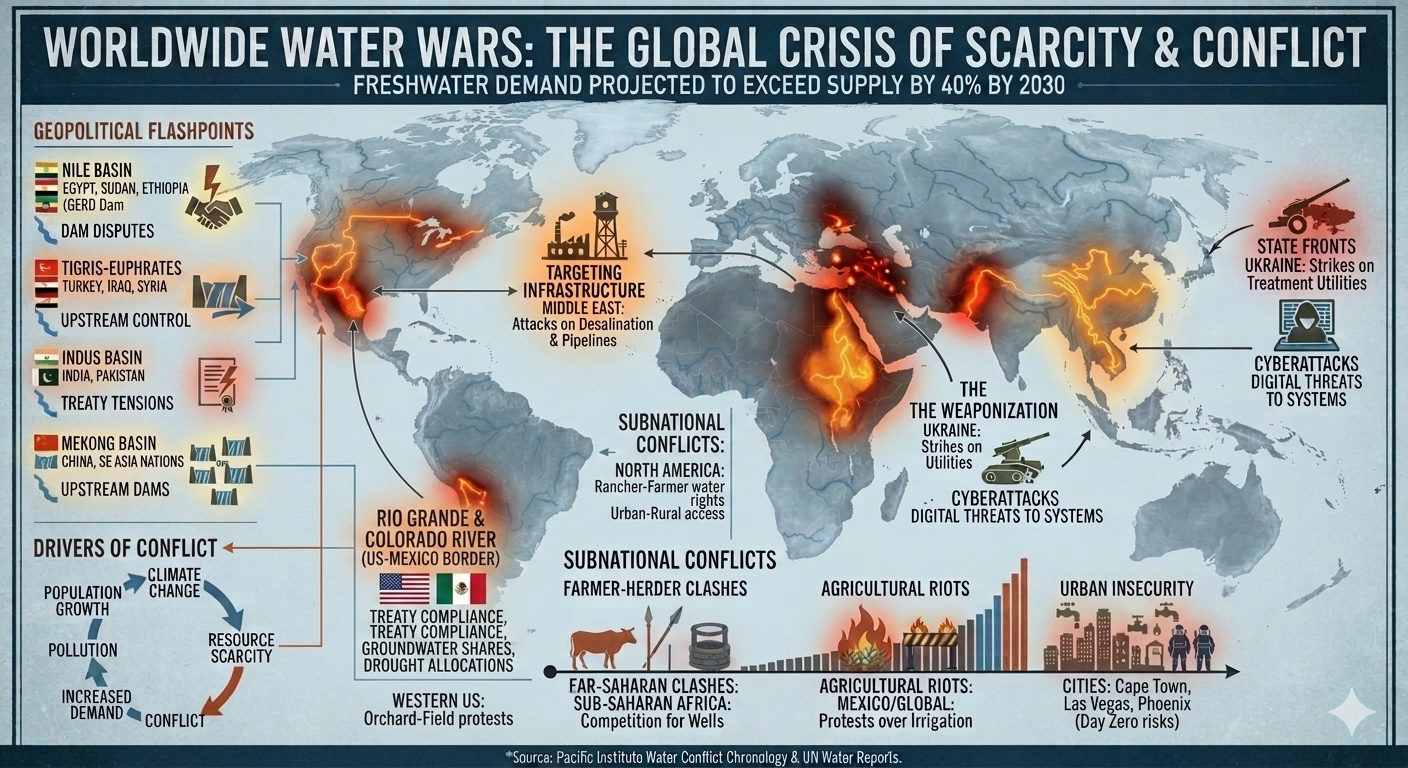
Water has become one of the defining geopolitical resources of the 21st century. Population growth, aging infrastructure, groundwater depletion, pollution, and climate change have pushed many of the world’s major river basins toward what researchers increasingly describe as global water bankruptcy—a condition in which demand permanently exceeds reliable supply.

While full-scale wars fought solely over water remain relatively uncommon, water has become an increasingly powerful geopolitical weapon. Governments use dams, reservoirs, and water diversions as strategic leverage. Armed groups target water infrastructure. Climate-driven droughts intensify existing political tensions, transforming long-standing disputes into national security crises.

Organizations such as the Pacific Institute have documented hundreds of water-related conflicts worldwide, with the frequency of violent incidents increasing as climate change accelerates.

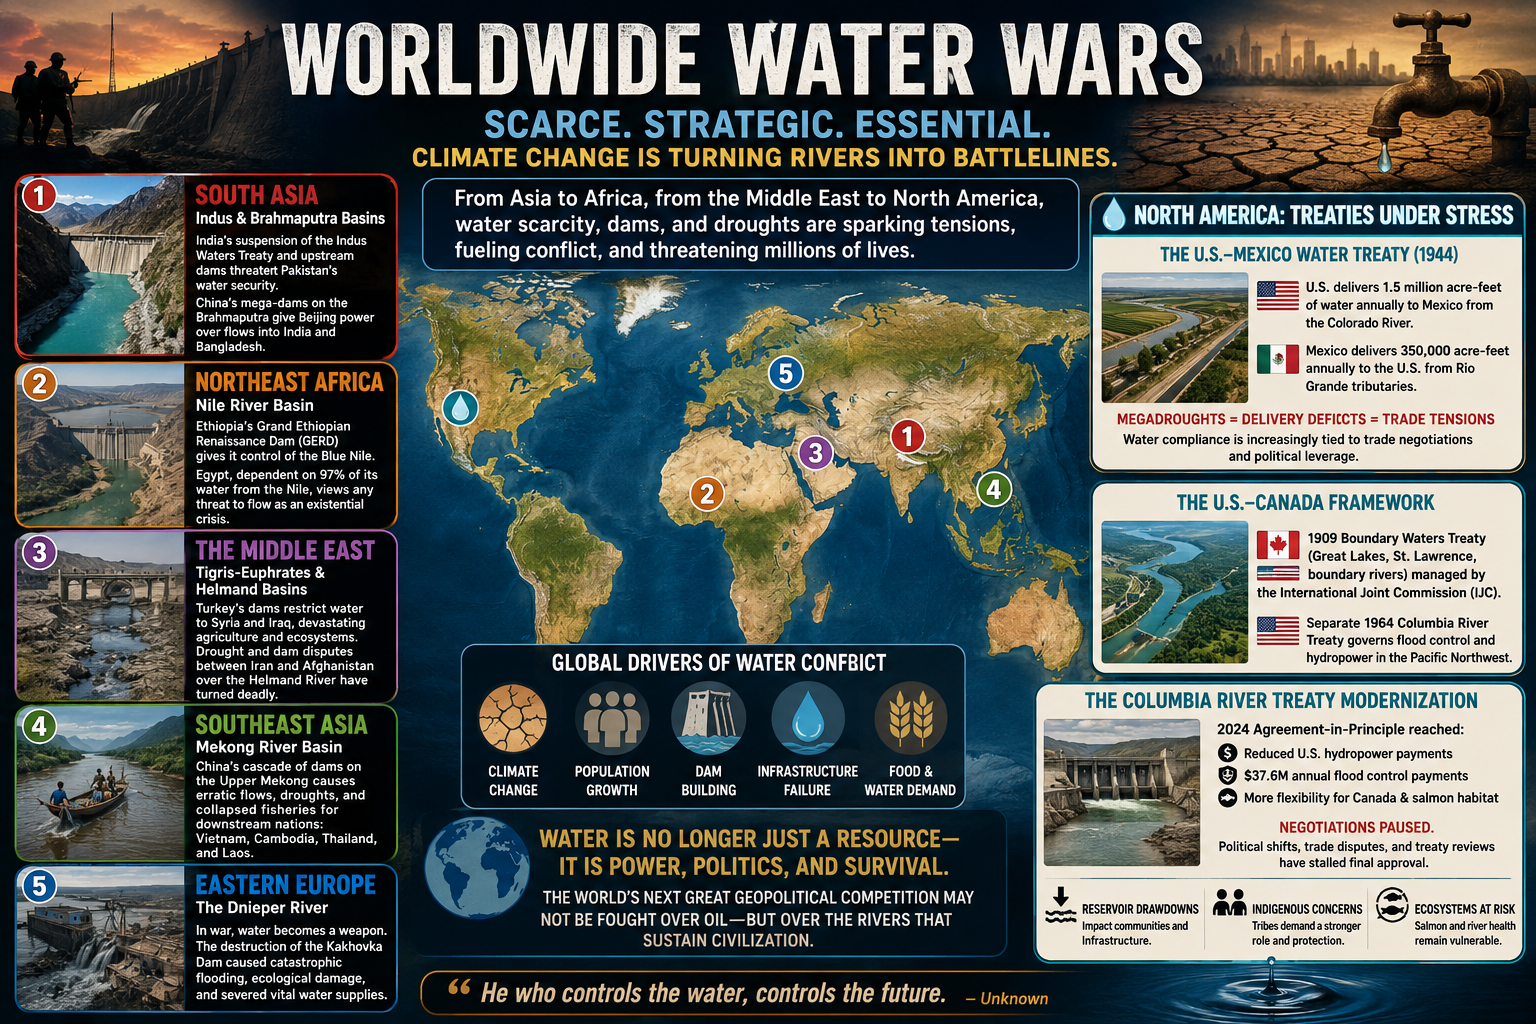
South Asia: The Indus and Brahmaputra Basins

The Indus River (India vs. Pakistan)

The Indus River remains one of the world’s most dangerous hydro-political flashpoints.

For more than six decades, the 1960 Indus Waters Treaty largely insulated water management from military conflict between India and Pakistan. However, deteriorating political relations have placed the agreement under unprecedented strain. India has accelerated construction of upstream hydroelectric projects and has suspended portions of treaty cooperation, while Pakistan has repeatedly warned that any deliberate interruption of water flows would be viewed as an existential threat.

Because the Indus supports the majority of Pakistan’s agriculture, even modest reductions in flow can have enormous economic and humanitarian consequences.

The Brahmaputra River (China vs. India)

Farther east, China is constructing some of the world’s largest hydroelectric projects on the Yarlung Tsangpo—the upper reaches of the Brahmaputra River in Tibet.

Although Beijing maintains that the projects are designed primarily for power generation and flood management, India and Bangladesh remain concerned that upstream control could eventually allow China to manipulate downstream water availability during periods of drought or political tension.

As climate change alters Himalayan snowpack and glacier melt, these concerns continue to grow.


Northeast Africa: The Nile River Basin

Ethiopia, Egypt, and Sudan

The Grand Ethiopian Renaissance Dam (GERD) has transformed regional politics.

Located on the Blue Nile, the dam gives Ethiopia significant influence over seasonal river flows. Ethiopia views the project as essential for economic development and electrification. Egypt, however, depends on the Nile for roughly 97 percent of its freshwater supply and considers uninterrupted downstream flows a matter of national survival.

Despite years of negotiations involving Ethiopia, Egypt, and Sudan, no permanent, legally binding agreement governing long-term operation of the dam has been reached.


The Middle East: Water as Strategic Leverage

The Tigris and Euphrates Rivers

Turkey’s Southeastern Anatolia Project (GAP) includes more than twenty major dams and numerous hydroelectric facilities.

While the project has expanded Turkish agriculture and electricity production, it has substantially reduced downstream flows into Syria and Iraq.

The consequences include:

  • declining agricultural productivity,
  • shrinking wetlands,
  • increased desertification,
  • deterioration of the historic Mesopotamian Marshes, and
  • heightened regional political instability.

The Helmand River (Iran vs. Afghanistan)

Water shortages have also intensified conflict between Iran and Afghanistan.

Repeated droughts have strained implementation of existing water-sharing agreements, and disputes over upstream reservoirs and dams have contributed to armed clashes between Iranian border forces and Taliban-controlled Afghanistan.


Southeast Asia: The Mekong River Basin

China has built an extensive series of dams on the Upper Mekong (Lancang River).

Downstream nations—including Vietnam, Cambodia, Laos, and Thailand—have experienced increasingly erratic river levels, reduced sediment transport, declining fisheries, and unexpected drought conditions.

Millions of people depend upon the Mekong for food security and agriculture, making river management one of Southeast Asia’s most significant long-term geopolitical challenges.


Eastern Europe: Water Infrastructure as a Weapon

The war in Ukraine has demonstrated how water infrastructure itself can become a military target.

The destruction of the Kakhovka Dam along the Dnieper River triggered catastrophic flooding, devastated ecosystems, destroyed farmland, disrupted drinking water supplies, and complicated cooling operations at the nearby Zaporizhzhia Nuclear Power Plant.

The event illustrated how modern warfare increasingly includes attacks on critical water infrastructure.


North America: Climate Change Meets International Water Law

Unlike many international river systems, North America has long relied upon formal treaties to govern shared water resources. However, prolonged drought and climate change are placing these agreements under unprecedented stress.

The United States and Mexico

The foundation of U.S.–Mexico water management is the 1944 Water Treaty, administered by the International Boundary and Water Commission (IBWC).

The treaty established a reciprocal exchange:

  • The United States delivers approximately 1.5 million acre-feet annually from the Colorado River to Mexico.
  • Mexico delivers approximately 350,000 acre-feet annually from Rio Grande tributaries into the United States, supplying much of South Texas agriculture.

Growing Tensions

Persistent megadrought across the American Southwest and northern Mexico has severely strained compliance.

Mexico has accumulated significant delivery deficits under portions of the treaty, leading to growing frustration among Texas farmers and lawmakers.

Water has increasingly become intertwined with trade policy. Some U.S. officials have proposed incorporating treaty compliance into future reviews of the United States–Mexico–Canada Agreement (USMCA), potentially linking water deliveries to trade negotiations.

The United States has also denied certain Mexican requests for additional Colorado River deliveries during periods of domestic shortage, illustrating how climate stress is reshaping bilateral diplomacy.


The United States and Canada

Canada manages shared waters with the United States through the 1909 Boundary Waters Treaty, administered by the International Joint Commission (IJC).

This framework governs:

  • the Great Lakes,
  • the St. Lawrence River,
  • the St. Mary River,
  • the Milk River, and
  • numerous other shared waterways.

A separate agreement—the 1964 Columbia River Treaty (CRT)—governs flood control and hydropower operations throughout the Pacific Northwest.


The Columbia River Treaty Modernization

For six years, negotiators from both countries worked to modernize the aging Columbia River Treaty.

The 2024 Agreement-in-Principle

Negotiators reached a tentative Agreement-in-Principle that included several major reforms.

Reduced Hydropower Payments

The United States negotiated reductions in the long-standing Canadian Entitlement, under which U.S. utilities compensated British Columbia for upstream water storage used to generate downstream electricity.

Modern Flood Control

Instead of relying upon the original prepaid flood-control system, the agreement would establish annual payments—approximately $37.6 million per year—for coordinated flood storage operations.

Greater Canadian Flexibility

British Columbia would receive greater authority to manage reservoir operations to support local priorities, including salmon habitat restoration and Indigenous cultural resources.


Negotiations Enter Political Limbo

Although negotiators reached broad agreement, final treaty language has not been ratified.

A change in U.S. presidential leadership placed many international agreements under broader policy review, delaying completion of the modernization process.

The negotiations have also become entangled in wider U.S.–Canada trade disputes, including tariff discussions and political rhetoric surrounding North American natural resources. Canadian officials have expressed concern that future treaty approval could become tied to broader trade negotiations rather than water management alone.


Interim Operations

Because modernization remains incomplete, water managers have adopted temporary operational agreements.

These interim measures attempt to replicate portions of the proposed treaty but have produced localized consequences.

For example, Lake Roosevelt has experienced larger seasonal drawdowns to preserve flood-control capacity, affecting ferry operations, recreation, and infrastructure serving the Colville Reservation.


Indigenous and Environmental Concerns

Many environmental organizations and Tribal Nations argue that modernization still falls short.

The original 1964 treaty focused almost exclusively on flood control and hydropower production.

Although Indigenous governments participated extensively in modernization negotiations, many advocacy organizations—including Save Our Wild Salmon—argue that ecosystem function should become a legally co-equal objective alongside flood protection and electricity generation.

With salmon populations already under severe stress from warming rivers, altered streamflows, and habitat loss, many conservation groups believe future treaty revisions must place ecological resilience at the center of water management rather than treating it as a secondary consideration.

Conclusion: Water Wars Have Already Begun

The phrase water wars once sounded like science fiction. Today, it describes a rapidly emerging geopolitical reality.

Climate change is reducing snowpack, accelerating glacier loss, intensifying droughts, and making precipitation increasingly erratic. At the same time, populations continue to grow while agriculture, industry, and cities demand ever larger shares of finite freshwater resources.

Most future conflicts will not resemble conventional wars fought solely over rivers. Instead, they will involve economic pressure, treaty disputes, dam construction, infrastructure sabotage, cyberattacks, migration, and political coercion centered on water security.

From the Indus to the Nile, from the Mekong to the Colorado, and from the Columbia River to the Rio Grande, freshwater is becoming both an environmental challenge and a strategic resource.

The world’s next great geopolitical competition may not be fought over oil—but over the rivers that sustain civilization itself.

bookmark_borderClimate Change and Water Rights: When Water Becomes More Valuable Than Land

By Daniel Brouse

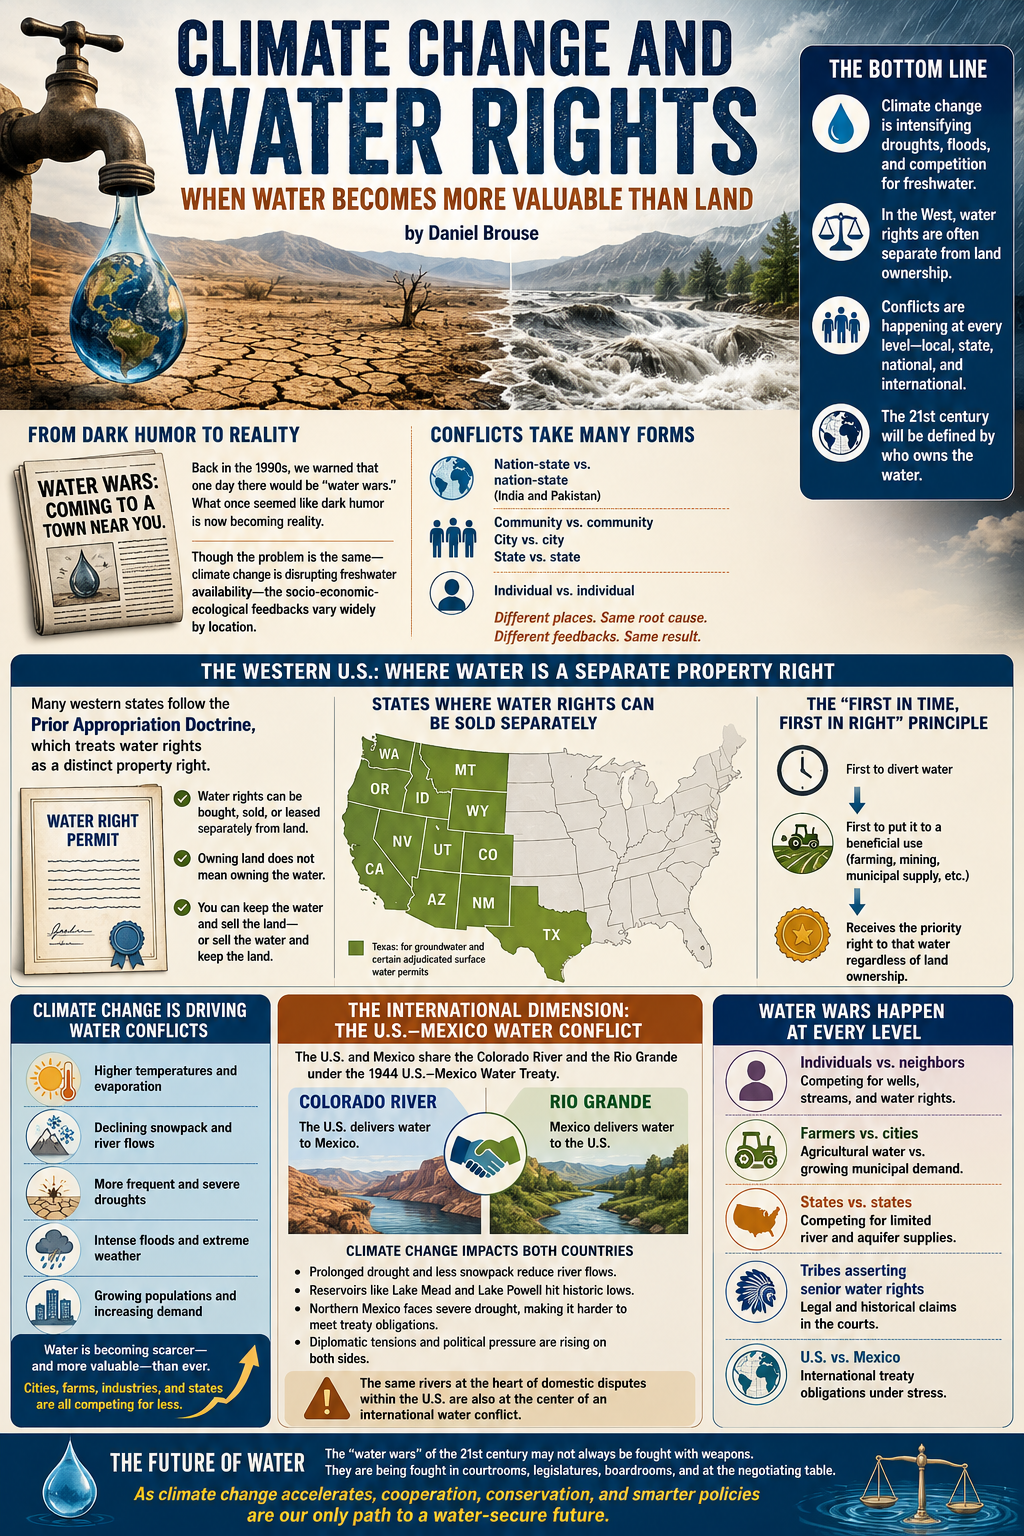
Climate change is making water security impossible to ignore. You don’t need a scientific report to see it—just look out your window. Floods, droughts, shrinking reservoirs, and increasing competition for freshwater are becoming part of everyday life.

Back in the 1990s, we warned that one day there would be “water wars.” We jokingly wrote headlines like, “Water Wars: Coming to a Town Near You.” Unfortunately, what once seemed like dark humor is steadily becoming reality.

The underlying problem is the same everywhere: climate change is disrupting the availability of freshwater. However, the resulting socio-economic and ecological feedbacks vary dramatically depending on geography, politics, and legal systems. In some regions, conflicts arise between nations, such as India and Pakistan over shared river systems. In others, disputes occur between neighboring communities, businesses, or even individual property owners.

The western United States provides one of the clearest examples of these emerging water conflicts. Unlike most of the eastern United States, many western states treat water rights as separate from land ownership.

Water Rights Are Not Always Property Rights

In much of the western United States, water rights can be bought, sold, or leased independently of the land itself. These states generally follow the Prior Appropriation Doctrine, a legal framework that treats water rights as a distinct form of property.

Under this system, owning land does not necessarily mean owning the water that flows across or beneath it. Likewise, someone can retain ownership of valuable water rights even after selling the associated land.

States Where Water Rights Can Be Sold Separately

States that commonly allow water rights to be severed from real estate include:

  • Colorado
  • Arizona
  • California
  • Nevada
  • New Mexico
  • Utah
  • Wyoming
  • Montana
  • Idaho
  • Washington
  • Oregon
  • Texas (for groundwater and certain adjudicated surface water permits)

The “First in Time, First in Right” Principle

These states generally operate under the principle of “first in time, first in right.”

The first individual or entity to divert water and put it to a legally recognized beneficial use—such as agriculture, mining, industry, or municipal supply—receives a priority right to continue using that water.

Because the right is tied to beneficial use rather than land ownership, water rights become a separate economic asset. A farmer, for example, may sell a ranch while retaining the associated water rights, or sell those rights to a nearby city while continuing to own the land.

Climate Change Is Increasing the Value of Water

As climate change intensifies droughts, reduces snowpack, alters river flows, and increases evaporation, freshwater is becoming an increasingly scarce resource. In many regions, water rights are appreciating faster than the land they once served.

Cities are purchasing agricultural water rights to supply growing populations. Farmers compete with municipalities, industries, and neighboring states for limited supplies. Rivers that once flowed year-round now run seasonally, while reservoirs experience historic lows followed by damaging floods.

The result is an expanding marketplace where water is increasingly treated as a financial asset rather than simply a natural resource.

The Future of Water Conflicts

The “water wars” we predicted decades ago have already begun. They may not always resemble armed conflicts between nations. More often, they take the form of lawsuits, interstate compacts, regulatory battles, infrastructure disputes, and competition between agriculture, industry, municipalities, and environmental interests.

As climate change accelerates, freshwater will become one of the defining economic and political issues of the 21st century. In many regions, the question will no longer be who owns the land—it will be who owns the water.

The International Dimension: The U.S.–Mexico Water Conflict

The western United States is not only experiencing domestic “water wars” between states, cities, farmers, and industries—it is also involved in an increasingly contentious international dispute with Mexico over many of the same river systems.

The conflict centers primarily on the Colorado River and the Rio Grande, which are governed by the 1944 U.S.–Mexico Water Treaty. Under the treaty, the United States delivers water from the Colorado River to Mexico, while Mexico provides water from tributaries feeding the Rio Grande to the United States.

For decades, the agreement functioned reasonably well because both countries generally had sufficient water supplies. Climate change has dramatically altered that equation.

Prolonged drought, declining snowpack in the Rocky Mountains, higher temperatures, and increased evaporation have reduced river flows throughout the American Southwest. Reservoirs such as Lake Mead and Lake Powell have reached historically low levels, forcing difficult decisions about how increasingly scarce water should be allocated.

At the same time, northern Mexico has experienced severe drought, making it difficult to meet its treaty obligations to deliver water to the United States. The resulting shortages have led to diplomatic disputes, political pressure, and growing tensions between agricultural users, municipalities, and federal governments on both sides of the border.

What makes this conflict particularly significant is that it is driven by the very same rivers already at the center of domestic disputes within the United States. States such as California, Arizona, Nevada, Colorado, New Mexico, and Texas are competing with one another for diminishing supplies while simultaneously relying on international agreements that are becoming more difficult to satisfy under a changing climate.

In effect, the Colorado River and Rio Grande now support multiple layers of competition:

  • Individuals versus neighboring landowners.
  • Farmers versus rapidly growing cities.
  • States versus other states.
  • Native American tribes asserting senior water rights.
  • The United States versus Mexico under international treaty obligations.

As climate change continues to reduce the reliability of freshwater supplies, these overlapping legal, economic, and political conflicts are likely to intensify. The future of water management will require not only engineering and conservation but also new approaches to interstate and international cooperation. The “water wars” of the 21st century are no longer a prediction—they are unfolding simultaneously at the local, state, national, and international levels.

bookmark_borderWildfire Smoke: How Atmospheric “Blankets” Increase Nighttime Heat and Drive Up Air Conditioning Demand

by Daniel Brouse

Wildfire smoke does more than reduce air quality—it can fundamentally alter local temperature patterns by changing how solar radiation and thermal energy interact with the atmosphere. Dense smoke layers can create a counterintuitive effect: cooler daytime temperatures but warmer nighttime conditions.

This disruption of the normal day–night temperature cycle can significantly increase air conditioning demand, strain electrical grids, and reduce HVAC efficiency.


Why Wildfire Smoke Lowers Daytime Temperatures

During the day, wildfire smoke acts as an atmospheric shield that reduces the amount of sunlight reaching Earth’s surface.

Blocks Incoming Solar Radiation

Thick smoke plumes contain millions of tiny aerosol particles that scatter and reflect incoming shortwave solar radiation back into space. This reduces the amount of direct sunlight reaching the ground.

Reduces Surface Heating

With less solar energy absorbed by land surfaces, buildings, roads, and vegetation receive less daytime heating. As a result:

  • Maximum daytime temperatures may be lower than forecast.
  • Surface heating is reduced.
  • The normal buildup of daytime thermal energy is weakened.

However, this cooling effect does not mean the overall energy balance has improved. Instead, the smoke changes when and where heat is stored and released.


Why Wildfire Smoke Increases Nighttime Temperatures

After sunset, the same smoke layer that blocked sunlight during the day can act like an insulating blanket.

Traps Outgoing Thermal Energy

Normally, the Earth’s surface cools at night by releasing stored heat as longwave infrared radiation into space.

A dense smoke layer interferes with this process:

  • Smoke particles absorb outgoing thermal radiation.
  • The absorbed energy is re-emitted in all directions.
  • Some of that thermal energy is radiated back toward the surface.

The result is a warmer nighttime environment with reduced radiational cooling.

The “Atmospheric Blanket” Effect

This process is similar to the greenhouse effect:

  • Less heat escapes to space.
  • More heat remains trapped near the surface.
  • Overnight temperatures stay elevated.

Instead of providing the normal nighttime recovery period, wildfire smoke can flatten the daily temperature cycle by lowering daytime peaks while preventing nighttime cooling.


How Wildfire Smoke Thermal Trapping Increases Air Conditioning Demand

The nighttime warming effect from wildfire smoke can significantly increase local cooling requirements by eliminating the period when buildings and HVAC systems normally recover.

1. Eliminates Nighttime “Compressor Rest”

Under normal conditions, outdoor temperatures drop after sunset, allowing air conditioners to cycle less frequently or shut off for extended periods.

With smoke-enhanced nighttime heat:

Continuous Operation

  • Outdoor temperatures remain elevated.
  • Indoor heat removal continues throughout the night.
  • Compressors operate longer and more frequently.

Instead of recovering overnight, HVAC systems may begin the next day already under stress.

Increased Mechanical Wear

Extended compressor operation can accelerate:

  • Electrical component fatigue.
  • Capacitor failures.
  • Motor overheating.
  • Refrigerant system stress.

A hot afternoon followed by a smoke-trapped warm night creates a longer continuous period of thermal stress.


2. Flattens and Extends Electricity Demand Peaks

Power grids depend on nighttime cooling periods to recover after daytime heat waves.

Wildfire smoke can disrupt this pattern.

No Overnight Demand Drop

When thousands or millions of homes continue running air conditioning overnight:

  • Utility demand remains elevated.
  • Transformers and transmission equipment receive less recovery time.
  • Grid operators lose the normal nighttime reduction in load.

Increased Infrastructure Stress

The combination of:

  • Extreme daytime temperatures,
  • Reduced nighttime cooling,
  • Persistent HVAC operation,

creates a sustained demand pattern that pushes electrical systems closer to their limits.


3. Reduces HVAC Efficiency

Air conditioners remove heat by transferring indoor thermal energy to the outdoor environment through condenser coils.

When outdoor conditions remain hot, this process becomes less efficient.

Poorer Heat Exchange

Higher outdoor temperatures mean:

  • The condenser must work harder.
  • More electricity is required to move the same amount of heat.
  • Cooling capacity decreases during peak demand periods.

Wildfire smoke can worsen this problem by extending the number of hours when outdoor temperatures remain unfavorable.


4. Smoke Particulates Increase Filter and Airflow Problems

Wildfire smoke introduces large amounts of fine particulate matter (PM2.5) into the air.

Many homeowners respond by running HVAC systems continuously to improve indoor air quality.

However, this creates additional challenges.

Filter Loading

Smoke particles accumulate rapidly on filters, causing:

  • Reduced airflow.
  • Increased blower motor workload.
  • Higher electricity consumption.
  • Reduced cooling performance.

A severely clogged filter can force HVAC equipment to work significantly harder while moving less air.

Balancing Cooling and Filtration

During wildfire smoke events:

  • Use high-quality filters rated for fine particles when compatible with the HVAC system.
  • Replace filters more frequently.
  • Avoid unnecessarily restricting airflow with filters beyond the system’s design capability.
  • Use portable HEPA air cleaners when possible to reduce the burden on central HVAC systems.

The Bigger Climate Connection

Wildfire smoke demonstrates that climate impacts are not limited to simple temperature increases. Climate change is altering the physical processes that regulate Earth’s energy balance.

A warmer atmosphere, longer fire seasons, and more intense wildfire events create cascading effects:

  • Smoke changes radiation patterns.
  • Radiation changes temperature patterns.
  • Temperature changes energy demand.
  • Energy demand increases stress on infrastructure.

The result is a feedback loop where extreme climate events amplify economic and technological pressures.

Understanding these interactions is increasingly important as communities adapt to a changing climate where heat, smoke, energy demand, and infrastructure resilience are becoming interconnected challenges.

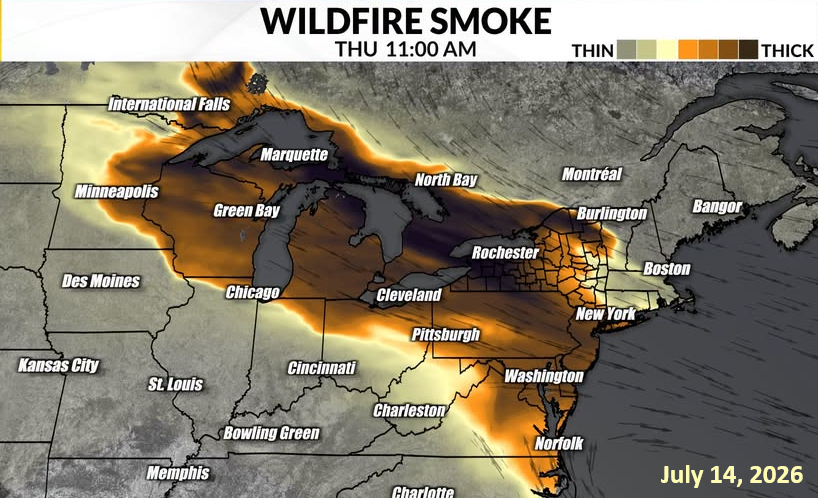
Canadian Wildfire Smoke Returns: A Growing Summer Threat to Philadelphia’s Air Quality

bookmark_borderClimate Change and Financial Liquidity

A Capital Preservation Strategy for an Uncertain Future

By Daniel Brouse

Introduction: Avoid the Minsky Moment

A “Minsky Moment” refers to a sudden, major collapse of asset prices following a long period of market growth and speculative risk-taking. Named after American economist Hyman Minsky and coined by Paul McCulley of PIMCO in 1998, the concept explains why long periods of economic stability inherently build the foundation for severe financial crises.

Climate change is no longer just an environmental issue—it is becoming a financial planning issue. Rising insurance costs, increasing weather-related losses, higher inflation risks, and growing economic uncertainty make protecting capital more important than ever.

The first objective of any sound financial plan is not maximizing returns. It is ensuring that your savings remain available, secure, and able to preserve purchasing power. Liquidity gives you flexibility when unexpected expenses arise, while capital preservation prevents temporary market disruptions from becoming permanent financial losses.

One of the simplest and most effective strategies is to combine a high-yield savings account with a TreasuryDirect account that invests in short-term U.S. Treasury Bills.


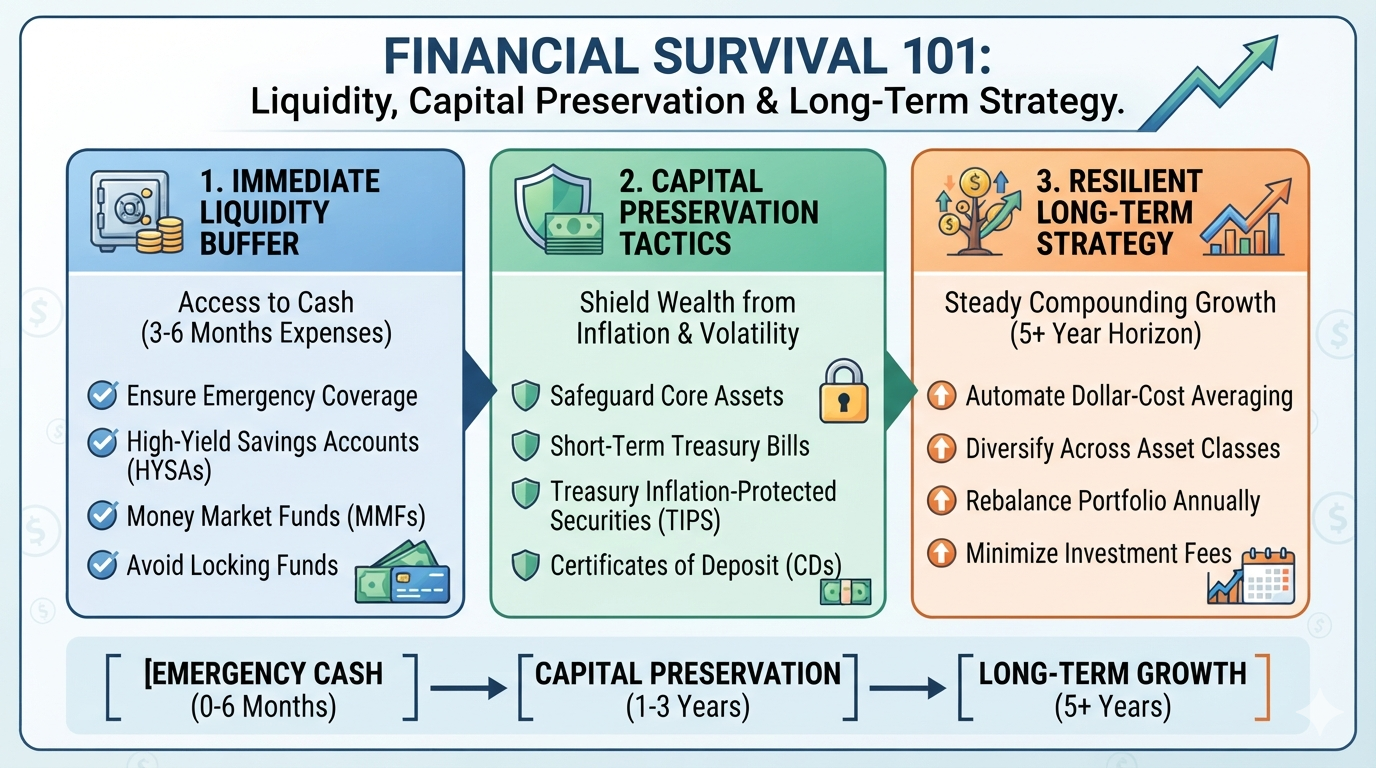
Step 1: Build an Immediate Liquidity Buffer

Every financial plan should begin with readily accessible cash.

Financial advisors generally recommend maintaining three to six months of living expenses in highly liquid accounts that can be accessed immediately during emergencies.

Good options include:

  • High-Yield Savings Accounts (HYSA)
  • Money Market Accounts
  • Money Market Mutual Funds

Unlike long-term investments, these accounts allow you to pay for unexpected expenses without selling stocks or bonds during a market decline.

A high-yield savings account serves as the foundation of your liquidity strategy.


Step 2: Open a TreasuryDirect Account

Once you’ve accumulated several hundred dollars beyond your emergency cash reserve, consider opening a TreasuryDirect account with the U.S. Treasury.

TreasuryDirect allows individuals to purchase Treasury securities directly from the federal government without brokerage fees.

Among the available securities, 4-week Treasury Bills (T-Bills) are particularly attractive for capital preservation.

Why 4-Week Treasury Bills?

Treasury Bills are considered one of the safest investments in the world because they are backed by the full faith and credit of the United States government.

Additional advantages include:

  • Extremely low default risk
  • Monthly maturity
  • High liquidity
  • Competitive interest rates
  • Exempt from state and local income taxes

Because they mature every four weeks, they provide exceptional flexibility if economic conditions change.


Understanding How Treasury Bills Work

Treasury Bills are sold through regularly scheduled government auctions.

Unlike traditional savings accounts, T-Bills are purchased at a discount to their face value.

For example:

  • Purchase Price: $99.60
  • Face Value at Maturity: $100.00

The $0.40 difference represents your interest earnings.

When the bill matures four weeks later, the Treasury pays the full face value directly into your account.

Funds used to purchase the bill are automatically withdrawn from your linked bank account after the auction.


Why Short-Term Bills Are Safer Than Long-Term Bonds

Many investors assume all Treasury securities carry identical risk.

They do not.

There is a critical distinction between:

  • Treasury Bills (4-week to 52-week)
  • Treasury Notes (2-10 years)
  • Treasury Bonds (20-30 years)

Longer-term bonds are highly sensitive to interest rate changes.

If inflation increases or interest rates rise, existing bonds decline in market value. Investors who need to sell before maturity can lose a substantial portion of their principal.

Short-term Treasury Bills largely avoid this problem.

Because they mature every month, your principal is quickly returned, allowing you to reinvest at current interest rates.

In today’s uncertain economic environment, short-term T-Bills generally provide much greater flexibility and significantly lower interest-rate risk than longer-term government bonds.


Automate the Process

TreasuryDirect allows investors to automatically reinvest maturing Treasury Bills.

For example:

  • Purchase a 4-week Treasury Bill.
  • Set it to automatically roll over for up to 12 cycles.
  • Each month, your principal purchases a new Treasury Bill.
  • Your interest is deposited back into your bank account.

This creates a largely automated income stream while maintaining monthly access to your capital.

As interest accumulates in your savings account, it can eventually be invested into additional Treasury Bills, creating a gradual compounding effect.


I Bonds: Protection Against Inflation

Another useful Treasury investment is the Series I Savings Bond (I Bond).

Unlike Treasury Bills, I Bonds are specifically designed to protect purchasing power during periods of inflation.

Their interest rate consists of:

  • A fixed rate
  • An inflation-adjusted rate that changes every six months

When inflation rises, I Bond yields increase accordingly.

During the inflation surge of 2022, newly issued I Bonds briefly paid annualized rates above 9%, illustrating how they can provide meaningful protection during periods of rapidly rising prices.

Additional advantages include:

  • Exempt from state and local income taxes
  • Federal taxes deferred until redemption
  • Potential education tax benefits if used for qualified higher education expenses and eligibility requirements are met

Because I Bonds cannot be redeemed during their first year and incur a modest interest penalty if redeemed before five years, they are best viewed as a medium-term inflation hedge rather than an emergency fund.


Retirement Accounts

Capital preservation becomes even more important inside retirement accounts.

Money that cannot easily be replaced should generally avoid unnecessary risk.

If you are nearing retirement—or simply wish to reduce volatility—consider investments that prioritize preservation of principal while earning yields comparable to short-term Treasury Bills or other low-risk cash equivalents.

The objective is not to chase maximum returns but to ensure retirement savings remain available when needed.


Building a Layered Financial Strategy

A resilient financial plan consists of three distinct layers.

Time HorizonObjectiveTypical Investments
0–6 MonthsImmediate liquidityHigh-yield savings accounts, money market funds
1–3 YearsCapital preservation4-week Treasury Bills, I Bonds, short-term Treasury funds, short-term CDs
10+ YearsLong-term growthDiversified stock index funds, international equities, retirement accounts

This layered approach allows each dollar to serve a specific purpose rather than forcing every investment to accomplish every objective. While there is no one-size-fits-all allocation, your age, financial obligations, income stability, and future plans should guide how much you keep in each layer.

For individuals following a prudent capital preservation strategy, a sample allocation might look like this:

  • Age 50 and older: Approximately 80% in immediate liquidity, 15% in capital preservation investments such as short-term Treasury Bills and I Bonds, and 5% in long-term growth investments.
  • Age 30–50: Approximately 50% in immediate liquidity, 40% in capital preservation, and 10% in long-term growth investments.
  • Under age 30: Approximately 20% in immediate liquidity, 60% in capital preservation, and 20% in long-term growth investments.

These allocations prioritize financial flexibility and preservation of principal in an era of increasing economic uncertainty. Younger investors generally have more time to recover from financial setbacks and can afford somewhat greater exposure to long-term growth assets, while those approaching or entering retirement often benefit from emphasizing liquidity and protecting accumulated wealth. Individual circumstances vary, however, so these percentages should be viewed as a prudent framework rather than a universal rule.


Long-Term Investing PrinciplesAfter establishing sufficient liquidity and protecting core capital, long-term wealth creation still depends on disciplined planning, risk management, and consistent investing.

Traditional investment principles remain important, but today’s financial environment requires a broader understanding of risk. Investors should consider not only market performance but also their ability to access capital, protect assets, and adapt to changing economic conditions.

Key principles include:

  • Maintain adequate liquidity and access to cash. A strong financial plan requires readily available funds to handle emergencies, unexpected expenses, and investment opportunities without being forced to sell assets at unfavorable times.
  • Evaluate insurance exposure. Rising insurance costs, coverage limitations, and changing underwriting standards can significantly affect personal finances and asset values. This applies not only to homeowners insurance but also to auto and rental insurance, which are increasingly influenced by climate-related risks. For example, hail damage is one of the leading causes of auto insurance claims, and the increasing frequency and severity of severe storms can contribute to higher premiums and reduced coverage availability. Renters can also be affected as rising property insurance costs are often passed through in the form of higher rents and fees.
  • Assess climate-related financial risks. Property location, extreme weather exposure, infrastructure resilience, and changing insurance availability are increasingly important factors in long-term financial planning. Climate risks can influence property values, mortgage decisions, municipal finances, and the overall cost of living in vulnerable areas.
  • Rebalance periodically. Adjust your portfolio over time to maintain your intended allocation among liquidity, capital preservation, and growth investments.
  • Minimize investment expenses. Lower fees allow more of your returns to compound over time. Favor cost-efficient investment vehicles such as low-cost index funds and ETFs when appropriate.

Markets will inevitably fluctuate, but disciplined long-term investing, combined with sound risk management and financial flexibility, has historically rewarded patient investors. The goal is not simply to maximize returns—it is to build a resilient financial foundation capable of adapting to changing economic, environmental, and personal circumstances.

Climate Change and Financial Resilience

Climate change introduces new financial risks that previous generations rarely considered.

Increasingly, homeowners and investors must account for:

  • Rising insurance premiums
  • More frequent weather-related disasters
  • Inflationary pressures from supply disruptions
  • Higher infrastructure costs
  • Regional declines in real estate values
  • Greater economic uncertainty

These risks do not necessarily mean financial collapse is imminent. However, they do reinforce the importance of maintaining adequate liquidity and protecting principal. Investors with readily available cash are better positioned to handle emergencies, adapt to changing market conditions, and take advantage of opportunities that arise during periods of economic stress.


Conclusion

Successful investing begins with preserving financial flexibility.

A high-yield savings account provides immediate liquidity. Short-term Treasury Bills offer one of the safest ways to earn competitive returns while protecting principal. I Bonds provide an additional layer of inflation protection for longer-term savings.

Together, these tools create a strong foundation for financial resilience in an increasingly uncertain world.

No investment strategy can eliminate risk entirely, but maintaining liquidity, preserving capital, and investing for long-term growth can help individuals and families navigate economic volatility—including the growing financial challenges associated with climate change—with greater confidence and stability.

bookmark_borderFinancial Survival 101: Liquidity, Capital Preservation & Long-Term Strategy

Preparing for Economic Uncertainty Without Panic

By Daniel Brouse


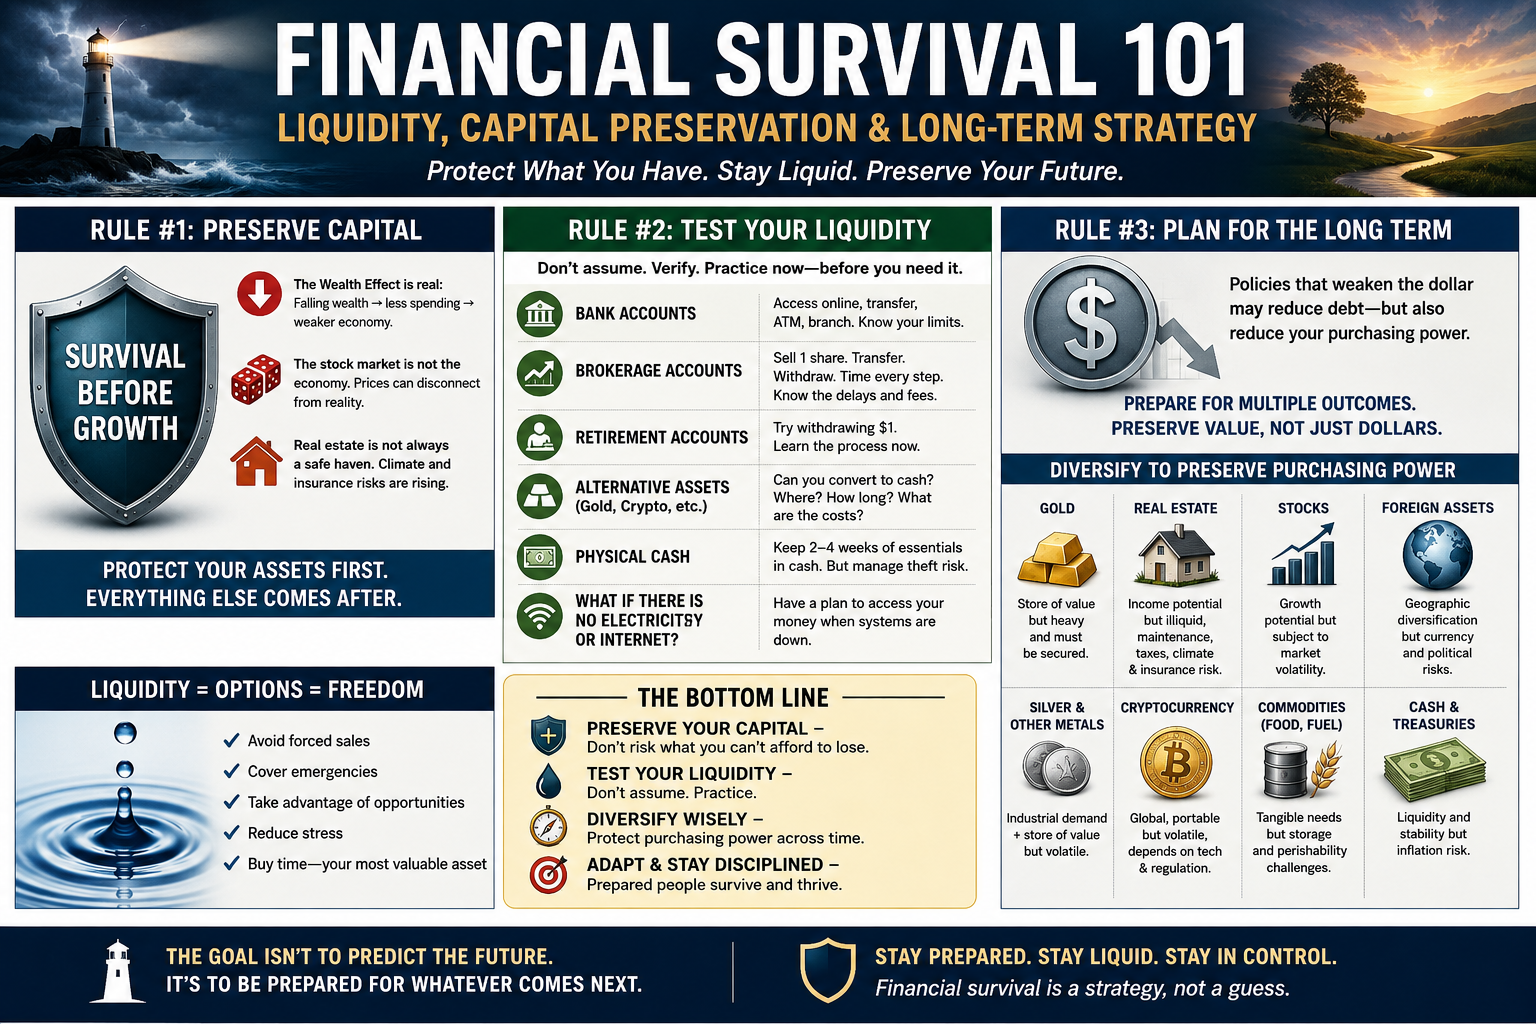
Capital Preservation Is Survival Rule #1

Capital preservation has always been a cornerstone of sound financial planning. In periods of heightened economic uncertainty, however, it becomes the overriding priority.

The goal is not to maximize returns at all costs. It is to ensure that you retain enough purchasing power and financial flexibility to navigate whatever comes next.

One concept increasingly influencing both Wall Street and Main Street is the Wealth Effect.

When household wealth rises—through higher stock prices, appreciating home values, or growing retirement accounts—people generally feel more confident. They spend more, borrow more, and invest more.

The opposite is equally true.

When people perceive themselves to be poorer, they begin cutting expenses. Vacations are postponed. New cars aren’t purchased. Home renovations are delayed. Restaurants see fewer customers. Businesses experience lower sales, which often leads to reduced hiring and layoffs.

The decline becomes self-reinforcing.

What begins as falling asset prices can eventually slow the broader economy.


The Stock Market Is Not the Economy

One of the biggest mistakes investors make is assuming that the stock market and the economy move together.

Over long periods they are related.

Over shorter periods they often are not.

Modern financial markets are increasingly driven by institutional trading, derivatives, leverage, algorithmic trading, and investor sentiment. Prices can become disconnected from underlying economic fundamentals for extended periods.

That means:

  • Rising stock prices do not necessarily mean the economy is healthy.
  • Falling stock prices do not automatically signal economic collapse.

Markets frequently overshoot in both directions.

Investors should avoid making emotional decisions based solely on market movements.


Real Estate Is Not Always a Safe Haven

For generations, real estate has been viewed as one of the safest long-term investments.

That assumption deserves closer examination.

Unlike stocks or bank deposits, real estate is highly illiquid. Selling a property can take weeks or months, and transactions involve significant costs, including commissions, taxes, legal fees, inspections, and financing contingencies.

Climate-related risks are adding another layer of uncertainty.

In many regions, insurance premiums have risen dramatically or insurers have withdrawn from markets altogether. Mortgage lenders are increasingly evaluating climate exposure, flood risk, wildfire danger, and long-term property resilience.

Some coastal communities, wildfire-prone regions, and flood zones are already experiencing declining property values, slower sales, or reduced insurance availability.

Examples include portions of:

  • California wildfire zones
  • Coastal Florida
  • Louisiana
  • Low-lying Atlantic and Gulf Coast communities

These trends do not mean that all real estate is at immediate risk. Many properties may remain attractive for decades. However, location-specific climate and insurance risks are becoming increasingly important considerations in short- and medium-term financial planning. Over the longer term, climate change is expected to affect virtually all real estate to varying degrees. The nature and severity of those risks will differ by location, but no property is likely to remain entirely insulated from changing climate conditions, rising insurance costs, evolving regulations, or shifting market preferences.

Real estate should no longer be evaluated solely by neighborhood, schools, and appreciation potential. Future insurability, financing availability, infrastructure resilience, and climate exposure are becoming equally important.


Step Two: Liquidity

What Good Are Assets If You Can’t Use Them?

After protecting capital comes a second priority:

Liquidity.

Liquidity measures how quickly an asset can be converted into usable cash without suffering significant losses.

During normal times, liquidity is often taken for granted.

During financial stress, it becomes priceless.

Many investors discover too late that assets they believed were readily available actually require days, weeks, or months to access.

That is why liquidity should be tested—not assumed.


Perform Your Own Liquidity Stress Test

Think of this as a financial fire drill.

You hope you’ll never need it.

But you’ll be grateful you’ve practiced.

Bank Accounts

Can you:

  • Access funds through online banking?
  • Use a debit card?
  • Transfer money electronically?
  • Withdraw cash from an ATM?
  • Obtain larger amounts from a local branch?
  • What is your backup plan if electricity, internet access, or electronic payments become unavailable?

Know your daily withdrawal limits.

Understand your bank’s policies before an emergency occurs.


Brokerage Accounts

Try the complete process:

  • Sell one share of a stock or ETF.
  • Transfer the proceeds to your checking account.
  • Withdraw cash.

Time every step.

Record:

  • Settlement delays
  • Transfer times
  • Bank holds
  • Fees
  • Unexpected obstacles

A brokerage balance isn’t liquid until the money reaches your wallet.


Retirement Accounts

Many retirement accounts allow withdrawals under certain circumstances.

Even if taxes or penalties apply, learn the mechanics now.

Understanding the paperwork, timing, and restrictions before an emergency reduces stress later.


Precious Metals

If you own gold or silver, ask yourself:

  • Where would I sell it?
  • How quickly could I receive payment?
  • Would I receive fair market value?
  • Would payment be immediate?

Owning precious metals is different from converting them into cash.

Practice the process.


Cryptocurrency

Crypto markets operate around the clock, but converting digital assets into spendable cash involves several steps.

Can you:

  • Sell cryptocurrency?
  • Transfer proceeds to your bank?
  • Withdraw physical cash?
  • What is your backup plan if electricity, internet access become temporarily unavailable?

Test a small transaction.

Don’t wait until markets become volatile.


Cash on Hand

Most financial planners recommend maintaining an emergency reserve.

Consider keeping enough physical cash to cover several weeks of essential expenses while avoiding excessive amounts that create theft or security risks.

Cash remains useful during temporary disruptions to banking networks, power outages, or payment systems.

bookmark_borderAll Real Estate Is Vulnerable to Climate Change

Understanding the Physical, Financial, and Market Risks Facing Property Owners

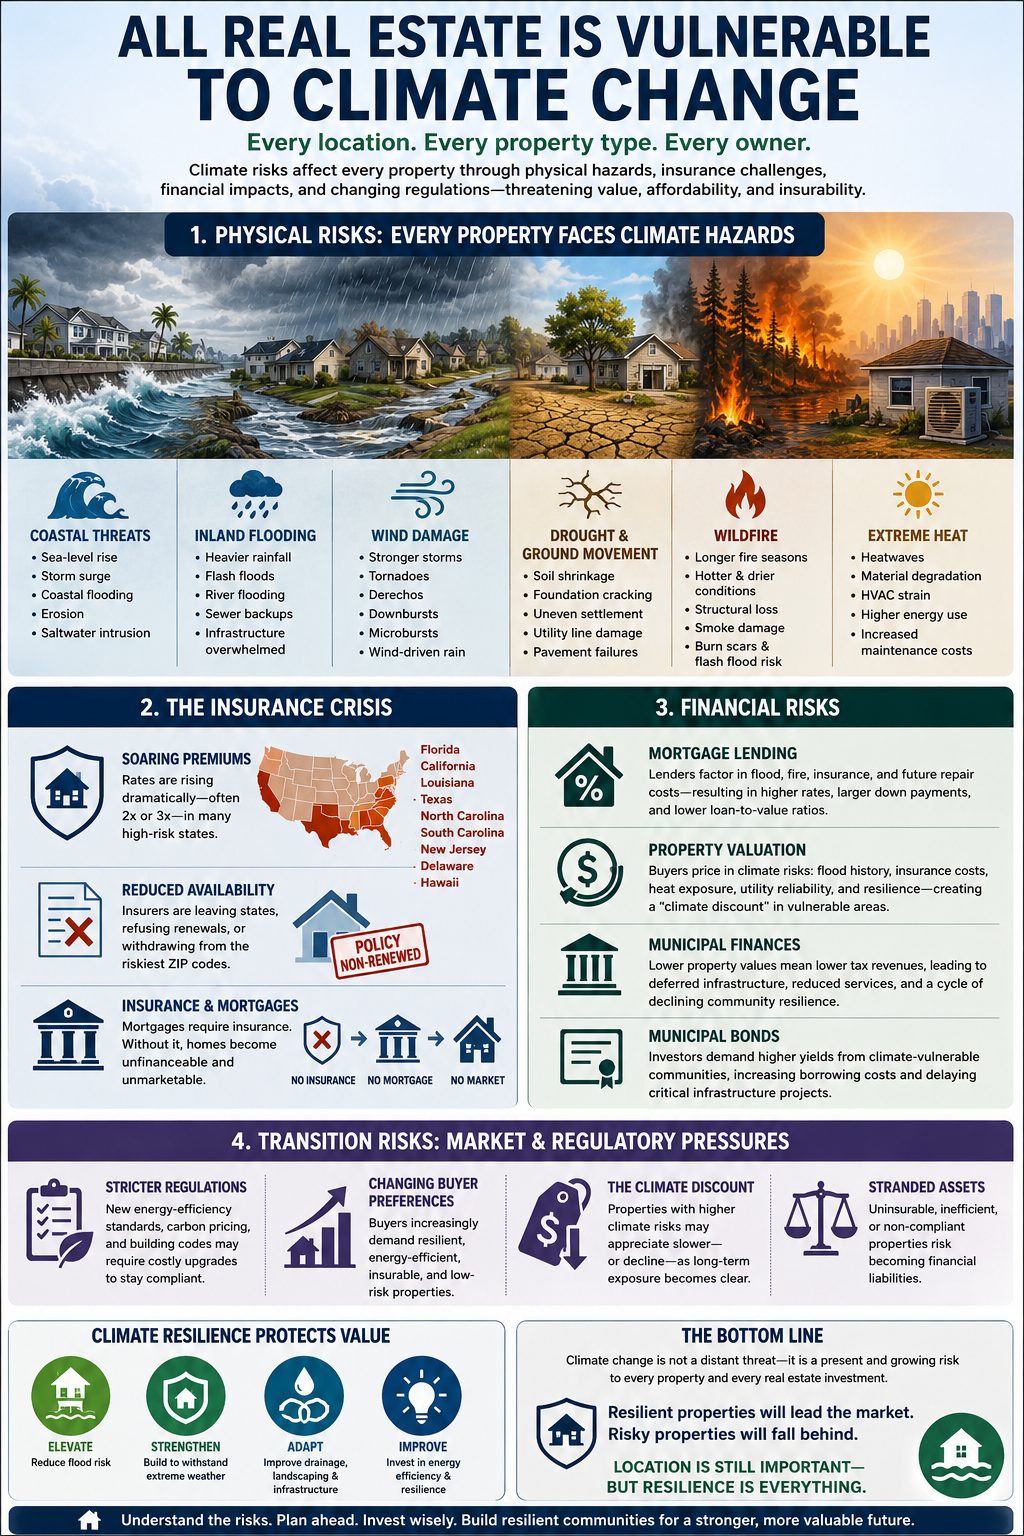
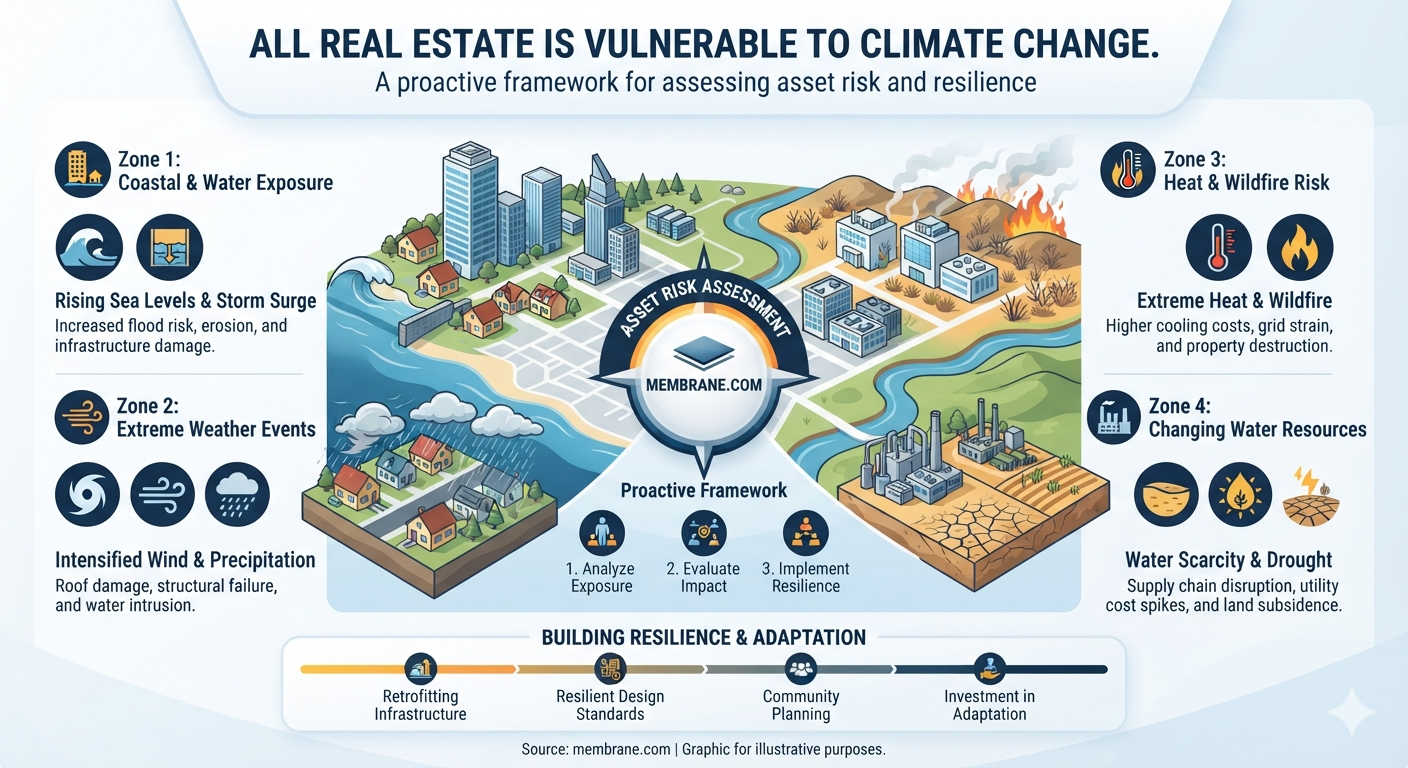
For generations, real estate has been viewed as one of the safest long-term investments. Land cannot be manufactured, buildings can be improved, and population growth has historically supported rising property values. Climate change is altering many of the assumptions that have underpinned real estate markets for decades.

Contrary to popular belief, climate risk is not confined to beachfront homes or wildfire-prone forests. Every property is exposed to climate-related risks, although the specific hazards vary by location. These risks extend far beyond physical damage. They increasingly affect insurance availability, mortgage lending, municipal finances, infrastructure reliability, property values, and long-term market liquidity.

The vulnerability of real estate can be understood through four interconnected categories: physical risks, insurance risks, financial and lending risks, and transition risks.


1. Physical Risks: Every Property Faces Climate Hazards

Climate change is increasing both the frequency and intensity of many weather-related hazards. Every region experiences different threats, but no location is completely immune.

Coastal Regions

Coastal properties face some of the most visible climate risks, including:

  • Rising sea levels
  • More frequent nuisance flooding
  • Stronger storm surges
  • Accelerated shoreline erosion
  • Saltwater intrusion into groundwater

Even modest sea-level rise significantly increases flood frequency because storm surges begin from a higher baseline.


Inland Flooding

Many inland communities once considered “safe” are experiencing increasing flood losses.

Warmer air holds approximately 7% more water vapor for every 1°C of warming, increasing the potential for intense rainfall events. As storms become more moisture-laden, drainage systems designed for twentieth-century rainfall often become overwhelmed.

Consequences include:

  • Flash flooding
  • River flooding
  • Basement flooding
  • Sewer backups
  • Road washouts
  • Bridge failures

Properties located well outside traditional floodplains are increasingly experiencing damaging floods.


Wind Damage

For much of the United States, wind represents the largest source of insured property losses.

Climate change is increasing atmospheric energy available for:

  • Severe thunderstorms
  • Derechos
  • Tornado outbreaks
  • Downbursts
  • Microbursts
  • Hurricane wind fields

Roofs, siding, windows, and mature trees are particularly vulnerable. Wind-driven rain often causes damage even when structures remain standing.


Wildfire

Longer fire seasons, hotter temperatures, and more frequent droughts have dramatically expanded wildfire risk.

Wildfires threaten real estate through:

  • Direct structural destruction
  • Smoke damage
  • Utility failures
  • Water contamination
  • Long-term reductions in property desirability

Burn scars also increase the likelihood of flash flooding and debris flows during subsequent rainstorms.


Drought and Ground Movement

Extended drought affects soils in complex ways.

Clay-rich soils shrink as they dry, causing:

  • Foundation cracking
  • Uneven settlement
  • Utility line damage
  • Pavement failures

Conversely, periods of heavy rainfall following drought can produce rapid soil expansion that further stresses structures.


Extreme Heat

Heat affects virtually every building.

Higher temperatures accelerate deterioration of:

  • Roofing materials
  • Asphalt pavement
  • Exterior paints
  • Sealants
  • HVAC systems

Buildings require more cooling energy while mechanical systems experience greater wear, increasing maintenance and operating costs.


2. The Insurance Crisis

Insurance is becoming one of the most important climate risks facing property owners.

Historically, insurance spread risk across large geographic regions. As climate-related losses increase, that model is becoming increasingly difficult to sustain.

Rising Premiums

Many homeowners and commercial property owners have experienced substantial premium increases.

States experiencing particularly rapid increases include:

  • Florida
  • California
  • Louisiana
  • Texas
  • North Carolina
  • South Carolina
  • New Jersey
  • Delaware
  • Hawaii

In many communities, insurance costs are rising faster than home values.


Reduced Availability

Some insurers are:

  • Leaving entire states
  • Declining to insure specific ZIP codes
  • Refusing policy renewals
  • Restricting coverage amounts
  • Increasing deductibles

As private insurers withdraw, many homeowners are forced into state-sponsored insurers of last resort, which often provide less comprehensive coverage at higher cost.


Insurance and Mortgage Lending

Insurance availability directly affects financing.

Most mortgage lenders require continuous hazard insurance throughout the life of the loan.

If insurance becomes unavailable or unaffordable:

  • Mortgage approvals become more difficult.
  • Existing homeowners may violate loan requirements.
  • Buyers qualify for smaller loans.
  • Market demand declines.
  • Property values weaken.

Without insurance, many homes effectively become difficult or impossible to finance.


3. Financial Risks Beyond Property Damage

Climate change affects real estate markets even before disasters occur.

Financial institutions increasingly incorporate climate risk into lending and investment decisions.

Mortgage Lending

Banks and mortgage investors evaluate:

  • Flood exposure
  • Wildfire risk
  • Insurance availability
  • Future repair costs
  • Local infrastructure resilience

Higher perceived risk may result in:

  • Larger down payment requirements
  • Higher interest rates
  • Reduced loan-to-value ratios
  • Shorter lending horizons

Properties once viewed as routine collateral may gradually become more difficult to finance.


Property Valuation

Real estate markets depend heavily on expectations of future value.

Buyers increasingly consider:

  • Flood history
  • Fire history
  • Heat exposure
  • Insurance costs
  • Utility reliability
  • Local resilience investments

Two otherwise identical homes may command significantly different prices simply because one carries greater long-term climate risk.


Municipal Finances

Local governments rely heavily on property taxes.

If climate risks reduce property values, municipalities may experience:

  • Lower tax revenues
  • Deferred infrastructure maintenance
  • Reduced public services
  • Higher municipal borrowing costs

This creates a feedback loop in which deteriorating infrastructure further reduces property values.


Municipal Bonds

Cities and counties finance roads, schools, water systems, and flood-control projects through municipal bonds.

Increasing climate risks may lead investors to demand higher yields from municipalities perceived as vulnerable. Higher borrowing costs can delay infrastructure improvements, making communities even more susceptible to future climate impacts.

Credit rating agencies are paying increasing attention to long-term climate resilience when evaluating municipal creditworthiness.


4. Transition Risks

Not all climate risks arise from weather.

Many result from changes in markets, technology, regulations, and consumer preferences.

Energy Efficiency Requirements

Governments are gradually adopting stricter standards for:

  • Building efficiency
  • Carbon emissions
  • Appliance performance
  • Building electrification
  • Energy benchmarking

Older buildings may require expensive upgrades to remain competitive.


Changing Buyer Preferences

Homebuyers increasingly ask questions such as:

  • Is the property insurable?
  • How often does it flood?
  • What are annual insurance costs?
  • Does the home have backup power?
  • Is the roof hurricane-rated?
  • Are energy costs manageable?

These considerations increasingly influence purchasing decisions.


The Emerging Climate Discount

Economists have begun describing the possibility of a “climate discount” or “climate bubble.”

Properties with elevated climate risks may experience slower appreciation—or outright depreciation—as markets increasingly recognize long-term exposure.

Unlike traditional real estate cycles, climate-related devaluation may persist because the underlying physical risks continue to evolve.


5. Climate Risk Is Becoming a Core Investment Risk

Climate change is transforming real estate from an asset class valued primarily by location into one increasingly valued by resilience.

Future property performance will depend not only on neighborhood desirability but also on:

  • Infrastructure quality
  • Flood protection
  • Insurance availability
  • Building efficiency
  • Utility reliability
  • Community adaptation efforts

Investors, lenders, insurers, and homebuyers are already incorporating these factors into financial decisions.


Conclusion

Climate change does not mean that all real estate will suddenly lose value or become uninhabitable. Real estate will remain one of the world’s largest and most important asset classes. However, the factors that determine value are changing.

The greatest risk is not a sudden collapse of the housing market but a gradual repricing of climate risk. Some properties may remain highly desirable for decades, while others may face increasing costs from insurance, maintenance, financing, and regulatory compliance.

Understanding these risks allows homeowners, investors, developers, lenders, and policymakers to make informed decisions. Investments in resilient construction, improved infrastructure, energy efficiency, and thoughtful land-use planning can reduce long-term vulnerability and help preserve property values.

The future of real estate will increasingly be determined not simply by location, location, location, but by location, resilience, and adaptability.

bookmark_borderWhy Climate Change Will Continue to Evolve for Decades: The Case for Long-Term Financial and Real Estate Planning

“The greater risk is a gradual degradation of living standards if adaptation is delayed.“

by Daniel Brouse

Introduction

Climate change is often discussed as if it will either produce an imminent societal collapse or, conversely, have little economic consequence. Neither view is supported by the physical science.

The Earth’s climate system responds over multiple timescales. While the atmosphere reacts relatively quickly to changes in greenhouse gas concentrations, the oceans—the planet’s largest heat reservoir—respond much more slowly. This difference, known as thermal inertia, means that many of the economic consequences of climate change will continue to unfold over decades, regardless of whether emissions peak today or several years from now.

For investors, homeowners, businesses, insurers, lenders, and governments, this distinction is critical. The evidence points not toward an immediate collapse of the global economy, but toward a long period of increasing environmental risks that will progressively reshape financial markets and real estate values.


The Ocean’s Long Memory

If greenhouse gas concentrations remained near current levels long enough to maintain today’s radiative forcing, it would likely take many decades to centuries for the global ocean to warm by an additional 3°C.

Current scientific understanding suggests:

  • The upper ocean (roughly the top 700 meters) could warm several additional degrees over approximately 50–150 years.
  • The deep ocean requires centuries to more than a millennium to approach equilibrium.
  • The global ocean average would likely require several centuries of sustained forcing to warm another 3°C.

More than 90% of Earth’s excess heat enters the oceans, giving the climate system enormous momentum.

Even if atmospheric temperatures stabilize, sea level rise, marine heat waves, glacier retreat, and many coastal impacts continue because the oceans continue redistributing heat.

Climate change therefore behaves less like flipping a switch and more like steering an aircraft carrier. Once underway, changes continue for decades.


Why This Does Not Mean Immediate Economic Collapse

The nonlinear acceleration of climate change does not imply that modern economies disappear within a few years.

Economic systems continually adapt.

History demonstrates remarkable resilience through world wars, financial crises, pandemics, technological revolutions, and natural disasters. Markets evolve. Capital reallocates. Infrastructure is rebuilt. New technologies emerge.

Climate change represents another major structural transformation—not an instantaneous end to economic activity.

The greater risk is a gradual degradation of living standards if adaptation is delayed.


Financial Markets Price Risk—They Do Not Ignore It

Financial markets constantly evaluate future expectations.

Investors already incorporate:

  • Inflation
  • Interest rates
  • Technological disruption
  • Demographics
  • Political risk
  • Corporate earnings

Climate risk is becoming another measurable input.

Rather than causing markets to cease functioning, climate change increasingly changes how capital is allocated.

Investment flows are likely to favor:

  • Resilient infrastructure
  • Water management
  • Energy efficiency
  • Distributed power systems
  • Climate-resilient agriculture
  • Advanced building technologies
  • Adaptation engineering

Markets rarely stop functioning.

They reprice risk.


Mortgage Lending in a Changing Climate

Mortgage lending has always depended upon one fundamental assumption:

The collateral will retain value over the life of the loan.

Most residential mortgages extend 15 to 30 years.

Commercial financing often spans decades.

Those time horizons now overlap directly with accelerating climate risks.

Lenders are increasingly evaluating:

  • Flood exposure
  • Wildfire probability
  • Coastal erosion
  • Extreme heat
  • Water availability
  • Infrastructure resilience
  • Local adaptation policies

Climate risk is becoming credit risk.

Properties with increasing exposure may experience:

  • Higher insurance costs
  • Larger reserve requirements
  • Lower loan-to-value ratios
  • Increased underwriting scrutiny
  • Higher borrowing costs

Conversely, resilient communities with strong infrastructure may receive more favorable financing because they present lower long-term risk.

Climate-informed lending is simply modern risk management.


Insurance Availability May Become the First Market Signal

Insurance companies often detect climate risk before property markets do.

Unlike homeowners, insurers continuously update catastrophe models using the latest observations and loss data.

When risks increase, insurers respond by:

  • Raising premiums
  • Increasing deductibles
  • Restricting coverage
  • Reducing policy limits
  • Withdrawing from selected markets

Recent developments in wildfire-prone states, hurricane-exposed coastlines, and hail-prone regions illustrate this trend.

In many communities, insurance affordability—not property damage itself—may become the first significant economic consequence of climate change.
Without affordable insurance:

  • Mortgage financing becomes more difficult.
  • Homeownership becomes more expensive.
  • Property values may weaken.
  • Municipal tax bases can come under pressure.

Insurance increasingly serves as an early warning system for long-term climate risk.


Municipal Bonds and Local Government Finance

Climate resilience is increasingly becoming a municipal finance issue.

Cities and counties finance much of their infrastructure through municipal bonds.

Those bonds ultimately depend upon:

  • Stable tax revenues
  • Economic growth
  • Reliable infrastructure
  • Sustainable operating costs

As climate risks increase, municipalities may require additional investments in:

  • Flood control
  • Stormwater systems
  • Water supply
  • Cooling infrastructure
  • Grid modernization
  • Emergency services
  • Road and bridge resilience

Communities that invest proactively may maintain stronger credit quality over time.

Communities that defer adaptation could face rising maintenance costs, increasing insurance expenses, and pressure on their fiscal health.

For municipal investors, climate resilience increasingly becomes part of long-term credit analysis.


Property Valuation Is Becoming Dynamic

Historically, property valuation focused on:

  • Location
  • Schools
  • Transportation
  • Employment
  • Neighborhood quality

Climate is becoming another location characteristic.

Future valuation models will likely incorporate increasing amounts of climate-related information, including:

  • FEMA flood maps
  • Local flood history
  • Heat exposure
  • Wind risk
  • Wildfire potential
  • Water reliability
  • Insurance costs
  • Building resilience
  • Community adaptation investments

Properties will not simply gain or lose value because of climate change.
Rather, markets will increasingly differentiate between properties based on their long-term resilience.

The result is likely to be greater divergence between communities that prepare and those that do not.


Investment Implications

Because climate impacts unfold over decades, financial planning becomes more—not less—important.

Assuming there will be “no economy” several years from now is neither supported by economic history nor by climate science.

Instead, investors should recognize that long-term wealth preservation increasingly depends upon understanding long-term environmental risk.

That includes:

  • Diversified investment portfolios.
  • Climate-informed real estate decisions.
  • Appropriate insurance coverage.
  • Infrastructure resilience.
  • Geographic diversification.
  • Long-term retirement planning.

Planning remains one of the strongest tools available for reducing future financial risk.


Fiduciary Responsibility Across Generations

Every generation inherits assets built by those before it.

Likewise, every generation passes assets forward.

That fiduciary responsibility extends beyond investment portfolios.

It includes:

  • Homes.
  • Communities.
  • Infrastructure.
  • Businesses.
  • Natural resources.
  • Financial systems.

Protecting both environmental and financial capital is not a contradiction.

It is prudent stewardship.

Planning for climate risk is no different than planning for inflation, demographic change, technological disruption, or changing interest rates.

Responsible investors prepare for foreseeable risks rather than assuming those risks either do not exist or will immediately end the economic system.


Conclusion

Climate science indicates that many impacts will continue evolving over decades because Earth’s oceans absorb and release heat slowly.

That long timescale does not support predictions of imminent economic collapse.

Instead, it points toward an extended period during which markets continuously adapt by repricing risk, directing capital toward resilience, and rewarding long-term planning.

For homeowners, investors, lenders, insurers, businesses, and governments, the challenge is not deciding whether there will be an economy.

The challenge is helping shape an economy that is both financially resilient and environmentally sustainable.

The goal is not simply to leave future generations a larger investment portfolio.

It is to leave them both a livable climate and an economy capable of supporting opportunity for decades to come.