bookmark_borderThe Meme Stock Market: Why Wall Street Is Defying Economic Gravity

Why is the stock market still rising when nearly every other economic indicator is flashing red? Bonds are weakening, real estate is cooling, manufacturing is in decline, and employment growth is softening. Yet the stock market continues to show upward momentum, seemingly disconnected from fundamentals.

The answer lies in a fundamental transformation of the market structure itself. Since the pandemic, retail investors—empowered by platforms like Robinhood and fueled by stimulus checks, social media hype, and a near zero-interest-rate environment—have reshaped trading dynamics. This new phenomenon has given rise to what I call the “meme stock market.”

Unlike traditional investors, who rely on fundamentals such as earnings, revenue growth, or long-term sector trends, many retail traders are driven almost entirely by momentum, sentiment, and speculation. The trading models at play are not designed to build wealth over time; they are designed to exploit short-term volatility. This speculation is often amplified by leverage, margin accounts, and options trading, making swings more dramatic and less predictable.

The problem is that momentum-driven markets lack stability. They create the illusion of strength while quietly building fragility beneath the surface. As more money chases speculation rather than fundamentals, valuations drift further from reality, creating a bubble that cannot be sustained.

This bubble will almost certainly burst. And when it does, the unwinding will be severe. Because so many retail traders are using leveraged positions without effective downside protection, the correction will not simply be a normal pullback—it will be a violent contraction with significant ripple effects across the economy.

The stock market’s current behavior is not a sign of resilience but of distortion. It is being propped up by short-term speculation rather than long-term strength. Prudent investors should recognize the risks and approach this market with extreme caution.

Retail Investor’s Impact

Retail investors are individuals trading their own money through brokerage platforms, rather than through institutional structures like mutual funds, pensions, or endowments. While they don’t own the largest share of total market capitalization compared to institutions, their behavioral impact on the market is outsized relative to their percentage of ownership.

Here’s why:

  • Concentration of activity – Retail investors tend to pile into the same “meme” names or high-momentum stocks, amplifying volatility in ways that broad institutional strategies (like index funds) do not.

  • Leverage & options trading – Post-pandemic, we’ve seen an explosion of retail activity in leveraged products, including options and margin trading. For example, options volume is now dominated by contracts with less than 24 hours to expiration (“zero-day options”), and retail traders are a major driver of that activity. This behavior magnifies short-term swings.

  • Market signaling – Even though institutions hold more shares, they often respond to sentiment and volatility triggered by retail traders. In effect, retail flows can act as a spark that ignites much larger institutional moves.

  • High churn – The percentage of total market ownership by retail investors (estimated around 20–25% of U.S. equities) is less important than their trading behavior. Retail traders churn their portfolios at much higher rates than institutional investors, meaning the same dollars are moving in and out of positions far more rapidly. This turnover creates disproportionate price pressure compared to “buy and hold” strategies used by pensions and index funds.

The key issue isn’t retail investors’ overall share of ownership—it’s the outsized impact of their speculative, leveraged trading activity. Their rapid-fire churn has fundamentally reshaped market dynamics, injecting far more instability than their raw ownership percentages suggest.

As of the end of Q2 2025, Microsoft (MSFT), Apple (AAPL), and Nvidia (NVDA) together made up roughly 20% of the entire S&P 500 index. Because the index is market-cap weighted, this unprecedented concentration in just a handful of companies means that movements in these few stocks disproportionately drive the performance of the broader market.

Layer on top the influence of retail traders, whose momentum-driven strategies are detached from fundamentals, and the result is extreme volatility. In fact, on any given trading day, as much as 95% of index swings can be traced back to a combination of two forces: retail churn and the heavy concentration of market cap in a narrow set of tech giants. This creates the illusion of strength while masking deep fragility in the underlying economy.

Trumpenomics: The Decline of the US
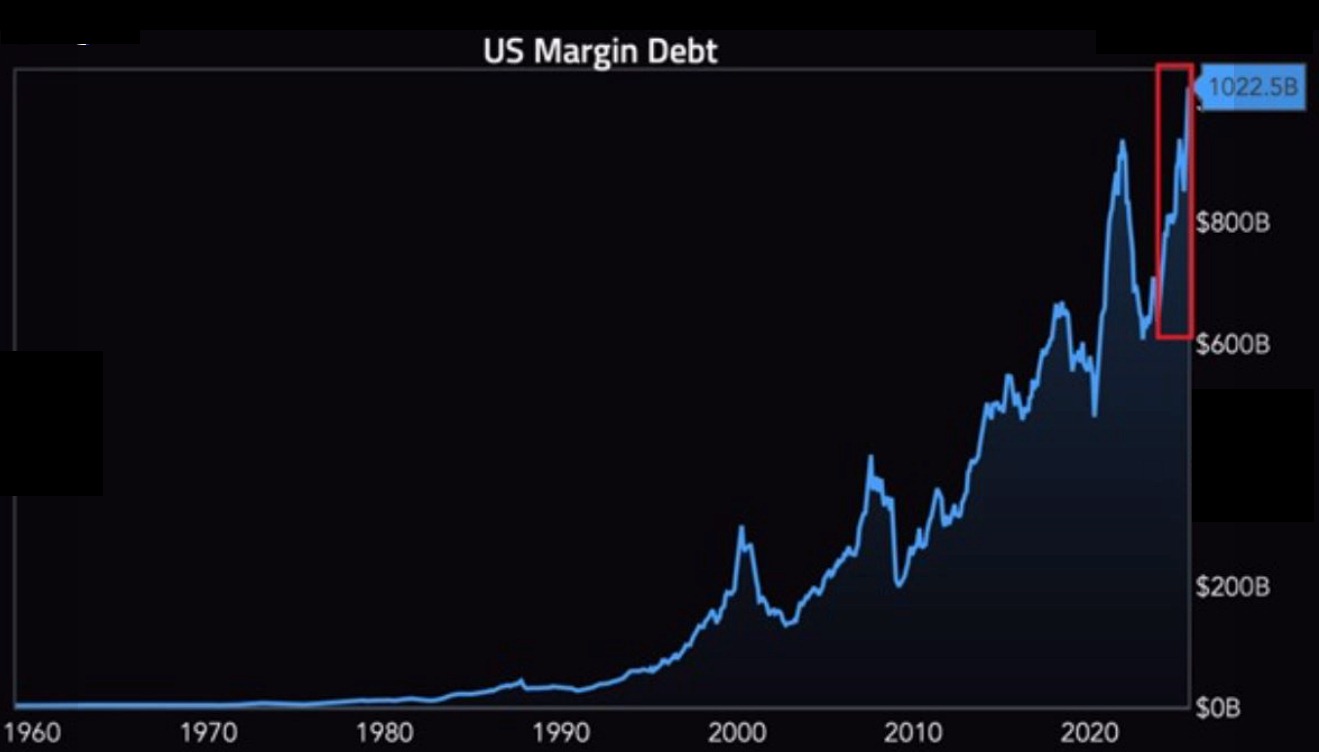
US Margin Debt (Buying Stocks With Borrowed Money)

bookmark_borderTrump’s Attacks on the Fed and Economic Institutions Signal Escalating Risks

Last night, President Trump fired Lisa Cook from the board of the Federal Reserve—a move that has sparked widespread concern. Despite her refusal to step down, domestic markets appear relatively unshaken. However, international observers are sounding the alarm: the independence of the Federal Reserve is a cornerstone of global confidence in the U.S. economy.

Trump’s continued and increasingly aggressive efforts to undermine the Fed may be among his most destabilizing economic actions. While protectionist trade policies, tariffs, and nationalist policies already contribute to economic uncertainty, this latest move threatens the very framework that underpins financial stability. A common misunderstanding by Trump is that the Fed controls market interest rates. In reality, the Fed sets rates only for overnight lending between banks; broader market rates are determined independently by supply, demand, and investor expectations. Historically, even when the Fed has cut its short-term rates, long-term market rates have often risen in response—meaning that Trump’s interference is counterproductive to any goal of lowering borrowing costs.

These actions are eroding U.S. credibility, weakening the dollar’s status as the global reserve currency, and undermining the perception of American economic exceptionalism. Simultaneously, Trump is acquiring stakes in private firms such as U.S. Steel and Intel. The Department of Defense recently took a significant position in MP Materials, a U.S.-based rare earth minerals company. Meanwhile, Nvidia and AMD are reportedly remitting 15% of their revenue from certain AI chip sales to China to the U.S. government in exchange for export licenses. Earlier today, the Commerce Secretary signaled that the administration is exploring acquisitions of major defense contractors, including Lockheed Martin.

Together, these moves reflect a troubling shift toward a centralized, corporatist form of control, blurring the lines between government and private enterprise—a trend that many analysts view as a step toward fascism. The combination of undermining independent institutions, aggressive protectionism, and state involvement in private industry signals growing risks not only for the U.S. economy but for global financial stability.

Trumpenomics: The Decline of the US

bookmark_borderU.S. Manufacturing Hits Historic Lows: Durable Goods and Philly Fed Data Signal Economic Weakness

The latest economic indicators reveal a troubling slowdown in U.S. manufacturing. Durable goods orders and the manufacturing index both posted their worst levels since the 2020 pandemic, signaling a sharp contraction in industrial activity.

Philadelphia once again made headlines as the Philly Fed reported a historic decline in its new orders index, falling to -1.9. This marks a significant drop, reflecting weakening demand for manufactured products in the region. Economists note that a negative reading in the Philly Fed new orders index often correlates with broader declines in production, employment, and business investment, suggesting that U.S. manufacturing is under mounting stress.

The combination of sluggish durable goods orders and contracting regional manufacturing indicators underscores the potential for a broader economic slowdown. Rising trade tensions, high tariffs, and persistent supply chain disruptions are likely contributing factors, compounding challenges already posed by inflationary pressures and global uncertainty.

Analysts caution that unless consumer demand rebounds and supply chain issues are mitigated, these signals could foreshadow deeper recessional trends in the industrial sector in the months ahead.

Trumpenomics: The Decline of the US

bookmark_borderTrump’s Tariff Gambit Backfires: European Postal Services Halt Shipments to U.S.

Postal services across Europe are suspending parcel shipments to the United States amid mounting uncertainty over Donald Trump’s escalating tariff policies. At the center of the disruption is an executive order Trump signed last month, abolishing the long-standing tax exemption that allowed small packages worth less than $800 to enter the U.S. duty-free. That exemption, widely used by small European businesses, had been critical for maintaining affordable cross-border trade in consumer goods.

The new rule, which takes effect on August 29, removes a vital lifeline for entrepreneurs who relied on low-cost shipping to reach American customers. Without the exemption, even inexpensive goods—from clothing and electronics accessories to specialty foods—face complex customs procedures and potentially punishing tariffs.

The fallout has been swift. Several European postal services announced they would temporarily suspend shipments of small parcels to the U.S., citing both administrative uncertainty and cost concerns. For small exporters, this amounts to a near-total loss of access to one of the world’s largest consumer markets. For American consumers, it means higher prices, longer wait times, and fewer choices.

The move is also drawing sharp criticism for its hypocrisy. Trump and his administration frequently accuse foreign countries of erecting unfair trade barriers against U.S. products, yet this policy places one of the world’s most restrictive trade barriers on imports of everyday goods. While Trump frames the measure as “protecting American workers,” the policy risks doing the opposite—raising consumer prices at home while triggering retaliation abroad that harms American farmers, manufacturers, and exporters.

Trade experts warn that this step is part of a broader strategy of weaponizing tariffs and abandoning long-established trade norms. “The U.S. is setting a precedent that undermines its own credibility,” one European trade analyst noted. “You can’t demand open markets for American goods while shutting your own doors to small-scale imports.”

With the holiday shopping season approaching, the suspension of parcel shipments could prove particularly disruptive for small businesses and consumers on both sides of the Atlantic. Meanwhile, Brazil, China, and other competitors stand ready to fill the void, further eroding U.S. economic influence.

In effect, Trump’s latest tariff gambit risks isolating the U.S. from global supply chains, worsening inflationary pressures, and accelerating the shift of trade alliances away from America. What was once touted as a move to “make America great again” looks increasingly like a strategy to make U.S. consumers and businesses pay the price.

Trumpenomics: The Decline of the US

bookmark_borderTrump’s Tariffs Are Crushing U.S. Soy Farmers While Brazil Gains

by Daniel Brouse
August 20, 2025

Trump’s latest wave of tariffs is already sending shockwaves through the U.S. agricultural sector, with soybean farmers among the hardest hit. The American Soybean Association has warned that many growers may lose their farms this year, as the trade disruptions come at a critical moment in the harvesting season.

Soybean producers were still struggling to recover from Trump’s first trade war with China in 2019. Before that conflict, China accounted for 33% of U.S. soybean exports. That share collapsed after China retaliated with tariffs, and even by 2024, the market had only clawed back to 25% of pre-trade war levels. In other words, farmers were still operating below historical export norms when Trump reignited protectionist battles in 2025.

This year, the damage has been swift and severe. Typically, by this point in the season, about 10% of the U.S. soybean crop would already be under contract with China. Instead, there have been zero new contracts. Buyers in Beijing are turning to Brazil, which has rapidly expanded its agricultural capacity in recent years. Ironically, even though the U.S. has imposed a 50% tariff on Brazilian goods, Chinese buyers are more than willing to pay for Brazilian soy rather than navigate the uncertainty and higher costs of American exports.

The economic fallout extends far beyond the farm. With fewer contracts, rural communities are losing vital income, credit markets that finance farm operations are tightening, and American consumers face the risk of higher food prices. To make matters worse, grain operators in rural areas are refusing to accept soybeans from local farmers unless the crops are already under contract—pushing many small farmers to the brink of collapse. Meanwhile, Brazil is solidifying its position as the world’s dominant soybean exporter, seizing on U.S. trade instability to expand its global market share.

The president of the American Soybean Association summed it up starkly: these tariffs are “destroying U.S. soybean farmers.” Without swift policy changes, this year may mark not just another setback but a permanent loss of market share that America never regains.

Trumpenomics: The Decline of the US

bookmark_borderAmerica’s Quiet March Toward Socialism: Trump’s Golden Share and the State’s Expanding Grip on Industry

The United States—long celebrated as the global champion of free-market capitalism—is drifting toward state-controlled economics at a pace few could have predicted. Recent developments reveal a pattern of government intervention in critical industries that blurs the lines between capitalism, protectionism, and outright socialism.

Trump’s Golden Share in U.S. Steel

Perhaps the clearest example comes from Trump’s move to socialize U.S. Steel, in which the government has secured a “golden share.” This arrangement effectively hands Trump final say over key corporate decisions, giving the government direct control over a private enterprise that has been central to American industrial history. For a nation that once railed against state ownership in places like China, this marks a striking shift.

Taxing Tech Revenues: Nvidia and AMD

In a separate but equally significant move, Nvidia and AMD have reportedly agreed to hand over 15% of their revenue from sales of certain advanced chips to China directly to the U.S. government. While justified as a way to fund national security and counterbalance Beijing, this model effectively amounts to government revenue-sharing on private enterprise—a system more often associated with resource nationalism in petro-states than with American capitalism.

Defense Investments in Critical Minerals

The U.S. Department of Defense has also stepped into the investment space, announcing $400 million in funding for MP Materials, a key rare-earth mining and processing company. The rationale is clear: securing supply chains for critical minerals is essential for both the green energy transition and national defense. Yet this represents another case of direct taxpayer investment into private industry, expanding the government’s footprint in the market.

From Capitalism to Corporatism—and Beyond

Individually, each of these actions could be defended on strategic grounds: protecting national security, ensuring supply chain stability, or countering foreign rivals. But taken together, they signal a profound reordering of the relationship between the U.S. government and the private sector.

  • Golden shares are a hallmark of state capitalism in places like Russia and China.

  • Revenue-sharing agreements resemble socialist taxation structures designed to redistribute corporate profits.

  • Direct government investment in strategic industries pushes the U.S. closer to an industrial policy model that relies heavily on state intervention.

The end result is a creeping hybrid system—part capitalism, part state socialism—that threatens to undermine the very principles of free enterprise that the U.S. has long championed.

The Bigger Picture

Critics warn that once the government establishes itself as a direct stakeholder in industry, it rarely retreats. What begins as a national security measure often morphs into permanent control, stifling innovation and distorting markets. Meanwhile, other nations are watching closely: how can Washington preach free-market values abroad while practicing state control at home?

Conclusion

Whether labeled as protectionism, industrial policy, or socialism, these moves represent a turning point. America is no longer the free-market exemplar it once claimed to be. Instead, it is quietly embracing a model of government-steered capitalism—a path that risks undermining both economic freedom and global credibility.

Trumpenomics: The Decline of the US

bookmark_borderProducer Prices Surge: Tariffs and Protectionism Poised to Push Inflation Higher

The latest Producer Price Index (PPI) figures have been released—and they came in sharply above expectations. This upside surprise suggests that inflationary pressures at the wholesale level are building more quickly than many economists and market participants anticipated.

While the most recent Consumer Price Index (CPI) data showed only a modest uptick—enough to be noticed but not enough to spook markets—the PPI data paints a different picture. Producer prices often serve as a leading indicator for consumer inflation, meaning the higher costs businesses face today are likely to be passed along to consumers in the coming months.

Why This Matters

The spike in PPI isn’t happening in isolation—it’s unfolding against a backdrop of rising tariffs and protectionist trade policies. Recent and proposed tariff measures, especially those targeting imports from China, are expected to directly increase the cost of goods. These increases are compounded by tariff stacking, where multiple tariffs apply to the same product, leading to taxes on top of taxes and magnifying the inflationary impact.

For example:

  • Tariffs on imported steel and aluminum raise manufacturing costs for vehicles, appliances, and infrastructure.

  • Component-specific tariffs increase the price of intermediate goods like semiconductors, batteries, and motors.

  • Reciprocal tariffs from trading partners can disrupt supply chains and force businesses to source from higher-cost markets.

This cost pressure is already visible at the wholesale level in the PPI. As these higher costs work their way through the supply chain, the CPI is likely to follow.

Market Response So Far

Markets initially took the modest CPI increase in stride, but the PPI shock is harder to ignore. Bond yields are likely to rise as investors factor in the possibility that the Federal Reserve could keep interest rates elevated for longer—or even raise them again—to counteract the inflationary effects of protectionism-driven cost increases.

Equities could face renewed pressure, especially in industries reliant on imported goods and materials, such as automotive manufacturing, electronics, and consumer appliances. Retailers and wholesalers may also see margin compression if they are unable to pass along all the added costs to consumers without hurting demand.

The Road Ahead

If tariffs continue to expand and stack across multiple sectors, the PPI could see sustained upward pressure well into next year. This would eventually force the CPI higher, potentially rekindling inflation fears that the Fed has worked hard to tame since the post-pandemic price surge.

The takeaway?
The latest PPI data isn’t just a statistical blip—it’s a warning sign. Inflation may not be finished with us yet, and protectionist policies could be the accelerant that keeps prices climbing.

Trumpenomics: The Decline of the US

bookmark_borderTariffs Fail to Tame Soaring U.S. Budget Deficit as Spending Outpaces Revenue

by Daniel Brouse
August 13, 2025

The U.S. government’s budget deficit surged nearly 20% in July 2025, reaching $291 billion for the month, despite a sharp rise in customs duty collections from President Donald Trump’s aggressive tariff policies. According to Treasury Department data released Tuesday, the deficit increase underscores that tariffs — often touted as a revenue tool — are not offsetting the broader fiscal pressures caused by rising federal spending and mounting debt interest costs.

Compared with July 2024, the deficit swelled by $47 billion, marking a 19% year-over-year jump. Receipts for the month grew modestly, up 2% ($8 billion) to $338 billion, driven in part by a nearly threefold increase in customs duties — from $7 billion a year ago to almost $21 billion in July 2025. This spike reflects the impact of steep tariff hikes on a wide range of imported goods from countries such as China, India, Brazil, and Canada. Tariffs are nothing more than a hidden tax on consumers — and this marks the largest effective tax increase in U.S. history.

However, federal outlays surged even more sharply, climbing 10% ($56 billion) to a record $630 billion for July — the highest monthly spending for that month in U.S. history. A major contributor was the escalating burden of interest payments on the growing national debt, which now consumes an ever-larger share of the budget.

For the fiscal year to date, the budget deficit has already topped $1.6 trillion, putting the U.S. on track for one of its largest annual deficits outside of a recession or major war. Debt servicing costs continue to climb as higher interest rates compound the burden of an already massive national debt.

The July data highlight a core reality of protectionist economic policy: tariffs are a regressive tax on consumers and businesses, raising prices while failing to meaningfully close the deficit gap. Instead of curbing borrowing, the Trump administration’s trade war has added complexity to supply chains, dampened export markets through retaliatory tariffs, and stoked inflationary pressures — all while doing little to address the structural drivers of U.S. debt.

Economists warn that without serious reforms to both revenue generation and spending control, the U.S. risks a cycle of mounting deficits, rising interest costs, and eroding investor confidence — an economic trajectory that could weaken America’s fiscal resilience for decades to come.

Trumpenomics: The Decline of the US

bookmark_borderThe Hidden Tax: How Rising Tariffs Harm the U.S. Economy and Burden Everyday Americans

As of August 7, 2025, the effective average U.S. tariff rate on imported goods and services has surged to approximately 22.38%. Historically, that number has hovered around 2.5%, reflecting decades of relatively free trade and open global markets. This abrupt increase represents not only a dramatic reversal of U.S. trade policy, but also the single largest tax hike in American history—and the most regressive, hitting working- and middle-class families the hardest.

While the rhetoric behind tariffs often focuses on “protecting American jobs” and “punishing unfair trading partners,” the reality is that protectionism inflicts long-term economic damage that far outweighs any short-term political gains.

How Protectionism Hurts the Economy

1. Higher Consumer Prices
Tariffs function as taxes on imported goods. When a 25–50% tariff is imposed on imports from countries like China, India, Brazil, or even long-time allies like Canada and the EU, U.S. companies either pass the added costs directly to consumers or reduce quality and choice. From automobiles and appliances to clothing, electronics, and groceries, everyday goods become more expensive. This disproportionately affects low-income households, which spend a higher percentage of their income on essentials.

2. Supply Chain Disruptions
Modern supply chains are global. Components for a single product may come from a dozen countries. By erecting tariff barriers, the U.S. disrupts these intricate supply chains, forcing businesses to reshuffle suppliers, reengineer products, or absorb losses—all of which increase costs and reduce efficiency.

3. Retaliatory Tariffs, Boycotts, and the Rise of Anti-American Sentiment

Other countries don’t stand idle in the face of U.S. protectionism. History shows that aggressive tariff policies almost always provoke retaliatory tariffs on American exports, which directly harms key sectors of the U.S. economy—particularly agriculture, manufacturing, and services. During previous trade wars, American farmers lost critical access to international markets, resulting in surplus crops, falling commodity prices, and the need for multi-billion-dollar taxpayer-funded bailouts to offset the damage.

But today, the consequences extend well beyond formal trade retaliation.

A growing number of consumers and businesses abroad are engaging in informal economic retaliation through boycotts. As the United States becomes increasingly viewed as economically combative and diplomatically unreliable, anti-American sentiment is rising. In many countries, people are intentionally avoiding U.S.-made products, U.S.-based services, and even U.S. tech platforms, choosing alternatives from Europe, Asia, or domestic providers.

This backlash is especially damaging given that the U.S. is no longer a manufacturing-based economy, but a service-based economy, heavily reliant on exports of financial services, technology, entertainment, education, and tourism. In sectors like film, software, consulting, and higher education, global reputation is currency—and that currency is being rapidly devalued by confrontational trade policies and erratic diplomacy.

Tourism is also being affected. Once a top global destination, the U.S. has seen significant declines in international travel, in part due to tightened visa policies, but increasingly because of growing distaste for the U.S.’s international behavior. Millions of potential visitors—who would have spent money in American hotels, restaurants, stores, and attractions—are now choosing to travel elsewhere.


4. Reduced Investment and Innovation
When trade barriers rise, investor confidence falls. Businesses hold off on expansion, hiring, or investing in new technologies if they’re uncertain about future access to foreign markets. Protectionism stifles the very dynamism that drives long-term growth and productivity.

The Regressive Nature of Tariffs

Unlike income taxes, which scale with earnings, tariffs are blind to income. A billionaire and a minimum-wage worker both pay more for a smartphone, a car, or a gallon of milk due to import duties. This makes tariffs a regressive tax, one that widens inequality by placing a heavier burden on those least able to afford it.

A Historic Mistake Repeated

We’ve seen this before. The Smoot-Hawley Tariff Act of 1930, passed in the early days of the Great Depression, raised tariffs on thousands of imports. Other nations retaliated, world trade collapsed, and the Depression deepened. Economists overwhelmingly agree that protectionist trade policy worsened global economic conditions during that period.

Now, nearly a century later, the U.S. is making the same mistake—again under the banner of economic nationalism. The long-term consequences could be severe: slower growth, weakened competitiveness, strained international relations, and a lower standard of living for American families.

In Summary:
A 22.38% average tariff rate is not a shield for American jobs—it’s a self-inflicted tax that increases costs, fuels inflation, restricts growth, and disproportionately hurts the average person. History, logic, and data all tell us the same thing: protectionism doesn’t protect—it punishes.

In short, the economic cost of protectionism isn’t just higher prices or lost trade—it’s a damaged global reputation, leading to long-term losses in consumer trust, market access, and global influence.

Reciprocal Tariffs

Brazil

50%

India

50%

Syria

41%

Laos

40%

Myanmar (Burma)

40%

Switzerland

39%

Canada

35%

Iraq

35%

Serbia

35%

Algeria

30%
   

Bosnia and Herzegovina

30%

China

30%

Libya

30%

South Africa

30%

Brunei

25%

Kazakhstan

25%

Mexico

25%

Moldova

25%

Tunisia

25%

Bangladesh

20%
   

Sri Lanka

20%

Taiwan

20%

Vietnam

20%

Cambodia

19%

Indonesia

19%

Malaysia

19%

Pakistan

19%

Philippines

19%

Thailand

19%

Nicaragua

18%
   

Afghanistan

15%

Angola

15%

Bolivia

15%

Botswana

15%

Cameroon

15%

Chad

15%

Costa Rica

15%

Côte d`Ivoire

15%

Democratic Republic of the Congo

15%

Ecuador

15%
   

Equatorial Guinea

15%

European Union

15%

Fiji

15%

Ghana

15%

Guyana

15%

Iceland

15%

Israel

15%

Japan

15%

Jordan

15%

Lesotho

15%
   

Liechtenstein

15%

Madagascar

15%

Malawi

15%

Mauritius

15%

Mozambique

15%

Namibia

15%

Nauru

15%

New Zealand

15%

Nigeria

15%

North Macedonia

15%
   

Norway

15%

Papua New Guinea

15%

South Korea

15%

Trinidad and Tobago

15%

Turkey

15%

Uganda

15%

Vanuatu

15%

Venezuela

15%

Zambia

15%

Zimbabwe

15%
   

Falkland Islands

10%

United Kingdom

10%

Other Tariffs
An average of an additional 50% on most goods from China

Aluminum 50%
Steel 50%
Copper 50%
Autos 25%

Trumpenomics: The Decline of the US

bookmark_borderTariffs, Hypocrisy, and Geopolitical Backfire: Trump Slaps 50% Tariffs on Indian Goods Over Russian Oil

In a move that is already sparking backlash among global trade experts and U.S. allies, former President Donald Trump has issued a directive to impose an additional 25% tariff on a wide array of Indian goods—raising the total tariff rate to 50%. This decision, according to Trump, is a response to India’s ongoing purchases of oil from Russia, despite the global push to isolate the Kremlin economically due to its actions in Ukraine.

But the rationale behind this punitive measure appears deeply flawed and hypocritical. The United States itself continues to import Russian commodities, most notably palladium, a rare and strategically important metal used in catalytic converters for gasoline-powered cars. Fertilizer components and other essential minerals from Russia are also still entering U.S. markets through direct or indirect channels.

India, on the other hand, has consistently argued that its purchases of Russian oil are both legal under international law and necessary to ensure energy security for its 1.4 billion citizens. Indian officials have questioned the sensibility and fairness of U.S. trade policy, pointing out the double standard at play. Why should India be punished for buying oil, while the U.S. continues trading in Russian metals essential for its fossil fuel economy?

More broadly, this action raises serious questions about U.S. strategic coherence, economic independence, and long-term competitiveness. If the U.S. truly wants to reduce reliance on Russian imports, the logical path forward is to accelerate the transition away from internal combustion engine (ICE) vehicles—which would reduce the need for palladium entirely. In that sense, India’s critique is not just diplomatic posturing; it highlights a genuine lack of economic sensibility in America’s reactive, ad hoc tariff policy.

The new 50% tariff could significantly disrupt U.S.–India trade relations, which had been steadily improving, and potentially alienate an important ally in the Indo-Pacific region. It also introduces unnecessary inflationary pressure at a time when the U.S. economy is already grappling with rising prices, job market cooling, and growing fears of stagflation.

At its core, this tariff escalation appears more about political optics than economic logic. Unfortunately, global markets and working families may once again bear the brunt of short-sighted, inconsistent trade policy.


The Human Induced Climate Change Experiment

Trumpenomics: The Decline of the US