bookmark_borderExtreme Rainfall–surge Hazard Risks

by Daniel Brouse

Most climate change models forecast rising sea levels as the predominant threat of a warming climate to flood risks. Though sea level rise is of great concern, so should be extreme rainfall.

Both the sea and air temperatures are rising. Warm air can hold more moisture than cool air. Warmer sea temperatures result in more evaporation. Warmer air can hold more moisture. The increased moisture in the air moves over land causing inland deluges.

Hurricane Ida in the summer of 2021 is a good example. Because of the 85 degrees Fahrenheit Gulf of Mexico ocean temperature, Ida rapidly gained strength right before it made landfall jumping from a Category 1 to a Category 4 storm. The warm air allowed more moisture to be carried as rain. The storm was so large that it was able to pick up more moisture from the Atlantic Ocean. The ocean moisture was carried inland and dumped over places like Pennsylvania and New York. Ida caused record flood damage in parts of Pennsylvania. The Philadelphia Inquirer reported, “The remnants of Hurricane Ida destroyed or damaged hundreds of homes in Southeastern Pennsylvania and caused more than $100 million in public infrastructure damage across the state.” There were more deaths in the Northeastern USA than where the storm made landfall in Louisiana. The New York Times reported, “The remnants of Hurricane Ida caused flash flooding and a number of deaths and disrupted transit across parts of New York and New Jersey. The storm killed at least 43 people in New York, New Jersey, Pennsylvania and Connecticut and left more than 150,000 homes without power.”

The Journal Nature published the study Tropical cyclone climatology change greatly exacerbates US extreme rainfall–surge hazard examining how current models underestimate the risk of Rainfall–surge Hazard. “Tropical cyclones (TCs) are drivers of extreme rainfall and surge, but the current and future TC rainfall–surge joint hazard has not been well quantified. Using a physics-based approach to simulate TC rainfall and storm tides, we show drastic increases in the joint hazard from historical to projected future (SSP5–8.5) conditions. The frequency of joint extreme events (exceeding both hazards’ historical 100-year levels) may increase by 7–36-fold in the southern US and 30–195-fold in the Northeast by 2100. This increase in joint hazard is induced by sea-level rise and TC climatology change; the relative contribution of TC climatology change is higher than that of sea-level rise for 96% of the coast, largely due to rainfall increases. Increasing storm intensity and decreasing translation speed are the main TC change factors that cause higher rainfall and storm tides and up to 25% increase in their dependence.”

From the article Rising Temperatures Bringing Bigger Floods published in the Journal Science, “CO2 emissions have boosted risk of intense precipitation and consequent flooding. To determine how rising temperatures have altered flood risk, atmospheric scientist Pardeep Pall of the University of Oxford in the United Kingdom and his colleagues ran thousands of climate simulations. In roughly half of them, they reduced atmospheric concentrations of carbon dioxide to levels measured in the year 1900, and they adjusted ocean temperatures and the amount of Arctic sea ice—which affects high-latitude weather patterns—accordingly. In the other simulations, they modeled modern conditions. Then they compared the rainfall amounts generated in both types of simulations. Finally, they fed the rainfall values into a model that assesses the potential for flooding. In 90% of the simulations, results suggested that the flood risk in England and Wales in autumn 2000 was at least 20% higher than it would have been in 1900.”

As the Earth warms, the air will hold more moisture. More moisture-laden air moves over land and creates atmospheric rivers (Pineapple Express). The Journal EOS in the article Atmospheric Rivers Spur High-Tide Floods on U.S. West Coast said, “Atmospheric rivers are narrow bands of moisture that travel across the lower troposphere, generally at the leading edges of massive low-pressure systems. At their peak, they can carry as much water through the sky as the Amazon River does on land. They unleash intense winds and heavy rain as they surge across the Pacific Ocean, eventually making landfall on the U.S. West Coast, contributing to many high-tide flooding events.”

The atmospheric rivers also bring heavy rainfall inland causing extreme flooding. In October of 2021 NOAA said, “a convergence of storms brought more than half a foot of rain to parts of the Bay area in addition to strong winds, flash floods, and mud/landslides. They also bring the potential for heavy snow to higher elevations in the Sierra Nevada mountain range.” (Atmospheric River Hits the West Coast)

More articles on Flood Insurance, Extreme Weather Events, Rising Sea Levels and Global Warming

bookmark_border26% Increase in US Flood Risk by 2050 Due to Climate Change

A study published in the Journal Nature, Inequitable patterns of US flood risk in the Anthropocene, models a 26.4% (24.1–29.1%) increase in US flood risk by 2050 due to climate change.

Flood Risk % Increase

“Our national depiction of comprehensive and high-resolution flood risk estimates in the United States indicates current average annual losses of US$32.1 billion (US$30.5–33.8 billion) in 2020’s climate, which are borne disproportionately by poorer communities with a proportionally larger White population. The future increase in risk will disproportionately impact Black communities, while remaining concentrated on the Atlantic and Gulf coasts. Furthermore, projected population change (SSP2) could cause flood risk increases that outweigh the impact of climate change fourfold. These results make clear the need for adaptation to flood and emergent climate risks in the United States, with mitigation required to prevent the acceleration of these risks.”

This study/model shows the heaviest impact on the Atlantic and Gulf coasts; however, as the Earth warms, the air will hold more moisture.
More moisture-laden air moves over land and creates atmospheric rivers (Pineapple Express). The Journal EOS in the article Atmospheric Rivers Spur High-Tide Floods on U.S. West Coast said, “Atmospheric rivers are narrow bands of moisture that travel across the lower troposphere, generally at the leading edges of massive low-pressure systems. At their peak, they can carry as much water through the sky as the Amazon River does on land. They unleash intense winds and heavy rain as they surge across the Pacific Ocean, eventually making landfall on the U.S. West Coast, contributing to many high-tide flooding events.”

The atmospheric rivers also bring heavy rainfall inland causing extreme flooding. In October of 2021 NOAA said, “a convergence of storms brought more than half a foot of rain to parts of the Bay area in addition to strong winds, flash floods, and mud/landslides. They also bring the potential for heavy snow to higher elevations in the Sierra Nevada mountain range.” (Atmospheric River Hits the West Coast)

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_border25% of Critical Infrastructure at Risk of Flooding

The First Street Foundation, a nonprofit research and technology group that assesses the threat posed by flooding across the country, released a report that found one-forth of critical infrastructure in the USA is at risk of flooding including: police and fire stations, hospitals, airports and wastewater treatment facilities.

“With an increasing number of flooding 1events making U.S. headlines, there is a greater awareness of the economic and human cost that
flood-damaged infrastructure can produce. For instance, Hurricane Sandy flooded hospitals, crippled electrical substations, overwhelmed waste water treatment centers, and shut down power and water to tens of millions of people (U.S. Senate Committee on Commerce, Science, and Transportation, 2012). More recently, the impact of Hurricane Ida stretched across the country crippling the electrical grid in southern Louisiana, flooding the transportation infrastructure in the NYC metro area, and killing nearly 100 people. It is clear, now more than ever, that the ways and places in which we live are likely to continue to be impacted by our changing environment. One of the most important implications in this development is the vulnerability of our national infrastructure.”

About 1/4 (2 million miles) of roads are already at risk of becoming impassable due to flooding.

“And as global warming melts ice sheets, raises sea levels and tilts the odds in favor of more extreme rainfall events, the risk will grow in many more communities, the First Street report found. Over the next 30 years, the number of residential properties at risk of flooding is expected to grow from 12.4 million today to 13.6 million by 2051, the report says. For critical infrastructure and commercial properties, the number of vulnerable facilities are projected to grow by 6% and 7% respectively over the next three decades,” said Drew Kann and Ella Nilsen.

Infrastructure Flood Risk

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderThe Cost of Flood Insurance

An article in the New York Times entitled The Cost of Insuring Expensive Waterfront Homes Is About to Skyrocket states, “Federal officials say the goal is fairness — and also getting homeowners to understand the extent of the risk they face, and perhaps move to safer ground, reducing the human and financial toll of disasters.”

“Subsidized insurance has been critical for supporting coastal real estate markets,” said Benjamin Keys, a professor at the University of Pennsylvania’s Wharton School. Removing that subsidy, he said, is likely to affect where Americans build houses and how much people will pay for them. “It’s going to require a major rethink about coastal living.”

In 2019, FEMA said it would instead price flood insurance based on the particular risks facing each individual property, a change the agency called “Risk Rating 2.0.”

“With a rapidly escalating threat of natural disasters, Risk Rating 2.0 is a much needed and timely change,” said Laura Lightbody of Pew Charitable Trusts, which has pushed governments to better respond to climate threats. Higher insurance costs, she said, were “a reflection of our new, wet reality.”

“For the first time, our policyholder premiums will be based on their individual risk,” said David Maurstad, who runs the flood insurance program at FEMA. “We pledge to continue to evaluate and make adjustments where and when it’s warranted.”

But the growing threat of climate change may make that kind of intervention less successful, said Roy Wright, who ran the flood insurance program until 2018 and now runs the Insurance Institute for Business & Home Safety.

“We cannot hide the truth of this increasing risk,” Mr. Wright said. “We shouldn’t hide it. Tell people the truth.”

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderCoastal Real Estate Financial Crisis

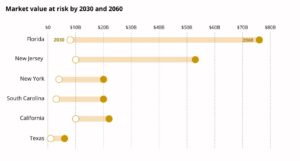
The rising sea level is putting a trillion dollars of real estate at high risk.

“The question is no longer if rising seas will erode coastal home values, but who will get stuck with the devalued assets when the markets turn,” reported Dee Gill.

“Alarmingly, more than half of that (at-risk property) exposure is estimated to lie outside FEMA flood zones. That means those properties are at higher risk of being underinsured, and, therefore, the loans attached to them are at higher risk of impairment, with increased risk for the value of the related CMBS (securities).” —CFTC

Market Value at Risk of Flooding

“Fannie and Freddie carry about $5.6 trillion in assets, mainly home mortgages and related securities. Ultimately, taxpayers backstop the payments on loans under the agencies’ control, UCLA’s Yu explains. Their regulator, the Federal Housing Finance Agency, issued a request for information in January, in part to assess flood risks. The entities require flood insurance that might mitigate their losses only on properties inside FEMA’s poorly drawn flood zones. Coverage limits imposed by NFIP — $250,000 for the structure and $100,000 for personal property — mean many coastal homes that have coverage are grossly underinsured.” — UCLA / Is the $1 Trillion Coastal Housing Market a Future Financial Crisis?

BlackRock, the G20-backed Financial Stability Board and the U.S. Commodity Futures Trading Commission are voicing concerns about unflagged flood risks squirreled away in mortgage-backed securities, bond markets and other real estate-backed investments. Common themes: The exact size of exposure is elusive but big; markets don’t currently price for it; these assets pose a threat to the stability of the global financial system.

More on Flood Insurance and Real Estate Risk

bookmark_borderNational Flood Insurance Program Increasing Rates

FEMA is updating the National Flood Insurance Program’s (NFIP) risk rating methodology through the implementation of a new pricing methodology called Risk Rating 2.0. The methodology leverages industry best practices and cutting-edge technology to enable FEMA to deliver rates that are actuarily sound, equitable, easier to understand and better reflect a property’s flood risk.

The Bradenton Herald reports, “More than a million Floridians will see their flood insurance premium rise next year, FEMA said Thursday.

The good news is, most will see increases of less than $120 a year. The bad news is that homeowners will likely see annual rate hikes like that for the foreseeable future.

The new strategy is meant to help pull the program out of its $20 billion debt and encourage people to live in safer, less flood-prone homes.

The new program will stop charging flood insurance premiums based solely on whether a home is within or outside of a flood zone and instead consider a range of factors like distance from the ocean, rainfall flooding and the cost to rebuild a home.

Starting April 2022, this pricing revamp will lead to higher prices for a majority of Florida’s 1.7 million policyholders — the most of any state — as well as a decrease for about 20% of policies, more than 340,000 policyholders.

“It allows us to set accurately sound rates and communicate flood risk better than we ever have before,” David Maurstad, senior executive of FEMA’s National Flood Insurance Program.

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderIncreasing Cost and Risk of Flood Insurance

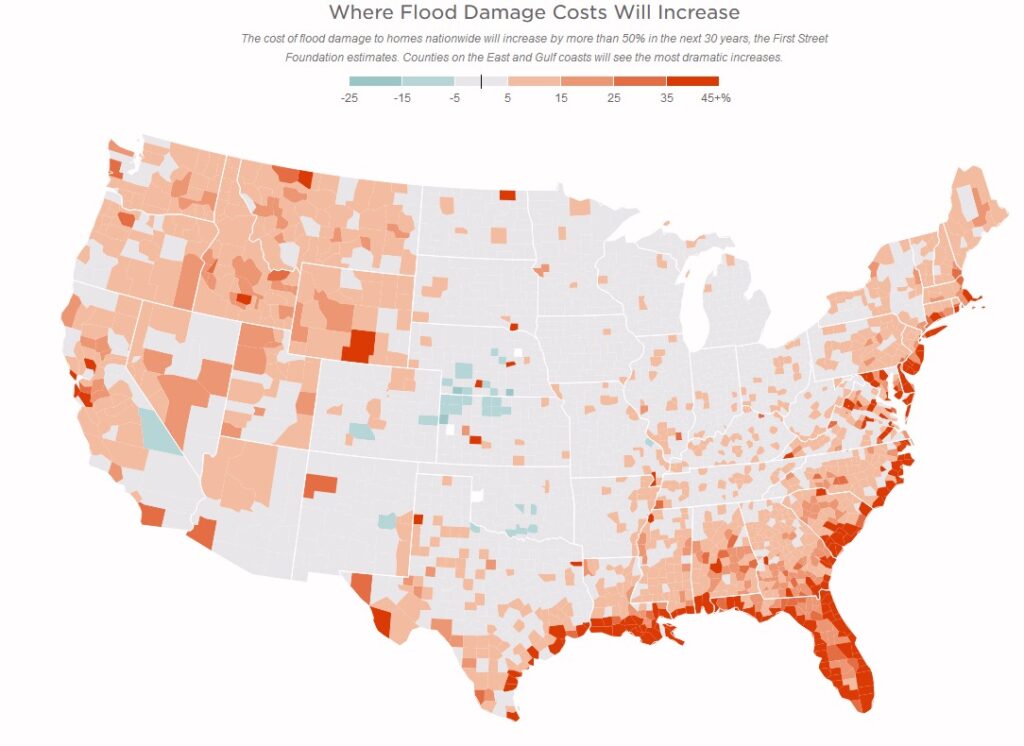
The cost of flood damage to homes nationwide will increase by more than 50% in the next 30 years, the First Street Foundation estimates.

Flood Insurance Forecast

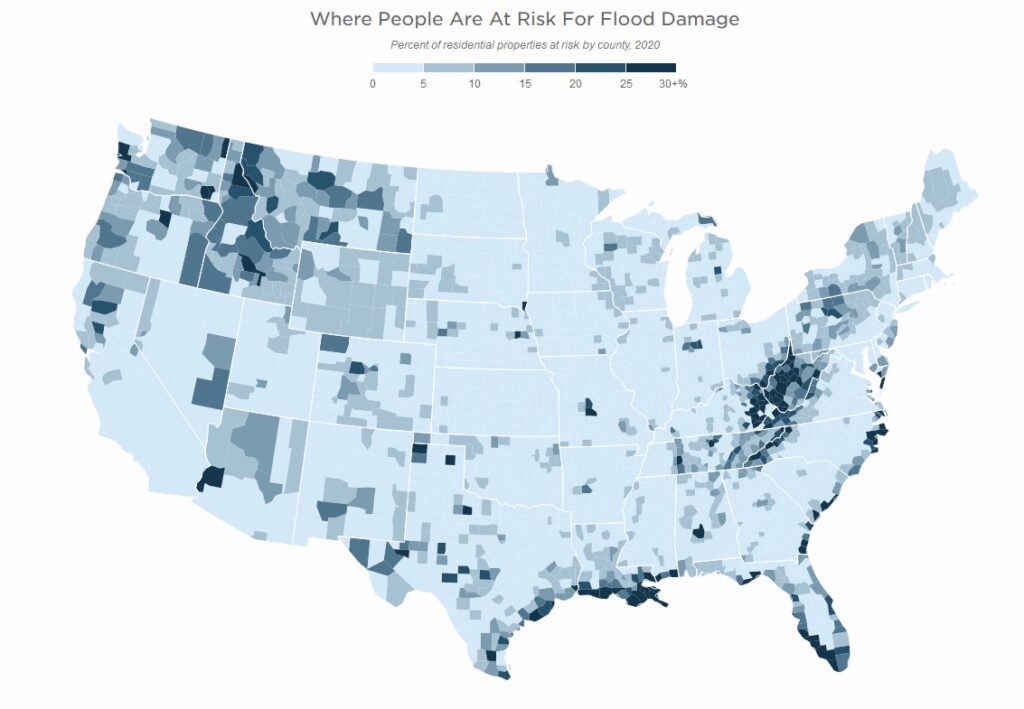
A report by NPR radio, A Looming Disaster: New Data Reveal Where Flood Damage Is An Existential Threat, found:
The federal government provides the vast majority of residential flood insurance in the U.S. Most policies are underpriced relative to the actual cost of flood damage.

The new data show that flood insurance rates would need to more than quadruple to keep up with the costs of climate-driven flooding. The Federal Emergency Management Agency is already preparing to raise insurance premiums in many places later this year in an effort to save the National Flood Insurance Program, which has accrued more than $36 billion in debt.

FEMA warns that the First Street Foundation’s analysis is only an estimate and that FEMA didn’t provide the research group with details about the new flood insurance pricing plan, known as Risk Rating 2.0.

“Any entity claiming that they can provide insight or comparison to the Risk Rating 2.0 initiative, including premium amounts, is misinformed and setting public expectations that are not based in fact,” writes David Maurstad, the senior executive of the National Flood Insurance Program, in an email to NPR. “While entities are free to suggest or estimate their opinion of what flood insurance premiums should be, they are offering exactly that — an opinion — and they do not have insight into the Risk Rating 2.0 initiative.”

For homeowners who are currently underpaying for flood insurance, FEMA says it plans to raise rates by up to 18% each year until the price is accurate, according to a January report by the Congressional Research Service. The agency will begin rolling out the new pricing in October.

As the cost of insurance goes up, many people who need flood insurance will likely be unable to afford it, leaving them to face lasting damage. Research has found that disasters can erode family stability and exacerbate mental and physical ailments when people don’t have the money they need to repair their homes.

“If you don’t have the finances you need to recover, then families have to make really difficult trade-offs, like maybe forgo spending on medical expenses because otherwise you don’t have a safe home,” says Carolyn Kousky, the executive director of the Wharton Risk Management and Decision Processes Center at the University of Pennsylvania.

Flood Damage Risk
Flood Damage Risk
Flood Damage Cost
Flood Damage Cost

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderIncreasing Cost of Flood Insurance

“Increased awareness of flood risk and rising future insurance costs impact perceptions of value, which will impact real estate markets,” said Matthew Eby, founder and executive director of First Street Foundation.

First Street Foundation published a report that concludes: “Rising sea levels and extreme weather could cause $20 billion of flood damage to at-risk U.S. homes this year, rising to $32 billion (per year) by 2051.”

First Street Foundation Flood Insurance Forecast

“Roughly 4.3 million homes – concentrated in Florida, California, South Carolina and Texas – have a substantial risk of sustaining economic damage from flooding this year, the report shows. The majority are not required by the U.S. government to have flood insurance. Were all of them to buy federal insurance, National Flood Insurance Program (NFIP) rates would need to increase 4.5 times to cover the risk, according to the report. The current average NFIP premium for these 4.3 million homes is $981,” reports Kate Duguid of Reuters.

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderFlood Factor: Estimate Flood Insurance Risk by Address

Flood Factor allows you to enter a property address to determine the future risk of severe flooding.

Access data calculated by a team of more than 80 world-renowned experts using decades of peer-reviewed research.

Over 142 million properties, neighborhoods, and cities analyzed
View any home’s Flood Factor and understand what can be done to protect it from flooding.

>FEMA Current Flood Maps by Address
Whether you are in a high risk zone or not, you may need flood insurance because most homeowners insurance doesn’t cover flood damage. If you live in an area with low or moderate flood risk, you are 5 times more likely to experience flood than a fire in your home over the next 30 years. For many, a National Flood Insurance Program’s flood insurance policy could cost less than $400 per year. Call your insurance agent today and protect what you’ve built.

More articles on Flood Insurance, Rising Sea Levels and Global Warming.

bookmark_borderDroughts and Rising Sea Levels

“There has been a 500% increase in the US drought area,” said Al Roker of the Today show while reporting on 2020 being tied for the hottest year.

The Washington Post reports, “Drought is the sleeper weather story you’ll hear more about in 2021.” [1}

“The impact of desertification is intensifying due to climate change, which is reducing the availability of freshwater, fertile soil, and forest and vegetation. As the degraded land loses value, investments in agriculture and rural development decline even more.” — Ban Ki-moonUnited Nations Secretary-General [2}

This doesn’t have to do with drought episodes. It has to do with areas prone to having droughts. As the area of land that is prone to flooding is increasing exponentially, so too is the land prone to severe, long term drought. We make it even worse by pumping ground water out for agriculture. This depletes the aquifers. The result is sinking land and rising sea levels. The depleted fresh water is then intruded by salt water. Salt water intrusion has a severe impact on the world food supply.

So, you have rising seas above and below the land. Compounding the problem — water expands when it gets warmer. About 1/3 of the rise in sea level is due to thermal expansion of water. [Volumetric Thermal Expansion] The warmer sea water also melts sea ice. The ocean doesn’t reflect the energy the way ice does. In fact just he opposite, the ocean absorbs the heat… making the water warmer… melting more sea ice…. and warming the planet. Which melts the land ice, which raises the sea level. A vicious feedback cycle of fresh water depletion and sea level rise has been created.

Climate change is making weather events more extreme and more frequent. More severe droughts, more severe floods, etc. Energy is being added to the system. “Climate change increases the odds of worsening drought in many parts of the United States and the world in the decades ahead. A changing climate can also alter atmospheric rivers (narrow streams of moisture transported in the atmosphere), which can especially disrupt precipitation patterns in the Western United States. Droughts can persist through a “positive feedback,” where very dry soils and diminished plant cover can further suppress rainfall in an already dry area.” [3]

“Risks from desertification are projected to increase due to climate change (high confidence). The combination of pressures coming from climate variability, anthropogenic climate change and desertification will contribute to poverty, food insecurity, and increased disease burden (high confidence).” [4]

1. Drought is the sleeper weather story you’ll hear more about in 2021. (The Washington Post)
2. DESERTIFICaTION (United Nations)
3. Drought and Climate Change (Center for Energy and Climate Solutions)
4. SPECIAL REPORT: Climate Change and Land Desertification (International Panel on Climate Change)