bookmark_borderGlobal Real Estate Climate Risk: A Multiplicative Vulnerability Ranking

by Daniel Brouse and Sidd Mukherjee

The Multiplicative Climate Risk Formula

The Multiplicative Climate Risk Formula is a real-estate climate-risk model designed to capture how multiple hazards and vulnerabilities can interact and compound rather than occur independently. The framework incorporates interconnected risks including sea-level rise, storm surge, extreme precipitation, flooding, hydroclimatic whiplash, wildfires, drought, extreme heat, hurricanes, landslides, avalanches, and other cascading hazards.

Rather than treating each hazard as an isolated threat, the model evaluates how hazard exposure, hazard coupling, structural vulnerability, insurance stress, and recovery deficits can multiply overall real-estate risk.

The central premise is simple:

Climate risk is not merely additive. When multiple vulnerabilities interact, their combined impact can be substantially greater than the sum of their individual effects.

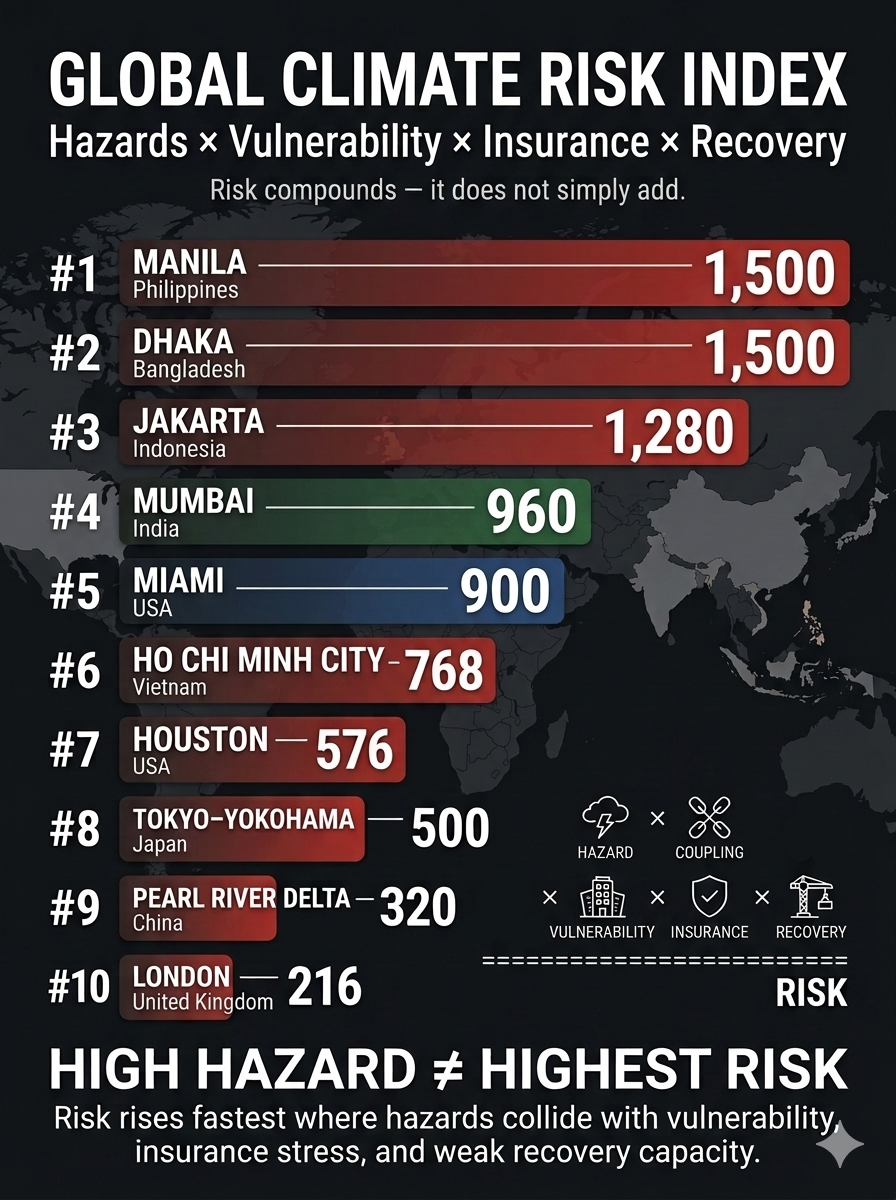
Applying the Multiplicative Climate Risk Formula on a global scale reveals that the greatest real-estate vulnerabilities are concentrated in major metropolitan and economic hubs where intense physical hazards intersect with structural fragility, insurance stress, and limited recovery capacity.

Unlike conventional hazard rankings, this framework recognizes that climate risk is not additive. A region can have relatively resilient buildings yet remain highly exposed because of insurance stress, infrastructure dependence, or coupled hazards. Conversely, a region with extreme physical exposure can rank lower when strong building standards, financial capacity, and rapid recovery systems substantially reduce vulnerability.

The global ranking applies the framework using a 1–5 scale, where 1 = Low and 5 = Extreme:

Hazard Exposure × Hazard Coupling × Vulnerability × Insurance Stress × Recovery Deficit = Multiplicative Real Estate Climate Risk

The resulting score is a comparative risk factor rather than a probability of loss or a forecast of future property values.


1. Manila & Central Luzon, Philippines

Hazard Exposure (5): Exceptional exposure to multiple severe Pacific typhoons, coastal storm surge, extreme rainfall, river flooding, and sea-level rise.

Hazard Coupling (5): Storm surge can coincide with torrential rainfall and river flooding, trapping inland water and producing prolonged flooding across low-lying urban districts.

Vulnerability (4): High population density, uneven construction quality, aging structures, and extensive informal development increase exposure to severe wind and flood damage.

Insurance Stress (3): Commercial insurance is more accessible for premium assets than for much of the broader property market, leaving substantial portions of residential and lower-value real estate underinsured.

Recovery Deficit (5): Severe recovery constraints can arise from infrastructure damage, disrupted electrical systems, engineering shortages, and delays in mobilizing reconstruction resources.

Total Multiplicative Risk: 5 × 5 × 4 × 3 × 5 = 1,500


2. Dhaka, Bangladesh

Hazard Exposure (4): Extreme exposure to tropical cyclones, riverine flooding, intense rainfall, extreme heat, and broader regional water stress.

Hazard Coupling (5): Extreme heat, heavy precipitation, drainage limitations, river flooding, and rapidly expanding urbanization can interact to amplify infrastructure and property losses.

Vulnerability (5): Large concentrations of densely developed, lower-quality and non-engineered structures create substantial exposure to flooding, subsidence, and extreme weather.

Insurance Stress (3): Formal property insurance penetration remains limited, leaving many losses concentrated on property owners and investors rather than broadly distributed through insurance markets.

Recovery Deficit (5): Limited fiscal capacity, infrastructure constraints, and dependence on external recovery financing can substantially extend post-disaster reconstruction.

Total Multiplicative Risk: 4 × 5 × 5 × 3 × 5 = 1,500


3. Greater Jakarta Area (Jabodetabek), Indonesia

Hazard Exposure (4): Severe exposure to chronic land subsidence, monsoonal flooding, extreme rainfall, coastal inundation, and sea-level rise.

Hazard Coupling (5): Land subsidence increases the effective impact of rising seas and high tides, while intense rainfall can overwhelm drainage systems and compound coastal flooding.

Vulnerability (4): Dense development, vulnerable transportation and utility infrastructure, and extensive below-grade systems increase exposure to flood-related disruption.

Insurance Stress (4): High climate-related losses and growing flood exposure can increase underwriting pressure, exclusions, deductibles, and affordability challenges.

Recovery Deficit (4): Major infrastructure investments are underway, but the scale of the metropolitan region and continuing subsidence create substantial long-term recovery and adaptation requirements.

Total Multiplicative Risk: 4 × 5 × 4 × 4 × 4 = 1,280


4. Mumbai Metropolitan Region, India

Hazard Exposure (4): High exposure to intense monsoon rainfall, coastal flooding, tropical cyclones, sea-level rise, and extreme heat.

Hazard Coupling (5): Extreme rainfall interacting with dense urbanization, inadequate drainage, coastal flooding, and heat stress can produce cascading infrastructure and real-estate disruption.

Vulnerability (4): Rapid development, extensive reclaimed land, aging buildings, and high-density urbanization increase exposure to flooding, structural deterioration, and infrastructure failure.

Insurance Stress (3): Climate-risk insurance penetration remains uneven, while rising exposure to flood and heat losses places increasing pressure on commercial and residential property coverage.

Recovery Deficit (4): Aging drainage systems, infrastructure deficits, population density, and high emergency-service demands can prolong recovery following major events.

Total Multiplicative Risk: 4 × 5 × 4 × 3 × 4 = 960


5. Miami & Southeast Florida, United States

Hazard Exposure (5): Exceptional exposure to major Atlantic hurricanes, storm surge, sea-level rise, tidal flooding, and recurrent coastal inundation.

Hazard Coupling (4): Storm surge, rainfall, rising seas, groundwater interactions, and porous limestone geology can combine to produce flooding beyond areas directly affected by rainfall.

Vulnerability (3): Modern buildings benefit from increasingly stringent wind standards, but extensive older and mid-tier residential and commercial properties remain vulnerable to wind, flood, and water intrusion.

Insurance Stress (5): Extreme insurance stress is driven by carrier withdrawals, rising premiums, higher deductibles, reinsurance costs, and growing exposure to catastrophic losses.

Recovery Deficit (3): High private wealth, federal disaster resources, and substantial construction capacity support recovery, although repeated disasters can strain public infrastructure and municipal finances.

Total Multiplicative Risk: 5 × 4 × 3 × 5 × 3 = 900


6. Ho Chi Minh City & Mekong Delta, Vietnam

Hazard Exposure (4): High exposure to chronic flooding, tropical storms, sea-level rise, extreme rainfall, and land subsidence.

Hazard Coupling (4): Tidal intrusion, river flooding, subsidence, upstream water management, and intense rainfall can combine to produce prolonged inundation.

Vulnerability (4): Large concentrations of low-rise residential, industrial, and manufacturing properties remain exposed to flooding and often lack comprehensive floodproofing or elevated mechanical systems.

Insurance Stress (3): Industrial assets may have access to international insurance capacity, but climate-risk pricing and coverage remain uneven across the broader real-estate market.

Recovery Deficit (4): Infrastructure investment continues to expand, but rapid urban and industrial growth can outpace drainage, flood-control, and adaptation capacity.

Total Multiplicative Risk: 4 × 4 × 4 × 3 × 4 = 768


7. Houston & Southeast Texas Gulf, United States

Hazard Exposure (4): High exposure to extreme rainfall, hurricanes, storm surge, coastal flooding, and occasional severe winter weather.

Hazard Coupling (4): Intense rainfall interacting with extensive impervious urban surfaces, bayous, drainage limitations, and coastal water levels can generate widespread property inundation.

Vulnerability (3): Large concentrations of slab-on-grade development and extensive construction across flood-prone areas increase exposure to flooding and infrastructure disruption.

Insurance Stress (4): Rising catastrophe losses, increasing deductibles, and elevated wind, hail, and flood costs place substantial financial risk on property owners.

Recovery Deficit (3): Strong corporate and regional financial capacity supports recovery, but large-scale flood-control, grid, and infrastructure projects can require years to complete.

Total Multiplicative Risk: 4 × 4 × 3 × 4 × 3 = 576


8. Tokyo-Yokohama Metropolitan Area, Japan

Hazard Exposure (5): Exceptional exposure to typhoons, storm surge, extreme rainfall, coastal flooding, and major seismic hazards.

Hazard Coupling (5): Typhoon rainfall can saturate soils and simultaneously trigger landslides, flooding, drainage failures, and infrastructure disruptions.

Vulnerability (2): Strong seismic engineering, rigorous building standards, sophisticated infrastructure, and extensive disaster-preparedness systems substantially reduce structural vulnerability.

Insurance Stress (5): Despite strong domestic resilience, the concentration of enormous asset values and catastrophe exposure creates substantial insurance and reinsurance accumulation risk.

Recovery Deficit (2): Strong national institutions, advanced emergency logistics, substantial financial capacity, and sophisticated construction and engineering systems support comparatively rapid recovery.

Total Multiplicative Risk: 5 × 5 × 2 × 5 × 2 = 500


9. Pearl River Delta — Hong Kong, Shenzhen & Guangzhou, China

Hazard Exposure (5): Exceptional exposure to typhoons, extreme precipitation, coastal flooding, sea-level rise, and heat.

Hazard Coupling (4): Extreme rainfall, storm surge, drainage constraints, underground infrastructure, and disruptions to industrial power and supply chains can interact to create cascading losses.

Vulnerability (2): Modern high-rise construction, extensive engineered infrastructure, and substantial flood and coastal defenses reduce the probability of widespread structural failure.

Insurance Stress (4): The extraordinary concentration of commercial and industrial assets creates significant aggregate-loss exposure for insurers and reinsurers during major catastrophes.

Recovery Deficit (2): Strong governmental capacity, extensive infrastructure, rapid mobilization, and substantial financial resources support comparatively rapid physical recovery.

Total Multiplicative Risk: 5 × 4 × 2 × 4 × 2 = 320


10. London & Thames Estuary, United Kingdom

Hazard Exposure (3): Moderate exposure to storm surge, coastal and river flooding, winter storms, extreme rainfall, and increasing heat stress.

Hazard Coupling (4): Sea-level rise increases pressure on tidal defenses, while a major surge combined with heavy rainfall could disrupt transportation, underground infrastructure, and commercial districts simultaneously.

Vulnerability (3): Extensive historic building stock, aging infrastructure, subsidence-sensitive soils, and limited cooling capacity increase exposure to certain climate hazards.

Insurance Stress (3): Insurance remains broadly accessible, but increasing exposure to flooding, heat, subsidence, and other climate-related losses may increase premiums and underwriting constraints.

Recovery Deficit (2): Strong institutions, substantial fiscal capacity, sophisticated infrastructure, and extensive engineering resources provide significant recovery advantages.

Total Multiplicative Risk: 3 × 4 × 3 × 3 × 2 = 216


Global Climate Risk Index Matrix

Because the framework is multiplicative rather than additive, high structural vulnerability and limited recovery capacity can propel a region above a wealthier, more technologically advanced city even when the latter faces greater absolute exposure to extreme weather.

RankGlobal RegionHazard ExposureHazard CouplingVulnerabilityInsurance StressRecovery DeficitMultiplicative Risk
1Manila & Central Luzon, Philippines554351,500
2Dhaka, Bangladesh455351,500
3Greater Jakarta, Indonesia454441,280
4Mumbai, India45434960
5Miami & Southeast Florida, USA54353900
6Ho Chi Minh City & Mekong Delta, Vietnam44434768
7Houston & Southeast Texas Gulf, USA44343576
8Tokyo-Yokohama, Japan55252500
9Pearl River Delta, China54242320
10London & Thames Estuary, UK34332216

What the Multiplicative Model Reveals

The ranking produces an important result: the most dangerous real-estate markets are not necessarily those with the most extreme individual hazards.

The multiplicative structure rewards resilience and penalizes systemic weakness. A highly exposed city with strong building standards, deep financial reserves, robust infrastructure, and rapid recovery capacity can therefore rank below a less technologically advanced city where multiple vulnerabilities interact.

This is the central insight of the model:

Climate risk is not simply where hazards are strongest. It is where hazards, vulnerability, insurance stress, and recovery deficits compound.

The greatest real-estate risks emerge when physical climate exposure becomes financially and institutionally amplified—turning a weather event into a prolonged property, insurance, infrastructure, and investment crisis.

bookmark_borderCoupled Climate Feedbacks and Cascading Real Estate Risk

by Daniel Brouse and Sidd Mukherjee

How Compound Flooding Is Reshaping Property Values, Insurance Availability, and Coastal Habitability

Climate change is creating a new class of real-estate risk in which the physical hazards of flooding increasingly interact with financial, insurance, infrastructure, and housing systems. Sea-level rise, heavier precipitation, and more intense or slower-moving hurricanes are not independent threats. They can interact to produce compound flooding, while the increasing frequency of damaging events can compress the time available for communities, property owners, insurers, and governments to recover.

The consequences extend far beyond the immediate cost of flood damage. As flood frequency increases, historical assumptions about property risk, insurance pricing, mortgage security, infrastructure design, and long-term property values become progressively less reliable. A property that was once considered a low-probability flood risk can become repeatedly exposed to flooding without the physical structure itself changing. As risk is repriced, insurance can become more expensive, less available, or unavailable altogether. Declining insurability can then reduce property values, constrain mortgage lending, discourage investment, weaken local tax bases, and reduce the resources available for infrastructure maintenance and adaptation.

This creates a coupled socioeconomic feedback loop:

Climate Warming → Hazard Intensification → Hazard Coupling → Compound Flooding → Damage and Losses → Insurance Stress → Property-Value Pressure → Reduced Investment → Infrastructure and Resilience Erosion → Greater Vulnerability → Greater Future Losses

A second feedback develops as recovery intervals contract:

Flood Frequency ↑ → Recovery Time Available ↓ → Unresolved Damage ↑ → Vulnerability ↑ → Subsequent Losses ↑

The resulting process is not simply an increase in flood risk. It is a potential transformation of real estate from a relatively stable store of household and institutional wealth into an increasingly climate-sensitive asset whose value, insurability, and financing depend upon the interaction of physical hazards and socioeconomic resilience.

The central argument of this paper is that real estate and insurance may become among the earliest and most visible indicators of cascading climate risk. When insurance becomes unaffordable or unavailable, property values weaken, lenders reassess collateral, investment retreats, and municipalities lose portions of their tax base, the effects of climate change have moved from the physical environment into the financial structure of communities.


1. Introduction: Climate Risk Is Becoming Real-Estate Risk

Climate change is often described in terms of rising temperatures, heavier rainfall, stronger storms, sea-level rise, and increasingly frequent flooding. Yet for households and communities, the most consequential effects may be transmitted through a different system:

Real Estate → Insurance → Mortgage Finance → Investment → Municipal Revenue → Infrastructure → Property Risk

A flood does not have to destroy a property to damage its economic value.

A property can lose value because:

  • flooding becomes more frequent;
  • flood insurance becomes more expensive;
  • insurance coverage becomes difficult to obtain;
  • insurers withdraw from the market;
  • lenders become more cautious;
  • infrastructure becomes less reliable;
  • buyers perceive increasing future risk;
  • investors demand higher returns for greater exposure;
  • municipal finances deteriorate;
  • repeated flooding reduces confidence in long-term habitability.

This changes the nature of climate risk.

The relevant question is no longer simply:

How much physical damage will the next flood cause?

It becomes:

What happens to the economic value and insurability of property when floods repeatedly occur before the community has fully recovered from previous events?

That is a fundamentally different risk problem.


2. Hurricane Harvey: The Beginning of the Feedback Chain

Hurricane Harvey provides a useful illustration of the physical mechanism underlying this emerging financial risk.

In August 2017, Harvey stalled over Texas and produced more than 40 inches of rainfall across a large area. At Nederland, Texas, 60.58 inches of rain was recorded, the largest single rainfall total associated with a tropical cyclone or its remnants in the United States. Damage was estimated at approximately $164 billion in 2026 dollars, with flooding responsible for most of the losses.

Harvey was also a compound-flood event.

Runoff from extreme rainfall moved toward the Gulf while storm surge pushed seawater inland. The elevated coastal water interfered with drainage, producing flooding through the interaction of rainfall runoff and storm surge.

The physical mechanism can therefore be expressed as:

Extreme Rainfall + Runoff + Storm Surge → Drainage Impairment → Compound Flooding

Climate change adds additional forcing:

Climate Warming → Heavier Rainfall + Higher Sea Level + More Intense/Slower Storms → Greater Compound Flood Risk

But the economic cascade begins after the water arrives:

Compound Flooding → Property Damage → Insurance Claims → Insurance Losses → Higher Insurance Costs and Reduced Availability

This is where physical climate risk begins to transform into financial risk.


3. The Three-Way Climate Pressure on Property

Three major mechanisms increasing compound flood risk along the U.S. Atlantic and Gulf coasts:

  1. More intense and slower-moving hurricanes
  2. Increased heavy precipitation as warmer air holds more water vapor
  3. Sea-level rise.

These mechanisms vary geographically.

Across the Gulf of Mexico and Florida, increased rainfall is projected to be the dominant driver in many locations. Across portions of the Southeast and Mid-Atlantic, changes in intense or slow-moving hurricanes become more important. Along the upper Mid-Atlantic and New England coasts, sea-level rise becomes increasingly dominant.

From a real-estate perspective, however, the distinction between the individual drivers may matter less than their combined effect.

The property does not experience three separate balance sheets.

It experiences one risk environment.

The resulting relationship is:

Sea-Level Rise + Extreme Rainfall + Storm Intensification → Compound Flood Risk → Property Risk

The financial system then responds:

Property Risk ↑ → Insurance Risk ↑ → Financing Risk ↑ → Property Value Pressure ↑

This is the beginning of the real-estate cascade.


4. Compound Flooding Creates Nonlinear Property Risk

The Harvey evidence demonstrates why conventional property-risk calculations can become inadequate.

A 2023 study found that approximately 19% of the flood area around Port Arthur, Texas, during Harvey resulted from compound flooding.

Under a scenario involving 0.57 meters of additional sea-level rise and 18% more rainfall, described as plausible around 2050, the compound-flooding area increased to 33%.

Under a scenario involving 1.6 meters of sea-level rise and 50% additional rainfall, described as plausible by 2100, compound flooding increased to 46%, while the number of structures affected was estimated to increase by approximately 23 times compared with 2017.

This is important for property markets because exposure can increase much faster than any single climate variable.

The relevant relationship is:

Climate Forcing ↑ → Hazard Interaction ↑ → Flood Exposure ↑↑ → Property Risk ↑↑

A property market that prices risk based primarily on historical flood frequency may therefore systematically underestimate future exposure.


5. The Return-Period Problem Becomes a Property-Valuation Problem

Real estate depends heavily on expectations about future risk.

A home buyer, mortgage lender, insurer, developer, or investor is effectively making a long-term assessment:

What is the probability that this property will suffer damaging losses during the period in which I own or finance it?

Historically rare floods can become much more frequent as the physical baseline changes.

Research found that human-driven sea-level rise has quadrupled the frequency of coastal sea-level extremes since 1900. At several locations, relative sea-level rise transformed a coastal flood that was a 100-year event in 1900 into an event occurring every five years or less frequently by 2005.

Recent examples illustrate the magnitude of this transformation.

A flood that historically occurred approximately once every ten years occurred:

Charleston → 17 times in 2025

Galveston → 9 times in 2024

Atlantic City → 10 times in 2024

Miami → 14 consecutive days in October 2025

Key West → 26 of 27 days in October 2025

For real estate, this represents a fundamental repricing problem.

A property does not need to be destroyed for its value proposition to change.

If the frequency of disruptive flooding changes from:

Rare → Occasional → Frequent → Persistent

then the economic characteristics of the property can change correspondingly.


6. The Insurance Market Is the First Financial Transmission Mechanism

Insurance is designed to transfer risk.

But insurance markets depend upon the ability to estimate and diversify that risk.

When climate change causes historical loss probabilities to change rapidly, insurers face a fundamental problem:

Historical Risk Models → Changing Climate Baseline → Increasing Loss Uncertainty

The response can take several forms:

Risk ↑ → Premiums ↑

Risk ↑ → Deductibles ↑

Risk ↑ → Coverage Restrictions ↑

Risk ↑ → Capacity ↓

Risk ↑ → Insurer Withdrawal ↑

For individual homeowners, the immediate consequence is affordability.

For the real-estate market, the deeper consequence is insurability.

Insurance availability is not simply another household expense.

It is part of the financial infrastructure supporting property ownership.


7. Insurance Availability Can Become a Property-Value Constraint

A property with affordable insurance can be financed, sold, and occupied relatively normally.

A property with extremely expensive insurance is economically less attractive.

A property that cannot obtain insurance may become difficult to finance.

The chain becomes:

Flood Risk ↑ → Insurance Cost ↑ → Ownership Cost ↑ → Buyer Demand ↓ → Property Value Pressure ↑

But the cascade can become stronger:

Flood Risk ↑ → Insurance Availability ↓ → Mortgage Financing Constraints ↑ → Buyer Pool ↓ → Property Liquidity ↓ → Property Values ↓

This produces a potentially powerful feedback.

As property values decline:

Property Values ↓ → Tax Base ↓ → Municipal Revenue ↓ → Infrastructure Investment Capacity ↓

If infrastructure resilience subsequently deteriorates:

Infrastructure Resilience ↓ → Flood Vulnerability ↑ → Property Risk ↑

The cycle closes:

Property Values ↓ → Tax Base ↓ → Infrastructure Capacity ↓ → Flood Risk ↑ → Insurance Stress ↑ → Property Values ↓

This is a coupled socioeconomic feedback loop.


8. The Insurance–Mortgage–Real Estate Feedback

Insurance and mortgage finance are closely connected.

A mortgage is a long-duration financial claim secured by an asset expected to retain sufficient value to protect the lender.

As flood risk increases, the financial system therefore confronts several interconnected questions:

Can the property be insured?

At what cost?

Will the property retain its value?

Will future buyers be able to obtain financing?

Will the property remain inhabitable?

The resulting feedback can be represented as:

Flood Risk ↑ → Insurance Risk ↑ → Insurance Cost/Availability Deteriorates → Mortgage Risk ↑ → Lending Constraints ↑ → Buyer Demand ↓ → Property Values ↓

The consequences can extend beyond individual homeowners.

Banks and mortgage investors may increasingly need to evaluate climate exposure at the portfolio level.

A geographic concentration of properties exposed to the same flood hazard creates correlated risk.

Unlike independent household losses, a major regional flood can affect thousands or millions of properties simultaneously.

That makes diversification more difficult.


9. Compound Flooding Creates Correlated Insurance Losses

This is one of the most important implications of compound hazards.

Insurance works most effectively when losses are sufficiently diversified.

But compound climate events can create geographically concentrated losses:

Extreme Rainfall + Storm Surge + High Sea Level → Regional Flooding → Thousands of Simultaneous Claims

A major hurricane can therefore produce simultaneous losses across:

  • homes
  • commercial properties
  • vehicles
  • infrastructure
  • businesses
  • utilities
  • municipal facilities

As compound events become more frequent, the financial system can face increasingly correlated losses.

That creates a feedback:

Compound Events ↑ → Correlated Claims ↑ → Insurer Losses ↑ → Pricing Pressure ↑ → Capacity Constraints ↑

This is fundamentally different from a world in which extreme floods are rare and geographically isolated.


10. Return-Period Compression Changes the Insurance Equation

Research examined extreme compound flooding defined as a one-in-100-year storm surge occurring simultaneously with a one-in-100-year rainfall event.

Historically, the combined event had a return period of approximately 200–500 years along the Gulf and southeastern Atlantic coasts and up to 1,000 years or more in parts of New England. Under an extreme warming scenario for 2100, the frequency increased by approximately 7–36 times in the South and 30–195 times farther north.

For insurance markets, the key issue is not the terminology “100-year event.”

The key issue is the frequency of claims-producing events.

If an event once expected to occur once in several centuries begins occurring multiple times within an insurance portfolio’s planning horizon, historical loss assumptions become increasingly unreliable.

Thus:

Return Interval ↓ → Claims Frequency ↑ → Expected Losses ↑ → Premium Pressure ↑ → Insurance Availability ↓


11. Stronger and Slower Hurricanes Increase Insurance Exposure

Our modeling projects the strongest hurricanes could become approximately 15–30% more intense while moving 20–30% more slowly along much of the U.S. coast. The combination increases the probability of simultaneous extreme rainfall and storm tide.

For property markets, this produces multiple simultaneous threats:

Intensity ↑ → Wind Damage ↑

Intensity ↑ → Storm Surge ↑

Intensity ↑ → Rainfall Potential ↑

Translation Speed ↓ → Rainfall Duration ↑

The combined result is:

Stronger + Slower Storms → Wind + Surge + Rainfall → Compound Property Losses

The insurance consequences can therefore be substantially larger than those associated with a simple increase in storm frequency.


12. Inland Property Markets Are Increasingly Exposed

Flood risk is not confined to oceanfront real estate.

Research finds substantial compound-flooding risks farther inland, including along Gulf Coast rivers where high streamflow can interact with storm surge. Increasing evidence suggests compound flooding can be greatest inland near the limit of tidal influence rather than directly at the coast.

A 2026 preprint found substantial increases in the probability of compound wind and precipitation extremes both within 100 kilometers of the coast and 100–500 kilometers inland under an extreme warming projection.

The significance for real estate is considerable.

Flood risk can migrate geographically.

Coastal Risk → Inland Watershed Risk → Inland Property Exposure

Communities that historically considered themselves outside the principal flood-risk zone can increasingly encounter climate-driven flooding.

That creates a major valuation problem because local markets may have little historical experience with these events.


13. Urban Flooding Creates a New Real-Estate Risk

Urban flooding introduces another dimension.

Extreme precipitation can overwhelm drainage systems even where properties are far from coastlines and major rivers.

The risk can become particularly acute in below-grade housing.

Extreme Rainfall → Stormwater System Overload → Rapid Urban Flooding → Basement/Below-Grade Exposure → Life-Safety Risk

This matters to real estate because conventional flood-risk perceptions often emphasize proximity to rivers, coastlines, or mapped floodplains.

But intense rainfall can create dangerous flooding through overwhelmed urban drainage systems.

As a result:

Flood Risk ≠ Coastal Risk Alone

Increasingly:

Flood Risk = Coastal + Riverine + Pluvial + Urban + Compound Risk

This expansion complicates property valuation, insurance underwriting, and municipal planning.


14. Recovery Deficit Is the Hidden Variable

The most important variable in cascading real-estate risk may not be flood magnitude.

It may be recovery time.

Consider:

Flood A → Damage → Partial Recovery → Flood B → Additional Damage → Partial Recovery → Flood C

If each event arrives before full recovery, unresolved losses accumulate.

A conceptual relationship is:

Resilience(t+1) = Resilience(t) + Recovery(t) − Damage(t)

When:

Recovery > Damage → Resilience Restored

But when:

Damage > Recovery → Resilience Declines

This creates a critical threshold:

Damage Rate > Recovery Rate

Once that condition persists, the system enters a recovery deficit.

For real estate, the consequences include:

Unrepaired Properties → Deferred Maintenance → Lower Property Quality → Lower Values → Reduced Investment → Greater Vulnerability

The property market therefore becomes a mechanism through which physical climate shocks can accumulate.


15. Repeated Flooding Can Produce a Negative Wealth Feedback

Homeownership represents a substantial component of household wealth.

Repeated climate-related losses can therefore create a feedback involving household balance sheets.

Flooding ↑ → Repair Costs ↑ → Insurance Costs ↑ → Property Values ↓ → Household Equity ↓ → Financial Resilience ↓

Lower household financial resilience can make recovery more difficult:

Financial Resilience ↓ → Delayed Repairs → Property Condition ↓ → Property Value ↓

The resulting loop becomes:

Flood Risk ↑ → Property Damage ↑ → Household Wealth ↓ → Recovery Capacity ↓ → Property Vulnerability ↑ → Future Losses ↑

This is particularly significant in communities where property represents a large share of household net worth.

Climate risk can therefore become wealth risk.


16. The Municipal Feedback Loop

The consequences do not stop at individual properties.

Municipal governments depend heavily on property values and economic activity.

A potential cascade is:

Flood Frequency ↑ → Property Damage ↑ → Property Values ↓ → Tax Base ↓ → Municipal Revenue ↓

The municipality then has fewer resources available for:

  • drainage improvements
  • flood defenses
  • road repair
  • stormwater systems
  • emergency response
  • public infrastructure maintenance
  • adaptation

This can produce:

Municipal Revenue ↓ → Infrastructure Investment ↓ → Resilience ↓ → Flood Damage ↑

The feedback closes:

Flood Risk ↑ → Property Values ↓ → Tax Base ↓ → Infrastructure Capacity ↓ → Flood Vulnerability ↑ → Property Risk ↑

At this point, the climate hazard has become embedded in the fiscal condition of the community.


17. The Insurance–Property–Infrastructure Feedback

The major feedback loops can be integrated into a single system:

Climate Warming → Hazard Intensification → Hazard Coupling → Compound Flooding → Physical Damage → Insurance Losses → Premiums/Availability Pressure → Property Value Decline → Investment Decline → Tax Base Erosion → Infrastructure Investment Decline → Resilience Erosion → Greater Flood Vulnerability → Greater Future Losses

This is the core cascading-risk mechanism.

The system is not linear.

Each component can alter the conditions affecting the next component.

The physical climate hazard creates the initial disturbance.

The socioeconomic system can then amplify the disturbance.


18. Insurance May Become an Early-Warning System for Climate Risk

Insurance markets have an unusual role in this transition.

They continuously translate physical risk into financial pricing.

Consequently, insurance-market changes may provide an early indicator of emerging real-estate instability.

The sequence may be:

Physical Risk ↑ → Actuarial Risk ↑ → Premiums ↑ → Deductibles ↑ → Coverage Restrictions ↑ → Insurer Withdrawal ↑

These signals can appear before large-scale property abandonment.

A community may therefore be approaching a real-estate resilience threshold even when most houses remain physically intact.

The early warning may instead appear as:

Insurance Availability ↓

Insurance Affordability ↓

Mortgage Availability ↓

Property Transactions ↓

Investment ↓

Property Values ↓

This suggests that insurance markets should be viewed not merely as financial institutions absorbing climate losses, but as risk sensors embedded within the real-estate system.


19. The Property-Value Feedback Can Accelerate

Once buyers begin incorporating future flood risk into property decisions, market expectations can change.

The feedback can become:

Flood Frequency ↑ → Risk Perception ↑ → Buyer Demand ↓ → Property Values ↓

Lower values can then produce additional effects:

Property Values ↓ → Equity ↓ → Investment ↓ → Maintenance ↓ → Vulnerability ↑

And:

Property Values ↓ → Tax Base ↓ → Public Infrastructure Investment ↓ → Vulnerability ↑

And:

Flood Risk ↑ → Insurance Costs ↑ → Total Cost of Ownership ↑ → Buyer Demand ↓ → Property Values ↓

The system therefore contains multiple reinforcing loops operating simultaneously.

This is what distinguishes a coupled-feedback system from a simple hazard-impact model.


20. The Sandy Example: An Accelerating Financial Risk Clock

Research found that a Sandy-like event in New York City, estimated at approximately once every 150 years in the current climate, could become approximately a once-in-65-year event by 2050 and once-in-30-year event by 2100 under the emissions scenario studied.

From a real-estate perspective, the significance is not simply that the probability of flooding increases.

The economic life of a mortgage, insurance policy, or property investment may span decades.

A hazard that occurs once every 150 years has a very different economic significance from one occurring once every 30 years.

Thus:

Return Interval ↓ → Probability of Loss During Ownership ↑ → Insurance Risk ↑ → Mortgage Risk ↑ → Property Risk ↑

The longer the investment horizon, the more consequential the changing hazard frequency becomes.


21. Sea-Level Rise Creates a Persistent Baseline Shift

Sea-level rise differs from many episodic hazards because it permanently alters the starting point from which future storms occur.

A higher ocean means:

Higher Baseline Water Level → Greater Storm-Surge Reach → Greater Flood Exposure

And:

Sea-Level Rise → Less Drainage Capacity → Greater Interaction Between Runoff and Surge

This means that even if a future storm were identical to a historical storm, its consequences could be different because it would occur against a changed physical baseline.

For property markets:

Sea-Level Rise → Persistent Risk Increase → Long-Term Property Exposure ↑

This is particularly important for real estate because buildings and infrastructure have long lifetimes.


22. The Coastal Property Paradox

Coastal property can remain economically attractive even while its physical risk is increasing.

That creates a potential divergence:

Amenity Value ↑

while:

Climate Risk ↑

For a period, rising demand may conceal increasing physical risk.

But eventually the financial system may begin incorporating the changing risk more aggressively.

The transition can be:

Physical Risk ↑ → Insurance Cost ↑ → Ownership Cost ↑ → Market Awareness ↑ → Buyer Demand ↓ → Property Values ↓

The result may be a delayed repricing.

Real estate markets do not necessarily respond immediately to slowly accumulating physical risk.

Insurance markets, however, may respond sooner because they must continually price expected losses.

This creates the possibility that:

Insurance repricing precedes real-estate repricing.


23. When Insurance Becomes Unaffordable, the Market Changes

Insurance affordability is particularly important because homeowners do not experience insurance as an abstract actuarial variable.

They experience it as part of the cost of owning a property.

The relevant relationship is:

Mortgage + Property Tax + Insurance + Maintenance + Expected Climate Losses = Cost of Ownership

If insurance premiums rise dramatically:

Insurance Cost ↑ → Total Cost of Ownership ↑

The property must either:

Price ↓

or:

Buyer Demand ↓

or both.

If insurance becomes unavailable:

Insurance Availability ↓ → Financing Constraints ↑ → Buyer Pool ↓ → Market Liquidity ↓

The property may remain physically valuable, but its economic utility as a financed asset declines.


24. From Insurability to Habitability

Insurance is not the only threshold.

Eventually, repeated flooding can affect whether a community remains economically and physically viable.

At the most susceptible U.S. sites, the odds of a one-in-50-year coastal flood could approximately double every five years under continuing sea-level rise. It also notes that many U.S. coastal engineering systems were designed around return periods of roughly 50–100 years.

As historically rare floods become increasingly frequent, the question changes.

It is no longer:

Can we recover from a flood?

It becomes:

Can we maintain a functioning community between floods?

That is the transition from flood risk to habitability risk.


25. The Real-Estate Resilience Threshold

A useful conceptual threshold is:

Insurance Cost + Expected Flood Losses + Infrastructure Costs > Property’s Economic Value Proposition

When this condition becomes persistent, the property may remain physically habitable while becoming economically unattractive.

A second threshold occurs when:

Damage Rate > Recovery Rate

At that point, the property or community cannot fully restore itself between successive events.

A third threshold may emerge when:

Protection Cost > Property Value / Tax Base / Available Capital

At that point, continued protection may become economically difficult.

These thresholds can interact:

Flood Risk ↑ → Insurance Cost ↑ → Property Value ↓ → Tax Base ↓ → Protection Capacity ↓ → Flood Risk ↑

This is a cascading threshold system.


26. From Property Decline to Retreat

The ultimate consequence need not be sudden abandonment.

A more realistic process may occur gradually:

Flood Frequency ↑ → Insurance Stress ↑ → Property Values Stagnate → Investment Declines → Maintenance Declines → Infrastructure Deteriorates → Insurance Availability Declines Further → Property Values Fall → Population Outmigration ↑

Eventually:

Population Decline → Tax Base Decline → Infrastructure Capacity Decline → Resilience Decline

At some point, adaptation may become economically preferable to continued protection.

This can lead to:

Protection → Adaptation → Managed Retreat → Abandonment

The timing and geographic extent of such transitions will vary considerably by location.

The key point is that the transition can be driven not by a single catastrophic flood but by cumulative climate risk interacting with economic feedbacks.


27. The Complete Coupled-Feedback / Cascading Real-Estate Framework

The emerging system can be represented as:

Warming → Hazard Intensification → Hazard Coupling → Compound Flooding → Damage → Insurance Losses → Insurance Cost/Availability Pressure → Property-Value Pressure → Reduced Investment → Tax-Base Erosion → Infrastructure Resilience Decline → Greater Vulnerability → Greater Future Losses

A second loop operates through recovery:

Flood Frequency ↑ → Recovery Window ↓ → Unresolved Damage ↑ → Resilience ↓ → Vulnerability ↑ → Subsequent Damage ↑ → Recovery Window ↓

A third loop operates through insurance:

Flood Risk ↑ → Expected Losses ↑ → Premiums ↑ / Coverage ↓ → Cost of Ownership ↑ → Buyer Demand ↓ → Property Values ↓ → Insurer/Lender Risk ↑ → Insurance and Financing Constraints ↑

A fourth operates through municipal finance:

Property Values ↓ → Tax Base ↓ → Municipal Revenue ↓ → Infrastructure Investment ↓ → Resilience ↓ → Flood Risk ↑ → Property Values ↓

These feedbacks are interconnected.

Together they create:

Climate Forcing → Physical Hazard Coupling → Financial Amplification → Resilience Erosion → Cascading Real-Estate Risk


28. A New Definition of Climate-Exposed Property Risk

Traditional real-estate risk often focuses on:

Location + Structure + Historical Flood Zone

A future-oriented model must incorporate additional variables:

Flood Frequency

Compound-Hazard Probability

Sea-Level Rise

Extreme Precipitation

Storm Intensity and Translation Speed

Insurance Availability

Insurance Affordability

Mortgage Availability

Infrastructure Resilience

Recovery Capacity

Property-Value Trajectory

Municipal Fiscal Capacity

The risk of a property is therefore not simply its probability of flooding.

A more comprehensive conceptual formulation is:

Real-Estate Climate Risk ∝ Hazard Exposure × Hazard Coupling × Vulnerability × Insurance Stress × Recovery Deficit

Again, this is a conceptual framework rather than a validated predictive equation.

Its purpose is to recognize that physical exposure and financial vulnerability can amplify one another.


29. Why Historical Property Valuation Models May Become Increasingly Unreliable

A property valuation based heavily on historical comparable sales assumes that the past provides meaningful information about future risk.

But if the climate baseline is changing:

Historical Flood Frequency ≠ Future Flood Frequency

And therefore:

Historical Property Risk ≠ Future Property Risk

This creates the potential for a valuation lag.

A property may continue selling at prices based on historical assumptions even as:

Flood Frequency ↑

Insurance Cost ↑

Infrastructure Stress ↑

Future Risk ↑

The market can therefore experience a delayed repricing once these factors become visible to buyers, lenders, and insurers.

The longer the delay, the greater the possibility of a discontinuous adjustment.


30. The Central Role of Insurance in Price Discovery

Insurance markets can force climate risk into property economics because they must continually reassess expected losses.

This creates a potentially important sequence:

Physical Climate Change → Insurance Repricing → Mortgage Reassessment → Buyer Reassessment → Property Repricing

In this framework, insurance functions as an intermediary between the climate system and the real-estate market.

This makes insurance availability and affordability among the most important indicators to monitor.

A deteriorating insurance market can signal that the physical risk has become financially material even before large-scale property abandonment occurs.


31. The Emerging Climate-Real-Estate Feedback

The broader system can therefore be summarized as:

Physical System

Warming → Sea-Level Rise + Heavier Rainfall + Stronger/Slower Storms → Compound Flooding

Insurance System

Compound Flooding → Claims → Losses → Premium Increases + Coverage Restrictions + Reduced Capacity

Real-Estate System

Insurance Stress → Cost of Ownership ↑ → Buyer Demand ↓ → Property Values ↓

Financial System

Property Values ↓ → Mortgage Risk ↑ → Lending Constraints ↑ → Investment ↓

Municipal System

Property Values ↓ → Tax Base ↓ → Infrastructure Investment ↓

Resilience System

Infrastructure Investment ↓ → Flood Vulnerability ↑

The loop closes:

Flood Vulnerability ↑ → Compound Flood Risk ↑

This is a coupled climate-financial feedback loop.


32. The Difference Between a Disaster and a Cascading Risk

A conventional disaster model begins and ends with the event:

Storm → Flood → Damage → Recovery

The cascading-risk model is different:

Storm → Compound Flood → Damage → Insurance Loss → Financial Stress → Property-Value Decline → Tax-Base Erosion → Infrastructure Stress → Reduced Resilience → Greater Vulnerability → Next Flood → Greater Damage

The disaster is therefore no longer an isolated event.

It becomes a state-changing event.

Each major flood can alter the economic and physical conditions under which the next flood occurs.

This makes the system path dependent.


33. The Most Important Variable May Be the Time Between Disasters

“The Floods of the Future Won’t Come One at a Time”—captures the central problem.

The issue is not simply that flood events become more severe.

It is that the interval between them can become shorter.

The resulting relationship is:

Flood Frequency ↑ + Recovery Time Constant → Recovery Window ↓

Then:

Recovery Window ↓ + Damage Per Event ↑ → Recovery Deficit ↑

Then:

Recovery Deficit ↑ → Property Condition ↓ + Infrastructure Condition ↓ + Financial Resilience ↓

Then:

Resilience ↓ → Consequences of the Next Flood ↑

This is the mechanism through which frequency becomes amplification.


34. From Compound Flooding to Cascading Real-Estate Instability

The complete process can now be expressed in one horizontal chain:

Warming → Hazard Intensification → Hazard Coupling → Compound Flooding → More Frequent Losses → Insurance Stress → Higher Cost of Ownership → Reduced Buyer Demand → Property-Value Decline → Mortgage and Investment Stress → Tax-Base Erosion → Infrastructure Resilience Decline → Recovery Deficit → Greater Future Flood Vulnerability → Cascading Real-Estate Instability

This is the central thesis of the paper.

The most important climate consequence for real estate may not be the destruction of individual properties.

It may be the progressive deterioration of the economic conditions that make those properties insurable, financeable, maintainable, and desirable.


35. Conclusion: When Climate Risk Becomes Property Risk

The emerging flood threat is fundamentally different from the historical model of isolated disasters.

Climate change is increasing the potential for:

Sea-Level Rise + Heavy Rainfall + Stronger/Slower Hurricanes → Compound Flooding

At the same time:

Flood Frequency ↑ → Recovery Windows ↓

These physical changes increasingly interact with:

Insurance

Mortgage Finance

Property Markets

Municipal Finance

Infrastructure

Household Wealth

The resulting system can develop reinforcing feedbacks:

Flood Risk ↑ → Insurance Stress ↑ → Property Values ↓ → Investment ↓ → Infrastructure Resilience ↓ → Flood Vulnerability ↑

and:

Flood Frequency ↑ → Recovery Deficit ↑ → Resilience ↓ → Future Losses ↑

These feedbacks create the possibility of nonlinear and cascading consequences.

The immediate manifestation may be rising insurance premiums, shrinking insurance availability, higher deductibles, declining property demand, or increasing difficulty obtaining mortgages.

The next stage may be declining property values and reduced investment.

The subsequent stage may involve weakening municipal tax bases, deteriorating infrastructure, and increasing difficulty financing adaptation.

The final stage in the most vulnerable locations could involve managed retreat, population displacement, and abandonment.

The critical transition is therefore:

Climate Risk → Insurance Risk → Real-Estate Risk → Financial Risk → Municipal Risk → Resilience Risk → Cascading Systemic Risk

This suggests that real estate and insurance markets should be treated as critical components of the climate system’s socioeconomic response.

Insurance is not merely a mechanism for paying claims after a disaster. It is a mechanism for translating physical risk into financial information.

Real estate is not merely a collection of buildings. It is a store of household wealth, collateral for debt, a source of municipal revenue, and the foundation of local economic activity.

When the physical climate changes, these interconnected systems change with it.

The most consequential question is therefore not simply:

Will a property flood?

It is:

Will the property remain insurable, financeable, valuable, maintainable, and economically viable as the probability of flooding changes?

That is the central real-estate question of the emerging climate era.

The ultimate risk is not a single catastrophic flood.

It is the transition from:

Rare Disaster → Recurrent Hazard → Compound Flooding → Insurance Stress → Property Repricing → Investment Retreat → Resilience Erosion → Cascading Real-Estate Risk

When floods begin arriving faster than properties, infrastructure, insurers, lenders, governments, and communities can adapt, the flood itself becomes only the initiating event.

The deeper crisis is the progressive erosion of the economic and institutional systems that allow a place to remain habitable and investable.

In that sense, the future of climate-exposed real estate may be determined less by whether a property floods once than by whether the surrounding system can continue to recover between floods.

The flood becomes the trigger.
Insurance becomes the transmission mechanism.
Real estate becomes the financial amplifier.
Resilience becomes the limiting factor.
And cascading risk becomes the ultimate consequence.
bookmark_borderHigh-Risk U.S. Real Estate Regions Under the Multiplicative Climate Risk Framework

by Daniel Brouse and Sidd Mukherjee

The Multiplicative Climate Risk Formula

The Multiplicative Climate Risk Formula is a real-estate climate-risk model designed to capture how multiple hazards and vulnerabilities can interact and compound rather than occur independently. The framework incorporates interconnected risks including sea-level rise, storm surge, extreme precipitation, flooding, hydroclimatic whiplash, wildfires, drought, extreme heat, hurricanes, landslides, avalanches, and other cascading hazards.

Rather than treating each hazard as an isolated threat, the model evaluates how hazard exposure, hazard coupling, structural vulnerability, insurance stress, and recovery deficits can multiply overall real-estate risk.

The central premise is simple:

Climate risk is not merely additive. When multiple vulnerabilities interact, their combined impact can be substantially greater than the sum of their individual effects.

Applying the Multiplicative Climate Risk Formula reveals an important characteristic of climate-driven real-estate risk: the highest-risk regions are not necessarily those experiencing the most dramatic individual weather events. The greatest systemic risk emerges where multiple risk dimensions interact and amplify one another.

A region can experience severe hurricanes, wildfires, flooding, or extreme heat without necessarily experiencing the highest level of cascading real-estate risk. The critical question is what happens when physical hazards interact with high exposure, hazard coupling, structural vulnerability, insurance-market stress, and limited recovery capacity.

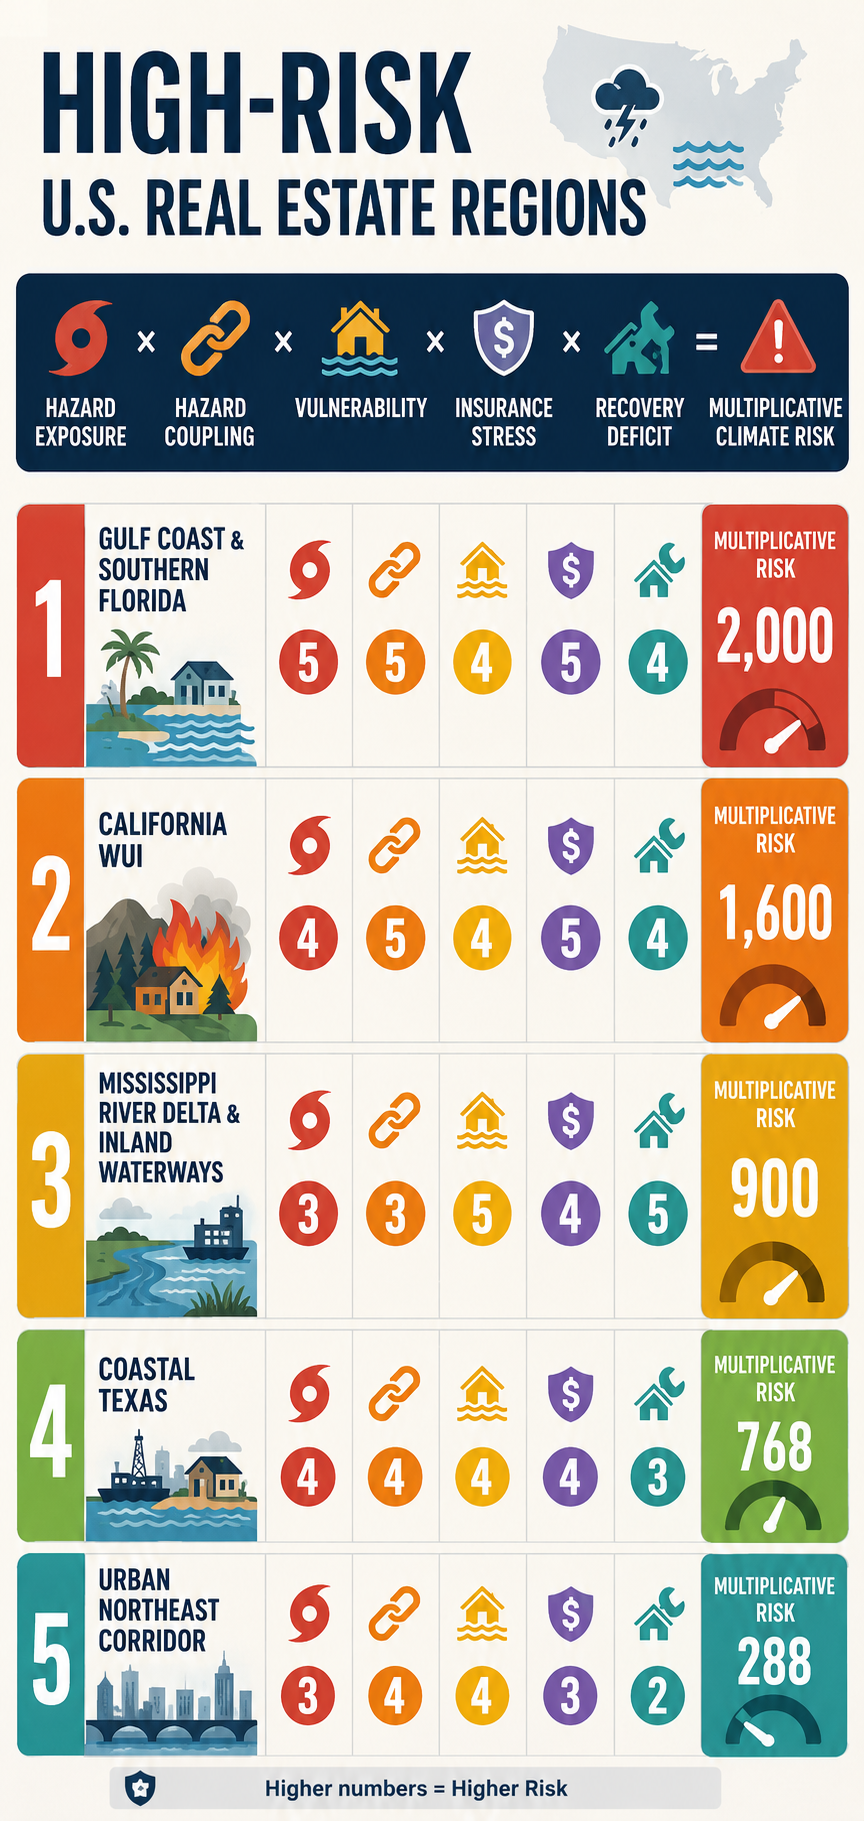
The framework therefore evaluates five interacting dimensions:

Hazard Exposure × Hazard Coupling × Vulnerability × Insurance Stress × Recovery Deficit = Multiplicative Climate Risk

Each component is scored from 1 to 5, where:

1 = Low Risk

2 = Moderate-Low Risk

3 = Moderate Risk

4 = High Risk

5 = Extreme Risk

The resulting score is not a probability of loss or a conventional actuarial measure. It is a comparative systems-risk index designed to identify locations where multiple weaknesses can reinforce one another.

This distinction is critical.

A region with a score of 5 in one category but relatively low scores elsewhere may be less systemically exposed than a region scoring 4 or 5 across nearly every category.

The multiplicative framework captures that interaction:

Physical Hazard ↑ + Coupling ↑ + Vulnerability ↑ + Insurance Stress ↑ + Recovery Capacity ↓ → Cascading Real-Estate Risk ↑↑

The following ranking represents a comparative assessment of major U.S. real-estate risk regions, incorporating physical hazards and the increasingly important financial and institutional dimensions of climate exposure.


1. Gulf Coast & Southern Florida

The Compound-Compounding Zone

Hazard Exposure — 5/5

The Gulf Coast and southern Florida face some of the country’s most concentrated combinations of acute and chronic climate hazards.

These include:

Major Hurricanes + Storm Surge + Extreme Rainfall + Sea-Level Rise + Coastal Flooding + Extreme Heat

The region’s vulnerability is not based on any single hazard. It is the convergence of multiple hazards affecting a densely developed coastal real-estate market.

Hazard Coupling — 5/5

The defining characteristic is the interaction among hazards.

A tropical cyclone can simultaneously produce:

Storm Surge + Extreme Rainfall + River Flooding + High Winds

Sea-level rise increases the baseline upon which storm surge occurs, while extreme rainfall can overwhelm drainage systems at the same time that elevated coastal water levels restrict drainage.

The resulting process is:

Hurricane → Storm Surge + Extreme Rainfall → Drainage Impairment → Compound Flooding → Widespread Property Exposure

This is precisely the type of coupled hazard that can produce disproportionate economic consequences.

Vulnerability — 4/5

The region contains enormous quantities of residential, condominium, commercial, and infrastructure assets exposed to coastal and flood hazards.

Building age and construction standards vary substantially. Newer construction and mitigation measures can reduce vulnerability, while older structures and properties with inadequate flood, wind, or drainage protection remain substantially more exposed.

The critical issue is therefore not simply the age of the housing stock, but the mismatch between:

Long-Lived Real Estate Assets → Rapidly Changing Climate Risk

Insurance Stress — 5/5

Insurance is one of the most consequential real-estate constraints in the region.

The combination of hurricanes, storm surge, flooding, wind damage, sea-level rise, and repeated catastrophe losses places substantial pressure on insurance availability and affordability.

The resulting feedback is:

Climate Risk ↑ → Expected Losses ↑ → Insurance Premiums ↑ → Deductibles and Coverage Restrictions ↑ → Insurance Availability ↓

For homeowners, insurance costs directly increase the cost of ownership.

For commercial real estate, rising insurance expenses can reduce net operating income and asset values by increasing operating costs. The effect is particularly significant for multifamily, hospitality, retail, and other income-producing properties.

The insurance problem therefore extends beyond individual policies.

It becomes a real-estate valuation problem:

Insurance Cost ↑ → Cost of Ownership ↑ → Buyer Demand ↓ → Property Values ↓

Recovery Deficit — 4/5

The region’s substantial public and private capital resources provide recovery capacity, but the scale of the infrastructure challenge is enormous.

Long-term pressures include:

Flood-Control Systems + Pump Stations + Drainage Networks + Seawalls + Roads + Bridges + Utilities + Wastewater Systems

The concern is not whether these systems can recover from one disaster.

The concern is whether:

Repeated Damage > Available Recovery and Adaptation Capacity

If the frequency of major events increases faster than infrastructure can be repaired, upgraded, or relocated, a recovery deficit can develop.

Multiplicative Risk

5 × 5 × 4 × 5 × 4 = 2,000

Total Risk Factor: 2,000

The Gulf Coast and southern Florida therefore represent the most pronounced example of compound climate-real-estate risk in the framework.


2. Central & Southern California Wildland-Urban Interface

The Fire–Flood–Insurance Cascade Zone

Hazard Exposure — 4/5

The Central and Southern California WUI faces a combination of:

Wildfire + Extreme Heat + Drought + Water Stress + Extreme Rainfall

The exposure is particularly consequential because enormous quantities of residential real estate have been constructed adjacent to or within wildfire-prone landscapes.

Hazard Coupling — 5/5

The defining feedback is:

Drought → Vegetation Stress → Wildfire → Vegetation Loss → Soil Destabilization → Extreme Rainfall → Mudslides and Debris Flows

This is a classic sequential compound-risk mechanism.

Wildfire does not simply produce immediate property losses.

It can alter the landscape in ways that increase the consequences of subsequent precipitation events.

The result is:

Wildfire → Landscape Transformation → Increased Post-Fire Flood/Mudslide Risk

This creates a risk cascade extending beyond the original fire.

Vulnerability — 4/5

Residential development in steep terrain, narrow canyons, and areas with constrained evacuation routes can create substantial exposure.

Vulnerability also depends on construction standards, defensible space, vegetation management, access routes, and the ability of communities to recover rapidly after catastrophic fires.

Insurance Stress — 5/5

California represents one of the clearest examples of insurance-market stress becoming a real-estate problem.

The combination of catastrophic wildfire exposure, rapidly changing risk conditions, and repeated losses creates pressure on insurers to increase premiums, restrict coverage, reduce exposure, or withdraw from high-risk markets.

When private insurance becomes unavailable or unaffordable, property owners may be forced into residual or state-backed insurance mechanisms.

The resulting feedback is:

Wildfire Risk ↑ → Insurance Losses ↑ → Premiums ↑ → Coverage Restrictions ↑ → Private Insurance Availability ↓ → Residual-Market Dependence ↑

This creates a second real-estate feedback:

Insurance Availability ↓ → Financing Constraints ↑ → Buyer Pool ↓ → Property Liquidity ↓ → Property Values ↓

The insurance problem can therefore become a leading indicator of broader real-estate repricing.

Recovery Deficit — 4/5

Large wildfire events can produce extensive reconstruction requirements simultaneously.

The recovery system must contend with:

Destroyed Housing + Infrastructure Damage + Debris Removal + Labor Requirements + Construction Demand + Supply Constraints

The resulting competition for labor and materials can extend rebuilding timelines and increase reconstruction costs.

The longer recovery takes, the greater the potential for:

Recovery Delay → Business Interruption → Household Displacement → Reduced Local Economic Activity → Reduced Community Resilience

Multiplicative Risk

4 × 5 × 4 × 5 × 4 = 1,600

Total Risk Factor: 1,600

The California WUI therefore represents a particularly important example of insurance availability becoming a leading indicator of real-estate climate risk.


3. Coastal Texas

The Industrial and Commercial Risk Hub

Hazard Exposure — 4/5

Coastal Texas faces:

Hurricanes + Storm Surge + Extreme Rainfall + Flash Flooding + Extreme Heat + Grid Stress

The region’s importance is amplified by its enormous concentration of industrial, commercial, petrochemical, port, logistics, and residential assets.

Hazard Coupling — 4/5

The physical hazards can interact through several pathways.

For example:

Extreme Heat → Electricity Demand ↑ → Grid Stress ↑ → Power Disruption → Cooling/Industrial/Commercial Disruption

At the same time:

Hurricane → Wind + Surge + Rainfall → Flooding + Power Loss → Business Interruption

And:

Flooding + Heat + Power Loss → Mold + Water Damage + Equipment Failure + Building-System Damage

This produces a multi-system cascade rather than a single flood loss.

Vulnerability — 4/5

Coastal Texas contains enormous concentrations of development and infrastructure in flood-prone and low-lying areas.

Impervious surfaces can increase runoff, while dense development can make drainage problems more consequential.

The concentration of industrial and commercial assets also creates correlated economic risk.

A single major event can affect multiple businesses, transportation systems, suppliers, utilities, and customers simultaneously.

Insurance Stress — 4/5

Insurance costs and coverage limitations are becoming an increasingly important component of real-estate risk.

Wind, hail, hurricane, flood, and business-interruption exposures can produce substantial premiums and deductibles.

As insurers reassess catastrophe exposure, property owners can increasingly absorb a greater portion of the risk through:

Higher Deductibles + Coverage Restrictions + Increased Premiums + Greater Self-Insurance

For commercial real estate, increasing insurance expenses directly affect:

Operating Expenses ↑ → NOI ↓ → Capitalization Value ↓

This provides a direct financial transmission mechanism between climate risk and commercial property valuation.

Recovery Deficit — 3/5

Coastal Texas possesses substantial private capital and strong economic capacity, which can accelerate reconstruction.

However, public infrastructure and regional systems can take much longer to repair.

The result is a two-speed recovery:

Private Capital → Rapid Property Recovery

while:

Public Infrastructure → Slower System Recovery

This creates a temporary resilience gap.

Multiplicative Risk

4 × 4 × 4 × 4 × 3 = 768

Total Risk Factor: 768

Coastal Texas represents an important example of how high-value commercial real estate can convert physical climate exposure into large-scale correlated financial losses.


4. Mississippi River Delta & Inland Waterways

The Structural-Aging and Recovery-Deficit Zone

Hazard Exposure — 3/5

The Mississippi Delta and associated inland waterways face:

River Flooding + Extreme Rainfall + Severe Convective Storms + Subsidence + Coastal Flooding

The region’s raw hazard exposure is lower than some Gulf Coast locations, but the interaction of hazards with infrastructure and socioeconomic vulnerability dramatically increases systemic risk.

Hazard Coupling — 3/5

One important pathway is:

Upstream Extreme Rainfall → River Discharge ↑ → Downstream Flooding → Prolonged Inundation → Structural and Infrastructure Damage

In coastal portions of the Delta, this can interact with:

River Flooding + Storm Surge + Sea-Level Rise → Compound Inland/Coastal Flooding

The duration of inundation can be as important as peak water depth because prolonged water exposure can increase mold, structural deterioration, electrical damage, and infrastructure failure.

Vulnerability — 5/5

This region’s primary vulnerability is structural.

Risk is amplified by:

Aging Infrastructure + Levee Dependence + Aging Buildings + Economic Constraints + Limited Local Fiscal Capacity

The critical issue is not simply whether flood-control infrastructure exists.

It is whether that infrastructure can be maintained, upgraded, and replaced at the rate required under changing climate conditions.

Insurance Stress — 4/5

Flood insurance is an essential component of property financing in designated high-risk areas where federal requirements apply.

However, the availability and affordability of private flood coverage can vary substantially by location and risk profile.

Where private coverage is limited, property owners can become increasingly dependent on federal flood insurance and other residual mechanisms.

This creates another form of concentration risk:

Private Insurance Capacity ↓ → Public Backstop Dependence ↑

The problem becomes more acute when repeated losses increase premiums, deductibles, or coverage restrictions faster than property values and household incomes can absorb them.

Recovery Deficit — 5/5

This is the region’s defining weakness.

A major flood can produce:

Property Damage → Income Loss → Reduced Local Tax Revenue → Infrastructure Damage → Limited Local Recovery Capacity

Federal disaster assistance can be essential, but administrative processes, funding requirements, and reconstruction complexity can extend recovery timelines.

The resulting feedback can become:

Low Local Fiscal Capacity → Slow Recovery → Persistent Damage → Lower Property Values → Lower Tax Base → Even Lower Recovery Capacity

Multiplicative Risk

3 × 3 × 5 × 4 × 5 = 900

Total Risk Factor: 900

This produces an important result:

The Mississippi Delta scores lower than Coastal Texas in raw hazard exposure but higher in total multiplicative risk.

That is precisely why a multiplicative framework is useful.

A moderate physical hazard can produce extreme systemic risk when combined with high vulnerability and a severe recovery deficit.


5. Urban Northeast Corridor

The Legacy-Infrastructure and Urban-Flooding Zone

Hazard Exposure — 3/5

The urban Northeast faces:

Nor’easters + Extreme Rainfall + Tidal Flooding + Sea-Level Rise + Urban Flash Flooding

The region does not necessarily experience the most extreme individual climate hazards in the country.

Its risk derives from density, infrastructure age, and enormous concentrations of economic value.

Hazard Coupling — 4/5

A central pathway is:

Sea-Level Rise → Higher Coastal Baseline → Reduced Stormwater Drainage Capacity → Heavy Rainfall → Urban Flooding

The resulting flooding can affect:

Basements + Subways + Tunnels + Electrical Systems + Transportation Networks + Commercial Districts

This creates a particularly important urban cascade:

Extreme Rainfall → Stormwater Overload → Transit Disruption → Workforce Disruption → Business Interruption → Economic Loss

Vulnerability — 4/5

The region contains extraordinary quantities of legacy infrastructure and older real estate.

Many structures were designed under climate conditions substantially different from those now emerging.

Below-grade spaces can be especially vulnerable:

Basement Housing + Electrical Rooms + Subway Infrastructure + Underground Transportation

This makes the region highly sensitive to intense precipitation even when properties are not located directly adjacent to rivers or coastlines.

Insurance Stress — 3/5

Insurance remains more available than in the most stressed coastal and wildfire markets, but the trajectory remains important.

Increasing flood claims, basement losses, storm damage, and infrastructure disruption can gradually increase premiums and deductibles.

The principal concern is therefore not an immediate insurance-market collapse but gradual repricing of urban climate exposure.

The feedback is:

Urban Flood Risk ↑ → Claims ↑ → Insurance Costs ↑ → Cost of Ownership ↑ → Property-Value Pressure ↑

Recovery Deficit — 2/5

The Northeast possesses comparatively strong municipal tax bases, financial resources, infrastructure institutions, and access to federal resources.

This provides substantial recovery capacity.

However, the scale and age of infrastructure create long-term adaptation challenges.

The region’s primary weakness is therefore not immediate recovery capacity but the enormous cost of modernizing legacy systems before they become repeatedly overwhelmed.

Multiplicative Risk

3 × 4 × 4 × 3 × 2 = 288

Total Risk Factor: 288

The Urban Northeast demonstrates that high population density and high property values do not automatically produce the highest multiplicative risk.

Strong fiscal and institutional recovery capacity can substantially reduce systemic risk.


Real-Estate Climate Risk Comparison Matrix

The following matrix applies the five-factor multiplicative framework:

RegionHazard ExposureHazard CouplingVulnerabilityInsurance StressRecovery DeficitMultiplicative Risk
1. Gulf Coast & Southern Florida554542,000
2. California WUI454541,600
3. Mississippi River Delta & Inland Waterways33545900
4. Coastal Texas44443768
5. Urban Northeast Corridor34432288

Why the Ranking Matters

The ranking demonstrates why climate-driven real-estate risk cannot be measured solely by the severity of weather.

The Mississippi Delta provides the clearest example.

Its 3/5 hazard-exposure score is lower than Coastal Texas’s 4/5, yet its overall multiplicative score is higher:

Mississippi Delta → 900

Coastal Texas → 768

The difference arises from the interaction of:

High Vulnerability + High Insurance Stress + Severe Recovery Deficit

This is the essence of cascading risk.

A region does not need to have the most extreme weather to have the greatest systemic vulnerability.

It needs to have the most dangerous combination of interacting weaknesses.


The Central Insurance Feedback

Across the five regions, insurance functions as one of the primary transmission mechanisms connecting physical climate risk to real-estate values.

The feedback can be represented as:

Climate Risk ↑ → Expected Losses ↑ → Insurance Claims ↑ → Premiums ↑ → Deductibles ↑ → Coverage Restrictions ↑ → Insurance Availability ↓ → Cost of Ownership ↑ → Property Demand ↓ → Property Values ↓

Once property values begin declining, another feedback can emerge:

Property Values ↓ → Mortgage Collateral ↓ → Lending Risk ↑ → Financing Constraints ↑ → Buyer Pool ↓ → Property Liquidity ↓ → Property Values ↓

Insurance therefore does not merely compensate property owners after losses.

It can influence whether a property can be:

Owned → Financed → Sold → Developed → Maintained → Insured

This makes insurance availability and affordability a critical component of real-estate climate risk.


The Major Coupled Feedback Loops

1. Insurance–Property Value Feedback

Climate Risk ↑ → Insurance Losses ↑ → Premiums ↑ / Availability ↓ → Cost of Ownership ↑ → Buyer Demand ↓ → Property Values ↓


2. Property Value–Tax Base Feedback

Property Values ↓ → Tax Base ↓ → Municipal Revenue ↓ → Infrastructure Investment ↓ → Resilience ↓ → Flood Risk ↑ → Property Values ↓


3. Recovery-Deficit Feedback

Disaster Frequency ↑ → Recovery Window ↓ → Unresolved Damage ↑ → Vulnerability ↑ → Next-Event Losses ↑ → Recovery Window ↓


4. Insurance–Mortgage Feedback

Physical Risk ↑ → Insurance Stress ↑ → Coverage Constraints ↑ → Mortgage Risk ↑ → Lending Constraints ↑ → Buyer Pool ↓ → Property Values ↓


5. Commercial Real-Estate Feedback

For income-producing properties:

Climate Risk ↑ → Insurance + Maintenance + Adaptation Costs ↑ → Operating Expenses ↑ → NOI ↓ → Property Value ↓

This relationship is particularly important for multifamily, hospitality, retail, industrial, and other income-producing properties.


The Cascading Real-Estate Framework

The five regional examples reveal several recurring stages in the emerging climate-real-estate cascade:

Physical Hazard

Warming → Sea-Level Rise + Heavier Rainfall + Stronger/Slower Storms + Extreme Heat + Drought

Hazard Coupling

Multiple Hazards → Compound Events → Greater Physical Exposure

Property Damage

Compound Hazard → Structural Damage + Infrastructure Damage + Business Interruption

Insurance Stress

Losses ↑ → Premiums ↑ + Deductibles ↑ + Coverage Restrictions ↑ + Availability ↓

Property Repricing

Insurance Cost ↑ → Cost of Ownership ↑ → Buyer Demand ↓ → Property Values ↓

Financial Amplification

Property Values ↓ → Mortgage Risk ↑ + Investment ↓ + Liquidity ↓

Municipal Amplification

Property Values ↓ → Tax Base ↓ → Infrastructure Investment ↓

Resilience Erosion

Infrastructure Investment ↓ + Recovery Capacity ↓ → Vulnerability ↑

Cascading Risk

Vulnerability ↑ → Future Losses ↑ → Insurance Stress ↑ → Property Values ↓

The resulting closed-loop system is:

Climate Hazard → Physical Loss → Insurance Stress → Property-Value Decline → Investment Decline → Tax-Base Erosion → Infrastructure Deterioration → Recovery Deficit → Greater Vulnerability → Greater Future Loss


The Central Finding

The Multiplicative Climate Risk framework produces a fundamentally different understanding of climate-exposed real estate.

The highest-risk region is not necessarily the region with:

The Most Hurricanes

The Most Wildfires

The Most Rainfall

or

The Highest Sea-Level Rise

Instead, it is the region where multiple risk factors interact:

Hazard Exposure × Hazard Coupling × Vulnerability × Insurance Stress × Recovery Deficit

The resulting system can become self-reinforcing:

Climate Hazard → Insurance Stress → Property-Value Decline → Investment Decline → Tax-Base Erosion → Infrastructure Resilience Decline → Recovery Deficit → Greater Vulnerability → Greater Future Loss

This is the central transition from climate hazard to cascading real-estate risk.

The most consequential property-market question is therefore no longer simply:

Will this property flood, burn, or be damaged by extreme weather?

It is:

Can this property remain insurable, financeable, valuable, maintainable, and economically viable as climate hazards become more frequent and increasingly coupled?

That question shifts climate-risk analysis from the physical event itself to the long-term resilience of the economic system surrounding the property.

And that is where the greatest risks may emerge.

The weather creates the shock.
Coupled hazards amplify the shock.
Insurance translates the shock into financial cost.
Real estate capitalizes the cost into property values.
Weak recovery capacity allows the damage to accumulate.
And cascading feedbacks can turn a climate hazard into a real-estate crisis.

bookmark_borderEmerging Coupled Feedback Loops Tip Tipping Points

by Daniel Brouse and Sidd Mukherjee

Coupled Climate Feedbacks: How Tipping Points Can Trigger Cascading Earth-System Instability

From Tipping Elements to Cascading Feedbacks

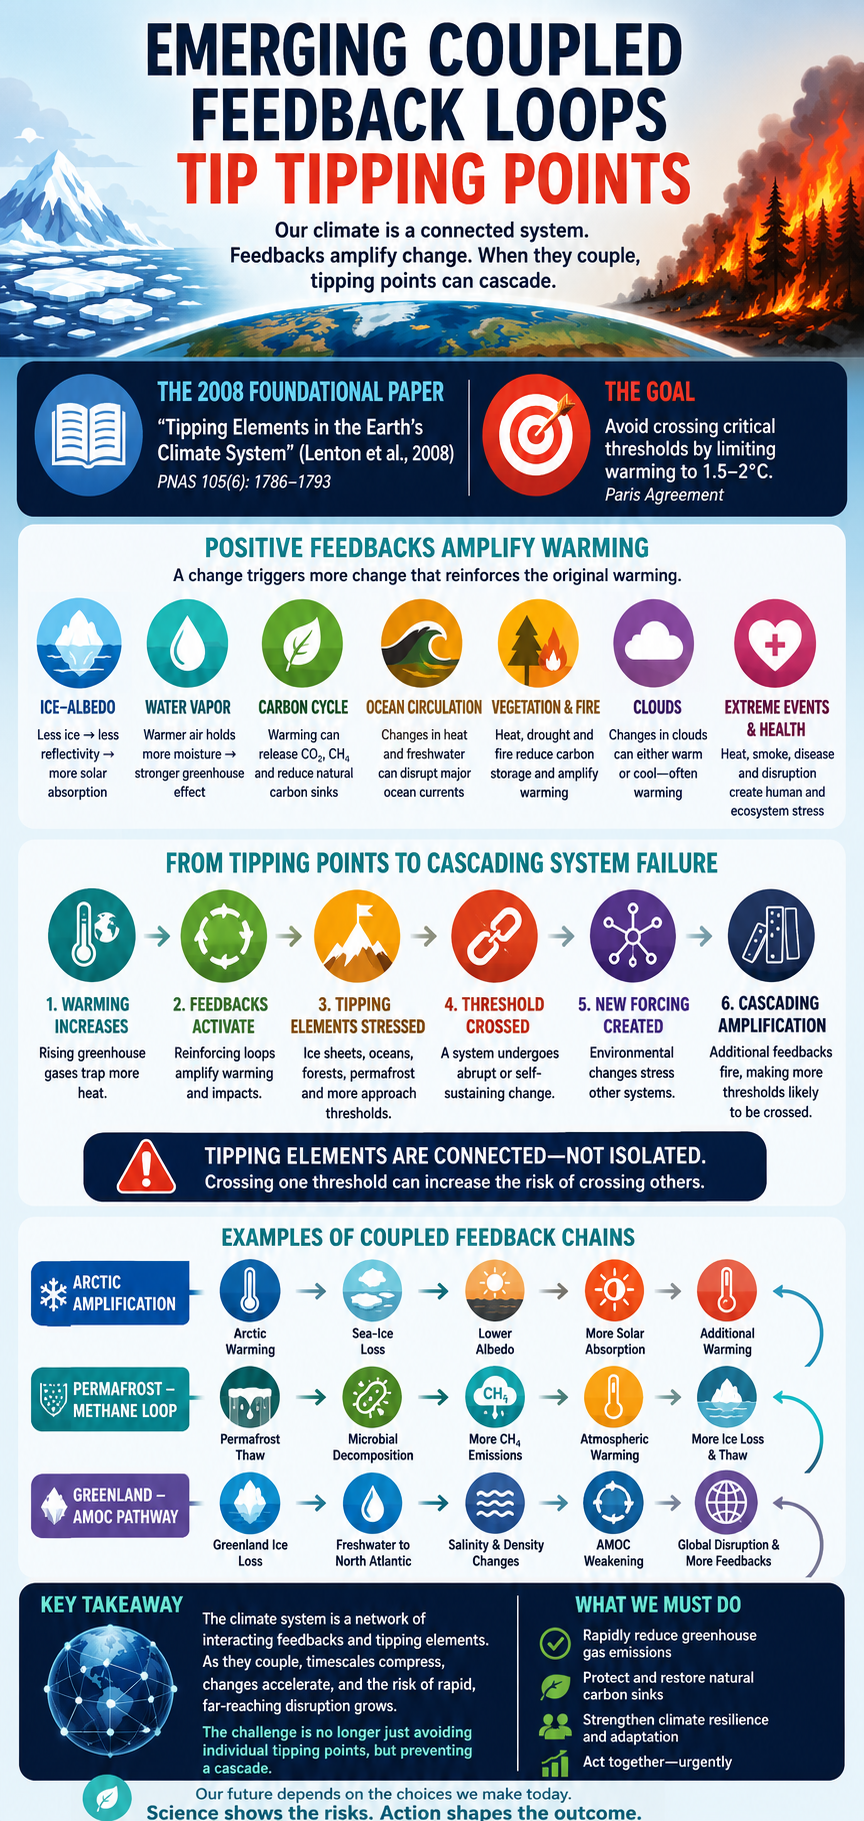
In 2008, a landmark climate-science paper, “Tipping Elements in the Earth’s Climate System,” brought renewed attention to the possibility that major components of the Earth system could undergo abrupt and potentially irreversible changes once critical thresholds were approached or crossed.

The 2008 Foundational Paper

Tipping Elements in the Earth’s Climate System
Lenton et al. (2008), Proceedings of the National Academy of Sciences

The paper examined several major climate tipping elements and highlighted the potential significance of warming in the range of approximately 1.5–2°C above preindustrial levels. These findings helped reinforce the scientific rationale for limiting global warming, including through the Paris Agreement’s goal of holding warming well below 2°C while pursuing efforts to limit it to 1.5°C.

At the time, the central challenge was framed largely as one of preventing individual climate tipping elements from reaching critical thresholds.

Today, the scientific picture is becoming more complicated.

Evidence of accelerating changes in several vulnerable components of the Earth system has intensified concern about approaching or potentially crossing thresholds. What was less well understood in the earlier tipping-point framework was the possibility that multiple feedback loops could interact, reinforce one another, and alter the timescales over which destabilization occurs.

The critical question is no longer simply:

How close is each tipping point?

It is increasingly:

What happens when tipping elements and feedback loops begin interacting with one another?


The Missing Dimension: Coupled Feedback Loops

In the 1990s, research associated with the Membrane Domain began exploring human-induced climate change through a nonlinear systems perspective, challenging the assumption that climate impacts would necessarily progress in a simple, approximately linear fashion.

Our research proposed that climate change could exhibit nonlinear and accelerating behavior as multiple physical, ecological, and socioeconomic feedbacks interact. The central concept was not that warming itself follows a simple exponential curve, but that the rate and consequences of change can accelerate as reinforcing feedbacks become increasingly coupled.

At the heart of this possibility are positive feedback mechanisms.

In climate science, a positive feedback is a process in which an initial change produces additional changes that reinforce the original disturbance. The term “positive” describes the direction of the feedback, not whether its consequences are beneficial.

Examples include:

  • Ice–Albedo Feedback — loss of reflective snow and ice exposes darker surfaces that absorb more solar energy.
  • Water Vapor Feedback — warming increases atmospheric water vapor, strengthening greenhouse trapping.
  • Carbon-Cycle Feedbacks — warming can alter soils, vegetation, oceans, and permafrost in ways that affect carbon uptake and release.
  • Ocean-Circulation Feedbacks — changes in temperature, salinity, and freshwater input can alter ocean circulation and climate patterns.
  • Vegetation–Climate Feedbacks — warming, drought, wildfire, and vegetation loss can reinforce regional drying and carbon loss.
  • Cloud Feedbacks — warming alters cloud properties and distributions, changing the balance between reflected sunlight and outgoing infrared radiation.
  • Extreme-Weather and Health Feedbacks — heat, wildfire smoke, air pollution, infectious disease risks, and infrastructure disruption can interact with ecological and societal vulnerabilities.

Individually, these mechanisms can amplify warming or its impacts.

The more consequential possibility is that they can also interact.


When Feedbacks Begin Coupling

A feedback loop does not have to operate in isolation.

For example:

Warming → Sea-Ice Loss → Lower Albedo → Greater Solar Absorption → Additional Arctic Warming

At the same time:

Arctic Warming → Permafrost Thaw → Microbial Decomposition → Greater Greenhouse-Gas Release → Additional Atmospheric Warming

These pathways can interact.

Additional warming can increase ice loss, which can alter atmospheric and oceanic conditions. Those changes can influence permafrost, ecosystems, circulation, precipitation, and wildfire behavior. Each affected subsystem can then introduce additional feedbacks.

The result is not necessarily one feedback loop.

It is a network of interacting feedback loops.


Tipping Points Can Become Connectors

Climate tipping points are often discussed individually: Greenland ice loss, Antarctic ice-sheet instability, AMOC disruption, Amazon dieback, permafrost thaw, and other vulnerable components.

But Earth systems do not operate independently.

When one component undergoes a major transition, the resulting changes can modify the conditions experienced by other components.

A tipping element can therefore become more than an endpoint.

It can become a connector.

A threshold crossing can alter temperature, precipitation, ocean salinity, atmospheric circulation, carbon exchange, surface reflectivity, or other physical conditions. Those changes can increase stress on another vulnerable subsystem.

This creates the possibility of cascading interactions:

Initial Warming
→ Feedback Amplification
→ Tipping-Element Destabilization
→ Environmental Change
→ New Feedback Activation
→ Additional Tipping-Element Stress
→ Further Amplification

The system can begin moving through a sequence in which each major disturbance increases the probability or severity of subsequent disturbances.


Tipping Points Igniting a Domino Effect

We understood that tipping points could eventually activate self-reinforcing feedbacks within the climate system.

What has become increasingly difficult to ignore is the potential importance of coupling and timescale compression.

The concern is not simply that individual thresholds exist.

It is that interacting feedbacks can change how quickly the system approaches them.

Consider a simplified example involving the Arctic:

Arctic Warming
→ Snow and Sea-Ice Loss
→ Lower Surface Reflectivity
→ Greater Solar Absorption
→ Additional Arctic Warming

At the same time:

Arctic Warming
→ Permafrost Thaw
→ Microbial Decomposition
→ Increased Methane and Carbon Release
→ Additional Atmospheric Warming

And simultaneously:

Arctic Warming
→ Atmospheric-Circulation Changes
→ Heat Extremes and Drought
→ Boreal Forest Stress
→ Wildfire
→ Carbon Emissions and Smoke Effects

These are not three isolated climate stories.

They are interacting components of a larger Earth-system network.


Cascading System Failures

The destabilization of climate subsystems is unlikely to resemble a smooth, uniform decline.

Instead, some changes can increase stress on other systems, producing cascading and compounding effects.

Consider the interaction between ocean circulation, Greenland, the Arctic, and the carbon cycle.

Changes in the Atlantic Meridional Overturning Circulation (AMOC) can redistribute heat and influence precipitation patterns across the Atlantic basin. Meanwhile, Greenland ice loss adds freshwater to the North Atlantic, affecting ocean density and stratification and potentially contributing to further AMOC weakening.

At the same time, Arctic amplification accelerates sea-ice loss and permafrost thaw. Permafrost degradation can release additional carbon dioxide and methane, adding greenhouse forcing to an already warming atmosphere.

Elsewhere, increasing heat and drought stress can threaten tropical forests. Amazon forest degradation and drought can reduce carbon uptake, alter evapotranspiration and rainfall recycling, and potentially increase the vulnerability of the forest to further drying and fire.

These processes can interact with one another.

The important point is not that every feedback necessarily causes every other feedback.

It is that the Earth system contains enough interconnected pathways that disturbances in one subsystem can propagate into others.


From Isolated Thresholds to a Network of Thresholds

This changes how climate risk should be conceptualized.

A tipping point should not necessarily be viewed as an isolated cliff.

It may be better understood as a node within a dynamic network of interacting thresholds and feedbacks.

The critical sequence becomes:

Warming
→ Feedback Activation
→ System Destabilization
→ Threshold Approach or Crossing
→ New Environmental Forcing
→ Additional Feedback Activation
→ Further Threshold Stress

Under this framework, the risk is not merely that one tipping element crosses a threshold.

The greater concern is cascading destabilization across multiple connected components of the Earth system.


The Central Risk: Nonlinear Acceleration

This is where nonlinear climate dynamics become especially important.

If each climate subsystem responded independently, the trajectory of global change would be easier to anticipate.

But coupled systems can behave differently.

As more feedbacks become activated, the effective rate of change in one component can be influenced by changes occurring elsewhere. This can produce periods of acceleration, abrupt transitions, threshold behavior, and substantial regional differences.

The resulting trajectory does not have to be a smooth curve.

It can become increasingly irregular and nonlinear.

That does not mean that the climate system is literally entering an uncontrolled “runaway” state, nor does it mean that every tipping point will necessarily cascade into every other one.

It means that the possibility of interacting thresholds and feedbacks makes the future more path-dependent, nonlinear, and difficult to manage.


The Climate System Is a Network, Not a Collection of Isolated Problems

The most important conceptual shift may therefore be from thinking about individual climate threats to understanding coupled Earth-system dynamics.

Ice loss affects albedo.

Warming affects permafrost.

Permafrost affects greenhouse-gas concentrations.

Greenhouse gases affect atmospheric warming.

Warming affects ecosystems.

Ecosystem degradation affects carbon storage.

Wildfire affects carbon emissions and atmospheric composition.

Ocean warming affects ice shelves.

Ice-sheet loss affects sea level and freshwater inputs.

Freshwater inputs can affect ocean circulation.

Ocean circulation redistributes heat and influences atmospheric conditions.

And each change can alter the conditions under which other feedbacks operate.

The resulting system resembles less a collection of separate dominoes and more a network of interconnected switches, where activating one pathway can change the sensitivity of many others.


The Real Challenge

The climate problem is therefore not simply about how much warming humanity produces.

It is also about how warming changes the internal dynamics of the Earth system.

The longer warming persists, the more feedbacks become active. As those feedbacks interact, the potential for nonlinear responses and cascading impacts increases.

The scientific challenge is to determine:

Which thresholds are approaching?

Which feedbacks are becoming stronger?

Which feedbacks are becoming coupled?

How quickly are these interactions changing the system?

And most importantly:

Are we beginning to compress the timescales between individual climate-system disruptions?

These questions deserve the same urgency once reserved for the identification of individual tipping points.

The climate system is not simply warming.

It is changing how it responds to warming.

That may ultimately prove to be one of the most consequential dimensions of climate risk in the 21st century.

Examples of Coupled Climate Feedback Loops and Tipping-Point Pathways

Climate feedbacks rarely operate in isolation. Many interact with, reinforce, or redirect one another, creating coupled feedback systems in which an initial warming response can trigger additional processes that amplify warming and increase pressure on climate tipping elements.

1. Lapse-Rate + Ice–Albedo Feedbacks

Two important feedbacks are the lapse-rate feedback and the ice–albedo feedback. They operate through different physical mechanisms but can become tightly coupled.

Lapse-Rate Feedback → Greater Near-Surface Heat Retention

Changes in the vertical temperature structure of the atmosphere can influence how efficiently heat is transported and radiated to space, affecting the amount of warming concentrated near Earth’s surface.

Ice–Albedo Feedback → Greater Solar Absorption

As snow and ice melt, reflective surfaces are replaced by darker land or ocean surfaces. Less sunlight is reflected back to space, increasing solar absorption and producing additional warming.

Together, these processes can form a reinforcing pathway:

Warming → Atmospheric Stability / Lapse-Rate Effects → Greater Near-Surface Heat Retention → Snow and Ice Loss → Lower Albedo → Greater Solar Absorption → Additional Warming ↺

This coupling helps explain why the Arctic has warmed substantially faster than the global average.

A simpler expression of the ice–albedo loop is:

Warming → Ice and Snow Loss → Darker Surface Exposure → Greater Solar Absorption → Additional Local Warming → More Ice Loss ↺


2. Ice-Sheet Melt–Elevation Feedback

Ice loss can also create a melt–elevation feedback.

Ice Loss → Lower Surface Elevation → Exposure to Warmer Air → Increased Melting → Additional Ice Loss → Further Elevation Loss ↺

As an ice sheet thins, its surface can descend into warmer atmospheric conditions, increasing the potential for further surface melting.

Ice-Sheet Thinning → Lower Elevation → Warmer Air Exposure → Faster Melting → Further Thinning ↺

This feedback can interact with the ice–albedo feedback, producing additional cryospheric amplification.


3. Greenland Ice Loss → AMOC Disruption

Greenland ice loss provides another important coupling pathway.

Greenland Ice Loss → Freshwater Input to the North Atlantic → Ocean Freshening → Changes in Salinity and Density → AMOC Weakening → Atmospheric and Oceanic Changes → Secondary Climate Feedbacks ↺

Large freshwater inputs can alter North Atlantic density structure and potentially affect the Atlantic Meridional Overturning Circulation (AMOC). Changes in the AMOC can, in turn, reorganize atmospheric and oceanic circulation and influence other climate processes.

The pathway can therefore be represented as:

Greenland Ice Loss → Freshwater Entering North Atlantic → Salinity and Density Changes → AMOC Weakening → Atmospheric and Oceanic Disruption → Secondary Feedbacks and Tipping Processes ↺


4. Permafrost Carbon Feedback

One of the most important carbon-cycle feedbacks is:

Warming → Permafrost Thaw → Greenhouse-Gas Release → Additional Warming ↺

As permafrost thaws, previously frozen organic carbon becomes increasingly available for microbial decomposition. This can release carbon dioxide and methane, adding greenhouse forcing to the atmosphere.


5. Arctic Amplification → Jet Stream → Heat and Drought

Arctic warming can alter the temperature contrast between the Arctic and lower latitudes, influencing atmospheric circulation.

A coupled pathway is:

Arctic Warming → Reduced Equator-to-Pole Temperature Contrast → Changes in Jet-Stream Behavior → Atmospheric Blocking → Persistent Heat → Drought and Drying

The resulting heat and drought can increase atmospheric moisture demand and vegetation stress:

Warm Air → Increased Atmospheric Moisture Demand → Greater Evaporation and Plant Water Loss → Drier Vegetation and Soils → More Flammable Fuels

This creates conditions favorable for wildfire development.


6. Heat → Drought → Wildfire → Pyrocumulonimbus Feedback

Extreme heat and drought can dry vegetation and increase wildfire risk.

Extreme Heat + Drought → Dry Vegetation → Wildfire → Pyrocumulonimbus Development → Lightning and Wind Changes → New Ignitions → Additional Wildfires ↺

A larger coupled pathway can be expressed as:

Arctic Warming → Atmospheric Circulation Changes → Heat Dome → Drought → High Vapor Pressure Deficit (VPD) → Dry Forests → Wildfire → Pyrocumulonimbus → Lightning → Additional Fires → Smoke Transport ↺

This illustrates how atmospheric circulation, land-surface drying, wildfire, and atmospheric chemistry can become interconnected.


7. Antarctic Ice-Shelf Instability

Ocean warming can destabilize ice shelves from below:

Warming Ocean → Subsurface Ice-Shelf Melting → Ice-Shelf Thinning → Reduced Structural Restraint → Increased Ice Discharge → Sea-Level Rise ↺

Warm ocean water reaching vulnerable ice shelves can contribute to basal melting and thinning. As ice shelves lose structural integrity, their ability to restrain inland grounded ice may decrease.

Warm Ocean Currents → Basal Melting → Ice-Shelf Thinning → Weakened Structural Restraint → Increased Ice Discharge → Rising Sea Levels


8. Ice Loss → Permafrost → Methane and CO₂

Ice loss can connect directly with the carbon cycle:

Ice and Snow Loss → Greater Solar Absorption → Arctic Warming → Permafrost Thaw → CH₄ + CO₂ Release → Additional Warming ↺

Wildfire can strengthen this connection:

Warming → More Severe Wildfire → CO₂ Emissions + Vegetation and Soil Loss → Accelerated Permafrost Thaw → Additional CH₄ + CO₂ Release → Further Warming ↺

The resulting system becomes increasingly interconnected:

Ice Loss → Wildfire → Permafrost Thaw → Greenhouse-Gas Release → Additional Warming → Further Ice Loss ↺

The major components can be visualized as:

🧊 Ice loss
🔥 Wildfire
❄️ Permafrost thaw
💨 Methane release
🌡️ Additional warming
↻ Further tipping-point pressure

A broader pathway is:

Human Emissions → Warming → Ice Loss → Permafrost Thaw → CH₄ + CO₂ Release → Additional Warming → Greater Wildfire and Ecosystem Disruption → Additional Greenhouse-Gas Release → Increased Tipping-Point Pressure ↺


9. Methane → CO₂: A Two-Stage Greenhouse-Gas Feedback

Methane has a relatively short atmospheric lifetime compared with CO₂, but its oxidation ultimately produces CO₂.

Methane Release → Strong Near-Term Warming → Atmospheric Oxidation → CO₂ → Long-Term Additional Warming

This distinction is important because methane can produce substantial near-term warming while its oxidation contributes to longer-lived atmospheric CO₂.


10. Wetlands → Methane → Warming

Changes in precipitation and flooding can alter wetland extent and microbial activity:

Rising Temperatures → Changes in Rainfall and Flooding → Expansion or Intensification of Oxygen-Poor Wetlands → Increased Anaerobic Decomposition → Greater Methane Release → Additional Warming ↺

A simplified feedback is:

More Warming → More Methane Release → More Greenhouse Warming → Greater Ecosystem Disruption → Additional Methane Release ↺


11. Coupled Cryosphere–Carbon Feedback Cascade

Multiple feedbacks can interact in sequence:

Arctic Warming → Sea-Ice Loss → Stronger Ice–Albedo Feedback → Additional Arctic Warming → Permafrost Thaw → Accelerated Microbial Decomposition → Increased CH₄ Emissions → Additional Atmospheric Warming → Further Ice Loss and Permafrost Thaw ↺

This creates a coupled cryosphere–carbon feedback in which warming reinforces both physical and biological processes.

Before tipping-point activation, the dominant relationship may be relatively straightforward:

Human Emissions → Greenhouse-Gas Increase → Warming

As additional climate-system feedbacks become activated:

Human Emissions → Warming → Permafrost and Wetland Changes → Additional Methane → More Warming

With multiple interacting tipping elements:

Warming → Ice Loss → Greater Solar Absorption → Permafrost Thaw → Methane Release → Additional Warming → Further Tipping-Point Pressure → Additional Greenhouse-Gas Release ↺

A more complex cascade can include wildfire:

Warming → Ice Loss → Greater Solar Absorption → Permafrost Thaw → CH₄ + CO₂ Release → More Warming → Intensified Wildfires → Forest and Soil Carbon Loss → Accelerated Permafrost Thaw → Additional Greenhouse-Gas Release → Further Tipping-Point Pressure ↺


12. Heat → Cooling Demand → Energy Use

Climate impacts can also generate feedbacks through human energy systems:

More Heat → Higher Cooling Demand → Greater Electricity Consumption → Potentially Higher Greenhouse-Gas Emissions → Additional Warming → More Heat ↺

The strength of this feedback depends strongly on the electricity system. As electricity generation becomes less carbon-intensive, the emissions component of this loop can weaken.


13. Ozone-Centered Earth-System Feedbacks

Tropospheric ozone provides another example of how atmospheric chemistry can connect climate, ecosystems, and wildfire.

Atmospheric Pathway

Warming → Lightning → Ozone Formation → Additional Warming

Ecosystem Pathway

Ozone Exposure → Reduced Photosynthesis → Reduced Carbon Uptake → Higher Atmospheric CO₂ → Additional Warming

Wildfire Pathway

Ozone Exposure → Vegetation Stress → Increased Wildfire Vulnerability → Additional Ozone Precursors → More Ozone

Lightning–Wildfire Pathway

Warming → Lightning → Wildfires → Ozone Precursors → More Ozone

Cryosphere Pathway

Wildfires → Dark Carbonaceous Deposits on Snow and Ice → Reduced Albedo → Greater Solar Absorption → Warming

Permafrost Pathway

Wildfires → Permafrost Combustion and Thaw → CO₂ + CH₄ Release → Additional Warming

A more integrated pathway is:

Combustion → Ozone Formation → Vegetation Damage → Reduced Carbon Uptake → Increased Atmospheric CO₂ → Additional Warming → Increased Wildfire Activity → Additional Ozone Formation ↺


14. Water Vapor + Clouds: Coupled Feedbacks

Water vapor is a powerful greenhouse gas and responds rapidly to warming.

More Greenhouse Gases → Warming → More Atmospheric Water Vapor → Stronger Greenhouse Effect → Additional Warming ↺

Clouds operate differently and can exert both warming and cooling influences depending on their properties and location.

Low-Level Clouds → Greater Reflection of Incoming Sunlight → Cooling

High-Level Clouds → Greater Retention of Outgoing Infrared Radiation → Warming

Because water vapor and clouds are physically connected through atmospheric moisture, convection, condensation, and radiation, changes in one can influence the behavior of the other.


15. Emerging and Less-Studied Coupled Feedbacks

Several additional processes may participate in interconnected climate feedback networks:

🔥 Zombie fires
🟢 Greenland ice algae
🏞️ Thermokarst lakes
🦫 Arctic beaver expansion
🪲 Boreal forest beetles
🌿 Arctic shrubification
💨 Wetland methane pulses
⚡ Lightning feedbacks
🦠 Soil microbiome feedbacks

These processes should not all be treated as equivalent in strength. Some are well-established components of climate feedbacks, while others remain active areas of research.


16. Zombie Fires → Soot → Ice Melt → Methane

These systems do not operate independently. A relatively small perturbation can propagate through several connected processes, creating a climate-system example of cascading effects.

For example:

Warming → Zombie Fires → Soot Deposition on Snow and Ice → Lower Albedo → Faster Melting → Thermokarst Lakes → Methane Release → Additional Warming ↺

Broken into individual links:

Warming → Zombie Fires

Zombie Fires → Soot Deposition

Soot → Darker Snow and Ice

Darker Ice → Faster Melting

Faster Melting → Thermokarst Lakes

Thermokarst Lakes → Methane Release

Methane → Additional Warming ↺


17. Greenland Algae → Lower Albedo → More Meltwater

Biological processes can also interact with cryospheric feedbacks:

Warming → Greenland Ice-Algae Growth → Lower Surface Albedo → Greater Solar Absorption → Increased Meltwater → Conditions Favoring Further Algal Growth ↺

The simplified pathway is:

Warming → Greenland Algae → Lower Albedo → More Meltwater → Larger Algal Blooms ↺


18. Forest Loss → Reduced Rainfall → Further Forest Loss

Forest ecosystems can participate in coupled land–atmosphere feedbacks:

Deforestation → Reduced Evapotranspiration → Changes in Atmospheric Moisture Recycling and Rainfall → Greater Forest Stress → Additional Forest Loss ↺

Another carbon-cycle pathway is:

Reduced Forest Productivity → Lower Carbon Uptake → More Atmospheric CO₂ → Additional Warming → Greater Forest Stress → Further Productivity Loss ↺


19. An Integrated Cascade of Coupled Feedbacks and Tipping Elements

The individual pathways above can ultimately become interconnected into a much larger Earth-system network:

Polar Amplification → Weakened Equator-to-Pole Temperature Contrast → Atmospheric Circulation Changes → Arctic and Greenland Ice Loss

→ ICE–ALBEDO FEEDBACK:
Ice Loss → Darker Surface → Greater Solar Absorption → More Warming → More Ice Loss ↺

→ MELT–ELEVATION FEEDBACK:
Ice Loss → Lower Ice-Sheet Elevation → Warmer Atmospheric Exposure → Faster Surface Melt → Further Elevation Loss ↺

→ LAPSE-RATE FEEDBACK:
Arctic Warming → Changes in Vertical Temperature Structure → Altered Near-Surface Heat Retention → Additional Warming → More Ice Melt ↺

These cryospheric processes can then connect to ocean circulation:

Coupled Cryospheric Amplification → Freshwater Input to the North Atlantic → Reduced Salinity and Density → Potential AMOC Weakening → Atmospheric Pressure-Field and Storm-Track Changes

Changes in atmospheric circulation may then contribute to:

Greater Jet-Stream Waviness → Slower-Moving Rossby Waves → Persistent Blocking and Omega Blocks → Stalled Atmospheric Rivers + Prolonged Heat Domes + Drought–Flood Swings → Hydroclimatic Whiplash

The resulting impacts can propagate through human and ecological systems:

Hydroclimatic Whiplash → Agricultural Stress + Infrastructure Damage + Ecosystem Disruption + Public-Health Stress

Meanwhile, other tipping elements can become increasingly vulnerable:

Permafrost Tipping Element

Permafrost Thaw → CO₂ + CH₄ Release → Additional Greenhouse Forcing → Arctic Warming ↺

Boreal Forest Tipping Element

Warming + Drought + Wildfire → Forest Degradation → Reduced Carbon Uptake + Carbon Release → Additional Warming ↺

Amazon Rainforest Tipping Element

Warming + Drought + Fire → Reduced Evapotranspiration and Rainfall Recycling → Greater Drought → Forest Loss + Carbon Release → Additional Warming ↺

West Antarctic Ice-Sheet Tipping Element

Ice-Sheet Instability → Accelerated Ice Loss → Sea-Level Rise → Additional Cryospheric Stress

At the planetary scale, continued redistribution of land ice and water can also affect Earth’s mass distribution and rotational dynamics:

Global Land-Ice Loss + Water Redistribution → Planetary Mass Redistribution → Changes in Moment of Inertia → Changes in Rotational Dynamics → Potential Changes in Length of Day


The Central Concept

The critical distinction is between an individual feedback loop and a coupled feedback network.

A single feedback may amplify or dampen an initial perturbation. But when multiple feedbacks become connected, the output of one process can become the input to another:

Initial Warming → Feedback A → Feedback B → Feedback C → Tipping-Point Pressure → New Feedbacks → Additional Warming ↺

The result is not necessarily a single runaway process. Rather, it can be an increasingly interconnected Earth system in which multiple reinforcing feedbacks alter the probability, speed, and severity of transitions across different climate tipping elements.

That is the central significance of coupled feedback loops: the climate system can behave less like a collection of independent mechanisms and more like an interconnected network in which changes propagate across atmospheric, cryospheric, oceanic, ecological, chemical, and human systems.

bookmark_borderFeedback Examples

by Daniel Brouse and Sidd Mukherjee

Examples of complex feedback loop coupling:
Two of the most important are the lapse-rate feedback and the ice–albedo feedback. They operate through different physical mechanisms, but they are tightly coupled:

Lapse-Rate Feedback → Traps Heat Near the Surface

Ice–Albedo Feedback → Converts More Sunlight Into Heat

Together, they create a reinforcing loop:

Warming → Atmospheric Stabilization → Surface Heat Retention → Ice and Snow Loss → Lower Albedo → Greater Solar Absorption → More Warming

This coupling helps explain why the Arctic can warm substantially faster than the global average.

Warming → Ice/Snow Loss → Lower Albedo → More Solar Absorption → More Warming
warming → ice and snow loss → darker surface exposure → greater solar absorption → additional local warming → more ice loss

Greenhouse Forcing → Atmospheric Stability / Lapse-Rate Effects → More Near-Surface Heat Retention → Warmer Surface → Snow and Ice Loss → Lower Surface Albedo → More Solar Energy Absorbed → Additional Surface Warming → Further Snow and Ice Loss ↺

Lapse Rate → Keeps More Warming Concentrated Near the Surface → Ice–Albedo → Turns More Incoming Sunlight Into Absorbed Energy → Surface Warming → Snow & Ice Loss → Even Greater Solar Absorption → Additional Warming ↺

Global Warming → Arctic Amplification → Coupled Atmospheric + Cryospheric Feedbacks → Accelerated Snow and Ice Loss → Reduced Reflectivity + Greater Heat Retention → Further Warming → Increasing Cryospheric Instability → Potential Threshold Crossing ↺

This is the Melt–Elevation Feedback:
ice loss → lower surface elevation → warmer surrounding air → increased melting → additional ice loss → further elevation loss

ice-sheet thinning → lower elevation → warmer air exposure → faster melting → further thinning

Greenland ice loss → freshwater input → North Atlantic freshening → altered ocean density → AMOC weakening → major atmospheric and oceanic changes → secondary climate impacts

Primary Ice–Albedo Feedback
Global Warming → Ice & Snow Loss → Ice–Albedo Amplification → Greater Heat Absorption → Additional Warming ↺

Ice-Sheet Elevation Feedback
Ice-Sheet Mass Loss → Surface Elevation Decline → Warmer Atmospheric Exposure → Increased Melting → Additional Elevation Loss ↺

Greenland–AMOC Feedback Pathway
Greenland Ice Loss → Freshwater Entering North Atlantic → Salinity & Density Changes → AMOC Weakening → Global Atmospheric & Oceanic Disruption → Secondary Climate Feedbacks & Tipping Processes ↺

warming → permafrost thaw → greenhouse-gas release → additional warming

Arctic warming → reduced equator-to-pole temperature contrast → altered jet-stream behavior → atmospheric blocking → persistent heat dome → prolonged drought and drying

warm air → greater atmospheric moisture demand → increased evaporation and plant water loss → drying vegetation and soils → highly flammable fuels

extreme heat and drought → dry vegetation → wildfire → enormous heat column → pyrocumulonimbus formation → lightning and wind shifts → new ignitions → more wildfires

Arctic warming → atmospheric disruption → heat dome → drought → high VPD → dry forests → wildfire → pyrocumulonimbus → lightning → additional fires → massive smoke transport

warm ocean currents → basal melting → ice-shelf thinning → weakened structural restraint → increased ice discharge → rising sea levels

Arctic Amplification
Arctic Warming → Snow & Sea-Ice Loss → Darker Surfaces → Greater Solar Absorption → Additional Warming ↺

Arctic–Wildfire Feedback
Arctic Warming → Jet-Stream Disruption & Atmospheric Blocking → Persistent Heat Domes → Drought & High VPD → Boreal Forest Drying → Wildfire → Pyrocumulonimbus Storms → Lightning & New Fires → Massive Smoke Transport ↺

Cryospheric Mass-Loss Pathway
Warming → Snowpack Loss & Glacier Melting → Glacier Mass Loss → Sea-Level Rise

Antarctic Ice-Shelf Instability
Warming Ocean → Subsurface Ice-Shelf Melting → Ice-Shelf Thinning → Reduced Restraint on Grounded Ice → Accelerated Ice Discharge → Sea-Level Rise ↺

Ice & snow loss → greater solar absorption → Arctic warming → permafrost thaw → CH4 + CO2 release → more warming

Then wildfire adds another powerful connection:

Warming → more severe wildfire → CO2 emissions → vegetation & soil loss → accelerated permafrost thaw → additional CH4 + CO2 → further warming

The result is an increasingly interconnected climate system in which one feedback can strengthen another.

🧊 Ice loss
🔥 Wildfire
❄️ Permafrost thaw
💨 Methane release
🌡️ Additional warming
↻ Further tipping-point activation

Human emissions → warming → ice loss → permafrost thaw → methane and CO₂ release → more warming → greater wildfire and ecosystem disruption → additional greenhouse-gas release → further tipping-point pressure

Methane leak → approximately 10–12 years of intense methane warming → atmospheric oxidation → CO₂ → centuries of additional warming

Rising temperatures → Increased rainfall and flooding → Expansion of oxygen-poor wetlands → Faster microbial decomposition → Increased methane release → Additional warming

More warming → More methane release → More greenhouse warming → More ecosystem disruption → More methane release

Ice loss accelerates warming → warming destabilizes frozen carbon stores → microbial activity increases → methane emissions increase → methane adds additional warming → more tipping points become vulnerable

Arctic Warming → Sea-Ice Loss → Stronger Ice–Albedo Feedback → Additional Arctic Warming → Increased Permafrost Thaw → Accelerated Microbial Decomposition → Increased CH₄ Emissions → Additional Atmospheric Warming → Further Ice Loss & Permafrost Thaw ↺

Before tipping-point activation:
Human emissions → methane emissions → warming

As tipping points are crossed:
Human emissions → warming → permafrost and wetland changes → additional methane → more warming

With multiple interacting tipping points:
Warming → ice loss → greater solar absorption → permafrost thaw → methane release → additional warming → further tipping-point activation → additional greenhouse-gas release

Warming → ice loss → greater solar absorption → permafrost thaw → methane + CO₂ release → more warming → intensified wildfires → forest and soil carbon loss → accelerated permafrost thaw → additional greenhouse-gas release → further tipping-point activation

More Heat → Higher Cooling Demand → Greater Electricity Use → More Greenhouse Gas Emissions → More Global Warming → More Heat

The emerging Earth-system framework can be viewed as a series of interconnected feedback loops centered on ozone:

Lightning-Generated Tropospheric Ozone and Earth-System Feedbacks
Atmospheric Pathway
Warming → Lightning → Ozone → Warming

Ecosystem Pathway
Ozone → Reduced Photosynthesis → Reduced Carbon Uptake → Higher CO₂ → Warming

Wildfire Pathway
Ozone → Vegetation Stress → Increased Wildfire Risk → More Ozone

Lightning–Wildfire Pathway
Warming → Lightning → Wildfires → Ozone Precursors → More Ozone

Cryosphere Pathway
Wildfires → Brown Carbon → Reduced Albedo → Warming

Permafrost Pathway
Wildfires → Permafrost Combustion → CO₂ and CH₄ Release → Warming

Combustion → Ozone Formation → Vegetation Damage → Reduced Carbon Uptake → Increased Atmospheric CO₂ → Additional Warming → Increased Wildfire Activity → Additional Ozone Formation

Water Vapor + Clouds: Coupled Feedbacks Driving a Warmer Planet
More greenhouse gases → warming → more atmospheric water vapor → stronger greenhouse effect → additional warming.

Low-level clouds Reflect sunlight → cooling
High-level clouds Trap outgoing heat → warming

🔥 Zombie Fires
🟢 Greenland Ice Algae
🏞️ Thermokarst Lakes
🦫 Arctic Beaver Expansion
🪲 Boreal Forest Beetles
🌿 Arctic Shrubification
💨 Wetland Methane Pulses
⚡ Lightning Feedback
🦠 Soil Microbiome Feedback

These systems don’t operate independently.

A small change can trigger multiple connected responses that amplify one another—a climate-scale example of the Butterfly Effect.

For example:
Warming → Zombie Fires → Soot on Ice → Lower Albedo → Faster Melting → Thermokarst Lakes → Methane Release → More Warming

Warming → zombie fires
Zombie fires → soot deposition
Soot → darker snow and ice
Darker ice → faster melting
Faster melting → thermokarst lakes
Thermokarst lakes → methane release
Methane → additional warming

Likewise:
Warming → Greenland algae
Algae → lower albedo
Lower albedo → more meltwater
Meltwater → larger algal blooms

Deforestation → Reduced evapotranspiration → Less rainfall → More forest stress → Additional forest loss

Reduced forest productivity → Lower carbon uptake → More atmospheric CO₂ → Additional warming → Further forest stress

Polar amplification → weakened equator-to-pole temperature gradients → reduced thermal contrast → atmospheric circulation changes → accelerated Arctic and Greenland ice melt → ICE–ALBEDO FEEDBACK: ice loss → darker surface → greater solar absorption → more warming → more ice loss ↺ → MELT–ELEVATION FEEDBACK: ice loss → lower ice-sheet elevation → warmer air → faster surface melt → further elevation loss ↺ → LAPSE-RATE FEEDBACK: Arctic warming → weaker vertical temperature gradient → reduced atmospheric cooling efficiency → additional near-surface warming → more ice melt ↺ → coupled cryospheric amplification → freshwater input into the North Atlantic → reduced salinity + density → AMOC disruption / potential weakening → North Atlantic pressure-field + storm-track reorganization → greater jet-stream waviness → slower progression → amplified Rossby waves → persistent blocking + omega blocks + meridional flow → stalled atmospheric rivers + prolonged heat domes + drought–flood swings → hydroclimatic whiplash → agriculture + infrastructure + ecosystems + public health stress → PERMAFROST TIPPING ELEMENT: thaw → CO₂ + CH₄ release → additional greenhouse forcing → Arctic warming ↺ → BOREAL FOREST TIPPING ELEMENT: warming + drought + wildfire → forest degradation → reduced carbon uptake + carbon release → additional warming ↺ → AMAZON RAINFOREST TIPPING ELEMENT: warming + drought + fire → reduced evapotranspiration + rainfall recycling → greater drought → forest loss + carbon release → additional warming ↺ → WEST ANTARCTIC ICE-SHEET TIPPING ELEMENT: ice instability → accelerated ice loss → sea-level rise → additional cryospheric stress → global land-ice loss + groundwater redistribution → planetary mass redistribution → altered moment of inertia → rotational dynamics → slight rotational slowing → changes in length of day.

bookmark_borderWater Vapor, Clouds, and Climate Change: Two Very Different and Connected Feedbacks

by Daniel Brouse

Water vapor and clouds are closely related, but they are not the same thing—and they play very different roles in the climate system.

Water vapor is Earth’s most abundant and most important natural greenhouse gas. As the climate warms, the atmosphere can hold more water vapor, creating a powerful positive feedback: warming increases atmospheric moisture, and that additional water vapor traps more heat, causing additional warming. Under the Clausius-Clapeyron relationship, the atmosphere can hold roughly 7% more water vapor for every 1°C of warming, provided sufficient moisture is available.

Clouds, by contrast, have competing effects. Low clouds generally cool the planet by reflecting incoming sunlight back into space, while high clouds generally warm it by trapping outgoing infrared radiation. But this does not mean that their effects are currently neutral or cancel each other out.

The critical question is not simply whether clouds cool during the day and warm at night. It is how climate change is altering the amount, altitude, thickness, reflectivity, lifetime, and geographic distribution of different cloud types.

Current evidence indicates that these changes are producing a net climate feedback that does not simply cancel out the warming influence of increased greenhouse gases and water vapor. In particular, reductions or thinning of some highly reflective low-level clouds can allow more solar energy to reach the Earth’s surface, amplifying warming.

Water Vapor: A Powerful Positive Feedback

Unlike carbon dioxide, water vapor is primarily a feedback rather than the initial forcing responsible for today’s long-term warming.

As carbon dioxide and other greenhouse gases warm the atmosphere, warmer air can contain more moisture. That additional water vapor absorbs outgoing infrared radiation and strengthens the greenhouse effect.

This creates a reinforcing cycle:

More greenhouse gases → warming → more atmospheric water vapor → stronger greenhouse effect → additional warming.

Water vapor also contributes to changes in precipitation, atmospheric rivers, extreme rainfall, and other aspects of the hydrological cycle.

Clouds: Their Effects Do Not Simply Cancel

Clouds are more complicated than water vapor because they can exert both cooling and warming influences.

Low-level reflective clouds, such as stratocumulus, tend to cool the climate by reflecting incoming sunlight back into space.

High-level clouds, such as cirrus, tend to warm the climate because they allow much of the Sun’s shortwave radiation to enter while reducing the amount of infrared heat that escapes to space.

It is therefore tempting to assume that the cooling effect of clouds during the day is roughly canceled by their warming effect at night. That is not an adequate description of the changing climate system.

Cloud feedback depends on far more than the day-night cycle. It depends on:

  • cloud altitude
  • cloud thickness
  • cloud coverage
  • cloud reflectivity
  • cloud lifetime
  • geographic location
  • underlying surface conditions
  • atmospheric temperature and humidity
  • changes in atmospheric circulation

Climate change is altering these characteristics. Consequently, the cooling and warming effects of clouds are not remaining in a fixed equilibrium.

The relevant issue is the change in the balance.

If highly reflective low clouds become less extensive or thinner, more solar radiation reaches the ocean and land surface. At the same time, persistent or changing high clouds can continue to restrict the escape of infrared radiation.

The result is not a neutral cloud system. Some observed and modeled cloud changes act as positive feedbacks that add to global warming.

Why Changes in Low Clouds Matter

One of the most important climate questions is how global warming changes the abundance, thickness, altitude, and distribution of clouds—particularly low-level marine clouds.

Several mechanisms can alter these clouds.

Declining Relative Humidity

A warmer atmosphere can contain substantially more water vapor without necessarily becoming more saturated.

In some regions, changes in circulation and surface conditions can therefore produce lower relative humidity and less favorable conditions for cloud formation.

The result can be fewer or thinner clouds even while the total amount of atmospheric water vapor increases.

This illustrates an important distinction:

More water vapor does not necessarily mean more clouds.

Water vapor can increase the atmospheric greenhouse effect while conditions become less favorable for the formation or persistence of certain reflective clouds.

Cleaner Air and Reduced Aerosols

Air pollution produces aerosols that can serve as cloud-condensation nuclei, providing particles around which cloud droplets can form.

Successful reductions in sulfur dioxide and other particulate pollution have produced major public-health and environmental benefits. However, removing reflective aerosols can also remove some of the cooling that previously offset greenhouse warming.

The interaction between declining aerosol pollution, cloud formation, and climate is complex and varies geographically.

Changes in Atmospheric Circulation

Climate change is also altering atmospheric circulation patterns.

Changes in subtropical circulation, storm tracks, ocean temperatures, and atmospheric stability can shift where clouds form and how long they persist.

These changes can affect the distribution and characteristics of reflective low clouds and potentially amplify warming.

The Cloud Feedback

The basic relationship can be summarized as follows:

Cloud typeTypical direct effectClimate-change concern
Low-level cloudsReflect sunlight → coolingReductions or thinning allow more solar energy to reach the surface
High-level cloudsTrap outgoing heat → warmingChanges in altitude and properties can increase heat retention
Middle-level/mixed cloudsCan produce both effectsImpact depends on altitude, thickness, and composition

The key distinction is this:

Clouds have both cooling and warming effects, but climate change is changing the balance between those effects.

Therefore, saying that clouds “cool during the day and warm at night” does not establish that their overall climate impact is neutral.

A cloud system can have a net cooling effect today while simultaneously undergoing changes that reduce that cooling effect and thereby produce a positive cloud feedback.

This is an important distinction between cloud forcing and cloud feedback.

Clouds have historically produced a substantial net cooling influence on the climate. But if warming causes reflective low clouds to decrease or become less reflective, the planet loses some of that cooling. The resulting change itself constitutes an additional warming influence.

Regional Exceptions Matter

Cloud behavior is not uniform across the planet.

For example, the rapidly changing Arctic climate produces complex regional cloud responses as sea ice retreats and previously ice-covered ocean becomes exposed. Open water changes evaporation, atmospheric moisture, aerosols, and surface energy exchange. Marine biological activity can also influence atmospheric particles that participate in cloud formation.

Thus, even when a broad global tendency exists, regional cloud feedbacks can move in different directions.

The existence of regional exceptions does not mean that cloud feedback is neutral globally. It means that the climate system is heterogeneous and that different mechanisms can dominate in different locations.

The Bigger Picture

The key point is that water vapor and clouds should not be treated as interchangeable parts of the climate system.

Water vapor is a powerful greenhouse gas whose atmospheric concentration increases as the climate warms, providing a major positive feedback.

Clouds are different. They redistribute energy through both solar reflection and infrared heat trapping. But the balance between those effects is not fixed.

Climate change is modifying the cloud system itself and appears to be a positive feedback accelerating climate change.

This matters because the climate system responds to changes in Earth’s energy balance. Even a relatively small persistent shift toward greater absorption of solar energy or reduced escape of infrared radiation can accumulate over time.

Water vapor strengthens the greenhouse effect, while changing cloud behavior can alter how much additional energy the Earth absorbs and retains. Together, these coupled feedbacks can reinforce warming, accelerate climate-system changes, and increase the risk of triggering or amplifying tipping points.

bookmark_borderAmericans Are Feeling the Heat—But Fewer Believe Climate Change Is Happening

by Daniel Brouse

An AP-NORC poll reveals a deeply troubling contradiction in the American public’s understanding of climate change: Americans are increasingly experiencing the effects of extreme heat, yet fewer now believe climate change is actually happening.

According to the poll, just 66% of Americans say climate change is happening, down sharply from 73% a year ago. That seven-percentage-point decline is particularly alarming because it comes at a time when Americans are reporting increasingly direct and disruptive experiences with extreme heat.

The disconnect raises an important question: How can people increasingly experience the consequences of a changing climate while becoming less likely to recognize climate change as the cause?

Extreme Heat Is Becoming Personal

The same poll found that 90% of Americans say extreme heat has affected their lives in some way, up from 83% in July 2024.

The impacts aren’t confined to abstract concerns about the environment. Americans report that extreme heat is affecting everyday life, including:

  • Electricity bills
  • Outdoor activities
  • Sleep
  • Travel and vacations
  • Daily routines

Perhaps most significantly, about 80% say extreme heat has affected their electricity bills, up from 69% in 2024.

In the Midwest, the increase is even more striking: 44% now say extreme heat has had a major impact on their electricity bills, compared with 29% two years ago.

That is climate change translated into something tangible: a higher household expense.

The Perception–Attribution Gap

The most important finding may not be the increase in heat-related disruption. It may be the growing gap between what Americans experience and what they believe is causing it.

The survey presents two seemingly contradictory trends:

90% say extreme heat has affected their lives.

Yet only 66% say climate change is happening.

And that 66% figure is down from 73% just one year ago.

This is a remarkable perception–attribution gap.

Americans can recognize that summers are becoming more difficult, electricity costs are rising, outdoor activities are being disrupted and extreme heat is affecting sleep—without necessarily connecting those experiences to a changing climate.

The result is a potentially dangerous disconnect between physical reality and public understanding.

Political Division Is Part of the Explanation

Political ideology continues to play an enormous role in how Americans interpret climate-related experiences.

Democrats are substantially more likely than Republicans to describe extreme heat as having a major impact on their lives. But that doesn’t mean Republicans aren’t experiencing the same heat.

The distinction is increasingly about interpretation and attribution.

People across the political spectrum can experience the same 100-degree day. They can experience the same oppressive humidity, pay the same higher electricity bill and face the same restrictions on outdoor activity.

But they may reach very different conclusions about why it is happening.

That distinction matters because climate change doesn’t require public agreement in order to produce physical consequences.

Climate Change Is Becoming an Economic Issue

The AP-NORC findings also demonstrate why climate change should not be viewed exclusively as an environmental issue.

Extreme heat creates a chain of consequences:

Higher temperatures → greater air-conditioning demand → higher electricity consumption → increased household costs

But that is only one pathway.

Extreme heat can also affect worker productivity, agriculture, infrastructure, public health, insurance losses and energy-grid reliability.

The household electricity bill may therefore be only the first visible economic manifestation of a much larger systemic problem.

The public doesn’t need to understand atmospheric physics to experience these consequences.

They simply need to notice that something is different.

The Most Alarming Finding Isn’t the Heat

The increase in extreme-heat impacts is concerning, but the seven-point decline in belief that climate change is happening may be even more alarming.

The country is experiencing a growing number of climate-related disruptions while simultaneously becoming less certain—or less willing—to identify climate change as the underlying cause.

That creates a dangerous situation for public policy.

Democratic societies depend upon the public recognizing problems before governments can effectively address them. If the physical impacts become increasingly severe while public recognition of their underlying causes declines, political pressure for adaptation and mitigation can weaken precisely when the need for action is growing.

This creates a potential feedback loop:

More climate disruption → greater personal impacts → greater economic costs → political polarization → weaker recognition of climate change → less public support for climate action → greater future vulnerability

That is not merely a communications problem.

It is a systemic risk.

Experience Is Increasing Faster Than Understanding

The AP-NORC poll doesn’t measure the physical climate system. It measures what Americans are experiencing and what they believe.

Those are different things.

The survey cannot establish how much of an individual’s electricity bill, sleep disruption or outdoor inconvenience is attributable specifically to climate change. Establishing those causal relationships requires observational climate data and scientific attribution studies.

But the poll does reveal something extremely important about the human response to climate change.

The consequences are becoming increasingly personal while public recognition of climate change is moving in the opposite direction.

That should concern everyone, regardless of political affiliation.

The challenge is no longer simply convincing people that the climate is changing.

It is explaining why their increasingly familiar experiences—extreme heat, higher cooling demand, disrupted outdoor activities, poor sleep and growing economic costs—are connected to a much larger physical system.

Americans may not agree about climate change.

But increasingly, they are living with its consequences.

And the most alarming finding from this poll is that as those consequences become harder to escape, fewer Americans say climate change is actually happening: 66% today, compared with 73% a year ago.

America Is an International Outlier on Climate Change

The decline in American belief becomes even more concerning when viewed against the rest of the world.

A 2025 Pew Research Center international survey of 25 countries found that a global median of 67% of respondents considered climate change a major threat to their country. In the United States, however, only 51% said the same—a gap of 16 percentage points.

The U.S. was among the least concerned countries surveyed. Americans were less likely than respondents in 13 of the 16 high-income countries included in the survey to view climate change as a major threat. In countries such as Argentina, Brazil, France, Japan and South Korea, roughly 80% of respondents regarded climate change as a major threat.

The difference is particularly striking because the United States is not insulated from climate impacts. Americans are experiencing extreme heat, rising cooling demand, disrupted outdoor activities and other consequences of a warming climate, yet concern about climate change remains comparatively low.

The American Divide Is Also Unusually Political

The international comparison becomes even more revealing when political ideology is considered.

Pew found that approximately 84% of U.S. liberals regarded climate change as a major threat, compared with only about 20% of U.S. conservatives. That enormous gap makes the United States an international outlier in the degree to which climate change has become politically polarized.

The result is a remarkable paradox.

Americans across the political spectrum can experience the same heat wave, pay the same electricity bill and endure the same disruption to their daily lives. Yet they may reach dramatically different conclusions about what those experiences mean.

The disagreement therefore isn’t simply about the physical environment. It is increasingly about how Americans interpret the physical environment.

Believing the Climate Is Changing Is Not the Same as Accepting Why

Another Pew measure illustrates the problem even more clearly.

In 2026, only 48% of Americans said the Earth is warming mostly because of human activity. That is substantially lower than the 66% who currently say climate change is happening in the AP-NORC poll.

The difference is crucial.

A person can acknowledge that the climate is changing without accepting that human activity is primarily responsible for that change. Others may accept human-caused warming but disagree about its severity, consequences or appropriate policy response.

This creates several layers of public perception:

Is the climate changing?

↓

Is human activity causing it?

↓

Is it becoming dangerous?

↓

Should government and society act?

Americans can answer those questions very differently.

An Alarming Combination

Taken together, the international and domestic polling reveals a troubling pattern:

90% — say extreme heat has affected their lives

80% — say heat has affected their electricity bills

73% → 66% — Americans saying climate change is happening

51% — Americans calling climate change a major national threat

48% — Americans saying warming is mostly caused by human activity

The numbers measure different things and should not be treated as interchangeable. But together they reveal a striking disconnect between experience, attribution and concern.

The United States is already an international outlier in climate skepticism and political polarization. Now, at a time when Americans report increasingly personal impacts from extreme heat, the share saying climate change is happening has fallen seven percentage points in only one year.

That may be the most troubling finding of all.

The physical climate signal is becoming harder to escape, while public recognition of that signal is moving in the opposite direction.

bookmark_borderStrategic Petroleum Reserve Falls to Lowest Level Since 1983

As of July 31, 2026, the U.S. Strategic Petroleum Reserve (SPR) held approximately 304.8 million barrels of crude oil, its lowest level since March 1983.

From its historic peak of roughly 726 million barrels in 2009, the SPR has experienced a cumulative drawdown of approximately 421 million barrels—about a 58% reduction. The decline has been driven primarily by major emergency releases following Russia’s 2022 invasion of Ukraine and subsequent supply disruptions associated with instability in the Middle East in 2026.

The U.S. Energy Information Administration (EIA) estimates that the reserve could eventually fall to approximately 243 million barrels as currently authorized emergency release schedules conclude.

Strategic Risk: Erosion of U.S. Energy Security

The primary risk of reducing the SPR to approximately 243 million barrels is a severe loss of national energy security and geopolitical leverage during a major global crisis.

At that level—near the lowest inventory in more than four decades—the United States would have substantially less capacity to respond to an extended disruption in global oil supplies. A depleted reserve could also reduce the credibility and effectiveness of the SPR as a deterrent against supply shocks, geopolitical coercion, or major disruptions to global petroleum markets.

Structural and Infrastructure Risks

Cavern Structural Integrity

The SPR is stored in underground salt caverns that require careful management of pressure, oil levels, and cavern conditions. Repeatedly moving crude oil and fresh water into and out of these caverns can alter the physical characteristics of the salt formations and potentially increase operational and structural risks.

Maintaining the integrity of the caverns becomes increasingly important as the reserve is drawn down because the SPR’s ability to rapidly refill or sustain emergency withdrawals depends on the continued reliability of this underground storage infrastructure.

International Energy Agency Compliance

A substantially reduced SPR could also complicate U.S. compliance with International Energy Agency (IEA) emergency-stockholding requirements.

IEA member countries are generally required to maintain emergency oil stocks equivalent to at least 90 days of net oil imports. The relevant measure, however, is based on a country’s total qualifying emergency stocks—not simply the number of barrels held in the SPR. Therefore, the U.S. position must be evaluated using the full national stockholding calculation, including other qualifying inventories.

The Strategic Concern

The SPR was designed as a national insurance policy against severe and prolonged disruptions in petroleum supplies. Reducing the reserve by more than half from its 2009 peak fundamentally changes the country’s ability to absorb a major energy shock.

If inventories approach 243 million barrels, the United States would enter a period in which rebuilding the reserve could become increasingly important but potentially difficult. Large-scale purchases to replenish the SPR would require substantial funding, available crude supplies, suitable market conditions, and sufficient time.

The central strategic issue is therefore not simply how many barrels remain, but whether the United States retains enough readily deployable petroleum reserves to withstand a prolonged global supply disruption while simultaneously preserving the infrastructure, flexibility, and geopolitical leverage needed to respond to the next crisis.

bookmark_borderWildfire Catastrophe Bonds Surge as Insurers Transfer Record Climate Risk to Capital Markets

by Sidd Mukherjee and Daniel Brouse

A New Era of Climate Risk Finance

Wildfire-exposed catastrophe bond issuance has surged to $5.183 billion year-to-date in 2026, rapidly approaching the full-year record of $5.55 billion set in 2025. Driven by escalating wildfire losses, expanding climate risks, and increasingly sophisticated risk models, insurers are turning to global capital markets to transfer unprecedented levels of wildfire exposure.

Catastrophe bonds—often called cat bonds—allow insurers and governments to shift extreme disaster risks away from traditional insurance markets and onto investors. Investors receive attractive returns if a defined catastrophe does not occur, but may lose some or all of their principal if a triggering event causes significant losses.

The rapid growth of wildfire-linked cat bonds reflects a fundamental shift: wildfire is no longer viewed as a regional insurance problem but as a major global financial risk.


Wildfire Cat Bond Issuance Reaches Historic Levels

According to data compiled by Artemis, wildfire-related risk capital has experienced dramatic multi-year growth:

  • 2023: $2.57 billion issued
  • 2024: $2.84 billion issued
  • 2025: Record $5.55 billion issued
  • 2026 (year-to-date): $5.183 billion issued

The acceleration reflects rising insured wildfire losses, increasing pressure on traditional insurers, and investor demand for alternative assets that are not closely correlated with stocks and bonds.


Wildfire Risk Becomes a Major Alternative Asset Class

From Niche Exposure to Global Investment Market

Wildfire risk is rapidly evolving from a specialized insurance concern into a standalone catastrophe-risk asset class. Investors are increasingly attracted to catastrophe bonds because disaster events generally have little relationship to traditional financial markets.

Unlike stocks, bonds, or commodities, catastrophe bonds are driven primarily by physical climate events rather than economic cycles.

Advanced Climate Risk Modeling

Improved modeling capabilities have increased investor confidence. Companies such as Verisk and Moody’s have developed increasingly sophisticated catastrophe models that incorporate updated climate data, changing fire behavior, and evolving exposure patterns.

These models help investors evaluate wildfire probability, potential losses, and appropriate risk premiums.

Human Mitigation Changes the Risk Equation

Wildfire risk differs from many natural hazards because human actions can influence outcomes. Measures such as vegetation management, defensible space creation, utility improvements, and community fire planning can alter expected losses and affect catastrophe bond risk assessments.


Key Sponsors and Expanding Markets

California FAIR Plan Returns to the Cat Bond Market

California’s insurer of last resort, the California FAIR Plan, returned to the catastrophe bond market through the Golden Bear Re Ltd. Series 2026-2 transaction, successfully raising its target to $400 million.

The move highlights the growing difficulty of relying solely on traditional insurance markets in regions facing persistent wildfire threats.

Mercury General Targets Fire Risk Transfer

Mercury General Corporation sponsored the Luca Re Ltd. Series 2026-1 catastrophe bond transaction, targeting $150 million in fire-related reinsurance protection.

European Insurers Explore Wildfire Risk Transfer

Although wildfire catastrophe bond issuance remains heavily concentrated in California, increasingly severe wildfire seasons are pushing European insurers to explore capital-market solutions and alternative risk-transfer structures.


How Catastrophe Bonds Work

A catastrophe bond transfers disaster risk from an insurer to investors.

The insurer pays investors a premium for assuming the risk. Investors receive regular interest payments, but their principal is placed at risk if a predefined catastrophe occurs.

How Investors Make Money

1. Regular Interest Payments

Investors receive monthly or quarterly coupon payments that compensate them for accepting catastrophe exposure.

2. Risk Premium Spread

Sponsors pay an elevated interest spread because investors are taking on the possibility of losing principal.

3. Collateral Yield

The invested principal is typically held in a secure collateral account that generates additional low-risk interest income.

4. Total Return

The investor’s return combines the catastrophe bond premium spread and collateral investment yield.


How Investors Can Lose Their Principal

Binary Catastrophe Risk

If a wildfire reaches the bond’s predetermined trigger conditions, investors may lose part or all of their principal.

Immediate Capital Transfer

When triggered, the lost principal is transferred to the insurance sponsor to help cover wildfire claims.

No Insurance Company Default Required

Unlike traditional corporate bonds, investors do not lose money because an insurer fails financially. The catastrophe itself triggers the loss.

Full Return Without Trigger

If no qualifying wildfire occurs during the bond term—typically three to five years—the investor receives the full principal back at maturity.


How Wildfire Cat Bond Triggers Work

Indemnity Triggers

Payments are based on the sponsor’s actual insured losses from a wildfire event.

Example: An insurer suffers billions of dollars in wildfire claims, triggering payment from the catastrophe bond.

Parametric Triggers

Payments are based on measurable physical conditions rather than financial losses.

Examples:

  • Acres burned
  • Fire intensity
  • Geographic location
  • Wind conditions
  • Temperature thresholds

Industry Loss Triggers

Payments are based on total insurance industry losses from a catastrophe, calculated by independent organizations such as catastrophe loss index providers.


Climate Risk Moves Into Global Finance

The rapid expansion of wildfire catastrophe bonds signals a major transformation in how society manages climate risk. As extreme wildfire seasons become more frequent and expensive, insurers are increasingly relying on financial markets to absorb losses that traditional insurance systems can no longer easily contain.

Wildfire risk is becoming not only an environmental challenge but also a major test of global financial resilience.

The Major Perils Behind the Global Catastrophe Bond Market

Tropical cyclones and earthquakes remain the two foundational pillars of the global catastrophe bond market, traditionally accounting for a large share of the roughly $65.6 billion in outstanding risk capital. Wildfire, however, has rapidly expanded into a significant standalone risk category as insurers confront escalating losses and growing climate exposure.

The catastrophe bond market now spans a broad spectrum of natural, human-caused, and emerging systemic risks.

Core Property Perils

Tropical Cyclones — Hurricanes and Typhoons
Tropical cyclones are among the largest sources of catastrophe bond risk. Coverage is concentrated in U.S. hurricanes, particularly along Florida, the Gulf Coast, and the Eastern Seaboard, as well as Japanese typhoons and Australian cyclones.

Earthquakes
Earthquake risk represents one of the longest-established and most consistently modeled catastrophe bond perils. Major exposure centers include California, the Pacific Northwest, Japan, and New Zealand, where severe seismic events can generate enormous insured losses.

Severe Convective Storms
This increasingly important category covers highly localized but frequent atmospheric hazards, including tornadoes, severe hail, and straight-line winds such as derechos. Repeated losses from these events have become a significant source of claims for U.S. property insurers.

Wildfires
Wildfire has rapidly evolved from a relatively specialized exposure into a major standalone catastrophe bond peril. California remains the dominant market, but growing wildfire losses are driving interest in risk-transfer solutions across other regions.

Winter Storms and Floods
Catastrophe bonds can also protect insurers against extreme winter weather, including freezing events, heavy snowfall, ice damage, and infrastructure failures, as well as coastal and inland flooding.

Emerging and Specialized Perils

Cyber Risk
Cyber catastrophe bonds are an emerging non-natural peril designed to protect insurers against systemic cyber events. Potential triggers include widespread cloud-service disruptions, ransomware attacks, or failures of critical digital infrastructure.

Life, Health, and Mortality Risk
Life and health catastrophe securities can transfer the risk of sudden, extreme increases in mortality or health-related losses. Pandemic-scale events represent one potential source of catastrophic exposure.

Operational and Terrorism Risk
Specialized catastrophe structures have also been used to transfer extreme human-caused risks, including terrorism and major operational disruptions affecting businesses, infrastructure, or public institutions.

Multi-Peril vs. Standalone Catastrophe Bonds

Catastrophe bonds do not always cover a single peril. Many transactions combine several risks into a multi-peril structure, allowing insurers to diversify their exposure and potentially provide investors with a broader risk profile.

For example, a single transaction may combine U.S. named storms, earthquakes, severe convective storms, and wildfire under one bond.

This structure is important because catastrophe bonds can function much like a portfolio of climate and disaster risks: investors are exposed to multiple potential events, while insurers gain protection against losses that could otherwise overwhelm traditional reinsurance capacity.

A Market Expanding Beyond Traditional Disasters

The evolution of the catastrophe bond market reflects a broader transformation in global risk. What began primarily as a mechanism for transferring hurricane and earthquake risk has expanded into a sophisticated financial system capable of pricing and transferring exposure to wildfires, severe storms, floods, cyberattacks, pandemics, and other low-probability, high-impact events.

As climate change increases the frequency, severity, geographic reach, or financial consequences of certain extreme events, catastrophe bonds are becoming an increasingly important bridge between physical risk, insurance markets, and global investment capital.

bookmark_borderMethane: A Rapid Link Between Feedbacks and Tipping Points

by Daniel Brouse

Introduction: The Fast-Moving Greenhouse Gas Accelerating Climate Change

Methane has become a rapid link between climate feedbacks and tipping points.

Methane (CH₄), the primary component of natural gas, is one of the most powerful greenhouse gases driving modern climate change. Although methane remains in the atmosphere for only about a decade—far less time than carbon dioxide (CO₂)—it traps substantially more heat over short time horizons, making it a critical driver of near-term warming. Additionally, when methane is oxidized after roughly 10–12 years, its carbon is ultimately converted into CO₂, which can remain in the atmosphere and continue influencing the climate system for hundreds of years.

Methane is responsible for approximately 30% of the global warming experienced since the Industrial Revolution. It also contributes to longer-term warming because atmospheric methane is eventually oxidized primarily into carbon dioxide and water vapor. Water vapor is the most powerful amplifying feedback in the climate system, intensifying warming initiated by other greenhouse gases. When methane is burned as natural gas, its carbon is converted directly into CO₂, adding a long-lived greenhouse gas to the atmosphere.

Global methane emissions have increased dramatically over the past two decades, rising by roughly 20% and reaching record levels of approximately 610 million tonnes annually. The growing concern, however, is not simply the amount of methane being emitted by human activities. It is the increasing number of coupled climate feedbacks capable of generating additional methane as the planet warms.

One of the most important connections begins with the ice-albedo feedback. The ice-albedo effect is estimated to account for approximately 10–25% of current global warming. As snow and ice melt, darker land and ocean surfaces absorb more solar radiation rather than reflecting it back into space, amplifying regional and global warming. The ice-albedo feedback does not directly inject greenhouse gases into the atmosphere. Instead, its significance is that it can accelerate other processes that do.

Among the most important is permafrost thaw. Increasing Arctic temperatures are penetrating frozen soils that contain enormous quantities of ancient organic carbon. As permafrost thaws, previously frozen organic matter becomes accessible to microorganisms. Under oxygen-rich conditions, decomposition primarily produces CO₂. In saturated, oxygen-poor environments, however, microbial decomposition can produce methane (CH₄).

The result is a newly coupled climate feedback:

Ice and snow loss → greater solar absorption → Arctic warming → permafrost thaw → microbial decomposition → CH₄ + CO₂ → additional warming

This process is particularly concerning because permafrost thaw can occur much more rapidly than the millennial timescales often associated with gradual carbon release. Abrupt thaw, thermokarst formation, changing hydrology, and wildfire can accelerate the mobilization of previously frozen carbon over years to decades.

Wildfire adds another important connection. Increasing heat, drought, and changes in vegetation and fire weather are contributing to more severe and persistent wildfire conditions in some northern ecosystems. Fires release large quantities of CO₂ directly into the atmosphere while simultaneously removing vegetation and insulating organic layers that protect permafrost from summer heat.

In boreal regions of Canada and Siberia, this creates another powerful coupled feedback:

Warming → more severe wildfire → direct CO₂ emissions → loss of insulating vegetation and soil → accelerated permafrost thaw → additional CO₂ and CH₄ → further warming

The methane feedback therefore cannot be considered in isolation. It is increasingly embedded within a network of interacting climate feedbacks and tipping points.

As warming approaches and crosses critical thresholds, the climate system can shift from one dominated primarily by direct human greenhouse-gas emissions toward one in which natural feedbacks increasingly contribute additional greenhouse gases. Ice loss can accelerate permafrost thaw; permafrost thaw can increase methane and CO₂ emissions; wildfire can accelerate both atmospheric CO₂ accumulation and permafrost degradation; and the resulting warming can intensify the original processes.

The central concern is therefore not simply that methane emissions are increasing. It is that warming itself is increasingly activating new methane sources and strengthening existing feedbacks at the same time that other tipping points are being approached or crossed.

This creates a progressively more interconnected climate system:

Human emissions → warming → ice loss → permafrost thaw → methane and CO₂ release → more warming → greater wildfire and ecosystem disruption → additional greenhouse-gas release → further tipping-point pressure

Methane is consequently more than a powerful greenhouse gas. As climate tipping points become increasingly coupled, it can become a rapid amplifier linking physical, biological, and chemical feedbacks across the Earth system.


The Heat-Trapping Power of Methane

A Short-Lived but Extremely Powerful Greenhouse Gas

Methane has a unique climate profile:

CharacteristicRaw Methane (CH4CH_4CH4​)Combusted Methane (CO2CO_2CO2​)
Immediate Heat-Trapping EffectExtremely highModerate
Global Warming Potential (20 years)More than 80 times stronger than CO2CO_2CO2​Baseline
Atmospheric LifespanAbout 10–12 yearsCenturies
Primary Climate RiskLeaks, venting, and natural feedbacksLong-term accumulation after combustion

Because methane is so powerful in the short term, rapid methane reductions can have an immediate effect on slowing global warming. However, continued emissions create a dangerous cycle because warming itself can trigger additional natural methane releases.


Methane’s Two Pathways to Carbon Dioxide

A critical question is often overlooked when comparing natural gas combustion with methane emissions:

If methane eventually breaks down into carbon dioxide in the atmosphere, does allowing methane to escape ultimately produce the same amount of CO₂ as burning it?

In terms of carbon atoms, essentially yes. One molecule of methane (CH₄) contains one carbon atom. Whether that methane is burned immediately or eventually oxidized in the atmosphere, that carbon can ultimately become approximately one molecule of CO₂.

But the climate consequences are dramatically different because of the pathway and timing.

1. Combustion: Immediate Conversion to CO₂

When methane is burned in a power plant, furnace, stove, engine, or flare, the conversion occurs almost immediately:

CH₄ + 2O₂ → CO₂ + 2H₂O

The carbon in methane is converted directly into carbon dioxide.

The climate consequence is therefore dominated by long-lived CO₂, which remains in the atmosphere and affects the climate system for centuries or longer.

But combustion also eliminates methane’s period of extremely strong short-term heat trapping.

2. Atmospheric Oxidation: Methane First, CO₂ Later

When methane escapes directly into the atmosphere, it does not immediately become CO₂.

Instead, atmospheric chemistry gradually oxidizes methane, primarily through reactions involving hydroxyl radicals (OH). The process occurs through a series of intermediate chemical reactions before the carbon ultimately becomes CO₂.

Methane has an atmospheric lifetime of roughly a decade, meaning that a large fraction of an emission is removed from the atmosphere over approximately 10–12 years.

During that period, however, the methane itself is an exceptionally powerful greenhouse gas.

The sequence is therefore:

Methane leak → approximately 10–12 years of intense methane warming → atmospheric oxidation → CO₂ → centuries of additional warming

This creates a crucial distinction:

Burning methane converts it to CO₂ immediately.

Leaking methane delays the CO₂ conversion—but adds a period of extremely powerful methane warming first.

That is why preventing methane leakage can produce a disproportionately large near-term climate benefit.

Why the Carbon Source Matters

The eventual conversion of methane into CO₂ does not mean that all methane emissions have identical climate consequences.

The critical distinction is where the methane’s carbon came from.

Fossil Methane: Adding Ancient Carbon

Methane extracted from natural gas and other fossil fuel deposits contains carbon that has been isolated from the active atmosphere-biosphere carbon cycle for millions of years.

When fossil methane is:

  • burned, its carbon becomes CO₂ immediately;
  • leaked, its carbon initially produces powerful methane warming and is then largely converted into atmospheric CO₂.

Either way, fossil methane represents a net transfer of geological carbon into the active atmosphere-climate system.

Biogenic Methane: Carbon Cycling Through the Biosphere

Methane produced by livestock, wetlands, and other biological processes is different.

Much of this methane originates from carbon that plants recently removed from atmospheric CO₂ through photosynthesis.

The simplified cycle is:

Atmospheric CO₂ → Plants → Organic matter → Methane → Atmospheric CO₂

This is part of the short-term biological carbon cycle, rather than the introduction of ancient fossil carbon.

That distinction, however, does not make biogenic methane harmless.

Methane can produce substantial warming during the decade or so that it remains in the atmosphere. Its eventual return to CO₂ does not erase that temporary but powerful climate forcing.

The Key Distinction

The important question is therefore not simply:

“Does methane eventually become CO₂?”

It does.

The more important questions are:

“What happens before it becomes CO₂?”

and

“Where did its carbon come from?”

That distinction explains why methane is such a critical climate-control target.

Fossil methane:

Ancient carbon → methane leak → intense near-term warming → CO₂ → long-term warming

Biogenic methane:

Atmospheric CO₂ → plants → methane → intense near-term warming → CO₂

The chemistry may ultimately return methane’s carbon to CO₂, but the climate system experiences the methane phase first—and that phase is extraordinarily powerful.

Major Sources of Methane Emissions

Methane emissions come from both human activities and natural systems.

1. Fossil Fuel Production and Use

The fossil fuel industry remains one of the largest sources of human-caused methane emissions.

Major sources include:

  • Oil and natural gas extraction: methane leaks during drilling, processing, storage, and transportation.
  • Coal mining: methane trapped in coal seams escapes during extraction.
  • Natural gas infrastructure: pipelines, compressors, and storage facilities can release large quantities of methane.

Despite industry commitments to reduce leakage, global fossil fuel methane emissions remain near record levels, estimated at roughly 120–150 million tonnes annually.

Recent tracking shows:

  • Oil operations contribute approximately 45 Mt/year of methane emissions.
  • Coal mining contributes approximately 43 Mt/year.
  • Natural gas systems contribute approximately 36 Mt/year.

Satellite observations have also identified frequent “super-emitter” events, where enormous methane releases occur from individual facilities, coal mines, and aging oil fields.


2. Agriculture and Waste

Human activities account for the majority of long-term methane growth.

Livestock Production

Ruminant animals such as cattle and sheep produce methane through digestion. Their manure also releases methane when stored in oxygen-poor conditions.

Agriculture contributes approximately 35–40% of human-caused methane emissions, driven largely by:

  • Expanding cattle and dairy production.
  • Increased global demand for meat and dairy products.
  • Manure management systems.

Landfills and Organic Waste

Modern waste systems create ideal methane-producing conditions.

When food waste and other organic materials are buried in landfills, they decompose without oxygen, producing methane that can escape into the atmosphere.

Rapid urbanization and rising consumption have increased landfill methane emissions worldwide.


3. Natural Methane Feedback Loops

One of the most concerning developments is that climate change itself is beginning to increase methane emissions from natural systems.

Warming Wetlands: A Climate Feedback Loop

Tropical wetlands have become a major contributor to the recent acceleration in atmospheric methane growth.

The mechanism:

Rising temperatures → Increased rainfall and flooding → Expansion of oxygen-poor wetlands → Faster microbial decomposition → Increased methane release → Additional warming

Research from NOAA and the University of Colorado indicates that tropical wetlands, especially in South America and Africa, have become dominant sources of the recent methane surge.

Wetlands accounted for approximately 40% of the increase in methane emissions between 2000 and 2022, demonstrating how climate change can activate self-reinforcing feedback loops.


Methane Emissions Are Accelerating

Global methane emissions have increased dramatically over the past two decades, rising by roughly 20% and reaching record levels of approximately 610 million tonnes annually.

Atmospheric monitoring from organizations including NOAA and the International Energy Agency (IEA) shows methane concentrations continuing a steep upward trend.

This acceleration is being driven by three interacting forces:

  1. Expanding fossil fuel extraction and infrastructure leaks.
  2. Growing agricultural and waste emissions.
  3. Climate-driven natural feedback loops, especially warming wetlands.

Why Methane Matters for Climate Stability

Methane represents one of the fastest opportunities to slow near-term warming because it has such a powerful short-term climate impact.

Reducing methane emissions from:

  • Fossil fuel leaks,
  • Livestock systems,
  • Landfills,
  • and industrial operations

could rapidly reduce the rate of warming.

However, continued warming threatens to unlock additional natural methane emissions from wetlands, permafrost, and other carbon-rich ecosystems. These feedbacks create the risk of a self-reinforcing cycle:

More warming → More methane release → More greenhouse warming → More ecosystem disruption → More methane release

Methane is therefore not only a pollutant—it is a critical indicator of whether Earth’s climate system is moving toward stabilization or accelerating disruption.

The Growing Methane Feedback: From Ice-Melt Acceleration to Tipping-Point Amplification

The ice-albedo feedback is one of the fastest climate feedbacks operating today. As Arctic sea ice and snow cover disappear, darker surfaces absorb more solar energy, accelerating regional warming.

But the climate system does not stop at the ice-albedo feedback.

As warming crosses additional thresholds, carbon-cycle feedbacks can become increasingly important—and methane can become a powerful amplifier of that warming.

This creates a critical transition in the climate system:

Ice loss accelerates warming → warming destabilizes frozen carbon stores → microbial activity increases → methane emissions increase → methane adds additional warming → more tipping points become vulnerable

The significance of methane is therefore not limited to today’s emissions. Its greater danger may lie in the possibility that warming itself progressively activates new methane sources.

1. Permafrost: A Gateway to Additional Methane

Permafrost contains enormous quantities of frozen organic carbon accumulated over thousands of years.

While frozen, much of this carbon remains relatively isolated from microbial decomposition. As temperatures rise and permafrost thaws, previously frozen organic material becomes available to microorganisms.

The resulting greenhouse-gas emissions depend on local conditions.

In oxygen-rich soils, decomposition produces primarily CO₂.

In saturated, oxygen-poor soils and wetlands, anaerobic decomposition can produce substantial quantities of methane (CH₄).

The feedback therefore becomes:

Warming → permafrost thaw → microbial activation → CH₄ release → additional warming

The important point is that permafrost thaw can turn a previously inactive carbon reservoir into an increasingly active source of greenhouse gases.

2. Why Methane Becomes More Important as Warming Accelerates

Methane is especially important because it is an extremely powerful greenhouse gas over short timescales.

When methane emissions increase, the atmosphere experiences a rapid additional warming influence. Although methane eventually oxidizes into CO₂, its initial warming effect is much stronger than that of an equivalent amount of CO₂ over the first several decades.

This makes methane particularly important during periods when the climate system is approaching or crossing tipping points.

The sequence can become:

Initial warming → methane release → rapid additional warming → greater probability of crossing another threshold

Once another tipping system begins to destabilize, it can generate additional warming or greenhouse-gas emissions of its own.

3. Tipping Points Can Transform the Methane Feedback

The importance of methane should therefore be considered as part of a network of interacting tipping points, rather than as an isolated feedback.

For example:

Arctic warming
↓
Sea-ice loss
↓
Ice-albedo feedback strengthens
↓
Additional Arctic warming
↓
Permafrost thaw increases
↓
Microbial decomposition accelerates
↓
CH₄ emissions increase
↓
Additional atmospheric warming
↓
Further ice loss and permafrost thaw

This network can become even more complicated as other climate thresholds are approached.

Warming can alter precipitation patterns, increase wildfire activity, change Arctic hydrology, and transform previously frozen or oxygen-rich soils into waterlogged environments where methane production becomes more favorable.

Consequently, the methane feedback can strengthen not simply because temperatures rise, but because warming changes the physical conditions controlling where and how methane is produced.

4. From External Forcing to Internal Amplification

This distinction is fundamental.

At the beginning of anthropogenic warming, the primary forcing comes from human emissions of greenhouse gases.

But as warming increases, the climate system itself can begin generating additional greenhouse-gas emissions.

The system moves progressively from:

Human emissions → warming

toward:

Human emissions → warming → feedback activation → additional greenhouse gases → additional warming

Methane is particularly important in this transition because it can provide a rapid amplification mechanism inside a much slower carbon-cycle response.

Permafrost does not need to release all of its stored carbon to become climatically important. Even a progressively increasing methane contribution can amplify warming during the critical period when other tipping points are becoming increasingly vulnerable.

5. Methane as a Tipping-Point Multiplier

This is why the methane feedback should not be evaluated solely by comparing today’s methane emissions with today’s CO₂ emissions.

The more important question is:

Does continued warming activate new methane sources that were previously largely dormant?

If the answer is yes, methane changes from being primarily an emissions-control problem into an increasingly important Earth-system feedback problem.

The distinction can be summarized as:

Before tipping-point activation:
Human emissions → methane emissions → warming

As tipping points are crossed:
Human emissions → warming → permafrost and wetland changes → additional methane → more warming

With multiple interacting tipping points:
Warming → ice loss → greater solar absorption → permafrost thaw → methane release → additional warming → further tipping-point activation → additional greenhouse-gas release

This is the critical danger.

The climate system does not have to experience one enormous methane release for the feedback to matter. A progressively increasing methane contribution, coupled with other feedbacks, can help push the system across additional thresholds.

The Emerging Climate Dynamic

The ice-albedo feedback may be one of the fastest visible accelerators of Arctic warming today.

But as warming continues, the relative importance of methane-producing feedbacks can increase because previously frozen carbon becomes biologically active and environmental conditions become increasingly favorable for methane production.

The resulting system can be viewed as a progression:

Ice loss → Arctic amplification → permafrost thaw → methane release → atmospheric warming → additional tipping-point pressure

The critical issue is therefore not whether methane will suddenly become the dominant driver of climate change.

It is whether methane feedbacks become an increasingly important amplifier at precisely the time when the climate system is becoming more vulnerable to cascading tipping points.

That possibility makes methane one of the most important short-term feedbacks to monitor as the planet moves deeper into a warmer and increasingly nonlinear climate state.